Small Cap Value Report (Fri 26 March 2021) - VLG, RNWH, IQE, DPEU, AFS, SPSY

Good morning, it's Paul & Jack here with the SCVR for Friday.
Timing - today's report is now finished.
Agenda -
Paul -
Venture Life (LON:VLG) - impressive 2020 results, and stuffed with cash for more acquisitions. Potentially interesting. Investor presentation next week should be interesting.
Renew Holdings (LON:RNWH) - A very good acquisition is announced, I have a rummage through the acquisition's accounts at Companies House, and like what I see. Also we get a reassuring, in line, trading update for the group as a whole.
Iqe (LON:IQE) - FY 2020 results published yesterday. I dig into the cash generation - looks like a one-off, with very low capex in 2020, but capex is guided to shoot up again in 2021. I'm not convinced the business model is any good.
Jack -
Dp Eurasia Nv (LON:DPEU) - still in business and with growth picking up, but events beyond management control are a concern
Amiad Water Systems (LON:AFS) - encouraging set of FY results and optimistic outlook, but high spread, small free float and lack of historical growth.
Spectra Systems (LON:SPSY) - solid growth from and exciting longer term prospects from this innovative small cap.
.
Venture Life (LON:VLG)
85p (up 4% yesterday) - mkt cap £107.0m
Venture Life (AIM: VLG), a leader in developing, manufacturing and commercialising products for the international self-care market, announces its audited results for the year ended 31 December 2020.
Record revenues and profit, amidst unprecedented global circumstances
This is quite a striking statement -
Since entering the public markets in 2014, the Group has achieved a compound annual revenue growth rate of 27% (up to and including 2020), which has come from a combination of organic and acquired growth. In 2016, 2018 and 2020, the Group acquired interesting assets that it could leverage with its operational base, and each of these assets has shown meaningful growth in revenues and profitability since acquisition. This strategy will continue to form the basis of future growth, making selective earnings enhancing acquisitions to utilise capacity and improve margins, alongside organic growth from our consolidated business.
Whilst that sounds impressive, I note that the share count seems to have gone up from 26m to 125.8m over that period, almost a five-fold increase.
Management seem to have been large sellers of shares in Dec 2020, at 90p, withdrawing about £7m. This reduced the 3 key Directors from 15.3% combined, to 5.1% combined, not something I view favourably. If the future is so exciting, why have they sold down their stakes so much? That doesn't make sense to me.
As mentioned here before, the last fundraising in Dec 2020 was unusually large, issuing 41.8m new shares at 90p (raising £37.6m before costs, £34.1m net of costs, which looks like a bonanza for the advisers!) which increased the share count by 50%, pencilled in for future acquisitions. None have been made so far. Normally, placings are done for a specific acquisition, or to repair a stretched balance sheet. It’s unusual to see such large dilution, and nothing done with the funds 3 months later. Maybe deals are in the pipeline? Ah yes, I see the broker notes say 3 deals are in the pipeline, with 1 imminent. With such a large pot of cash ready for acquisitions, that could boost future profitability considerably, if the money is spent wisely. The danger is that they spend the money on something duff, which is a risk - lots of acquisitions destroy shareholder value, after all look how often we see big write-offs of goodwill.
Hence the key point with this share, is how wisely that cash pile is spent.
Reviewing the figures, the P&L is impressive -
- Revenues up 49% to £30.1m
- Gross margins have improved, because gross profit is up more than revenues, at +61%
- Profit before tax is up 141% to £3.28m, but that’s stated after costs of £405k (impairment of financial assets) and £909k intangibles amortisation, which some people might adjust out, which would boost adj PBT to £4.6m. Adjusted PBT and EPS figures are not provided, which is quite unusual these days.
- Reported EPS is 2.74p, but the broker notes use their own calculations, making adjustments, e.g. Cenkos adjusts this up to 4.5p, as does N+1, so I’ll work on the broker adjusted figures. It would be more helpful if the company could in future be consistent with the brokers, and also publish adjusted EPS figures.
- Broker notes to the rescue, many thanks to Cenkos and N+1 Singer for putting updates on Research Tree yesterday.
Balance sheet - stuffed full of cash, ready for acquisitions to be made.
Cashflow - looks decent, although note that a lot of the cash generated was absorbed into increased working capital.
Investor presentation - excellent, this is imminent, 13:00 on 29 March 2021. I shall sign up for this, as getting a feel for what management are like, and their prior experience, seems particularly important with this share.
My opinion - open-minded at this stage. 2020 results were very good, and it sounds like we’re about to get news on more acquisitions.
At this stage, management selling two thirds of their own shares at 90p recently, rules it out for me. I look for the opposite.
The big Chinese contract has apparently re-started in 2021, but no figures given for recent deliveries. Note 2.4 shows that total sales to China were £2.3m, not particularly significant.
Let’s see what the investor presentation is like next week, and take it from there.
.
Renew Holdings (LON:RNWH)
573p (up 7% at 08:15) - mkt cap £448m
Renew (AIM: RNWH), the leading Engineering Services Group supporting UK infrastructure...
Immediately earnings enhancing acquisition strengthens Renew's exposure to UK water market
With interest rates so low, anything profitable should be immediately earnings enhancing! Still, it’s good to have that flagged as the headline.
RNWH is buying J Browne Group for £29.5m cash (all on completion, no deferred payments or earn-outs).
In the year ended 31 March 2020, J Browne reported profit before tax of £5.5m on turnover of £79.2m (including share of joint ventures). In its current financial year to 31 March 2021, the business has seen a reduction in activity due to the transition from AMP6 to AMP7 and is expected to report turnover of £63.3m, but this has now increased back to historic run-rate levels as activity has normalised in AMP7.
I’ve had a rummage through the accounts filed at Companies House for J Browne (co. no. 06599855), and it looks excellent. A decent, profitable, cash generative business, making good margins. Looks an excellent fit for RNWH, and it looks a favourable purchase price too. A thumbs up from me, this looks a good acquisition, as far as I can tell.
I particularly like the comments from RNWH’s CEO, Paul Scott (!), because this shows that RNWH knows what it’s buying, hence the acquisition risk sounds low, which is very important -
We have known Jeremy and his team for many years and have tracked how they have successfully grown a business with an excellent reputation for directly delivering reliable engineering services to a number of water companies...
Net debt - we’re reassured that this acquisition won’t stretch RNWH’s bank borrowings -
Post-acquisition, Renew will continue to have net debt/EBITDA of significantly less than 1x.
Trading Update (FY 09/2021) - this all sounds reassuring too -
- Trading in line with management expectations, and ahead of last year.
- Lockdown - the latest one has not had any material impact on trading.
- Demand - continuity across all markets.
- Full year - confident of delivering consensus expectations (no footnote to say what the figure is, unfortunately)
- Net debt & cash generation also in line with expectations.
- Order book - underpinned by long-term framework deals, and new contract awards - again, in line with expectations.
Diary date - 18 May 2021, for publication of H1 Figures to 31 March 2021.
My opinion - the weak balance sheet at RNWH has always put me off, as that creates too much risk for my appetite, in a notoriously risky sector where many companies with weak balance sheets have failed.
That’s a pity, because RNWH has built a good track record, of growing revenues, margins, and EPS, as you can see -

.
The latest acquisition looks a cracking deal, which should drive further growth, at good margins. Hence expect to see broker forecasts raised considerably, to include the future earnings of J Browne.
The PER is quite low, which is normal for this sector. Note below also the high quality scores.
I’ve highlighted below the Price to Tang. Book line, which shows “n/a” - that is the quickest way to check if a balance sheet is strong or not. If it says n/a, then the balance sheet is weak, having negative net tangible asset value.
It’s also worth checking the Z-score, which is actually not too bad here -

.

.
Just because a company does well, and the share price goes up, doesn’t mean that the risks weren’t there. They were just navigated successfully, and could still become a problem in future.
Overall, I wouldn’t invest in this sector at all, but if you are going to, then RNWH looks a decent business. If it finds more acquisitions as good as J Browne, then I could see this share price continuing its long term up-trend.
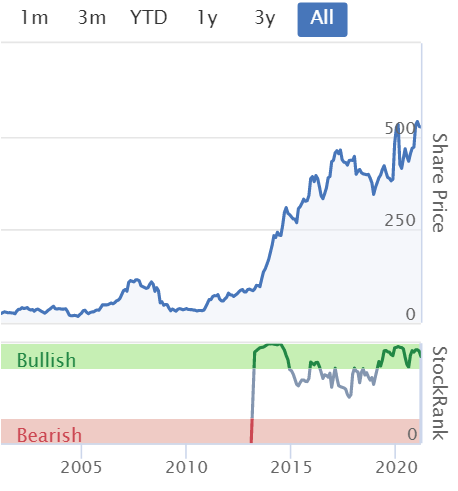
A fantastic long-term chart below, and the StockRank is high too. Lots to like here!
.
.
Iqe (LON:IQE)
58.8p (down 4.6% at 09:55) - mkt cap £471m
IQE plc (AIM: IQE), the leading supplier of advanced wafer products and material solutions to the semiconductor industry, announces its full year results for the year ended 31 December 2020.
Record revenue of £178m underpinned by the start of the 5G mega-cycle
The market doesn’t seem to like these numbers/outlook, which were published yesterday morning. The share price has dropped from 73p to 59p in the last 2 days, a drop of c.20%. I do think it’s worth pointing out that we’ve been spoiled rotten, with a 6-month period of indiscriminate share price rises. Hence companies really do need to deliver strong results/outlook, to justify these big rises.
If not, then price corrections can be quick & brutal. As a general point, if there’s no obvious reason why a share has risen a lot, then maybe it’s time to bank some profits, if something isn't a core long-term holding?
Revenue of £178.0m is up 27.1%, a good start.
Below that, we’re given a bewildering array of alternative profit & cashflow numbers.
If in doubt, I usually go to the cashflow statement, which gives a more sensible picture of reality than the P&L. Here it is -

.
My notes -
- Cash generated from operations is genuinely higher, at £35.5m, compared with £8.9m a year earlier. This has to be read in conjunction with note 6 in the accounts, which is a long list of non-cash adjustments to get from the loss before tax, to a large positive cashflow. It’s complicated, but the simple version is that there are lots of depreciation, amortisation & impairment charges in the P&L, which are non-cash.
- Capex - i.e. purchases of property plant & equipment have dramatically reduced from £31.86m in 2019, to only £4.99m in 2020.
- Capitalised development spend has also reduced, from £8.4m in 2019, to £4.7m in 2020.
- IFRS 16 entry, for an element of lease payments (property rents, etc) which is put down in finance costs, thus inflating the subtotals above. IFRS 16 is such a nightmare, it’s a terrible accounting standard that has managed to mess up all the key financial statements! It needs to be repealed asap in my view. But in the meantime, remember that cashflow figures are often now over-stated because part of the rents are low down, in finance costs.
Overall, what the above means is that IQE consumed cash & increased its net debt in 2019, but generated cash in 2020, and reduced net debt. So that’s good.
Balance sheet -
NAV: £260.4m, less £105.8m intangibles = NTAV £154.6m - i.e. fairly healthy.
This is a capital-intensive business, with £126.2m in property, plant & equipment (note the heavy capex in 2019 and earlier). So the hope is now that it has modern equipment to make the products efficiently. Although how long I wonder will it be, before improved machinery is needed and has to replace the existing machines? Technology seems to move fast in this sector, giving a competitive advantage to whoever has the most modern equipment, that’s what worries me about this share - it might need almost continuous heavy capex to remain competitive?
Working capital looks OK, with a current ratio of 1.94.
Lease asset/liabilities look quite hefty, suggesting it operates from sizeable premises, with a lease length of c.10 years from the looks of it (current lease liability of £4.8m should approximate to annual rent), then another £42m lease liabilities in long term creditors. A long lease is only a problem if a company wants to get out of the property, and nobody else wants it. Having secure, long-term premises, is probably an advantage for IQE, hence why it’s so daft to have future years’ rental obligations on the balance sheet. £4.8m p.a. rent is only 2.7% of revenues, which is quite modest, so doesn't look a problem.
Outlook - my summary of key points -
- Trading has continued positively in 2021.
- Opportunities for new 5G-related products are positive.
- Forex headwind, as revenues earned in US$, but reported in sterling.
- H1 revenues & adj EBITDA in H1 2021 expected to be similar to last year.
- Capex - is going back up again, a lot. £20-30m in 2021.
My opinion - I’m not keen on the business model here. It’s too capex hungry, and sounds like that’s probably an ongoing thing, for exciting new products - which is what generates a wave of investor euphoria every few years.
So where’s the shareholder return going to come from? I see from the StockReport that it doesn’t pay any divis.
Overall, I can see why the share price has fallen back a lot in recent years. It’s difficult to see any worthwhile investment case here. I’m not sure it has any sustainable competitive advantage, but I have no knowledge of the sector, I just look at the numbers. One year of positive cashflow isn’t enough to convince me. So personally, I’m not interested in getting involved here again.
IQE shares were a lucky trade in 2017, when the market got excited about wonderful new products, and positive trading updates. Lots of private investors (including me!) got terribly excited about it, the share multibagged in 2017, but it turned out to be largely hot air, as you can see from the long-term share price below. That’s why I’ll need a lot of convincing that anything has changed, to want to get involved again. There again, there are lots of new people in the market now, who won't know the history of this share, and who may lap up the story of 5G mega-cycle, etc? So it could be a cynical trade on that, at some point, who knows?!
.

.
Jack's section
DP Eurasia (LON:DPEU)
Share price: 62.6p
Shares in issue: 145,372,414
Market cap: £91m
Dp Eurasia Nv (LON:DPEU) is the exclusive master franchisee of the Domino’s Pizza brand in Turkey, Russia, Azerbaijan and Georgia. It’s the largest pizza delivery company in Turkey and the third largest in Russia by store count.
It was founded in 1996 by current CEO Aslan Saranga, as the master franchisee of the Domino’s Pizza system in Turkey. It expanded rapidly, in 2012 it was awarded the exclusive master franchise for Russia. Then, in 2015, it opened its first franchised stores in Azerbaijan and Georgia.
But with the unstoppable rise of delivery aggregators such as Deliveroo (which is soon to list on the London stock market), is this pizza delivery business model what it was in the noughties?
There’s also country risk here, with economic events in Turkey drowning out operational progress. The share price chart since IPO tells a story:

These Domino’s Pizza franchises can build high-quality, long-term revenue and cash flows when they get it right and, with 771 stores, DPEU is already quite big versus its market cap of £91.6m. So if it can push on and recover then its shares might be a good investment.
But currency dynamics are important here, too.

My concern is that the share price is being driven by factors outside of management’s control. This probably puts it in the ‘too difficult’ and/or ‘too risky’ pile for some. On balance, I would include myself in that camp.
Preliminary Results (released Tuesday 23 March 2021)
Highlights:
- Group system sales +14.6% to TRY1,569.9m; Turkey +26.4% to TRY 1,069.1m, Russia -6.3% to TRY 471.6m, Azerbaijan & Georgia +37.9% to TRY29.2m
- Group revenue +4% to TRY1,019.2m,
- Group adjusted EBITDA -30.7% to TRY131.5m,
- Group net loss increased from TRY5.6m to TRY107.6m.
It’s clearly been a tough year for DPEU with unprecedented trading conditions. Net losses have increased but the group was able to increase system sales by 14.6% on the back of strong Turkish performance.
Some 27 stores were closed in Turkey and Russia but the total estate grew by six sites, reaching 771 stores across the four countries of operation.
Online sales grew 40.3% and system sales like-for-like growth in the first two months of the new financial year have been encouraging, up 37.8% (Turkey +49% and Russia +6.4%).
DPEU is also reinstating guidance for FY21: net store openings of between 30-40 in Turkey and 15-20 in Russia; like-for-like targets of 21-25% in Turkey and 12-15% in Russia; capex of TRY45m in Turkey and RUB160m in Russia.
One interesting point is that private equity group FIDES has sold its c32% stake in the company to Jubilant FoodWorks (market cap of £3.79bn). Jubilant FoodWorks is India’s largest food service company and it also has the Domino’s Pizza franchise in India, which operates 1,314 restaurants in 285 cities.
So that could be a vote of confidence in DPEU’s operations from another master franchise operator.
Conclusion
It is possible that there’s quite a strong underlying Domino’s Pizza master franchise operator here, but there are also a lot of moving parts in the accounts and a lot of risks to factor into the analysis.
It does trade at a notable discount to other Domino’s Pizza operators around the world, according to some metrics:

And it looks like there are early signs of improving momentum. Target like-for-likes of 21-25% for Turkey and 12-15% for Russia are quite bullish. Meanwhile, the Jubilee shareholding is intriguing.
This stock might be worth revisiting in the future to get to grips with it a little better. I think there’s potential in the business and the valuation, but for now I’m nowhere near buying due to the substantial risks involved.
The concern I have is that the main determinants of DPEU’s share price performance at present might be more currency and economy-related, rather than anything operational that is within the control of what looks to be a relatively competent management team. That rules it out for me.
Amiad Water Systems (LON:AFS)
Share price: 300p (+5.26%)
Shares in issue: 30,398,357
Market cap: £91.2m
Amiad Water Systems (LON:AFS) specialises in developing and marketing environmentally friendly water filtration solutions to protect water applications in the irrigation and industrial markets.
The group is headquartered in Israel and operates through ten subsidiaries, with a network of distributors to customers in more than 80 countries. FIMI Opportunity Funds (Israeli private equity fund), is a controlling shareholder with an interest in 39.5%.
It’s got four technologies:
- Screen - flushing tech that automatically cleans screens when they get dirty,
- Disc - automatic depth and surface disc filtration technology for handling high organic dirt loads,
- Microfiber - fine threads are wound over a rigid grooved base plate that are mounted on hollow collector pipes to filter fluids, and
- Media – devices that filter water through a thick layer of graded granular particles such as sand, glass, gravel or other, called a filter bed.
All of these products are designed to deliver clean water.
Amiad's filtration solutions for the Irrigation segment prevent organic and inorganic materials from clogging the emitters of irrigation systems. Revenue from the Irrigation segment was $56.4m in 2020 (2019: $59.3m), accounting for 53.9% of revenue (2019: 51.3%).
In the Industry segment, Amiad operates in the metal, plastic, energy and chemical industries as well as providing solutions for municipal purposes, where its products are used for purposes such as protecting the nozzles or membranes of the filtration system and removal of invasive species. Revenue from the Industry segment was $48.2m for 2020 (2019: $56.2m), accounting for 46.1% of revenue (2019: 48.7%).
The practical applications and demand of such products are obvious but when you look at Amiad specifically, it has struggled to generate revenue growth over time.

And net income has been patchy.

So while the products and market sound interesting, I have questions around the investment merits here. It looks like the company needs some kind of definitive catalyst to bring about a step change in revenue and profitability.
On that note, R&D spend has been increased over the years and the group shows signs of good cash generation. But returns on capital and operating margins are low, and trading has so far been volatile.
I don’t mind volatility if you can see an underlying uptrend, but that doesn’t seem to be the case here based on the ten-year period to FY19.
FY20 Highlights:
- Revenue -9.5% to $104.6m,
- Gross margin +1% to 39.9%,
- Operating profit +74.2% to $5.4m,
- Profit before tax +412.5% to $4.1m,
- Fully diluted earnings per share of 9.3c compared to a FY19 loss per share of 8.2c,
- Cash generated from operations +76% to $22.7m,
- Net cash of $23.5m compared to $12.5m of net debt the prior year,
That puts the group on about 42x FY20 earnings per share. Amiad has struggled to generate more than this in the past, so it looks like a lot of growth is priced in here. It’s trading at a little over 1x sales, though, so if the group can continue to drive margin growth then the earnings could rise quite quickly.
And the results do look much better than I was anticipating, with margin expansion and dramatically improved cash generation.
What’s driving this? The group says it is introducing further manufacturing automation and other process enhancements. It has also managed costs in response to Covid.
It looks like this is one of those instances where the events of the past year have possibly spurred some longer term operational efficiency gains. That looks the case to me, judging by the materially enhanced cash generation.
Meanwhile Amiad has secured a new five-year global distribution agreement with irrigation solutions provider Netafim for Amiad's disc filtration products for the irrigation market, and a new disc filtration system has been launched post-period.
Group CEO Dori Ivzori comments:
Looking ahead, we entered 2021 with a significantly higher backlog than at the same point of the prior year and there has been a strong increase in sales activity, reflecting improved conditions in all of our markets... We expect to report revenue growth in both the Irrigation and Industry segments for the full year compared with 2020 and to continue to drive improvements in the efficiency of our operations, subject to no further unexpected disruption arising from the pandemic.
Additionally, with our strong financial position, the Board intends to explore acquisition opportunities to accelerate our growth.
Conclusion
Since the end of 2019, Amiad has focused on improving its operations, with a particular focus on efficiency. Covid may have accelerated this, as well as prompting some cost mitigation measures.
In addition, the financial position of the Company was strengthened through raising gross proceeds of $21.8m via an open offer and a subscription by existing shareholder FIMI Opportunity Funds. The outlook also sounds quite promising.
Operationally, this sounds good but I’m drawn back to the track record of limited consistent growth. The spread is brutal at 1,053bps and the free float is tiny at 23.78%. I’m undecided here, it’s probably worth a closer look given today’s results but there are a couple of risks to take into account as well, and the lack of longer term growth keeps me on the sidelines for now.
Spectra Systems (LON:SPSY)
Share price: 171p
Shares in issue: 45,429,766
Market cap: £77.7m
Spectra Systems (LON:SPSY) was pitched to the Investment Club a few months ago - here’s the write up.
It’s a fascinating company, with loads going on under the stewardship of founder, president, CEO, and 5% shareholder Nabil Lawandy. The group’s a world leader in providing security technology materials for use in banknotes, product authentication, and gaming.
The group has grown to occupy a strong position in the currency and document authentication markets, where it has established a track record of R&D and product innovation and attracted both government and corporate clients. These factors are now allowing Spectra to generate some attractive returns on capital.

Banknotes are the group’s bread and butter, but Spectra’s solutions are also used in other products such as energy drinks, shampoo, wine, spirits, coffee and tobacco. Meanwhile, its security software is used by international lotteries and the group is an associate member and active participant in the North American and Provincial Lottery Association (NASPL) and the World Lottery Association (WLA).
Finally, Spectra has recently started investing in early stage companies where it feels it can gain an edge with its technology capabilities. Its first investment, recently announced, is Solaris BioSciences.
Audited results for the year to 31 December 2020
Highlights:
- Revenue +11% to $14.675m,
- Adjusted EBITDA +16% to $6.357m,
- Net income +18% to $5.124m,
- Adjusted earnings per share +14% to 11.9c,
- Cash from operations -3.7% to $5.124m,
- Net cash position steady at $14.038m (with $1.099m of restricted cash and investments); no debt,
- Annual dividend of 9.5c per share,
- 645,000 shares bought back in the period.
Compared to the disruption witnessed by other companies over the past year, the fact that Spectra can sail through and maintain its double digit growth rates is impressive. Growth has been consistent over the past few years as well.

Spectra’s exposed to some big markets and has plenty of runway for growth assuming it can continue to successfully commercialise its products and technology.
As ever with this company, there’s a lot going on. Notable developments in the period include:
- Execution of a contract for Phase 1 development work for sensor technology development for a central bank,
- Completion of three quality control systems for a central bank print works,
- Execution of a new contract with a central bank to enhance existing authentication sensors,
- Strong sales of optical materials for K-cups (coffee cartridges),
- Launch of a new phosphor which outperforms existing leading materials and undercuts them on price,
- Successful production of fully printed, machine-readable polymer banknotes with covert taggants,
- Ongoing Covid-19 studies on Aeris banknote cleaning decontamination efficacy at a major University with Bio-Safety Level IV facilities,
- Completed development of a Covid-19 decontamination system to disinfect 5,000,000 notes in one to two hours,
- Six lottery contract renewals for the Secure Transactions Group, and
- Expansion of the patent estate with the granting of 11 new patents for authentication technology.
Conclusion
This looks like an excellent performance given the global disruption witnessed in 2020 and suggests Spectra’s business is quite resilient - although the group does add that revenue and profit growth was driven by larger demand from one central bank customer.
There’s a possible risk here in that a material amount of business can come from relatively few clients.
But Spectra has long and collaborative relationships with central banks and banknote suppliers, and sees plenty of scope to introduce more advanced, value-added products into these markets. It’s got great visibility into its customers' needs.
Banknote revenue streams are stable and help fund the group’s R&D and product pipeline, enabling the company ‘to continuously innovate with products that could lead to more explosive growth in the coming years.’
It can be challenge visualising the scale and nature of the opportunity here due to the multiple markets and avenues of research, but putting the growth potential to one side for a moment and focusing on the present there are reassuring signs that management is looking out for shareholders with share buybacks, dividend payments, and steady, profitable growth.
The company says it has excellent prospects for maintaining strong earnings in 2021 and beyond and is extending the share buy-back authorization of up to 4,500,000 common shares through the end of March 2022. A total of 846,000 common shares have already been purchased and retired under this authority.
Nothing’s ever a given in investing, but there has been a lot of talk about finding stocks with compounding potential recently and I think Spectra is a worthy candidate in that discussion. It’s got proprietary tech, strong cash generation, consistently high R&D levels, and it operates in large markets.
Given the above and the high returns on capital it is now racking up, there’s plenty to like about Spectra Systems at the current share price in my view.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

111 comments
Spectra Systems (LON:SPSY)(I hold)
I've just read through the FY20 Annual Report and based on the below I'm wondering whether the G7 banking customer is the US Federal Reserve.
It surely must be as:
If correct, that's:
a) quite impressive, and
b) a nice safety net to have when predicting revenues several years into the future.
Cheers
A
A bit OT - but to carry on the conversation sometime back with regard to the subject of whether the new covid mutations will be an ongoing issue and whether there is any possibility that covid could be wiped out in the next 2-3 years (i would love it if that happens - said in the best kevin keegan voice) - Dr John's Capbell's latest video sort of touches on these questions to a miror degree - he is does have some hope we could eradicate or get down to background levels covid within 2-3 years - he isn't exactly nailing his flag to the mast here - and i don't blame him as the truth is its all speculation as to how long covid will continue to be a thorn in our side.
https://www.youtube.com/watch?v=h9irEbq43Qc
Recent pop-science report that two Cambridge researchers found encouraging evidence that ongoing somatic hypermutation amongst our B-cells makes our immune system better able to identify and suppress new variants of the covid https://theconversation.com/co...
As an aside, I did several central London parks today. Came across many large groups of peeps, including many youngsters, and most takeaway outlets had queues. A marked contrast to last spring when there seemed a real element of fear and suspicion aboard. Perhaps 'the wisdom of crowds' is telling us the virus is well in retreat; after all, these front line people will be well aware how many in their friendship groups are falling sick (or not).
Hi Paul, keep up the good work. I read your reports regularly.
Regarding the bod selling shares in VLG, back in Dec.2020, it states in the RNS that the same amount of shares sold were bought by the wife and husband of the sellers, making it basically not sells, but transferring to their partners.
re Venture Life (LON:VLG) director interests - not so - that December RNS is supplementary to the 20th November one and shows the same interest (that includes spouse) %. Here is the November sale:
Following exercise of the EMI Options and sale of the Sale Shares, the Sellers (and their families/ pension plans) will retain the following interests in the Company:
Interests as the date of this Document Interests at Admission
No. of Ordinary Shares % of issued share capital No. of Ordinary Shares % of issued share capital
Jerry Randall 3,769,729 4.5% 1,884,865 1.5%
Sharon Daly (née Collins) 2,019,953 2.4% 1,009,976 0.8%
Gianluca Braguti 7,085,459 8.4% 3,542,730 2.8%
Edit: I spent ages getting that table properly spaced but Stocko will not have it and every sequence of spaces has been reduced to one space. Grrrr.
Just to mention that Spectra Systems, Tandem,SCS and many more will be featured in the March results round up in the MelloMonday show in two days time. It will be a really packed five hour show but here are the timings....
Programme for the evening
5.00 pm Introduction to our Mello Roadshow
5.05 pm Alun @MrContrarian reviews the Mello BASH companies
5.10 pm Company presentation by Judges Scientific
5.40 pm How to join corporate fundraisings with Primary Bid
6.00 pm Company presentation by Filta Group
6.30 pm Leon Boros interviews Peter Harrison from Bioventix
7.00 pm Company presentation by Digital Box
7.30 pm A March results round up with Paul Scott, Gordon @glasshalfull & Alan Charlton
8.00 pm Company presentation by Get Busy
8.30 pm Mello BASH with Alan Charlton, Alex Schlich, Richard Crow (@RebelHQ) and Kevin Taylor
If you have not been before the webpage is here Https://melloevents.com/mellomonday-29th-march/ Do use this code for a half price ticket MMStocko21
SPSY is a company I view as being undervalued and very much under the radar. DNLR is probably ahead in the latter because it is well known.
My view on the phenomenal results can be read here.
I was also lucky enough to be invited along to the WHI presentation on Thursday. Nabil was his usual self, confident and very bullish. The buybacks are likely to be employed as a strategy again because he argues the share price should be much higher. Yeah, I know, shock horror! He is right, though.
I'm pleased Nabil made the same point I made about physical cash. There is a wrong perception society is becoming more and more cashless when the truth is the opposite.
Spectra Systems (LON:SPSY)
Nothing’s ever a given in investing, but there has been a lot of talk about finding stocks with compounding potential recently and I think Spectra is a worthy candidate in that discussion. It’s got proprietary tech, strong cash generation, consistently high R&D levels, and it operates in large markets.
Given the above and the high returns on capital it is now racking up, there’s plenty to like about Spectra Systems at the current share price in my view.
I am a little baffled by this company. As you rightly point out Jack it is facing many large markets, with many fingers in many pies and yet the turnover has barely moved up from 2015 to date? (£14.1M - £14.7M).
Meanwhile the s/p seems to have been going more or less sideways for the past 3 years or so despite ratios etc that are all moving upwards at a gallop e.g. EPS, Margin, ROA, ROCE, ROE, Cash Flow, FCF.
With the P/E (ttm) ratio at 22.7 I feel this share is probably slightly on the dear side if anything - although I note it has been higher historically. Is this looking like a 'jam tomorrow' story or am I being too harsh (I HOLD).
Spectra Systems (LON:SPSY) (I hold)
"the turnover has barely moved up from 2015 to date? (£14.1M - £14.7M)."
I'm sure others here know more than me, but from a quick look at the 2016 Annual Report the decline in 2015 vs 2016 revenues was due to a switch in revenue sources:
"In-house manufacturing was in effect for the last quarter of 2016 and will continue for the duration of the contract to beyond 2026. Both of these revenue streams are sales of consumables to large central bank end customers, as opposed to more intermittent hardware revenue, and are therefore expected to continue to fuel profitability in the long term."
This explains why even though revenue stepped down from 2015 to 2016, net profit actually went up, and both revenue and profit have continued to rise since then.
With the benefit of hindsight, what management said in 2016 has turned out to be quite true.
Fingers crossed going forward.
Cheers
A
Sorry...forgot to say the K -CUP comment below refers to Spectra Systems (LON:SPSY) . The market being that they code the genuine pods so that Keurig can modify the machines to stop users buying cheaper 'me-too 'pods or even counterfeit pods which are on the market.
If you think that one through, the possibilities are endless
I need to check the recording from Thursday's presentation. I think Nabil stated K-Cup sales were c$400k and growing.
SPSY Zulu report!
Paul and Jack - thanks so much for all the write up this week, there's been so much I dont know how you get through it all! It's much appreciated. Hope you have a great weekend.
UIPATH announced plans to float on the US markets and have filed their S1. £GROW have about 150m wrapped up in this and depending on the success of the float could bring some more upside to them. I am sure they'll make an announcement at some point tonight or Monday
I am a long term holder in GROW
Nerd of the day comment... for the uninitiated....a K Cup is a coffee pod rather like a nespresso pod but double the size. They are made for Keurig Inc.. The product is usually a desktop machine and produces Starbuck sized coffees, in fact they even market a Starbucks licensed pod. They are the coffee market leaders in the USA ! They are BIG. They tried a uk launch but couldn't move enough people away from Espresso based drinks to Filter coffee drinks. You can still get them here via companies like https://www.coffeesense.coffee (i hold)
They’re also rubbish.
Well, I might be being unfair there. The hotels I go to with the massive Nespresso capsules tend to provide poor quality coffee. But I find that to be American culture generally, never mind the quality, look how much you got.
#SPSY has all the ingredients to become a 100 bagger.
So misunderstood at the moment.
Spectra Systems (LON:SPSY) -
When was the last time you used a bank note?
I don’t think I have used one since before Lockdown 1!
I also haven't used a bank note in a long time but I'm also a big believer in the prospects of Spectra Systems (LON:SPSY) . Profitable and with many products in the pipeline, there's plenty to get excited about. A potential deal with Apple or other major brands for their smartphone-readable packaging films might also increase interest in the company and lead to greater product demand plus a higher share price.
Low bank note usage by many/most of the UK public has proved to be a dreadful indicator of the demand for bank notes... ...which both De La Rue (LON:DLAR) and Spectra Systems (LON:SPSY) regularly confirm is growing strongly.
Spectra Systems (LON:SPSY) So who is using banknotes? Why the demand?
I have not used any for about 1 year, before that I was using them all the time.
Is it because they are printing new notes, £5, £10 and £20s?
Or are people storing them under the mattress?
Hi Herbie,
I'm afraid your UK perspective (and others here) is partly what is holding back £SPSY. The truth is that there are over a billion people on the planet for whom cash is still very important and digital banking is either out of reach or not used. So whilst the demand for banknotes is slowing in the west it is growing elsewhere.
This report may help develop the understanding as to what is going on https://www.smithers.com/en-gb... and includes the story that De La Rue (LON:DLAR) is investing $14m in a Kenyan bank note facility.
Nabil the CEO wrote a long eloquent piece about the bank note market, last year or the year before. I can't seem to find it now but it helped explain the market in great detail.
That being said, Spectra Systems (LON:SPSY) have lots of irons in many other pies including Trubrand which has great potential so to focus on them as only a banknote security company misses the point.
Hope that helps
Cheers
Francis
Spectra Systems (LON:SPSY) I read that link but it talks about "The slow growth forecasts are symptomatic of disruption in the industry" Also: " Stricter fitness criteria can act to reduce the lifecycle of banknotes, forcing issuing authorities to produce higher volumes to meet demand. In response, demand has increased for durable substrates in the form of polymer, composites and paper treated with varnishes and coatings that increase the lifecycle of a banknote. The net effect of longer-life banknotes and shrinking demand is a decline in the number of printed banknotes annually, at net lower costs."
Not sure when that was written, was it before Covid?
It is not just in the west that notes are declining, in many Asian countries also such as China, India and Thailand etc.
Yes Africa is where some growth is but Covid has changed rapidly people spending methods. Note some countries charge for ATM use unlike the UK, so even more reason not to use cash. More things/transactions are being done online, so more reasons for not using cash.
I only time I will use cash now, is when I go abroad but even that will decline, as more places take credit/debit cards.
Exactly, as you say, western society may use less cash due to the growing use of digital wallets; cash is still king in many countries because there is a lack of banking access to so many people worldwide. Nabil gave a good overview on this topic on Thursday. Nabil appears to have realised he needs to hammer home this message to the investment community that seem obsessive about cryptos and digital wallets.
Exactly, as you say, western society may use less cash due to the growing use of digital wallets; cash is still king in many countries because there is a lack of banking access to so many people worldwide.
If that's the argument for investing in Spectra Systems (LON:SPSY) I'd be a bit worried.
The lack of banking access worldwide is a bit of a myth. Pretty much anywhere you can have a mobile phone you can have electronic payment - take MPesa in Kenya, which is run by the telco, not the banks. Well over 80% of the population of sub-Saharan Africa have a mobile phone. The direction of travel is inevitable, it's just a question of how long.
Despite this the number of banknotes in circulation continues to rise - even in the Eurozone, which is plentifully supplied with other payment methods. The so-called paradox of banknotes - cash in circulation is increasing while cash transactions are decreasing - is a puzzle for central bankers. Roughly, the answer lies in undocumented transactions (person to person, cash in hand, etc), a tendency for people to store cash under the bed and the use of strong currencies in third-countries - e.g. the use of the dollar in Zimbabwe.
Broadly the market for banknote production is increasing at around 2.5% a year, with Africa the major contributor at over 4% growth. Globally, as more durable polymer notes come into production then the replacement rate will drop. If we peer forward dimly then it's hard to believe that we'll still see growth in cash in circulation in ten years time.
Despite all of this I think Spectra Systems (LON:SPSY) ought to have an excellent future. Banknotes will continue to be produced, albeit in smaller numbers, while the market for security methods on all sorts of assets is going to explode. As I noted elsewhere on Stocko this week, the tokenization of physical assets is likely to be one of the biggest trends of the near future, and I can't see why Spectra can't have a major role to play in that area.
timarr
timarr6:50 am
Exactly, as you say, western society may use less cash due to the growing use of digital wallets; cash is still king in many countries because there is a lack of banking access to so many people worldwide.
''If that's the argument for investing in Spectra Systems (LON:SPSY) I'd be a bit worried.''
You need not worry. I was merely agreeing on a single point.
Here is my reason(s) for investing in SPSY.
Spectra Systems (LON:SPSY)
It is not just western countries, look what is happening in Asia, which has a far larger population.
Also with the new type of polymer banknotes these will last longer. I think part of the reason for a rise in banknotes is the issuing of new notes in recent times. Also there are probably many people like me, who have them in their wallets along with the moths, mine have been in the wallet for a year.
That is even before you start considering cryptos currencies.
(LOD:SPSY) They are printing notes for all around the world not just UK. In fact the uk notes are probably a very small percentage.
Low bank note usage by many/most of the UK public has proved to be a dreadful indicator of the demand for bank notes ...which both De La Rue (LON:DLAR) and Spectra Systems (LON:SPSY) regularly confirm is growing strongly.
I think "strongly" is a bit ... well, strong. Bank note use is growing globally, though, albeit quite slowly and is expected to start to reverse in the coming years. It's mostly in developing nations and a few places underserved by modern payment systems, like the USA.
The main drivers against cash use are the increased availability of alternatives - contactless cards and digital wallets mainly. Much of the Nordics are virtually cash free for instance, the use of cash in China is falling rapidly and cash use in India dropped after the demonetization drive in 2016. At some point in the next decade we'll see the introduction of Central Bank Digital Currencies, which will also mitigate against cash use. Most governments want to reduce cash use, and are enacting policies, often not overt, to support that direction of travel.
In addition the increase in polymer notes reduces the need for replacements, and that'll have an impact as they roll out more widely. There are also clear age related trends - older people tend to prefer cash but that, clearly, is also a declining market.
That said, bank notes will be with us for a long time so it'll remain a valid business, albeit one that's likely to see decreasing volume over time. Ideally you'd really want to see companies in this space diversifying in preparation for a contracting market. The alternative is looking to take over competitors to shrink the supplier base.
So, yes, it's still a perfectly viable business area but I'd be careful about future growth prospects.
I hold Spectra Systems (LON:SPSY).
timarr
Good example of realising that personal exper is not always indicative of wider trends!
This ft article recently says EU banknotes increased 12% during 2020! https://www.ft.com/content/c8c...
You're missing the point entirely. Go and have a deep dive over the weekend and it will all become clearer.
I have tried to buy Spectra Systems (LON:SPSY), but through HSBC InvestDirect but without success;
" the security selected is not available for investment via this service"
...any ideas please?
It is a US company listed in London, some brokers may not want to trade it. You will need to complete a W-8BEN form.
It is available on HL and IG but it is fairly illiquid.
Best way to buy Spectra Systems (LON:SPSY) is in a SIPP. No W8 form to fill, no headache of US withholding tax on dividends.
But some brokers won’t touch these types of Shares in a SIPP or won’t recover the dividend tax.
Similar issues with Somero Enterprises Inc (LON:SOM)
A SIPP is more tax efficient but HL for one will not let you buy any US companies without a W8-BEN form.
It's a fairly trivial effort to fill one out every couple of years but people are disproportionally put off. One for Daniel Kahnemann or Richard Thaler to explain.
Spectra Systems (LON:SPSY) in a SIPP
That's a top tip by dahokolomoki, I bought for the first time a month or so ago via A J Bell. To be honest I didn't even realise there was an issue with it being a US security, the deal went through as it would for any other share. Even the spread wasn't too bad (or more accurately the deal was inside the quoted spread, not too far above the mid-price). Perhaps that's because it was a starter position (<£5k).
Thanks to all for such an excellent debate on Spectra Systems (LON:SPSY) this really does show the breadth of knowledge in the Stockopedia community. And thanks as ever to Paul and Jack, the quality and quantity of analysis this last week has been phenomenal. I truly don't know how you do it.
Venture Life (LON:VLG) was David Thornton's pick in his 2020 round up. Hear him cover it here at 11m30s.
Yesterday, Cvs (LON:CVSG) gave a interim results presentation to analysts, here. Over 3m households have bought a pet during lockdown, their new client registrations are up 17%.
Beyond this, this week we have published results presentations for:
Tandem (LON:TND) FY20 results
Bonhill (LON:BONH) FY20 results
Eagle Eye Solutions (LON:EYE) H1 results
Somero Enterprises Inc (LON:SOM) FY20 results
£LCM H1 results
Last week results presentations for: Emis (LON:EMIS) FY20; Empresaria (LON:EMR) FY20; Kape Technologies (LON:KAPE) FY20; Sthree (LON:STEM) Q1 TU; Brand Architekts (LON:BAR) H1.
Others: Samarkand (OFEX:SMK) IPO; Parsley Box IPO and Begbies Traynor (LON:BEG) placing and acquisition.
Find them all at piworld.co.uk
Next week we have two results webinars:
Personal Group (LON:PGH) FY20 results webinar: Tuesday 30.3.21 at 11.30am. Register here.
Ra International (LON:RAI) FY20 results webinar: Wednesday 31.3.21 at 11.30am. Register here.
Finally, we were thrilled PIWORLD was awarded Best Investor Relations Content Provider in the ADVFN International Financial Awards 2021, this week.
Another day, another RNS from Open Orphan (LON:ORPH) (I hold). This RNS slightly more material than some. But you have to laugh at Finncap, the house broker. Their note this morning includes:
"We leave forecasts unchanged,but with substantial room for upside to our target price of 28p." 13% below last night's share price.
I've noticed down-targets before and wondered what the hell that's all about.
Basically the target is what the broker thinks is a fair price based on numeric criteria which they sometimes spell out. When that goes negative it simply means that the market has got ahead of events.
In the case of finnCap (access is free if you register with them) and Open Orphan (LON:ORPH) they last did a detailed note and raised their TP to 28p on 20/10/20 when a major contract was announced. In that note there was great detail on how that figure was calculated summed up as "a sum-of-the parts approach to valuation and applied minimum and maximum EV/Sales multiples to each revenue stream, reflecting both growth potential and EBITDA margin....."
Since then there have been no trading/results announcements, just a tsunami of RNSs such as " First volunteer dosed in intranasal COVID-19 vaccine clinical trial ". Did that really warrant a full RNS?
finnCap do not recalculate everything when they do a short 1 page note as this morning but they did indicate that when they do recalculate there was substantial possible uplift of target 28p "as this excludes potential monetisation of its non-core assets (eg. Imutex and PrEP Bioharm)".
It is usually good news when an RNS carries the weight of a nice cash figure like £7.5m, others will carry a £10m figure, or so we are told, when you are the world leader with a significant moat, you can do this. There is much more to come from Open Orphan, as I have attempted to spell out here!
Here's hoping Invesco have closed the tax year-end book on this; thus release the brakes.
Venture Life (LON:VLG)
I wrote yesterday "At the time of the P.O.O. @ 90p in November we were teased with details of 3 acquisitions in progress "Project Vulcan" , "Target A" and "Target B". This morning all we get is "We are continually reviewing opportunities in the market place and we expect to complete on some of these during 2021".
Let's see what they have to say on Monday.
Acquisitions are key here - not just in using that cash pile from the placing. My main reason for buying this was the potential at the factory in Italy. It has a lot of spare capacity meaning that if the production of an acquired product is transferred to there it leverages all the fixed overheads.
Here are my SCVR heat maps for today (prices as at ~9:00am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my heat map thread for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Venture Life (LON:VLG)
Paul - you say "Reported EPS is 2.74p, but the broker notes use their own calculations, making adjustments, e.g. Cenkos adjusts this up to 4.5p, as does N+1, so I’ll work on the broker adjusted figures. It would be more helpful if the company could in future be consistent with the brokers, and also publish adjusted EPS figures".
Well, the brokers did get their adjusted figure from the report. In the most dreadful way of laying it out the company put adjusted EBITDA but basic EPS in the highlights. It is not until we get to Note 5 to the a/cs that we find:
This had me in a panic before 8 a.m. yesterday as I could see the brokers' estimate (they use adjusted figures) of 4.43 on the stock report and 2.74 in the RNS "highlights".
Thanks sharw,
Really useful information, pointing out that Venture Life (LON:VLG) disclosed adj EPS in note 5. I didn't get that far through the RNS, as I don't have time to read the whole thing, or I'd only be able to cover 1 company every day!
The table you posted above is also useful in that it shows a fair bit of potential dilution is on the cards!
Regards, Paul.
Aviva (LON:AV.)
Off topic with the large caps but the transformation at Aviva appears to be nealy complete now - they have sold the non crown jewels crown jewels in just 8 months for £7.5 billion cash proceeds (market cap £15 bill).
It will be interesting to see if this strategy will add sharheolder value or not - the only presumption i have is that the worst case downside scenario re solvency worries has completely vanished or at least massively diminished by them selling these "non" (hopeffully) crown jewels.
They quote IFRS net asset value per share of 493 pence compared to shareprice of 400p - i have no idea if these are real tangible number or not but better that number than soething lower.
would be interested thoughts of people who undertstand financials of financial companies as to whether there is still potentially untapped value to be outed or whether its likley taht there never was any untapped value i the firstplace. i am not generally a fan of quickfiresales of trading entities that earn your crust - i am hoping here though this route is specifically the best oiption for me the shareholder - that would be a nice thought :)
There are no Crown Jewels at Aviva (LON:AV.) It is a collection of rubbish businesses and while they may be selling off the worst that does not mean that what is left is any good. It has probably been the worst performing share in the FTSE100 since it was formed via a merger between Norwich Union and CGU about 20 years ago. Why? Because it’s businesses are low quality. Readers should also note that life insurance accounting is not compatible with the screens that are used on sites like this and therefore what optically may appear to be cheap is actually anything but. Put simply, life insurance earnings are accounting profits that don’t translate into hard cash for shareholders. Aviva is one to continually avoid and those who are attracted by the dividend yield should look at the companies track record of cutting the dividend which must be among the worst in the FTSE 100.
Cannot disagree that £av and life insurance generally been terrible investment over last 20 years, but as it stands today feel the sector is very well capitalised and should easily support dividends going forward, on top of additional release of capital either for reinvestment or return to shareholders. The sector faced big headwinds over last couple of decade - falling interest rates increasing their liabilities, credit losses from the financial crisis and more onerous regulations requiring ever more capital. However, interest rates can't really go much lower, while regulations could potentially be eased post Brexit. Asset portfolios now very robust and very little exposure to riskier bonds or equities. £av still well below book value so see good value there.
What do you think of the discount rate they use to value their life insurance liabilities and the actuarial margins within their reserves? Knowing the answer to those is key before opining on how well capitalized they are.
Just my view, but I think the assumptions they use to model future liabilities and the amount capital they are required to put aside is extremely prudent, hence I would expect excess capital to be released as liabilities unwind.
On £AV. Jefferies predicts Aviva will return capital to investors in the first quarter of 2022. The market consensus is for a share buyback of between £3bn and £4bn. The reason for the delay is that it will take a while for all the approvals to come through for the business disposals.
I note the earlier comment about the quality of the business but Aviva does seem to trade at a large discount. My reading of today's statement "Uplift in IFRS net asset value of £1.8 billion, representing a 46 pence per share increase from 31 December 2020 IFRS net asset value per share of 493 pence" is that the NAV (after the disposals) will be about 540p against a share price currently around 400p. Legal & General (LON:LGEN) arguably a higher quality business trades at 1.6x NAV per Stocko so there appears scope for Aviva (LON:AV.) to re-rate to NAV at least.
Amanda Blanc, the newish CEO, seems to be taking decisive action following years of inaction by her predecessors.
Aviva (LON:AV.)
Thanks for your comments all , i guess i will probably just hang on here until the dust settles , or the price moves materially upwards or there is any adverse trading news.
I have always been aware that the quality metrics of the busines have not been rated by the market as being nay good, and i have been aware that i dabble at my own risk - i think when there were credit issues within the EC Aviva did seem to have some potential adverse nasties.
I have held Aviva a couple of times in the last decade and have been lucky enough to buy both times in the 300's when i thought the company was trading at a low p/e - so more bottom fishing in hope than any cunning plan here. I must admit this time i did buy back in for the dividend 18 months back and the plan didn't really go to will with the dividend being chopped. I did have sense to back 2 horses when i invested in Aviva and i also bought Legal and General the sme day - and that has turned out to be the better investment over the last 18 months - so it does kinda backup the last of quality or market faith that does exist here - lets just hope this dog has its day and soon :).
Amanda Blanc, the newish CEO, seems to be taking decisive action following years of inaction by her predecessors.
Since Blanc took over in July last year Aviva (LON:AV.) has sold subsidiaries worth £7.5 billion. The entire company was only capitalised at about £9 billion at the time.
You don't always have to invest in quality companies to make money on the stockmarket.
timarr
Good morning Paul ,
Robinson (LON RBN) I Hold - figures of yesterday looked good and with the news of property disposals. If you have time would you like to comment.
Hi rkells,
Robinson (LON:RBN) is terribly illiquid, and small, so we're trying to focus a bit more on slightly more liquid small caps.
Looking at its results now;
Overall - this looks quite good!
Regards, Paul.
Thanks Paul
Good morning Paul and Jack, if its a slow day I'd love to get your analysis of Spectra Systems (LON:SPSY) results from Monday. I know Jack has looked at them in depth recently so it would be great to get his thoughts about their FY results. And judging by the upticks I and other posters got on Monday, this would be appreciated by your readers.
cheers
Francis
Many thanks Jack, I very much appreciate the review. I agree there is risk concerning customer concentration and, as we saw with Ixico (LON:IXI) this week, that can be a problem. However the nature of Spectra Systems (LON:SPSY) business means there are relatively few customers for its core banknote products and time has shown that they are very sticky contracts. And the more they diversify into new fields, the less of a problem that will be. I hold a shedload and will patiently wait for their SP to appreciate and collect the nice annual dividend in the meantime.
Have a great weekend
cheers
Francis
Hi Francis,
I totally agree with you. The core G7 central bank customer has a 20+ year relationship with Spectra Systems (LON:SPSY) - and it is this customer that they are in the process of developing the new sensors for at present (into phase 2 of the contract). This contract looks likely to bring $30+m revenue from sensor sales and then servicing, plus subsequent product (I would assume). So you have a core customer who is likely to still be a customer in 10 years time, as that is the life of these sensors.
The banknote materials business has had its best year ever, and they are expecting these revenues to underpin existing forecasts to 31/12/21.
In the meantime they have a choice over whether to use the free cash flow to pay dividends (getting about 4%), buy back shares (4.5m is about 10% of total share count) or invest in new projects (like Solaris).
The only thing that worries me is the "black box" nature of the business, due to security / confidentiality, meaning it is more difficult to really understand operations. I also note that the auditor is a very small firm called Miller Wachman LLP.
Mothercare (LON:MTC) if you get a chance please Paul - i saw some comments yeteday that the business model here is now different from what it was so would be interested to here your thoughts. The brand name here probably isn't what it was but it is still a brand that should be able to sell itself really with its nice simple uncomplicated name.
Yes, I second this. I was trying research this yesterday and couldn't find too much info.
Venture Life (LON:VLG) (no position)
Hi Paul
Thanks for the write-up today.
---
From memory, I believe there have been a couple of acquisitions over the last 12-15 months, so this will have fuelled that revenue growth. I couldn't find revenue numbers attributed to these acquisitions.
I recall doing a "control-F" for the word "organic" yesterday and found no figure for organic revenue growth - suspicious.
---
I also noted that Dentyl revenues actually dropped from H1 (£2.8m) to H2 (£1.5m). This is despite more shelf space in the UK with some big names + the mega €165m 15 year deal with a Chinese distributor.
I've remained wary of this company (to my detriment) but for me there are too many missing puzzle pieces so I will stay on the sidelines.
Cheers
A
abtan - I too am wary of Venture Life (LON:VLG) (I hold). Not just Dentyl, despite the hype about use by Cardiff University in a trial for use of mouthwash on covid, but also their hand sanitiser DISINPLUS which sold £3.2m in H1 and £0.4m in H2.
Never mind, Dentyl go a product placement on Easteders the other day:
Hi Sharw,
VLG - I spoke to management several times last year.
There is only £1m in the forecasts for handwash this year.
I did have a very large position which I sold after the December RNS for the placing etc....
Boohoo (LON:BOO)
Nice piece in the times - i take confidence from the following quote.
Reaney said that while the number of suppliers had been reduced, Boohoo was giving more work to bigger factories. “One supplier I met with yesterday has taken on another floor in the building and an extra 50 workers . . . Our UK suppliers are growing in line with the volumes we are seeing,” he said.
It was being speculated in yesterday in the comments section yesterday that Boohoo may lose their edge if they had to source more goods from overseas and would lose their ability to get their product to market quickly as they did quickly. I think boohoo have been in the game long enough and they have had enough time to see these changes coming so that hopefully there is no material "long term" impact from these changes other than the onvious slight hit to margins i woudl expect - so hopefully its mostly a shifting of the decks behind the scenes rather than them losing their competitive edge here by not being able to get new designs to market quikcly. The comment above do sort of backup my thoughts that the good skilled workers will not be going anywhere and its brillaint if they are brought within a legitimate orginiation where the minimum wages are being paid and taxes are more likely to be paid by those buisness owners. Being frank i suspect a lot of these previously hidden workers may have been scamming the system** in conjunction with factory owners scamming the system - so i for one am happy if everything is more legitimised. Hopefully the marginal increase in costs to boohoo is manageable
** I have got zero sympathy for anyone who defrauds the benefits system end of.
Boohoo (LON:BOO) (I don’t hold). There’s been a lot of debate about the merits of supply chain onshoring vs continued global integration during the pandemic. While I’m generally sceptical of the onshoring perspective (I would be as a former trade lawyer), I do think there are merits in the fashion retail industry and Boohoo’s case in particular.
First, with Germany the latest nation to subjugate trade policy to broader policy objectives- with tariffs/barriers now dependent on the human rights and labour standards upheld in third party company’s supply chains- we’re seeing a world in which vertical integration becomes a bit more attractive. The EU has appointed former Belgian Justice Minister Didier Reyners to consider a similar 27-member state wide EU proposal, which suggests the era in which trade policy and social policy imperatives were compartmentalised is under question.
Second, the Commission’s proposal for a Carbon Border Adjustment Mechanism (CBAM), which is designed to impose higher tariffs on companies operating in nations pursuing lower greenhouse gas emissions, would impact supply chain imports from developing countries the most. Even if these go direct from developing country to UK, rule of origin requirements could catch Boohoo out.
Third, the EU-UK trade agreement has not included allowances for “diagonal cumulation” in calculating Rule of Origin calculations (under EU rules, 55% of a product’s value needs to have been produced in the UK if it is to benefit from the EU - UK zero tariff regime). This 55% requirement would have been a lot easier to meet had the EU allowed for “diagonal cumulation”- this is the fancy term for saying that supply chain imports to the UK that come from a third party country with whom both the UK and EU have a trade agreement wouldn’t be counted as “foreign” as part of the 55% calculation.
I saw comments from Sirius Real Estate (LON:SRE) management that they are seeing strong demand in their German business parks from Mittelstand companies bringing production back home to Germany. It will take a lot to reverse the huge amount of work that has flowed to China.
I think you need to look harder at what Germany is doing. We only need to look at Nordstream 2 to understand Germany’s continued ‘beggar thy neighbour’ approach to trade.
It’s broadening it’s ties with China and Russia, so all talk of human rights abuses are second to its economic aims. Further, I don’t see how Germany can control tariffs/barriers as the single market is controlled centrally.
And if it is able to control tariffs and barriers outside the single market, surely this is just further evidence the single market is a sham.
And if it [Germany] is able to control tariffs and barriers outside the single market, surely this is just further evidence the single market is a sham.
Well, as it's not true does that mean that the single market isn't a sham?
What Germany has done is introduce a law that means they can fine German companies up to 2% of their global annual turnover for labour or environmental abuses in their global supply chains:
https://www.metals-hub.com/blo...
In the context of the EU trade policy is an exclusive EU competence - so the EU, not member states, legislates on trade matters and handles international trade agreements. Which is why, despite attempts by the UK to negotiate directly with Berlin and Paris, the Brexit withdrawal deal was eventually negotiated by the EU, with Ireland's interests put front and centre. And that, of course, is now causing serious issues for the UK government.
However, in general, the EU is seeking an expansionist trade policy post-Brexit - the Japan and Mercosur deals and mooted cooperation with China being the most visible signs of that. Quite how human rights fits with the latter is an open question for all Western liberal democracies, ours included, as we struggle to balance the need to maintain trade relations with the world's second largest economy with protests against the human rights abuses that are rife there.
The UK, of course, faces a unique issue over Hong Kong. But no doubt sending our aircraft carrier to float around the China Sea carrying Union Jacks and US planes will make China think twice about that.
timarr
The single market is a sham and applies solely to goods. Services are explicitly and deliberately excluded, though now that London is out of the way I expect Paris and Berlin will be more amenable to forcing through alignment.
I can give you a real world example. I had to do some consulting work near Paris in 2019. It took over a month for the company’s agents and the French authorities to clear all the paperwork to allow me to work short term in France.
The EU hasn’t put Ireland’s interests “front and centre”, it has put its own short term revenge plan “front and centre” and is using Ireland as a pawn as evidenced by the humiliatingly badly handled partial closure of the Irish border when they didn’t even bother to do the courtesy of phoning the Irish government to let them know.
But in the end though, the original premise that Germany are raising tariffs and barriers is false, and I was responding to a misleading argument. Thank you for clarifying that (although they are in effect increasing non tariff barriers but only for their own companies - I guess as long as they don’t enforce the same standards on all goods they can act unilaterally).
Some minor corrections - one of our aircraft carriers, with UK aircraft.
The EU hasn’t put Ireland’s interests “front and centre”, it has put its own short term revenge plan “front and centre”.
In terms of Ireland specifically - no, this isn't about revenge. It's about the impossible challenge of figuring out how to handle the UK leaving the EU while maintaining the Good Friday Agreement which assumed that the UK was part of the EU.
The last minute nature of the Brexit deal, in which Johnson and Frost agreed to put a border in the Irish Sea is politically unacceptable to Unionists. They either didn't understand the consequence of their deal or they never intended to honour it - the latter being the suspicion of the EU.
As for revenge more generally in the EU / UK context - well, if we allow that as a premise then why would we expect anything else?
The EU was never going to make it easy for the UK as that would open the gates for other countries to look to exit - not that most countries have any desire to do so after witnessing the fiasco in the UK. And of course, Johnson and co have made it very clear that they are seeking to compete with the EU - so why should the EU do anything to aid a competitor?
All this was discussed during the long-drawn out Brexit process, it shouldn't be a surprise to anyone. But as my friends in Switzerland have taken great delight in telling me for the last 5 years - negotiations with the EU never end. This is just going to go on and on and on ...
timarr
FY results from Kenmare Resources (LON:KMR) were well received on Wednesday. 2020 was a year of transition and the company is well positioned to generate significantly higher cash flows in 2021 and a large component will be returned to shareholders via dividends. If you’d like to hear more then watch the recording of the FY results webinar here. A write up is also available on the discussion section of the Stockopedia Kenmare page.
Retail sales rose 2.1% in February, recovering some ground from a steep fall in January.
The Office for National Statistics (ONS) said sales were still down by 3.7% on a year earlier, before the impact of the coronavirus pandemic.
Morning all. RNWH. BRIEF-Renew Holdings To Buy J Browne Group Holdings For 29.5 Mln Stg. Immediately earnings enhancing. services to the water industry. More Grist to the mill. Update inline with management expectations and ahead of last years earnings not materially effected by COVID . Regularly winning new contracts. Reviewed by Roland Head this week but didn't quite make it on to his team sheet .
Renew Holdings (LON:RNWH) up nicely on its acquisition and in-line announcements. Returning to yesterday's 100 bagger theme, Renew Holdings (LON:RNWH) has 10 bagged for me over the ten years I have held. if it repeats the performance over the next 10 years it will have 100 bagged. Is 20 years a reasonable time frame to 100 bag? However I am now 76.....
My morning smallcap tweet: Egg on my face over TTG
TT electronics (LON:TTG) Immedia (LON:IME) Safestay (LON:SSTY) Proteome Sciences (LON:PRM) Assetco (LON:ASTO) Totally (LON:TLY) Argo Blockchain (LON:ARB) Rotala (LON:ROL) Open Orphan (LON:ORPH) Chamberlin (LON:CMH) Adams (LON:ADA) PCF (LON:PCF) Oxford Instruments (LON:OXIG) Renew Holdings (LON:RNWH), Idox (LON:IDOX), Stagecoach (LON:SGC)
TT Electronics (TTG) iAbra's Virolens 1 minute covid test registered for UK sale by the the Medicines and Healthcare products Regulatory Authority. "A high proportion of the commercial interest in Virolens to date has been outside of Great Britain and any revenues resulting from this interest require further regulatory approval in those territories...There continues to be a wide range of potential commercial outcomes." I'm stunned it really works. Egg on my face. That's great news. [SP=233 Cap=407m]
Immedia (IME) gets £900k (max) loan at 15% from Spirit, a property data specialist. Also wlll "work towards the possible acquisition of Sprift by the Company for a total consideration, to be satisfied by the issue of new Immedia ordinary shares, of £35m". This would be an RTO so shares suspended. Spirit had FY20 rev of £175k and lost £194k. £35m seems a fairly full valuation then. [SP=35.5 Cap=13m]
Safestay (SSTY) sells a hotel for £16m, 22% over book. "The Board believes that an asset disposal is the optimal approach for the Group to raise new capital in the current market environment." [SP=19.3 Cap=12m]
Proteome Sciences (PRM) guides FY20 pretax materially higher than announced in Jan, primarily due to higher than expected royalty receipts from Thermo Scientific.. [SP=3.54 Cap=10m]
AssetCo (ASTO) intention to change its business strategy to the development of an asset and wealth management business. Will seek authority to issue up to 100% of share capital to raise cash for acquisitions. So why did it make a tender offer for 50% of shares on;y 3 months ago? [SP=716 Cap=94m]
Totally (TLY) gets place on the regional Integrated Urgent Care Clinical Support Framework hosted by Yorkshire Ambulance Service. Worth up to c. £2.7m. Also 12-month Contract Extension with Vale of York CCG. [SP=31.6 Cap=58m]
Argo Blockchain (ARB) sticks an ESG sticker on the box by jointly launching (with another mining co) a Bitcoin mining pool powered by clean energy. "This pool will initially consist of both Argo's and DMG's hashrate which is mostly generated by hydroelectric resources." This aims to reduce the impact of Bitcoin mining on the environment. So all that hydro electricity would be wasted otherwise? [SP=209 Cap=798m]
Rotala (ROL) Mayor of Greater Manchester made the formal decision to press ahead with franchising the bus market. Co has already made a court application to subject to judicial review. Co paid £5.3m for bus assets in Manchester. [SP=33.5 Cap=17m]
Open Orphan (ORPH) it's been 24 long hours since the last RNS for Cathat Friel. This is a decent slug though - a £7.5m study due to commence in Q4 2021, with the majority of revenues being recognised in 2021. [SP=32 Cap=214m]
Chamberlin (CMH) £3.5m placing at 6p, a 14% discount to the pre-suspension price in Dec, to keep the lights on. Also FY(Mar 20) trading: rev down 21%. [SP=7.4 Cap=1m]
Adams (ADA) £562k placing and £4m OO at 6.5p, a 26% discount, to fund its investment strategy. Great to see an OO bigger than the placing. [SP=9 Cap=7m]
PCF (PCF) recent 5 months' new business volumes in line with management's adjusted targets. [SP=23 Cap=58m]
Oxford Instruments (OXIG) guides FY(Mar) rev marginally ahead of last year and adj op profit £55m to £57m. In line? [SP=1792 Cap=1030m]
Renew (RNWH) makes £29.5m acquisition which is expected to be immediately earnings enhancing and to deliver high single digit earnings accretion on a full year basis. Trading in line. [SP=532 Cap=419m]
In line: Idox (LON:IDOX) Stagecoach (LON:SGC)
Has there ever been a study of which company issued the most RNSs in a year? :)
Hi Fegger.
On the subject of RNS diarrhoea I’m not aware of any academic studies but I recall some discussion here a few years ago. I think Metal Tiger (LON:MTR) was a popular pick for being one of the worst/most prolific offenders.
Gus.
Some people are never happy. You get management that engages with investors and makes every effort to communicate and you complain that they won't shut up.
Cathal is delivering on his promises which is the main thing.
re: Open Orphan (LON:ORPH) - The RNS yesteday was that 3 people have completed a COVID quarantine prior to commencing a clinical trial. What next? Trial Director receives randomisation protocol via email? Patient liaison parks her car and approaches building?
re Open Orphan(LON:ORPH) I take it you dont have a holding then
Not been in from 9p then
Where did you park your car?
Hi Mr C,
AssetCo (ASTO) intention to change its business strategy to the development of an asset and wealth management business. Will seek authority to issue up to 100% of share capital to raise cash for acquisitions. So why did it make a tender offer for 50% of shares on;y 3 months ago?
My assumption here is that Assetco (LON:ASTO) wanted to distribute to investors the benefit of its successful litigation against Grant Thornton. By tendering for shares, the company enabled non corporate sellers to sell some shares back to the company for cash, and would be liable for CGT (or, in an ISA no tax) rather than income tax that would be levied on a dividend at probably a higher rate. If only all managements and bankers were as considerate!
Ricardo
Good morning Paul or Jack. It was a busy day yesterday. Were either of you intending to comment on the finals of Iqe (LON:IQE) from yesterday? The market seemed to be rather displeased with them to say the least. Im sure a number of contributors here would be interested in your insights. Thank you - in hope and anticipation!
Splendid idea
"Splendid idea"
If only the rest of us knew what it was.
If you follow up the treasure trail of the 'reply' chain, you'll find out! I presume you're looking at your 'unread' posts? Above each, it tells you who they were replying to.
No it does not go anywhere just back to the original comment. I’m not looking at unread posts either.
Posters should put in the company name and use the reply option.
"If you follow up the treasure trail of the 'reply' chain, you'll find out!"
Ah, sorry. I hadn't realised that this is all a magical mystery tour. If only everyone had unlimited time to play pass the parcel rather than be a bit more selective and only spend time on things that are, or might be, of interest.
It really is very easy to put £ plus the ticker so that scanners don't miss something they might actually be interested in.
Yes we could, but if I write a comment I want people to read it and understand it. Not skip it because they have to do research fo find out the context. It's easy to either refer to the company, or to include a short relevant quote from the post being responded to. So please do it, it makes reading these discussions easier and more worthwhile for everyone.
And if it's not important enought to include context then that's what the "like" button is there for.
ah, we’re back to arguments because people don’t use the new site with its far superior threading system for comments, or aren’t reading the thread as a thread.
Why we’re expecting posters to spend time rewriting something that’s already written a small scroll away is beyond me.
It was a reply to Ridavies in regards asking Paul to look at IQE- sorry for the confusion
Morning ridavies!
OK, I can take a look at Iqe (LON:IQE) results from yesterday, leave it with me!
Regards, Paul.
thanks you Paul, much appreciated. I feel one needs the patience of a Saint with IQE .
I bailed out of £IQE a good while ago. I fell in love with what felt like a leading edge set of products. Then a set of gaffes (Tax issues), unfortunate events (death of the young FD), a lack of conviction in the now President, Chief executive, Nelson (who engaged in a personal share sell back/loan scheme that seemed an odd priority ahead of shareholder interests), dominance of Apple in one of their product markets, the requirement for heavy capital allocation etc, and the usual under delivery against product promise, decided I had enough. Never looked back!
I can relate to this with £Iqe although I never get emotionally involved so no love or hate involved :)
Thanks for taking the time Paul and posting about IQE, it was very informative. I should of bailed out a long time ago. Classic case of being sentimentally attached.
Tt Electronics (LON:TTG)
Further to the announcement on 25 March 2021, TT Electronics plc ("TT") confirms that the Medicines and Healthcare products Regulatory Authority ("MHRA"), which is responsible for ensuring that medical devices meet applicable standards of safety, quality and efficacy, has registered Virolens® for use and sale in Great Britain and iAbra has been granted Certificates of Free Sale ("CFS").
Im really glad to see Virolens works.
If nothing else to put two fingers up to the snobs at the FT with their smear job. Want to see why British tech pack up and move to the US then this is another example.
I don't think this news means that Virolens has been shown to be a sufficiently accurate test. Trials are ongoing. I personally have doubts that the tech will be accurate enough to be useful.
TTG/Virolens. I think this compliments Boris 's vaccination program and will enable sports venues entertainment , travel, work to open up with a higher degree of confidence. this a 20 second no fuss test that can detect COVID19 and working on adapting to detect many different viral and bacterial infections. Its cheap quick and easy to deploy with no lab or medical staff required. It British designed and British made. Brilliant !
Histate, which is distributing the test, said it would
launch with immediate effect following the approval in the UK by
the Medicines and Healthcare products Regulatory Agency (MHRA),
and was hoping for a further rollout in coming months.
Histate said trials had indicated the test had 98.1%
sensitivity, meaning it returns few false negatives, and 99.7%
specificity, meaning few false positives.
the trial data hasn't been released and the sample size was reported to be only 400 people. The device has only had registration approved by MHRA which is not full clinical validation as per lab tests. The press release is rather misleading .
The 'trials' from which they drew the sensitivity and specificity look to be in vitro, i.e. not in or with people. Company look to have a track record for misleading press releases if the FT article is anything to go by. Still, it's about time the UK tech scene caught up to the US and we had a Theranos all of our own.
Not really. It’s the same requirement as for any of the Lateral Flow Tests that have been approved (Excalibur, Innova etc.) and they all quote the sensitivity / specificity figures from 400 clinical samples (150 positive / 250 negative) with different viral loads as required by the MHRA. They were running a live trial in February in The City looking 400 people and then checking them with PCR tests. I’d be surprised if they went ahead with registration if that had hadn’t given at least acceptable results, particularly after the media backlash in September.
The lateral flow tests are horrendously inaccurate in real world use, they miss loads of infected cases both symptomatic and asymptomatic and the only reason they're being used is because no one will admit they've been a colossal waste of money.
Momoko
Can you cite any sources to back up that claim?
Without such your comment is at best of no value and at worst dangerous disinformation.
One thing that may have been on you mind in making that assertion may be stories that a parallel PCR vs LatFlow study of tests at Birmingham University.
The Lancet, however looked at this in more detail in this article.
To attempt to precis what they found.
To very much paraphrase, they concluded that the LatFlow tests are ideal to determine whether an individual has transmissible levels of the virus; whereas the highly amplified PCR tests that could detect a trace infection on Mars (my hyperbole!) is suitable to track the level of infection at a population level.
No doubt there are other studies out there, so I won't hold this one as Gospel, especially if you can provide an alternative source, but it seems to me that the evidence suggests that LatFlow tests are a valid and highly important tool in controlling the virus spread,
A rider to this however is that I having been doing twice weekly LatFlow tests and they are a little challenging to do; you have to tickle your tonsils with the swab to the point you evoke a gag reflex (if you have one) and stick the swab so far up your nose as to meet resistance. I am pretty confident that I have been doing this right and that most people who read the guidance properly will also do so.
However, were I a younger person, considering myself therefore to be invulnerable, having spend a fortune on a ticket to see my favourite band doing a test at the arena gates to allow me to walk in 30 minutes later - I wouldn't find it too hard to miss my tonsils and gag on thin air and then wave it in the lower reaches on my nostrils.
I am probably over cynical, but when in comes to a self administered test, you do need to consider the Freakinomic benefits of each outcome.
The lateral flow tests are horrendously inaccurate in real world use, they miss loads of infected cases both symptomatic and asymptomatic
Can you cite any sources to back up that claim?
this BMJ report (25/3/2021) had the following to say (test copied below) - based on these stats i would say the point being made by Momoko Miyamoto seems to be reasonably valid from my quick reading of the situation. Note hopefully the accuracy of these tests can be improved over time - you could perhaps argue this historical data may not reflect the reality on the ground now if tests have improved - and as this dataset includes non UK data it might be (i would like to think it is!!) that the tests being used in this country are of much higher quality than the sample data.
https://www.bmj.com/content/37...
News
Covid-19: Lateral flow tests
The World Health Organization’s performance standards require that tests correctly identify at least 80% of infected people (test sensitivity) and exclude infection in at least 97% of uninfected people (test specificity). The Cochrane analysis found that test sensitivity in symptomatic people ranged from 34% to 88%, with an average of 72%. The figure for the Innova test used in the UK was 58%. The tests worked best in the first week after symptom onset.
In people without symptoms the tests correctly identified an average of 58% of those who were infected. However, the number of samples from asymptomatic people was around 10 times lower than from symptomatic people in the studies analysed, limiting the conclusions that could be drawn, said the authors.
In uninfected people the tests correctly ruled out infection in 99.5% of people with covid-19-like symptoms and in 98.9% of those without.
The performance of the Innova lateral flow test in asymptomatic people was not included in the analysis, as studies have yet to be published.
this BMJ report (25/3/2021) had the following to say (test copied below) - based on these stats i would say the point being made by Momoko Miyamoto seems to be reasonably valid from my quick reading of the situation
It's only valid out of its proper context.
Lateral flow tests are a useful addition to a wider test and trace regime, as they allow us to catch asymptomic cases that would otherwise be entirely missed. Removing even a small number of cases from general circulation helps to decrease overall infection rates. Catching 50% of those cases would, in most circumstances, be enough to push R below 1.
For instance, in schools where teachers and children are operating in bubbles, a single positive test will lead to the whole group isolating and getting PCR tests. That's a very effective way to drive down community transmission.
Where they don't add much value is where they're being used to detect individual cases. For instance, if they're used to allow people access to nightclubs then the rate of false negatives is a problem, because a single case slipping through can lead to hundreds being infected, as was seen in South Korea.
It's horses for courses, but the generalised statement "the only reason they're being used is because no one will admit they've been a colossal waste of money" is, simply, wrong.
timarr
FYI. Despite the unbalanced headline, this is by far the most balanced article I have seen from The Times during the whole of the recent Boohoo (LON:BOO) news coverage.
"Boohoo ditches suppliers after factory scandal"
https://www.thetimes.co.uk/art...
Looking now as if Boohoo (LON:BOO) has had its day in the sun.
Thanks for posting The Times article about Boohoo (LON:BOO) (I hold).
As you say, by their warped standards, it's actually quite balanced! Although I couldn't help laughing when the journalist couldn't help but put in a couple of barbed comments towards the end!
It does all make me wonder who (if anyone) BOO uses to do its PR? Whoever it is, they're useless. All this hostile press over several years, could have been neutralised by a skilled PR operator, buying them nice lunches & gently putting across all the stuff that BOO has been doing to sort things out. Maybe it's because of lockdown, that the lunches haven't been possible?
Anyway, all background noise. Reading the Leveson Report, it really does sound like BOO is very serious about making Leicester a centre of excellence. That comes at a price though. The organic growth at BOO is so high (something like 35% p.a. for the main brands) that it's possible they could be increasing production in Leicester at the same time as increasing the % of garments imported from abroad?
One way or another, the team at BOO are such experienced rag traders, and talented at all aspects of eCommerce, that they'll find a way of driving forward the growth, keeping profits high, and honouring the ESG agenda. In my opinion.
Regards, Paul.
Very good point Paul. Boohoo (LON:BOO) have been well off point in the PR stakes. Though ultimately the successful delivery of the ESG strategy will achieve the reputational reset they need, it would be more constructive and speedier with some good PR and comms management. Though I do think it is a Covid issue as well. Because so much of ordinary life is no longer occurring, the media are struggling to fill their slots. It has been noticeable for many stories just how long the media have nurtured and sustained them, as there is comparatively so few competing stories for the space.