Small Cap Value Report (Fri 27 Aug 2021) - AIR

Good morning, it's just Paul here today, with the SCVR for Friday.
Update at 08:28 - that was easy, only 1 company in our small caps area reporting today, so I'll sign off now, as have other jobs to do - wishing you all a lovely long weekend! Today's report is now finished.
Agenda -
Paul's section:
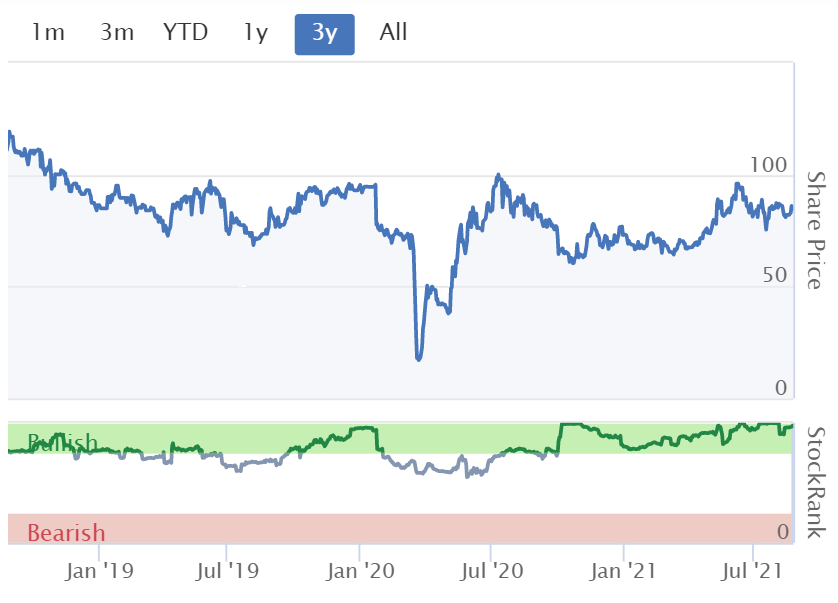
Air Partner (LON:AIR) - announces an acquisition. Positive trading update, with H1 profit of at least £3.7m. Lots of moving parts in this small group, some being helped by the pandemic, others being harmed, so it's difficult to work out how the group might perform once travel conditions normalise.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section
Air Partner (LON:AIR)
84.6p (pre market open) - mkt cap £54m
Acquisition - of Kenyon International Emergency Services Inc.
Air Partner acquires world leading emergency planning and incident response company
Price paid: $10.3m, plus up to $1.4m deferred - so a fairly significant sized acquisition, relative to AIR's £54m market cap.
Funded from existing cash resources.
Post transaction, the Group has net cash of £8.3m, excluding JetCard cash, and access to a debt facility of £9.5m.
More details here - video is an excellent way to explain acquisitions, so I hope more companies do these -
.
- Continues to trade strongly
- H1 (Feb-July 2021) underlying profit before tax will be >£3.7m
- Private jets doing well
- US performing very well, with leisure travel for rich people offsetting weakness in business travel
- Activity in Europe "remains limited"
- Jet Card product "performed particularly well"
- Good trading in Group Charter - driven by Govt work
Outlook -
The Board remains encouraged by this performance and is optimistic about the prospects for both the Charter and Safety & Security divisions for the rest of the financial year.
My opinion - for such a small company, there seem to be lots of different divisions & activities. It's difficult to work out how the business might perform once travel conditions normalise. Therefore I'm not sure how to value this share. Still, it's traded well in H1 so this update should drive broker upgrades I imagine. There's no broker research available to me, so the figures will remain a mystery until published.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Andrew - I agree with Gnome2 - don't get into large cap/small cap or long term/short term boxes, just find what works for you. My best share has been a company called Cadcentre. I bought it when it had a Mcap of £50m. It is now called AVEVA (LON:AVV) and has a MCap of £12.6bn. Were it not in my ISA I would have a potentially very large CGT charge.
As well as IG you could look at xo or iWeb. Both have low dealing charges and no standing charge, including ISAs.
Hi sharw thank you for your reply. Yes I have wondered what I will do if one of my holdings in Freetrader skyrockets and I have to pay CGT because it is not in my ISA and think I have made a mistake. I sure am on a massive learning curve! I am definitely having a rethink after your comments. Thanks for the dealing suggestions, I will have a look at these options over the weekend. Well done with Cadcentre btw.
Time in the market not timing the market is one of my favorite sayings already!
I am 51 and wish I had started investing years ago but we can't turn the clock back. It will be interesting to see where I am in 5 years time with my investments but at the same time we don't want to wish our lives away!
Thanks once again for your suggestions.
It's hardly a mistake if you have made significant profits enough to need to pay some tax. Don't let the tax tail wag the dog.
Hi, I wonder if anyone can advise me? I am relatively new to investing. I have invested about £40K since the beginning of the year in an ISA with H&L. Mainly large caps so I purchase a larger holding thinking this is sensible due to the £11.99 fee to buy & sell. Currently 12% up so not too bad for a beginner although I plan to hold for 10 years plus.
I have opened a freetrader plus acoount and invested about £15k in smaller companies. As these are smaller holdings I wanted to avoid the fees otherwise the % gain doesn't make sense to me and I don't plan to hold these for as long. Currently 15.9% up.
However, some companies are not always available. For instance I did some research on UPGS a few weeks ago but not available on freetrader so didn't make the purchase and they have gone up so missed the boat maybe. Was thinking of doing more research on Air Partner but just checked and not available on freetrader either.
Hope I don't sound stupid but am I missing something?
It looks like you need Freetrade + (£9.99 pcm) if you want to be able to trade a lot of stocks.
However, you should remember - there are no free lunches! If Freetrade are not charging commissions they are making it in other ways, and that will likely be via the prices they offer when buying and selling. That may make sense for smaller portfolios and trades, but as the trade size increases you may end up losing more money on poor trade prices than you would pay in commissions
Thanks for your reply Peter. Funny you mentioned buying and selling prices on Freetrader because I suspected that but thought I was imagining things. As I have got a little wiser over the past 6 months I have clocked that the buying prices are slightly higher. I have experienced an attempted purchase being rejected over 5x in a 10mins period by which time the price has gone up 10% +
I will check out IG Group as suggested by Herbie.
There will be restrictions with platforms such as Freetrade, not all stocks will be available and prices may not be as good as the more expensive platforms, you may have more trouble selling if there is a problem. You could look at Ig Group (LON:IGG), £3 per trade, prices same as HL on all the ones I checked, sometimes even cheaper. They also have all UK stocks available same as HL as far as I know. I moved most of my account from HL, their fees are too high and their service has gone down. HL fees on foreign stocks are even worse with their 1% forex fee.
Thanks for your reply Herbie I will look at IG Group. I think you are absolutely right about HL fees and their service. You have confirmed my decision not to put my next ISA allowance in. Of course thats 2022/23!!
Just looking at another company but yet again, not available on Freetrader! Doing my head in when the first thing you need to do is see if it is available before doing any research!
I also had a lot of trouble with HL transferring my cash to another ISA provider, they delayed it as much as possible, it took over 4 months. IGG are not perfect, their contact by phone is bad, but I rarely have to phone up.
Andrew, well done for taking the plunge and it sounds like you’ve got off to a solid start. I just wonder why it is that you have made a distinction between large cap shares which you intend to hold long term and small cap shares for shorter term?
There are many good quality small cap shares that could be good long term holdings. Up Global Sourcing Holdings (LON:UPGS) is one that I hold and intend to hang on to. I don’t hold £AIR but I think it’s one of Lord Lee’s holdings and he’s definitely in the long term buy and hold camp. The point is that it’s often the smaller cap shares held over the long term that can really power your portfolio.
Just something to think about.
Hi Gnome thanks you very much for taking the time to reply and I value your comments. I have reflected on what you have said and it has prompted me to have a rethink. Especially with the similar post by sharw. Large caps seem to be 'slow burners' and my % gain is higher on mid and small caps which seems to prove your point. I think I am right in saying this is the difference between value and growth investing. Both have their pros and cons.
I will still need to solve this issue of stocks not being available on Freetrader but you have all kindly offered me some good alternatives which I have time to research over the bank holiday weekend.
Hi abtan.
Interesting comments about overseas shares. With a couple of exceptions (shares held over from previous employment/ company distributions) I only hold U.K. listed shares. All of my overseas stuff is either in ITs/OEICs or ETFs. With the possible exception of Saxo Bank I’ve yet to find an attractively priced/easy to use platform for dealing on other exchanges. (Most likely indolence too!) Was this the historic thread discussing FX charges you had in mind?
https://www.stockopedia.com/co....
Gus.
Hi Paul
A bit late in the day but any thoughts on the announcemnt of the T Rowe Price holding in Boohoo (LON:BOO) I hold.
There are a couple of coments on the General Discussion page at
https://www.stockopedia.com/co...
Have a good weekend.
Regards
Michael
Even later in the day - but good to see that Morgan Stanley bidco suggesting shareholder of Augean (LON:AUG) (I hold but sold 20% yesterday) do nothing. Would be nice to have a bidding war.
Putative offer for Daily Mail And General Trust P L C (LON:DMGT) has been nudged along today by the completion of the Cazoo business combination with the Ajax1 SPAC on the NYSE which will be listed from 2.30pm today.
https://www.investegate.co.uk/...
Completion of this combination was one of the primary conditions to a possible offer for the rump of the DMGT group by Rothmere Continuation Ltd., and a spin off/distribution of the Cazoo shares. I hold.
Gus.
Royal Mail (LON:RMG)
Cheers peeps - think i may take the plunge here next week if the price doesnt spike up before i deploy my funds. Royal Mail tweeked my interest as i noticed "the popular investor" (by far my favourite you tube commentator on shares) has added here. His rationale for investiong isn't yet available for non chosen disciples yet- but generally all the sensible ducks need to be lined up for him to add , looks as simple as pe 8 decent balance sheet and i am guessing (not checked yet) decent cashflow and ebida earniongs - i particularly love watching his stuff when he uses elliot wave theory to predict future share price movement he certainly won't be as good as the "great" Hari Seldon (28 days and counting till Hari hits the small screens woop) but it all looks very fancy i must say.
Good luck with your Royal Mail (LON:RMG) investment, I would not touch them, I think they have benefitted from Covid and the lockdowns, if life returns to normal I believe the parcel demand will fall, letter post has declined considerably. I had a recent poor experience with them with an important delivery, their tracking is hopeless, about 12 hours out of date, they could not even get the day right and their tracking after I picked up says I collected a day later. I think DPD parcels is eating their pie as well, seems a lot of companies now use them instead of RM, they are much cheaper, more reliable and the tracking is within about 1 hour, they even notified a 1 hour time slot for delivery.
thanks for that Herbie
Royal Mail (LON:RMG)
I think all the points about uncertainty here are very valid - must admit that that i have been less than impressed in the past by their tracking compared to other like DX/DPW or whoever? where you can get a map and even a drivers name (even if they are soemtimes wrong). In some respects if they are doing ok with less than good tech one would expect that they should massively improve in this regard over the next couple of years (surely?) - as long as they don't lose all their business in the meantime!!.
I suspect the market is factoring in some sort of backward regresion here even if the current guidance from the company is that they were on track this year for good numbers as recently as last month (with uncertainty caveats included) and all the brokers seem to be sticking to their guns at present that next year will be ok (presuming stocky figures are not outdated). I think for pe of 8 there is always going to be some concerns that this may some sort of value trap - i tend to prefer quality over value nowadays but still do get tempted by the odd value play from time to time as is the case here.
I think investing in the technology will be expensive and may not work. The forecasts look pretty flat for the next 2 years although they have been revised upwards recently. Not sure I have much faith in the management and then there are the unions to contend with. I look for growth stocks more than value, I have ben tempted by a few VM (value/momentums) stocks this year that have not worked out, so I prefer QM stocks. RMG is a top QM stock but I'm struggling to see much growth, I'm inclined to feel that parcels could decline in the next 2 years. But the shares are down 20% from their peak so it could be a good time to buy.
I'm having difficulties with letter deliveries. I spoke to the postman who said they are short staffed and most letters sit in the depot for 2 or 3 days before being delivered. Doesn't matter if it's first or second class.
I asked if it was due to covid but he said it wasn't, they just wouldn't employ extra staff.
I've no idea if this is a local issue or not. I'm just mentioning it as something that might be of interest before investing..
sg31 - you are not alone - Royal Mail (LON:RMG) has this problem all over the place. Just put:
royal mail spokesman "disruption to service due to COVID related absences"
into google and see what happens!
Out of interest who is your favourite YouTube commentator on shares?
Hello imranawan
As per the original post today the you tube channel is called "the popular investor"
here is link to you tube channel
https://www.youtube.com/channel/UC-CfltxhlMMCT5pJNIfQhlQ/featured
and here is live portfolio tracker detailing live performance of his portfolio including monthly stats - current holdings etc - you can click on current holdings to see when they were added.
https://www.etoro.com/people/robertmerc/stats
I would say for a one man band its a highly professional outlook this gentleman has with regard to everything he does - top notch interesting stuff IMHO.
Hi Paul. Would you mind making a note to look at Mattioli Woods (LON:MTW) at some point please. It reported another small bolt-on acquisition today and I don't think SCVR has covered it before. Always interested in your thoughts. I hold, but thought it might be of interest to others. Enjoy your weekend.
Air Partner (LON:AIR) (I hold)
The most positive thing I noticed from today's updates was the current cash balance of £8.3m*.
This is in comparison to the Y/E cash balance (@31st Jan, 2021) of £9.9m*.
*(both figures exclude JetCard Cash)
---
If the company has used $10.3m = c.£7.5m on today's acquisition so far, that implies H1 cash generation of £5.9m.
For context the current EV of the company is only c£50m.
---
The 2 things that I can think of that might be skewing this seemingly remarkable cash generation would be:
The year end Customer Deposit position was only £1.6m though and I can't imagine that this would have changed much.
In any case it looks like it's either been a decent H1 or a decent H1 + 1 month.
Happy holder for now.
A
abtan - sorry to burst the bubble of your Air Partner (LON:AIR) calculations but if you watch the video you will note Mark Briffa say that £5m was drawn down from the RCF to pay for the acquisition and the rest from cash. That would reduce your H1 cash generation figure from £5.9m to £0.9m.
£AIR
Hi Sharw
On my phone now and formatting is always strange, so apologies in advance.
Yes, I heard that too so went back to check. They said "Post transaction, the Group has net cash of £8.3m, excluding JetCard cash, and access to a debt facility of £9.5m.".
So as far as I can tell my bubble is still okay and cash generation does look very good.
Cheers
Royal Mail (LON:RMG)
Well ot this one but Friday is a normally a quiet day so i though i would break etiquette and sneak it in. Market cap is only 494 mill if i accidentally miss a zero off the end - easy done when ones eyes are aged over 50!
With shareprice at 500p ish p/e is currently standing at 8 - stock ranking is 99 and per stocky numbers looks like the balance sheet is more than decent - i have had a quick look at annual report and to my very untrained eye it doesnt look like they have any issues with pension deficits (there is big numbers here though -s o thats not to say no risk)
They did 57p EPS 2021 and are forecasts to do 61p 2022 and also 61p 2023 - so it seems ticketyboo with current forecasts - albeit nil growth.
My main worry here is that earnings growth may have spiked with covid as there has been a stepup in profit for 2021 compared to what went before - having said that stocky is showing higher "normalised" EPS for earlier years so perhaps some large intangible adjustments may have previously been included that are not there now? (i need to dmor in that regard still).
I have previously dismissed Royal Mail as a long term investment on the basis the workforcee were too militant for my liking - but i am guessing times will have slowly changed over the years - are the new guard as militant as the old guard - possibly not? - and i suspect contracts for staff now may give them less leeway to hold the company to ransom.
In summary this stock seems way too cheap unless those in the know expect current earnings not to be sustainable long termn - or there is something fundamnetal here that i am missing. that affects the price (any regulation issues?)
I am much more positive ref shipping companies like this post brexit - as they have the ability to offer new services with regard to the complexities of moving stuff in and out of the uk and from uk to NI. From an unscientific viewpoint i also know someone who uses royal mail for most of their bulk business post - this surprised me somewhat as i kinda presumed they might be old skool inefficient and more expensive than the smaller nimble competitors perhaps this is not the case - possibly large is better here in that regad.
Does anyone in the know have an idea why the p/e is only 8 here ? or have any viewpoints with regard to how good they are at what they do or any other useful tittle tattle - cheers.
The share price has drifted down by around 20% in last couple of months on seemingly no news. Does seem very cheap and took opportunity to take very small position, although need to do further work as haven't studied the company closely. The main concerns appear to be the highly unionised workforce, increased competition in the parcel sector (many of whom are largely automated, such as Amazon) and whether the uptick in earnings during covid can be sustained. I would suggest these are more than priced in, and recent trading update suggested parcel volumes holding up reasonably well.
Royal Mail (LON:RMG) rmillarie - share your intrigue in low rating but.... My Parcelforce delivery guy has told me a few times over the summer that a new algorithm introduced for sequencing load factors and routes has seriously impacted performance. He estimated taking 20% less out per day and taking longer to get round. Management offering additional overtime to correct this but most of the guys not interested as already doing a standard 2 hours a day OT already.
He thought the guys could do better without the algorithm. May just be his depot, may be wider.
On bulk mailing, in previous job we used a variety of printers and mailing houses. Most still seemed to use RM for onward distribution.
Certainly a sector and business that is benefitting hugely from increased online shopping. That won't reverse to any great extent IMO with city centres introducing Clean Air Zones, hiking up car park charges and turning over much more space to cycle lanes and pedestrians in the wake of covid. Plus all the anchor store/department store closures. Might make them more pleasant places to live though!
Just tittle tattle, as requested.
Royal Mail (LON:RMG)
Hi Rmillaree
Thank you for sharing your thoughts here.
I must admit to never looking at Royal Mail (LON:RMG) before, but the financials are indeed appealing.
I hold PostlNL (basically the Dutch equivalent) and have seen them develop into a highly cash generative company with some interesting expansion plans.
One only needs to look at a company like Quadient (France-based) to understand how profitable something as simple as a parcel locker can be.
One would imagine that a company the size of Royal Mail (LON:RMG) , even if it's only a "£500m" company, would have similar avenues in mind for future growth.
Cheers again
A
Royal Mail (LON:RMG)
"One would imagine that a company the size of Royal Mail (LON:RMG) , even if it's only a "£500m" company, would have similar avenues in mind for future growth."
Just to be clear here market cap of royal mail is £5 billion - my £500 mill comment was meant to be an obviously incorrect amount being referenced - poor atempt at humour possibly!! - then again perhaps you are playing along in that regard.
Royal Mail (LON:RMG)
Yes, I was continuing the humour :)
A
Hi Abtan,
I've noticed over the 6 months or so I have been a Stockopedia member that you both research stocks very thoroughly and also hold a fair few European stocks. I wonder if you would be willing to pass on a few pointers in respect of the latter. I have some euros I would like to deploy without changing back into sterling. So far I have only bought Linde as a large cap hydrogen play. I noticed you prefer Westwing over Made. Indeed, my son has Made furniture on order but there are long delays. Our over-reliance on China is causing a lot pf problems.
Two points which have not been mentioned today - First the 15% holding of the Czech investor and second the very thin 'moat' around the business - which I suspect has been weakened even more this week with the announcement from the Post Office that they have signed a Click and Collect deal with DPD. RMG must be fuming..!
Hi Roger
Please accept my apologies for the slow reply.
I'm away at the moment and using my phone for comments during the day just doesn't work, especially for longer responses.
You asked for pointers on European stocks.
I must be honest and say that I'm not sure what I can add will be that useful, but here are some thoughts off the top of my head.
I generally source my ideas from 3 places:
2. and 3. are definitely the greatest resource for finding new stocks, both UK and European.
Beyond that, many European-listed companies publish their reports + do online presentations in English, so there isn't really much difference vs researching a UK-listed company.
https://www.introduce.se/ run fantastic day webinars full of presentations by predominantly Nordic-listed companies, with much (all?) of it in English.
I recall seeing a presentation on there from CTT and coming away very impressed.
I don't have a position, but I keep a close eye on it as one day I might do.
https://www.ctt.se/investors/
https://www.stockopedia.com/sh...
European broker notes do exist and sometimes are available for free on a company's website. For example:
https://www.ezag.com/home/inve...
https://www.northmedia.dk/en/i...
I have tried investing in foreign companies with no English Investor Relations page, but it just hasn't worked for me.
---
As for wanting to use Euros, I personally just take the FX hit when investing abroad. If I think a company will go up +100%, a 10% adverse FX movement is something that I can live with. I think there was a Discussion on this forum a few years ago, which provided interesting insight from quite a few people on this. Perhaps someone can find it and share here?
---
Thank you for your comments on Made.com.
I like the company and have my finger close to the buy button. but I'm holding off until I see the impact of the higher freight costs. Based on your son's experience, perhaps there will be a slow down in revenue soon too?
Westwing have finally announced increased freight hitting their operating profit margins, but the share price has not suffered (yet). I wonder whether Made's share price would suffer though given the sentiment of it being a recent IPO?
On a similar note to the above, I should add that many foreign companies, like Westwing, generally have webcasts in English, which are then published on their website. I find this most useful.
I've also found European Investor Relation teams generally quite good at engaging with English-speaking investors.
----
Apologies for rambling, I have no idea if the above helps in any way.
I should add that without a Stockopedia multi-region subscription I never would have found most of the international companies that I have invested in.
Good luck and happy investing.
A
I haven't looked at closely as I missed the price rise but it is only over a year ago that Rico Black was forced out over his failure to get the unions to agree to modernisation. I think an agreement has since been reached. Royal Mail is so stuck in the past that the majority of the parcels it handles are completely sorted by hand, from collection at the Post Office right through its depots as it moves around the country, to the last mile delivery. It means it cannot compete on next day delivery contracts.
If that can change it opens up a huge slice of the market to them and would give them a big advantage as from an ESG perspective it cannot make sense to have all these different delivery vans constantly going up and down streets delivering single parcels. You also potentially end up waiting in for several parcels all being delivered at different times when one delivery a day would be just fine.
The share price jumped because a Czech company Vesa bought a 5% stake and have since increased to 15%. (also bought into Sainsbury's)
Royal Mail's European parcel division was from memory its most profitable.
Good update and news to day. I added to my £AIR holding this month when price fell to ~81p. Good metrics and an interesting sector, especially freight (alternative to rising shipping costs and scarce availability of critical components?) plus aircraft safety following mothballing, airport security and critical evacuation skills, plus HNW and corporate charter market in USA. All-in-all plenty of opportunities for this to go further. Good luck to holders.
Serving the rich (Luxury) has done well during the pandemic and Air is no exception.
Recent evacuation from Afghanistan may benefited the company.
Air Partner (LON:AIR) Acquisition of Kenyon International, earnings enhancing in first full year. AIR have benefitted from emergency-type operations since Covid struck and this would seem to be a good fit with their existing business. Funded internally so no dilution. Kenyon (new to me) deal with emergency stuff and this sort of work must be very specialised also Governments are a major client and can be inclined to spend heavily when motivated.
https://www.londonstockexchang...
And video here:-
https://www.airpartnergroup.co...
I have to agree GN100, Kenyon does look like a particularly good fit for them. if these reoccurring revenues can be maintained then it should add a little more of a back stop for the share price. As you mention, I am sure there are some strong margins to absorb here.
Good to hear they have the wind in their sails for many other parts of the business, with all the traffic light rules still in place across the world, I cant see commercial travel picking up as soon as everyone wishes.
Would you have any insight who their closest competitor is? as I would like to compare some ratios, as I am not sure what the average PER would be in this sector. Thanks
I suspect that Air Partner (LON:AIR) nearest competitor is Netjets, which is owned by Berksire Hathaway.
https://www.netjets.com
According to Stocko Gama Aviation (LON:GMAA) is in a similar line of business. AIR looks by far the better proposition.
My morning smallcap tweet: Friendless Amigo staggers on
Air Partner (LON:AIR) Sportech (LON:SPO) Amigo Holdings (LON:AMGO)
Air Partner (AIR) guides H1(July) U/L pretax at least £3.7m after continued strong trading. [SP=83.44 Cap=53m]
Sportech (SPO) CEO & CFO resign post the reduction in the operational scale. They are thanked. [SP=39.16 Cap=74m]
Amigo (AMGO) the very naughty subprime lender's Q1(June) better than expected. Net loan book down 48%. Adj EPS 3.2 (AMGO). Going concern material uncertainty. [SP=7.9 Cap=38m]