Small Cap Value Report (Fri 27 Sept 2024) - RFG, ADVT, IES

Good morning! Paul is travelling and news flow is quiet, so I'm holding the fort this Friday morning.
All done now. Have a nice weekend! Graham.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
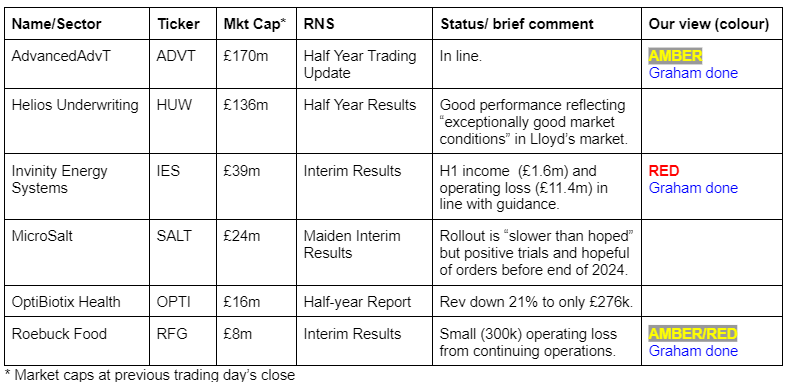
Companies Reporting
Summaries
AdvancedAdvT (LON:ADVT) - up 3% to 131p (£174m) - Trading Update - Graham - AMBER
An in line with expectations update from this vehicle led by Vin Murria. It includes a group of software businesses, over £80m of cash (likely to be used in substantially more M&A), and a stake in M&C Saatchi (LON:SAA). It is arguably trading around fair value here, if you’re happy to value its software businesses on a generous adj. EBITDA multiple.
Invinity Energy Systems (LON:IES) - up 10% to 9.6p (£42m) - Interim Results - Graham - RED
Financial results remain terrible here. The company has raised large sums from investors and the cash pile at the end of H1 (£49m) was larger than the current market cap. However, cash burn has been very heavy and I would continue to vigorously avoid these shares.
Short Section:
Roebuck Food (LON:RFG)
Unch. At 15.8p (£8m) - Interim Results - Graham - AMBER/RED
Until 2021, this was known as Norish plc. Our former colleague Jack Brumby referred to it as a “temperature controlled logistics provider” that year (link).
It has been through plenty of change since then, and today’s interim results outline more change.
A couple of disposals have taken place in H1; the company now consists of:
Moorhead & McGavin - a Motherwell-based business that supplies “pulses, cereals, pasta, rice and flours to the food industry, with clients including Aldi, Brakes, Kerry, Princes, Baxters, the NHS, Stirling Group and Booker”. Sales are up 22% in H1.
Foro Food Solutions - a Cork-based food sourcing business.
Net debt - close to zero as of June 2024 (£0.1m).
Outlook - the disposals have served to “greatly simplify” Roebuck, and management are excited for future prospects.
Financial statements - there is a £300k loss from continuing operations, on nearly £6m of sales. There are also substantial losses from the discontinued businesses.
The balance sheet shows net assets of £2m.
Graham’s view - it’s a Friday, which is a good day to check up on stocks that we don’t normally cover, to see if there is anything that we should be covering more often. Unfortunately based on the financial statements, this looks like it might be too small to be listed. The £8m market cap agrees with me. So for that reason alone I have to take a mildly negative view.
As a reminder, the number of AIM-listed stocks has more than halved from its peak (from 1,700 to 700). Takeovers have played a part in that, but much of it is due to plain old delisting, We need to take delisting risk very seriously for small companies. Let’s move on to something else!
Graham's Section
AdvancedAdvT (LON:ADVT)
Up 3% to 131p (£174m) - Trading Update - Graham - AMBER
AdvancedAdvT Limited (AIM: ADVT, "AdvT", "the Group"), the international software solutions provider for business, compliance and resource management, has published a trading update for the six months to 31 August 2024.
Paul looked at this one in July, noting that it had £82m of cash and a 9.8% shareholding in M&C Saatchi (LON:SAA).
Vin Murria is the Executive Chairperson and owns 13% of ADVT.
Trading update: in line with expectations. H1 revenue c. £19.5m, adj. EBITDA c. £4m.
Net cash rises slightly to £83m, and the shareholding in M&C Saatchi (LON:SAA) is worth about £25m.
Comment by Vin Murria:
We continue to experience positive momentum, with all the acquired units benefiting from the operational and financial actions implemented since acquisition.
"SaaS revenues have shown positive growth, with Resource Scheduling SaaS revenues recording significant gains. This combined with our focus on customer value has driven notable improvements in both revenue and EBITDA performance.
"Whilst we see numerous opportunities for organic business growth, particularly with AI, automation and SaaS offerings, we remain committed to exploring acquisition opportunities to expand the Group."
Graham’s view
Subtracting the value of cash and SAA shares, ADVT’s enterprise value today is £66m.
As noted above, the underlying businesses generated H1 revenues of £19.5m, and adj. EBITDA of c. £4m.
Let’s simply double these to get an idea of roughly where annual numbers might land: revenues of £39m, adj. EBITDA £8m.
One of the recent acquisitions did not actually join ADVT until July 2024. So performance will get a boost from this.
That business - Celaton - previously generated annual revenues of £3.3m and adj. EBITDA of £1.2m.
Adding these on to the numbers above,, I think ADVT’s underlying annual performance is at least revenues of £42m and adj. EBITDA of £9m.
Is that worth the £66m enterprise value? It could be. An adj. EBITDA multiple of 7x for business software businesses is not out of the question at all.
Therefore I’m happy to sign off on a neutral view on this stock, as Paul did in July.
Does it make sense for a large cash pile, a stake in M&C Saatchi, and a group of software businesses to sit together in the same corporate entity? I suppose it does, if you have faith in Ms Murria and you want to make a bet on her business acumen.
Invinity Energy Systems (LON:IES)
Up 10% to 9.6p (£42m) - Interim Results - Graham - RED
Invinity is “a leading global manufacturer of utility-grade energy storage”.
Paul has been RED on it (link). Today’s interim results are as follows:
Total income (sales + grants) of £1.6m
Loss from operating activities £11.4m (H1 last year: £12.6m).
Sales measured in megawatt hours were lower than H1 last year (4 MWh vs 5.38 MWh last year).
Cash finished the period at £49m after the company raised £57m in May 2024. This included £25m from the UK Infrastructure Bank.
Management: in H2, the CEO has retired and been replaced by the former CFO.
A new manufacturing facility has opened, and a new production line has been ordered for another facility (Bathgate).
Outlook:
During the remainder of 2024 we plan to deliver against the near-term corporate goals and set in place the foundations for 2025 and beyond. We believe Long Duration Energy Storage remains critical to increasing the penetration of renewable energy and in advancing the path to net-zero - this is not capable of being achieved by lithium alone. Vanadium flow batteries remain, in our view, the most credible and advanced such alternative and if we can deliver on our corporate goals, the market opportunity remains very significant.
Graham’s view
The fundraising has left it with enough cash to survive in the short to medium-term (at least two years).
So it’s not on the block for short-term insolvency. It has time to improve its financial performance under new management.
However, there is no denying that the numbers up to this point have been awful.
The involvement of the UK Infrastructure Bank is worth a mention. One of its primary purposes is to invest in climate change projects, particularly in projects that will help to meet the government's “net zero” target.
As IES are explicitly trying to help efforts to meet that target, it makes sense that the UKIB would want to get involved.
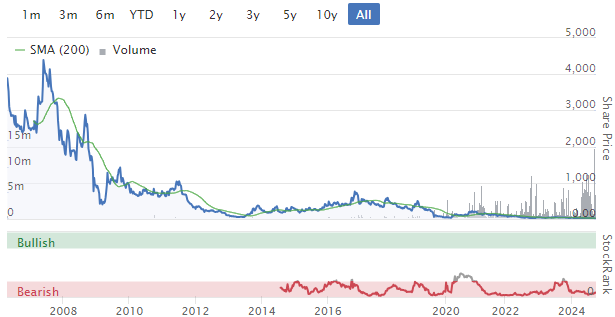
But for investors who are more concerned with the financial risk: reward on offer, I can see few reasons to invest here, even at a discount to the cash pile. The StockRanks agree with me:

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Paul, just listened to your always entertaining/informative podcast. I'm a share geek but Ive no problem listening to an hour, beats watching TV that's for sure.
Listening on Spotify it had an explicit warning, so was excited at the thought of maybe a little 90's gangster rap thrown in. As it was 'Buffalo Bill', ' revolting shakes', 'absolute rubbish' and 'who cares' made up for that. With the cherry on top being the mystery share, which you then gave the ticker for haha
Anyway keep highlighting the rubbish, my yearly performance has improved 5% or so I'd say since reading scvr and much of this is steering me away from junk, so as you say it's a important service
This weekend's podcast is now up.
The "mystery share" (just for Stockopedia readers) is Fonix (LON:FNX) . I don't know why its shares fell last week, but on good results & outlook, and likelihood of beating modestly-set forecasts, I think this might be a buying opportunity. Not particularly cheap, but it's a quality company with a superb track record.
Regards, Paul.
D'Oh! I just listened back, and like a complete numptie, I read out the ticker FNX just after saying it was the mystery share. I knew that reading, thinking and talking at the same time was difficult. Sorry about that. My version of "Don't tell him Pike!"
Also, I did mystery shop Tortilla Bournemouth this afternoon, having a pork burrito. It was absolutely HUGE, and really tasty. I couldn't manage all of it, which is most unlike me! The lovely girl serving spontaneously gave me a free burrito voucher, because she said she felt bad that my loyalty app didn't work (I need to update it). Wasn't that nice! Sounds similar to something Pret does, where they give staff some free vouchers to hand out to people they like, or fancy (apparently). I'm always pleasant and smiley to staff, as I encountered so many rude customers back in the day when I was serving in a coffee shop, aged 14-16 for £1/hour, and it was really nice when customers were pleasant, and gave me a reassuring smile, so I always do that myself now. Always respect people who bring you food or drink, as bad things can happen in the kitchen if you don't.
Good on you for being polite. It doesn’t cost anything but can make another persons day!
I thought I misheard it at the time, but was gently amused.
There are few things I dislike more than people being abrupt/rude/talking down to service staff (who BTW have name badges for a reason!)
My father once observed that if you are out with someone who is trying to be nice/impress you but aren't treating the staff/most junior person present well than they're not a nice person or someone you want to associate with.
A smile and courtesy cost nothing but make life better and happier for everyone.
Talking of food Paul, I think you mentioned a couple of weeks ago, in the context of some company that supplied pies to supermarkets, that the quality of these was generally very poor.
I agree with the exception of Marks and Spencer, whose gastropub pies for two are superb, even better than the ones I make myself. Both the chicken and the steak ones are top notch, and actually are large enough to leave a third portion for the next day.
https://www.marksandspencer.co...
Well worth checking out, not cheap of course, but very good.
"Well worth checking out, not cheap of course, but very good."
This is why I am a contented holder of Marks and Spencer (LON:MKS) - as you say the food is very good, and the adverts are correct, it is not just a pie, it is an M&S pie.
Also when Mrs B comes home having spent £30 on 6 items from our local M&S at least I know that I have contributed to the E part of their P/E!!
Hi Tim,
Regarding your comment "it is not just a pie, it is an M&S pie".
Around 10 years ago I saw a rather mucky M&S 40 ton lorry parked up in a lay by on the A565 Formby Bypass. Normally, smart alecs would enscribe the words "Also available in white" in the dirt on the side of the lorry. However, on this occasion some smart alec with a wicked sense of humour enscribed in the muck...
"This is no ordinary muck, this is M&S muck" ...... priceless and it made me smile.
David.
M&S food hall in Manchester is like visiting a foreign super-deli. And I mean that as a huge compliment.
Paul, feedback you requested: make your podcast as long as you like. I'd actually be disappointed if you shortened them but maybe that's greedy. Always entertaining and informative.
Fonix (LON:FNX) - davidjhill also noted this below in his posts at 1:30pm and 4:37pm along with drops in MPAC (LON:MPAC) Journeo (LON:JNEO) Card Factory (LON:CARD) and Activeops (LON:AOM) . Buying opportunities being presented? Maybe not in all cases.
Paul,
Please keep your Podcasts as they are. They are terrific thank you.
Agreed. My wife listens in the background: loves your turn of phrase; finds you "uplifting"; and went as far as suggesting that should you stray into our patch in deepest, darkest rural north Dorset we'd have you in for drinks.
SSON I had a chance to look at the Smithson Investment Trust AGM from 4 months ago. It operates on the same principles as the better known Fundsmith, but for companies in the £500m-£15b range. Simon Barnard is a portfolio manager.
SSON showed a FCFy (Free cashflow yield) of their portfolio of 2.4% for 2023, although he says that the figure is somewhat outdated and a more representeative figure would be around the 3% mark.
The comparative index (MSCI World SMID ex-financials, i.e. small and medium companies without financials) is 3.3%, but I think that is also an outdated figure.
I just pulled out a few of what I consider quality companies from my own portfolio, and here's the FCFy yields I came up with: BMY 5.9%, BNZL 7.3%, CCC 9.5%, CWK 5.0%, FOUR 5.6%, GAMA 5.1%.
My take away from this is that it ought to be possible for UK investors to outperform the world small/mid cap market. You can find better-quality companies with good growth prospects relative to the world market, and at cheaper valuations.
Have a happy weekend.
Comparing FCF is quite tricky to do because there are so many ways of calculating FCF and many different FCF definitions. To my knowledge Fundsmith never explained their definition of FCF.
they did in their earlier videos + some of the questions asked at AGM's covered it...those videos have now all gone ofc, including the full length AGM videos (minus the most recent one)
fortunately, people have clipped bits here and there! just type "terry smith free cash flow' into YouTube and you'll find him explaining it
you may find it referred to as 'free cash flow yield' which is FCF/shares outstanding, or free cash flow/market capitalisation x 100 which = a % yield, similar to a bond
(you are correct that there are various, more specific, ways to calculate cash flow w/adjustments but you are really getting into the weeds there)
hope that helps!
FCF is OCF (operating cashflow) less capex. Capex comes in two type: MCX (maintenance capex) and GCX (growth capex). I don't try to distinguish them, but it's a nuance worth nothing. MCX is what you have to spend, GXC is what you choose to spend.
In my view, and others may disagree, real free cashflow is OCF less MCX. With this cashflow you can choose to pay a dividend or reinvest in the business as GCX.
The point I'm trying to make is that for an established business that is reinvesting, the FCF figure is artificially low, so if you look at the FCFy you are looking at a conservative figure with a margin of safety built in automatically. If it passes a hurdle rate, then all well and good.
I guess some people like to make things too complicated. I think FCF can act as a sanity check on the good ol' PE ratio.
Morning Mark,
I agree and basically FCF is nothing else than cash left for distribution to shareholders (buybacks, dividends, special dividends) and/or acquisitions.
The only thing I disagree with your post is that most and not some people like to make things too complicated.
All the best
In my view, and others may disagree, real free cashflow is OCF less MCX. With this cashflow you can choose to pay a dividend or reinvest in the business as GCX.
But should FCF be before or after lease payments? For some companies, not including lease payments makes a big difference to the FCF figure. The Stockopedia FCF number does not include lease payments.
3 profit warnings in this month for me
Next 15
Card Factory
IG Design
Things will only improve when we know what is happening in next months budget - agree large caps seem to be trading better
Might be worth everyone going through their portfolios to identify anything else at risk of warning - specifically looking at anything low margin and exposed to a consumer slowdown and/or higher input or wage costs. Those seem to be the problem areas right now.
Tony
Card Factory (LON:CARD) wasn’t a profit warning. Why do you say that - it was an in-line?
The fact that it dropped 25% is not because it changed expectations.
Not a profit warning as such, but a 34.4% fall in first half adjusted pre-tax profit. And that on increased revenue.
Agree David, Card Factory (LON:CARD) was an in-line.
Ignoring the wider CGT/small cap hammering theme my oversimplistic view is that current sellers believe it won't sell more cards over Christmas; I'll eat my hat if it doesn't, and so will continue to hold.
One of the main problems for Card Factory (LON:CARD) was the increase in the minimum wage. This is not a one-off cost that will not be repeated.
Sorry John but did you not read or listen to the results?
The minimum wage increase has been offset by a series of efficiencies that come into effect in H2. Those are also not one off either so whilst the initial impact was in H1 it is offset thereafter. The company flagged this but obviously investors didn’t listen/understand/believe it.
The CFo put up a good slide showing the bridge.
The problem with minimum wage increases are that those impacted are incentivised to eliminate jobs so whilst it benefits those employed initially it drives down employment as automation becomes economic. the net result is often weaker customer service. There is always a lag - Card Factory (LON:CARD) have done well to minimise that to one half.
But that was not new - they had talked about it extensively.
Re Card Factory (LON:CARD) - medium term, the min wage hit will probably have hit Card Factory (LON:CARD) less hard than most other card retailers because its average LFL sales/sq ft is better and, with scale and vertical integration, it has more levers to pull to mitigate against the wage increase. As the market leader with low entry price points with some space to price up still according to its research, it will also benefit from its low income customer's wages going up.
So unless we all reduce our sending our cards, I think Card Factory (LON:CARD) is a going to grow mkt share and be a winner for a few more years yet with strong chance of a cyclical upturn at some point.
FWIW - I also think CARD is beginning to do better at adding gifts to its cards and party accessories business (following Moonpig (LON:MOON) although this is not yet fully reflected in its sales) . I am also more optimistic than I was about them finding international opportunities than I expected; wholesale entry to the US could be big and smart.
Net, with debt under control and a decent divi, I think Card Factory (LON:CARD) is a good prospect at anything up to 150p.
If the BOD didn’t think they would hit their full year profit target wouldn’t they need to confirm-in mid year announcement?
Card Factory (LON:CARD) Blimey, a fall from 141 to 103 in a matter of days. Anyone buying at these levels? Looks tempting.
Feels like it might dip below 100p so not tempted quite yet, but keeping an eye on it.
Card Factory (LON:CARD) a couple of months back it was bouncing between 90p and 110p, so would look again maybe below 100p, it is on the list but not rushing to use the cash pile today
Small cap market being battered. My large caps are all doing quite well but my smaller co’s are dreadful…..PERs moving back under the 10* range. Lots of 20-30% markdowns on no change to fundamentals. A sea change to a couple of months ago. Whilst the rest of the world performs we are stuck in a vacuum of our own making. Depressing
Out of interest which shares of yours are being hit? Most of my small caps holding up ok and the small cap index itself only off a few percent. For me it's the 2 oil majors which have hurt over last few days - tempted to sell BP and just keep Shell which seems a safer bet/less accident prone.
The press says that the Saudi Arabia has decided to drop its (previously assumed) aim to raise the oil price to $100 and decided to chase market share instead by raising output That suggests that the oil price may remain low for a while.
MPAC (LON:MPAC) is down 25% for no reason and now trades on a 1Y fwd PER of sub 10
Journeo (LON:JNEO) down 10% despite in-line and doing well
Card Factory (LON:CARD) bizarre 30% drop on an in-line statement and now trades on a PER of 6
Fonix (LON:FNX) in-line with a new country coming on-line where expectations take no account of that but should be quite earnings accretive. Very sticky revenues so trades on a higher multiple but suddenly hit 15% for no reason
Activeops (LON:AOM) off 20% on no news - yet growing well
Whereas my bigger stuff like Marks and Spencer (LON:MKS) and some financials all looking ok.
Hunting (LON:HTG) Suprising downward price action here . No bad news so far as I am aware.
Ive got a few pinned on the ropes too .
Vertu
Wynnstay
Centaur
Titon
Vertu an ok hold but i sold most a few weeks ago
Wynnstay solid enough hard to see any catalysts but nice company
Centaur is the one i think is buy
Titon probably going to profit warn so avoid
Got a few solid but cant see any upturn until post budget so hoping for some capitulation drops in the next period .
basically ill just increase all my current holdings if they get thoze silly spikes down .
Would you have time to look at Hargreaves Services report/
Campaign groups have urged the government to cancel major road building schemes including the Lower Thames Crossing, amid growing speculation that ministers could divert money earmarked for new roads into rail and other public transport. The transport secretary, Louise Haigh, is due to decide in a week whether to sign off a development consent order [DCO] for the £9bn road crossing linking Essex and Kent. - Guardian
Another potential Hargreaves Services (LON:HSP) contract about to be canned?
I hold. At least the German JV is finally providing income.
Good asset base, decent mgt, interesting property developments and pays a decent div, A long term hold for me
Ceres Power Holdings (LON:CWR) results seem promising. Any chance you could have a look Graham?
Restore (LON:RST)
A share I like the look of. The document storage division is the mainstay of the company with significant recurring revenue. Returning CEO, Charles Skinner is doing a good job in addressing the hubris of previous management, significantly reducing head office numbers, merging some operations onto the same site etc.
The company is trading in line and operating margins are expected to improve towards 20% from the current 16.5%, or thereabouts. Debt has also started to reduce
Also and what piqued my interest is that there has been some large director buy. Mr Skinner recently acquired 300,000 shares at 280p and the CFO picked up 50,000 at 271p.
Despite the above there has been constant selling of the shares of late. They are currently trading at around 246p. The shares are AIM listed and qualify for IHT, which may be the cause of the selling, but I have no idea if this is the cause or only part of the reason?
Comments from members wiser than me and there will be many welcome.
Not one I follow Jonno but from memory Naked Trader is in this and he doesn't get many wrong, might be worth checking his last 1-4 blog pages as pretty sure its one he's bought in last 1-2 months.
Restore (LON:RST)
Hi Jonno
I saw the director purchases as well, which led me to take a look for the first time a few weeks ago - I'm always intrigued when a CFO makes a decent sized purchase at a recent high.
The last Annual Report was full of useful information, but one page stood out - across all 5 divisions the highest market growth figure was predicted to be only 5%.
In their largest division the growth is only expected to be 1%.
This does not seem very exciting.
This led me to focus on the possibility of margin expansion and I looked back at the pre-covid years to ascertain if there was any obvious upward trend.
Sadly there didn't seem to be, with PBT% fluctuating between 5.8% and 11.5%.
For context he PBT% at the interims this year was 6.2%.
---
Next I looked at the possibility of growth by M&A. The main thing that put me off here was the existence of a much larger US-based company in the UK - Iron Mountain (NYQ:IRM). If there was anything available to acquire that was truly lucrative, then maybe Restore wouldn't even be able to buy it.
---
Having said the above:
My own near term estimate is that the company will generate £25m of FCF against an EV of c£400m. That's not bad, especially given how sticky their main product is. However, given the slow growth of the divisions I've decided to watch from the sides for now.
All the best if you decide to buy.
Cheers
A
I agree with all of that, excellent analysis Abtan, I too watch and wait, a good stock to own but only at the right level...
“Out of adversity comes opportunity”
Cant remember who said this though I did used to say it a lot when the shit was hitting the fan at PX.
Certainly made me feel better and in control not sure about everyone around me .
Anyway maybe were looking at the impending doom of a nasty budget the wrong way.
For sure the market will over shoot if removal of IHT and increase in CGT .
Good companies on AIM will remain good companies and in actual reality the 2 year threshold holding period only applies to a % of holdings not all
Going to have a good think this weekend but think my strategy will be a combination of
- forced seller on a % the big risers (transense, filtronic) to lock in lower rate CGT . No point hooding as any future gain is cancelled out by CGT . Could always buy back in after 30 days .
- sit on this cash and look for over reaction / forced selling which will push small caps to extreme volatility .
Dont scale in when buying as price will swing up on first sign of buyers , so buy big and buy bold .
Have a ready list of 10 - 20 stocks to buy in any meltdown and know no fundamentals have changed only mr market is having a meltdown .
Spiderman's uncle Ben.
Actually, maybe I've got the wrong Ben...
Mobico (LON:MCG) (I hold)
Showing signs of life.......clearly a beneficiary of the lower oil price? US bus sale impending? Or short covering over the last few days by Messrs Marshall Wace & others?
Paul - Not sure if you are aware already and apologies if anyone else has previously pointed this out, but you have now posted over 10,000 comments on Stokopedia (10054 to be exact!). Quite the contribution!
As always, thanks for your analysis and views.
Enjoy a well earned travel weekend.
BenHazz
CWK Not a tiddler at £2.7b, but what a good-quality company. It issued a trading update today towards the upper end of expectations, but did remain cautious about current market and wider economic and geopolitical conditions. The market reacted well, sending the shares of nearly 5%.
Over the last decade gross profit per share has been increasing at around 11% pa. Blimey. Return on capital has been high and they have little debt. Fwd PE is 18 and P/FCF is 20, which is at the upper end of what I'd be prepared to pay.
I hold, and of course it's been a little firecracker for me. In retrospect I wish I had bought years earlier. Hindsight is always 20/20 of course.
Agreed, did a deep dive a few months ago and the organic development over the last decade has been exceptional. I was therefore amazed to see Marshall Wace disclose a 0.5% short position earlier this month, which is equivalent to £13-14m. Proves they short anything that moves on the UK market.
MicroSalt (LON:SALT) I don't know a lot about the company itself but this seems the dumbest of enterprises. Salt with a bit less salt in it. i.e. watered down salt, diluted salt. Really?? That's it??
Hi doctor dave - I think the concept is that they have found a unique way of making salt provide the same taste with far less sodium through a technique that involves concentration. Clearly that could have a big market given we all eat too much salt with the corresponding health detractors.
However, the problem as with most of these type of things for MicroSalt (LON:SALT) is commercialisation. I haven’t seen much of it yet so I will steer clear. My issue with it is that you need to replace something that is relatively cheap and embedded in the supply chain and to do that you need good distribution and sales - and to do that well is expensive. It’s not like they can go to 4 or 5 big players, convince them of the benefits and price point and suddenly it is marketed around the world. They will have a vast network to navigate - that’s not to say it can’t happen of course with good management but is probabilistically unlikely and they are not endowed with a large war chest to do so.
I compare that with 4Basebio (LON:4BB) which is also early revenue and the prospects appear to be night and day. This is artificial dna that has huge advantages over existing dna (not least safety) and can be done much cheaper and in scale. Given the biotech and pharma industry is rapidly moving to the use of dna it’s a rapidly growing market and 4Basebio (LON:4BB) is on the forefront and mainly just need to convince the tier 1 pharmas. They’ve already done that with one and more on the way…..so their route to commercialisation appears a lot more straightforward. And they’ve done it before so the management track record is strong. This view appears to be shared by some clever fund management institutions that have just given them a £40m war chest at above the current share price to make it happen. So clearly they think it is worth a lot more.
Not only that if you look at online reviews , it doesn't taste like salt to many people.
Agree this totally
Good spot doctor dave , As a previous Peppermonger & Salt trader (I kid you not) ...I wish them well but this is going to be super hard for MicroSalt (LON:SALT) ...even with patents even with the large US market.
Lo salt has been around for ages. And no one cares. Fat-sugar-salt is the holy Pringle trinity. Obesity & cardivascular disease continue to rise. Another pringle anyone?
Salt is the 2nd oldest original trade (available everywhere from Timbuctoo to Droitwich) and it's very very cheap and very plentiful. The sun dries the sea- you sprinkle it on everything. The simplest business model ever.
Anything manufactured (or dried say with gas or electricity) has to compete with sun dried Guerande -Fleur de Sel or China's 53 Million MT from salt pans which are basically free.
If MicroSalt have a ninja sales team and a super brand they might survive a few years- they don't have much money.
If you invest I salute you - but I wouldn't recommend investing your whole salary. (see what I did there?)
Doctor Dave, it would certainly be dumb if you put it into a soup or stew, because then you need just as much sodium chlorine to get the same level of saltiness. But if it's sprinkled on crisps or chips you need a lot less to get the same salty flavour on your tastebuds.
Whether it turns out to be a dumb investment - we will have to wait and see.
Just been reading yesterdays comments about the "good life" in the sunny mediterranean. Too hot and it is going to get hotter. Try the Scottish Highlands instead. I can recommend the crofting lifestyle. No Olives but lots of good tatties!
No Olives but lots of good tatties!
Plenty of top restaurants scattered around the Scottish coastline
I love the Hebredies, Inner and Outer - the scallops are amazing.
We went to beautiful Murano in early August. My fair haired frau, with her factor 50 sun tan lotion complained, as did I, about the heat. I said next year we're off to Oslo!
Just spent a few days camping in the Highlands the sun shone every day the views were sublime, good for the soul
Don't forget the wonderful midges :-)
Midgey jackets work a treat,
My morning smallcap tweet: World Chess postpones endgame with cheques
Puretech Health (LON:PRTC) Big Technologies (LON:BIG) World Chess (LON:CHSS) FIH (LON:FIH) Totally (LON:TLY) SLF Realisation Fund (LON:SLFR) Real Estate Credit Investments (LON:RECI) Iofina (LON:IOF) Invinity Energy Systems (LON:IES) MicroSalt (LON:SALT) OptiBiotix Health (LON:OPTI) R E A Holdings (LON:RE.), AdvancedAdvT (LON:ADVT)
◄PureTech Health (PRTC)► KarXT gets FDA approval for the treatment of schizophrenia in adults, the first new drug mechanism approved in over 50 years. Co gets $29m milestone payments. Bristol Myers Squibb to market KarXT as Cobenfy. [SP=150.4 Cap=482m]
◄Big Technologies (BIG)► c.£6m buyback. [SP=117 Cap=349m]
◄World Chess (CHSS)► Cheques please! €1.2m subscription at €0.10, a 59% premium, to keep the Knights on. Will be made in 3 instalments, last on 15 Jan 25. [SP=5 Cap=35m]
◄FIH (FIH)► AGM stmt. Special div of 10p. The Falkland Islands Company had a difficult start to the this FY due to continuing slippage of construction tender awards. [SP=257.8 Cap=32m]
◄Totally (TLY)► wins 2 contracts worth c.£6.1m. [SP=8.5 Cap=17m]
◄SLF Realisation Fund (SLFR)► to return 0.5p/sh to Ordinaries and 2.25p to C shareholders. [SP=1.61 Cap=11m]
◄Real Estate Credit Investments (RECI)► another buyback, of £10m max. [SP=127 Cap=282m]
◄Iofina (IOF)► signs agreement for new plant, IO#11. [SP=19.3 Cap=37m]
◄Invinity Energy Systems (IES)► H1-June. Sells a 1.2 MWh Mistral battery system. [SP=8.88 Cap=39m]
◄MicroSalt (SALT)► H1-June. The rollout of MicroSalt across new and/or further product lines has been slower than hoped but "increasingly confident of announcing further commercial volume orders before the end of 2024". [SP=51 Cap=25m]
◄OptiBiotix Health (OPTI)► H1-June rev down 21%. Guides FY rev well ahead of FY23. Straining to sound confident eg "substantive opportunity to leverage market interest by increasing customer awareness blah blah blah". [SP=16.5 Cap=16m]
◄R.E.A. (RE.)► further re changes to selling prices and export tariffs for crude palm oil and crude palm kernel oil in Indonesia. [SP=80 Cap=35m]
In line: ADVT
On form this morning, Mr Contrarian. "World Chess (CHSS) 1.2m euro subscription to keep the Knights on". Love it!
OPTI. Another TW. howler! Thank the Lord I no longer listen to his hot share tips.
Yes, I found out that he is the Joker in the pack. I do hold OptiBiotix Health (LON:OPTI) in my kennel.
Some appreciation (will not do any harm) for people that have been around for so many years unraveling so many scams that went to ZERO.
There have been definitely more howlers here than TW site.
I don’t rate OptiBiotix Health (LON:OPTI) nor KEFI Gold and Copper (LON:KEFI) and I think TW is being played from the people involved in both.
At the end of the day it’s all about DYOR.
All the best
Who is TW, please?
Tom Winnifrith at shareprophets.com
An honest, reliable and value for money service that actually cares about small cap investors.
All the best
Winnifrith is a very marmite character. He has a track record for exposing scams - from memory he was one of the first to point out quindell, globo and Chinese aim stocks (and probably others) as things to avoid. He was also a long term booster of opti. Not read him for about 3y.
TW does a really great and important job in rooting out the greed, fraud and general uselessness which plagues the small cap arena. I always check what he has to say about any share tha t I might be considering and he has saved me from a few bad mistakes.
I would be much more cautious about his tips mind!
Yiannos, thank you for the clarification and helpful comment.
Richard
CHSS What a sorry state of affairs. StockRank of 3. Crikey. Surely the point of investing in pre-profit companies is seeing growing revenues, which it hasn't done. Hmmm.
Or
The cheque mate? - it's in the post
Forgive me but it has been a big week for Macro. I spent yesterday relooking over Zotefoams (LON:ZTF) which I like but don't own yet. Feels like a starter position is warranted. My guess is the market has just got a little bored waiting for news... and 15x seems fine versus 20x where reZorce already had some value attached. A fair price not a great price Id say. One slight concern would be if they go it alone and need to raise money.
Anyway back to macro and China. It has continued to follow through, more fiscal policy and stronger rhetoric. Is this a "whatever it takes" moment, certainly feels like it. HK and Shanghai both up 2.5% again...so expect Fidelity China Special Situations (LON:FCSS) to follow and also, esp. in the UK commodities exposure. Think copper, silver, gold, etc... I would add oil but this market has more issues so it's less clear.
In the short term I only see positives. The twin policy moves from the Fed and China will reduce the impact short term (weaker) data has... and so Q4 looks to be sitting pretty. In fact data should be improving in Q125 and so who knows, possible Goldilocks scenario. Of course longer term, we probably should think less rate cuts everywhere and possibly more inflation. This you will see in rising long bond yields ...the steepener. The inversion has reversed ( without recession) but remains mild ( or flat ) so 2s-10s...20bps and 2s - 30s...50bp.....and I would say at 100+ and this becomes a talking point. ie 30 year Treasury yield 5%. ( I would add; this is make hey time for financials .. esp Banks )
These are positive problems however since the fuel will have done its job... so the economy and earnings should be stronger... and yes, that benefits a more cyclical stance. Hence the rally in the UK, Sterling, comodities etc small caps always benefit last but potentially benefit the most.
Not much change form me, staying long and fingers crossed.
Morning RD, I asked the CEO/CFO about the possibility of a raise to support the Rezorce rollout. Their response was essentially that the size of the market opportunity and what they are looking to do would not be able to be supported through a fundraise and it is not something they are exploring.
The mindset being that if the product is market ready, they need a financial partner to support them as they are looking at sums well beyond the market cap in order to meet the possible demand for the product. This was a few months ago but I think the raise is something I'm confident we don't have to worry about.
So we are just back to people getting bored and shares retracing previous strength.... so the entry level looks attractive to me.
Agree 100%, it's just buyer boredom. If it wasn't already my largest position I'd be topping up.
According to today's FT apparently: "UK chancellor Rachel Reeves is ready to water down her planned Budget tax raid on non-doms amid Treasury fears that some of the measures may fail to raise any money." It comes amid warnings that thousands of wealthy foreigners with non-domicile status were looking to leave the UK.
Hopefully this 'smell the coffee' moment might even percolate across the rest of her 30th Oct Budget.
Meaning maybe other 'negative tax raising' proposals she was considering - such as removing EIS or IHT relief on AIM shares - also get shelved?
https://www.ft.com/content/7c0...
Let's hope she gets her coffee this morning with a few extra shots (and she normally drinks decaff).
Thanks Paul
I believe Rachel Reeves has already announced the extension of the EIS and VCT regimes, with their respective sunset clauses being moved back 10 years to April 2035 >>>>>
https://taxscape.deloitte.com/...
But we await her plans on BPRs more generally, specifically applicable to AIM shares.
Thank you, did not know VCT had a sunset clause.