Small Cap Value Report (Fri 28 July 2023) - TMG, PODP, FRAN, WHI, FOXT, CHRT

Good morning from Paul. We have Graham here today too, despite it being a Friday, to help cover some of the backlog items from yesterday, thanks Graham!
Cohort (LON:CHRT) - CEO interview
This niche defence group impressed me with its recent results - record profits and order book, strong balance sheet with net cash, and a reasonable valuation. So I reached out to invite the CEO to let me interview him over the phone. As usual, I select only companies that I think are interesting, and GREEN on our traffic lights here, and it's completely independent, as I don't charge any fees.
Anyway, here it is - Paul Scott interviews Cohort CEO Andy Thomis, 28 July 2023.
Let me know what you think in the reader comments here, as quite a bit of work goes into preparing these, so it's good to know whether people find them worthwhile (or not).
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
I've (Paul) got to prepare for my next CEO interview with Cohort (LON:CHRT) this afternoon, so unfortunately we're not making that much of an impact on the backlog items, sorry about that -
Summaries of main sections below
Franchise Brands (LON:FRAN) down 5% yday to 140p (£271m) - Interim Results - Graham - AMBER
The outlook is at least in line with expectations at this company which offers a range of van-based services internationally through its franchisees. Results are complicated by acquisitions, including a very large one this year (£200m+). Worth keeping an eye on this.
WH Ireland (LON:WHI) down 60% today to 8.9p (£6m before a placing) - Trading Update and Proposed Placing - Graham - AMBER
I remain neutral as it fixes its balance sheet with an emergency placing, shortly before it would have needed an orderly wind down. There are few signs that this company is being run for its shareholders but hopefully it can ensure its survival for the medium-term now.
Foxtons (LON:FOXT) 38.6p (£116m) - Interim Report - Graham - GREEN
Trading is in line with expectations at Foxtons as it shows both revenue and profit growth despite adverse conditions in the London property market. With recurring revenue from lettings keeping it in the black, I’m happy to give this stock the thumbs up at this stage.
Paul’s Section:
Profit warning special
Yesterday we had 5 minnows warn on profit, as follows, taken from yesterday's agenda -
Mission (TMG) - mild profit warning (down 13%)
RBGP - profit warning (down 21%)
Empresaria - TU £26m (down 28%)
XL Media - TU £26m (down 5%)
PodPoint - PW in the afternoon.
I’ll have a quick look at each, to see if there are any bargains or any avoids. These may not interest you, but I want to get facts/views into the archive, so that if anyone is temped to buy them, they can first check our analysis. If that helps people avoid a lousy investment (or find a bargain occasionally), then it's worth doing!
Mission (LON:TMG)
42p (£38m) - Trading Update (mild profit warning) - Paul - AMBER/RED
MISSION Group plc (AIM: TMG), creator of Work That CountsTM, comprising a group of digital marketing and communications Agencies delivering real, sustainable growth for its Clients, is pleased to issue a trading update for the six months ended 30 June 2023 ("the period" or "H1").
The point of difference with TMG is that it’s an acquisitive group, buying marketing/PR agencies that are not London-centric. History has been a bit mixed, I’ve followed this for many years. It got into balance sheet/debt trouble and looked precarious for several years, but remedied that, and has been a fairly decent dividend payer. So it’s a reasonably decent company I think, which might be worth putting on our watchlists as a medium-term cyclical recovery candidate. Obviously marketing companies usually see a downturn in business, often quite serious, when the economy goes into recession. That’s because marketing budgets are a quick & easy way to slash overheads for the customers, when times are hard.
Accounting adjustments at TMG are extensive, and sometimes questionable.
Yesterday’s update says -
H1 revenue £42.0m (up 12% on H1 LY), helped by notable new client wins.
“Headline” PBT in H1 is £1.0m, down 44% on H1 LY £1.8m - it blames higher interest rates.
Surely profit should be up, not down, when revenue is up 12%? It blames margin mix, esp from US tech cos.
H2 weighting to profits is usual, which I’ve confirmed on Stockopedia’s handy half-yearly results table here.
Full year guidance -
Whilst the Group remains on track to meet full-year guidance, profitability is likely to be at the lower end of the Board's expectations, with profit before tax expected to exceed that of 2022 (£7.8m).
That’s not too shabby at all, given tough macro. Although I’d suggest that the risk of another profit warning in the more important H2 looks quite high to me. For that reason I’d be reluctant to get involved at this stage.
Outlook -
"Despite the more challenging trading environment, it is pleasing to see double-digit revenue growth and continued strong Client retention and acquisition. The investments made across the Group in recent years underpin a robust performance for the period.
"We enter H2 with a degree of caution linked to the wider economic backdrop but with the tailwind of notable Client wins and an encouraging pipeline of new business opportunities, which reinforce the Board's confidence in the long-term outlook for the Group."
Paul’s opinion - I wouldn’t dismiss TMG out of hand. If you’re fishing in this sector right now, then you’re obviously looking for bargains, but must have a stomach strong enough to hold through any profit warnings (high risk of those happening, I’d say). The worst thing is to buy now, hoping it won’t warn on profit, then sell in despair when it does.
Given its history of doing too many debt-fuelled acquisitions, then getting into trouble in recessions, I would pay particular attention to the balance sheet and debt, before considering risking any money here. Looking at its last balance sheet, risk is too high for me, as it has too much bank debt, plus some acquisition-related liabilities. NTAV was negative £(9)m at Dec 2022, so I think that rules it out for me at this stage, but I’ll keep an eye on it as a possible punt once the macro backdrop is improving.
On reflection, I think with a weak, overly indebted balance sheet, and operating in a cyclical sector, I'll have to lean towards a slightly negative stance, so AMBER/RED, to reflect the higher risk.
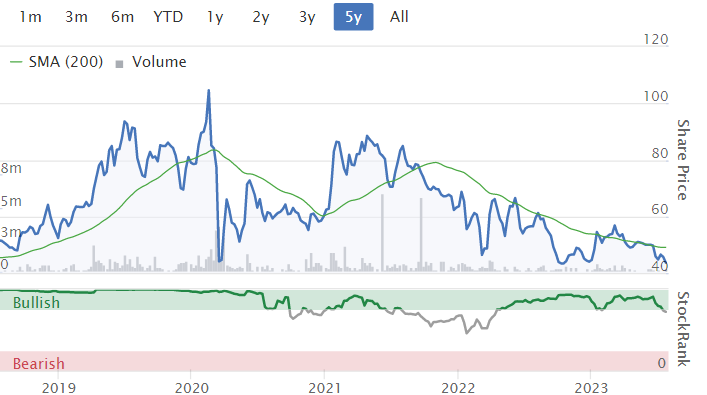
As the 5-year chart below shows, it's not created any sustainable shareholder value, being back down where it was in later 2018. There have been some divis along the way though. I wouldn't rely on the forecast 7.3% dividend yield, given its weak, indebted balance sheet, those divis are not really affordable in my view, during tough macro uncertainty.
Pod Point group (LON:PODP)
30p (£47m) - Updated Guidance (profit warning) - Paul - RED
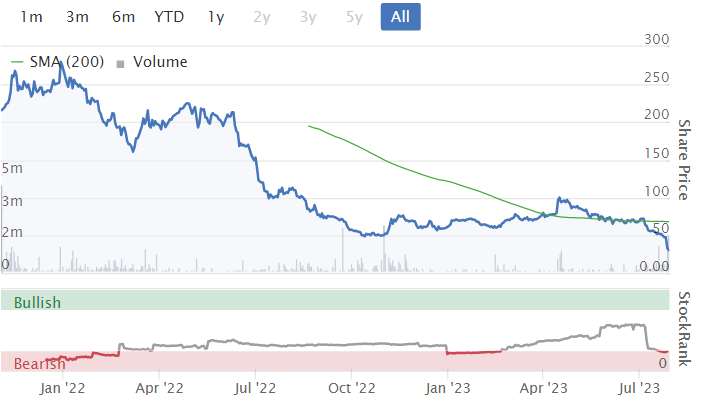
I’ve sounded the alarm on this EV charging point installer before, because it simply is not a viable business - that’s glaringly obvious from the previous results. My first review of it here in Nov 2022 concluded that it looked a lousy investment. It took a while for the market to realise this too, but the share price has really been tanking since the inexplicable 100p high in May 2023, we’re over two-thirds down from that now, at 30p.
The founder was ousted recently, and his cash-burning strategy has left a big headache for new management. Their update yesterday was a profit warning, saying -
Revenues of £60m expected in FY 12/2023 (StockReport shows consensus of £83.4m)
EBITDA loss of £17m! (not a typo)
Net cash of £58.8m - above the market cap, but don’t get excited, as it’s ripping through that cash, and no doubt will also incur hefty restructuring costs too. Cash was £74m at Dec 2022.
Paul’s opinion - just awful. EDF still owns 54%, so the logical thing would be for it to re-absorb PODP at some point, or just let it go bust once the cash has all gone. As it’s in EDF’s interests to have more EV charging points installed, then I see a potential conflict of interest here.
Can new management at PODP restructure the company so that it might be able to generate profits? I doubt it personally. Most of its business is one-off domestic installations for EVs, on peoples’ driveways. There’s no money in that, so why bother? Other larger installations mean PODP spending on capex up-front, so further depleting its cash pile.
As things stand, I think this is a completely hopeless situation. Something has to change radically, otherwise the share price is just likely to keep tracking the cash pile downwards, with the occasional rally along the way providing selling opportunities. The institutions are high & dry, but there’s no excuse for private investors holding on. Better to throw them out, even if it means taking a haircut, or resign yourself to ongoing losses.
This was another of 2021's awful IPOs. Were fund managers' brains fried by covid, I wonder?!
Graham’s Section:
Franchise Brands (LON:FRAN)
Share price: 140p (-5% yesterday)
Market cap: £271m
This is the company whose 12% shareholder, Nigel Wray, must be hoping will turn into the next Domino’s Pizza.
The Executive Chairman at FRAN, Stephen Hemsley, is also a 12% shareholder here. He spent 21 years at Domino’s and took it “from private ownership to a market capitalisation of almost £1.5bn”.
Both Franchise Brands and Domino’s are based on the franchise model, a business structure that we talk about regularly here at the SCVR.
Let’s briefly review these interim results from Franchise Brands:
System sales (i.e. sales by franchisees to customers) +81% to £146m
Revenue for FRAN +57% to £70m
Adjusted PBT +45% to £8.6m
Net debt £79m (it previously had a net cash position)
The situation here is complicated by acquisitions. As we discussed in April, FRAN spent over £200m on a deal to buy Pirtek. The company borrowed £110m and raised £110m in new equity at 180p.
This means that we really need like-for-like numbers for FRAN, as they are more meaningful than the total numbers. Today’s report doesn’t give me an overall like-for-like growth number, but it does give the following information:
Filta International: Like-for-like system sales up 16%
Filta UK: like-for-like growth of 5%
Kemac Plumbing: Like-for-like sales up 11%
Outlook:
The outlook for the remainder of the year is positive and we anticipate full year performance to be at least in line with expectations.
The deleveraging profile is ahead of schedule and we fully expect the acquisition facilities to be repaid within 5 years.
Graham’s view
I’ve previously been neutral on this one and I’m inclined to stay that way today, although I must admit that the declining share price is starting to get me interested:
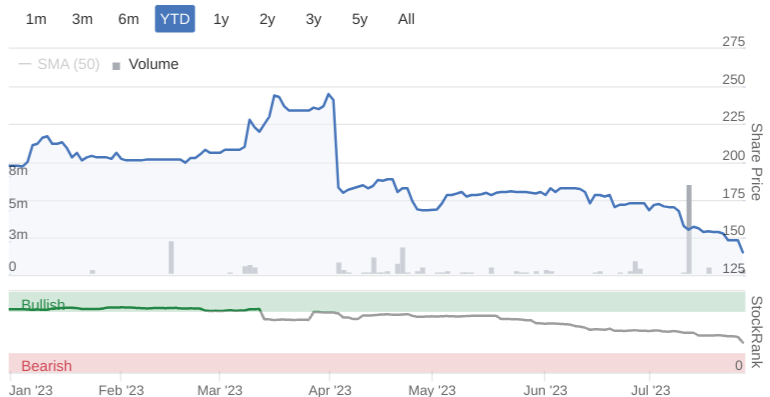
The share price is back at a level first reached in early 2020, while revenues are profits are reaching new heights:
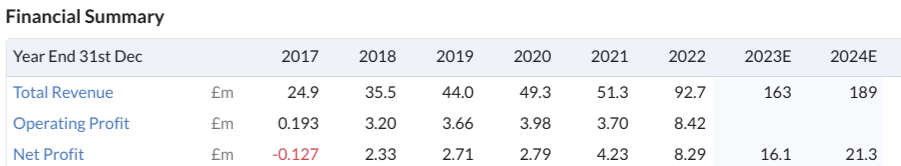
However, are these “real” profits? Today’s income statement shows less than £1m of statutory profits, although it’s closer to £4m if you are willing to add back in the non-recurring items. Adjusted EBITDA looks unrealistic to me at £12m.
On balance, I’m still neutral. However, there are certain people you shouldn’t bet against and I do think that Nigel Wray might be one of those people. I would be tempted to own a handful of these shares just on the off chance that it turns out to be the second coming of Domino’s.
WH Ireland (LON:WHI)
Share price: 8.9p (-60%)
Market cap: £6m
This has temporarily fallen below our market cap cut-off limit but I thought it was worth commenting on:
The Company announces it is carrying out a conditional placing to raise approximately £5.0 million, before expenses, by way of the issue of new ordinary shares in the capital of the Company (the "Placing") to certain existing shareholders and other investors at a price of 3 pence per share (the "Placing Price").
The Placing Price represents a discount of approximately 86.67 per cent. to the Closing Price of 22.5 pence per Ordinary Share on 27 July 2023, being the latest practicable business day prior to the publication of this Announcement.
A deeply discounted placing is a disaster for the value of a company’s existing shares, and a discount of 86.7% is about as bad as it gets.
To raise £5m at 3p per share, the company will need to print 167 million new shares. There are only 65 million shares currently outstanding, so that’s dilution of over 250%.
Or in other words, the existing shares will represent less than 30% of the company, after the placing.
Why the desperation to sell shares at this level?
The company lets us know that they’ve made a £1.1m loss in Q1 (April to June), and they believe that they will remain loss-making “until at least November 2023”.
And then things get really serious:
In recent weeks… the Company has been in discussion with the FCA… in order to ensure that, in the absence of the injection of further capital pursuant to the Placing, the Company could deliver a solvent wind down for the Group, if required, in line with the Company's solvent wind down plan ("SWDP")...
On the basis of the adverse current and forecast trading and resultant losses, without further funding pursuant to the Placing, the SWDP would be required to be implemented on 31 July 2023.
In other words: without this placing, it is highly likely they have reached the end of the road.
That explains the desperation to raise funds.
As for why the placing is at such a discount? It’s simply a matter of supply and demand. In discussions with potential investors, they must have found that nobody wanted to refinance them at 22p. At 3p, there was some interest.
Here are the top existing shareholders:
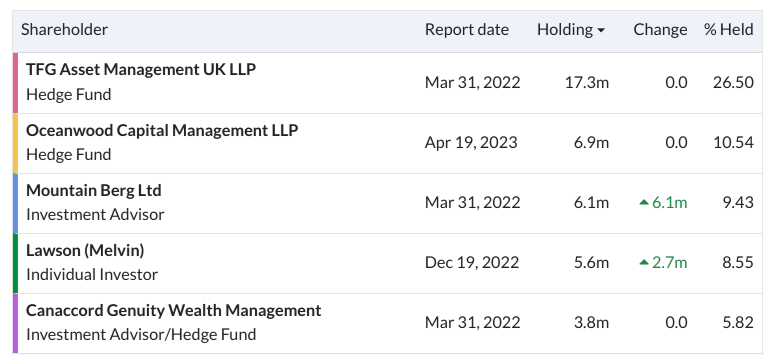
Top shareholder TFG have indicated they will put in between £2m and £2.5m, so they will remain the top shareholder.
Irony: the broker for the placing is none other than WH Ireland. I suppose they will at least save on some of the costs associated with raising money!
Graham’s view
Firstly, I’m relieved to see that I took a neutral stance on this one in April. I’ve been bullish on many financial stocks, including small brokers and boutique investment banks, for the past year. But WH Ireland’s history of losses kept me cautious. I said “it seems to offer a decent service to its wealth management clients, but it hasn’t done enough over the years to suggest that its stock is worth buying.”
Today’s news puts a new spin on things, and not in a good way. It shows that management drove the company right to the cliff edge, where they were just a few days away from winding down.
They will now reduce headcount and seek to cut costs, but does that mean the stock is worth backing at the current level? I would say no. At around 9p per share, that implies a new market cap of £21m (with 232 million new shares after the placing). This is superficially too cheap for a company with total AUM of nearly £2 billion, but the company hasn’t paid a dividend since 2015 and the track record of profitability is spotty to say the least!
So I’m not convinced that this outfit is being run for the benefit of its shareholders, and today’s 87% discounted placing would appear to confirm that. I’ll stay neutral on the basis that I wouldn’t want to short it after it fixes its balance sheet, and it could be a takeover target. But I wouldn’t want to buy it either.
Foxtons (LON:FOXT)
Share price: 38.6p
Market cap: £116m
Let’s check in on this estate agency business. The highlights table is promising:

Note the small difference between adjusted operating profit and actual PBT: I love to see it!
London property sales remain very difficult, but Foxtons’ success in lettings offsets this.
CEO comment:
Our continued focus on growing non-cyclical and recurring revenues is working and has enabled us to deliver strong revenue and profit growth despite a challenging sales market and investing in recruiting more fee earners.
In the first half of the year we cemented our position as London's largest Lettings and Sales estate agency brand. We not only had the largest market share of instruction volumes in London, but we also grew instruction market share quicker than any of our competitors as recently implemented operational upgrades yielded significant gains.
Organic growth in non-cyclical lettings revenue was 14%. Lettings revenue almost hit £50m.
Sales revenue was down 16% to £17m. As indicated above by the CEO, the company maintains that it grew market share despite this.
Outlook - trading is in line with expectations. In sales, volumes are up as deals in the under-offer pipeline are completed, but new enquiries are lower (thought to be due to rising mortgage rates). So it’s a mixed outlook for H2 in sales.
Net debt is £2m and is not at a level that worries me. The company has access to a £20m RCF.
Interim dividend is unchanged at 0.2p.
My view
I feel obliged to take a positive stance on this stock today, something I’ve resisted doing before. In April, I described Foxtons as a turnaround stock that “might” succeed. The share price hasn’t budged since then but the turnaround is materialising, and it’s doing this despite interest rate rises in an overall very tough property market.
The exciting prospect is that if the company can generate this level of profitability when the sales market is in the doldrums, what might it do when London property sales are booming again?
It’s a different business these days, compared to what it was before. It now has a very substantial and stable revenue stream from lettings, combined with an option to generate large profits from sales, when conditions allow.
So I’ve seen enough here to give it the green light at this valuation.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Hi Paul - did you manage to complete the review on Mobico - or have I missed something?
Thx Paul
Brilliant stuff this week Paul and Graham much appreciated. as an aside Zotefoams (LON:ZTF) with whom you had an equally-interesting interview recently has shown signs of recovery on no particular news up 16% this week . Let’s hope this is a sign we have reached the bottom and recoveries await.
Thank you to everyone who has left feedback on my Cohort (LON:CHRT) interview, much appreciated. I tried not to duplicate the results presentation published by Equity Development, so did my own thing, focusing on a few key areas.
I agree the CEO comes across really well, and being very long-serving, he feels a safe pair of hands, particularly when it comes to acquisitions, not rushing in to buy anything, but waiting for the right opportunities.
Regards, Paul.
My weekend tasks are now sorted!
Spreadsheet is updated, so you can quickly see what companies we cover, and search for anything very quickly.
Podcasts recorded & distributed on podcast platforms, or you prefer the web versions, they're here:
Part 1 (small cap companies reporting), and
Part 2 - markets/ macro news & views.
I did a bit of more general ranting about various topics too. It's free, and not moderated, so I can say what I like in the podcasts, so sometimes let rip where I've otherwise had to hold back.
Podcast Mystery Share - my best idea for the week, held back for Stockopedia readers, which is Gaming Realms (LON:GMR) - see my section in Thursday's report here. I think this one is worth a fresh look - I've previously been quite sceptical about it, but fair do's, the company has delivered on its promises and is now nicely profitable & cash generative, and showing strong organic growth. The valuation still looks reasonable, so I think this could be poised to re-rate once investors become more bullish, and focus on the 2024 forecasts. Providing, as always, that nothing goes wrong, always a risk with all small caps.
Best wishes, Paul.
Many thanks Paul for another superb podcast. Always entertaining and very informative.
I do just want to comment about Somero Enterprises (LON:SOM. I don't think they have ever claimed to not have competition. In fact to the contrary, I think they have acknowledged they are in a very competitive space - I believe management have been very upfront about this.
It has been discussed in the last 2 management interviews on PI world. approx. 32mins in to the first link (interview from 5 months ago), and approx. 19m 45sec in the 2nd link (interview from about 10 months ago)
Somero Enterprises (SOM) Full Year 2022 results presentation - March 2023 - YouTube
Somero Enterprises (SOM) Interim Results 2022 presentation - September 2022 - YouTube
Anyway as I said, great podcast, just thought I would mention this for some further context / clarification. And many thanks also to Tamzin and PI world, I find these interviews really useful.
ps. apologies for the post at graveyard hours, needed some time to kill while waiting for the UFC :)
Hi MetalMaid,
Many thanks for those interesting points on Somero Enterprises (LON:SOM)
I'll follow the links you provided - sounds like I might be a little out-of-date on Somero's position re competition. It's probably going back a few years now, when I recall Jack Cooney saying there wasn't really any competition, sounds like that might have changed - which could put pressure on SOM's high margins & cashflows perhaps?
Regards, Paul.
I like the longterm ownership of the largest holder. Thank you for bringing that out, I'd not spotted it. I knew the Alvis connection. Alway was a fan of Alvis, but I'm getting distracted.....
I used to hold Cohort (LON:CHRT) but sold a couple of years ago. They are on my watchlist but I remain concerned that with the UK MoD (perennially short of funds) as their primary customer (over 50%?), the long term order book is great - but the pace of organic growth is probably constrained by MoD funding, and the very long time - many years - and expense it can take to win (or lose) long term defence contracts.
It is a slightly eclectic group of companies. Not necessarily a bad thing. It gives them opportunities but probably limits their ability to act in concert with scale. And why they retain the individual company structures? MASS is probably the crown jewel in the business. Very high margin software service business with repeating long term MoD contracts over decades. But its small and its not clear how it can scale up? If it could - it would probably transform their prospects. SEA (in a former life I have background in the defence/aerospace sector and worked with them occasionally) is doing well, probably also a crown jewel, not to the same margins, but with more opportunity to scale up through exports? It's been disappointing that Chess seems to have been unable to capture the rapidly expanding anti-drone market so far? Something seems to have not quite been going right there with talk of 'legacy issues' and 'margin improvement'. But winning long term defence contracts against tough competition can sometime turn out to be a poison chalice, locking you into low margin business that you under-bid to avoid losing it? Been there. Tried hard not to do that.
The ROCE/ROE and operating margin are towards the bottom end of where I'd want to see them? Which probably fits with the modest forecast growth in organic revenue and profits? Which you tried to tease out in the interview.
If they can make another good acquisition or two, perhaps building scale in their Sonar or anti-drone businesses, or driving up exports then I could see them stepping up a gear. They don't currently have access to the US market which is the gorilla in the playground and would be very interesting. But the price of defence businesses is probably rising now as defence spending increases. And countries that were happy to buy abroad to save a buck are suddenly getting concerned about their domestic defence capabilities. It may be harder to acquire at the right price now - but Cohort have a good track record here.
I sold my small cohort holding to build my holding in MS International (LON:MSI) who have quite a transformational opportunity in the anti-drone market, primarily through the US and international markets. Also I hold and am buying - when funds allow - Science (LON:SAG) whose recent acquisition of TPGroup has transformed them into a defence contractor with potential access to the US market. I'll be watching progress atCohort (LON:CHRT) closely - they are high on my watchlist - and if it looks like they'll step up a grear they'll be on my buy list. At the right price. I wish them well! In my view the UK needs more really good steady firms like Cohort,
and thanks once again for the excellent interview,
cheers
Mark
Thakns Mark, that's very interesting, and it sounds like you know a lot more than I do about Cohort (LON:CHRT) and its sector! I also like MS International (LON:MSI) (I hold) due to the big recent defence order intake. CHRT looks in a similar position - big order intake, although it's a good point you make about its dependence on the MoD.
Science (LON:SAG) is another one I also like, so we're perfectly aligned here - I like being in such good company, as I know from your track record here that you're shrewd!
Regards, Paul.
Reiterating others comments, but a great podcast switch Cohort (LON:CHRT) Paul. It really gave me confidence in the company as an investment. CEOs knowledge was in-depth and it's amazing that he and CFO have been around for so long as a steady ship. Also like the flexible approach of the various companies in the group. Overall it's got the Thumbs Up from me. PS LOL at the Keele Uni mixup. All the best.
Hi Paul, I really enjoyed your interview with Cohort (LON:CHRT) I have held a small position for two weeks and on the strength of your podcast I have bought more. I was impressed with Andy's ability to provide in-depth, clear, jargon free and concise information. I was also given the impression that if you are a talented engineer Cohort would be a great place to work and build a career. Looking forward to the next one - Thanks
Hi Paul
I listened to the podcast with Cohort (LON:CHRT) and I thought it was very interesting. I particularly liked how reassured and knowledgeable Andy Thomis is. I also liked the fact that both he and his CFO have been with the group since it's inception.
Your questions drew out some interesting information - not least that the largest shareholder, despite retiring, still hasn't sold his holding and maintains a keen interest in the business.
I also agree with Steven below. It is so important, having asked a question, to shut up and listen to the answer. Sometimes, if you leave a long enough pause the interviewee feels the need to say something and so you could even draw out more info than you bargained for.
Please keep these up as it helps us to make a better judgement about the company in question and who is running it.
Ps Did Cohort supply the gun that you fired to start the new bull market?
Looking for something to invest in. Maybe tomorrow.
Oh I see you're doubling down. Doubly boring.
Paul, Enjoyed your Podcast with Cohort (LON:CHRT) and thought the CEO was very clear in describing company and how it operates. It's always nice to hear someone talking passionately about their company . I also liked how you gave him plenty of time to talk about his company without unnecessary interruptions. Thank you found it very useful and informative.
Thanks steven! Much appreciated. These interviews are a lot of work, for no money, so it's nice when people find them useful, and let me know. Thank you! :-)
Home Reit (LON:HOME) makes the defunct Woodford Equity Income Fund (WEIF) look like a well run investment.
Excepts from today's RNS
[The new manager] AEW is now taking steps to assess and stabilise the property portfolio and the
financial condition of the Company and will seek to maximise income and
capital returns.
For the period 1 May to 30 June, the Company has demanded £8.77m of rent, of
which 7% has currently been collected.
AEW to take
steps to assess and stabilise the property portfolio and improve rent
collection through extensive tenant engagement and asset management
initiatives.
2-3 year stabilisation period
No indication of when the accounts will be filed, allowing move towards relisting
MidCap Vanquis Banking (LON:VANQ) has warned today. I don't hold, as I do not think this sort of sub prime lending is very sustainable, but maybe an interesting read across to other such lenders. The credit card bank has moved into loss because of a much higher interest cost, higher overheads and larger impairment charges. I guess this sort of business has been squeezed as they were already charging very high interest rates to borrowers. Doesn't look very well positioned if we are heading into a recession.
Franchise Brands (LON:FRAN) - Graham, LFL figures and other useful info were given by Exec Chair Hemsley yesterday in his results presentations. The presentation I watched is (or will be when the recording is ready) at https://www.investormeetcompan... I think Hemsley is the star here; Wray (and I) cling on to his coat-tails, as he (and I) did in Domino's Pizza (LON:DOM). He has a clear plan for dealing with his scarily-big acquisition of Pirtek and getting the debt back down.
[Disclosure - i have held Franchise Brands (LON:FRAN) for a while now although I top-sliced on the way down. I will now be buying back in. ]
I often despair at so called advisors being paid good fees for what I would consider poor general advice on market dynamics. Two recent examples….
GlobalData (LON:DATA) . Split the stock to reduce spread and make more attractive to retail investors who can’t possibly afford £12.50 a share!!!
net result - spread is now 4% whereas before it was 3% and it’s become less attractive, driving the share price down 10% in an otherwise positive market…….
I also spoke with the board of another company recently whose advisors had said the impact of an announcement would likely be x% and in the event it was 4* x% !! The advice wasn’t really worth the paper it was written on.
Sigh………… irritable mumble over!!
Every time someone mentions GlobalData (LON:DATA) here, I check the register of shareholders to see if Michael Danson still owns over 50%. Looks a wonderful business with all that high margin, high return, sticky, recurring subscription revenue. Such a pity about the risk of a delisting, which quite possibly won’t happen. But the risk is there.
Why does Stockopedia not have data on GlobalData (LON:DATA), for institutional holdings or largest holdings? It is 1.4bn mcap.
GlobalData (LON:DATA) "Institutions Insufficient data available"
You could try the green button which means them asking Refinitiv and waiting for a reply. On the other hand the company provides detail here : https://investors.globaldata.c...
Still waiting for other reported issues to be resolved. One is 5 months old, similar issue with director deals.
Hi Boon - I agree with you. PayPoint (LON:PAY) is ignored by the market as being ex-growth, but all its divisions grew impressively. The long-term revenue trend is somewhat impacted by disposals and changes in revenue recognition (i.e. net or gross revenue recognition).
The Love2Shop acquisition of Appreciate makes a lot of sense as they can really push the cards at their 50k or so Paypoint sites. Appreciate was poorly run for a few years by the previous CEO, so Paypoint should be able to run it with a much lower cost base and higher growth potential. After Amazon it has to be the number 2 in the gift card market. Impressive that the Park christmas savings scheme is growing again as well. Collect+ is growing well. With Returns on Equity of about 50% and a c10% dividend yield from my purchase price a few months back, it was difficult to ignore. Net debt at £72m is a tad on the high side for my liking but should come down quickly given how cash geenrative the business is.
Hi, sorry we didn't get round to covering £PAYP - checking the archive, we've been positive about it for a while, as a nice value share, low PER, great divis. Quite a decent c.20% bounce from the recent lows. Results today, on a very quick skim, look good, top end of guidance, and positive Q1 trading. So I'd say happy to keep our GREEN view on this one. Although I don't suppose it will ever attract a premium rating, so the risk is people start top-slicing if it keeps rising.
Glad to see a similar bull on PayPoint (LON:PAY) like me! And for similar reasons too.
The other thing I haven't mentioned is that I think entrenched tech players are going to have a field day for the next 5 years. As VC funding has dried up, they can now have a clear road to growth and dominance, without pesky new VC-funded startups trying to muscle in, with subsidized solutions and products. Since PAY already have the largest convenience store network by far, there really isn't any external obstacles to high margin dominance here. That for me is the key investment point - that isn't picked up by investors yet, who still look at it at a glance and assume they are just a commoditized player in a fragmented market - hence the low current PE rating.
(I hold in the Boon Fund)
Franchise Brands (LON:FRAN) Graham many thanks for your comments. Here's the interim results presentation given yesterday, to analysts, which gives a flavour of all the management and how the integration of Pirkek and Filta are both going, together with their strategy going forward. They also have a new CFO, Mark Fryer joining (appropriate name for Filta!) next Friday, whose recent roles include Gp CFO of Augean and Dialight. For their outlook they say the full year aEBITDA will be at least in line with expectations. Video & podcast.
Rotala (LON:ROL) Interims today which seem to be satisfactory. No movement in the share price ( No volume either).
Says passenger numbers nearly back to pre Covid levels. Business running well it seems. What a contrast to Mobico (LON:MCG) in share price performance. The underlying businesses cant be so different in the UK at least ?
WANdisco (LON:WAND) - Been away for a few days and now seeing this crazy share trading again and rising each day from the 50p restart, earlier this week. I wonder who is buying - perhaps the list of major shareholders now needs updating. And NO - I won't be buying any more thanks!
I hope Paul's boots are being filled daily...!
Virtually of course! But I did do a real Paul yesterday although on XLMedia (LON:XLM) , doubling down big-time.
I hold XLMedia (LON:XLM) but I am losing confidence in their US Sports Betting business. It is the driver for their recovery, and if it doesn't work there isn't an investment case, but the way things seem to be working is that they get a boost in income as each state legalises online betting, but that quickly falls off, and they've had a few recent misses where new states have come online (no pun intended) and there hasn't been the expected large boost. They need to get sustained revenues before they run out of states (I think there's about 30 left although I guess some will hold out on the basis that gambling is the work of the devil).
Doubling down on XLMedia (LON:XLM) is definitely NOT "doing a Paul".
I've never touched XLMedia (LON:XLM) - check our archive for why. It's a pile of crap, and always has been.
Not sure if it’s fair to say “it’s a pile of crap”. Over the past two years they’ve gone through a significant restructure and focus on positioning for the high growth US market. The recent update is a product of their restructuring plus some delays to state openings. Yes, they do get spikes on state openings but much of that is due to existing commerical deals with operators where they historically go paid one off CPA (cost per acquisition). This is a typical deal structure in early gambling markets, however as they mature the deal structures move to revenue share which means XL will receive up to 40% net revenue of customers it sends to operators. This is trailing commission sometimes up to lifetime of the customers activity. XL have recently signed a rev share deal with the largest global operator Bet365. With H2 weighted due to NFL and rev share deals starting to kick in with a more efficient op model I believe next few years, especially at this price, could be very positive.
I hope Paul's boots are being filled daily...!
They are! Funny how things turn out. I've top-sliced some of my WAND profits today. c.114m shares in issue, so maybe the IP could be valued at £100m+? Hence why it was an interesting trade at 50p. I've sold about 40% at c.100p. Let's see what happens with the rest. It's fully funded, and the IP is worth something. Hence why it's an interesting punt I think.
I was just scrolling down todays SCVR and whizzed past Pod Point group (LON:PODP) I couldn't believe my eyes when I saw the ticker "POOP" - only when I stopped and read it again did I realise my mistake................. but having now read the summary I am not sure it is a mistake :-)
They originally wanted ticker "SHITE" but it was taken :)
Tho surprisingly can't blame AIM for this one. It was on my short list last year but I figured they had such a large cashpile theyre bound to preserve cash, how stupid of me.
Thank you Wolfie.
When we see something really, really, bad - we shout from the rooftops here.
Like I did with Pod Point group (LON:PODP)
Any PR company taking fees to promote this type of shite should be ashamed of themselves.
Vanquis Banking (LON:VANQ) - profit warning here so now in small cap report territory as its down 30%. Ouch!
Vanquis Banking (LON:VANQ) A very unpleasant business. I was a victim of identity fraud facilitated by these creeps. They pretended to take it seriously but clearly I was just collateral damage (as the Americans say ).
Yes - originally Provident Financial. Neil Woodford once owned 25%, hence why I am never persuaded that there were no warning signs about how he ran his funds....
Angling Direct (LON:ANG)
Completely off topic but it is a Friday.
I noticed that a newly launched (March 2023) small cap fund Dowgate Onward Opportunities, which seeks to generate absolute returns of 15% per annum, has made their first core investment in Angling Direct (LON:ANG)
https://onwardopportunities.co...
If you are a holder of this company or it's on your watchlist then I'd highly recommend reading their Q2 factsheet linked above.
Thank you for that bsharman. we hold Angling Direct and I'd seen it nudging upwards. We might buy a few more.
"Thank you for that bsharman. we hold Angling Direct and I'd seen it nudging upwards. We might buy a few more."
So what?! Imagine if thousands of subscribers posted the same type of pointless remarks? We'd be wading through thousands of pointless messages. Please ADD VALUE.
Be interesting to see what other lines of stock they pick up. I could see someone was buying in the market - lets hope the new management can make something of this rather sleepy retailer.
The list of major shareholders is impressive esp for such a small company - but also leaves very little room for liquidity with almost 90% owned by these major holders !
Interestingly, significant ONWD shareholder, Ray Kelvin, is a big fan of fly fishing!
Several typographical errors in the ONWD factsheet, not a particularly good look.
Mobico is on sale, Half price!
started the year at 180 and it is nearly 90 p now.
Last week report promised better second half despite the losses.
Travelling was picking up but recent events in southern Europe has damaged the sector.
Mobico, however, has operations in US which is doing well.
Paul is kindly reviewing the company and it would be a good read.
gMobico (LON:MCG) I know nothing about the company but its exactly what I want to avoid. Downtrending share, lots of debt,falling eps forecasts
It's made a series of lower lows and lower highs. Maybe want to wait until it makes a higher high before considering buying which would be >105. Could be the bottom here or it might half in price again, can never tell.
Price follows earnings-
I'm too tired to do Mobico. Exhausted actually.
Breathe .... thank you to Graham and Paul for all their effort this week. I always feel like a draw in a week like this is a good result. As its holiday season I thought I would list a few things I am listening to....we are truly spoilt with free content these days in podcast land....
Pauls Small Caps podcast obviously
Forward Guidance with Jack Farley... the Julian Brigden interview very good
Macrovoices have Lyn Alden this week.
Market huddle
Hidden Fources interview with Neil Howe - Fourth Turning
Odd Lots
Inside Baseball with Old chestnut
A different Perspective with Nick Searle
Merryn Talks Money
I also pay for Grant Williams....
Enjoy the weekend and holidays if you are taking them.
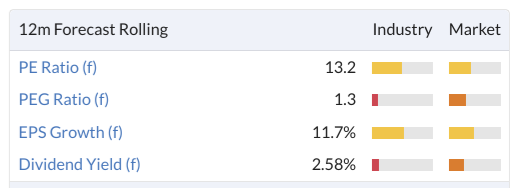
Will be interested to hear in your Cohort (LON:CHRT) interview as I am currently a shareholder in Qinetiq (LON:QQ.) and was wondering whether to switch as both are defence stocks. However cohort is on a prospective PE of 13.7 compared to 11.5. Forecast revenue growth two years out is 6% for cohort and 7.3% for Qintec (figures taken from Stockopedia.)
Redde Northgate (LON:REDD)
Commencement of a £30m share buy-back. Also indicates:-
"The Group has continued to enjoy robust demand in the first months of the current financial year and there is good momentum across the business."
Might put some fire back into the SP - who knows?
(I hold)
PayPoint (LON:PAY) results out to date. Be good if these can be covered today Paul please?
I held Appreciate, took the cash and then eventually reinvested some of the proceeds into Paypoint shares on price weakness. I think Paypoint shares were weak earlier this year because of Appreciate shareholders selling their small positions. Results possibly confirm this as they look fairly good, and don't justify the sharp earlier drops.
I agree - unfortunately I sold out of PayPoint (LON:PAY) recently as I was concerned about the overhang. Interestingly I went back into Redde Northgate (LON:REDD) as I think that this is a decent business which can do well, quite quickly, whilst paying a decent divi. Time will tell what was the better move.
Agreed on Redde Northgate (LON:REDD) I reviewed my holding recently (one of my top 5) and decided I was happy to stay on board for the long term. The forecasts suggest declining profitability over the next 2 years but I'm not sure I believe them. This is a capable management team and I don't think they will sit on their hands and watch that happen.
Today's buy-back announcement is not that significant in the scheme of things (£30m out of a £775m market cap) but it does show that management think carefully about capital allocation and will take opportunities where they see them. And as Viz and topvest point out, there's a decent divi in the meantime.
I did the same. Took my gains from Appreciate. At the time PayPoint (LON:PAY) shared were too expensive for my taste. They declined, and I found a good entry point.
I like Paypoint because they are building a very nice big moat and a dominant position. That position is in providing the tech infrastructure for small convenience stores. There is no other competition. And the opportunity for tech in convenience stores are big.
Now to watch them roll out more tech solutions for stores, and increment their revenues per store. High margins. Rock solid dominance of their market. This is the Google or Meta of their niche.
Trading at 8x historic PE!
(I hold in the Boon Fund)
I like Paypoint because they are building a very nice big moat and a dominant position. That position is in providing the tech infrastructure for small convenience stores. There is no other competition.
I thought this was an extremely competitive space. Fintech solutions and point of sale solutions are pretty common offerings with many companies offering a unique / bespoke service. The profitability metrics are great, but they have struggled to grow revenue and net profit over the years, these numbers suggest possibly no moat! I hold Paypal and PAGS (both recent purchases) and have held Visa for about 8 years. They are all growing revenue and net profit and therefore their moats / competitive advantage are visible in the numbers imo.
But that's what special about PayPoint (LON:PAY)
It is not just a POS or payment processing service like Square, Sumup, etc...
They offer new revenue sources for convenience store owners. Not just a way to process payments and transactions.
In many ways they are positioning themselves to be the Operating System of a convenience store. Then every other service that needs a technology route in to a convenience store, needs to go via Paypoint. And they will take their gatekeepers fee. Or become the indispensable platform to convenience store
RE: PayPoint (LON:PAY)
In many ways they are positioning themselves to be the Operating System of a convenience store. Then every other service that needs a technology route in to a convenience store, needs to go via Paypoint. And they will take their gatekeepers fee. Or become the indispensable platform to convenience store
And get sued for operating anti-competitively ...
https://www.cityam.com/paypoin...
timarr
Hi timarr - yes, on PayPoint (LON:PAY), I noticed the legal claims wording but it does look like they have a strong case to defend them successfully. This issue was effectively settled with Ofgem a few years ago, without enforcement action from what I can see, by voluntarily removing exclusivity clauses and paying £12.5m. The two claimants are weak players in the market, so it looks to me like a bit of a try on.
Utilita is nearly bust and one of the worst suppliers for customer service. Global-365 are tiny, also almost bust, and seem to be claiming because of their own failed business model. Legal claims are always a worry though, but it kind of underlines that they have a strong market position, in my view! I'd be worried if they get a claim from a more competent company though, so thanks for flagging as it's something to keep a watch on.
WH Ireland (LON:WHI) todays 3p Placing to keep the lights on demonstrates how tough things are out there (tho I would also say that management may have brought this on themselves, see previous media stories)
Sad to see redundancies looming for the staff
Too risky for me but perhaps another financial services company may now swoop in or wait for them to enter administration
I thought the update yesterday from Eenergy (LON:EAAS) was interesting and relatively positive.
My morning smallcap tweet: Broker broke
WH Ireland (LON:WHI) AFC Energy (LON:AFC) Cineworld (LON:CINE) Greencore (LON:GNC), Inspecs (LON:SPEC), PayPoint (LON:PAY)
◄W.H. Ireland (WHI)► £5m placing at 3p, an 87% discount, to prevent a solvent wind down. Co is c.£1.9m below the current FCA regulatory capital requirement. CM transactional activity poor. Expects co to be loss making until at least Nov. [SP=21 Cap=14m]
◄AFC Energy (AFC)► proposed launch of a dedicated hydrogen powered generator plant hire business in JV with Speedy Hire. [SP=14.68 Cap=110m]
◄Cineworld (CINE)► administration of group (as expected) on July 31, shares suspended day after. When will we seen another blockbuster short like this? [SP=0.38 Cap=5m]
◄Greencore (GNC)► to sell Trilby Trading, one of Ireland's leading importers and distributors of vegetable oils and fats for the food processing, for €9.8m. Trilby made pretax of €2.9m. "Trilby is a great business with attractive assets and a fantastic team. However, given our strategic focus on the UK convenience food market, it is no longer a core part of Greencore's plans." Why did co sell it for 3.4x pretax? [SP=87.1 Cap=425m]
In line: SPEC, PAY