Small Cap Value Report (Fri 28 June 2024) - HFD, MOON, REC. Briefs: KWS, DEVO, OPTI, MMAG, MIRI, NGHT, SIS, THRU, XLM, POLX

Good morning from Paul! I'm ready for the weekend, after a really busy week here writing the SCVRs whilst Graham's sunning himself in the Med!
Right, all done for today and the week! Have a super weekend.
It's the last trading day for AIM companies to report their FY 12/2023 accounts before shares are suspended, so there's some dross on the companies reporting list today.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
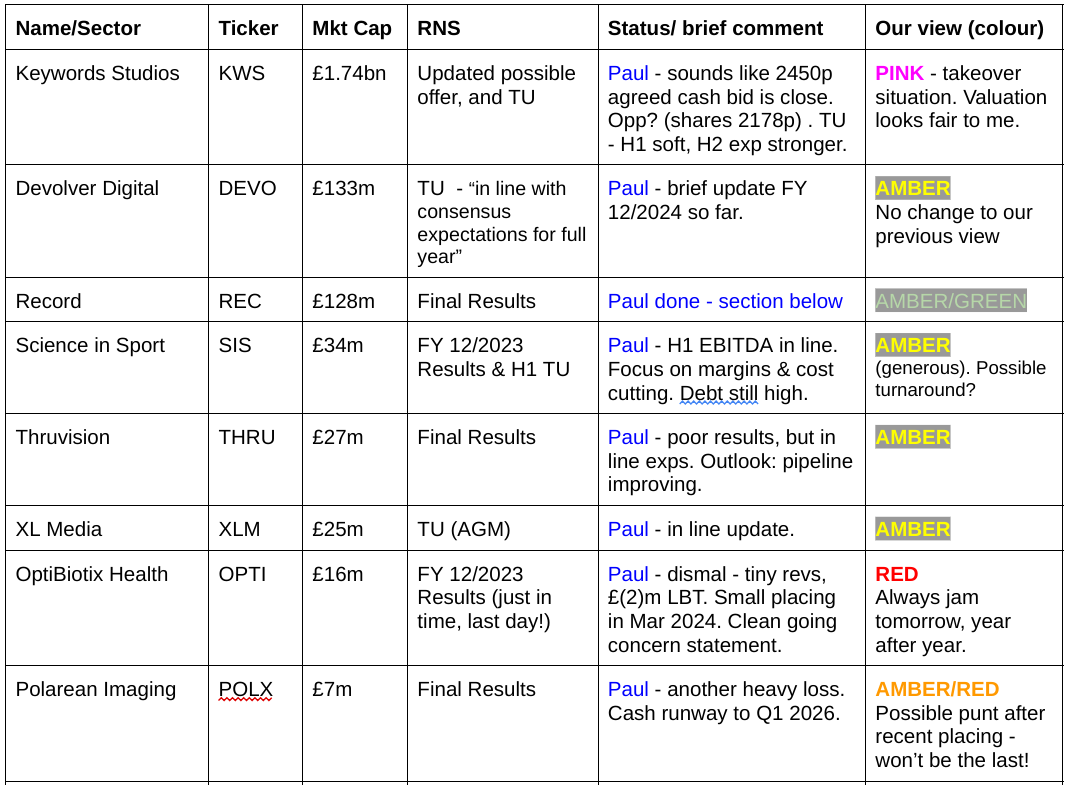
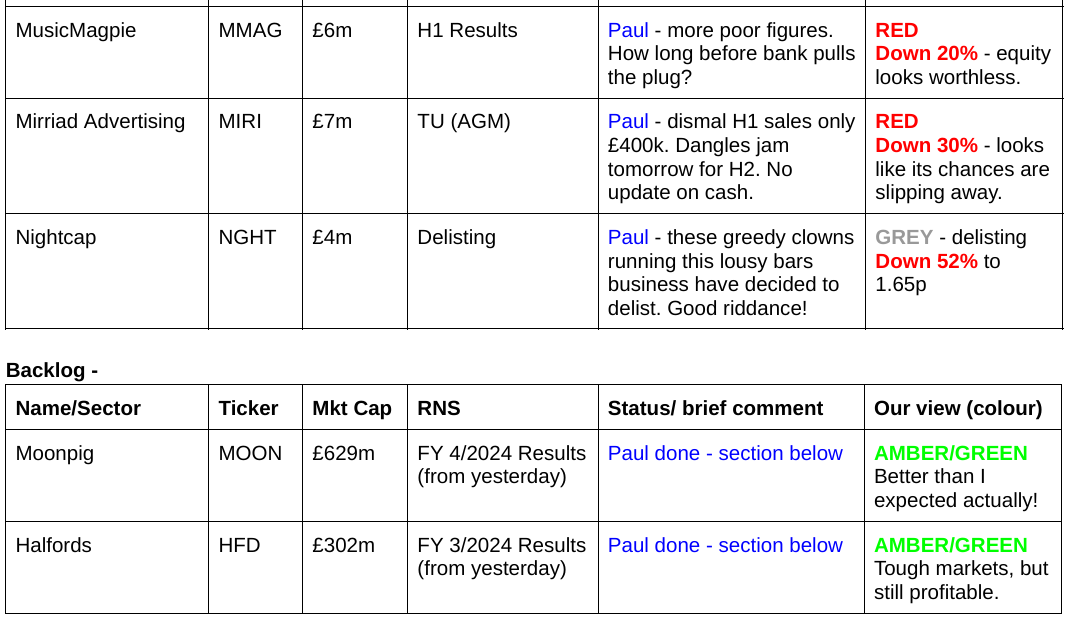
Summaries
Halfords (LON:HFD) - 138p (£302m) - FY 3/2024 Results - Paul - AMBER/GREEN
Trading continues to be subdued, but in tough macro I'm quite impressed HFD has remained profitable and paying divis. Finances look fine, with negligible net debt and ample liquidity. Could it attract private equity bidding interest? I wouldn't be surprised. On balance, I think there could be good cyclical upside here, but have no idea on timing.
Moonpig (LON:MOON) - up 15% y’day to 183p (£629m) - FY 4/2024 Results - Paul - AMBER/GREEN
I like these results (out yesterday). It's demonstrated very strong cashflow, which has taken a big chunk out of the previously worrying net debt. A positive outlook, and valuation that now looks quite reasonable to me, means I'm happy to move it up a notch from amber, to AMBER/GREEN.
Record (LON:REC) - down 1% to 64p (£128m) - FY 3/2024 Results - Paul - AMBER/GREEN
Results look OK, and the main attraction of a big dividend yield (now 7.2%) is maintained. However, outlook comments sound a bit cautious, and with talk of the medium-term, it sounds as if any upside on the shares might require patience. So I've shifted down a notch to a still positive AMBER/GREEN.
Halfords (LON:HFD)
138p (£302m) - FY 3/2024 Results - Paul - AMBER/GREEN
I’ve been keeping half an eye on HFD shares, as it looks cheap, and a good potential cyclical (no pun intended) turnaround.
Its results didn’t come up on my usual sweep of the RNS, I think they use a different news service. So I’ll come back to it now.
Three headlines make interesting points -
Strong revenue growth of +7.9%, with underlying profit before tax of £36.1m
Good strategic progress; market share gains helping to offset significant external headwinds
Strategically important Services business now represents more than half of Group revenue
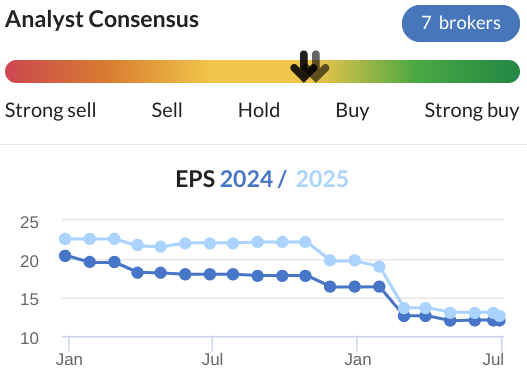
As you can see below, HFD has been struggling for a while, with a downward trend in broker forecasts reflecting that. Probably due to tough macro, but also the pandemic cycling boom probably pulled forward demand, which for long-life products like bikes, means we’re now seeing reduced demand. Who knows what normal will look like, as we've been in permanent crisis for over 4 years now.
Although it is an important point that HFD has been growing through diversification into buying & rebranding car repair/servicing/MoT businesses. That strikes me as a good sector to consolidate, being very fragmented, and capable of improvement through centralising websites, marketing, etc.
It blames the following areas for weak performance -
“Business performance has, however, been impacted by continuing declines in the Consumer Tyres and Cycling markets, and in consumer demand for big ticket purchases… drivers continue to delay the replacement of unsafe tyres. In a recent survey of 6,000 tyres at Gatwick, Manchester and Edinburgh airports, we found that one in four vehicles had tyres that were dangerously worn or damaged.”
Reading the summary points, this actually seems quite reassuring to me -
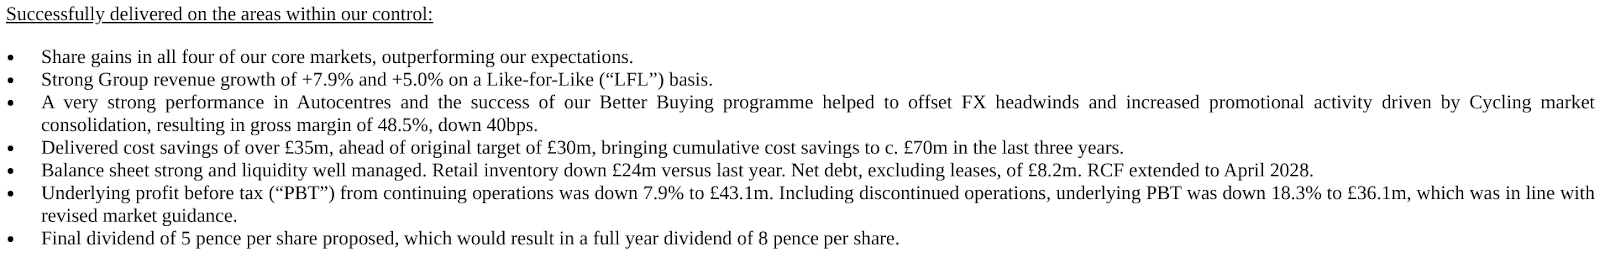
Dividends total 8p gives a lovely yield of 5.8%, and that could have scope to rise, if we’re at or near the low point of the earnings cycle, perhaps?
Low margins - adj PBT of £43.1m is only 2.5% of the £1,697m revenues. Does this indicate a fundamentally poor business, or could it be an opportunity to see operationally geared upside (with gross margin 48.5%) in a consumer recovery? Or both maybe?!
Adj EPS is down 14% to 15.1p, that’s a PER of 9.1x - cheap, if we’re at bottom of the cycle earnings, but we don’t currently know if that’s true or not.
However it then goes on to say that a reduced adj EPS of 12.7p (PER 10.9x) is more accurate and comparable to forecasts, which includes costs of running (since disposed of) tyre supply operations, which will now be outsourced, hence I presume the costs will increase in future correspondingly. The StockReport shows broker consensus of 12.1p, so actual looks to be a beat.
Outlook - CEO comments make me cringe by using the meaningless, infuriating and seemingly now ubiquitous phrase “profitable growth” -
“While the short-term outlook remains challenging, we continue to build a unique, digitally-enabled, omni-channel business, which is well positioned for profitable growth”.
This longer outlook section below sounds like a business that’s hunkering down to endure continuing tough conditions. Also it’s interesting to see the mention of sea freight costs rising, and the effect quantified -
“Trading since the start of FY25 has continued to be soft, impacted by low consumer confidence around big ticket, discretionary purchases, and poor spring weather, which has reduced store footfall and affected sales of both cycling and staycation products. Whilst we continue to expect market share gains in the year ahead, based on what we are currently seeing we now expect market volumes to decline in FY25 in cycling and consumer tyres, and to remain broadly flat in motoring servicing and retail motoring products.
Inflation remains a material headwind, particularly driven by the 10% increase in the national minimum wage. More recently we have seen very significant increases in sea freight rates, with spot rates more than doubling since the start of our financial year. Whilst we continue to successfully secure rates well below market spot rates, we now forecast freight costs to be £4-7m higher than we anticipated at the start of the year.
Against this backdrop, we continue to focus on optimising the platform we have built, and controlling what we can. As such, we plan for proportionately fewer resources to be allocated to strategic transformation, as set out in more detail at the end of the Strategic and Operational review.
We do not expect these headwinds to persist in the long term. Consumer price inflation is easing and our core markets are expected to improve in the mid-term. We remain confident that the financial targets announced at the April 2023 CMD are achievable assuming markets ultimately recover as forecast, albeit this will take longer than we envisaged last year.
We remain very confident in the Group’s strategy, as we build a stronger and more resilient platform for the future and continue to take market share.”
I was hoping to see signs of economic recovery by now, so it’s disappointing to have lots of companies saying there isn’t yet much of a sign of recovery. Trouble is, we don’t really know if that’s due to macro factors, or that competitors are taking away business from each company? Our house expert on the cycling sector, PlanetX, has been telling us for a while in the reader comments that selling bikes has been tough for a while, with a glut of supply due to over-production and over-ordering in the pandemic boom. Maybe he can update us with the latest market conditions, and when things might normalise?
Balance sheet - looks healthy. NTAV is modest at £70m, but being a retailer, it’s mainly supported by trade creditors, hence there’s not much need for equity on the balance sheet. Nice position to be in, where suppliers effectively fund your business, interest-free! Many retailers operate like this, and if stock turn is managed well, you can often sell the product for cash to end customers, before you’ve paid the supplier.
With negligible net debt (excl leases) and a bank facility of £180m to April 2028 (option to extend to 2029), liquidity seems ample, and safe.
So no issues here to fear dilution or insolvency.
Cashflow statement - is large and complicated, with the lease entries in particular making a nonsense of things, with supposed cash generation of £178m, but further down there are (property) lease costs of £93m.
Capex was £46m, just over halved on last year. This includes £23.7m of intangible assets, so I’d like to know if that’s IT spend, which it looks like.
Share repurchases cost £10.2m, plus divis cost £21.7m. Given the balance sheet includes hardly any net debt, these shareholder returns look fairly safe, providing trading doesn’t deteriorate any further. The risk is that future divis might come under strain if it moves into losses in future. But for the time being the yield seems safe, but is subject to flexibility under HFD’s dividend policy.
Paul’s opinion - I still like HFD as a potential cyclical recovery share. I’m encouraged that, despite difficult market conditions, it’s still profitable and financially sound - there’s ample liquidity, and negligible net debt, so this looks a fairly safe bet.
There was bid talk a while back, and I suspect this could attract bidding interest from private equity, which is a nice reason to own this share.
On the downside, conditions still sound difficult, with as yet no sign of a consumer recovery.
On balance I think I’m leaning slightly positively in my assessment of risk:reward, taking into account that it’s still profitable, even in very tough macro, and has weathered multiple macro storms (pandemic, energy crisis, cost of living squeeze, higher wages/energy/freight costs, etc) and still remained profitable and cash generative. There must be less competition too, as independents either close down or get bought by Mike Ashley!
Halfords is a very recognisable brand too. I often buy products like oil or brake fluid there, as they’re too heavy to be ordered online at a reasonable delivery price. Although I do worry that they over-charge for smaller items, and must suffer a lot of pilferage from customers and staff (if you can find any in store!).
Leases are relatively short, and flexible, so it should be able to run down the cost of occupancy as sites come up for renewal.
With a perhaps 1-2 year view, it’s possible that HFD might be starting to report improved demand and profits, which I imagine could see its shares recover, with possibly 50-100% upside on the current share price if performance does improve? So yes, I quite like it, but don’t know when the low point for earnings will be, there could be further downside before a recovery, who knows?
Moonpig (LON:MOON)
Up 15% y’day to 183p (£629m) - FY 4/2024 Results - Paul - AMBER/GREEN
Nice prompt reporting here, I do think that UK companies should generally have quicker reporting cycle.
Revenue and profit growth underpinned by technology and innovation
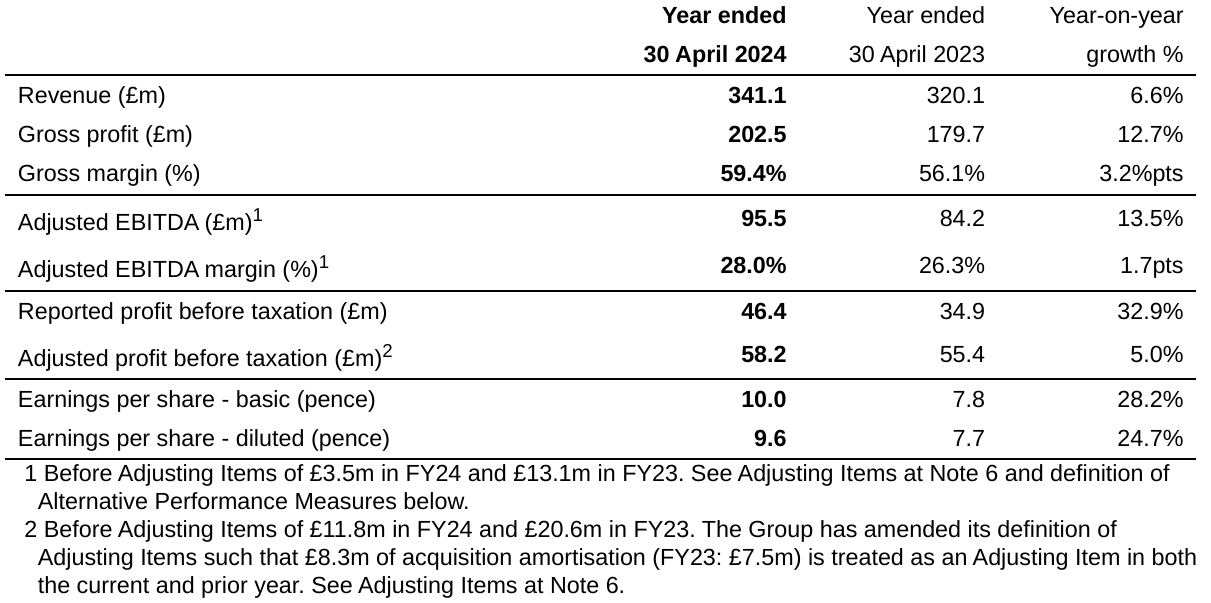
From the options above, my preferred profit measure is adj PBT (where adjs are reasonable). This is up a modest 5%, not bad I suppose, in a macro situation which has been tough for discretionary consumer spending. It sounds like a one-off benefit was gained this year from some experiences vouchers sold in the pandemic having expired without being used.
That’s a good PBT margin of 17.1%, demonstrating a business with decent pricing power.
“Adjusted profit before taxation of £58.2m (FY23: £55.4m) reflecting stronger trading offset in part by higher interest charges and the amortisation of technology platform investments.”
Debt - my previous concerns with Moonpig was that it overpaid for a poor acquisition, and ruined its balance sheet. That seems to be getting repaired now - eg
“ Net leverage improved to 1.31x at 30 April 2024, from 1.99x at 30 April 2023. Given our strong cash generation, there is potential for a similar reduction in net leverage in FY25. To maintain an efficient capital structure, our target is to operate with net leverage of approximately 1.0x over the medium term, with flexibility to move beyond this as business needs require.
We will continue to prioritise investment to drive the execution of our growth strategy. With our consistent strong operating cash generation and the progress being made with deleveraging, we will also have the financial flexibility to consider returning excess capital to shareholders."
Balance sheet - still looks very weak to me, but this is a capital-light business model. NAV has improved from £(33.7)m last year, to scraping into the black at £3.8m. But that last figure includes £204m of intangible assets (mostly goodwill and similar). So NTAV is a dismal £(200)m, with this balance sheet hole being mostly filled with £118m borrowings. Net debt excl leases was £109m, down a very impressive £39m from last year. To put that another way, to reach net cash neutral position, would take about 3 more years of retaining all cashflow generated.
You could argue that a business as cash generative as this could happily support c.£100m net debt, but that’s not cheap any more (finance costs are a walloping £20m pa), and it’s the reason why there are currently no divis.
Overall though, I’m happy to say that it’s moved from an alarming balance sheet weakness, to an acceptable level of balance sheet weakness where I don’t think there’s any risk of needing to do a placing any more.
Management talks about doing more acquisitions. Let’s hope they don’t, as there’s no evidence they know what they’re doing on that front, and made a bad decision in the past. A decent, cash generative business making bad/overpriced acquisitions squanders shareholder value in my view.
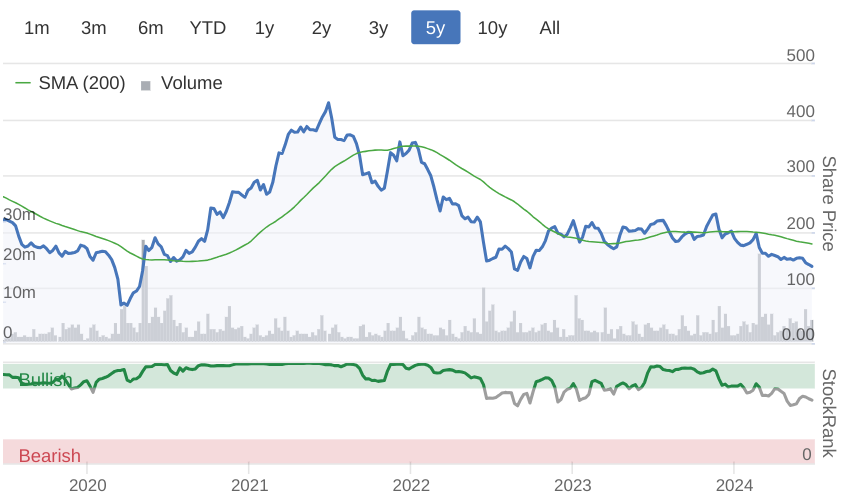
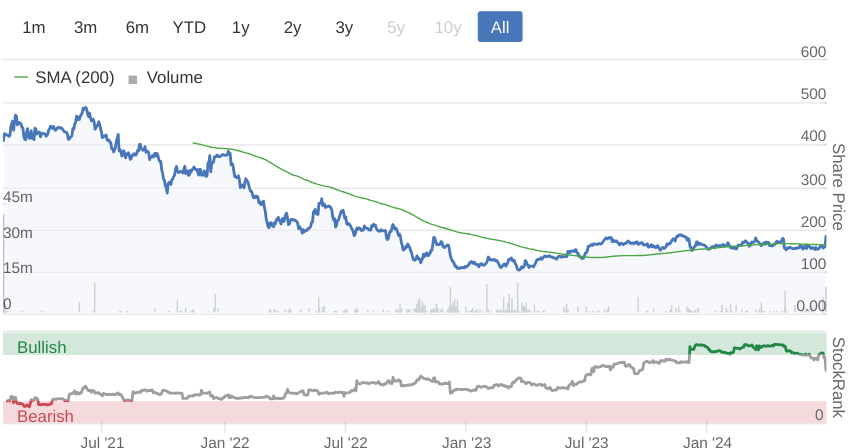
Also bear in mind MOON was a cynical, overpriced IPO during the pandemic, and is still way below that price -
Outlook - sounds pretty good, I have to say -
“Trading since the start of the year has been in line with our expectations with both new and existing customer orders in growth. In the context of the current macroeconomic environment, we expect FY25 revenue growth (after adjusting for temporarily higher breakage on experience vouchers in FY24) at a mid to high single digit percentage rate, underpinned by growth in orders at the Moonpig brand.
Our business is well positioned to deliver sustained growth in revenue, profit and free cash flow, driven by our continued focus on data and technology. With respect to the medium-term, we are targeting double digit percentage annual revenue growth, an Adjusted EBITDA margin rate of approximately 25% to 26% and growth in Adjusted earnings per share at a mid-teens percentage rate.”
The Moonpig Plus subscription scheme has exceeded our expectations, passing the milestone of half a million members within one year. Our investments in new AI technologies are delivering an increasingly personalised experience for our customers. As the clear online leader in greetings cards, Moonpig Group is well positioned to benefit from the long-term structural market shift to online."
Valuation - apparently 8 brokers cover MOON, but none of them let us see their notes! The Stockopedia chart of broker consensus does show a slight tick up in forecasts for FY 4/2025 and FY 4/2026, as you can see -
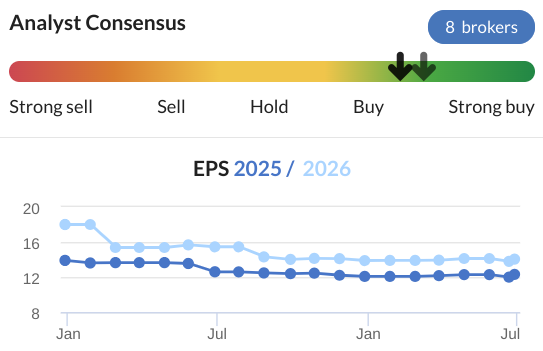
What PER should we put these forecasts on? I’d say given the more perky outlook comments about future growth, a PER of say 15-20 is justifiable. This is a quality, cash generative business I’d say, and the balance sheet weakness is no longer a deal-breaker for me, since it has demonstrated very good debt reduction this year.
That gets me to (based on 12.3p current year forecast) a share price of 185p to 246p. The current price is 183p, so that shows some potential upside in my view.
Paul’s opinion - I’m much happier with these numbers than last time. Good progress has been made in debt reduction, emphasising that this is a nicely cash generative business. Let’s just hope management don’t repeat the previous mistake of overpaying for a dubious acquisition, and taking on too much debt to fund it.
It’s market leader in online greetings & presents, with a very well known brand, which in itself creates a barrier not to entry, but to scaling up (massive marketing spend over years is required, and that’s a sticky sort-of-asset, since people remember jingles for many years, even decades, if they’re catchy)
My view has been steadily improving as the facts & figures improve - we always look at each company with fresh eyes. So amber/red last autumn became amber the last time I looked on 14/3/2024.
Putting together the big reduction in net debt this time, and a perky outlook, combined with valuation which I think could have further upside, I feel the correct view to take now is up another notch, to AMBER/GREEN.
I like the sound of its subscription service, and might have to look into that. Despite having birthdays recurring on my calendar, I still frequently forget to send cards in time, so automating it completely does sound a nice idea. Ecards have never taken off, and remain just a curiosity in limbo. You can't beat receiving a physical card through the door, especially if it comes with a bottle of wine.
Record (LON:REC)
Down 1% to 64p (£128m) - FY 3/2024 Results - Paul - AMBER/GREEN
Record plc, the specialist currency and asset manager, today announces its audited results for the year ended 31 March 2024 ("FY-24").
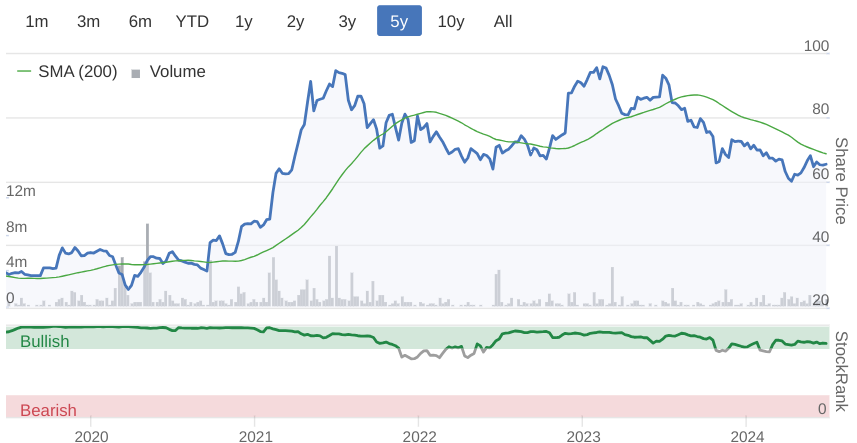
The share price remains in the doldrums, despite this quite upbeat-sounding headline -
“Positive net inflows take AUM to a record high”
I’ve viewed REC shares positively, GREEN, three times so far this calendar year. Although I’m the first to admit that I’m certainly not an expert in this field, so maybe I’ve missed something? What appeals to me is its niche activities, a step change upwards in EPS throughout the pandemic, good cashflows, and generous dividend yield, with an OK balance sheet.
It’s not a forex/payments company, it’s more a specialist fund manager.
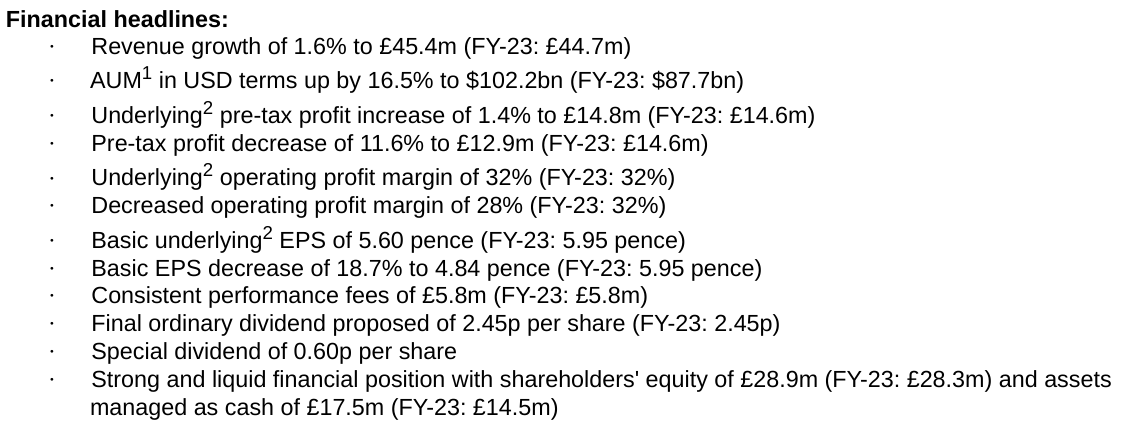
To save me typing, here’s the highlights table - which I’d say looks OK, considering the share price has been bombed out for a while -
Outlook - sounds a bit defensive, with not much sign of profit growth (NB not "profitable growth" thank goodness!) -
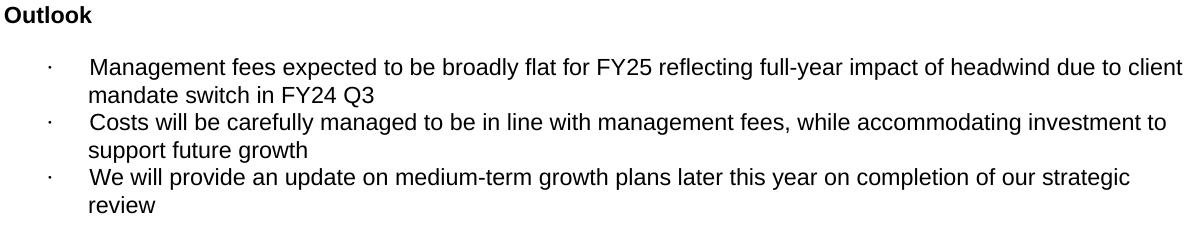
I don’t really understand why profits are flat, given that AuM are hitting new highs?
Dividends - total 4.6p, a yield of an attractive 7.2%
Balance sheet - looks healthy, with £29m NTAV, almost all liquid assets.
Paul’s opinion - I’ve not read all the detailed commentary, so this review is just a quick skim of the numbers. This share remains moderately attractive to me, with the main attraction being a lovely dividend yield.
Outlook comments talk a lot about the medium-term, strategy, etc. So it’s giving the impression of being a little bit under pressure, but still producing decent profits, just not any further profit growth.
Maybe I should moderate a little, from green to AMBER/GREEN, just because it has the look of something that’s more likely to tread water, rather than deliver stunning growth. Although getting paid 7.2% pa to sit and wait, is far from shabby.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

74 comments
As for Record plc's profits remaining flat despite the increase in funds under management, as I understand it there is a broad range of products available, and the fees REC charge vary accordingly. While passive hedging, the more 'run-of-the-mill' service, might be to some degree equated to tracking the interest/exchange rate market, there are other layers of complexity, and higher fee rates. When Record report a significant increase in FUM accompanied by a fall in margins, it is due to a relative rise in these lower margin funds. When they announce a significant rise in earnings it is because they have received (won) a mandate for a much higher margin "currency-for-return" product which, though apparently not so large, produces much greater rates of return when the stars align, so to speak.
I hope this isn't too simplistic, but I might save time for some from having to dive into too much reading up on it. I am buy-and-forget long on Record.
Audit report delays: Paul in his recent podcast made the point that delays in audit reports might not be the red flag they once were. From experience post covid there has been a reduction in both the quality and speed of service in professional services. Leeds now has the biggest legal and financial services sectors outside of London. The KPMG office is rarely busy but the coffee shops, bars and restaurants are full of the "WFHomers". Check out the Wellington Place Leeds website and you can begin to understand why work deadlines are less of a priority.
It's lucky there aren't any 3-pin sockets in town and city parks this weather.
Record (LON:REC) There was an impairment cost of £1.9m relating to IT costs which was debited to the P&L I understand. The special dividend I see the board being confident for the future.
Property Franchise (LON:TPFG)
Have added a few this morning on my view that it will come in ahead of consensus for the current year. I predicate this on the improving outlook for sales and significant financial services offering within the company post its merger with Belvoir, aided by a widely expected fall in interest rates.
The general election may temporarily interrupt sales momentum, but assuming the elected party has a working majority and if rates fall in August, albeit by 0.25% house sales should gain traction.
What could go wrong? A hung Parliament, which appears highly unlikely. My expectation is that Labour will achieve a working majority and/or interest rates are not cut, again the balance of probability given the overtures from Andrew Bailey is that they will be reduced. Fingers crossed.
From the recent AGM statement:
As reported at the results in April, FY24 started with good momentum and that has continued to build. Our longstanding businesses have traded in line with our growth objectives. Notably, their lettings' revenues have continued to grow at similar rates to last year and the sales-agreed pipeline at 30 April 2024 was 20% up on the same period in FY23, signalling a much stronger sales market so far in FY24.
I have funded the purchase by selling a few Volex (LON:VLX) , which remains my largest holding at around 7.5% of the portfolio. I also sold 50% of my holding in Sanderson Design (LON:SDG) at a small loss as there are potentially more promising companies to invest in/add to in the medium term. Card Factory (LON:CARD) is a candidate for topping up and am currently going through the recent Equity Development review of the company.
Greetings all,
Just to say that I have really enjoyed reading today's posts. The debate on and detailed analysis of, the bicycle industry, has both amused and informed.
Paul - Duke Capital came out with what I thought were rather good numbers yesterday. The market response was a collective meh! I think that you have reviewed this company in the past. Any chance that you might run the slide rule over their latest pronouncement, please? (I hold).
Hi Lord Gnome
It was "our Graham" who knows and does the Duke Capital (LON:DUKE) reports, so might see if he will circle back when in the chair once more
Tommy
Made Tech (LON:MTEC)
Thanks to Yiannos for flagging yesterday. I had a look over the investor meet presentations, results and broker notes last night and this morning and my thoughts are as follows. Apologies in advance for the lengthy post but I know Friday can be a little slow. I'm no whizz with numbers so apologies in advance for any lack of clarity or errors.
Made Tech (LON:MTEC) - Company is focused on digitisation to improve productivity and efficiency. Public sector driven. Growth profile has struggled previously, trades at half sales, and should trade at closer to one times sales if this can be improved. 2023 finals showed a trend of winning bigger contracts, however this took a big hit in the run up to the election and 70mil bookings in 2023 dropped to 36mil in 2024. CEO said in 2023 – “Election creates uncertainty which will slow growth as new priorities. All signs point to drive change over time, good foundation for growth.” So this reduction was not unexpected.
The pipeline is still healthy.
The CEO is targeting 100mil and 15% EBITDA on 3-4 year view. In FY23 he said he wanted focus on improving gross profit margins in FY24. He delivered on his ambition and FY24 saw a modest improvement from 35.8% to 37%, although forecast to pull back to 36% in FY25. Gross profit is also due to decline from 14.2mil to 12.8mil. EBITDA is increasing YOY, despite this, still some way off the 15% target at around 6% as of writing.
In FY23 one concern was that staff retention rates were quite low at 70%, they were unable to match salaries of larger competitors. In response 1.6mil spent on new capabilities to grow the team and big focus on the right people to drive growth, this included a new CFO. He seems a little wooden but knows the numbers well. Came across more confident than the previous CFO in the investor meet.
The client list is impressive and growing:
Prior to the election announcement the CEO said (paraphrased) - “Election creates uncertainty which will slow growth as there are new priorities and customers are more cautious. Unknown on election timings – contracts are in market despite this. Focused on delivering short term performance. All signs point to drive change over time, good foundation for growth. Over time the company should look to gain market penetration and the product space would have a big impact on growth”
Fast forward a few months and we now we know about the election and realistically we already know the outcome. So the thought process would be that the bottom is in for Madetech, the election is almost boxed off (excuse the pun) and this should be the catalyst to move back to revenue growth.
Very large multi-million contracts have started to get signed in the past couple of years. Madetech believe they hold an excellent position in this long-term growth market and so far they have retained all of their clients.
Revenue has been roughly constant over FY23 and FY24, expected to pull back slightly to 35 mil in FY25. With EPS increasing progressively from 0.3 to 0.5p and EBITDA improving from 1.5mil to 2.4mil. For me, here lies the opportunity, the forecasts are simply accounting for the current clients and known contracts.
The company stated in its FY23 results presentation that is was expecting a lull in contracts until post-election. That process has been accelerated and will soon be finalised with a labour government. I imagine behind the scenes the work has already started new contracts.
Already 11mil of contracts for H1 since the election announcement, which was unexpected. If it can win more large contracts, which with an incoming government looking to evidence that are having an impact is highly likely, the SP could rerate significantly.
I wanted to pull out some examples from the labour party manifesto documentation to outline the potential for new large contracts. Importantly, MadeTech can benefit from both the policies to reduce spending and also the new policies funded by these spending cuts:
If the government are to reduce consultancy spend then their own systems will need significant investment, this could place nicely into the hands of Madetech.
In boosting tax compliance the National Audit Office have estimated using HMRC figures that investments in technology can achieve a return of £2 for every £1 of investment within a parliament. As technology and analytic improvements in the IRS that will boost productivity.
For this alone 300million per year over 5 years has been allocated. Even a small slice of this could be material for Made Tech (LON:MTEC) .
It appears that less autonomy will be given to local government and Labour are looking to prioritise spending on central systems, this is reflected in the shift at Made tech, with only 1.8m of revenue from local in FY24.
As with all investments, there is a degree of unknown. The contracts may or may not materialise. However, on balance there does seem to a potential for significant growth through the award of new contracts. It may not be a winner in the short term, but over the next few years the CEO’s goal of becoming a 100mil company is certainly feasible. There is good visibility due to the length of the previous contracts being multi-year, reducing the downside risk. Decent cash pile to support the balance sheet, so no risk of a fund raise. The risk reward to me seems good and I have opened a starter position and will look to add.
It is worth noting that the founders own around 40%, although I think they would struggle to go private, could be a take-out by a larger company potentially.
Thanks much appreciated as it is obvious that you have spent some considerable time on this.
Made Tech (LON:MTEC) I agree about the risk/reward and also the new but proven CFO that made me invest in it. Looks a multi bagger on a 2/3 year horizon.
All the best
Thanks Yiannos - All a learning process for me as I have only been investing for 3/4 years. I recognise I still have a lot to learn, particularly around analysis of the numbers which is something you can only get better at though regular exposure. I find writing it all down helps me to understand the investment case a little better, organising my justification for buying/selling. Posting on here also helps to highlight my mistakes, as people are helpful and point them out in a amicable manner.
Reading management and getting a feel for the people running the company by watching them is something I do back myself with - and I like the CEO/CFO here.
As you say the risk/reward looks good. Cheers.
Reach (LON:RCH) - currently 99.7p (up 3.4%)
Commenting on their 2 May 2024 Trading Update, Graham's view was
"This update is “in line”, despite all metrics appearing to move in the wrong direction and a stunning 33% decline in page views. But the consensus operating profit figure for FY 2024 is a remarkable £97.6m. If Reach hits this target without putting too many costs into its adjustments, the stock is likely too cheap." GREEN
Reach qualifies for Charles Kirkpatrick Bargain Screen, and the momentum and stock rank number have gone up in the last 30 days. The chart also appears to be forming a nice upward curve:
Looks like some major shareholders have been adding since the update.
I hold.
Made Tech (LON:MTEC)
Ben, you’re missing the elephant in the room, which is SBC. Add that back in and you have next to no profit at all. I’m a fan of the sector - formerly outright owner of a competitor and a shareholder in MTEC to boot - but this business has never made a real profit despite operating in a huge growth industry. There’s a real chance that I took the losses on the way down and now will miss out on the gains out of stubbornness, so do factor my bitterness into your thinking. Nevertheless, stick those EBITDA numbers in the bin and look at cash profits - if you can find any.
BnB - No doubt the cash profits are low and not currently growing. When adjusted, 23- 1.1mil, 24-1.1mil and 25E 1.0mil. Quite consistently meek for a few years. It all comes back to the growth prospects under the new government and if they can turn it around. With the growing size of contracts and robust client list, if they can push out a few 10mil+ contracts in the next few months the SP is only going to head north, especially with the market cap being so small. You clearly will have a lot more knowledge of the sector having worked in it (In contrast am a teacher with 4-5 hours spent looking at the company!) and I value your opinions. Do you think that even if some large contracts start flowing the profits will remain depressed, or will they be able to break out of the current trend? If they can't pull off the turn around in the next few years I think it would be safe to say it is never going to happen for them!
Out of interest when it comes to SBC is there a way to explicitly identify the impact of this on the balance sheet or does the exact value remain hidden, diluted alongside other costs? Balance sheet analysis is still something I am learning as I have no financial background.
Well, MTEC were previously unable to make a profit when revenues were higher in the past, so it’s not a given. The key is managing resources - take on too few and you fail to deliver, too many and the weight of those fallow salaries eats up your profit, find yourself in a red-hot hiring war and salary rises deplete your margin. Bear in mind as well that the slight improvement in profit of late derives from a lowered reliance on contract hires. Once the market picks up however, they will come back to the reuiters begging for a higher proportion of contractors - and that will hit margins hard. More income - but higher relative costs. That said, there are companies out there doing very well, eg KNOS with operating margins at 15%. Those however are boosted by software and IP sales, which MTEC is only just setting out to achieve.
If you want to invest in government IT outsourcing with a balanced risk/reward, buy KNOS, which has pulled back hard after a very positively received recent update - perhaps on election uncertainty. If you want to double or triple your money with the very real possibility of losing half to all of your investment - stop losses won’t help when a stock falls 45% overnight - then go for MTEC.
Cheers BnB, lots of factors to consider as always - Kainos has been on my watchlist for a while but I have never bought a position. It does look a very good company with good upside. Made Tech (LON:MTEC) has joined Evoke (LON:EVOK) in my higher risk, higher reward shares pot. Only 2.5% of my portfolio allocation in each. Although the cash rich balance sheet, lack of debt and 60mil of revenues already mapped out over the next few years at Made Tech gives me some reassurance that a huge drop would be less likely. I am looking forward to the FY24 investor meet presentation when that comes out, hoping to get a feel for the CEOs optimism on new government contracts moving forward.
Yes, I'm another in the 'bitter and twisted' camp like BnB having held Made Tech (LON:MTEC) and sold at a small loss. My concern would be that this stock came to market as a go-go growth story that completely stalled. Then it decided to cut contracted staff and run for profits and still didn't make money. The lack of software and ip sales is a big negative here and suggests they will never earn the Kainos type margins. I also don't like the very expensive share options. So, I am sitting on the sidelines - which probably means its a five-bagger in three years!
Reach (LON:RCH) yields 7.7%! They have a rich database of first party data. Amazon have already announced usage (no numbers mentioned). Euros and election must be helping too.
Publisher Future (LON:FUTR) has had a double upgrade from Jefferies recently.
I hold Reach (LON:RCH) too. The investment thesis of holding the share getting large divis whilst waiting for the price to go up seems to be gaining traction. The pension has been looked at, digital growth should be coming and their data on users is what I think may be the jewel in the crown. Perhaps a stage 2 forming here?
Reach (LON:RCH)
'their data on users is what I think may be the jewel in the crown'
Imo, analysts, investors and businesses themselves are getting too carried away with the idea that their data is highly valuable. I don't see much value in what Reach have, data wise. The data imo seems of limited use / interest to 3rd parties - so how valuable is it?
Most of the companies that I hear talking about data are clearly just trying to seduce investors with what has become the latest buzz word (not quite to the level of Ai, but is being overly used imo). What they don't do is explain what data they actually have - how they have been collecting it (and for how long, and how detailed is this data) - and what use cases it has. How will it benefit their business or how will it be useful to a 3rd party. Almost always they give no detail but just throw the idea out there that they have this great potential opportunity.
As I see it, the reality is that half the worlds developed economy is pretty much digital. So 'everyone' has data. There is so much of it, and it is growing at a ridiculously rapid rate, that its value will only be defined by its usefulness. So I remain sceptical that this will drive material gains for the the majority of these non data specialist companies. Unless these businesses clearly identify how they are using the data with a clear business model for gains. But at the moment you hear a lot of superficial buzz word commentary with zero detail and therefore imo minimal credibility.
Also just to add, only recently we have seen Yougov's fairly rapid (maybe temporary) share price collapse. It is perhaps being realised / or questioned - that maybe the value of some of this data has become so commoditised, and the landscape so competitive, that this whole industry could become a race to the bottom.
The mag 7 have shown the power of data - but they have also developed business models around the use of data, and have become data specialists - and have been specialists in this area for a number of years. So although there are clearly small UK companies that do have important and valuable data, imo it's not going to be the case for the majority of claimants. This industry is only going to become more competitive; so I think one really needs to ask themselves - does this business really have useful and valuable data, and are they able to exploit this data successfully? I have heard a lot of silver tongued CEOs mentioning data, while offering no substance or detail, and in some cases it's actually just a bit weird that they actually think their data is valuable, or that anyone would believe that their data is valuable.
I (X) Net Zero (LON:IX.) delisting from aim. A bargain matching facility is proposed. Does anyone have experience of this - how long it lasts, what can one expect from it?
Of course IX. was massively undervalued, today's results - NAV virtually doubled- have proved the ability of the new management, and doubtless there would have been a positive reaction. All seems so 'unfair'. They always seem to come for me. Can we now expect a huge fire at the MSI Norwich factory, a massive cyber attack at Beeks, and a walloping fraud at Pollen Street? Sell in June and go away.
How can a share with a NAV of £1.39 be selling on AIM for only 9p? What an arbitrage!
Sorry to harp on, but the US shares and the AIM shares are in the same company with the same NAV. Somebody who knows how this works can buy shares in I (X) Net Zero (LON:IX.) for around 10p today, and pocket an NAV of £1.39. It's not as though the shares are written off. Who makes the arbitrage?
I know nothing of I (X) Net Zero (LON:IX.) as a business so I make no comment on the validity of the NAV
But a bargain matching facility is just a way of loosely connecting buyers and sellers through a broker off market. So the company is not listed and has none of the protections of listing but if you want to sell shares you can tell the broker how much you would accept and in what size and similarly a buyer might be willing to take shares off people at a certain price. The problem with it is there is clearly no liquidity so very little price discovery and everything is matched. Ie there has to be a buyer and seller, there will be no MM taking your stock on and guaranteeing a price.
As with any delisting though you have to take a view on when / whether some realisation of the assets will take place. Some investors don’t like it as they don’t want to be locked into a private vehicle for a potentially very long period of time. If you are a small shareholder you are also unlikely to get much in the way of communication with which to assess what price and when you might sell stock (if there are any buyers ofc). That’s generally why share prices tank when a delisting is announced.
Back in the days of certificated holding 25 years ago. I got left with a very small holding which had cost me £250. The company offered a matched bargain facility which I never took advantage of and recently they tracked me down to a new address and offered me just about £500 which I was happy to accept. There were many disadvantages to being on a public share register in those days with a listed phone number too. I told many a scammer to f*** off. Glad to have a nominee account these days.
It is a month since Ed Croft discussed Smooth Momentum. This portfolio is up 4% compared to the FTSE All which is down 0.6%. Anyone else following this?
Not me, somehow I must have missed it. I do run a virtual portfolio on shares I fancied at the time and that is about 18% up while the footsie all share 9%.
Hi Paul Halfords (LON:HFD) I thought had a software element to their operation which was performing well and mentioned over a year ago, making good progress, did you see any updates on that as I thought that had lots of potential too? Thanks
I think I read that the SaaS business was doing extremely well. Big deal with Bridgestone and 2 or 3 more new customers coming on board. Also launched a “new” parts business which they see as a big growth opportunity.
Anyone else holding/following Gulf Marine Services (LON:GMS) I hold.
Seafox is biggest shareholder by far c28% and has just sold $10m through Zeus at a discount to closing market price, 17p vs 20p close last night. Of course no reason for the sale is given - so far so bad. (At least there is now a 75 day lock in period in which Seafox can't sell)
As expected the shares opened at just above the 17p price this morning. I guess you could say this puts a floor under the share price especially as the placing was oversubscribed by 10%.
Clearly there is risk with this company but I see it as similar in one way to Smiths News (LON:SNWS) I also hold - stay with me here! Basically a business historically carrying too much debt but with very good cash generation and good visibility of earnings.
As debt is reduced then the risk to lenders starts to diminish and so finance costs and costs of finance (lending margins) also fall and so value starts to flow from debt to equity. Furthermore as debt becomes more manageable then any covenants regarding dividend payments are gradually relaxed.
Gulf Marine is not in a structurally declining industry and doesn't deliver newspapers to oil rigs however, once it clears it's debts, the massive free cash flow will be available for divis and fleet expansion/investment.
In the meantime the world is waking up to the fact that gas and oil are needed for the foreseeable and so investment in these areas is rising. GMS' platforms can also be used for wind farm installation.
I was hoping that Seafox would make a bid for GMS otherwise why hold nearly 30% of the stock? Back in May 2020 Seafox did bid but only offered around $32M I think and this was rejected by GMS. Looking at todays market cap of over £200M you can see why!
My conclusion is diarise for 75 days and see if any more shares are sold. In the meantime I've dusted down my tin hat!
Keywords Studios (LON:KWS)
I would agree with Pauls comments the revised offer price is fair. Unless i have missed something this is actually a reduced offer based on original offer price of 2550 - i dont think the lower 2430 offer of mentioned from wednesday was announced to the market?
If thats the case practicably speaking the offer has been reduced by 100p not increased by 20p based on what was publiclly known last night last night.
trading update here too and conditions are softer and earnings are H2 weighted and some cancelled stuff that has hurt them a bit in H1 - so factoring in the great offer premium in the first place and slightly sketchy outlook i still think the offer price is 100% acceptable to me - only shame is thats its not a done deal that i can bank today - price is 150p below the offer so this imho is far from a done deal - even if it is progress that offering company havent taken the opportunity to walk away.
Slightly annoying that i have 3 current pending takeovers where i am being too stubborn to simply take slightly less than the offer price - thats always a risk and i would say risk with Keywords Studios (LON:KWS) is deffo above average as its a big premium to prior price and its a complicated buisness - due diligence would be easy. Hey ho i can dream of the day when i have next wads of cash to spend (Virgin Money UK (LON:VMUK) and International Distribution Services (LON:IDS) being the other two)
Hi Paul could you have a quick look at Harworth Harworth (LON:HWG) £106million land sales yesterday directors buys straight after small amounts, discount to NAV and fste 250 entry possible. You not looked at HWG since 2015 so another share to tick off?
Harworth (LON:HWG) they seem to be really on a roll recently with a sting of good updates and director buys. Yesterday's sale of land was at a more than 100% premium to its book value (not sure why they didn't highlight this in the headlines?) indicating there could be a lot of hidden value in their landbank. Could also be a beneficiary if Labour push through more building projects and ease planning constraints.
Harworth (LON:HWG) , which is held in my wife and daughter's ISAs is a property stock so I doubt that it will covered in the SCVR.
As Bouden54 mentioned it is on a roll now, but you couldn't give it away last October, when it dipped below 100p. I was fortunate to add at around 106p, my regret is that I didn't buy some for my ISA!
SysGroup (LON:SYS)
Don’t know anything about this company but it seems that NR has acquired 3% in the latest fundraise.
Perhaps people who know more about SysGroup (LON:SYS) can give some thoughts.
All the best
Yiannos, did have a quick look at SysGroup (LON:SYS) when the fundraise was announced. They've at least gone for a proper sized raise, so won't be back every 6 months with the begging bowl like many others.
There's a useful note by Zeus available if you haven't already read it. New management team, some interesting names for such a small company, can see possibility of good growth.
" SysGroup has transformed its senior management team. The previous 13person management team has been replaced with an eight-person team with six external appointments. The new management team has strong track records in managing rapid growth, executing acquisitions and building sales teams. SysGroup has already hired four salespeople from Softcat, implemented performance-driven compensation schemes and built a blue-chip team of AI experts from JP Morgan, AWS, McLaren and others."
It's not my usual thing as it's about a year earlier than I'd normally be interested but Ive been pondering a punt. Be interested to hear what you think when you've taken a look
Thanks Wolfie
I ll have a look over the weekend.
All the best
Great report Paul Thanks. Also like the humour. Very good :)
" Paul’s opinion - I still like HFD as a potential cyclical recovery share."
Personally I still don't know why these bike companies don't hire bikes for kids. I remember our 3 had Isla bikes and outgrew them every 2 years. But they held 85% of their value on secondary. Would have made more renting with warranties. Speedy Bike Hire anyone?
Assetco (LON:ASTO) half year out today, loss reduced to 1.6m. Proposals to create 2nd class of shares to better reflect value or Parmenion. That's the interesting bit for me - but does anyone know how that would work in practice? Says won't be tradeable on AIM.
Nightcap (LON:NGHT) and I (X) Net Zero (LON:IX.) proposed delisting. What a shame. Said nobody!
Except perhaps their shareholders...
My morning smallcap tweet: Between a crock and a mad case
Nightcap (LON:NGHT) Musicmagpie (LON:MMAG) I (X) Net Zero (LON:IX.) Renalytix (LON:RENX) Tyman (LON:TYMN) Science in Sport (LON:SIS) Proton Motor Power Systems (LON:PPS) Ethernity Networks (LON:ENET) Home Reit (LON:HOME) Surface Transforms (LON:SCE) Guild Esports (LON:GILD) Catenai (LON:CTAI), Devolver Digital (LON:DEVO), Mirriad Advertising (LON:MIRI), Symphony Environmental Technologies (LON:SYM), Thruvision (LON:THRU)
◄Nightcap (NGHT)► proposed delisting due to low SP. Warns FY-June rev in line but adj EBITDA below market expectations blaming a sack of slings and arrows plus the costs of delisting. Er, that's only just been proposed. What crock. [SP=3.2 Cap=8m]
◄musicMagpie (MMAG)► H1-May. Uses 'second-use' as a new and incorrect euphemism for secondhand. It's better than the ghastly 'pre-loved' I supposed. Outlook "remains confident in the strategy of unlocking inventory in people's homes". Like burglary then? [SP=7.44 Cap=8m]
◄i(x)► Net Zero (IX.) proposes delisting after only 30 months. Blames SP below NAV, and liquidity. [SP=16.2 Cap=14m]
◄Renalytix (RENX)► gets stay of Nasdaq delisting. Will present plan to get SP above $1 again. [SP=12 Cap=26m]
◄Tyman (TYMN)► revised rec offer - adds 15p special div. [SP=351.79 Cap=691m]
◄Science in Sport (SIS)► guides H1-June rev down 27% but U/L EBITDA c.£2m up 77%. Blames rev drop on "shift in sales towards a royalty based model in certain export regions as well as a conscious step back from marginal revenue channels". Guides FY rev down but thereafter "sustained revenue growth via effective marketing and strong commercial execution." [SP=18.58 Cap=34m]
◄Proton Motor Power Systems (PPS)► another loan, €12m, from Falih Nahab, a large shareholder. [SP=2.19 Cap=36m]
◄Ethernity Networks (ENET)► wins $1.05m contract with majority of delivery expected during H2 2024. [SP=0.74 Cap=3m]
◄Home REIT (HOME)► FY22 accounts delayed to August because the auditor needs more time. [SP=38.05 Cap=301m]
◄Surface Transforms (SCE)► FY-Dec. Warns FY24, 25 will be at the lower end of range in last month's fundraise. Writes off one of the new furnaces since it doesn't work. [SP=1.55 Cap=20m]. I hold a cold ember of this.
◄Guild Esports (GILD)► H1-Mar. Outlook - cost cuts, cautiously optimistic. Material uncertainty going concern stmt. [SP=0.32 Cap=3m]
◄Catenai (CTAI)► FY-Dec. Material uncertainty going concern stmt. [SP=0.26 Cap=1m]
In line: DEVO, MIRI, SYM, THRU
MrContrarian. Really appreciate your morning summaries and laughing out loud at the quips inserted at various points. Sets me up for the day. A staple of the SCVR.
The quality of humour on here keeps getting better.
Some horrific announments today. Seems like lots of delistings? Wondering if they purposely chose a sunny summer Friday as a quiet day to slip out bad news...
Halfords and market conditions .
Paul
In response to your comments -
“Maybe he can update us with the latest market conditions, and when things might normalise?”
Here’s my thoughts
The industry is still working through its stock of oversupply of bikes, probably 18 months left until this unwinds .
Companies that survive or are reborn out of bankruptcy / administration will be left in a leaner markst as the over leveraged, poorly run and frankly froth has gone .
Kona for example was bought by Canadian private equity 3 years ago and has just been bought back by the owners .
Wiggle became a giant that obliterated the bike market by never making anuch money and trying to become a global player , stupid VC / private equity lemmings loading it with huge debts and just clueless how to run a business in tough times .
It was all very predictable and “everyone has a plan until you get punched in the face”
I’m currently very positive predictions
- there is one more top 10 bike company about to fail
- out of adversity comes opportunity for correctly run efficient and lean organisations to do well
- 18 months for oversupply to unwind
- Mike Ashley / sports direct have a golden chance to grab control of the cycling market with the distressed assets they have bought . They should buy Halfords .
- Mike Ashley / sports direct will fail to take the opportunity and leave the door open
Bike parts and accessories has already turned and there’s an upswing in sales .
I bought a very small company out of administration a year ago , “Banana Industries” and the consumables such as tyres / saddles / tubes etc are all Massively up the last months .
There is no competition left with industry knowledge and contact so wide open and the overstock in zP / A has already cleared .
Triathlon is massively out of fashion .
High end road racing and time trialling is non existent
Manils are playing golf and watching football
Gravel and mountain bike are doing well .
Kids bikes are doing ok .
- there’s a very very strong move (as in fashion) to repurpose and upcycle old bikes (a few paris / London / Copenhagen are doing some very cool stuff (exact same id happening in fashion )
Lookong around at the UK market I can’t see anyone in the industry that knows what they are doing.
But maybe that’s the crux of the issue .
The “industry” was historically a collection of maybe 2000 hard core hard working mom n pop / founder led enthusiastis with some strong brands all run by ultimately enthusiasts that always did it for passion more so than profit .
The globalisation and commercialisation. and leveraged debt and private equity / VC front both changed the landscape and destroyed the industry as it was .
So now it’s an emerging ghost town with a vacuum of strong players and no mom n pop stores left and no one to supply them .
Someone once said to me “the only way to get a million quid out of the bike industry is to start with two”
However to end , here the thing .
- cycling by definition has to be a long term success for the environment so lots of people will ride bikes in the future
- repurposing old and used bikes is going to gain momentum (more parts / accessories)
Funny , I just wrote all this and realise that my thesis is the same as I have with JD sports where new fast glossy fashion is going to struggle as the recycled repurposed resold bandwagon becomes an industry is currently what is happening right now which means there will a much changed Landscape in the next years .
So get out that old mountain bike , put on some green tyres , a BMX handlebar , a red saddle and go for a city ride down to Brick lane .
Anyone interested look on Instagram at
Loup_et-cheyenne
Anyway totally unstructured post .
Personally can’t wait for all the private equity / VC guys go take home their easy money and froth and let real people compete fairly and honestly in a great market there aren’t many left so just a few more to fall over
Fascinating stuff PlanetX, I think I got the gist of most of that! Many thanks, Paul ;-)
Paul
And if you need some green tyres or a sauna tent here’s where you can go
www.bananaindustries.c.o.uk
(Delete if not allowed )
This is maybe the “mad max” thunderdome future , definitely this is “happening” in the next years, upcycked and recycled .
Great timing, just about to put fresh tyres on 6 bikes coming out of storage. That green tyre is daft but tempting...should lift the spirits on a wet commute. Good luck with it and thanks for the terrific industry info.
love this and the post Planetx, covered A LOT of ground with useful 'local knowledge' on the bike world... are ebikes helping?
Manil meaning ? i googled it and went down a rabbit hole.....
is it the same as MILOAF? (men in lycra over the age of forty). :0
all the best with your new venture....
.
I think its a typo Patrick,
I believe it might be MAMIL rather than MANIL - standing for Middle Aged Men in Lycra.
Pretty close to your MILOAF acronym.
Best
Richard
Hi Planetx, What are your thoughts on Tandem please? (LON:TND)
Tandem
Think they have blown it by building big stupid warehouse that is too big .
Their plan is now to offer 3PL to fill it but that’s another business entirely and there are real experts in that .
The brands are weak
The CEO is average to poor
They will get hammered on freight this year
But it’s cheap, I talked to David Jeremiah Barry about it 6 months ago and he just bought 3% !
So couple years more of underperformance but they might catch the upswing if it happens .
My issue is they blew the cash buffer on the warehouse .
Back in the day about 20 years when I was young and ambitious ago we looked at buying them, pension deficit put us off , valuation was about 3 million then which was ludicrous .
The CFO at the time was totally uninterested and cared about his salary , options and nothing else didn’t want to engage . He’s long gone along with his pension which still needs paying .
Probably needs to go private
If they were opportunistic and entrepreneurial they’d be mopping up the likes of Moore large / wiggle etc but they are run by industry journeymen asleep at the wheel and they’ve just given all the petrol away .
It’s going to be down to market turn to save them
Cheap for a reason .
who or what is 3PL?
guessing at third party logistics ?
Third Party Logistics
Yes 3rd party logistics , effectively doing warehousing job for others . We used to use clipper at one point .
Another issue surely must be the proliferation of the ride and drop off anywhere bikes . Why buy a bike when you can so easily and cheaply rent a temporary bike and drop it off anywhere you choose?
Maybe true in cities in the south and that big place with all the money, what’s it called ? Er oh yes London .
They tried that in Sheffield with one of my ex employees running it and all the bikes ended up in the river Don (wasn’t me honest guv)
Hi Caper4,
I used to ride the hire bikes in London, but have stopped now, as they're so expensive! Lime is a good scheme, but I used one to cycle about 20-30 mins into central London from my base in Canonbury (about 1 mile North of Angel), and it cost me about £6 or £7 just for that one short trip! Similar sort of thing with another bike hire scheme with dark green bikes, where they give you supposedly 10 minutes free, but after that it's expensive. And I was landed with a fine for not parking it in a correct zone (but thought I did), so have never used them again.
I suspect most of these short hire bike schemes will end up in the river, like so many of their bikes! Did you see the TV footage of the French dredging the Seine ready for the Olympics, and it was load after load of hire bikes coming to the surface! Why do people do this?!
They're a damned nuisance on the pavements too, often left in brazenly dangerous positions esp for blind or partially sighted people. Still, they do give something convenient for Seamus (my one remaining dog) to sniff and wee on, as we pass by, on his increasingly slow and short walks.
Paul.
Hire bikes
Could go the other way
If these do fail and fall over that’s a positive for bike sales .
From what I understand they don’t make any money so probably only a matter of time before they all end up in the rivers.
I do recall there are literally millions of these used / damaged / broken bikes in a graveyard of broken bikes somewhere in China after failed schemes .
Here it is , you can tell what I read
https://www.thesun.co.uk/motor...
PEDAL TO THE METAL
‘World’s biggest’ bike graveyard has mountains of cycles left for scrap – & bizarre reason they’re all the same colour
A once-thriving industry's collapse has been blamed for the 'waste'
I used to work in london and used the santander (not Boris!!) bikes. cost me £90 for an annual memberbship. you used an app to find where the stands were (and how many bikes/spaces they had). Free for 30 minutes use !!!! Throw in an extra £1 per trip for an electric one!
this versus £25 a week for the crowded Underground. plus I got to ride thru london down the mall and thru hyde park everyday . Amazing
Worked very well in london and bikes that aren't returned to the correct stands you get nailed for a fine of £400 on a guilty til proven innocent basis. So lose is probably low....
Set up right I think these schemes are brilliant for big towns... in terms of health, traffic, pollution etc etc... But agree with PlanetX don't make any money... (Ask Santander !!). Sorry bit off topic investment wise....
Interesting. Did not realise they were so expensive as are widely used where I live in south west London . So many of them all over the place and see frequently being used by all sorts of young people. No idea where they get their money from if so expensive !!
A friend went to Chinese city over five or more years ago when these 'free' bike schemes were all the rage, and was surprised to see huge numbers of bikes proliferate, with bikes scattered in certain street areas. As ever there was a massive oversupply.
Now much less visible. Probably the eternity of the Chinese Covid lockdown (nearly 3 years?) didn't help either.
Wonder what happened to all those Chinese bike manufacturers?!
Great post thanks PlanetX.
(As a self confessed Mamil who also plays golf and watches football, isn't the latter tedious at the moment?)
'Manils are playing golf and watching football'
Or like me they have graduated from MAMIL to OAPIL.
Interesting Planet X.
I've done the Etape over Col de Tourmalet and dragged myself round the Dragon, so enjoy my riding.
However, just crashed my main bike and I'm not finding a lot of bargains out there in shopping for a replacement (admittedly I need a 61cm or a 64cm).
I recall buying 105 & Ultegra equipped bikes for just over £1k/£2k a decade ago, same spec now can take you past £3k/£4k, even without Di2.
That is way ahead of inflation (and sterling weakness), so what has changed?
Monty carlo
What’s strange is that despite there being this huge overhang of stock that the bargains are not on offer
I think the inventory is not actually in the uk / Europe but still in far east .
Planet X most famous model was pro carbon ultegra at 999 which sort of broke an industry barrier and was untouchable but we always sold direct and bought direct .
Agree no reason for a 105 bike to be much over 1k but that requires lean production and direct sales and there’s no one left .
Customers actually had it so good a few years back with amazing value and those days are gone and prices are revering to more traditional pricing with higher margin and distribution margins in the mix
So don’t think you’ll have much luck getting ultegra anywhere near 1k .
Record (LON:REC) - be interested to get your thoughts on this currency managers results today. I hold. It looks a strong set of results albeit growth appears to be flatlining a tad. Great cash flow and dividend. They seem to be getting more focused on 6 core product categories which is sensible, as I think the previous CEO (whilst very entrepeneurial) probably got into a few too many new things.
Thanks topvest for your synopsis of REC results, helpful.
I like Record (LON:REC) so will prioritise that as the first proper company I look at today.
Regards, Paul.
Vertu Motors (LON:VTU) CEO (via his wife) ditched 2million shares over the past few days for around £1.5million. Nice payday for them but I can't imagine the market will be best pleased this morning. Especially, as this share is regularly seem as one with huge buyout potential... this sale would appear to pour a bit of cold water on that narrative, at least in the short term.
Good morning BenHazz,
I noticed that too, and thought also, why sell now. But they do still hold over 5.5 million shares. If they sell any more, I’ll start to get worried.
All the best.
Could this [Vertu Motors (LON:VTU) director's wife's sale; I hold] just be a bit of sensible planning ahead of a possible hike in capital gains tax?