Small Cap Value Report (Fri 28 Oct 2022) - LIKE, MADE, FRAN, MRK

Good morning from Paul. Today's report is now finished. Join me tomorrow afternoon for my latest weekly roundup podcast!
Interview with corporate bond expert, Paul Hawkins. Click here for the audio. It's also been published on my podcast channel ("Paul Scott small caps"). I was burning the midnight oil yesterday evening, typing it up too (exclusively for Stockopedia subscribers) which is a separate post here. Very interesting, and I learned a lot (in particular that bonds do usually have covenants!). We discuss bonds generally, and also the SAGA 2026 bond, and how it relates to Saga equity (I hold).
Next CEO interview - will be next week, on Tuesday, with Cerillion (LON:CER) - an excellent software company, that's performing so well.
I was hoping to also talk to Shoe Zone (LON:SHOE) - another impressively performing company - but they declined my invitation, with no reason given. Rather disappointing, but never mind! I'll just give the slot to a different company that is more interested in talking to small shareholders.
Agenda
All written by Paul today, as it's a Friday.
Likewise (LON:LIKE) - my first look at this challenger carpet distributor (with Headlam (LON:HEAD) being the dominant player in that sector). It issues a fairly mild profit warning today, due to tougher market conditions & higher costs. But it's still profitable, and I check out the last balance sheet, which is solid (with freehold property included). Overall, I'm pleasantly surprised, and think this share is worth me covering in future. It could be a serious challenger to HEAD, as it's growing fast, and already delivering revenues of c.£120m for this year, so not a small business any more. Potentially interesting longer term, maybe?
Made.Com (LON:MADE) - an article in Retail Gazette, says that MADE could be going into administration with PWC imminently (today maybe?). The founder lashes out at management.
Franchise Brands (LON:FRAN) - issued a positive Q3 trading update yesterday, ahead of expectations. It looks a good business, which has established a strong track record of growth since listing in 2016. FRAN shares have been a rare strong performer this year. It's not cheap, but does seem an impressive growth business, with scope to bolt on more franchise businesses.
Marks Electrical (LON:MRK) - I missed this one about 2 weeks ago, but managed to catch up with it today. Good revenue growth in a weak market, but profits are reducing. I like the company a lot (lean, efficient), but dislike the electricals sector, and struggle with the valuation still, despite a hefty fall. Could be good long-term though, maybe?
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Likewise (LON:LIKE)
18p (pre market open)
Market cap £44m
I’ve been meaning to look at this carpet distributor (a smaller rival to Headlam (LON:HEAD) ) since it listed in August 2021, but didn’t see much point, given that HEAD shares offer such good value, and a decent turnaround story too.
This is the only news today in my sphere, so I’ll have a quick look.
Likewise Group plc (AIM:LIKE), the fast growing UK floor coverings distributor, provides a trading update for the current financial year ending 31 December 2022 ("FY22").
Revenues growing fast - Q3 growth of 96% (of which 26% organic)
FY 12/2022 revenues expected to “slightly exceed current market expectations”
Profitability “lower than originally anticipated” - blamed on -
- “Pace of investments”
- Inflationary cost pressures
- Unfavourable market conditions (blamed on Ukraine, UK politics, and hot weather)
PBT margin now expected to be c.2% (below existing market expectations)
Next year FY 12/2023 expecting similar profit to this year.
New distribution centre in Glasgow opening in Q1 2023.
Sticking to growth strategy, not trying to maximise short-term profits.
Claims a strong balance sheet, with over £40m NAV (I check out this claim below)
Dividends - planning on maintaining same level of divi as July 2022, in 2023.
Interim Results - these were issued on 26 Sept 2022, for the 6 months to 30 June 2022. I’ve had a quick look. Key points -
Very rapid revenue growth, up 108% to £58.4m in H1 (27% organic)
H1 underlying PBT £1.9m (up 77%). That’s a 3.3% margin, which compares favourably with the guidance today for FY 12/2022 PBT margin of 2.0%, which implies H2 not much above breakeven.
Lots of adjustments, so statutory profit in H1 was only £0.1m
Net cash of £1.9m
NAV £39.7m, less £10.8m intangible assets = NTAV £28.9m - that’s actually quite good, and means that 66% of the market cap is asset backed.
Note that £20.9m assets are “land & buildings” which is nearly always freehold property. This is confirmed in the narrative, with 2 freehold properties being mentioned. This is a strong positive for the shares.
Revised forecasts - thanks to Zeus for an update note today. It’s obviously lowering forecast profit, by 33% to £2.5m this year FY 12/2022. That’s on £120m revenues, so management is building a decent sized business here.
It’s still profitable, albeit reduced somewhat (but still above profit last year).
My opinion - this looks better than I expected, particularly the decent asset-backing.
This is a profit warning today, so the shares are likely to fall. Although I wouldn't expect a particularly large fall, as the price is already very soft.
I much prefer larger carpet distributor Headlam (LON:HEAD) but it looks as if LIKE is becoming a significant challenger. Although it might struggle to be able to fund any more acquisitions without raising fresh equity, which existing holders probably wouldn’t want, given the low share price.
Overall though, for my first look at this share, I’m pleasantly surprised by LIKE, as I was expecting to dismiss it, but it actually looks quite interesting, if it can achieve greater scale. So I’ll add it to my mental list of things that are worth reporting on in future.
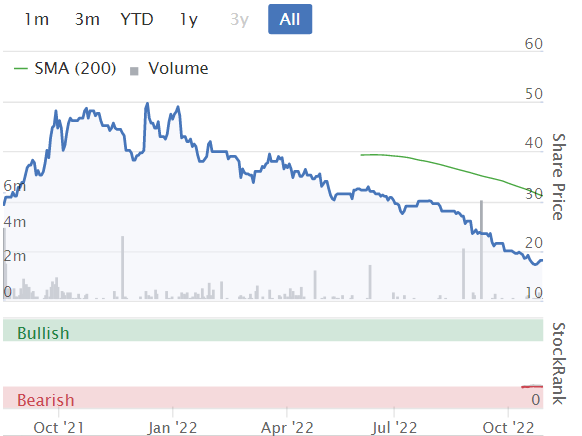
Note that the StockRank is very low, but it's a new share (floated in Aug 2021) so there's probably not enough data yet to produce a meaningful score.
.
.
Franchise Brands (LON:FRAN)
160p
Market cap £208m
We should have covered this update yesterday, as it was ahead of expectations, which we always try to focus on (over, or under expectations are a priority for us here).
To get up to speed, I’ve just read an excellent review from Roland here in Feb 2022.
More recently, Graham reviewed its interim results here in July 2022, and saw himself being “won over” by FRAN’s good performance & track record.
Even though I write a lot of the material myself here, the SCVRs are so useful as a quick way to get up to speed on the key issues, for hundreds of companies.
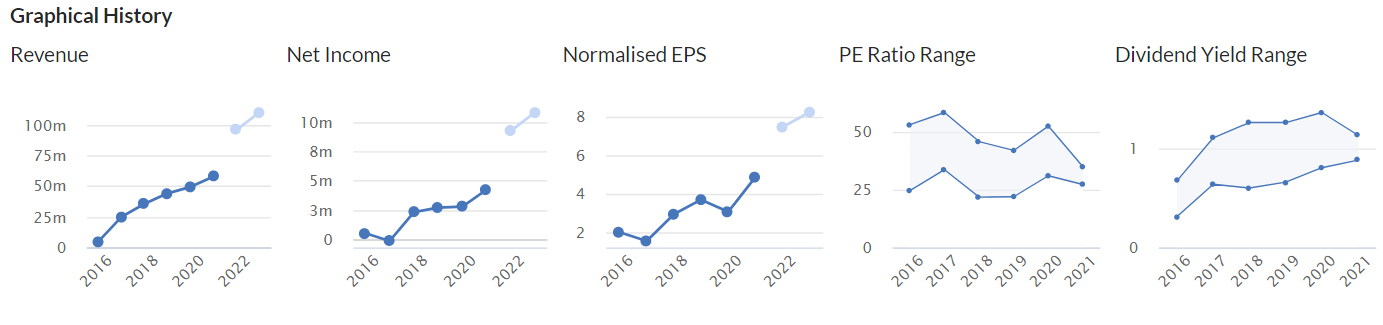
As you can see from the graphs below, there’s an excellent track record since it listed in Aug 2016. The key one for me is EPS, because FRAN has issued a lot of new shares to fund acquisitions, but if EPS is still growing strongly, then it tells me the acquisitions have been good.
Also note from graph 4 that this share has been consistently highly rated, so the forward PER of 19.8 showing today on the StockReport is relatively low -
.
Strong contributions by Filta North America and Metro Rod
It says these two are the biggest businesses within the group, and both trading well.
Board confident of exceeding current consensus market expectations for the full year
Graham looked at the acquisition of (listed) Filta in July 2022, and thought it seemed a good deal. Today FRAN says that Filta has benefited from the elevated price of cooking oil, because Filta can double the useful life of this expensive ingredient. That sounds positive. Dollar earnings have helped, translating into higher sterling amounts - but watch out, because forex is often swings & roundabouts. So one year's tailwind, could be the next year's headwind maybe?
Metro Road, and Metro Plumb are also doing well.
The only negative comment is this -
The B2C Division continues to experience headwinds in franchise recruitment and retention as a result of the unusual conditions in the labour market in the UK.
I’m not entirely sure what that means?
Overall - with thanks for the footnote, which saves us all time, and gives clarity.
Overall, the Board expects the Group's revenue, adjusted EBITDA, and adjusted EPS for the year ending 31 December 2022 to be ahead of current consensus market expectations*.
* Consensus market expectations for the financial year ending 31 December 2022 are revenue of £92.9m, adjusted EBITDA of £14.3m and adjusted EPS of 7.31p.
I’m not interested in EBITDA, but adj EPS is usually fairly reliable.
Broker update - thanks to Dowgate Capital, which has modestly raised its FY 12/2022 expectations from 7.3p to 7.7p - not bad in the current macro conditions I’d say.
FY 12/2023 is little more than guesswork for many companies, but they’re pencilling in 8.3 adj EPS.
Valuation at 160p/share comes in at a PER of 20.8 for 2022, and 19.3 for 2023.
This is a tricky one - can we justify a high PER in a bombed out market? I’m much more comfortable with toppy valuations (relative to the market) when a company is trading well, as this is. Also, FRAN has now established a really good track record, so clearly management is doing a good job, and has lots of skin in the game too.
My opinion - it’s not cheap, but that’s because it has a good track record, and is trading well. So it’s really up to you to decide if you’re prepared to pay a fairly full price, or not.
This bit from the Exec Chairman’s comments is interesting -
"I am particularly pleased that the acquisition of Filta has given us a significant international presence in the large franchise-friendly North American market. This will considerably enhance our scope for both organic development and accretive B2B acquisitions.
Note that management trumpets the “strong ungeared £100m balance sheet”. I’ve just checked, and £86m of that is intangibles (goodwill on acquisitions). Remove that item, and we’re left with an adequate, but quite modest balance sheet. It does have £7.5m net cash (this is as at 30 June 2022). So for a £208m mkt cap company, there’s actually very little asset backing, but that’s fine as this investment is about profit & cashflows, not assets. It does however mean that any more meaningful acquisitions would need either fresh equity issuance, or taking on debt, or a mix of the two. Management seem good at acquisitions, so neither is necessarily anything to worry about, and in a downturn there might be some good opportunities?
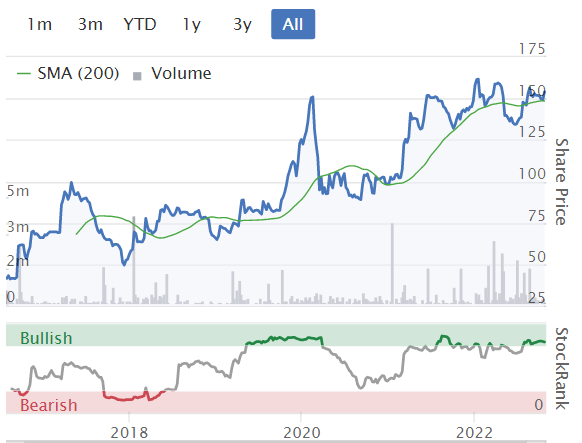
Very good-looking chart, you would hardly know there's been a pandemic, or a financial crisis from this, and FRAN has done well since it listed -
.
Marks Electrical (LON:MRK)
63p
Market cap £66m
I’ve reported positively on this online electrical retailer 4 times this year.
The latest update on 11 October slipped through the net here, so I’ve caught up with it today.
H1 Trading Update (6m to end Sept 2022)
H1 revenues £43.1m, up 15.1% vs LY, a slight acceleration from the +13.7% reported in the first 4 months of this year FY 3/2023.
Market shares gains.
Particularly challenging market backdrop.
H1 margin pressure from competitors discounting, but abating now.
Rigorous cost control.
Should benefit from operational leverage in peak H2 trading.
Robust debt-free balance sheet (Paul: it’s OK)
Net cash £7.7m at Sept 2022.
Confident of achieving FY 3/2023 targets.
Improved stock turn.
Latest forecasts from Equity Development is 4.32p EPS for FY 3/2023, down from 5.0p in the previous 2 years.
Forecast for next year is 5.74p, but it’s too early to be anticipating earnings growth, I feel.
My opinion - same as before. This looks a really interesting business, in a lousy sector, with little to no pricing power, selling other peoples’ products. So it’s all about efficiency. I like the business model at MRS - small, lean, and efficient (watch a mgt webinar to see what I mean).
So this is the investment case - small & lean, in a big market, so opportunity to grow fast, gaining market share. There’s also the chance that larger competitors might go bust in a recession.
Given the macro uncertainty, and falling earnings, I can’t see a strong case for buying this share right now. A PER of 10 would be a share price of about 43p, which is the sort of level I might consider a small purchase. So at 68p, it’s well above the level I think makes sense in tricky markets/macro. Long term though, this company looks a potential winner.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Paul, the boss at Likewise (LON:LIKE) is Tony Brewer, ex chief at Headlam. They poached a number of people to set up the business. Must have been a falling out somewhere along the way or someone felt they weren't being adequately rewarded.
Alternatively it may be that Headlam (LON:HEAD) perhaps got too unwieldy through all the acquisitions they made over the years and there was too much resistance to change in the management team. Certainly Headlam have been trying to drive increased efficiency over the last few years to get operating margins up. Seem low for both and if now competing nationally it may be that they won't improve much for either. Share price trend for both looks similar for this year. Steadily down.
Hi sevencc,
Yes that's right. Given that Headlam seems to have needed a massive sort-out, with numerous inefficiencies and problems being identified & improved by the new management, for me that puts a big question mark over the ability of the old management to do things any better at Likewise!
Regards, Paul.
Morning Paul,
Just listened to your interview with Paul Hawkins on Bonds etc.
Very informative, thanks to both of you for putting that up.
Richard
I think bond investment sounds really appealing. However, approaching it as a complete novice it's so difficult to find good quality information about what's on the market. Unlike equities where the data is easy to find. It may just be my approach.
I've listened to the podcasts, which are fantastic, and thought an etf or fund would be a good first step. So, far I'm struggling to find anything that matches the yields being discussed. Will continuing researching however, as on the face of it I find the topic fascinating.
May be easier to stick to equities!
I'm with you!
The bond market is huge and overwhelmingly comprises professional investors. Why wouldn't it be efficient?
The Zulu Principle (Jim Slater) wouldn't seem to apply to corporate bonds, nor does the PI's abilility to be agile and to trade smaller volumes than the professionals. Where's our edge?
Good points FREng!
What interests me, and where I think we could actually have an edge, is identifying bonds that are very unlikely to default, but where they've gone below investment grade for whatever reason, which then triggers an avalanche of sellers who are forced sellers under their mandates. This creates dislocated prices.
I know several distressed bond investors, who are real experts in that field, and they make fantastic multi-year returns, using this strategy.
The main problem seems to be that the minimum size can be £50-200k per bond, so this would only really work for people with portfolios probably £5m+
That said, Paul H did highlight Prefs, and investment trusts, which might be better ways for us to dip our toes in, and learn the ropes!
Fascinating subject though, so I really enjoyed learning more about it.
Regards, Paul.
Yes 'fallen angels' as they are known in the fixed income world (companies downgraded from investment grade to junk). These often do very well for the reasons you mention - they can be picked up very cheaply due to forced selling (eg pension funds may not be allowed to hold junk bonds).
Wisealpha sells fractional bonds (I have a small amount with them)
Hargreaves Landsdown have a list of bonds, but the spreads seem to wipe out the yield. Anyone have any thoughts?
Hi se01pfd,
>> and thought an etf or fund would be a good first step
If one is not averse to paying a management fee a collective type vehicle is certainly worth a consideration. It is the route I have chosen in this area as I just don't believe I could add anything e.g. in determining the creditworthiness of a corporate over and above that of a manager who has been doing this on a professional basis for 20+ years. I would be totally outside my circle of competence, so am happy to pay somebody the management fee.
My largest holding in this space is CQS New City High Yield Fund (LON:NCYF) which is an investment trust. This is currently yielding over 8% and would give one immediate access to a whole bond portfolio. With ITs one obviously has to be comfortable dealing with the discount/premium - I have held this over several years and opportunistically bought more whenever there was a meaningful discount. Very happy with results so far.
If ITs interest you, I'd start with the AIC website - here is a list of other ITs in the "Debt - Loan & Bonds" sector:
https://www.theaic.co.uk/aic/f...
My personal preference is just for Investment Trusts, so I have no knowledge of ETFs or OEICs (Funds).
Hi welwichia,
Thanks, very interesting. Quick question, does the investment trust you mention pay out the divis, to you as an investor, or do they accumulate the payments from the underlying bond holdings? Or a mixture?
Thanks, Paul.
Hi Paul,
they pay out quarterly and drop into my HL ISA as a regular cash dividend.
Here is the recent history:
The one thing to mention of course is that unlike holding an individual bond, you don't get to hold to maturity with a collective ... i.e. they just keep rolling over into new issues etc. So there is an element of uncertainty that you don't have with an individual bond where you know pretty well what you stand to gain if you hold to maturity. But in my case, I am just after a fire-and-forget stream of income ...
https://www.theaic.co.uk/compa... has all the dividend history, portfolio composition etc.
Hi Paul NCYF pays 1/4 ly divs. currently 3 x 1p,and final 1.48p.
Have held for many years ,probably added from J Baron comment. Tony Axon
I like to look of Invesco Bond Income Plus (LON:BIPS)
Quality bond investments and manager likely to be adding more in this environment. Decent yield around 6.8%. Any holders/views?
Thank you. I will take a look at this. Sounds promising.
This is very interesting thank you. Amazing performance over the last year all things considered... the premium a little off putting to me. Just read their report though and it all reads well. On the list. The one small reservation I have is that its towards junk and actually I can weather single stock risk and get a higher investment grade... Im not so keen on high yield as a space but that's a timing issue.
CQS New City High Yield Fund (LON:NCYF) , CQS New City High Yield Fund welwichia response and query.
You say you are ''very happy with the results so far''. However, checking the HL website it shows the performance as being negative ober 1, 3 and even 5 years - -9.9%, -12%, -17% respectively; this against a yield quoted as 8.5%.
There is a premium to NAV of 5%., why pay a premium for such poor performance. I don't follow how you can be 'very happy' on these figures. Have I missed something?
Hi dartagnan2019,
if you think this is a poor performance, you should see some of my equity holdings over the last 12 months! :-)
More seriously though, we are probably looking at this from very different perspectives. In terms of capital gains, individual results will obviously vary a lot depending on whether one's purchase points coincide with the precise look-back dates you have chosen. As its stands, I am showing a small positive gain on the capital front ... however, this is not at all why I hold this! To my mind it does not make sense to evaluate a Fixed Income investment on anything other than a Total Return basis ... I have a small allocation here as a diversifier to an otherwise very equity-heavy portfolio. The regular and (so far) dependable cashflows at times like these are very welcome and provide "dry powder" that can be redeployed into equity assets that are trading a depressed valuations.
Also, in periods where the market just goes sideways for a prolonged period some form of yield may be the only achievable return. So, both in terms of a bit of non-equity diversification and in terms of providing a regular cashflow CQS New City High Yield Fund (LON:NCYF) has delivered for me ... even during the Covid period when many equity dividend payers had to cut or stop paying out.
I don't know if HL provides charts showing the total return - this is from sharepad:
I focus only on the black line (TR) and have used the dips in shareprice as opportunities to top-up. As they say ... YMMV ... for my particular circumstances, with my particular portfolio's purpose and composition it does currently meet the investment objectives I had hoped for ... for somebody else it may be the opposite of course.
have a good weekend!
Hi all. Just been taking a look at STV (LON:STVG)
It's been looked at a fair bit in the past in the SCVR and the fly (or more like elephant given the size of it) in the ointment is always the pension scheme liability, and this is what has always put me off.
But... I got to thinking about the effect of the brave new world of inflation and high interest rates on all this. Clearly this is complex, and the scheme will be affected on both the assets and liabilities side by the current market conditions - given the way both bonds and equities have gone this year, it would be surprising if the investment assets value has not slipped accordingly. The interesting part though is the effect on the liabilities side of the equation given the unprecedented rapid change in the interest environment and, with it, bond rates, which impacts the discount rate applied by the pension scheme trustees. There is also an adjustment to be applied for the assumed rate of inflation (which will also have increased).
Anyway, after a bit of digging, the STV annual report helpfully provides sensitivity tables for what would happen for every 0.25% of change to the discount rate and the expected inflation rates. These rates were set at 1.9 and 3.55 respectively for STV at year end 2021 incidentally.
Accordingly to PWC figures (see link below), as at September 2022 UK companies had generally been adopting a discount rate around 3% higher than this for pension valuations, so there is a big change coming at year end. RPI inflation assumptions (STV does use RPI rather than CPI) meanwhile have only risen by about 0.5% to around 4% total. This surprised me - despite this being based on the long end of the yield curve I though the change might be more - again this is a positive given the big change in the discount rate would very much outweigh this.
Back to STVs sensitivity tables, this suggests pension scheme liabilities revalued at these rates would drop by more than 30% - i.e. 150m lower given STV liabilities of around 500m. This would wipe out entirely the pension deficit if there were no reduction in assets. Of course there will in reality have been some reduction in assets so there will still likely be a deficit, but the chances are that the assets will not have reduced by as much as the liabilities.
The short version of all this is that the pension scheme deficit could easily be a lot smaller for year end 2022.
One niggle I don't like is that they have assumed zero salary growth for pension valuation purposes (something they have always done) - not sure they will be able to justify retaining this approach now, which could sway the figures a little.
It is 2 more years until the triennial revaluation, so this won't immediately affect the payments they are making into the scheme of course (and who knows what the market rates will be in 2 years time), but it could potentially make the books look a lot better at year end 2022 this year and give a big boost to the balance sheet. If this is the main thing the market has been marking the price down for, then it could easily spur the price along.
All of this is a backstory to what is a strong underlying business with fantastic free cashflow and very little debt - plus a heap of other positives already noted by Paul and Jack over the past two years (see the discussions tab for past comments on this). It's also a Lord Lee favourite for those inclined to follow that sort of thing.
If the pension position is improving thanks to the economic landscape, this share (and others previously rejected on pension grounds) could be worth another look.
BIACS
https://www.pwc.co.uk/pensions...
I am also actively looking for "pension assets" hidden in companies. This is why I've taken a position in LPA (LON:LPA) in Oct. Scheme was already in surplus, and it looks like OKs like they "derisked" it in 2021, so hopefully no big equity losses. They've been meaning to sell it off for a while, so hoping any minute now for a huge cash windfall.
(I hold in the Boon fund)
Morning chaps, I received an interesting email from www.gmo.com last night. You need to sign up (no cost), some excellent research on their site. Anyway they have written a piece about attractive valuations in quality small cap US. Just another piece in the jigsaw as we get off the drugs of the last decade but encouraging.
I was tempted enough by the Meta capitulation to at least cantor through the stocko pages of extremely large US tech cos. In contrast to the above piece its hard to argue on price to revenue multiples these stocks are cheap. Meta still trades at 3x Sales, which is fine if margins hold but potentially why the stock reacted so badly...less fine if they drift back to 20s operating margins. The same can be said one way or another for the others. A feature of the last decade has been stubborn profit margins...but now we have "the inflation" and these large tech business are extremely operationally geared.
Why mention all that....well the market seemed in a rush to get out of these stocks this week , and there are better places for capital. Have a listen to Paul and Paul, even though its a bond discussion, it also makes you think about equities and where the money will flow. In some cases you might say I will take 7% for a couple of years in the corporate bond, in others you might say no, the growth in the equity will make way more money.
I took a look at base rates in the early 2000s... they were 4% and 5% during the tech crash....but spreads did little and moved around between 100 and 200bps. So nominal redemption yields were very similar. ie 7% for OK credits and higher where things are more stretched. Again you can ask what's my point? Well as money is recycled away from mega cap US stocks .... it has a variety of options... not least Treasuries yielding 4%..corporates 7%.... and therefore equities need to offer good value. Personally I don't feel like growth ever falls out of fashion, its just those stocks at the very top are forecast to deliver a linear growth profile that looks stretched. It also offers the prospect of index returns that are held back by the largest constituents disguising much more attractive opportunities underneath.
The search goes on. Good luck out there.
Are the big ad tech companies like Meta that operationally geared though?
On the surface yes - huge part of their costs are lumped into "fixed" -> which is headcount.
But at least in the USA, they can give 2 weeks notice, and little redundancy/severance. Granted, outside the USA in the UK and EU, it is a different story.
Plus they have so much "fixed costs" to trim -> free yoga classes. Free steak lunches. I am actually very sanguine that if they really wanted to, it would be easy for them to trim fixed costs, at least for the first 10-30% of fixed costs.
#AGY - This has got to be one of the best descriptions of a banking covenant breach ever by Allergy Therapeutics .
"At the expected reduced levels of underlying profit, excluding R&D costs, the terms of our NatWest revolving credit facility would not allow use of the facility."
That's not a covenant breach - that is a drawstop term / condition precedent. Not allowing an advance / further advances of a facility does not in and of itself constitute a breach. You could of course have a separate breach as a distinct term / separate item, but the above quote says nothing about that.