Small Cap Value Report (Fri 29 Dec 2023) - SND, SED, DUKE

Good morning from Paul.
Today's report is now finished.
Half-day today - market closes at 12:30. So if you're still staring at your watchlist at 13:00, amazed at how illiquid the market is, that's because it's shut! ;-) [we've all done it!]
It's the last SCVR of this calendar year! What a year it's been too, with greatly widened coverage of the market - at the latest count, Graham, me, and Roland covered 607 unique UK listed companies here. That's all in the archive now, for reference under the "Discussion" tab of each company on the StockReport.
It's been a pleasure, and sometimes a challenge, to produce all these reports. I have to say that working with both Graham and Roland is an absolute dream, I don't think we've ever had crossed words.
Graham's top 10 share ideas for 2023 delivered a fantastic return, make sure you check out his new article here, with an astonishing +25% profit for the year. Well done Graham!
** STOP PRESS! ** - Megan's just published this very interesting review of how the StockRanks performed this year. I think it nicely reinforces how the StockRanks are not infallible for individual stocks, but for a portfolio they skew the odds in our favour.
I must also mention the fantastic quality of reader comments this year, with some wonderful contributions from many subscribers, thank you to everyone who has contributed in a positive, courteous way.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
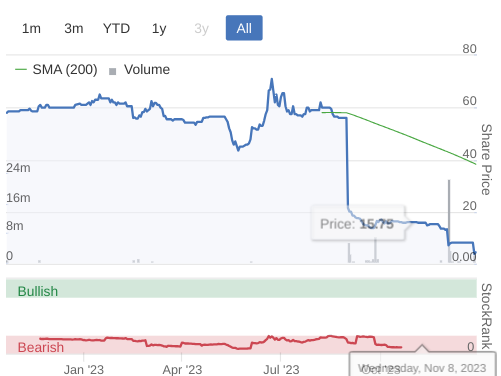
Sondrel (Holdings) (LON:SND)
Down 54% to 3.75p y’day (£3m) - Trading Update (profit warning) - Paul - BLACK (profit warning) & RED (fundamentals)
Sondrel (AIM: SND), the fabless semiconductor business providing turnkey services in the design and delivery of 'application specific integrated circuits' ("ASICs") and 'system on chips' ("SoCs") for leading global technology brands, provides the following trading update.
We’ve only covered this disastrous Oct 2022 IPO once, here on 31 Aug 2023. My summary comments form then were -
A hideous update from this chip designer, which has seen expected revenues all but dry up for H2, due to project delays. I think that leaves it in a precarious financial position, as there are some nasties on the balance sheet. The company reckons it has enough cash, but I disagree - expect a distressed placing at a discount. Looks like the fund managers were sold a pup, in this Oct 2022 IPO. [SCVR 31/8/2023, shares 21p]
Yesterday’s update was worse still. Actually, this is one of the worst trading updates I’ve ever seen, because it basically tells us the company is insolvent - unable to pay its liabilities as they fall due is surely wrongful trading under UK insolvency law?
The issue is that project delay/problems means £1.7m of expected milestone payments have not been received from a customer. This has left SND with inadequate funds to meet its Dec payroll! Management and most staff have agreed to deferral of salaries until the milestone payments are (hoped to be) received in Jan - Feb 2024. Although it says additional costs will be incurred to solve the project issues.
Funding - it says additional funds will be required before end March 2024, or earlier if the delayed milestone payments have not been received. So brace for probable substantial dilution in an emergency fundraise.
Paul’s opinion - I’m glad we steered clear of this one when it warned back in Aug 2023, and the company’s assurances that it had enough cash did indeed prove incorrect, as I indicated was likely at the time.
Although the market cap of only £3m is well below our usual £10m cut-off, I’m intrigued to see how this one will pan out. It’s either going into administration, or major shareholders might prop it up with an emergency placing. Note the CEO owns 45%. Small shareholders are now completely at the mercy of what big shareholders decide to do.
Super high-risk now, and insolvency could come any day, if the lawyers tell them they’re trading whilst insolvent (which triggers senior management becoming potentially personally liable for the company’s debts).
I wish shareholders well, but with c.95% of the original share price already gone, I suppose most people will have mentally written it off by now. Hopefully people will avoid the temptation to throw good money after bad - averaging down on an investment that has gone completely fundamentally wrong, is best avoided in my experience.
Delisting risk must be high, with a 45% founder CEO, and not enough cash to make payroll. So listing costs would be the obvious thing to slash next.
Any upside? I could imagine shares bouncing, if the company announces it has received delayed milestone cash from customers. But ask yourself if it's worth risking a 100% loss, for that uncertain upside?
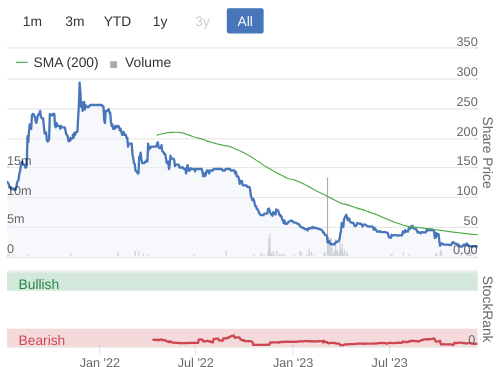
Saietta (LON:SED)
Down 3% to 17.5p (£25m) - Interim Results - Paul - RED
Saietta Group Plc (AIM: SED), the multi-national business which designs, engineers and manufactures complete eDrive systems for electric vehicles, today announces its unaudited interim results, covering the six-month period ended 30 September 2023 (the "Period").
We’ve covered this share negatively (RED) 4 times this year, most recently on 20 Oct 2023, where I summarised it like this -
Saietta - down 29% to 27p (£28m) - unsuspended now late FY 3/2023 accounts published. Cash burn so bad, I reckon it's out of cash again. Could be a zero. Just awful.
We don’t need to spend much time on this. The interim numbers are terrible, with tiny revenues, and a £7.9m loss in H1. It had run out of cash by the period end.
However, it raised £7.1m in a Dec 2023 fundraise, which it says will only be enough until March 2024, due to the continuing very heavy cash burn. So expect another fundraise, and more dilution in early 2024. Let’s hope shareholders are feeling flush, and still believe the story.
Going concern statement includes a material uncertainty line, but I challenge whether this statement here below is true, as it doesn’t align with the facts. Actually, this bit below is obviously untrue, since the company only has enough cash to last until Mar 2024 -
The condensed interim set of financial statements included in this half-yearly financial report have been prepared on a going concern basis as the directors consider that the Group has adequate resources to continue operating for the foreseeable future.
Paul’s opinion - I remain extremely negative, because the company is a big cash-burner, but seems to limp along from one fundraise to the next, with no discernible commercial progress apparent in the figures yet, other than talk about orders, etc.
Small shareholders are very vulnerable here, to further ramping from paid-for commentators, sucking in the unwary before yet another discounted placing.
I have no idea whether the product is any good or not. That’s largely irrelevant to me, since the company’s finances currently make it uninvestable.
Duke Royalty (LON:DUKE)
Up 2% to 33.25p (£140m) - Trading Update & Investment - Paul - GREEN
Graham normally covers this share, and he’s been consistently positive, green, on it for a while. Several shrewdies have flagged this share to me too, so I’m pleased to have the opportunity to take a quick look today.
Duke Royalty, a provider of alternative capital solutions to a diversified range of profitable and long-established businesses in Europe and North America, is pleased to provide guidance on its trading for its third financial quarter ending 31 December 2023 ("Q3 FY24") and to announce a follow-on investment of CA$8.6 million (approximately £5.1 million) into its existing royalty partner Creō-Tech Industrial Group Inc. ("Creō-Tech").
Trading update sounds positive -
"We are pleased to report that despite the ongoing macroeconomic uncertainties, we continue to deliver revenue growth, with Q3 FY24 on course to maintain this upward trend, underpinning our stable dividend which at the current share price, represents an approximate 9% yield.
"We believe the Company's rebrand, alongside our expanded investment team, will position Duke to take advantage of the abundance of new opportunities in the Private Credit market, which has become increasingly mainstream in the SME lending space."
A dividend yield of c.9% has certainly caught my eye.
Also the growing quarterly recurring revenues of £6.2m look good.
The StockReport shows shares trading below NTAV, at 0.84x
Paul’s opinion - it’s dawned on me that this is a more complicated situation than I realised, and I’ve run out of time as family have just popped in for a late breakfast. So I’ll have to park this one until 2024.
It’s essentially an investment company, that has invested money in other companies in order to generate recurring royalty income. This is mainly financed by equity, but also some debt.
At first glance, it looks quite interesting, so would be worth readers taking a closer look I think. Since Graham knows it much better than me, and is green, I'm happy to maintain that view myself.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Maybe Sondrel (Holdings) (LON:SND) isn't totally dead after all.
Apparently this UK nano-metre ASIC chip designer played a key role in assisting Lon Musk's California-based Neuralink project to implant a chip inside a patient's brain for the 1st time on Sunday.
https://www.dailymail.co.uk/ne...
It's quite interesting to see the overall performance of people's investing . Mine as been a bit of a rollercoaster . I decided to start investing in 2019 after 4 years I am 29% up not great by some peoples achievements but I am only a amateur investor and if it wasn't for the last few months it would be nearer 0% . Things change quickly when invested with fewer stocks especially small caps . If I learned to sell at the top instead of holding on to some investments I would do better . Good luck for 2024 everyone . Happy New year
Finished 18% up in 23, happy with that result.
What I’ve learnt
What I need to do better
Good luck to all in 2024
My portfolio update for the year:
I made a 9% profit on my portfolio of roughly 40% individual shares, 45% investment trusts and 15% bonds.
For comparison: that's 2% better than FTSE Total Return and 2.5% worse than Vanguard 80:20. So a very average year but much better than last year.
Container shipping costs up again
Freight prices rose 80% in the past week, having already gone up nearly 50% the week before.
Thanks Paul, Graham and Roland for all the insights and top quality coverage in 2023. Look forward to following along in 2024.
Duke Royalty (LON:DUKE) Is an interesting investment vehicle (I hold) . The yield of 9% plus growing revenue- up 12% YoY makes this look pretty solid for income seekers with capital growth as interest rates fall.
Anyone got an insight on Somero Enterprises (LON:SOM) (I hold). Going straight up in recent days (up 33% from the double bottom). Is it just the realisation it’s been oversold or something else? Either way I’m not selling.
Anyone got an insight on Somero Enterprises (LON:SOM) (I hold). Going straight up in recent days
It’s basically catching up with what all construction related stocks have been doing of late, thanks to the potential for interest rates to fall which is already anticipated in falling bond yields
I looked around extensively for any concrete news on this (excuse the pun) and found nothing . The trade sizes seem highly variable and the volume low, so it doesn't look like a big stake being built by an institution. I think anyone who has held this long was in the "I'm not selling" camp and there simply aren't enough sellers to match the buyers. Once a bit of momentum started that has just exemplified. I wouldn't be surprised to see this jump higher in the new year if interest is maintained and volumes increase a bit more.
Sharepad showing divi forcast reduced by 24% to 27c - that puts it on a divi of around 5.6% at current price - not sure SP will go much higher until divi is returned to the higher levels previously seen.
Hi all,
Thankfully I am in positive territory after a good run from October onwards. I don’t often post, but remember not so long ago posting how it was all getting me down. After some thoughtful comments and advice from the SCVR family I have remained positive, and things can quickly turn around. Thank you to everyone on that day, it was much appreciated.
Highlight of the year for me Warpaint London (LON:W7L)
Lowlight of the year iEnergizer (LON:IBPO^E23)
Good luck for 2024 all !
I remember lefty, I'm glad things turned around for you.
There's no harm in reorganising portfolios a little now if anyone was feeling stressed a couple of months ago. Much better to do it when sentiment is high.
Market closing in less than half and hour so will keep this brief. I know there is not much interest in biotech in discussions and apologies if I have missed it before, but for those interested, PureTech Health looks worth a look despite the recent rise. Compare the cash it is likely to get from the BMS deal plus its stake in Karuna Therapeutics with its market cap.
Re Puretech Health (LON:PRTC) the cash they will get from BMS is in return for their stake in Karuna is it not? I’m wondering whether they will have any ongoing financial relationship with Karuna after the bid. Moreover last year they had written a call on their holding and I’m concerned they may have done so again thereby limiting their full upside of the bid. I imagine the co will have to make a pretty full RNS early in 2024. But they have some good pipeline products and an excellent history of founded company success.
Oversolds / Out of favour
Wynnstay and Hargreaves services
Both very solid “Benjamin Graham” type stocks are languishing pretty out of favour.
Not sure what might make these change direction but on 3 year timescale look pretty bulletproof
Think I’ll take a review over the weekend if they take a leg downwards will look too cheap
I sold a chunk of Hargreaves right at the top of recent spike of 480 so might go back in if it drops to 370 level which is too low
Oversolds / Out of favour
Wynnstay
I bought a half position this morning. Could go lower but I’m buying at a big discount to NAV when it has traded at 1.5x in better years. I find the ERP on this attractive at these levels for a (hopefully) reliable asset yielding almost 5% against gilts at 3.6% GRY today. Will top up within the coming months in the expectation that I’ll get a better price in the new year.
Loving the daily reports here, thank you guys. I use them a lot to research Companies updates
Heres my list for 2024 - I aim to get companies with a Divi over 4% and a low PE of under 15 - looking forward to the dividends (and growth hopefully). On Twit, err X, I'm @UK_Investor71 if interested, DMs are open
Good luck, health and wealth for 2024 to you all
Not a full list, but I thought it would be good to share this list of takeovers published by Peel Hunt at the end of October. Since then, other bids include Smart Metering Systems (LON:SMS) which I held
https://www.peelhunt.com/news-...
Congratulations to all those who were holders of any bid stocks.
Thanks to Paul, Graham and Rowland for their analysis, and the posts from others which has helped me find (and have the patience to hold on to) winners and also to avoid some stocks.
After the horrors of 2022, and a rollercoaster 2023 I will be happy with my 15% return for the year.
Wishing everyone a prosperous 2024
If anyone is interested in Investments Trusts there are a few new threads on this IT discussion blog https://www.stockopedia.com/co...
I have just rejoined Stockopedia because the daily SCVR is so useful. So thanks Paul, Graham and Roland and the rest of the staff for all your work over the year and I hope we can look forward to an interesting 2024
Great news! Welcome back martin576 :-)
Interesting pickup in volume this month at Nexteq (LON:NXQ) 5x normal volume today. Theres been a large seller for some time here, but first time in 9 months price is now above the trend line. Trading update Jan. If 2024 outlook is better then could be due a decent run. Market seems to be pricing in a big slowdown.
I already highlighted the attractive metrics on here a few days ago when. Nexteq (LON:NXQ) . Have taken an initial position.
Nexteq (LON:NXQ) haven’t been following this so am surprised the share price has dropped into such deep value territory. And I agree with you the chart looks like it could be turning. Thanks for posting Wolf, will look into numbers this weekend, this could be my first trade of 2024 ;)
Sosandar (LON:SOS)
Jigsaw sales and profits surge as it hits expansion trail - Retail Gazette
A piece from this morning's Retail Gazette, I imagine Jigsaw is one of the competitors that Sosandar refer to in their results presentation re the comparison to similar brands with their own bricks and mortar outlets. The piece refers to Jigsaw's sales increasing by 19% mainly due to it's tie up with Next. On the face of it this would ask a few questions about Sosandar's rather pedestrian sales performance.
My end of year report.
Following a disastrous 2022, this year seemed just as difficult but pleasantly surprised to report up 17.32%, for comparison the work pension (Scottish Widows) only up 11.08%
Largest Winner Sureserve 49%
Largest looser Argentex (LON:AGFX) -32% now firmly in the -20% and your history club.
Best wishes for 2024 everyone and thanks to Paul, Graham and Roland for keeping us entertained.
Transense Technologies
Sone unusually chunky buys and sells going through in the past few days expect to see a few RNS in next day or so .
Some heavy selling with a very large amount of stock available at circa 103 level for past 2 days.
I’m pretty sure this is long term shareholder Seneca unwinding their position, they are to my knowledge very early investors often pre flotation .
I took advantage of the unusual increase in liquidity and took it to a full position which would normally clear most of the stock causing a spike but didn’t happen so that means it’s a major seller exiting .
Probably went a touch too high for where I should have gone to so actually sold a few today as it wasn’t sitting right and was feeling had jumped in to a full holding a bit too head first .
Big buyer now buying in 75k chunks (approx 0.5% of the company each time) which I suspect is Dowgate increasing further, two chunks gone through this morning
Given free float won’t be that high looks like a major swap out of Seneca for Dowgate that’s my guess though Harwood also on the register but don’t think they are active currently .
RNS should reveal all .
This is pretty under the radar stock but too small for many .
Hi Paul,
as it is a quiet Friday excuse the incredibly off-topic comment, but you may be interested in the new Rolling Stone podcast with Chaka Khan?
Thanks to all the staff and posters this past year. I don't post that often but I read every day and find the level of knowledge helpful and inspiring.
Good luck for next year everyone, may all your picks be winners.
I may post a year-end summary for myself at some point when I crunch the numbers.
Cheers!
Many thanks for your contributions this year Paul & Graham (and the rest of the Stockopedia staff). It's been a pleasure as always to be a subscriber. On a personal note I have been extremely busy at work this year so I have had less time to do my own reading and researching my own ideas, so I have relied on the SCVR even more for inspiration and notes on what's going on in the market. I have also enjoyed your podcast Paul - mainly for your macro thoughts; I listen to it in the gym or out running.
As per your invitation, I thought I'd share my year in review. I run my year until Christmas Eve so no-one should accuse me of posting this a few hours too early!
This year I made 8.5%. I've now been properly investing for 10 years and my CAGR is 10.12%.
My performance:
2023: 8.5%
2022: -14%
2021: 28.8%
2020: 24.6%
2019: 19.1%
2018: -8.8%
2017: 18.4%
2016: 4.8%
2015: 4.2%
2014: 25.2%
I won't bore you with how my individual shares performed although to note I benefited strongly during the Santa Rally from my 'geared plays' on lowering interest rates and improving market conditions - notably Cavendish Financial (LON:CAV) & Tritax EuroBox (LON:EBOX) which are two of my largest holdings. I also avoided heavy losses this year on anything which is always a big help. My worst performer by far was Argentex (LON:AGFX) which I lost 38% on but in previous years I've sometimes lost 50%+ on some holdings.
I've copied below my own notes on what went well/not so well and my thoughts on 2024 in case of interest!
What worked well
Other positive lessons from previous years to remember
What worked less well / lessons learnt
My approach for 2024:
My current holdings are: Begbies Traynor (LON:BEG) City of London Investment (LON:CLIG) Tritax EuroBox (LON:EBOX) Cavendish Financial (LON:CAV) Jet2 (LON:JET2) Jupiter Fund Management (LON:JUP) On Beach group (LON:OTB) PayPoint (LON:PAY) Polar Capital Holdings (LON:POLR) Redde Northgate (LON:REDD) Renold (LON:RNO) Sanderson Design (LON:SDG) Volex (LON:VLX) WisdomTree UK Equity Income UCITS ETF (LON:WUKD)
The general approach I will carry on with:
Hope this is vaguely of interest! Best of luck in 2024 everyone!
I am on Twitter/X if you'd like to follow: @InvestTortoise
Valuable sentiments, Tortoise. "(When I've bought into good results or off the back of newspaper takeover speculation on shares I don't understand very well this has generally gone badly for me) especially - speaking for myself this goes for 90% of any speculation I read, mostly because the eagle has already landed. Have a great new years investing.
Silver
Saietta
This made me chuckle
“Small shareholders are very vulnerable here, to further ramping from paid-for commentators, sucking in the unwary before yet another discounted placing.”
Wonder who the “paid for” commentators are?
Saietta (LON:SED) I notice PH has just posted a long piece on Linkedin. I won't copy it here. (I don't hold)
And now the inevitable piece on Vox. This entitled "Saietta set for growth after transformational 1H23" Oh dear.
On a positive note though it serves to remind me how lucky it is that we have the likes of Graham, Roland and Paul S upon whose sage advice and integrity we can rely. Thanks guys you are stars.
BenHazz - A year in review:
Years investing: 2 / Age: 35
Portfolio performance 2023: +5.3% YTD (+2.1% in 2022)
Most successful 2023 share: Crowdstrike Holdings (NSQ:CRWD): +149%
Least successful 2023 share: Watkin Jones (LON:WJG) : -53% (at point of sale)
After just breaking even in 2022 I am pleased to have seen another positive year in 2023, albeit since I started investing I have failed to match inflation and would have done just as well sticking it all in the bank with a decent rate. Working full time with a wife and young son I try to balance my time and spend an hour or two most days reading and learning about investing, it has become a hobby I have enjoyed greatly over the past couple of years. Before investing in my first company, it is safe to say I had zero knowledge of investing, I actually signed up to Stockopedia a few days before buying my first share - I must have recognised I was going to need a lot of help! Much of my new knowledge has come from the experts who share their views on the SCVR, primarily Paul and the other writers, as well as podcasts, articles, books and the IC. I know my limitations, I am still not cut out for balance sheet analysis just yet, so am content to rely on the expertise of others until that time comes.
Over the past couple of years, it has been a wild ride with some crazy ups and downs, a baptism of fire jumping headfirst into a drawn-out bear market. A “proper education” as my dad would say. It has been an ongoing learning experience, one that is worth far more to me than the 5.3% annual return I have to show for my time and effort. The most important lesson I have learned is that you have to be humble and accept when you are wrong. Doubling down on Watkin Jones (LON:WJG) was naïve but I learned from it. Trying, unsuccessfully, to use AI to predict trends in footfall and busyness earlier in the year was ambitious and also a little naïve, but I learned from it. With the latter, I am glad I tried a novel approach and do not view it as a failure.
Only 2 months ago I was sitting on significant losses, wondering if I was cursed when it came to profit warnings, frustrated by the slow decay of my portfolio. Takeovers seemed like a weekly occurrence for some (I’m talking to you BnB!) but they would not grace my portfolio, selling out of SCS (LON:SCS) a few weeks before their takeover was a bitter pill. I would be lying if at times I wondered if I had made a poor choice to choose investing, and contemplated how many more losses I could stomach. The message from the community was clear – hold your nerve, stay invested, and the good times will return and when they do, it will happen quickly. Thank you. A 26% portfolio gain from those October lows has been quite the turnaround, a much-needed one at that!
After two tough years, I hope that 2024 is when I get to experience one of these bull markets that everyone speaks so fondly of! I remain fully invested and quietly confident of a strong year. My picks for a strong rebound in the next few months are Card Factory (LON:CARD) and ME International (LON:MEGP). By this time next year, I have a lot of confidence in the recovery at Saga (LON:SAGA) and see JD Sports Fashion (LON:JD.) performing well, I also believe Seplat Energy (LON:SEPL) could rerate significantly. As a wildcard keep an eye out for Crispr Therapeutics AG (NMQ:CRSP) over in the US, their (now FDA approved) technology could open the door for cures to several diseases that have previously required lifelong management. If they have the same success with heart disease and cancers as they have just had with Sickle cell disease the sky is the limit. Vertex Pharmaceuticals (NSQ:VRTX) could snap them up for a big premium.
Shoutout of the year goes to Boon for putting On Beach group (LON:OTB) on my radar early doors where I accumulated a big position size, leading to me making me some significant gains. I'd love to thank you all, but particular recognition to Wolf, BnB, Rusty, PlanetX, Mojo, Camtab, MichaelTaylor, Rmillaree, DavidJHill, Jonno, RDHowarth, Paul Hill and of course MrContrarian for regularly sharing your insight. Many happy portfolio returns to everyone on the thread and best of luck in 2024.
BenHazz
Nice post BenHazz and good luck for the year ahead.
Hello BennHazz thank you for your candid year in review. I am over 20 years older than you but only have three years experience in buying individual shares. The last couple of years have definitely been tough to have been starting out in investing but also an educational one. I remember hearing Morgan Housel saying something like that it's probably better starting out in a bear rather than a bull market because of the greater danger of the risk of the false optimism for when the market turns. This however only works if you don't get too demoralised in the initial bear market. If you can manage the level of losses or eke out a small return which you have that should stand you well for when the market does pick up. In my case I have the advantage of previously investing in tracker funds in my pension which I use in a variant of an all weather portfolio. This provides a very effective buffer that allows me (as in for my risk appetite) to take on more risk, in my late 50s, in my small to mid caps shares that I hold inside an ISA. I obtained a return of just over 10% in 2023 with returns from Marks and Spencer (LON:MKS), Warpaint London (LON:W7L), Baltic Classifieds (LON:BCG) , SCS (LON:SCS), and Recursion Pharmaceuticals (NSQ:RXRX) (a rare exursion for me into the US) making up for several disasters including Synthomer (LON:SYNT) . I am broadly positive for 2024 but do still think that there is a lot of post-pandemic and geopolitical uncertainties, with the risk of another uptick in inflation that could mean that we continue to bump around the range of valuations we have seen in 2023. Of course that is just my view and something else may happen in the economy and or the market. Importantly however, as Paul, Graham and others on these pages have demonstrated even in these uncertain times it is still very possible to obtain impressive returns.from many of the businesses discussed in the SCVR. Best of success to you and all in 2024.
I think this is a decent two year performance given how awful 2022 was for UK small caps investors - well done.
Good luck with the pharmaceutical investment(s). Despite having a lot of career knowledge of the sector I find it extremely difficult to unpick different companies' prospects so I have that whole sector in the 'too difficult' category.
I was invested in Saga (LON:SAGA) but sold as its insurance arm seems to be struggling to maintain margins with the new 'loyalty penalty' rules and 'consumer duty' from the FCA so I worry that even if cruises bounce back (why has that not happened already?) then it will get nowhere near previous levels of profitability. The current p/e of 7 therefore looks about right to me given the debt profile.
Congratulations, BenHazz, on a positive return 2 years running in the bear market we have just experienced. There will be few who will have done the same. To have achieved that means that you are surely very well set up to succeed in investing with many decades left to grow your pot.
Nicely written.Lovely read as a newbie too i have appreciated all the unbiased teachings and real life experience from Paul, Graham, Roland and all the Stocko team and ofcourse all the knowledgable commentary posters in the cheap seats!I've learnt a lot already.And thanks to the Boon Fund for putting me onto On Beach group (LON:OTB) too at the low £1 level.
P.P.S. There certainly has been a fair whack of M&A going on in the big pharma world of smal/midcap US listed pharma lately with a lot of patent cliffs approaching for big pharma incluidng Bristol-Myers Squibb Co (NYQ:CELG RT) recent purchase of Karuna Therapeutics (NMQ:KRTX) for $14 billion, which was originally developed by UK listed Puretech Health (LON:PRTC) .
There was an article in Investor's Chronicle on the upcoming big pharma patent cliff in the last year.I wish i had bought Vertex Pharmaceuticals (NSQ:VRTX) years ago, but i had only really heard of Pfizer (NSI:PFIZER).
Thanks for your work this year guys. I've come back to Stockopedia after a couple of years with a competitor and feel that the content here is better suited to what I need: you can sometimes have too much information and not enough insight!
Oakley Capital Investments (LON:OCI) have announced today that one of their funds has been wound up and they will end up holding 38% of Time Out (LON:TMO) . Since you last looked at TMO in 2022, the business seems to have turned a corner. If you fancied casting your eyes over it again that would be much appreciated. The model of open air "best of the city" markets seems a good one, just a question of whether it can be rolled out profitably and whether it is too capital intensive to ever really make sense. It doesn't feel like a business that fits OCI's core approach, so I suspect will be on the market. At what price, though?
Welcome back Donald. What is the position re Phoenix Copper please ? Presume OK to hold on and hope for better news next year .
I'm limited in what I can say, but yes, the overall message is very positive for 24. The company needs to finalise financing but is confident that will be done very shortly, on the basis of copper bonds (rather than equity) and when it is, that will be transformative. But of course, as Paul and Graham would emphasise, there are never any guarantees when it comes to funding.
This being a very quiet week for announcements, with none for my own holdings, I started looking at others and couldn't believe this one yesterday from Symphony Environmental Technologies (LON:SYM)
https://www.investegate.co.uk/...
Basically the entire board has options due to expire on Sunday and these have been extended to 31/12/24 for "practical" reasons, whatever they may be. The number of options are:
750,000 Nicholas Clavel, Non-Executive Director and Chairman
2,201,500 Michael Laurier, Chief Executive Officer
3,280,000 Ian Bristow, Chief Financial Officer
2,210,000 Michael Stephen, Executive Director and Deputy Chairman
They then state: "The exercise prices of the Options are 4.5 pence and 12.5 pence, so all the Options are below the prevailing price of the Company's ordinary shares".
According to Stocko the share price yesterday was 3.75p. I take that to mean that the options are ABOVE the sp and therefore worthless. Does that mean that they want to hang on to them in the hope the sp recovers?
Never mind - Nomad Zeus thinks this is " fair and reasonable insofar as the Company's shareholders are concerned". Humph.
Well done Paul, amazing work this year covering so many companies. You deserve a New Years drink or two.
Saietta (LON:SED) going concern statement sums up the difficulties -
"On 15th December 2023 the Group announced a fund raise of £7.14m before expenses. At that time, the Group indicated that the fund raise would meet the Group's working capital needs up to the end of March 2024. Thereafter additional funding would thus be required. Whilst the Directors expect that such additional funding can be raised this is not guaranteed and when continuing with an accelerated expansion this presents a material uncertainty which may cast significant doubt over the Group's and the Company's ability to continue as a going concern"
My daughter thought my attempt at a Christmas cracker joke yesterday was pathetic, she ordered me to tell her favourite current joke instead.
Why do ducks have feathers?........to cover their butt quack!
I've put together a little stock picking competition if anyone is interested?
There's a short / long competition and best username
All just for fun (no prizes and I have nothing to sell you)
https://www.multibaggers.co.uk
Thanks A-S. I tried to make 5 share picks, but the 2 smallest tickers were rejected (c. £20m market caps in both cases). Is there a minimum mkt cap rule?
Hi Paul,
The list of stocks that are eligible is here:
https://www.multibaggers.co.uk...
It's cut off at about 20M mkt cap.
Thanks for taking a look!
Thanks for this,
unfortunately it would not accept 4 of my 5 picks. Which is almost half my portfolio. I'd end up submitting the ones I think are least likely to multi-bag. All below £25m marketcap.
cheers
Mark
Similarly I just tried one with market cap of about £35m (but advfn out of date still says £21m) that didn't work. Only want to pick one or two also
Hi illiswilgig
The stocks do need to be on the list of over 1100.
The cut off is approx >£20M mkt cap.
Thanks for having a look!
Morning Paul. I’m glad you’re highlighting Sondrel (Holdings) (LON:SND) because the rns late yesterday was a shocker. I’d be amazed if the board isn’t kicked out en masse except I believe they do have significant holdings.
many thanks for all your hard work this year together with Graham and Roland.
Happy and prosperous new year to all.