Small Cap Value Report (Fri 29 May 2020) - Riots, JDG, JSG, VLE, SHI

Good morning!
Today we have:
- Judges Scientific (LON:JDG)
- Johnson Service (LON:JSG)
- Volvere (LON:VLE)
- SIG (LON:SHI)
Finished at 2.40pm.
Short political comment - I'm slightly alarmed by overnight news from America about riots and looting.
Everything in America tends to be bigger and louder, and that goes for civil unrest, too.
Check out this tweet from the verified Twitter account of the City of Minneapolis:
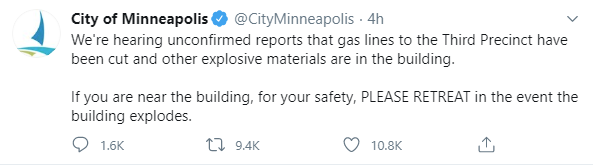
That police building has been abandoned by the authorities and set on fire by the protestors.
I've seen videos of protestors climbing on top of moving vehicles and emptying large department stores. There is unrest in Minneapolis, Denver and LA.
But I don't want to overstate the importance of these events.
I was living in London during the riots of 2011, and remember thinking how strange they were - but they ended soon enough, and weren't talked about much afterwards.
It's no coincidence that they happened in August - rioting is much less fun in the cold and rain.
The relevance to investors is that we are about to have a very noisy election season in the US, and I'd expect tensions to be high for the next few months. We can look forward to thousands of headlines about the Trump/Biden contest.
Most of these stories can be safely ignored by investors, but I wouldn't want to ignore them completely.
The extremely divided country is still a great place to invest, but politics will be an important theme this year. For example, President Trump has just signed an executive order to make it easier to sue social networks.
The monopolistic power of Big Tech (especially Twitter and Facebook, but others too) could be vulnerable.
I own shares in Alphabet and through Berkshire Hathaway, I also own Amazon and Apple.
Since the outcome of this year's election will play a big role in determining US tax policy, competition policy, trade policy, and (increasingly) monetary policy for the next four years, I think it's compulsory to keep half on eye on it.
Judges Scientific (LON:JDG)
- Share price: 4970p (+1.5%)
- No. of shares: 6.3 million
- Market cap: £310 million
Acquisition of Health Scientific Company Limited
Volvere is on my mind today - it's my top holding by a mile, and it has released final results.
But it's a very small company, and very illiquid. Something like Judges is more appropriate for a much larger group of investors.
I covered Judges during the height of the Covid-19 stock market crash, and described it as being "on sale" at the time. Its share price that day was £32.25p.
It's up over 50% since then - and I'm sure many of you will have participated in that rally.
It is no longer "on sale", at a P/E multiple in excess of 30x.
The reason for its high valuation is that it tends to earn very high returns on its investments (in scientific instrumentation businesses).
Today's acquisition appears in line with that track record.
Judges has bought "Heath Scientific Company Limited" which owns Thermal Hazard Technology Limited.
This company: "specialises in the design, manufacture and sale of instruments used to measure the thermal properties of lithium batteries and other reactive materials. Its main product, the Accelerating Rate Calorimeter, is a key tool to improve and verify the safety of lithium batteries and of other chemical reactions."
Sounds good - should be a growth area.
- £5.3 million purchase price, plus another £2 million in earn-outs.
- Heath earned PBT of £0.7 million in FY April 2019 (on revenues of £4.4 million)
- adjusted for non-recurring costs and for costs that will be eliminated by Judges, operating profit would have been almost £0.9 million.
- Net tangible assets of £1.9 million and cash of £0.8 million.
All of these numbers are more than a year old - I wonder if there was an improvement in FY 2020?
Based on the 2019 numbers, Judges is paying an enterprise value of £4.5 million (excluding the earn-out). So that's only 5 times operating profit.
Other key points:
Synergy - Judges expects a "constructive interaction" between Heath and its first investment, Fire Testing Technology. Both companies make "calorimeters", and use similar underlying science.
Retirement - I think this is a common feature of the Judges strategy. It enables founders of small scientific businesses to retire. Heath's MD, a co-founder of the business, will retire. He will be replaced on Heath's Board by his son.
Self-funded earn-out - Judges will have to pay £2 million to the sellers, if Heath earns adjusted EBIT of £1.2 million in FY April 2020 or in calendar year 2020.
But if Heath does that, and its profits convert to cash, then it will probably have around £2 million on its own balance sheet anyway. So it will be able to fund the earn-out itself.
Debt with (hopefully) rapid payback - Judges tends to borrow to fund its acquisitions, and pay back those loans quickly. This is the process by which it produces incredible value for its own equity holders.
If it had simply raised equity to fund every deal, then it would not have been the stunning success for its shareholders that it is.
The latest deal is being funded by a facility from Lloyds Bank. Hopefully it will not take too long to pay it back.
My view
It should be clear that I am positive on this news.
As stated before, the main question mark for shareholders at this point is whether the strategy can be scaled up to manage a much larger and wealthier group.
It's not a bad position to be in. Judges has been so successful that it is now arguably too wealthy to be able to deploy all of its cash flows using the original strategy. The special dividend paid last year was highly noteworthy in this regard.
Ultimately, my view on this is that I would back management, even if they have arguably more funds than they need.
I would much rather back management who have proven they are capable of allocating small amounts of capital extremely well, instead of backing management who lack any convincing track record at all (which let's be honest, is probably most management teams).
If David Cicurel finds that there aren't enough good deals coming his way, I expect him to propose even more of those juicy special dividends for Judges shareholders. That wouldn't be a terrible outcome, would it?
Johnson Service (LON:JSG)
- Share price: 124.12p (-13%)
- No. of shares: 370 million
- Market cap: £459 million
Proposed Placing to raise approximately £85 million
It has been a long three months since I mentioned this company's final results.
As a provider of table linen and napkins to the hotel, catering and hospitality industry, it is not ideally placed to weather these conditions.
As of early March, it said it had not seen any impact on trading. Then of course, the lockdowns began. On March 20th, it unsurprisingly announced that a slowdown had been seen.
Net debt was c. £88 million at year-end.
Placing - it wants to issue 74 million new shares at 115p each.
That's a fairly aggressive discount to last night's 143p close, though it's less aggressive if you look at the average price over the last two weeks (which is the perspective the company takes).
Raising £85 million would effectively wipe out the debt that it started the year with.
Trading update - "significant disruption".
In the Workwear division (garment rental, protective wear and laundry), revenues were slightly down year-on-year in Q1 and down 12% in April. Some indications of customers reopening in May.
As for the Hotel/Restaurant/Catering division, it has basically shut down. March revenues were down 27% and April down 97% (no surprise that economic data points to this being an awful depression, possibly the worst one ever).
May numbers are only "slightly ahead" of April's, meaning that they are still close to zero.
Management actions - huge cost cuts, no dividend, staff furloughed, tax payments deferred, etc.
Net debt - reduced to £85 million by the end of April, thanks to cash conservation measures. The total size of the bank facility is now £175 million, so there should be some headroom.
Covenants are relaxed until the end of next year.
Government Loan - JSG is eligible for £150 million under the Covid facilities.
Scenario Planning - JSG has modelled various scenarios, and thinks that peak net debt will occur in April 2021, at £110 million.
But in bear case scenarios, e.g. a slow recovery in hospitality and catering only starting in September, net debt would peak at £142 million.
In these scenarios, JSG would be forced to reduce stocks and cut its PPE spending even further, and would be reliant on the government's furlough scheme for longer.
Net debt of £140 million+ would clearly be uncomfortable if the bank facility is only for £175 million. The Government's Covid facility would be required to save the day.
My view
I think this Placing is a good idea for the company. Not doing it would risk leaving it in a very uncomfortable position over the summer/Autumn.
However, taking a longer view of JSG's progress, I must say that I think the overall cash flow picture leaves a lot to be desired.
Since 2008 (which was another year when it raised lots of equity), it has paid out c. £60 million in dividends, by my calculations.
Isn't it interesting that today's proposed equity raise is big enough to reverse all of those dividends?
The ROCE/ROE numbers here aren't bad, and those who invested in the depths of the 2007-2008 financial crisis have done very well, but the overall quality of the business is still somewhat questionable for me.
Volvere (LON:VLE)
- Share price: £14.50 (+5.5%)
- No. of shares: 1.8 million
- Market cap: £25 million
Please note that I have a long position in VLE.
As you may already know, I have an overly large position in this - 25% of my portfolio. Not exactly in tune with standard portfolio construction practices.
When I originally bought in, it was for less than 10%. But the price has nearly trebled, so here was are.
It's a turnaround investment vehicle, typically buying businesses out of administration. It then reinvigorates them, gives management a decent stake, and helps them to grow, before selling them on.
Results - for those who closely follow the company, I don't think these results contain much that is new.
The main points are:
- NAV per share now £13.85
- Net assets £25.4 million (excluding non-controlling interests), of which £19 million is cash.
- The only operating subsidiary which was left at the end of year, Shire Foods, grew revenue by 25% and PBT (before Volvere's charges) almost doubles to £1.4 million.
Volvere owns 80% of Shire (the rest of it was awarded to management), so its adjusted pre-tax profit that is attributable to Volvere is £1.1 million.
One of the key features of the Volvere strategy is incentivising management at subsidiaries, and I note that Shire paid a £500k dividend. Shire management will have received £100k of this.
Success in 2019 is explained as follows:
I am pleased with the growth achieved in 2019, which came principally from a deepening of relationships with existing customers, resulting in wider distribution and broader product ranges. Particularly encouraging was the growth in vegan product lines, where we believe we have developed flavours and textures that appeal to a wide consumer audience
Covid-19 impact - "too early to say" whether the sales uplift to supermarkets will be sustained and result in full-year growth.
Foodservice customers have been hammered, and they represented 12.5% of Shire's 2019 sales. Volvere expects them to return to normal when trading restrictions are ended.
Production and costs are affected by social distancing measures - "we are still achieving an encouraging level of output and, for the most part, meeting customer demand".
Indulgence Patisserie - a small acquisition made earlier this year. It is making progress, with more to do:
"...we have been working to improve customer and supplier relationships, increasing teamwork and investing in new systems - and whilst we have been encouraged on a number of fronts, there is still work to be done in making the business more efficient and reducing costs."
Strategy - this bit is interesting. Jonathan Lander said on April 21st that markets were experiencing "peak gloom". But it looks like Volvere is waiting for more fallout from this crisis, before it does another deal. It's not in a rush:
We are already seeing increased levels of distressed deal flow due to the COVID-19 pandemic. The length of the economic effects is uncertain, but I fear it is likely to extend well into 2021 and possibly beyond. The anticipated reductions in financial support from state schemes will probably trigger more hardship for individuals and companies.
We will do what we can to rescue those businesses which we believe viable, in all sectors and geographies, in accordance with our investment mandate, but with added focus on building a larger group of food businesses, leveraging our competencies in this area.
I think this is fairly clear, and sounds sensible.
Remember that Volvere's strategy typically involves buying out a bank loan for a company in administration.
But with the government support schemes currently in place, such as furlough and loans, many companies have avoided going into administration.
It makes sense to wait until some of these schemes are over, and only then to make a move.
My view
No change to my view here (what did you expect?!)
The share price is now at a small (5%) premium to NAV, but I don't think that's unfair. Remember that this vehicle has compounded wealth at an extraordinary rate for nearly 20 years now. A small premium for this sparkling track record hardly seems unreasonable.
If we deduct year-end cash from Volvere's market cap, we are left with an enterprise value of just £6.4 million.
With Shire earning (pre-tax) £1.1 million for Shire in 2019, the implied pre-tax earnings multiple is a mere 6x.
Some cash has been used to buy Indulgence, but I note that Volvere did not even pay a premium over book value in that deal. And there is clearly some potential for it to benefit from the association with Shire, as they are both in the business of manufacturing frozen food.
Happy to continue holding, then.
SIG (LON:SHI)
- Share price: 29.7p (+6%)
- No. of shares: 592 million
- Market cap: £176 million
This ticker has been blowing up my Twitter feed, and blowing up the message boards too, by the looks of things.
It's a mysterious thing - why do some companies capture the imagination? And why would SIG capture the imagination? It's "a leading supplier of specialist building products and solutions to trade customers".
One feature of the markets that will never change, is that people are attracted to high-risk shares.
The SIG balance sheet is broken, and they are trying to fix it:
Strengthening the capital structure for the long term:
Constructive discussions ongoing with lenders to reset covenants and agree other amendments to the Group's financing facilities
Intention to raise approximately £150m in new equity in the coming weeks
Good luck to the company. If you are holding the equity in this, one of your main sources of risk is that even if a fundraising occurs to save the company, it can be almost impossible to predict how much of it you'll be left owning.
In an unfavourable scenario, the percentage you are left with is tiny.
I hope that doesn't happen to the existing equity at SIG.
Calling it a day there, have a fantastic weekend everyone. Thanks for your comments as always.
Best,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

51 comments
It might just be me but I find the SCVR comments section increasingly reads less like investing discussion and more like Facebook.. lots of arguing over politics and people desperate to have the last word. It is human nature to want to put a point across if you read something that you vehemently disagree with, but it just ends in lots of acrimony. Aside from anything else it means really good thoughtful investing posts are lost in the noise. Maybe we could get back on track this week? The thumbs up/down is there for posts you don’t like. Maybe G&P could delete posts and replies that veer massively off-topic? Just a thought.
Maybe G&P could delete posts and replies that veer massively off-topic? Just a thought.
While I agree with the point, it's Paul or Graham that set the tone for the day. Here Graham opened with a political comment on the US riots and we get a bunch of related opinions. The same is true whenever one of them leads off on Covid-19 or some other macro point.
timarr
Thats a very valid point. I also have no idea how the most people feel about this, they might disagree entirely with my view and enjoy the ‘banter’.
..............................,-~*`¯lllllll`*~,............................................. .....
...........................,-~*`lllllllllllllllllllllllllll¯`*-,..........................................
......................,-~*llllllllllllllllllllllllllllllllllllllllllll*-,......................................
..................,-*llllllllllllllllllllllllllllllllllllllllllllllllllllll.\... ..................................
................;*`lllllllllllllllllllllllllll,-~*~-,llllllllllllllllllll\....................................
................\lllllllllllllllllllllllllll/...........\;;;;llllllllllll,-`~-,................................
.................\lllllllllllllllllllll,-*.............`~-~-,...(.(¯`*,`,...............................
...................\llllllllllll,-~*........................)_-\..*`*;..)..............................
.....................\,-*`¯,*`)............,-~*`~................../...............................
.....................|/.../.../~,......-~*,-~*`;.................../.\..............................
.................../.../..../..../..,-,..*~,.`*~*..................*...\.......................... ...
...................|.../.../..../.*`...\................................)....)¯`~,........... .........
...................|./..../..../........).........)`*~-,............../.....|..)...`~-,..............
.................././.../....,*`-,.....`-,....*`....,---......\...../...../..|..........¯```*~-,,,,
.................(............)`*~-,.....`*`.,-~*.,-*.......|.../..../..../...............\..........
..................*-,.......`*-,...`~,..``.,,,-*.............|.,*...,*....|.................\.........
......................*,.........`-,....)-,..................,-*`...,-*.....(`-,..............\........
........................f`-,........`-,/...*-,___,,-~*.....,-*......|....`-,...............\.......
timarr - it's The West Wing coming to real life
Hi Graham,
Firstly, I whole heartedly expect this post to receive a lot of negativity. In my opinion it needs to be said so here goes ...
Re: riots ...
Do you not think you are missing the bigger picture?
For me the real story and the real threat to the US economy is the continued oppression of people of colour not the destruction of a couple of blocks of property. It feels to me as if there is a potential powderkeg on both sides and all it would take is a spark.
You're correct in saying this has happened before in the US but the difference is the US has a "leader" who proactively fans the flames rather than soothing. Who polarises rather than unites.
You said...
"Most of these stories can be safely ignored by investors, but I wouldn't want to ignore them completely."
For me, when something becomes divorced from the lived experience of individuals we are in big trouble.
Please watch a selection of recent incidents and for any other readers who feel like they want to respond I'll only engage if you have truly watched all of the videos.
Here's the footage of Floyd's arrest ...
https://edition.cnn.com/videos/us/2020/05/28/george-floyd-death-reactions-girlfriend-mayor-marquez-pkg-tsr-vpx.cnn
The police claimed he was resisting arrest but subsequent footage from the store which called the Police and from eye witness testimony including the shop owner indicated that he was compliant.
If this was your son, your brother, wouldn't you be raging?
Here's an account from an eye witness, listen to emotion in his voice ...
https://edition.cnn.com/videos/us/2020/05/28/george-floyd-arrest-witness-donald-williams-cuomo-intv-cpt-vpx.cnn
To me as I read your preamble it felt as if you were trivialising the response as "fair weather rioting" , a chance to have a bit of mayhem.
It's not just about Floyd either.
It's taken months to bring action in the Ahmaud Arbery case. Ahmaud an unarmed jogger was shot and killed on Feb 23rd and it's only as a result of huge pressure (and I mean huge pressure) that charges were eventually filled in May. One of the three men arrested was a former police officer.
https://abcnews.go.com/US/hearing-set-georgia-men-charged-ahmaud-arbery-killing/story?id=70906145
Then there's kids who are scared by Police behaviour (I wonder why?) ...
https://edition.cnn.com/2020/05/28/us/tye-anders-midland-texas-police-trnd/index.html
Then of course you just have the regular day to day racism which is being exposed more and more ...
Amy Cooper calls Police on a bird watcher in Central Park and claims (falsely) he threatening her life because wait for it ... he asked her to put her dog on a lead in a section of the park where dogs are required to be on leads.
https://www.thecut.com/2020/05/amy-cooper-central-park-dog-video.html
Or some guys working out in the gym associated with their office ...
https://nypost.com/2020/05/27/minneapolis-man-asks-black-tenants-if-they-belong-in-building/
On and on and on it goes ...
Imagine that ... having to have your phone ready all of the time you are out in case someone challenges you?
So why is this at all relevant?
Trump knows he's going to lose the election in the autumn. If he loses the elction in all likelihood he'll be arrested as the unidicted coconspirator in the Michael Cohen case.
He is going to use everything he can to prevent that from happening and riots provide him with an opportunity to respond as the tough guy which'll play right into his base. It's perfect for him. For me, it's on a knife edge and Trump isn't worried about the impact on anybody else but himself.
My prediction is this ...
Trump will either:
a) attempt to delay the elections citing Covid distancing precautions as inhibitors to a free and fair election
b) lose the election and claim it wasn't free and fair. We're already seeing him sowing the seeds of that by claiming:
i) that mail in votes are subject to fraud which Twitter fact checked him on.
ii) he's being censored by social media
Please let's try if we can to walk a mile in another person's shoes. We're here to make money but please let's not lose sight of the plight of our fellow citizens.
Warm regards
Phil
Just to give you a sense of the forces at play here ...
A guy was videoing the protest outside the Police station in Minneapolis when a "protestor" started to break windows ...
https://twitter.com/neetpolice/status/1266222612641992704
It's been suggested that this individual is a serving Police Officer identified by his ex-wife acting as an agent provocatuer presumably to shift focus from a mudering racist police officer to evil rioters.
https://twitter.com/GypsyEyedBeauty/status/1266162964727562240
Who carries a deployed umbrella to a riot?
I think Graham’s comments were made from the point of view of the effect on stock markets, rather than an analysis of the incident itself and those who perpetrated it.
attempt to delay the elections citing Covid distancing precautions as inhibitors to a free and fair election
He might be able to do that - but regardless his Presidential term ends on 20th January under the 20th Amendment and nothing he can do can stop that. The next in line is the Vice President, but his term also ends on the 20th January,
Now it gets interesting ... next in line is the Speaker of the House of Representatives - aka Nancy Pelosi. However, the House is 100% up for election in November - so if there's no election there's no House and therefore no Speaker ...
However, there will still be elected members of the Senate because 50% are elected every two years. Half of them will have to stand down but the remaining half remain in place. The next in line is the President pro tempore of the Senate who is currently the Republican Charles Grassley ...
However, the remaining sitting members of the Senate will have a Democratic majority subject to arguments over whether sitting governors can just appoint Senators. Assuming they can't then the Democrats get to elect their leader which means that the most likely future President if Trump manages to delay the election is ...
Elizabeth Warren or Bernie Sanders ... :)
So that ain't going to happen.
timarr
The New Yorker carried a relevant short story recently. Strongly recommended.
I don't disagree with what you are saying at all here but I'm not sure this is the right place that this "needs to be said", Graham is just focusing on the investment view and trying to be objective in that focus.
With that said - I'm not a fan of Trump but him being president again is not bad for companies and there is a very real chance he will win again. China's actions in Hong Kong are giving him the perfect opportunity to bolster his core support.
Biden winning may not be so good for markets (higher taxes etc) but who knows, maybe it will.
Hi Thornbian,
What prompted my reply was ...
What would I think if I was black and reading Graham's report?
If I'm honest to me it felt insensitive.
Best of luck
Phil
Hi PhilH - ever try asking yourself whether 'the continuous oppression of people of colour' story that u buy into is a story line that the virtue signalling careerist MSM wish to promote and do so by maximising every negative racist news story they can find to promote the racist angle whilst minimising coverage of any inconvienent stats that might counter it i.e what proportion of the millions of African Americans have been victims of direct racism or police brutality and if it is as widestream as the MSM claim then how come millions of African Americans are American patriots and thousands of African Americans have joined the American Police force over the years?
What is not reported is the extent to which the police may turn an eye to black crime the way that in the UK the police and others turned a blind eye to white teenage girls being exploited by ethnic sex grooming gangs in towns like Rotherham because the police officer and others were scared of being called racist.
Note all over in Europe there are ladies who have gone to the police claiming they have been raped by migrants .This news story the MSM tries its best to minimise reporting because it does not fit their politically correct worldview.If you research New Years Eve 2015 in Cologne you were find literally dozens of females claim they were sexually assaulted by a migrant mob.Initially the German MSM refused to report the story for 4 days and it was only after widespread video coverage on the internet that the news story was taken up.
Well said. Not sure why the original poster has decided this is the right place to post such musings.
well you could just ask the OP. You do mean Graham right?
Why is Smartspace Software (LON:SMRT) up 50% today with no RNS?
Interesting mid-day update from Wizz Air Holdings (LON:WIZZ) on its expansion plans, opening up 51 new routes during a pandemic!
Judges Scientific (LON:JDG) Hi Graham - agree with pretty much everything you say. But, I suspect, the special dividend paid on 10 December had a bit to do with the General Election 2 days later! I'd rather David Cicural holds on to the cash & continues to buy small, below the radar, specialist companies. I don't want to read about a "transformational" deal - and don't think I will. I have held for some time & intend to continue.
Watchstone (LON:WTG)
Just announced a further return of cash to shareholders, which with the April announcement seems to amount to a total of £1.5 worth.
Price is hovering at £1.7 ish.
Any thoughts on the prospects thereafter?
Watchstone (LON:WTG)
Hi Trident,
You asked about the prospects after the 150p per share cash return set to take place over the coming months.
I personally think that a share price of 170p is fair value (current SP is slightly above this).
Indeed I sold out of my position for c.165p recently.
There will be c.30p of cash remaining in the business, and an assumed share price of 20p.
So why would I sell?
I believe that the remaining business, black box car insurance , will be suffering as revenues were not large enough to cover expenses beforehand, and there won't be any new customers signing up right now, so for me, that makes the short term risky.
I know they are looking to sell this last business, but who would buy a loss making business in this climate?
It's been a great holding over the last few months, and was indeed the only thing I was buying in the 1st half of March (it was my largest position until a few weeks ago), but now that it's done what I bought it for (ie provided a cash rich safety net), I'm happy to move on until there is more visibility on their future revenues.
Cheers and good luck
A
Thanks Abtan. I was thinking of selling off my modest holding
Morning Graham!
I'm glad you mentioned the US political situation. I have that down on my pad, as being something I was also going to flag up.
I generally don't follow US politics in any detail, as it gets me too worked up, and is thoroughly surreal at the moment. And ultimately, it's a matter for Americans, not us.
However, I did listen to an interview with Jo Biden the other day on CNBC. The policies he set out are to basically reverse Trump's tax cuts - i.e. raising corporation tax considerably (I noted down from 21% to 28%, but am not sure if that's correct), and much higher Capital Gains Tax.
To my mind, Biden's policies would be likely to trigger maybe a 10-20% fall in the stock market, as earnings drop due to higher corporate taxes, and people sell to dodge a higher CGT liability in future.
I then looked up the likelihood of Biden becoming President, and he seems to be well ahead in the polls. Therefore this looks a very considerable potential risk for US stocks, and hence US indices.
It's another reason why I'm keeping quite big short positions on the Dow, and the NASDAQ. Other headwinds include increasing tensions with China, also likely to be cranked up since it appeals to Trump's core supporters. Chinese stocks listed in the USA could well fall, as people sell them ahead of possible de-listings, due to increased regulatory scrutiny.
Plus of course we have the rather important matter of 40 million unemployed currently on furlough, but only some of whom may be re-employed. Therefore, despite unprecedented stimulus, there's still plenty of scope for this to get pretty ugly. Even if we do see a V-shaped recovery, Govt & companies end up up to their eyeballs in debt.
On a more positive note, there was encouraging data from the US retail sector. On re-opening malls reported sales at 55% of usual, and non-mall shops reported business at a remarkable 85% of usual. That's on the initial re-start, so could improve further from there. Younger people in particular, apparently have hit the shops on re-opening, with apparel a strong sector. This is very encouraging, if repeated in the UK. Maybe retail could recover better than we think? We'll have to wait & see.
I feel that we have a duty of support local businesses, so personally I will be going shopping as soon as shops re-open, on the basis that this will help support jobs & keep retailers going. It would be such a shame to see High Streets become wastelands. Use it or lose it, as the saying goes.
Regards, Paul.
Paul, 'if we do see a V-shaped recovery' has surely passed it's sell-by date, to my mind it looks like it will be one of those mathematical signs where the bottom of the V climbs halfway up and then levels off there. Sorry to be pessimistic but things are more heavily weighted against full recovery than anything I ever saw.
William
Couldn't agree more! I feel the chance of a V shape recovery are slim.
I agree with your hunch, but in my comment above I pointed out some recent data from the USA, which indicates a V-shaped recovery may not necessarily be impossible. There's also been positive data on mortgages, and demand for housing in the USA.
On balance, I'm leaning towards being negative, but it's important to look at data, especially when it contradicts our existing opinions/beliefs!
I expect in the short term shopping activity will be quite close to 'normal' levels but will it last? That is the question!
Short term shopping will be partly influenced by the social distancing measures in each store.
Anywhere that is usually fairly busy will probably trade below normal, as social distancing will result in a long queue outside, which will put off customers. Quiet stores should do no worse than normal, possibly better if trade is effectively diverted to them.
A lot depends on how social distancing is implemented. I visited Wickes earlier in the week, which was a poor example. They had one member of staff outside, enforcing one in one out. The big error was only having one till open, despite sufficient spacing to easily open 2 of them, so there was a long wait to be served and a third member of staff doing nothing other than marshalling the queue. The slow till service just means a long queue outside.
About 3 others were preparing click and collect orders, which looked pretty inefficient. I'm not going back there until they get their act together.
About 3 others were preparing click and collect orders, which looked pretty inefficient. I'm not going back there until they get their act together.
How will you know ;)
But seriously, I know I should wait until it's official but I read today that employers will have to meet 25% of furloughed staff wages from August. Given impact on sales that all these restrictions will have, especially in the hospitality sector, doesn't that mean a lot of furloughed staff about to become unemployed staff?
I have seen some baffling incompetence (Iceland, massive queue outside, one till with long queue, and shortened opening hours) and Asda who seem to have solved the problem.
Thankfully capitalism will move the custom to the businesses that behave competently.
Based on the big increases in Corporate and personal debt , I am expecting an 'L' shaped recovery ... ..as in Bloody L !!??
From what I have heard about the individual retailers plans, (social distancing at 2m in stores, no touching merchandise, one way traffic, regulated numbers / queueing, social distancing 'marshalls' etc) it does not seem that physical shopping is a worthwhile experience. Better just to stick to online. My feeling could be anomalous and not replicated of course.
As far a V shape recovery is concerned, would that not be predicated on rapid opening of economic activity ? Here we will not have anything like that with a slow bitty opening; no network effects.
On the other hand we have never (as far as I am aware and I am excluding the Fed, ) had an economic downturn created by sudden government fiat with no fundamental problem with the general economy beforehand so maybe it 'will be different this time' ?
Hi Paul
With regard to a political risk to stocks with a Biden win, you probably won't be surprised to know that I think that a Biden win would be a win win for everybody (apart from Trump) but also there is an article in the FT written March 5th at:
https://www.ft.com/content/38829e98-5180-11ea-a1ef-da1721a0541e
Which US president is best for stock markets — a Republican or a Democrat?
Markets have favoured Republicans, but investors have done better under Democrats.
But one analysis states:
"With the results clouded by both compounding and outliers, he concludes that “party affiliation of the US president is a poor framework for thinking about equity returns”.
I particularly like the last comment on the article:
"Being, “pro business”, is a bit like being the fun parent. All of those sugar highs seem great, until you have to go to the dentist. Then suddenly the fun is over."
It makes for interesting reading.
Best wishes
Michael
Hi Graham,
I just want to add to your comments. I also share your concerns with riots in the USA but I am not overly surprised. I'm more alarmed the policeman responsible for manslaughter has no been arrested or charged yet!
Kind regards
BSV
That Hussman commentary makes for sobering reading.
Must admit I can't take anyone seriously who reminds everyone reading he has a PhD at every possible opportunity. I lost the will to live reading it and gave up. Lots of the usual pontificating about Covid, and as fast I can see his PhD is not in epidemiology. As Howard Marks correctly points out:
“It’s so silly for an investor to build his investment conclusions around his view of what the disease holds when he knows nothing about it,”
All the best, Si
I was referring to the over-valued nature of stocks heading into an obvious recession.
I don't go to fund managers for epidemiological advice.
I was referring to the over-valued nature of stocks heading into an obvious recession.
I don't think there's anyone who invests in stocks that isn't surprised by the market reaction and doesn't feel that way, so he's not really saying anything we don't already know, is he? However, some of us could make as good a case in considerably fewer words and without so much hand-waving. I don't have a PhD.
All the best, Si
Interested in comments on Dwf (LON:DWF)
Weekend reading
Latest Hussman Funds commentary about Covid and over-valuation of US stocks
https://www.hussmanfunds.com/comment/mc200420/
"...it took too long to accept that the IQ of Wall Street hit zero the moment interest rates did.
That’s fine. We’ve adapted. As the Scottish golfer said as a gust blew his companion’s drive into the trees, 'Well, laddie, now we’ve got to play the wind too.'
Recent interview with Howard Marks
https://blogs.cfainstitute.org/investor/2020/05/19/know-what-you-dont-know-six-tips-from-howard-marks-cfa/
"Every great investment begins in discomfort,” Marks explained. “If everyone else didn’t hate the investments, they wouldn’t be cheap.”
That Hussman commentary makes for sobering reading. Thanks.
Hussman's main fund has returned 0.28% annualised since inception in 2000.
He has been bearish pretty much since 2010, and missed one of the biggest and longest bull runs in history.
Like lots of economists - and he's a Stanford PhD, don't you know - he appears to be much better at creating a compelling narrative than actually predicting the future or, more realistically, just making money.
Yes
He admitted he got it wrong for a long time because he confused valuation with internals, i.e. a high PER rating is fine if the growth is there.
20 years is a long time to be confused. His clients made annualised returns of 0.28% on their money, John P. Hussmann Ph.D makes 1.15% annualised on their money.
He's lucky his clients are more confused than he is!
"Buy the fund managers not the funds"
Bonitabeach
I thought I'd just pull out this news article yesterday on Air Partner (LON:AIR) given the general interest from the community in this company: "Aviation services company Air Partner’s global private aviation team has seen more than a 210% increase in requests for future flight bookings during May compared to last May, as governments around the world begin to ease Covid-19 restrictions. Enquiries for private flights are for June until the end of August with individual and corporate clients seeking alternative solutions for flying to leisure destinations or traveling for essential business matters." (Source)
Sounds good and feels like this will be a bumper year for the company. There should be a further update next week as the company has committed to updating monthly.
(I am long and wish I had bought in when it was much lower than my entry price of 57p!)
Here's Paul Scott's COVID investing / piworld webinar28.5.20. Paul's made good returns this year, and although we hear (almost) daily his thoughts and what he's up to, it was great to hear the journey over the year, and how well he's played it. Lots of familiar stocks mentioned, and some more recent additions. Highly recommended. Honest, engaging and informative - as Paul always is. Enjoy!
Next week's guest on piworld's Thursday webinar, is David Stevenson, who writes The Adventurous Investor column in the weekend FT, as well as writing for Money Week and Citywire. David is an accomplished investor. He will cover his views of the markets, how he's played the 2020 so far, and where to find income in these days of suspended dividends. Register via this link.
Further, we have two company presentations. 2.6.20, Panoply Holdings (LON:TPX) management will give us an update on trading, contract wins, and more detail on what dramatically moved the share price up this week. And, 9.5.20, Tr Property Investment Trust (LON:TRY) will outline the fund. (Discount to NAV 12%. Dividend 4%. Less risky property sectors). Both should be very interesting. Register via this link.
Thank you for yesterday Tamzin, Paul was excellent.
I will plump for £13.3m Rev and a PBT of about £0.65m ...cant be too many surprises now and lower growth I hope reflects weakness in food service. I don't expect a profit from Indulgence 2020 and see 2021 as being a more important year.
In 2021 we should see earnings become more relevant to drive visible value of the Food business rather than historic book value.
Eagle Eye Solutions (LON:EYE) announced resilient trading to date, and forecasts adj EBIDTA and cash slightly above market expectations (I hold), despite a severe revenue hit from its non food retail clients. For those who think that we might be near the end of the Covid effect, Eagle Eye though inserts a note of caution:
"We are conscious we are only at the start of the impact of COVID-19 on the economy and the retail sector in particular and, therefore, while we believe digital, personalised connections with customers will continue to grow in relevance, we will maintain our strong focus to ensure we successfully navigate these challenging times for all."
Tip of the Day... if you use LSE RNS when Investegate lets you down... never be tempted to tick the professional investor box.... you won't be able to access the full RNS for 24 hours. Private Investor only.
Great advice - In my haste, I have been there done that!
My morning smallcap tweet: EVE, the slumbering midget
eve Sleep (LON:EVE) DWF (LON:DWF) Volvere (LON:VLE) Deepmatter (LON:DMTR)
eve Sleep (EVE) last four months in line. Cash burn £0.1m pcm. Net cash £7.5m.
DWF Group (DWF) guides FY(Apr) rev up only 11% cf prev guided 15-20%. EBITDA £34m (IFRS16), underlying adjusted EBITDA £21m. Net debt better than expected at £64.9m, available facilities £122m. CEO scarpers. He is thanked. Chmn takes over.
Volvere (VLE) FY(Dec) as guided. Q1 boost to rev but too early to say whether this will be sustained. Seeing increased levels of distressed deal flow.
DeepMatter (DMTR) FY(Dec) rev £1.2m (0). Post-tax -£3.02m (-£1.81m). "The pipeline of revenue remains strong and the impact of the virus on customer working practices has increased interest in our DigitalGlassware™ platform and other products."