Small Cap Value Report (Fri 3 Feb 2023) - BWNG, BBSN, NANO, TUNE, Paul's portfolio now

Good morning from Paul!
I've got a bit of catching up to do today, so you have my full & undivided attention until at least 13:00, possibly longer.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda/Summaries -
I'll aim to look at some of the items in the backlog section from previous days this week -
Paul's Portfolio Now
This started off as a reply to a reader comment, but it's probably worth repeating here as a main section.
People might be interested in my current holdings, since I recently deployed some spare cash from a successful bid at BUMP.
As always, it might shock you that I'm taking a fair bit of risk here, but just because I write a value/GARP column, doesn't mean I have to invest my own money in the same way! So here goes (initially a reply to joshwood's comment below)
Yes good idea, I can do an updated list of my own personal holdings. It would be quite easy now, because (as mentioned numerous times here & in my podcasts), I capitulated with my spread bet accounts last year, and closed them. Now I'm just concentrating on ungeared investing, so smaller positions, and less risk. The plan being to just gradually rebuild, rather than shoot for the moon & the stars again, before burning up on re-entry, which is the story of my life to date! ;-)
Actually, let's do it now, it won't take long - my current portfolio, positions in descending size order (so BOTB is my largest holding), with reasons -
Some of these are quite recent purchases, from the proceeds of selling my Seraphine (LON:BUMP) shares (takeover bid in progress, but I gave away the last 3% in order to grab some opportunities where I see more immediate upside (and so far so good))
In size order, largest first -
Best Of The Best (LON:BOTB) - I'm very impressed with the most recent update - interims, reviewed here. Business has now stabilised after the pandemic boom. Cash in bank, pays generous divis/buybacks, fwd PER is only 8.5, so under-priced as it is now. But international growth through Tedi Sagi's 30% investment is the exciting bit, which could transform things for the upside. If BOTB's cautious management don't want to run fast enough, then maybe Sagi might bid for the whole thing? Risk:reward looks tremendous to me, but might need to be patient. Intended holding period - 2 years to begin with, but depends on newsflow.
XP Factory (LON:XPF) - more speculative, but I really like the concept of experiential leisure, and think the Boom Battle Bars concept is a winner. Very rapid roll-out done in 2022. In line recent update. Should out-perform regular bars. I think a consumer recovery is coming in 2023 or maybe 2024, so good upside from a bombed out sector maybe? Some risk, as cash looks tight, but it can safely run existing bars for cashflow (EBITDA positive now), and some are franchised, lowering risk. Great deals from landlords, who prefer this concept to regular bars, big reverse premiums cover most of the fit-out costs. Switched-on CEO.
WANdisco (LON:WAND) - bit of a punt. Mentioned a lot in SCVRs. Something big seems to be happening, with repeated, large contract wins in the last 6 months. Huge market cap for a loss-making co with a terrible track record. 3 out of 5 major shareholders (including shrewdie Richard Griffiths) are adding (recently). So this has credible backers (including USA funds), not a bulletin board ramp. Has amazing momentum at the moment - buyers are catching every dip.
Revolution Bars (LON:RBG) - a recent purchase at 6p. I'm worried about bank debt taken on to buy Peach Pubs, but am hoping that the bank might remain co-operative. Wobbly recent trading at core business, but good at Peach. Tiny market cap is the main attraction here, so just a shorter term trade on trading improving, which could make it return to 20p, a 3-bagger, possibly? Also, energy cost headwinds could become a tailwind, if current trends continue. Horrible sector, might gain market share as competition goes under? So quite high risk:reward here, not for widows/orphans. I've gone into it with eyes wide open, so it won't kill me if they have to do another discounted placing, which is main risk.
hVIVO (LON:HVO) - another recent purchase, covered in SCVR 25 Jan 2023. Readers got me onto this one, and I'm impressed with the latest update, big contract wins, moved into profit. All suggests something interesting is going on here, and claims to be world leader in its niche. CEO seemed a bit over-excitable in recent webinar! But with contracted order book covering nearly all 2023 forecast, looks set up for trading ahead exps updates.
Beeks Financial Cloud (LON:BKS) - a long-standing position, covered frequently in the SCVRs.
Watkin Jones (LON:WJG) - builds student housing, and build to let. Forward-sells projects, so little balance sheet risk. Demand returning from institutions, after wobbles caused by political shenanigans last autumn. Expect soft H1 2023, but after that should do well. Cheap on fwd PER & divi yield, lower margins for a year or two, but that's all baked into forecasts. I think shares could double/triple on a 2 year view.
Portmeirion (LON:PMP) - just too cheap, and performing well. Could be a doubler if things go well?
Cambridge Cognition Holdings (LON:COG) - longstanding position, I remain positive about it, long-term holding.
MJ GLEESON (LON:GLE) - my favourite housebuilder, bounced, but still cheap. Builds very affordable houses that are likely to remain in demand. I'm looking through likely soft patch in H1 of 2023. Could be a doubler, once economy back on track in 2024 or beyond? Amazing bal sht, so no risk, even in a bad recession (looking less likely now).
Oxford Biodynamics (LON:OBD) - just a punt, after they got a placing away at a premium. Low conviction, but small enough to not worry about this holding.
Please don't rush out and buy any of these without doing your own research. In fact, some readers might decide this is a good list to open short positions on, which would have served you well with my main share picks after the market peaked in about summer 2021!
So rather than just buying back my old stuff, I've mostly picked new ideas.
Anyway, I hope that's interesting, and gives you some ideas to research.
I've got a list as long as my arm of other ideas to invest in, so see my spreadsheet here of 2023's best value/GARP watchlist ideas from me - some of which will do well, others won't, which is what I expect to happen. Note the "Speculative" tab is fanning out quite strongly with some doing well, and some doing badly. But the main 2 tabs are up 12% YTD, because we're currently in a bull run for small caps, so they're just rising with the market I think. No stock-picking genius involved, I could have picked anything!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Weekend podcast - I've recorded it, and just published it on podcast platforms (such as Apple, Spotify, and others), just search for "Small Caps Podcast with Paul Scott", or any part of that.
I'm having temporary technical problems with my own little website, should be fixed on Monday, so I haven't been able to publish it there yet.
Thanks Paul. Always great to find an hour or so to listen and take stock.
Enjoy the weekend (perhaps better on the coast than here in deepest, darkest, rural North Dorset is grey).
As always, great podcast Paul!
Hi All, seeking a little advice/opinion on (HUI) Hydrogen Utopia International PLC, having just noticed on HL that they are planning to delist from the LSE on 14th February. I've got a reasonable position on them, but unsure whether to continue or trade them in. I very much like the business & service, but I'm not sure I'm brave(?) enough to have them moving around elsewhere with my £!s ;)
HUI are delisting from AQSE on the 14th Feb having just got a listing on the LSE .
Thanks nitnia, HL do not make it clear where they are de-listing from, which I did think rather strange, as of course they have just listed on the LSE?! Thanks again :)
Hi Paul,
I’ve been listening to you great weekly podcasts via your quality small caps website but suddenly this is coming up with a security warning stating the connection and the website aren’t private nor secure. Are you or other subscribers aware of this?
Hi Jayman,
Yes sorry about that, my little website for publishing podcasts has got a problem with the SSL certificate. I've bought another one, but it isn't configured properly apparently. I don't understand all the emails I'm getting from the hosting company, so will have to try and sort it over the weekend. Sorry about that.
In the meantime, I'll put tomorrow's podcast on the main podcast platforms as usual (e.g. apple, google, spotify, etc). So it might be better to access it via that. I publish through acast, which then distributes my podcasts far & wide on the various platforms!
Regards, Paul.
Thanks for the colour Paul
There seems to a case of indiscriminate buying of late just as we suffered indiscriminate selling last year. Boohoo (LON:BOO) for instance is up 30% in the last month - fundamentals don't support this imo. There are others too. Is it just a case of FOMO?
You may well subscribe to Bloomberg's John Authers daily newsletter, if not it is usually worth a read, especially at times like this.
Although his take is more US centric I imagine the same scenario applies more or less to UK and Europe.
In answer to your question this is a section from this morning's offering.
Apologies for some reason not being able to just add a link.
How to Make Sense of This?
If risk assets have enjoyed a historic rally, it remains difficult to see exactly why. Even if traders are right to call central bankers’ bluff and bet that target rates will soon come down, after all, that still implies a slowdown in the economy — which would be bad for risk assets. If the economy isn’t grinding toward a halt noticeably, why would the central bankers cut rates?
As ever, positioning plainly has much to answer for. Across markets, this looks like a classic “short squeeze” as the stocks that had taken the biggest hit have seen the biggest rebound. For one nice illustration, this chart shows the performance of S&P 500 members for the year so far, on the vertical axis, and from August’s brief high to 2022’s year-end on the horizontal axis. The biggest fallers in the last downdraft of 2022 are the biggest gainers in this rally, with Tesla Inc. in the vanguard:
The short squeeze is particularly effective because there’s an abundance of liquidity to finance it. Arguably, this is the critical factor that had not been expected even a month ago, and that has turned market dynamics on their head. Some of the reasons for the turn in liquidity are counterintuitive, and include:
On top of this, the fall in yields creates its own momentum, making money cheaper and enabling more speculative activity. The liquidity effect in China has been most dramatic, as illustrated here by Mike Howell of CrossBorder Capital. The orange line shows the rolling three-month total of liquidity injections by the PBOC via open market operations, while the dotted black line is a NowCast of moves in global GDP:
Liquidity on this scale can keep markets moving for a long time. Howell tends to think this is the beginning of a new liquidity cycle, which could mean a long strong run for risk assets. Others expect it to be shorter-lived. Harry Colvin of Longview Economics said: “What we’ve seen for the last few weeks has been a short-covering rally, and then in the last few days an aggressive short squeeze.” With the economic data still pointing to an imminent recession, he suggests the short squeeze can’t last much longer, and that buying bonds is going to make far more sense than equities for the rest of the year.
And indeed, if this isn’t a short squeeze it looks an awful lot like one. John Roque of 22V Research points to a series of startling successes during this rally, which have all the hallmarks of an indiscriminate liquidity-driven rally. Non-profitable tech stocks are up 17% in the last five days, he says, and 27.5% in 2023. Meanwhile, high beta momentum is also up 17% for the week, and 28% for the year to date, while the most heavily shorted stocks have done better still, up 15% in five days and 29% for the year.
It’s dangerous, as ever, to try to get in the way of a wall of liquidity. But unless that liquidity succeeds in keeping the economy afloat, the risk is that asset prices will sink.
I'm struggling to see the connection between increases in liquidity in China, Japan and the USA ,and the price of Boohoo (LON:BOO) on the LSE. But it appears the shorts are capitulating to some extent, whatever the reason may be.
That is nothing, ASOS (LON:ASC) is up about 90% in just over a month, many retailers are also strongly up. Some had good Christmas trading.
Best Of The Best (LON:BOTB) - not a fan of 'spot the ball' but do get tempted sometimes ...
Hello Paul, is it possible to put a link to your daily spreadsheet, on the SCVR, everyday, please.
I've Bookmarked the spreadsheet so it's always easy to find
Yes but does not seem to update.
Works for me and shows latest version
https://docs.google.com/spread...
Maybe it was not updated for a while, I looked yesterday and there was nothing fir a few days. Today it is up to date.
But anyway a link is useful. Tabs get cleared sometimes.
Paul said earlier this week that he didn't want to publish his link in SCVRs as the link would get out to recipients of Stockopedia's marketing emails.
So how will new members find it, in the future?
Maybe we need a members only area?
Paul,
Many thanks for responding, and giving your thoughts on Porvair. Very kind of you at such a busy time.
I'm a keen but amateur investor, so the detail you give on companies, including Porvair is invaluable. I'm able to take a view about niche, moat, record of cash flow etc, but , for instance, I'm far too ignorant and idle to understand about Pensions. Which are obviously important, and which you cover well.
I agree with you about stingy dividends from Porvair. I am a top-rate taxpayer (paying nearly 40% tax on dividends) , so I don't chase dividends, and in theory I should prefer companies to spend surplus cash on buybacks, capital investment, suitable acquisitions , and so on. BUT, I do like a modest dividend, and I do like it to increase each year.
This is because: 1. it is a great comfort and safety net, when the market nose-dives. And 2. like cashflow, it is a splendid empirical bit of evidence of how a company is doing. Unlike profit, the figure can't be fudged.
Although an ignorant and amateur investor (who can't even read a balance sheet) , I offer here a free bit of advice to readers. When you are considering investment in a company, have a look at the Stocko chart, and see if they paid a divi, or even an increased divi, during Covid.
I've had a look at two of my best investments. Halma ,whose shares have increased about 17 times since i purchased them , and Diploma , which have increased about 11 times. I notice that they both increased their divis during Covid. Of course, many companies would have been sensible not to pay a divi during this time, and this should not be the only criterion for selecting an investment, but an increased divi during Covid is quite a cheering sign!
If you open an ISA account you can trade dividend paying companies without a tax issue, and if you reinvest them via a DRIP, if you enough faith in them, they do a little bit of averaging down (and up) during market wobbles/runs.
I am sure you must be well aware of this, but never let it be said I didn't fail to take the opportunity to say something unoriginal :-)
Great updates Paul. Many thanks. I too believe in Revolution Bars (LON:RBG) and XP Factory (LON:XPF) but still feel that the consumer pinch has still to affect these shares. I sold my RBG beofre the recent drop as I wory about their debt management. I had similar consumer spending considerations for Sosandar (LON:SOS) but feel that will ride this out and keep growing through and into 24/25 and so added.
Crestchic
Anyone still holding ?
I’ve sold half in the market in the past month or so.
Samson rock have been buying like crazy and are up to 13% implying they think there is somehow sone upside ?
Could really do with selling the rest of mine and use for something else but the meeting is 6 Feb .
Aggreko need to get 75% .
Let’s assume Samson keep buying away they will be up near 15%
Might be worth going to the meeting ?
All a bit puzzling
Still holding onto Crestchic (LON:LOAD).
Do you know the timetable for completion?
I sold my K3 Capital (LON:K3C) today, don't want it delisting in my ISA, had a nightmare with another delisting, with my broker, took ages to sort out.
Do you know the timetable for completion?
I happened to look into this earlier today - the following is lifted from the RNS here
https://www.stockopedia.com/sh...
--------------------------------------------------------------
"EXPECTED TIMETABLE OF PRINCIPAL EVENTS
The following indicative timetable is based on Crestchic's and Aggreko's
current expected dates for the implementation of the Scheme and is subject to
change. If any of the dates and/or times in this expected timetable change,
the revised dates and/or times will be notified to Crestchic Shareholders by
announcement through a Regulatory Information Service of the London Stock
Exchange.
Event
Time and/or date
Publication of the Scheme Document
22 December 2022
Latest time for lodging Forms of Proxy for the:
Court Meeting (BLUE form)
11:30 a.m. on 2 February 2023((1))
General Meeting (WHITE form)
11:45 a.m. on 2 February 2023 ((2))
Voting Record Time
8:00 p.m. on 2 February 2023 ((3))
Court Meeting
11:30 a.m. on 6 February 2023
General Meeting
11:45 a.m. on 6 February 2023 ((4))
The following dates are indicative only and are subject to change((5))
Sanction Hearing (to sanction the Scheme)
13 February 2023((6))
Last day of dealings in, and for the registration of transfers of, and
14 February 2023
disablement in CREST of, Crestchic Shares
Scheme Record Time
6:00 p.m. on 14 February 2023
Suspension of listing of, and dealings in, Crestchic Shares on AIM
by 7:30 a.m. on 15 February 2023
Effective Date
15 February 2023 ((7))
Cancellation of admission to trading of Crestchic Shares on AIM
by 7:00 a.m. on 16 February 2023
Latest date for dispatch of cheques, and crediting of CREST accounts and
within 14 days of the Effective Date
processing electronic transfers due under the Scheme
Long Stop Date
11:59 p.m. on 31 May 2023 ((8))"
-----------------------------------------------------------------------------
HTH,
OK, thanks very much, not long now then.
Rusty2 - the timetable (below) for K3 Capital (LON:K3C) is actually one day ahead of Crestchic (LON:LOAD) which makes me puzzled as to why you sold it. "delisting" normally refers to a company where you retain the shares but they are no longer tradeable on AIM or the main market.
Scheme Court Hearing 10 February 2023
Last day of dealings in K3 Shares 4.30 p.m. - 6.00 p.m. on 13 February 2023
Suspension of K3 Shares from trading on AIM 7.30 a.m. on 14 February 2023
Effective Date 14 February 2023
Latest date for despatch of cheques and crediting CREST accounts: By 28 February 2023
Rusty, I'm of the understanding tyhat Bidco will pay 350 pence per K3 Capital (LON:K3C) share, in cash, this going back to an RNS on 16th December. Don't know whether there has been any changes since then.
Crestchic (LON:LOAD)
This can obviously work in both ways but anyone who sold at the point the bid was confirmed and recycled into pretty much any decent small or mid cap would have enjoyed an extra return in double figures by now. That’s why I always sell once the SP is within 5% of the bid.
In the first half of last year, this would not have worked as your repurposed funds would likely have joined the tumbling valuations - as I found to my cost.
However, even if January’s gains are a bear market rally, we are probably nearer the end than the beginning and I would be looking to grab upside elsewhere, but ideally from 1st Jan, not 3rd Feb!
As I said I sold half right away ,
Most of that went into Colefax at 620p so that’s had a big swing .
Think the strategy was ok , if anything jumped out as good buys I’ve been selling the Crestchic down as and when since (still sat on 40%)
I was massively overweight in Crestchic before the bid so no point selling everything and rushing to deploy .
I was also hoping it might not all crystallise till after tax year do CGT would split over tax year .
Eg today topped up Belvoir , Croma today on lows
Bought somero few days ago on the drop also Avingtans and Wynnstay on the drops in the past weeks
bought Finsbury half position at 90p and like Paul Watkins jones - so that’s where it’s been deployed .
Also titon at its lows . (67p) which is the company that I’m quite big on , found out last week their real estate in the accounts at 3 million level has a current market price of over 6 million so it’s a Benjamin Graham classic albeit a bit of a cigar butt in a tough trading space (it’s cheap now for a reason )
A lot of the gains are in the frothy shares that get bounced around not in the good solid long term companies I try to be involved with so would never have gone there anyway .
Colefax was a big win though .
Avation (LON:AVAP)
This trading update today is typical of the way this company interacts with its shareholders. Gruff, short on detail and always leaves the reader wanting more information. Illustrated by the number of times there has been "response to analysts questions" on RNSs. This strange because when I have met Richard Wolanski he has been very effusive and more than willing to expand on the business.
However I continue to hold thinking they have survived quite well. Interesting to see how the get on with their off lease aircraft sales, of which of course there is no detail, surprisingly!
I've met the management and been to their semi annual presentations and don't find it gruff at all. They are usually pretty patient and responsive to questions. Remember that as a leasing company they don't have lots of people - it is a surprisingly small number so there is a time element here.
I think the trading update is what it is and pretty much as expected. I've been through the numbers and there is a lot of hidden value in the B/S that will come out later down the line I think.
As I understand it only 1 of the old Virgin Aus aircraft are yet to find a home and that shouldn't take too long - the others should be be done shortly.
Market dynamics are good - second hand plane values are going up and lease market currently in favour of the suppliers. A lot of old aircraft were retired during covid and this has left a gap.
Debt is completely misunderstood by some retail investors.
1) Most of the debt is actually matched on a plane by plane basis against the lease. That means the lessor is actually paying down the capital as well as the interest. Thus at the end of the lease Avation (LON:AVAP) own the aircraft unencumbered and can re-lease it or sell it. However, as planes have a solid 20 year plus lifespan if maintained well and most leases are around 10 years the asset value actually goes up rather than down as a second hand car might. They don't take interest rate risk so the only risk is counterparty credit risk.
2) The bonds of $350m make up the rest but I expect $100m of these to be bought back at 85c in the $. That should release another $10m to NAV and lower ongoing costs. The residual $250m is fine to 2026. I expect circa $50m will come from FCF, $100m will come from unencumbered plane sales and the residual will be re-financed.
Thus the main risk is not debt at all as this is all asset backed and the second hand market is liquid. Main risk is lessee's going bust or 2nd hand values falling. Market dynamics don't suggest the latter but you do have to be comfortable with the companies policy on the former. Nonetheless trading at 40c in the $ leaves a lot of margin. Historically aircraft lessors trade at 1.1* NAV. I see this doubling but I don't know when - will depend on sentiment.
If you email Richard you will usually get a very prompt response.
unlikely - Richard left the company some time ago :)
Nonetheless if you email investor relations they are pretty good at getting the right person to answer sensible questions where they can.
Oh no.....I was counting on Richard for a spare propellor for the model Avation ATR in my son's bedroom!
The senior team at Avation (LON:AVAP) come across well in presentations and face-to-face, yet evasive in written statements. Today's RNS went down badly, though you could argue the SP got ahead of itself last week.
My conclusion is that they are badly-advised by their comms company and should report a standard range of metrics and KPIs (not choosing the ones that look best) with prior-year comparatives as Mr Contrarian has pointed out. I have more sympathy with them on aircraft sales, what can they say? A deal's not a deal until it's done. They don't want to appear desperate.
If anyone is interested in Intercede (LON:IGP) there's been more director buying announced today. Not massive in cash terms but reasonable size considering how much it normally trades.
Thanks for that, I am a holder of Intercede (LON:IGP) and had noticed the spike up today, but hadn't got round to investigating the reason for it
...talking about raises on AIM (see Brave Bison (LON:BBSN) chat)...
Itaconix (LON:ITX) are absolute champs at it. Doing it persistently ahead of seeming to really prove out anything material. Anyone in here got a case for them and see the future so have a rational for their raising success?
FWIW my feeling re Brave Bison (LON:BBSN) including after seeing them at Mello is that it's a 'trade' not an 'investment'. They have an odds and sods collection of things that make some cash (and they can clean them up to make a better return). They push them together to make a bigger 'brand'...veneer as much as substance IMO (in terms of the synergies/value of combination).
In 'social and digital media' (ie fancy word for monetising some data processing) its hard to have brand and durability. Its doesn't come from messing around with the data. It comes from performing a service or being placed in the value chain in some strategic/indispensable way. Brave Bison have a helluva lot to prove and build to get anywhere near that...and I suspect that isn't for the brothers (attention or skillset)...they see a chance to repackage something, create a bit of value that wasn't visible before and then profitably exit. There's a bit of me that also thinks they are doing it for the shitzngiggles too...not intended to be facetious but to capture that I think this is a fun exercise for them...make a bit of money, learn some stuff...maybe earn the cred to have a pop at something bigger in future.
So not saying that you can't make money out of it...just saying I don't see a durable franchise...and I'm just never really in for the trade so biased against
(I should point out the above is partially informed drive by banalysis!...I'm not expert on the company just looked at it at various points in last few years)
I don't take seriously companies with funny names.
I don't take seriously companies with funny names.
Google?
I don't take seriously companies with funny names.
Google?
It is just a really big number: https://en.wikipedia.org/wiki/Googolplex It is a name that prompts me to smile, so maybe it is a bit funny…although I am more inclined to call it questionable spelling and (eventually justified) hubris.
Many thought Apple was a funny name in the early days.
It is said it was because Jobs was a fruitarian. But according to Walter Isaacson's biography he came up with the name simply because “it sounded fun, spirited and not intimidating...plus, it would get us ahead of Atari in the phone book.” - oh the days when just had to trawl through the printed page of the FT.
Mojomogoz
I am quite bullish but I take your point , which is a good one
Although, the Greens have put several million into Brave Bison (LON:BBSN) in buying their initial stake and in the 2021 fundraise - it is difficult to know what proportion of their wealth is invested here. In the past I went through the accounts of the unlisted Tangent Communications and Portland Asset Management but was not much the wiser.
I do think they know the business and from what I can tell they work hard. I am sure they would like a larger vehicle - but I think that they see Brave Bison (LON:BBSN) as the vehicle that they want to grow. In my mind, I therefore discount any talk about a bigger media group buying £BBSN. I doubt the Greens would want to sell - and as you say the asssets are a bit of a odd mix that the Greens need to work hard to put into a coherent shape - so who would buy them?
I never read too much into LTIPs. But I think it is worth looking at the (comparatively low) salaries of the Greens (and no bonuses) and the LTIP announced in RNS on 20 Dec 2021. The LTIP is arguably very generous but for it to be worth anything the share price has to rise to 3p and was set up when the price was at 1.425p. It starts being worth very meaningful amounts if the share price rises to 5p or 7p. My reading from the LTIP is that the Greens are (maybe) committed at least medium term.
I am only reading the tea leaves - the best we can do as outsiders.
Yes. Good points. I have looked as I think it might be successful...but I run up against my own biases with it so no for me.
The share price going up is the name of the game and if that's through aggressive acquisition to fulfil LTIP targets then that's still a win for earlier shareholders regardless of dilution. TBH I think punters are too anti raising in general...its whats a growth market like AIM is supposed to do
I am a holder of Brave Bison (LON:BBSN) (formerly Rightster Group) and have bought into the idea that Oliver and Theo Green (who acquired a large stake in 2019/20) can turn around this perennial underperforming group. I think the acquisition of Social Club (social media advertising and influencers) makes a lot of sense and is consistent with group strategy. The group is acquisitive and the two Green brothers appear keen to build a sizeable business.
This acquisition follows the acquisition of Greenlight (digital advertising) in August 2021 . Greenlight’s revenues when acquired was £14m. Social Club’s revenues are £13m. Therefore these two acquisitions will contribute approximately 2/3 of the 2023 group revenues. So the group going forward is very different to what they were in the past.
The acquisitions have also made the group much more of an advertising company and de-emphasised the social media content that used to be a key part of Brave Bison.
Despite much of the talk in today’s RNS about growth (and the company often mentions growth), one reason I have held the stock is that the Green’s in reality have kept a close control on costs and cash. Cash at end-2022 was £6.2m, up £300k on end-2021, despite £0.9m being spent on minor acquisitions (Best Response Media).
Brave Bison has embraced working from home culture - reducing property costs at it King’s Cross Office and hiring remote workers world-wide at lower rates than the UK. How this fits in with the Social Club acquisition (which from the sound of the RNS is quite office focused - Manchester, NY and London) remains to be seen.
A bugbear of mine is that in this deal (as in Greenlight acquisition) no offer is being made to existing retail shareholders. As Brave Bison is likely to do more acquisitions - shareholders should expect future dilution.
Hi Paul - do you remember last year (or maybe it was 2021!) you gave a list of your top holdings in order with a short summary and a price target attached? Do you think you will do it again? I found it very insightful
Morning joshwood976,
Yes good idea, I can do an updated list of my own personal holdings. It would be quite easy now, because (as mentioned numerous times here & in my podcasts), I capitulated with my spread bet accounts last year, and closed them. Now I'm just concentrating on ungeared investing, so smaller positions, and less risk. The plan being to just gradually rebuild, rather than shoot for the moon & the stars again, before burning up on re-entry, which is the story of my life to date! ;-)
Actually, let's do it now, it won't take long - my current portfolio, positions in descending size order (so BOTB is my largest holding), with reasons -
Some of these are quite recent purchases, from the proceeds of selling my Seraphine (LON:BUMP) shares (takeover bid in progress, but I gave away the last 3% in order to grab some opportunities where I see more immediate upside (and so far so good))
In size order, largest first -
Best Of The Best (LON:BOTB) - I'm very impressed with the most recent update - interims, reviewed here. Business has now stabilised after the pandemic boom. Cash in bank, pays generous divis/buybacks, fwd PER is only 8.5, so under-priced as it is now. But international growth through Tedi Sagi's 30% investment is the exciting bit, which could transform things for the upside. If BOTB's cautious management don't want to run fast enough, then maybe Sagi might bid for the whole thing? Risk:reward looks tremendous to me, but might need to be patient. Intended holding period - 2 years to begin with, but depends on newsflow.
XP Factory (LON:XPF) - more speculative, but I really like the concept of experiential leisure, and think the Boom Battle Bars concept is a winner. Very rapid roll-out done in 2022. In line recent update. Should out-perform regular bars. I think a consumer recovery is coming in 2023 or maybe 2024, so good upside from a bombed out sector maybe? Some risk, as cash looks tight, but it can safely run existing bars for cashflow (EBITDA positive now), and some are franchised, lowering risk. Great deals from landlords, who prefer this concept to regular bars, big reverse premiums cover most of the fit-out costs. Switched-on CEO.
WANdisco (LON:WAND) - bit of a punt. Mentioned a lot in SCVRs. Something big seems to be happening, with repeated, large contract wins in the last 6 months. Huge market cap for a loss-making co with a terrible track record. 3 out of 5 major shareholders (including shrewdie Richard Griffiths) are adding (recently). So this has credible backers (including USA funds), not a bulletin board ramp. Has amazing momentum at the moment - buyers are catching every dip.
Revolution Bars (LON:RBG) - a recent purchase at 6p. I'm worried about bank debt taken on to buy Peach Pubs, but am hoping that the bank might remain co-operative. Wobbly recent trading at core business, but good at Peach. Tiny market cap is the main attraction here, so just a shorter term trade on trading improving, which could make it return to 20p, a 3-bagger, possibly? Also, energy cost headwinds could become a tailwind, if current trends continue. Horrible sector, might gain market share as competition goes under? So quite high risk:reward here, not for widows/orphans. I've gone into it with eyes wide open, so it won't kill me if they have to do another discounted placing, which is main risk.
hVIVO (LON:HVO) - another recent purchase, covered in SCVR 25 Jan 2023. Readers got me onto this one, and I'm impressed with the latest update, big contract wins, moved into profit. All suggests something interesting is going on here, and claims to be world leader in its niche. CEO seemed a bit over-excitable in recent webinar! But with contracted order book covering nearly all 2023 forecast, looks set up for trading ahead exps updates.
Beeks Financial Cloud (LON:BKS) - a long-standing position, covered frequently in the SCVRs.
Watkin Jones (LON:WJG) - builds student housing, and build to let. Forward-sells projects, so little balance sheet risk. Demand returning from institutions, after wobbles caused by political shenanigans last autumn. Expect soft H1 2023, but after that should do well. Cheap on fwd PER & divi yield, lower margins for a year or two, but that's all baked into forecasts. I think shares could double/triple on a 2 year view.
Portmeirion (LON:PMP) - just too cheap, and performing well. Could be a doubler if things go well?
Cambridge Cognition Holdings (LON:COG) - longstanding position, I remain positive about it, long-term holding.
MJ GLEESON (LON:GLE) - my favourite housebuilder, bounced, but still cheap. Builds very affordable houses that are likely to remain in demand. I'm looking through likely soft patch in H1 of 2023. Could be a doubler, once economy back on track in 2024 or beyond? Amazing bal sht, so no risk, even in a bad recession (looking less likely now).
Oxford Biodynamics (LON:OBD) - just a punt, after they got a placing away at a premium. Low conviction, but small enough to not worry about this holding.
Please don't rush out and buy any of these without doing your own research. In fact, some readers might decide this is a good list to open short positions on, which would have served you well with my main share picks after the market peaked in about summer 2021!
So rather than just buying back my old stuff, I've mostly picked new ideas.
Anyway, I hope that's interesting, and gives you some ideas to research.
I've got a list as long as my arm of other ideas to invest in, so see my spreadsheet here of 2023's best value/GARP watchlist ideas from me - some of which will do well, others won't, which is what I expect to happen. Note the "Speculative" tab is fanning out quite strongly with some doing well, and some doing badly. But the main 2 tabs are up 12% YTD, because we're currently in a bull run for small caps, so they're just rising with the market I think. No stock-picking genius involved, I could have picked anything!
Regards, Paul.
Weren't you already heavy in Revolution Bars when it was trading much higher?
Oh I've held Revolution Bars (LON:RBG) numerous times over the years. Heavy losses mostly. Although I did get most of the losses back with a big position bought at 11p, and sold at about 35p, just before they dropped the bombshell of the second 20p placing, so that was a lucky escape.
I'm not for a moment saying RBG is an especially good business. It's just too cheap right now - so the reason I've bought is because it looks mis-priced, rather than something I want to hold forever. So for me, it's a double or triple my money, then out again trade (if it goes my way). Or lose maybe half my money, if it has to do another placing. Or worse still, can't be ruled out. So a high risk:reward one.
Wow - thank you for this Paul. Will take a further look at some of those names.
Is there any reason you don't own Volex (LON:VLX) or Sosandar (LON:SOS) given you have written very positively about both of them recently?
Is there any reason you don't own Volex (LON:VLX) or Sosandar (LON:SOS) given you have written very positively about both of them recently?
Yes - not having enough money! LOL (I want to concentrate on about 10 shares at the moment, so that positions that work move the dial enough to make it worthwhile)
Fair play to you Paul. I always respect how open you are about your holdings. Am surprised not to see you holding Shoe Zone (LON:SHOE) or ME International (LON:MEGP) which you've spoken of quite highly. I used to hold these until selling out in 2020 when I thought prospects looked bleak, then never got back in :-(
Always interesting to contrast your open view of your investment style versus your view/caution in the SCVR on shares. Maybe quite reflective in that as a long term reader I don't have any holding matching yours. I think mine is a slow and steady, diversified portfolio of >30 shares at the moment.
Hi wildshot,
I've got so many good share ideas, but not enough money to put meaningful money into all of them. So I've concentrated on the share ideas that I think could double fairly soon, about 10 shares, rather than spreading it 2-3% in 30-40 positions, lots of things that might do alright over time.
Regards, Paul.
Thanks for the update on your holding and views, very interesting. I am also a holder of hVIVO (LON:HVO) and like you was a bit put off by the over-excited CEO at the recent presentation. I would prefer by holdings to be run by a sober business head, over an excitable cheerleader!
I like Mo Khan at hVIVO (LON:HVO) and he's a great and sober (!) update on the prior mad pumping CEO tho didn't watch his past presentation! I don't invest as I think its overvalued relative to likely development path (I thought this as 10p...so I was only interested in doing more work on a fall)
Hi Paul, may I ask if you have ever considered the possibility of doing a Stocko webinar based on your research process? (endorsed by Ed of course). I think would be an incredibly interesting watch and probably quite worthwhile for subscribers? Maybe a joint venture with Graham? Thoughts?
This would be brilliant!
Good idea! Maybe that's something I could do once it's quieter in between reporting seasons?
Good morning,
What is the general consensus on house builders post the rate hike? I hold MJ GLEESON (LON:GLE) which is up 25% in the past month and trading with good volume now. Passes 9 Stocko Long Screens and 200 SMA in sight.
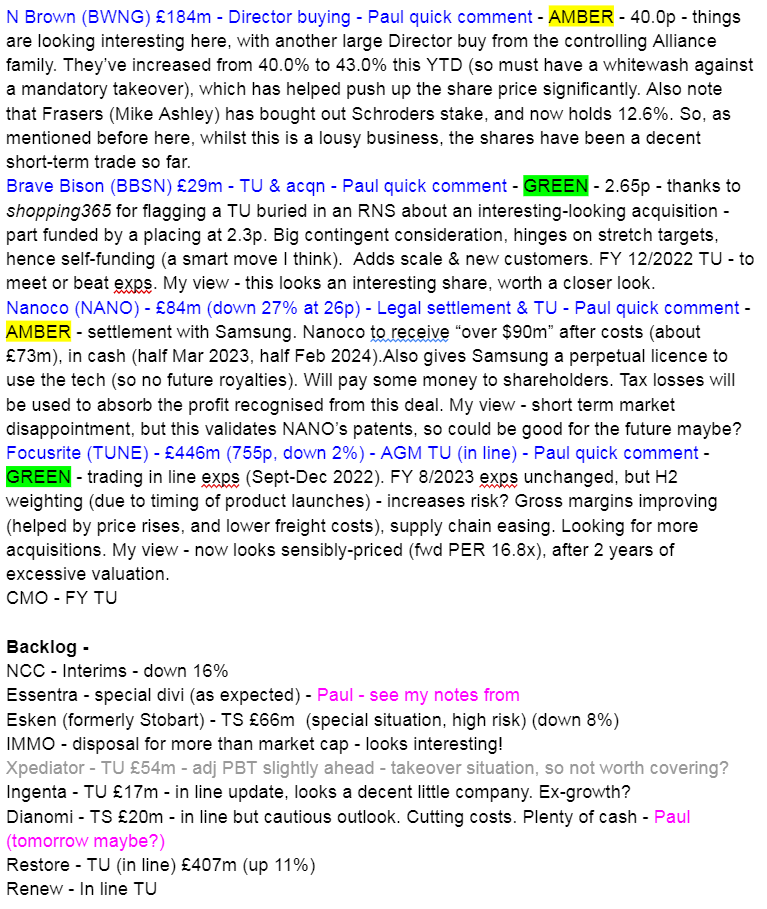
Nanoco (LON:NANO) settlement with Samsung for $150m, $90m net of litigation. Be interesting to see how the company uses this given the settlement is global & includes future royalties
My morning smallcap tweet: I will look for you, I will find you, and I will grill you.
MGC Pharmaceuticals (LON:MXC) Triple Point Social Housing REIT (LON:SOHO) Itaconix (LON:ITX) CMO (LON:CMO) Avation (LON:AVAP), Focusrite (LON:TUNE) Nanoco (LON:NANO)
◄MGC Pharmaceuticals (MXC)► gets $600k funding the $10m Convertible Securities Financing Facility with Mercer Street Global Opportunity Fund, CFO scarpers. She is not thanked. [SP=0.58 Cap=35m]
◄Triple Point Social Housing REIT (SOHO)► arrears reach 8% (0.2%) due to two of 27 lessees. "The Board recognises the ongoing resilience of the Company's portfolio, notwithstanding the sector-wide pressures social housing providers are experiencing." [SP=50.81 Cap=205m]
◄Itaconix (ITX)► £10.3m placing at 5.1p, a 5% discount, for general working capital purposes to support continued revenue growth. [SP=5.5 Cap=25m]
◄CMO (CMO)► guides FY-Dec rev up 9%, LFL 2%. Adj EBITDA c.£2.1m (£3.7m). In line? "Despite the macro-economic and industry headwinds seen in 2022, CMO delivered significant sales growth." But it's less than inflation. [SP=27.5 Cap=20m]
◄Avation (AVAP)► guides H1-Dec rev c.$46m (no comparative given). In fact it's down 23%. Total contracted future lease revenue receivable $509m ($568m). In line? Not helpful. [SP=131 Cap=91m]
[edit]◄Nanoco (NANO)► gets $90m (£74m), less a 'modest' tax liability, from Samsung case, net of $60m fee. Also H1-Jan trading: rev in line, adj EBITDA loss better than mgmt expectations.
In line: TUNE
GOOD LUCK !
Good morning Paul
I would welcome your comments on today’s RNS from Brave Bison which headlined as a statement about an acquisition but also contained a positive trading update. This is a rapidly growing debt free company in the social media space, who gave a very interesting presentation on Mello Monday last year that spurred me into taking a small starter position.
Good morning shopping 365!
Thanks for flagging this hidden trading update, and a relatively big acquisition, from Brave Bison (LON:BBSN) - it does indeed look interesting, I'll put up a brief comment on it next.
Best wishes, Paul.
I am just commenting that I found the Green Bros to be one of the most impressive teams recently at Mello, they are certainly ones to watch. I am beginning to wonder whether this could be a nice opportunity to get on board something exciting at an early stage. I have a toehold, but will be considering whether this could be worth a larger position.
Thanks Mark. Do you (or anyone else) have any links to video webinars from Brave Bison (LON:BBSN) mgt please?
There are several BBSN presentations on InvestorMeetCompany - most recent from September 2022 (interim results).
BBSN I was their room monitor at Mello and despite sitting through their whole presentation & Q & A, I’m afraid I’m still not very sure what they do (suspect it’s my small brain).
However, they do present well and with their PE background know what to say so I’m sure it will do well for you