Small Cap Value Report (Fri 30 July 2021) - TUNG, PDG, LOOK, GETB, EPWN

Good morning, it's just Paul here today, with the SCVR for Friday.
Timing - I'm still plugging away, so intend finishing about 4pm today. Update at 15:39 - all done for today!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Section:
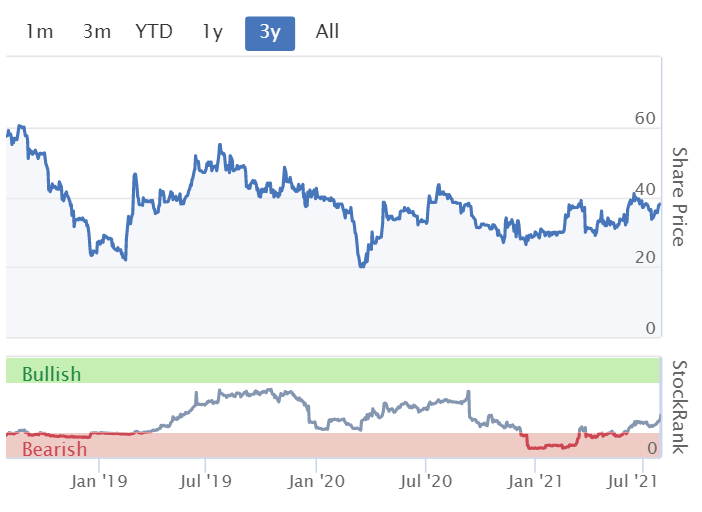
Tungsten (LON:TUNG) (I hold) - I review in line results for FY 04/2021. What interests me here is that cash burn has been almost eliminated, and this software company has big name clients, and 93% repeating revenues. Cheap compared with other software companies, and could attract a takeover bid in my view.
Pendragon (LON:PDG) - another car dealer chain reporting a trading bonanza. Although it's a one-off benefit, from a spike upwards in used car prices, which is bound to reverse at some point. Mentions similar uncertainties for H2 as Vertu did yesterday. The whole sector looks very cheap at the moment, even allowing for profits falling when this current bonanza ends.
Lookers (LON:LOOK) - to complete the hat-trick of strong trading updates from car dealers this week.
Getbusy (LON:GETB) - a quick look at interim results from this small, niche software company. It stays on my watchlist as potentially interesting, but there's nothing in the figures or commentary that gets my pulse racing.
Epwin (LON:EPWN) - a positive trading update from Weds. Looks good!
Tungsten (LON:TUNG)
(I hold)
38p (last night’s close) - mkt cap £48m
Tungsten Corporation plc (AIM: TUNG), a leading provider of digital financial management products and software solutions, announces results for the year ended 30 April 2021
Preamble - I last looked at this software company here on 4 June 2021, when it issued an in line with expectations trading update for FY 04/2021.
Several things have changed for the better at Tungsten - cost-cutting to eliminate cash burn, big name contract win with NTT (Europe), and new CEO who came from NTT (so must have been impressed with the software from a client perspective).
On the downside, TUNG has previously announced that a major client (5% of revenues) has given notice to terminate its contract in FY 04/2023, so a negative hit to profitability is in the pipeline.
Today’s results - for FY 04/2021 look as expected.
Revenues £36.1m (down 2%) - I see this as a resilient performance in a year dominated by the pandemic, and it shows the benefit of having 93% of revenues recurring or repeating.
Adj EBITDA is £3.6m (up 33%) - but this is a fantasy number due to capitalised development spend of £2.4m
Huge loss before tax of £34.6m, mainly caused by impairments (non-cash) totaling £27.9m, and a £3.3m forex loss, and £2.1m exceptional costs. So underlying profits close to breakeven.
Net cash of £2.1m (down by £1.1m in a year) - cash burn now largely eliminated. Also note that, being a software business, its costs are quite flexible, being salaries mostly. This is noted in the going concern section, which says that even in a severe downside scenario, it could cut costs accordingly.
Balance sheet - is weak. I would like to see a top-up fundraising. NAV of £56.2m becomes negative NTAV of £(10.3)m. Working capital looks weak, but bear in mind the company receives cash up-front from customers, like a lot of software companies, so it can operate normally with a weak balance sheet.
Cashflow statement - always useful where the P&L is confusing, and there are lots of adjustments. To sumamrise it, operating cashflow is £2.5m, less £2.6m capitalised development spend, less £1.1m in lease payments. So cashflow as I see (i.e. all the important items) is negative £(1.2)m. That’s not great, but it’s vastly better than in the massive cash burning days of old.
Tax losses - don’t seem to be recognised on the balance sheet. But note the accumulated losses are £164.1m, so if TUNG does become profitable, it shouldn’t be paying any tax on those profits.
Outlook - talks mainly about plans to develop its software, and improve the way the business is run. I can’t see anything specific about financial guidance. Existing consensus forecast shows a rise in revenue to £39.0m this year FY 04/2022, and a move into a small profit.
Bear in mind there’s a headwind coming as previously announced loss of a major customer generating 5% of TUNG’s revenues will be phased out. I’d like to know the reason why the major client is withdrawing.
My opinion - software companies seem to be valued on multiples of sales, which I don’t agree with, but that’s what the market is doing right now, so it doesn’t matter what I think!
Recurring/repeating revenues are highly valued, but not in this case.
The £48m market cap seems strikingly low compared with other similar-sized software companies. TUNG also stands out for having very big name clients, which could be of interest to an acquirer. Therefore my main reason for holding a small speculative position personally is that I reckon it could attract a bid at the current valuation. Proactis took me by surprise in that regard - it was practically insolvent, performing poorly, badly managed, but it attracted a bid at a large premium.
.
Pendragon (LON:PDG)
18.4p (unchanged at 10:12) - mkt cap £257m
Preamble - we looked at Vertu Motors (LON:VTU) (I hold) yesterday, which issued a remarkably large upgrade to profit guidance for the half year, and full year. It seems that car dealers are having an absolute bonanza at the moment, due to arguably one-off factors like supply shortages causing a rise in prices (hence also profit margins), particularly for used cars.
Vertu warned of several key uncertainties in H2 - supply shortages of new & used cars, pandemic disruption, higher salaries. Hence it’s guiding for hardly any profit in the seasonally quieter H2, probably lining things up for another upgrade later this year, is my guess.
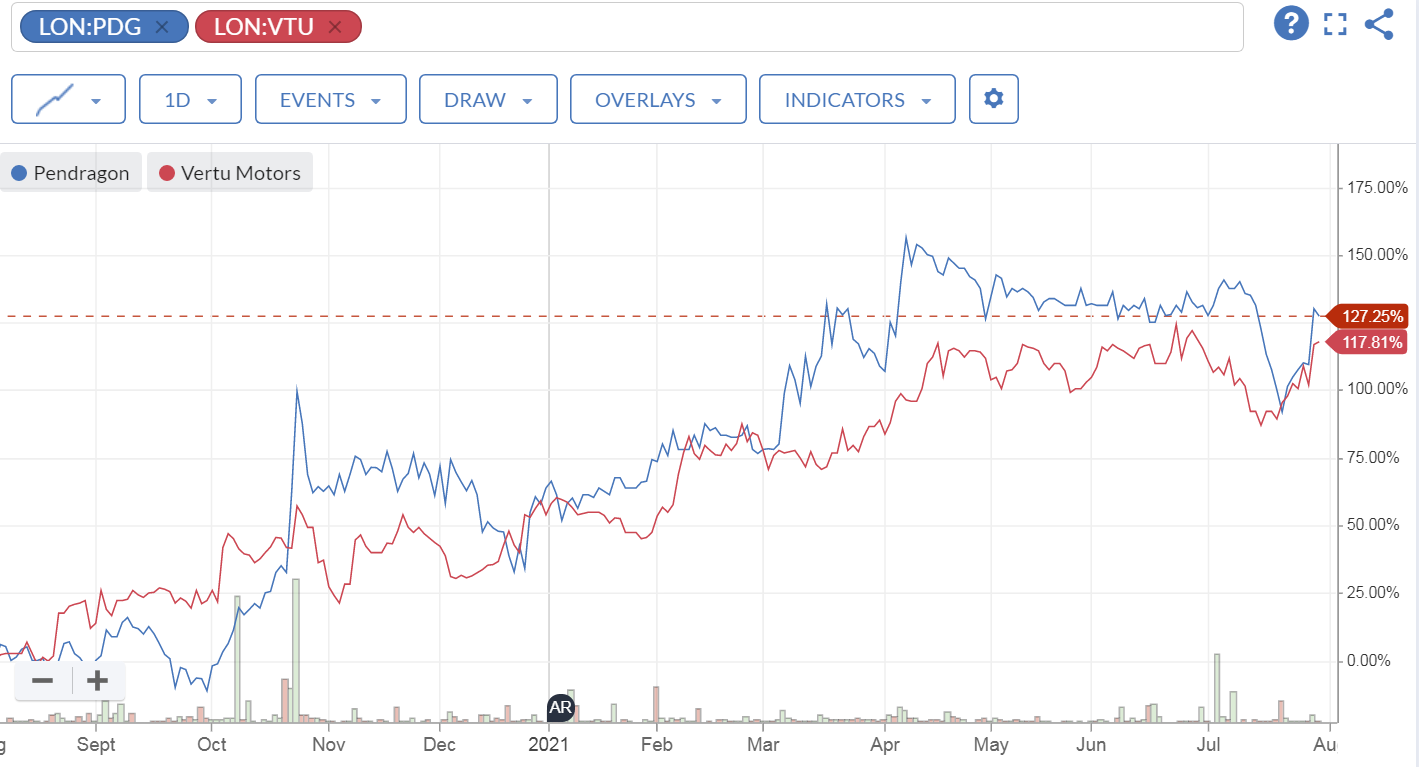
It looks as if the market has already done the read-across to sector peers, because Pendragon’s share price had bounced by a similar amount before today’s positive update. See how closely correlated the shares of Pendragon and Vertu have been over the last year -
.
Today’s update -
Pendragon PLC (the "Group") today provides a trading update and increases underlying profit before tax guidance for the full year to 31 December 2021 to a range of approximately £55m to £60m.
That’s a lot of profit for a company with a market cap of £257m.
Other points -
- Strong close to June
- Continued momentum in used cars in July
- Supply constraints led to “exceptional gross profits per unit”
- “Good levels of demand”
- Achieved good levels of used car stock availability, from broad range of sourcing channels
- Net debt of £46.0m a year ago has been eliminated, with net cash of £9.5m at 30 June 2021
- Outlook - mirrors what Vertu said yesterday - uncertainty on supply constraints, pandemic, and when (not if) profit margins on used cars return to normal
- Guidance - Full year 12/2021 expected to be £55-60m u/l profit before tax.
Valuation - I haven’t seen any new broker updates today. Working on a note from Zeus on 1 July, it was forecasting £46.9m FY 12/2021 u/l PBT. So today’s £55-60m range is an increase of 17-28% - a big uplift.
Zeus EPS forecast was 2.5p, so I’ll increase that by the same percentage, arriving at 2.93p to 3.2p EPS.
At today’s 18.4p share price, the current year PER is 5.8 to 6.3 - dirt cheap in other words, but we are using the 2021 unusual, one-off spike in earnings, which is not really a valid way to value a company.
My opinion - I think the listed car dealers are very similar in most regards. The reason I prefer Vertu to the others, is its stronger balance sheet. VTU trades at around NTAV = 1, so you’re effectively buying the net assets, and getting the business in for free, so it doesn't really matter what happens to profit, as you'll always be protected with the asset backing. Whereas PDG has negative NTAV at the last year end, which is a major difference.
.
Lookers (LON:LOOK)
70p - mkt cap £273m
Another car dealership chain, which reported yesterday.
Lookers plc ("Lookers" or the "Group"), one of the leading UK motor retail and aftersales service groups, today provides a trading update covering the six month period ended 30 June 2021 ("H1" or the "Period") and an increase in the Board's expectations for underlying profit before tax for the full year.
Factors mentioned for the “excellent” H1 performance -
- Continued outperformance of the UK new retail car market - this sounds ambiguous to me, is Lookers saying that it out-performed the market, or that the market out-performed (what? overseas markets?)
- Strong used vehicle volumes and margins
- “Improved hybrid, omni-channel customer experience”, so it claims, for a sector-wide period of strong trading
- Resilient aftersales performance
- Material cost reductions
Guidance - revised upwards to £50m u/l PBT, just for H1. No specific guidance for the full year.
Of this £50m profit, £13m has come from taxpayer support measures. The company really should pay that money back, given its bumper H1 profits, in my opinion. Although you could argue the Govt will get some of it back from higher corporation tax, and other taxes from buoyant trading (e.g. payroll, VAT). Tricky one.
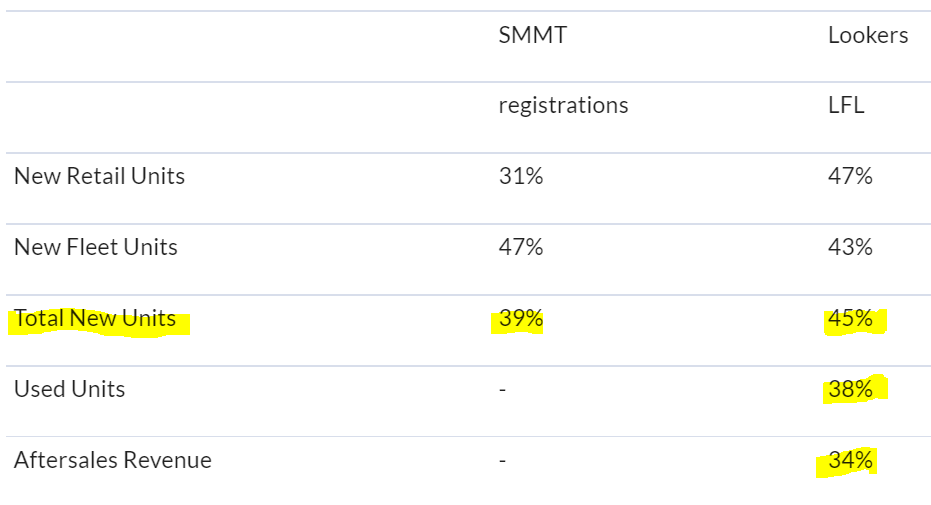
Table below showing out-performance against industry average (“SMMT”). Although comparisons with last year are bound to look good, since that was lockdown 1 a year ago. Still, 45% for new cars uplift, is better than +39% industry average. Vertu and Pendragon didn’t give us this information in their updates this week.
.
Liquidity - ample, and a similar move from net debt into net cash as we saw at Pendragon -
The Board retains its focus on cash management and liquidity. At 30 June 2021, the Group had a net cash balance of approximately £30m compared to net debt of £11.0m last year and £40.7m at 31 December 2020.
Property portfolio is worth £300m it says.
Dividends - intend to resume them.
Outlook - expects FY 12/2021 to exceed previous expectations, but doesn’t provide any numbers on the full year guidance.
Some uncertainty & challenges.
H1 profit weighting expected to be greater this year than previously.
Valuation - many thanks to Zeus for providing an update note today. It’s raised FY 12/2021 profit by 19%, which translates to 12.5p EPS - a PER of just 5.6
That drops to 10.9p in 2022 & 2023, raising the PER to a still very cheap 6.4
I feel Lookers should have a discount to peers, as its shares were suspended for a while, due to accounting problems. Personally I’m not very forgiving about that sort of thing, and prefer to hold a similarly cheap competitor which has not had accounting problems.
My opinion - see what I mean about the listed car dealerships being very similar?
I suppose you could argue that this year’s out-performance is next year’s tough comps.
Overall I find this sector very attractive for the value investing segment of my portfolio, especially now divis are coming back, and balance sheets have been bolstered by the bumper profits this year.
Who would have thought that industry supply problems would send profits soaring?!
.
Getbusy (LON:GETB)
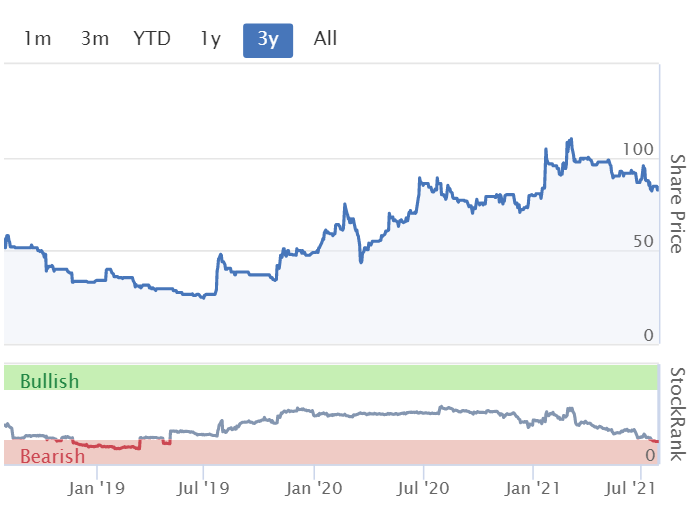
84p - mkt cap £41m
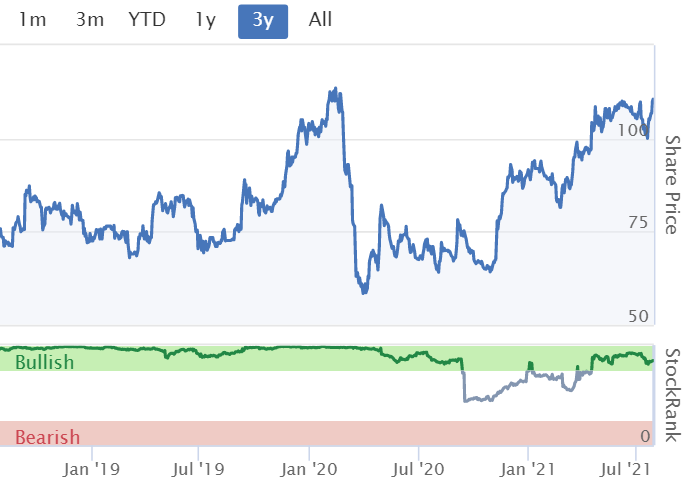
This small group of software companies peaked at about 110p in March, and has fallen back almost 25% from the top - like so many other companies, it amazes me how charts look so similar over the last year.
There’s a half year results presentation on IMC at 11am on Monday (2 August), so I’ll tune in to that, as this company does intrigue me. It’s got some older software (Virtual Cabinet) that is a cash cow, and it’s using the cash from that to develop some new things (Smart Vault).
Smart Vault saw +17% revenue growth (+28% at constant currency) - not bad.
Virtual Cabinet saw flat revenues, and decent profits of £2.1m, up 6%, although I recall they classify a lot of costs as central, which helps the divisional profitability look better.
Overall, the group is still loss-making, at £(949)k in H1.
Balance sheet - quite weak, with negative NTAV and a not very good working capital position.
Outlook - sounds confident -
We continue to see a significant scaling opportunity for our document management business through SmartVault, on which we intend to capitalise. We expect continued strong growth in recurring subscription revenue in that business during H2 and, as we invest in the scale-up, we see an opportunity for the growth rate to potentially increase over the next few years. We look to the future with increasing confidence.
My opinion - I’m keeping this one my watch list, as it’s an interesting niche business. I’m looking for signs that its newer software might reach an inflection point where it begins to rapidly sell. There’s not really any sign of that yet.
.
.
Epwin (LON:EPWN)
109.5p - mkt cap £159m
Epwin Group Plc (AIM: EPWN) ("Epwin" or the "Group"), the leading manufacturer of low maintenance building products, supplying the Repair, Maintenance and Improvement ("RMI"), new build and social housing sectors, announces its half-year trading update in respect of the year ended 31 December 2021.
This update came out on Weds this week, but slipped through the net here on the day. I’ve come back to it, because it looks positive -
Strong trading continues, ahead of previous expectations
- H1 revenues are £157.8m, up 13% on pre-pandemic trading in 2019 (and up 69% on lockdown 1 impacted 2020)
- Supply chain issues continue - raw materials prices continued to rise.
- Selling prices being raised, but lags increased input prices (implying pressure on margins in the short term)
- Net debt of £15.9m at 30 June 2021, a modest 0.6x EBITDA, and £60m headroom - looks fine to me
- Diary date - 15 Sept 2021, for interims to 30 June.
- Outlook - “continues to be favourable” despite supply chain issues
Guidance raised, but no numbers provided -
Assuming that the Group does not experience material supply chain or COVID-19 related impacts in H2, the Board now expects adjusted profit before tax for the full year to be materially ahead of its previous expectations.
Broker update - many thanks to Shore Capital for making its research available to us on Research Tree, that’s extremely helpful.
They have 7.8p EPS this year, and 9.5p next year, giving a PER of 14.0, falling to 11.5 - which looks good value.
My opinion - neutral, as I’m not really up to speed on my research of the company, but the low PER, and positive trading/outlook make this look quite interesting for value/GARP investors.
.
.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

94 comments
If you have a spare couple of hours this weekend (anyone else expecting to sit in a traffic jam on the A303 heading down to Cornwall?) you could do a lot worse than download Robbie Burns/the Naked Trader’s latest Freedom & Sunshine podcast for a listen. Entertaining chat (some of it shares related) and plenty of catchy tunes that will appeal to those of us of a certain age.
https://soundcloud.com/thenake...
Gus.
Cheers for the podcast tip, love the disclaimer at the start!
Read across on Augean bid for Gresham: House Strategic which holds 27% of its assets in the company. Outcome huge after recent wobble for the Trust Managers. No way could they exit this in the market given liquidity in the stock poor. Expect the price to rise strongly on Monday
Re. the read across from the confirmation of the Augean (LON:AUG) bid to its impact on the Gresham House Strategic (LON:GHS) share price, given the latest reported NAV of 1,749p per share was calculated on June 30th when the Augean share price was already at 290p there’s not much immediate upside from today’s bid confirmation as it stands. I agree it gives them a nice clean exit for their 5.8% holding in the company (roughly 6 million shares against an average daily traded volume of about 130,000 shares) but with Augean (LON:AUG) already in play I suspect a half decent broker would have been able to place the shares for them without too much of a discount. Accordingly much of the benefit from the takeover premium may well already be in the Gresham House Strategic (LON:GHS) price. I guess we’ll find out on Monday.
Gus.
Paul
Thanks for your comments on Epwin (LON:EPWN) which I flagged here earlier in the week.
I have a 1% position as a value/UK recovery /inflation play. Eroding the debt as trading improves would provide a nice extra bump to the figures. Additionally this a rather unloved stock by PIs which adds a little more if things go well.
Michael
Augean (LON:AUG) Recommended offer at close of play. Min £2.80. I'm afraid I can't remember who brought this to my attention, but if you are reading this, thank you very much for a 6 bagger!
Must confess to being slightly disappointed by the Augean (LON:AUG) recommended bid at 280p plus a tax claim rebate contingent note potentially worth up to another 20p per share. Felt there was a lot more upside in the company medium to long term and with a running dividend yield on my original investment price of over 5% I was happy to sit and wait. At 45% acceptances and with a board recommendation it looks to be a done deal unless another party (possibly a trade buyer) comes along and offers a minimum 7.5% premium over the Morgan Stanley offer. Still with the aborted Revolution Bars (LON:RBG) bid experience in mind, can’t be too greedy so have to be content with the bird in the hand.
Gus.
The rose-tinted glass view of Boohoo (LON:BOO) story as a growth at any price company is now starting to erode and investors are starting to question its valuation. FCF is very low, the company does not seem to be able to produce much cash, and ultimately it is FCF that creates value.
It is now incurring additional capex to support growth (adding two new sites and enhancing existing facilities – capex for the year in the region of £125m - £175m), and again investors are starting to realize growth comes with a price. Asos (LON:ASC) in this respect is much better, it seems to have incurred growth capex in 2017/18/19 and now its FCF is much improved (until the next bout of capex).
Add ESG worries, questionable family ownership, low margins and £4.99 dresses to the mix. Throw in some Technical Analysis “wisdom” like shareprice below a downtrending 200dMA while the market is uptrending and perhaps the recent sell-off will appear a logical conclusion of the overall market on Boohoo (LON:BOO) ?
DYOR as I have.
QARPY
Boohoo (LON:BOO)
FCF is very low, the company does not seem to be able to produce much cash, and ultimately it is FCF that creates value.
It is now incurring additional capex to support growth (adding two new sites and enhancing existing facilities – capex for the year in the region of £125m - £175m), and again investors are starting to realize growth comes with a price. Asos (LON:ASC) in this respect is much better, it seems to have incurred growth capex in 2017/18/19 and now its FCF is much improved (until the next bout of capex).
strewth - not quite sure what some bods expect from fast growing companies?
In 2019 boohoo turned over 850 mill - 4 years later the sales are expected to be £2.8 billion and they should be making 170 mill a year profit . Its a given this is a monumental investment and cashflow will be poor whilst they are in this phenomenal in this growth phase - the reward is the pots of cash that is thrown off when the investment is fully complete. I am really not sure what some people expect from a fast growing company ?- it certainly doesnt make the company a company a bad investment (IMHO) due to the fact that they are an this investment phase. Ok there may be some execution risk but we cant really knock boohoo on that front with their decent history of growth mostly (if not all?) self funded
+1 agreed.
On the surface, Boohoo (LON:BOO) is a no brainer. You can read through all the positive arguments for it. It is probably the most discussed share on Stocko, and also probably on many other investor forums. It was the top pick for the Stocko challenge I believe at the start of 2021.
Yet, with all that retail interest, and the "Buy" meter on Stocko never below 20% meaning PIs keep buying, the SP has persistently been drifting lower since Feb/Mar.
My finger has been hovering on the Buy button many times, but my investor-spidey-senses always tingle. Can't put my finger on it, but that sixth sense has served me well - I've held off investing in Boohoo so far.
There is usually no smoke without fire, and unfortunately there always seem to be smoke around Boohoo. Still not cheap enough yet for me, even if its trading at a "bargain" 20x, 25x PE.
Yet, with all that retail interest, and the "Buy" meter on Stocko never below 20% meaning PIs keep buying, the SP has persistently been drifting lower since Feb/Mar.
Though if you read timarr's post on yesterday's Boohoo thread that appears not to the case. It looks like it's been retail investors who have been dropping out, and instis picking the shares up from them. Still a large proportion of retail investors in Boohoo (LON:BOO) though.
Stocko figures are not very accurate as they just count stocks on watchlists, does not mean subscribers are actually are buying/selling shares.
Retail investors can buy/sell much faster than institutions due to smaller amounts and quick decision making.
The question here should be: where do i think this Company will be in 5 years time? Short term issues are short term issues, what makes them so attractive is long term travel.
Possibly a stupid question, sorry if so. But does anyone know how the property / land on these car dealers balance sheets are valued? Is it at cost (potentially from when they bought it years ago, and so potentially out of date and (likely) understated), or are they estimating the value each year and reflecting that in the balance sheet? Thanks
I hold Caffyns and they revalue their freehold sites ( all are in this category for their outlets) annually. If the thought is they could be sold for an alternative purpose then clearly they have a greater value assuming PP ( last mile logistics or housing). Have a look at the annual report for your target as this will be covered.
Does anyone have anything to say about ITV? Just asking for a friend.
Hi Bruce
Yes I hold and the recent results were OK. Good to see advertising revenue coming back strongly It is a typical ' value' investment given it intrinsic link to the UK economy. I bought for the div of which there is still none but at least now the prospect of one. It is on my long ' sell ' list to be honest although I am content to hold at present as it just looks too cheap if you are a value bull. Britbox is doing OK but not shooting out the lights and the studio activities just about recovering from COVID .The sum of the parts is worth far more than the whole here so a break up bid is possible but I think not a huge odds on bet. ITV needs a good roster of programmes to keep advertisers happy so Love Island x many is needed!
Hard to see the business growing dramatically in truth but it is pretty lowly rated at present. I would not be adding to my holding any time soon
Many thanks, Martin. That is a very clear account of what I was ‘feeling’ about ITV, but unable to articulate. Much appreciated.
I also had a look at Itv (LON:ITV) yesterday. It has gone onto my watchlist. Same as Martin says, they still get vast majority of profits from TV ad revenue, so having a view on that is critical.
Then there is ITV Studios. Growing fast, and wonder if potentially one of the big media streamers might make a play to buy it for its catalogue. The flip side, is if Netflix, Amazon Prime, etc decide to cut back their content budgets.
All the other stuff like Britbox is still too small IMO to see if they have potential.
I have set a buy target price myself which is quite a bit lower than the current share price.
I have resisted commenting here on a large cap company beginning with B because we have been asked not to and have started a thread over at
https://www.stockopedia.com/co...
However I do thing that as someone has pointed out in another comment, people want to discuss stocks, they want opinions, information etc on why a stock has declined (or increased) in price and are probably seeking reassurance that their investment is not a mistake.
The SCVR is probably the only place where a comment will gain traction and bring, if about a company of interest to subscribers, a good number of comments and opinions.
I am not sure what the solution is. Perhaps a discussion section below the news section on the Stockopedia home page, showing the latest threads by date or company.
Personally I would be happy to see any company, of whatever the size, discussed here, but that does not seem to be the general wish of most of the people who comment and I am more than happy to abide by the wish of the majority.
That said I hope Paul might pop over to my thread and leave a comment about B..... though I suspect he just re-iterate that this is all noise!!
Regards
Michael
One solution could be to start a dated "Daily Thread" where any conversation is allowed. People will start to post daily news bits in there, ask questions about events of the day etc and hopefully, it would become the "go-to" place for more generic comments, rather than here in the SCVR.
I think we need discussions on mid and large caps too. You have my vote.
The Forum belongs to subscribers so I think you discuss any stock you wish to.
BSV
The clue is in the name, SCVR!
agreed
SubsCriber Voice Rally
PIWORLD interview with Andrew Hollingworth. Topically, he is bullish about £BOO. Lots of reference to Buffett and Munger. We learn how he views current markets and what he's buying and selling. Includes Young & Co's Brewery (LON:YNGN) Easyjet (LON:EZJ) Jet2 (LON:JET2) Boohoo (LON:BOO) Vp (LON:VP.) Frasers (LON:FRAS) & lots of international holdings - how does he cover so many markets?! Video & podcast.
Creightons (LON:CRL) full-year 2021 results presentation including 2024 aspirations. A superb management team executing well. (Sadly, the acquisition didn't get completed for them to expand on this during the webinar.) Video & podcast.
Thanks for the Creightons (LON:CRL) presentation Tamzin. The management are extremely open and their presentations are usually more important than their RNS' - which is helpful for those familiar with the company but maybe it would be helpful if they included more commentary in their formal results for newcomers to the stock.
A few key things I took away:
(I don't hold as I sold on results day after realising what a large amount of revenue hand hygiene delivered)
£Boo is a separate thread on here and you guys knocking this great British Co, remember this. Did your grannie own a house over a long period?. Did she write about it when a headline stated, 'house price to crash' Of course not, she just held on to her house and made a fortune?. Forget all the noise, its garbage, and short-term noise, so close your ears to it and move on.
Do you have a link to that separate thread?
There are several but this is probably the main one: https://www.stockopedia.com/co...
No not forget the noise, its garbage, thats the words of someone just ramping, listen to what others say even when its a different opinion to yours and make an informed decision
What are you on about.. There are too many sensitive soles on here like you.. I read all that is written here and some of what is written are in my view GARBAGE.
I am not ramping but supporting a great British business, where the owners have skin in the game if you see that as ramping. Tough
Take care everyone, sensitive soles can be a symptom of type 2 diabetes.
https://www.thediabetescouncil...
What are you on about.. There are too many sensitive soles on here like you.. I read all that is written here and some of what is written are in my view GARBAGE.
I am not ramping but supporting a great British business, where the owners have skin in the game if you see that as ramping. Tough
More negative news about exploitation of Muslim women in a UK garment factory in the 1pm News on telly today. Something about being paid the Minimum Wage and then privately required to hand most of it back so as to circumvent the Law. I may have misunderstood due to hearing problems unattended to by the NHS during this Covid period.
I think the forum/discussion section needs looking at so that threads can be made and kept visible more easily, it seems completely random how it works and the "date" bit makes everything look old and outdated when its not, but nobody ever seems to say anything.
The reason the SCVR always gets spammed with other stuff is that its the only thread that ever seems "current" .
The system needs a revamp, more of a reddit style message board with the latest clearly at the top with the date based on recent comments, not the OP date.
People seem like they cant be bothered to make a new thread for a topic such as "boohoo drops on continued ESG fears" because they know 90% of people wont see it and all the discussion will just end up happening in the SCVR
Jup, very likely to big for small cap,maybe market starting to price in peak Aum( £60bn),one item that stuck out fees up £60m,"while most of the world struggles", paul as much as we would hate to lose you have you ever considered fund management where you get paid handsomely for mediocrity.
Would be interested to get one of the chaps thoughts on Jupiter Fund Management (LON:JUP): at some point loads of take overs and mergers going on in this sector at the moment with Charles Stanley (LON:CAY): being the latest to get bought out yesterday.
Jupiter have been failing on the execution strategy since joining up with Merian but a lot of people think its one of the top targets for private equity or a larger fund house to acquire.
Would welcome the thoughts good or bad of anyone more clued up than me.
Regards Andy
The latest memo from Howard Marks is out today. It's been long overdue. Well worth the reading time of everyone IMO.
https://www.oaktreecapital.com...
Forget trying to predict at a macro level, and ignore economists, as part of your investment process, basically. Preaching to the converted with me but some other may find his thoughts challenge their opinion of their own skillset.
Sorry to interrupt the Boohoo thread...
All the best, Si
Marks says that the most important rule in investing is to remain fully invested unless there is compelling contrary evidence. But invested in what? Stocks? Bonds? Cash? Commodities? Property? ...
Someone running a stock fund, or a bond fund etc. doesn't have to make that decision because it is made for them. Everyone else does - though many make the decision without knowing that's what they're doing, or why. Anyone who thinks the best answer is always 100% UK small caps, or even 100% equities, should do some more research.
That asset allocation investment decision is more important than any decision about specific assets within any asset class and making that decision involves assumptions about the macro environment.
Those assumptions may be explicit or implicit but they will be there. Asset allocation decisions rest on the probability of macro outcomes.
Thanks for posting a very interesting link. But I firmly believe as follows:
Fund managers are unable to time the market because they are unable to trade at sufficient volume without creating large adverse share price movements. So they keep chanting the mantra that "It is time in the market that counts, not timing the market" This is because they want to continue to keep collecting fees from their customers without any nasty interruptions. However, it is possible for a skilled private investor to time the market because they are trading smaller volumes. To do this one needs to keep paying close attention to the markets, and be ready to sell everything in a hurry. It also leads to rather short term outlook. But it can be a very successful approach.
Tungsten has a record of consistent and large losses, these appear to be unaudited accounts and I can see no fixed assets of note. £48mn market cap seems a more than adequate valuation on what we know, which is very little.
To move away from discussions on £1 billion plus companies ...
For anyone interested in the discussions on Made.com (LON:MADE) and Everyman Media (LON:EMAN) yesterday there were a couple of really interesting posts by abtan on them late in the day, which people may have missed:
https://www.stockopedia.com/co...
Both look interesting to me, although if the post lockdown slowdown in house purchasing continues we may see MADE at a lower price yet.
timarr
Everyman Media (LON:EMAN) + OT Inside info is actually in the public domain
Cheers for that timarr - i always higly value abtans input - havent looked at Everyman Media (LON:EMAN) before but it certainly looks interesting - the following stat left me slightly gobsmaked as to how much cash each venue can bring in - certainly makes me want to do some further research as i do like cash money making machines!
Ref Everyman Media (LON:EMAN)
Each venue, on average, generates £1.2m of gross profit per year.
OT - Inside info is actually in the public domain
One other very interesting point raised by abtan (might not have been in yestrdays post but i only spotted it yesterday) that i had missed previously was that it appears google can keep tabs on card income being booked by all businesses to a certain degree (this doesnt seem right from a privacy point of view IMHO - but pracicably spekaing they are working backover from non perosnalised data) they then sell this info onto hedge funds et al. It should be reasonably easy therefore for bods with this info to potentially have a handle on current trading before it is announced to the market - this data may not be totally reliable but any edge is a edge and if someone can see trending card sales data compared to prior years and i cant i fear i am investing blind unless i do so soon after trading updates. I have not been averse to buying on price drift on no news previously - but for companies reliant on card sales (eg boohoo) i think in future i will now only buy after a recent update so i am not missing out on important inside info soon to be announced.
This sales info is one of the main reasons that payment processing companies like ADYEN et al are so valuable.
google can keep tabs on card income being booked by all businesses to a certain degree (this doesnt seem right from a privacy point of view IMHO - but pracicably spekaing they are working backover from non perosnalised data) they then sell this info onto hedge funds et al
Not just Google - the big card companies (Visa, etc) have a major slice of this data and there are other players in the payment ecosystem who have access as well. Remember Google only have a slice of online data, there are lots of other channels - in store, via app, via Apple etc - that they don't have.
But if you're a wealthy fund you can buy access to multiple sources, merge the data and get your elite university computer science graduates to run their algos to identify the next turn in the market. The idea that private investors can outsmart institutions with large companies is risible, to be honest.
Once a company gets on the major institutions' radars - over £1 billion, roughly - then you're fighting nuclear weapons with pitchforks. Private investors have two edges over institutions - the ability and willingness to invest in smaller companies and patience, lots and lots of patience ...
timarr
Agreed £made looks interesting but price still dribbling down so still waiting for a good entry point
I have become quite interested in Made.com (LON:MADE) since Richard Leonard "pitched" it on the PI World interview as Paul points out in his reply to a comment yesterday:
https://www.stockopedia.com/co...
it is loss making but it does appear to be growing pretty rapidly. I to have an aversion to loss making companies (all my holdings are profit making and as far as I can tell, apart from Volex (LON:VLX), debt free).
Of course if you can find the next currently loss making company that ends up having say 1% current mkt cap of £AMZN, then you have a company valued at $13,000,000,000.
Made is down again today but I am not yet tempted.
Regards
Michael
Circling back to earlier in the week I've just looked at Moonpig (LON:MOON) 's maiden results following its IPO. This is a greetings card company which operates online in UK and Netherlands (with a smaller, growing presence in US and Australia). I know people will complain about low barriers to entry for greetings card companies etc but I am quite fond of Moonpig (LON:MOON) as it has good, customisable products (I can insert my niece's face into a racing car on his birthday card) and has quite a good brand. It has 27,000 different cards to choose from and works with key brands - including I see Team GB.
At IPO I thought it looked a bit pricey given there will have been a COVID benefit and the company does say they expect buying patterns to normalise so I have been waiting for this to decline in price. I like that they have given quite clear guidance for FY22 of £250-260m which by my calculations will translate to adjusted EPS of about 11.7p (they tend to make 20% adjusted PBT and then I've taken another 20% tax of which the company says is their normal expected tax rate - so say £40m profit after tax for FY22?). The company advises it expects mid-teens longer-term growth.
Current ratio is 1.17 which is OK but could be better for a capital light business? At 377p today I'd like to wait until it's a little lower before I'm comfortable buying - especially as the IPO documentation didn't put much emphasis on driving international growth - but it's firmly on my watchlist.
I have this ( hopefully temporary ) fixation that anything Kate Swann is involved in tends to turn to gold until she leaves ( e.g SSP) I have been watching Moonpig ( review in IC this week). The bear case being that those who used on line will all return to physical shopping is not clear to me ( if so is there a read across to Card Factory?) Both the bull and bear cases seem pretty equally balanced at this time. I think they offer customisation that CF and its ilk cannot but the jury remains out on whether this is just some COVID lockdown induced fad. I would see cost as a pretty clear catalyst for card buyers so were CF to indulge in pricing to recover its market share then MP would be perceived by Mr Market as a loser. You need to believe that the MP platform can leverage other more high margin types of product for the gift market to justify the current share price. I like the business model but it I concur with Patrick that it is over valued at present. A little more tilting towards ' value' will see this type of stock drift lower!
Boohoo (LON:BOO) Beyond the noise, we can now pickup a wonderful growth company at under 20x forward earnings.
Brokers seem to be trimming forecasts very slightly since Asos (LON:ASC) update. Even so, looks good risk/reward for anyone with patience.
Boohoo (LON:BOO) is getting hammered this morning. Down another 7%.
I will sit tight but it is frustrating. I am hoping they will deliver some really good news at some point.
The question is will it remain a growth company if the brand becomes tainted by all these stories, which are unlikely to stop anytime soon. Rightly or wrongly the press have clearly got the knives out for them. Perhaps they could changed their company name to Debenhams whichever would be a bit less toxic?
"the brand"
It's many brands. Only those interested in share markets will know just which brands Boo own.
Absolutely and also I doubt the demographic that is currently driving Boohoo (LON:BOO) sales will read this news or (rightly or wrongly) be bothered by it if they did.
Just listened to Andrew Hollingworth’s views on Boohoo (I hold) on the latest PI World video, excellent balanced view IMO. Many thanks to Tamzin and PI World for these excellent very informative productions.
Thx Mark for pointing out that Andrew Hollingworth gives his views Booldemort, it who must not be named.
Video can be found at
Regards
Michael
Boohoo (LON:BOO) Is there not a problem with BOO's business model in that it delivers supplier prices that can only really be delivered from suppliers in low cost countries. It is never going to work in Leicester. Paying the UK minimum wage is too much ?
Or is it a productivity problem ? Only a very few UK suppliers can work with the prices offered by BOO ? Is this going to change only when BOO gets it's state of the Art factory up and running - ie they in effect cut out third party UK suppliers.
Boohoo (LON:BOO) Ah sorry. I think this is on the wrong thread now
I wonder whether Boohoo have a sustainability issue. Listening to the radio the other day they covered a movement to buy second hand clothes, which seemed to be gaining momentum. If second hand becomes cool, where does that leave Boohoo?
before clothes can become second hand, they have to be first hand...
Nothingventured,
"Second hand" has been rebranded to "vintage" and has been cool for a few years now. There are many reasons why I would not buy Boohoo, but this is not one of them.
Surely investment in your infrastructure rewards you with better margins? If you're running your own factory and cutting out the middle /third parties, you're adding their previous margin share to your own.
And you're controlling the quality, pioneering standards, building your team and allowing rewards for staff loyalty and other incentives.
Preparing your infrastructure for the next stage of growth is what ambitious yet smart companies do.
We often talk about coffee can shares. One holding I have done well with is Ally Financial in the US. The chart speaks for itself. They have done well at attracting bank deposits which provide cheap funding for simple lending products such as vehicle finance.
Off topic, but as it is a quiet morning, worth a mention.
My morning smallcap tweet:
ImmuPharma (LON:IMM) Total Produce (LON:TOT) Pendragon (LON:PDG) KRM22 (LON:KRM) Proton Motor Power Systems (LON:PPS) AIQ (LON:AIQ) Airea (LON:AIEA) Hornby (LON:HRN)
Immupharma (IMM) CEO and 2 NEDs scarper. They are thanked. [SP=8.71 Cap=22m]
Total Produce (TOT) merger complete. Holders will get Dole shares. [SP=165 Cap=NA]
Pendragon (PDG) hikes FY(Dec) U/L pretax range to £55m to £60m from £45m to £50m only a month ago. [SP=18.4 Cap=257m]
KRM22 (KRM) three-year contract extension with a tier one customer, increasing ARR of £0.4m PA up £0.15m. [SP=35 Cap=10m]
Proton Motor Power Systems (PPS) further to the MoU with Electra Commercial Vehicles it has now received an initial order for a fuel cell HyRange system. [SP=44.09 Cap=341m]
Aiq Limited (AIQ) H1(Apr) rev a miserable £12k (£25k). "As a result, due to the impact of the pandemic in Malaysia in the first half and the early nature of the business in Hong Kong, the Group continues to anticipate that revenue for the year to October will be lower [YoY]." [SP=6.09 Cap=7m]
Airea (AIEA) H1(June) rev up 5% and pretax £464k (-£54k). No div. Outlook "The UK sales recovery is expected to continue with a strong order book, however the impact of lifting lockdown restrictions is unknown and so forecasting sales performance in the second half is particularly difficult." [SP=36.66 Cap=14m]
Hornby (HRN) pays £1.3m for the remaining 51% LCD Enterprises (majority owner of Oxford Diecast Group) from the CEO and wife. [SP=46.15 Cap=77m]
Boohoo : 2 bad news today. Would be nice to here your view on this Paul. Thanks.
Hi Pavel, I can't see any news in my RNS feed, did something happen this morning?
Hi Carvalio. News came out last night on Sky about workers in factories in Leicester being paid less than minimum wage. Boohoo was mentioned but not linked. Not great news though!!
Thanks Simmo
https://news.sky.com/story/how...
"There is no suggestion Boohoo know about this practice."
"The couple say before Boohoo inspected the factory she was earning £5.50 an hour and this new system began after Boohoo insisted that staff were paid the minimum wage."
Boohoo (LON:BOO) seem in the clear here, its the same as my employer asking for cash back, I wouldn't hold a customer responsible for my employers actions, I suspect any audit will stop at pay slips / published accounts.
That said, this will be a breach of suppliers rule and result in a termination, so a good test for the new regime in my view.
And there are news from USA court - they ordered Kamani to testify by video call before August 15
It seems Boohoo (LON:BOO) low price fast fashion is still dependnent on underpaying people. You could say they are unaware of or aware of the situation, but still responsible in some way for how much they are willing to pay for the contracts. It seems like Boohoo (LON:BOO) business model is broken without underpaying people for less than the minimum wages, and the ESG policy is not worth the paper it's written on.
One I would sell now and ask questions later.
BSV
Boohoo Group has severed ties with over a 100 garment factories after a sweeping review of its supply chain in the UK.
In its second Sir Brian Leveson-led report investigating its supply chain, the retail giant published a list of 78 approved manufacturers operating across 100 sites in the UK, meeting a commitment for increased transparency.
Boohoo (LON:BOO)
Bluesky Ventura
It seems Boohoo (LON:BOO) low price fast fashion is still dependnent on underpaying people
I would totally refute this accusation- boohoo has great margins and will do just fine in that they can relatively easily absorb any pass through price increases that may occur - the marginal extra cost of labour is not particulrly material in the overall scheme of things - thats IMHO other may disagree. They also have the option to not produce stuff in the uk if goods do become too expensive to produce in the uk. You have a valid point about taking reponsibility here - but that area is a fine line in that like any other business ultimately they want to pay minimum price possible without breaking any rules - that discussion has been done to death here and its well flagged up what they need to do in that area going forward and they know fine well they are being closely watched. More of an issue today is the US legal wranglings - IMHO the US authorities are not be messed with , perhaps bohoo need to pay a wad of cash to make this issue go away which isnt exactly great for shareholders. I would be slightly nervous about Kamani being quizzed on the record - particulalry if its a fair cop what has gone on and its directly come from him!
It does make one wander if boohoo is now big enough to stand on its own two feet without Kamani in charge - i feel they are thankfully less reliant on him than they were back in the day.
Boohoo (LON:BOO) I would totally refute this accusation- boohoo has great margins.
Typically Next (LON:NXT) operating margins are 20% compared to Boohoo (LON:BOO) at 7%. Boohoo (LON:BOO) margins, which are not so great and don't seem to be improving over time.
As Alway DYOR to sure of the facts.
BSV
Next (LON:NXT) operating margins are only 12% now, there is no growth in their own brands but in other brands such as Boohoo (LON:BOO) that they now stock, maybe that is why their margins have fallen so much?
Hi Herbie47,
Next (LON:NXT) operating margins
2015 - 20.07%, 2016 - 20.88%, 2017 -20.16%, 2018 - 18.76%, 2019 -20.18%, 2020 -20.02%,
2021 operating margins are 12.63% with stores closed and sales decline 17%. soon to recover to 20% if the store stays open.
Boohoo (LON:BOO) operating margins
2015 - 7.58%, 2016 - 7.67%, 2017 -10.27%, 2018 - 8.23%, 2019 - 6.98, 2020 -7.45%.
2021 operating margins are 7.11% after competition shut down and sales rally 41%, Don;t see how margins can improve for this company.
BSV
Boohoo (LON:BOO)
Typically Next (LON:NXT) operating margins are 20% compared to Boohoo (LON:BOO) at 7%. Boohoo (LON:BOO) margins, which are not so great and don't seem to be improving over time.
There are different ways to make money in business - i must admit Next are gold standard in everything they do - Boohoo are more along the old Mike Ashley route of pile it high and sell it cheap so they aren't really directly comparable IMHO. You are correct though in that with lower margins in theory they are more at risk if costs go up without being able to be passed on - so you could be right that this may be an issue that i am ignoring.
I look at the simplistic facts of how much an extra £2 an hour say in labour costs for bottom end bods would add to each item of clothing. If we say they say they process no less than 10 items per hour - then that increase is 20p per item of clothing - if that item retails at an average of £10+vat - then IMHO a price increase of 20p would hardly even be noticeable to the customer. Obviously those 20p's do potentially add up somewhere in the overall picture - however as they are at present expanding still at a decent lick - its not all about maximising current margins - the longer game is building up large enough customer bank that you can really pimp out when the business matures. Even with these lowish margins net profit 2019 was £43 mill and is expected to be £171 mill next year - thats the main figures i look at and say boohoo is doing very nicely with regard to the most important numbers that matter as things stand.
Boohoo (LON:BOO)
"I look at the simplistic facts of how much an extra £2 an hour say in labour costs for bottom end bods would add to each item of clothing. If we say they say they process no less than 10 items per hour - then that increase is 20p per item of clothing"
I certainly believe this to be the case and I believe Paul has previously said much the same thing.
Regards
Michael
BSV
Yes Next (LON:NXT) may be a good (great?) company but that doesn't make a good investment.
The stock is currently back at the price it was in October 2015, having been below that level in the intervening period.
Regards
Michael
MichaelFBS
Next (LON:NXT)
but that doesn't make a good investment.
The stock is currently back at the price it was in October 2015, having been below that level in the intervening period.
I think generally Next has probably been a good investment for most people who still hold. Ok a small subset of bods may have bought at the peak 6 years ago - but for most of the last 5 years the price has been significantly below where it is now - so i am guesing the vast majority of bods posting here who have bought next will probably have done quite well out of it. With ups and downs though there can be a luck of the draw element to it. I must say i am slightly biased having gota decent increase from 4k to 7k whilst i held. I giess with numbers we can always pick the data that suits us
Yes and Boohoo (LON:BOO) is at a price it was back in 2017.
BSV
BSV
"It seems Boohoo (LON:BOO) low price fast fashion is still dependnent on underpaying people."
Could you explain what evidence you have for this?
From what I have read everything points to the exact opposite. That is that the model is not broken by having to comply with minimum wage legislation.
Regards
Michael
Just Watch the news.
BSV
Boohoo (LON:BOO) same here carvallo- what news? The only news I can find is Simply Wall Street suggesting yesterday it is undervalued by 25%.
https://finance.yahoo.com/news...
Thanks Simmo 1a. I see the Boohoo (LON:BOO) item now on Sky News
That is reassuring about £BOO as I am 25% down. :-)
News stories B..... are at:
Reports today that Kamani has been ordered to give evidence in U.S. fraud case.
https://www.bloomberg.com/news...
and Sky News article:
How workers in Leicester's textile industry are still being exploited
https://news.sky.com/story/how...
My separate post on B... is athttps://www.stockopedia.com/co...
Regards
Michael
Would be helpful if you said what this bad news was - can't see anything obvious
https://www.businessoffashion....
Boohoo (LON:BOO) Despite much protestation from Boohoo PLC Chairman, Mahmud Kamani, the Federal Judge in California has ordered that Kamani must appear via video conference for a four-hour deposition on or before 15th Aug 2021.
There may be a read across from the sexual harassment claims of suppliers of ASOS on the front page of the Telegraph. the slightest ESG problems in the fast fashion world always hit Boohoo (I hold) hard even if it has nothing to do with them.
Good morning. I am not sure if it was mentioned yesterday but Oakley Capital Investments (LON:OCI) announced it's NAV is now 445p per share. They base this on the current EBITDA at the same multiple they bought the individual businesses within the portfolio. When they sell a holding it is always in excess of that because they have a longer track record of growing earnings.
Current share price is 354p offering a discount of over 20%
Oakley Capital Investments (LON:OCI) have also announced they will be commencing a share buy back of 2 million shares.
There is a good presentation to view. They present OCI after 35 minutes:
https://www.piworld.co.uk/company-videos/lpec-listed-private-capital-part-2-featuring-bmo-global-am-cvc-credit-ptns-oakley-capital/
Their track record is excellent. I hold this and will continue to do so in the long term.
Hi Camraid - we very briefly discussed Oakley Capital Investments (LON:OCI) in the comments a couple of days ago when they announced results. There's also a good presentation from them here on InvestorMeetCompany which they gave yesterday. I hold.
Thank you gwilli68 - apologies for any duplication