Small Cap Value Report (Thu 29 July 2021) - VLX, WATR, EMAN, HEAD, TPFG, VTU

Good morning, it's Paul and Jack here, with the SCVR for Thursday.
Timing - today's report is now finished.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research) - don't blame us if you buy something that doesn't work out. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Section:
Volex (LON:VLX) (I hold) - an encouraging trading update for Q1, "slightly ahead". Some potential headwinds are mentioned, more generic than company-specific. Valuation looks reasonable. Remains a "coffee can" holding for me.
Headlam (LON:HEAD) - I'm feeling a bit smug about this one, which has panned out exactly as predicted here - broker forecasts were way too low (fairly obvious, it has to be said), and divis are resuming. Still good value.
Vertu Motors (LON:VTU) - astonishingly good H1 guidance announced today, with car dealers seemingly enjoying a bonanza, driven by buoyant used car prices. Although this looks a one-off, exceptional effect, but even on a more cautious outlook, this share looks outstandingly cheap. And it's fully backed with freehold property as well. Very attractive value share in my view. Potential for takeovers?
Jack's Section:
Water Intelligence (LON:WATR) - very strong momentum here and the group remains upbeat about a global opportunity. Valuation remains high but over the longer term this company can continue to grow.
Everyman Media (LON:EMAN) - premium cinema operator is making its way out of lockdown and looks ready to continue taking market share, but the stock is illiquid and pricey.
Property Franchise (LON:TPFG) - trade has rebounded strongly thanks to government initiatives and generally favourable conditions. This might turn at some point, but the group has a resilient and cash generative business model and is modestly valued with scope for long term growth.
Paul’s Section
Volex (LON:VLX)
(I hold)
340p (at yesterday’s close) - mkt cap £540m
Volex plc (AIM:VLX), the global manufacturer supplying power products and integrated manufacturing services, is today holding its Annual General Meeting. At the meeting, Executive Chairman, Nat Rothschild, will make the following statement on trading for the three months ended June 2021.
- Strong customer demand has continued
- Consumer electricals “remains very strong”
- Electric vehicle revenues “continue to grow”
- Medical & complex industrial technology - seeing a “healthy recovery”
- Recent acquisition (DE-KA, in Turkey) “continued to trade well”
- Outlook - potential impact on trading from - supply chain shortages, cost inflation of materials, freight challenges, and the pandemic
- Key point - increased price of copper has been “successfully passed through” to customers
- Robust cashflow in Q1
- Acquisitions - pipeline is being advanced, helped by financial flexibility
Guidance raised -
Overall, whilst still early in the year, the positive trends in the first quarter lead the Board to expect to deliver full year underlying operating profit slightly ahead of current market expectations1."
1 Latest company compiled view of market expectations shows an underlying operating profit consensus of $50.0m with a range of $48.9 million to $51.0 million.
Valuation - remember that results for FY 03/2021 benefited from an unusually advantageous tax charge, hence EPS will fall this year, despite pre-tax profits forecast to be up about 20%.
Stockopedia shows a consensus of 24.6c, so that’s probably likely to rise to about 26c after today’s update. Divide by 1.39 to go from dollars into sterling, that’s 18.7p EPS.
(EDIT: an updated note from Singers has just come through via Research Tree, they've up current year forecast to 26.5 US cents. So my guess at 26 cents is very similar. End of edit).
At 340p per share, the PER is 18.2.
We also have the likelihood of more acquisitions to boost earnings further, which should be possible without issuing fresh equity, because the balance sheet is strong, with only negligible net debt reported at FY 03/2021 - here are my notes on those results.
My opinion - this company is a class act, and remains one of my core, long-term holdings. Management with a major equity stake, are doing a terrific job. There are also industry tailwinds from electric vehicles, and the 1-2 year replacement cycle of cabling in data centres.
Today’s update confirms my view that this is an excellent company, reasonably priced, trading well, and with a successful acquisitions strategy.
Plenty to like here. The price doesn’t look stretched at all, despite having almost quadrupled in the last 2 years - performance has fully justified it.
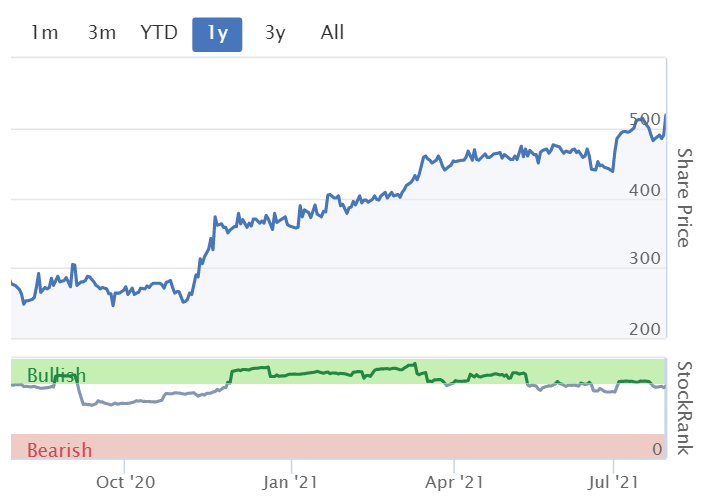
I’m not sure why the StockRank has been falling of late.
.

.
Headlam (LON:HEAD)
524p (up 7% at 08:25) - mkt cap £447m
Annoyingly, I don’t currently hold this one, as my position was in a spread betting account which got the mother of all margin calls in the recent flash crash, so I was forced to close something. Was hoping to buy back in, but looks like I’ve missed the boat now, with this positive update today, drat.
It’s playing out exactly as indicated here previously - i.e. broker forecasts ludicrously low, and out of step with trading updates from the company. So it’s not a surprise to see forecasts raised today, it was inevitable.
Headlam (LSE: HEAD), Europe's leading floorcoverings distributor, is pleased to provide a trading update ahead of announcing its interim results for the six months ended 30 June 2021 ('H1 2021') on 2 September 2021.
Trading is going well, with u/l PBT guidance going up from £29m to £35m, up 21% -
Given this sustained year-to-date performance and the Company's traditional second-half revenue weighting, the Company now expects full year performance to be materially ahead of current market expectations². After factoring in prudent revenue assumptions, and performance-related employee bonus payments due to the current outperformance, it is anticipated that 2021 underlying profit before tax will be no less than £35.0 million¹(,)² (unless exceptional or unforeseen circumstances prevail).
² Company-compiled consensus market expectations for 2021 revenue and underlying profit before tax (prior to any updates following this announcement) are £653.5 million and £29.0 million respectively (on a mean and post IFRS 16 adoption basis).
Valuation - Stockopedia is showing 26.0p EPS forecast for FY 12/2021, so if we raise that 21% then it comes out at 31.5p. At 524p per share, the PER is 16.6
Personally I’ve been working on the basis that, after cost-cutting and an efficiency drive, Headlam should be able to reach c.50p EPS in due course, maybe next year. If I’m right, that would bring the PER down to only 10.5 - hence this share still looks good value, and further upgrades to guidance seem likely later this year.
Dividends - Headlam says it will return to normalised level of dividends, as previously predicted here! A key reason to hold this share is the dividend paying capacity of the company is considerable, given its strong balance sheet, and trading returning to normal pre-pandemic levels.
Footnote 3 says the target is dividend cover of two. Therefore if my 50p EPS target is right, that would mean 25p in annual divis, yielding 4.8% - an attractive, and sustainable yield. Also this has inflation-protection too, because a distribution business like this would be able to just pass on cost inflation to its customers with price rises.
My opinion - this was an entirely predictable, even obvious situation, and has been flagged here frequently in the last year or so. Hence I hope some readers have made a bob or two on this!
Based on my figures above, it still looks good value, with the attraction of a generous, twice covered dividend resuming.
.
Vertu Motors (LON:VTU)
(I hold)
46.5p (up 7%, at 11:32) - mkt cap £171m
As a consequence of the continuing strong trading performance, the Group is providing an update on current trading and an upgrade to the full year outlook.
- Exceptional UK used car market conditions
- High gross margins
- “Material positive” effect on profits & cashflow
- Despite tight supply, sales & inventories of used vehicles have been higher than expected
- New vehicle volumes & margins have “remained strong”
- New vehicle supply constraints have had “no material impact” on H1 trading
- Service revenues & profit “strengthened in recent weeks”, mirroring patterns of last year
Revised guidance - this is just for H1 (March-August 2021) -
The Board now anticipates that the Group's adjusted profit before tax for the six-month period ending 31 August 2021 will be no less than £40m.
Seasonality - given that VTU is flagging a huge £40m profit for H1, I wondered what seasonality there is to the business in normal times?
Stockopedia has a really neat feature, which splits the Income Statement for any company into H1 & H2, going back several years. It’s under the “Accounts” menu on any company’s StockReport, then you select Income Statement, then click on “INTERIM” - I’ve done a screenshot below, with the relevant bits highlighted.
As you can see below, in each of the 3 years before the pandemic, Vertu did make a larger profit in H1 (highlighted) than H2, so yes there does appear to be a usual H1-weighting to profitability.

.
H2 Outlook -
VTU flags various uncertainties -
- New vehicle supply may be constrained, hurting profits
- That could cause a knock-on restriction in supplies of used vehicles
- Covid uncertainty
- Upward pressure on employment costs
- Therefore it is guiding for only £0-5m profit in H2, added to the £40m made in H1, giving £40-45m for the full year (ending 28 Feb 2022).
Forecasts - both Liberum and Zeus (who both produce excellent research) update their numbers today.
FY 02/2022 - Zeus raise by 35%, to 8.4p. Liberum is even more punchy, at 9.7p.
My feeling is that something exceptional, and one-off in nature seems to be happening this year, hence I wouldn’t value the shares on an exceptional year’s earnings.
FY 02/2023 - more normalised trading expected, with an average of 6.3p forecast by the two brokers. I’m happy to put that on a PER of say 12, which gives my price target of 76p. That’s 63% upside on the current share price, which is more than enough to keep me interested, hence is a strong hold for me personally.
My opinion - H1 has been staggeringly profitable for Vertu (and presumably other car dealers too). However, it does look a bit of a one-off.
Even so, valuing the shares on next year’s lower forecast earnings, still gets me to a price target 63% above the current price.
What’s even better is that downside protection is almost complete, with a strong balance sheet groaning with freehold property.
The valuation makes no sense to me, I think the market is just pricing car dealers wrongly at the moment. Even if internet competitors (e.g. Cazoo, Cinch) do take a chunk out of Vertu’s business, it’s still a very big market, and I reckon most people will still want to touch, and test drive, a car before buying it. Furthermore, if you look at Vertu’s website, it also has the same click & collect, 14 day money-back guarantee, free delivery offer that the internet companies do. If I decide to buy a car online, would I feel more comfortable buying from an internet startup, or an established local dealer? The latter. Writing off existing dealers seems premature to me.
The other argument against car dealers, is that electric cars won’t need as much servicing as conventional cars, and we might end up buying direct from the manufacturers, cutting out the dealers. Even assuming that analysis is right (which I’m not convinced about, as plenty of things can go wrong with electrics, as they age), then car dealers could just convert their redundant sites into supermarkets or residential, morphing into property companies which in the case of Vertu fully supports the current market cap, before adding on any development upside on its extensive freehold property portfolio.
Hence risk:reward looks very attractive to me. Copper-bottomed thanks to the property assets, and on an amazingly low PER for current business which is booming. You don’t see that combination very often.
Finally, I think sector consolidation is looking very likely now. With all these takeover bids happening, there must be private equity people crunching the numbers for buying up dirt cheap UK car dealerships. It’s tailor-made for private equity - do a sale & leaseback on the property, and you get the business practically for free! If someone offers me say 50% bid premium on the current price of Vertu, I would be delighted.
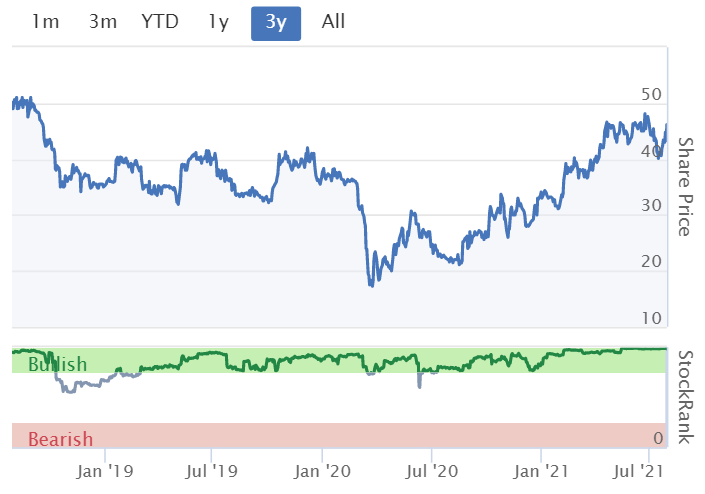
Note that the StockRank has got jammed on maximum! That's before the latest big broker upgrades feed through, so this could start blowing some servers at Stockopedia HQ! It also has the coveted "Super Stock" classification.
.
.
Jack’s section
Water Intelligence (LON:WATR)
Share price: 990p (+1.54%)
Shares in issue: 16,289,521
Market cap: £161.3m
(I hold)
This is a fast-growing water lead detection company that has built up a strong market position in the US and UK with its proprietary non-invasive technologies. These allow the detection of leaks without breaking down walls, meaning customers save money.
The group operates a hybrid corporate-franchise model, which allows for both high returns and profitability margins, as well as strategic optionality - it can encourage higher margin franchise stores, set up its own corporate outlets where it has more control, or buy back franchises as it sees fit.
More recently, Water Intelligence has set about a more global expansion. The growth rates here are very impressive and there’s plenty of scope for expansion.

International requires more corporate expansion though, tying up more capital and potentially lowering returns compared to the more established US business.
That aside, the momentum here is excellent. The recent final results also contained a trading update for the first four months of the current year, which showed revenue growth picking up from 38% to end-March to 47% to end-April. Profit growth improved from 152% after three months to 154% after four. It’s rare to find such numbers.
Which is why the shares look very expensive.

The Group's acceleration in performance reported in 1Q continued during 2Q, producing a strong 1H. Moreover, transactions executed at the end of 2Q and beginning of 3Q fuel further anticipated growth for 2H and beyond… Implied total annualized sales to customers (gross sales from which franchise royalty is derived plus direct sales from corporate locations) has surpassed $140 million providing critical mass
Highlights:
- H1 revenue +44% to $24.7m,
- EBITDA +73% to $5.4m,
- Statutory profit before tax +92% to $3.8m; adjusted PBT +77% to $4.2m,
Both core business units - American Lead Detection (ADL) and Water Intelligence International (WII) grew strongly across residential, commercial, and municipal markets.
ALD revenue grew by 42% to $21.9m (1H 2020: $15.4m). Royalty income from franchisees grew in absolute terms by 6% to $3.7m, despite eight franchise reacquisitions during 2020 and one during 1Q. Franchise-related sales (national accounts; parts and equipment; franchise territory sales) grew 14% to $4.9m. Corporate location sales grew 75% to $13.3m.
The insurance business-to-business channel grew 15% to $4.5m. Four national insurance contracts have been won.
WII revenue comprising international corporate locations grew 65% to $2.8m and statutory PBT grew by 92% to $3.8m.
Adjusted for acquisitions and the recent July placing, WATR has $11.2m of cash and $9.2m of bank borrowings, meaning net cash of $2m.
The acquisitions include the eight franchises noted above, as well as a plumbing company in Louisville, Kentucky, and the IP assets for irrigation and stormwater run-off and launch of Intelliditch.
WATR is also commercialising a proprietary sewer diagnostic product and has strengthened its board with two hires: one with financial markets experience and the other with additional industry experience.
Exec chairman, Dr. Patrick DeSouza comments:
We are accelerating our efforts to build and deliver a world-class company because we are on a mission to provide private sector leadership and solutions to water and wastewater infrastructure problems, especially in light of climate change...
We look forward to attacking this global market opportunity… As jurisdictions around the world invest in infrastructure in the aftermath of the pandemic - underscored by Biden Administration's American Jobs Plan and its anticipated $100 billion investment in water and wastewater infrastructure - we anticipate strong demand for our solutions to safeguard the world's most precious resource.
The group plans to announce its interim results in mid-September 2021.
Conclusion
This is the type of momentum, operating activity, and financial results that we are coming to expect of this company.
These first half results follow a strong full year 2020 which, despite Covid-19, produced 17% revenue growth to $37.9m and 78% statutory PBT growth to $4.2m. Since 2016, WATR has achieved a CAGR of 33% in terms of revenue and 53% in terms of statutory PBT.
After 44% revenue growth in the first half of this year to $24.7m, the consensus revenue figure for 2021 of $47m looks set to be beaten. I would expect further upgrades this year and into FY22 if past performance and present conditions are anything to go by.
Edit - I've received a WH Ireland comment (one of the brokers):
We have upgraded several times recently, notably on July 8th, when we raised FY22E PBT forecasts by 17%. However we see further scope in the future, given the strong momentum, and our fair value estimate now stands at 1100p (1075p) in recognition of this.
The only real sticking point for now is relative valuation. Not many companies deserve a 43.7x forecast earnings ratio and in the short term, that valuation might temper further share price gains. But over the medium and longer term, Water Intelligence faces a global opportunity and has decades of experience doing what it does, so I would back it to continue growing.
Everyman Media (LON:EMAN)
Share price: 140p (-0.36%)
Shares in issue: 91,155,469
Market cap: £127.6m
Everyman is an independent UK cinema chain that has built a useful market position by offering customers a premium experience, with more comfortable seating and good food. It sticks to unique venues and aims to make cinema trips more memorable.
It’s a smaller company and the free float is 43%, so liquidity is an issue. The top ten holders actually have about 76% of the stock.
I’m a fan of the company and its sites but the shares have always looked pricey to me after a run up in 2017 - a peak that has never been topped.

Of course, the past year has been heavily disrupted, so what’s of interest here is the degree of recovery currently being experienced and the outlook in the months ahead.
Trading update for the 26wks to 1 July 2021
Highlights:
- 33 venues re-opened on 17 May, with Glasgow re-opening on 6 June and Belsize Park closed for refurbishment,
- £21m liquidity headroom,
- Return to profit and cash generation on re-opening.
All venues were closed for the first 20 weeks of FY21 due to the Covid-19 Lockdown. Everyman used this time to conserve cash and upgrade kitchens.
Admissions in the period since re-opening until 1 July reached 66% of 2019 levels despite restrictions such as the Rule of Six, table service, 50% capacity restrictions in venues, and social distancing. So in context, it is quite positive.
Market share has grown since re-opening and the business is well positioned to return to pre-COVID-19 Lockdown levels of trading and to grow beyond.
Everyman expects to announce its half year results on 23 September 2021.
Conclusion
Everyman has every chance of continuing to carve out a position in the UK market. It’s a great cinema operator offering a superior product that people want to pay for. We all want to spend a great time out with friends and family now more than ever.
But the valuation here is too rich for me given the nature of the business. It trades at nearly 3x tangible book and roughly 2x FY19 revenue - and that year the profit margin was just 2.7%. If you apply FY19 EPS to today’s share price, that would be a PER of 57.4x.
Compare it to Water Intelligence above, for example. Just by nature of being a cinema operator, Everyman produces lower returns on capital, lower profit margins, and has to spend far more on capital expenditure. Water on the other hand is already executing its global rollout and has more optionality in its hybrid business model.

It’s true that Everyman has been firmly in expansion mode in recent years, acquiring and refurbishing new sites, so perhaps capex will moderate. But by that point older sites will need new fixtures and fittings and it will have more sites to keep up to spec, so I imagine this will remain a relatively capex-heavy enterprise.
Meanwhile, the lack of liquidity makes it tricky to buy (or sell) in scale.
Property Franchise (LON:TPFG)
Share price: 314.8p (+0.9%)
Shares in issue: 32,041,966
Market cap: £100.9m
The Property Franchise Group is the UK's largest property franchisor. I’m a fan of this business model, which is shared by Belvoir (LON:BLV) and M Winkworth (LON:WINK) . All have fantastic returns on capital, profit margins, and cash generation along with solid runways for steady future growth.
They are very profitable and resilient enterprises with sticky revenues, so I’m not at all surprised to see TPFG retain its 99 Q Rank.

I sold this one back in the 2020 post-lockdown market turmoil - the share price had held up relatively well and I wanted to free up funds for more opportunistic investments amid exceptional market conditions.
But, as is so often the case with these steady quality stocks, I needn’t have bothered as TPFG has comprehensively surged to new all time highs.

Admittedly this has been helped by an acquisition, but management has repeatedly flagged they will buy at the right price, and there is plenty of scope for further acquisitions in what is a large and relatively fragmented market.
The Group has achieved strong results in the first six months of 2021. Pleasingly, like for like revenue and Management Service Fees were significantly up on the same period in 2020 and, more importantly, 2019. This is owing to a very active residential housing market, and the acquisition of Hunters Property PLC ("Hunters"), which completed on 19 March 2021.
Highlights:
- Group revenue +111% to £11.4m; like-for-like (LfL) revenue +35% to £7.2m on H1 20 and +33% on H1 19,
- Management service fees (MSF) +69% to £7.1m; +35% LfL on H1 20 and +23% on H1 19,
- Network income +118% to £89.4m; +38% LfL to £56.3m,
- Sales agreed pipeline +247% to £29.5m; +64% LfL
- Managed rental properties up from 58,000 in 2020 to 73,000 today,
- EweMove sold 37 new territories (2020: 6),
- Net debt of £5m after borrowing £12.5m to fund the acquisition of Hunters.
The increase in network income and group revenue has been driven by two factors: government initiatives to support the housing market and remote working leading to more demand, plus a 10% increase in average sales fee charged (in line with increasing house prices).
Sales agreed are considerably higher than 2019 and this momentum has continued beyond the reported period. Given its pipeline, TPFG remains optimistic about the sales market this year.
Lettings income is proving to be resilient, with a 7% like for like increase in MSF over the same period in 2020.
EweMove, the hybrid estate agency, has continued to build on its brand positioning, with the sale of 37 new territories in the period setting a new record for the total number of territories operating of 149. It’s on track to double the size of territories to 230 by end 2022.
The integration of Hunters continues to progress well. TPFG has historically focused on lettings, so this acquisition of a more sales-focused estate agent was well-timed.
Chief Executive Officer, Gareth Samples, commented:
We are delighted to report that the first six months of trading have been an exceptional period for the Group. The UK's housing market has seen activity levels that I have not witnessed before in my career, supported by peoples' desires to move homes.
Conclusion
Given the strong trading and favourable market dynamics, TPFG is confident of a ‘very strong trading performance for the full financial year’.
And it remains modestly valued at 13.8x forecast earnings and with a forecast yield of 3.5% even after its rerating. It has a smaller market cap than Everyman, for example, but with market-leading profitability and quality characteristics.
Are current conditions sustainable? At some point the wider housing market might turn and government initiatives could be withdrawn or changed.
But while the share price could fall at some point due to changing macro conditions, TPFG itself will survive because of its strong finances, sticky lettings revenue, and cash generation. And over the longer term, through the cycles, the group has proven its ability to grow steadily in a large market. So it looks like a sensible buy and hold candidate to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

82 comments
Re LON:VTU
I have been really bullish on this one since the SCVR brought it to my attention. The valuation is nonsensical to me for all the points you have raised Paul. Also, I would never buy a car online without having a test drive first. It has to feel right - the way it drives, handles, comfortable... especially if you spend a lot of time in it!
Can you imagine buying online, waiting for delivery, only to hate how the vehicle feels? I imagine its a faff to try get them to refund/swap, and even if its the most simple process, you still have to wait for them to collect it, look for a new one, and wait again just to risk it all over!
Car dealerships are going nowhere and im sure they can adapt to the inevitable switch to electric vehicles. Its something they should absolutely be planning for now - potentially a question for management at the next opportunity.
Can you imagine buying online, waiting for delivery, only to hate how the vehicle feels?
Well, I have to confess that my current car was bought new, online, after I'd test driven at a local dealer. Not behaviour I'm too happy with but in my defence I bought online from a different main dealer on the other side of the country for around 15% less, and before buying I went back to the local dealer looking for a compromise over the difference in price, and they refused to budge by even 1p. Faced with that I was quite happy to cut them out of the loop, and very happy with the result and the savings.
I'd certainly agree that there is a real role for physical dealers, and aI'd always prefer to deal with one, but online clearly does put downward pressure on what they can charge, and can't just ignore it.
Everyman Media (LON:EMAN)
Hi Jack
Thanks for your write-up on Everyman Media (LON:EMAN) .
I hold a sizeable holding and your measured write-up made me sit up and question my analysis - always a good thing.
For now I remain a happy holder and I'd like to explain why.
Possible Masked Optimism From Today's Update
The comment today on £21m of liquidity headroom was the only real indication of cash generation since May 17th, which for me is the most important thing.
And by my calculations it looks like it was pretty good.
That actually sounds ludicrous, but given the number of leases negotiated down or cancelled over the last year, alongside what looks like increased ticket prices (I check regularly) and presumably higher beverage and food spend, perhaps this isn't so far-fetched?
To be honest, even if I've made an error in my assumptions, and the company actually generated half of this £6.3m I would still be impressed, given the rather short time period.
Of course, to caveat the above, there must have been some tax benefits/deferrals, but even including this, that appears to be quite a decent result.
Normalised Cash Generation + Refurb Capex
In 2019, aka "old normality," operating cash flow was +£14m.
Below is my calculation of annual refurbishment capex.
I think this is the "before" picture (from 2009):
https://www.villagehallcinemas...
vs what it looks like now:
https://hirespace.com/Spaces/S...
I'm not convinced it would cost £800k for every refurbishment either, but again, for prudence, let's assume that it does.
(Also this doesn't factor in the likely Virtual Print Fees Everyman would have received back from the studios - like a rebate - for upgrading to digital screening technology around this time, something I was involved in as I used to work for one of the major studios.)
That would imply <1 year payback on refurbishments and then 5 years of >£1m gross profit generation.
The above also implies £4.7m spent on refurbishments every year by the company (35 venues / 6 years * £800k).
So underlying cash generation, excluding expansionary capex, would be at least c£9m (£14m operating cash generation - £4.7m refurbishment spend).
To add some reality to the above (because note every refurb will actually cost £800k) let's assume it's a true range of £9m-£12m of underlying cash generation per year.
Let's not forget that the cash generation valuation multiple pre-covid was x20, which would imply a target EV of £180m-£240m.
Conclusion
Assuming no more lockdowns and cinemas remaining open, I personally don't think the valuation looks stretched at all.
I'm regularly on the bookings website and also continue to see many sold out showings throughout the week.
A cinema chain like Everyman also has the benefit that it can increase admissions and food/beverage prices and people will still want to come.
And hopefully growth can start again in the near future to help ramp up both that gross profit and the company's market cap.
The downside...well, I think that's pretty obvious, but for now, in this moment, I remain cautiously optimistic.
Fingers crossed.
A
Hi abtan/Jack.
Just want to compliment you both on the quality of your (soft) bear/bull discussion of the investment case for Everyman Media (LON:EMAN) . Makes such a change from some of the swivel eyed nonsense that sometimes graces these discussion threads of late. I don’t hold Everyman Media (LON:EMAN) at the moment although I’m an occasional customer at the Oxted and Reigate venues (which are excellent) but feel I have a much better handle on what makes the business tick now. Still think it looks a bit expensive as an investment - perhaps the share price has recovered too quickly compared to the underlying business on the ground and maybe has a few “hobby holders” i.e. customers that buy the shares based on their good vibes about the product (not necessarily a bad guide to investment) - but definitely more likely to consider it now.
Thanks again.
Gus.
Water Intelligence (LON:WATR) - there is no magic bullet for insurance companies to deal with claims in a 'non-invasive' way. Thermal cameras and other high tech equipment has come a long way but with modern building techniques (timber frame in UK), basements, double basements, roofs of all sorts - there will always be a need - unfortunately. But if their marketing department is on top form then gold medal time.
Garry,
The Water Intelligence (LON:WATR) USP is to locate the leak in a non-invasive way. It may then require a hole to be knocked in the wall to get in to repair it, but at least it is just one hole.
Additionally, I believe that a lot of their work is to do with swimming pools. I don't know anything about the plumbing of swimming pools but I imagine that a lot of the pipework is underground, so the benefit of accurate location before you start digging is clear.
I agree the comments on Water Intelligence. I love the business model and the opportunity taken to re-acquire franchises makes sense when your PE is a screamingly expensive 43 and your green credentials on display. Just too expensive for my taste..........
i agree death of car dealers much exaggerated. The point highlighted applies equally to one I have held as a property play ( Caffyns) for far too long. The question is how will the new car regime evolve over the nest few years given electric is now the only game in town. ? Many have switched to Hybrids but even here I see this as a half way house. More bullish on small dealers as there has to be consolidation. Caffyns may be worth a look ( has VW dealership which IMHO will be leading electric brand quickly) but the shares are pretty illiquid and market cap is very low.
The question is how will the new car regime evolve over the nest few years given electric is now the only game in town.
This certainly is the elephant in the room - its a question to me of whether the franchise model will still exists and if it does what % of car sales will be with companies that have full vertical integration and sell everything direct under their brand. My worry would be that the car manufacturers will all look at teslsa and see a car as being akin to an apple iphone where it probably is more about the associated services rather than the car itself ref making future profits - keeping in house should maximise any monthly revenues that can be extracted for auto driving upgrades / remote maintenance checks etc etc etc . Are any of the car companies up to doing it themselves - probably not many at present but i see the franchise dealers as being really at risk that the brands they deal with may say asta la vista baby i will not be back. I would much prefer to hold somethig like motorpoint as they don't have a master that they rely on. One could possibly just as easily argue - subcont it all out like it has always be done and split the revenue fairly and don't have the hassle of having the sites on book - so perhaps my asumption that franchised dealers may die away to a lesser or greater degree could easily be wrong.
With regard to EV service revenues, the Vertu Motors (LON:VTU) CEO, Robert Forrester, retweeted this the other day (so presumably agrees with it to some extent). https://twitter.com/kab604/sta...
Where’s Effortless Cool?
We can normally rely on him to give us an in-depth analysis of the Water Intelligence (LON:WATR) updates. So, I do hope he’s ok.
Hi Graham,
I'm well, thanks. I took my first trip back to our office in The City for 16 months today, mainly to dispose of paperwork that I haven't missed having access to, so presumably don't really need.
Have no fear - I'll be back manning the WATR pump at the weekend!
The market certainly likes the upbeat update from Headlam (LON:HEAD)
It always seemed likely they will beat the forecasts as the housing market has been running red hot. The question in someways was to what extent the market knows that and it’s already in the price. Well today we have our answer that the market hadn’t priced this in fully.
The next questions for me are how long will the growth last and if it tails off will that too take the market by surprise triggering a big sell off? The housing market may well slow down a bit as the COVID-19 spurt and stamp duty relief drivers abate. That seems like a certainty. Headlam may be able to keep profits growing by becoming more efficient. But that’s far from certain. So, this is a reopening bounce in my view that probably won’t continue. Or there’s a substantial risk that it won’t.
No position currently.
Lots of points being raised about Volex (LON:VLX) here today so this is a reminder that you can ask questions direct to the company at the AGM at 2 p.m. on Investor Meet Company.
Lots of points being raised about Volex (LON:VLX) here today so this is a reminder that you can ask questions direct to the company at the AGM at 2 p.m. on Investor Meet Company.
Hi sharw, thanks for flagging this. I listened in, and it lasted all of 12 minutes!
They ran through the formal AGM business, I noticed that the slide showing proxy votes showed a significant No vote against the Remuneration Committee Report, of 18.7%
Only one question, are you experiencing increased freight costs & raw materials costs? Answer - yes, but we're passing on higher freight costs to customers "where possible", so a bit vague. Component shortages is an issue, being managed well by Volex teams, parts mainly come from China.
That was it!
Regards, Paul.
Morning all,
One risk to be aware of for Vertu Motors (LON:VTU) is the agreement with Stellantis franchises which includes Peugeot, Vauxhall, Citroen, DS Automobiles and Jeep and makes up 18% of Vertu outlets. The existing agreement has been terminated (2-years notice from 31 May 2021) and a new one is being negotiated. While the outcome is expected to be positive for VTU, there's a risk that it may not and it could impact the business. Fingers crossed it's good news :)
Cheers,
Thanks for flagging that issue about the Stellantis contracts, Kierankj077, I'd forgotten about that.
Regards, Paul.
Devro (LON:DVO) - manufacturer of collagen products for the food industry ie sausage skins. Finding its way back by cutting costs, concentrating on growth markets and restoring dividend growth. Its 2022 prospective PE of 12.1 does not reflect this change in fortune. Not for vegetarians.
Many thanks indeed for your recent superb write-up on Headlam (LON:HEAD) Paul.
It's the sort of business and under-valued opportunity that I simply would never have spotted without your analysis. After DMOR, I'm grateful to now hold a small position.
FR
Made.com (LON:MADE) - I have been following this since the Richard Leonard interview on PI World. I would be interested in your views Paul as price is plummeting and major shareholders seems to be offloading since IPO . I wonder what you feel would be a fair valuation?
From a quick glance through IPO docs this appears to be still loss making so I didn't look any further (may well turn out to be a good investment, but I generally exclude anything that's not profit making, unless I really understand the investment case).
Hi FH,
I was quite surprised when Richard Leonard waxed lyrical about Made.com (LON:MADE)
I've had a quick look at the Prospectus, and for me the deal-breaker is page 9 - it doesn't make any money!
.
Yet the share was floated at 200p, with 387.7m shares = market cap at IPO of £775m! Good grief, how on earth did they manage that?!
As you say, the share price has since dropped and is now at about 159p, or a market cap of £610m - still way, way too high, in my opinion.
I've generally done very badly buying shares in loss-making companies, floated on hype about their amazing future potential. Things rarely pan out as planned, and profitability nearly always takes longer, and needs more funding, than the original forecasts.
Maybe the bulls have some other angle on it? E.g. the company must be spending a lot on marketing, so they might be stripping that out and imagining there's a great business underneath? But the marketing spending is what's driving growth, so it can't just be ignored.
I see that Made is also international, which might be getting people excited.
Why would anyone pay £610m for Made, a loss-making company still, when for £109m you can buy profitable Scs (LON:SCS) which is actually slightly larger than Made on a revenue basis? Generous divis are in the pipeline from ScS too.
It's almost as if people think these internet-only companies have invented something amazing & new. Yet the existing furniture companies are already selling on the internet, as well as from stores, and are growing their internet operations considerably.
I'll go for the cheap, profitable, low PER, dividend paying company every time (SCS), not the inflated valuation of a loss-making IPO.
You knew I was going to say something like this didn't you! :-D
Regards, Paul.
I was certainly hoping/expecting you to say that! SCS have a trading update due out very soon too. I'm keeping my fingers crossed for a positive one and that shipping costs (which have certainly increased) do not effect the company's progress too much....
£Made has great products. When my son married 3 years ago they furnished their first home largely with their products. So it fulfils a key factor of buying a company I like. They have great worldwide prospects and are forecasting £1.2 billion turnover by the end of 2025 but maybe that will come earlier. At that point the argument is that they will be making very considerable profits. RL's estimate was for a doubling in price from 200p over the next two years. Having followed him into Reach, Redde Northgate, Bloomsbury and Polar Capital, I will give him the benefit of the doubt although they should have built up the business in the US and IPO'd there!
Paul - Made.com (LON:MADE)
You knew I was going to say something like this didn't you! :-D
Well I didn't know, but I am not surprised. You make the bear case very well.
I have bought a very small position - 0.5% of my folio for 3 reasons:
[1] As far as I can work out they lost money in 2020 but generated cash. Not a lot. But some? In the first 3 months of 2021 they generated more than 25m of cash. More than they generated in the whole of 2020. Still an operating loss - as you point out. But more cash in the bank. Which interests me. Way too little information to know anything for sure.
[2] The company raised £90m in the IPO for specific reasons - £20m for European expansion, £20m for working capital, £20 to establish a home-wares market place and most of the rest retiring the debt. And of course the balance sheet was in dire need to some strengthening!
[3] Existing shareholders did not significantly sell down on the IPO - roungly 10% was sold to new institutions - the likes of NFU mutual, who are not short term investors? Most of the share sold at IPO were to raise capital for the company. That intrigued me, as its not very common for an IPO?
And I suppose there is a 4th reason
[4] As you described so well today - I have taken a small position so that its firmly on my radar and I have now got to do some work with funds at risk.
None of my thinking comes close to balancing out your well made argument that this is a loss-making company that may not go anywhere or make a profit ever. My gut sniffs an interesting opportunity - but my head is refusing to allow me to invest more than a tiny position without more data. This was always likely to be a wild ride - and its not looking like its going to disappoint on that. Interesting times........!
cheers
Mark
Mark - with regard to Made.com (LON:MADE) do we want it to make a profit soon? I would prefer it to use every penny to grow the business. This is a great brand according to my son and per the prospectus its target customers are relatively young and tech savvy. My son could write a few pages on this but no one would read it at this time!
Made.com (LON:MADE)
Mark/doublelutz/Fool Hardy/Paul/every Made.com contributor today
Thank you for bringing this up today.
---
I wrote about this 2 weeks ago and had no idea the price had dropped by 25% since then. It's rapidly descended into potential buy territory for me now.
To save me repeating the entirety of my previous thoughts, here is a link to that comment from 2 weeks ago:
https://www.stockopedia.com/co...
---
The short version is that the trajectory for Made.com looks quite similar to WestWing (I hold) a German-listed competitor, but about 2 years behind in its evolution (or 3 years if we account for the covid-induced boost).
WEW made an EBITDA loss of 10mEUR in 2019; this year it's on track for +60mEUR profit (with a lot of cash generation.)
If Made.com (LON:MADE) can replicate this feat and generate, for example, £50m Operating Profit in 3 years (which doesn't seem overly unrealistic) then the current EV of £550m doesn't seem overpriced to me at all.
REASON FOR PRICE DROP
I've noticed unknown price drops in the past and wasn't sure what was driving them.
Then I discovered that many funds have access to anonymised email and credit card data, so get live updates of how sales are going.
So for example, if you bought a sofa from made.com you might receive an automated "order received" email in your gmail account. Google scoops up that data and sells it into the market to anyone interested in made.com sales.
Visa/Mastercard do the same with their credit card data.
Effectively the big hedge funds know how a company is performing well before any RNS or trading update. I've previously asked Stockopedia to look to buy this data in the future.
I do wonder if this is behind the current price drop? I wouldn't be surprised if there is some near-term slowdown that big players can see already.
So I'll be waiting for the next update before deciding whether to further investigate or buy in.
In any case thank you to whoever brought this one up today.
Cheers
A
Thanks for sharing this, never knew this was achievable but you can see how valuable it would be. Good suggestion!
£Made - With reference to the comment from Fool Hardy, in the context of the number of shares held I would hardly call this offloading!
Made.com (LON:MADE) - doublelutz - are these share sales notification of the over-subscription allotment announced by JP Morgan on 16th July?
RNS - 16th July - 'has today given notice to exercise the over-allotment option (the "Over-allotment Option")
granted by Level Equity Growth Partners I, L.P., Level Equity
Opportunities Fund 2015 L.P., Level Equity-Made Investors, LLC., Partech
Growth FPCI, Haka Investments Limited, Europe Ventures II LP and By
Design (UK) Limited in respect of 2,878,701 ordinary shares in Made.com
Group Plc at the offer price of 200 pence each.'.........
............Giving effect to the exercise of the Over-allotment
Option, the final total size of the Offer is £199.6 million (99,793,745
Shares), in total representing 25.7 per cent. of the Shares in issue.'
Seems to me that they are?
cheers
Mark
Yes, Level and Partech are two of those involved in the over-allotment and as they are the two to sell while retaining very considerable holdings that would seem a reasonable assumption.
Hi Paul, You mention in your OMTP section yesterday that position size is everything, would you be able to expand further? i.e how do you decide on the initial size and so you monitor as the investment/portfolio changes?
Personally all my purchases start at the same size and are then allowed to run from there, trying to run the winners as long as possible. I don't consider how big the position is relative to the portfolio but this probably isnt the best idea from a risk management perspective?
Or how do others size their initial positions/ monitor existing position sizes?
Hi JamesS,
You asked me about position sizing.
Personally all my purchases start at the same size and are then allowed to run from there, trying to run the winners as long as possible. I don't consider how big the position is relative to the portfolio but this probably isnt the best idea from a risk management perspective?
There's no right or wrong on this, everyone has their own approach, dependent on their appetite for risk.
What I personally do, is filter out most ideas altogether right from the start. So I say no to at least 90% of the ideas that come my way, trying to filter out high risk companies (weak balance sheets), weak management, poor business models, over-valued shares, entire sectors that I don't like or have inadequate knowledge of, etc.
Anything that gets past my stringent initial filters, must have a recent positive trading update. That tends to reduce the risk of a profit warning, at least in the shorter term. I'm looking for shares where something is changing for the better (e.g. effective new management, favourable markets, competitive strengths).
Then comes the decision on position size. Like yourself, I tend to start with a standard position size of about 1% of my portfolio. Or if it's something very tiny, where liquidity is a problem, then probably just 0.5% of my portfolio. Below that, I figure it's not worth getting involved.
The advantage of having a smallish opening position size, is that it then focuses my mind on really properly getting stuck into the detail, to a deeper level than before, because there's now money riding on it.
Over time, I closely monitor the newsflow, and find that you spot things where you already have a position, because it goes on my priority watchlist for RNSs, which I look at first each morning. Hence when something good or bad happens, I spot it early, and might otherwise miss it altogether.
I also discuss shares I think are interesting with other investors, by email, WhatsApp groups, etc. Plus of course we have useful & interesting discussions here about many shares, which help me develop & adjust my views on companies.
Having done all that, I tend to buy more of the shares that seem to offer the best risk:reward. Hence typically, I'll go up to 2-3% of my portfolio in good solid companies that I think are doing well, have good prospects, and are still reasonably priced.
Often at weekends, I do a portfolio review, and look through the maybe 40-50 positions I usually hold, and decide which ones to trim or cull completely, and which ones are not big enough. Quite often I think to myself, gosh why have I only got £x in that one, it's superb. I should have 2x or 3x in it!
I like a highly concentrated portfolio, because to my mind it makes sense to back my best ideas with the most money. So my top 3 positions can make up nearly half my portfolio. That's far too risky for most investors, and I'm not in any way giving advise here, just answering your question.
I've found that every now and then, one of my big positions really motors, and that tends to make more than enough money to mop up all the inevitable mistakes, or things that are just currently out of favour. Often stuff I buy takes time to gestate, so something is not necessarily a mistake just because you have to wait 2-3 years for it to re-rate (e.g. Intercede (LON:IGP) springs to mind, and Cambridge Cognition Holdings (LON:COG) )
What's not working very well at the moment, is my largest position Boohoo (LON:BOO) which seems very much out of favour, along with Asos (LON:ASC) which have both seen a similar decline. Frustrating, but there we go.
It can quite often be the most unexpected things that suddenly become highly profitable. It's gone a bit wobbly recently, but Best Of The Best (LON:BOTB) was a stunning 30-bagger from when I originally bought quite a small amount, but I added to the position when it became clear the business was growing better than expected.
So for me, one of my key aims, is to try to focus my money into my best ideas. This was a key theme in the recent book we discussed here, The Art of Execution. I agree that some of the data in the book is questionable, but the concepts (running winners, cutting losers, put most money into your best ideas) are timeless and very good ideas & helped focus my mind on sharpening up my performance in those areas. Although I think longer term, and some of that book was more for traders, and people who chase shorter term out-performance against indices.
Regards, Paul.
As usual an interesting read, thanks Paul.
There was another book recommended here recently which i found simply fascinating and it really helped me on many levels and that is "Richer, Wiser, Happier" by William Green . There is some great nuggets in there, especially concerning identifying your investing goals, which i think i had done but not consciously.
Richard
I'm part way through that book right now and love it!
Good honest thoughts and ideas Paul many thanks!
Hi Paul,
I know you're not a fan of charting, but fwiw, I think the downwards action on Boohoo (LON:BOO) may be about to turn. It seems to be gravitating to the blue area I've highlighted below (where I'm looking to top-up), which is a happy confluence of:
- 250p (round number)
- weekly 200MA (which price has bounced aggressively off in the past)
- upwards trendline of the long-term pennant
- Previous significant support / resistance level
It wouldn't surprise me if we hit that area, then see a fairly rapid recovery in the SP.
Use or ignore as you prefer.
BT.
Boohoo (LON:BOO) - good call, the knife may have hit the floor - but putting money in would mean an uptrend and volume. I'm nursing a loss as are many others.
PS. We can all make charts work to our view. Just put an ALERT in stocko and wait for the email.
Avon Protection (LON:AVON) - I supported this at 3000 so we are where we are but always though some takeover target - i.e. better management. Nice volume here.
Strong update from Headlam (LON:HEAD) today (I hold)
Given this sustained year-to-date performance and the Company's traditional
second-half revenue weighting, the Company now expects full year performance
to be materially ahead of current market expectations². After factoring in
prudent revenue assumptions, and performance-related employee bonus payments
due to the current outperformance, it is anticipated that 2021 underlying
profit before tax will be no less than £35.0 million¹(,)² (unless
exceptional or unforeseen circumstances prevail). The Company will provide
further updates as necessary as the year progresses.
Additionally, as a consequence of the trading performance above, strong
balance sheet, and confidence in the prospects for the business, the Board
will now expedite the resumption of normalised levels of dividend payments.
Another upgrade from Vertu Motors (LON:VTU) driven by strength in used car market. H1 2022e Adj PTP guided £40-45m (prev cf £28-32m). Liberum forecast FY22 adj PTP £40.5m & adj EPS 8.4p (upgraded +34.9%). The adj PTP fig implies they have almost no contribution in H2?! CEO and CFO are presenting on Tuesday 17th August at 4.30pm. This has taken an age to organise, so I hope you can join us to hear more. Register here.
Tamzin - I will be joining as I hold the company and believe that it is one of the best value shares on the market. If anything I'm a little disappointed by the market's reaction to this trading statement but I'm sure in the long run the value will out!
Purely anecdotal, but I used to work with Volex (LON:VLX) for an OEM, developing wiring harness systems for commercial vehicles.
Found them to be very good to work with, they would have a person on site to support full time, and would pro-actively review designs to question anything they thought may not be right - very often picking up things which would have caused an issue if released to production.
They lost the business eventually, as it was given to a different harness supplier who seemed to have 'friends in high places' within our organisation. The support from that new supplier was not as good - build quality not at the same level, lead times were longer, and they were effectively a 'dumb' resource i.e. they would produce whatever they were given without checking the design for potential issues.
So, long story short, I hold Volex partly because of my positive experience working with them. I think we're still at the foothills of large scale electrification, and their services will be in demand for years to come IMO. Def a coffee can holding for me too.
"Purely anecdotal" - such anecdotes are very important in assembling a 360 degree view of a possible investment. Thank you.
Thank you for this piece of scuttlebut on Volex (LON:VLX). I hold.
Solid results from Devro (LON:DVO) today.
My morning smallcap tweet: Car dealers wheelin', Zoetic wordplay special.
Creightons (LON:CRL) Volex (LON:VLX) Property Franchise (LON:TPFG) Accsys Technologies (LON:AXS) Zoetic International (LON:ZOE) Quixant (LON:QXT) Mode Global Holdings (LON:MODE) Mirriad Advertising (LON:MIRI) Everyman Media (LON:EMAN) Biome Technologies (LON:BIOM) Lookers (LON:LOOK) Headlam (LON:HEAD) Vertu Motors (LON:VTU) SRT Marine Systems (LON:SRT), Eleco (LON:ELCO), Trackwise Designs (LON:TWD), De La Rue (LON:DLAR)
Creightons (CRL) buys Emma Hardie skincare for £6.36m in cash and shares. Target had rev £3.8m and pretax £47k. [SP=93 Cap=60m]
Volex (VLX) AGM stmt. Guides FY U/L op profit slightly ahead of market expectations of $50m. [SP=340 Cap=537m]
Property Franchise Group (TPFG) guides FY(June) rev up 111% and 35% LFL. "Confident in a very strong trading performance for the full financial year. " [SP=310 Cap=99m]
Accsys Technologies (AXS) buys stock, equipment and technology of wood manufacturing plant for €1.2m. Accsys will repurpose the equipment to convert Accoya wood into its new Accoya Color product. [SP=165 Cap=316m]
Zoetic (ZOE) buys chill.com domain in 'game-changing' move. Will rename co as Chill Brands. Chill products are now stocked in c.2,500 outlets across the US."Cadence and schedule of previously announced 3,500-store rollout modified in collaboration with major US partner." Cadence! PR doesn't even know the meaning of the word. [SP=50.7 Cap=108m]. I'm short.
Quixant (QXT) guides H1(June) double-digit revenue growth and profits which are comfortably in line with management expectations. [SP=164.6 Cap=109m]
Mode Global (MODE) partners with Young Lives vs Cancer charity to enable donations with only 0.5% processing fee. [SP=44.3 Cap=41m]
Mirriad Advertising (MIRI) warns converted sales will remain lower than previous expectations for the remainder of 2021, despite the first signs of improving market conditions in May and June. H1 rev up 27%. Guides H2 rev 70% - 90% higher than H1. [SP=42 Cap=117m]
Everyman Media (EMAN) admissions since re-opening were 66% of 2019 levels, ahead of director expectations. Co returned to profit and cash generation on re-opening. [SP=140 Cap=128m]
Biome Technologies (BIOM) guides H1(june) rev £2.6m (£2.5m), constrained by ongoing turbulence in shipping. These were factored into expectations. "The second US end-customer of scale to deploy Biome's proprietary compostable coffee-pod filtration material has identified an engineering solution for the delay detailed in the recent Trading Statement. The customer is now proceeding with suitable procurement and rectification work." Overall in line. [SP=359 Cap=13m]
Lookers (LOOK) guides FY(Dec) above mgmt exp after H1 U/L pretax c. £50m. [SP=67.4 Cap=263m]
Headlam (HEAD) guides FY(Dec) materially ahead of market expectations of £653.5m rev and £29m U/L pretax. Guides U/L pretax at least £35m. [SP=490 Cap=418m]. I hold.
Vertu Motors (VTU) guides H1(Aug) adj pretax at least £40m. Hikes FY figure to £40m - £45m (previously £28m - £32m). [SP=43.3 Cap=160m]. I hold.
SRT Marine Systems (SRT) FY in line. "These are obviously very disappointing results and I personally apologise to our shareholders who had expected this year to be our take-off year." How long have we been on the runway? Is the airport even still open? Soon "a number of customers will complete their contracting formalities". [SP=35 Cap=57m]. I hold. Yes, I know.
In line: Eleco (LON:ELCO) Trackwise Designs (LON:TWD) De La Rue (LON:DLAR)
Nice Update from Lookers (LON:LOOK) but mentions £13M of Government Support saying that they do not anticipate needing any further support. No mention of plans to repay. I hold
https://www.londonstockexchang...
Volex (LON:VLX) AGM statement - they’re looking likely to be “slightly ahead” of market expectations for fy22 profit based on current trading. Would appreciate someone deciphering what “slightly” means in this context. 1%, 2%, 10p? Or are they effectively saying “inline” with a positive spin as they expect to hit top end?
Alternatively, do I just need to wait for the interims to get a better understanding as we’re only 1q into FY22?
£Vlx "
1 Latest company compiled view of market expectations shows an underlying operating profit consensus of $50.0m with a range of $48.9 million to $51.0 million."
Err ok, not sure that answers the question but thank you for adding more context for other readers.
Michael Prince Volex (LON:VLX) yes, interesting that note 1 - I had initially missed it as small print in my first reading. I guess it could be interpreted as slightly ahead of the consensus $50m or slightly ahead of top of range $51m, maybe as little as $0.5m in each case. Interestingly it is well ahead of any of the figures on the Stocko page. I wonder why?
I do find these discrepancies disturbing as they cause me to wonder how far to rely on the Stocko figures.
Hi GN100,
I can't see any discrepancy with the Stockopedia figures for Volex (LON:VLX)
Remember that the "Net profit" figure on the StockReports is post corporation tax, so will be about 20% lower than pre-tax figures.
Stockopedia shows consensus forecast EPS of 24.6 US cents for FY 03/2021. That ties in closely with 25.3 US cents on a broker note from N+1 Singer, issued in mid June.
So all looks fine to me.
Regards, Paul.
EDIT: I should add that the data provider Thomson Reuters makes its own adjustments to numbers, to make them consistent, which can be frustrating because then the numbers don't necessarily tie in with what companies report.
Volex (LON:VLX) Thanks Paul, I had forgotten about the Corp. Tax.
Hello Paul,
Just looking at Volex (LON:VLX) figures. 2021 the Op. profit was $30.7m and net profit was $38.9m.
Forecast for 2022 is Op. profit is $50m which is 63% higher than 2021 yet the EPS is forecast to be 10% lower?
Is this what you are expecting?
Re Stockopedia fall in ranking is due to Quality falling maybe due to debt increase (Altmann score) and also Momentum has fallen, share price has been flat for last 7 months, forecasts are flat for the next 2 years.
Hebie
Just looking at Volex (LON:VLX) figures. 2021 the Op. profit was $30.7m and net profit was $38.9m.
Forecast for 2020 is Op. profit is $50m which is 63% higher than 2021 yet the EPS is forecast to be 10% lower?
Is this what you are expecting?
Herbie i presume you mean 2022 when you say 2020?
Note forecast is for "underlying operating profit" of $50 mill.
thats only 16% up on last years total (ye4/4/21) which was $42.9 (i think you are either mixing operating profit with underlying operating profit or were comparing to 2020?)
Ref EPS - not clear to me they has some chunky deferred tax credits last year - these should not be expected every year - they possiby have losses -and or r&d claims which may mitigate tax - i would expect its much less likely tax would be as large a credit but anything is possible. Inc circumstances like this much better to only compare pre tax numbers - with any lack of tax of credits being chery on the cake.
Word of warning here underlying profits are before share based payments - imho share based payments are akin to salary and sums involved are ridiculously material - 6 mill last year and 8 mill the year before. I have no idea if those higher numbers are outliers compared to normality- they might be connected to near trebling of shareprice which is fair enough. Note it is standard practice and not something dodgy that volex are doing.
To be fair to volex underlying profit is a good "main metric" to quote as it concentrates on core business profit made - but you need to always adjust in the below line items that will appear come year end - operating profit is much better reflection of reality in that repect.
Thanks re Volex (LON:VLX). Yes it was a typo that I corrected, should have been 2022.
Good point about the share based payments.
So it looks like pretty flat growth over the next 2 years, I don't think that is what many followers are expecting.
I was going to top up today but will hold fire for now.
Herbie
Volex (LON:VLX)
So it looks like pretty flat growth over the next 2 years, I don't think that is what many followers are expecting.
Strangely numbers look fine and dandy to me at "underlying operating profit level". (caveat below the line inspection needed before purchase of shares)
5/4/2020 $31.60
5/4/2021 $42.9
5/4/2022 projected $51
5/4/203 ???? ** (lets pencil in $58 see below and use half way mark)
5/4/2024 $65 if we cheekily us the "operating income"
That looks fine to me - i am much more comfortable now with this share than i was at the start of their turnaround - i wasnt 100% convinced then that they might not simply have hit a purple patch ref part of thir business and then defaulted back to the norm (prior 5 years) . I am now happy that the 5 wasted years of making zilch is practicably speaking a completely different entity (what a waste those years were) to where they are at now.
** Would be interested to see if there are any broker estimates ref 2023 year
Volex (LON:VLX), I'm talking about eps growth.
There are brokers forecasts on Stockopedia for 2023 year: 39.5m net profit and 0.27eps
I was late getting into Volex (LON:VLX), so don't know the history.
Volex (LON:VLX)
Volex (LON:VLX), I'm talking about eps growth.
ahhh ok i see.
I think where tax materially alters EPS away from reasonable lfl calculations i would always adjust for standard tax rate or compare numbers pre tax adjust. So the tax isn't providing a misleading picture with regard to undelying buisness comparitors that matter.
If they will go from adding 20% onto pre tax figure in 2021 to taking 20% from pre tax figures in 2022 (seems a distinct possibility) the EPS numbers may be completely masking the good progress made (as evidenced by good trend in underlying profits growth).
Volex (LON:VLX) it seems some of the share based payments relate to acquisitions so that ok but I would still expect some eps growth over the next 2 years.
herbie47
Volex (LON:VLX)
Volex (LON:VLX) it seems some of the share based payments relate to acquisitions so that ok but I would still expect some eps growth over the next 2 years
If growth in underlying or pre tax earnings earnings is 40% over next two years and adverse tax adjustments to EPS total are 40% in same period - then i would expect EPS not to grow ar all. This is very real posibility with tax ye 5/4/2021 being negative 20% - correction to the norm of +20% - is 40% swing. All % 's used are very rough and ready numbers for simplicity purposes.
Infact i have done a little table - and it suggests if we increase pre tax profit 40% and tax changes from +20% year zero to zero year 1 and normal 20% rate (deduction) year two - earnings for EPS purposes will drop 9% year two compared to year zero (2021 )- i wasn't expecting that bizarre bit of maths but there you go.
if Im reading into it correctly, the stockreport shows OpP for 2021 as 30.7M, so 50M is stonking growth. They also say, in Layman's terms, "we're loaded and looking to buy stuff". Heck, Im in
aknownmoose
Volex (LON:VLX)
if Im reading into it correctly, the stockreport shows OpP for 2021 as 30.7M, so 50M is stonking growth. They also say, in Layman's terms, "we're loaded and looking to buy stuff". Heck, Im in
I think you must be getting this completely wrong (i stand to be corrected here as i am simply making a presumption) unless you post is done in the best traditions of sarcasm (hard to tell here at times)
The quoted figures are the previous expectations before todays news (ie as of last night) - there is no upgrade from 30.7-50. 50 is where they were previous whatever stocky says. Ie they were at 50 last night no slightly ahead to perhaps 51 midpoint.
Additional notes ref comparing figures to stocky
You need to see if stocky is using different currency or may be slightly out of date or using different metrics - first up year we are talking about is 2022 and stocky quotes after tax numbers and operating profit used by company today is not real profit - eg pretty sure finance expense are excluded from operating profit but will be deducted (if relevant) to get to net profit there could be any number of such adjustments - look at last year end accounts to see typical differences.
The Volex (LON:VLX) $30.7m Op. profit figure is in the 2021 results, so if it's $50m for 2022 that is a considerable increase yet the EPS is down 10%, what am I missing?
herbie47 - I havent looked in depth at this at all but I suspect the difference is related to the tax charges. Op profit is before tax, EPS calculated after tax. Paul mentions above that they benefit from " an unusually advantageous tax charge".
Volex (LON:VLX)
The Volex (LON:VLX) $30.7m Op. profit figure is in the 2021 results, so if it's $50m for 2022 that is a considerable increase yet the EPS is down 10%, what am I missing?
see my post above you are confusing underlying operating profit with operating profit - its $50 mill compared to $42.9 mill!
Volex (LON:VLX) (I hold)
Hi IGPJ
I would suspect that there are too many moving parts ("supply chain shortages, material cost inflation and freight challenges, .....Covid-19" - today's RNS and "We have an exciting pipeline of acquisition opportunities" - 2021 results presentation) for the board to give a precise percentage figure on where they expect operating profit to be for a year that does not end for eight months.
For me Volex (LON:VLX) is a long term story on where the company will be in say five to ten years in context of the market it is targeting. Whether it slightly under or overshoots a market forecast in any one year is not particularily relevant.
And though Nat Rothschild is a billionaire in his own right and heir to the Baronetcy, one gets the impression that he is, with his 25% share holding (£131.99m), very focused on delivering the company's target - "...five-year plan laid out in October 2019 to deliver revenues of $650 million and $65 million of operating income by 2024".
This would give a price of £8.77 if the share continues to re-rate to a PE of 25. I will be more than if it is up more than two and half fold in three years.*
Regards
Michael
*Edited. Sorry I was getting my dollars and pounds confused.
PS Singer today in its note:
"We have upgraded our adjusted operating profit estimates by c.5%"
The note is available on Reseach Tree.
Volex (LON:VLX)
five-year plan laid out in October 2019 to deliver revenues of $650 million and $65 million of operating income by 2024".
This would give a price of £10.23 if the share continues to re-rate to a PE of 25. I will be more than if it triples from here in three years.
The problem with 5 year plans like this is they can be massively misleading - company can easily reach this objective with takeovers using paper for purchase - if its a 5 year plan to hit operating profit of $65 mil on organic basis thats great. Anyway what the heck is is "operating income?" they quote underyling operating profit / operating profit and statutory profit before tax and then this bilionaire makes up his own stat not referenced anywhere else in the accounts - strewth.
And happily, another takeover - Charles Stanley (LON:CAY) at 515p a share, a 43% premium:
https://www.investegate.co.uk/...
Looks like a done deal with over 30% of shares already committed to the offer.
It really is open season in the UK market at the moment.
timarr
Great stuff re Charles Stanley (LON:CAY) (I hold). I'm getting hungry for more takeovers...
FR
Morning Paul one I bought from Mello Samarkand Group plc, initial results after IPO I know you like your e based companies and this ones a tad different. Thoughts as always welcome.
I like the look of Samarkand, but it's listed on a junior market, and my broker wasn't able to buy any shares in it. For that reason, I'll probably not cover it until they move to AIM.
re. Samarkand (OFEX:SMK) , VSA Capital have produced a Brief research /update on the 2021 results which includes a bullish 12 month price target of 300-326p (against current 148p). VSA brought the IPO to market so may well be looking through rose tinted spectacles but the company are in an interesting niche and have done well since launch albeit with quite a strong sentiment headwind against all things Chinese over the past few months. VSA make their research available for free if you register with them. Bought into the IPO and happy to continue holding. Here’s the link:-
https://vsacapital.com/investm....
Gus.
Further to my earlier comment on the Samarkand (OFEX:SMK) results vis a vis the recent sell off of Chinese related equities, I it might be helpful to share this commentary from the Fidelity China Special Situations Investment Tust Portfolio Manager about his thoughts on the reasons behind the sell off.
https://www.investegate.co.uk/...
Gus.
Great update from Vertu Motors (LON:VTU) today.
Vertu Motors (LON:VTU) (I hold)
Yeah, it was everything I was hoping for except for the full year guidance. I understand the pressures and desire to under promise and over deliver. However, how do you say 1H profits will be no less than £40m and full year will be in range of £40-£45m. I’d appreciate your view here, Paul as I’m a bit of a confused holder…
I think they're taking every worst case scenario. More new car delays, trouble getting used cars, another lockdown and/or employees having to isolate which would have an impact.
Hopefully they'll be able to upgrade as the year progresses
A comparison with (LON)LOOK would be interesting as they both updated today