Small Cap Value Report (Fri 30 Oct 2020) - KAPE, RNO, MMX, TGP, ALT

Good morning, it's Paul & Jack here, with the SCVR for Friday.
Timings - it's Friday, so I'm taking things at a leisurely pace. Finish time estimated at 3pm.
Update at 14:50 - today's report is now finished.
Agenda -
Kape Technologies (LON:KAPE) - interesting, large fundraising at no discount
Renold (LON:RNO) - overlooked trading update from 16 Oct
Minds Machines (LON:MMX) - Jack's contribution, re accounting investigation
Tekmar (LON:TGP) - (I hold) - savage market reaction to a profit warning
Altitude (LON:ALT) - Full year results
I dropped Dp Poland (LON:DPP) from the running order, once I realised its shares are suspended (and it's a complete crock anyway!)
.
In case you missed it, here is the link to yesterday’s completed SCVR, which included a reader request section on Redde Northgate (LON:REDD) - which I (Paul) think might be potentially very interesting, so it’s worth a look, and a debate. I very much want to hear your informed opinions, if you’ve done proper research and have some insights. Hunches, or that you happened to have bought or sold at this or that price, is not of interest!
Good podcast - I really enjoyed this podcast from PIWorld, with Andy Brough and Richard Leonard, hosted superbly by the unflappable, charming, and highly knowledgeable/experienced Tamzin. It felt like sitting in the pub with a couple of experienced old hands, who’ve been in the market for decades, and full of insights. A reminder that mere striplings like myself, who’ve only been doing small caps for 20 years or so, still have much to learn!
Firstly let’s start with a couple of stragglers from previous days;
.
Kape Technologies (LON:KAPE)
Share price: 160p
No. shares: 158.5m (before placing) +59.2m new shares = 217.7m after fundraise
Market cap: £348.3m (after fundraising)
Fundraising
I’ve not looked at this company before, and don’t have a view on it, but a large fundraising caught my eye, so just thought I’d flag it up, as this could be interesting maybe?
Proposed placing to raise $100m - c. £77m, a big fundraising of about 30% of the existing market cap. Use of proceeds is unusual, mainly $72m to buy out the shareholdings of the founders of an acquired business, PIA, which Kape acquired in 2019.
.

.
o c. US$72 million to buy out the equity interests in the Company of Andrew Lee and Steven DeProspero (the "PIA Founders"), the two co-founders of Private Internet Access ("PIA"), a company acquired by Kape in 2019; and
o the balance to strengthen Kape's balance sheet and enable fast execution of further selective acquisitions, building on Kape's excellent M&A track record and continuing pursuit of growth.
The PIA founders have 6.64% of KAPE, which I make £16.8m or $21.7m. So it’s not immediately clear why they are being paid $72m to exit? Could there be some lucrative share options scheme, or similar? Ah, I've just found it, here we are;
On 16 December 2019, Kape completed the acquisition of PIA, a leading US-based digital privacy company (the "PIA Acquisition"). As part of the consideration, Kape issued, in aggregate, 10,500,726 new ordinary shares ("Initial Consideration Shares") to the PIA Founders, with a further 27,994,720 Ordinary Shares in aggregate to be issued to the PIA Founders over a two year period from closing ("Deferred Consideration Shares").
The Company and the PIA Founders have reached an agreement with respect to the sale and purchase of the Initial Consideration Shares and their right to receive the Deferred Consideration Shares, for a total consideration of approximately US$72 million (the "Purchase Agreement").
It just shows that checking the detail on deferred consideration creditors, is incredibly important.
Tax benefit - I’m not sure why this would be, but the company says it will save a lot in tax over the long term from buying out Messrs Lee & DeProspero (an apt surname there lol!)
As a consequence of buying out the equity interests of the PIA Founders, Kape expects to realise an expected tax benefit of approximately US$50 million over the next 15 years.
Trading update included within the placing announcement -
Kape announced its interim results for the six months ended 30 June 2020 on 15 September 2020. In the three months to 30 September 2020 (Q3), Kape's trading was at the upper end of management's expectations. User growth in the Privacy division continued to ramp up, reaching a run rate of 14 per cent. annual growth during Q3 2020. The Company also successfully launched several product development initiatives and experienced continued strong user retention. Revenues for the year ending 31 December 2020 are expected to be between US$120-123 million, with adjusted EBITDA in the same period expected to be US$35-38 million.
Support of major shareholder - of the $100m fundraising, the major shareholder seems to be underwriting most of it;
The Company's majority shareholder, Unikmind Holdings Limited, has entered into a subscription agreement with the Company, pursuant to which it has agreed to subscribe in the Placing for shares worth up to US$72 million at the Placing Price (the "Subscription Agreement"), although this figure may be reduced depending on demand generated in the Placing.
PrimaryBid - there’s a separate raising through this platform.
Result of Placing & Retail Offer - this was published on Thursday morning. It’s been upscaled from $100m to $115.5m. The price is 150p, a negligible discount to the market price when it was announced - a strong sign.
The major shareholder bought 28.5m shares in the end, and now has 65.0% of the total - good or bad? You decide.
My opinion - none, as I don’t know anything about the company. However, this fundraising looks noteworthy, because it is;
- Large relative to the size of company
- Negligible price discount, so clearly strong demand - the roadshow must have been convincingly good
- Major shareholder standing its corner
- Buying out holders of rights to future shares, suggesting that maybe the company thinks its shares are likely to rise?
- Sexy, tech sector
I’m just flagging it, as something that readers might want to look at, if you understand this sector, which I don’t. It smells good to me, for the above bullet point reasons.
For more information, see a recent PIWorld video results presentation here.
I’d like to see proper numbers, not EBITDA numbers, when they are issued.
As others have commented, Israeli/international tech businesses can be a hot spot of expertise & innovation, so they’re worth looking at with an open mind, I reckon.
.
Renold (LON:RNO)
11p - mkt cap £24m
(I hold)
A tiddler that put out a trading update last week, 16 Oct 2020, which we overlooked at the time, due to being busy.
Renold, a leading international supplier of industrial chains and related power transmission products, today issues a period end trading update covering the six months ended 30 September 2020 (the 'period') ahead of announcing interim results on 11 November 2020.
Renold delivered a resilient performance in the first half despite its markets being significantly impacted by the Covid-19 pandemic. The business remained profitable throughout the period and achieved a significant reduction in net debt of £10.2m to £26.4m (FY 2019/20: £36.6m), despite sales revenue down 17% on the prior year, at £82m.
The Group continued to benefit from a combination of improvement in the strategic cost base and the productivity gains made in recent years, together with tactical short term cost saving measures. These enabled the Group to achieve a positive operating margin for the period.
Reflecting the impact of global shutdowns and lower levels of demand across a number of the Group's markets, order intake in the period was down 21% year on year to £76m. However, trends through the period end suggest that order intake should continue to slowly improve, albeit at levels below the prior year in the near term.
Whilst considerable uncertainty remains, Renold benefits from significant geographic, customer and sector diversification. The Group's ongoing focus on cost control, operational efficiency, productivity, and cash management is helping to offset the subdued demand and should enable the Group to make continued strategic progress in the second half.
My opinion - I last looked at Renold here on 24 July, and am thinking along the same lines today. It’s a lowish conviction, small long position in my portfolio - mainly because I think it might be potentially interesting in the future, but don’t have enough information to commit to a full sized position at this stage.
It’s fine to be unsure about things, actually it’s good to be unsure, if the facts & outlook are not clear.
I see some potentially promising signs here though, so am keeping an eye on Renold.
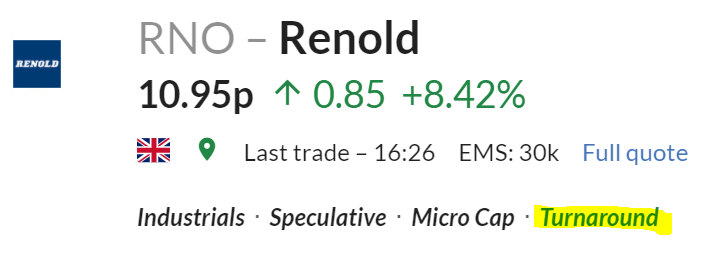
It's interesting that the Stockopedia computers have picked up on the turnaround potential here. Although I heard a McKinsey advertisement today say that 70% of turnarounds fail, based on their research, a thought-provoking point, and sounds about right to me. Mothercare springs to mind!
.
.
** This next section contributed by Jack **
Minds Machines (LON:MXX)
Share price: 4.50p (+9.22%)
Shares in issue: 902,033,984
Market cap: £40.6m
(Jack writing)
Statement re: Contract, Investigation & Board
Minds Machines (LON:MMX) owns and operates a portfolio of top-level domain assets.
It focuses on website addresses based around geographic domains (e.g. ‘.london’), professional occupations (e.g. ‘.law’), consumer interests (e.g. ‘.fashion’), lifestyle (e.g. ‘.yoga’), outdoor activities (e.g. ‘.fishing’) and other more generic names.
On 9 October the group announced a formal investigation into revenue recognition regarding a contract. This had no cash impact but damaged the share price, which dropped nearly 50%.

Today the group updates on that contract investigation and concludes that revenue has been incorrectly recognised.
Cash of $1.125m was received in connection with the specific contract and revenue of $938,000 was recognised in FY-2019. Any cash sums initially received should have been classified as a deposit against future sales and then recognised as revenue as the partner made sales to end-users. It booked sales too early.
To date, the partner has made $201,900 of end-user sales under the contract (as opposed to the $938,000 recognised).
In addition, the investigation has identified two additional contracts entered into in FY-2019 totaling $790,000 where receipts were incorrectly categorised as revenue.
Perhaps the shares are up today because the CEO and CFO have both resigned with immediate effect. Guy Elliott, Non-Executive Chairman has agreed to assume the role of Executive Chairman on an interim basis and former COO Tony Farrow is the interim CEO.
Bryan Disher, independent Non-Executive Director will assume the role of interim CFO.
The group’s proposed tender offer of £3m has also been postponed.
Conclusion
Clearly MMX is trying to draw a line under an accounting issue that has harmed its credibility and damaged trust with shareholders. The investigation has led to another two incorrectly recognised contracts.
It looks like the auditors, Mazars LLP, totally missed this in its auditing of revenue recognition. It’s approaching the 9th year that Mazars has acted as Independent Auditor here, so I wonder if other contracts were missed in the past?
And you might expect existing board members to have discussed such policies, yet they continue to be appointed in interim roles. I note that FY19 was ‘the first year the Group has presented an Audit Committee Report. In future the content and detail of the Audit Committee Report may be expanded, and formal procedures will be put in place to assess the effectiveness of the Audit Committee’s role.’
Clearly this is needed.
In fact, the chair of the Audit committee is none other than Bryan Disher, who has been appointed the interim CFO. Just as a reminder, this committee meets throughout the year to discuss the quality of the company’s financial reporting, and its internal control environment including internal control over financial reporting...
MMX is cash generative but corporate governance questions remain, in my view. I don’t agree with the market today on this one. It’s a big stock market, with lots of companies to invest in - so why go near one that can’t keep on top of its revenue recognition?
Good luck to holders, anyway - perhaps this really is drawing a line under the issue.
.
Tekmar (LON:TGP)
Share price: 42.5p (down 41%, at 12:40)
No. shares: 51.3m
Market cap: £21.8m
(I hold)
CEO’s Review, Trading Update & Change to Year End (profit warning)
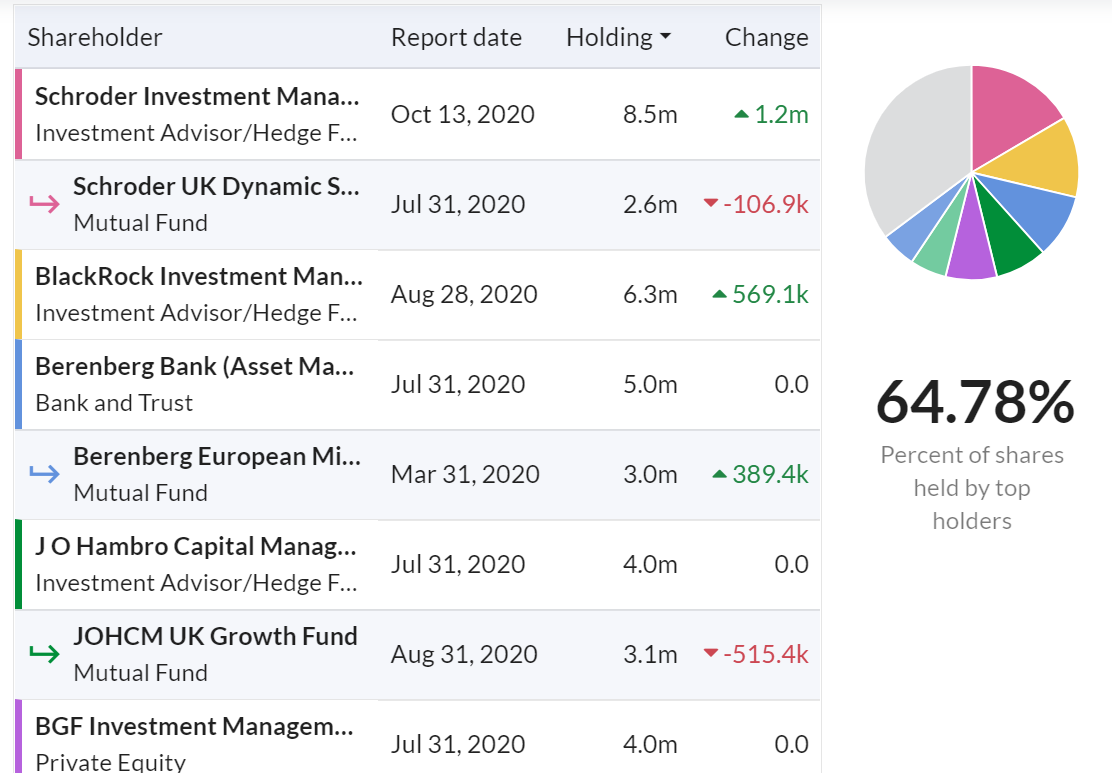
There’s been a brutal price fall on this profit warning, it was down over 50% earlier this morning, and has recovered a little to down 40% at lunchtime. Also noteworthy is the huge volume, and number of trades today. This is normally thinly traded, due to it being a micro cap, and about two thirds of the shares being locked up with major holders;
.
.
Given that 5.4m shares have already printed today (at 12:51), over 10% of the company, plus any delayed prints for larger trades that might appear at the end of the day, then it looks as if at least one institutional holder must be liquidating their position in the market, and it looks as if private investors might be buying up the stock. That often happens when small caps disappoint - institutions dump their holdings, and there’s a shift in ownership towards private investors. This type of situation can be a buying opportunity sometimes, because exiting institutions have to force the price down very hard, in order to attract enough buyers to clear them out. Then once the big sellers have gone, the price is free to recover at least somewhat. Therefore I have to decide whether to top up my position, or not. Or whether to sell up & move on. Or do nothing. It’s only a tiny position in my portfolio anyway, I bought at about 110p, thinking it looked good value, and based on previously upbeat management outlook comments. So I'm not very happy.
Looking back, I reviewed the results for FY 03/2020 here in early August. Re-reading my notes, the figures were OK, and the outlook comments seemed really upbeat. Which does raise the question as to why performance has suddenly deteriorated, and can we trust management commentary? Or is the new CEO kitchen-sinking expectations to set the bar low, and blame problems on previous management? Who knows. Outside investors never really know what’s going on in any company. Only insiders know the true picture, in my view.
CEO Review - is ongoing, results to be announced with H1 report on 1 Dec 2020. This is focused on profitability, through cost savings & efficiency gains. Sounds good to me. Although this sort of reorganisation usually involves some up-front costs, and exceptional write-offs.
...Alasdair and his executive management team are currently working through the details of a business reorganisation which will deliver operational cost savings and further integration efficiencies across the Group, putting the business on a stronger footing and in the best position to grow profitably in the expanding global offshore energy markets.
Trading for the 6 months to 30 Sept 2020 -
During HY21 the Group has experienced some short-term delays in contract awards and sales order intake as a result of the COVID-19 disruption. This has resulted in revenue in HY21 being 10% lower than HY20.
Notwithstanding the disruption to project timings, the visibility of the project pipeline is strong and opportunities in the offshore energy market continue to grow and the focus is now on positioning the Group to maximise on this potential.
That’s a bit disappointing, but does it justify the company halving in value? Seems rather extreme.
Competition - new entrants emerging. This may have spooked some investors, as this could put downward pressure on future pricing & hence margins;
The long-term structural growth prospect of the global offshore wind market is now attracting new entrants and the Group is seeing increasing competition in Tekmar Energy's core market for TekLink. However, through ongoing investment in product development, its new Generation 10 product will help the Group retain its strong market position. Generation 10 will be launched in Q1 2021 and provides a more tailored solution to meet the more demanding requirements of future projects.
Guidance remains withdrawn - not helpful. I would prefer a range of possible outcomes, rather than no guidance at all;
Whilst the Board remains confident that the future of the business remains strong, due to the ongoing impact of COVID-19, the directors consider it prudent to continue to refrain from providing financial guidance for FY21 until patterns of demand stabilise.
Change of year end - the reasons given are logical, but the timing is terrible. Nobody bats an eyelid at year end changes when a business is going well. But to coincide with a profit warning, does raise suspicions with some investors.
The Board believes that it is in the best interest of the Company and shareholders to change its accounting reference date and financial year end from 31 March to 30 September.
The seasonality in the Group's core markets creates a peak of activity around the current financial year end and short-term delays to contracts can have a significant effect on the Group's full year results. Moving the year end to 30 September will allow the management to focus its full attention on the business during its busiest trading periods and the provision of financial results at a more normalised period end.
We’ll now get an 18-month financial “year”, to 30 Sept 2021. I really dislike year end changes, as it messes up the comparability of numbers in the historic tables of multi-year information, such as the StockReport. Although if the year end is causing operational problems, then I can see it makes sense to change it.
My opinion - the share price fall looks overdone. However, I’ve decided not to buy any more, because I’ve got better opportunities on my buying list in larger, more liquid things, where I have higher conviction.
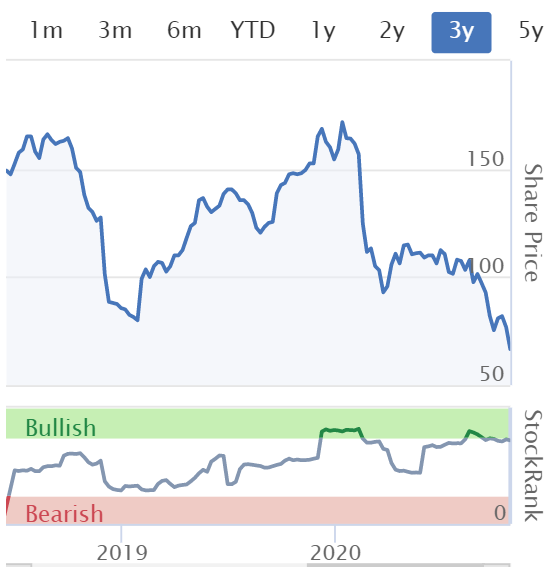
I imagine the high StockRank will lurch down, although there’s only 1 broker covering it, and they might suspend forecasts, in which case the StockRank computers won’t realise that forecasts need to be reduced. This is where manual intervention can be helpful in unusual times like this - i.e. you cannot rely entirely on an automated stock selection system, when forecasts are wrong, or out of date, or withheld completely due to chaotic & unpredictable macro conditions.
.
.
Altitude (LON:ALT)
Share price: 11.25p (down 4% today, at 14:13)
No. shares: 70.1m
Market cap: £7.9m
Unaudited full year results and operational update
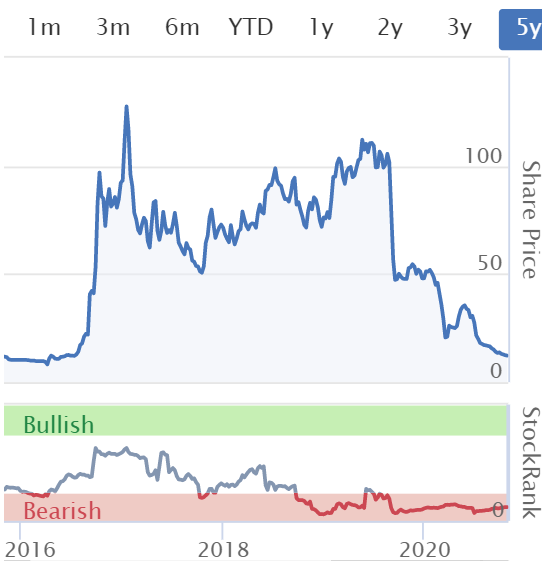
As you can see from the chart below, this share has failed to live up to the expectations of creating an online portal for the promotional goods sector in the USA. Is it a busted flush, or could there be an opportunity here? Let’s find out!
.
.
Note that the StockRank system was very sceptical about this share, even during the boom times when lots of private investors piled into this share, thinking the future was bright. StockRanks are usually low for jam tomorrow type of shares, and personally when I ignore a very low StockRank, I usually end up regretting it! What a low StockRank is telling us, is that there’s little to no support from fundamentals, and the share price is therefore based on hype. Occasionally a share like this does deliver, and becomes a multi-bagger though, hence why it’s interesting having a look at the more credible-sounding stories.
Altitude Group plc (AIM: ALT), the operator of a leading marketplace for personalised products, is pleased to announce its unaudited results for the 15 month period to 31 March 2020….
This period is largely pre-covid, so the numbers are academic now, but just for the record;
- Revenues £8.3m (up 188% due to an acquisition called AIM)
- (Heavily) adjusted operating profit of £461k
- Loss before tax of £(2.7)m
- Plus a £(3.3)m loss from discontinued operations
Balance sheet at 31 March 2020 - looks reasonably OK, providing there are not more heavy losses which could tip it into a more precarious position. As at 31 March the figures look OK, with NAV at £9.1m less £5.9m intangibles, giving NTAV of £3.2m - this includes net cash of £2.35m
Going concern note - says that on base case forecasts, things will be OK. On a more severe downside scenario, the business would need to raise more cash, hence there’s a material uncertainty over going concern. This is a big red flag, and means this share should be seen as particularly high risk.
The Directors consider that such a severe yet plausible scenario indicates the existence of a material uncertainty which may cast significant doubt on the Group's ability to continue as a going concern.
Outlook comments;
Due to the uncertainty it remains too difficult to quantify our short-term profitability whilst the restrictions due to the pandemic continue and the rate of prospective market recovery remains uncertain and therefore we remain unable to give guidance at this time.
The Group has recourse to substantial mitigating factors not currently included in the forecast model which supports the adoption of a going concern basis of preparation.
We remain excited and confident in the prospects for AIM Smarter and we believe that some of the practices and learnings from this period will make us stronger in the future. We have maintained our AIM distributor member base throughout this period representing circa. 8% of the US promotional products market and we believe that as soon as Covid-19 is behind us we will rebuild our revenues and profitability quickly.
My opinion - I looked briefly at promotional products company 4imprint (LON:FOUR) in the comments section below. It shows that demand is still weak, but is steadily improving. Therefore there seems good evidence that this sector is indeed recovering, which I imagine would also help ALT.
I’m not fully convinced that ALT’s business model is any good. Therefore we’re having to assess what impact & recovery potential there might be from covid, but also whether the business has good potential or not. I don’t have enough reliable information to form a judgement on that.
Also, the uncertainty over whether it has enough cash to survive, and the lack of guidance in today’s update, is too much for me. I feel at this stage it would just be a punt, not a reasoned decision, to buy this share. So I’ll pass. I’d be more inclined to have a punt once it’s done a placing, to remove the insolvency risk.
.
It's been a bumpy week, so I hope you're not too stressed out!
We have the US Presidential election to entertain & enthrall us next week.
Plus the worsening covid situation. I was hopeful when UK deaths reduced down to single digits per day a few weeks ago, but am sad to see them now back up to a hundred or more each day. It's a huge quandary as to what Govt policy should be, and how to handle this. I certainly wouldn't want to be in a position of having to make such big decisions, hence why I temper any critical thoughts I might have of decisions & decision-makers.
Let's enjoy the weekend!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

88 comments
Regret come Monday it will be deja vu.
For those in cash it will be an outing to the sales. (eventually)
Watch for shares that hold their value. (as best as poss)
Invest in shares connected to covid-19???
I’m trying to play this forward in my head. Markets will react on Monday (but they were likely to do that anyway before BJs announcement - we will hear increasingly shrill reports from the US next week). The UK needs to come forward with another package of fiscal and monetary support (it was always planned for November). They can’t afford to do so until the US does (or risk devaluing the currency to such a level that is unsustainable). We are in a bit of a stand-off right now until end of next week. Shares likely to fall next week (especially miners who have been retreating this week as support package risk of delay). But they represent a brilliant buying opportunity as they will be massive beneficiaries once next round of spending comes. We need this US election sorted.
The more I think about it there is a huge opportunity next week for good traders - it is going to be intense...
" It’s a big stock market, with lots of companies to invest in - so why go near one that can’t keep on top of its revenue recognition?"
I think Jack hammers home a good point here.
There is no excuse to be investing in stocks that you believe to be bang average.
Altitude (LON:ALT) "a busted flush" - or maybe
"has hit some turbulence"
"run out of air"
"fasten seatbelts and form crash position"
Non-standard Finance (LON:NSF) issued H1 results today - what a car crash, by far my worst investment ever.
Was always a high risk opposition and unlucky to be hit for for 6 by COVID - after all, its USP was supposed to be F2F lending !!!
But despite huge value destruction over p5 years and a series of mishaps (tied to Woodford, failed expansion of Home Collect, abortive T/over of PFG, FCA inquiry into Guarantor loans!), still no sign of CEO/Mgt sharing the pain with pay cuts or job loss.
PE (Alchemy) in the chair with 29.9% of shares and 'supportive' of equity raise but no doubt at a punishing dilution with no guarantee of participation for the little man.
Will be a tragedy if locked out as conditions are now good for well run established non-standard lenders. Got to be a real risk it will be bought and taken private for peanuts IMHO.
I hold KAPE and like the fact that they have managed to fund raise and communicate that effextively and look set to continue to benefit fron the M & A that they have been undertaking. Notoriously difficult to value sucb companies but I have a target of £3 in the next 5 years, and I have been selling at £2 and buying back at £1.6 to benefit from the volatility
Whether Tekmar have been unfairly ravaged today is a story to be written over time. I have some friends in the sector who suggest that they were early in and benefitted accordingly but the sector is becoming increasingly competitive. So my guess is they will stabilise between 40p and 60p. The sector grows 15% per annum which is healthy but if margins (which are pretty slim anyway) are being slashed there isn't much to go at. Problem is there is no moat!
Foxtons (LON:FOXT) statement was covered yesterday in detail. However, after the close more director buying was declared. That is about 280K invested by directors since the April fundraise at 40p. All at about one third of the 52 week high achieved in February (on average).
The FTSE100 pushed down to as low as 5534 this morning. That is getting closer to the April lows (March was lower but soon bounced above current levels). No real panic it seems to me; just a steady decline. There must be value here at some stage but will investors commit more money to the markets even at this level? With dividends being cut or not allowed to be paid I wonder.
Dear Barnet. But what would you buy? I took a small one in Royal Dutch Shell (LON:RDSB) just now as it has just increased its dividend and 915p is so cheap.. Also had a look at Edinburgh Investment Trust (LON:EDIN) which might be a safer way to play the FTSE - the new manager was on Citywire Funds Fanatic podcast and gave a good account of himself.
kgh .....I have bought Bp (LON:BP.) at an average of 192p. Dividend confirmed and at decades low. Small weekly or monthly buys in selected UK investment trusts; agree that is a valid strategy at this level.
I was one of the 0.1% that voted against the Jarvis Securities (LON:JIM) share split which happened today. I thought it a pointless waste of effort and yet today it reaches a new high for no particular reason than there are more shares in issue (at lower value) so what do I know. Pretty sure the market is not that efficient sometimes.
As a side note I popped back to the old site to update my portfolios as the new doesn't have this yet and won't let you do a zero value transaction. It was like visiting an old friend, it's a shame it lacks some newer features because I find it better and more comfortable in lots of ways.
And now Jarvis Securities (LON:JIM) finishes the day down 11%
I sometimes wonder just what is going on that isn't obvious to me? Bonkers.
Doug, try putting a '1' in after several or less zeros, Stocko will then recognise the price but the total won't be changed.
Silver
Good job it cost less than £6k, albeit I agree it’s completely pointless.
Hi please could somebody enlighten me as to why I’ve got 4 negatives on my (LON:MCS) comment? I thought people might be interested that the Redrow owner was topping up his stake as an indication that he might expect a counter bid. I think Paul wrote up the story in some depth when the bid was launched. I’m new to the site and perhaps unknowingly I’ve made an error. Or perhaps people thought it irrelevant. Thanks
I suspect it's because you didn't use the £ sign... the keyboard warriors on Stocko prefer to use the down vote rather than offer constructive feedback.
Helpful Tip: Use the £ sign in front of a ticker to turn Vodafone (LON:VOD) into Vodafone (LON:VOD)
Mccarthy & Stone (LON:MCS)
ha! Yes I think you’re right, I keep forgetting the £, now I know! I thought the brackets turned it into the share name, silly me! Thanks very much Forsby!
Hi Peter,
It is because you simply posted a link with no information beyond an EPIC (and then posted the same again). Had you included the explanation in your latest post, I doubt you would have got the downticks.
You can't reasonably expect readers to click through random unattributed and unexplained links to see if there is anything worth reading.
thanks Effortless, duly noted
If is the post I think it is, then it is just a lazy link to an article that requires subscription/login to read. A precis of the article would be of much more interest. If you could add your unique interpretation as well, then that would be even better.
hi DWit, sorry, I thought the headline to the link said it all, apologies for perceived laziness, thanks for feedback.
But you would have to click on the link to read the headline, even you'd even just copied that in as well as the link, you wouldn't have been under the thumb!
Peter M your post has been removed by Stocko. So we can not comment, but you must have said something offensive, you can always ask Stocko why they remove it
thanks Terry no there was nothing offensive, perhaps just an unattributed link.
re Redde Northgate (LON:REDD) from yesterday . I think this chart shows US data but a similar phenomenon in the UK perhaps given the company's comments re residual values on a couple of occasions recently. The delivery boom. Resale an important part of profit.
https://themarketear.com/posts/cWmpfNgTRa
I think that Jack is a bit unfair to the Minds Machines (LON:MMX) Audit Committee in the main article. The Audit Committee reviews information presented to it by the CFO and the external auditor. If the CFO has misrepresented revenue and that has not been picked up by the auditor, then it is very hard for the Audit Committee to see through this - they would not normally be reviewing contract terms to check that they have been properly reflected in the accounts.
The main failing here would seem to lie with Mazars, the auditor, who could and should have checked that revenue was being recognised appropriately on these new, large contracts. In my view, they should be replaced.
It is noteworthy that the CEO has left forthwith, along with the CFO. That would seem to indicate that he also had prior knowledge of the issue that the NEDs were not privy to. It would be interesting to know if any executive remuneration thresholds were passed due to the inflated figures at end-2019.
LON:MCS
https://reactnews.com/article/...
A request for Altitude (LON:ALT) please, up buttons if anyone else would like this please.
An unmitigated disaster of a holding and the shares down 10% again today after a 15% fall in the week (leaky ship?). The criticisms of this company are consistent, lack of consistent KPI’s and contradictory statements such as optimistic chair and CEO comments about future and cash but statement in rsn saying ‘ the Board has a reasonable expectation that the Company has adequate resources to continue in operational existence for the foreseeable future.‘
Why interesting? They previously supplied software to the AIM network in US, largest co-op of promotional products in US. Then they decided to buy AIM and mash it in with the software platform. They were executing & covid hit, promotional products obviously smashed. But if they recover & and they look like they can, then potentially huge re-rate. They have very high customer support & the model looks pretty good.
So a share in the recovery bucket/multibag potential.
Ah, Altitude (LON:ALT) the company that, iirc, shifted the reporting ‘year’ three months to the right two ‘years’ in a row.
Dog of a share, needs to show profits and growth before I’ll go anywhere near it again. Management have lost all credibility.
Help
Forgive me for going off topic, is anyone else having trouble with the message button.
I get the message "unable to load messenger" and have no idea if it's a general problem or my PC.
Samsgrandad - works OK on my laptop - just sent you a message.
While there found a message (thanks Forbsy) pointing out that it cannot be accessed from the new site.
I raised the disappearance of member to member messaging with Stocko a while back - they said that the member to member messaging wasn't used much, so they had dropped it for the new site. I think that's a big shame - occasionally it would be v useful to be able to contact another member directly. Anyone else disappointed it's gone? Maybe upvote if you agree?
Hi
Sorry this is probably my lack of understanding. Strix (LON:KETL) have announced today are holding a "capital markets day", no PI's allowed but we can watch the video later on the website.
Is this just an update and pitch to the institutions and analysts that they do not understand the business?
Or is this a prelude to a fundraising?
Thank you
Tommy
£KETL isnt that illegal excluding PI’s , or is it only legal if nothing price sensitive is released but given anything they say could change the price....
Really f..... annoying, its not like having people listen on a phone costs time and effort.
Re Strix (LON:KETL) I don't know the legality but I would take it as a message that they don't want me as a shareholder. I've been made welcome at other Capital Market days as a small shareholder in the past. Open management who engage with small shareholders is a big plus point for me.
With webinars they don't even have to feed us coffee or biscuits.
Strix (LON:KETL) did a webinar at 3.30 on 23 September
Tekmar (LON:TGP) Tekmar
Paul, I wonder if you could have a look at this. It is a company you had a look at the last time it reported and formed a generally favourable view on. Since then the share price has continued to drift down until today’s report which has resulted in a circa 40% fall. today. On the face of it the reported review and 10% reduction as a result of deferrred contracts does not seem to justify quite such a dramatic price reduction. Might this represent a good entry point to a currently unfashionable share?
The update looks pretty stark, so not surprising there is a 50% decline on top of a 30% decline over the year. I sadly hold.
1. Increased competition. The long-term structural growth prospect of the global offshore wind market is now attracting new entrants and the Group is seeing increasing competition in Tekmar Energy's core market for TekLink
2. No further guidance FY21. The directors consider it prudent to continue to refrain from providing financial guidance for FY21
3. Change of financial accounting year.
4. Short-term delays in contract awards and sales
Revenue in HY21 being 10% lower than HY20: Which does not seem so bad until you add it all together. Looks like the companies fortune is pinned on the TekLink Gen 10 success in Y21
Really annoying considering it was less than two months ago that the Chairman was so upbeat about the future.
Tekmar (LON:TGP) - today was a little shocking (I hold) given:
- Schroders recently topped up
- recent Boris' ramping of windfarms. You would expect good tailwind.
- H1's performance striked me as resilient
Tekmar (LON:TGP)
I was tempted by this a few months back at around 80p (floated at 150p in June 2018) but I decided they didn't have a "moat" and in selling what are basically plastic mouldings, the Chinese would stomp all over them as and when the potential market had grown large enough. Intellectual Property rights are never an obstacle for the Chinese.
The other concern was that while other countries support their industries and their industrial workers: Britain is for sale to the lowest bidder. Only in Britain would this happen: Scottish BiFab
Yes you read it correctly: Scottish windfarm contract awarded to American company to be fabricated in China and UAE.
Tekmar, I fear for your future.
Bonitabeach
Thanks for this. Out of all the warnings in the update, the one that made me sell $TGP this morning was the warning on increased competition.
Like you say there is little or no preference for local businesses. There are also the costs associated with bidding for these contracts. As the process gets more competitive and complex the cost of bidding drives business out of the process and eventually only the really big companies can play.
Minds Machines (LON:MMX)
I hold and, given today's drop, it's fortunately only a small position.
I'm unsure what to make of today's announcement.
I've been basing my outlook on:
(For reference H1 cash generation was $1.9m, with a usual 2 weighting.)
Neither of the above 2 things has really changed (in fact, the company will need to increase revenues in the books this year), so I guess the big risk now is that there are more skeletons in the closet.
For any interested, I did have my finger on the sell button, and was being allowed to sell my very modest position, however, when I tried to double up, I was unable to buy anything.
I'm surprised by this as I thought everyone would be running for the hills - why is no-one selling?
I'm going to hold for now, as the company is still generating cash and I do believe they will grow. It would certainly be interesting to hear from other holders or followers.
Cheers
A
Morning abtan,
I'm also a holder of Minds Machines (LON:MMX), and see good and bad in this morning's RNS.
The bad is obvious - 2019 revenue and profit were materially overstated by $1,715k and $1,895k, respectively. Looking at the historical revenue trend, it is apparent that new channel revenue spiked up in 2019 H2, so thus is likely when the "misstatement" occurred.
The good? Well, 2020 figures have actually improved; revenue restated $80k higher and profit $211k higher, with more in the pipeline. The company is still cash generative and still trading positively on an improving trend. Additionally, the NEDs have performed impressively, ensuring the investigation was completing quickly and taking decisive action on its conclusion.
I have revised my valuation model to reflect this announcement. The main change has been to move from a PE multiplier at a premium to the market (because of the annuity-like characteristics of its revenue stream) to a discount (reflecting the risk of more skeletons and the makeshift management team in place). I have also simply written off the balance of deposit cash not yet earned as revenue. These changes still leave me with a valuation in excess of 5p per share.
I went up to my shower this morning with MMX down 20% and me deliberating on how to proceed. I came down determined to buy more but found the price had rallied and, like you, I could not buy in any quantity at all but could sell loads, had I wanted to.
My view of the company's prospects is broadly as it was when I made the decision to invest, albeit there is more uncertainty around it. I do also think it is vulnerable to a takeover now, and has characteristics that would be attractive to private equity. I am, therefore, still holding.
RE: Minds Machines (LON:MMX)
I sold my stock when the original revenue recognition issue was announced. It's entirely possible that this is a one-off but painful experience has taught me that any kind of accounting issue is a red flag. About 50% of the time the event is a one-off but those are odds that don't interest me.
In theory, the revenue recognition issues simply move the revenues forward, the original investment case holds and the stock looks very cheap. I'd note, though, that removing both the CEO and the CFO over revenue recognition issues seems like an extreme step.
timarr
Minds Machines (LON:MMX) is a strange situation and actually up 5% at the moment despite the accounting error and departure of CEO and CFO. They seem financially secure and cash generative and have published revised figures for 2019 and H1 2020. If anyone has done a deeper analysis, I'd be interested to know their conclusions.
I've been in and out over the years - to me it seems like a lifestyle company for the employees - especially the former CEO but also too heavily staffed.
I wonder how much Toby Hall and Mr. Salazar made (in bonus and grats of shares) out of these mis-posting of sales?
It might have been worth a punt if you had got in under 4p but from my experience, you need a huge amount of patience to get anywhere with this share.
They have been promising to pay a div for years but went for share buy backs instead because management bonuses were linked to increased share price...
If you can't get in below 4p, it's one to avoid I'm afraid.
Minds Machines (LON:MMX)
Hi FREng and others kind enough to share their opinions on this company,
Following my morning decision to hold, I have done a complete 180 and sold out his afternoon.
I was trying to update my own tables from H1 2019, but then realised that I couldn't.
I can't even work out revenue after partner payments, which is sort of crucial - it looks like partners take a 15% cut, but is that still strictly correct? I imagine it is, but until updated accounts are published, it's impossible to know.
I was also a little thrown by the updated figures today. Why has Investing Cash Flow changed? What does that have to do with revenue recognition? If there were any changes they should surely only happen under Operating Cash Flow.
There may well be an explanation, but as mentioned above, I think we're all flying blind until updated, accurate figures are released, which will be a while away.
I imagine the cash generation will be as good as previously "implied", but I don't think the share price will move for quite some time now, even on positive covid news.
I have a large buy list and whilst I don't usually like chopping and changing, this seems like a good time to make a minor change.
Cheers
A
I know virtually nothing of Minds Machines (LON:MMX) and haven't looked at the announcement - but might the difference on investing cashflow be to do with IFRS16 leases?
Minds Machines (LON:MMX)
Hi Gromley
Today's announcement stated that the issue was with revenue recognition only.
If there was a lease recognition correction as well that they just threw in there, but chose not to mention, then my confidence in the company would lower significantly.
In any case, leases cash flow would be included within Financing Cash Flow, which hasn't been adjusted for H1FY20.
As I mentioned, until completely new accounts are published, it is really hard to understand how profitable/cash generative the company really is.
Cheers
A
Yes, sorry my thoughts were just a case of "drive by commenting" - hadn't read anything and just picked up on a couple of key words and shot from the hip (let's pass on the fact that simile doesn't work if you are driving by!)
From a further (very quick) look I can see that what has happened is that as a result of derecognising/not yet recognising some "cash" transactions have been reclassified from being "operational" to "financing" or "investing" (ie transactions that may (or not) impact the P&L in the future.
Still very superficial but it looks as though they might have reclassified some (net) receipts from customers as either financing or investment. Without further detail I don't fully understand it, but I suspect it is less of an issue than why they had to derecognise (or defer) revenues.
Potentially it does not look like a major issue from a cursory view. However, from a personal experience of a business on a different scale, undue pressures to accelerate revenue (or profit) recognition can be a red flag.
The "resignation" of the CEO & CFO suggest that it may have been a deliberate mis-statement, rather than accidental, but with a will to avoid any repetition I would say it i probably okay.
As I mentioned, until completely new accounts are published, it is really hard to understand how profitable/cash generative the company really is.
Hi abtan
I don't think that matters. If you can't trust the company to deliver clean figures then you can't trust them to do anything. In the end the numbers are a reflection of the business, not the other way around - they're the validation of the business model, the management vision and the company culture. People who invest solely on the numbers are, in general, missing the point (although not as much as people who invest solely on the story).
None of which means this won't come good and make tons of money for shareholders - but that's fine, there are thousands of other businesses out there without governance issues.
timarr
Minds Machines (LON:MMX)
Hi Timarr
I appreciate your comments as always.
My opinion on mistakes in published figures probably differs to most here, because I actually used to be one of the finance bods who put those numbers together.
Mistakes happen.
I certainly made mistakes in my career. An individual learns from them and (hopefully) management learn from them too.
I've seen contracts misinterpreted, revenue missed and costs/rebates not billed for in probably every company/public institution I've worked for, including one that is now FTSE100-listed. Things get missed and slip through the gaps and sometimes someone notices - it's not necessarily a reflection on management that someone somewhere cocks up or information is lost as roles change.
For reference, I do invest solely on the numbers and a set of quantitative rules - I never meet management and sometimes when I have spoken with them, it's hard to think subjectively given the very nature of someone wanting to sell you a positive message. If management or a company are good, it will show through in the numbers.
Well, that's my thinking anyway
As for Minds Machines (LON:MMX) , if updated numbers are good, then I would have no problem buying back in - until then, it's hard for me to quantitatively continue to hold.
Cheers
A
Hi abtan
For reference, I do invest solely on the numbers and a set of quantitative rules
I re-analysed and then sold Airtel Africa (LON:AAF) earlier this month after your considered thoughts on their numbers, so I'm not complaining, far from it ...
I also see our esteemed PM, a details man if there ever was one, is going to pronounce to the nation once more at 16.00. I sense another "investment opportunity" looming. Hopefully investors here are appropriately positioned, it's not as though it hasn't been heavily flagged in advance.
At some point, as spring approaches, there'll be real value in whatever is left in the beaten up and beaten down sectors suffering the brunt of successive restrictions, but not yet, not yet.
timarr
Airtel Africa (LON:AAF) - I hope I haven't made you miss an opportunity there! By a very strange coincidence one of the directors is actually an old university friend, one of the smartest guys I've probably ever known (and certainly much smarter than me).
Given my (negative) diagnosis of the accounts I was quite surprised to see his name and it made me question whether I made a mistake somewhere, so apologies in advance if I've made you miss something too.
I've actually assumed a 2nd national lockdown is already baked into the markets (wasn't is obvious when France and Germany shut down?), but if good news ie a vaccine, is on it's way in the next 60 days I'm happy to hold my majority non-Stay-at-Home-focussed portfolio. I'm hoping quite a few will materially re-rate when that news comes through.
Fingers crossed
Airtel Africa (LON:AAF) - I hope I haven't made you miss an opportunity there
Err, no. I make my own mistakes. It's my capital, if I lose it I have no one to blame but myself. Of course, if stuff goes up I give full credit where it's due - e.g. Purplebricks (LON:PURP) - but it's still my capital! :-)
With Airtel the investment case is a bit hit and miss - the ownership structure is a bit of a governance issue, it's never going to be straightforward. I'm not complaining, I made 65% or so on it - although I lost half of that on MMX and the other half on Tp Icap (LON:TCAP) ...
A vaccine won't tigger a reopening although it will give the markets a few happy pills for a few days. A reasonable guess is that we'll have a relaxation at Christmas and then a further tightening in January (other guesses are available). If working vaccines can be delivered then by spring we'll see a proper loosening of measures, but it's unlikely the initial vaccines will work perfectly and delivering them where they're needed will be a challenge. The aim must be to make sure we don't have the same problems next winter. I'd note that Chris Whitty has so far been the best forecaster of markets during the pandemic.
As regards markets anticipating a lockdown - well, you'd have thought so, wouldn't you? But if you look at the sort of companies that could be made to close again - stuff like Hollywood Bowl (LON:BOWL) or Ten Entertainment (LON:TEG) or Gym (LON:GYM) or Restaurant (LON:RTN) - then the price has barely flickered in the last week. Although On The Beach (LON:OTB), which I do hold, has fallen quite sharply. Maybe this was already priced in, I don't know, but there does seem to be a lot of wishful thinking about.
But perhaps the announcement won't be a full lockdown. We shall see.
timarr
Re £MMX Not a holder and totally not surprised to see that the company that brings us the .sex and .porn and .xxx domains might have some accounting issues.
Minds Machines (LON:MMX) not an ESG then. Apparently all the thing.
Minds Machines (LON:MMX) (no position) have let go the CEO and CFO after accounting errors.
I second Paul’s praise for the PIWorld podcast with Andy Brough and Richard Leonard. In which Richard thought that M&A activities would increase or as he put it ‘the urge to merge’ I for one would really like to see a Stockopedia item on how to spot potential acquisition targets – assuming this is indeed possible from the Stockopedia reports and maybe other supporting evidence too. Would anyone else be interested in this?
Hi Chriskay,
A piece on how to spot M&A targets would certainly interest me as I am utterly hopeless at spotting them. I had one in 2016 (Avesco) and then three last year (Manx Telecom, EU Supply and Safecharge where incidentally, Tedi Sagi was a dominant shareholder) but nothing in between or since. Yesterday, there was a piece in Shares Magazine listing all the M&A activity on the UK market this year, all of which I had been blissfully unaware of. Perhaps these things tend to occur more at the value/recovery end of the spectrum?
I have little further to add other than I concur that it would be an interesting topic to see covered either on Stockopedia and/or by a PI World video guest.
Cheers
Simon
Monumental effort yesterday Paul. Thank you so much.
Thanks lestat101! I'm not an early riser as you know, but I sometimes build up steam during the day, and was on fire yesterday LOL!!! :-D
Morning Paul and Jack. Computacenter (LON:CCC) and 4imprint (LON:FOUR) gave trading updates today. i currently hold both. Im considering topping up on both today and would appreciate your analysisof the updates.
Morning Christian Wright,
Computacenter (LON:CCC) is too big for us here, with £2.6bn mkt cap, and I don't have a view on that company either.
As regards 4imprint (LON:FOUR) - it's a terrific company that I followed here when it was a small cap, but resolutely refused to buy any as it was always too expensive on a high earnings multiple! Of course it multi-bagged, because it kept growing strongly, so a good example of where being too tight on PERs can mean you lose out on the best companies.
I've just had a quick look at the StockReport, and it seems the valuation is already factoring in a big recovery in earnings. So again, it looks expensive! There again, if we ignore analyst estimates, and assume that over time, earnings are likely to recover to peak 2019 earnings of 152p, then the current share price of 2040p would look cheap, a PER of only 13.4. In that scenario, I would expect the share price to rise to 3000p, 50% up on where it is now.
Today's update shows that the business is recovering, current run rate is 35% below last year, improved from 80% down in April. But that still means results for 2020 are likely to look grim. Investors are clearly looking through that, at further recovery, which makes sense to me.
Overall then, the current valuation looks about right to me, but I reckon FOUR has longer term upside potential as earnings recover.
Regards, Paul.
Thanks Paul. a very comprehensive update. I appreciate the details you have given.I bought 4imprint (LON:FOUR) when it was just under 2000p in may and sold half when it got to 2500p in June. i bought back in again in early October at 1949p and was thus considering whether to top up this morning. so far i haven't but will see what the price action is like.
I topped up on Computacenter (LON:CCC) as am a holder from 1600p.
Regards Christian
Stockopedia post
My morning smallcap tweet: Low altitude warning
Volvere (LON:VLE) Minds Machines (LON:MMX) Supply@Me Capital (LON:SYME) Intelligent Ultrasound (LON:MED) Altitude (LON:ALT) Oncimmune Holdings (LON:ONC) De La Rue (LON:DLAR) Open Orphan (LON:ORPH) Tekmar (LON:TGP), AIB (LON:AIBG)
Volvere (VLE) £10m placing and PrimaryBib offer at 1350, a nil disc, ' in furtherance of the Company's investing strategy'. VLE returned cash only 18 months ago! [SP=1302 Cap=25m]. I hold.
Minds + Machines (MMX) the accounting investigation finds that $928k should been counted as a deposit and not rev in FY19. Also 2 additional contracts in FY19 totalling $790k where receipts were incorrectly categorised as revenue. CEO and CFO resign. Proposed tender offer postponed. [SP=4.05 Cap=37m]
Supply@ME Capital (SYME) decides to partner on an exclusive basis with only one investment fund whose intention is to subscribe for the whole of the first issuance (guides c.€300m) and become an ongoing partner. Slightly delays first issuance. [SP=0.43 Cap=141m]
Intelligent Ultrasound (MED) GE Healthcare's Voluson SWIFT ultrasound machine using MED's ScanNav Assist AI technology, has receive clearance from the FDA for sale in the USA. [SP=14.5 Cap=39m]
Altitude Group (ALT) FY(Mar) pretax -£2.7m(15 months) (£2.7m). Net cash £2.4m. "onfident that Altitude has sufficient financial resources and liquidity to see the business through to more normalised market conditions assuming that the steady recovery in the promotional products market place as witnessed since June 2020 continues, whilst accepting that there remains material uncertainty as to the future continuation, rate of recovery and overall economic impact of Covid-19 on the revenue." [SP=11.95 Cap=8m]
Oncimmune (ONC) FY and development update. "Negotiations with the NHS to adopt EarlyCDT Lung are approaching a conclusion with announcement expected soon of first contract to sell EarlyCDT Lung." [SP=180 Cap=114m]
De La Rue (DLAR) BoE uses option to extend banknote print contract by three years. [SP=136.4 Cap=266m]
Open Orphan (ORPH) wins 2-year contract with a tier 1 German pharma co. G'teed revenue, will start this month. That's today then. No €€€. [SP=25 Cap=166m]
Tekmar (TGP) guides H1 rev 10% down due to contact delays. No FY guidance. Extends FY by 6 months to Sept 2021 because of peak demand near FY end. New CEO review to eliver operational cost savings and further integration efficiencies. [SP=73 Cap=37m]
In line: AIB (LON:AIBG)
Hi Paul and Jack. Do you have an opinion on £Vol Volvere fund raise . It seems strange to me what they want to use the funds for.
Thanks
Mark
Volvere (LON:VLE) funds wanted "in furtherance of the Company's investing strategy." Why strange?
The opposite of strange IMO.
£VLE - As an existing shareholder, does anyone know if I have to use the Primary Bid website to take up the offer? Their release this morning says :
"The Company is also conducting a placing of Treasury Shares to new and existing investors at the Placing Price as announced earlier today."
I can't see how to access this through my broker
I took part in a placing for another share with Primary Bid. You need to sign up for an account there and you pay directly to them. Afterwards you give them your broker/custodian details and they transfer the shares to your account
possible investment into unlisted entities
Volvere (LON:VLE) buy companies at attractive valuations & turn them around. The covid crisis should create more opportunities, so it's logical that they want more capital at this time.
EDIT: I briefly considered the Primary Bid placing, then realized that as I cannot use funds already in my ISA, these shares could only end up in a taxed account. I'd rather buy at market prices and have them in the ISA.
I agree Volvere (LON:VLE) may hope for opporunities to buy good companies distressed by covid but more than half of the market cap of Volvere (LON:VLE) was already net cash before this extra fund raise. It has always had a huge cash pile but rarely spends it. Two months ago this company announced a half-year loss again, in fact it has not made a significant (>£0.1k) PBT since it sold Impetus Auto two years ago. I just wonder whether this fund raise-could be opportunistic, possibly marking a top after a terrific run of six+ years? (May not be a popular suggestion!).
HI Splode,
Re: Volvere (LON:VLE)
I've seen Jonathan Lander speak on a number of occasions and have pulled out my notes from 18months ago when he had just acquired Shire Foods. He has a stated aim of delivering 17% compound growth pa which he has easily achieved with Impetus and SIRA. And he said as he was learning more about the food business, he was interested in expanding on their knowledge and assets in this space so long as the price was right. The recent dessert acquisition was small but at a great price underpinned by the property freehold asset.
Whilst it is no mean certain, I believe he needs these funds to greatly expand their food offer and suspect he has a target in mind. So I'm excited about this news.
What is however very frustrating about this retail offer (as I understand it) is that it expires today so one needs funds to hand to subscribe (who has thousands of pounds sitting in their current accounts?). Shame as I was aiming anyway to double up on my holding but haven't bought enough in the market to date.
Cheers
Francis
Volvere (LON:VLE) i think your post is very helpful because it is an alternative view point and thus helps all challenge their bias. For me the 2 brothers have a great track record and have nothing to prove. They have consistently delivered and 2 years ago when they returned CASH it seemed very shareholder congruent b/c they didnt see any opportunities. I like the fact that they have waited 2 years and now the market place has thrown up opportunities. So either they see something of scale or they see more than 1 acquisition.
I was intrigued to see that there are 2 amendments to their terms:
1 - fees paid halved from 2.5% pa. of NAV to 1.25% - this makes sense given the increased scale. but it is a net reduction - why did they accept this?
2 - but also their CASH bonuses on sale will be replaced by a 10% carry in their next investment. a CASH bonus on proven success (i..e the sales price of a business) seems very logical to me, so why is the incentive carried over into their next investment? maybe the shareholders insisted on it as it incentives the duo to continue and not to rest on their last success, or maybe the duo wanted it b/c they have identified a bid opportunity and want 10% direct stake in the turnaround?
Volvere (LON:VLE) disc: i have held but not currently. defo on my watchlist
I only wish Volvere (LON:VLE) would raise a lot more money, and scale up with new investments. At the moment it's too small & illiquid to interest me.
There must be lots of interesting opps out there right now, to buy good, but financially distressed companies at cheap prices.
The Lander duo have a very good track record. They're very selective about what they buy too, so a safe pair of hands. But maybe too cautious?
Regards, Paul.
Kape Technologies (LON:KAPE) update from Progressive Equity Research https://www.progressive-resear...
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.
Hi HollandSmith
Your morning read outs are great as they cover mid and large caps as well as tiddlers.
Gold star.....
Hi Paul
Thanks for your views on Redde Northgate (LON:REDD). I have been buying into this for a couple of months now and was very pleased to read what I felt was a positive AGM statement on Wednesday and then watched as the share dropped 10%!
Richard Leonard made a very good case for the share on a PI world interview on the 7th August here at 42 mins:
https://www.piworld.co.uk/2020/08/07/piworld-interview-with-richard-leonard-investor-trader-life-in-a-family-office/
The Northgate Van hire side of the business is going really well and i feel will continue to do well in the future with the increased demand from Internet deliveries, small business deliveries , Christmas etc . Another positive is that Northgate is disposing of many of its owned vans of a certain age through one its businesses Van Monster. 2nd hand vans are currently in huge demand with prices I believe up in the region of 30% to a year ago (figure taken from a news article i read, sorry no link).
The Redde side of the business doesn't seem to be going quite so well. Traffic levels returning to pre covid levels would appear to me to be a big factor in it getting back to normal. Here is a link to transport use since 1st March:
https://www.gov.uk/government/...
The figures show in brief summary that cars and light commercial vehicles usage went from 100 % in early March to 30-40% in April, 50-60 % in May, 60-70% in June, 80-90% in July, 85-95% in August, 90-100% in September and now in October after some local lockdowns still a relatively high 85-98%.
Clearly more severe lockdowns would not be ideal for Redde Northgate but current traffic data looks to be a positive since the huge April/May drop,. Levels have been between 80- 100 %. since July which appears encouraging.
Despite a slight lack of confidence in the Redde side of the business i feel Redde Northgate (LON:REDD) looks a great value buy at this time considering how much the share price has dropped since March. It also has the added bonus of a nice dividend and the prospect of potential growth with the group acquisition of Nationwide Accident repair services in September.
My lads company got a refund on their guaranteed pick up / drop off parcel deliveries last week, Every hired / delivery van in Manchester were so tied up, packed with Amazon Prime day deliveries, they would not service their regular contracts.
Doesn’t seem much of a “guarantee” :/
I would not be surprised to see road traffic levels rise above pre COVID levels next year because people are avoiding public transport if they can.
On CNBC I see Jim Cramer telling people to buy shares in the US car companies because they are seeing such high demand.
I’m a Redde Northgate (LON:REDD) holder also surprised by the fall in price so I have made the rare step for me of buying some more on the drop.
Redde Northgate (LON:REDD) had a positive update in Sept 20, which felt the headwind of Sept 20 correction. Again with the recent update, it encountered this week's concerns. So unfortunately, bad timing.
It is worth fleshing out a bit of background on Kape Technologies (LON:KAPE) especially as it seems to be something of a bulletinboard / twitter favourite.
The controlling shareholder Unikmind Holdings Limited is a vehicle of Teddy Sagi who has a chequered past.
The company itself has a chequered past. Nowadays it positions itself as "the digital security and privacy software business" under its previous name Crossrider plc is was a originally "the creator of digital advertising platforms specialising in monetising web and mobile media through the use of big data".
Poacher turned gamekeeper maybe?
There were suggestions in the past that the crossrider platform was involved in distributing mal\spyware - I am not particularly well up on the details of that, but it was a good time in the past.
The more recent puzzle for me however is this.
Kape acquired PIA back in December 2019 and based on what we were told it was a very successful US based company and Kape was acquiring them at a very low valuation. A US tech stock bought out at a low valuation by a UK listed business - was that only me that found that odd? Why would the seller be selling at such a low ball price? Well including the deferred considerations, the total price was $53m plus 42.7m Kape shares. The share price prior to announcing the deal was around 80p, so the shares element was just less than 50% of the deal (but with potential to be much more).
Kape (& I think PIA) at the time pushed the story that the PIA founder was really looking forward to driving forward with the new bigger entity. That might have been a reasonable explanation for the apparent lowball price. That story seems to have unravelled now; true the PIA founder originally had c. $44m worth of KAPE shares and now they are getting c. $80m, but it still doesn't make a lot of sense to me.
Just by way of disclaimer - I did short Kape last December thinking everything was too good to be true. That was a painful loss! No position at the moment, but I still have suspicions that things don't add up so I might be tempted if the story starts to breakdown. Of course my scepticism means nothing if they go on to be the next member of the FAANG family!
hi Gromley,
I hold Kape Technologies (LON:KAPE) but i share your concern, when the bought PIA and the co founders were to join and drive the company forward, great, excellent. But i also thought how often does that work out. Founding private entrepreneurs now having to report to a Boss, within the structure and constraints of a plc, hmm.
So now they are leaving, i have seen hiw this can evolve first hand, sadly not as a beneficiary, but the old ceo is heavily incentivised, here $70? , that should keep him focused, but the old CEO imakes himself such a pain, unmanageable & completely maverick, the board just buys him out. Done.
Where this might not matter is the exsting management are SME’s in vpn & they have an extreemly effective in house marketing platform which PIA has been dropped into. That platform is now to supercharge the client acquisition, they have also dropped the prices of the products. They state the focus is now not integration but marketing and clients for the PIA products. If true the next results could really be impressive.
Id like to see the institution holders.
One concern is regulation. Given we are seeing an unbelievable assault on personal freedoms around the world, justified by a disease or not, the rairly discussed option of VPNs being banned is there. Nearly all of the dictatorships around the world ban VPNs, ( i mean china, n korea, etc, not the current European dictatorships :)