Small Cap Value Report (Fri 31 Jan 2020) - FCCN, STAF, GAN, SAA

Good morning, it’s Paul here, with Friday's SCVR.
Estimated timings today - it's a shorter & earlier report today, because I'm off to Malaga for the weekend with a couple of friends, for one of their birthdays. So I have to head to Heathrow mid-morning. So as not to short-change you, I got up at 5am to write some general ramblings here. Then I'll have a quick skim through the RNS after 7am. Fridays are normally very quiet for newsflow anyway.
For any new subscribers, I focus here on small cap results & trading updates. So I won't normally comment on other announcements (somebody asked me to comment on a placing & acquisition yesterday, which I wouldn't normally cover, unless there was something particularly noteworthy about it).
No reader requests today please, as there's not enough time.
This report will have to be completed by 10am, otherwise I'll miss my flight! And yes, I am offsetting my carbon!
Update at 09:14 - today's report is now finished. I think that's the earliest ever finish time!
USA Markets
These seem to be searching for direction. So far, fears of coronavirus haven't had much impact on the US market, as perhaps people are thinking it won't impact them, or is just a temporary factor? Also, I'm told quarterly earnings season so far has been good, which is normal for the US, where companies traditionally tend to set expectations at a level that is usually beaten.
I recently mentioned here the top 5 (by market cap) US stocks are such impressive, dominant companies, that their valuations don't actually look excessive to me. Here's the table again which I posted the other day, from Stockopedia's list of everything in the S&P 500 (in the "Browse Indices" section), which you can then sort & dig into any way you want.
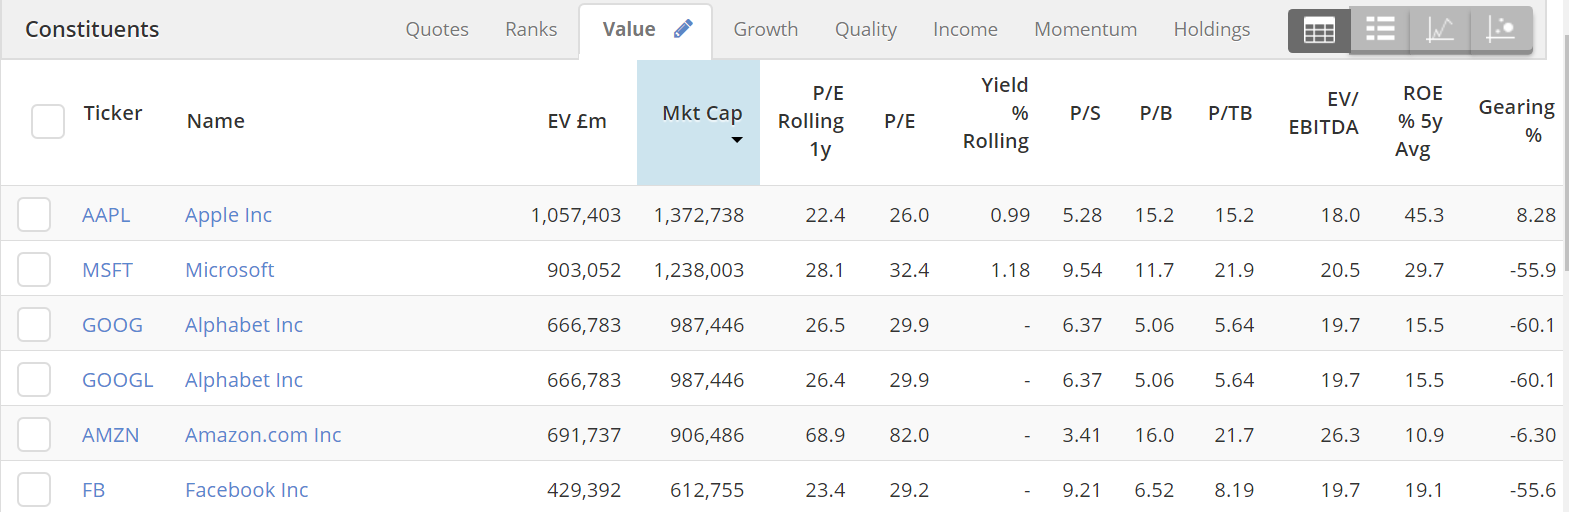
Reviewing the news feed for each company, here is the state of play for the top 5 largest companies (by market cap) in the S&P 500;
Apple - reported on Tuesday, with growth in iPhone sales pushing profit above expectations. BUT it is quite heavily exposed to China. Skimming through the news feed, Moody's says that Coronavirus will temporarily slow down Apple's strong earnings momentum.
Microsoft - reported positively on Wednesday, with growth in cloud computing strong. I heard some very bullish analyst commentary on CNBC, who are expecting the share price to continue rising. Microsoft seems very unusual, in that it was an early computers success story, with Windows and Office software. However, instead of withering on the vine (as usually happens) it has since become an even bigger success in new areas, such as cloud computing.
Alphabet (Google) - it doesn't look like this has reported yet, this quarter. I note from the news feed that it is temporarily shutting all its offices in China, but I don't know if that is significant or not.
Amazon - reported last night, and the shares shot up 10% apparently, on it beating forecasts.
Facebook - the only one of the top 5 to disappoint, with shares down about 6% on results.
Overall then, the 2 largest companies in America have reported positively, as has Amazon. Only Facebook disappointed. The key question is, how much of the total indices do the top 5 constitute?
S&P 500 - google says its total market cap is $28.1trn. By my calculations, the top 5 companies make up $5.3trn, or 18.7% of the S&P 500, by market cap.
Dow - Only Apple and Microsoft seem to be in this, and make up 25% of the total value. Hence the Dow is more closely correlated to its biggest elements, but is only 30 companies anyway.
My hedges - I didn't really think this through, when I decided to (in a bit of a panic) hedge my portfolio on Monday morning. More through habit than anything, I put a big short on the Dow, and also the Hang Seng 50. The idea being that I just wanted portfolio protection, in case the coronavirus spreads & hits my UK portfolio.
Obviously, it feels grubby to be thinking about money, when people are suffering, but we cannot ignore these things.
Given that the 2 largest Dow constituents (Apple and Microsoft) have just reported positively, and make up 25% of the total Dow, then it looks like I've hedged badly, and need to re-think this. So I should probably reduce, or close my short on the Dow.
The Hang Seng short has performed better, because (sad though it is), it's correlated far more closely to the risk factor concerned - coronavirus. Therefore as I want to hedge against that particular risk, this position makes a lot more sense, so I've increased it.
Realising you're wrong - this psychological factor does the most damage to investors. We all find it difficult to close losing positions. Being able to ditch shares on the opening bell, when the bull story has gone badly wrong, often saves a lot of money and anguish, but is so hard to do.
Hence why I'm thinking out loud here, in trying to convince myself that I've made a mistake in trying to hedge my longs by shorting the Dow. It was the wrong instrument to short, and I should now cover some or all of that position. I probably won't though, because like most men, I have a stubborn streak that makes it very difficult for me to make the right decisions, even when I know I'm wrong! It's vital to overcome this problem, if I want to become a better investor. Sometimes I can overcome it, but not often enough.
Tesla - The above reminds me of what's gone on with Tesla. A very heavily shorted, perennially loss-making company share has unexpectedly become a star performer, rising from around $250 to $640 in the last 3 months! The valuation is madness now, but it doesn't seem to matter. Although the company does now seem to be moving into profit, and production numbers are good. There's a ton of new competition being launched now, so it won't have the luxury electric car market to itself any more.
At least two of my friends were heavily shorting Tesla shares, and have suffered large losses. In both cases, they said the same thing to me (independently). One said, "I should have closed my short when the good production data came out" [which is what triggered the start of the huge rise].
The other friend said of his Tesla short, "I've got to learn when to throw in the towel, when I've got something wrong".
These are both highly experienced, very successful investors I should add. So behavioural flaws affect everyone, even the best investors. That's my thought for the day!
Dry January
I've successfully reached the end of Dry January! No alcohol (or, the devil's urine, as I like to call it now) has passed my lips since New Year's Eve. Apart from a shot of Bailey's, which a friend slipped into my hot chocolate without my prior knowledge at Winter Wonderland in early January, because I was apparently "being too boring". So that doesn't count.
I was going to do a charity fundraising for Dry January, but didn't get round to it. However, I'm shortly launching a big fundraising for destitute pensioners in Zimbabwe, more details to follow next week. I've come up with a great idea to leverage small donations into bigger donations, and have agreed with ZANE a specific fund which they desperately need to replenish, to continue doing amazing work with old soldiers who served the British Crown, and their widows, but have been left to die without even basic health care, by the British Govt. ZANE is putting that right (to be fair, partly using some money which was forthcoming from the UK Govt, but is now running out), so it's a brilliant cause. More info to follow next week. I met a lot of these old soldiers when I visited Zimbabwe a year ago, and can attest that they are people you would really want to help, and deserve our help, if you'd met them too. Like the shares here, I've done the due diligence on this.
I'll extend Dry January into the whole of February too, as part of the charity fundraising. Hopefully subscribers here have noticed that my productivity has shot up this month! I've been pulling out all the stops, and putting in at least double the usual time for every SCVR, because I'm hoping that will make subscribers here more likely to support my charity fundraising.
Although this weekend I'm having a free pass, to get jolly with my friends in Malaga, and it would be rude not to mark Brexit Day with a few glasses of champagne courtesy of British Airways. Although my celebrations are going to be muted, and in my head only, because I think we all need to come together, rather than have any more antagonism. Hence the bunting has remained untouched, gathering dust in my wardrobe.
Audiobooks
This section is just a time filler, as it's not quite 7am at the time of writing. Like a coiled spring, I'm waiting for the trading updates to start landing in my inbox, with various pinging noises.
My sister-in-law introduced me to audiobooks some time ago, saying that she was enjoying Brian Blessed's memoirs. Curious, I took a look/listen, and can honestly say Audible has changed my life for the better! These days I probably spend at least an hour each day listening to audiobooks, in otherwise wasted time (e.g. when mooching about in town, or walking around the supermarket, on the train, when exercising, in the bath, etc). Podcasts are great too.
EDIT: Just remembered, that one of our aims for 2020 is to start a regular shares podcast, probably with me & Graham. Or possibly some other format - I've experimented with monologues, but they're a bit boring. Two people is better & more interesting. So watch this space for our podcasts, probably once Graham's settled into his new house. End of edit.
I particularly enjoy political memoirs, and recommend David Cameron's and (surprisingly perhaps) Ed Balls, as interesting & very human memoirs. Both focus not just on the facts & events (as they see them), but also talk about human issues (such as Ed Balls speech impediment, and how he overcame it), and with Cameron of course the very moving story of his late severely disabled child, Ivan.
Gordon Brown's memoirs were pretty dire, I suffered 19 hours listening to those. It's important to challenge oneself though, and to listen to memoirs from people that I might fundamentally disagree with. That's the only way to see a wider perspective, and be less dogmatic.
Which brings me on to my latest audiobook, "Think Big & Kick Ass!" by Donald Trump, from 2007. It's actually quite good, in some respects, as a motivational book urging readers to never give up, and do whatever you're passionate about as work, etc. I don't have to agree with his politics, or like his personality, to find a book interesting.
The pinging has started, let's get stuck into today's news...
French Connection (LON:FCCN)
Share price: 22.7p (down c.30%, at 09:00)
No. shares: 96.6m
Market cap: £21.9m
(I'm long of this share)
End of sale. No, not half price clothes, but the sale of the business has fallen through.
No surprise here really. The sale process has been going on since Oct 2018 - that's not a typo, it's 16 months. If a deal was likely, it would have happened by now. So I'm not sure that talks ending is going to be price sensitive either way, as there's no bid premium in the valuation anyway.
Instead it's going to focus on a turnaround strategy;
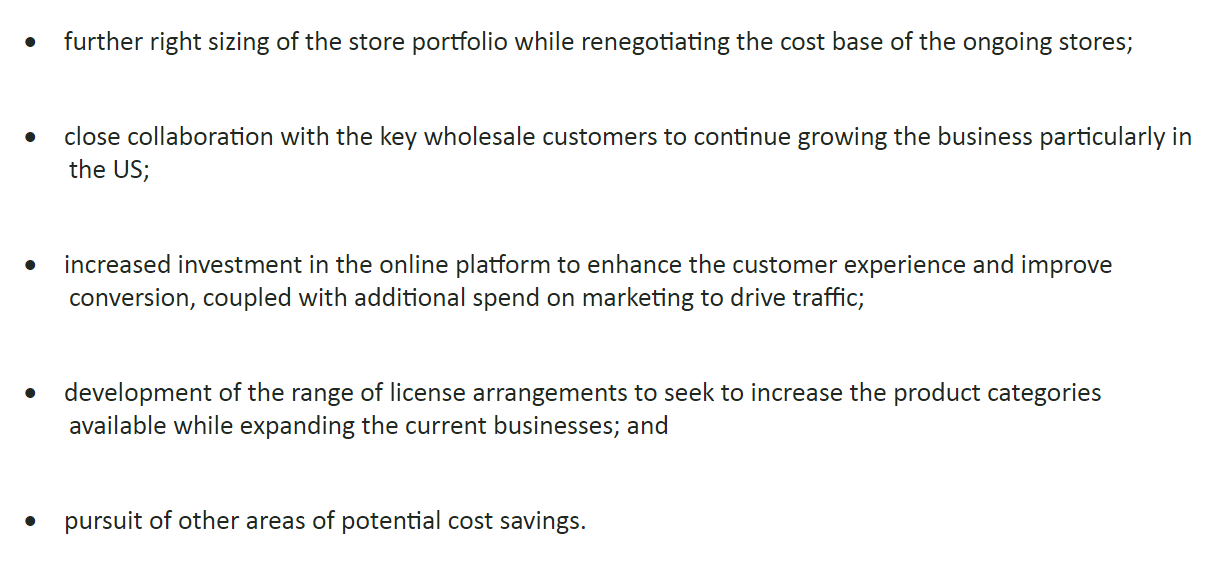
In practice, I suspect this means that potential buyers were not prepared to pay enough to satisfy Stephen Marks (the founder & major shareholder) price expectation for his life's work.
Trading update - this is a mild profit warning, so is more disappointing than the sale falling through;
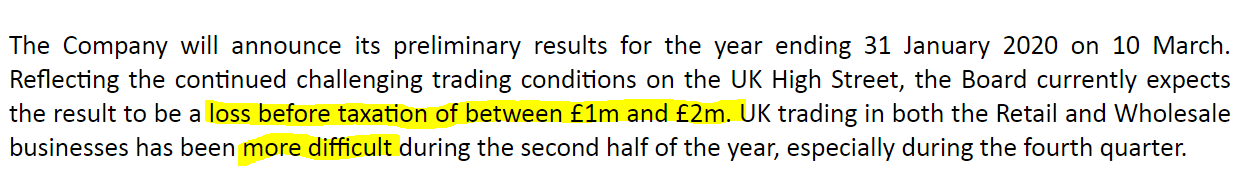
That's disappointing, but not a disaster. The market cap is only £32.4m, and it is fully supported by NTAV of the same amount. The Market was expecting a small profit.
My view - annoying, but not entirely unexpected. I'm continuing to hold, as the licensing & wholesale businesses are good, and decently profitable. Retail losses are taking an eternity to decline, but as the problem leases expire, these losses will slowly disappear. Only for very patient investors though. I expect a sharp fall in share price today (this section written pre- market opening).
Staffline (LON:STAF)
Share price: 67p (down c.10% today, at 09:03)
No. shares: 68.9m
Market cap: £46.2m
Trading update (profit warning)
Investors can be forgiven for letting out a little FFS under their breath, on reading this update.
More accounting write-downs are needed;
Although the year end audit process, with our new auditors, Grant Thornton, is on-going, we have already identified that it is appropriate to increase certain provisions and make further write downs.
Therefore, it's another profit warning;
Due to these net charges, the Board now expects the Group to report full year adjusted operating profit (being profits before interest, tax and non-underlying charges) for the period ending 31st December 2019 materially below our previous guidance.
This announcement is no good, as it doesn't give us any revised figures. Not even a footnote saying what previous expectations were. What is the new guidance? It doesn't say.
Revised forecasts - Liberum to the rescue, giving us the information we need that was omitted from the RNS. An update note from them on Research Tree gives revised estimates, and also provides other useful information - thanks to Liberum for providing this information to us via RT, it's extremely useful to investors and commentators.
FY 12/2019 - EPS forecast is now reduced by 84% to just 2.0p. To understand just how bad this is, consider that the company reported 110.1p underlying EPS in 2018! That's dropping to tuppence for 2019.
FY 2020 - forecasts are unchanged, but who would rely on any forecasts from this company now? I wouldn't.
Outlook - at least things aren't getting any worse, although we're only 1 month into the new financial year;
The Board is pleased to report that 2020 has started well and the Board's expectations for the FY 2020 are unchanged.
Is it likely to go bust? - we're told the bank is being supportive;
Staffline maintains a constructive relationship with its lending banks and consequently the Board does not anticipate any covenant issues.
The Company is also actively considering certain strategic options which may significantly reduce net debt during H1 2020.
As the Liberum note explains, there is substance to this - it sounds like Staffline's Irish business might be sold. Another option is invoice discounting could replace other bank facilities (after all, STAF does have a big, blue chip, debtor book. So lending against that would be very low risk for the banks).
I'm guessing here, but the Singapore investors who recently overpaid for a big stake in the business, which was bad luck as they bought just before a profit warning, could possibly be relied on to stump up loans or fresh equity. The terms might be highly dilutive though, if there's no alternative, and could involve a de-listing, so this route could have ruinous consequences for small shareholders, in the worst case scenario.
My opinion - Banks are not charities, they act in their own self-interest. In this case, the bank(s) continuing to support Staffline, whilst it sorts out other options, is logical. So I imagine the bank pulling its funding & putting it into Administration, is very unlikely.
We don't know how shareholders will fare. There are a range of potential outcomes, and it's little more than guesswork to predict which is likely to happen.
A sum-of-the-parts valuation might be the best way to look at Staffline?
I gave up on this share some time ago, as it didn't do what I hoped for. The accounting & operational problems turned out to be worse than expected. I'm not interested in getting involved again.
There is also the issue of IR35, and companies employing people directly rather than through agencies, to take into account. We discussed that earlier this week, pertaining to £EMR and Gattaca (LON:GATC) . This must have some bearing on STAF too, I imagine.
GAN (LON:GAN) - before I go, just to flag up an interesting-sounding update from this gambling software company. The share price has more than tripled in the last year, and it looks to be gaining new clients rapidly, and moving apparently into profit.
I started researching it this morning, but have run out of time. Readers might want to take a look, and if you think it's interesting then I'll circle back to it next week.
Today it says trading is ahead of expectations, and that it intends to list in the USA.
M&C Saatchi (LON:SAA) - announces the FCA is launching an investigation into its "accounting adjustments".
Not good news for a PR company - I can imagine competitors are likely to use this news to damage SAA in their client pitches.
Not that Saatchi is such a good name these days anyway, after previous bad publicity.
I have to stop there, sorry. Have a lovely weekend!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
Gan (LON:GAN) - another vote from me for your input on this company. I have been a holder for a while and barring any punitive future US regulations/taxation on online gambling consider this has the potential to really expand rapidly.
If anyone has any information or ideas I would be interested to learn more about the breakdown of their income; how much from sports betting, casinos, internet games....
I have had a cursory look around at some basic sports betting patterns in the US.
US football accounts for almost half of all US sports betting and the Super Bowl on Feb 2nd which closes the football season is the countrys biggest sports event for gambling.
March madness - Two weeks of a NCAA basketball tournament is the second largest sports betting event.
Baseball - more bets placed for the world series - at the end of October than the whole April-September season combined.
Does that suggest that their revenue from sports betting drops significantly for six months from April - September ?
Paul, would like to have your thoughts on Gan. I have had great success with gambling stocks over the past few years and put a chunk of realised profits into Gan when it was in penny street and been in and out of it as it was an unknown quantity. However I think the pendulum is swinging in the coys favour and I think a US listing would be the icing on the cake just so long as they do not delist from the Uk.
Thanks Paul for the heads up on the Ball’s memoir. I am currently half way through the very touching Cameron book which, as you say, you don’t have to agree with to enjoy.
May I endorse your comments re ZANE which I have supported for some years now. It is a truly excellent tiny charity doing splendid work in a much needed area.
Enjoy Malaga. Maybe pronounced MyLager? I hope the sun shines.
Mark
Can you also look at the update from Sylvania Platinum (LON:SLP) when you return as well as Gan (LON:GAN)
A second request for Gan (LON:GAN) when you return.
and a third!
One matter just as a general comment about Recruitment Agencies. Many operate providing contractors to companies on longer term contracts. This might be to companies directly, or through some third parties who then contractor an end client.
Under forthcoming changes, theoretically an end client may become liable to any unpaid or underpaid tax due where HMRC believes that the contractor does not pass scrutiny as independently self-employed. That is they are deemed to be in disguised employment, and liable for NI, and income tax that should have been paid as an employee.
Unfortunately the tests for this are often impossible to establish beyond all reasonable doubt, and the tech industry, and probably many Govt projects are underpinned by these contractors.
The rule change was originally introduced for the Public sector, who promptly ditched most contractors. You will note fuss from BBC contractors, for example, who were made to go through service companies, and then were told they had a huge tax liability.
So now its coming around to the Private sector, and it's a total mess, and Recruiters have written to the Govt advising them that projects will go offshore, and work will be lost if this change is put through 'as is'.
A lot of the Banks have already ditched self-employed contractors.
The origins of this particular legislation have been around under HMRC IR35 rules for a while, but this new end client liability has caused a bigger negative reaction. Phil Hammond some years back tried to push through a National Insurance increase for the self-employed, which was unpopular with Conservative back bench MP's, but had the merit of being a direct tax. The new legislation is a consequence of his row back, but is arguably much more damaging because of its inherent uncertainty of application.
So Recruiters will be in the firing line if longer term projects are rehashed, because the end client will push back on taking any liability, and so on down the chain.
Frankly its an absolute dogs breakfast that will hit the tech industry, and recruiters in a way that is unpredictable, but I have my doubts many in Govt understand it.
Recruiters try to include in their terms and conditions that the ultimate tax liability is passed on, but they will get strong push back down the chain now. Why pay a fee to a recruiter if they are dodging liability?
Look forward to the podcast guys, you have a subscriber right here!
$TSLA - Prof Scott Galloway, author of 'The Four' and tech spokesman has long been down on the stock and last year predicted its demise this year. He recently admitted he has got this all wrong and was chastened by a wealthy VC friend of his who advised him to 'never bet against a company with great product'. Clearly there are plenty of cases of great product failing for other reasons, but you have to tip your hat to Musk, whatever you think of him, he has a way that works and it is working. The valuation clearly seems nuts today, as it did 2 months ago when I was tempted to invest following the good production news and unveiling of the Cybertruck. I felt I had missed the party at $320 but its progress is now a momentum stock but where it ends I have no idea, it feels like the Bitcoin run in late 2018. I could nt buy now as it will surely correct at some point, but the company has got an awful lot right and seems unencumbered by the politics and drag of other mainstream Car Builders. Its a very interesting story.
I’m ignoring Coronavirus from an investor point of view, but:
Reports out of China suggest a mortality rate of 2% and a hospitalisation rate of 20%. The latter is stunning; there is no way that the NHS could cope.
Let’s just hope that the number of cases has been hugely under reported, which would reduce the 20% to something more reasonable, and the same with the 2%.
This could be a bumpy few months, especially as by far our largest asset allocation is to South East Asia.
Sylvania Platinum (LON:SLP) 9% drop in profits in Q2 from Q1, delivered 19,206 ounces for Q2 a drop of 8%
Costs per ounce decreased 7% per Ounce which should offset the lower production.
Issues include lack of electricity, water supply and depressed chrome prices impacting on fresh feed sources.
Eskom is the state-owned utility that supplies 95% of South Africa’s electricity. At least one-third of its power stations are broken or shut for maintenance. Due to lack of regulation and corruption, new players are not able to feed into the national grid.
According to South Africas new president Cyril Ramaphosa, an additional 5000 megawatts of electricity is needed to stop the South African economy shrinking but I can't see where this is going to come from given it's not clear yet if he has the power to break the grip his own party has these utilities.
Installed Capacity: 51,309 MW
▪Thermal: 46,776 MW
▪Hydroelectric: 661 MW
▪Other Renewables: 3,872 MW
SA Government making a big deal about a $250 million of financing to support the 60 MW Boschoff Solar Park in the Free State province of South Africa but that is just a drop in the ocean for the required 5000 megawatts. Private players are starting to enter the market but it will require the ANC owners to open up the grid something that they have been saying they will do for over 20 years now.
According to the Economist March is the worst time with Eskom regularly taking 4000 MW out of the system.
I am a holder of Sylvania Platinum (LON:SLP) but electricity is becoming a big concern for me. The requirements of a mine are way too high for generators and companies have no idea if the government will ever deliver anything.
Hi
I think comparing Q1 to Q2 for this company is very misleading. They themselves have said Q2 and Q3 are lower production quarters historically due to holidays etc.
If you look at Q2 results to Q2 and Q3 in 2018-2019 the results appear very positive.
Just my thoughts.
I hold Sylvania Platinum (LON:SLP) but I top slice my big gains, like this one, so I can look at it with a level head. I'm now considering selling out of my remaining position. You added useful info on the power question, thanks for that. But it seems to me that the water issue may be even worse. At least with power, you can see a solution that the country as a whole is in need of. But what's the fix to the water problem?
I have been top slicing and topping up on the dips. What makes me keep coming back is watching the price charts for the PGM group of metals and Rhoduim which just keeps going north. It has top notch management which is key.
Re. Paul’s short position on US large caps, one thing that springs to mind is the heavy concentration in a small number of mega tech caps such as Apple and Amazon in the context of the growing use/size of Index tracker funds and ETF’s. Previously, I’d thought in ignorance that an index such as the S&P 500 was quite diversified and that single company concentration risk was a minor issue. However, as these mega caps get bigger presumably the concentration in the funds get higher which in turn forces the index trackers to buy more of these stocks to track their index benchmark. While it’s a virtuous buying circle in a rising market presumably there’s a big risk that if sentiment or results turn there will be a reverse downward spiral that could get messy. Whether we like it or not, anyone holding a US index linked fund is probably holding a fair chunk of these stocks and isn’t really as diversified as they might like to think.
Gus.
I hold Gan (LON:GAN) and would be interested in an assessment. The shares are very expensive but I think the opportunity lies as individual states in the US roll out legalised gambling/gaming and GAN simply duplicates an existing opperation with new casinos and on-line gaming sites.
A US listing would be very interesting for holders.
While Paul raised the theme of Audiobooks I will post my relevant favourites and hope not to be downvoted too much:
1. Treasure Islands - Tax Havens and the Men Who Stole the World - By Nicholas Shazton Brilliant book about the history of tax havens but also about the fascinating history of the city of London and the City of London Corporation
2. How to get rich - By Felix Denis - From a giant in British publishing an anti-self-help book on the pitfalls of getting rich, growing businesses and the value of ownership.
do members have any view re the market now that the coronavirus has been confirmed in the UK?
Paul, I wouldn't attempt to tell you what to do, but I commented on your US short when you opened it, so I'll take the liberty of commenting on your updated position.
I doubt you remember my comment, but given what I said before, I obviously agree with closing your US position. But the best hedge for your portfolio (which was your declared intention) is still the FTSE250, considering all factors including liquidity. A short on the Hang Seng is less a hedge and more an active bet against that index.
You are still exposed to a divergence between UK small caps and your shorted index. There are many reasons why they could diverge, with the Hang Seng outperforming the UK. Hong Kong was in recession before the coronavirus outbreak. The political protests and trade wars had a big negative impact and the Hang Seng underperformed global indices all last year. In many ways, it is now primed for a rebound.
That rebound could easily come at a different time to the UK. Consider one example: reports show that the outbreak is slowing, with little impact on Hong Kong. Markets rise in anticipation of better news, as they always do, causing you to close your short, then a late outbreak in Europe/UK hits shares here badly, causing you double losses. That's just one example.
An active bet against the Hang Seng might still have legs, I'm not comenting on that, and It's not for me to tell anyone what to do. But I thought I'd update specifically on hedging in case it helps anyone out there clarify their own thoughts.
short and sweet. and getting it finished so early...well done Paul...Have a good and sober weekend
The other friend said of his Tesla short, "I've got to learn when to throw in the towel, when I've got something wrong".
Even more important I believe is to learn when to throw it in when you know you're right
Enjoy a well deserved break Paul and thanks (to you and Graham) for all your efforts in these excellent reports. The general/macro musings are also a really good read, please keep them up too!
I would be interested in your thoughts in Gan (LON:GAN) too if you get a chance when you get back - I currently hold and very positive about it.
Have a great break Paul.
As an aside a Tweet this morning:
”Jeff Bezos’ wealth increased by one Ray Dalio after hours yesterday!”
Yes please Paul. Enjoy your short holiday and a look at Gan (LON:GAN) when you get back would be most welcome.
Sold my small holding in French Connection (LON:FCCN) this morning. Taken a big loss percentage wise, but thankfully was only a small amount of money.
Lesson learned - holding a share on the basis that might be taken over is more risky if the company behind it is not great quality (or something like that). Staffline (LON:STAF) could be viewed in the same light I think.
On a positive note, it has removed one of the big RED shares from my portfolio.
FCCN seems a tale of two different businesses: the wholesale one is currently good, the retail one very bad.
They have cash, but how much of that is going to be left by the time the problem leases expire?
A lot of their stores also are in concessions in House of Fraser or John Lewis. Both of these will have to trim stores, and IMO the massive department store seems a flawed business model nowadays.
I ain't so sure a predominantly wholesale or licence-led company will work in the long run. Already FCCN have drifted downmarket on this in the form of cheap cosmetics and if you so wish you can pick up a FC suit for £50 or a jumper for £10 on M&M. In time the value of the brand decays. There are plenty of other brands which were premium one time but now are pretty much junk, ie Peter Werth/Pierre Cardin.
That said, a takeover could still happen at any time. I wouldn't mind betting that if the brown stuff truly hits the fan in a couple of years or so due to the cash running out, the brand will end up in the hands of Mike Ashley. For Marks it might boil down to a simple choice of that, or FCCN simply disappearing and to be truthful even if it did it would hardly be missed in the market.
Do we know if £gan will dual list or delist from aim. If so what happens to uk holders
I believe the plan for Gan (LON:GAN) is to dual list
Have a good weekend away, Paul.
Although you say the Wholesale business is good in French Connection (LON:FCCN) they do state that business for Wholesale in H2 was more difficult, and especially in Q4.
Paul I love you very much but "offsetting" is not really an option.
"Investors can be forgiven for letting out a little FFS under their breath." LOL
You know us well Paul. :)
What a coincidence that French Connection (LON:FCCN) was in a position to report a warning on the same day as it ended the sale process.
Most Q4 sales were surely pre Xmas and up to early Jan. Peers reported well before now.
Not good enough.
Tesla - The above reminds me of what's gone on with Tesla. A very heavily shorted, perennially loss-making company share has unexpectedly become a star performer, rising from around $250 to $640 in the last 3 months! The valuation is madness now, but it doesn't seem to matter.
Is the valuation madness though?? , they model Y (in production as we speak) should be a real cash machine and provide some good operational gearing for the company also if the (ridiculous) pickup takes off and compete with the for F100. I can easily see the company generating $3 bill a year in profits (ignoring any investment in future discretionary products) in 24 months time - pe of 30 then for a company whose customer tech interface is probably only rivaled by apple doesn't really seem ridiculous. Would i take the risk and buy at current prices - No. But do i think the valuation is ridiculous - No. I think alot of bods have seriously underestimated this companies ability to survive and grow into its valuation. Come on though Elon raise $5-$7 cash now and bump up the balance sheet.
To me the popularity of the model 3 says it all - it is popular and has beat the competition into oblivion, the model Y will doe the same bit on a greater scale. Why bet against inevitability? - all IMHO and i could easily have egg on my face in that regard.
This is about the most sensible comment on TSLA I've read on a public board. It is making very popular products but, more importantly, has invested in a huge infrastructure that others will struggle to match. Those who assume it is clearly overvalued because it is valued at more than GM and yet GM sells more cars really are missing the point.
Hi Paul,
Hope you have a great break. With regards struggling to sell mistakes - I've found a solution that works for me. Particularly when things have gone wrong and I know it - but I'm struggling to press the button and thereby realise the loss and the damage that that will do (psychologically and to my realised returns) .
What I do is sell a proportion of the holding. Often it's quite hard to sell the lot - so instead I sell half, or a third. Bizarrely I find it much easier. It reduces the potential risk of further damage and it also partially insures you against that horrible situation where you might be selling right at the bottom (a skill I am excellent at).
Then after a few days you can review the position and if it's still going the wrong way sell a bit more (which is again easier - as you feel pleased with yourself for calling it right with the previous sell). And of course if things have bounced up, then you feel pleased with yourself for not selling everything. Both ways you end up being able to pat yourself on the back and move forwards.
Hi dfs12, I do the same - can feel comfortable pretty much which ever direction the share price takes afterwards.
I've started to do the same and feel far more comfortable with my larger holdings looking like winners with the loosers looking far smaller. What I've not managed to do is average up which some investors do - thus baking their winners with more capital. I've never had the confidence to do it and isstead slice some profits.
Jim
I used to follow the edict of selling half when the price had doubled, so that the remaining holding was `free'. But I found that I was then likely to be annoyed whatever happened. If the price went up I kicked myself for having halved my profit; and if it went down I kicked myself for having not sold the lot!
In practice I've found that a trailing stop loss is the best solution, as it cancels out the gambling instinct, though that then raises the problem of how big a margin to allow to trigger a sale. And, of course, it can also effect a sale when there's just a blip in an otherwise upwards trajectory.
There's no perfect solution. Much as I enjoy investing I can see all too easily why so many people just invest in managed funds!
I also sometimes use the sell half if it doubles. Sometimes I kick myself for not keeping the whole investment going, sometimes it works well as it has for me with PURP. I still feel the estate agency market needs shaking up, and am more relaxed now to hold some PURP (who may or may not be the right bet on this), but as it is now a small holding, and cost me nothing it's OK
I have been arguing the bullish story for Tesla for a while but their valuation at the moment has certainly gone too far. Eps of 56 cents per share on a company trading at $640 is completely stretched based on any potential growth model.
The return on investment at the current price is a very long time!
Apple on the other hand, there seems to be a lot of upside there. I have been down on Apple for years but the thing which shocked me with their results was the ability to increase base users of hardware again by 10%!
Services were flat as it isn't quite there but considering it has the cash and short term assets in hand to outright buy Netflix, I think it can certainly put that right.
I'm considering buying it for the first time ever and trading at 25 times earnings makes it all the more attractive.
A similar story can be made for Microsoft it seems but kind of in reverse as it is more driven buy cloud sales.
Paul, as always many thanks for your honest and enlightened writings. Enjoy Malaga.
piworld were recording the analyst presentation for SThree (LON:STEM), on Monday (when results were announced), here's the video, with the (relatively) new CEO Mark Dorman, and CFO Alex Smith.
https://www.piworld.co.uk/2020/01/31/sthree-stem-fy-results-presentation-year-end-30th-november-2019/
SThree (LON:STEM) are the only specialist STEM recruiter. (STEM stands for Science, Technology, Engineering, Maths).
Hats off to SThree (LON:STEM) (and any other companies) who publish their analyst presentations, so all have access.
Arrived in Malaga last night. Blue skies, warm temperature and strong coffee. 'Tis a good call at the end of a grey January.
timarr
I publish and tweet these daily: always useful to look at the Yin to the RNS Yang
French Connection (LON:FCCN) has pretty low liquidity but clearly a lot of folks were holding on the expectation of a sale
Warning Rant
Staffline (LON:STAF)
What a disgrace the board of the company are , really shareholders (particularly anyone who has stumped cash since the January update last year ) have been royally screwed by the jackanory false statement made to the market coming from the board. Not sure whether it has been deliberate , hapless or a bit of both but it's not often i will slate a companies board like Staffline (probably not sensible in the current litigation era). Really this company is a complete writeoff. Damn disgrace that they can't give us the truth and wrap it up in excuses. On ething the board are well paid to do is give us numbers that bear relation to reality and this company doesn't.
Specific issues - what they sai on 30/1/2019 last year.
Further to this morning's announcement, the Company can confirm that this morning concerns were brought to the attention of the Board relating to invoicing and payroll practices within the Recruitment division.
The Board is confident that its policies in relation to these matters are appropriate,
I would love to know what checks they did to see that they were performing their duties and why they were so confident there were no issues when plainly the numbers were a heap of crock. It's bad enough having a heap of crock but to go to the specific time and effort of saying its not while it is is ridiculous. Simple
12/3/2019
The Board remains confident that its policies in relation to these matters are appropriate. However,.............
Hold on you start admitting you have a heap of crock and at the same time say no biggie - time to come clean guys and gals and nope lets pretend there are no issue. There as clearly a false market in these shares from that day onwards with the obvuous elephants in the room being ignored and saved for many later days.
What they say today doesn't matter as theboard has no credibility but is more of the same - i don't believe it.
the Board has continued projects to improve Staffline's internal controls.with our new auditors, Grant Thornton, is on-going, we have already identified that it is appropriate to increase certain provisions and make further write downs.
I would love someone who knows the legal aspects of what duties directors have to shareholders to look at every one of the directors of this company and do a detailed investigation of whether they have been remiss (or worse) since january 2019.
Rant over
I know it is not really the satisfaction you are looking for but worth pointing out that Ed Barker (NED and chair of the audit committee) has resigned from Staffline (LON:STAF) board effective today.
Also what I don’t understand from today’s announcements, which on the surface seem to be mostly accounting charges and provisions, is why Liberium’s spot net debt forecast for FY20 has increased by £21m to £65m. I can’t follow Liberium’s reasoning that higher growth in Recruitment in FY20 will use more working capital - as Liberium has not changed its forecasts for FY20.
Paul - Malaga is a great place for a long w/e, enjoy yourself
Must admit I didn't carbon offset my last w/e there!
Your dry (January) Rambles have been most enlightening
Not necessarily inviting comments on the latest announcement by Optibiotix Health (LON:OPTI) of yet another “mega Slimbione distribution deal” (this time in the US) but just wanted an excuse to share this classic Farside cartoon to lighten the mood.
Gus.
Change the company name.
My morning smallcap tweet: STAF & FCCN big downers. I hold both.
Staffline (LON:STAF) GAN (LON:GAN) Gulf Marine Services (LON:GMS) French Connection (LON:FCCN) Toople (LON:TOOP) EQTEC (LON:EQT) Open Orphan (LON:ORPH) Billing Services (LON:BILL) Novacyt SA (LON:NCYT), Northbridge Industrial Services (LON:NBI), Smart Metering Systems (LON:SMS)
Staffline (STAF) MORE provisions and write-downs. FY adj op profit will be materially below our previous guidance.. FY20 unchanged.
GAN (GAN) sees FY rev up 115-120% and EBITDA margin ahead of market expectations.
Gulf Marine Services (GMS) rolls covenant tests again to end Feb.
French Connection (FCCN) holders' patience rewarded with a slap in the face. After an absurd 15 month attempt to sell itself it ends the process. Co will "will now focus on completing its turnaround." Will continue to cut costs, close stores, expand licencing etc. Guides FY pretax loss £1-£2m due to poor Q4.
Toople (TOOP) £1.2m placing at 0.1p, a 38% discount to buy another comms co, DMS Holding, for £1.56m (mostly in new shares at 0.1p). Also issues £1.63m of zero coupon secured Loan Notes to raise £1.24m net. Acquiree is "cash generative, accelerating Toople's timeline to achieve profitability and positive cash generation."
EQTEC (EQT) new CEO 'very pleased' progress. Lots of positive noises but no new numbers.
Open Orphan (ORPH) £5m (min) placing at 6.1p, a nil discount, "to fund the growth and synergies programme" after recent merger with hVIVO.
Billing Services Group (BILL) sells BSG Wireless business for $5.25m (£4m). Leaves the struggling Wireline Business and the stagnant TPV Business. Will return some of the cash to holders. BILL cap £3.1m.
Novacyt (NCYT) launches the research-use-only novel coronavirus test which it mentioned in finals 3 days ago.
In line: Northbridge Industrial Services (LON:NBI) Smart Metering Systems (LON:SMS)
Re: Short the DOW
Not sure your instinct/logic was wrong. Seems a sensible hedge to me (WDIK).
Maybe better instrument in Short dow/Long Faang??
Warning tax return deadline day today !!!! - hopefully all slackers have their gateway login details to hand and haven't consciously forgotten that the generous 301 given has almost elapsed.
Not Just returns but also payments due
FWIW (and not advertising) when in practice I used TaxCalc a simple way to do and submit ITRs
Now retired still only costs me £30 or so for multiple returns for the family
As with all these things, like selling losers and not pressing the buy button when you should, its just a question of gritting teeth and doing it and then sighing with relief when done along with a small dram
Morning Paul,
I’ve been a Stockopedia subscriber for about a month and find these daily reports excellent. The insight provided is invaluable. Thanks for all your efforts and enjoy the weekend away in Malaga.
Kieran