Small Cap Value Report (Fri 31 Mar 2023) - TGP, TPX, NCC, SWG, EMIS, ECSC, JHD

Good morning from Paul!
Today's report is now finished.
A busy week, with 2 CEO interviews published this Weds & Thurs - a reminder of the links here -
Interview with Dorian Gonsalves, CEO of Belvoir (LON:BLV) - I thought this went really well, lots of interesting points about the property market. I rate this share highly, and despite a recent bounce, it's still attractive value on a PER of about 10, and divis yielding about 4.7%. On top of that, it's paid off all bank debt in recent years, and has self-funded more acquisitions. Management impress me as down-to-earth, experienced, hands-on people. They'll be at Mello Chiswick in May, so you can meet and chat to them, as I did last year. A big thank you also to BLV for making a generous donation to ZANE, my favourite charity providing humanitarian aid to destitute pensioners mainly, and other terrific projects, in Zimbabwe.
Interview with Mike Raybould, CEO of Portmeirion (LON:PMP) - another interesting interview I thought, with more energy than the rather dry presentation on InvestorMeetCompany! The group is performing well, and has a large tailwind this year from freight costs which will be millions lower than last year. High inventories are also likely to normalise, which should wipe out net debt in 2023. Given the decent 2022 figures, and sound outlook for 2023, this share looks obviously under-priced to me. There's also a decent yield too.
The weekend podcast from me will go out early tomorrow, because I'm jetting off to Malta (Gozo) for 4 weeks! I'll be on holiday for 2 of those weeks, so Graham & Roland will be covering things here. Obviously I'll be heckling from the back, in the reader comments, I won't be able to keep away!
Have a lovely weekend everyone! :-)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
It's quiet for news today, being a Friday. (EDIT: or at least it was quiet!) This is what's on my list -
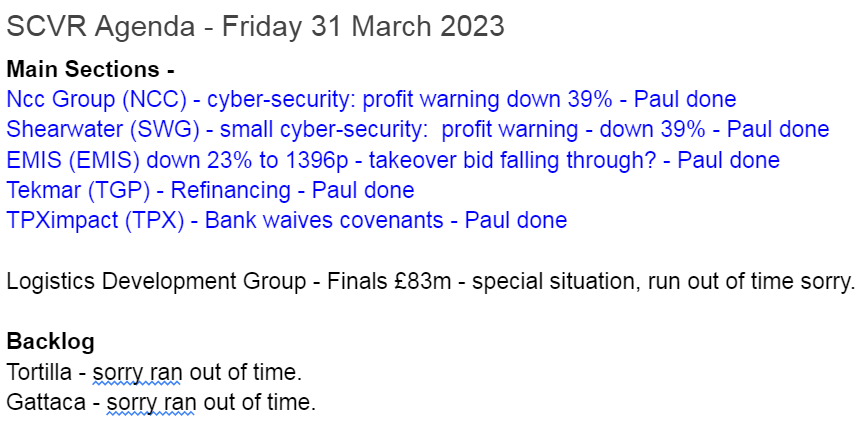
Quick comments (no sections below) -
Ecsc (LON:ECSC) - Another cyber-security company! Nanocap £2m mkt cap last night, receives a recommended bid approach at 54p cash, a 170% premium on an admittedly bombed out share price. (no section below). There was me thinking Fridays are quiet!
James Halstead (LON:JHD) - Interims - up 1% to 182p (£790m) - revenue up, but PBT down 9%. Quality company, making a healthy profit margin of 15.5%. Nice strong balance sheet. Inventories reduced in last 6m, but still look high. Strong cashflow statement, and pays out decent divis (yield 4.3%). Shares down a lot in last year, but still not exactly cheap, on 18.7x PER. Decent outlook comments, “very encouraging” recent weeks sales & demand. Could be worth considering an opening position, possibly? V good long-term share price performance.
EMIS (LON:EMIS)
Down 23% to 1396p (market cap £878m)
CMA Investigation - This is an unusual situation. A recommended takeover bid has been in progress for a while, as you can see from the chart looking like a table. The UK’s Competition & Markets Authority (CMA) has put a spanner in the works, by rejecting a proposed remedy for CMA’s previous concerns. So a phase 2 investigation is now happening. Both parties are “considering their options”. Judging from the share price reaction, it looks like investors reckon the deal’s likely to fall through. Pity, as it was a generous bid (at 29x PER).
This raises the question of whether it’s best to wait for a bid to complete, or maybe even be improved, or to sell in the market once a bid is announced. At the moment it’s looking as if selling in the market was the right move here - hindsight eh! Bad luck to any holders, but who knows, the deal might come back.
Shearwater (LON:SWG)
Profit warning - another cyber-security group that issues a profit warning - down 39% to 50p (market cap £12m)
Says much the same things as larger NCC - customer spending decisions slowed or stopped in Q4 (of FY 3/2023). Resulting performance “significantly behind market expectations”, guiding £breakeven adj EBITDA (forecast and LY actual were both £4.4m, so this is a big miss) - ouch, that is bad.
Also a £0.8m hit from unhedged forex movements. It is hedging from now on.
Net cash is up though, at £3.4m.
Says the pipeline is still strong.
Last balance sheet has an odd item (£7.1m non-current receivable - what’s that for?) and is dominated by intangible assets. Only £3m NTAV.
My opinion - not clear that this is a viable business - history shows it’s never made any significant profits, usually loss-making. No divis paid historically. But £12m market cap is very cheap - recovery opportunity possibly? Delisting risk, as 6 big shareholders own c.63%?
Tekmar (LON:TGP)
9.0p
No. shares: 61.0m existing + 80.8m fundraising + 11.1 retail offer = 152.9m after the placing + up to 155m convertible loan shares = 308m potential shares assuming full conversion of the £18m convertible loan facility. Of this, SCF would own 70.4% of the maximum enlarged share capital. So existing shareholders are now just along for the ride, with SCF now in effective control.
Market cap £14m after placing. Then up to £28m if convertible loan fully converts (£18m)
Refinancing - SCF Partners (private equity firm) is the new investor (putting £4.3m into the placing element of this). Talks have been going on for a while, so we knew TGP was trying to refinance. It’s raising £7.3m through issuing 80.8m new shares at 9p each - the same as yesterday’s closing price, and similar to what we’d be guided to expect in previous announcements. That’s big dilution, more than doubling the share count from its current 61.0m.
There’s also a convertible loan deal, up to £18m over 3 years, which if ultimately converted would be a lot more dilution. The convertible loan facility is described as a “war chest” primarily for acquisitions. The terms put SCF in the driving seat - it can “request” TGP to draw down the loans, or they can be drawn down at TGP’s option. Repayment is 2 years after drawdown, which seems quite short term. Not cheap either, with 10% interest. Conversion price is 11.6p.
There’s a retail offer of up to £1.0m alongside the placing, which is good to see.
My opinion - Tekmar has been a disastrous float (in 2018), going from being a nicely profitable company, to a cash-strapped basket case, with the share price collapsing accordingly. It’s good to see the company securing proper finance, but all of this is likely to limit the upside on the share price, due to heavy dilution. It should at least de-risk the company by properly funding it. Looking at the terms, I think this effectively hands control of the company to SCF. So it’s probably best seen as a deferred takeover bid priced at 11.6p. That’s not enough upside on the current share price to make it worth my while buying and holding this share. The upside case would be that the expansion strategy results in the creation of a much more valuable company, but SCF would get most of the benefit from that, so what’s the point in maintaining a stock market listing? It’s quite a strange deal - I don’t see why SCF didn’t just take over the whole company. I can't get excited about this share, so it's just AMBER for me, assuming the refinancing deal completes.

Tpximpact Holdings (LON:TPX)
Up 10% to 31.4p (market cap £29m)
Covenant Waiver & Current Trading
Continuing the theme of lousy floats and financial distress. This software services company has been on a knife edge recently, due to onerous bank debt. I last looked at it here on 31 Jan 2023, when it fell 38% to 28p on a profit warning, also flagging a likely bank covenant breach on 31 Mar 2023 - very high risk, so I had to flag it as RED. There's a 10% relief rally today, but I don't think shareholders should be celebrating yet, as it's not out of the woods by any means.
Crunch day is today, talk about cutting it fine. The bank has given it temporary breathing space -
Further to the announcement made on 31 January 2023, the Group reports that it has been granted a waiver from the requirement to test each of the financial covenants applicable to its £30m revolving credit facility as of 31 March 2023. TPXimpact's lender is currently undertaking a review of the Group's short and medium term cash flow forecasts, the outcome of which will determine the nature and extent of future waivers. A further update will be provided when this review is concluded.
I don’t like the sound of that one bit - bank reviews often end badly. It seems to me that a placing (on possibly bad terms for existing holders) might well be the price for ongoing bank support.
Current trading/ order intake sounds OK though -
The Board confirms trading in January and February 2023 was in line with management expectations. In addition, the momentum in new orders has continued in Q4 FY23, with new business wins of over £30m in the quarter.
My opinion - still too high risk. I wouldn’t want to hold this share until it’s properly refinanced, which I think would need to involve an equity raise. Even then, it’s not clear if this company is actually any good or not. So why get involved? It might be a recovery situation, with breakeven forecast for this year, but a return to decent profit next year FY 3/2024. So if that recovery in trading is achieved, the shares could recover too. As you can see from the chart below, this share was a stock market darling in 2021, so there's plenty of scope for it to rise substantially, if dilution is avoided. So high risk, potentially high reward I'd say. Might be worth a closer look once the financing has been sorted one way or another. Overall, it's too high risk still, so I have to maintain my RED stance.

NCC (LON:NCC)
93.6p (down 38% at 10:14)
Market cap £292m
Bad luck to shareholders here, with £186m wiped off yesterday’s £478m market cap. It's a profit warning I'm afraid.
Trading Update (profit warning)
NCC Group plc (LSE: NCC, "the Group"), a leading independent provider of global cyber security and resilience services, is today providing a revised outlook due to further deterioration in the macro-economic and market environment.
The current year is FY 5/2023.
Previous guidance (with H1 results) was FY adj operating profit of £47m.
Since then market conditions have worsened, especially in the USA.
Delays & cancellations by customers, driven by tech sector staffing layoffs.
Banking turmoil recently has led to reduced customer appetite for tech project spend.
Higher interest rates and inflationary challenges for customers.
New guidance - adj operating profit £28-32m.
Cost-cutting is now being considered.
Challenges above expected to continue into FY 5/2024.
Strategy is to deepen client relationships & offer broader services.
Confident in medium term prospects.
"Macro-economic headwinds, market volatility and uncertainty are undermining business confidence, particularly in the technology sector where we are well represented, and as a result we are seeing demand fall in the form of projects being further delayed, reduced or cancelled.
I’m not familiar with this company, or its cyber-security sector, so I can only really comment on the numbers. Here’s my take on the last H1 results (6m to 30 Nov 2022) -
Net bank debt of £54.8m is quite hefty, but well within an enlarged facility that was agreed in Dec 2022 (4-year £162.5m RCF +£75m accordion option).
Balance sheet is weak - NAV of £303m contained £392m of intangible assets, so NTAV is ugly at £(89)m - although software companies don’t tend to need much in the way of assets. Bottom line here is that there’s no balance sheet support for the shares, this company will be valued entirely on earnings. Since these have missed forecast by a long way, then inevitably the share price has fallen considerably today, as it should.
NCC has been highly acquisitive, including a huge acquisition (IPM) in June 2021 costing $216m.
Not particularly cash generative in H1, with all cashflow being paid out in dividends - makes me wonder if the divis might be at risk of being cut in future?
Outlook comments (published 2 Feb 2023) mentions lengthening of sales cycle, and delays in buying decisions. So the writing was on the wall. Also broker forecasts have been reducing in recent months -

Unfortunately, there are no broker notes available on Research Tree for NCC, so we’ll just have to work out the figures manually.
NCC achieved 10.8p adj basic EPS for FY 5/2022. That was based on £48m adj operating profit.
Today it’s saying £30m (mid point of range) for this year. That’s a 37% drop in profit, so if I apply the same % fall to EPS (not strictly correct, but it gives us a rough idea) then we get to 6.8p EPS for this year (my estimate). That’s well below existing broker consensus of 10.0p.
It sounds like there’s little prospect of much recovery in FY 5/2024 too.
So we should probably only be valuing this company on a lowish PER of maybe 10-15 times? That would get me to a theoretical share price of 68-102p, compared with the current price of 95p, which is at the top end of my range.
So today’s share price is still arguably a little too high, but that depends on whether you think future performance will improve, get worse, or stay about the same.
My opinion - it’s not a disaster, but clearly is a considerable disappointment. I'm quite surprised, as I would have thought cyber-security would be a vital, and growing space.
I’m worried that it might have overpaid for previous acquisitions.
Balance sheet is weak, hence the generous divis might not be sustainable.
I don’t know enough about the company or sector to form a judgement on whether this is a bump in the road due to macro factors, or whether there’s something more serious happening. Hence neutral view from me, AMBER.
Amazingly, the share price is now back down to where it was 12 years ago -

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
For those interested in GKP there is an important announcement:
https://twitter.com/rudawengli...
Deleted apparently! Was it the rumour that oil exports will restart tomorrow? It may take a little longer.
Hi Paul thanks for these brilliant articles there really helpful to a young investor like me their a great place for me to find some new ideas.
If you get a quite day,Could you have a look into Lords group trading please and Tissue Regenix. Lords is a small cap builders merchant that is 51 percent own by the CEO and has been showing signs of growth. There results are out on the 5/4/23.
Tissue Regenix is a regenitive health care company with some amazing technology that has been improving its whole financial position for a few years now and is now set to really push on.
Thank you for your time Paul
Olly
NCC (LON:NCC) For me this is very straightforward. The best indicator of future share price movements is the forecast EPS which is charted at the bottom right of the stock report. And the trend is your friend because trends continue until they stop or reverse. So if the forecast EPS trend is downwards then it's a sell, unless recent news is very positive. The converse applies too. And one should always take into account whether the share is cheap or expensive. So if both the share price and the EPS forecast have been going south, then it's an obvious sell. You could buy again after the share price fall.
If you have done a lot of qualitative research (eg quality of the management, quality of the product, competetive moat, etc, )and you still think that you should buy it, then at least wait until the share price has stopped falling, and this will likely prove to be your best entry point.
NCC (LON:NCC) the shares are already up over 33% off the low, or are you talking about closing prices?
Hi Rusty re NCC (LON:NCC) . I would wait until the share price was higher than it was compared to a week previously. This would lessen the chance of the share price continuing to fall after you have bought it.
Bouden54 thanks for your post on Burford Capital (LON:BUR) as like you I am a long suffering holder.
There is a well informed chat on ADVFN going on but I guess you know that. This Share is the share above all others that I will remember for all sorts of reasons. It will be an interesting few days ahead that is for sure.
Paul - let me add my thanks for the Portmeirion (LON:PMP) (I hold) inteview with CEO Mike Raybould. Even going over the same ground again helps to add to information - but you managed to draw out insight in some interesting areas. Well done! Thanks largely, I think, to your friendly and knowledgable rather than confrontational approach.
Overall I am a little more confident that they have a plan and are executing it well. At this stage most of the investor discussion has been around margin improvement and share buybacks. No problem. Classic value territory. And probably plays to Mike Raybould as ex-CFO. Though I was pleased to hear him stress his previous operational experience.
I'm slightly more interested in the long term global growth potential of these brands. I note that they took a big charge in H1 largely to restructure all their sales teams and brought Bill Robadee, CEO of Nambe and President of North America onto the main board as global director of sales. I don't think we have any view of what consistent sales growth rate Portmeirion can manage - I think the brands could support a low double digit growth rate, or more with the right sales and product launches. And the odd bolt-on acquisition in time. Which would make this more of a GULP (Growth at Ultra Low Price - yes I know that's not very good, I'm still working on it :-) than a value share - and I'll be looking to see what Mr Robadee can do here.
He seems a little more cautious than last year- but that's hardly surprising, and it's sensible under the circumstances? I don't think it reflects upon the prospects for the business. But then I am a glasshalfull investor by nature. I'd be buying more on any weakness - but I've already checked down the back of the sofa and I don't have any spare cash right now being at the fully invested end of fully invested.cheers
Mark
GULP - what a lovely term (growth at ultra low price) - I might have to adopt that myself!! ;-)
Late spike in Burford Capital (LON:BUR) share price nice to see for a long suffering holder. Appears to be finally some positive developments on their Petersen case.
Have a great holiday Paul. Whenever I see the word Gozo I cannot stop myself thinking of the Muppet character with the beak.
Ecsc (LON:ECSC) Blast!! I had been waiting for an opportunity to buy in again since listening to new management at the last Mello Chiswick. A quality service in a huge and growing market at a market cap of £2M! I have learned to be cautious over the last two years, perhaps too well.
AOB - have a great break Paul.
All these software woes…. Stick to Microsoft, chaps…..
EMIS (LON:EMIS) own health data for a large proportion of English citizens. do we really want that to go overseas!!
EMIS (LON:EMIS) own health data for a large proportion of English citizens. do we really want that to go overseas!!
I struggle to see why a foreign bad actor is worse than a British one. It’s not as though the NHS has lost your health record in the process (well, it is conceivable given the parlous state of NHS systems, but not in principle). The value of the data is in producing new and better-targeted therapies. It’s a common, global good.
Have a great holiday Paul.
Regards
Andrew
An interesting presentation by tinyBuild (LON:TBLD) on Investor meet company last night.
I wasn't entirely sure what to make of it but behind the enthusiastic founder-CEOs quirkiness and the orange hats seems to be a business that has done pretty well since inception.
From somebody who grew up with computer games on a cartridge/floppy disk, the world of "indie games" was definitely something new.
It looks like they've spent heavily this year creating new titles and its now a case of wait and see regarding whether the returns match their historic performance
Any other thoughts from those having watched the presentation?
Yes, an interesting presentation, though I could not make out anything the CFO said. The acquihire concept is novel as is the decentralised nature of the business. At least I think so, not being a games player. They have very good staff loyalty and one of the lowest, if not the lowest, staff turnover rates in the business. I am tempted to invest more but just don't know enough about the sector. I liked the way the CEO started off the presentation by telling a joke, although I didn't understand it...More CEOs should tell jokes in their presentations...
NCC: just to add to the irony - struggling cyber security firm ECSC has just accepted a recommended offer of 54.02p a 170% premium to latest share price!
I think that this might be illustrative - if you pay over the odds for these firms you destroy value. The staff's cyber skills are in-demand and they can easily walk and find another highly, probably more-highly, paid job.
It’s great to hear that you are taking some well deserved time off Paul. I continue to be in awe of the quality and quantity of output you produce on a daily basis and the civilised discussion that it inspires . Enjoy your holiday!
How kind, thank you! :-)
Dear Paul
NCC Group (NCC- LON)
I have managed to see some revised figures following this morning’s trading announcement which might be of some help to you and other subscribers. For the year-ending May 2023, the analyst is now forecasting EBIT of £28m, pre-tax of £20.9m and EPS of 4.8p. For the year-ending May 2024, the analyst is forecasting EBIT of £34m, pre-tax of £26.9m and EPS of 6.1p. For the year-ending May 2025, the analyst is forecasting EBIT of £51.1m, pre-tax of £44.1m and EPS of 10.1p. Interestingly enough, in each year the annual dividend of 7.8p is forecast to be maintained. So, at the current price of 98p, the prospective PER to May this year is 20.4, falling to 16.1 in 2024 and then 9.7 in 2025. If the dividend is maintained, then the prospective yield is 7.95%. My best guess is that it will take time to rebuild confidence in the business model and the newish CEO has much work to do before investors revisit in any meaningful way. Personally I don’t hold, although I have been watching it over the past year so as to better understand the business. I’m not sure I am much the wiser now!
Kind regards
Phillip
Great analysis!
The thing with NCC is the same sort of thing happened a few years ago. If my memory serves me right, that is. I was a shareholder at that time and decided to sell up.
Basically my reasoning at the time was that the share price had fallen quite a bit and with a few plausible assumptions about recovery it would be good value in a year or two. And as a bonus I'd be a shareholder in a tech company- woo!
So I found today's RNS interesting. It's always tempting to catch a falling knife, but trying to be objective, NCC's decade long performance as a business is quite pedestrian. I can't see the attraction in investing in a firm like this unless it has a low risk balance sheet (as Paul's says, it doesn't), and/or it is extremely cheap (it isn't).
Hi Paul,
Have a safe journey and a well deserved break and thank you for your continued hard work. It is always appreciated .
H
Paul,
Isn't time for you to buy some Belvoir shares?
Isn't time for you to buy some Belvoir shares?
I'd love to, but no cash available, and I don't want to sell any existing positions :-(
Do tell....
Maybe it's a bit late, Belvoir (LON:BLV) sp is flying after their report (over 25% already).
Results from Quarto (LON:QRT) a few minutes ago (I hold)
Operating Highlights
· Increase in Adjusted Operating Profit of 33% due to tight cost control, lower pre-publication and amortization costs
· Profit Before Tax up 47% at $20.9m
· Revenue of custom publishing channel of $14.2m, up 33% year on year
· Net debt down by $4.9m to $0.6m
Up about 16%
Great results looks rock solid . Well done
I looked at this and thought it looked remarkable value I think there was a large controlling shareholder in Hong Kong ?? that put me off .
Bloomsbury is my favourite share and this is sane sector .
I seriously think “reading is the new golf”
The “book club” is the new cycling club / golf club or maybe I’m just getting old ?
Is there a reading books thing going on ? Rising tide for quarto / Bloomsbury etc ??
I wonder if its anything to do with the growth in Audiobooks. I just typed audiobook growth in Google and this was the first thing that came up.
"Globally, audiobook revenue is projected to be worth over $5.38 billion as of 2022. Revenue from audiobooks is expected to grow 26.4% every year from 2022 to 2030 and reach $35.05 billion in 2030. This makes audiobooks the fastest-growing book format in the world by a wide margin."
I am addicted to audiobooks and so are a lot of people I know.
Thank you.
Their website is worth a look - they seem to specialise in low cost, glossy, nice looking books covering lots of subjects that people obviously want to buy and hold in their hand and give as gifts etc (as opposed to ebooks or digital books)...
For me, a decent bottle of wine, or a good book would be the perfect gift to receive -I don't really need anything else, as like most people here I would imagine, I can just buy it for myself...and as for golf - I'm far too young!
Made me laugh planetx but I think you've nailed it! My wife is in two book clubs and we watch and enjoy the TV programme Between The Covers, younger family members are also into books. When I mention investing in Quarto or your favourite she'll be on the buy button before I've finished the sentence. Anyway golf takes too long.
There's a lot to be said for finding a rising tide sector and backing great companies in great sector .
Both Bloomsbury and Quarto tick a lot of boxes and look very solid.
Bloomsbury trades between ranges so I may just wait for it to drop to the bottom of trading range and if it does add there (circa 420).
Quarto feel like its on a spike after few results lets see if it comes back when the market comes under pressure again .
Cant think of too many sectors feeling as warm and lovely right now just got to time Bloomsbury right it moves around quite a bit, though Im already at a pretty full position .
There's a lot to be said for finding a rising tide sector and backing great companies in great sector
That's my whole investment strategy pretty much summed up - badly thwarted however by the rising tide of interest and discount rates and the correspondingly sinking ERP (equity risk premium).
Books get covered a lot in Tik tok. Also think people are realising the enjoy met from reading physical copies rather than on a Kindle.
I hold both Quarto and Bloomsbury and I have done well with them. Their Little People, Big Dreams books are really accessible for kids
CMC Markets (LON:CMCX) [I hold]. The big share price fall for CMC this week was promptly followed by a downgrade from Jefferies yesterday that warned of possible loss of market share and noted a divergence in forecasts from sector competition.
I'm interested to hear the opinion of fellow readers on future risk/ opportunity and whether this week's news has spurred action one way or another!
Stockopedia continues to report highly on quality, with momentum and value moving rapidly in opposite directions. While still high the StockRank is naturally dropping away a little and may yet plummet. It's not long since generally positive (green) analysis here in SCVR but I sometimes infer a little scepticism and even head scratching into contributions and comments when it comes to this company. Maybe that's warning enough?!
Thanks in advance to any responders for their views.
I can only repeat what I've written on lse:
still puzzled with several things regarding the trading update,
- "lower equity volumes in Feb & March" - really ? the sell off and volatility just prior to the update must have been off the scale and right in their sweet spot, I would have thought they must have been inundated with margin calls, maybe the update was written before the recent volatility
- why issue the update during trading hours ? - most unusual
- all these broker downgrades coming in day by day rather than all at once
- also why release the trading update on 27th March when they told us they were going to "announce its pre-close FY23 update on Friday 14 April 2023" within the January trading update ? Why the rush to bring it forward ?
It's like they are all doing their best to drag the sp down, I know it's unlikely but the sceptic in me is looking for some form of ulterior motive. I wonder how long it will take before rumours of a buyout by IG group (LON:IGG) surface
I too am puzzled by the profit warning. The question is whether the profit warning is just a temporary set back or does it have a long term impact. I feel it is just a temporary since the company also stated:
"Development upgrades across both its investing and trading platforms continue
and the expansion in the institutional business remains on track. CMC's
diversification strategy in its investment business advances with CMC UK
Invest (https://www.cmcinvest.com/en-gb/) expanding its offering and with the
recent award of its regulatory licence, CMC Singapore Invest is due to go live
over coming months.
These strategic objectives underpin the expected 30% growth in net operating
income based on the 2022 results over the next three years.
CMC will announce its FY 2023 results on Tuesday 13(th) June 2023."
Tempting to go for the knocked down underdog Cmcx but I’d probably go with IGG to keep winking the race ?
I sold out this morning of Shearwater (LON:SWG) after a car crash announcement. How they didn't think of telling shareholders that revenue was 25% off and profit had disappeared before a regular trading update is beyond me. when management aren't capable of that then that's a sell for me. Nursing a big loss from this one. I need so stop investing in jam tomorrow stories and focus on companies that are delivering today.
I see EMIS (LON:EMIS) has dropped >~ 20%, I understand because the merger is frowned on by the CMA. Wonder if it is approaching buy territory yet (only sold my holding this month)?
Hi Gripple, thanks for flagging EMIS (LON:EMIS. I sold out shortly after the bid was announced (a bird in the hand etc.) but now it could get interesting again if the bid fails, so I have put it back on watch.
Compliments to: @sam88990 at Twitter
https://www.linklaters.com/en/...
Thanks Dojosan, those are useful statistics; coulda sold last year and put the funds in something else.
#NCC - Brutal trading update today from cyber security & software services expert NCC Groupc .
To me, it appears the consultancy arm is reeling from delayed pipeline conversion & negative operating leverage.
Value play or value trap? I suspect the latter given the 10x EV/EBITA multiple at 80p
On NCC (LON:NCC) Extract from the RNS:
"As noted in our unaudited interim results for the period ended 30 November 2022 (FY23 interim results), the Group expected to deliver an FY23 Adjusted operating profit of around £47m (after the impact of FY23 strategic investments of £5m).
Since then, market volatility has materially increased and is having a significant impact on our near-term cyber security revenue and profitability, particularly in the North American technology sector and to a lesser extent in the UK.
The key factors are:
· Buying decision delays and cancellations now exacerbated by North America tech sector client layoffs; staffing has not yet normalised, so continued sector layoff rounds are introducing more uncertainty.
· Turmoil in the Banking sector following the failure of Silicon Valley Bank has further knocked market confidence leading to reduced appetite to spend on technology projects across sectors.
· Recent interest rate increases in both the US and UK are creating further inflationary challenges for clients.
The Board now expects Assurance (Cyber Security) revenue growth on a constant currency basis to be low single digits compared to the high single digit growth outlined in our FY23 interim results. The Software Resilience (Escrow) business remains on track to perform as set out in our FY23 interim results, with revenue growth in H2 FY23 offsetting most of the decline seen in H1 FY23, with a full year outturn of c.1% revenue decline still expected.
As a result of lower Assurance revenue, Group Adjusted operating profit is now expected to be within a range of £28m to £32m after the impact of FY23 strategic investments. On this basis, the Group is scrutinising the underlying cost base and will take appropriate action in due course."
If this series of events genuinely could not be anticipated by competent management, we should expect more trading updates like this across the sector
Especially companies that provide services to US IT related companies.
But I always thought Cyber Security was more of a hygiene issue (you cannot not keep the toilets flushing) and so on the basis of no facts lean towards management not recognizing / planning for the event that a small number of really big contracts get put on hold.
Happy to not be a holder. My employer was a customer of their escrow service and it struck me as boring but profitable (this was ~'18), I looked but the sp was way too high.
@paul, thank you for pointing this out, the sp is a lot lower and so I have put it on my list. However as you noted, that it is low now does not mean it cannot go a lot lower.
"· Turmoil in the Banking sector following the failure of Silicon Valley Bank has further knocked market confidence leading to reduced appetite to spend on technology projects across sectors."
Wonder if that means impact on other tech related stocks with key clients in the banking sector. D4t4 Solutions (LON:D4T4) etc?
Well you can never say never but all I would say about D4t4 Solutions (LON:D4T4) is that they have clients in 27 countries and in a wide range of sectors, from financial services to retail, healthcare and telecoms so the business is not banking sector dependent. Insurance and healthcare + telcos, retail and hospitality make up maybe 75% of their business. Probably the other thing to say is that they have now finished switching to an ARR model (basically this is why they are H2 weighted as a lot of those contracts happen to renew in the 2nd half). The benefit of ARR is that whilst banks may be cautious with regards to new capex type spend the renewals are unlikely to be impacted. ARR now makes up almost 70% of their revenue as well so visibility should be pretty high. (The ARR are usually non cancellable 3 year deals too btw)
So my take is that any banking sector spend caution in its own right shouldn't be a major issue but obviously if this extends wider across industries it could. But with 70% annual contracted revenue and £25m net cash thats also a help.
Check out the podcast below. It is a really good explanation of the business and where their revenues come from, how they charge etc.
Tech Talk podcast: D4T4 with CEO, Bill Bruno and CFO Ash Mehta
Paul, I would echo the thoughts on your interview with Mike Raybould yesterday. A really good interview. Let's wait and see if the Board 'eat their own cooking' and add to their minimal shareholding.
Have checked my dealing records and note that I bought the shares at 300p. It offered great value then and continues to do so despite the share price rise.
To paraphrase Howard Marks who I admire as a great exponent of investment psychology, one of the principles of successful investing is the relationship between value and quality. The price reflects investor optimism or pessimism. In the case of Portmeirion (LON:PMP) sentiment continues to reflect the latter.
It is not what you buy it is what you pay that really counts, although one should always retain a degree of scepticism.
Paul may not have had chance to post yet, but Portmeirion (LON:PMP) interview is here https://qualitysmallcaps.co.uk...
Journeo (LON:JNEO) another smallish contract but does seem to be genuine momentum in the business. The regularity of contract wins coming through appears to support forecasts well. Think they have an IMC shareholder meeting next week so that will be interesting to listen / ask q's.
Now they have scale, decent net cash and a global growing business my question arises as to valuation - what multiple should we put on this business - is 12-15* unreasonable given the earnings growth?
Was it worth the time and expense of putting out an RNS for a contract that ultimately will be <1% of expected company revenues over the next 3 years?
It seems to be that the Journeo (LON:JNEO) management are a bit addicted to the dopamine rush of putting out regular contract announcements - a nice small boost to the share price each time, some more buying activity. Like a hamster that has figured out how to press the food dispenser button and get a pellet to nibble on.
And all these contract wins are already in management/market expectations of revenue growth, so really is just delivering what they're currently paid to do so, and not exceeding expectations!
Agreed - I think historically these were seen as material enough to merit an rns but now the size of the group is big enough that the threshold should go up.
However, useful for me as a holder currently to see these at it tells me how much business momentum the group now has.
James Halstead (LON:JHD) performance at interims both disappointing and encouraging at the same time. The results are behind last year at same time, but the projects going on in their markets around the world seem to be demonstrating government type spend is there
Nevertheless, the demand for flooring for refurbishment projects across healthcare, social housing and education is significant with projects such as Terminal 1 at the Paris Charles de Gaulle airport, the Sema Park urban regeneration project in Romania and the Kāinga Ora state housing projects in New Zealand.
as for the outlook, the nasty trending cost figures experienced last year are also trending in the right direction. They make no mention of hedged energy costs which are still at an inflated level, but they do make favorable comments on those items which will help them in the second half - energy, shipping, and that wonderful phrase 'improved productivity' which is so often mentioned in the UK as something to be aspired to but never achieved!
As we move into the second half of the year, energy costs appear to be holding stable, with the mild winter in Europe helping the wholesale gas prices fall from their peak in August 2022. Whilst energy costs are still in excess of prior comparatives there are positives. Availability and cost of shipping to our global markets is vastly improved. Raw material availability and the costs of those materials are more favourable. Production from our UK factories is higher, and with that we should see improved productivity.
Sales also seem to be trending in the right direction, so there is room for hope. For a share that is over 30% down in the last year, that would be encouraging.
Most importantly, sales in recent weeks in the UK and many export markets have been very encouraging with our core commercial vinyl ranges experiencing especially robust demand.
I wonder if Cyber security provider NCC (LON:NCC) is worhty of a look now. It has downgraded guidance to low single digit revenue growth, due to macro, but appears profitable the last few years, and appears to be generally healthy, : cash on BS, and historically reasonable ROCE for its services...
It is down 48% today
MCAP now £255m
NCC (LON:NCC)
I can’t deny the price suddenly looks attractive for what is a well-placed business sector-wise. I just wonder whether trends in the cybersecurity market from expert-led and back-up-secured (NCC’s model) to software, infrastructure, AI-driven (Crowdstrike, Microsoft, Palo Alto, Fortinet, zero-trust architectures) and cloud-based applications all position NCC as a long term irrelevance.
Although lengthening sales cycles have been a feature of US IT earnings reports, several US-based cybersecurity infrastructure businesses reported decent figures in Q1 so NCC’s US troubles may be more idiosyncratic than claimed - or NCC is a canary in the coal mine for US vendors. However, NCC is blaming the three week-old SVB turmoil for hitting revenues, yet the financial year is 80% done - a very weak excuse!
These are good questions BnB, though my work in the software industry convinces me that the general quality of software is remarkably poor, because most developers incorporate other developer's code that they do not fully understand and cannot analyse, and make further mistakes in the new code they write. They then rely on testing to show fitness-for-purpose when it's well known that no practical amount of testing can possibly find all of the important defects and vulnerabilities in a software system. That can't change without a radical, expensive and lengthy change in the way software is developed and assured.
As the Turing Award winner Professor Sir Tony Hoare FRS FREng once said:
We are like the barber-surgeons of earlier ages, who prided themselves on the sharpness of their knives and the speed with which they dispatched their duty -- either shaving a beard or amputating a limb.
Imagine the dismay with which they greeted some ivory-towered academic who told them that the practice of surgery should be based on a long and detailed study of human anatomy, on familiarity with surgical procedures pioneered by great doctors of the past, and that it should be carried out only in a strictly controlled bug-free environment, far removed from the hair and dust of the normal barber's shop.
Cybersecurity is an arms race, and the attackers only have to win one assault, whereas the defenders have to defeat all of them. I think that the 'expert-led and back-up secured (NCC’s model)' of cybersecurity has years of relevance remaining, unfortunately.
That can't change without a radical, expensive and lengthy change in the way software is developed and assured.
Such as placing your enterprise applications on the cloud protected by a zero-trust architecture, for example? I don’t see where NCC fits into this model. Perhaps its “experts” are your barber-surgeons?
Acknowledging of course that until every enterprise application is on the cloud, there will be plenty of weakly defended software to protect!
Such as placing your enterprise applications on the cloud protected by a zero-trust architecture, for example?
That doesn't remove the risks, it just moves them and changes their nature. The "cloud" in the end is just someone else's computer.
That said, NCC (LON:NCC) 's model seems very yesteryear with extremely poor visibility. But that's technology for you, always evolving, hard to stay ahead of the game. Always best to buy tech companies that are embedded rather than external and today's API driven architectures make it ever easier to jump horses.
Question is - is this a canary in the coalmine, or simply a dead parrot?
timarr
Question is - is this a canary in the coalmine, or simply a dead parrot?
A bit of both is my guess. But lengthening sales cycles have been the dominant theme in earnings reports for the past two quarters in US Tech - I’ve heard nothing else for the last six months. So did NCC simply not get the memo? Or is management only today blaming macro for their own inadequacy? I was struck by this towards the end of the RNS: “These economic headwinds and current challenges to the Group's cyber security revenues, which the Board expects will persist into the next financial year, reinforce the need to implement the next chapter of the NCC Group strategy”. So their service offering is sub-optimal?
But lengthening sales cycles have been the dominant theme in earnings reports for the past two quarters in US Tech - I’ve heard nothing else for the last six months. So did NCC (LON:NCC) simply not get the memo?
It was specifically mentioned in their finals, but without the grim consequences. If their visibility is this poor then it's not a good investment at any level. It's not like they blow out the lights on the upside, they're not selling anything obviously scalable.
timarr
hi FREng
Very useful explanation of most current software model vulnerabilities, much appreciated. I guess the NCC model is more thorough and reliable but as a result more costly to develop / implement?
I did hold NCC several years ago but sold out after holding for 2/3 years due to the then management team being quite accident prone. Not sure much has changed despite new management.
Snazzy
The profit warning at NCC (LON:NCC) has brought them into SCVR territory. Broker forecasts have been falling recently (today's forecasts seem already to have been picked up in the StockReport).
How can macro events have caused such a large reduction in forecasts in the 3 months since the Interims without individual contract delays and cancellations that were large enough to trigger an RNS?
The NCC long-term chart shows large drops in SP 2 to 3 years apart. They seem surprisingly accident-prone but appear to recover more quickly than suggested by Ed's analysis of the typical profit warning.
No current position.
No mention of such strife as delays and uncertainty due to Silicon Valley Bank, etc over at one of my favourite holdings Computacenter (LON:CCC) today. They have astonishingly increased headcount by 4,500 to 20,000! :0
Sadly also a longtime holder of NCC (LON:NCC which like iomart (LON:IOM) just never seems to get traction.
National World (NWOR)
Total wind up share options package for top two cronies at NWOR
Circa 400k shares each at nominal value.
Super soft targets using a trigger price of 19p and EPS that is hardly good performance
Very very disappointing by Montgomery in particular who already has a big holding .
Why do these self entitled greedy under performing money grabbing individuals believe that shareholder theft is rewards for them to plunder .
At least Dick Turpin wore a mask when he robbed you
Is a reasonably big holding of mine but really cannot stomach this and Montgomery is not remotely interested in shareholders but views this as his personal vehicle .
Total wind up .
does feel like that planetx - I am not against rewards for generating shareholder return per se but the triggers for vesting are ridiculously soft in this case. Disappointing treatment of shareholders - have to ask why the Rem Comm / NEDs waved this through without more stringent targets
I just get the feeling at NWOR. the vehicle is that of David Montgomery and they senior team and advisors are all in it together .
Shareholders are a side show .
I think it’s partly the big hitter personality led mentality .
If you recall a while back I think the FD left and I’d guess anyone not prepared to play ball is exited .
NED and Renumeration committee tend to drink ftom the same trough .
Will sell up now in the next weeks .
Might put the funds into Georgia capital ?
This is held in my pension so can buy main market shares .
Any other suggestions ?
For what its worth planetX I would suggest an opening position in Portmeirion (LON:PMP) . I would also offer Watkin Jones (LON:WJG) as a suggestion. The share prices of both, especially the latter are unloved and in the doldrums.
I own both so am clearly biased.
I bought Watkin Jones (LON:WJG) recently at its lows, where it still trades, give or take a few pence. Before doing so I watched the recent investor presentation on the full year results and went through the Progressive research note. It is very cheap subject to forward guidance being in the right ball park. Importantly the balance sheet is sound even after the £30 million cladding provision.
If you believe that there will be a continuing demand for build to rent and purpose built student accommodation, which anecdotal evidence indicates is the case, the risk reward balance for investing in Watkin Jones (LON:WJG) appears sound over the medium term, notwithstanding the current hiatus caused by interest rates.
Just my thoughts
Jonno
Thanks, both on my very short list .
Portmerion I like a lot but I probably wouldn’t hold in my pension as I’d like the IHT in trading account . Think I prefer SDG over Portmerion due to the lovely license income though could hold both . Don’t like the stock build though that’s lazy
Watkins Jones I have held twice and both times got timing completely wrong . I actually sold a couple weeks ago as I need cash . It doesn’t excite me much which I think is why I’m in and out , which is a bad sign .
But both good shouts .
Cheers planetX, I would be interested to know what you eventually decide.
I very much like Sanderson Design (LON:SDG) and held for a long time having bought before and added during the pandemic, but sold recently. I will look to buy back in if market malaise brings the price back 10% to 15%.
Slightly disappointed regarding the two recent licensing announcements, perhaps somewhat unfair to say that the company is being disingenuous, but the agreement with Next (LON:NXT) it appears is already in the company's figures to be reported shortly and there were no financial metrics in the recently announced licensing agreement with Sainsbury?
NED and Remcomm should always be independent. If they aren't you shouldn't own shares in the company imo. They should act against group think and challenge. I'm not saying they didn't here but the result is sub optimal from an independent shareholder perspective I agree.
At the moment I like Petrotal (LON:PTAL) particularly now that it will pay 10% dividends and will buy back 10% of its share capital. Combined with a very conservative production guidance, net cash of 20% of the EV and upside to guidance I think they have a good margin for error.
I still like Bank of Georgia (LON:BGEO) & Georgia Capital (LON:CGEO) despite the turmoil. The former has strong liquidity and capital, excellent dividends at around 10% and doesn't appear to hold long duration assets. The latter just looks like the wrong price with way too large a discount.
Osb (LON:OSB) also has very high liquidity (200% or thereabouts), a big dividend and trades on 4* earnings. Again nothing long duration and almost all of its retail deposits sit below the 85k guarantee threshold so risk of a run is low. Industry leading cost/income ratio and a very well regarded credit model.
On the riskier end Journeo (LON:JNEO) just looks like it has great business momentum - is trading on 10* earnings for this year with net cash about 20-25% of market cap.
Then I like Argentex (LON:AGFX) and Equals (LON:EQLS) as I don't think this play around making money move faster around the world has anywhere near played out and these two could carve out a very nice niche for themselves. Suspect both may be on the end of a bid in the not too distant future. Equals (LON:EQLS) is trading on 10* its cash generation with 1/3rd market cap in net cash - that just looks the wrong price. Investors seem to be focusing on the accounting numbers, which is daft in my view when you can see the cash gen.
David
Thanks for the thoughts .
Equals I’m already balls deep in (though like a muppet trimmed 10% a few weeks ago when I had a cash crunch in my new business ). it’s one of the small caps that is relatively liquid so had to cut some .
Argentex looks great but I know the CEO Harry adams from 20 years ago when he was a currency trader we used to use and I always imagined him as a cheeky chappie spiv , that’s a reflection on my prejudice not his current CEO capability .
Bank of Georgia I like and hold but I’m not a fan of bank shares don’t excite me
Georgia Capital I like a lot and have been buying this morning .
Journeo feels a bit frothy right now and I wouldn’t hold in pension so that’s out .
Pet total is out because I’m just too thick to understand commodities and oil and gas .
J Smart I really like and hold a small position , hard to buy but I really rate the value metrics of the share plus the management have a superb record of smart deal making in the ups and downs of property market . They will find long term positives out of short term negatives .
So far it’s Georgia Capital and J Smart
Very much enjoyed listening to your interview with Portmeirion this morning. As a holder appreciated your direct, challenging questions re how they were actually going to improve margins and why inventory had risen. All asked though in a friendly, unassuming manner - a chuckling assassin!
Hi Kouremenous & others,
Many thanks for the feedback on my PMP interview, it's really useful to know if people find them interesting or not. Otherwise it feels like I'm shouting into an empty room!
Regards, Paul.
My morning smallcap tweet: There's no fuel like a new fuel
Velocys (LON:VLS) Chill Brands (LON:CHLL) Shearwater (LON:SWG) Tekmar (LON:TGP) Journeo (LON:JNEO) Oxford Nanopore Technologies (LON:ONT) Powerhouse Energy (LON:PHE) Active Energy (LON:AEG) Tpximpact Holdings (LON:TPX) Cerillion (LON:CER) LifeSafe Holdings (LON:LIFS) Fireangel Safety Technology (LON:FA.) Jarvis Securities (LON:JIM)
◄Velocys (VLS)► welcomes yesterday's gov't consultation paper containing a number of proposals aimed at supporting and financing the development of the sustainable aviation fuel. Proposals "will [would?] help support the ongoing development and financing of the Company's Altalto Immingham reference project". [SP=3.27 Cap=46m]
◄Chill Brands (CHLL)► initial purchase order for its new range of nicotine-free vapour products from a new distributor operating in Florida and the surrounding states. Also taking steps to enable online sales of its vapour products via the Chill.com website using specialist carriers in the US. [SP=4.2 Cap=11m]
◄Shearwater (SWG)► warns FY-Mar rev down 25% and adj EBITDA about zero, significantly behind market expectations of £37.7m and £4.4m resp. Did co really only realise this huge miss yesterday? Blames "delays in orders being finalised with customers in our Services and Software businesses, as well as the recent move by some key customers to one year deals providing more reliable revenue mix in the future." [SP=80.15 Cap=19m]
◄Tekmar (TGP)► subscription, placing and retail offer to raise up to £7.275m at 9p, a 2% premium, to strengthen the balance sheet and working capital. Also £18m max convertible for 'financing acquisition-led growth although is also available to finance significant organic growth initiatives'. Converts have 10% interest and a low 11.6p strike. [SP=9 Cap=5m]
◄Journeo (JNEO)► £0.6m contract with CrossCountry Rail; includes three-years' support and licencing [SP=169.9 Cap=28m]
◄Oxford Nanopore Technologies (ONT)► platform to be used in study. Will sequence up to 22,000 samples to further research in the initial areas of psychiatric, common and rare disease. [SP=205.03 Cap=1694m]
◄Powerhouse Energy (PHE)► confirms discussion with National Hydrogen regarding projects in Australia and Singapore. [SP=1 Cap=40m]
◄Active Energy (AEG)► CoalSwitch progress update. Co "has sufficient funds to finance all current marketing and sales activities required to accelerate and complete the first commercial roll out and deliveries of CoalSwitch". [SP=4.5 Cap=7m]
◄TPXimpact (TPX)► gets waiver on covenant tests due today. Lender reviewing short and medium term cash flow forecasts. Trading in line. Down 90% from peak. [SP=27 Cap=25m]
◄Cerillion (CER)► £10m 10 yr contract with an existing telecommunications customer. [SP=1100 Cap=324m]
◄LifeSafe (LIFS)► trading has continued to exceed mgmt expectations. Signs £250k invoice finance facility, in case it is required. [SP=35.5 Cap=8m]
◄FireAngel Safety Technology (FA.)► £6m 3 yr contract from British Gas Services. [SP=9.25 Cap=17m]
◄Jarvis Securities (JIM)► Skilled Person review* continues. Further update in due course and within the next three months. [SP=135.7 Cap=61m] * I initially posted 'killed Person review'. Is that why it's taking so long?
I noticed that and wondered who Jim had killed, a proper Mr Contrarian Murder Mystery.
Great work BTW.