Small Cap Value Report (Fri 4 Dec 2020) - DBOX, NANO, WSG, MCB, SBTX, HUNT, SMRT, TPX, IGE, EVE

Good morning, it's Paul here with the SCVR for Friday.
I didn't plan it this way, but today's report turned into a nano cap special.
Timing - update at 16:31 - I'm winding down for the weekend now, so today's report is now finished.
Agenda - firstly a few tiddlers left over from yesterday;
Digitalbox (LON:DBOX) - Trading update (profit warning)
Nanoco (LON:NANO) - Trading update
Westminster (LON:WSG) - deeply discounted fundraising & more jam tomorrow promises from this serial disappointer
Mcbride (LON:MCB) - Positive trading update
Skinbiotherapeutics (LON:SBTX) - Final results - with zero revenues
Hunters Property (LON:HUNT) - potential takeover approach
Smartspace Software (LON:SMRT) - Trading update with no figures in it, and tells us almost nothing about trading!
Panoply Holdings (LON:TPX) - Interim results from Monday this week
Image Scan Holdings (LON:IGE) - Final Results from this nano cap
Eve Sleep (LON:EVE) - Trading update
.
Retail carnage continues with Bon Marche going into administration, for the second time in just over a year (Oct 2019 previously). 225 stores under threat. It's so tough out there, but this is (sadly for the people involved) a necessary thinning out of weaker, not very relevant brands. Capitalism’s process of creative destruction has to force the weak out of the market, to leave greater market share (of a smaller market) for the survivors
People are buying so much online, that we just don’t need as many physical retailers. Harsh but irrefutably true. Let's not be hypocrites about this - you can't be on first name terms with your local Amazon delivery drivers, and lament the demise of the High Street at the same time. We're causing it, because it's easier to buy lots of stuff online.
Here are quick comments on some micro caps from yesterday, so I can reduce the number of open tabs on my computer screen;
Digitalbox (LON:DBOX)
5.6p - mkt cap £6.4m
Quite an interesting, tiny company. It makes the satirical website & TV show, The Daily Mash, and Mash Report, which can sometimes be quite funny. It’s profitable, so superficially attractive. However, I quickly sold my shares in it some time ago, when I realised that the profits come from perhaps unreliable digital advertising. As we’ve seen with other digital advertising companies, those profits can quickly vanish, or greatly reduce, if giants like Google change their algorithms.
Trading update - for FY 12/2020. This triggered an 18% drop in share price yesterday.
- Difficult Q2
- Improvement in Q3
- Market-wide algorithm change negative impact in lead up to US Election
- Will miss market expectations for revenues & profits, but H2 stronger than H1, still profitable for year as a whole (but no figures given)
- Student/youth brand, The Tab, acquired Oct 2020, doing well
- Net cash of £1.1m
- “Strong position to benefit as ad market recovers in 2021…”
My opinion - too small to be listed (hence de-listing risk), and too much uncertainty over sustainability of profits, which this trading update confirms. Reinforces my view that investors must carefully consider, with all investments, how sustainable profits are. Anything operating in digital advertising is at high risk of only delivering fleeting, unsustainable profits, hence great care is needed with this sector.
.
Nanoco (LON:NANO)
9.8p - mkt cap £30m
I briefly held shares in this micro cap too, but sold out a while back, because it seemed to me that the company’s future was so heavily geared towards a legal action against Samsung, that it was impossible for me to value the shares. I don’t like holding shares in anything which is subject to make-or-break litigation, because I have no edge, so it’s little more than gambling.
It updated us yesterday for Aug-Nov 2020;
- Delivering R&D services for customers, most significant being ST Micro - negotiating for next phase
- Innovate grant, announced 25 Nov, to fund £0.8m of £1.0m project cost of testing kit for Covid-19
- Trading in line with the Board’s expectations
- Has contingency plans if not able to generate new commercial revenues
- Samsung litigation - Board confident of a positive outcome, but trial date set for Oct 2021, and could slip further.
My opinion - it’s low on cash (no update given today), and the crucial Samsung litigation could be a year or more to be resolved, unless a negotiated settlement is agreed beforehand. Therefore I can’t possibly predict what the future holds, so it’s impossible for me to value, it could go either way.
.
Westminster (LON:WSG)
Deeply discounted £5m fundraising, at 4p (with warrants bringing potentially more dilution).
It’s promising more jam tomorrow. I cannot understand why shareholders keep giving this company the benefit of the doubt, given its awful track record.
.
On to Friday's news, of which there isn't much;
Mcbride (LON:MCB)
Share price: 72p (up 10%, at 09:23)
No. shares: 181.4m
Market cap: £130.6m
McBride (the "Group"), the leading European manufacturer and supplier of Contract Manufactured and Private Label products for the domestic household and professional cleaning/hygiene markets, provides the following trading update.
This relates to FY 06/2021, so we’re almost halfway through this financial year.
I last looked at McBride here on 24 Nov 2020, when it put out a reasonably OK trading update, mentioning various factors which would mean H1 should be more profitable than H2.
Today’s update shows a further improvement, saying;
In 2019, the Group experienced a weak November and December trading period, however in 2020, these months are now expected to trade very favourably ahead of last year with the result that the Board now expects first half sales growth of approximately 2%.
This improved revenue performance combined with continued factory efficiencies, limited operational impact from COVID-19, lower than expected operating costs and input costs for certain raw material and packaging items, will see a material year-on-year improvement in first half earnings.
Consequently, the Board's current outlook for the year ending 30 June 2021 is that profit before tax is expected to be at least 10% ahead of the current market consensus of £25.2m albeit the Board remains mindful of the continued economic uncertainty created by Brexit and COVID-19, together with expected increases in certain input costs in the second half.
This is a well-written announcement, giving us precise guidance, very helpful indeed, thank you to the company & its advisers. My job would be so much easier if all companies followed this straightforward, transparent approach to trading updates. It makes sense, because if a company gives investors clear guidance, rather than leaving us scratching our heads trying to decipher the nuances of some waffly text, then we’re more likely to buy the shares, as there’s no uncertainty about how the company is actually performing.
Valuation - current consensus EPS seems to be just under 10p. So it sounds like we can probably work on 11-12p EPS, giving a PER of 72p/11-12p = 6 to 6.5 - dirt cheap in other words.
Part of the reason this share is cheap, as I covered in detail last time here, is that it’s got a lot of debt, and a pension deficit. Even so, neither look ruinous, so the very low PER looks to have some possible upside.
My opinion - it’s probably too cheap, given that we’ve now got an out-perform trading update, and 10% rise in FY 06/2021 earnings forecasts. I’m tempted to pick up a few, as this looks like it might re-rate somewhat. Possible upside to 100p if things continue doing well? The chart looks nice too, and the StockRank system likes it a lot, nice confirmation. I'll put it on my watchlist and might buy a few on a down day.
.

.
Skinbiotherapeutics (LON:SBTX)
16.5p (down 3%) - mkt cap £26m
Full year results y/e 30 June 2020
The income statement is missing something important - income! It’s a zero revenues research company. So how on earth are we meant to value it?
It seems to be burning about £1m cash p.a. Therefore the £2.2m cash pile at end June, plus £4.45m raised in a placing post year end, so it looks fully funded.
It’s from the same stable as Optibiotix Health (LON:OPTI) - so lots of scientific updates, and deals announced, but nothing of commercial substance so far.
My opinion - there’s nothing concrete to base a valuation on. I do wonder if we should lobby to have stock market rules changed, to stop zero revenues companies from floating at all. These companies tend to suck in inexperienced investors, who nearly always get diluted with repeated fundraisings. It’s very rare for such blue sky companies to deliver the shareholder value they promote as being on offer at the start when they float.
.
Hunters Property (LON:HUNT)
75p (up 28%) - mkt cap £24.6m
Statement re possible offer
The company says it has received a “preliminary approach” from The Property Franchise Group, which isn’t a lot bigger than Hunters, being listed, and having a £46.6m market cap last night. So I doubt this would be a cash bid, probably more likely to be a merger?
TPFG has also issued a statement, emphasising that this is an early stage approach.
I’ve had a look at TPFG’s last balance sheet, and I don’t think it could buy Hunters without doing a substantial placing. That could be why TPFG’s shares are down 4% today.
My opinion - this approach doesn’t look terribly credible to me, so I’d be inclined to sell in the market for a 28% gain today, if there’s anyone buying (Hunters is a very illiquid share).
.
Smartspace Software (LON:SMRT)
Product launch & trading update
This update is almost entirely waffle. It talks about products, and makes general comments, but with nothing to indicate how the business is actually performing, and no figures. What's the point then? It reads like a PR release that might be sent to journalists in a trade magazine, in the hope that they'll mention something.
It concludes;
So overall, SmartSpace continues to push forward with strong opportunities across the Group in delivering future significant growth
My opinion - I have to award this an E grade. And that's being generous. It tells me nothing about how the business is performing, or how to value its shares. SMRT shares have done very well this year, so clearly it has caught investors imagination. Potentially interesting company, but I need more meaningful financial information before I can form a view on whether the shares are worth buying or not.
.
Panoply Holdings (LON:TPX)
Share price: 202p - mkt cap £136m
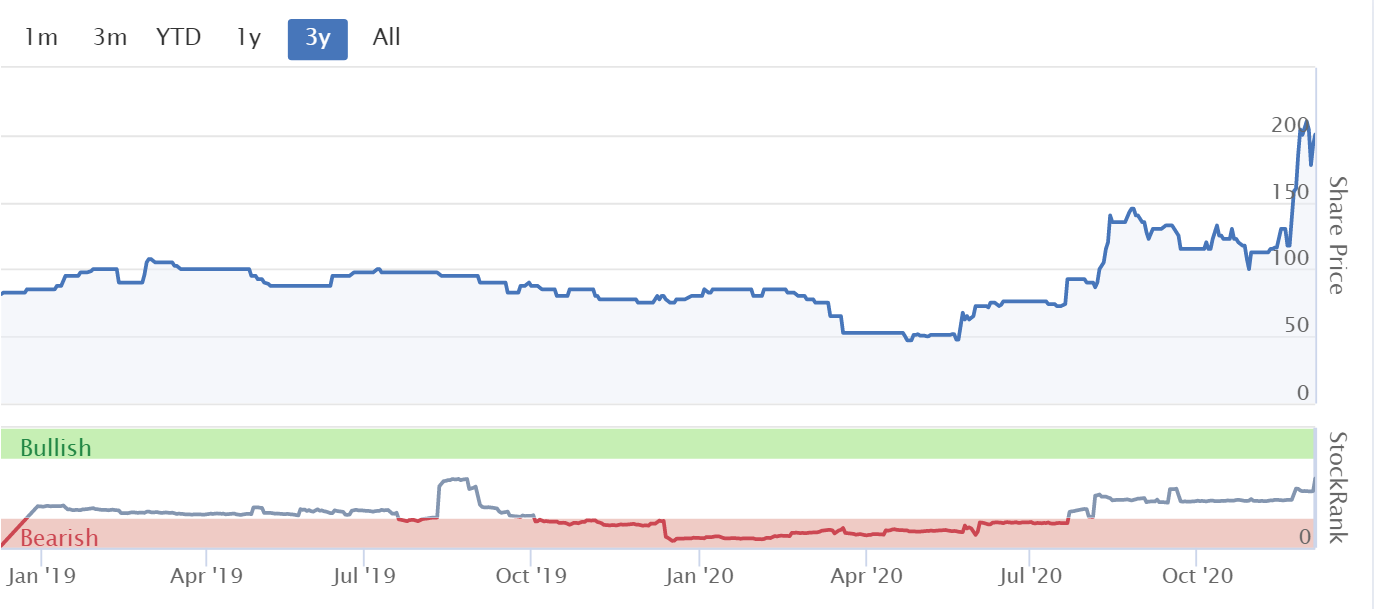
This share has almost doubled in the last months, mostly just before it put out interim results on Monday this week. I ran out of time to look at it then, so am circling back today, as it’s quiet for news. Surely they could come up with a clearer company description than the following?
The Panoply, the technology-enabled services group focused on digital transformation, is pleased to announce its results for the six-month period ended 30 September 2020.
The title says;
Like-for-like revenue growth of 18% and significant contract wins provide confident outlook
- Revenue in H1 up 58% to £21.2m, of which 18% is organic, the rest from acquisitions
- Adjusted diluted EPS of 2.6p (doubled from H1 LY)
- Statutory loss of £1.7m, caused by £2.5m additional deferred consideration on an acquisition
- Mainly public sector customers - 70% of revenues
- Maiden dividend, but only 0.2p, so insignificant
Results webinar recording is here, courtesy of our friends Tamzin & Tim, at PIWorld;
.
.
Outlook comments sound upbeat;
The outlook for the Group remains positive with our brand consolidation programme well underway and a number of significant new contracts being signed post-period end. We remain on track to achieve our commercial vision of both £100m revenue and £12-14m adjusted EBITDA, on a run rate basis, by 31 March 2023."
The strong momentum built in H1 has continued into current trading, as we continue to see higher-value deals signed across the Group. These include the previously announced £4m HM Planning Inspectorate contract, various NHS-related projects as well as a new project for the Welsh Government. Our focus in the second half will be on driving organic growth through continued consolidation of the brands, ensuring strong cash conversion and, as always, pursuing accretive acquisitions.
We are now seeing mass demand for our distinct style of digital transformation project delivery: fast, good value and genuinely effective. COVID-19, alongside numerous other factors, has created an ideal environment for us to prove ourselves and to continue taking market share.
Adjustments to profit - see the table below. These look like genuinely non-underlying costs, so I’m happy to use adjusted profit as the figure which measures the underlying performance of the business.
We’re not ignoring the highlighted items, it’s just that I wouldn’t include them when valuing the company on a multiple of profits, because they don’t relate to the underlying performance of the business. They’re either one-offs, or non cash items, which it’s generally OK to adjust out, in my opinion, when forming a view on how much the shares are worth;
.

.
Dilution - an unusual, but very important point to take into account when you value this share, is that it acquires lots of companies, and uses contingent, deferred consideration for some of the price paid.
This means that an unusually large number of shares could be issued, as set out in the EPS calculation below.
This could explain why management seems keen to talk up the share price, as that could then minimise dilution, if the same £ payment can be satisfied with fewer, higher priced shares, maybe?
.

.
Balance sheet - is weakish. Once we strip out £53m intangibles, then NAV of £37.5m drops to NTAV of negative £(15.5)m.
Note that deferred & contingent consideration liabilities are £8.6m inside 12 months, and £4.8m over 12 months. If those are going to be paid in shares, then that’s fine, because the liabilities would then disappear, boosting NTAV by £13.4m in total, which would bring it back almost to neutral.
Once we adjust for that factor, then the rest of the balance sheet looks reasonably OK. There’s cash of £5.9m, less interest-bearing debt of £7.1m, so a very modest net debt of £1.2m.
Overall then, I can live with this balance sheet, it’s not the best, but should be fine once the deferred consideration has been sorted.
My opinion - I’m going to watch the PIWorld results webinar recording over the weekend. This group does seem ambitious, and is operating in an interesting area.
Although it looks a bit richly valued for my tastes, and the pace of acquisitions looks a bit too fast. So I’m a little wary of this one.
That said, look at the stellar growth in valuation achieved by Kainos (LON:KNOS) which also focuses on public sector IT projects. So clearly there are rich pickings in the area.
TPX listed on AIM 2 years ago, and is starting to get noticed;
.
.
Image Scan Holdings (LON:IGE)
2.68p (up 25%) - mkt cap £3.5m
Final Results
A very quick mention, as there are plenty of nano caps doing crazy price moves at the moment, so there might be some opportunities for the more adventurous amongst you!
I've followed this tiny company for a few years, it makes X-ray security screening equipment. Unfortunately, it didn't live up to expectations, hence the mkt cap now being so tiny, there must be a risk of de-listing. So high risk I would say.
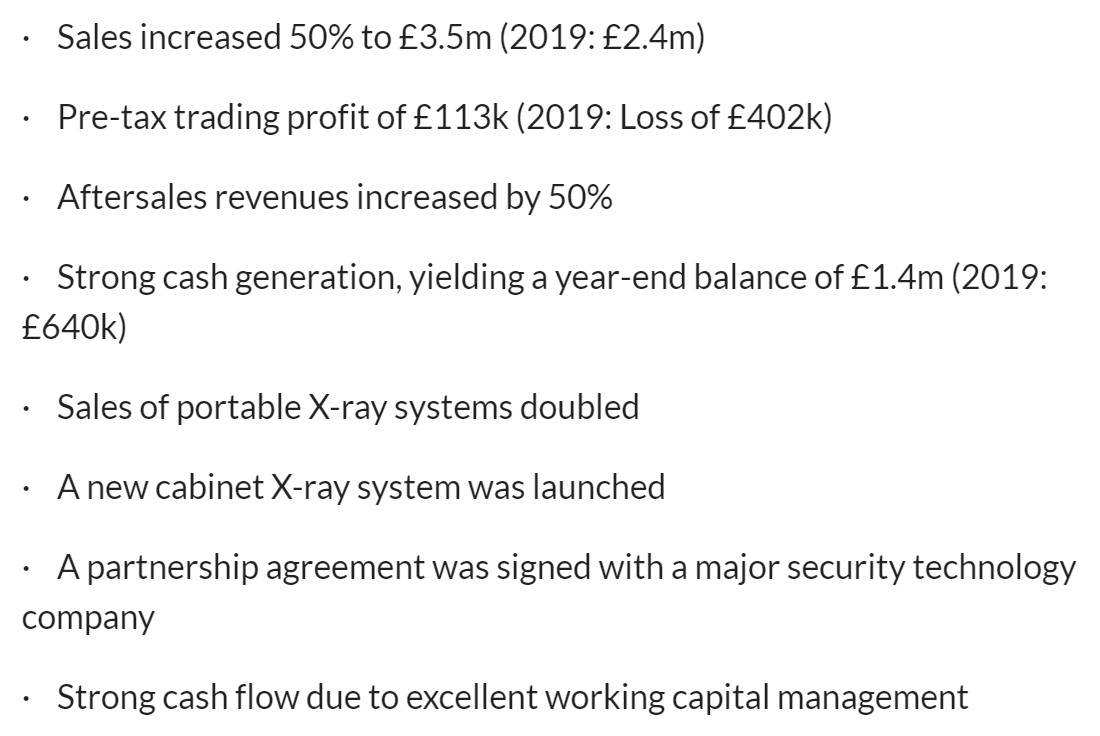
Given that the mkt cap is only £3.5m, these highlights today look quite good;
.
.
Outlook comments sound interesting;
The recent launch of the Axis-CXi cabinet X-ray machine is an exciting step forward for the Company and should bring new customers and new sources of revenue. With our strong cash position and our ambitious product development programme we look to emerge from the pandemic well-placed for the future...
Without the benefit of exceptionally strong order book going into last year and the current delays in the placing of large orders, we therefore expect a challenging year ahead.
Order book is well down;
The Company ended the period with an order book of £633k (2019: £1.7m)
My opinion - on second thoughts, maybe it's not worth a closer look, due to the weak outlook & order book.
.
Eve Sleep (LON:EVE)
4.65p - mkt cap £13m
Continuing the theme of nano caps, this mattress company reported yesterday.
Let's not beat about the bush, EVE has been a disaster historically. However, the company now seems to be greatly reducing its losses, and gaining some traction selling online. Importantly, it still has cash in the bank, which buys it time to attempt a turnaround.
Yesterday it said;
Strong trading through November, further upgrade to expectations
- Revenue expectations raised in Sept to £22m for FY 12/2020
- Further raised now to at least £24m revenues
- Strong summer trading & also strong over Black Friday
- BUT it's still loss-making, albeit reduced, to £2.5m at underlying EBITDA level (77% reduction on LY loss, so a big step in the right direction I would say)
- Net cash of £8m at end Nov 2020 - more than half the mkt cap, although this is likely to reduce with further cash burn
My opinion - I'm tempted to have a little punt on this. Greatly reduced losses, and plenty of cash remaining, and a modest market cap, means there's a chance that a turnaround could work.
.
That's all from me today, and for the week. Many thanks for tuning in, and for your excellent, interesting, and good-natured comments, it's been a pleasure discussing shares with you.
Have a lovely weekend.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
I am staying away from Mcbride (LON:MCB)
Debt and pension. Low margins. If you look at the broker forecasts graph, they were declining every month until covid started.
Covi ssaved this company, as suddenly there was a huge surge in demand for hygiene products. Even better, supermarket own brand was flying off the shelves as they were the only retail stores open. This boosted revenues and margins for Mcbride.
But could they be a post-covid loser next year? Very likely.
Thanks Paul, you covered an incredible amount of ground today, brilliant effort. Hope Paddy's stable...
Thanks Rodgers63. I thought it would make sense to cover lots of companies, but do shorter sections today.
I thought we were going to lose Paddy this time last week, but he seems to be on the mend somewhat. He's been in doggy hospital now for a few days, they're dressing his wounds every day, and he's had treatment on a drip. Seems crazy for a dog really, but he means so much to us, that he's part of the family, and we had to try to save him, even though it will end up costing a few thousand quid. Lucky timing, as the markets have been good to us recently!
The vet will decide if he needs another operation to graft some skin over the wound, but I'm more than 50% hopeful he should recover, which is lovely! At least I've been able to focus properly on work, now he's recovering, and is in good hands.
Have a lovely weekend.
Best wishes, Paul.
Re: Panoply Holdings (LON:TPX)
Thanks for nice overview of this oddly named company with an odd business model. Highly acquisitive with many of them overseas so fair bit of operational risk. CEO talks a good talk but sometimes this is a bit of a flag.
Hi Momoko,
I know what you mean. Every time I listen to management of Panoply Holdings (LON:TPX) presenting, I think they come across as very smart people, fluent, clearly ambitious, and it all makes a lot of sense. But I can't shake off an uneasy feeling that it's all being hyped up a bit too much.
On balance therefore, I'm probably just going to keep a watching brief, and see how it develops.
Regards, Paul.
I have a technical question, wondering if anyone could help me learn.
Its about Boohoo (LON:BOO)
I've noticed lots of notifications of major holdings in last two weeks, from Morgan Stanley. But they're all tiny moves up and down. My understanding was that the notification was only required when you moved between specific percentages - 3%, 5% etc.
Is a notification required for any amount of shareholding change, regardless of size? Or are MS having to notify so frequently for another reason?
I think once over a certain threshold, any change has to be notified.
I hold Boohoo (LON:BOO) and have noticed this, maybe to do with limits within their funds? But this has been going on since end of October.
I believe once your holding is over 3% you have to notify of any and all changes, until you fall back under 3%.
Hi Patrickmylnetrade Boohoo (LON:BOO) and notifications daily
Are the company making buy backs and reducing the issued shares thus causing a holding % reduction?
Someone surmised the other day they were facilitating short selling through their prime brokerage hence the small movements
This is correct, they are over the disclosure threshold.
Zytronic have a reassuring update out today. I originally picked some of these up as a result of this page. Like Paul I liked their honest,clear management, focus on a strong balance sheet and healthy yield at the time. Extremely difficult period for a touch based product provider and shows the good sense in focussing on balance sheets and good management. Cash pile has increased. I own and have all the way through, no intention of selling for transparency.
Zytronic (LON:ZYT)
camtab
Cash pile has increased.
wow - cash up £14 mill - market cap £22 mill i make that (136p*16 mill?)
The Group's cash position continues to be strong at £14.0m (2019: £13.1m) and has increased by £1.6m since 31 March 2020, benefitting from a reduction in working capital.
Certainly a solid balance sheet here - on that basis its formally gone onto my watchlist - the closer the market cap gets to the cash in the bank the more interesting this looks. Ok the sales trends are pretty woeful - but if they can remain at least breakeven on lower turnover it does give more confidence that the cash will hang around to provide some decent share price support? 80p-90p perhaps?. At present though unless they reverse sales trend its hard to see what would send the price much higher than it is now. If share price does drift back down though closer to the value of teh cash pile the risk reward seems tempting as a punt.
On top of the cash the rest of the balance sheet seems rock solid - looks like there is £3 mill of freehold property if we use cost price (18p a share albeit market value of freehold could be owt ) - and positive value of "others" when it comes to what they need ref working capital.
I can't see a trading update from Zytronic (LON:ZYT) , only a notification that its results for FY 09/2020 will be published on 8 Dec 2020.
Zytronic (LON:ZYT)
Looks like you are correct Paul - trading update was issued 21st October not today.
Thanks for clarifying, thought I'd missed something there!
Apologies guys.
That's OK. They have some best in class tech but overly focussed on gaming has been there current drag. If they can gain material/profitable volume in another area, i.e. industrial displays or newer growing concepts i.e. restaurant table top ordering or fast food self orders, then they may turn around. But they need a bigger sales hitter at director/sen man level to refocus on new areas.
I think the value in Hipgnosis Songs Fund (LON:SONG) (I don't hold) is purely when Apple or Amazon music to buy it out once all the hard work is done prizing nice little earners from the bands / artists who own the the rights - Noddy Holder is still supposed to earn £250K every year from one song - Slade's Merry Christmas Everybody
Good statement today from micro React (LON:REAT) This is an honest hard working business; deep cleaning. Mostly of offices, schools, hospitals . Strong demand for services continues. They raised over a million in new cash at 1.5p in the summer and the price is currently well below that. A former CEO of Redstone Connect Plc has taken over as Chair of the company. Never going to be a huge star but perhaps worth a small punt at this level (disc I hold).
Paul, thank you for recommending John Authers' newsletter. It really is excellent. This morning's article is an outstanding summary of the current position with regards to equity valuations. It also refers to an adjustment Shiller has just made to his CAPE ratio, 'Excess Cape Yield', which I'm sure many will find interesting.
The article made me recall an eccentric professor of mine who would scream 'ceteris paribus' in her thick Irish accent umpteen times a lecture - the words are indelibly stamped on my conscience as a result! It even became something of a campus catchphrase.
One of the findings is that UK equities may be quite cheap at present. While US multiples are high, earnings are also astonishing. I may be wrong on this, but such high and apparently sustainable earnings growth from the largest stocks in the world, may be unprecedented in history?
Those with the US subscription can see that Amazon's revenue was $280bn last year, forecast for $380bn this year and $450bn in 2021. Whereas the UK's largest stock, Unilever, makes £50bn in revenue full stop. Amazon is almost adding two-times Unilever's current revenue in just one year! Astonishing.
I'm generally a sceptic of US valuations, although you can't really argue with growth like that: even a P/E of 70 can eventually be justified if such growth continues. The risks, as Authers points out, are earnings disappointments and/or significantly higher interest rates.
Hi Chris,
I agree, today's John Authers article was fascinating, and I really like the concept of using an earnings yield (the inverse of PER) and then comparing it with long-term interest rates - makes a lot of sense.
Although I must admit, in parts, I was struggling to fully understand some of the article & charts, but got the general gist!
It seems to me that interest rates are probably now permanently low, because they're rigged by central banks, who have created artificially low interest rates by QE. Governments are not likely to want this arrangement to change, because it provides them with a painless, basically free, way to fund deficit spending. It shouldn't work, but so far, it has done, for the last 12 years, so why would they want to change things by pushing up interest rates?
On that basis, then a PER of say 20 for a reasonable quality company, which I would have found expensive a few years ago, I now think of as a reasonable price. An earnings yield of 5%, actually looks pretty good compared with alternatives.
Regards, Paul.
Your last paragraph touches upon a very important point Paul. With bond yields so low, equity valuations could in fact be much higher, if using an equity risk premium / discounted cash flow approach. Assuming rates stay low, of course.
Aswath Damodaran is I would say the expert on investment valuation, academically. While his 900-page textbook is a bit much to digest, his website contains some excellent information on current valuations. Link here.
Within downloadable datasets, spreadsheet 2 shows the Implied Equity Risk Premium from 1960 to 2019 for the US markets. Damodaran computes the implied ERP monthly, and the latest figure is around 5%, which is comfortably above the historical average of 3% - 4%. In the dot-com bubble it got as low as 1% - 2%.
So basically, risk aversion is still (technically) above average and animal spirits have by no means taken hold. Of course, if the risk-free rate (govt. bond yields) increased, equity valuations would need to adjust, but the high ERP is perhaps accounting for some of that already.
Your last paragraph touches upon a very important point Paul. With bond yields so low, equity valuations could in fact be much higher, if using an equity risk premium / discounted cash flow approach. Assuming rates stay low, of course.
While economically sound this is a complex way of arguing that the invisible hand will work to push up equity prices. All things being equal prices should adjust to ensure the same return on investment regardless of investment class - that's the Law of One Price in operation.
But equities consistently return more than they shoud so economists have invented the equity risk premium to argue that risk (which in the weird vocabulary of neo-classical economics equates to volatility) puts people off investing in shares. Thus the prices are lower than they should be and returns are greater for those of us willing to accept the risk (i.e. random fluctuations in capital).
Regardless of whether any of this linguistic claptrap is correct when interest rates are hovering around the square root of zero simple behavioural analysis would predict people will start to hunt returns. You can see some of that in the Robinhood frenzy in the US. However, as we can see via market returns in the UK that hasn't happened.
There's probably a few reasons for that - we don't have any of those exciting tech unicorns (nor are we likely to, on other than a one-off basis, you need a sufficiently large home market to address in order to scale efficiently) plus we've had a series of shocks over the last decade - austerity, Brexit and now a particularly hamsfisted handing of the pandemic by the marketing agency that passes for our government.
However, if those shocks recede - the government has now got a taste for spending, Brexit will soon be a thing of the past (I jest, but at least we'll have a temporary resolution one way or another) and we can get hold of a vaccine and it works - then, assuming interest rates stay at rock bottom, there's clearly a good chance that more people will start hunting for yield. You just hope that they can stay clear of the guaranteed get-rich-quick merchants who will be out in force.
timarr
"...by the marketing agency that passes for our government", that comment absolutely made my day. I am going to use that. Brilliant
I should point out I voted from that marketing agency in case I am labelled red.
Good post.
There were the 20s (automobiles, radio), the 60s (computers) and possibly the 90s (internet). They all ended the same way
Hi Paul,
There's been a lot of price movemet for Bigdish (LON:DISH) over the last couple of days (circa 50% rise), but I can't find anything anywhere regarding the cause.
I know you are a holder yourself, so it probably hasn't gone unoticed. Are you aware of anything, imminent announcement of funding secured perhaps?
Hi jabbamonkey,
No, I'm not aware of any news re Bigdish (LON:DISH) . It doesn't need funding until well into 2021 anyway, so I don't think there's anything going on there.
For me, this share is just on the back-burner, I'm a bit frustrated with the business model constantly changing, but I suppose that's better than ploughing on with something that wasn't working during lockdowns, etc.
If it doesn't work, then I imagine they would reverse something else techy into the shell.
Tiny market cap, very speculative, it's just a punt really.
Regards, Paul.
Many thanks for the prompt reply Paul - very useful insight too
Completely agree with summary of £dbox. These businesses will also become challenged with the "death of the cookie" when Google switches off third party cookies on Chrome browser. So unless you have a first party, logged-in audience, you're going to struggle.
Dear All, I'm afraid the RSS feed I used to get RNS information is still broken so I cannot include reliable news / reporting information on the heatmaps. Apologies.
Here are my heat maps for today (prices as at ~9am).
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR world filtered to 'interesting' instruments ('interesting' means: reporting soon or recently; trending; breaking out; increased volatility - volume / ATR up; moving more than a 20d EMA of the ATR):
Big movers today in the SCVR world (moving more than 20d ATR EMA against either yesterdays close, or today's open):
Small Caps breaking out today:
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 75 instruments.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many (from my own application and database) to help focus my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria (a 'T' in the top-right of the heatmap, meaning: profitable; low-debt; reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the identified instruments in more depth using the Stockopedia StockReports.
How (or indeed if) you use these heatmaps is up to you, I contribute these SCVR related ones here in the hope that others may also find them interesting or useful. I aim to post sometime in the morning when I can, but sometimes work / family and other priorities get in the way.
greensiax
Useful and very interesting. Thank you for all your work and published stuff. One query. What if the border colour is white - means? Thanks
Thank you mercury61,
Good question and I need to add it to the key, so thank you for raising it.
White means utterly neutral, i.e. neither positive or negative to any meaningful degree.
Cheers,
greensiax
Paul - £NANO - Dont know the company - too small for me but your comment re litigation certainly rings with me - Seen it before - Some years ago Ted Baker (LON:TED) was litigating against their insurers AXA after a fire - spent lots of money for nil result. Accsys Technologies (LON:AXS) was in arbitration (which can also be very costly) with Far Eastern agents - nil result and of course we now have £INDV. What you have to bear in mind is that people get blinkered to the obvious and of course lawyers will rarely tell clients they dont stand a chance. Suppose should also mention a coy that makes money from it all - guess who - Burford Capital (LON:BUR)
Picking up on Paul's comments earlier in the week this mornings newsletter from John Authers is another brilliant piece of analysis. It is a fascinating look at US stocks and the reasons for their sky high valuation. The conclusion would seem to be invest in markets outside the US though the FANGS+ continue to defy gravity.
Jeremy Grantham has been saying to switch out of the US and into emerging markets for a while now. In this interview he says;
“But you only need one big asset class to get rich,
That asset class is emerging markets, which are guaranteed to grow fast, he said. It consists of 26 countries and covers every industry you could want – at 10-times earnings.
He favors China, which will get 30% of world’s growth, and India, Russia and Brazil. Collectively they will be a much bigger part of world GDP, according to Grantham.
“A bet on emerging markets is a bet on the future against the past,” he said. “The only thing interesting outside of that are the FAANGs, but more so intellectually than financially.”
Grantham said he is sympathetic to the lack of opportunity in this low-yield environment, “but the market doesn’t care about that.”
“Your desperation is your own matter.”
Or what about Bill Ackman’s Pershing Square Holdings (LON:PSH) which holds a concentrated basket of around 10 US holdings at a discount to NAV of 25%?
Interactive Investor have put up an interesting 10 min interview with him this week at the link below.
https://www.ii.co.uk/analysis-...
£SONG came out with 2 announcements today. One a trading update showing an increase in NAV in line with recent share price increases and another saying they exploring another fund raising as they have a pipeline of £1bn in opportunities. I hold and still consider this a nice income /long term value stock.
The real interesting opportunity here is as they continue to amass a large portfolio (think they have now something like 27 of the top 100 most played songs) will they be able to change the dynamics?
As we have seen on the TV owning to rights to content is becoming more valuable than streaming it. Will we see SONG eventually look to stream or bring their catalogues directly to consumers bypassing Youtube/Spotify etc? or will they merely use their strength to negotiate higher prices?
Either way happy to hold and see how this runs
Hipgnosis Songs Fund (LON:SONG)
I also hold BUT what I am seeing is continual growth of the catalogues they own (due to equity raises) BUT no significant improvement in EPS. The dividend is increasing slowly but they do not seem incentivised to actually make the music they own work harder and generate more income.
The NAV is increasing when considered per share but some of that is from accounting changes (see latest RNS)
This is a good steady eddie dividend stock for me in a non equity market BUT I am starting to question whether I hold long term unless the management company (which gets paid a lot) starts to generate income growth from the existing catalogues.
RE: Hipgnosis Songs Fund (LON:SONG)
I also hold BUT what I am seeing is continual growth of the catalogues they own (due to equity raises) BUT no significant improvement in EPS.
I hold as well but at the moment it's a gigantic Ponzi scheme - raise money from shareholders, recycle some of it back as dividends. It would be better if they scrapped the dividends and just used the cash to build the portfolio but if you don't pay a dividend income funds can't invest (this is the same reason that companies occasionally maintain the fiction of a payout using script).
This BBC article indicates where they want to take the company:
By then, he hopes Hipgnosis will have a catalogue of around 60,000 songs, at which point they'll get out of the acquisition business and focus on placing their hits in video games or TV shows, getting new artists to cover them, and making sure they're featured on prominent playlists.
https://www.bbc.co.uk/news/ent...
They're currently at about 15,000 songs so this cycling of cash is likely to go on for a long time. We either need to buckle down for the ride or go elsewhere for a few years.
I like the idea of song royalties as a permanent income stream and I also hold Spotify as I think the market for streaming is only going to grow. There's also the recently launched Round Hill Music Royalty Fund Lp (LON:RHM) which I'm also keeping an eye on.
timarr
I think you've hit the nail on the head timarr. Hipgnosis Songs Fund (LON:SONG) seems to me to be a serial fund raiser that taps the market whenever it wants more money, without demonstrating any organic growth. Decidedly off-beat and out of tune to my mind!
It’s a similar model to healthcare property owner Target Healthcare Reit (LON:THRL) isn’t it? Build an ever larger portfolio of income generating assets through fund raising, polish the assets and squeeze greater returns out of them. (I hold both in my income portfolio .)
I am becoming a disillusioned holder of £SONG. Looking at the NAV bridge from116.7p to 125.4p during the six months, the "strong fair value uplift" only contributed 0.6p. The reduction in discount rate from 9.0% to 8.5% added 10.5p. Haven't the foggiest what a reasonable discount rate should be but the Group probably is looking to further reductions to fuel NAV rises.
Announcing the possibility of further share issues is also a good way to dampen short term demand for the shares.
Re Hipgnosis Songs Fund (LON:SONG) - I actually think they did pretty well under the circumstances.
Need to bear in mind the very substantial hit to revenue that CV19 will have caused to live music. Maybe not so much to the half reported on, as there is some delay to money coming down the pipeline.
Earnings from live performances is not to be sniffed at - and there haven't been any.
Impact going to be even more noticeable in the next set of results and I'll be keeping some money available to buy more in case those results scare a few holders into selling.. Concert halls, arenas and stadiums are going to be packed from next summer with acts desperate to make up for a year of negligible earnings for more than a year and ticket prices are only going one way.
PAUL/JACK - could you analyse this Hipgnosis Songs Fund (LON:SONG)? It is niche but actually could be v. valuable....
Hi Snooker2020,
I've had a quick look at Hipgnosis Songs Fund (LON:SONG) - it's almost £1bn market cap, so I wouldn't normally cover that here unless I had some particular insights (e.g. if it was in my sector specialism of retail/eCommerce). We tend to stop at approx. £400m market cap here, with only occasional incursions into larger companies' territory.
Personally I cannot see the appeal of SONG. Music seems widely available free on the internet, and streaming services like Spotify pay peanuts to the owners of the songs. So quite where that leaves the long-term prospects for SONG, I don't know.
Hence, long-term sustainability of profits is my main concern, which rules it out as an investment for me.
Regards, Paul.
"Hence, long-term sustainability of profits is my main concern, which rules it out as an investment for me."
You might be rights as far as Hipgnosis Songs Fund (LON:SONG) is concerned Paul (that's probably a call on the people running the company) but, on a general point, songs can make an excellent investment. As far as I can see, copyrights in songs are even better protected than patents and that protection lasts a lot longer.
Music might appear "free on the internet" but, in the vast majority of cases, someone is paying for it, whether it be by subscription charges, advertising etc. You could just as easily say that music is free on the radio - but the BBC (and all those other radio stations that people listen to) pay millions for the rights to broadcast music.
Yes, streaming pays peanuts - but you can get a pretty good meal out of millions of peanuts. And that's only part of the income stream. As I mentioned in an earlier post today, the live performance royalty rate increased by over 30% and that on ticket prices that themselves have been increasing by multiples of the rate of inflation for years.
There's a helpful Hipgnosis Songs Fund (LON:SONG) results powerpoint https://static1.squarespace.co...
Rather more upbeat than the webcast. Should have enough info (p 21) to allow you to substitute your own preferred discount rate or estimate the mean term of projected revenue streams. Personally I'd prefer to see a projected revenues chart (from existing catalogue) as obviously very many assumptions go into this, eg royalties inflation (if any) and rate of decline as songs fall out of favour. A slight red flag is that two of MM's family have key roles - General Manager and Chief Creative Officer. (Remember the Burford CFO scandal?)
To me, some key risks are:
But I bought in as a pure income play so it's pleasing to see potential for revenue growth. At the end of the day, it's little different from a traditional REIT but with IP not physical assets so different risks and potential opportunities.
Yes Spotify pay peanuts per song but they are spreading into new areas, such as Russia, they now have about 300m users, Deezer also is similar size. Amazon also do streaming as well as Apple, it will be how most music will be consumed, even Japan will move in that direction soon. You just need to look at how cd sales have fallen in the last few years and see how streaming has replaced it. Also Youtube and internet radio stations all pay a fee, not much is free.
But I think this year has been very good for streaming services, not just in the UK but in many countries around the world.
I don't hold Hipgnosis Songs Fund (LON:SONG) but I'm considering it.
Thanks for the comments. Also thanks to readers who commented. My view, the catalogue is actually not great quality and not v current.
Hi Snooker2020 - Hipgnosis Songs Fund (LON:SONG) - You mean there is nothing from Paul's Disco Bunny era?
With Nile Rodgers as one of the Hipgnosis Songs Fund (LON:SONG) founders I suspect Paul's Disco Bunny era is well covered.
Hipgnosis Songs Fund (LON:SONG) But more people are streaming this year than ever, as they switch from buying cds to streaming, also with the lockdowns and people not working, they will be streaming even more. I see Covid being an advantage for them not a hit. Spotify and others are doing very well this year.
Why will they make money from live music?
Re Hipgnosis Songs Fund (LON:SONG)
"Why will they make money from live music?"
Copyright owners in the songs get paid a royalty whenever that song is performed at a concert. The royalty rate went up last year from 3% of value of ticket sales to 4%, although the rate for qualifying festivals went down slightly.
That's pro-rata, so if 20 songs performed at a concert then each song earns 1/20th of 4%.
The Hipgnosis Songs Fund (LON:SONG) investor call just now was rather dull. MM spouting on about all their recent additions, says 'nostalgia' has been strong in lockdowns. They do seem to have a strong management team. Just a few random points:-
NAV upping reflects indep valuer discount rate falling from 9% pa to 8.5% pa. Justified lower risk premium on grounds of greater confidence in streaming as a stable income stream. Has analogies with renewables sector where similar derating of discount rates in recent years has seen 200-300bps compression.
Live revenues obviously very weak this year but Sync (14% of revenues?) is strong - eg have a song featured in M&S Xmas ad. Peleton and TikTok also growing (I thought recently Peleton were in trouble for royalty dodging).
Streaming proved resilient to economic stress during lockdowns.
Approval for up to 30% gearing.
Operating costs falling as a % of revenues.
Royalty collection/audit process improving.
Seeking to grow young artists from scratch.
Boosted song management team - I gather these dudes work actively to promote songs in media.
Overall I came away with confidence that they know what they're doing and the recent acquisitions look sensible. I've held for 2 years now.
Oddly, I do slightly mourn the gradual loss of physical clothes shopping. That certainty that something fits and doesn’t make you look like you have a weird body simply cannot be achieved shopping online. I hate shopping online for clothes. I know that bucks the trend. My better half is a clothes returning ninja and is very successful, everything I send back either gets lost in the post or isn’t refunded quickly (if at all!). For clothes specifically, I don’t know how shopping online could provide a better experience than it does, but it will never beat the feel good factor of walking into a shop, trying something on, being assured it works, and buying it!
I think it will bounce back fairly well, although it will never be as big as it was. Physical cloths shopping was/is too big a leisure activity for many to not return. How else can better half's punish their partners, than be dragged despondently around waiting rooms? That's why I think Boohoo (LON:BOO) success may slow especially considering their demographic.
My wife complains all the time that if shopping she has to see how the clothes fit on her so won't buy online. The issue this causes with high returns (20-40%!) is the main issue with online sellers to my mind as it's the huge cost that has to be solved - it's why I think guys like BooHoo at the cheaper end have a chance but the higher end guys will have it very rough if they try to migrate out of physical stores.
I've thought for a long time there is a massive opportunity with body mapping for online clothes selling (basically advanced method of fitting where customer is photographed beforehand and clothes can be shown fitted on them). I've yet to find any route in the public space though to invest in it. There was a US company Body Labs that was flirting with listing a few years ago (and got me excited) but then got bought out by Amazon for $70m-ish. Don't think they ever did anything with the tech yet. There's another company I've been looking at - Zeekit, VC backed Israeli outfit whose tech I think is awesome but no sign of them coming to the market yet. Anyone know of any others in the public sector who might be worth a look?
Hi Phuntt
Following on from your post about clothes bought online not fitting, I think there was a Japanese company that tried body mapping a couple of years ago too, but that also failed to take off (the clothes that arrived still didn't fit properly).
In any case my understanding is that for single brand sellers it's easy for a customer to know what their size is once they have tried it once.
I imagine it's harder for an online player such as Asos (LON:ASC) which is essentially a marketplace for several brands, each with their own slightly different interpretations of what a size 10 is.
In response to your last question - "Anyone know of any others in the public sector who might be worth a look?" - I'd like to suggest SFIX (Stitch Fix).
It's certainly not an idea that I ever thought would work, but they're booming right now. The advantage they have over traditional online sellers (is that a term yet?) is that they know:
It's a very powerful tool, with high conversion rates and reduced returns, driving higher margins and sticky customers.
The only other player I know who are now trying the same thing is...Amazon.
I see this is as a good thing, because clearly Amazon sees something in the model too.
Results for SFIX are out this Monday. I don't hold yet, but it's very high up my watch list.
Cheers
A
Was that UNIQLO, they do go into more detail about sizing. Not very large in the UK but popular in Asia.
Yes if you know the brands then sizing should not be such an issue.
No, it wasn't Uniqlo.
Just found it - the Zozo suit.
This is behind a paywall but you can read just enough to see that the body suit idea didn't take off.
https://qz.com/quartzy/1539036...
Uniqlo have their own piece of sizing stupidity, as they now stock men's jeans with only 34" inside leg in the UK.
Their argument is that they do a free alterations service, so these can be shortened.
That's OK if they can fit in the order when required AND the customer has time to pop back later.
Even fast growing successful retail businesses make mistakes.
A doddle! Solid pair of scissors and a reel of that iron-on hem tape will do the trick, speaking as a short-legged dude.
Thanks for reply Abtan. I listened to great interview with Katrina Lake from Stitch Fix during the summer - https://podcasts.apple.com/gb/... if interested. I never invested because I don’t like the box model (although their return levels are best in class).
To be honest, I’m still pretty sure Amazon are going to end up dominating this space. Can you imagine a world where all their customers (which is most of the western world after lockdowns) are perfectly sized into every item of clothing on their site and customers can look at themselves in catalogs of the clothing before purchasing? They would quickly dominate the clothing world and with AWS they have the spare computing power to make it happen like no one else. That’s what I see as the main competitive threat to retailers like Boohoo (LON:BOO) unless there is a viable option for them.
At last, someone who cares about how it fits......
Agreed, I rarely go clothes shopping, but do prefer going into a shop to try before I buy on the rare occasion I do. The strong retailers will survive / thrive, the likes of Primark, Zara, H&M, Next who have well invested estates and have strong brands will bounce back strongly with physical stores, where there will be even fewer competitors.
I wholeheartedly agree. Not once, when I have bought clothes online, have they been a successful purchase, and the hassle of returns is somewhat painful. Needless to say I have never tried to but footwear online. IMHO I think you have to be able to try things on.
I tend to order online and then pick from a shop, if they don't suit then I can return them to the shop. I found going into shops frustrating, as often don't have the size/colour I want and are often cheaper online. I usually buy from the same shops, so have an idea if they will fit. I have given up buying clothes from Amazon etc., as often don't look the same as the image and had trouble with returns. I have bought shoes online which were fine, NB trainers. Clarks, I ordered online in their sale and then tried them on in the shop, note most of those were not available in the shop, I then returned all that were not good enough, I think I bought 2 out of the 7 I ordered. I even got a further discount as the online prices had fallen since I ordered them.
So physical shops are useful to me.
Yes I used to but about 10(maybe it was 15 time flies at my age!) for the colder months, so probably 8/9 months of the year, I adopted the Steve Jobs school of dressing (black roll neck from Amazon and black jeans) always same brand. I just order online when I need and always fits. Reduces the time thinking about clothes and the shopping for them.
Summer is little more varied but not much.
I can highly recommend it. No need to visit a clothes shop ever again and I like clothes shopping. I worked in retail for six years a long time ago.
I thought roll-necks went out in the 70s?
You are the only person I have heard admitting to wearing them. I think I even had some in the 1970s, never liked them. I wear fleeces now.
HI Michael
With not having to commute all over the country and have regular periods living away from home Monday-Friday I have found that I have far too many clothes, so I am just now cycling what I own and actually wearing things out rather than getting more, finding the wardrobe/drawers down shut and then having to find a charity back to clear something out.
And then I plan on following my step-mum down the recycle route of purchase as much as possible so ebay or the local charity shop. Until my daughters complain then they can get me a couple of outfits they will maybe consider being seen with me in public.
Cheers
Tommy
ps. Boohoo (LON:BOO) I hold
Property Franchise (LON:TPFG) (which I hold) possible bid for Hunters Property (LON:HUNT) which looks like a reasonable geographical fit. The property franchising model has come through the downturn in good shape and TPF's return on capital is much better than Hunter's so it looks accretive to growth. They'll have to raise funds, though.
As with all people businesses there's always a risk in these transactions but franchisees will be committed to their businesses. I do like a well run franchise model.
Increasing corporate takeover activity both from overseas and internally isn't surprising - the UK has had the worst performing stockmarket since the Brexit vote, sterling is on its knees, the global perception of the handling of the pandemic is poor ... in short, it's probably a good time to get on board.
Anecdotally - and an anedote is only ever a data point, never proof - I'm seeing a lot of friends approaching me for advice on investing in shares. The reason's fairly obvious - returns on everything else liquid are dreadful. It's hard to see how stockmarkets can't climb in this environment. Which is not to say short-term volatility isn't possible - if the Brexit deal fails, or the vaccines don't work, or we get another series of lockdowns then they'll fall. And the more naive money enters the market the quicker it will be to leave.
Still, for investors, these look like good times.
timarr
My morning smallcap tweet:
Telit Communications (LON:TCM) Hunters Property (LON:HUNT) Smartspace Software (LON:SMRT) McBride (LON:MCB) Tavistock Investments (LON:TAVI) Image Scan Holdings (LON:IGE) Sutton Harbour (LON:SUH)
Telit Communications (TCM) Dbay considering increasing its offer to 190p. "Dbay does not believe the u-blox proposal [worth 250p in shares] is compelling and does not intend to accept the proposed all-share proposal should such an offer be made by u-blox." [SP=202 Cap=269m]
Hunters Property (HUNT) possible offer. [SP=61.93 Cap=19m]
Smartspace Software (SMRT) Evoko releases next generation meeting room panels 'Naso'. "irectors believe the relationship with Evoko has the potential to generate significant future revenues for the Company in the form of both revenue sharing from the sale of Naso panels and SaaS software subscriptions." Trading: 'good progress' nut no numbers. Anders & Kern still below pre-covid rev. [SP=99 Cap=28m]. I hold.
McBride (MCB) guides FY(June) pretax at least 10% ahead of the consensus of £25.2m after H1 rev up 2%. [SP=66 Cap=120m]
Tavistock Investments (TAVI) postpones AGM to reconsider outrageous new LTIP after holders object. [SP=1.5 Cap=9m]
Image Scan Holdings (IGE) FY(Sept) rev up 50%, pretax £113k in line with Oct trading stmt. Outlook "some larger government procurements of security systems have been delayed. Nevertheless, we have continued to receive a steady stream of smaller orders and are optimistic that this will continue. By continuing to invest in the portable X-ray product range we expect to be well positioned when procurement returns to a more normal level. We aim to make the first sales of our new cabinet X-ray systems." No current rev figure. [SP=2.2 Cap=3m]
Sutton Harbour (SUH) FY(Sep) NAV 39.8p/sh up 0.1p in H2. "[covid] restrictions have had an impact on trading revenues but to date our business activities have shown resilience to recover as more normal operations can resume." [SP=14.55 Cap=18m]