Small Cap Value Report (Fri 4 Oct 2024) - JDW, RBGP

Good morning from Paul!
Very quiet for news today. I'll leave it there for today, and the week. Have a smashing weekend, and see you back here on Monday hopefully!
Weekly macro/markets summary -
Usually included in my podcast, I thought we could trial having a written version here, as it’s very quiet for company news today. If people like it, I can make this a regular feature.
These are the significant markets & macro points which I jotted down on my pad this week (necessarily not exhaustive) -
Escalation of Arab/Israeli conflict, after Iran fired c.200 missiles into Israel. Minimal casualties, but Israel/US reportedly considering retaliation on Iran’s oil and/or nuclear facilities. Said to be the cause for 5% rise (Thu alone) in spot crude oil price from recent low of $65, to c.$73 (as at Thursday evening). Bank of England Governor also mentioned the risk of oil prices soaring due to M.Eastern conflict. This again questions the wisdom of the UK pursuing net zero priorities, instead of national energy security (particularly gas).
Also this week Israel invaded Lebanon with ground forces, another major escalation, so we should be increasingly worried about geopolitical crises, including of course the continuing Russia:Ukraine war. What (if anything) should we do with our portfolios?
Key comments from Bank of England Governor in a Guardian interview indicated that UK interest rate cuts could be more aggressive, as inflation is easing better than they expected. This put a stop to the rising pound, now fallen from a peak of c.$1.34, to $1.314 at the time of writing. Lower interest rates obviously good for equities, and earnings (at leveraged companies).
Rachel Reeves speech at Labour Conference reiterated that Corporation Tax would not be changed for the duration of this parliament - reassuring for businesses and company earnings forecasts.
UK services PMI data (a key forward-looking indicator of business confidence for the bulk of the UK economy) - softened to 52.4 in September, down from 53.7 in August.
Profit warnings (covered in SCVR) - 7 this week: ECO Animal Health (LON:EAH), Inspiration Healthcare (LON:IHC) , Wynnstay (LON:WYN), Aston Martin Lagonda Global Holdings (LON:AML) , Brighton Pier (LON:PIER) , Surface Transforms (LON:SCE) , and Likewise (LON:LIKE)
Ahead of expectations (covered in SCVR) - modest beats or raised forecasts for James Halstead (LON:JHD) and Renew Holdings (LON:RNWH) . Note large cap Tesco (LON:TSCO) also raised guidance.
Takeovers - Australians withdraw approaches for Rightmove (LON:RMV) after being rebuffed. Hopeless Musicmagpie (LON:MMAG) receives a rescue bid at 9p (it floated at 193p!) from AO World (LON:AO.). Learning Technologies (LON:LTG) possible bid at an opportunistic 100p (too low I think).
Good institutional support (at only a 4% discount) for MPAC placing & acquisition - an encouraging sign that the market is still working, and will fund companies, if the right deals are put together. Strong share price reaction afterwards too.
Private equity bids - why are management teams often supportive of deals that don’t seem to offer much shareholder value? Self-interest perhaps, but also that private ownership can make it easier to expand rapidly, avoiding the slowness, cost and bureaucracy of raising money from public markets. Stock market listings less attractive than ever, maybe?
Mortgage approvals up again in August (source: Bank of England) after a strong July, more evidence that residential housing market is improving gradually.
Nationwide house prices index confirms this, with average house prices up 3.2% over the year to Sept 2024.
AIM feels wobbly, and with erratic price movements. Increasing speculation that this could be due to budget-related actions by some investors, in particular worries that AIM IHT relief could be curtailed or scrapped (Peel Hunt note warned that this could hit some AIM shares by c.20-30% if IHT funds become immediate sellers from redemptions). Also some scuttlebutt that some SIPP holders are liquidating positions in order to take their 25% tax-free lump sum. All worrying, but we could also be laying the groundwork for a strong autumn rally, if the disaster scenarios don’t happen. Your guess is as a good as mine!
Reader comment of the week, “I like the muppets, leave them out of this…!” (Peter T)
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Summaries
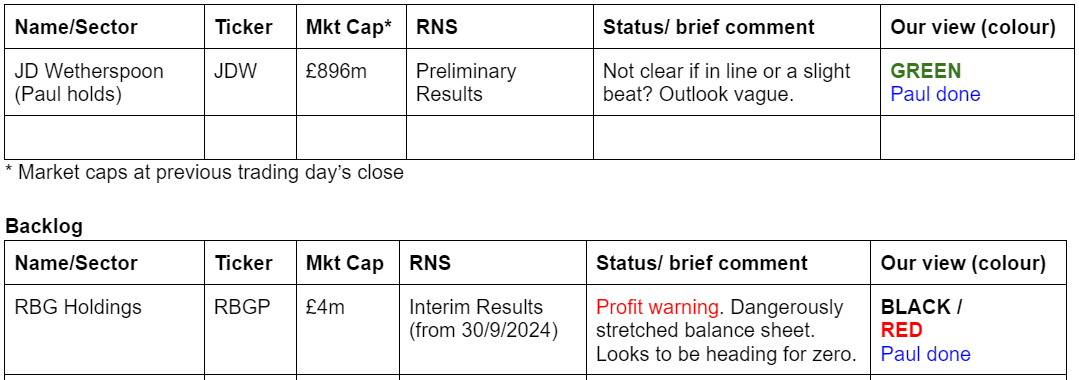
J D Wetherspoon (LON:JDW) (Paul holds) - up 1% to 729p (£904m) - Preliminary Results (52 wks to 28/7/2024) - Paul (I hold) - GREEN
Results look in line or slightly above. Outlook vague, but no different to usual. Balance sheet has plenty of freehold assets which comfortably exceeds debt, so no issues there. Most pubs are now freeholds. I remain of the view this looks a decent, differentiated business, that has further upside to earnings as it continues to rebuilt profits. Looks reasonably priced. So I see quite good risk:reward here.
RBG Holdings (LON:RBGP) - down 21% to 2.38p (£3m) - Interim Results (RNS 30/9/2024) - Paul - RED
Rather belatedly, I look at H1 results out on Monday, and as the share price has been clearly signalling, the news is really grim. The plc looks essentially bust to me, so the only question is what form a refinancing will take, and will there be any value remaining for plc shareholders? Sorry I didn't update sooner on this one, which back in the spring looked as if it might be a risky, but possible turnaround. Not any more unfortunately, based on the worsened balance sheet weakness, excessive bank debt, and another profit warning.
Paul’s Section:
J D Wetherspoon (LON:JDW) (Paul holds)
Up 1% to 729p (£904m) - Preliminary Results (52 wks to 28/7/2024) - Paul (I hold) - GREEN
The value for money pubs chain (also small hotels operation too) puts out decent results to July 2024 today.
Highlights table -
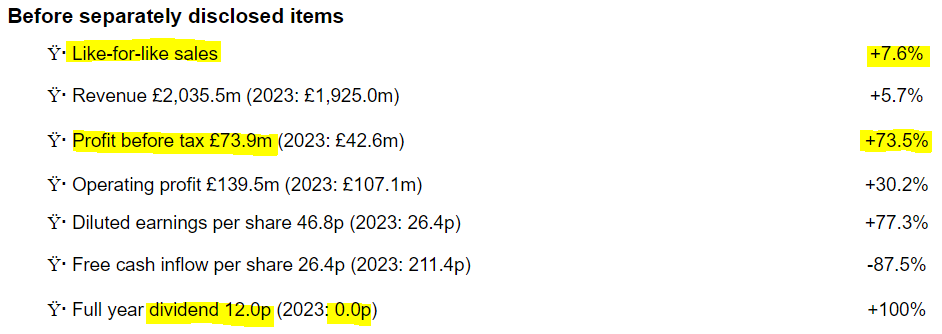
I’m not sure why it has a capital Y with an umlaut for each bullet point above? Maybe it’s supposed to be a picture of a cocktail?
JDW is showing strong profit growth, as it continues recovery from the pandemic lockdowns, and of course more recent headwinds from consumer squeezed incomes, and cost inflation. As a holder myself, I’m happy with these numbers.
Dividends have now resumed, only a 1.65% yield at 12p, but it’s a start.
Is this an earnings beat? I’m not sure as there aren’t any broker updates available. Stockopedia has 43.1p adj EPS as the forecast average from 9 brokers. Actual (not necessarily on exactly the same basis though) is above, at 46.8p (PER 15.6x). So this seems to be in line, or slightly above, which is what the fairly static share price is telling us today too.
Adjustments - or as JDW calls them, separately disclosed items. Are they reasonable? Note 4 gives the detail, which shows quite hefty losses of £32m this year, and £48m last year, relating to property - eg impairments on closure of sites, and various other adjustments. I would like some reassurance that these are not likely to keep happening every year. These have been mitigated (2024) or more than offset (2023) from gains on finance income, which I think relates to the inspired decision to cash in a massive profit on interest rate hedges taken out during the zero-interest rate era. So I’m flagging note 4 for you to have a closer look at, as it does seem that heavy property losses have been obscured somewhat.
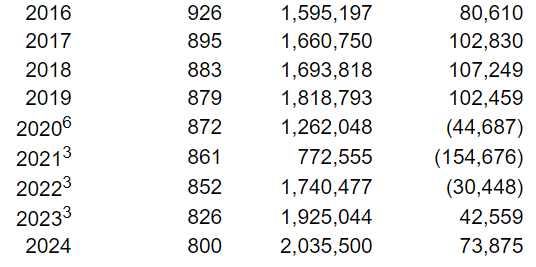
The usual table is shown (below) of the remarkable long-term growth of JDW. The recent years excerpt below is there to demonstrate how its profits peaked at just over £100m in 2017, 2018, and 2019 (pre-pandemic), then were obviously clobbered by the lockdowns in 2020,2021 & 2022 (also start of energy crisis), before recovering nicely in 2023 and 2024. It stands to reason that there should be scope for profitability to recover further back to c.£100m.
The columns are, left to right, year, number of sites (notice it’s fallen, as under-performing sites closed), revenue in £k, and adj PBT in £k.
Rather repetitive commentary from eccentric Chairman/founder/25% shareholder Tim Martin covers the usual themes -(in a section headed “You cannot be serious”!)
Worries about more lockdowns, and lack of analysis as to whether they were effective in saving lives or not,
Price disparity & unfair taxation for pubs vs supermarkets.
Scottish business rates being unfair.
VAT inequality.
Pubs collect in a huge amount of tax for the Govt.
The usual points about corporate governance rules forcing out experienced, sector knowledgeable Directors.
High staff retention, staff bonuses, and profit shares.
Awards won.
Press lies about JDW, which constantly have to be corrected, but still get repeated.
He doesn’t like proposals to curtail pub opening hours, and points out pubs market share has fallen vs supermarkets, despite longer opening hours introduced in 1988 & extended in 2005.
Pubs are regulated, and drinking supervised (and recorded on CCTV), much better than drinking in parks, homes, etc -
“This does not mean that pubs are invariably oases of tranquillity but, in general, pub behaviour is good and pubs are valued by communities.”
He also rebuts the “slightly daft” proposal from Cambridge University, that beer should be sold in “schooners” (⅔ of a pint) not traditional pints -
“For example, our Aussie cousins, notorious guzzlers, already use schooners without any noticeable reduction in consumption.”
‘Spoons top selling draught drink is Pepsi, with coffee outselling Pepsi. Although it’s cleverly worded, and I bet you 50p that all the beers added together sell a helluva lot more than Pepsi! So I think we can take this with a pinch of salt. But it is a fair point that many people in ‘Spoons are eating & having soft drinks. I mystery shopped the Mary Shelley in Bou’mth again yesterday, and was delighted with the table service via app, my Stella arrived in literally about 1 minute, and a nice enough microwaved curry (I accidentally over-ordered and it came with 4 poppadum, plus a nan) followed about 5 minutes later, all for £12.47 - not much more than you’d pay for some supermarket beer and a ready meal. And no washing up to do. I also had the dubious pleasure of listening to some nearby “old gits” (think a cross between Alf Garnet and one of Paul Whitehouse’s characters) loudly putting the world to rights, and accusing various celebrities of being terrible people. Plus some incomprehensible story about a builder being paid to stay away from a building site in the 1970s or something. I shouldn’t have been earwigging, but they were so loud, they drowned out my headphone podcast.
Outlook -
"The company currently anticipates a reasonable outcome for the current financial year, subject to our future sales performance."
As indicated above, sales continue to improve. In the last nine weeks, to 29 September 2024, like-for-like sales increased by 4.9%.
I suspect some investors may be missing a trick on LFL revenue growth. Last year, inflation was much higher than it is now. So although LfL sales have slowed from +7.6% FY 7/2024, to +4.9% in the new financial year, inflation has fallen from c.5.9% a year ago, to c.2.2% now. So the “real” revenue growth by my simple calculations has actually gone up from +1.7% a year ago, to +2.7% now.
Hence sales growth in real terms, has not slowed down this new financial year, it’s actually grown slightly.
Freeholds - note JDW has been steadily buying more freeholds (excellent, in my opinion) and 72% of its sites are now freehold, up from 41% in 2010.
Expansion - there are currently 800 ‘spoons, it says there’s scope for c.1,000 in the UK. So not particularly exciting growth potential. Although there could be more growth from hotels, which is an interesting sideline, and it talks about expanding existing successful pubs into adjacent buildings, adding beer gardens, etc.
Would it ever consider overseas expansion I wonder? Probably best not to risk it, is my view.
JDW has also started doing some franchised sites, including at two universities, and is considering other franchise opportunities. Interesting!
Overall then, growth does seem to be on the agenda, despite the reduced number of sites. I recall in an interview earlier this year, Tim Martin said they made a mistake in duplicating sites in the same location, where they had a quiet pub, and a noisy pub (with music), but that idea didn’t work, hence why some sites have been closed, he even laughed about making a mistake that cost the company £100m.
Multi-site operators in retail and leisure are constantly assessing and tweaking their estates, so I don’t see any issue with any of this, in fact it’s good to see an estate being actively managed to weed out the under-performers, or let sites go where landlords demand excessive rental increases, etc.
Balance sheet - the massive item is £1.37bn in fixed assets (property, plant and equipment), of which most is freehold (and long leasehold) NBV £1.07bn.
Working capital is heavily negative, or favourable I should say (as cash comes in before trade & other creditors have to be paid), with current assets of £122m, and current liabilities of £351m.
Long-term borrowings (excl leases) is substantial at £719m, but of course this is comfortably exceeded by freehold property assets, so it’s not a concern.
NAV is £402m, with only £6m intangible assets, so £396m NTAV or 320p/share, so some asset backing of the 729p share price.
I can’t find any mention of what the current market value is for its freehold estate. Freeholds seem to be in the books at cost, and don’t seem to have been revalued upwards. So possibly there might be upside on freehold valuations, although town centre properties may also have fallen in value. A property surveyor once told me that pub freeholds are based on the profitability of the individual site, which makes sense, or alternative use if loss-making.
Bank facilities were renewed and improved, and fresh interest rate hedges are now in place, to protect against an unexpected spike up in interest rates, which may be unlikely, but that’s what people thought in 2022 and 2023 too! JDW’s hedges then proved a stroke of genius/luck.
Paul’s opinion - I’m happy with this, there don’t seem to be any issues.
I remain of the view that ‘Spoons is a differentiated business (much cheaper selling prices than the competition), hence has a loyal customer base. It’s the pile it high, and sell it cheap operator in the pubs space, with decent enough product at good value prices. I've never had any problems at many 'Spoons sites I've visited, nobody's ever bothered me.
I think profits could have further scope to rise further, and maybe return to historic margins, which would mean a higher share price I think.
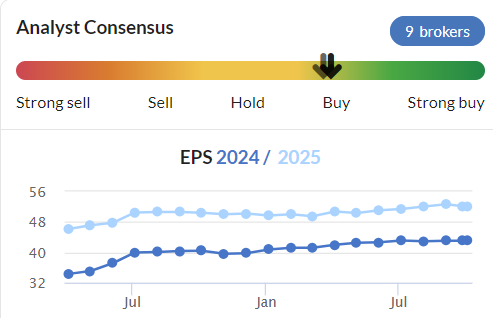
Stockopedia shows a fwd PER of 13.9x, and that’s on what seem conservative forecast assumptions. I’m hoping it might continue to see forecasts edging up, with a positive trend well established already -
Summary - I think JDW is a decent, differentiated business, with a strong market position. Shares look good value to me, so I’m personally happy to continue holding. I think there’s a possible opportunity here for earnings to rise more, and the PER to expand a bit further too. This share probably won’t shoot the lights out, but I can see more upside than downside on it at the current price.
RBG Holdings (LON:RBGP)
Down 21% to 2.38p (£3m) - Interim Results (RNS 30/9/2024) - Paul - RED
I meant to review this earlier this week when H1 results came out, as there was a lot of reader interest in it, at/near the top of the “most viewed” home page widget. Shares are in freefall now, so obviously the damage has been done for any bulls still left holding it. However, I thought it might be useful to review the situation anyway, in case people are tempted to bottom fish for a possible recovery (the short version is, I wouldn't personally).
I’m embarrassed to see that when I last reviewed this problematic holding company for 2 legal practices, I was amber/green back in March and April. Obviously that looks really bad now, six months later. However my view back then was moderately optimistic because RBGP had taken seemingly good turnaround actions - disposal of the last problem division Convex, small placing to improve balance sheet, renewed bank facilities, and turnaround actions (eg cost cutting). Hence to me, at the time, it looked an interesting potential turnaround, albeit peppered with high risk warnings in the SCVRs at the time.
Unfortunately, the last six months have not gone well, despite the perky tone of the H1 results commentary out on Monday.
“RBG Holdings plc (AIM: RBGP), the legal services group, today announces its unaudited results for the six months ended 30 June 2024 ("H1 2024").”
“Executing a clear strategy to restore value and reduce risk profile”
Trading - was in line for Jan-Apr 2024, but saw “a marked decline” in May & June 2024.
Adj LOSS before tax of £(2.8)m in H1 - statutory LBT £(5.7)m - I think that’s so bad, it might not be a recoverable situation.
I cannot fathom this quote below, how is this possible? Maybe the banks relaxed the covenants? -
“The Group was during the period and remains in full compliance with its banking covenants.”
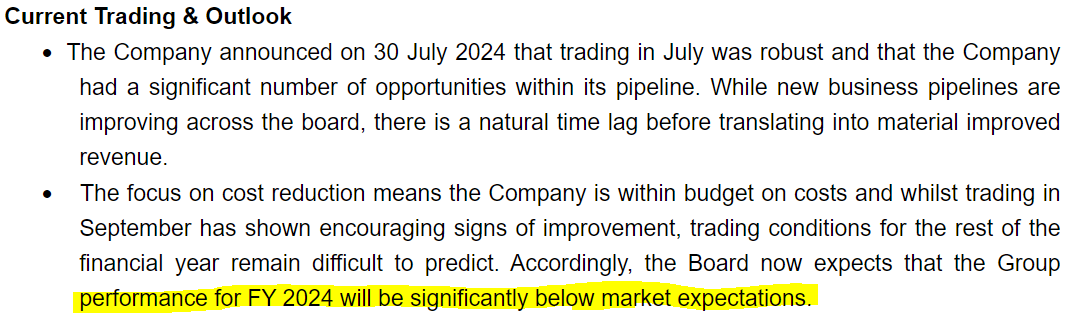
Outlook - is another profit warning, despite an attempt to polish the proverbial turd -
Balance sheet - is also really bad, and doesn’t look sustainable to me as currently structured.
It’s laid out wrong, in the American style with assets bunched together, then liabilities lower down.
I’ll edit & summarise the balance sheet below - with all intangible assets and lease entries removed.
Fixed assets £1.8m (office fitouts & computers, so probably very little resale value)
Receivables £19.4m (which tend to be high at solicitors, but often are not fully collectable)
Cash £1.5m
Tax assets £2.2m
Current assets total £23.1m
Trade & other payables £11.5m
Debt (excl leases) £4.1m
Current liabilities £15.6m
Net current assets £7.5m
So far that looks a survivable position, providing it can collect in the receivables at a sufficient pace to meet the payables due.
On to >12 months creditors, oh dear, this is the breaking point -
Debt £21.75m
Net tangible assets negative £(12.5)m
Hence this business is completely dependent on the bank debt remaining in place. I imagine the bank must be having kittens at how bad the H1 results are, and the uncertain outlook. In total the bank is owed £25.9m secured (on what? Receivables presumably?) so it’s really in a quasi-equity position now. Four times the commentary says it is and remains in compliance with its bank covenants. I don’t believe that’s likely to remain the case - how can it? A loss-making business that owes its bank about 10x its market cap!
Going concern - gives itself a clean bill of health, with no explanation. I have to invoke Victor Meldrew here - “I don’t belieeeeeve it!”
RBGP is clearly going to need a refinancing, probably at a guess I’d say it needs c.£13m to correct the negative NTAV position back to c.zero, and pay down half the bank debt. Given the market cap is now down to only about £2-3m, then dilution from any fundraise now looks likely to be ruinous, and could be at any price (1p? Less? Who knows).
Existing equity now looks probably worthless unfortunately. Maybe a restructuring could involve putting the plc holding company into administration, after selling off the operating companies to anyone who’s prepared to fund newco. I seem to recall there are difficult rules around legal firms and insolvency, as you would expect.
On Tuesday this week, 21% shareholder Ian Rosenblatt told Sky that he’s intending to requisition an EGM to remove the CEO. The company hasn’t issued any RNS, so possibly has not yet received any EGM requisition. We were told yesterday by RNS that the Senior Partner of Rosenblatt (the main operating business of RBGP) has resigned as a plc Director, but remains a Director of two companies below plc level. This suggests to me that Rosenblatt (the firm and the individual) are possibly trying to extricate themselves from the plc in some way.
Paul’s opinion - things have clearly deteriorated considerably, and the hoped-for turnaround which seemed possible six months ago just hasn’t happened. Hence this plc now looks essentially bust to me, with bank debt now being the main priority. It’s the type of situation when RNSs start to talk about “stakeholders” instead of “shareholders”. Could it be a multibagging turnaround? It’s possible, but looking increasingly remote in my opinion.
I don’t know what the outcome will be, but the facts have clearly worsened very considerably, from a high risk possible turnaround, to a very high risk likely wipeout for equity. For that reason, I think it’s very important not to risk money we can’t afford to lose on this share. Adding to existing positions in the hope of a miracle very rarely works in my experience. So rather belatedly, it has to be RED - best avoided.
I won’t be tempted to have a punt on this, as I think the risk of a total, or near-total loss has to be over 50% after these awful interim results. That’s what the share price is telling us too. If it was going to be rescued, then insiders would be filling their boots, which they’re not.
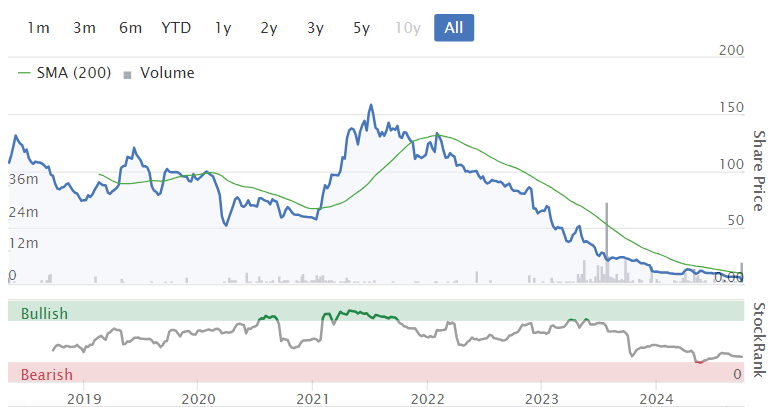
IPO to catastrophe in just over 6 years -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

134 comments
Thanks to everyone who offered suggestions on how to invest in gold.
Don't forget Silver. Gold down on Friday but Silver held up. Silver has been following recently and there is a disconnect with the gold/silver ratio.
When gold becomes very expensive (the BRICS have bought it all up) then silver will pick up as money again. Its also used in solar panels and lots of electrical connections so has industrial demand supporting its future wealth value - imo.
Good advice thank you. Physical gold and silver are available as individual ETFs but it would seem there is not an ETF that combines both.
Morning SCI20,
"but it would seem there is not an ETF that combines both. "
Have a look at Sprott Physical Gold and Silver Trust (LON:0N2R) :
The Sprott Physical Gold and Silver Trust
Why Invest in CEF?
Morning Alphaflight, I researched the Sprottt combined ETF and it is exactly what I am looking for, however AJ Bell my pension platform provider does not offer this. It would seem I will need to open a gold and silver ETF separately. I note that Edmund Shing has today highlighted the strength of silver.
Hi Paul,
Yes please to your offer of a weekly markets/macro summary
I can't believe it's not butter!
Games Workshop (LON:GAW) hit a yearly high today. Amazon sales ranking of its products has been impressive, especially the new Space Marine II game. On a micro scale, my wife is an artist and attends cons around the country. One of her upcoming cons has two Warhammer painting workshops, and both are sold out apparently. Little things...
I wouldn't be surprised if we get another 'ahead of expectations' update next month, after the shortest ever 'trading in-line' statement last month. Amazing company, fanatical fan base with spare money, and a fantastic IP.
Tottenham Court Rd shop is empty. Grandkid into Skipidi toilet and Robucks. I did hand painted Napoelonic figures as a youf but not sure this lot have it. Nice if they do.
Hi guys
I actually think the quality of the SCVR is amazing. To me the summary, podcasts, macro, more detailed company & comments sections all fit like a glove.
Yes, people have different opinions and occasionally get things wrong - myself very much included.
Yet equally, investing all about the head & the heart. Thinking rationally, formulating views on IMPERFECT data, recognising/accepting emotional biases, and balancing risk & reward. SCVR does all this brilliantly.
Why has anyone implied that the quality of the SCVR is not amazing?
The quality of the SCVR is and very informative and a tool for further research.
It’s the quality of the comment section that has lost its quality-for example people posting that there is an imminent yen carry trade 2! , without even realising that there were elections the day before.
You know what I mean……
All the best
Oh dear
Love the weekly Macro/Micro summary. Please keep doing it.
Gattaca plc (LON:GATC) for those who have noted the progress of the new management (see August TU) there will a FY results webinar by the CEO and CFO for all interested investors on Thurs Oct 24th at 11am. Just register here https://us06web.zoom.us/webina...
A decent employment report, with headline rate falling to 4.1%. So soft landing on... with Fed put active... all very Goldilocks.... fingers crossed CPI data remains weak.
Many thanks for the Macro Markets Summary, Paul.
As a 'slightly less than successful' investor, I find it really helpful.
Please try to make this a regular contribution, if possible.
21 billion bill coming our way .
Politics again
21 billion bill for the taxpayer to take care of the shit that companies are putting into the atmosphere .
Surely you should tax the companies contributing not tax the taxpayers .
And heres thinking we had a “black hoke” in finances .
Thats a lot of money to clear up someone elses poluution
But hey ho lets give it to the taxpayers .
Mental, it's the recycling scam all over again.
They produce it, we pay to clear it up.
The technology doesn't even work, they will be ploughing money into hydrogen next, keeping AFC Energy (LON:AFC) ITM Power (LON:ITM) and Powerhouse Energy (LON:PHE) in the lifestyle they have become accustomed to.
In the latest Serica Energy (LON:SQZ) IMC presentation, I'm sure the CEO was saying how oil companies used to buy CO2 to help force out the oil.
In the pandemic, we had all that drama about not enough CO2 for food and drink.
Surely their industrial and energy transition strategies extend beyond what the previous government had signposted?
You could equally make the argument that as shareholders we have benefitted from the profits polluting companies have made, without deducting the costs of clean up.
If I'm honest, I would be a contributor to the carbon problem. Not sure how anyone can't be. I have solar panels and a hybrid car, but I use trains, planes and other automobiles. I therefore am a consumer of all petrol chemicals and benefit from them - so this is also my problem.
Mark B,
Haha well we're all carbon based lifeforms. CO2 (0.04% of air) is the air all animals breath out and plants breath in. The plants recycle the carbon into wood, fruit, crops, and release the oxygen (20%). It's called the Carbon Cycle. Apparently our politicians are unaware of this...
From what I read, this doesn't look good. Creating expensive carbon capture processes will only do us good if we can sell the technology to India and or China and they can make it at scale for the rest of the world - so it becomes a no brainer. But, I am inclined to think that poor people will go for the cheapest energy and if it is the dirtiest, so be it - their priorities will be different as long as they are poor. We really need a great innovation that is cheap (or better, free) and works for everyone. I personally like trees.
Hi Mark B,
The global south countries are continuing to use fossil fuels, the G7 countries are deindustrializing. Note that 25% or 30% of the world's electricity still comes from coal...
The last time the Britain couldn't make steel was about 3000 years ago. Those arc furnaces are only good for recycling existing steel, not converting a rock containing iron ore to steel (making new steel).....
Economic growth requires affordable energy. Spending billions of pounds to capture carbon is going to end up in a negative NPV investment for the tax payer.
"We really need a great innovation that is cheap (or better, free) and works for everyone. I personally like trees."
Yes we need a break through in physics. The so-called renewables are just "fossil fuel extenders", they need diesel powered machinery, steel, concrete and so on in order to function (i.e. they need fossil fuels to function).
I'm heavily investing in oil, natural gas and coal. Essentially I'm doing the exact opposite of the UK government.
And nuclear of course but that also involves huge use of the above natural 'processed' resources, which we can only increasingly import and from our blessed direct neighbour.
Grandad said "follow the money" (on a windy day) - sorry Grandad I said I can't invest in the Crown Estate, just have to pay for it.
Yes constant "base load" electricity (from coal, nat gas, uranium) is key. Renewables don't produce constant base load electricity. One obvious issue around nuclear is that half of the world's enriched uranium comes from Russia. Even today the US buys enriched uranium from Russia...
"Grandad said "follow the money" (on a windy day) - sorry Grandad I said I can't invest in the Crown Estate, just have to pay for it."
Haha
Fortunately, most of our politicians - but scarily not all - believe in science and not the misdirection you employ.
The issue is not that that C02 is a tiny % of our atmosphere. The issue is that has doubled in the last 150 years and, crucially, along with methane (called natural gas to make us feel better) and other gases, it causes global warming, itself a nicer name for Climate Emergency.
(It is of course possible that 99% of scientists are wrong but like using a surgeon rather than a friend to do an operation, I think I will go with the majority and support the experts here)
The danger with Carbon Capture schemes is that it will be used by vested interests to deflect from real action and soak up some subsidies. Hydrogen is being talked up in the same way. Any role it will have is likely to be tiny in very selected uses. The political failing is not ignorance but low level corruption/cowardice in being unwilling to confront the changes we all need to be making.
The money promised by the government would be far better used in simple demand avoidance (insulation, fuel efficiency measures); better capacity management (shifting demand via price signals across the day); and building out the electrical grid for now proven at scale technologies like renewables (wind, solar & battery) whose chief barrier now is the finance upfront.
To try to steer this back to shares rather than political hot air, I therefore will simply say I think the science will out and currently unfashionable renewable shares like Renewables Infrastructure (LON:TRIG) will do well over time as will those that will indirectly benefit like Stelrad (LON:SRAD) although it may take some more freaky weather to provide the trigger!
"Fortunately, most of our politicians - but scarily not all - believe in science and not the misdirection you employ. "
What misdirection? The science you say....?
"There is “no science” that says the world should phase out fossil fuels to curb global warming to 1.5 degrees Celsius, according to Sultan Al Jaber, the president of the COP28 climate summit"
COP28 President: There Is "No Science" Behind Calls For Fossil-Fuel Phase-Out
"...as a society we have spent $5T on alternative energy and reduced the market share of fossil fuels from a high of 82% in 1982 all the way down to 81% in 2024. A $5T investment has lowered the market share of fossil fuels by 1%." - Rick Rule
Nice to have opposing opinions and it is important - cannot avoid politics when clowns are in charge of our energy security and stewardship. Net-zero may be nice but don't want to die getting there.
To build the infrastructure will need processed natural resources. Wind farm to socket outlet and all the control equipment in-between.
So need to know the companies in that space. Will check who's on the next honours list. Must find out who makes those plug in cable thingys.
Think the budget will launch the National Wealth Fund and GB Energy to entice our pension trustees and retail to invest in said infrastructure. So will likely be holding inadvertently anyway.
Net-zero may be nice but don't want to die getting there.
Trouble is many don't want their children and grand children dying from not getting there!
And somewhere in the middle is the truth. Talk of killing our grand children is very dramatic, which tugs at the emotional heart strings - yet the evidence is not so conclusive. Dying to get to net zero is the same thing in reverse. Careful study and pragmatic application based on the facts is generally key to a successful outcome. I have faith in the ability for humanity to succeed, as we've always found a way. Extreme views are very popular as they attract all of us - it's our nature - but we don't have to subscribe to them. The mundane work of sifting through all the information is tedious and therefore avoided in the main, so we rely on others to summarize. Too often those we invest our trust in to summarize, have different incentives to us and we get the wrong end of the stick. And this is why I think, somewhere in the middle is the truth.
Hi Mark B,
If it was all about our future health and well-being then the EU presumably wouldn't be placing 45% tariffs (sanctions?) on Chinese EVs for example. Instead they would be encouraging us to buy them...
100 % agree Mark, I would include myself in that same consumer camp despite similar best efforts ... a carbon footprint offset donation helps to assuage guilt, but sadly still consuming...
When I set fire to my sofa in the garden instead of taking it to the skip I think I burned 3 lifetimes of carbon footprint. I'm nice to young kittens tho so it sort of balances out :)
Rockwood
Just dipping below its NAV after being at a small premium for a while .
Have to say if there is turbulence in the markets throwing up opportunities I cant think of anyone more credible than Richard Staveley at seizing the moment .
There is possibly going to be a 5% short term drag on Rockwood as all shares are getting dragged so maybe next month will see a retreat to 235-240
Given his proven outperformance of both the market and my piss poor efforts Im going to switch 35-40% of my money invested in Rockwood and let the man with the tan crack on .
Will save a boatload of time and effort .
Of course the remainder of my holdings are primarily Rockwood companies in turnaround but im only staying with the ones I am very comfortable with.
Given my portfolio was largely restricted to IHT cover and the circumstances for that changed recently (seperate to the government possible removal) .
Anyway - think if its choppy in the next months then Stavely will be having a field day and on a 3 year timescale looks good idea .
I disagree with practically all of your political posts and think there's a better place to talk politics than the SCVR but absolutely agree on Rockwood. When you find a manager with the record and expertise of Richard, it's hard to think of good reasons not to invest while shares trade close to NAV. I think most Investors wouldnt be able to make the claim that they will outperform Rockwood themselves, especially in the current environment. Rockwood are the largest share in my portfolio too.
Good to find another person disagreeing with all my “political” posts .
Great inventions:
No. 62 - velcro
No 5 - mouse scroll wheel.
I like the weekly macro round up Paul, its a reminder like the podcast what has happened this week and points to circle back round to take a look at. We all know its a load of work for you however it’s very much appreciated.
Paul,
A day late, but regarding the Buy-back at Galliford Try Holdings (LON:GFRD) .
As soon as they announced it, complete with the usual gubbins about how it is a "return to shareholders" (Selling shareholders, those who wish to remain with the company get nothing), it got my spidey sense tingling. A quick check and low and behold the Director's LTIP pays out based on, would you believe it.......EPS!
The odds of the Director's doing something that would, purely coincidentally, improve their own chances of seeing their LTIP payout must be miniscule!
Given the history of huge, and contentious, bonus payments to Directors at GFRD, I suspect we all know who the company is run for. The fact they have just spent £10m of company/shareholder money to try and improve their own chances of hitting the LTIP speaks volumes for me. Other opinions are available, and I do not know the exact vesting conditions, my quick Google search didn't reveal them.
They are not a company I have ever looked at and I make no judgement on whether or not they are worthy of further investigation, but I felt it worth pointing out. All too often cynicism proves to be incredibly valuable and accurate in this game.
Hi Jeremy Rea,
Re GFRD buybacks - good point, well made!
Thanks, Paul.
Card Factory (LON:CARD) - Edison interview with CEO and updated fair value of 200p/share (from 180p). Obviously Edison are paid but well worth a read/watch - https://www.edisongroup.com/ed...
Hi yiannos1, just had a look back at some of your historical comments. Not always quality. Why waste space with a negative comment.
Mr Greece has restarted the yank thread - well appreciated and only for the Billions Club (the companies not me lol). Check the discussion boards, something I forget to do.
Paul
Thank you very much for your new weekly macro summary.
There is obviously a large overlap with Economics and Politics impacting the stock market.
I very much hope that you will continue to provide this Friday summary which I found very helpful.
Since I had a pleasing response to my listing of my European and Japanese holdings together with a summary of my fund objectives, and as it’s a quiet day, I’ve prepared this summary of the US portion of my fund a day early for those who feel the weekend is upon us already. I hope there’s something of use in there and, if there are any questions, do please ask.
BnB's contribution above is very useful reading for anyone holding US stocks - do go and have a read.
Zotefoams (LON:ZTF) I have taken a starter position, mainly because of reZorce I must say. The market was very excited about trials of this product but in the absence of newsflow, the stock has retraced from 580 to 413.
I have just had a closer look at the finals 2023 and interims 2024. I have to say they aren't perfect... and both cashflows show signs of stress...and quite a jump in net debt. The company is not growing particularly quickly and doesn't really explain why investment in working capital has been so high. As reZorce investment picks up this is a bit or a worry. If we shelve reZorce for some reason we aren't completely insulated here... did anyone sign in to the sharesoc post results analysis?
Working capital flows were impacted by their biggest client, Nike, at last year end. They paid soon after year end. Interims then reflected gearing up for an increased range of Nike footwear. Hence H1 was deemed relatively strong by management.
Thank you this is helpful... the relationship with Nike feels like a double edged sword, nice for growth, bad for cashflow. This isn't helped by Nike having their own issues at present.
"Said to be the cause for 5% rise (Thu alone) in spot crude oil price from recent low of $65, to c.$73 (as at Thursday evening)"
Iran has been clear that they can shut down the Persian gulf via the strait of hormuz if this war escalates sufficiently. If this occurs then >30% of the world's oil supply would go off line. We are consuming 6 barrels of oil and replenishing 1 barrel right now anyway so oil to me looks mispriced...
"... so we should be increasingly worried about geopolitical crises, including of course the continuing Russia:Ukraine war. What (if anything) should we do with our portfolios?"
The 60/40 portfolio no longer works, look at 20 to 25 year US sovereign debt (iShares 20 Year Treasury Bond ETF (NMQ:TLT) ), physical gold is replacing US Treasuries, we have been seeing countries outside of the G7 (the "Global South") selling treasuries and buying gold. Hence why gold is at all time highs measured across all currencies now.
As I've said before, the the BRICs Kazan meeting at the end of this month may be a profound event.
I currently hold 20 year US Treasury Bonds and have been considering holding physical gold. Do you have a preferred way of holding it?
Hi SC120,
Have a look at https://www.goldmoney.com and https://www.silverbullion.com, these are both excellent. With GoldMoney you get access to Brinks and Loomis vaults.
Unlike your cash in the bank above a certain threshold level, the physical metal is 100% insured. So it is safer than any UK bank account...
The lazy option is to use an ETF, however the only one I'd use would be the Sprott Physical Gold Trust (PCQ:PHYS), because after what we saw around 2020 with allocated and unallocated account issues with some of the other high profile Gold ETFs I wouldn't trust them one bit...
Thanks for the information Alphaflight. Goldmoney is listed in Canada?
"Goldmoney is listed in Canada"
You are very welcome SC120. Yes it is a publicly traded Canadian company Goldmoney (TSE:XAU)
Disappointingly AJ Bell does not offer trades in Goldmoney or Sprotts Physical Gold. I will need to research an ETF.
Hi SC120,
Regarding Goldmoney, rather than buying their stock I meant that you could become a client of Goldmoney and then buy physical gold / silver through their platform. You would then store said physical metal in a Loomis or Brinks vault (e.g. in Switzerland, Singapore etc - you can choose the vault(s) via their system). If goldmoney went bust for example, and their stock went to zero, your physical gold is still fully insured and still physically held with Brinks/Loomis in your name.
Note that an ETF is still a paper (well digital) asset whereas the physical gold is a "hard asset" i.e. outside of the finanzialised world.
Gold coins (e.g. UK Britannias) for example have no capital gains tax liabilities attached to them because they are UK legal tender (they have a face value of £100 but are worth around £2k). So if you bought a few of these coins years ago for say £800 and you sell one of them today for around £2k, you wouldn't have to pay any capital gains tax on the circa £1200 gain. See here, they also have a vault service.
For physical gold I use The Royal Mint Physical Gold ETC Securities (LON:RMAP) which claims to allow retail investors to redeem for physical bars and coins stored at The Royal Mint’s secure vault in Llantrisant, Wales. I wonder whether anybody has ever taken up that option?
DWit199,
Yes this is much better than an ETF.
The only caveat is that a lot of the gold bugs tend to argue that you shouldn't hold your gold in your own country of residence in case of government expropriation (as seen plenty of times in the past) and so on. I'd tend to agree with this. I think that Singapore and Switzerland are safer jurisdictions. For example the Swiss have various things written into law making it pretty much impossible for their government to ever steal gold from people.
SC120
Another option for the real metal that I use is Bullion Vault ( https://www.bullionvault.com/).
For an ETF I use Wisdomtree Metal Securities (LON:PHGP).
Make sure the Fund or Etf actually holds Gold and not a future or option structure. The better ones will allow you, at a cost, to realise your investment in Gold rather than cash. This obviously means they are not levered and do hold actual Gold rather than electronic or financial Gold. Holding actual Gold does mean it needs to be stored and this isn't free ... so the ETFs that match this rather than storing gold bars yourself is my preference since I figure I want a financial hedge ... not protection from a more gloomy scenario. Also be aware there is a natural currency exposure of any Gold held... so if for example Sterling is strong this will limit any gains in £ Gold.
Spot on re currency RD a prime example being UK investment trusts investing in Japan last year returning about 40% of with the nikkie did in appreciation.
I Shares Physical Gold ETF is a decent option
Ishares Physical Metals (LON:SGLN)
Great - your a high net worth individual and can hold gold bars or better silver bars in some vault good for you. There is a cost and it does not pay interest so purely an inflation hedge. Rainy day asset, but how collect, carry and transmute into cash - is that liquidity I hear.
ETF can trade, CFD's can trade, individual miners can trade, royalty cos can trade Royal Gold (NSQ:RGLD) Wheaton Precious Metals (LON:WPM) not a sad choice. Newmont (NYQ:NEM) and Barrick Gold (NYQ:GOLD) are candidates.
In the UK we have (loud trumpet sound) The Royal Mint Physical Gold ETC Securities (LON:RMAP) - but they are focused on some woke type coin issues.
Prefer the John Wick version and buy the small denomination and bury it under the garage concrete for the 'rainy day'.
"There is a cost and it does not pay interest so purely an inflation hedge. Rainy day asset, but how collect, carry and transmute into cash - is that liquidity I hear. "
I started buying gold when it was around £400/ troy ounce so I have no complaints. If you hold it in a vault with goldmoney or silverbullion you can sell it back to them at close to spot and convert to fiat (USD / GBP/ SGD /EUR).
"ETF can trade, CFD's can trade, individual miners can trade, royalty cos can trade Royal Gold (NSQ:RGLD) Wheaton Precious Metals (LON:WPM) not a sad choice. Newmont (NYQ:NEM) and Barrick Gold (NYQ:GOLD) are candidates. "
All of these are excellent choices. I own hold all of them.
"Prefer the John Wick version and buy the small denomination and bury it under the garage concrete for the 'rainy day'."
Yes there is logic behind that as long as you don't lose them in a boating accident:-)
Hi net worth individual ! this is news to me Harry if you could point me in the direction of my alleged millions you can have half.
Your wife may have suggestions :)
Any and all information gratefully received. Would like to see the macro summary continue.
Funding Circle Holdings (LON:FCH)
Oliver White CFO of FCH sells 129,870 shares at £1.35. Looks like he bought the exact same amount in Sept 2022 at 39p. Is this an example of someone realising a gain now to face current taxation, rather than risking a sale post Budget?
Hi, Slightly off topic but I am getting close ( a few months) to wanting to access my SIPP and I was just wondering if , among the mass of knowledgeable subscribers, anyone can recommend a reasonably detailed book (or similar) to run through the do’s and do not’s etc. Thanks in advance.
If you're looking to take out 25% tax free cash be prepared for it to take a while as they will often ask for IFA advice to be taken. I did not do so but that slowed the process. Hope that makes sense.
i think a good starting point is reading all the articles watch some you tube vidoes that you can find - make some notes. at first its the stuff to "avoid doing" that probably really matters - then you can tactically plan once you understand the complicated options. Until you do soem research its lilely that if you ever speak to anyone you would probably get overwhelemed by the complexity - note the powers that be do a free chat with someone - so might be rworth doing that
then plan before you do anything as anything you do has consequnces
main practical questions are
do i want to continue to add to pension and how much - whne you strat drawing your options to add aagin may be severley restricted - but ther may be scope to partly recycle fund back ijn under limited circusmntances.
also be careful about your tax free amount - at present this will continue to grow - by starting withdrawal process you may do something that stops future tax fre growth so thats one to understand consequences. there may be competing things here if you have allowances you want to use up.
in summary be careful before you do anything and you cant do enough background reading so that you understand as many of the pitfalls as you can - there are plenty of them too
If anyone has linked to good articles or videos please post - i think a reading variety of sources means you are less likely to miss out on something useful.
is there a book there probably should be its that complicated - how to pimp out your pension for dummies .
I think if you're not familiar with the dos and dont’s, the legislative issues, tax implications etc, I would pay for a couple of hours with a suitably qualified IFA to set these out in writing for you, not just to educate but also so you have recourse if something goes awry. I think in the end, its a lot cheaper and much less time consuming to pay for expert advice, rather than go it alone for the sole purpose of avoiding a fee.
Hi jimbob2,
Get a free appointment with Pension Wise. They'll go through all the options.
"Pension Wise is a service from MoneyHelper, backed by government. We offer free, impartial guidance to over 50s. We’ll explain the options to take money from your defined contribution pension pots."
https://www.moneyhelper.org.uk...
For structures that are meant to keep you alive, pensions are potentially lethal if you take a DIY approach to accessing the funds. So many pitfalls and one-way streets. You make a mistake, there is no reverse gear, and a simple misunderstanding can prove hugely expensive.
This is a useful concise summary of most, but not all, of things you need to worry about:
https://www.londonwallpartners...
My intention in posting that link is not to promote the firm concerned (I don't work there), more to persuade you to take great care.
Many thanks All, much for me to consider !
May I have a refund on my subscription when Mr Contrarian doesn't post? :-)
I want a refund when he posts profit warnings!
Quality of this thread has deteriorated dramatically.
Over half of the comments are thanking Paul about his comments on his podcasts on politics and the rest do not want to read anything related to politics.
Yiannos
Brutal but true .
It is brutal and probably unfair, I think the level of the thread is reflective of the overall general interest in small caps at the moment, especially a Friday plus we seem to be in a holding pattern around the budget and it’s ramifications for small cap holders. Warren Buffett seems to be a successful investor and a pleasant person, the two are compatible.
Politics influences the markets. Hence its relevance.
There's no company news today, apart from JDW.
If you don't like the comments, maybe don't add to the irrelevance with a complaint about comments being irrelevant? Everyone pays the same subscription fees, so they have a right to post.
My "politics" points are actually all very relevant and specific to markets. That's why I mentioned them.
Yes correct everyone has the right to post.
I am talking about the quality of the thread so I thought if I added to the irrelevance maybe something will change.
All the best
Yes correct everyone has the right to post.
I am talking about the quality of the thread so I thought if I added to the irrelevance maybe something will change.
All the best
So irrelevant you posted it twice Yiannos! :-)
Since the UK voted for Brexit we have become world leaders in developing our irrelevance capability...
it's almost as if people are just typing a comment rather than thinking of the value it adds.... eh!
It takes me seconds to decide if I want to fully read a post or not. I read some macro posts and skip others, in exactly the same way I read or skip individual company posts. I think you are overreacting a little, with respect.
I am what might be referred to as a "lurker" as opposed to being a contributor! I read the site daily. Politics is integral to all our investment decisions and how we manage them in various ways such as SIPPS; ISAS; etc. The oil and gas sectors is one such example. Yesterday there was considerable debate on WYN.No one mentioned the comments made 6 months ago on why trading was down. What was said is that trading was down as many of our arable land was being re- allocated to have solar farms n them instead of crops. The Fens were a particular example and on a recent trip I saw examples of this transition. That makes WYN uninvestable for me. It has a diminishing market. I love the debate on this site, which is constructive and friendly. Long may it continue despite different political viewpoints.
I agree with you re Wynnstay (LON:WYN) . I've tried to keep quiet as I have no holding in the company but I do have quite a bit of knowledge of the sector, having close family farming and providing services to farmers.
The Sustainable Farming Incentive (SFI) scheme is another reason why I believe that Wynnstay may struggle to reach previous profit levels in future. Almost all of the different grants and incentives under this scheme will lead to reduced use of fertiliser and/or livestock feed. As you rightly say, land is also being used for other purposes, thousands of acres being planted with trees or covered with houses. This land is the almost impossible to ever return to agriculture, at least solar panels do often allow grazing beneath them and can be removed relatively easily in the future.
For these reasons, although I see Wynnstay as a well run company in the sector, it could well be a value trap in the long-term.
hi derek, welcome u lurker ! i'm invested in Wynnstay (LON:WYN) , but certainly don't see solar as a competitor for farmland.. i'm adding a link posted on a 'solar' message board conversation..
https://www.carbonbrief.org/fa...
obviously it's messaging from a green site but does use a lot of facts to back up it's case.
most farmers are using solar as a value add for a business that struggles to make profit or land they can't farm.
As for Wynnstay (LON:WYN) i was tempted to sell out at the profit warning (come in 3's :o ) but looking at the resilience of the price action , especially with so many others being punished for just an inline update, i've decided to hold and will average down when the dust settles.
i don't have a crystal ball but think the worst is now priced in. just waiting for a return to form, with divi's along the way...
Each to their own Yiannos but couldnt disagree more. The comments are hugely useful and as Paul says on the podcasts they can be as useful as the reports themselves. Unfortunately due to work commitments I don't read until 9pm++ and by then see little point in posting. There are a huge number of factors which affect markets. Where I don’t think they are relevant I just flick past them. Maybe I miss key points maybe I dont.
As for thanking Paul that is again up to the writer. I dont agree with everything he says but the work he puts in is unbelievable. As well as this the weekly podcasts, interviews, extra videos, hardly any holidays. So if people wants to express this good luck to them.
We will only appreciate Paul when he has had enough and packs it in. I hope thats not until the 2040’s so in the meantime just appreciate.
Paul - thanks! And likeswise to Graham (and Roland) too. What we get for the subscription is unbelievable value.
Thumbs up for the written market summery Paul much appreciated
Videndum (LON:VID) I notice a tick up in the price today, it looks like Wellcome Trust have taken advantage of the recent weakness and built up a 6.07% stake, they’re no mugs, possibly a good sign at these levels. No posn in the stock myself just one I’ve followed in the past and know it has a following here.
Love the macro / market summary section Paul. Thanks
For Uranium watchers, Yellow Cake (LON:YCA) and Geiger Counter (LON:GCL) ( I own both) in the UK, some decent podcasts of late; Marco voices with with Mike Alkin, Going Nuclear update "sentiment reversal" and finally Odd Lots with Jigar Shah... the stocks have been given a lift by this change in sentiment. The spot price is off the bottom but not really moved yet.... +4% to 82. The mircosoft deal has really got everyone excited. The odd lots pod hints at more moves like this likely to follow. All interesting stuff and the stocks remain below previous highs with an outlook that appears to be strengthening .. prospects for Q4 look good IMO.
The US and Canadian uranium stocks have shot up recently, lets hope the UK ones follow suit. I hold both of those.
Ramsdens Holdings (LON:RFX)
The gold price continues to head north, now around £2025 an ounce while the share price heads in the other direction? Admittedly it is one of four revenue streams for the company, but I expect another earnings upgrade should gold stabilise at the current level or continue to appreciate.
On a more tenuous note falling interest rates, if Andrew Bailey adheres to his recent narrative, should be positive for foreign holidays, hence FX, and jewellery sales.
Needless to say I hold and have recently added, notwithstanding the endless speculation by the Statler and Waldorf's of the investment world regarding AIM and IHT. Share prices eventually follow earnings.
Apologies to Peter T for plagiarism regarding the Muppets but I couldn't resist.
Accept the £ fell due to interest cut speculation, not so good for foreign holidays.
Hi Rusty, the two sides of the same coin I would suggest. Lower interest rates mean lower mortgages, HP etc and more disposable income.
Also despite the recent fall in the £ it remains historically strong against the other main currencies, given that interest cuts in the the EU and America are it appears fairly imminent.
Ramsdens Holdings (LON:RFX) agree this looks positive on most measures, although not sure how exposed they are to the rise in the minimum wage? I'd imagine salaries make up a decent chunk of their costs.
I'm new to smallcapland & screening in general (having previously just gone on gut instinct; amazon/apple/bitcoin/nvidia have done ok-ish so far!)
I am curious if anyone can point me to some good analytic tools...Other than Stocko which is obvs great. I follow the wiggly lines on the small cap charts but fear they are at best incomplete , at worst misleading.
Paul mentioned this the other day on the Vox video with Other-Paul ; "Wynnstay share price doesn't take into account regular 6% dividends over time- that would make a good chart".. .
So the question is; can I get a chart for 5 years with share price +dividends +buybacks - dilution - inflation. Or is that too obvious? Or am I being stupid. That is also very possible.
One last thing... is there a ratio for turnover growth vs net profit margin growth? (vanity vs sanity etc)
Questions questions. Thanks for any help.
"So the question is; can I get a chart for 5 years with share price +dividends +buybacks - dilution - inflation. Or is that too obvious? Or am I being stupid. That is also very possible."
certainly not on stocky and it really is a big miss bearing in mind how important divis are to the overall returns calcs when they are material amounts - hey ho perhaps one day
A Stocko employee on a conference stand verbally indicated that they were working on "total return" (i.e. incorporating dividends into performance & charts) well over 5 years ago.
Since then nothing, other than lots of very dodgy "if we add dividends" when talking about the performance of stock rankings, and lots of inappropriate usage of the word "performance" in articles that would get any FCA regulated entity in very deep trouble.
It is a little embarrassing. No long term chart is worth anything without the compounding of divis and special divis, and income is the majority of the return on UK indices in recent decades. Awkward.
You will also discover that Stocko does not make total return indices available in the Folios section either - you only get the capital return indices. On querying this (after wasting several days loading in my full transaction/divi history for one account) I was told it was a "commercial decision" - i.e. they probably didn't want to pay Refinitiv (who in turn probably don't want to pay the admittedly extortionate amounts FTSE Russell tries to charge for index data)
However - I should add that doing total return isn't easy - it is not a simple on/off switch. Not only do you need very accurate divi and corporate action data - there are nuances like on what date you reinvest dividends, what you do about £ stocks declaring US$ divis & FX rates, whether you reinvest into the security itself or build up cash, what rate of interest applies, compounding methodology etc. If you have the luxury of access to a Bloomberg terminal take a look at the "TRA" functionality to get some insight into the complexity.
My personal conclusion is that Stocko have decided the project is too expensive/difficult. Which is a pity because it is possible in a retail facing product - we know this because Sharesight have actually done it (at the portfolio level, at least). I think Sharepad also has some total return functionality - the total return indices are there.
Thanks Monty Carlo. A really enlightening post.
As a newbie here it seems extraordinary that the focus is on notional returns not real total returns with compounding effects over time. (Will check out sharepad-sight. thanks!)
Agreed - I think it was expensive/too difficult - but now It also feels like it's a dream difficult question that AI could answer before the kettle finishes boiling.
It seems odd to compare PE / EPS / yields etc etc when shurely the only number that matters is sector comparative total return? Or am I missing something?
Will investigate and report back. Winding up the ChatGPT machine and putting the kettle on now...
Hi Fire Juggler,
Perhaps have a look at Sharepad - it complements Stocko really well and may offer up much of what you are hoping for.
Best
Richard
maybe consider another app, I use Dividend Watch for tracking divs, provides both capital growth and dividend growth. Horses for courses
I recently observed while shopping in Marks and Spencer (LON:MKS)
in Torquay 2 teenage lads buying jumpers in the menswear dept.A very rare sight.It made me realise that Marks is spending part of its Budget on attracting the younger shopper and it might be paying off.
Marks food offering is better than ever and the SP is going in the right direction after years in the doldrums.I do not hold but am very tempted despite all the fears for retail.
Tongue in cheek portugull, they might be buying for granddads?
In my experience Granddad\s size will have sold out, and the ultra slim sizes they won't be buying for themselves will be filling the shelves
MKS Back in the 80's I received some M&S vouchers as a pressie. I went into M&S and I think there was another guy in there doing likewise. I came to the conclusion that the only time men went in there was to use the vouchers. I don't think I was their target demographic though.
Now I like M&S clothing. Must be some kind of gene that switches on when you reach middle age. Admittedly, I haven't shopped at M&S for a number of years, but I think I would if there was one closer.
It would be a sad day if M&S were to disappear.
I live in the back of beyond. All the men's shops have closed down within a 25 mile radius. Maybe except one shop, which I refuse to go to because their prices are high and their quality is low.
Do men buy clothes? It's difficult to tell. We just get given clothes by our nans in our early 20's and use them until retirement. Or else our purchases get lost in the mists of time and it just looks like gnomes refresh our wardrobes on an as-needed basis.
Hi Portugull
Marks and Spencer (LON:MKS) - I highlighted a few months back that when in a queue to get on a plane a group of teenage girls behind me were commenting on one of the girls outfit and she said guess where it’s from…….etc. and then they were discussing that Marks does some good clothing ranges etc.
Whilst that is far from any sort of representative survey it did prick my ears up. If late teenagers are talking about shopping in M&S then it makes me think the clothing strategy is starting to work. We already know the Food strategy is working. Combine those with the new store layouts (30% less space and 30% increased sales) and I can see why management are bullish in their calls.
I was late to the party and had to be patient but picked up my stake around 240p and still see plenty of opportunity left. Let’s hope we see these random reference points show up in the trading.
really interesting observation, maybe they also looking to differentiate from primark offerings. I have regularly upped my holding, the food offering is world class
Lots of young men and women are talking about Marks and Spencer (LON:MKS) clothing. Women’s jumpsuit seem particularly popular. Tom Kerridge food range also sounds exciting.
They are doing concessions, think I saw Jaeger, Under Armour, etc and their own good brand Autograph. Debenhams used to do the same, the concession basically 'rents' the space or a % of profit made in store. And gains access to M&S finance, loyalty card and pay in 3. The larger stores are warehouses so full utilisation.
Also note instead of putting out of season leftovers on sale, has a rack of 'last look' and at full price lol. Then go off to the Outlet stores.
Nice big store at London Stratford Westfield - space and not a rugby scrum like say Primark.
Long may they be on the better High Street.
I think the macro discussion is so predominant and can be very political it might just take over the single discussion we have on the SCVR - I know it's quiet today for company reporting so doesn't matter but usually I think it would be better on a separate main post so people could get their thoughts across without filling the small cap feed.
Second this, please let us keep the politics off the SCVR, it rarely adds anything but heat and noise.
Obviously paul can say what he wants on his podcast, because that is his personal work. For the avoidance of doubt, I do like the podcast, politics and opinion included, just don't think it is useful here.
David
I respectfully disagree. Politics is having a disproportionate impact on investing whether it is O&G, U, commodities or UK small cap land. It is certainly something I am taking into account and I thought Paul's commentary an excellent summary of the political unknowns and knowns that are impacting all our portfolios. Where it tends to go wrong is when folks start sharing their personal political views .... that is a different matter, and I agree: of little interest to anyone. I am fairly sure that no one, part from my collies, have the slightest interest in my personal political views.
And here I am thinking that a wholly separate political-themed Post was raised a couple of weeks ago so where have you been chaps?
I enjoy your podcasts especially the macro introductions, my only worry about putting them in here is that they may get dropped from the podcasts and it may start political discussions.
Hi Paul,
Re PE bids, mgt self interest is a good point and makes me think of a couple of recent/ongoing PE bids that seem poor value considering growth rates. PE tend to give the top exec’s an equity incentive well in excess of those seen in UK listed LTIPs. For example a ‘sweet’ equity pot between 5-15% of the ords is not unusual. Of course the exercise price is effectively the take out EV, and there’s usually plenty of debt in the purchase consideration so it’s highly geared upside.
Like the macro comments Paul - thumbs up from me!
Ps. If you wanted to record them first and then get AI to transcribe it for us readers then it might save you time? Copilot is incredibly accurate at transcribing now unlike most of the traditional speech to text applications (for me anyway!)
J D Wetherspoon (LON:JDW) - Tim Martin's Chairman's statement is always a very informative read, in my view. You might not agree with everything he says, but you always learn something new, unlike most Chair statements!
J D Wetherspoon (LON:JDW) For eaxmple - the changing face of pubs with Pepsi the top leading draught seller at Spoons, while coffee and tea is sold in double the volume of Pepsi.
J D Wetherspoon (LON:JDW)
Unlike the Gov Sir Tim happy to look after our pensioners on a cold winters day when its likely to be far cheaper to pop in and spend 4 hours drinking coffee and having full on breaky than heating ones home for the morning.
Hi rmillaree - Your slant/twist on Sir Tims Spoonerisms fits a quiet Friday morning perfectly
Absolutely. He continues to make a good case that the on-trade is over-regulated vs the off trade. Some very interesting stats including that the tax burden per pub is now £1m p.a.. Enough to make you choke on your pint.
The current US Treasury yield curve :
6m 4.37
2Y 3.7
10Y 3.82
30Y 4.15
As you can see, from the small 2 year 6 month inversion the markets think that short rates are little high. The much watched inversion of 2 year to 10 and 30 has unwound. This reflects the Fed policy shift. Looking forward how this shape evolves as we pass through unemployment and inflation data has implications for the cycle. We are currently enjoying a period of falling inflation but rising unemployment. This is "normally" a recession, but it could be mild, the soft landing. We can watch how this shape reacts to the data each month. At the moment we have broadly neutral picture with inflation at about 2.5% and unemployment at 4.2%.
The theory would be the that if the markets believe the Fed is supporting employment through policy at the expense of longer term inflation expectations then the long end yields should rise. If we cut another 50bp it will be interesting to see how the curve reacts... at the moment the curve believes the Fed has room. We are in a goldilocks period.
It's not just about the Fed though. HK up another 2% over night and at some point "sugar rush" high concerns will emerge... maybe Q1 25. Today is non farm day... Id be surprised if the data changes the picture much... but Ill be mainly watching the long end over the next month or two.
By comparison UK 30 year rates are already 4.6% and may explain the slightly more cautious BOE before yesterday's comments from Andrew Bailey. The currency markets reacted as you would expect and the £ fell.
J D Wetherspoon (LON:JDW)
Is he serious?
Commenting on the results, Tim Martin, the Chairman of J D Wetherspoon plc, said:
"The company continues to be concerned about the possibility of further lockdowns and about the efficacy of the government enquiry into the pandemic, which will not be concluded for several years.
I thought exactly the same, he sounds utterly deranged...
If he had said the opposite he would be condemned for being blase. Aren't we all concerned about such matters, however far in the future they may be?
Anyway this is not the place for such a discussion (unless said by Paul!).
Points agreed.
I think his point that the extended period of lockdowns was clearly detrimental to many aspects of uk life is pretty serioud and valid point. I was all for lockdowns at start of pandemic but by time we got into second and third wave i think the case for continued lockdowns at level they had was weak at best and probably a shockingly poor decision with the benefit of hindsight - efforts should probably have been more spent on protecting the vulnerable. anyway he has is free speech and is using it. And its valid point that the enquiry will costa fortune to say nothing other than the standard who lagline that the who was super brilliant.
The whole 'pandemic' fraud is easily exposed with a bit of research. Which means the lockdowns and all the associated horrors of that time are crimes against humanity. Until those responsible are brought to justice there is every possibility this could happen again which Martin is right to be concerned about.