Small Cap Value Report (Fri 5 Apr 2019) - TET, MOTR, CREO, TCN, LWB

Good morning, it's Paul here.
My plan today is to set aside some time to catch up on a few things that I missed earlier in the week. In addition to reporting on today's news too, of course.
Move to subscriber-only editorial
Most readers here are subscribers. We got one or two negative, and inaccurate reader comments yesterday, complaining about the move to put all editorial here behind the pay wall, w.e.f. next Saturday.
To prevent any more misunderstandings, Ed explains here why this decision has been taken. It's worth a read, as he also updates us on other improvements to Stockopedia.
A couple of small acquisitions are announced;
Begbies Traynor (LON:BEG) is acquiring a profitable, small firm of chartered surveyors. The deal looks sensibly structured, with a 3-year earn-out on stretch targets. I like BEG's strategy of developing its property services division. This generates some growth, which is lacking in its core insolvency division.
Scientific Digital Imaging (LON:SDI) is acquiring a small but profitable, complementary business here. Again, not material.
Treatt (LON:TET)
Share price: 392.5p (up 1%, pre-market open)
No. shares: 58.8m
Market cap: £230.8m
Treatt, the manufacturer and supplier of innovative ingredient solutions for the flavour, fragrance, beverage and consumer product industries today publishes a trading update for the half year ended 31 March 2019 (the "Period").
Nothing madly exciting here, it's an in line update (right at the end, in the outlook section);
... the Board, therefore, continues to believe that profit before tax and exceptional items will be in line with its expectations for the financial year ending 30 September 2019.
Other points sound reassuring overall;
- H1 revenues up 7%
- Encouraging opportunity pipeline
- New $14m US facility, completed in Mar 2019, will be fully operational by June 2019
- UK relocation, costing £35m, due to start summer 2019, occupancy due to begin in summer 2020
- Forex hit of £0.6m - doesn't really matter, as it's swings & roundabouts
My opinion - there could be a good opportunity here. It's not cheap, on about 20 times forecast earnings, but that doesn't include upside from the major new production facilities it is creating.
The new facilities could increase margins (from more efficient manufacturing), and also increase capacity (hence revenues & profits, if there is currently unmet demand). I think these are the key issues to focus on, when researching this company further.
Lord Lee was (and I presume still is), very keen on this company, rating it & management highly. Long-term I think it looks a potential winner, if the new facilities work out well.
EDIT: I've just confirmed with Lord Lee that, yes he is still very keen on Treatt, and it remains his largest personal shareholding. End of EDIT.
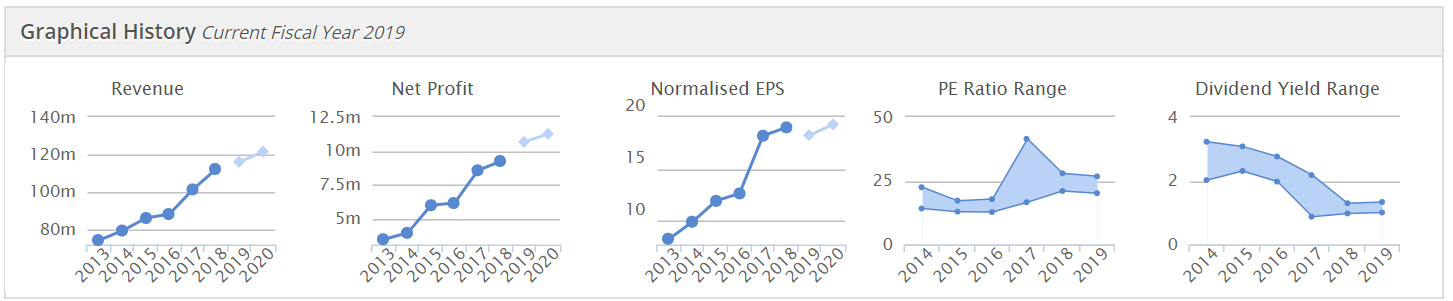
The progression of profits & EPS looks excellent. Heavy capex now & into 2020, should hopefully deliver considerably higher profits in future. It would be worth getting hold of some broker research on the expansion underway;
Motorpoint (LON:MOTR)
Share price: 190p (pre-market open)
No. shares: 96.1m
Market cap: £182.6m
Motorpoint Group PLC, the UK's largest independent vehicle retailer, is pleased to announce the following trading update ahead of its preliminary results for the year ended 31 March 2019 ("FY19").
Business model - I like the business model of car supermarkets - large sites, selling secondhand cars only, at competitive prices. The StockReport shows that it generates c.£1bn in revenues, on just £8m of fixed assets. That's disruptive towards conventional car dealers, with higher fixed costs. Also, it's a simple model to roll out. So a thumbs up from me, for the basic concept. The main downside is probably that there are few barriers to entry for competitors.
The StockRank is fairly healthy too, so no alarm bells here;
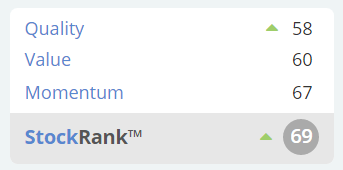
I hardly ever mention the 4 indicators on the StockReport, but after prompting from Graham, think I'll refer to these items more often in future;

3 of these 4 indicators look fine, but the Beneish M-Score is flagging a "High" risk of earnings manipulation. More details are here. I've never really looked into the M-score, but will check it out properly when time permits. Stockopedia obviously thinks it's important, or it wouldn't be on the StockReports.
Trading update - this sounds a little soft to me, but not a disaster by any means;
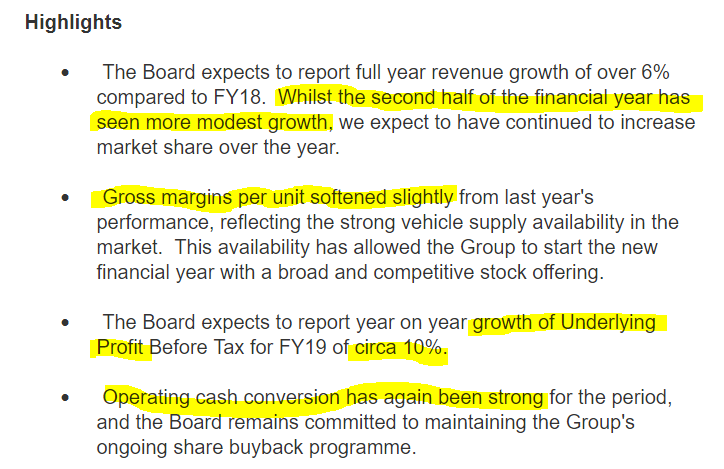
It depends what the market was expecting. Stockopedia shows broker consensus forecast for FY 03/2019 net profit (which is after tax) up nearly 19% (£19m vs £16m).
Looking on Research Tree, a broker note from Nov 2017 is the most recent currently (although I expect there will be new note there later today) suggests that underlying profit before tax was forecast to grow nearly 16%. Therefore today's announcement looks like a profits miss - achieving +10% growth in aPBT, below the +16% forecast growth in aPBT.
Cash conversion - is always likely to be strong, as secondhand cars are sold for cash or external finance. So I would expect the cash to come in instantly, before cars are released to the buyers.
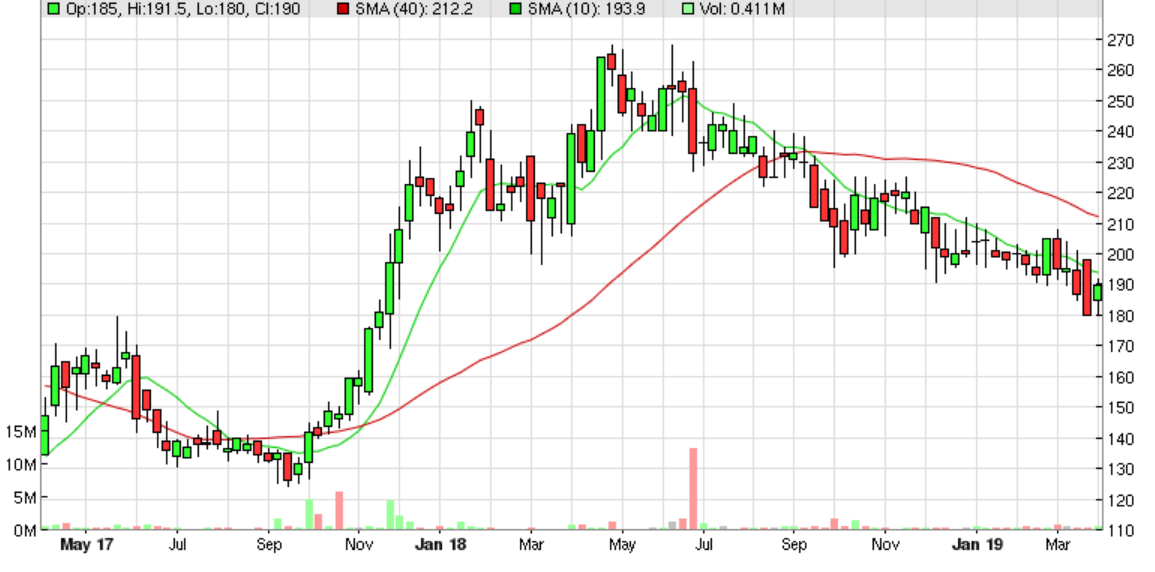
Valuation - was already modest, as the share price has been drifting down over the last year. However, that doesn't seem to matter at the moment. In this bearish-feeling small caps market, disappointments seem to often be punished quite hard.
Outlook comments are cautious.
I'm not sure what this means - could do with some clarification on this;
... In spite of this the Board expects to make further progress in revenue and underlying profit, but notes that there will be a c£2m (non-cash) profit headwind in FY20 compared to FY19 from historic deferred extended guarantee income.
My opinion - if the share price is really slammed hard today, that might present a buying opportunity. This strikes me as a sound business, with a decent business model, modestly priced.
Divis are pretty good too, at over 4%, and growth should come from rolling out more sites. It is planning on opening one new site, which will take the total to 13. There must be scope for many more in the UK.
Creo Medical (LON:CREO)
Share price: 192p (down 3% today, at 11:42)
No. shares: 121.5m
Market cap: £233.3m
Creo Medical Group plc (AIM: CREO), a medical device company focused on the emerging field of surgical endoscopy, announces its audited results for the 18 months ended 31 December 2018, in line with management expectations.
This is just a quick section, to get something into the archive here for future reference. This is not the type of share I would normally report on.
Revenues - nil - I don't usually invest in any pre-revenues companies, because very few of them deliver on the business plan sold to investors
Losses & cash burn - this seems very well-funded after a big fundraising;
· Cash and cash equivalents of £44.6m at 31 December 2018 (30 June 2017: £13.7m)
· Operating loss of £17.7m (12 months to 30 June 2017: £8.9m) including £1.8m share based payments, in line with management expectations
· Underlying operating loss of £12.6m (12 months to 30 June 2017: £5.6m)
The previous 18 months reflect a period of considerable progress in the development and path to commercial launch for the Company's CROMA Advanced Energy platform and Speedboat device for use in Gastrointestinal ("GI") therapeutic endoscopy, the first in a suite of products being developed for the CROMA platform.
My opinion - the £233m market cap suggests that some investors think this is going to be the next big thing. I've no way of knowing whether this is likely to work or not, so it's not for me.
Tricorn (LON:TCN)
Share price: 19p (up 19% today, at 12:54 today)
No. shares: 33.8m
Market cap: £6.4m
Tricorn Group plc (AIM: TCN.L), the AIM listed tube manipulation specialist, provides the following pre-close trading update for the financial year ended 31 March 2019 (the "Year").
I wouldn't normally mention something this small. However, a couple of readers have expressed interest, and it's up 19% in price, so there must be something potentially interesting going on.
Revenue up 2.5% on prior year. LY was £22.18m, so that's £22.73m for FY 03/2019
Adjusted PBT for the Group is expected to be around 30 per cent. up on the previous year. This looks good. The FY 03/2018 results report underlying profit before tax at £0.83m. Assuming that adjusted, and underlying, mean the same thing, then a 30% uplift gives us c.£1.08m adj profit for FY 03/2019. It did £553k of that in H1, so H2 is about the same. Therefore this looks to be a continuation of the improved H1 performance, rather than a further improvement.
That's consistent with the outlook comments at the interim stage, which said;
Over the past two years, we have seen significant growth in our end markets. However, towards the end of the period, we witnessed signs of this growth slowing. Against this background, and after considering the impact of new business wins, the Board anticipates Group revenues in the second half to be similar to the first and full year underlying profit before tax to be in line with market expectations."
[taken from RNS dated 5 Dec 2018]
Broker update - there's a one-pager out this morning, available on Research Tree. It confirms that results are as expected, so no changes to forecasts.
Balance sheet - had £3.3m net debt as last reported at 30 Sept 2018. This is funding the gap between inventories+ receivables, less trade creditors. It's not unusual to use bank debt to part-fund working capital, but it's better to be debt-free.
The 2018 Annual Report shows £1.34m of land & buildings within fixed assets, at cost. It would be interesting to find out if this is valuable property, worth more than book value, or not.
My opinion - it's difficult to get excited about this - a small engineering group, with a bit too much debt, is not going to attract a high rating. Once you get below £10m market cap, you have to be very careful about de-listing risk. That can hit the share price by 50% instantly, if the company announces it's going private. Do the listing costs make sense for a group with a market cap of only £6m? Is there any liquidity in the shares (probably not much)?
On the upside, it is generating solid profits now, which over time should help reduce debts. I see that divis are re-starting too, after a 5-year absence. If revenues can grow further, then operational gearing could improve profits further, on a geared basis.
It doesn't really float my boat, but it's almost certainly one of the better companies at a sub £10m market cap.
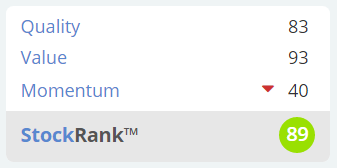
Stockopedia's computers really like it;
This section is from Monday's report, which I have now finished. Here is a copy of the new section;
Low & Bonar (LON:LWB)
Share price: 13.6p (down 20% on the day, at market close)
No. shares: 689.8m
Market cap: £93.8m
Trading update (profit warning)
Low & Bonar PLC ("the Group"), the international performance materials group, today issues a trading update for the period since 30 November 2018.
[note that the group's financial year end is 30 Nov, so this is an update for the first few months of FY 11/2019 - Paul]
Hmmm, this looks like a complicated situation;
As set out in January in the Group's 2018 financial results announcement, 2019 is expected to be a year of transition as the Group simplifies its portfolio and structure and works on resolving legacy issues to improve operational performance, following the successful equity fundraising that was completed in February.
Disposals - are in progress;
planned divestment of the Civil Engineering ("CE") division is proceeding well, with sale processes for the two businesses in this division, Construction Fibres and Needle-Punched Non-Wovens, progressing positively. Both of these processes are expected to conclude during the current financial year, and the division has continued to trade in line with expectations.
>span class="al">During the quarter, the Group completed the exit from the Bonar Natpet joint venture in Saudi Arabia.
Continuing operations - are not trading well;
As a result of reduced volumes, Group revenues in the first quarter were below prior year levels and management's expectations. A temporary increase in inventory as a result of the lower sales will be addressed during the year as part of a continued focus on working capital.
Overall, despite some benefit from lower raw material costs, the weaker revenues and some manufacturing inefficiencies contributed to lower than expected profitability in the quarter, which the Board expects will have an impact on full year performance.
Outlook - improving trends are hoped for, later in 2019. Uncertainties are mentioned.
Fundraising - the group recently decided to strengthen its balance sheet, with a £50m (after costs) equity raise at 15p per share. That was definitely necessary, I've been saying for years that the balance sheet here has too much bank debt. This raise doesn't resolve the issues fully, but certainly helps.
Results - for FY 11/2018 are not good. In summary;
- Underlying operating profit fell 45% to £16.7m.
- Net debt of £128.5m was way too high (albeit since reduced by £50m)
- £58.9m of exceptionals, mainly writing off goodwill - value destruction from previous acquisitions, in other words, belatedly recognised
My opinion - it's all down to whether management can turn around the business successfully. It looks quite a large, and complex group, with all sorts of problems. I prefer to invest in smaller, more simple businesses, where everything is running smoothly.
It's almost impossible for private investors to assess what the prospects are for this group. So how can we value the shares? It's too much of a leap into the unknown for me, even though it looks a lot of business for under £100m market cap.
It's not clear to me what competitive edge this business has (if any), and whether competitors might be squeezing it? Altogether, this is just outside my ability to assess whether or not the shares might be a good investment or not. Hence I'll steer clear.
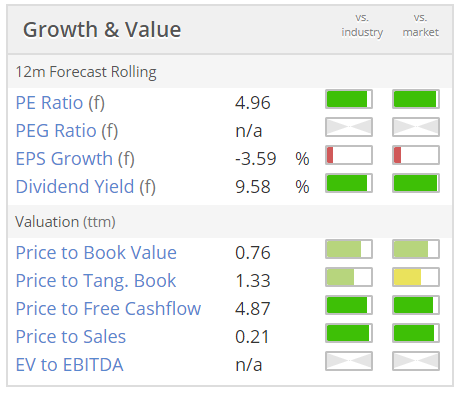
When the forward PER, and dividend yield are this cheap, it nearly always means that there's something wrong (i.e. the numbers are not likely to be achieved);
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
Good to hear Lord Lee is well and active. The WB of the UK.
One other point about Tricorn (LON:TCN) - the major shareholder is a 72-year-old NED with 33% of shares. He's surely going to want an exit soon. So I think there is a bigger chance of a decent sale here rather than a de-listing.
Paul - Thanks & Goodbye
So there is no free lunch and with other non-subscribing 'lurkers' my daily 5 minutes free scan of amusing analysis and comments is over.
You guys did get up and write the stuff and Somero (SOM) was added to my watch list so thank you for your efforts and may you grow rich and enjoy spending it.
Back in the day the Motley Fool was a great site to 'lurk' and Stephen Bland (PYAD) was a big influence (though I never had a farm to bet) and in the FT John Lord Lee wrote more sense than most. Also read Nassim Taleb (Fooled and Black Swan) also Peter Bernstein 'Against the Gods' - the story of risk
Read and inwardly digest investing of yesterday (Wiley Investment Classics) in particular 'Where are the Customers’ Yachts?' and 'Reminiscences of a Stock Operator'
I have always lost my own money by which I mean I never paid someone else to lose it for me. - never found a share analysis site that could show me their customers’ Yachts – though I think the site owner may have had ‘ a good living’
Lastly before you buy or sell a share get a line chart showing at least 5 years history (more years better) overlay two SMA's 200 day and 500 day then look at the right hand side (latest price) - stand back and think about the 'story' in front of you. As the Merchant of the City of London once told me "buy cheap and sell dear"
Bye PFJ
If I may join in on the ASOS (LON:ASC) returns topic.
I've pointed out to many friends/family that if they didn't over-order, then the prices could come down - simple economics (obviously, the companies may not reduce prices, and just make more profit ! lol)
I do deal with Amazon quite a lot, and a while ago they bought in a 'seller-tool' being a 'auto no-return refund'. Basically, by a seller agreeing to this, if a buyer wanted a return/refund, then they'd automatically be refunded without having to return the item ! I can imagine once scam-buyers had worked out who had this facility in place, they would have quickly shared the seller's details with all their other scamming associates !
Sellers are now sharing many more details about scammers and their tricks, trying to keep one step ahead. i.e. finding buyers on Facebook who've posted images of their items (clothing, laptops (>£1,000 !), etc.) and trying to get a refund for non-delivery. Apparently, couriers now take images/videos of items being delivered.
With regards to the sizing, there was a website I recently found, that would allow a buyer to input their measurements, and it would then advise on the best size to purchase from each of the main online retailers. On Amazon, their shoe dept., give approx. cm sizes (foot width and lenth) within their size guide(s).
I imagine these online returns will lessen as buyers become more aware of what they actually need, realise they're being monitored if they abuse the system (Fraud Watch etc.) and are generally more sensible with their purchasing.
Disc: Big % of folio in Boohoo (LON:BOO) and very small punts in Sosandar (LON:SOS) & French Connection (LON:FCCN)
Happy weekend Stockopedians :o)
Courtesy of the brilliant Tim Vine:
I had a dream last night that I was cutting carrots with the grim reaper. Felt like I was dicing with death.
Richard
When die I want to go peacefully like my grandfather did- in his sleep. Not like his passengers did, yelling and screaming!
Paul,
Any catch up thoughts on £G4M trading update from earlier this week. My notes from update were
Positives
* Revenue +37% organic growth to £109.9 on LFL 12month basis (+33% UK, +41% ROW)
* Active customers +53% and website conversion rate up again (to good 3.4%)
* Own brand up more than branded in last half - good sign for margins in the long term
* Ger/Scand dist. centres now fully up and running and with headroom - no news on (final?) Euro hub in S Europe
* UK fulfilment capacity increased by new efficiency measures - delays need for more UK warehouse CAPEX
* £5Mn in cash and less debt "than expected" at year end
Negatives
Chiefly lower margins than prior year (but recovering H1 27.5, H2 28.5% attributed to
* "Competitive pressures" (not sure if these will ever go!)
* Cleared some excess and slow moving stocks during period
* Courier and distribution cost inflation, allegedly now partly reversed and /or mitigated by using Euros centres
* Promise of focus and initiatives to push up % GM again going forward eg focus on higher margin lines
I bought in (too soon as ever!) a few months ago and intend to hold for 4 or 5 years. On this timeframe, if sales can double from here to £250Mn pa, or 5% market share on their market size data, I am very optimistic about a good return.
Short term, a recession and a sterling devaluation would hurt progress badly as it would require reductions in the marketing spend which is key to slowly building scale across UK/Europe and a bit of a brand moat in the segment they target (which in my view is undemanding entry to mid level hobbyists).
There has been in past months quite a lot of comments on here about the cost of returns to online retailers. The below BBC article states ASOS will start blocking "serial returners".
https://www.bbc.co.uk/news/business-47820387
I would think there are all sorts of pricing variations that could be used to deter moderately excessive returners, such as variable price discounts & shipping charges according to previous customer behaviour.
Some simple software should be able to calculate all this.
Obviously the ones who completely take the mick would still need to be banned.
Re balancing online sales vs stock returns (comments 16 and 17) - been thinking about this a lot.
I agree that once the market settles for these down (returns at this scale and with AI/data analytics is still relatively new ), we should expect differences to emerge by (fashion) retailers as they use data to understand segment their customers better. High returns are not going to go away once purchasing via physical stores shrinks.
However, rReturns will also become recognised as environmentally harmful (, costs and footprint of packaging and delivery vans etc). This will become a big negative as planet-conscious younger consumers become a bigger share of purchases. It will also favour those businessed with structurally advantaged models to cope with high returns.
This includes in my view
i) high basket value/high margin products ( eg Sosandar (LON:SOS) )
ii) multi-wear clothing (since I hear v, cheap, one use clothing is simply binned on return eg £NEXT
iii) quality brands where other reasons are minimised (picture/descriptor show it correctly, fit is consistent, quality is high (£SDRY)
I wrongly thought N Brown (LON:BWNG) with its mail order background would manage this well but it seems it was not quality 'born online' but rather historic success in focusing on formerly underserved markets (old & plump) now much better served
Losers will be :
ii) cheap brands (I think Boohoo (LON:BOO), PLT etc are very vulnerable to environmental shaming)
iii) one wear clothing ( Boohoo (LON:BOO), QUIZ (LON:QUIZ) )
iv) mis-described items ( Boohoo (LON:BOO), PLT ???)
Disc. I hold NEXT and SOS and have just exited BWNG (sadly at great loss)
Re BBC report ASOS returnd. Interesting (if true, I am not sure how much the BBC gets right). I find Julie Lavington’s (at £SOS) approach (as outlined to Paul at http://qualitysmallcaps.co.uk) much more refreshing. The living room is the changing room and as customers get more use to sizes, returns will drop. I think if you are getting it right, then serial returners should be a very small part of your customer base. Obviously if they are returning items with sweat marks (or worse!) that is different matter.
I worked in a department store in London many moons ago and this lady came in complaining that the sweater she had bought, had shrunk when she hand washed it. It was obvious that it had either been tumble dried or machine washed. We sent her away with a flee in her ear!
I hold a very small position in Sosandar (LON:SOS) pending more research.
Ref the Small Cap Value Report
Its hosted on Stockopedia's servers
Its written by Stockopedia staff or people related to the company
If they want to put it behind their firewall and only available to subscribers they can, its their report
Also no one should abuse the writers for their opinions
Treatt (LON:TET) - Edison note just out - https://www.edisongroup.com/publication/another-positive-half/23866
Hi Paul - a bit off topic, but have you any insight into why Sosander is sliding down at the moment?
Thanks, Pete
Hi PeteB, in the past when I have asked similar questions, nice contributors within our community tell me Paul doesn't tend to comment on share price movement. He responds to company announcements. The point being that sellers and buyers tend to affect short term price movements and who can predict those? Hence I am passing that kindness on, and affordng you the courtesy of a response.
My best wishes
Pete- Sosandar (LON:SOS) on a racy rating (6x next year's sales) and has lost momentum, plus backdrop of retail uncertainty. Such shares tend to be volatile. Simple as that I think! I have held off from buying them before but 3x expected 2020 sales is not an absurd price to pay if it keeps up the performance - Boohoo (LON:BOO) is on 2x 2020 sales and a more mature company now. So it could be a good entry point.
CEO of Airea (LON:AIEA) has sold his entire holding to the EBT. He pockets c£1.7m.
Not the best news for holders. But does it signify an issue that should be of serious concern? He has sold at a good price to the employee benefit trust, of which I assume he will be one of the beneficiaries, so he will be expecting to get some of those back for free in due course. Certainly not the best look for investor sentiment, however
Hi peter
I’ve spoken to the company
I’ve tweeted a synopsis but to your point he’s not an EBT benificiary...& I’m ok with the rationale for the transaction...he’s played a blinder but with benefits for all holders imho
Motorpoint (LON:MOTR)
Paul
So you've got interest-bearing debt of £65.4m, supporting £93.2m of inventories (at cost), which turns over about every 5-6 weeks. Why is that a problem? It looks absolutely fine to me.
I don't think its particularly a problem while the business is profitable - i was probably perhaps hoping for too much safety in that regard - it is a big number owed out in total though and with retailers if there ever is problems whats on the other side of the balance sheet doesn't always provide the support one would hope. Reflecting on it more though for a company making £20 mill a year + profits that shouldn't really be a problem - presuming its not trending in the wrong direction going forward.
Trust is the most important factor in all good things, so with regards to second hand car dealers. In the back of my mind there would always be a nagging doubt that what they say is not candid, so for me it is a dumb, but calm and relaxed, No, I'll try something else instead.
Hi Collector,
Trust is the most important factor in all good things, so with regards to second hand car dealers.
That reminds me of my 2nd favourite Bob Monkhouse joke - "Sincerity is so important, in showbiz. Once you can fake that, you've nailed it!"
My favourite joke of his, is this one, "When I was growing up, people used to laugh when I said I wanted to be a comedian. They're not laughing now!"
It's Friday, so why not have a couple of jokes!
Regards, Paul.
"When I was growing up, people used to laugh when I said I wanted to be a comedian. Haha They're not laughing now!"
Paul, so pleased you picked that one as it's my favourite one of all time, there was one other (not by Bob) but I've forgotten it lol.
Bob Monkhouse - one of the wittiest standups of all time
hi Paul
Bob looking back fondly on his childhood
"...on a Sunday evening after dinner, all the family would gather round the piano.....wishing one of us could play"
Motorpoint (LON:MOTR)
Cash conversion - is always likely to be strong, as secondhand cars are sold for cash or external finance. So I would expect the cash to come in instantly, before cars are released to the buyers.
Hello Paul
Strangely i was thinking exactly the opposite that cash conversion would be the primary problem for this company. Perhaps we are looking at this from a slightly different perspective in this regard - i would agree that once the car is sold they get the cash immediately job done.
But i am guessing they have to pay upfront for the cars they have to sell - so its cash outlay - car sits waiting to be sold for potentially a long period of time before they get their cash back. so to me cash conversion could be an issue if for example the pace of car sales slows or there is a material drop in used car prices? that can work to their favour in reverse too though).
Looking at the balance sheet - which is probably all important for retailers like this
inventories (93 mill) receivables 11 mill and cash 15 mill total 119 mill 65 mill is
Trade and other payables £102 mill - of which "stocking finance facilities. (0.8 mill interest paid
They have land of 1.7 mill and total plant of 7.5 mill which i will disregard as i would say it would cost them money to exit leases
To me this balance sheet is anything but bulletproof as the size of the inventories is much larger than asset surplus - and they are funding the stock on finance. Practicably if they were ever in a financing problems then they cant pay down debt without selling down the stock which would ruin the business model.
I put this company into ????? - i quite like the business model, reasonably simple and probably works well with the scale they have. The balance sheet isn't a killer but i think it's wishy washy enough at present to put me off investing when aligned with the pretty low margin business type. Not for me i guess but i see the attraction.
One added thought - do they earn good money by offering crap finance terms to customers? - if they do this would be the kind of nightmare risk issue that could destroy the company if they ever had any ppi type redress issues dating back multiple years. I don't know enough about their business to know whether that could be a potential banana skin. or not.
Hi millaree,
I don't understand why you think there is a problem with the Motorpoint (LON:MOTR) balance sheet - it looks absolutely fine to me.
Conventional car dealership chains tend to have a current ratio of about 1. As you suggest, the big assets are inventories, and the big liabilities are creditors (manufacturers & stocking facilities).
MOTR is somewhat better, with a last (interims) current ratio of 1.18
Stock turn looks to be a bit over a month. It's doing c. £1bn revenues, with £93.2m inventories (at cost). Assuming roughly a 10-15% markup on cost, then they seem to be turning over their inventory about 10 times per year - very good.
Assuming they get about 30 days credit from the bulk vendors of cars (possibly ex-hire fleet cars, ex company cars, etc), then the money going out for purchases looks to be on a similar timescale as the money coming in from turning over their stock.
Although it looks as if they probably do pay cash for most of the cars (as you suggest) and use a stock-funding facility - here is the breakdown of current liabilities as last reported in note 13 to the 30 Sept 2018 balance sheet;
Accruals seems high- I would like to know what is in there.
Note the £2.5m deferred income. Sounds like that is ending, hence the headwind noted in today's report.
So you've got interest-bearing debt of £65.4m, supporting £93.2m of inventories (at cost), which turns over about every 5-6 weeks. Why is that a problem? It looks absolutely fine to me. It's safe lending for the bank, and is a very cheap facility - the P&L finance cost is £0.8m for the year, for the stocking finance facility. So a big rise in interest rates would be expensive for MOTR, but that doesn't seem likely any time soon.
I prefer the capex-light model of MOTR to conventional dealers, who are beholden by the new car manufacturers to spend on glitzy showrooms.
Good final point you make about the potential for PPI-type fines, if MOTR (and other dealers?) have been mis-selling finance. I recall something about that recently, which I wrote about, where I think the FCA are investigating car credit brokers, who are given leeway to change the interest rate apparently, which sounds a bit fishy.
To me, the attraction of MOTR is that it has the potential to scale up much more quickly than conventional dealers, and its sites are doing something like £80m revenues each. Hence opening say 5 or 6 new sites, would grow the business by about 50%, at very little capex. That looks quite attractive. Also as it doesn't sell new cars, MOTR shouldn't be affected much by any supply disruption, Brexit, etc.
It's not a stock I hold, but it's on my watchlist as a possible future purchase.
Regards, Paul.
I think the potential problem is in a recession people won't be buying cars or very few will be, I remember the last recession, dealers were desperate to sell cars to free up the cash tied up in them, I got a very good deal. So instead of the normal 5-6 weeks what if that becomes 20 weeks and the prices are reduced. I'm seeing around me quite a bit of competition to Motorpoint (LON:MOTR), I don't know if others are finding that in their areas. Their cars did not look cheap to me, I traded mine in locally for a good deal. Looking at the reviews they are good so most people seem to be happy. If looking for a used car I would use Auto Trader (LON:AUTO), good way to find what you want in your area and then just go the dealer, they even give you a price for a trade-in I was surprised the dealer nearly matched, deducted a bit for a couple of problems, which was fair.
My biggest failure was a car supermarket called Car Group. If a low margin business finance stock with debt then any sudden dislocation in the market kills the firm stone dead. In my case it was a dramatic move of the euro: sterling exchange rate which suddenly led to the UK being flooded with cars from the confident. This depressed the value of stock and slowed stock turnover. Moral of the story is with high debt low margins, don't underestimate black Swan risk as the firm has nothing to fall back on and will go bust.
Treatt (LON:TET)
This is another one that got away. I held several years ago and one of the reasons for holding was the Bovill family having a large amount of skin in the game. I sold in March 2013 when they announced their intention to sell their holding.
In hindsight I made a bad decision as it has almost 4 bagged since.
Paul - any thoughts on today's pre-close from Tricorn (LON:TCN) ?
It looks roughly in-line with forecasts but this share is one that has not recovered from the great autumn slide, in fact it kept going down so that we have a prospective p/e of 5 for the year just ended and a stockrank of 89 despite momentum rank of 40.
Hi sharw, I hold Tricorn (LON:TCN)
I think it was sold off because of concerns that revenue were flatlining after experiencing stronger growth in early 2018. In my opinion that kind of missed the point as the share is all about the turnaround in operating margin and falling debt - hence why today despite only a 2% rise in revenue there is still a 30% rise in pre-tax profits.
The company still has high debt which hopefully is being pared down and it's a very small cap, so it shouldn't be on a very high multiple, but today's positive update should give it a decent lift into the higher single digits hopefully.
My morning smallcap tweet: Squaring the funding circle.
Scientific Digital Imaging (LON:SDI), Matomy Media (LON:MTMY), ProPhotonix (LON:PPIX), Bilby (LON:BILB), £K3C, Motorpoint (LON:MOTR), Funding Circle SME Income Fund (LON:FCIF), Funding Circle Holdings (LON:FCH)
Scientific Digital Imaging (SDI) £1.6m acquisition of business with rev ] £1.9m and PBIT £0.31m. Adds ~14% to rev and is earnings enhancing.
Matomy Media Group (MTMY) is offered $36m for its 90% holding in Team Internet AG subject to due dil. Cash would be used to reduce convertible debt.
Prophotonix (PPIX) FY slightly ahead of guidance with rev down 8%, net loss -$1.3m (-$2m). Rev down mainly due to a customer's delayed new product launch. Outlook: Bookings in the first 13 weeks $4.2m ($4.3m), backlog $7.8m ($7.4m).
Bilby (BILB) CEO resigns, new CEO starts 15 April. Sounds amicable but clearly board knew a while ago.
K3 Capital Group (K3C) cuts FY EBITDA guidance to £4.5m-£5m. Blames delay in a number of the significant transactions in KBS Corporate Finance Division which may not close in the FY.
Motorpoint Group (MOTR) guides FY U/L pretax up 10%. Stockopedia F/C is for 18%. Gross margins per unit softened slightly. Outlook - progress in revenue and U/L profit but ~£2m (non-cash) profit 'headwind' from historic deferred extended guarantee income.
Funding Circle SME (FCIF) EGM to approve wind up and return capital. "Funding Circle has reaffirmed its willingness to support the Board so as to effect the best outcome for the Company's shareholders."
Funding Circle Holdings (FCH) re FCIF wind-up - FCIF was projected to fund only ~3.5% of FCH's origination volume in 2019. FCH confirms FY guidance.