Small Cap Value Report (Fri 5 Oct 2018) - MOTR, CALL, PLA, QUIZ

Good afternoon,
Drat, I forgot to put up the placeholder last night, my apologies. I blame Emily Thornberry, who worked me up into a lather, with her bullying of Isabel Oakshott on Question Time. She's a nasty piece of work if you ask me.
Anyway, it looks as if there's little for me to cover today. I'll be updating this article throughout the afternoon.
Motorpoint (LON:MOTR)
Share price: 211p (up 3.9% today, at 12:44)
No. shares: 97.6m
Market cap: £205.9m
Motorpoint Group PLC, the UK's largest independent vehicle retailer, is pleased to announce the following trading update ahead of its Interim Results for the half year ended 30 September 2018.
- H1 revenues expected to be up c.9%
- Operating margin similar to last year
- Pleased with quality & mix of current vehicles in stock
- 12th site, in Sheffield, is performing well
- Pipeline of new sites under review
Outlook - sounds alright;
The Board continues to closely monitor customer confidence in light of the ongoing economic and political uncertainty. However, the Board is encouraged with the recent trading performance and remains confident that Motorpoint's independent and flexible model leaves it well placed to increase market share.
My opinion - it's striking how some companies are blaming Brexit uncertainty, the weather, football, etc, for poor performances. Whilst other companies are just getting on with things, and doing well. Motorpoint seems to be in the latter category.
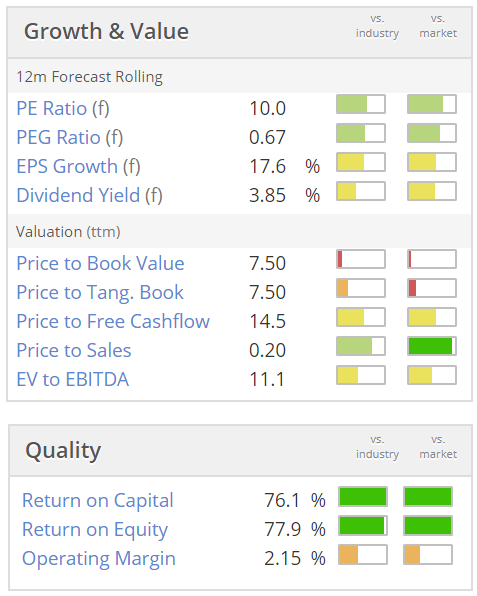
The valuation looks attractive to me - see below - for a company with a proven formula, which is opening new sites. Could be worth a closer look, and adding to my watchlist for things to buy on any panic sell-off. The return on capital & equity look very good. It doesn't seem to need much capex. Just a piece of land with a few large sheds on it.
Flogging good quality secondhand cars to the public, at bargain prices, won't ever go out of fashion. So this is a good business.
Cloudcall (LON:CALL)
Share price: 103.5p (up 9% today)
No. shares: 24.2m
Market cap: £25.0m
(at the time of writing, I hold a long position in this share)
Large trades
There's no announcement as yet, but there will have to be soon. I note that 4,781,288 shares have changed hands at 90p today - that's significant because it's 19.8% of the whole company.

I've been able to tie some of these trades to the disclosed >3% holders.
Miton - holds 1,440,288 shares - so that could be the 100,000 + 1,340,288 trades above.
Legal & General - holds 1,146,000 - the same size as the 4th trade on the list above.
I've asked my broker to make some enquiries, but we've been rebuffed & told we'll just have to wait for the RNS(s). Could be interesting anyway. I won't speculate on what might be happening, as I got into trouble last time I did that. One to keep an eye on maybe?
The company is growing strongly (organically), but keeps missing its breakeven target, which has clearly driven some large holders into throwing in the towel. Pity, as I think the company's on the cusp of something good. Mind you, I've been saying that for about 5 years!
High margin, high recurring revenues SaaS businesses are in demand at the moment, so at some stage I think there's a chance of a decent re-rating here. It seems that an overhang has been cleared anyway. We'll soon find out who the buyer is.
Plastics Capital (LON:PLA)
Share price: 114p (up 2.7% today)
No. shares: 39.0m
Market cap: £44.5m
This is a small group of companies making niche plastics products.
It's half way through the current year ending 31 Mar 2019.
... the Company continues to trade in line with market expectations...
Trading during the six-month period ended 30 September ("H1 2018/19") saw an improvement on the prior year.
Sales have continued to grow at double digit rates and profitability has improved as the revenue mix shifted towards the higher margin Industrial Division.
- Forex has been helpful, as old currency hedges are being replaced with cheaper ones.
- The films division is expanding capacity.
- Matrix business also performed well. Strong sales growth.
- Mandrel business - weak order book.
- Comments on plastic waste, recycling, environmental issues.
My opinion - I can't get excited about this company.
Dividends ceased in 2016, which reinforces the reality that this business does not generate much cashflow. Free cashflow has been negative for the last 4 years. It's quite capex-hungry too, and has a fair bit of debt. None of which is good.
The share price has gone nowhere in the last 5 years. It's just not a very good business, in my view. I cannot understand why anyone would want to buy or hold this share.
QUIZ (LON:QUIZ)
Share price: 98.5p (down 33% today)
No. shares: 124.2m
Market cap: £122.3m
Trading update (profit warning)
QUIZ, the omni-channel fast fashion brand, announces a trading update for the for the six-month period to 30 September 2018 ("H1 2019" or the "period").
What's gone wrong?
- Stores & concessions did well over the summer, but sales were lower in Sept 2018 - blamed on lower footfall. More likely to be due to new season autumn product not being good enough, in my view.
- Previously reported, on 5 Sep 2018 trading update, a £0.4m hit related to the collapse of House of Fraser. So this is not a new point - hence I'm unsure why it has been mentioned again today?
- Online sales via third-party websites (e.g. Next, Zalando) were disappointing, with no growth on the prior year's H1. However, own-website sales are growing very strongly, at +70% (and these are higher margin sales too).
Quantifying the H1 impact - the company has very helpfully spelt out the impact of the above factors;
EBITDA for H1 2019 will be not less than £5.5m, being £1.5m lower than its previous expectations.
This is quite worrying. Given that the company said it was trading in line with expectations as recently as this update on 5 Sept 2018, then a £1.5m profit hole has appeared in the last month. To me, that suggests that the autumn range has probably flopped - which has read-across for the full year figures. Sales may continue to be subdued in H2, and there may be a need for more discounting, to shift slow-moving lines.
Full-year outlook - again, very helpfully, the company updates us on its full year expectations;
In addition, the Board has taken the prudent assumption that should the trend in online third-party sales continue during the second half of the financial year, Group revenue for the full year to 31 March 2019 would be lower than current market expectations at approximately £138m (FY 2018: £116.4m) and the Group's EBITDA for FY 2019 would to be in the region of £11.5m.
The most recent broker forecast I have found suggests £150.2m revenues for FY 2019, and £15.7m adjusted EBITDA. Therefore this seems to be quite a large miss, at -27% below forecast EBITDA. That suggests to me something more significant has gone wrong.
Also note that £11.5m forecast EBITDA for FY 2019 is actually down on FY 2018, which was £12.7m. Therefore unfortunately, I think this seriously damages the profit growth credentials of the business.
Using EPS, the adjusted FD EPS forecast was previously 7.7p. If we reduce that by 27% as well, then it falls to 5.6p (down from 6.3p last year).
Valuation - this share previously attracted a fairly high PER, due to its growth. With profit growth now apparently stalling, then I think the share is likely to de-rate considerably.
The still-rapid growth in own-website sales means that I think a PER of perhaps 13-15 can still be justified. That suggests a share price of 73-84p would be about right, the way I see things.
My opinion - it's always tempting to leap in after a profit warning, since our minds naturally anchor to the previous share price, and we imagine it looks a bargain. However, crunching the numbers shows that it probably isn't a bargain yet.
I liked this share a lot when it listed, having been impressed by a polished performance from management at an IPO meeting. Plus the figures & growth looked outstanding.
It's all gone a bit wrong today. I'm minded to keep my distance for the time being. If it drops into my 73-84p target range, then I would consider a purchase. The risk is that, if autumn ranges have not been well-received, then that could set the company up for another profit warning later in the season perhaps?
I have nagging doubts about the quality of the brand too, which seems not terribly aspirational. The website isn't a patch on the better quality look of say Sosandar (LON:SOS) (in which I hold a long position).

That's it for today, unless there's another profit warning!
Apologies again for being late today, but we got there in the end.
Have a smashing weekend!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
Had a look at cars at Motorpoint (LON:MOTR) I thought they were quite expensive and little choice, I looked on Autotrader and found one at a dealer not far from me for far less money, low mileage and in the colour I wanted, they also gave me a good trade in price. I think there is quite a bit of competition. In a recession people don't change their cars so much, so it's not one for me.
Bit naughty of QUIZ (LON:QUIZ) releasing that update midway through a Friday afternoon.
I don't hold any of these but I take comfort from their own website on-line sales progress as a read across to Boohoo (LON:BOO) and Sosandar (LON:SOS) where I do hold (a lot).
I follow QUIZ (LON:QUIZ) closely so here's my take on their mid-afternoon RNS. I sold out a few weeks ago over the concerns about Debenhams (LON:DEB) future as QUIZ (LON:QUIZ) is heavily exposed. See here for my take on that: https://www.stockopedia.com/co...
Today they say revenues for H1 18/19 are up 19% overall and 44% online. They warn that there is flat revenue from third party websites. As you can see from previous statements, their growth is slowing:
Total revenue growth
H1 17/18
Xmas 17
H2 17/18
FY 18
H1 18/19
35.2%
31.9%
24.8%
30%
19%
Online revenue growth
H1 17/18
Xmas 17
H2 17/18
FY 18
H1 18/19
204.6%
119%
127%
158%
44%
They helpfully provide some numbers on full-year expectations, although referencing EBITDA is a bit annoying. Expected full-year revenue was £152m (and 7.95p adjusted EPS) and they are now saying it will be £138m.
"The Board anticipates that, as a result of lower than expected sales through third-party online partners in the second quarter of the financial year, the performance of our UK stores and concessions during September and the provision against the outstanding House of Fraser debt, EBITDA for H1 2019 will be not less than £5.5m, being £1.5m lower than its previous expectations. In addition, the Board has taken the prudent assumption that should the trend in online third-party sales continue during the second half of the financial year, Group revenue for the full year to 31 March 2019 would be lower than current market expectations at approximately £138m (FY 2018: £116.4m) and the Group's EBITDA for FY 2019 would to be in the region of £11.5m."
Not a disaster. But presumably EPS will now be closer to say 7p? (if one ignores the House of Fraser provision). The trouble is I am still concerned by the Debenhams exposure so I probably would still want a slightly cheaper entry point than this.
Separately I am intrigued by this: "the Group experienced a lower sales performance across its stores and concessions during September reflecting less footfall." Could this be because September has been warmer than most so maybe people aren't needing to rush out and buy new clothes? That could affect other clothing retailers too obviously.
Stop press! Profit warning from QUIZ (LON:QUIZ)
I'll add a section on this once I've finished lunch.
I would also welcome your views on the Indigovision (LON:IND) scheme. My back of envelope calculation is that they would get the maximum (20% of capital) at eps $1, currently 77p. Taking the p/e of 14 of rival Synectics (LON:SNX) as a guide that would give a share price of 1078p which would delight those currently holding at 106.5p!
Hi Paul, interested if you have a view on Gfinity. Interesting RNS about them running an eSports competition for the Premier League. Problem is the cash burn is so high.
Thanks
Andrew
Hi Andrew,
As it's a quiet news day, I've had a quick look at Gfinity (LON:GFIN)
The last interim results were absolutely dire! £1.8m revenues and a £7.7m loss before tax, in just 6 months!
So it's likely to need regular fundraisings.
Personally, I wouldn't go near anything trading this badly, burning through cash so fast, and in a sector that I don't really understand. So definitely not for me!
I think Nigel Wray is involved in this, and he tends to back management that he rates highly.
Regards, Paul.
Re Gfinity,
Thanks Paul, that’s really helpful, I appreciate you taking a look. I guess it will be very difficult to build shareholder value near-term with those sort of losses.
The trades on Cloudcall (I hold) are intriguing- I hadn’t spotted what was going on. Be very interesting to see who the buyer or buyers are. I’m a bit surprised/worried though about likely several institutions throwing in the towel. I personally think the drivers for stronger growth going forwards are probably there and current levels of growth are decent enough.
Regards
Andrew
Gfinity (LON:GFIN) is another of my large array of very small shorts, so the 17% share price rise yesterday was not especially welcome. But the beauty of these positions being individually so small is that a single move like that barely moves the needle.
I'm fighting a loosing battle to remain strategically ignorant about the companies in my short folio, so I am having to settle for being strategically indifferent .
Yesterday's announcement seemed pretty impressive
Good and impressive stuff, could it be a game changer for the company?
I really don't know, it seems like a pretty cool badge of honour, but unfortunately they left out the part of the RNS that would have told us whether they will actually make any money out of this.
I'm quite happy therefore to keep my short open and ride this out. (The share price has already given back 1/3rd of yesterday's gains).
I'm intrigued by companies like Motorpoint (LON:MOTR) (and Computacenter (LON:CCC) is another one) which look like great quality companies with good ROCE etc. but have tiny margins which I normally take to be a sign of a poor company.
I can never quite reconcile the two things in my head and tend to shy away from them. I'm always too worried that with thin margins profitability can disappear too quickly.
https://www.moodys.com/research/Moodys-assigns-Ba2-CFR-to-Playtech-PLC-stable-outlook--PR_389601
For those interested, Moody's report on Playtech (LON:PTEC). Seems mildly positive.
Any views on the LTIP at Indigovision (LON:IND) ?