Small Cap Value Report (Fri 6 Mar 2020) - TENG, KIE, DLAR, WEY

Good morning, it's Paul here, with Friday's SCVR.
As usual, this is initially a placeholder article, to allow subscribers to add comments from 7am, as I gradually write the main report throughout the morning. I have to stick to the official 1pm finish time today, due to travel plans.
Edit at 11:19 - today's report is now finished.
I hope you're all coping alright with the current very difficult market conditions. It's a gruelling time, so I sympathise if your portfolio is getting knocked about as much as mine.
In case you missed it, I wrote a new section late afternoon about Hostelworld (LON:HSW) in yesterday's report. The key issue with travel companies, is whether they can survive the sudden drop in passenger numbers. I focused on this in my report on HSW, and it's a good template for looking at other travel companies too.
As Flybe showed, airlines that are already in trouble, are likely to be pushed over the edge with recent developments. I'll focus on that here, and try to steer readers away from companies that could go under, as usual.
There's an interesting article here in today's Telegraph showing that half of Flybe's routes have already been taken up by competitors. With about 80% likely to be taken up within a week. This seems to confirm that the Govt made the right decision, not to prop up Flybe with taxpayer money. Capitalism can be brutal, but re-allocating resources to more efficient competitors is ultimately the best thing.
It's all very well people saying that coronavirus is just a temporary blip, but operationally geared companies (high fixed costs) may not be able to survive even a few months of disruption. I think we could see large numbers of independent cafes/bars/restaurants go under, because many are already on a knife-edge financially, due to over-capacity in the sector. Hence a sudden, and large drop-off in customer numbers, which is probably imminent if not already happening, could be the final straw for lots of small businesses. That could tip our services-based economy into recession, in my view.
The head of the IFS says that the UK could experience a technical recession (2 consecutive quarters of negative growth), triggered by coronavirus, in Q2 & Q3 of this year.
Please see the header above, for the companies I intend covering today. Only TENG reported today, the others (Kier, De La Rue, Wey Education) are backlog items on my notepad, that I didn't get round to looking at previously, but want to look at. There won't be any time for reader requests today, sorry.
Ten Lifestyle (LON:TENG)
Share price: 75p (down 10% at 08:20)
No. shares: 80.65m
Market cap: £60.5m
Ten Lifestyle Group plc (AIM: TENG), a leading technology-enabled global lifestyle and travel platform for the world's wealthy and mass affluent provides a Trading Update and notice of its half-year results, for the six months ended 29 February 2020, which will be announced on Thursday 14 May 2020.
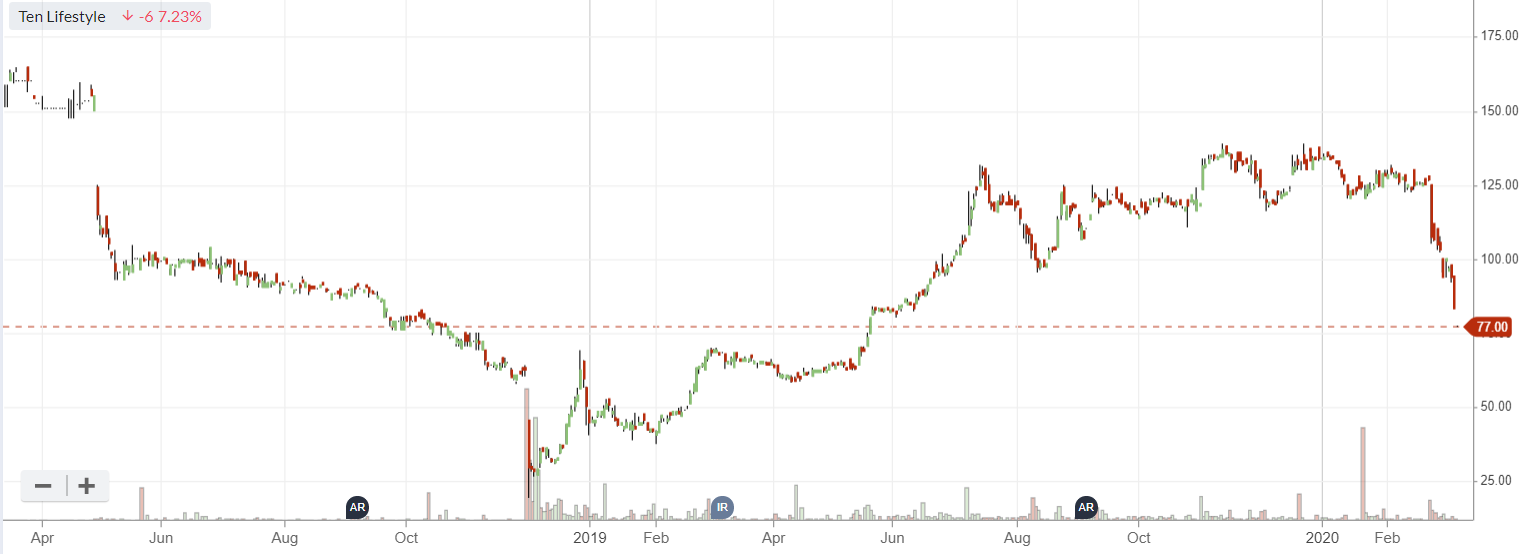
As you would expect for anything travel-related, this share has been beaten up in recent weeks, due to coronavirus:
.
For anyone not aware, the dotted horizontal red line above is the current share price. In this instance you can see that it gapped down a bit this morning - suggesting this is probably a mild profit warning.
Key points;
Trading at adj EBITDA breakeven in H1 - said to be in line with mgt expectations, and an improvement on last year. Although to my mind, it's really still loss-making, since adj EBITDA is the softest profit measure possible.
Still burning cash - which is down £2.8m in 6 months, to £9.5m - enough to keep going for now.
This period would have been barely affected by coronavirus, so the outlook comments are more important that what is now historical performance.
Coronavirus update -
Ten's revenue substantially derives from service delivery rather than the conversion of bookings such as a travel or event ticketing stand-alone business.
This sounds ambiguous. I think what they're saying is that revenue is subscription-related, not commission-related. In which case, why didn't they just say so?
This bit is also unclear;
We experienced some disruption in our APAC region in January and February and during this period we have been able to support our members in relevant ways, mitigating the financial impact on our business.
Clarity doesn't improve much with this next bit either;
Currently, service activity and member engagement levels remain as expected on a group-wide basis and we are successfully supporting our members with both 'business as usual' requests and other requests related to the Coronavirus
There's another paragraph of waffle, so let's ignore that and cut to the chase:
As a result of the above, the Board expects a reduction in Net Revenue growth for FY20 compared to expectations. However, the Board expects continuing operational efficiencies to mitigate the impact on adjusted EBITDA and net cash for the year.
Broker updates - nothing available for private investors, so I can't take this any further.
My opinion - what a useless update, it's almost entirely just waffle!
All it really tells us is that there is some unspecified impact from coronavirus disruption, and that they're mitigating it with some cost-cutting.
This business has been loss-making in the past, although it was bearing down on breakeven before this crisis erupted. The only logical conclusion is that the current crisis must be bad for business, hence it's likely to remain loss-making. As such, it doesn't interest me at all. I'm looking to buy great businesses that are taking a short term knock, which this is clearly not.
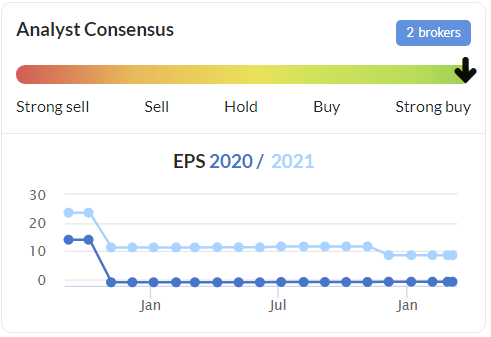
Note that optimistic broker forecasts were slashed almost a year ago. Therefore I would take current forecasts of a big rise in profit next year with a pinch of salt.
.
Kier (LON:KIE)
Share price: 111p
No. shares: 162.1m
Market cap: £179.9m
Kier Group plc (the "Company" or the "Group"), a leading construction and infrastructure services company, announces its results for the six months ended 31 December 2019 (the "period").
I've covered this group a couple of times here, concluding that its finances are nothing like as bad as basket case Carillion, which of course went bust. Hence, despite widely reported problems, my view was that Kier looks salvageable, although too risky for me to want to get involved personally. The trouble with these large construction & contracting groups, is that there can be any number of problems lurking under the surface. So many have gone bust in recent years, that the whole sector terrifies me. That said, of all the problem shares I've looked at in this sector, Kier looks the most likely to come good, as it's still profitable, and has a half-decent balance sheet compared with others which went bust.
Key points from interim results -
- Pre-exceptional operating profit of £46.7m - on £1,866m revenues, a low margin of only 2.5%
- Exceptionals take it to a -£41.2m statutory loss before tax
- Net debt of £242.5m, average month-end net debt of £395m is a more realistic figure. Well within bank facilities. Although renewal of facilities & bonds will be a key issue in future
- HS2 proceeding is good news for Kier, and lots of recent big contracts won - huge forward order book of £7.9bn
- Very complicated turnaround plan underway - many moving parts - disposals, cost-cutting
- Going concern note - no bombshells in it that I could see
- Balance sheet weak - NTAV is negative, at -£355.2m
- Pension schemes, am just flagging this, as not got time to delve in that today
My opinion - there are so many moving parts here, it's an incredibly complicated situation. I remain of the view that it looks a potentially survivable situation, providing nothing else goes wrong. Would I want to get involved? No, it scares me too much! That said, if things work out well, then this could be a potential multi-bagger from £180m market cap. Or if something major goes wrong, existing equity could get wiped out. I cannot predict how things might pan out, it's too complicated & uncertain.
.
De La Rue (LON:DLAR)
Share price: 124p
No. shares: 104.0m
Market cap: £129.0m
2019/20 is for the year ending 31 Mar 2020.
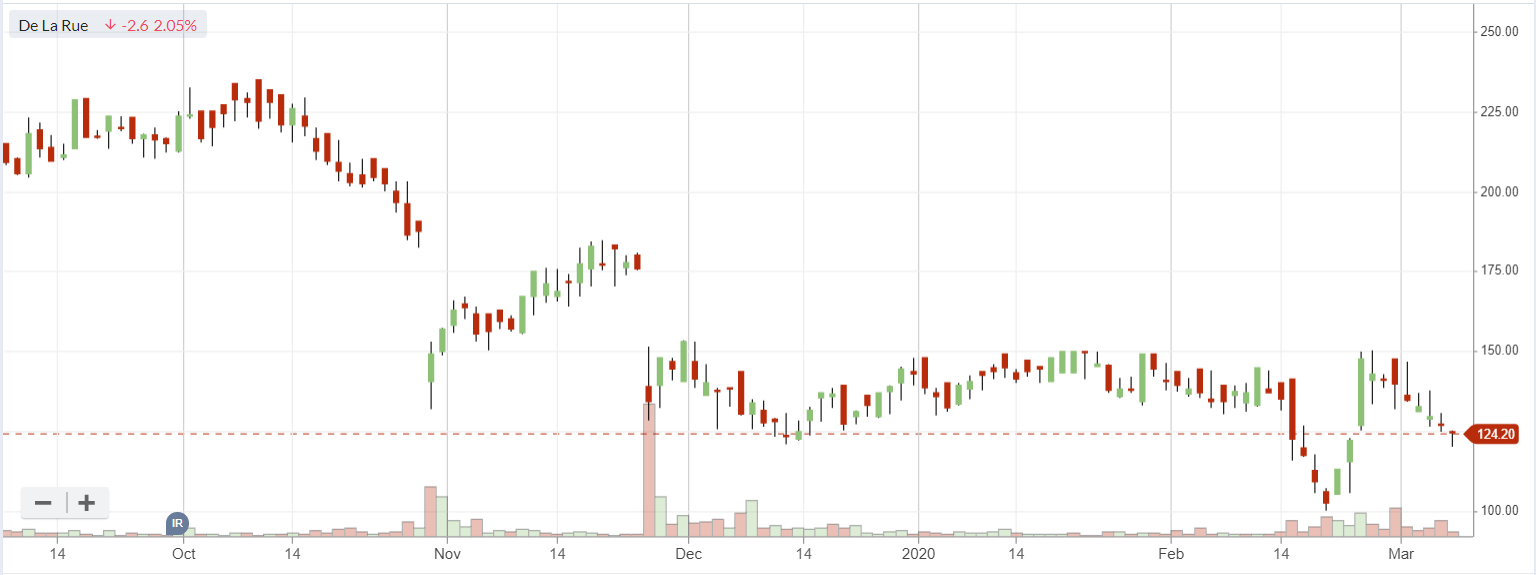
This announcement was issued on 25 Feb 2020, caused a brief surge in price, as you can see below;
.
I went through the interim results in some detail, here in Nov 2019, and re-reading my notes, it's already putting me off! There would need to be something very special in the latest update to induce me to buy shares, especially in the current chaotic market sell-off.
Current trading -
Trading during the second half for both divisions has been satisfactory, and the Board reconfirms the current guidance for adjusted operating profit for FY2019/20 of between £20m and £25m.
That's encouraging, because it only made £2.2m adj operating profit in H1. Therefore, the hoped-for big turnaround in H2 performance, which previously looked very optimistic, does seem to have happened.
Bank facility/covenants -
The Group expects to operate within its banking covenants for FY 2019/2020, including the net debt/EBITDA covenant of ≤3.0 times and maintains a good level of liquidity headroom under its £275m revolving credit facility which expires in December 2021. The covenant ratio excludes the pension deficit liability.
That's a huge bank facility, which I imagine is likely to be reduced in future.
Also, bear in mind the above statement only applies to covenants to end March 2020. What happens after that?
Cost reductions - significant proportion by Aug 2020. £10m p.a. already done, with another £25m p.a. in the pipeline. Those are large savings. Will there be any reduction in revenues from these cuts I wonder?
Other developments - there's more detail, which I won't regurgitate here, but it sounds positive.
My opinion - on a brief review, I think this is starting to sound a credible turnaround. Although see my previous article (link above) to see the full extent of the balance sheet issues, so there's a lot to overcome. Overall, I think there could possibly be speculative upside here, but it's risky.
Wey Education (LON:WEY)
Share price: 17.75p
No. shares: 138.2m
Market cap: £24.5m
Wey Education plc (AIM: WEY), the online educational services group is pleased to update the market on current trading.
WEY has a 31 Aug 2020 year end date.
- Trading ahead of expectations
- Revenues expected to be £7.5m, up 25% on LY, and significantly ahead of market forecast - great stuff!
- Profit - will only be in line with forecast, because extra revenues are being reinvested in marketing & more staff
My view - this is a pretty decent growth company. Small, but with a good product offering, which I've checked out in quite a bit of detail before.
I think investors should be pleased that the company is re-investing for growth, rather than chasing short-term profitability.
The valuation looks a bit aggressive now, particularly in current market conditions, but once things settle down then it should be OK.
Home-based internet schooling is obviously a hot topic right now, given the coronavirus situation - which might trigger a more permanent upsurge in enquiries for internet-based teaching, perhaps?
Sorry, but I have to leave it there for today & the week - a week that I'm sure we'd all like to quickly forget!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
It looks positive as directors are buying into it.
"One budget related rumour that seems relevant is the removal of BPR"
If this happens I wonder if it'll be retrospective, or if it'll only apply for "new" money invested after Wednesday. If the latter, then not much time to top up any BPR portfolios.
For my mother's account (for which I have some involvement) I've hedged her bets by only moving a proportion of her portfolio into BPR shares.
Why cant the actual trade log from the platform be used? That is the true record, assuming no editing....
That gets round the 'it takes too long, I trade too much argument' doesn't it?
5Interesting
One budget related rumour that seems relevant is the removal of BPR which might impact the demand for a number of qualifying shares on AIM.
Good spot, thank you
Richard Holway reported a recent conversation with the CEO of Computacenter (LON:CCC) where he said that firms were buying a lot of laptops to support home working.
anyone with ideas on what is going on with Avon Rubber (LON:AVON) today? 12% drop on no obvious news despite being very resilient so far to the Corona fears!?
I am also puzzled by Avon Rubber (LON:AVON) ( down 14% now). Biological protection suits would seem to be a winning choice and presumably the dairy equipment is more likely to be renewed than reused.
It had a high rating but this was well signalled by a series of good recent announcements.
So like you I don’t get it, I don’t have the conviction to declare it underpriced and back up the truck, regrettably the reputation of the market leads me to believe that somebody knows something that I don’t.
A very uncomfortable feeling
agreed - I was looking to top up to existing holding until today but with some very strange movements and volatility at the moment will wait for things to settle down
I am also puzzled by Avon Rubber (LON:AVON) ( down 14% now). Biological protection suits would seem to be a winning choice and presumably the dairy equipment is more likely to be renewed than reused.
Avon Rubber (LON:AVON) is priced to perfection so it's vulnerable to any kind of earnings hit. Someone may have figured out an issue in the supply chain for instance.
However, at this point, I wouldn't look too hard for causal connections - there might be business reasons for the fall but it's at least as likely that a large holder is selling for technical reasons. For instance, they might be rebalancing away from equities to bonds or have a call that they need to fund by selling whatever they have that's liquid. If they're selling into no demand then the price will tank.
This kind of inexplicable price fall happens a lot during corrections.
timarr
Avon Rubber (LON:AVON) They are going backup now, so only about 10% down now, I did have problems getting a price a while ago but can trade now.
Spoke too soon now back down again.
”It's all very well people saying that coronavirus is just a temporary blip, but operationally geared companies (high fixed costs) may not be able to survive even a few months of disruption.”
I am sure you are right and if you a company is operationally geared, it needs to be cautious, have a strong balance sheet and the means (cash or secure lines of credit) of weathering any storm. Covid19 is a temporary blip but there will be other temporary blips. Of the black swan variety or otherwise.
I am learning a lot going through this current pullback, about myself and about investing.
As an aside I was shocked to learn from drjram below that because FlyBe was registered in the IOM the pension plan/deferred income (people often forget that that is what a pension fund is) of the employees is not covered by Government protection. Capitalism works, we know that, and FlyBe was rightly allowed to go bust but it, Capitalism, only works when regulated properly.
The fact that FlyBe is owned by three liquid and profitable entities only makes this more sickening.
So here's an interesting snippet
The FEDs Bullard says the market seems to be pricing in the very worst case and expects slowdown in growth from virus impacts to be temporary. Lower rates in market will help.
Obviously at odds with general panic that's ongoing.
Also note volumes taking European stocks to new lows is less than half the volumes in the initial sell off. Also suggests the move lower lacks real conviction. Could be retail capitulation.....often the bottom though I'd hesitate to call that right now.
this is a quick beauty ? parade of indices YTD in 2020
FTSE 250 has gone from the star of 2019 to the dog of 2020 and is off over 17% from its recent highs so approaching a technical bear territory
FSTE 100 has suffered less although weak GBP has helped
These are sector performances YTD in the FTSE 100 , with the green in Utilities, household goods , with Pharma Tobacco and F&D retail outperforming relatively ....while deep in the red are O&G, Mining, Travel & Leisure and other cyclicals
Looks a bit like a recession rotation with a coronavirus narrative
Thanks for that - very interesting chart. The big surprise here is that telecoms are the worst performers and have done worse than travel/leisure and the miners... this seems wrong and is ultimately likely to shake out to be either an overreaction in that sector or an under-reaction in the others mentioned - anyone who figures out which it is could do very well out of that...
Aviva (AV.:LON) at 338p yielding 9.2% - in a low inflation, low interest rate environment, that's not normal - something's got to give.
Bonitabeach
Long (AV.: LON)
agree - can't work this one out. eps of 60p so a PE of 5 trading 30% below NAV and yielding 9%. I think market has this one very wrong and will be looking to buy some more for the longer term. Same with L&G.
Insurers the likes of Aviva ship most of their liabilities (from insurance products) to reinsurers. I'm not an expert, but I remember reading ages ago that most of these reinsurance contracts are structured so that the primary insurer (Aviva) themselves take most of the inital hit if losses are higher than expected?
They're definitely exposed to Travel Insurance, Health Insurance, Life Insurance, etc. Of course, they'll benefit from any isolation (i.e. no claims on auto insurance if people aren't driving). Hard to quantify.
Also they do more than insurance, but also lots of investments. Their bonds will be doing well at the moment, but equities probably taking a hit.
Yes but who writes the reinsurance? With large claims it is the excess of loss reinsurers that carry the can.
Yes, but a lot of the policies around health and life get very expensive as you get older and as a consequence lots of people past working age do not have them. I'd therefore be surprised if they have very much exposure to the age group that is most likely hospitalised or claiming on life assurance (70's & 80s).
Premiums will be hardening as we speak and I suspect demand will be higher than normal to buy policies too.
Their capital adequacy is very strong. Anyway, we will see but I suspect they are being dragged down with everything else rather than a specific rationale. I will buy some around a 10% yield for the longer term.
re Aviva (LON:AV.), and others of that ilk like L&G, I assume the market is looking at the shedloads of corporate bonds which they hold, and pricing in a few corporate defaults in a recession. Not sure how justified that is - these companies are meant to be disciplined and hold only the bluest chip paper. I hold, think they are too cheap.
Yes, they do look cheap - Aviva and L&G.
But, they have long term liabilities. L&G having purchased a load of private pensions. These need to be funded. Last I looked at L&G they held a chunk of BBB paper, probably desperate for yield. If there is a credit event, could be washed out.
But the wider theme is the never ending grind down in interest rates and bond yields. How will they fund future liabilities without traversing up the risk curve?
No question they look cheap, great yield, but as a long term investor I would need to answer these questions, which is hard. Requires a line by line run through their balance sheet and future liabilities, match them up, then run sensitivity to lower future yields. Internally, their actuaries would have done all this work, but I've not seen it released.
Most financials are in this trap now - look at Euro and Japanese banks, thanks to negative interest rates, dead.
But if bond yields stop falling, or even rise, yes, they will look like a bargain!
if things werent scary enough we now have a run on a large Indian bank (hands up who though it was going to be an Italian bank 1st)
https://www.bbc.co.uk/news/bus...
I really need someone to pat me on the back and tell me everything is going to be okay, say that this sea of red will end soon
Virtual pat on the back from me ambrosia. What doesn't kill us will make us stronger (probably not the best analogy right now).
I agree Timarr, it pays not to be myopic. S&p up 30% last year, down 11% from highs. Its all relative, some long term small cap holds look cheap as they are down 20%, but still up 200% over 5 years, there is potentially a lot of profit to be protected, ie sold down. If you look at the tech stocks, a lot of people have huge profits in these, not difficult to see continued selling down over big price falls to protect that profit.
So just a couple of thoughts for the day whilst portfolios are looking decimated.
1) I had a conversation with the CEO of a listed leisure firm last night. He was currently seeing no change to footfall in the many locations they operate in and business was performing inline with previous updates. Assuming this also holds then it seems a chunk of the massive hits to the leisure industry may prove to be a little premature. I note Cineworld (LON:CINE) said the same thing this morning. Probably similar story then for Revolution Bars (LON:RBG) (of interest to Paul).
2) China demand is recovering rapidly. Hotel bookings were up 40% from previous week and flights up 230% from the lowest recorded levels.
The excellent free daily email from Langton Capital says:
Starbucks yesterday said that LfL sales in its shops in China were down
by 78% last week. The worst week was week 2 of February and the group
has seen ‘sequential improvements’ since then. Starbucks said in a
conference call that its US business had not (yet) been impacted.
Starbucks is still paying wages to its staff in China. The company says
‘while the current situation in China continues to be dynamic, we
believe that the financial impacts of COVID-19 are temporary, and we
remain confident in the strength of the Starbucks brand and the
long-term profitability and growth potential of our business in China.’
... and ...
China tourist departures well down. Chinese departures to the Americas
are said to be down 63.2% over the last month or so on the same period
last year. Departures to all destinations are down by 55.9%. Visitor
numbers to Europe are down 36.7% per Forward Keys. Some 415k Chinese
tourists visited the UK last year, spending an average of £1,680 each.
Chinese number of tourists are down because the chinese govt. cancelled all the tours: "China has cancelled all domestic and outbound group tours until further notice as cases of novel coronavirus mount"
I don't think the problem is what is necessarily happening now.
I think the issue is that as the virus spreads (which it will to an unknown degree) and the circular flow of cash slows down by people working from home, projects being cancelled, holidays being postponed, etc.., then disposal income will go down, at least temporarily.
That, in my opinion, is when the retail/leisure/netflix sectors will start slowing down.
Of course, I could be completely wrong...
Abtan - the market is obviously pricing a lot of that in as it is "supposed" to be forward looking. Disposable income going down is possible but central banks and governments will be keen for that not to happen. To counter there will be interest rate cuts lowering mortgage bills and fiscal incentives such as tax breaks and infrastructure spending to ensure people have cash. The UK budget will be most interesting in that respect.
The problem is more what consumers do with that cash and fear is the big issue. We've created a monster panic out of this virus that breeds a self perpetuating cycle of economic misery. If people either hoard the extra cash from monetary/fiscal policy or stop going out that causes lots of problems. If they continue broadly as normal and don't avoid public spaces then the economic impact could actually be quite limited. That is why it is interesting to note that CEOs of leisure companies are not seeing a drop off in footfall yet. For me this is a key thing to watch. Similarly how fast does demand rebound post the subsidence of fear, hence the China hotel/airline booking stats. Quite quickly in the East it appears, but will it be the same for the West...
The market drop is what it is. I don't say that lightly as it has cost me a pretty penny but what I am looking for is the right time to buy in general. I am trying to avoid a "buy the dip" mentality, as this doesn't feel relevant to the current market conditions, so I am looking for other indicators.
Hi David
Agreed, the UK budget will indeed be interesting. though I really can't imagine what might be offered in this moment to change the path that we are inevitably on.
Interest rates are already low, so the impact on mortgage payments/loans will be limited (and will do nothing for those on fixed term mortgages).
As for fiscal incentives, that would presumably mean passing on responsibility to corporations, not individuals.
In any case, given the stretched public purse, I'm not sure what the government could do that wouldn't hit their own pockets at such a crucial time.
Irrespective of whether one thinks this panic is exaggerated, it is happening and it will affect supply chains/employment rates/spending.
It's an interesting assumption that people will still have cash to spend and jobs to go to. Based on my points above I would bet that disposable incomes will go down. I'm not even sure what people are going to do if they need to take time off for their kids when schools are closed.
I see some commentators saying that any decreased spending would just be a blip. I would agree as downturns are just blips in the long run.
I wasn't heavily invested in the markets in 2007-2008, so these market conditions are new to me. I always thought I would be a buy and hold sort of person in these situations, but I have realised I am not. I don't want to wait years for prices to return to previous levels and I personally believe that market sentiment is skewed downwards. I have accordingly adjusted my portfolio and given the upcoming US election and UK political events in the next 12 months, I don't think it's a badly timed strategy.
There will still be money to be made in the markets from 2021 and beyond.
Portfolio not looking great, second guessing my decision to sit on my hands. Off to bury my head in the sand for a couple of weeks (literally I am going on holiday).
Earlier this week there was a classic dead cat bounce, wishing now I'd sat on my hands.
We've just published a piworld interview with Michael Taylor, AKA ShiftingShares who swapped the day job for trading, in his 20's. Today, he's still in his 20's (just!). Beyond trading, he also writes about trading for Investors Chronicle, ShareScope and other publications. He's published trading books, and has run courses.
Hear Michael talk about his journey, his trading and views on markets generally. (This was filmed before the market meltdown, so although he's no doubt he's been busy at his screen, we miss his take on that).
https://www.piworld.co.uk/2020...
For the back catalogue of all piworld interviews see the Education/Interviews tab on piworld, or find here.
Hmmm. A 20 something day trader. If he is successful at day trading (when evidence shows most fail) why is rsorting to publishing books and running courses?
I might be being cynical, but this just sitnks of a BBC / Daily Mail style story of a 'how someone made it rich day trading FX' etc.
Where does it state he’s a day trader? Which he isn’t, by the way,
He says he does 5 to 10 trades in the average day, sounds closer to "day trader" than "investor" to me.
I wouldn't call myself a day trader (though I do scalp and close trades within minutes), but I'm definitely not an investor.
Some days I might be very active with 5-10 trades, and some days I might not trade at all. I don't want to force trades or boredom trade. Of course, if I don't trade, I don't make any money, but that is the nature of the business.
If Michael (shifting shares) started in his twenties, and is now 29, he has had the markets on his side for his entire trading/investing career. We may be better off judging his performance in a decade or so from now.
Fully agree with this Beginner.
It's easy to make money in a bull market (though the stats for trading from spread bet firms suggest otherwise), and I think unless you've been through a full market cycle it's hard to evaluate how good you actually are.
I have strategies that work now - as described in the video - but markets change and one has to adapt. What worked one year may not work the next.
I must admit I admire anyone who can make a profit, let alone a living, at trading. You need to be smart, diligent, and perhaps have the sympathy of the gods. I wish you very well for the future, and hope you are coping profitably with recent events. I have seen my profits for the last seven years disappear in a puff of virus!
That's a fair point Cranium.
I've been around on Twitter since 2015, and I haven't made a single penny from my books as I gave them away for free. You're welcome to download them fron www.shiftingshares.com and unsubscribe when you have them, and you won't hear from me again. Always open to constructive criticism.
Last year I ran three courses, which had 100% positive feedback. I may run another in future, as I think the current competition is mostly people selling £10k+ 'get rich quick' type courses, which I disagree with. Trading is not easy (as you point out most fail) and it's time consuming, and sometimes very stressful.
"If he is successful at day trading (when evidence shows most fail) why is rsorting to publishing books and running courses?"
My family's income is almost fully dependent on stock market profits, which offers zero security. I hope to be a Dad one day, and I'm told that having kids seriously depletes both energy and time. I have been withdrawing cash from spread bet accounts and ISAs now to pay our bills since December 2016 and having extra pressure is not something I want when starting a young family.
Any money that I earn from my articles on Stockopedia or elsewhere is money that I don't have to withdraw and can them compound even quicker.
"I might be being cynical, but this just sitnks of a BBC / Daily Mail style story of a 'how someone made it rich day trading FX' etc."
I did expose this scam in MoneyWeek. There is (sadly) no magic pill in trading. It requires effort, and places unique psychological challenges on people. How many people can say they've been to work for an entire month and say they've lost money? It's not nice.
Michael's a lovely guy, and very smart. But I think he needs to establish a track record before being quite so self-promotional. He knows I think he's cocky, because I've told him! We get on very well, he's a nice guy, so I'm not talking behind his back here.
But I think he needs to establish a track record before being quite so self-promotional.
I have said something similar :-)
Yes, reminds me of a certain chemist:
https://citywire.co.uk/wealth-manager/news/reality-bites-for-fantasy-fund-manager-as-manek-shuts-down/a1069811
You have Maynard, and since our conversation I've been thinking about how I can do this in a way that doesn't affect my trading or take too much time!
Thank you Paul - I know why you think that. I can have strong and cynical views, as a result of having been burned on AIM stocks in the past.
I lost a lot of money on 7digital, which I apologised publicly for those who may've bought it as a result of an article I posted. Since that conversation, I realised I need to be more open-minded about stocks rather than just assume they are bad first. It would've hindered me making money in future.
It's one of the reasons I enjoy speaking to yourself, and other people a lot smarter than I am. The investing community and the SCVRs here have helped me greatly, and it's one of the reasons I'll always attend Mello despite not being an investor - I like learning and I have a lot of it to do.
Re trading - I have to be brutally honest about my failings as I don't have a career to fall back on. There are a lot of things I need to improve on, and there always will be as the market changes.
My regret having watched the video back with Tamzin is that I could've said more about problems in trading. At one point, it placed great stress on my marriage. I messed up badly. It's not the glamorous lifestyle the Facebook and Instagram traders would like people to believe. It's an emotional rollercoaster.
Hello Michael,
It was good to read your comments and feedback on this forum.
May I make a suggestion or an Idea for all those traders who are promoting themselves or trying to help others (whether for profit or not). It would be great if you recorded your trades on a platform like the Stockopedia fantasy fund or something similar which are real time. I believe it would give so much credibility to their systems/methods when they are beating the index (or not) and PROOF that their ideas/methods/systems work. I know some do (Michael you may be as well) and good for you.
Having been around a while has made me more of a cynic particularity when it comes to the market but proof is proof.
Guy - I agree with you. I'm working on something with my developer that will give some credibility and plot some trades on my site. I used to post some trades on Twitter, but found this time consuming.
Full real time isn't possible for me, because by the time I post the trade somewhere the price will have moved, and it then becomes a hindsight trade. It's easy to post a trade when the price has already moved in your favour, or if you've sold before a profit warning after the event.
Buying something and then selling it a few minutes later (which I often do) means posting trades is impractical. I also don't want to be accused of pumping a price to sell, as my tweets have moved stock prices before.
There are also some trades that only work because so few people know about them. I'm happy to keep those to myself. Nobody else pays my bills, so I'm not obliged to give away any edge I've worked for.
However, I'm sure I can put something in place here. Yes, it won't include all of my trades, but then I'm not forcing anyone to read my free book or any of my articles either.
Thanks for responding.
First of all good luck and fortunes with your trading career.
The reason I raise the idea of real-time is many traders say they are making a profit/succeeding but very few actually prove it real-time rather as you mention post-trade/ backtesting or just saying it is so. Now many are not promoting themselves or their methods or charging anything and therefore in my opinion can do and say as they want. However, as you have exposed there are so many scams (or just people way over their head) in this sector from people charging or promoting a system - to them I say add credibility it will only boost you and help you stand out from the crowd and seperate you from the scammers/amateurs.
I certainly understand that day trading would be complicated and pricing would be off for real-time I am more thinking about swing-trading and long-term trading trades. For me personally if I was to one day decide to promote or sell my method - I would have no problem sharing all my trades real-time as my system has so many rules I doubt people would able to work it out correctly. I would of course put a large legal caveat that this is not advice etc. I also don't trade AIM so no fear of making a stock price move.
Finally it is important to reiterate (like you did in an earlier post) trading is HARD DIFFICULT FRUSTRATING there is a reason a vast majority fail.
Good idea but Fantasy funds are not available on the new site. Also you can’t match the prices, I find they have a wide spread on Fantasy funds and also they can’t deal with share splits. If you are trading many times a day I can’t see that working. Also 20 minute can make a big difference.
Yep fantasy funds are far from perfect and I hope they will be available on the new site soon.
Even so, for non-day traders (swing/long term) it would more than indicate if a traders method/strategy is working. Also doesn't have to be on Fantasy funds there is a least one member of the stockopedia community who shared their method/strategy on a live account as part of a challenge - to me it only re-emphasised how important this is and sometimes the difference between a method/strategy in theory versus the method/trading in real-time.
It is interesting there are many people promoting themselves as good traders with courses/seminars/books on how to help people succeed in trading. Maybe they are or not?
The reality is most traders fail (much better to invest long term first) and for someone who has been around for a while I don't believe any of of them unless they can prove their method or system works. For example, the fantasy fund function on Stockopedia is a nice tool (as long as you don't mix stocks from different countries) to prove or not your trading method works. Very few 'expert promoting' traders (there are some that do) are brave/silly enough to prove whether their methods or systems work real-time. And Ignore those that prove their system/method through primarily backtesting.
When was that filmed, I'm fairly sure I have seen it before.
I enjoy Michael's Stockopedia articles. I hadn't considered the difference between investing and trading before, being mainly an investor myself; I really appreciate another view point / outlook. My biggest mistakes so far have been getting purchase timings wrong I.e buying at a peak to then watch the price drift back. Some of Michael's approach with charting can help with this :) (Fingers crossed)
Gold and gold miners holding up pretty well. Will gold break through $1700? interesting times
Will gold break through $1700? interesting times
Perhaps the most interesting aspect of the gold trade is the widening gold-silver ratio. It's only ever been this high once before (well, at least in the last 50 years).
timarr
Perhaps the most interesting aspect of the gold trade is the widening gold-silver ratio. It's only ever been this high once before (well, at least in the last 50 years).
Any idea why? I have no interest in gold, but if I had to guess I'd say this is very probably another skewing of historical norms caused by the popularity of ETFs ?
All the best, Si
Any idea why? I have no interest in gold, but if I had to guess I'd say this is very probably another skewing of historical norms caused by the popularity of ETFs ?
Hi Si
Into the realms of guesswork - but in times of heightened uncertainty gold is the defacto safe haven, so money pours into it. Silver is the poor relation and gets less of the stupid money, but eventually the ratio normalises - either because gold prices revert or silver moves up. Given that the current situation is likely to continue to generate scary headlines for some time to come I don't think gold prices will drop much.
I take the point about gold - it's an unproductive asset, but I find its contracyclical properties make it a useful place to park cash in a crisis while I wait for stock prices to become "interesting".
timarr
Gold/Silver Ratio
Silver also has a lot of industrial applications so the ratio is also flattered by a drop in the expected demand in the event of a slowdown: the ratio therefore is indicative of both a flight to safety (gold) and a negative indicator of economic activity (silver)
As and add-on , and given many people are not keen on owing shiny pet rocks or their ETF/ETC derivatives, below a plot of outperforming gold miners in 2020
Petropavlovsk (LON:POG) announced yesterday it is moving from AIM to the FTSE 250 so that will likely get a boost as funds and trackers buy into it
Highland Gold Mining (LON:HGM) carries a nice divi and an SR over 90
Neither are appropriate if you have an aversion to companies with Russian operations
I take the point about gold - it's an unproductive asset, but I find its contracyclical properties make it a useful place to park cash in a crisis while I wait for stock prices to become "interesting".
Well, I'm not a sophisticate like you :-) I am happy to hold cash whilst waiting. Currently 35% and increasing :(
Unilever (LON:ULVR) is up a smidge today as I write. It's acting more like a bond but I can't believe we won't get a P&G type warning from them at some point. Interesting to also note Fundsmith is only down 0.3% ytd.
All the best, Si
Unilever (LON:ULVR) is up a smidge today as I write. It's acting more like a bond but I can't believe we won't get a P&G type warning from them at some point. Interesting to also note Fundsmith is only down 0.3% ytd.
Unilever (LON:ULVR) is down 16% from its year high. Finsbury Growth & Income Trust (LON:FGT) as a proxy for the Lindsell Train trusts is down 15% from its high point, Buffetology dropped 11% last month. But we know quality companies have been trading at high earnings ratios relatively speaking, a bit of reversion isn't making them cheap - yet.
The PER on the FTSE All Share went well under 10 during the GFC, it's still over 15 as we speak. So far this isn't even a proper correction. At this point the market looks, roughly, fair value with the odd inexpensive looking thing - M&g (LON:MNG) looks wrongly priced, for instance. and some of the other fund managers are beginning to look interesting. But it ain't particularly cheap unless you're prepared to take a deep breath and look at travel related stocks.
timarr
Very good article in today's Times setting out the disgraceful financial engineering that was a major factor in Flybe's collapse, and why the Govt was right not to inject any funds.
See: https://www.thetimes.co.uk/edition/business/flybe-failure-blamed-on-u-turn-over-100m-loan-nrrbnrxqd
I think they have set a marker that indicates that companies that suffer near terminally from Covid-19 fallout should not expect Govt bail-outs.
Also this as well, even more damning:
https://www.thetimes.co.uk/edition/business/flybe-owners-didn-t-bother-to-prop-it-up-09slmhwhq
The bearded billionaire, mega cap Delta (last reported annual profit c$5bn) and NY hedgie wanted £100m from our pockets rather than funding it themselves. Tells you all you need to know about its viability.
Very bad news for the pension fund members however as they're not covered by the UK scheme being IoM registered. They are far more deserving of assistance than the bearded tax exile and US investors who were only ever really interested in the LHR hubs and did a hatchet job on the previous owners last year.
He is well known tax scammer, going back to his early VAT at the start of his career.
My morning smallcap tweet: ASH to ashes?
Ten Lifestyle (LON:TENG) Ashley House (LON:ASH) Rurelec (LON:RUR) Hawkwing (LON:HNG) Immedia (LON:IME), PCF (LON:PCF)
Ten Lifestyle Group (TENG) H2 trading - rev miss but adj EBITDA breakeven, in line with the Board's expectations. Covir-19 may impact near-term general marketing spend and initiatives, as well as the timing of client launches. Guides FY rev miss but operational efficiencies to mitigate the impact on adjusted EBITDA.
Ashley House (ASH) suspended as subsidiary F1 Modular unable to pay creditors, applies for administration. ASH still seeking funding.
Rurelec (RUR) received a further US $1.44m owed by Patagonia Energy. Possible (likely!) hit from Argentinia ruling that co will be linked to Peso not $, for gas turbines generation. Other rev unaffected.
Hawkwing (HNG) suspended as it has failed to make an RTO in time to eet cash shell rules.
Immedia (IME) wins IKEA contract extension.
In line: PCF (LON:PCF)