Small Cap Value Report (Fri 6 May 2022) - SDI

Good morning, thank goodness it's Friday!
Agenda -
Sdi (LON:SDI) - a positive trading update, and forecasts are raised. This buy & build group is delivering very impressive performance. It also sounds upbeat about the outlook for FY 4/2023. This looks an excellent long-term investment, in my view.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Sdi (LON:SDI)
173p (up 15% at 09:49)
Market cap £177m
What a pleasure to be reporting on some good news for a change!
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing and control applications, is pleased to provide an update on trading for the year ended 30 April 2022.
Here are the main points -
Subject to finalisation of the accounts and audit, we expect revenues and profits for the year to materially exceed current market expectations1. Sales are expected to be approximately £49m (FY2021: £35.1m). We expect organic sales growth2 for the year to be in excess of 20%, which further builds on last year's 19% organic growth…
Adjusted Profit Before Tax3 is expected to be at least £10.5m (FY2021: £7.4m). We also expect to report very strong operational cashflows, significantly ahead of market expectations.
1. Analysts from our Broker finnCap Limited and from Progressive Equity Research regularly provide research on the Company, accessible from our website, and the Group considers the average of their forecasts to represent market expectations (prior to this Trading Update) for FY2022 being Revenue of £46.65m and Adjusted Profit Before Tax of £9.65m.
How about that for clarity, excellent stuff!
This translates into 7.6p EPS (Finncap), or 7.9p (Progressive). I’ll go with 7.9p, since that effectively comes from SDI itself, via a commissioned research company.
That gives us a PER of 21.9 - expensive in a bearish market, but I think the excellent performance deserves a premium rating.
Acquisitions - 4 have been done since Dec 2020, and today SDI confirms all are doing well.
Ukraine/Russia - no material exposure.
Outlook for the new year, FY 4/2023 also sounds excellent -
…we expect FY2023 to be the Group's best year yet, also ahead of current market expectations.
My opinion - this looks really good, and there must be solid reasons for the company to be so bullish on the new financial year that has just started.
I very much like the strategy at SDI, buying high margin niche businesses, it reminds me increasingly of Judges Scientific (LON:JDG) which of course has been a fabulous share over the years.
Shareholders must be delighted with today’s update, and today’s update seems to remove the risk of a 30-40% lurch down on a profit warning, which we’re being hit with at the moment in increasing numbers.
Overall, SDI gets a solid thumbs up from me, I think shareholders are likely to continue doing well, taking a long-term view.
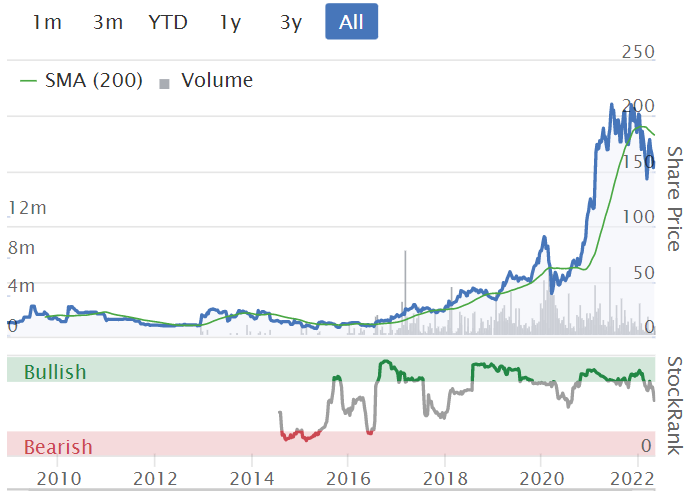
Fantastic chart, and note the high StockRank too - likely to increase once higher forecasts feed into the data -
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
According to Sky News, Morrison's have secured Mccolls. Good news all round I think. Importantly for contributors to the Mccoll's pension scheme who will avoid getting shafted. Also it would appear for Smiths News (LON:SNWS) and Supreme (LON:SUP) shareholders.
Shares will bottom before the outlook does. Nothing is obvious, neither where the economic or stock bottoms are. But for sure inflation will be transitory...but in the meantime there is no doubt re inflation spike. The only way inflation will not be transitory is if a strong and durable credit creation cycle takes off pronto....anyone see one?...
Can you translate that into English by any chance Mojo ?
Well is this an opportunity to add to Smiths News (LON:SNWS)? It appears that Morrisons have agreed to clear up the mess left by Mccoll's Retail (LON:MCLS), including its debt?
Looks it's Asda from what I can see. I guess we'll find out more on Monday. In any event I think Smiths News (LON:SNWS) will be able to recovery a decent chunk of what they're owed and very unlikely they will take the full £7m hit, so could be a buying opportunity if its doesn't recover first thing.
Yep, Morrison's approach has been rejected and the new Asda owner's have made an approach. Current news is that if successful they will take on the £170m debt, but they don't want assume responsibility for the two McColl's pension schemes. I agree that Smiths News (LON:SNWS) are likely to recover all or most of the debt.
The situation with McColl's does appear at odds with what was said in the recent Smiths News (LON:SNWS) webinar where when asked about its exposure to McColl's, Paul Baker, the CFO replied that there were being paid on a weekly basis in line with their expectations. This appears very much at odds with today's announcement.
Anyway assuming McColl's is kept afloat, which appears likely it will need to sell newspapers and unless there is an agreed arrangement on debt I can't see anyone supplying them. The only other UK newspaper distributor is John Menzies which is in private ownership. We shall see what the weekend brings?
Anyone know why K3 Capital (LON:K3C) sold off so suddenly today? Another buying opportunity to add to the list?
Mccoll's Retail (LON:MCLS) Just gone into administration says the BBC.
Heads up - if anyone holds Paypoint (LON:PAY) that you should sell now as the shares will go lower once they release a statement.
They will be impacted by the McColl's administration.
Smiths News (LON:SNWS) - news out that they have £6-7m in bad debt exposure to £MCLS.
Just when you think the week couldn't get any worse. How an earth did they allow MCLS to run up so much debt given the obvious problems they are facing?
Some interesting valuation charts here. US has been overvalued historically for a while. Some of that hot air coming out now if, and it's a big if, forecasts are met. US has a much more robust/dynamic economy than Europe so I can see the reasoning for higher valuation. Does make you wonder why supposedly professional investors/funds were happily buying UK shares at multiples of 30 or 40x as supposed long term holds.
Whats a reasonable multiple in a high inflation environment is the question. UK shares with steady growth im generally only interested in 10x or under. 10%+ Growth 12-16x .
Retail investors heading for the exit door.
S&P ETFs are so popular now I wonder what the effect of panic selling would be. Can't remember them being such a large factor in 2008
Just to keep things in perspective the S&P has only fallen by around 14% after a huge rise in the past 18 months. Average bear market 100+ years is 37% decline.
Tech mega caps are distorting things tho as many companies have already dropped more than this.
Looking at a few random fund types, it does make me wonder why I bother devoting so much of my time when I could just drip feed into a vanguard S&P ETF. I suppose we all love finding that nugget of gold, and it keeps us going.
"Tech mega caps are distorting things tho as many companies have already dropped more than this."
As is the case in most bear markets. Breadth declines before the headline indices. In 1999 tech names kept the US headline indices going for over a year while the majority of stocks fell. Market watchers seem to call this "narrow leadership".
And right now, breadth in the S&P500, as well as FTSE100, FTSE250, and AIM are all quite low.
The problem is that conventional wisdom says to rotate into bonds when stock market breadth is declining or low. But....
Even gold hasn't been doing as well as it would have done in past market drops.
Where is safe to put one's money right now?
Wine and woman?
I think it depends on what you mean by "safe" and how long you'll leave it there, but I like the thinking behind the saying "do more of what's working and less of what isn't". Over the last few months my portfolio has moved towards: cash; selected commodities, agriculture and oil and gas names; infrastructure; REITs, particularly non-cyclical and other non-cyclical sectors such as Defence and Health incl. Pharma. Some of these are not "safe" (e.g. the oil price is probably near cyclical highs) but there are other reasons for holding them, including how they hedge other parts of my portfolio and personal risks, and the optionality they provide me if things go very badly.
Looks a bit like some of my returns YTD! Interesting thought on ETF investing and tech mega caps. Yesterday a number of NASDAQ constituents fell by c. 5% including £AAPL and £MSFT. These represent over 40% of the holdings in £IITU ETF. Overall the top 10 holdings in this ETF representing 67.5% of the funds value were down by a weighted average of 3.6%. However, the GBP version of £IITU was down less than 1%. It is probable that the remaining third of the value of the ETF went down by more than 3.6%. I assume this discrepancy between the price performance of the US constituents of this ETF and its UK price must be down to the falling pound as I can’t think of any other reason unless someone can put me right!
Yup, falling pound. $1.25 compared with ~$1.35 a month ago.
Supreme (LON:SUP) is one of those shares (as mentioned by jonno) where you wonder why your perception is so different to that of Mr. Market. This morning they hit a new low - presumably as a result of the situation at Mccoll's Retail (LON:MCLS) yet the company answered this in their recent presentation - here is the answer to a question on exposure.
As for Mccoll's Retail (LON:MCLS) Paul said here "...as we expected, the company finally admits that existing equity is worth "little to nothing"."
Following rumours of administration yesterday the company put out a statement after close concluding:
"However, whilst no decision has yet been made, McColl's confirms that unless an alternative solution can be agreed in the short term, it is increasinglylikely that the Group would be placed into administration with the objective of achieving a sale of the Group to a third-party purchaser and securing the interests of creditors and employees. Even if a successful outcome is achieved, it is likely to result in little or no value being attributed to the Group's ordinary shares.
This morning the rumour on Sky News is that Morrisons would take over which should actually boost the Supreme sp following the answer given in the presentation.
£mcls
Beeb has just announced that they have been placed into administration
Hi Sharw
You beat me to it. Yes it appears that Morrison's have agreed to acquire Mccoll's Retail (LON:MCLS) including taking on its pension and debt. Positive news for Supreme (LON:SUP) and Smiths News (LON:SNWS), even though the former confirmed in its recent trading update webinar that it was not directly exposed to Mccoll's Retail (LON:MCLS) and such exposure was indirect via Morrisons.
Hi
Apologies up front this is not a small cap.
I thought it might interest some that the badly delayed prelims for 2021 of S4 Capital (LON:SFOR) are out today.
Scanning comments on today's SCVR thread with regard to buy & build company Sdi (LON:SDI) and the discussions about revenues for £ITV (directly associated with advertising spends) it seemed reasonably fitting to mention S4 Capital (LON:SFOR) as it might present an opportunity for some (who like buy & build, advertising, innovation and digital plays).
The share price has been falling from an ATH 870p (29/09/21), to a low of 289p (31/03/22). On 29th March S4 Capital (LON:SFOR) failed for the second time to deliver its prelims. Auditors would not sign them off. The price fell from 482p to 289p over 2 days.
Finally today, S4 Capital (LON:SFOR) has presented its report ...
The (rather badly formatted) RNS is here https://www.investegate.co.uk/...
The full report, much more readable is here https://www.s4capital.com/data...
On notice of these results being released yesterday the SP rose +17% and is +5.28% today as I type.
A key message to note, I think, the share rice fall is therefore not a profit warning (it might have been), but instead its a weakness in operations which is entirely fixable. So, not a falling knife I would argue.
S4 Capital (LON:SFOR) is very much following an aggressive a buy & build strategy. Perusing the goal to disrupt the global legacy advertising agency model. By becoming leaders in advanced marketing and advertising technologies.
They are targeting a 25% annual growth rate.
I expect S4 Capital (LON:SFOR) is of little interest to most SCVR readers but some who favour growth, innovation and technology led companies might be interested to assess if the share price declines might offer a point of entry which is not as eye watering as it used to be.
It might also interest some that Martin Sorrell has stated he would also like to list S4 Capital (LON:SFOR) in the US which would open it up to a very large investor base and other large institutional investors.
The current Stock Report is not attractive so very much a DYO on the stock.
I hold a small amount and lost quite badly in my trading in the past months. It is volatile as newly listed growth stocks so often are.
Will it become a British success story and bring new life back into the FTSE, I have no idea, but have cautious optimism as several ingredients for growth do seem to be evolving quite well.
Regards
Howard
Thank you Leebod, timarr, cmpeckham & jonno for your very interesting comments on £ITV.
My average price is 64p having bought over 50% of my position in July 2020 at 61.5p.
My feeling has long been that the "big boys" have been manipulating the SP and that eventually Itv (LON:ITV) will be bought out but I guess it may happen when we least expect it.
The Dividend of 3.3p to be paid on 26th May alone gives me a return of 5.16% so I am happy to continue to hold as I am prepared to wait and to sell at the current price makes no sense.
The reason I am a big fan of Stockopedia is the quality of the discussions on the SCVR.Long may it continue.
A macro comment. Skip if not interested.
John Authers' 'Points of Return' today seemed to me to be worth serious thought. Here are a few excerpts.
The bottom line is clear enough — elevated inflation and the growing
reaction to it in monetary policy are causing a steady increase in bond
yields and a steady fall in share prices. Along with that, we have a
rising dollar and rising commodity prices. How far we’ll go remains in
doubt, but the direction is as clear as ever, even after two bizarre
days of trading.
This brings me to Jeremy Grantham, the founder of the fund management group GMO. Last year, he made the bold call that markets were in a bona fide bubble and cruising for a fall. I talked to him after markets closed Wednesday, and at first he sounded philosophical. “So far this year, I was very impatient about the market,” he admitted. “I couldn’t believe how slowly it was coming down, and how vicious the rallies were, and I was trying to explain it.”
Grantham noted continuing signs of speculative excess, and the fact that many American investors still had piles of unspent cash burning a hole in their pocket. But standing back to view the bigger picture after Wednesday’s big rally, he could see he was missing the context. “This was the biggest decline of the S&P in the first four months of trading since I was one year old, in 1939,” he said. “There’s a huge gap between perception and reality. The reality is that this is about as rapidly as any market comes down. And there are no rallies as spectacular as bear market rallies.”
Back in the summer of 2007, Grantham warned that the stock market was like a brontosaurus, whose brain and nervous system were so inefficient that it would take a long time to realize that it had been bitten in the tail. Sure enough, subprime lenders began to go bankrupt in early 2007, and the stock market didn’t collapse until the fall of 2008. This time around, sauropod stocks are still taking their time to adjust to rising interest rates and high inflation. But they’re getting there.
Inflation is the fascinating point. It wasn’t at all unreasonable for the world to take a long time to grasp last year that inflation really was back. It had, after all, been absent for four decades. A spry octogenarian like Grantham has direct experience of investing when consumer prices are rising — but nobody much under the age of 60 has ever had to deploy assets in an environment of high inflation before.
This helps explain why the stock market kept rising until the turn of last year, even though a spirited debate over inflation had been running since the spring. It took that long for investors to realize that they had “returned to the 20th century,” as Grantham put it. “Prior to the 2000s, inflation was always in the background. It was always part of the discussion. And then it began to disappear.”
... when inflation rises, investors require a lower earnings multiple before
they buy stocks. This time, p/es began to correct as inflation took
off, although much of this was an attempt to unwind the excess caused by
the pandemic. If inflation cannot be reeled in quickly, history
suggests that multiples will have to fall much further ...
This is about the USA, but my experience is that UK share prices often follow US prices, so I'm capitulating on some serious losses today. So long as I have cash, I can rebuild.
Yes i like the dinosaur analogy. It seems that people haven't thought through the implications of higher interest rates. They have to be high enough to cause a substantial drop in demand. Only then will firms reduce margins and prices. But the consequence is lower profits and higher unemployment. Things have to be tough before inflation is defeated. But a recession can't be good news for the market.
"It seems that people haven't thought through the implications of higher interest rates. They have to be high enough to cause a substantial drop in demand."
This is the opposite of what the Bank of England have been saying for a long time and repeated again yesterday. The BoE have consistently portrayed inflation as transitory - they still do, just lasting a lot longer than was thought a year ago. They emphasised that in a supply crisis, macroeconomic tools can do little to solve the problems. A key component of this thinking is that inflation (of the supply driven kind that we are experiencing) itself destroys demand without the need for much higher interest rates. They may be right or wrong, but they disagree with your statement.
Apparently the brontosaurus brain was primarily engaged with sexual reproduction, I never attended any BOE Covid Parties so cannot possibly make further comment.
Appreciate you putting this up FREng. I would add that the Bank of England's comments were fairly clear and there have been harbingers of doom for quite a while now. There remains a problem with where you put your money but the general direction of the market seems clear for now.
Ive made some poor investment decisions based on macro reports. Im not saying that its wrong or that investors might want more cash on the sidelines but equally don't just sell everything because the macro outlook is poor.
Im sure there is a lot more pain to come but I'm not heading for the exit yet.
"... don't just sell everything because the macro outlook is poor."
Indeed. In fact, buy as much as possible when the outlook is at its worst, because things will improve from there.
But, history shows that when the first derivative of the macro outlook is very poor, then it is indeed a good time to sell.
It must be one of those wait-to see days today.
Seeing as it's a quiet day can I ask a question about ETFs. Can someone explain to me firstly how a specialist ETF decides which companies fall within their remit and secondly how they allocate resources between their chosen companies. I guess the answer will be that every ETF makes up its own rules but it would be interesting to know if there are broad underlying processes. ETFs are promoted as being cheaper than Trusts and not subject to the whims of a fund manager. But I have been surprised by some of the companies which were included in particular ETFs and wonder if the mangement is as passive as they claim. Thanks for any comments.
Usually ETF's track indices. So to take £ISPY as an example it says
The fund will seek to track the performance of the ISE Cyber Security® UCITS Index Net Total Return, being an index comprised of equity securities issued by publicly-listed companies from across the world that are actively involved in the cyber security industry.
This is partly why there are so many indices. They are often created because there is a demand from ETF suppliers for an index to track. As you have seen it's best to check what companies are in the index to see what you will actually be buying.
A number of subscribers have commented on their portfolio losses this morning so I thought I would briefly summarise my experience.
Since early August last I am 25% down hit by Boohoo (LON:BOO), Saga (LON:SAGA), Ferrexpo (LON:FXPO),Polymetal International (LON:POLY), and big falls in my two largest holdings Entain (LON:ENT) and £ITV.
However during that period I have sold Reach (LON:RCH) & Redde Northgate (LON:REDD) which proved that for once I got my timing right banking nearly £36k in profits.
I am confident Entain (LON:ENT) will be taken out by a US buyer in the next 2 years but Itv (LON:ITV) is a real brain teaser. I would welcome any views on Itv (LON:ITV) which has fallen from 130p to 70p in a short period.
I have held ITV for about 5 years and every time it shows signs of recovery I end up buying more saying this time it's different; it then issues a warning and I'm down 30% - it's always on the takeover list but it never happens. I'm refusing to sell as I sit on the current 30% loss but next time, definitely next time I will sell as soon as I see green. In the meantime a yield of 7% at the current share price will do - that nearly covers inflation. sigh. My commiserations.
I would welcome any views on Itv (LON:ITV) which has fallen from 130p to 70p in a short period.
I've been giving this a great deal of thought because it's one of my larger holdings (albeit significantly smaller than it was). No matter how I twist the numbers I can't see how the current valuation makes any sense.
Clearly the £3 billion or so mooted investment into ITVX has spooked investors, but what do they expect? The unwillingness of UK institutions to invest in growth at the expense of companies being overtaken by more far-sighted competitors is legendary, but this seems especially stupid. And in any case the investment isn't guaranteed and will clearly be cut back if conditions require it.
Obviously the recent Netflix numbers provoked some concern (but those numbers weren't particularly bad, they just weren't what the market wanted). However, if people stop watching streaming channels they'll be more likely to watch free-to-air channels, so that doesn't seem particularly negative overall.
Then we have a looming recession which will hit advertising revenue - but, again, if ITV has more eyeballs it has a better chance of driving viewing numbers. Plus people will tend to go out less. But still, a recession is usually not great for broadcasters.
Then there's the potential bid for Channel 4. Again, more investment, probably dilution to fund it. But again, probably positive overall.
Finally we have the Ofcom review of the Channel 3 licence due in 2024, with their initial report out next month. It seems likely that there'll be a requirement for UK PSBs to be given prominence on the major streaming platforms, which again will help ITV. It also opens up the possibility of ITV handing back it's PSB licence - which would have all sorts of implications, but would definitely put it into play. ITV has a strong hand in negotiations with Ofcom, so it'll be interesting to see the proposals next month.
Overall I can see why the ITV share price is depressed but the current price at less than 70p really doesn't look right. IMO.
timarr
"However, if people stop watching streaming channels they'll be more likely to watch free-to-air channels, so that doesn't seem particularly negative overall."
This appears to be a leap of faith.
UK TV viewing (minutes/weeks) has been in an inexorable decline since 2011:
The bounce in 2020 is arguably a result of tthe first UK lockdown - we may have to wait for 2022's numbers to confirm this.
On top of this we had Reach (LON:RCH) yesterday highlighting print advertising falling by 10.1% in the last four months.
Give the inherent operationalgearing at Itv (LON:ITV) , 2022/23 forecasts may prove optimistic.
RE: Itv (LON:ITV)
This appears to be a leap of faith ... UK TV viewing (minutes/weeks) has been in an inexorable decline since 2011
It's a fair point, but at the same time UK online TV revenues have been rising inexorably:
Seeing some swapping of online minutes to free-to-view minutes doesn't seem unreasonable.
However, you're quite right that the operational gearing means that a drop in advertising revenue will disproportionately impact profits. We've seen profits wiped out in previous recessions, so yes, current forecasts could easily be too optimistic.
timarrI too am an Itv (LON:ITV) holder and have been thinking whether to top-up or sell out. Still on the fence at the moment.
I won't rehash all the bull and bear points that have been well covered by others already - but it still strikes me as good value even if you expect a decrease in profits.
Even if you chop off -30% off FY22 EPS forecasts (and bear in mind we already had a good Q1 trading results in the bag), its still only at a 7.35x PE, with a 7% dividend with a still-healthy dividend cover.
I think M&A is a very slim chance now. Most media groups already have debt, so any strategic acquirer will need to fund it with fresh debt, which probably isn't forthcoming for Media M&A at the moment.
So I'm still mulling whether to sell or buy more. But in the meantime, I rest in comfort that the current valuation isn't too demanding, the debt load is manageable and long-term secured, and the dividend will provide me some inflation protection this year. There are worse areas to park my money.
(I Hold)
I would agree with many of the positive things said about Itv (LON:ITV), but I don't see any need to rush in and buy. As with many UK shares, a look at the chart would suggest that now is not a great time to buy. It's also worth keeping in mind that despite all the focus on new media, they are still dependent on consumer advertising, and the outlook for the consumer is dire.
I also think that concerns about their long term future competing against the likes of Netflix and Amazon are legitimate. There are too many unknowns about how this market will play out. In a battle with these giants of modern media, how will ITV fare? How many streaming services will the average consumer keep in future? Will this market, as with so many others, be dominated by 2 or 3 players, with the rest just being a long tail? Even the winners will struggle in the new landscape as Netflix showed recently.
Despite all of that, I think there is a lot to like about the company. My bet is that the shares will find a level from which they can prosper, I just don't think we're there yet.
Morning Portugull
I have a portfolio of 27 stocks and run slightly smaller portfolios for my wife and daughter. The last 3 months have not to put to fine a point on it been torrid. I would estimate that I am down 20% from last August. My approach is ordinarily to buy and hold, which I did through the pandemic and within reason will continue to do. I remind myself that at the height of the pandemic my portfolio was down 40% and some 15 months later had tripled in value from that low point.
I look at share prices of companies like £RBPG £VLX K3 Capital (LON:K3C) and Supreme (LON:SUP) and think even allowing for the dire economic situation, I am missing something, or has Mr Market lost the plot. I also think is Smiths News (LON:SNWS), now financially stable, only worth a PE of 3.5 and 10% yield, despite operating in a declining market.
Anyway on to the reason for my post £ITV I have held it for 3 or 4 years and it has been a poor investment, in large part due to my inability to recognise the transition of advertising from linear to digital the rise of streaming as an entertainment media.
I have done a little selling and buying in the period. I added at 59p during the pandemic and sold some at 112p. From memory; I tend not to look at my portfolio, especially when there is a sea of red, my average price is 120p. The recent prelims were very good and I was surprised by the market reaction. I continue to hold, the reason being that ITV Studios that has made some excellent productions such as Line of Duty and the enormous back catalogue are in view worth substantially more that the current share price. The rest of the company free to air advertising, Britbox etc that have value are in the price for free. I would add that the company is financially stable and pays an attractive dividend.
On the downside I am not sure that spending a kings ransom on the upcoming ITVX is the way to go. Also advertising revenue will no doubt fall given the economic outlook, still the forthcoming World Cup should be positive for it. What will be he catalyst for change? Perhaps the acquisition of £STVG (LON:STVG) or possibly Channel 4, or ITV is eventually bid for. All three options may encounter competition/quasi political issues. In truth I don't know, but in time something will give, no doubt when one least expects it.
On the media front, which is on a roll in the UK, I also hold Vitec (LON:VTC) and Facilities By Adf (LON:ADF)
Whilst the markets are grim and my portfolio looks like a dogs dinner, at least I am not at risk of being shot or bombed unlike the poor people of Ukraine. Such a senseless conflict.
To quote George Harrison, all things must pass.
All the best
If you strip out O&G stocks much of everything else seems to be in a downtrend. The bounce back after Covid was probably overdone - maybe the climax top of a long bull market. Decent results (eg VLX) are getting sold into. I have come to the conclusion that there’s no point holding stocks in this environment.
Like many, i am down substantially. But it is important to focus on the process not the outcome.
I think my procedure is correct; diversify over 30 shares, look for QM and VM shares. Hold for a reasonable period, i use 6 months. Don't sell or buy on a sudden drop or rise in price. Diversify over different investment strategies. Take a long term view, i am investing for the next 20 years, not just this year. Keep your sense of humour!
Morning Paul, guess you'll happily cover SDI trading update. A great read in these difficult times for small companies. Update for current year was uplifting ,one of those, 'better than expected .' RNS's . For me the highlight was, the 2023 comment :- ' Ken Ford, Chairman of SDI, commented: "We have executed again on all facets of our buy and build strategy, delivering record performance in FY2022 and setting up what looks like another record year in FY2023.". Look forward to your take Tony
Slightly odd that another company Ken chairs, Cmo (LON:CMO) , has also reported today. Also broadly reassuring, tho' I can't find any forecasts to compare it against.
Yes, another Tin Hat week with all my shares becoming even better value :-)
Although it seems to me that the howls of the bears are now dominating discussion, I don't' think we're at the turning point yet. But the one thing I do know - is that I have no idea of timing. Never been good at it.On the flip side - I seem to be surrounded by amazing bargains on all sides. Shame I don't have fresh funds to put in now. All I can do is work even harder to research, analyse and challenge my assumptions - improving the portfolio of companies in which I hold shares, both to survive these difficult times and to benefit from the upside - when it arrives.
Good luck all
Mark
The property is a Leasehold so they may be paying rent to the Freeholder meaning the yield is not as high as the £300k pa income suggests
If it was valued at £1.5m when interest rates were say 0.5%, then with interest rates at 1% and rising, £1.75m may not be good. Either way it is still £1.75m !
I meant "may not be bad " ie Good !
Unbound Group property disposal looks strange .
Anyone know the property disposed of ?
Selling a property with a blue chip tenant like Fujitsu with s yearly rent of 300k for 1.5 million looks strange.
Wish I could find commercial properties to buy paying 20% yield !
Could this be a sign of distress at Hotter ?
Unbound (LON:UBG)
That property is leasehold so the income they were getting would have been for limited period of time only.
It's still 17% income for £UBG. I'd love to have an asset like that, even for only a year!
It's not though is it? (Genuine question, not sarcastic question mark). As andydil says, as a leaseholder, that GBP300k isn't staying in UBG's pockets. A big chunk of it will be going back to the freeholder. So UBG's yield would have been much smaller. Now they have some cash to reduce the bank debt, and/or help with new partnerships etc. (fingers crossed).
I'm grateful for the cynical view on this though, I hadn't thought of it like that this morning.
Cheers
Chris
Unbound (LON:UBG) must have a better use for the money. I hope it's not a sign of distress. The RNS says "The Factory was a legacy investment by Electra Private Equity plc and is not used for the operations of Unbound or any of its subsidiaries. Unbound will deploy the proceeds into continued development of the Unbound
platform and for general working capital purposes."
Per Stockopedia, most of their £25m cash is needed as working capital, so the extra liquidity should provide quite a lot of extra flexibility and may help avoid or reduce the use of available credit at a time when interest rates are rising.
The distress comment was more about the value achieved as opposed to the clearly correct commercial decision to divest of a legacy property .
300k yielding commercial properties do not sell for 1.7 million so the price achieved could do with some simple explanation .
The RNS is quite poorly worded and vague , the yearly income received by Unbound does appear to be 300k from the information tendered .
Having said that hard to give an explanation if it is a dash for cash distressed sale .
Don't forget, this is leasehold, so the sale is of the lease only, not the building itself. So it's a simple calculation of the rent, plus how long is left on the lease (including break clause). So it could be good value, bad value, we don't know without more info. The fact that the lease was valued on the books at GBP1.5m suggests it wasn't bad value, although that depends when the last valuation was.
Cheers
Chris
A great update from Sdi (LON:SDI) - I would welcome your thoughts Paul
Indeed, a very good update from Sdi (LON:SDI) . Organic sales growth up by 20%, adjusted
Profit Before Tax expected to be at least £10.5m (FY2021: £7.4m).
What I love about SDI is they always seem to under promise and then over deliver.
(I hold) but a wee bear case for Sdi (LON:SDI) is that they are being boosted by sales from their Atik camera unit for PCR testing. They forecast these would drop off this quarter but seems it hasn't happened yet, but sooner or later it will. I plan to continue to hold, but am tempering my joy at the lastest jump in the share price.
Sdi (LON:SDI) (no position)
Hi JCPr
You said:
"a wee bear case for Sdi (LON:SDI) is that they are being boosted by sales from their Atik camera unit for PCR testing"
This is what put me off buying over the last 12 months - the idea that the Atik Camera sales would be one offs.
I'm now struggling to understand whether the Atik orders are still one-offs in FY23 (as announced in January 2022), or if we should expect these annually for the foreseeable future.
In the last AR the company itself stated:
"There is no certainty of further orders once this contract has been fulfilled."
Note that:
I should also add that I'm put off my the large share issuance over the last few years, though I haven't looked at the detail for this so it might not be an issue.
---
On a less bearish note I'm wondering whether I should even care about Atik sales dropping post FY23. There have been a decent number of acquisitions in recent years, which will probably offset lost covid-related sales.
I remain on the side lines, but I must admit to being intrigued to see the detail in the final results.
GL all holders.
A
Sdi (LON:SDI) is currently up 15% today
Paul have I missed something ? I always liked your wider general thoughts on the investment world, boy do we need courage at the moment I bet many of us are nursing a plus 20% decline in our portfolio's value
Yes, I'm around 15% down from portfolio high of last autumn. Was 75% in cash until recently, have started tentatively buying these past few weeks, with mixed results! Even when something looks cheap it can still fall further in this market.
All about keeping your nerve at the moment, as hard as it is mentally.
Yes I seem to range from 10-15% down. A bit depressing. I will however sit tight. I think I own some good shares. I am confident they will recover. However, inflation will weigh heavy as will the Ukraine issue. I hope they can find a solution like the Ukraine agreeing to remain outside of Nato. We will see.
Ukraine cannot join Nato while they are involved in a conflict, or that used to be the rules. Maybe they should not have started shelling eastern Ukraine starting back in 2014, just because they dont seem to like the Russians and eastern Ukraine is mainly Russian speaking, although they share a border with Russia. Its certainly not a white or black scenario.