Small Cap Value Report (Fri 6 Sept 2024) - G4M, ASC, NFG, XPF

Good morning from Paul!
All done for today, and the week. Podcast should be tomorrow morning.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 26/8/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting

Summaries
Gear4music (HOLDINGS) (LON:G4M) - 186p (pre-market) £39m - AGM Trading Update - Paul - AMBER/GREEN
An in line trading update, with a generally positive tone. Shares have had a good run, but still look reasonable value, given improving trend of profits (from a very low base though). Chinese direct to consumer competition is a big worry longer term. There could be a bit further to go in this current bull run in G4M shares, possibly?
Asos (LON:ASC) - up 18% y’day 434p (£518m) - Refinancing, Topshop JV, FY 8/2024 Trading Update - Paul - AMBER/RED
Interesting deals announced yesterday - selling its best brand to a JV (retaining 25% ownership) to raise £118m, but will hurt profitability of course. Refinances super cheap 2026 bonds with expensive 2028 junk bonds, in order to reduce net debt and buy time, but at a large increased annual finance cost. TU is ambiguously worded. I remain negative on the fundamentals, and think equity could end up at zero, but there could be speculative upside, who knows?
Next 15 (LON:NFG) - down 48% to 427p (£435m) - Trading Update [Profit Warning] - Paul - BLACK/ AMBER
A savage market reaction, with shares halving on a profit warning concerning the loss of a major contract, and continued weak spending by public sector and tech clients. I don't have enough information to form a clear view, so it's AMBER whilst we await more information.
XP Factory (LON:XPF) - 13.7p (£24m) - IFRS 16 treatment of leases - Paul - AMBER/GREEN
This is postscript to my review here on 2/9/2024 of XPF's 15-month results. I had a chat with the company, who told me that IFRS 16 has penalised their profit by £1.5m compared with the old lease accounting standards. This is apparently due to opening lots of new sites, where the rules are harsher under IFRS 16 in the early years, compared with the previous accounting method. I asked for a reconciliation, as I don't fully understand IFRS 16 workings, which was sent to me by XPF's finance department. This is clearly material to the profits, so I thought it was worth repeating here -for your consideration & possibly comments -

Paul’s Section:
Next 15 (LON:NFG)
Down 48% to 427p (£435m) - Trading Update [Profit Warning] - Paul - BLACK/ AMBER
A spectacular fall from grace here. A previous high-flyer, this share roughly 47-bagged from the 29p 2009 low, to 1,376p in April 2022. Down to 427p now, we’re back at 2017 price, and fairly near the 2020 pandemic lows.
What does NFG do? I’ve never really been sure, and had it down as a PR/marketing type group. Its website includes this in the “what we do” section -
“...combining growth consulting with marketing services, data and technology platforms and business transformation projects – for companies like Alphabet, Amazon, P&G, Johnson & Johnson, Toyota and many more.”
There was a sign of possible trouble on 27/6/2024, when its in line AGM TU mentioned trading being “resilient, despite a tough macro environment”, and “delays in some clients’ spending, notably relating to government contracts… Spending across the Group’s technology customers has remained soft”.
It said an improvement in trading in H2 was expected.
That triggered a c.15% share price fall over several days, and with hindsight the sellers in late June made the right decision, as things are now much worse.
This is today’s bombshell -
“Contract non-renewal and trading update
Next 15 has been notified that the contract with Mach49’s largest customer has not been renewed after its initial three-year term and will now end on 31 December 2024. This contract had been expected to contribute just over £80m of revenue in FY26. While we anticipate that the client will continue to use Mach49’s services in the future, we believe it is prudent to materially reduce forecasts for the financial year to 31 January 2026. This will in turn reduce the earnout obligation to Mach49’s shareholders due over the next three years.
While the Group has seen strong performances from a number of its consumer-facing businesses, it has continued to see an ongoing weakness in spend from its technology customers as well as a reduction in revenues from its public sector clients.
As a result of these factors and the contract ending which will impact the last month of the fiscal year, the Board now believes FY25 revenue will be lower than planned, and profits to be materially below management expectations."
It’s important to note that NFG’s year end is 31/1/2025. So this major contract loss will only give a glancing blow (one month) to FY 1/2025, but knocks out a huge £80m revenue hole in FY 1/2026.
The StockReport shows forecast revenue for FY 1/2026 at £644m, so losing an £80m contract is losing over 12% of forecast revenue. Operational gearing means the impact on its profit could be much larger than 12%. It does raise the question of client concentration - often something that’s difficult to find out, unless you’re an insider - and a good question to ask all companies in their webinar Q&As. We should probably scrutinise the notes in annual reports more closely, and the risk warnings for signs of excessive client concentration risk, but how many of us have the time to do that in reality for the hundreds of companies we look at?
Results FY 1/2024 look very good - eg revenue £578m, adj operating profit £121m (a high 21% operating margin), and 81.6p adj EPS. There are some funnies in finance income & finance costs, relating to deferred consideration liabilities (earn-outs on acquisitions).
Balance sheet is goodwill heavy, with £279m intangible assets from previous acquisitions. That means NAV of £156m becomes a negative NTAV £(123)m. This also includes a deferred tax asset (unusual) of £62m, less deferred tax liabilities of £6m, gives net deferred tax asset of £56m. I tend to remove deferred tax, so that takes NTAV down to a concerningly bad £(179)m. So when NFG says it has a strong balance sheet, they’re certainly not looking at the numbers in a prudent way. They might be referring to liquidity, as its 31/1/2024 year end net cash was almost neutral: £42.9m cash, less £44.2m “loans & borrowings”, so only £1.3m of net bank debt. That means tons of headroom on the £150m+£50m HSBC facility.
However, there’s a sting in the tail. The balance sheet also contains substantial deferred consideration liabilities (earn outs). These are big numbers - let note 9 do the talking -
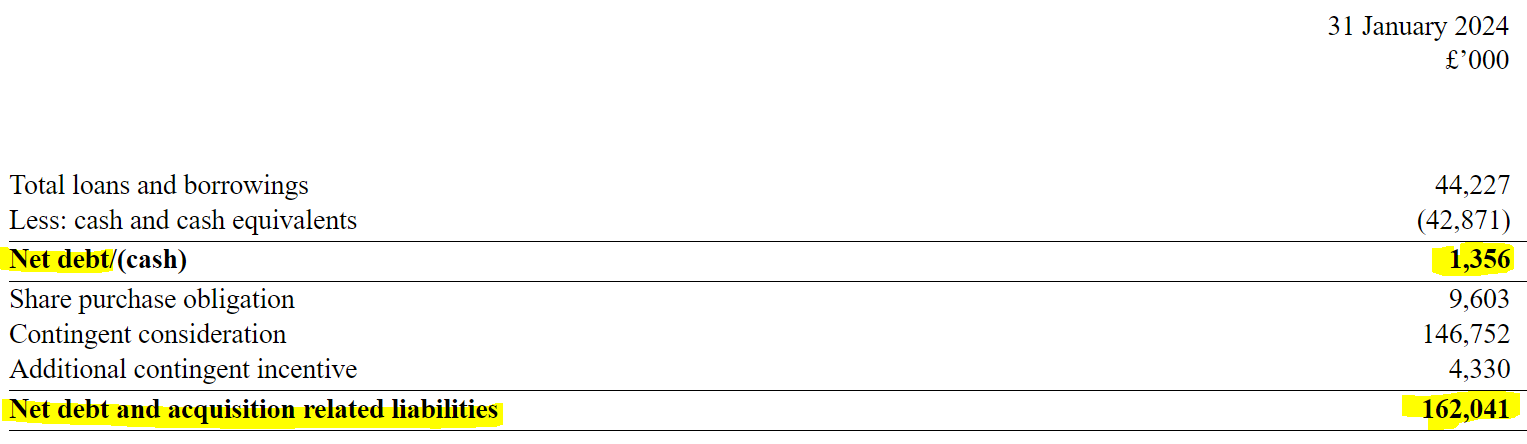
Although note the profit warning today indicates that the earn-outs will reduce, but we need to know by how much.
Broker updates - nothing available. We can’t possibly judge this without sight of revised FY 1/2026 forecasts. Losing 12% of revenue, which could be high margin work (we don’t know, but it’s a high margin group, so that stands to reason) could have a devastating impact on next year’s profit. Hence it’s not possible to value this share without the revised forecasts.
Key other information is by how much the earn-out liabilities are going to reduce? As they stand, paying those liabilities recorded at 31/1/2024 would theoretically use all of the available bank facilities. That probably won’t happen, because the amounts payable should now reduce after Mach49 lost this major contract, and the earn-outs are spread over several years, but we need an updated figure.
Paul’s opinion - all of this leaves the question as to whether NFG’s super profit margins depended on one big contract? How will the business look afterwards now it's ended?
Reduced spending by tech customers is also a worry, and reminds me of the point some are saying that massive spending on AI might be sucking cash away from other budgets at IT companies? YouGov (LON:YOU) delivered a similar devastating profit warning earlier this year, and is slashing overheads to rebuild margins. It looks like NFG will also need to slash its own overheads, which means redundancies seem likely unfortunately.
Without any updated forecasts, it’s impossible for me to assess whether this share is cheap after today’s 50% fall, or whether the fall is justified.
I don’t see any immediate risk of financial crisis, due to the neutral net bank debt position and plentiful facilities available. However, a lot depends on how much, and when the next earn-out payments will be, which could significantly increase bank debt.
Hence it all looks impossible to judge right now, due to lack of key information. So I’ll stick it in my “don’t know, awaiting further facts/figures/forecasts, but no insolvency risk for now” tray, so AMBER.
My profit warning data clearly showed that in the last year, the larger small-mid cap companies (c.£100m-1bn) which have savage profit warnings do tend to recover, at least somewhat. Whereas it's the sub-£100m profit warnings which usually continue falling. So I think there's a chance both Next 15 (LON:NFG) and YouGov (LON:YOU) could be interesting potential trades, worth doing some further research on.

Asos (LON:ASC)
Up 18% y’day 434p (£518m) - Refinancing, Topshop JV, FY 8/2024 Trading Update - Paul - AMBER/RED
Trading Update -
“ASOS expects FY24 adjusted EBITDA at the top end of consensus estimates2, sales slightly below guidance, and all other guidance as set at FY23 year end remains unchanged.
2 Company-compiled consensus, as available on ASOS Investor Relations website.
Extract from Asos website -
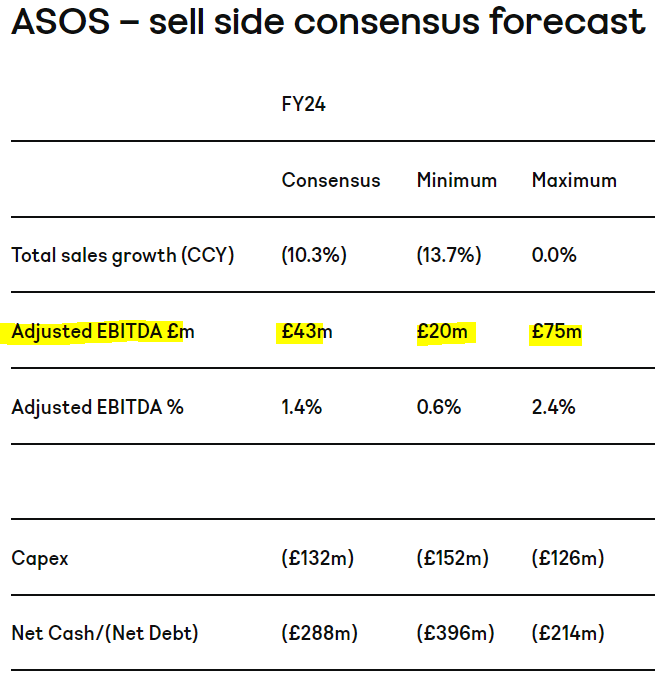
I’m not clear what the phrase “at the top end of consensus estimates” actually means. Is it referring to the £43m consensus figure above? Or the range from £20-75m? That form of wording could mean either. "Consensus" is the average, it’s not a range, so how can you be at the high end of a specific figure? All of the above numbers turn into PBT losses anyway, so it's arguably splitting hairs.
There are no broker notes on Research Tree to help me here.
The StockReport’s EPS analyst consensus data has updated overnight, which shows a slight improvement in FY 8/2024 EPS loss from -116.2p to -112.7p. Note that the nonsense EBITDA figures at Asos turn into losses before (and after) tax. So this is not a healthy, profitable business, it’s loss-making and has a weak balance sheet, as I’ve flagged before.
Sales are shrinking, as the consensus is -10.3% fall in sales, and it says “sales slightly below guidance” - so what maybe -12, -13%? Why can’t they just give the number instead of making us guess? Probably because they haven’t reconciled the year end numbers yet, which isn’t unreasonable given it’s only 6 days after the year end cut-off. Although sales really should be a very simple number to produce.
Topshop JV - selling the family silver? This is a cash raising exercise. Asos bought Topshop (including TopMan, plus Miss Selfridge and HIIT) from the administrators of Arcadia in Feb 2021 for £265m cash - overpaying, in hindsight, at the peak of the pandemic boom in online sales.
Topshop brands have now been sold to a new JV at a £180m valuation. Asos will own 25% of the JV, with HEARTLAND owning 75%. So it looks as if Asos will receive cash of £135m, which after fees and other, will net to £118m net cash for Asos - helping its balance sheet, but of course reducing future profits from selling a profitable brand and instead having to pay a royalty to use it.
HEARTLAND is connected to Bestseller, which is Asos’s largest and longstanding shareholder, currently at 27.1%, which on paper has lost billions on this share. I think it’s worrying that the biggest shareholder wants to secure for itself the best brand asset - that’s the sort of thing you see happen when a company’s long-term survival is in doubt.
JV financial impact? - this is confusing -
“The Joint Venture will grant ASOS certain design and distribution rights for the TSTM brands in return for a royalty fee to enable it to continue marketing and selling the TSTM brands online. For FY25, the Transaction is expected to have a £10-20m negative impact on EBITDA and to be increasingly EBITDA accretive over time.”
The way I interpret that, is this deal will hit Asos’s profits by £10-20m pa. What the last bit means, who knows? Since it’s harming profit, how can it be “increasingly EBITDA accretive over time”? That doesn’t make sense. My best guess is that they’re trying to say the financial impact will lessen over time, but who knows? This announcement looks like it’s been heavily edited by the PR people to confuse with positive spin.
Timing - expected to complete in Q4 2024, which must mean calendar 2024, as FY 8/2024 Q4 has already passed.
Asos’s strategy is -
“to turn ASOS into a company that delivers sustainable, profitable growth.”
A nice aspiration, as currently it’s not profitable, and isn’t growing either.
Refinancing - this relates to bond financing, which is key for Asos’s balance sheet. It has benefitted from insanely cheap interest rate bonds issued during the zero interest rate period. That was a time bomb though, as finance costs would shoot up when the bonds expired, and that’s assuming Asos would even be able to refinance the bonds. Worst case scenario, bondholders would end up owning the company, with equity wiped out.
“ASOS today launches a refinancing, which will include (i) an offering of approximately £250m Convertible Bonds due 2028 and (ii) a concurrent partial cash repurchase of the outstanding £500m 0.75% Convertible Bonds due 2026 issued by Cornwall (Jersey), with full details included in a separate RNS.”
Two separate announcements yesterday on the refinancing. I’ll concentrate on the later, outcome RNS called “Successful placement of Convertible Bonds due 2028…”
The rationale is to buy back (at a discount to par) the existing April 2026 bonds, using the £118m proceeds from the Topshop JV disposal, and a new issue of longer-dated 2028 convertible bonds. That reduces net debt, and extends the maturity. Although it will of course greatly increase the cash outflows for paying interest on the bonds, something it doesn’t mention in the rationale bit!
New bonds - carry a coupon of 11%, and are issued at par. That’s a huge hike in interest cost from just 0.75% on the old bonds. I’m not a bonds specialist, but google tells me that 11% coupon is into junk bond territory - higher risk, higher reward.
Conversion (into ordinary shares) price is the same as the old bonds, at an absurd £79.65/share. So forget the convertible element of the bonds, they won’t convert unless there’s a miracle, given the current share price is just £4.34.
Sept 2028 redemption date buys Asos more time to sort itself out.
Redemption price is 120% of par, so that’s another hefty but deferred cost. This takes the yield to maturity up from 11% to 14.84% pa - very much a junk bond.
Old bonds - Asos offered to buy back the 2026 bonds at 85p in the pound, so a useful benefit to its balance sheet by eliminating some of its net debt, but at substantial additional costs from the very expensive new bonds.
£173.4m have been bought back for cancellation, announced last night.
It says £73.6m of the old bonds remain outstanding.
This deal looks very bad to me, and is all about survival, rather than good economics. Financing cash outflows are now going to shoot up, due to taking on expensive new bonds, in order to buy time to try and move from trading losses into profits.
Paul’s opinion - I’m astonished Asos shares shot up yesterday, as the bond deal means its finance costs will soar - and reinforces that this is a financially distressed business, having to issue a junk bond on poor terms.
Also the current trading statement is ambiguous, and means Asos remains loss-making at the PBT level.
Its last balance sheet showed negative NTAV of £(72)m, and remember that’s getting worse every 6 months due to ongoing trading losses.
This share could easily end up a zero in my view.
So why is it worth £518m market cap? There could be strategic value given Asos has >£3bn pa revenues, and a very well known brand and repeat customers. Mike Ashley’s scattergun approach of buying retailer stakes includes Asos, where his Frasers (LON:FRAS) empire holds 22.4% of Asos. The 3 big holders (Bestseller, Frasers, and Camelot Capital Partners) control 64% together, so there might be a tussle for control.
Turnaround potential is intriguing, as with over £3bn revenues, each 1% improvement in the profit margin is over £30m additional profit (or reduced losses more accurately at this stage).
Hence this share is best seen as a special situation, where anything could happen.
From my point of view, after following since the start, it looks very much like we’re witnessing a business that originally had stellar growth, but has made negligible profits (only £228m retained earnings since day 1), has never paid any divis, and now seems to be in serious trouble.
Hence I’m keeping my AMBER/RED negative view, based on the interim results, which I explained here on 17/4/2024. The deals announced yesterday are not positive in my view. They buy it more time, but at considerable cost - selling its best brand, and agreeing to very expensive new junk bonds which will increase its cash outflows.
Anything could happen though, Asos may have strategic value to an acquirer, or it might pull off a trading turnaround, who knows? Refinancing the bonds means it has time on its side, hence you could argue a speculative positive case too.
Cradle to grave? -

I'd be surprised if yesterday's spike up in price sticks -

Gear4music (HOLDINGS) (LON:G4M)
186p (pre-market) £39m - AGM Trading Update - Paul - AMBER/GREEN
Gear4music (Holdings) plc, ('Gear4music' or 'the Group') (LSE: G4M), the UK's largest retailer of musical instruments and music equipment…
Reassuring comments today for FY 3/2025 -
"We are pleased to report that trading during the financial year to date has been in line with the Board's expectations.
Having successfully reduced our net debt and operating costs during FY24, during the early stages of FY25 we have focused on implementing the growth strategy outlined in June and expect this to start delivering results in the second half of this year.
We are well prepared operationally for the upcoming seasonal peak trading period, and the Board remains confident of the delivery of our medium and longer-term profitable growth strategy.”
Broker update - thanks to Singers for its note this morning. It talks about EBITDA, but of course that’s not a reliable number in this case, as explained here before. However the real profit figures look quite good too, with adj PBT forecast to rise from £1.1m in FY 3/2024 actual, to £2.7m in FY 3/2025 forecast. That’s adj EPS of 9.4p, rising further to 14.6p in FY 3/2026. PERs are 19.8x and 12.7x - perfectly reasonable I’d say.
Paul’s opinion - I upped us from amber to AMBER/GREEN at 147p on 25/6/2024, on improving fundamentals - notably improving profits from restructuring, and a balance sheet gearing problem resolved. Revenues are now in a modestly rising trend. I’m not convinced the acquisitions previously have added much value, maybe it should stick to its knitting rather than buying more brands?
Shares are up nicely this year to 186p, but don’t look stretched yet in valuation terms, and it wouldn’t surprise me to see a continuing bull trend up to maybe 200-250p at a guess? Quite good, but not madly exciting. This is after all a highly competitive, and low margin market. Also the growing threat from Chinese direct to consumer websites puts me off buying any shares in companies that have products made in China and sell them in the UK. I’ll cover this in more detail in my forthcoming weekend podcast. A quick search on TEMU shows it is already supplying cheap musical instruments & accessories (although quality can be very hit & miss with TEMU, so I suspect many people wanting musical instruments might prefer to stick with a trusted UK brand).
On balance, AMBER/GREEN still feels about right.
An interesting rollercoaster since G4M floated in 2015. Note that it floated with 20.2m shares in issue, and now has a barely changed 21.0m - clearly showing the watchful eye of its owner-manager Andy Wass in eschewing dilution. That also means in theory there's nothing to stop the share price regaining previous highs, if the market gets into another speculative frenzy over growth.
Brexit restrictions on trade might have helped impede sector leader, Germany's Thomann possibly? I've heard previously that UK customers prefer the rapid delivery times that G4M can offer domestically in the UK.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Just listened to Saturdays podcast, so thanks for brightening a dull Sunday. Did make me chuckle on your investigations of OnlyFans. Never been brave enough to go anywhere near it, but gobsmacked that it is just full of people making Olive Oil, though you didn't go into detail of what they were using that Oil for.
It was the comment about rugby players that had me laughing out loud. Your best yet, Paul. And worth a pint at Mello Derby if you’re not overwhelmed with fans!
How fortuitous the CEO sold a chunk of shares in May Next 15 (LON:NFG)
The events have launched and the links and info are on the Mello website
This is the link to the two day Anniversary show
Mello 10th Anniversary tickets – Mello Events
This is the one day London show...
Mello @ LIS tickets – Mello Events
As a weekend offer if any Stockopedia subscribers buy a ticket for the Derby event before Monday at noon we will give them a Mello Monday Pass to November for free
Have a great weekend
I looked into this with focus on the all share index a few years ago. My note to self says
Don't go short in dec or apr
Don't go long in july or nov
of course you may get a different answer depending on the calculation.
I received a message from TraderMark72 on Bluesky earlier about Next 15 (LON:NFG) . Some broker notes emerged after hours .
Radnor note out after hours. Revises FY 25, 26, 27 as follows:
Revenue; £585.3m; £530.2m; £558,6m
PBT: £111,6m; £88.8m; £105.7m
EPS: 75.6p; 61.4p; 73.3p
Sees the valuation as too low..
Maybe these will help shed some light on events.
Weekend at last, I near despair with these markets just when will it improve, the years slip by same old same old, for heavens sake cut the % rate
Assuming that you mean the BOE Rate Mike ? I wouldn't be too optimistic of the BOE acting aggressively with inflation busting wage rises being negotiated...
I share your pain! just read this interesting article on interest rates https://doceo.tv/insights/news... It would seem that Point 1. is overriding a lot of the positive things that should result from lower interest rates. It seems the market thinks that the Central Bank thinks (at least in US) that a recession is more likely than a renewed burst in inflation.
There is a classic investment thought - which I've often found to be true.
"Its better to travel than arrive."
This seems to be playing out at the moment. Wouldn't surprise me if markets fall initially as rates are cut.
BWDIK
Albertos, I’ve seen this chart posted a few times, I can’t vouch for the accuracy, but backs up your last comment
Bought some more Cairn Homes (LON:CRN) on results but now regret on today’s fall. Results were stellar ? Would appreciate Paul’s view.
Think you can just put it down to the usual September being a dog of a month everything is off this week ftse 250 stuff especially , oil at low for year, mining off big last two weeks on recession fears.
Normally 8 times out of 10 mid Oct onwards is a good run for last ten weeks of the year if that doesn't happen might be worth positioning accordingly I don't know why but ever since I can remember September is always awful.
In my 14 years of investing, my portfolio shows June 7%, Sep 47%, with Mar and Aug around 50% of how often it was an up month.
I think the key thing here is as you said Dragon "my portfolio" if you do a google of stock market average monthly returns Sept is always showing the worst figure.
If I've missed subscriber comments on Cairn Homes results on Wednesday, I apologize. It's one of our top holdings and I'm disappointed and surprised by investor selling since. We now know the CEO planning to sell 8 million shares (now sold) can't have helped but with Cairn still buying back shares at what was momentarily the top price they'll have a pleased CEO and some puzzled investors. I know it's late in the day on Friday and after the event but I welcome any observations on those results and the reaction so far.
No idea why CEO sold through a placing. CGT is 33% in Ireland so a third will go to the state. As far as I am concerned figures looked good, outlook promising and the Irish government have put in Real measures to get houses built. Hopefully the Gov in UK will do the same. So I see no reason to be concerned.
I saw latest broker forecast for next year to be slightly down compared to the previous forecast. Maybe the outlook for next year is not that bright and we are missing some information here? Anyway it might be nothing and just getting some good profits for the hard earned work, we will never know but I wouldn't blame him!!
Do you have the broker's note ? I have always been rebuffed when requested ?
I'm afraid not, I'm on holidays and always found hard to check Research Tree on my phone (not even sure if there are notes available). I've noticed it from Stocko broker forecast
OK - Brokers sadly do not share, not sure where Stocko get them from. Unless I have got Irish house building badly wrong looks positive. I have held for a while Glenveagh Properties (ISE:GVR) but sold and bought Cairn Homes (LON:CRN) , Enjoy your holiday.
I know there’s lots of Funding Circle Holdings (LON:FCH) followers on here, just announced Harwood sold 1m shares, top slicing on the recent good move up.
For a marketing company, Next 15 (LON:NFG) seems to have chosen a surprising ticker, however prescient it turned out to be.
Hi Paul - IFRS16 - I am (sadly) an accountant but in simple terms IFRS16:
1. Makes EBITDA even more stupid a measure of performance, as all rent costs are now classed as either depreciation or interest (both being excluded from EBITDA in the P&L) rather than being recognised as a rent cost (which is included in EBITDA in the P&L).
2. Chucks a load of "assets" and "liabilities" onto the balance sheet that are based off subjective opinion - e.g. in calculating the net present values of each lease based off a hypothetical interest rate is charged.
As an example - imagine a 5 year lease at £10k per annum.
Under the old regime the P&L rental charge would be £10k per annum and EBITDA impacting.
Now under 1FRS 16, and assuming a 5% interest rate to discount your annual rental liability:
Annual Depreciation charge over 5 years = £8.66k per annum
Interest charges:
Yr 1 - £2.165k
Yr 2 - £1.77k
Yr 3 - £1.36k
Yr 4 - £0.9k
Yr 5 - £0.47k
Both are classed as below EBITDA so in effect if you analyse performance based on EBITDA then you need to remember to add back an actual rent charge to align with comparatives, otherwise EBITDA is artificially inflated.
In short - DO NOT RELY ON EBITDA FOR COMPANIES WITH LEASES!!!
Now with reference to XP Factory (LON:XPF) and only looking at the material items in their reconciliation, they have added back both the deprecation and interest charges (2.474m and 2,374m respectively), then deducted the actual rent payments that would have been classed as rent under the "old" regime (3.593m). For a business of their size this is a seriously impactful reporting standard and a good example of why EBITDA cannot be relied on.
From a professional point of view (25 year qualified Chartered Accountant) I do understand why the standard was brought in (essentially to prevent off balance sheet liabilities) but I totally disagree with how the P&L impact is recognised. It is simply nonsense.
All the best.
its a shame these companies dont simply also do an "old skool set of acounts" too
It's all down to cost - IFRS 16 is an auditors feast in terms of fees, as are many of the new accounting standards. Although for internal management accounts purposes yes the old skool is far more relevant.
I'm sure you will be teaching your kids about finance, pensions, compounding interest, saving and investing. Don't expect it from the schools too focused on critical race theory or wokedom.
Robert Kiyosaki "Rich Dad Poor Dad" was an ok read (make money in real estate, but also now self help books).
Hopefully with this government tax avoidance will closely follow the basic lessons, closely followed by where can you earn good money with less tax in the other parts of the planet.
Gear4music (HOLDINGS) (LON:G4M) Paul :
Gear4music has several warehouses and showrooms in Europe, including:
Any other holders thoughts on Cairn Homes (LON:CRN) price movement and announcement?? . The stock dropped from £1.64 seemingly based on Chairman offloading a third of his stake at £1.55.. (a cool £12Million) at not quite an all time high; just before Ex-Div which is next week...
Scratching my head as to why if the Outlook seems strong as stated in latest results..... Have the buybacks, of which most recent was €45million, helped elevate the price too.. Throw in 4 million shares bought for the "incentive plan" will we see a major correction now for a company that can seemingly do no wrong... The bear on one of my shoulders whispering conspiracy/greed theories, is getting louder than the bull saying top up again while it's dropped on a moment of madness... Gotta love investing...
i know another poster was hoping for the paul/graham wisdom on their latest results, i would be too, especially with this latest news...
however rather than ask them to do all the work... casting my basic eye at the figures and outlook.. it would seem an obvious Green again... which is where Graham had it in dec 2023 .
any other better researched holders have any knowledge of Directors reasons for sales (lots of big sells on the data over time)
thanks in advance
I'm in the same boat Patrick with Cairn Homes (LON:CRN) today and Ashtead Technology Holdings (LON:AT.) all week. Two of my better performing investments and both fundamentally doing very well. Its very frustrating.
However i don't think the situation is any more then simple profit taking, both have done very well since the summer last year and there is bound to be a pull back and some point, although Ashtead Technology Holdings (LON:AT.) looks a little other done. As long as they stay on my screens ( Im a systematic / rules based invester) I see no reason to sell.
Good Luck
I posted on Cairn before scrolling Patrickmyinetrade, I'm puzzled too and wondering about adding.
ASC Oh how the mighty have fallen.
I think that a few of years ago legendary investor Nick Sleep sold his Amazon shares to buy into ASC. Oops. I think he saw many similarities between the two companies.
It's a reminder that even the canniest investors make huge blunders. Not long ago I discovered that highly-respected fund manager recommended Ted Baker about 10 years ago. Ouch.
It's quite chilling and it should be quite sobering.
The rag trade is a notoriously hard business. I also heard that fund management business are somewhat fragile, too.
Nick Sleep once said "The best founders don't care about money".
A little interesting tidbit: 10 months ago, Morningstar picked it as stock of the week at 365p, with a 5 star rating.
A very bold pick!
Yellowstone Advisory is pleased to announce that Transense Technologies (LON:TRT) will be presenting at our next in person event on 25 September.
Management teams from Transense Technologies (LON:TRT), Checkit (LON:CKT), Safestay (LON:SSTY) and Light Science Technologies Holdings (LON:LST) will be presenting and there will be plenty of time after the presentations for informal discussions with the management teams over drinks and canapes following the formal presentations.
The event starts at 5.30pm at the offices of Hudson Sandler, 25 Charterhouse Square, London, EC1M 6AE
You can get your tickets here (no charge)
PayPal Holdings (NSQ:PYPL) I recently purchased an airline ticket for £703.79 plus £304.00 for the seats with Emirates.
I decided to cancel the booking and did it online, Emirates refunded £483.79 for the flight keeping £209.97 as a cancellation fee (it says £200 on the website). I then had to request the £304 separately, which they declined to refund. I sent a really nasty swearing email in reply as they were keeping 50% of the ticket price.
So I contacted Paypal to raise an issue for the £304.00 and managed to get the refund, I then get another email from Paypal refunding the £209.97, which I hadn't asked for, so a full refund. Well done Paypal, I hold.
So the moral of the story is, don't accept the Terms and Conditions always challenge it and last resort is, hit them with a Chargeback.
I used to work for a Online Travel Agent and we were with Worldpay, they tended to push chargebacks through even if the customer was wrong and our T's and C's were correct. (There are different, more expensive fares you can pick up with better t's and c's)
We swopped to another payment processor.
I can't see Emirates missing £500 but suppliers do get to choose if they want to use PayPal Holdings (NSQ:PYPL) or not.
Eurocell (LON:ECEL)
Excellent presentation on IMC this morning, in summary the new CEO is great and they are doing everything they can pending a market recovery, tight rein on costs, more buy backs, few more branches etc it's safe and steady, just patience required.
However what i wanted to highlight was his comments regarding govt housebuilding targets of 300,000 pa, basically saying it's not going to happen, the capability is just not there in terms of skilled labour or even materials never mind the planning obstacles. Everyone I listen to in the industry says the same thing, it's just fantasy to think we can get anywhere near that sort of number.
But he did say even a recovery to 200,000 homes pa would make a material difference to the building materials sector, so that's something to think about...
Off to the Ashtead Technology IMC now at 10:30am that should be worth watching too given the share price collapse over the last few sessions..
Hi Burnt Onions, I was not able to attend the Ashtead IMC, would you please be able to provide any key observations/thoughts?
Hi Steve
Ashtead Technology Holdings (LON:AT.) This has been a big winner for me over the last couple of years and I was going to stick it in the old coffee can and forget about it but fortunately I started selling out a few weeks ago as I felt the price was very over extended but what to do now?
Well the presentation was good, all very confident, costs are up, margins are slightly lower due more to the product mix (increased services less robot hire), debt levels edging towards the upper end of comfortable.
They can see a big runway ahead of them and want to grow into it so that is going to dictate their capital allocation going forward, ie. buying more equipment to hire out or make more bolt on acquisitions as oppose to paying down their debt and returning cash to shareholders (and rightly so). Uk is now a much smaller part of their business so they expect little impact from Milliband's energy 'strategy'.
However for a business that is forecast to grow organically at circa 10%+ pa over the next few years it's still trading at circa 9x EV/EBITDA (by my maths), that's still too rich for me.
I would definitely buy back in but would want to see a 4 in front of the share price, but that's just my take.
The new board (all in place only 3 months or less) at Digital 9 Infrastructure (LON:DGI9) has “provisionally” cut the NAVps by 43% to “around 45p.” The main reason given is “a reassessment of the assumptions relating to the availability of finance for portfolio companies and its impact on portfolio companies’ growth outcomes.” Only goes to show how “finger in the air” the NAV on many “alternative” investment trusts are. Also highlights how dubious it is to include future growth opportunities (for which financing is not yet in place) in an NAV.
Admittedly, the market has understood the published NAV was not reliable for a long time and the share was trading at just over 20p before today’s update (on which it so far this morning has fallen another 3p).
The key to me is the sales process of alll assets (ex Arqiva). With the £53m RCF due to be repaid by end-March, the sales can not drag on too long. Hopefully the 45p indicative NAV has been informed by where “non-binding” bids have come in from first round bidders [although there is no mention of this in today’s RNS.] Now we move on for “selected” bidders to detailed due diligence in a second round. While there are four different assets up for sale - it is really only Aquacomms (underwater cables - mostly between US and Europe) that will move the needle. [I hold.]
Wimbledonsprinter I just emailed the Board -via of course the managers TriplePoint as the only way of contacting the board- see on the Investment Trust thread https://www.stockopedia.com/co...
The FT reports today that UK pension funds now only allocate 4.4% of assets to UK equities.
Makes you wonder what could happen if the government intervenes and mandates a minimum percentage.
Nothingventured. Yes, you make a good point. The government could also adopt a carrot & stick approach to this. ie they could offer incentives to UK pension funds to increase their allocation of funds to UK equities.
The problem is that the only thing the government are focused on is tapping pension funds to fund their green transition dreams: more off and onshore wind turbines, more pylons, more solar farms (built on prime farmland to the detriment of food security), etc. Ordinary UK listed equities are not a focus. Meanwhile our neighbour Norway continues to exploit their portion of North Sea at full pelt whilst their Sovereign Wealth Fund divests from listed oil & gas operators like BP and lectures them on the evils of fossil fuels, whilst enjoying the bulk of incremental funding from said fossil fuels. I know we are not meant to discuss politics here. But there are days it’s very hard to motivate yourself to allocate any incremental capital to this country / market. You don’t know whether to laugh or cry. I can’t in all honesty blame our pension funds when we have such self-destructive policies. That said, over allocating to expensive / over crowded US tech is not a panacea either, as a lot of people will find out. But that’s another story
Hi Phil, this is how we achieve energy security! Onshore wind especially is much cheaper than any other form of energy, including new gas turbines. And on land use, even if we max out solar, it will still take up about half as much land as golf courses;
https://www.carbonbrief.org/fa...
Also in practice solar is sometimes combined with sheep grazing.
Personally, I think with falling rates Foresight Solar Fund (LON:FSFL) and Renewables Infrastructure (LON:TRIG) look a steal with their current yields, and a government that is keen on boosting renewable production. (I hold both.)
Phil 117 makes some very valid points and puts it better than I could
Will right something in politics thread about this but the myth of energy security through wind and solar is not really viable you would need huge redundant capacity for when they are not producing
Energy storage would be the only solution or generating hydrogen with excess electricity which would both need long term huge investment
Look below in the winter for instance solar produces very little
https://gridwatch.co.uk/
This has been something I have been arguing for a long while.
All pensions funds globally allocate assets across multiple countries but the UK pension fund industry stands out like a sore thumb in terms of the proportion of its assets allocated to its home country.
Pretty much every country without exception is more than double the levels the UK pension funds allocate at 4.4% - ie they are pretty much all 10% - 20% (Japan being the highest)
So the governments job is to make sure pension funds allocate capital in a way that supports British businesses and the last government failed miserably at this. whether this lot dare to do any better who knows.
I think the MPs pensions fund allocation is something like 1% to the UK from memory (I might be wrong on that - it needs checking) - but if that is true it is a damning indictment and frankly should not be allowed. Public sector pension funds should be the leading examples of helping British businesses not the laggards in my view.
I wonder if a min 50% UK allocation for MP's pension might be an idea to focus thinking?
Businesses make money, governments spend it. The two should not be confused.
Good God.
Not sure, but (regrettably) isn't it the case that given the DB nature of the public sector pension schemes, the liabilities of the fund will remain the same regardless of the investment target location?
On that basis, isn't there a risk of the funds underperforming with a UK mandated focus, therefore leaving the taxpayer even worse off? That has certainly been the case vs the US for maybe 20 years?
I don't disagree with the sentiment at all of encouraging more UK investment, but absent structural changes in fund risk/reward, and alignment of those risks/rewards with pensioners, then no-one really has any incentive to invest in the UK or cares about the outcome of the businesses that make us prosperous via wealth creating laws.
Totally agree Don think it would be a disaster the last thing the UK pension firms and the public who are invested in them for their own pensions need is government pressure to force them to invest in UK firms regardless of their performance relative to other options
Personally own Phoenix group (LON:PHNX) and would have to reconsider me investment if this was enforced
I sold Phoenix yesterday for general pension meddling reasons Bullhead, but I hope that I'm wrong... Labour talked a decent game leading up to the election, so hopefully the budget will be more economically friendly than currently feared..... Phoenix group (LON:PHNX) is close to 1 year highs and struggling to trade up through the descending channel.... plus I wanted some cash to invest in Wise (LON:WISE) which just seems too cheap for a UK tech company with huge scalability and market potential... I recently became a customer and the service / product is fantastic... critics may argue re it's moat / differentiability, but I think that its an accumulate on dips stock....
Thanks Cancun will hold Phoenix group (LON:PHNX) for the moment more for the yield than any share price growth but if as we both fear they do start pension meddling it will lead to a decline in that too
Let’s hope we are both wrong and they don’t go down that hazardous path
Will have a look at Wise (LON:WISE) don’t normally invest in individual tech shares tend to do it through Polar Capital Technology Trust (LON:PCT) HgCapital Trust (LON:HGT)
Last big investment in tech company in UK market was ARM
Have used Wise (LON:WISE) for transfers to different currencies abroad it gave good rates cheaper than other ways and simple to use would recommend it for anyone looking to do the same
Wise (LON:WISE) has great functionality through its app. I’m a user and am looking to open a position but the SP is in a downtrend so entry point is uncertain.
UK pension funds’ allocations to British stocks hit historic low
https://x.com/MerrynSW/status/...
Here's Merryn's take on the British ISA
https://archive.ph/SiBnL
My ISA is invested as a provision for my old age, with a similar aim to the pension trustees. It was, and I think still should be, the aim of this or any government to encourage people to have the ability to not just take care of themselves in retirement, but build up their wealth which as a consumer economy is a huge general benefit. The £4bn Merryn notes as a benefit given by the government is utterly piffling beside the strain on the economy of more people relying on government support. It makes no sense to force investment into companies that otherwise cannot attract it.
So any government needs to make it clear that having companies helped (or at least not obstructed) to do business is a key aim, as is welcoming the idea that people aspire to acquiring wealth. On the second point this government gets coy - yes, they say ,they want people to save and build wealth but, (in the same breath), not too much and they will define that amount, so that they can skim off the "extra". Equivocation like this destroys the confidence needed to make long term decisions on pensions, saving, mortgages and insurance for consumers, and undermines the commitment that companies need make in this market.
Trust. Lose Trust (not Truss). This seems now a more serious conversation than in the past. My pension is my future life. Start messing with that for your London centric rubbish then even the blue rinses will rise up.
Wouldn't be the first time, they have form with what Gordon Brown did, but it seems politicians never learn.
"Govt intervenes..." channeling my inner lord Salisbury "why change things, they are bad enough already"
The reason pension fund equity holdings are so low is a long series of govt meddling (both sides not political) dating from the late 80s on. Basically the treasury thought actuarial surpluses are a way of hiding taxable profits (partly true) and so limited them. So surpluses were reduced and then when share prices fell it all started going wrong (over simplistic but...). Further regulatory change should be treated like v.v.v. Long fuse ordinance.
Realistically all the Government needs to do is message that it expects Pension funds will allocate assets in line with how other countries do asset allocation to their home country and if progress isn’t seen in this regard over the next 12-24 months then it will take action. Most managers would prefer self governance and will likely start an allocation move towards the target. The benefit of doing it this way is that it’s technically optional, non restrictive from a set %age level and the effects will be a gradual increasing of capital allocation to British businesses rather than a sudden uplift which may be difficult to digest.
Couldn't agree more David.
I entirely agree David that carrot is preferable to stick. However one action that could easily be taken is to require pension funds to publish annually their UK allocation percentage. Starting with the MP’s fund.
All true, and to add a little detail....
Some companies were manipulating their earnings through pension contributions.
Maxwell raided the Mirror pension schemes and the rules were tightened.
We got a Pension Regulator in 1995, replacing the Occupational Pensions Board
In 1997 Gordon Brown removed the pension fund tax credit on dividends that recognised corporation tax had already been paid (and you wonder why pension funds stopped bothering with UK equities?)
The Pension Protection Fund arrived in 2005 to bail out failing DB schemes, funded by solvent DB schemes....
Throw in Equitable, the BHS mess and all the British Steel transfer nonsense and there is no shortage of reasons why pension trustees are now extremely conservative in their approach.
Even where there has been no malfeasance you have some unhappy situations - just look at what has happened to the Universities Superannuation Scheme who decided it would be too expensive to hedge their inflation/interest rate risk.
Those "LDI" thingies that amplified the Liz Truss gilt shock were actually rather sensible provided you managed your collateral properly.
There was a piece on Sky news this morning promoting a new campaign to encourage younger people to invest / invest more in their pensions.
The FT and others have, over the years, highlighted how Brits don't like to discuss money, while other countries such as the US (401K) and Australia (Super) it is normal to do so .
It must be at least 10 years since the pension dashboard was first proposed. A quick search indicates that they are only now beginning to test it, and the connection deadline for schemes is October 2026. https://www.pensionsdashboards...
This is a step in the right direction which should be backed up with better personal finance education in schools - Richi Sunaks offer of double maths was never going to fly.
Pensions dashboard ... one reason I am long regulation.
The original idea was great - you ask one place to tell you about all the pensions you have. Lots of people forget. That could've been a glorified set of telephone directories.
This somehow became an online web service that aggregates the current benefit values from all sources. That means pension providers have to have an up to date value of benefits. If that is a DC pot, usually no biggie. If a DB pension not so simple (not involved directly just sit next to people). So a scheme may have to implement a new calc then set up new interfaces to an 'isp' (i dont know either). The cheap method is to send a data extract. Still not cheap though.
ps Oct 26 deadline is not going to be met by everyone.
Centaur media
Normally illiquid with a big spread but the past weeks the opposite and this morning the buy and sell are the same
Downing are selling their last 3% in the market so thats circa 1.3 million quids worth they are unloading, putting the downward pressure on Centaur nothing to do with company performance .
Harwood / Rockwood are maxed out on 30% and smart cookie Richard Griffiths is on 4% so this us goong to get broken up or sold at some point .
There was a withdrawn bid at circa 50p 6 momths ago .
This seems on opportunity in the market caused by Downing wind down I bought yet more this morning at 29.95 which I think is ludicrous value, when Downing are out there will be a squeeze in the opposite direction for sure .
I hope you are right, planetx. I also hold Centaur Media (LON:CAU) but was alarmed by the withdrawn bid. This stock has refused to re-rate despite the supposed improvement in operating performance in the last three or four years. When private equity came sniffing around I thought this was the opportunity to see how valuable an asset Centaur would be to a trade buyer. Therefore the apparent lack of interest from elsewhere and the prompt withdrawal of the bid don't look good to me and I suspect we should be cutting our losses rather than doubling up.
Regarding Centaur Media (LON:CAU) , I'm not sure there ever was a bid to be withdrawn and hence no need for alarm. I believe there was a "highly preliminary expression of interest" which resulted in there being a decision not to make an offer. This obviously could have been for all manner of reasons and may simply have been that WPEF were never going to make an offer acceptable to Harwood and other majority shareholders.
Irrespective of the size of the overhang, it should eventually clear and the dividend offers nice compensation in the meantime whilst waiting for the value to out or for the turnaround to complete.
I liked Richard Staveley's comments in his recent interview with Paul Hill about a group of mates getting together to buy the company (his mates are obviously better off then me and my mates :-) and then owing the esteemed publication The Lawyer in perpetuity after maybe 5 or 6 years of free cash flow paying back the original investment.
With EV to EBITDA currently under 5, significant net cash, a 6% dividend yield and Harwood / Rockwood pushing the turnaround, it feels like a decent mid to long term bet IMHO.
Shades of Crestchic maybe?
I’ve been keeping a watchful eye on Centaur Media (LON:CAU) for just the reasons you give PlanetX but I’m afraid the overhang is much bigger than your assessment. From what I’ve been told it’s at least 3 times more than that and there are multiple sellers. Remains on the watchlist but suggests there’s no rush…(happy to be proven wrong I should add)
Where did you get the '3 times more' and multiple sellers info from? Centaur Media (LON:CAU)
From a City friend with much better connections than me- sorry I cannot tell you any more
But the city friend's view does not accord with the RNS for Centaur Media (LON:CAU) which states on 01 Aug 24 Downing reduced to 2.95% holding (4,327,931 shares remaining)
If I am not talking gobbledy gook then this supports what PLanetX has stated (selling remaining 3%)
or 4,327931 shares x £0.29p per share = £1,255,099 residual..
As you see I said I believed there are several sellers- for example Aberforth last released an RNS in May that they have reduced from 15.87% to 14.96%. Stockopedia show 5 shareholders who have sold some shares- we may not know if they’re still selling until the RNS is released but from what I was told there are several holders still selling
Aston Girl
I think you are mistaken in believing the reductions are due to selling .
Stockopedia shows 5 shareholders who have reduced slightly but this is due to issuance of shares under LTIP there y diluting then slightly
An RNS is thus forced for each time you drop a % point .
I know Harwood arent selling yet stocko shows the reduction .
It was me who looked at the Stockopedia numbers so mea culpa
Like you I shall be watching closely for what follows once a further £1.3m worth are sold (& as I said I’m happy to be proven wrong as it’s one I’m watching)
Abercorth
- 10 may shares issued under LTIP
- 16 may aberforth dropped from 15% to 14%
The RNS doesnt show the trades just the reduction .
Maybe your friend in the city needs to pay a bit more attention to the mathematics .
Pretty sure Ive got this right, I only follow 20 companies so dont miss much .
I posted at 8.50
Three big trades 40 min later (30k gbp each ?
Someone on here ?
Halifax house price data showing strength again , and this is before the effect of the August rate hike , falling mortgage rates and peak selling season begins . BOE mortgage approvals hit a high not seen since Truss mini budget . Wages to house price ratio has improved dramatically but affordability has not thanks to higher interest rates . If mortgage rates come down we are set for a roaring housing market again . There is a massive undersupply of housing in this country as population growth has far outstripped housing growth
Typo? I think you meant August interest rate cut, not hike? (from 5.25% to 5.0%). You can edit any post within the first hour by clicking on the fat pencil.
As a landlord who has already sold down some of my portfolio here are my observations:
Prime central London (PCL) has traditionally been the first mover, with volumes and prices recovering 6 - 18 months ahead of the national/regional figures. With Russian and Chinese investors out of the market, and the government hardly rolling out the rug, never mind red carpet, for others with wealth, it is difficult to see happening this time.
Contrary to media reports, many homes in PCL are at prices similar to where they were in 2015 and the period to achieve sales is currently double what it was then.
The majority of small to medium size landlords bought most of their portfolio in their own name and are now 60+. George Osborne's S24 and other tax changes combined with interest rate hikes have reduced profitable portfolios to being marginally so. This combined with increased red tape and court delays has lead to a significant increase in landlords selling up.
The threat of tax rises and removal of reliefs has added more supply to the market, so I do not see a significant rise in house prices for at least 6 months, even if volumes do begin to rise.
If the Government want the market to recover, they need to make the sale/purchase process fit for the 21st century, increasing the use of digital tools to remove delays. They should also push for the outstanding fire safety works on flats to be accelerated and explain how Europe's oldest and least energy efficient housing stock will be retrofitted. At present there is no clear standard, no plan, and not enough skilled workers.
There are no houses / hotels or other accommodation to put people in when you need your property back as your legal rights - so all the courts, local authorities, bailifs etc are dragging it so it becomes a nightmare. Certain tenants need 'eviction' so can jump the housing ladder - they are vulnerable, disadvantaged, or grifters, and fighting over all the other above.
It is not good for a first world country. Or was.
A housing growth for those that can afford it. Otherwise a growth in the social budget.