Small Cap Value Report (Fri 7 Aug 2020) - SCPA, PURP

Good morning, it's Paul here with Friday's SCVR.
Today's report is now finished, due to lack of relevant announcements.
Pubs and restaurants seem to be seeing a surge in demand, thanks to the Eat Out to Help Out Govt discount scheme. Industry data suggests that sales were up 70.9% in the first 3 days of the scheme (food up 114.3%). I decided to mystery shop/dine Wildwood, in Bournemouth, a pre-covid favourite of mine, on Weds earlier this week. I couldn't believe how busy it was - packed downstairs, and a good smattering of groups upstairs too (which is usually empty). I asked the waitress how business has been, she replied, "very busy, every day, since we re-opened on 18 July". Isn't that surprising? She said the Govt scheme has helped, but it was busy already. Bournemouth generally was busy with people at about 6pm, although being a seaside town, and the weather being pleasant, and people not going abroad, then perhaps those factors help. It looks very mixed anyway - central London is still almost deserted, but by the looks of it seaside/holiday towns are doing alright. I'm going to mystery shop Franco Manca for lunch today!
.
Scapa (LON:SCPA)
Share price: 91.6p (before market opens)
No. shares: 186.9m
Market cap: £171.2m
Scapa Group plc is a diversified Healthcare and Industrial company focused on bringing best-in-class innovation, design and manufacturing solutions to its customers...
Scapa's year end is 31 March 2021. Hence Q1 update today covers April-June 2020.
Scapa has delivered FY21 Q1 revenues in the three months to 30 June 2020 well ahead of its COVID-19 scenario plan. Trading in both divisions has also continued to improve into FY21 Q2 to date. Scapa acted swiftly to implement structural costs changes across the business in response to the impact of the COVID-19 pandemic on the reduction in product demand, as well as ensuring variable costs were closely managed to match the new demand levels.
The combination of the better than anticipated business performance in FY21 to date, early cost intervention measures and continued improvement across both divisions mean the Group's outlook on full year trading profit is trending approximately 10% ahead of market expectations.
That's great, but it's a pity the company fails to provide a footnote detailing what market expectations are, which is best practice being followed by some companies and not others. Anything that helps investors quickly understand the picture should be provided. We have to look at lots of these updates between 7-8am, so wasting time having to look up forecasts (if they're available at all) is not helpful.
Never mind, the key point is that the company is trading surprisingly well. I say surprisingly, because the share price has been very weak since the refinancing, which (wrongly) lead me to surmise that the company must be trading badly, hence I ditched my shares a while back when a margin call forced me to cut back on a few things where I had limited conviction, such as this. That probably means I'll miss out on a rise in share price today. Oh well.
Liquidity - sounds OK;
Working capital management remains strong, with adjusted net debt¹ at the end of FY21 Q1 of £18.4m (including net proceeds of £31.6m from the equity placement in May 2020), compared to the FY20 year-end position of £54.4m.
There's an omission here too - we're not told how much the company has benefited from deferral of payroll taxes, VAT, etc. If the company has not taken advantage of such schemes, then it should have said so.
My opinion - good news on trading, but we're not told how much net debt has benefited from stretching creditors such as tax.
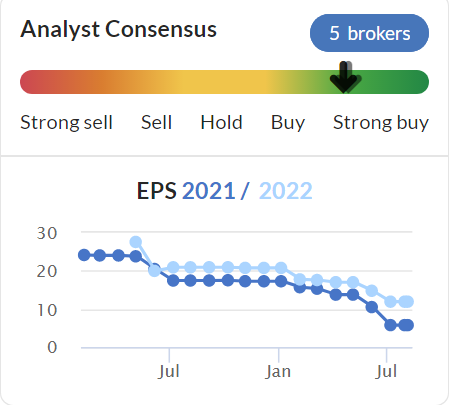
I can't find any recent broker research on it. The broker consensus graph on the StockReport here shows a steep decline in forecast EPS, so it looks as if these figures might have factored in covid, hence we can probably rely on the numbers below. The current year forecast FY 03/2021 (the darker line for colour-challenged readers) is 5.5p EPS, recovering to 11.9p the following year, PERs of 16.7 and 7.9 respectively. We're told today that the company is trading c.10% ahead of the forecast it gave at the time of the fundraising, which I assume brokers will have reflected in their forecasts. So that means maybe 6p earnings this year FY 03/2021? Then some recovery is likely next year, once the impact of covid washes out.
Overall - an encouraging update, and this share looks cheap to me. There is an unresolved legal action underway, with a former major customer, which makes me a bit nervous though.
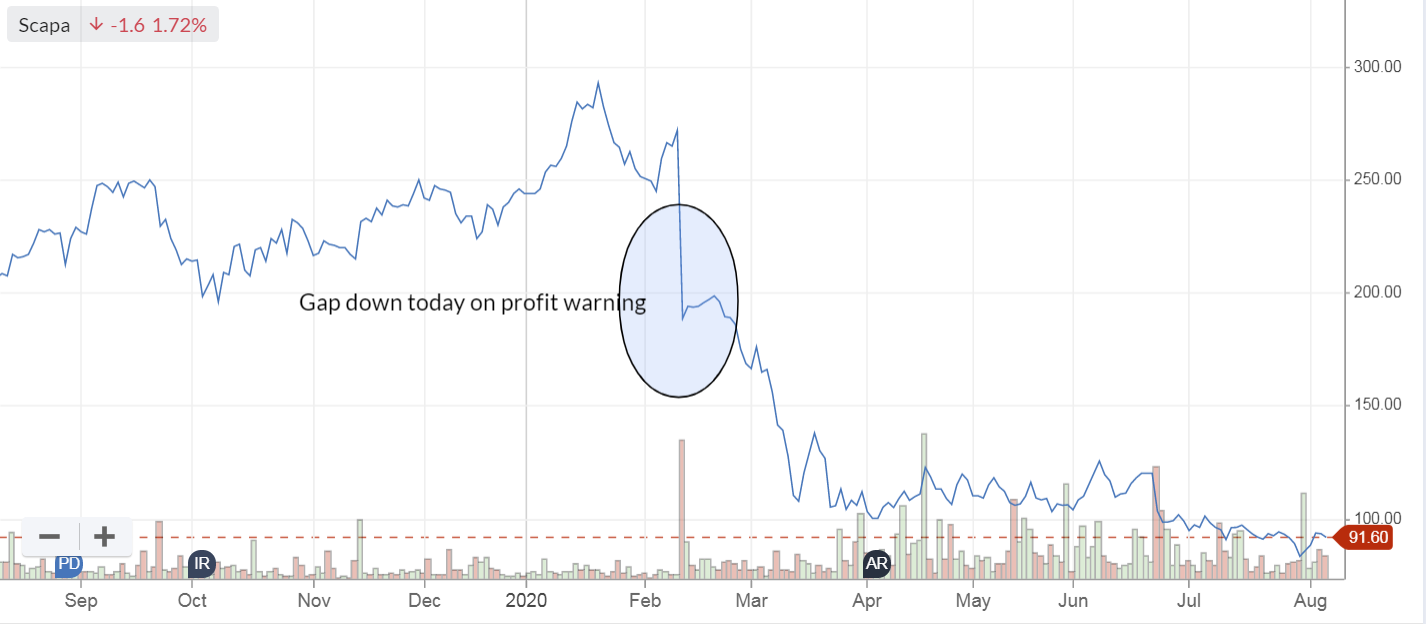
I see that Stockopedia has saved the comment I added to SCPA's chart back in March. That's a really neat feature! So I could add more comments as time goes on, and build up a nicely annotated chart with major events noted. Although I have to say, I find the chart draw tools very difficult to use, I'll have to read the instructions properly as they're not at all intuitive to me.
.
.
UPDATE: I see that SCPA's share price has shot up superbly today, up 39% to 127p at the time of writing, 11:37. It's perplexing that the share price has previously been so soft, when the company was trading well. Just goes to show I suppose, that the market doesn't always know what's going on. What a pity, as I did some good research on this, and was right about it being cheap, but didn't have the courage of my convictions. Anyway, I hope some readers made a few bob on it.
.
I know that a lot of readers are coining it in on Boohoo (LON:BOO) at the moment, so that's wonderful news. Hopefully readers are recouping the losses from Revolution Bars (LON:RBG) which has been a bit of a disaster. Oh well, some things work, others don't.
.
Purplebricks (LON:PURP)
EDIT: I don't take much notice of Director buys, unless they're a £6-figure sum. One has just popped up in a stock where I've recently taken a small opening position, Purplebricks (LON:PURP) as follows;
Director/PDMR Shareholding
Purplebricks Group plc (AIM: PURP), a leading UK estate agency business, has received notification that Senior Independent Non-Executive Director Simon Downing purchased 500,000 shares of £0.01 pence each at a price of 57.5p per share on 6 August 2020.
That's £287,500 purchase in the open market. Pretty impressive.
Here's Monday's SCVR, where I reviewed its results, and concluded there might be speculative upside on this share.
Just thought I'd flag this, as it's not often we see Director buys in small caps of that size, which might be a positive sign.
There's nothing else of interest to report on today. The sun's out, it's a glorious day, I expect many readers are sitting in your gardens, laptop next to you, hitting the space bar a few times every 10 minutes to make it look like you're working! I'm going to down tools, as there's nothing else to report on. I've got family visiting tomorrow, so need to clean the flat, and pop to M&S for some ready prepared food.
Enjoy the weekend!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
At 115p today this looks a reasonable entry point and I'm comforted that Octopus has increased its holding to over 9%.
SCAPA
Net debt position vastly improved after equity issue (May, 30.7mn shares at 105). Good news if ias it has now rallied above that placement price. Has now raised £70mn over past three years so has not yet added much value. Deeply cyclical earnings pattern over past five years, largely low returns, competitive market. Why have margins been so volatile?
Quite a few stocks on the move today, not the usual sleepy Friday. Naked Wines (LON:WINE) is breaking new into highs.
Dear Paul
One of the brokers that covers Scapa has today published a note and is expecting earnings of 6p in the current financial year to March 2021, rising to 12.2p in the subsequent year. No dividend is expected this year and 1.88p is forecast the following year. As the analyst was already ahead of consensus estimates, there is only a slight nudge upwards to forecasts . More importantly, debt is forecast to fall to £19.8 million to March 2021 and then £16.6 million in the following year. This suggests to me good cash management following the recent equity raise and of course the impact of losing the Convatec contract which has yet to be resolved through the courts.
The share price response this morning also tells me that analysts are having much more difficulty in providing estimates when this management, alongside so many others, have withdrawn guidance. A multiple of 12x earnings two years out is, in my opinion, still not expensive for a business that was historically very highly rated but where the loss of the Convatec contract has clearly eroded investor confidence and this will take time to rebuild.
Kind regards
Phillip
Interesting reading your summary of PURP. Trying to buy a property via PURP has proved how cheap their price and what utter rubbish is their service i.e. there isn't any!! Wouldn't touch them even though insider buys alert investors. Have found other internet agents far more efficient.
I know a few on this site wonder about the tech boom in the USA. If you are can I recommend a podcast on We Work - WeCrashed: The Rise and Fall of WeWork? its really good.
This was brought to mind yesterday watching Uber results on CNBC - its accumulated losses are now more than $21bn but it still has a market cap of $60bn. I also saw a 'pre revenue' but also 'pre factory being built' electric truck vehicle company which has a market cap of $14bn.
Rightmove (LON:RMV) - the latest financial report is showing decreases everywhere and yet the share price goes up?
Was randomly selected by Imperial College for a swab test, a pre-and-post questionnaire. I have had a message bot sending me reminders to complete the questionnaire, although this has already been done. Nearly 2 weeks since the test swab was completed and collected, and no feedback on the results.
Thank God they don't try and run p**** ups in Breweries.
Obviously Imperial College read Stockopedia as a message has now arrived giving me my results. All clear!
Just published Imimobile (LON:IMO) FY20 results presentation by Jay Patel, CEO & Mike Jefferies, CFO
Video or podcast
You are right about BooHoo and it is entirely (well, for many) due to the good folks at Stockopedia.
Thanks for your post yesterday about Immotion (LON:IMMO) @davidjhill. I looked at the company and bought some - The 15% rise today is pleasing. I agree that their UV steralisation cabinet might be a significant new product for them, with a wide range of applications. I hope they have found a way to protect their IP!
I missed this video https://www.proactiveinvestors... by the CEO a couple of days ago that's worth watching.
The nub of it is that Mandalay Bay VR centre is pulling in £105k p/m already. They've just opened Oklahoma who have seen such a demand they've asked for more seats to be installed and that although the sites they are operating in are at reduced capacity the demand for Immotion (LON:IMMO) VR in these sites is almost at pre-covid levels. That's fantastic!
To me that means that even in a social distancing environment the demand for VR remains robust, people aren't worried as the headsets are all properly cleaned quickly and leisure facilities/aquariums etc desperate to increase revenue will, I suspect, be clambering for their service. I hadn't actually seen the video prior to the announcement on the UV cleaning.
I feel like this could be worth several times the current market cap in a couple of years albeit I temper my enthusiasm a bit given the macro uncertainty. I want to see them profitable and growing as that feels like the inflection point which had just happened pre covid.
I have met the CEO a couple of times. He is credible in my view. Good track record of building and selling businesses (check his bio) and appears highly adaptable to changing circumstance, which I like a lot, especially in such uncertain times. This is a business I wish I'd bought more of frankly.
I responded to your post yesterday on £IMMO ....Uvisan -> product gross margin is in the 70-85% area
thanks Mojo - that's good to know. I have no idea how well Uvisan will sell or how that will play out but I think it appears to be almost an entirely a free option, a rarity in todays excitable covid and tech market. If it does well I'd wager they will spin it out into a separate listing but we'll see.
Well, I enjoy being a good Stockizen....what I know about Uvisan i put here:
https://www.stockopedia.com/co...
As you say, the guys that run the company know how to make things happen and Uvisan is an impressive little wiggle in current environment.
If it has legs it will need resources backing it that they don't have in place right now. The high margin long duration and low competition VR edutainment stuff is higher quality and durability IMO so I'd like them not to get too distracted. The Uvisan opp could be large but short duration. I think ideal structure if it develops beyond a bit of low maintenance and attention short term cash flow is to partner with a tech distribution business that will provide the expansion capital
Have Immotion (LON:IMMO) been able to patent anything novel in their cabinet? Oherwise, their market lead may be rather short.
FREng -> no. They have some distribution exclusives. I don't think Uvisan is likely to be the Immotion (LON:IMMO) story. But they have a product that the market wants (that they knocked up to make their customers feel safer with VR headsets). The VR headsets are not patented either (off the boat from China...but with a significant element of reengineering work from IMMO to make them lighter and cheaper...note that Mandalay Bay has a full set of backup headsets to ensure that there's no unnecessary down time due to breakage etc...this was standard before Covid and probably pretty handy now...it more profitable to ensure throughput when demand is high than ration the hardware). The only thing with significant protection is their VR productions and their 'cinematic' operating system (can't remember what its called technically but they have put a significant amount of proprietary coding and hardware refashioning into ensuring they can operate and sync 36 seats at once, up from 2 when they started out).
All in the hardware is a relatively small cost for all they do and the $$$ cost go mostly to the soft factors around their installations to entertain and suck customers into the experience
I bought Immotion (LON:IMMO) on spec earlier this year (pre-Covid). Having then gone to the O2 to test out the product, I sold it again. I see the O2 site is back up and running - I would suggest London-based investors try it out. (My own view was it was not bad but for me it did not have a “wow” factor.)
O2 and stuff they have in shopping centres is the old Immotion (LON:IMMO) plan. The new one if high throughput edutainment experiences attached to themed visitor attractions (eg aquariums).
I had a small bit a year ago and sold after visiting their Nottingham installation. Was in a gaming shop and was not popular for host of reasons.
The benefit of this shift is that they now don't spend nearly as much money on content.
I wouldn't be surprised if the company exits places like O2 and shopping centres. Partly wrong format, partly much more costly and takes much more interaction with support staff. That said, to date mgt say they stick with it as they want to find the right and higher profit formula in these sites
Watchstone (LON:WTG) people may remember we discussed this around 6 months ago on here as a special situation worth playing. It was 150p at the time with a TNAV exceeding 200p and given the planned capital return of 150p looked like a pretty safe way of achieving a 30-50% return sub 1 year horizon.
Fast forward and the 150p return has been made so I am now breakeven with a free ride on the rest. I see this morning they have finally announced the lawsuit against PWC which makes pretty interesting reading. It is for £63m+++
the market cap is now £26m and this is pretty much all covered by TNAV so it feels to me like the potential for a damages claim of 2-3* current market cap is worth playing out. Feels like my risk is maybe 10p as the rest is protected by cash but my upside is 150p or 15 : 1 ? I'd imagine if the case is strong it may well get settled for less out of court so potential reward is anything up to an additional 150p.
Anyone else still following and have any thoughts? Wondering if it's actually good value and worth increasing holding here maybe too rather than just sitting tight.
I followed your analysis of Watchstone (LON:WTG) and bought some 6 months ago, so I'm in the same position that your describe above. Many thanks for the original posting.
The management seem to have delivered on their promises, so I'm inclined to trust them. I'm considering adding too. I'll certainly continue to hold.
Glad to hear it.
I think part of the value of this type of board led by Paul is that sensible investors can spot these type of opportunities and I would hope would offer them up on here so that we as a community can benefit from the analysis. I try and do that as I'd like others to do the same for me :)
I looked at Watchstone but I'm still scarred from the Quindell saga!
Watchstone (LON:WTG)
I looked at Watchstone but I'm still scarred from the Quindell saga!
I don't blame you Rob Terry was a thoroughly disingenuous shyster of the highest order IMHO - i won't normally get personal on a bulletin board about individuals but i have no qualms saying that about him . I think it was one of the poor Cannacord brokers that stood up to Terry the rest of the city seemed to be happy to play along to his tune - which was make it all up as you go along. To add to the comedy of the whole situation i think Rob Terry even tried to sue Watchstone after he left - ridiculous.
Hi Paul,
I agree with you that the draw tools on the charts are not intuitive! Also just wanted to say thanks again for mentioning which line for colour-challenged people in your report!
Morning Paul - I just wanted to add a few comments after your analysis of Ince (LON:INCE) at the start of the week (for full disclosure I own the stock). Firstly I love your updates and don't know how you keep up with so many stocks! It's great stuff.
I sat on the Investor Meet Company (what a great platform btw) presentation on Wednesday and can add some colour to some things you brought up.
Non-controlling interests: The non-controlling interests (which are huge) at the profit level is an accounting presentation of pure partner salaries as it seems they are salaried out of a separate company - which is a contractual formula so if they earn more this will be higher but so will Ince's revenues. So the company would much prefer to simply present a profit attributable to the company figure and have that cost higher up the P&L.
Deferred consideration on the balance sheet: This is earn-out (I think largely due to the Gordon D/Ince transaction) and they have provisioned for the maximum amount possible in the balance sheet. But to be clear this is only payable if those partners hit their targets and if they didn't nothing would be payable. So call it accrued salary or whatever, and it is certainly real, but there is an element of "if Ince does well we pay this out". Once the Ince acquisition unwinds this will reduce.
Cashflow: The £15.5m outflow on "transitions with non-controlling interests" is again an Ince Acquisition factor and according to the company will not repeat.
Receivables: They are definitely large but much better than the service company I run, and are better than their legal peers (100 day lock up versus 120 on average). It looks like they are conservative in their provisioning.
The (newish) FD: I think he's pretty good, he answered the questions well and clearly has a mastery of the detail and the bigger strategy.
So in summary I know I won't get you to change your mind in terms of investing in listed legal companies (you make some valid points about talent taking all the returns and then walking - and this applies to Ince as well) BUT I believe the market doesn't understand this stock and it is hard to analyse - but will become less so as the Ince acquisition unwinds. The CEO said on the call that the greatest proof of shareholder value is cash generated per share and he is focussed on that. And also that they will think hard about updating the market more often on a quarterly basis. If they can unwind the Ince acquisition with cash generated from operations - and yes the balance sheet is week in terms of cash - I think this stock is interesting. There are listed peers like Knights Group etc who are valued dramatically higher than Ince - they only have to move a tiny fraction towards them to double.
The highly dilutive equity raise at the beginning of the year was down to the third tranche of the Ince acquisition - it still doesn't explain why it was at such a discount - and of course the worry is they have to do the same again (albeit CFO said they are not looking to do so). So no investment case is perfect - but I think on balance if they scrape through COVID and unwind the acquisition without an investor call - in valuation basis this stock is so cheap there is some real upside. A risky one - but perhaps not totally uninvestable!
Hi FM1975,
Excellent stuff, thanks for that. Most of it was pretty much as I had worked out, but you certainly provided some extra colour!
I think the problem is that the structure is so adverse to ordinary shareholders, through the massive partner drawings, that few people would want to touch the shares. Also, the 50% discount fundraising was so bad, that I wouldn't touch it at any price, it's just too risky. The partners are surely hugely incentivised to hit their earn out targets, and will they care what price the next big fundraising is done at, seeing as they'll just want the cash?
It seems to me that it's structured as a vehicle to fleece the ordinary shareholders, for the benefit of the partners. The 50% discounted fundraising rather confirms that!
You're taking a huge risk with this share, I hope your position size is such that you can afford to lose the lot!
Regards, Paul.
Ha! Many thanks Paul - I guess as ever time will tell. Keep up the great work and have a good weekend. Fred
I had a look and it seems it was a company run for the benefit of the partners and to provide them with a structure where they don't have to contribute loans yet get a profit share. Cant see whats in for a shareholder other than to keep providing them with capital to make more acquisitions.
FM1975, I’m concerned your comment about the £15.5m cash flow with non-controlling interests “will not repeat” is not correct. My understanding is that it absolutely will repeat because it is just the cash side of the big non-controlling interest in the P&L (with a timing difference to do with the fact the partners are not paid until the customer pays and taxes the company has to withhold on the partners behalf). To Paul’s point in his reply to you, this is so material to the accounts/cash flow, I would urge you to check this with the company directly if you have any sized position. I will gladly be told I am wrong if I am.
I listened to the call too, and until Monday was a shareholder. I agree with time the new FD will improve things but the accounts are really complicated and I asked questions of their investor relations team several months ago - I sold out because I didn’t feel they had gone far enough to explain things clearly, particularly the deferred consideration liability for acquisitions in the balance sheet which is huge - dig into Monday’s release and they have quietly changed the previous year’s balance sheet to increase this liability further (and increase goodwill/intangibles and changed various other debtors and creditors) with no explanation I can find. They say the acquisitions deferred consideration liability is prudent, but the accounting standards require it I think to also be a fair value best estimate - there is so little disclosure around the range of outcomes that I think it is impossible to get a feel for how much will eventually be paid and whether there is in fact a cushion.
I like the company, and on several metrics it seems a bargain, but I am steering clear until it is clearer what cash return there might be for shareholders.
Just published piworld interview with Richard Leonard - Investor & Trader: Life in a Family Office
Video or podcast
Richard has achieved an average annual return of over 30% pa over the last 10 years. Here is outlines what he looks for to achieve that. Bursting with enthusiasm, together with some great stock pics, with an engagingly honest insight to his reaction to CV19, which many will relate to. Richard believes today is the beginning of an economic cycle, and is a great time for equity investors.
Stocks mentioned:
Polar Capital Holdings (LON:POLR)
Up Global Sourcing Holdings (LON:UPGS)
Redde Northgate (LON:REDD)
Morning Tamzin , I listened (and laughed a lot) to Richards very honest, open and very engaging interview yesterday, might even have learned something. Never seem a presenter so impressed by a listeners question either! (not mine) Good one, highly recommend
Thanks for another great interview Tamzin, an interesting watch and someone achieving enviable returns on average per annum. Also gives me some assurance that many of the stocks he discusses are holdings or in my watchlist, unfortunately most are in my watchlist!
Keep up the great interviews, along with Paul and the SCVR you are providing a very valuable source for us little guys and girls.
My Wife and I are staying in a hotel in Surrey for the weekend and have been surprised that it's completely booked up, restaurants are full and even when we went into town restaurants were busy.
Let's hope it keeps up and people stay respectful and take responsibility to wear the masks when it's appropriate.
I note your comments on Stocko ChartsI find them very difficult on Ipads and sometimes the features just don't work at all. For charts I prefer IG. That said Stocko charts are better than when I first tried them. A lot of traders use Stoicko so good charting is essential
Sharescope is the best for charts. Much quicker than any web based platform, you can look through dozens of charts in seconds rather than minutes. A link up with Stockopedia, allowing access to stockranks etc. directly from Sharescope, would be ideal. Don't know if there's any prospect of this actually happening at some point or if it's ever even been mooted. Would get my vote anyway.
Hi andyd
I think that a great idea to link Stocko with Sharescope. I have been using Sharescope for years now and you right, it is really fast at clicking through a large number of charts.
Ed what can we do?
Yes i agree, have used Sharescope for near on 20 yrs and love the fact i can have many different layouts for a whole range of analysis at the touch of a button . Subscribed to Stockopedia since day one and could not do without that either. Once Stocko ' was under way i noticed that Sharescope upped the standard of its analysis and filtering , possibly feeling the competition. However i would prefer to see them owned as separate entities to keep them competitive and on edge, after all neither is that expensive and easy to switch between with two screens. Yes I do all my stuff on a decent sized Desk top.
Yes you're right. I tried the other day on my iPad with the Apple pencil as i thought it would be ideal. Ended up being a right pain, needs a bit of a tweak to get it functioning better!
Interesting your comments today Paul on pubs and restaurants being so busy. Living way north of the border (Aberdeen) we have seen the same trend and can honestly say, I've never seen the town so busy with locals and tourists. Visiting my folks at the weekend in remote Scotland with sandy beaches full of tourists (unheard of previously). Unfortunately the busyness seems to have been their demise, and we are now back in lock-down with all bars, restaurants and cafes ordered to close for at least 7 days along with local restrictions on travel and visiting. The small rise in cases seems to be attributed to locals going on pub crawls around the city, unaware that they had COVID, and then reporting this to all bars they visited. Shame that cafes have been dragged into the mix and closed down also, having only recently opened again. Scotland does seem to have a harder approach to lockdown and I'm sure Aberdeen isn't going to influence the stock market, but it does show how quickly it all can change with an increasing number of cases. i work in the oil industry and the sector has stayed open throughout, managing the risk with a number of mitigation's. Risk assessing is a daily part of life in this industry, and I believe if the government doesn't take a similar approach (rather than a blanket approach) then the country is going to be shutdown/opened up a number of times over the coming months with the hospitality sector taking the brunt of it in most instances.
Has also been busy in Richmond,Surrey which is why I am surprised that Revolution Bars has not opened its large place,which is situated in an ideal location on the banks of the Thames near Richmond Bridge
website says Richmond and Putney are opening on Monday
Thanks. Bet they wished they had opened today. Already it’s absolutely jammed on the riverside
Morning Ipreidster - Interesting that Scottish Gov advice to Aberdonians is NOT to go away on holiday during the current local lockdown. However working in an office (locally) is OK
The trouble is that Aberdonians travel the world with their Oil and Gas skills, I wonder if large operators will place a ban on vendors supplying labour resident in Aberdeen whilst the local lockdown is in place rather than risk their offshore key operations being compromised?
Sign of the [New times] we will all have to operate in for the forseable?
The oil market in Aberdeen has been volatile over the last 5-8 years, especially with the oil crash a few years back. Service companies (contractors) have taken the brunt of it and are hired when oil price is high and projects are all go, then fired as quick when the oil price drops and projects are halted. COVID has been transformational with oil companies, with the majority working at home (except offshore personnel) and not expected back in the office this year, with companies already stating flexible working going forward. When COVID hit, oil companies went to minimum manning and all vendors were essentially sent home and only a small trickle have returned.
Onshore accepted and understood - I was referring (in the wider sense) to the offshore service company personnel as you describe them. I was proposing that they would NOT be allowed onto offshore installations which are KEY to UK Energy security in case of contamination and disruption to production.
I think operators must be planning some sort of track and trace for the local address of contractors travelling to installations offshore
THAT risk consideration will I am sure be prevelant in this and similar industries until (at least) a valid vaccine is available. = Ongoing increased cost/risk to business?
A number of offshore personnel are classed as essential workers (roles may change depending on the needs to keep the installation running). Most companies I know bring workers to Aberdeen a couple days prior to going offshore into designated hotels where they are COVID tested prior to going offshore. This has been ongoing for a number of months, using private healthcare companies. There may be an increased testing costs, but looking at the overall costs, there may be other savings for operators.... office blocks empty, (heating lighting, catering companies), workers accommodation empty (i.e. those previously working in Aberdeen offices), projects deferred or cancelled, pay-offs, voluntary redundancy drives, minimum manning (where appropriate), and business travel all but brought to a halt, all with little to no reduction of oil extracted. There has also been a big drive over the last few years to reduce lifting costs and increase production efficiency. https://www.ogauthority.co.uk/benchmarking/ukcs-production-efficiency-2019/ . Also, the oil price is slowly sneaking up.........
I live over on the West Coast of Wales. We have luckily all but missed covid so far (only 60 cases in total), everywhere here is really busy. Tried to eat out twice this week (lunchtimes) both places were over an hour wait. The council has now made the towns on the coast one way to cope with the extra pedestrians (widened the paths).
Re, Aberdeen
The more socialist or left wing the (local) Government, the more over the top the over-reaction to the bug, and the less sympathetic to the needs of business and consumers.
Interesting report on Wednesday's Newsnight suggesting the virus has been over-rated in risk and health affects.
Krankie can do what she likes knowing full well that The Barnet Formula and MOD will always bail her out.
Nobody seems to be able to answer what it means if you test positive. Have you had it (maybe without realising), is it a false positve, have you had it and not had symptoms yet, are you now immune and therefore able to go to work etc. The tests have been proven to be highly unreliable and most people have minor if any symptoms if they are healthy.l
Marigold,
There are 2 different types of test. The “Have you got it now?” test and the “Have you had it?” (or antibody) test.
If you contact the NHS with symptoms, you will be invited for a have you got it test. You may have seen these on the news. They require you to stay in your car and insert a swab to the back of your throat until you gag (or your nose which is not pleasant either) BUT if you don’t stick it in far enough, the test may be a false result. Also, like a pregnancy test, a negative reading today does not mean a person may not get the virus tomorrow.
The other type of test is the antibody test. These are available in the private sector for around £80 to £100. My wife (who is a doc) says the ones which are presently available are not reliable as they have a high percentage of wrong results (false positives or negatives). Also, if this test shows that you have had it, that does not mean you cannot get it again. They do not know yet how long the antibodies may be effective for (think flu, which you can get year after year as the virus evolves).
There is a lot of activity in the small company sector in trying to produce better, faster, more reliable tests. See, for example, Ekf Diagnostics Holdings (LON:EKF) Avacta (LON:AVCT) Genedrive (LON:GDR) etc. It is not always clear which test they are working on.
I hope this helps.
Ricardo
There are two different tests. The usual meaning of "test positive" is that you have a positive test from a nasal/throat swab and active virus has been found - so you currently HAVE COVID-19 and might infect others.
The other test is a blood test for antibodies, where a positive result shows that you have HAD COVID-19 in the past few months and are unlikely to be infectious now, though not necessarily protected against catching it again.
EDIT:
It's imortant to remember that a positive test that's 95% accurate doesn't mean you are 95% likely to have the disease - it depends on the prevalence of infections in the population being tested. Let me give a worked example because this always feels a surprising result.
The ONS has been doing random tests and says that 1 person in 1500 in their random tests of people at home currently has the infection. That's the 'prevalence' in the tested population. A random test with 95% accuracy will therefore give 5% false positives in every 1500 people, which means (approximately) that each person who tests positive FROM A RANDOM TEST with 95% accuracy has approximately 1 chance in 75 of having the disease (1.333%), rather than 95%
Of course, the prevalence in some areas is higher, especially in people who are tested because they have symptoms, and this greatly changes the calculation.
Bad maths. 95% accuracy DOES NOT mean the missing 5% are all false positives.
Saw a BBC clip interviewing old boy in Aberdeen city centre bar...he's not impressed.
As an Aberdonian in exile I can tell you its not a socialist city and locals dinnae taak weel ta ootsiders tellin em fit ta dee. Thon gype wifie Sturgeon's got her knickers in a twist o'er a puckle cases o bug.
I don't really know how to write the dialect...being classically trained and all ;) https://media.scotslanguage.com/library/document/RGU_Doric_Dictionary.pdf
Summer is fleeting in Aberdeen and from late August on can get cold and a cold enveloping haar comes in off the North Sea. Nicola's sent a few extra polis up to make people obey...I reckon the younguns will party on regardless
Anyhoo, of the cluster of 54, 4 are my brother's friends after a day out golfing in Aboyne. All are fine (mild to no symptoms)
Hilarious mojomogoz! Love your posts.
Well...I'm pleased someone does...although I hope they don't run you out of the village
Hi lpreidster,
Interesting, thanks. From what I can gather from TV news, nobody is suggesting that a full national lockdown would happen again. They seem to be monitoring things locally, and only re-imposing restrictions where specifically needed.
Re pub crawls - that chimes with what happened somewhere abroad, in the Far East, where one super-spreader visited a load of bars & infected lots of people.
Maybe we need a one venue only per day rule? i.e. a ban on pub crawls?
Hopefully testing should get to a point where we can test ourselves at home, every day, before we go out. That would be ideal.
I'm sure that human ingenuity & all the brilliant minds working on this (I mean the medical profession, not the Govt LOL!) are likely to defeat it. Hence I think if investors sink into excessive gloom, there could be good opportunities missed.
Regards, Paul.
Hi Paul, I agree that local shutdowns will be the way forward and I used the word "country" in the broader sense. I'm long on a number of shares in this sector - it might just be a bumpy ride along the way :). The 90 minute test, if released to the public should hopefully make a difference to bringing us back to some sort of normality whilst waiting on a vaccine!
great job this week Paul no going to Sandbanks beach is full today!
Hi Paul
I know of the following broker's report:
Scapa (LON:SCPA) - 23/6/20 - Analysts at Berenberg slightly raised their target price on healthcare and industrial group Scapa from 140.0p to 150.0p on Tuesday, stating the firm's 2020 numbers were better than it had anticipated.
Berenberg noted that Scapa's full-year revenue and cash generation performances came in ahead of expectations, while trading profit was in line with forecasts.
In spite of this, the SP tumbled on that day
My morning smallcap tweet: Detecting the Undetectable.
I have linked news to RNS pages. Hope it works.
IQ-AI (LON:IQAI) SIMEC Atlantis Energy (LON:SAE) Scapa (LON:SCPA) Newmark Security (LON:NWT) Distribution Finance Capital Holdings (LON:DFCH)
IQ-AI (IQAI) H1(June) rev a paltry £117k down 18%, due to covid? Has a product IB CA - 'Detecting the Undetectable'. Maybe it will foresee profit here. [SP=3.73 Cap=4m]
SIMEC Atlantis Energy (SAE) following Thursday's placing, signs a Heads of Terms in relation to the mooted JV. [SP=12.85 Cap=55m]
Scapa (SCPA) Q1 rev well ahead of covid scenario but no £££. Guides FY trading profit c. 10% ahead of market expectations. [SP=91.6 Cap=171m]
Newmark Security (NWT) wins 2 US contracts, one at least $1m over 3 years, the other up to $3.8m over 2-3 years. [SP=1.3 Cap=6m]
Distribution Finance (DFCH) push back on capital classification on resubmitted banking licence application. Co "will take certain reorganisation steps in respect of parts of the existing share capital within the Group, which will be carried out before any final authorisation decision will be considered by the PRA." [SP=38.24 Cap=42m]
Morning MrContrarian - Just tested 3 random links and they all worked fine - Great update, invaluable. Many thanks (again) for your efforts
Thank you very much, MrC. Always appreciated!
Morning Paul,
I’d be interested in your thoughts on £SCPA. Announcement today that they are trading 10% above ‘market expectations’ whatever they are. I recently sold my holding but remain intrigued.
Thanks