Small Cap Value Report (Fri 7 Jan 2022) - AIR, SAA, JDG, SDI, GRG, NXT, BME, LOOK

Good morning, it's Paul & Jack here with the SCVR. Today's report is now finished.
Agenda -
Paul's section:
M&c Saatchi (LON:SAA) - a rather disappointing announcement, that Vin Murria wants to "merge" her listed cash shell Advancedadvt (LON:ADVT) with SAA in a paper deal. I can't see why SAA would be keen to surrender control to her? Let's await their response (since published, article updated).
Judges Scientific (LON:JDG) - a strong year end trading update, with profit guidance ahead of expectations. 2 brokers have upped forecast earnings by about 10%. Not cheap, but the stunning long-term track record justifies a premium price.
Sdi (LON:SDI) - a small acquisition is made, and an important repeat order is received, resulting in a significant 22% increase in Finncap's forecast for next year FY 4/2023. SDI has a fantastic track record of creating shareholder value, so it's toppy valuation looks justified.
Lookers (LON:LOOK) - yet another out-perform update. It seems car dealers are still enjoying booming profits, driven by a shortage of new and used cars. I very much like this sector, and think it's still far too cheap - even when you adjust for earnings normalising. More takeover bids look likely.
A quick review of yesterday's larger cap retailers updates;
Greggs (LON:GRG) - slightly ahead of forecasts. Too expensive.
Next (LON:NXT) - trading well, ups guidance. Cheap on a PER of 14
B&m European Value Retail Sa (LON:BME) - also trading well, looks good value on a PER of about 14.8 by my calcs.
Just FYI, I'm planning on looking at the following updates as this morning progresses: LOOK, Churchill China
Jack's section:
Air Partner (LON:AIR) - I hold - another materially ahead update, just three or so weeks after the last. Vaccine freight demand continues to drive business. This will revert at some point but could also last for longer than anticipated, which could potentially lead to FY22 upgrades. Assuming it does revert, the group has diversified its operations in recent years and is well-funded for further investment / acquisitions.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
M&c Saatchi (LON:SAA)
210p (closing price y’day) - mkt cap £257m
There’s an interesting twist in this story. The key thing to note is that the announcement this morning of a Potential Merger has been issued by Vin Murria’s acquisition vehicle, listed cash shell Advancedadvt (LON:ADVT) . As yet there has not been a response from SAA.
ADVT says that it wants to acquire (“merge”) SAA via a share exchange. I don’t like this at all. Why would SAA shareholders want to swap their SAA shares for shares in a cash shell? If SAA needs cash, which I don’t think it does, then it could do a placing.
The key question is whether Vin Murria taking control of SAA would result in a better outcome? If this bid approach fails, then her position on the Board of SAA would seem awkward, at best, and possibly untenable.
I’ve had a look at the last accounts for Advancedadvt (LON:ADVT) here, key points -
- Company was incorporated in BVI (British Virgin Islands) in July 2020
- £130m raised in a fundraising in Mar 2021, at 100p per share
- Seeking acquisitions in software sector
- First acquisition target fell through, in software sector (aborted costs of £1.85m)
- Company is a cash shell, with no operating business as yet, with £129.2m cash at 30 June 2021
ADVT has since utilised some of its cash buying shares in SAA, 12m shares at 200p = £24m, hence ADVT would have around £105m cash remaining. The idea is this could be used to enlarge the acquired SAA business, through acquisitions, and settling the previously problematic options arrangements.
That doesn’t strike me as a compelling reason for SAA shareholders to effectively give up control of the business.
Plus of course the clock is ticking for ADVT to do a deal, as there are now time limits on cash shells doing something.
My opinion - I think this is a disappointing development, and if I held SAA shares I would reject an all-share deal, and want to retain my SAA shares.
I’ve just looked at the share price, and the market has reacted negatively too, with SAA shares currently down 16p in early trading, to 192/196p bid/offer price (although you can usually deal within the quoted spread, as with most shares).
Maybe ADVT might buy more shares in the market, as it’s got the cash? I think the current situation is that Vin Murria’s personal shares would be seen as a concert party with ADVT’s holding - so 12.0m (ADVT) plus 15.2m (Vin Murria) = 27.2m, with 122.3m shares in issue (see at the bottom of the StockReport) = 22.2%
Will she be able to strong-arm, or persuade the other big shareholders in SAA to accept ADVT shares for their SAA shares, and effectively give up control to ADVT? I’d be surprised if they do, but you never know.
The other question, is what theoretical valuation any all-paper deal puts on SAA? That remains to be seen.
I shall follow developments with interest, but so far, this looks a bit messy. Lots of talk about digital strategy, etc, from ADVT, but SAA is already doing that, and trading well, so I’m not convinced “merging” with ADVT would necessarily be a good deal for SAA.
EDIT: Here is the response from M&c Saatchi (LON:SAA) itself.
Statement regarding possible offer
This looks a very sensible response from SAA's independent Directors -
The directors of the Company other than Vin Murria (the "Independent Directors") have now received an initial non-binding indication of interest (the "Proposal") from AdvT, whereby AdvT would offer each M&C Saatchi shareholder 1.86 new AdvT ordinary shares for each M&C Saatchi ordinary share. The Proposal is conditional, inter alia, on the recommendation of the Independent Directors.
The Independent Directors' initial opinion is that this all share proposal does not articulate an alternative strategy for the benefit of the Company's stakeholders beyond an initial change of control of M&C Saatchi. Furthermore, the Proposal does not reflect the value of the business and its future prospects and would disproportionately transfer equity value from M&C Saatchi shareholders to AdvT shareholders.
M&C Saatchi's current strategy has been in place since Q1 2021, and has resulted in a number of positive trading updates. Meaningful new client wins include Uber, Google, Tiktok and Tinder as well as new assignments from existing clients including the UK Governmerice nt, Pepsico, Reckitt and Lexus. It is not clear to the Independent Directors how shareholders and other stakeholders would benefit from ownership dilution and a change in board leadership of the Company.
Price - in offering 1.86 new ADVT shares for each SAA share, this values SAA at 98p * 1.86 = 182.3p - not an attractive price, given that ADVT paid 200p in the open market recently for its 12m share stake. Which makes me wonder if this bid approach might fall foul of the regulations. I thought a bidder had to offer at least the highest price they have paid in the market, which would be 200p?
My opinion - this looks an unsatisfactory proposal, and seems a strange thing to have done, without apparently securing the support of SAA's Board. It now hinges on what the institutional shareholders in SAA decide. I 'd be amazed if they support Vin's proposal, which looks to have gone off half-cocked.
Judges Scientific (LON:JDG)
8470p (up 4% at 09:17) - mkt cap £538m
The Board of Judges Scientific plc, a group focused on acquiring and developing companies in the scientific instrument sector, provides the following update on the Group's trading performance for the financial year ended 31 December 2021.
My summary -
- Order intake is good (organic) - up 25% on 2020, and up 8.5% vs previous high in 2019
- “Order intake remains the main driver of performance and consequently the recovery in orders resulted in good progress in revenues.”
- Starting 2022 with strong order book (22.5 weeks revenues)
- Good performance from recently acquired businesses
- Organic revenue was +5% in H1, accelerated in H2, in double digits for the full year
- Diary date: 23 March, for FY 12/2021 results publication
Profit guidance - ahead of expectations, and we get a footnote too, which quotes EPS - the best figure for me, as I can quickly work out valuation from that. Marvellous -
As a result of the positive performance of the Group, the Board now anticipates that Adjusted3 Earnings Per Share for the full year ended 31 December 2021 will be ahead of market expectations4.
4. Market consensus Adjusted Earnings Per Share of 209.7p.
Broker updates - many thanks to WH Ireland which has issued updated forecasts available on Research Tree, for 229.5p adj EPS, and upgrade of 10%, on top of a previous 10% upgrade in Sept 2021). That gives a 2021 PER of 36.9 - a very full valuation, but reflecting the strong recovery from covid impact I suppose.
WHI’s FY 12/2022 forecast is only marginally higher at 236.5p, which strikes me as far to cautious, given the strong starting order book. Maybe we could push the boat out, and imagine that profits might recover to something like 300p EPS? That would reduce the PER to 28.2 times - still pretty punchy. So there’s considerable out-performance already baked into the share price.
Thanks also to Liberum, which has issued similarly upward revised forecasts today, again available on Research Tree.
My opinion - it’s not cheap by any means, but I wouldn’t expect it to be cheap, given strong performance.
Skill at making value-adding acquisitions justifies a premium rating.
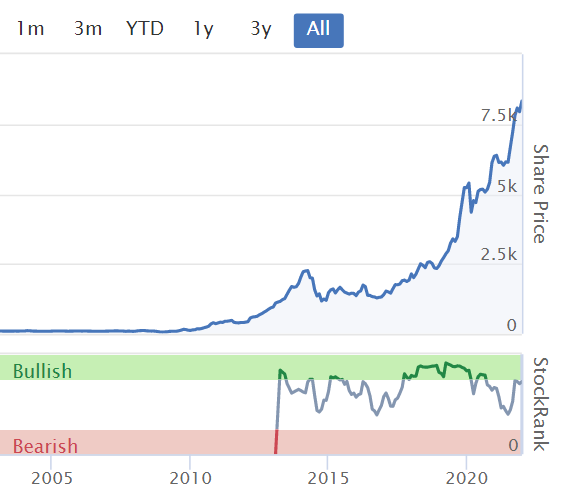
Stunning long term shareholder value creation - a 100-bagger in 12 years. Hence I certainly wouldn’t bet against it.
Although at over £500m market cap, it might be more difficult to find cheap acquisitions that move the dial much, which is what drove previous gains. Feast your eyes on the long-term chart below!
.
.
Sdi (LON:SDI)
210p (+5% at 11:15) - mkt cap £210m
Acquisition, and Further Atik Cameras Order
SDI Group plc, the AIM quoted Group focused on the design and manufacture of scientific and technology products for use in digital imaging and sensing control applications…
This follows on nicely from JDG, since SDI has a very similar business model, in a different niche - building a group from reasonably-priced acquisitions.
So far, the long-term chart of SDI looks remarkable similar to the chart of JDG too, although SDI has only 20-bagged, not 100-bagged!
.

.
The main problem with SDI recently, has been the (fully disclosed) one-off nature of some large orders, hence why brokers are forecasting that FY 4/2023 earnings might fall from bumper FY 4/2022 earnings.
I reported on the interim results from SDI here in Dec 2021. The longer I’ve followed SDI, the more impressed I’ve become with it, and want to buy some for my long term portfolio at some point. Uncertainty over contracts, and the high valuation are the only things currently putting me off from buying.
Acquisition - SDI is buying Scientific Vacuum Systems Ltd, just a small deal, at £4.9m (total consideration, including earnout). That’s just 2.3% of SDI’s market cap, so doesn’t move the dial much. It bolts on £2.5m revenues, and £0.7m EBIT (operating profit). Sounds good, but we have to be mindful that private companies often pay Directors via dividends for tax reasons (to avoid NICs), which is below the operating profit line. So once they become part of a listed company, then that element of remuneration moves up the P&L, and hence reduces EBIT.
Actually, forget that point, because I’ve checked SVS’s accounts at Companies House (co. no. 02538608), and it’s fine - there are only 2 Directors, who were paid £272k (9/2020) and £275k (9/2019), and dividends of only £36k were paid each year.
Profits: SVS made £280k EBIT in 9/2019, just £2k in 9/2020 (lockdown 1 year), so the £0.7m mentioned today for EBIT in 9/2021 is a big jump - what caused that jump in profits, and is it sustainable?
FY 9/2021 accounts have not yet been filed at Companies House (they have until June 2022, 9 months, to file them).
There was a useful £190k R&D tax reclaim in 2020 (2019: nil)
SVS's fixed assets are only £56k, being mostly fully depreciated, old equipment. Does the company need capex to replace fixed assets I wonder? It has cash, so probably would have done so, if necessary.
The acquisition is earnings enhancing, unsurprisingly, since SDI is highly rated (a forward PER of 34.7, from the StockReport here). Hence it’s in that lovely position where it can buy companies on a cheaper rating, thus creating instant shareholder value, as the larger group is rated more highly than the acquisitions. That’s exactly what JDG has done so successfully. As long as the stock market keeps the acquirer on a high rating, then it’s just rinse & repeat with more cheap acquisitions, don’t make any mistakes, and the shares keep going up. What a terrific business model! I like it a lot. SDI’s Board has a lot acquisition experience too, which reduces the risk of them slipping up with a bad deal(s).
Repeat order - more important than the small acquisition is this news today -
Further Atik Cameras Order
The Company also announces that its Atik Cameras division has received a further firm order for cameras to be used in PCR machines, for delivery in the year ending 30 April 2023, extending the series of orders related to the COVID-19 pandemic.
The way I look at it, that defers the problem of falling profitability, rather than eliminating it. But we’re not given any figures, so I can’t quantify it. Thankfully we have 2 broker note updates to guide us today, Finncap & Progressive.
Finncap will have spoken to the company no doubt, so its forecast increase should be reliable. We now have 6.9p EPS for FY 4/2022, and a 22% increase in FY 4/2023 EPS to 6.4p - note that it’s still 7% down on the current year though.
That’s a very high PER still at 32.8 times for FY 4/2023 - a really punchy rating considering earnings are still forecast to fall, so I don’t think I can bring myself to pay that much.
My opinion - I like SDI more, now the cliff edge on earnings from expiry of one-off contracts has been pushed out another year. That reduces the shorter term risk to the share price.
I think the bull case with SDI is to look at the great long-term track record, and forget about short term valuation. I’m slowly persuading myself to bite the bullet and buy some, but am not quite there yet!
FYI, the StockReport contains an error, saying that 2 brokers rate SDI as a strong sell. That’s wrong. I’ve just raised a green blob, to ask Stocko HQ to contact the data provider again, and get this corrected.
.
The following 3 items are not small caps, but I've looked at them anyway, so might as well share my notes from yesterday.
Greggs (LON:GRG)
FY 12/2021 outcome “slightly ahead” of previous exps (although note that consensus forecast more than doubled from April 2021 onwards, from 50p to 110p)
Intending to accelerate growth in store numbers, 150 new ones in 2022 planned
Brought forward staff pay rise by 5 months
Cash of £198m
Special divi £30-40m planned
Inflationary pressures increased in 2021
My opinion - a lovely business, but I can’t get anywhere near the current valuation of 3000p (it recently peaked around 3400p, which was crazy. Forward PER of 26 is just too much, given that earnings growth could be more difficult to achieve against increased cost headwinds (e.g. Living Wage going up 6.6% in April 2022). Plus business rates coming back.
GRG product is cheap, it’s the Wetherspoons of takeaway food, so upping prices by say 5% probably wouldn’t affect demand.
I wonder how many more stores it could add, without cannibalising existing?
More people working from home in future, irrespective of covid, could be an issue too. Although GRG seems to be doing well on deliveries. I tried it out, and ended up with a big bag of lukewarm stodge! They're much better in store, fresh.
Overall then - smashing business, but too expensive for me.
.
Next (LON:NXT)
The pinnacle of reporting, as usual. Although the focus on 2-year like-for-likes is less transparent than usual.
Profit guidance for FY 1/2022 increased by £22m to £822m (530p EPS)
Profit guidance for FY 1/2023 up 4.6% to £860m, or 554p EPS (before benefit of buybacks)
Further special divi of 160p
Low inventories
Labour shortfalls hit delivery service levels
Tougher environment expected in 2022
Cost inflation expected, so raising prices
My opinion - fabulously well-run company, I remain a long-term bull on Next. Forward PER is only 14 - that’s cheap for a business of this quality.
.
B&m European Value Retail Sa (LON:BME)
Q3 (to 25 Dec 2021) was good - FY 3/2022 EBITDA expected to be £605-625m (consensus is £578m).
Applying same uplift to EPS, I get c.42p EPS. That’s a PER of 14.8 - looks good value, for a growth company. I’ve not looked at the balance sheet though, so if it’s highly indebted, that would need to be adjusted for.
.
Lookers (LON:LOOK)
72.3p (up 3% at 13:32) - mkt cap £282m
Lookers, one of the leading UK motor retail and aftersales service groups, today announces a trading update for the financial year to 31 December 2021…
Strong trading continued in Q4. As we know, the whole sector is coining it in, due to fat gross margins on new and particularly used cars, due to supply shortages. That’s obviously a short-term bonanza, so we have to be careful to value shares in this sector or normalised earnings.
Lovely clear guidance provided here - this is even better than a footnote, we’re given the market consensus figure in the key highlights section at the top of the announcement -
… expectation of record underlying profit before tax ahead of company compiled market consensus of £82m
Trading in Q4 remained strong and above the Board's expectations, principally driven by excellent new and used vehicle margins, a continued focus on tight cost control and like-for-like growth in aftersales revenues.
Throughout Q4, the ongoing global shortage of semi-conductors continued to place pressure on the supply of new and used vehicles. In Q4 like-for-like new retail unit sales increased by approximately 2.0% and used unit sales were down by approximately 14.2%. Aftersales revenues remained robust and on a like-for-like basis were approximately 7.1% ahead of last year.
Estimates have been beaten again, despite having quadrupled from original expectations for 2021.
"2021 was an exceptional year for Lookers and we now expect to beat our previous estimates with record profit for the year…
Asset backing - this is what I particularly like about the car dealers - with many of them you’re not only buying a business that is making bonanza profits, but it’s also asset backed with freehold property -
strong balance sheet, with net cash* of approximately £8.0m as at 31 December 2021 (2020: net debt £40.7m) and property with a book value of £303.9m (equivalent to 77.8p per share) as at 30 June 2021
Outlook - cautious. Profits probably only have one way to go, after such a remarkable year in 2021, i.e. downwards. But we already know that.
The Group has had an exceptional year in 2021 and is starting 2022 with an excellent new car order bank. However, given ongoing global supply chain disruptions, uncertainty as to the availability of new vehicles and the sustainability of used car margins at current levels, the Board believes it is right to remain cautious.
The Board is also conscious of general inflationary pressures and increased utilities costs, and is managing these risks through a continued focus on working capital management and tight cost control. The Board is confident that the Group remains well positioned to capitalise on the opportunities ahead and achieve its financial expectations.
Dividends - are set to resume, this is confirmed.
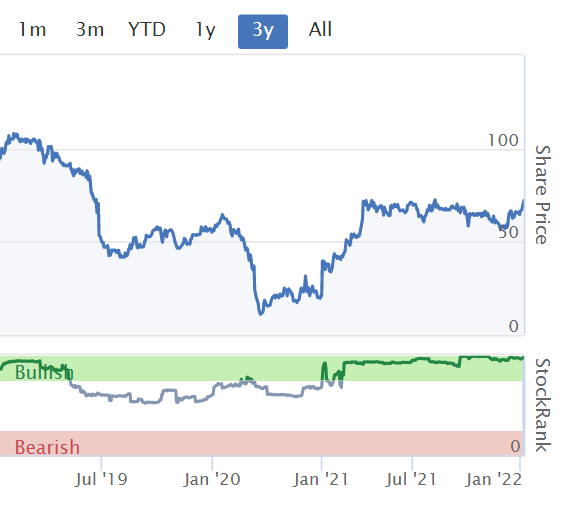
My opinion - I like this whole sector very much. Valuations are still low, even if you normalise (i.e. reduce) earnings to a more sustainable level. Plus the listed car dealers have loads of freehold property (plenty with alternative use value).
The icing on the cake is takeover bidding activity - Marshalls Motors has recently sold for a nice premium, and I expect more to follow.
Global supply constraints are good for car dealers, so let's hope supply chains remain in a mess.
There seem to be new internet-only competitors cropping up all the time. I reckon they’re the most likely buyers of existing chains, as they begin to realise they’re not disrupting anything - conversion rates are tiny, because most people want to test drive, and carefully scrutinise a new car, not buy it blind on the internet. Existing dealers offer an internet-only option anyway. Plus existing dealers have better sourcing, via trade-ins of new vehicles, and relationships with manufacturers. I cannot recall ever seeing so many new entrants flock to “disrupt” a sector that is so unsuitable for disruption! Hence why I suspect internet disrupters might need to buy up existing dealers, to paper over the cracks of their wobbly business models.
There's more info in today's update about strategy & growth plans, if you're interested.
.
Jack’s section
Air Partner (LON:AIR)
Share price: 86p (pre-open)
Shares in issue: 63,562,601
Market cap: £54.7m
(I hold)
Having held for a couple of months now, Air Partner strikes me as a slightly frustrating share in that it has a habit of staying rangebound despite good news. I’m not sure what to make of that, but the group has traded well through the pandemic and has also released positive updates post-lockdown thanks to an increasingly diversified range of air travel activities.
It’s a short update, with the key paragraph below:
As a result of continued strong customer demand throughout December, the Board of Air Partner now expects that underlying profit before tax for the 12 months to 31 January 2022 will be materially ahead of market expectations at the time of the December 2021 trading update. December's performance has again been driven by high levels of Freight bookings, notably for the continued transportation of vaccines.
Revised broker forecasts as of the 17th December were for FY22 profit before tax of £7.8m and earnings per share of 8.9p.
Between the SCVR posts and user comments, we’ve probably written a book’s worth of commentary on the supply chain situation and its effect on various companies over the past year. It’s a pleasant change to write about a beneficiary although increased levels of freight due to vaccine demand sounds like a temporary rather than permanent growth opportunity.
At some point that demand will revert but there’s no let up in vaccination campaigns so far. The group’s previous update was just a fortnight or so ago and that was materially ahead too. So we’re materially ahead of materially ahead.
The cash position remains strong with net cash of £12.9m as of 31 December 2021 (31 July 2021: £9.8m), up from £12.7m on 30th November. This figure exclues customers' segregated JetCard deposits and a £1.4m provision for deferred consideration on the Kenyon acquisition.
Conclusion
I think the stock looks reasonably valued given the trading momentum. It’s on a forecast rolling PER of 10x (and likely less given today’s update) with a growing net cash position. Canaccord has proven to be very conservative in its post-Covid adjustment and looks to have increased its earnings per share forecasts four times since then. There will likely be a fifth.

If we upgrade by 10% to PBT of £8.58m and EPS of 9.79p, then that implies an FY22 PER of 8.8x or just 6.7x adjusting for net cash.
This is a transitory freight boost though. Note how forecasts for the following year have not increased in line with this year’s. But, on the other hand, it’s entirely possible that vaccine-related freight demand will persist into FY22, in which case additional upgrades are likely (holding all else equal).
In the meantime, higher earnings will translate into greater cash flows and year-end balances. Air Partner already has a solid net cash position excluding jetcard deposits, along with diversified operations (and an asset-light business model generating reasonably high returns on capital). So there’s a healthy financial platform to make further acquisitions and organic investments.
It reported in its previous update that it had handled the transition to post-lockdown well, with broad growth across its divisions, so I’m not too concerned about trading prospects once this vaccine freight dynamic has faded. Here’s the FY21 operating profit split from Cenkos. Note this includes heightened freight demand.

Dividends have taken a knock in recent years, but the sheer length of time over which cash has been returned to shareholders is notable, as are the old special dividends, although that’s from quite a while ago now.

I’m happy to hold this one given the valuation and trading momentum. Air Partner’s multiples are at low levels so there’s a chance of both earnings upgrades and multiple expansion.

GIven net cash, acquisitions etc. I think it can get back to FY19 levels of 10p or more per share at some stage. It’s worth noting that pre-Covid forecast EPS was trending at 13.2p. On 12x earnings of 10p that would be a share price of 120p, +40%, at which point I might reappraise the situation. But I think there are decent longer term prospects here too, hopefully beyond that level, so I wouldn’t necessarily be selling.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
Positive take on M&c Saatchi (LON:SAA) situation from Richard Holway this morning:
''
Vin Murria strikes again!
Richard Holway, 08:25, 07 January 2022
I’ve known Vin Murria for well over 20 years back to her (and my) days with Elderstreet. Together she took on the small and loss-making Computer Software Group in 2002 and sold it for £500m in 2007. How in 2008 she turned her attention to Advanced Computer Software and grew it from scratch before selling it to Vista in 2015 for £765m. I was involved as a shareholder in all these transactions. I also had a bit of involvement when Vin was rightly awarded an OBE in the 2017 New Year’s Honours . Many call Vin the ‘Queen of UK Tech’ – I would concur!
In the last c5 years Vin has been involved as an NED in several companies – most notably Zoopla, Softcat and Bunzl – as well as backing a variety of smaller private companies eg Celetron .
In May 2020, Vin took a stake in the then much troubled M&C Saatchi. I fully declare that I am a bit of a Murria groupie. Whenever I learn that Vin has bought a stake or become an NED (BTW - always by reading it in the press!) I tend to follow suit. Vin was appointed to the M&C Saatchi board in March 21 a few weeks before she launched her SPAC - AdvancedAdvT
On Wednesday, AdvancedAdvT bought a 9.82% stake in M&C Saatchi and told the board to expect a takeover bid ‘in the near term’. As you might expect, M&C Saatchi shares have surged. Indeed they have now nearly tripled since I bought in 2020… BTW – It has been virtually impossible to buy shares in AdvancedAdvT – which was probably no bad thing as they have slumped on this news!
Since Vin joined the M&C Saatchi board the old board has been replaced and a new CEO appointed. The results have been really encouraging. Knowing Vin, she will use M&C Saatchi as her first block in building a bigger group by a series of acquisitions. Interestingly, M&C Saatchi new clients in the last year have mainly been in the digital tech world – Uber, Google, TikTok and Tinder to name but a few. So I can see the building of a group of digital media assets. A very good place to be methinks!
Those with access to the HotViews archive can read the many posts I have written about Vin. I suspect I will be writing many more in the near-term future!''
The problem I have (which doesn't matter, as I sold my SAA shares a few weeks ago, thinking they looked fully priced), is that Vin Murria is not a PR specialist, she's a software specialist. Her approach mentions focusing on digitalisation, but SAA is already doing that.
SAA has done a great job in fixing historic issues, and above all improving trading, with a series of strong, out-perform trading updates from mid-2021 onwards, hence why I turned positive on this share in H2 of 2021, eventually buying some.
That doesn't strike me as a situation where a turnaround, and change of strategy or control is necessary, or beneficial. Combined with it being an all-paper offer, where ADVT shareholders are effectively trying to buy a slice of SAA and hence dilute existing holders, and take control, for no particular benefit to existing shareholders.
I think this approach looks ill-judged, and likely to be rejected by independent major shareholders.
Should Vin Murria resign as a SAA Director, if (as seems likely) the bid falls through? I suppose that depends on whether talks are amicable or not. If she backs down, and issues a statement saying she remains a supportive shareholder & Director, then maybe she could stay on. Or maybe shareholders would want her out?
A fascinating situation anyway, which I'm enjoying following!
Regards, Paul.
10 year treasury yield at one-year high of 1.80%. Watch out US tech holders?
Duplicate
10 year treasury yield at one-year high of 1.80%. Watch out US tech holders?
US tech ex FAANG is down 30% already in little over a month. We regret that your warning comes a little late for us, though your concern is appreciated :-)
The key is where does it go from here? :)
Also it is not just tech shares that are hit, but a whole range of other implications. Heavily indebted companies, on floating rate debt (to LIBOR? EURIBOR? etc) will face steeper interest rate costs next year. Of which many had never forecasted. That, along rising input costs (labour, raw materials, etc) is going to make 2022 really difficult for some companies, IMO.
In addition, companies below investment grade that have benefited from easy refinancing of their debt, will now face difficulty as the junk bond market liquidity dries up (since debt investors will have better yields in investment grade debt). What implications does that have?
Where could it go? With an increasingly hawkish fed , it could go up a lot more….
Bad news for tech.
I posted the trade plan shown below on Jan 5th, in the scores on the doors thread.
The upper section of the head has just completed on this week’s weekly candle. I remain short.
Quarto Inc (LON:QRT) interesting that Lion Rock has bought a further 1.2m shares in recent weeks - at an average of 119p. given the price a few weeks back and the trading volumes they must have paid up to 125p for a good chunk of those.
QRT has huge H1 profits and gave a +ve trading update. the growth in the books sector this has been confirmed by industry stats, by Bloomsbury Publishing (LON:BMY) and by Lion Rock itself.
there is the potential of the triple benefit here of rising profits, reduced debt and higher rating. cuurently the shares are rated a fraction of £BMY.
the chart looks very solid.
the Stock Rank = 99, having been in the top green zone for over 2 years.
disc i bgt today
First mention I have seen of £QRT on Stocko for a long time. I bought in last year. Simple strategy as a starting point - looking for top ranked shares on Stocko which also had significant director buys. Then saw that they had been steadily reducing debt and turning the business round in an industry ( publishing ) that was doing well. Lots of discussion about Bloomsbury and other publishers but almost no discussion of Quarto on here or any of the bulletin boards. Have watched it quietly and steadily climb. With another 12% lift today I am now over 50% up on this one which is of course satisfying. As you say, potentially triple benefits and much further progress with this one. A similar strategy with a share which has had a huge amount of discussion on here has not been so successful. Great stock rank and directory buys at Volex (LON:VLX) but I am currently 10% down on that one. Certainly holding though as it is usually a good strategy and the metrics and potential for Volex (LON:VLX) remain.
Not sure Air Partner (LON:AIR) has necessarily said its expectations are “materially ahead of materially ahead!”. The company said in December that it expected FY PBT to be materially ahead of market expectations. Today they have said expected FY underlying PBT will be “materially ahead of market expectations at the time of the December 2021 trading update”. So it is not clear to me that the company’s expectations have improved in the last thee weeks.
Anyway I continue to be a sceptical holder (and will continue to try to be sceptical about all my holdings).
"Following the announcement (https://tools.eurolandir.com/t... by Air Partner, the global aviation services group, on 17 December 2021, the Company is pleased to report a further positive update on trading for the 12 months to 31 January 2022" - I read that as an improvement in the last 3 weeks although agree not clear and some numbers would have been helpful.
My modelling suggests even with freight normalizing to 2019 levels P/E is still below 9 once accounting for the growth in PJ business, the return of Group Charter and Safety/Security revenue streams (incl. Redline acq which has had no impact to date), and the recent Kenyon acquisition. Plus net cash equated to c.25% of the market cap. It is still only a small-mid sized position for me given the noise in the numbers and lack of historical evidence of value accretion from recent acquisitions vs. consideration paid.
Thank you Alan Partridge & davidjhill for your very interesting responses to my post today on £TSL.
Like you Alan I do see $SQ. as a giant in the making but the deal is very complex and I would say a very rare situation given Thinksmart (LON:TSL) is listed on AIM and Afterpay is Australian and $SQ. is listed in the USA. I had not considered the point you make about crypto. It did not cross my mind!
Prior to my top up today I held 40k Shares in Thinksmart (LON:TSL) so under the formula announced by the Thinksmart Board my Shares would equate to 232 Shares in $SQ in late January if the deal is agreed by the Thinksmart Shareholders on 14th January.
At todays exchange rate US Dollar to the Pound my Shares in theory would be valued at anything between £25k and £51k depending on the $SQ. SP over time. In arriving at these numbers I used yesterdays closing price of $144.73 and $300 in time.
I suspect david that you have a far better understanding of this deal than I do but I share your views about the Board of Thinksmart who I feel should have given a much more detailed RNS given the complexity of the deal.
Thanks again to you both it proves again the deep value to me of Stockopedia.
Sdi (LON:SDI) has only 20 bagged We wish???
Hi Benson,
Sdi (LON:SDI) has only 20 bagged We wish???
I've got an approximate share price of 10p for SDI in 2015, and c.200p now, so a 20-bagger, no?
Paul.
I have held for about 4 years and was saying that I wished that I had the full 20 bagged sorry if I misled
With regards to Greggs (LON:GRG), 'I wonder how many more stores it could add', I think Newcastle has some more space for Greggs....
yeah totally agree it’s really annoying when walking from the cluny to the botanist that there is no greggs on route - bir of a disgrace as that’s a good 15-20 minute walk so deffo nowhere near saturation level even in the toon
When I was last in my home town, there was just one Greggs ... up by the Haymarket. Wish I'd been interested in investing way back then (and seen the possibility). Could have made a sizeable fortune.
Greggs (LON:GRG) - there is limited comparison with Weatherspoons (historic interesting estate in a lot of popular town centre ish locations and sell beer cheaply). Greggs (LON:GRG) growth I thought was road users - to compete with The McD, not some town centre caf or bakery - nice little businesses on their own but not investments. It's about real estate - there are only so many roundabouts with services attached so once in place then nobody should be able to squeeze you out. Some ex travel agent shop convert into a sausage roll heater is wasting energy. If M&S start to do hot food in service stations and close down the competition then the rest can have their 'cafes'. All depends on whether we can afford to drive anywhere of course in the not too distant future.
re M&c Saatchi (LON:SAA) ... I am thinking its potentially interesting as a non holder but don't know M&c Saatchi (LON:SAA) well.
I accept as an existing M&c Saatchi (LON:SAA) holder an all share deal on the face of it is unattractive. I wonder if holders were expecting the company to raise money at some point?
Vin has revealed her hand and, as an old institutional backer of Advanced Computer, my experience was very positive. She has a good track record with acquisitions and a cashflow focussed approach.
Clearly to merge with a cash shell is dilutive and as Paul says, they could just raise the money themselves. However this would also be dilutive. How much money do they need? On the face of it, none, they have £32m net cash which matches the put costs, give or take. However, its possible this then boxes them in re acquisitions. If the target pool is rich then raising £130m at the current share price give or take could be seen as attractive, could it not? Id venture a pretty significant discount if the company did a rights issue as part of a deal. The put option alone was reported as 20% dilutive.
The real issue whether a holder or not is how quickly that cash will be deployed... increasing the value of the business.. creating a more meaningful entity ... offsetting the dilution from the cash. I would see the more significant role of Vin as positive here.
Given Vin is a shareholder and on the board, deputy Ch. I wonder if this is semi friendly, can we sell it to shareholders? Possibly they can actually and whilst its not the 30% pm you normally get the longer term upside could be much more. The additional firepower could add 50% plus value added by the M&c Saatchi (LON:SAA) management team... a wild stab in the dark, team Vin offers 100% upside Vs maybe a cash bid of plus 30% Vs what as an existing business?
The downside for me, as a non holder, would be it doesn't go through. I guess the board have sort of revealed their hand a little... and so Id be interested in backing team Vin not so much the existing team. Happy to hear what im getting wrong.
duplicate deleted
Thanks for the note on Judges Scientific (LON:JDG) Paul. I think I commented on its valuation back on the last update in September that its price was lagging the international market in high ROCE Life Science mid caps. I checked the valuation only yesterday after a 20% gain in the meantime, expecting to see greater parity, only to find that the name still lags peers. It’s not cheap by SCVR standards, for sure. But the price still looks unchallenging next to global peers in this highly regarded segment. I’m a holder for some time and agree the valuation might be intimidating but I’d encourage others to look out for dips, which inevitably occur.
Thanks BnB for pointing out that Judges Scientific's valuation may not appear so expensive in relation to global peers. I would add that successful serial acquirers also tend to attract higher valuations, such as the clutch of successful companies of this type in Sweden (I don't know why there are so many in Sweden) most of which are on higher p/e's than Judges. Examples include Lifco AB and Addtech AB, both of which have a p/e of around 50. I'm not suggesting they merit this, but Judges and SDI look cheap by comparison.
I think the situation for M&c Saatchi (LON:SAA) is a potential misstep for Advancedadvt (LON:ADVT) unless somehow for the board they see a personal and shareholder advantage in being part of the merged entity.
There are no listed Company savings, and all the usual disclosures, so no material personal benefits for the board, or shareholders.
I don't know to what extent Vin Murria has consulted other block shareholders in M&c Saatchi (LON:SAA)?
But this looks a little opportunistic. Her reputation is very much based on a history of buying software businesses with recurring income, on relatively low cost buy-outs, and then judiciously incorporating them into a consolidating vehicle on the market with a much higher multiple, creating an earning enhancing reputation.
This is quite different given that M&c Saatchi (LON:SAA) is on a reasonable multiple already, and Advancedadvt (LON:ADVT) has no reputation in the market. Effectively it seems to be a swap of shares for the cash which is sitting unused in non trading cash shell.
Locating a company in the Virgin Isles, as Advancedadvt (LON:ADVT) it seems to me achieves usually a few aims. One is disguise the underlying shareholders. The other is avoiding some of the takeover rules, due to jurisdictional location. I suspect the third possible is tax treatment, but I am not sure what benefit that is if you are a UK resident, as Vin Murria appears to be. Not sure therefore if they get the total benefit of Virgin Isles registration, given the shareholdings of Advancedadvt (LON:ADVT) seem to be known, and I not sure of the status of her vehicle if it is fully listed (or is it AIM listed?), as this may affect takeover procedures. She will no doubt have had some smart advice.
We are back to being a no premium merger with no obvious benefits other than to give Advancedadvt (LON:ADVT) something to do with its cash. So, the Chairman of M&c Saatchi (LON:SAA) really has a job to do to assess the benefits for shareholders. Of course he might think if they were on the point of diluting shareholders to raise cash, there might be some benefit to such a move, depending on the terms.
I sold half my shareholdings in SAA yesterday at 205p as having a shrewd value investor effectively endorsing your analysis is reassuring but being shrewd they want to extract the maximum benefit for themselves which isn’t often in your benefit so it is a bit of a double edged sword.
Hence my decision to lighten my holdings once the share price was above the price paid by Vin Murria’s most recent purchase.
I seem to remember investing in the past in a couple of companies Peter Gyllenhammar had an interest in. He did well - me less so.
jonno thanks for your comment on Thinksmart (LON:TSL) ref Simon Thompson of IC.
I did read his piece last night which concludes that he sees the SP fall as a buying opportunity. I added this morning. I first bought in at 20p in June 2020.
Air Partner (LON:AIR) - the problem here is that the company has embarked on an acquisition spree that so far seems to have destroyed value. I assume the market worries that profits will continue to be diverted to building the empire.
Air Partner (LON:AIR) (I hold)
Hi shipoffrogs
I actually hope that the company does keep empire building or, at the very least, that they start buying back shares for cancellation.
I would prefer the above over any sort of special dividend.
I have no idea when, but all else being equal, eventually the share price will catch up with the reality of how much cash is consistently generated year after year, something which should grow with each new acquisition.
Cheers
A
Abtan - I suggest you look at the post acquisition records of the companies they've bought - the accounts can be found at Companies House.
Air Partner (LON:AIR) (I hold)
Hello again shipoffrogs,
I have actually looked at some of the subsidiaries in Companies House and came to the conclusion that they didn't really tell me much.
Cash flow statements (which contain the key metrics that I look for) are often not included and it was hard for me to discern what synergies, cross-selling opportunities/realisations or intra-group transactions were affecting the accounts that were published.
For balance, I certainly recall impairments in the Parent accounts, and there was one where the impairment occurred relatively quickly after acquisition (was it Redline?)
But to be honest, if the parent cash generation is strong - as it appears to be - then I'm okay with the occasional acquisition not working out.
I actually think the group's diversification has been crucial over the last 2 years, and is reassuring for the future too.
A
Morning Jack
Thank you for your review of Air Partner (LON:AIR) . I have held for quite sometime. I remember adding at 46p when it, like all shares plummeted at the start of the pandemic, thinking what a bargain, only to see it bottom out at 17p the following day. Still I have added since, most recently around 77p. I am confident that if it continues to execute well, discounting any one off pandemic benefits, it will eventually be awarded a higher market rating.
JCPr and abtan make some very valid points below, with which I agree.
I wonder if any subscribers hold Thinksmart (LON:TSL) a share which attracts very little attention on Stockopedia.
I am a long term holder and it represents 5% of my portfolio.
The SP has fallen rapidly since the Board of Thinksmart issued an RNS just before Christmas. It is an interesting deal which if approved by Shareholders on 14 January will see Shareholders end up owning shares in SQUARE in the USA.SQUARE is to be renamed BLOCK.
SQUARE is a Tech business in the BNPL field and has the potential to become a very big player but whose SP has fallen recently due to the threat that the FED will increase interest rates.
Any comments from those investors better informed than me would be much appreciated.
£TSL has very recently been revisited by Simon Thompson on the Investors Chronicle website.
Block is run by Jack Dorsey, ex Twitter CEO. The change of name reflects a pivot to blockchain and crypto, something which divides opinion.
So you need to decide how you feel about that.
I am a Thinksmart (LON:TSL) holder and, whilst I'm gutted at the share price decline in the last couple of months, I'm happy to sit tight and become a long-term $SQ shareholder.
It's a very strong founder-led international business with a track record of execution and high growth, along with a secular tailwind behind it. It also provides crypto exposure without having to actually own coins.
Holding Thinksmart (LON:TSL) effectively enables you to own $SQ at a wide discount, which in turn has a lot of upside itself. I think the average target price for the scores of brokers that cover the stock is around $300 dollars when it's currently trading at half that (as are many high growth stocks in the US, probably due to current Fed tightening).
Personally, I'm being greedy when others are fearful!
Thought it was a shocking deal personally. Investors had been led to believe there was a material crystallisation event in cash coming in 2022 or 2023. That now changes to an open ended punt on Block. The business Thinksmart (LON:TSL) sold into Afterpay is now so diluted away from having any meaningful impact on your investment return that you are no longer really exposed to it. The board, in an attempt to justify it talk about benefits of diversification, but frankly that is laughable. They've effectively exchanged the keys in a massively growing business to a punt on Jack Dorsey, whilst more than halving the value at the same time!
The company was always at pains to point out the specific and measurable parameters that were set out in the sale and purchase agreement that would be used to independently determine the put/call price. To then cite uncertainty of valuation as a reason to accept the share swap to me either means the parameters were far from measurable or there was another reason for accepting the shares. The board noted in a recent RNS that the number of shares referenced in the RNS was solely attributable to Thinksmart (LON:TSL) shareholders. The ESOP element will be satisfied separately also in Afterpay shares.
Nonetheless the directors own 40%+ of the business so they are obviously somewhat happy to take a punt on Block despite my misgivings but don't kid yourselves that you're somehow owning Block at a discount. Block did the deal with Afterpay when they were priced at something like $250. Given the subsequent massive fall in Blocks share price I imagine Afterpay shareholders are probably now wishing they hadn't sanctioned the deal. The shares in Block will not be fully reflected in the Thinksmart (LON:TSL) share price until they are converted to cash, there is always a discount applied.
Which means you are left with a choice - have an open ended 3rd party interest in shares in Block, which could be worth considerably more or considerably less, when finally liquidated, or get out when you can find an appropriate discount and take the pain. Yes, analysts all think it is worth $200-300 p/share but I wouldn't want to be reliant on analyst target prices! If you assume you want to achieve 15% compound growth from here given that you're probably looking at 2 years plus to realise the assets then Blocks share price will need to exceed $200. Is there better value around at lower risk? - quite probably!
Not a great choice shareholders have been left with then. From my lens the board appear to have managed to snatch a heavy defeat from the jaws of victory!
Edited : I see there was a clarification that the ESOP rights to 35% of the sale proceeds fell away so part of this was post not relevant so deleted.
RE: Thinksmart (LON:TSL)
Not a great choice shareholders have been left with then. From my lens the board appear to have managed to snatch a heavy defeat from the jaws of victory!
As I've noted before, Afterpay held the TSL stake in Clearpay in their audited accounts at a far lower level than TSL's independent valuation. In fact, roughly at the level that TSL's shares have fallen to.
This was never definitive, obviously, as the valuation process agreed between the parties has never been disclosed but when you have two opaque valuations and the only possible buyer values the asset significantly less than the seller does it's only reasonable to assume that the eventual price will be somewhat closer to the former than the latter.
The whole thing is deeply unsatisfactory but the information was in the public domain to allow investors to make their own judgements. As for Block - well, I've never understood the valuation.
timarr
The problem with that is that you were not comparing apples with apples. There were big timing differences and the accounting rules and basis in each country are different. Given Blocks share price the valuation may now meet an accounting valuation Afterpay used some 15-18 months ago, but that is just completely random.
The point was that according to Thinksmart (LON:TSL) the independent valuation parameters were designed to be measurable and therefore have minimal room for difference when it actually came to the negotiation. Nothing was ever mentioned about the Put/Call being paid in shares of another company! As it happens the price - ie number of shares Afterpay have agreed to pay to Thinksmart (LON:TSL) works out at around a NAV of 125p if you use the Block share price as at the date of the offer for Afterpay, so not so far from Thinksmart (LON:TSL) stated valuation at the time. The problem has been the collapse in Block, which is what shareholders now finally get whereas what shareholders expected was cash!
RE: Thinksmart (LON:TSL)
The problem with that is that you were not comparing apples with apples. There were big timing differences and the accounting rules and basis in each country are different.
Well, as of 30th June last year Thinksmart valued the Clearpay stake at £125 million based on an unpublished independent valuation method, so no accounting rules involved. On the same day the Afterpay FY21 results calculated the value of the stake at just under £50 million.
From the announcement by Thinksmart on 20th December the valuation of the Clearpay stake, in Square shares, was calculated at £78.1 million, which appears to be the price the TSL directors agreed to strike the deal at, not the Block price at the time of original Afterpay / Square deal.
However ... 35% of that £78.1 million goes into the employee share option scheme so the actual value of the stake at that point was just over £50 million. However, even if we're generous enough to backdate that deal to the original Square / Afterpay transaction it was still only worth £73 million to shareholders.
The best you can say about it is that Montarello and Gammell have got plenty of skin in the game.
timarr
No - what they did was agree on a number of Afterpay shares that convert to Block shares (618,750). That number would be the same if it were at the time of the offer or now.
At the time of the offer Block traded at $260 so the value would have been £125m + £6.5m in other assets = £131m. This equates to 125p
Today the value of those shares is £65m + £6.5m = £72m or 67p
This is the amount that goes to shareholders for the 6.5% stake (ie the 35% ESOP is already taken account of in the shares to be issued).
So the value agreed upon is 125p at the time of the offer and 67p now.
(Remember the price formula included reference to the Afterpay share price so given the falls in that todays price would be different to that on the date of the offer, even if it were cash.)
The £TSL price is now 49p so there is a 30% discount to NAV but in my experience there always will be at least a 15-20% discount until the shares are liquidated.
I agree about the best we can say is Montarello and Gammell have got plenty of skin in the game but the game has changed and its now a play on Block instead of a cash crystallisation event.
Hi Jack,
You've found Air Partner (LON:AIR) a bit frustrating after holding for 2 months! I've held since May 2020. It's a share to try one's patience bur I'm sure if i sold it would shoot up afterwards.
I put it down to three factors. It's seen by some as a 'travel' stock. The market cap is small enough for it to be under the radar. And there are probably still memories of the accounting scandal of a few years ago hanging around.
please sell and when the shares shoot up I like to sell too!
I have held this for 20 years and has not gone anywhere.
Air Partner (LON:AIR) (I hold)
Morning Jack
Many thanks for your commentary.
I continue to really like the cash generation here:
So cash generation should be c.£13m for the year. Not bad for a market cap of £55m.
---
Freight is doing well at the moment (although H1 really wasn't anything exceptional - £3.8m), but once this reverts to historical norms, I believe it will simply be replaced by:
Accordingly I personally believe that if there was going to be a "dip" year, then it was this year (FY22, ends Jan 31st) and that once Freight reverts back to its historical £3.2m - £4.9m range, any "lost" profits will be naturally replaced by the company's other services.
As a holder I hope so.
Thanks again
A
Just had a quick glance at the capex cash flow, and it looks a bit low at first glance, on the Stocko financials. Air Partner (LON:AIR) is a share I've never held before; do they own their own planes? And what's the capex requirements looking like for the next few years?
Air Partner (LON:AIR)
Hi Dahokolomoki
The company does not own any planes - instead they act as an intermediary between people/organisations/governments and plane owners.
As per their website they have 'access' to 7,000 aircraft.
To caveat the above, there was a £3.7m lease payment outstanding for an Italian aircraft on the balance sheet at the end of last year (and I think at the interims too).
I don't know the history of this, though I believe the final payment was originally meant to happen in 2021, but was then delayed until 2022.
Aside from this, there are no material capital expenditures that I would expect either now or in the future.
Cheers
A
That is really interesting, basically an asset-light model. In an industry that is usually asset-heavy. I'm going to have a deeper look at Air Partner this weekend!
A very full trading update and update on Group strategy from Lookers (LON:LOOK) this morning. Beating latest forecast for profitability and very strong balance sheet with property assets valued at over 77p per share. Obviously cautious of what 2022 might bring given the continuing issues of semi conductor availability in the vehicle manufacture industry, but intending to bring back dividends.
As Paul said some time ago, the unusually high profits made this year have really strengthened the balance sheets of motor retailers and put them in a much more resilient position to face the future.
The strategic review made interesting reading, but will be more interested to see what has been achieved and to what value when they report in a year's time.
Further thoughts, anyone?
Sorry for double posting. Stocko said they were having some trouble at the time.
A very full trading update and update on Group strategy from Lookers (LON:LOOK) this morning. Beating latest forecast for profitability and very strong balance sheet with property assets valued at over 77p per share. Obviously cautious of what 2022 might bring given the continuing issues of semi conductor availability in the vehicle manufacture industry, but intending to bring back dividends.
As Paul said some time ago, the unusually high profits made this year have really strengthened the balance sheets of motor retailers and put them in a much more resilient position to face the future.
The strategic review made interesting reading, but will be more interested to see what has been achieved and to what value when they report in a year's time.
Further thoughts, anyone?
lookers net cash is down from the last quarter report?
Interesting extra details on Vin Murria deal for M&c Saatchi (LON:SAA) which is reminiscent of her historical build and success with Advance Computer Software. She currently sits on the Boards of Bunzl Plc , Softcat and DWF Plc so is still a highly active business lady. Any thoughts Paul or Jack - or any other readers of course - on what is still a relatively quiet period.
We crossed in the post! I recently posted my comments on SAA above.
Indeed. Thank you, Paul.
Bewildering downgrade for Sthree (LON:STEM) from Jeffries this morning. Demand for tech and life science skills is at an all-time high yet shares have now fallen below long term average valuation on a PER and EV/EBITDA basis, perhaps anticipating the top of the cycle. Yet, this hiring cycle in SThree’s segments is only just getting started and should run for years. Look at the long run turnover and profit growth, tripled in the last decade.
I don’t have access to the narrative relating to the downgrade so, if anyone does, please share, thanks.
the ceo announced he was leaving for personal reasons a couple of weeks ago and the share price dropped quite a bit on the day . Not sure if this is related but apparently he was well regarded in the city .
I liked Dorman too and had some interesting discussions with him, but he was only at £STEM for a couple of years so the long term growth of the business was demonstrably not of his making. He wasn’t even a recruitment guy, unlike the interim replacement, so I think there’s more to the downgrade, possibly margins, as these attracted some attention in last month’s TU.
Very irritating that we are unable to at least have an outline of the reason for the downgrade Sthree (LON:STEM) I understand that it is private research that needs to be paid for, but its clearly had a big price impact so surely all market participants should be allowed to understand the thrust of the argument.
It’s hard to divine the logic. The fundamental driver of the business, contractor numbers, is growing strongly - order book up 30% on 2019! And this is a leading, not trailing indicator, unlike perm placements.
Not seen the Jeffries note - but I got an email missive this morning about UK macro conditions, citing
This and the aformentioned margin pressue that was discussed recently on the IMC presentation (due to investments in headcount and IT, I believe) could be the main reasons? Quite a large drop though, from 650p - 500p.
But Sthree (LON:STEM) is international not just UK, I can't remember what the split is. Also if that's so, then why have Robert Walters (LON:RWA) not fallen back as well, I looked at other recruiters as well and they are not down either. I think it is to do with the broker note, which do seem to be having far more impact on share prices, than they used to do.
Yes it appears from the newswires that the downgrade was due to concern over CEO departure and margin impact from increased infrastructure spend. So in other words things that were already known about and already reflected in share price!
You could argue their previous target of 650p was a bit punchy so perhaps 500p more reasonable, but this is still well above current share price (ie Jeffreys actually see good upside) so on this basis today's fall also looks irrational.
Yes it appears from the newswires that the downgrade was due to concern over CEO departure and margin impact from increased infrastructure spend. So in other words things that were already known about and already reflected in share price!
This was my hunch - that the note was likely a tardy reflection of the mid-December TU. I said back in December the sell-off was way overdone and I hold to that view. Infrastructure spend is minuscule for recruitment companies next to variable staff costs and shouldn't affect margins long term at all. The new price target was just the usual "stick 10% on this morning's price"!!
Of course it's reasonable that the market is waiting for confirmation of a new MD but 25% is too big a sell-off for a company that has upgraded forecasts umpteen times this past year
A pleasing and perhaps not unforeseeable update from £AIR. Underlying profit before tax to be materially ahead of expectations. The company continues to perform and remains underappreciated by the market in my view even if one discounts the one off benefits derived from the pandemic.
Jack do you have any thoughts to add to your commentary of 17 December?
Lookers (LON:LOOK) another profit upgrade Paul any thoughts net cash now also finance costs dissapearing
A long awaited acquisition for Sdi (LON:SDI)
It is accretive from day 1. EBIT of £700k from a turnover of £2.5m
Seems they have paid 5.7 - 8 X EBIT depending on earn out. Paid from cash.
SDI is valued at 18 X EBITDA so it is value creating and earnings enhancing.
Hi Paul, there was a Hindenburg short report on Royal Caribbean yesterday. Might be worth a read in relation to £SAGA.
Hi Funnymoney,
Hi Paul, there was a Hindenburg short report on Royal Caribbean yesterday. Might be worth a read in relation to £SAGA.
(as an aside, if you put a full stop or any other character after a £ticker then it won't work. There has to be a space after the £ticker for it to work)
Thanks for flagging this. I've had a quick look at a press article summarising this short attack on Royal Caribbean, and it seems to mainly focus on RC's high debts. Also mentions increased fuel prices & higher operating costs for cruise ships.
I don't see any read-across to SAGA (I hold) from this report, because -
I haven't looked at Royal Caribbean's numbers for a long time. I did look at Carnival (LON:CCL) (I hold) and was surprised at how robust its balance sheet & debt position is, so I bought some near the recent lows.
These cruise companies generate enormous cashflows, once they can trade without restriction. It all boils down to when you think that might be the case. My view (right or wrong, we don't know) is that highly transmissible omicron seems to be the climax of covid infections, which should result in herd immunity thereafter (we hope).
That could mean a multi-year bonanza for cruise & travel generally, hence I remain very bullish on SAGA, and it's now my largest personal position, so am obviously talking my own book, but being my largest position it's very high conviction. And don't forget that the short seller is not publishing a report from the goodness of their heart! They're trying to panic people and manipulate the share price down, to make a short term profit. That's very different from a long-term holder like me giving my opinions on the share, because I don't care what the share price does, other than it affecting my general mood.
People shouldn't under-estimate how much pent-up demand there is. People who enjoy cruising come back to their favourite brand year after year. It's not for everyone, but this "floating petri dish" dismissal of the sector that you hear from bears is not how the customers see it. There's massive demand for cruising - evidenced by strong bookings for future cruises even during lockdowns.
Thanks again for flagging this, very interesting!
Regards, Paul.
P.S. Also, I think for shorting attack dossiers to be effective, there has to be a smoking gun - some kind of evidence that something has gone seriously amiss, e.g. evidence of fraud. Just putting out a report saying you're bearish on a share, due to obvious, publicly available info, is not likely to have any serious or lasting impact.
Paul,
Some punctuation does work such as commas but not . and ?
It does seem quite inconsistent the £ticker, sometimes it works and sometimes it does not, much worse on the new site. I've had to add a , sometimes to get it to work. Does not work on mobile phones?
Saga (LON:SAGA) Saga (LON:SAGA), £SAGA.
Yes the whole punctuation after the £ sign is an annoying mess. Stocko should fix it rather than spending years "educating" users about it.
I have tried all the variations and can't seem to get it to work on my iMac.
agree, I happen to feel the same way on the 'everyone must remember to tag all posts with a ticker because some people don't read in threaded mode' angle. just fix the app to repeat the ticker from parent comments, its simples.
a reasonable chunk of the capability of this app/service is a forum tool (this), which has some clear and highly discussed faults that we don't see getting attention from the dev team.
I can't imagine it would take a lot to sort the text parsing issue to look more carefully at any word starting with a £, and doing a trailing non-alpha trim before replacing with the ticker macro if a match vs the known world of stocks. I know there are special cases such as Aviva (LON:AV.) which would add some secondary check behaviour to kick in, but these should be quite well understood by now.
I think it's because some legacy tickers still have dots after them? Like £BT.?
As far as I know both Saga cruise ships have been operating non-stop since they resumed cruising last Autumn. Of course, we don't know the load factors, whether they are having to discount etc. but I'm sure they must be making a positive financial contribution.