Small Cap Value Report (Fri 7 May 2021) - NUM, KITW

Good morning! It's Paul here with Friday's SCVR.
Timing - today's report is now finished, there's hardly any relevant news, and a lunch opportunity has just arisen, so I'll down tools for the week. Have a smashing weekend!
My recent article on Boohoo (LON:BOO) (I hold) results wasn't quite finished, so this is just to flag up that I spent some time yesterday afternoon typing up the rest of my notes from the company's webinar. So here's the link for the completed report.
It's quiet for news today, but I won't short change you! I might look at a new float instead.
Agenda -
Numis (LON:NUM) - stunningly good interim results. Cyclical business of course, but everything seems to be booming at the moment.
Kitwave Group - a new listing on AIM, in the pipeline. I've started to look at it, and see enough positives to make me want to dig a bit deeper.
.
Numis (LON:NUM)
418p (up 7% at 08:33) - mkt cap £450m
Numis is a leading independent investment banking group offering a full range of research, execution, corporate broking and advisory services to companies in the UK and their investors. Numis is listed on AIM, and employs approximately 290 staff in London and New York.
I last looked at this listed broker here in July 2020, when it issued a positive trading update, with upbeat outlook comments. Last year, there were bumper fees from many fundraisings, whereas this year M&A and IPOs are surging. Even Wh Ireland (LON:WHI) managed to report a profit recently, so market conditions must be outstanding.
For the six months to 31 March 2021.
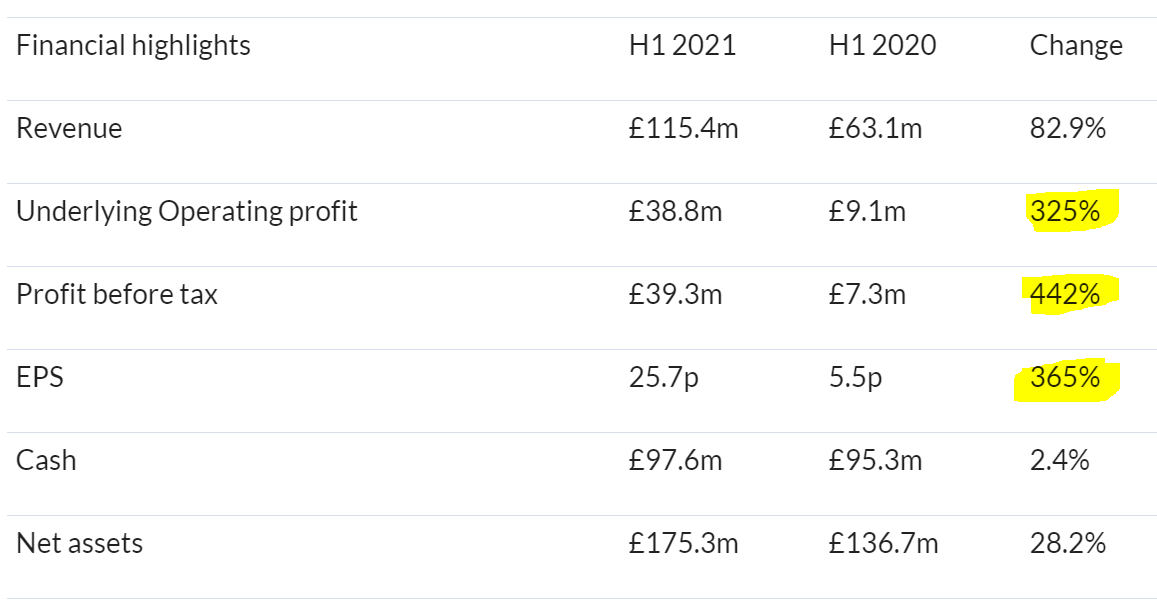
Take a look at these figures, which are stunningly good, albeit against soft H1 comparatives. H2 last year was much stronger -
.
.
Share repurchases of £11.5m done, which should enhance EPS. Or some people see share buybacks as a way to disguise dilution from share options, if you’re more cynical.
Picking a few interesting points of wider interest, from the commentary (these are all copy/pasted, with nothing added by me) -
- As markets exhibited signs of a sustained recovery, volatility subsided, and corporate confidence returned, the environment for capital markets activity improved significantly
- IPO volumes over the past 6 months have been at their strongest level for many years
- volumes were materially ahead of the comparative period which was adversely impacted by the start of the pandemic and the pause in deal flow ahead of the UK general election
- UK M&A volumes have started to recover driven by both domestic and international buyers identifying attractive investment opportunities and being able to secure the necessary financing
- Proposed Dublin office offers strategic opportunity to leverage Capital Markets capabilities in Europe…Whilst Brexit has had minimal impact on the performance of the business, an EU office would both restore certain EU institutional client relationships and provide us with the opportunity to expand our Capital Markets offering throughout Europe with the benefit of passporting.
- In addition, the Brexit deal agreed in December 2020 improved investor sentiment toward the UK. Consequently, the UK has outperformed a number of other markets over the past 6 months and flows into UK equity funds have improved over the period
Outlook -
The Investment Banking pipeline continues to benefit from a high volume of IPO mandates and the near term outlook for further Growth Capital Solutions and M&A revenues is also encouraging. We therefore expect the broad profile of Investment Banking revenues featured throughout the first half to be sustained in the second half of the year.
Whilst our pipeline is becoming more diversified by sector as market confidence builds across a wider range of industries, execution of the IPO pipeline in particular will be dependent upon the current positive market environment persisting.
Balance sheet - very strong. There are some large numbers in working capital, but the net current assets position of £164.4m is very healthy. This includes £97.6m cash.
The only long-term creditors are £38.7m lease liabilities which doesn’t seem excessive to me. Although there might be a question mark over whether big glitzy London offices are necessary these days? For this type of business, I think they are necessary, and we'll probably be back to near-normal later this year. In the worst case scenario, businesses like this have everything in place to return to work from home if it proves necessary again. So I'd say they've got all outcomes covered.
My opinion - we’re seeing boom times for financial markets, and personally I can’t see any reason why that would end any time soon. Assuming Numis achieves a similar result in H2, then that could be c.50p EPS, so a PER of just over 8. That looks cheap, but remember it could be at, or near, peak earnings. Inevitably the future is going to contain some fallow patches too.
I rarely invest in brokers, but have to say Numis would probably be top of my wishlist, even after a strong run up in share price lately. This strong level of performance justifies it.
What a pity that Numis keeps its research hidden from private investors. They should consider at least letting us read the small caps stuff, where we create the market liquidity & set the share price. The more informed private investors are, with good quality research, then the more likely we are to buy the shares, which would benefit Numis and its clients. That message doesn't seem to be getting through to them, which creates opportunities for their competitors, who do see the benefit in engaging with private investors.
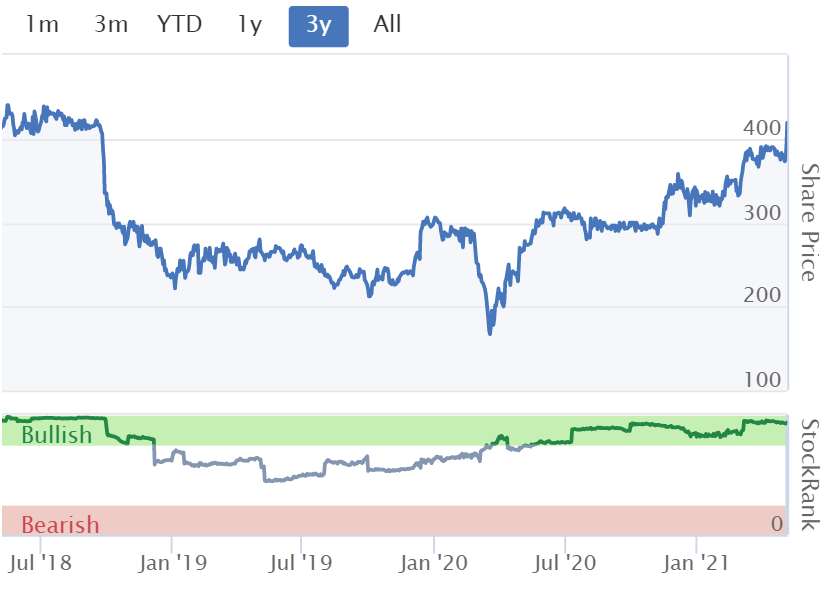
Note the high StockRank below. Also, I see NUM has been a solid dividend payer, with a decent yield over the years.
A thumbs up from me, this looks an excellent share.
.
.
Kitwave Group (KITW)
Placing & Proposed Admission to AIM
This proposed new listing has caught my eye, because the list of institutional investors is like a who’s who of the great & the good in the small caps world. They’ve done their due diligence, and obviously like it, because they’re buying shares in KITW, which is a good starting point for us to see if we like it too.
Key points are -

.
Despite the selling shareholders, management will retain a healthy 22.3% of the company, so it gets a tick in the crucial “skin in the game” box.
I think it’s private equity backed, so will probably have a lot of debt, hence the new money raised is really to pay off the existing financial backer. That’s not necessarily a bad thing - PE funds tend to like to exit things after a few years, to recycle money for new deals.
What does Kitware do? It’s a wholesale distribution business, experienced in M&A by the looks of it, so that could be of interest in making further acquisitions. I like the idea of backing a management team who know what they’re doing, experienced in M&A -
"To date, we have executed a highly successful buy-and-build strategy, having acquired and integrated 10 wholesale distributors into the Group since 2011, and we are confident that trading on AIM will enable us to continue to support this strategy. Furthermore, the Directors believe that Admission will enhance the profile of the Group and its brands, improve Kitwave's position with key suppliers, strengthen the Group's balance sheet, and provide the Group with greater ability to incentivise and retain key employees going forward…
Kitwave Group plc is an independent, delivered wholesale business with approximately 1,100 employees and a network of 26 depots able to support delivery throughout the UK, specialising in selling impulse products (such as confectionery, soft drinks, snacks, ice cream), frozen and chilled foods, alcohol, groceries and tobacco to approximately 38,000, mainly independent, customers. Currently, the Group sells a broad portfolio of approximately 33,000 Ambient, Frozen & Chilled and Foodservice product Stock Keeping Units (SKUs).
The diverse customer base includes independent convenience retailers, leisure outlets, vending machine operators, foodservice providers and other wholesalers, as well as leading national retailers.
The Group was founded in 1987, following the acquisition of a single-site confectionery wholesale business based in North Shields, Tyne and Wear, United Kingdom.
.
That gets another tick from me - an established business, with sensible activities, not blue sky nonsense.
Very brief financials - hmmmm, it’s low margin, to be expected from a distribution business I suppose -
revenue and Adjusted EBITDA growing to £592.0 million and £27.6 million respectively in FP20 (an 18-month period). In the 12 months to 30 April 2020, the Group's revenue and Adjusted EBITDA was £399.0 million and £17.5 million respectively.
So systems & financial controls will be of vital importance. I’m still scarred by Conviviality going bust (taking £30k of my money down with it) a few years ago, because they made a hash of acquisitions, and failed to have proper financial controls in place to invoice clients correctly & collect in the customer cash. That’s the big danger with high volume, low margin businesses. Also customers going bust can be a problem in difficult economic times - one customer going bust, wipes out the profits from many others.
This is required under AIM Rule 2, giving information in a prescribed format about the company, in advance of it listing on AIM.
This is where I found the list of institutions which are buying into the IPO, I’ve highlighted the ones that I particularly rate as shrewd -

My opinion - too early to say, as I’ve not read the Admission Document yet, as I can’t find it. If anyone does find it online, perhaps you would be kind enough to post a link, then I’ll have a rummage over the weekend (maybe).
After Deliveroo flopping so badly, I don't think we can assume that IPOs will automatically go to big premiums. I tend to look at IPOs in terms of, is this a great business that meets my investing criteria & has the potential to grow a low, and do I rate management (subjective of course). Plus, is it attractively priced?
Of recent IPOs, the two that stand out to me as coming close to meeting my criteria, were Virgin Wines Uk (LON:VINO) (covered in yesterday's SCVR) and Parsley Box (LON:MEAL) . In both cases I'm not intending to buy any time soon, and want to see how things progress once lockdowns have fully ended. It's good to see companies build up a track record of say 2 years as a listed company, before taking the plunge, in my opinion, because often things seem to go wrong in the first 1-2 years.
If anyone spots any decent IPOs, do leave a comment here, as I don't have a system to look at them properly, it's largely random if I spot something.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
Paul, of new IPOs I quite like the look of Moonpig (LON:MOON) - the online greetings card and gifting company. Capital light, good organic growth, and clear market leader. I buy their products regularly and think the range of cards and personalisation offered is fantastic. However, the share price looks punchy trading on 40x estimated FY22 so I think this is one to return to when H1 FY22 results come out in the autumn and when strong comparatives (stellar lockdown performance with card shops shut) might soften the price and create a more attractive entry point. It's on my watchlist.
Re Moonpig (LON:MOON) - interesting discussion on whether it is market leader or not!!
It may be online leader but even after a year of lock down, I suspect that Card Factory (LON:CARD) will be clear overall card market leader again by calendar 2022 - and thus still good value despite its large debt large reduction in footfall if it can finally i) sort out its borrowing and ii) medium term, generate enough cash to invest in Marketing to win its fair share online (and in doing so drive its retail operations). These 2 major "ifs" but offsetting potential explain its current share price. Will be fascinating to see how things look as Covid retreats and shops re-open. My guess is a lot of well attended summer birthday parties, with physical cards! Disc. Card Factory (LON:CARD) holder).
Hi Paul,
One of the more interesting upcoming IPO's I'm aware of is Alphawave IP. However, it's not yet clear whether it will be available to the retail market. I suspect it will be kept for institutions only given the small free float.
The company has only existed for 4 years so the IPO looks a little opportunistic to me, however it is already a highly profitable company. They license semiconductor IP (so a bit like ARM) for high-speed interconnections both internal and external to chips. So very much in vogue with booming AI, Data Center etc. sectors.
More details here: https://www.cityindex.co.uk/ma...
A suggested $4.5bn valuation looks very rich but I guess we'd expect that in a hot market, particularly given the fantastic early stage growth and profitability metrics to December 2020.
All the best, Si
No, the Human League lead singer is Phil Oakey, not Phil Oakley.
Paul, if time time permits you might be able to to give us a quick summary of your top 20 holdings? Also, any further thoughts you have on Mothercare (MTC) would be of interest. Thanks.
Paul, if time time permits you might be able to to give us a quick summary of your top 20 holdings?
Oh crumbs, I know this has been hanging around on the to do list for ages, and it feels like a chore at the moment, as there's so much else going on all the time. Best thing is, just leave it with me, and I'll do it when it's enjoyable to do & I don't feel under pressure.
Thanks, Paul.
Hi Paul,
I really appreciate the fantastic work you do in producing the SCV reports. They are very interesting and readable and are great for the likes of me who's eyes tend to glaze over while reading most financial stuff. I also find many of the subscribers' postings very helpful, and I often wish I had a bit of knowledge myself so I could contribute now and again.
On the subject of your own personal portfolio, I would rather manage by not knowing what it comprises. Your reports already have a very user friendly personal touch, it's more than enough.
Hi Paul.
On the topic of recent IPO‘s, Chinese eCommerce platform Samarkand (OFEX:SMK) has been on a bit of a roll of late touching 176p (now 169/175p) against an IPO price in March of 115p. No earth shattering news driving this although they announced a couple of brand acquisitions in the mother and baby nutrition sector earlier this week that have been well received.
https://www.samarkand.global/2...
Very illiquid with limited trading/secondary market activity on Aquis and I gather it’s impossible to get a spread bet price with any of the trading platforms. Trading history via the link below shows just how thin the market is.
https://www.aquis.eu/aquis-sto...
Managed to get in at the IPO stage but have been unable to add to the position. Management still hold a substantial chunk of the equity so there could well be a secondary-PO to cash in some equity in due course or possibly another fundraise to finance growth.
Gus.
Samarkand...I am surprised to hear that you couldn't add to your position. I added via HL into ISA about 3 weeks ago. You may have to execute via phone though. Pleased I did it though because there appears to be some good momentum.
I probably wasn’t trying hard enough. As you say, telephone orders only at the moment (via my Charles Stanley Direct account at least) and I was put off by the wide spread quoted at the time.
On the subject of Samarkand (OFEX:SMK) , slightly odd announcement this morning that they’re placing about 2.7m shares (c.5% of shares in issue) with big (£32 billion market cap) Chinese distributor United Win Asia this morning.
https://www.investegate.co.uk/....
Nice to have a big strategic partner and all that but the placement is being done at the initial IPO price of 115p compared to the current share price of about 172p , about a 33% discount. Not sure if this was built into the original IPO terms as otherwise it seems a generous/dilutive move. Given the two principal founders still hold 29% of the equity, I guess they must think it’s a good idea (unless UWA made them a Godfather like “offer they couldn’t refuse”!)
Gus.
There used to be a 10% of issued share capital limit on options, and you had to apply to extend it. Buying in shares to say an Employee Trust to cover the potential exercise of those options does in effect mean less dilution (i.e. no new shares are issued) but does not change the strict eps etc because those buy in shares, unless cancelled, are treated as still being in issue.
Hi Paul - re Numis (LON:NUM) and your comment about dilution:
"some people see share buybacks as a way to disguise dilution from share options, if you’re more cynical"
You can see this is definitely the case here since the company has spent £40m (c.10% of the current mkt cap, after the big rise) on this over the last 3 years yet the share count is unchanged.
Cheers
My earlier whinge is justifiable then, thanks sartingstall.
Silver
I realise I'm going off-piste but after my experience with Numis (LON:NUM) i worry about the following companies I hold. Amino Technologies (LON:AMO) Plus500 (LON:PLUS) Rightmove and (LON:S32 are buying back their own shares, I sincerely hope they will not cause a dividend famine and thus lose shareholder confidence if they go mad in handing out share options to their directors.
Silver
To add flesh to the bones, on the £6000 invested over the 4 years £617 was returned in dividends which is 2.57% annually before tax. Better than bank interest but one does need to ask where the bought-back shares ended up and why.
Paul/Jack
I was wondering if you fancied having a look at Dr Martin, £DOCS. Not a small cap, but Phil Oakley seems quite taken with the company, which has recently floated. I regretted dismissing Fevertree when it floated at 134p, several years ago and J D Weatherspoon which floated at 160p, 'when Queen Victoria was on the thrown' and I was but a young man with a passing interest in financial matters.
Just a thought, no problem if it is not for you.
All the best
Is that the same Phil Oakley that was in Human League?!
You never know he may have had a makeover, but his younger alter ego is a columnist for Investors Chronicle and Sharescope! Although I am sure that young Phil would have owned a pair of Doc Martens in his early days.
Except that was Phil Oakey.
Must be the day for retro 1980’s pop stars making a comeback on the London markets as I see the CEO of IPO candidate Kitwave is a certain ........ Paul Young.
Gus.
Wherever he leaves his hat...
...... that’s his home”
Gus
Hi Paul
Re Numis ( I hold ). I loved your remarks re share repurchases! I greatly appreciate your write ups and wit.
Following on from the very popular Introducing your kids to investing, Edmund Shing (AKA The Idle Investor), goes on to explain to us how to start investing with funds to newbie investors: Introducing your Kids (or anyone!) to investing: Part 2 Funds. Video and Podcast. Just 20 minutes to gem up on the key bits to look for when selecting funds. Edmund believes investors can run their portfolio with just one or two funds. Video & podcast.
Also, published on piworld yesterday, the FY20 results presentation from Property Franchise (LON:TPFG) is worth a listen. Good growth drivers: strong property market, Hunters acquisition, EweMove and the financial services tie up with LSL.
Sherborne Investors (guernsey) C (LON:SIGC) have announced they have sold their Barclays shares..and NAV = 79p. They have identified a new target and started investing. When they reach a disclosable level they will announce. Exciting news...so no longer do we have the headache of being a bank shareholder.
"Normally" when the new target is announced you get a pop from the target.. and therefore a lift in the NAV...with £550m to invest... they could target a smaller company and retain some cash (potentially to fill a funding shortfall). This brings the target range of size of co to a sweat spot £1.5bn - £4bn. I normally assume a 10% holding but higher improves the chances in a vote....
My best guess is an NAV approaching 90p on announcement of the target and assuming its interesting enough... you have a path to 100 value short-term and 200 longer term since broadly speaking they look to identify targets with 100% upside.
Mid 60s for 79p largely cash seems too small a reaction today to me.
Yes Barclays (LON:BARC) always seemed too big a beast to for Sherborne to have any real clout and glad they have just cut their losses rather than wait for this position to breakeven (could have been a very long wait). My sense is there must be a lot of companies in the 1-2 billion size bracket where there is a lot of value to be extracted. At current price of 61p this is still on very wide discount to the 79p NAV which is now largely in cash. I agree once they confirm the new target this could pop higher and could eventually go to a premium so very happy to hold this.
What I don't understand is why buying an investment in a company than invests in one other company makes any sense when I can just buy the other company directly?
I invest in a lot of closed investment funds that typically buy stakes in startups and have wide portfolios but this just seems very strange.
I agree ... except that at the moment you pay 63 for 79p of value... and you don't know the target. As I say, normally the target pops when the investment is announced, Barclays rose 10%... so if you follow them into the target you either pay this level or have to wait and hope you get a better opportunity. Normally you do but.... at the moment the discount offers you the chance...some obviously don't like being blind... its a little like being in a SPAC...but the discount, I think, compensates you for this. If the shares moved to a premium post announcement, then I would switch back to the underlying.
Sherborne are activist investors so typically look for a company where they can unlock value - often this might be to push for the breakup of the company and return cash to shareholders. This was what happened with Electra Private Equity (LON:ELTA) which is now down to its last 2 investments - I believe the returns extracted there have been pretty good.
What's the bear case for this? I cant really understand why the SP would be circa 20% below NAV but Ive not really followed this company - is there a justifiable reason for such a discount that anyone knows of? Is it primarily past performance?
The Barclays investment didn't really go to plan as they couldn't get their changes implemented and the Barclays share price tanked for separate reasons - this explains the discount in this instance.
There are two bear cases as I see it:
1. They do something even more unpopular than Barclays. The shares of the target fall on announcement. Let's say they went for Aggreko (LON:AGK) and it fell 15% because the shareholders voted with a Sherbourne plan rather than the acquisition. Thus NAV falls rather than the opposite. This is of course a short term risk but my own view would be Aggreko (LON:AGK) is being sold too cheap. Longer term this value should be captured.
2. The existing institutions are not happy and just want their 79p back. This is not much of a bear case at 63.
IMO the reason the shares are not reacting better is most likely there is still an overhang that is being cleared. This could be tied to the US market. I am speculating.
I am happy taking the reinvestment risk because I have followed these guys for a long time. I accept its not for everyone but lows 60s is a great value for 79p cash/the new target. I think they are under a lot of pressure to recapture the 100 level and more.
Would love you to look at a niche business 57 million cap Frenkel Topping £FEN that reported final results earlier this week . Refreshed management a couple of years ago building a new team . 19% increase in revenue 13% increase in AUM. 32% increase in final divi. 3.17% dividend at current share price. Its Buy and Build Stretgy seems to be working too. In a specialist area that is very sticky (99% retention rate) yet plenty of opportunities for growth . Specialist financial advisor , investment and other related services such as witness services.
Yes, I own Frenkel Topping (LON:FEN) they are doing very well. Despite being relatively market neutral in terms of the nature of their business the shares fell a lot in March 20 then just chased ahead of my limit buy orders through the early 20 pences until I gave up. Now 53p grrr!
Morning Paul, interesting to see the ceo of Saga (LON:SAGA) with a rather large purchase.
Well yes, but that was yesterday's news.
Good morning Paul. Do you have any comments on today's announcement by Rambler Metals and Mining (RMM). Do you think it will fly?
Hi LinnetIC,
Sorry I don't cover any natural resources stocks, because there are too many companies, and I have no sector expertise or experience. We have to stop somewhere, and I cover about 500 other companies, which is quite a challenge!
Jack sometimes does look at an occasional resource stock (producers), but he's busy on other things today. Sorry about that.
Regards, Paul.
Paul. You never short change us.
Morning Paul. Any chance you could share your thoughts on Parsley Box (LON:MEAL) (I hold) please?
Hi Simmo1a,
These reports are driven by the day's newsflow (primarily results & trading updates). I can't see anything from Parsley Box (LON:MEAL) today.
I did review it here on 1 April 2021 - with mixed views. That report didn't come up on a search, so I've edited it to include a tag for MEAL, so it should now appear on a search.
To find previous commentary on companies, just go into the StockReport for any company, the click on the "Discussions" tab. It will then list all articles which have been tagged with that company's ticker.
Useful tip - not many people know this, but if you put a company name or ticker in the search box (NB but don't press return), a list comes up which you can scroll through, which picks up all articles that mention that share.
Regards, Paul.
Thanks Paul, will do
Paul,
That info re the search box is brilliant, thank you. There are so much data and stats on Stockopedia and short cuts to accessing them that us mere mortals know nothing about. Maybe someone needs to produce an instruction manual.
Richard
On a very quiet day £TEK announced that Belluscura has announced its intention to float on the AIM. Targeted price means that they have a holding of between 7-8m GBP in the company. Given TEK has a market cap of around 17m then there's a good opportunity of a rerating given there other three companies are doing well. A video came out yesterday if you have a spare 20 mins of your time.
Tekcapital (LON:TEK)
Hi Brookeda
Thanks for highlighting this announcement.
I've not looked at this one before, but I always like to find a gem.
I'm not convinced there's one here (yet), but for those interested here's my summary of the company's holdings from the latest information I could find.
FINDING THE DATA
For reference it was quite hard to collate this information as Tekcapital (LON:TEK) only generally announce their holding in a parent company, and not necessarily that company's subsidiary, which is where the actual value is.
I don't like this. It should be easy to find this information.
Also, their Annual Report had no mention of NAVs for each of its holdings. I had to go into the press release for the full year results to find this and, to be honest, it puts me off that they make it so difficult.
SOME GOOD
As for the potential, I'm honestly not sure what to make of it.
They're saying that Belluscara will list @£50m.
Just 6 months ago the fair value of the business was $11m/£8m.
That's quite a jump in 6 months.
Could there be other positive surprises?
SOME BAD
Then you have the other side of the coin in Salarius, which owns 87% of Microsalt, which reverted to crowdfunding last year.
There are no doubt success stories from crowdfunding websites, but from personal experience this route does make me wary.
Sales are also in the tens of thousands, with huge losses, yet it's worth $5m. Seems like a crazy valuation to me.
More information can be found here for any interested:
https://invest.microventures.c...
WORST CASE SCENARIO
I've assumed Salarius goes to zero and Guident's valuation is reduced by 50%
If Belluscara IPO goes ahead @£50m, then the risk looks quite minimal actually, with only a 2% downside risk vs the current share price.
MY CONCLUSION
It's an odd one. I'll keep an eye, but I'll probably pass.
Good luck to any holders.
x
Super analysis and thanks for sharing.
on Tekcapital (LON:TEK) if you go to the back of the annual accounts there is a table of portfolio investments and their valuations. Belluscura was valued @$2.1m (£1.5m) as part fo the overall NAV of $32.7m @30/11/20. I don't know why they don't give this more prominence , its vital information. SPAngel also talk about this in their broker reports, available on Research tree. So if they get the IPO away @lower end of 42-48p guidance then the Tekcapital (LON:TEK) valuation rises to £7.2m , a 4.3p increase per share by my calculation, taking NAV from 17.8p to 22.1p. Please check these numbers as its easy to make mistakes !
Tekcapital (LON:TEK)
Hi mepfish
Ah yes, I've just found it now. That NAV table is an image so Control+F doesn't work. Very unhelpful.
Presumably 42p = £50m, as per today's announcement, so the Tekcapital (LON:TEK) holding@17.8% should in fact be at least £8.9m.
A
remember that they own 17.8% of current sharesin issue , post the proposed placing the % will fall , hence I used 17.1m shares to work out my calculation
Stock Slamlast 9th April: Alex Schlich: Tekcapital (LON:TEK)
Small-cap investment group specialising in commercialising university IP around the world. Has made four key investments with the aim of tapping large potential markets with good management. Price fall in March caused by a discounted equity raise - but they do have sufficient cash and are likely to be selling portfolio businesses soon.
(Took me until yesterday to find some money to buy - so I missed more than half of the recent price rise)
This is what first alerted me to the opportunity.
I bought in two lots at an average of 11.6p so I am pretty happy so far.
Any chance of a ramble on Numis (LON:NUM): Paul as per Mr contrarian below figures across the board well up with pre tax profit up over 300%.
If we are due the best economic year since world war 2 could there be more to come or have they had their sweet spot with all the fund raises needed to survive the pandemic.
Regards Andy
I hold Numis (LON:NUM) and have held ever since April 2017 when the p/s was 284 pence. I bought again in May 2017 at 414 pence. So far so good but I should have sold rather doing what I did, buying in July 2018 at 426 pence. It has remained with me like a faithful dog. I see the price has risen 4% today on yesterday's price and now sits at 319 pence, oo-er, a correction as I see 399 pence right now. I think I see a chink of light at the end of my 4-year tunnel. Well, Edmund Shing, bless his soul, rates patience as to be highly recommended.
Silver
Cenkos Securities (LON:CNKS) is an alternative to Numis worth considering. Their results on 22nd March were covered in the SCVR then. Cenkos are not winning as many IPO’s etc as Numis but the valuation reflects that. Also Cenkos goes ex a useful 2.5p dividend next Thursday. Share price is up 4p to 84p today, probably in reaction to Numis’s results.
My morning smallcap tweet:
Sensyne Health (LON:SENS) Sealand Capital Galaxy (LON:SCGL) Numis (LON:NUM) H C Slingsby (LON:SLNG)
Sensyne Health (SENS) MagnifEye AI software gains MHRA 'Authorisation of Special Use' in connection with Innova rapid covid test. What is Special Use? [SP=160.5 Cap=265m]
Sealand Capital Galaxy (SCGL) exclusive three-year product-specific distribution contracts with two British brands and two Nordic brands. Co in negotiations for the sale of these products by an internationally known department store. [SP=1.45 Cap=7m]
Numis (NUM) H1(Mar) rev up 83%, EPS up 365% to 25.7p. Div 5.5p (5.5p). Outlook for H2 encouraging. [SP=391 Cap=421m]
Slingsby (SLNG) FY(Dec). This Q1 rev up 8%. Outlook cautious since FY20 got a covid boost. Also "cost increases impacted on gross margin in Q1 2021 and could continue for the remainder of the year." [SP=235 Cap=2m]
Mr C - Sensyne Health (LON:SENS) - not sure if your 'What is Special Use' is rhetorical? I'm sure it is - but in case its not I believe the Special Use refers to the conditions of use of the Lateral Flow Test.
Special Use means that we have a big Warehouse full (and reputedly half the docks at Felixstowe full of containers )of these tests bought from Innova (US) but designed and made in China. They WILL be used. But they don't work well enough to enable ANYTHING except another test. aka 'Special Use.' Which is good - because by using one test you actually have to use a box full in order to try to achieve anything. And you still probably won't achieve anything - but by using the tests you will be contributing to unclogging Felixstowe docks.
In the Liverpool pilot trial the LFT detected 60% of symptomatic cases and only 30% of unsymptomatic cases and thats in a supervised trial. In other words - most people who have the virus and don't know it will be falsely reassured by the LFT. Will they do anything as a result of the test? Probably. Will they do anything even if the test looks a little bit positive? Maybe? Will they self-isolate or mis-report the test and use it claim a recent negative test? Ooops.
Does the high number of false negatives cause more onwards transmission than the actual positive detections prevents? Who knows? Opinions vary. But the figures don't look so good?
It looks as if this software will help to reduce the very high level of false negatives. And bearing in mind the difficult of self-administering and intepreting the tests, together with the desire not to have the disease - it may do more to prevent fraudulent use than in an AI improving the test results? Useful tool. AI - not so much?
cheers
Mark
Special Use is a regulatory term, it means the software is not currently approved for use by the local regulator but in certain circumstances they can enact emergency powers to use them.