Small Cap Value Report (Fri 9 Dec 2021) - RNWH, RBN, PHTM

Good morning, it's Paul here with the last SCVR for this week.
Agenda -
Paul's Section:
Lengthy preamble about current market conditions, and how I see the outlook for small caps, and areas of concern.
Renew Holdings (LON:RNWH) - another set of impressive results from this infrastructure support group. It's been a 25-bagger over 11 years, and still looks reasonably priced, considering earnings keep rising. Balance sheet still quite weak though.
Robinson (LON:RBN) - a profit warning due to higher costs. Profits expected to improve in 2022, as cost increases are passed on to customers. Surplus property disposals are imminent, but that cash looks necessary for debt reduction, which is too high. Overall then, it doesn't interest me.
Photo-me International (LON:PHTM) - reassuring update, trading towards top end of existing guidance for FY 10/2021. Looks great value on a PER basis. Might be worth a punt, but I'm not sure about the long-term outlook.
Paul’s Market View
When markets are turbulent, I tend to be deluged with messages, asking for reassurance about particular shares (e.g. BOO & SAGA - two of my largest positions, which have been poor performers of late), and what my market view is.
I always emphasise that I don’t know (and don’t try to guess) what market prices will do in the short term - nobody knows, and I particularly dislike it when people comment that “this will happen”, etc, when we’re all just guessing. I prefer “could”, or “might” happen. Although it is easy to accidentally slip into overly confident language, so I’m sure there are plenty of examples of that to be found here in our archive too! We all tend to become over-confident in bull markets.
Small caps seem to have been absolutely dire in the last few months. As is often the case, many charts look strikingly similar. This is how I see things over the last couple of years -
- Late 2019/early 2020 - what they called the “Boris bounce” - removal of uncertainty over Brexit fuelled a big rally
- Massive sell-off in Feb/Mar 2020 when covid originally struck - wave after wave of panic selling, globally
- Strong recovery from April 2020 - driven by huge Govt stimulus & support packages (e.g. furlough), and re-opening in the summer
- Drifting down in the summer/autumn of 2020 - valuations extremely cheap by then
- Huge “everything rally” began around Oct/Nov 2020 on news of successful vaccines
- Bull run continued until the summer of 2021, with many valuations becoming stretched, and momentum/complacency fuelling further increases. Easy money pulled in many inexperienced new traders, who think markets only ever go up!
- Summer-2021 to now - a big sell-off in small caps, culminating in sometimes irrational, panic-driven selling, lack of liquidity in small caps, inflation & supply chain worries, and renewed covid fears
Nobody has to fill in a form to say why they’re selling or buying a share, so we just attribute reasons to market moves, which may or may not be accurate.
The above is obviously just my personal view, and with the benefit of hindsight.
Although to be fair, we did see the covid crash coming here at the SCVR - I remember writing about it in Feb 2020 before the big crash, as did Graham Neary, who was contributing at the time, discussing the different strategies when you think a big market downturn is coming, which are -
- Sell at the first sign of trouble, and sit in cash. If you’re going to sell, it’s usually best to be the first to sell
- Put on some short positions to hedge the longs (this is what I did in early 2020), or
- Do nothing - just ride out any downturn, in the knowledge that markets always come back up again, sooner or later (this was Graham’s approach at the time).
- The worst option, to be avoided at all costs - cling on, with increasing worry, then panic sell at or near the bottom, then watch from the sidelines as things bounce back.
When time permits it will be interesting to re-read some of the SCVRs from early 2020, to remind myself how things unfolded with the first wave of covid.
More recently, my usual strategy of hedging my longs by shorting US indices worked well until Sept 2021, but has since been an absolute disaster. The nightmare scenario has unfolded for me personally, with my hedges (shorts on US) soaring, thus incurring heavy losses, at the same time as some of my UK small cap longs plunging. So my portfolio has really taken a battering. My ungeared, long-term positions (SIPP & ISA) are down about 20% from the summer peak, but still up year to date. Whereas my geared portfolio must be down about 40% from the peak, but is also still up a bit year to date. All pretty grim, but not disastrous.
Markets go up & down, and we have to accept that. It’s certainly given me food for thought, and I won’t be using that hedging strategy again! (although it has worked really well in the past, just not this time).
So if your portfolio has taken a battering in recent months, you might get some solace from knowing that your % losses are probably less than mine!
Buying/Selling - I think it’s important to try to be clear in our own minds what we are doing in the markets. If you’re making buy/sell decisions based on the movements in share prices, then you’re trading, not investing. Nothing wrong in that, if it works for you. But don’t kid yourself that you’re an investor. I know lots of people who think they’re investing, but are constantly buying & selling shares, based on sentiment & emotions, not fundamentals.
Whereas if you’re investing, doing thorough research, and avoiding speculative shares, then you can ride out market downturns. If the fundamentals of a company are still good, then the share price should recover from any downturn. Although it’s always important to constantly check whether you’ve missed something important - e.g. a change in competitive landscape in an industry, or downside risks we may not have spotted before.
If doubts emerge, I find it’s usually best to sell at least some - e.g. as happened recently with Purplebricks (LON:PURP) - when I read negative press on it, I sold out at a loss, but the loss would have been larger if I’d dithered and put off the decision to sell.
We don’t have to be emotionally committed to any share - it’s not like supporting a football team. Changing our minds on shares, when the facts deteriorate, is probably the single most important way to avoid losses - which often means taking a small loss before it becomes a larger loss. I’m not preaching here, this is very much a memo to self, and it’s useful writing it down to collect my thoughts, and other people might find it interesting too.
Growth/value - looking at my own portfolio, it does seem that the value shares have generally fared a lot better than growth shares, with some exceptions. Car dealers have been particularly good this year, with their plentiful freehold property assets, and bumper one-off profits. Plus takeover activity emerging too with Marshall Motor Holdings (LON:MMH) (not one I hold, but could be indicative of takeover interest in the whole sector, I reckon). I think Vertu Motors (LON:VTU) (I hold) still looks cheap, and Redde Northgate (LON:REDD) (I hold) recently published fabulous numbers, helped by its fleet of vehicles rising in value, and strong demand for its leased white vans.
I’ve noticed that lots of small caps on (what I consider to be) irrationally high valuations, have plunged - examples that spring to mind are Tristel (LON:TSTL) and Dotdigital (LON:DOTD) . Maybe they’ll go back up again, I don’t know? But it could take a lot of good news to power expensive shares back up to previous highs, let alone exceed them.
For this reason, I’m currently not opening any new positions (or holding existing ones) where the valuation looks stretched. The danger is that they may have been resilient so far, but it only takes a bit of selling to smash a price down - e.g. Sdi (LON:SDI) earlier this week suddenly dropped 10% for no apparent reason. It could be a buying opportunity, but what if the seller has a big position to unwind? We just don’t know, that’s the trouble.
Are share prices rational? - in a word, no. Or more accurately, not always. Share prices are not an accurate valuation of a company and its prospects. The share price is just the current balance of marginal buyers & sellers. People buy & sell for all sorts of reasons, and using many different strategies.
This creates opportunities for us - every now and then, the market throws bargains at us, particularly when panic selling sets in, as it has done recently. If you’ve got an irrational seller, then the chances are they could be selling at the wrong price. Or, they could know something important that we don’t, which is always the worry.
This is why I tend to like buying things only if there’s been a fairly recent trading update. That reduces the risk of something bad lurking out of view.
It’s usually best to hold our nerve during periods of market volatility, in my view. Although an alternative view is that selling, sitting in cash, and buying back when the uncertainty has lifted, can be a good strategy too. Although you often have to pay more for less uncertainty.
Over/under shooting? I remember earlier this year, by spring/summer our comments on company updates here in the SCVRs usually seemed to say something like, nice company, trading well, but the valuation is too high.
I feel overall, the “everything rally” from last autumn got out of hand by spring/summer 2021, and we’ve now seen a correction of often inflated prices. Hence recent market falls could be seen as logical, as the froth comes off the market. A good example is Gattaca (LON:GATC) - it was a good recovery share, and I banked my profits at 150p earlier this year, based on that being a fair price for the share, in my assessment. Imagine my bewilderment then, when almost the next day, it began a powerful move up to over 250p! I checked the figures again, and couldn’t see any rational basis for that move. Since then, it’s come all the way back down again, and is now down to only about 132p. I’ve crunched the numbers again more recently here on 5 Nov, and think it looks quite good again now on fundamentals, providing nothing has gone wrong that the company hasn’t disclosed.
My point being that we shouldn’t anchor to the peak price of 260-270p in the summer, because that was probably an irrational, inflated price. So the price now being half the recent peak doesn’t necessarily mean the share is good value. In this case, I think it does look quite good value now on fundamentals, as you can see from the Growth & Value section of the StockReport -

.
As always, this is not a recommendation. We don’t recommend shares here - Stockopedia is all about using the research tools, and thinking for ourselves. Writers discuss what shares we like, and why, but obviously some will do well, and some will do badly. That’s life, nobody is infallible, because the future is inherently unpredictable, and things change all the time.
I haven’t got a clue what the share price of GATC is going to do. But I’d rather buy now, when the valuation looks good value, than buying into a speculative, momentum-driven spike at double the price. People like buying shares that are going up in price, but if you detach too much from fundamental valuation, then it’s an accident waiting to happen. I like buying good companies when they’ve gone down a lot. Which sometimes works, and sometimes doesn’t, like all strategies.
Covid risk - where do we start with this?! I think the last 22 months has taught us one key thing - nobody knows what’s going to happen!
What we have seen though, is which companies & sectors coped best/worst with covid, and it was often very surprising.
Looking forwards, I’m no expert, but for me the key points are that vaccines can be quickly changed - both Moderna and Pfizer have said in the last week that work has already begun, and will take about 3 months, to adapt the vaccines to target the omicron variant more specifically. Hence the worst case seems to me another possible lockdown in the spring? Will the public stand for that though?
The shares I hold are all companies that are securely financed, with plenty of liquidity, so they could easily survive another lockdown, and then benefit from pent-up demand again afterwards. So this doesn’t worry me particularly, and arguably has already been priced-in, with travel/hospitality shares looking bombed out again.
New anti-viral drugs are coming in, which have shown very good results in trials.
I’ve read that viruses mutate over time, into milder illnesses, which is how Spanish Flu died out apparently. Anyway, I’m already way out of my area of expertise, so won’t go any further!
Following data from S.Africa, omicron is highly contagious, and is rapidly displacing delta as the main strain, and (so far) seems milder. If that remains the case, then it could be very good news. (Source: Dr John Campbell)
The key point is that the world has not come to an end with covid, and I suspect it might end up being a game of cat & mouse between the virus & mankind. Maybe with 6-monthly or annual booster jabs for the vulnerable, something like the seasonal flu jabs? Hence based on the information available now, I am not particularly worried about covid, or its impact on the long-term value of shares. It’s likely to cause plenty of volatility in the meantime though, with an ever-present risk of good or bad news.
Investors/traders seem to react, or over-react to every twist & turn of the covid situation, which creates buying & selling opportunities for people with a longer term investing perspective.
Inflation - this is a worry. As we’ve mentioned before, the main issues seem to be -
- Higher inflation could see expensive growth shares being de-rated to lower PERs
- Ability of companies to pass on price rises to customers - is the absolutely critical question
- Wages - I see in today’s paper, some Tesco workers are rejecting a 4% pay rise, saying it’s below inflation of 4.2%, and unions are planning strikes. That worries me, and could be the start of a self-fuelling run of inflation.
I’ve done a lot of research on the Thatcher era, as I’ve mentioned before, and inflation was incredibly difficult to eradicate. Once inflation expectations become embedded, then it tends to self-fuel. Government spending also runs out of control, mainly due to inflationary pay rises being required every year for millions of civil servants, benefit claimants, pensions, etc.
I reckon inflation was masked in recent decades by ever-cheaper imported goods from the Far East, offsetting price rises elsewhere. That's now reversed, this year anyway. In future, who knows?
There again, we had a couple of short-lived bursts of higher inflation in the last 10-15 years, linked to sharp falls in sterling triggering higher import costs, and it washed through the following year and inflation fell back down again. Maybe that could happen this time too, as supply chains get sorted out in 2022 or 2023?
Higher wages and possible industrial action are new things - e.g. press reports that some Tesco workers rejected a 4% pay rise, and threatened to strike, because it's below inflation at 4.2%. Plus remember that minimum wage goes up by over 6% in April 2022. Also I hear that companies are enhancing perks, to retain staff, so more hidden costs there. There again, higher wages gives workers more spending power, so they can afford to continue buying higher priced goods in the same quantity, which feeds through to higher revenues for companies selling them things.
Nobody knows, but at the moment I’m sceptical that higher inflation is just a blip. For that reason, I think property and shares are the only places to invest. Cash and bonds are the worst areas, where value is eroded by inflation. So I see higher inflation as potentially good for shares in companies with pricing power, and bad for shares where there isn’t pricing power. I wouldn’t touch supermarket shares, for example, or their low margin suppliers either.
Which brings me on to…
Supply chain - obviously this has been chaotic of late, with delays & huge cost increases primarily for imports from the Far East, but also lorry driver shortages in the UK & elsewhere.
Yes this is causing profit warnings for some companies, but it’s temporary. Supply chain problems always get resolved, but I have no idea how long this is going to take.
I take typically a 2-5 year view with my shares, so personally I’m looking through this, and accept that there might be some more profit warnings in my portfolio.
Once supply chains normalise, then inflationary pressures could reverse, and solve the issue of inflation, who knows?
We’ve seen this week a profit warning from Made.com (LON:MADE) which saw FY 12/2021 guidance on revenues fall by 10%, due to shipping delays. However, this year’s profit disappointment should feed through to next year’s profit boost, as the deferred sales are booked in 2022. We’ll probably get similar news from Scs (LON:SCS) and Dfs Furniture (LON:DFS) , both of which have fallen in sympathy. Again though, to long-term shareholders, this doesn’t matter at all, and provides a cheaper entry price.
Interest rates - the traditional link between inflation & interest rates doesn’t seem to exist any more. Governments need to borrow heavily, and what better way than to print money (QE) and buy up their own bonds using this newly created money.
I don’t believe that Govts can stop doing QE any time soon, whatever they say, and that interest rates seem likely to stay low maybe for a very long time.
Hence personally, I don’t see higher interest rates being a particular threat to equity markets.
With real interest rates (after inflation) now heavily negative, then holding cash only makes sense for shortish periods of time. Or if you‘re expecting an imminent market crash. After all, we can’t buy bargains if we don’t hold any cash. Holding cash comes at a cost though - with c.5% p.a. of that money’s purchasing power vanishing.
Overall - putting all that together, I’m happy to sit tight in my carefully chosen UK small caps.
I accept market volatility, even though it’s been painful in recent months, we have to take the rough with the smooth.
Everyone has their own strategy. Mine is to seek out large, multi-year rises, in value/GARP shares. I only need a couple of big winners each year for things to work out reasonably well. Inevitably, plenty of things go wrong, or disappoint. For example, I never imagined that Boohoo (LON:BOO) (I hold) would halve in price this year (along with sector peers), nor that Quiz (LON:QUIZ) (I hold) would double or French Connection (LON:FCCN) more than triple this year. It’s quite bizarre how things pan out sometimes, hence why we need to put our eggs in plenty of different baskets - over-concentration can be horrible when it goes wrong.
As always, the above is just my current view on things, which could turn out to be right or wrong, and is subject to change at any time.
On balance then, I’m expecting continued volatility, maybe some more profit warnings, but I think all my positions are companies which should be more valuable in 2-5 years’ time than they are now. Some are bound to go wrong, but that’s life. The winners should outweigh the losers, I hope.
Robinson (LON:RBN)
82.5p (down 12% yesterday) - mkt cap £14m
Trading Statement (profit warning)
Robinson plc ("Robinson" or the "Group"; stock code: RBN), the custom manufacturer of plastic and paperboard packaging, today issues the following trading statement, prior to the announcement of its final results for the year ended 31 December 2021, which are scheduled to be released on 24 March 2022.
Revenue guidance for FY 12/2021 - £45m (up 21% on LY) - driven by an acquisition, and price rises (passing on higher resin costs)
Announced previously that Q3 demand was weak, which has continued (or worsened in some sectors) in Q4
Profit margins down, due to higher costs (eg energy, freight, wages)
Margins expected to “start to recover” in 2022, seeking “substantial price increases from all customers”
Small restructuring done in Nov 2021 - saving £0.3m annually, with exceptional costs of £0.2m
Property disposals - £3.4m gross proceeds expected to be split between 2021 and 2022, £2.4m above book value. Further disposals expected in 2022.
Profit guidance -
As a result of the lower sales volumes, the directors now anticipate that full year operating profit before exceptional costs and amortisation of intangible assets will be in the range of £1.2m - £1.3m.
Profits in the 2022 financial year are expected to be ahead of 2021.
My opinion - this is a very illiquid share, so doesn’t really interest me.
It’s only set to make 4.4p EPS in FY 12/2021, a PER of 18.8
However, the £14m market cap does look appealingly low, given the £3.4m property disposals, and that it’s still profitable, with 2022 figures set to improve on a disappointing 2021 (there are no forecasts for 2022).
However, the last balance sheet shows that debt has risen considerably following an acquisition and capex, with net debt too high at £13.7m as at 30 June 2021. I would therefore expect the cash from property disposals being needed to reduce debt, so no upside for shareholders.
Could be worth a little dabble possibly, if profits in 2022 can be managed upwards, but on balance I think the high net debt puts me off.
.
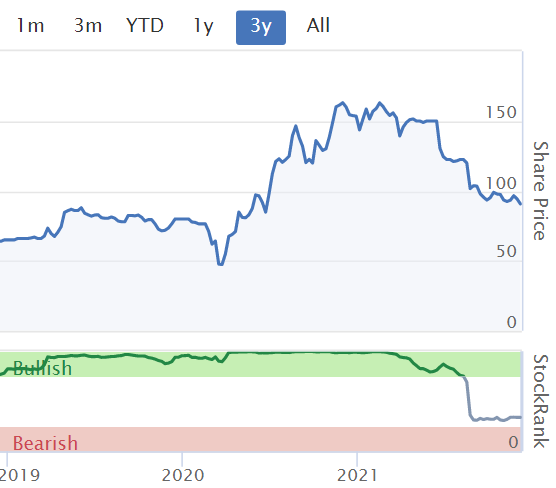
.
Renew Holdings (LON:RNWH)
845p (up 5% yesterday) - mkt cap £665m
Renew (AIM: RNWH), the leading Engineering Services Group supporting UK infrastructure, announces its preliminary results for the year ended 30 September 2021 ("the period").
Very good numbers - adj EPS is up 22.5% to 50.5p - giving a PER of 16.7
Outlook sounds confident -
Current Trading & Outlook
· Positive trading momentum carried into new financial year
· Strong forward order book underpins confidence in achieving further progress in 2022
· Confident in our future prospects and well positioned to capitalise on our strengths to target new opportunities in attractive markets
Balance sheet - is still weak, with NTAV negative at £(44.1)m - although there is very little net debt, so it seems to benefit from negative working capital.
My opinion - this share has been a huge success in the last 11 years, rising about 25-fold.
Well done to the company, and any shareholders who have held all the way up!
The valuation doesn’t look stretched, because rising earnings have justified a higher share price. As you can see from graph 4 below, the PER range has re-rated back up to where it was about 5-6 years ago.
Stockopedia shows the forward PER as about 15, which seems fair for a business that has established such a good long-term track record.

.
Photo-me International (LON:PHTM)
58p (pre market open) - mkt cap £221m
Photo-Me International plc (PHTM.L), the instant-service equipment group, announces an update on the Group's trading for the financial year ended 31 October 2021.
This is self-explanatory, and very clear guidance, which sounds reassuring -
The Group's better than expected trading momentum in May, June and July continued in the fourth quarter of the financial year ended 31 October 2021, driven by continued recovery in photobooth activity and a strong Laundry performance.
Consequently, the Board expects that revenue will be slightly ahead of previous expectations of approximately £210 million, and profit before tax (before exceptional items) will come in towards the upper end of previous expectations of between £25 million and £30 million, subject to completion of the FY21 audit process.
Europe - trading well, particularly France
UK returned to profitability after restructuring
Japan revenues fell due to covid restrictions on travel (China similar impact)
Excluding Asia, the Group is making good progress in returning to pre-pandemic performance levels in the last months.
Expansion ongoing, of laundry & food vending machines
Healthy net cash of £33.8m, even after paying £10.8m for acquisitions this year
Outlook - “business activity is returning to pre-pandemic levels”.
Cautious about inflationary cost pressures.
My opinion - neutral, because as we’ve discussed before, the group doesn’t provide the information investors need to determine the revenue/growth/profits by division. The worry for many years has always been that photo booths are likely to ultimately be in structural decline, and could eventually disappear. Although I remember investors worrying about that for the last 20 years!
Valuation looks very attractive, with lots of green (long bars, for the colour-challenged) here, in particularly look at that low PER, which I’m drawn to like a moth to a lightbulb. So it could be worth a punt at this level, more as a trade than a long-term investment, maybe?

.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

101 comments
Dear All
The second comment is we all have our own investment style, choices, ideas and thoughts. There is no right, no wrong. There is always I could do better, and I made a good choice. It is always about being opened minded, knowing your bias, being prepared to listen and to be prepared to change.
Having learnt painfully through the last couple of years, to do your own thing, to make your own choices, is very hard.
To give my personal perspective of telling my 79 year old mum having taken over from a BEEP BEEP BEEP BEEP BEEP wealth manager wish I had done it 10 years earlier when even knowing nothing I would have saved her 10's of 1000's, that her pension (all ISA) has gone down >30% and the low point was July 2020, got out, went back in and watched it all go down further...we are still in recovery mode and are still below January 2020, we got close in September but not there yet. But to be able to say this week if Australia opens up next year you can go and visit your big sister for the last time (having lost her brother last Christmas and sitting in her front room watching the funeral on my work laptop) and if Aunty Flo is not there go see your Katie and Pru (nieces) and just get Business both ways there is the money there, if not I will cover it is a good thing. We have enough to cover your basic lifestyle (state pension + forecast dividends), and it is 50:50 income:growth.
I will say from a personal perspective, sometimes being totally in cash is the right decision, if that means you sleep at night (ok not a lot and you are answering calls and messages but you try), get your kids breakfast, iron their uniforms whilst they eat and get them to the school gate before it shuts, and be there to listen to your wife in tears at her mum's bedside whilst she is dying (having lost her gran 1 year earlier and her dad 2 years earlier) and then turn up and deal with a stressful day at work, before walking out to get the girls from the school gate and go I will do the other hours after they are asleep, and don't forget to load the washing machine as they have no clean uniform! Yes I missed rises, but I also missed falls, but then I did with hindsight what was the best decision I could make at the time? I was there, I was not perfect, I made lots of mistakes, I was grumpy and cranky, I had 3.5/10 days for my girls but in 20 years time what am I going to think I should have not sold £ZYX or I should have bought YXZ I could have made or not lost?
I still remember @Carmensfella giving a lovely message and an invite to Mello, yes I eventually watched the catchup at a similar time at night to this message, but the feeling that someone cared enough to say here is something to hopefully make a positive in your day is massive. Yes I want to subscribe because they are amazing events, but I just physically do not have the time in my day right now, this month, next month. And that right now is a massive positive to me knowing that I cannot do everything and admitting that. I am a full time dad, I try to be the best husband I can be, I am kind of holding down a full time job and in between I am responsible for my mum's sisters and own financial wellbeing. Oh and daughters and nephews...
Currently I am still trying to apply my Lent resolution, to be Content. It is not easy.
I am incredible lucky. I have a wife, I have two lovely daughters who know their dad and are in the bedrooms either side of me. I have a job. I have a house in what I feel is a nice place. I have a pension (Fidelity and Aviva, as I am not at the point where I can emotionally or mentally go to a SIPP but I hope that I will be able to in 2022 or maybe 2023), I have cash savings and I have an investment portfolio.
If I go simple numbers, Pension 60%, Property 30% and Investments 10%. Yet the 10% sometimes can drive emotion disproportionately.
There is only one person locally I talk money too locally, a friend of my wife's and her daughter is friends with my daughter. She knows the facts of where we are as a family, and trusts me to help her to help her family get there too. How to learn about money, finance, investment when your own parents know nothing. Now that is scary too, what do you tell others? But she wants to extend it to other mum's, I am not an IFA and part of me says run away and do the opposite to what I do. But then she never claimed Child Benefit and lost several years of state pension as a result, so maybe I am not as stupid as I sometimes feel I am and maybe I do add value to others? I was there to talk through remortgaging options when her husband was not...
But I also have responsibility for my mum's ISA - which is her pension. My sisters ISA/Shares, and currently trying to sort my dad out him having talked to my sister 2 weeks ago finally asking for help at 82...
But right now I am 8 working days from Christmas. The job I am working on feels a total car crash (or appropriate description) and who knows if I will be made redundant again in the New Year, or offered an assignment that I will never take.
My glass is so overflowing that I am stood knee deep in a beverage. But there are days I feel that it is empty or I do not have a glass.
I think to the people I work with, manage, supervise I cannot be honest with my current financial circumstances, we are just too different.
So to conclude as I need to go to dad's in a few hours and try to work out what is wrong with the chimney so why they can have a fire, obviously they will not accept putting the heating on and me just buying them another tank of fuel oil (rural Cumbria here).
We all have our right decisions and wrong decisions. What is right for me might be wrong for Paul or Jack. What is right for Paul and Jack, might be wrong for me. But the ideas, creativity and thoughts on here are amazing, please keep inputting your ideas, I am choosing not to name the stars in a reasonably priced car (does that show my age?)
Just to read today's report I have five companies, and trusts to have a look at and think about written on my note pad. To go with the other pages of notes, maybe I will make something, do nothing, or lose lots, but that is next weeks decision. Or maybe next months.
My sister is 50% cash, mum 15% and me 40%. But I sleep at night - ok badly but I get some, I still have a job, the girls have clean and ironed uniform and breakfast and my wife has a brick (apparently that is not an acceptable modern word for emotional support)! We are all slightly up this financial year (sorry I go from 6th April due to tax). So glass filling up. But not as high as June or September...
And the last part is, Hambleton Food bank has just had an electronic transfer as my Christmas gift to those who actually need, sorry this delayed the posting. That is only one part my realization that I, we, have an obligation to society, yes we pay too much tax and do not get me into a rant on government and organizational inefficiency, yes I give to selected charities on a monthly basis on a percentage of net take home (I could give more), but we have a decorated tree with presents underneath, we have family plans with those still alive, but there are those who's needs are far greater than ours, and is our >50% loss is just a dream to them. When you actually talk to the people who run the charity, they do not want Tesco Finest in the foodbank bin, they would rather have three Tesco Value (or supermarket chain of your investment choice - I do not hold any) because that is three meals not one.
So Paul your support of Zane is thoroughly encouraged, is it worth doing another pitch pre-Christmas? Jack what is your charity of choice? Not that we are tugging the heart strings but really can you not give away £10 to a good cause this week?
Ok time to switch the laptop off.
Thank you everyone, I am so grateful to be a part of this group.
Tommy
Ps. I hold
pps. I do not hold
pps. I bought too high
ppps. I sold too low
Paul, apologies you will be enjoying life and I am catching up with what happened a long time after the markets closed and the kids are asleep.
Thank you for taking the time to give your thoughts, they are always appreciated and I have been here a long while it would seem and you are a big part of that.
Jack, you are an upcoming star and keep up the performances!
Brilliant Paul, thought provoking article to recap the very purpose of Investing versus Trading and the purpose of Stockopedia.com website, at times, I forgot it in the "go along with the crowd" tide.. Thanks again.
Thank you for your thoughts, Paul, and I really appreciate your open analyses. I know you are SCVR in your bones, but for the sake of some others, as this is a general market commentary discussion, I would just like to say that my take on portfolio construction is that there are diversifiers that help me sleep nights. I don't rate cash much, like you, but rather than hedge the UK companies' market, I use UK listed collectives or one sort of another.
Firstly, a few investment trusts in very specific areas a PI can't realistically cover, like £VOF. This has performed very well and is still on a 20% discount to NAV. Why, because it's far away and niche (and has a communist tinge?). My take is that Vietnam is larger than the UK in population, probably twice as large in working population, growing 6-7%, handling the pandemic better than the UK, with inflation falling back below 2%. It has a significant trade surplus, and a continuing runway for growth from those wanting to move manufacturing from China. Oh, and it's only just beginning to re-open tourism, which would boost GDP further. Imagine if the UK could be described that way. But some 93% of stocks are held by Vietnamese nationals. It's done very well for me, even if all parties are frustrated at the discount.
The Stockopedia guys know my frustrations at the cessation of RNSs on ITs. You can also get access to Private Equity through a few, mostly very well performing, listed PE funds now. Yep, it's equity investing, but it's easier to have a long-term view in responsible PE these days (e.g. Oakley Capital Investments (LON:OCI), Princess Private Equity Holding (LON:PEYS), £BEPT), see Tamzin's PI World webinar from earlier this year, which opened my eyes.
And bond proxies like Biopharma Credit (LON:BPCR) and Real Estate Credit Investments (LON:RECI) paying 7.5% to pay the bills seem satisfactory.
If there were more of an interest in listed collectives, perhaps a board for that would be of interest to some?
Oops, not £BEPT but £BPET!
Thanks for sharing your thoughts with us Paul. If there's one thing that investing teaches us it's humility. I'm pleased to say that RNWH has been a 20 bagger for me, having originally bought in 2002, and topped up 7 years later. If there's a downside to successes like that, it's that they become too large a slice of one's total. I have sold a few, but only to utilise my annual CGT allowance. Having been investing directly in UK equities for over 50 years, I regard myself as a (somewhat grizzled) old timer. The Covid collapse of Feb/March 2020 was certainly a bleak time for most investors. My way of coping: hide behind the nearest sofa and chain myself to the nearest radiator. There have been other bleak times though, for example the bear market of the early 70s. Hard to believe, but before the market turned, previously blue chip stocks (eg Dixons Photographic) were reduced to penny stocks status. The overwhelming consensus was that we were witnessing the end of capitalism in the UK. That's the time to wade in with all guns firing. A group of institutions started buying and the market rose almost vertically for about six weeks.
Perpetual loser Bidstack (LON:BIDS) just announced what appears to be a company changing deal.
Main problem, as always with these small companies and big deals, no mention of revenue expectations.
I wouldn't say Bidstack (LON:BIDS) is a perpetual loser. Fundamentally it made a similar mistake to many others in that it didn't raise enough money and expected revenues to kick in much earlier than they did. They had an opportunity to raise funds at an elevated price and also failed to do so. A lack of market knowledge/experience within the board I concluded.
The concept and the tech may have real legs medium term though. Plenty of execution risk but this exclusive deal with one of the worlds largest sport franchise game companies is a big endorsement - primarily because it is exclusive.
Revenues come from a %age of any Ad spend so now they put the demand and supply together. Typically you see circa 3-5% in commission in the AdTech industry. This is why you often see a big J curve effect in AdTech businesses. Once they put the demand and supply together you can get a huge revenue impact very quickly. Before you do that it's often no more than a dribble. This is why, as exciting as an opportunity may be in this space , you always have to consider that early stage investments (speculations) may lose all your money.
I am long but with my eyes wide open, but this announcement has de-risked my speculative position considerably in my view. What I am looking for now are signs of the impact the deal has on (a) other exclusive deals and (b) revenues coming through at what should be a good time of year for games advertising.
Bidstack (LON:BIDS) the hint is EA Sports (they have historic dabblings with and some connections thro advisors and/or board)? If it is someone like that then its gigantic. If its an exclusive with a private marketplace for advertisers on EA games facilitated thro Bidstack's platform then that's premium stuff.
Short term there will be a TU maybe pre new year or maybe bit after. If existing biz has met expectations or exceeded and they guide well for 2022 then price legs again. If its a bit meh for 2021 then pulls back.
Even at 3.5p and >£30m market cap Bidstack is v low price IF (!) it is next thing in ad tech platform on seen to be clearly executing and commercialising.
Lots of uncertainty and risk. Lots of potential. Note, Bidstack (LON:BIDS) have a potentially much more robust, scalable and sustainable high margin ad tech platform than someone like Mirriad Advertising (LON:MIRI) ...which got a lot of love on little results
Agree. Still plenty of risk but de-risked. Let's see if it is EA Sports......as you say that would be huge exclusivity.
on the AdTech / MarTech topic I listed to quite an interesting new IPO called Silver Bullet Data Services (LON:SBDS) They have a new automated platform called 4D that acts as a targeted advertising service in the world of no cookies. They also take a %age cut so revenues have large (but speculative at this stage) potential, though their advisory service is apparently profitable. Not enough on its own to justify the market cap in my opinion but the 4D business "could" be very exciting. Got £9m in the bank - burning £350k p/m on investing in the platform but have a blue chip and pretty extensive client list. I'd be interested in your thoughts - I did pick up a small position, but only small as still feels very speculative to me.
I'll look..I really might not have view/understanding tho. This is one of the reasons that Tremor International (LON:TRMR) will be okay in no cookie world as there will always be innovative data work rounds (Tremor also have other reasons cookies is as much positive as threat to them given their platform).
A problem for someone like Silver Bullet Data Services (LON:SBDS) is that ultimately they are a price taker from a bigger buyer as its unlikely they can corner the non cookie iteration of the world and will have many competing services and work rounds
I think the Silver Bullet Data Services (LON:SBDS) platform is designed to sit above the DSP layer. So the advertisers who are looking to better target their adverts plug into the platform and it then uses its proprietary data algo's to allocate to the supply side. Agree there may be other competing services but what drew my attention to them was the current and growing client list. They are clearly doing something right on the advisory side and that feels like it may well translate into take up of the 4D platform. If it does I could see them as a take out target for someone like Tremor International (LON:TRMR) perhaps.
I say going from 40p to 2p, continuous false dawns, missed targets and repeated fund raisings is the very definition of perpetual loser.
Should say I hold a considerable amount (for me - 10% of portfolio by purchase cost, less by current value) at average 5p.
For the record: On Mello Bash on 21 June 2021 when Bohoo was 360 the Expert audience vote was like this:
Buy 68%
Hold 22%
Avoid 5%
We all base our opinions on the facts and figures as at that point in time. Can you predict the future with certainty? If so, what's your trick? A time-travelling spaceship? A crystal ball? Tealeaves?
thanks for the opening comments, really good stuff
Interesting market commentary. Perhaps I have missed it but I haven’t seen any discussion here of the very different interpretation (financial not medical) of this ‘pandemic’ provided by, amongst others:
Ernst Wolff
John Titus (BestEvidence)
Catherine Austin Fitts
Gregory Mannarino
Anton Kreil
Their views certainly help to explain why shorting the US market up until now has been a losing game!
Are share prices rational?
Shares in Peloton fell 11% after a fictional character in a TV show died of a heart attack after using a Peloton bike....
https://uk.finance.yahoo.com/n...
C'mon man, spoiler alert!
Boohoo (LON:BOO) A comment in the FT that Morgan Stanley are saying it is only Primark in the UK that can compete with Shein on price, which probably doesn't help sentiment. I dumped mine quite early thankfully, but I can't believe the price they have got to. they look like they will be the classic "why didn't I buy these?" in two years' time. Gattaca (LON:GATC) I'm still impressed with the £0.5m the founder spent on shares.
On another point, all the small caps investors in the US are complaining too. On growth stocks, I follow the US investing champion from 2019 and he has been on "risk off" for about a week and prior to that amber for some time. When the market is rolling over then breakouts stop happening and that is a warning to be wary.
Stocko has been saying £Boo is best ever investment and a no brainer for ages......!!!!!!
Thank you Paul for an excellent review , as always; and for those specialist who add insight into their specific Sector and Industry with which they have professional knowledge.
Thank you Paul and all contributors to the discussion this morning.
A word from me on supply chains.
My career has lasted about 50 years in freight forwarding (supply chain, logistics or whatever you want to call it) :)
I've never seen anything like the current disruption and I remember the days of Suez closure (not the Ever Given) and Sheikh Yamani doubling the price of crude in the early 70's. I don't think the logistics issues are over yet. The fact that the steamship companies are charging USD 8000 per TEU* from Far East to Europe when two years ago the price was a bit shy of USD 1500 demonstrates that the carriers have learned how to earn money and they will not "unlearn" that any time soon. During the first covid shutdowns when cargo originating in China all but dried up, the carriers implemented a program of "blank sailings" - this meant omitting ports of call to create demand on the next sailing. This put a floor under the freight rates. Then when demand for consumer products (stuff) escalated , as consumers couldn't spend their money on fancy holidays, the shipping companies couldn't believe their luck. There were simply not enough containers to go around and they were going to the highest bidder. Then the ports of discharge for all this additional cargo couldn't cope with the volume. For example in November 2021 there were occasions when more than 70 containerships were waiting outside the port of Los Angeles. If those ships were on average 20,000 TEU each, that's one massive pile of containers just sitting outside the port (average waiting time for a berth was 17 days). Once landed, it was taking more than two weeks to get a container on to a truck and out of the port of Los Angeles (normally takes 1 or 2 days). Those delays meant that empty containers could not be returned to China in the usual timescale adding to the scarcity of shipping opportunities.
There are bigger container ships under construction, but these won't come into service in any meaningful number till 2023, but these will mainly replace existing ships, so not make massive increase in capacity.
Shipping industry insiders are predicting a correction in freight rates, maybe 20% early next year which will still leave shipping costs more than 4 x two years ago.
If I were a betting man, I'd say historically high freight rates will be with us throughout 2022. The shipping companies will be loathe to give up the huge profits they are currently enjoying.
* TEU = 20ft Equivalent Unit, so 1 x 40ft container = 2 x TEU
so you are saying buy Braemar Shipping Services (LON:BMS) or maybe £CKSN ?
Another possibility is Tufton Oceanic Assets (LON:SHIP)
http://www.tuftonoceanicassets...
The shipping companies are giving up significant business as larger customers turn to hiring their own ships. Amazon, Wal-Mart, and Home Depot are all doing this in the US and routing to less congested ports.
Amazon are acting as freight forwarders and buying their own design 53 foot containers.
https://www.cnbc.com/2021/12/0...
https://www.supplychaindive.co...
https://www.freightwaves.com/n...
Although they are large companies, I think they will be a small proportion of containers shipped. Amazon has been this for a while, yet container rates have still increased in the last year. That is also the US, so will be less relevant to the UK? Also where are Amazon charting the ships from? Presume these same shipping companies?
I was looking at freight rates and surprisingly to me Air fright is less than 2x the shipping freight rates for 200kg. Freight rates have fallen back a bit since the peak in September, maybe that was for Christmas orders? Here are some freight rates: https://www.freightos.com/ship...
Braemar Shipping Services (LON:BMS) I hold, I think the shares went down too far, I notice directors have been buying.
Electra Private Equity (LON:ELTA) just going through the recent investor presentation on Hotter shoes (current Electra Private Equity (LON:ELTA) with name change and switch to Aim then being called Unbound).
Could be an interesting play here, so be good to get others thoughts to see if I've got anything wrong.
Hotter confirms it is trading at above £5m ebitda in current year (around £5.5m based on broker forecasts). Current gross debt is £12.5m but there is over £6m cash on b/s split equally between Hotter and Electra Private Equity (LON:ELTA) so post name change net debt should be circa £6m.
So we have the business on an EV of £31m trading at just 5* EV/EBITDA
There is also an insurance claim for covid of £15m which the board think has a strong chance of success, so there could be hidden value here as well being as much as half the EV.
Given that Hotter seems to be growing well this valuation feels wrong to me.
Yes, but the near term is uncertain for Elta/Unbound as we don’t know how many of the current holders need to sell up which could cause a large overhang. Time will tell, but it could be a bumpy ride for a while.
I hold.
Hi David
I can't fault your analysis of the value in Electra Private Equity (LON:ELTA) (I hold) but as IGotPoesJacket points out there is an uncertain overhang of stock from institutions (who only have mandates to hold Investment Trusts, don't want to hold such a small cap, cannot invest in AIM listed entities). Hopefully patience will be rewarded!
Re Electra Private Equity (LON:ELTA) (really Hotter/Unbound!) - I have followed the same logic (and hold). If accounts correct, and nothing changes (except an 8% Mgt dilution at demerger) then in round terms, on x10 5mn EBITDA, I put the value in £Mns at (5x10) -5=45; 41.4*0.92 vs 26 today .
If they had listed 6months ago when online was hot and the market more optimistic.....
My only concern (beyond an all male core Mgt team and an MD with a suspected man bun focused on over-55s female core audience!) is that fixed costs are still quite high. I hope that is because they have an infrastructure to support growth.
I really like the table of strategic drivers and target market (old/rich/underserved online whilst going online fast). If they do build any kind of platform or eco-system, they will become an attractive target to someone like Saga (when they are themselves generating cash!).
Excellent Paul, a really great read. Honest and comon sense.
Keep it up!
Wow Paul! At your brilliant best today. Have a great weekend.
Steve
Hi IGotPoesJacket,
Also, you may have sold one at a decent profit that went on to go further, but did the next stock you bought do even better?
Excellent point - my current quandary is whether to hold a couple of stocks that have gone down but look like they are on the turn, or sell them and buy something else that may or may not do better faster. It would then be the comparison that counts, performance-wise. I'd have to include transaction costs, as my holdings are not large enough to regard these as negligible.
Paul - many thanks for that comprehensive review of the market - excellent.
One minor point - you put it up at one minute to midnight when it was still the 9th - you may wish to change the header to the 10th.!
Paul: "I think property and shares are the only places to invest"
As you emphasise Paul, the future is unknowable, so why are property and shares the only places to invest? If the future is unknowable then we should accept the possibility of a wider array of possible outcomes, including recession, stagnation and deflation. Or how about a little outbreak of cyber war? Also, I'm told that history shows the possibility of things like global pandemics too, although I can't imagine such an outlandish thing ever happening in my lifetime. All of those would be terrible for property and shares but other asset categories would benefit.
Also, you expect volatility, but a portfolio of property and shares is not well placed to handle volatility. If volatility is what you expect then why not invest accordingly? I disagree with your idea of holding cash only for short periods of time or when you expect a market crash. Most people are pretty terrible at judging such things.
Your portfolio is a bet on the positive performance of the (UK) economy, with zero probability assigned to other outcomes. Given your age, that's not a bad bet to place, but it is a bet. Many of your readers have different circumstances and particularly for those with a little more grey hair, UK property and shares are definitely not the only places to invest.
Every dog has its day, remember when those cars and motorbikes that had the word 'Sport' behind their logo? Now we are down to having fun on electric scooters before legislation and the police catch up so enjoy betting on the stock market while you can, cmpeckham, as I do.
Silver
Hi Paul,
Interestingly frank and honest intro, as ever.
Please take this as the constructive criticism intended, but I have no idea why you think shorting US Large Caps to hedge a concentrated portfolio of UK small caps is a good idea. Why should it work? For any hedge to work there has to be correlation and I just don't see it. Like all things where the results rely on luck I'd be surprised if this worked more than 50% of the time if you toss the coin often enough. While I'm glad to hear you are still in positive territory for the year I know you wont kid yourself that's a good result on a risk adjusted basis... BTW I sometimes find myself trying to fool myself and justify poor results on the same basis, it's only natural! :)
As for your comment on inflation, this is something I hear all the time. IMO the "higher inflation => cash is bad" is a lazy generalisation propagated by the investment industry to keep those customer fees coming in. What this fails to take into account is that everyone has their own inflation rate based on the goods and services they buy. All I know is that the basket used to calculate UK CPI and RPI bears no relation to how I live or spend my money, so all I can concentrate on is the overall performance of my portfolio.
We have to remember that cash is a position in itself, it acts as a natural partial hedge too without the cost (other than opportunity cost) of trying to do something like shorting an index . From a portfolio perspective, capital loss is far worse than the effect of inflation on any cash holdings, so it's important that we don't all feel the need to lower our investment criteria just to reduce the cash in our investment accounts because we are fearful of something that is important but unknowable longer term. If you have a well proven investment process, stick to it, don't let something unknowable steer you off course.
All the best, Si
I always think of cash as an option on equity purchase at a later date.
I thought we would see the end of the photo booth with the rise of digital photography however after trying to do my own passport photo and failing I found these booths made the whole process a piece of the proverbial. Remember this next time you renew a passport. I don't hold £PHTM.
On Photo-me International (LON:PHTM) the hidden value would be if governments decided to also collect biometric data for passport applications. I believe this is what is happening in Japan (hence why the boom for them as all ID applications had to go via a booth?) and also in France with e-signatures? I remember reading in my research some time ago that many countries are moving to collecting more data (signatures, fingerprints, etc) for ID documents. Which will mean a market for "booths". But of course there is the data privacy opposition to that.
They key is the chairman and de-facto controller of the company. Who has been buying steadily throughout the 2020s and 2021s, which is a strong vote of confidence.
A very personal thank you Paul for your bearing of the soul on the one hand and the very practical review of your thoughts on the recent past, the current and the future. I have taken a copy of it and an early new year's resolution to read it at least fortnightly in the next 12 months. Its something I should have done myself,for myself, and I thank you for it.
Re Gattaca (LON:GATC) I have always thought it was a disaster, as the two individual companies and now the combined one. With hindsight it has been in the right place at the right time this year, but has never justified its rating. I just think it has relatively poor staff and management compared with some of its peers. Slow and ponderous come to mind, probably unfairly.
I do think that consumer spending thinking is changing, and that will come out in the new year with companies like Scs (LON:SCS) showing poor results and poor repeat orders. I think that something like the power issue - where it has all gone horribly wrong and we will see price hikes not seen for some years - may have a disproportionate effect on thinking, The same goes for inflation on staples which I am seeing in the shops. I think that mass consumer thoughts will go into having a good expensive Christmas, then holding back for a good summer holiday away with the family. Im not sure that spendingon sofas etc will hold up. Ditto on bathroom etc - carry across to Victorian Plumbing (LON:VIC) I wonder though that may be much more complicated. ( Even so, a good buy in opportunity now I would think, and an interesting £500k purchase by a member of the family reported today)
Just my thoughts on a small element of the market, but there it is for what its worth. Thanks again Paul and a happier new year for your portfolio and investing style.
I own Scs but and my stop loss is 200.
Thanks for the write up today. When things haven't been going so well it can get frustrating and actually quite depressing and I've certainly felt this in the last few months as some of my shares have gone down by 30-50%.
I have a basket of about 35 shares though and so that's contained my losses to about 10% (I am still up about 19% for the year.) I feel I start questioning myself and my convictions and the temptation to sell (based on the trading instinct) is strong but I've held firm for now.
Working full time I still generate excess cash to add to my portfolio at the right time but I haven't done so this year (for the first time in a few years) as I have been too cautious about the overall risks to the market but am also conscious this money is being eroded by the perils of inflation.
Its important for my well being and state of mind to be able to sleep well and I'm reasonably risk adverse on the whole. Hearing how others are doing helps put things into perspective much more than just being in your own portfolio bubble so again thanks for the write up, I often prefer the macro look to the company led discussion.
Fantastic preamble.
With the unbelievable speed of transmission of omicron I think a lock down (or something similar - Plan C?) is highly likely well before spring.
Article in the Telegraph this morning is suggesting that there may be between 500,000 and 1m new cases per day by Christmas (based on figures doubling every 2.5 to 3 days). We are currently reporting about 50,000 new cases per day. Even if the symptoms are commonly mild, this explosion in numbers will cause a huge growth in hospital numbers and is likely to put the NHS under intolerable strain.
Hopefully the article is completely wrong and things pan out much better than predicted.
@dfs12
Why would mild symptoms cause a huge growth in hospital numbers?
I see this latest panic as a dead cat ploy. Boris is in trouble so he puts a dead cat on the table to distract attention.
I'm no epidemiologist. If interested full article here:
https://www.telegraph.co.uk/ne...
Why would mild symptoms cause a huge growth in hospital numbers?
Because not all symptoms are mild! We don't yet know the full story with Omicron, but yes, it appears the average symptoms may be less severe. But as with all other variants the symptoms almost certainly range from none to death. The mean of that distribution may be at lower than for Delta, in terms of severity, but if Omicron is much more infectious, as is clear, then if you end up with a lot more people infected you can still have a lot more people with severe symptoms or dying than we have with Delta. You can't just look at the average symptom severity, the infectivity matters too - and that's clearly higher.
I won't disagree that what finally got Johnson to act was an attempted diversion, but if that's the case it's a good thing - though as usual the advice is a opaque mess and not strong enough. Why on earth are things like singing, about the most infectious activity possible, exempt from restrictions, and night clubs, likewise very infectious, exempt unless very large? And why not bring in covid passports for activities like that, except for being scared of his more outrageous backbenchers?
Following up Paul’s superb market view and comment today, I wonder what readers here think of this information?
https://www.cityam.com/anxious...
This link is to a City AM article suggesting there hasn’t been a single death from omicrom variant in 38 Countries. That’s hard to believe in view of the more stringent regulations here and elsewhere since news of this new variant broke.
If death rate really is still zero and it remains that way with new variant very fast spreading but much milder than previous variants what are the market implications, especially for the sectors that have taken a terrible covid hit like hospitality, holidays and travel? The obvious conclusion is that current stricter regulations might be quickly reversed.
I'm not sure what to make of that. It will be interesting to see the analysis in a few weeks.
I've just read through this thread on twitter which also provides reassuring reading.
The nutshell is that deaths are significantly fewer in the latest wave in South Africa. Possibly attibuted to greater immunity in the local population rather than a milder strain even allowing for the younger infected population. The caveat is that it is still early days and the death rate is seemingly a way from the peak.
Also cases seem to be nearing a plateau (or a limit of testing).
https://twitter.com/jburnmurdo...
You may be less likely to die but more likely to catch it, which may increase the burden on the NHS. That is the main reason for the restrictions.
You may be less likely to die but more likely to catch it, which may increase the burden on the NHS. That is the main reason for the restrictions.
Correct. People are still ending up in hospital, but for less time and with less severe outcomes.
So far Omnicron has only been seen at scale in younger populations who are mainly unvaccinated but previously infected. It looks like Omnicron can evade natural immunity, and we are waiting with baited breath on what level of protection vaccination brings and the levels of hospitalisation among older, vaccinated groups.
If the vaccination firewall holds then probably Omnicron is good news. If not, then we've got another miserable winter ahead while the vaccines are tweaked.
EDIT: in fact the first data is out, albeit on a small sample. Protection against Omnicron from two doses of Astrazenca and Pfizer is very low after 25 weeks (10% for Astrazeneca). That protection rises to 75% with a booster jab.
https://www.theguardian.com/wo...
timarr
Following up Paul’s superb market view and comment today, I wonder what readers here think of this information?
https://www.cityam.com/anxious...
There's certainly some promising news in that link. However, it's probably still too early to say if the death rate from Omicron will really be that low. It's only 16 days since first reports. Up till now really severe infections have usually taken two weeks or so to develop, and deaths seem to lag by about 3 weeks from rises in infection.
It's certainly beginning to look as though the severity of infection is less with Omicron than Delta, but given it's much greater transmissibility there remains a very real risk of a big increase in hospitalisations.
1m cases per day here in the UK????
Maybe the journalist who wrote this thinks that our population is not 70m but 70b.
Just makes me wonder what is going on behind the scenes and who is benefiting from these foolish headlines.
This has been discussed before, cases don't go on doubling every 2.5-3 days. When Covid first came here we saw similar increases in cases. Cases have been around 40-50k for a while now.
The article lacks some context. For example, at the height of the Swine Flu epidemic (mild symptoms for most - mild being I spent three days in bed as mid thirties, fit strong male) what was the case rate per day? No one knows because they didn't measure it, could well have been several hundred thousand.
If it's a million cases a day, it will all be over by the end of January.
Very thorough review Paul. It is worth listening to Andy Brough’s latest interview on PI World.. He sees more value at the moment in parts of the FTSE 100 than in small caps. His last purchase was Royal Mail (LON:RMG) and he also mentioned Marks And Spencer (LON:MKS), both of which I hold.
His last purchase was Royal Mail (LON:RMG)
Really!? If Paul is worried about workers striking for inflationary pay rises, I couldn't think of a worse share to hold! I'm not particularly impressed by Andy Brough myself and that goes back a long way as I used to hold one of his Schroder UK Unit Trusts from when I first started out investing in 1995. The performance was terrible, mainly because he bought rubbish companies. I wish I'd known that at the time :)
All the best, Si
Apparently the latest Royal Mail (LON:RMG) results presentation started with the union leader saying how great everything is.
I'm not going to invest in Andy Brough's funds; I prefer to make my own mistakes. But you don't have to agree with everything he says to find the interview interesting.
I'm not going to invest in Andy Brough's funds; I prefer to make my own mistakes. But you don't have to agree with everything he says to find the interview interesting.
Good for you, John. I don't find his ideas the least bit interesting (they all seem to be poor quality recovery plays) but then he's about as diametrically opposed to Terry Smith and Nick Train as you can get in the investment world, so that should be no surprise!
All the best, Si
Agree with you Simoan. A lot of the 'top' fund managers seem to make a lot of bad calls. I know not everyone can get everything right all the time, and that's probably why they hold 50-100+ stocks, to ensure a bad call can get easily absorbed.
I remember on a PI World interview with Richard Leonard, he came across very obnoxious and arrogant talking about how he could "make a lot, I mean a LOT of money" when he bet big on Novacyt. What happened after? It dropped like a bomb after a profit warning. In his subsequent interview with Tazmin, he talked about how he had sold a lot of Nova (despite claiming in his first interview it was a long term hold) when it started to peak before the big drop - how convenient?!
He's also talked about Made.com being a huge conviction play - it's been dropping continuously since the IPO, and following the profit warning this week, it'll be interesting to see whether Mr. Leonard sold it well in advance of said warning ;)
What about the other calls he made that quadrupled???
Reach plc for example.
It’s not fair to pick 2 wrong calls and just completely ignore 10 correct ones.
Diversification is the name of the game.
What is his performance though?
I looked at Andy Brough's funds and they are pretty average, around the same as the FTSE AllShare index. A lot of funds don't outperform the index.
Not keen on his largest holdings either Tremor International (LON:TRMR) and Frasers (LON:FRAS)
Presumably rubbish!
This is why they are in these positions for so many years!!!!!!
Cause they are not good enough!!!!!!!
Anyway thanks for cheering me up.
Good luck with your investments.
Well in my opinion, there is no point in buying active funds unless they out perform the index, you may as well buy a tracker, which usually has lower fees. Actually I was disappointed in Andy Brough's funds, I thought they would have performed better.
If you have the Richard Leonards funds performance figures, post a link.
No I haven’t.
I just think that overall they are winners and this is all that matters.
With your suggestion regarding active funds I agree.
However, knowing what they are buying for these funds and then doing your own research on individual shares of interest is a good start.
Diversification and holding on these big winners is the recipe for success.
Seen it , done it.
Enjoy your weekend.
It is interesting to listen to these different Fund Mgrs. but i consider that often they are selling their own book. If you do ever get tempted Trade it and monitor the news & price & sell at your own stop loss level.
I also hold Royal Mail (LON:RMG) - I think the relationship with the CWU (most of the frontline postal staff) is much better than with Unite (which represent the management levels - and where many of the recent cuts have been). It is Terry Pullinger (Deputy General Secretary of the CWU) who is put in front of the investors on the results.
Clearly strikes have plagued Royal Mail for decades and the current job market with pressures on supply chains and truck drivers is not ideal for Royal Mail. There is a new round of negotiations about to kick off. But on the last results call it was stated that Royal Mail was not seeing too many problems and it was more their competitors who were now being forced by market pressure to start offering terms and conditions closer to those currently offered to regularly employed Royal Mail staff.
Royal Mail (LON:RMG)
simoan
"Really!? If Paul is worried about workers striking for inflationary pay rises, I couldn't think of a worse share to hold!"
I sort of had that default simplistic position too until recently - I did revisit this share not so long ago though , as someone i respect invested in RMG and they never invest without doing some very decent research. I too have ended up having a dabble despite my slight concerns about their old skool tech and union issues.
Note if you ignore Royal mail side of teh buisness and look at the GLS subsiduary that had an adjsuted operating profit of £358 mill year end 28/3/2021 - the current market cap of the whole entity is only £4.86 bill. So as a separate entity the p/e for that side of the business alone could almost justify the full market cap is you give it pe of 14!
The royal mail side of the business made £344 mill adjusted operating profit on its own so not too shabby.
Note there are £51 mill of intragroup costs that need to be allocated between tose two business - so probably deduct £25 each from the above numbers.
I would say year just finished wss stonkingly good year for royal mail - so there is the danger this is a value trap if this level of great earnings does not repeat into the future. As things stand though 70% of the way through the current year forecasts for both 2022 and 2023 look intact.
To boot royal mail has gota great balance sheet - so much so that they have just voted through nice chomping special dividend this year with share buybacks in place too.
So the numbers look decent even if the future prospects are probably uncertain and unions tech and the stuff are obvious future concerns.
Hi rmillaree,
I sort of had that default simplistic position too until recently - I did revisit this share not so long ago though , as someone i respect invested in RMG and they never invest without doing some very decent research. I too have ended up having a dabble despite my slight concerns about their old skool tech and union issues.
I appreciate things may have changed but the reality is the price is lower than when I stagged the IPO in 2013 ! I'm not a "value" investor and the potential union issue is just the cherry on the top of a not very high quality cake (awful margins, returns on capital). I wish you luck with it.
All the best, Si
Royal Mail (LON:RMG)
Must admit i made a quick buck on then IPO too - i think the main thing is the current level of profits being generated is a step change up from what the company has done in the past. It's certainly not a high conviction play but with the current expectations being that profits will stay at this level (i suspect they may hit some headwinds at some stage) i am happy to hold. Ref margins and returns on capital - well most of the investment has been done here in the past - even after acounting for capex they did 82p of freecashflow last year (60p previous year) so on current cashflow metrics the current price is stonkingly cheap (and presumably why some shrewd cookies are investing). As you say any low margin business has to be highly vulnerable to the earnings vanishing in a puff of smoke if or when times get tough - so i can fully understand with this company is uninvestable for some on that basis alone.
I hold both, made 150% on Marks And Spencer (LON:MKS) and Royal Mail (LON:RMG) has a nice divi.
Well done Paul, a brave and thorough review.
I guess that I am at exactly the opposite end of the spectrum to you; I'm driven by a long term, asset allocation based view of the market. So I tend to change my perspective about once every three years, most recently into buying quite a few private equity trusts.
I only started to keep an annual record in 2007, so 14 years ago, but my plodders score is as follows:
Personal investments +365% and I've spent all the dividends
Personal pension +355% and I've drawn down 25% to help my family
Wife personal pension +466%, no money drawn
FTSE 100 around break even, excluding divis
So I very much believe in the power of markets to compound wealth, even without being at all clever.
I have no idea what the compound interest rate is to arrive at the above, but I think it's around 9.5%. Someone will tell me that I've got it entirely wrong!
Using dates of 1.1.07 and 1.12.21 and 360 as a finish I make it 8.9% ignoring withdrawals.
Good morning Paul - Could you review Nexus Infrastructure's (NEXS) results - (I hold)
A quick nose test at full-year results looks promising:
"TriConnex has had a significant year on revenue and profit in 2021, passing
£50m revenue for the first time. We believe 2022 will be a breakthrough year
for TriConnex in the residential energy transition.
eSmart Networks is at the cutting edge of EV charging for cars, fleets and
buses and has delivered exceptional growth, profitability for the first time
and a burgeoning order book."
Thanks...Zorba
Re Paul's pre-amble, the screen that I tend to use for self-generated ideas returned nothing through the spring and summer but is now beginning to return some options (including slightly bizarrely, Glaxo!).
Wow, today's must be your longest preamble yet, Paul! But again many thanks for your insight, I'll be looking at it now and then all day.
Thanks for the kind comments re my preamble today, much appreciated.
Large cap Associated British Foods (LON:ABF) might be worth a look - it owns Primark, and today reports strong trading at Primark (ahead of expectations), and in line trading at its food/agriculture division.
Taking these factors into account, we continue to expect significant progress, at both the half and full year, in adjusted operating profit and adjusted earnings per share for the Group."
At 1934p per share, Stockopedia is showing the forward PER as only 13.7, and the shares have sold off a lot recently. Could be a buying opportunity, as Primark is so dominant, and expanding internationally too.
I'm not that familiar with its figures, so more than ever important to DYOR, just thought I'd flag the possible potential here. I don't have any spare cash, so can't buy any personally, although I would if funds were available.
Regards, Paul.
I agree Associated British Foods (LON:ABF) looks very good value and I hold. Remember it is not just Primark, they have a large food business which has performed very well and that is probably worth £10bn on its own. They also have net cash, so on a sum of parts Primark is almost being thrown in for free!
hi Paul
Thanks for your preamble today. A great read and some very thought provoking commentary.
I have used Sharepad for a few years but only recently joined Stockopedia. One of the main reasons for joining was the SCVR having seen you present on Mello a few times.
I'm enjoying my daily read of SCVR. This service is worth the subscription on its own.
Many thanks to you and Jack for your terrific daily input. Keep up the excellent work.
ditto ^
'Paul's Market View'
A really interesting read this morning. As a relatively new investor, I particularly welcomed your thoughts on selling shares. An awful lot of time and comment is given towards buying, but some really great info in there on thoughts regarding selling.
Also I think it is important to talk about losses, again we usually only hear about the winners, not the losers. I picked up a very good tip from the rather insightful Tim Marr on these pages, keep a watch list of your shares sold, it can be very illuminating!
Norfolk'n'Good: I keep a weekly-updated .xls spread sheet listing the prices and another for my sold shares which is never updated but includes an extra sheet listing those companies which multi-bagged since they were passed on to optimists. I update that sheet when I need a reality check:(
Silver
I keep a weekly-updated .xls spread sheet listing the prices and another for my sold shares which is never updated but includes an extra sheet listing those companies which multi-bagged since they were passed on to optimists. I update that sheet when I need a reality check:(
I can't believe others don't do this. How else can you sanity check your investment process if you don't monitor your selling discipline? I have a sheet in my XLS that shows all sells with price. I can see it right now and beat myself up if I want to! :) Fancy selling Vertu Motors (LON:VTU) at 47p! Even though that represented a 110% return I've missed a further 47% rise. I know you're supposed to leave something for the next holder but that's a little too much :)
All the best, Si
Shirley though, when you feel like beating yourself up on the one that got away, you go and find one that plummeted after you sold it? Also, you may well have sold at the right time and the share did indeed stagnate or even fall after your sale but then circumstances change and the share goes again on an upward trajectory without you revisiting it.
Also, you may have sold one at a decent profit that went on to go further, but did the next stock you bought do even better?
All data has context, just looking at a stock price as a stick to beat yourself with probably isn't helpful.
My tail of woe was selling out of XP Power last december ish (slightly overvalued) and moving into Carnival (Cruises) in the january - what a muppet i am. Didn't even have the sense to sell carnival as covid worsened. One up 60% and one down 60% sigh - perhaps i should stick to index trackers?
Would you like to buy my buy high, sell lower, buy back higher and then sell even lower training courses? :)
Sorry late at night and just nice to see an honest I beeped up comment rather than an hey look at the amazing profit I made on this am I not a genius?
Tommy
ps. I hold neither
pps. I hold some good companies that are in green (Stocko +ve)
ppps. I hold some even better companies that are in red (Stocko -ve)
Tommy, you sound extremely stressed. I also live in Cumbria. Would you like to meet for a chat? I understand your situation. It gets better. In time you will look back and wonder what you worried about. Cumbria is a great place to live. It’s like having won the lottery. Go climb a hill or two. It will help put life into prospective. This is my therapy.
Please do feel you can talk to someone. Money does matter but it is not everything. I know this because I have lost it all in the past. You have a wife and kids, sit back and watch them. Nothing is more important. I was married once and I miss having kids. I had 3 kids. The eldest will be 30 now. We have spoken once in 5 years and that was at my second sons funeral 3 years ago. It is my second sons birthday today. He would be 28. But I still have my daughter and a3 yo granddaughter. So I’m lucky I invest and trade so hopefully I can leave her a sizeable fund. The beauty of investing is it is long term. A few days won’t make a difference.
Keep smiling.
Thank you Paul - what an excellent summary and ramble for a Friday Morning.
My relatively concentrated (20 ish) share portfolio is entirely in small caps (because I enjoy it much more) and despite a relatively small overlap in shares (Boo and Saga I think - which are relatively small positions for me) I am down a very similar 21% since a peak in September. And in the classic way, gently at first and recently much more quickly. I am also still up a few percent on the year as a consolation.
I don't know when it will stop. But then I didn't expect to fall this far right now. As a long term investor it's not my style to take abrupt action - so double checking my rational and valuations and sitting it out is all I can do - especially since some of my holdings are tiny and illiquid - though I probably dabble a bit too much whilst I am waiting.
Anyway - despite the way it feels right now - which is like I worked really hard on my homework and somebody just handed it back to me with 3/10 - 20% down is really not a big deal in the scheme of things.
By the way - I also enjoy hearing from John Campbell and find him a good and balanced source of information in comparison to many these days,
Keep your views coming - I really value them.....all of them, especially the ones that are a bit harder to take on board.....
cheers
Mark
Fabulous start to the day Paul, thank you. Investing is a lonely business in that we are each pitting ourselves against others in the market. The SCVR is such a great place to share and enjoy the views of others about markets and companies and your in depth perspective today is a great example of the value it brings to me.
Cheers
Francis
[edit] Distribution Finance Capital Holdings (LON:DFCH) £28m placing last night at 40p, a 28% discount, "in response to investor demand". You remember the law of supply and demand? Well chuck that in the bin.
Hefty Director buy at Victorian Plumbing (LON:VIC) announced this morning - Product Director Neil Radcliffe has spent £498k buying 529,267 shares at 94p.
He now holds 30.2m shares, 9.3% of the company, so is obviously wealthy. Even so, half a million quid is a fair chunk of change, so I think that's positive. Probably under pressure from Institutions, to show some positive commitment, I imagine.
I like the look of Victorian Plumbing (LON:VIC) around this level.
It's amazing how eCommerce companies have sold off, down almost to value share territory now. I think this whole sector could be a really good opportunity in 2022, if growth rates return to pre-pandemic levels, after the boom & bust of 2020 & 2021 growth rates. So a recovery in eCommerce sector shares will probably be one of my main themes for 2022.
Regards, Paul.
same directors sold at 268 at the IPO
Well the CEO partially realised some of his position at IPO but maintained a big stake. I think that's perfectly reasonable as not prudent to have your entire wealth tied up in a single company. If institutions were willing to buy these at 260p I would have done the same.
A great read, Paul and one which I shall return to at my leisure and with a cup of tea.
Terrific, thought-provoking overview, Paul. Many thanks!
Excellent summary of where we are now- you have an amazing ability to tackle difficult subjects and provide great insight. Keep the faith Paul all things turn.
A virtuoso performance Paul, thank you (and all the other authors) for your contribution to the SCVR.
I really appreciate your style which does not shy away from talking about losses / failed strategies.. although tough to take, these are the best learning opportunities!
Thank you!
Hi Paul
What a fabulously candid review of the market and your own experiences/investments.
It is this open reporting style that means I can trust the opinions that you (and other contributors) give.
It has also taught me to try to use a longer time frame when investing and resist the temptation to react to short term volatility.
Your work is much appreciated.
Fair enough Paul, as I agree with most of your comments.
However, I believe that the markets major problem is liquidity and that this important issue will be carried over at a faster pace in 2022 and become the major driving force for even more correction in medium and small caps.
I have never experienced so many new issues and so more placements in the market before. I can name here over 20 placements that went wrong, for example McColl’s, and even more new issues that went horribly bad, for example Victoria Plumbing or Parsley Box.
As bubbles take time to form , for example Bitcoin , the same can be said with liquidity drying out.
However, as you correctly pointed out, being invested in good growth valued companies ( with no or small debt ), will have no material impact in a portfolio in the near future.
It is also helpful that the company you give your money to , the likes of Somero or Vertu , RESPECT the concept of shareholding.
Personally I hold 40% now in cash.