Small Cap Value Report (Fri 9 Feb 2018) - IQE, TNI, HRG, 7DIG, SUS

Good morning!
Paul is writing again this morning, with additions to yesterday's article. He will be adding:
- DFS Furniture (LON:DFS)
- Dillistone (LON:DSG)
- Elektron Technology (LON:EKT)
- Creightons (LON:CRL)
So if you're interested in reading about them, his article is here.
Over here, I'm planning to start with:
- IQE (LON:IQE)
- Trinity Mirror (LON:TNI)
- Hogg Robinson (LON:HRG)
- 7digital
- S&U (LON:SUS)
And then I'll see if there are any other interesting stories to cover.
Cheers!
Market movements: a quick follow-up on the general market level. The FTSE is in the red today, at 7140 as I write this. This compares with 7780 on January 12. So we have a lot more potential bargains lying around than we did a few weeks ago.
Last year's low was around the 7100 level, so I'll reiterate that this is a key "level" - I think the mood would start to get a lot more bearish if we retraced back into 2016 territory.
I am still 25% in cash and have placed a few bids under some stocks I'm interested in. If somebody hits my bids, I'll be pleased. Or if the market doesn't drop low enough to hit them, then the rest of my portfolio will probably be doing ok.
Don't forget to bear in mind the potential impact of a stronger GBP on your stocks. One of the big-caps I own is British American Tobacco (LON:BATS) and I need to remember that its earnings in dollars aren't worth quite so much as they were before, when converted to GBP.
I'm also still playing with the idea of shorting the NASDAQ or some component of it, to hedge my exposure to market sentiment. However, the logical side of my brain is telling me that the hedge has a negative expected outcome and that it's a fine strategy to remain unhedged while also holding plenty of spare cash in the event of a major market crash.
IQE (LON:IQE)
- Share price: 98.7p (-2%)
- No. of shares: 756 million
- Market cap: £746 million
Response to Share Price Movement
Another prominent bear has had a go at IQE, the manufacturer of semiconductor wafers.
This time it's the US-based Muddy Waters. You can find its IQE research on its website.
It calls IQE an "egregious accounting manipulator".
I've had a chance to read the document and I am much less convinced by this document than I am by the typical short thesis published by these folks.
The argument is that IQE's transactions with its joint venture, the Compound Semiconductors Centre (CSC), are "not substantive". But I think everybody already knows that this is the case.
MW says that IQE might have "taken advantage" of its joint venture partner, the University of Cardiff. It is indeed something of a mystery how IQE's PPE contribution to the joint venture, in lieu of cash, was valued in the deal at nearly 5x its previous carrying value.
But in the worst case scenario, and if the PPE was overvalued, then what? It means IQE got a good deal, and therefore we should short IQE? How does that follow? Unless relations with Cardiff University were to break down, is there a problem?
- Accounting Issue 1 (IP Licensing).
I agree with MW's take on this. CSC bought intangible assets from IQE and started amortising them (writing them down) over seven years.
IQE recognised the payments from CSC as revenue. However, if these are purchases of IP, as described in CSC's reports, then IQE should have recognised the payments as representing a gain on sale of intangible assets, rather than as ordinary revenue. So IQE's revenues and gross margin would be overstated.
- Accounting Issue 2 (cash-cost purchases from CSC)
MW says that IQE is disadvantaging CSC by buying things from it at cash cost, instead of allowing CSC to make a profit margin.
I'm not entirely convinced by this. IQE's argument, paraphrasing it, has been that it is effectively doing its joint ventures a favour by sending them business, so as to help build them up to eventually win independent customers. These arrangements were temporary while they worked to become standalone entities.
That seems fair enough to me, so long as the unusual arrangements only last for a few years. On the other hand, it does make the 2015/2016 numbers less meaningful. And it's MW's job to find questionable accounts, so I can understand why it would want to look at this.
- Accounting Issues 3 & 4 (IQE carrying CSC at zero carrying value, and not recognising CSC losses)
The next issue highlighted by MW is that IQE arbitrarily changed its accounting policies and may have done so in a manner designed to deceive investors. It wrote down the value of its CSC investment to zero, after which point it did not have to recognise its share of CSC losses.
Again, there is no "smoking gun". There is no proof any wrongdoing whatsoever by IQE. As MW concedes, it may just be a somewhat arbitrary accounting policy.
This isn't to suggest that IQE bulls should be complacent. Losses have piled up at CSC which does suggest that the value of its preferred shares (£8 million) which are owned by IQE is speculative.
- Accounting Issue 5 (CSC is "non-substantive and an alter-ego of IQE)
For me, this is the least convincing line of argument. MW made a bunch of phony calls to IQE/CSC, and viewed lots of LinkedIn profiles, to determine that IQE and CSC are very closely related. Isn't that sort of obvious?
IQE's response includes the following statement:
CSC staff are employed under their own contracts. IQE provides support services including recruitment, to avoid the duplication of costs. The costs incurred by IQE are recharged at cost to CSC, as disclosed in IQE's annual reports and financial statements.
Sounds ok to me.
Conclusion: I think I can see both sides' point of view. I continue to think that IQE shares are probably overvalued. £150 million of revenue from a such a capital-intensive business doesn't justify the current market cap, in my opinion.
Also, the 2015/2016 numbers are hard to make sense of, given the transactions with the JVs. It's been helpful of Shadowfall and Muddy Waters to shine a light on them.
But, does that really matter? Most IQE shareholders are focused on the opportunity for revenue growth from Apple and other customers in 2018 and beyond. I'm sceptical of such growth materialising or at least translating to cash flow in a manner which would justify the current market cap, but isn't that what counts? Nobody investing in IQE today is doing it because of its profitability in 2015/2016.
Trinity Mirror (LON:TNI)
- Share price: 72p (+3%)
- No. of shares: 275 million
- Market cap: £198 million
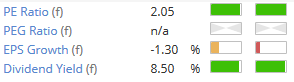
If you ever wanted to buy a stock on a PE ratio of 2x, the newspaper group Trinity Mirror is your chance.
In the trading update, Trinity helpfully tells us that market expectations for adjusted operating profit and EPS for 2017 are £121 million and 34.6p, respectively, and that it will "marginally" beat these forecasts.
Summary:
- Like-for-like revenue will reduce by 9%.
- Net debt c. £10 million
- Pension deficit £378 million, a reduction of £88 million versus the prior year.
- Outlook for 2018 in line with expectations.
Overall, it's a nice trading update with the key number for me being the pension deficit reduction.
We then have the announcement of the proposed £127 million acquisition of the Daily Star, Daily Express and related titles from Richard Desmond. His company, Northern & Shell, also owns Ok! magazine.
Northern & Shell's adjusted EBITDA for 2017 is estimated at £34 million, and Trinity reckons there are £20 million of cost savings to be achieved.
I've pulled out Northern & Shell's Annual Report for 2016 from Companies House.
In 2016, Northern & Shell performed as follows:
- Turnover from continuing operations down 11% to £208 million
- Operating loss from continuing operations of £17 million, versus a loss of £10 million in 2015
- Strong financial position with net assets (after deducting its pension liability) of £360 million, or £290 million if you exclude the value of all non-current assets. Most of the value is in cash and short-term investments.
- Pension deficit £64 million
These are 2016 numbers, so maybe things improved materially in 2017.
If its balance sheet is still strong, maybe this deal allows Trinity to solve some of its own balance sheet issues? According to the rationale:
Following the Acquisition, the Enlarged Group will have a robust balance sheet and leverage not increasing beyond one times EBITDA.
Later in the announcement, it says that the enlarged group will have "pro forma net assets of £635 million".
My opinion
My interest is piqued by this deal. The total consideration is £184 million, or 5.4x the adjusted 2017 EBITDA performance. We should be very sceptical about how much of that adjusted EBITDA was converted into net income. But if £20 million of cost synergies are achieved through 2019, this would be enough to send Northern & Shell back into profitability, on the basis of its 2016 figures.
There is no denying that the whole thing is very complicated. There are transaction costs of £7 million to be paid by Trinity and it will be a big job to separate the publishing assets at Northern & Shell from the other activities which Trinity is not buying. Trinity needs a new £75 million loan facility to pay for everything.
Further down the announcement, we learn more about Trinity's own pension scheme. The triennial valuation by actuaries (not by accountants) says that the deficit is c. £600 million (£1.5 billion of assets and £2.1 billion of liabilities). Trinity is supposed to pay about £50 million per year until 2027 into these schemes.
The whole thing is very ugly and complicated. It could be a value investing opportunity, but there is a lot to unpack to try to understand how performance might look in a few years. I've done some of that initial research this afternoon, but I think there is a lot more work required to try to understand what is happening.
The ValueRank is a perfect 99, if you are greedy for cheap earnings and dividends:
Another newspaper group which caught my eye recently is Independent News & Media (LON:INM). It looks a much more straightforward proposition than Trinity Mirror (LON:TNI).
Hogg Robinson (LON:HRG)
- Share price: 116p (+49%)
- No. of shares: 328 million
- Market cap: £380 million
Sale of Fraedom and Offer for Hogg Robinson Group
Congratulations to all shareholders after some excellent news this morning.
It is another case of a company which had a very large pension deficit, which dragged on the stock market valuation.
Maybe we worry too much about pensions sometimes?
Background: Hogg Robinson Plc has two divisions. These are HRG (travel management), and Fraedom (software to help companies manage card payments and their expenses as a whole).
It is proposed that Fraedom be sold sold to Visa for £142 million in cash (at a multiple of 17x operating profit in FY 2017), while HRG be sold to American Express Global Business Travel for between 110p and 120p, depending on how much Visa eventually pays for Fraedom.
It's an unusual deal structure. If the Fraedom deal falls through, AmEx will happily buy Fraedom and HRG for £361 million. If the Fraedom deal goes ahead, AmEx will instead effectively buy the sale proceeds (£142 million) plus HRG for £394 million.
According to my maths, therefore, AmEx thinks that HRG is worth £252 million and Fraedom is worth £110 million, while Visa thinks Fraedom is worth £142 million.
What a great result by Fraedom - two heavyweights willing to pay up for it!
My opinion:
I've not studied Fraedom before, so I can't comment on the merits of the price offered for it.
The price offered for HRG, however, looks to me like a great outcome for shareholders. Travel management is not a high-tech service and so I think 8x annualised operating profit (using H1 2017 figures) is a good result, particularly given the £250 million accounting pension deficit.
What to do? A circular will be posted tomorrow. Then we will have some idea about the timeline involved.
I've done a dummy trade for a couple of thousand pounds. With shares offered c. 116.4p, the effective price is c. 117.3p after commission and stamp duty.
So assuming that the Fraedom deal goes ahead (it has nearly 50% irrevocable undertakings already) and then the AmEx deal does too, there is a gross return of up 2.3% available to buyers at the current offer.
That's assuming they subsequently receive 120p from AmEx, which is the best-case scenario. There is a downward adjustment mechanism which could reduce the amount paid by a penny or so.
Might be worth a look.
7digital
- Share price: 4.8p (-1.5%)
- No. of shares: 399 million
- Market cap: £19 million
Everything I've covered so far today has been very complicated, so I'm hoping for a nice simple trading update here.
7digital provides music/radio services to businesses. Browsing its website, it offers a wide array of services - developer tools, a music catalogue, radio production, etc.
Revenues for 2017 are up £6 million to £17.3 million, the improvement being more than fully accounted for by £6.5 million from a single new client.
The revenue result is lower than analysts were forecasting, but the company reassures than adjusted EBITDA losses will be reduced versus 2016 and better than market expectations.
I can see forecasts for a pre-tax loss of £3.5 million in 2017. The company is supposed to break into pre-tax profit of £0.5 million in the current year.
It recently raised £8.5 million, massively increasing the share count and leaving it with a war chest of over £7 million.
Outlook: on the back of a profitable H2, the CEO says the company has "the right foundation for full year profitability in 2018".
My opinion: there are grounds for optimism, now that fresh funds have been raised and the company is probably in the black.
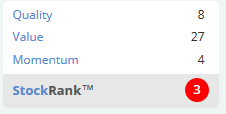
That said, there is no getting away from its speculative nature, and the Stockopedia computers identify it as a highly speculative Sucker Stock.
If you can figure out what the company's unique selling proposition is, and you have room in your portfolio for some early-stage companies, then it could be worth investigating. It's not really my style to invest in something like this, so I'll move along.
S&U (LON:SUS)
- Share price: 2205p (unch.)
- No. of shares: 12 million
- Market cap: £264 million
This is a financial stock which I started covering last year and which I've had a positive impression of so far.
Trading as Advantage Finance (external link), this is a motor finance company in the subprime sector with a small property bridging arm attached.
I own shares in one of £SUS's peers, PCF (LON:PCF).
Today's update says that trading is "strong and in line with expectations", and the share price hasn't budged. The outlook statement from the Chairman is confident.
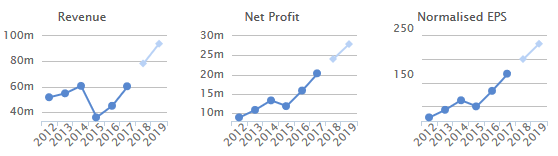
My opinion: I remain interested in and impressed by S&U. The growth in customer numbers is excellent (54k versus 43k a year ago) and revenues are set to have grown 33% in the most recent financial year ending January 2018.
A word on risk. Impairments are significant, at 23% of revenue. It's very much catering to those with weak credit scores. So it could be vulnerable in the event of a deterioration in conditions for the weaker consumer.
Stockopedia algorithms give it just an average rating.
On balance, I like it. It's clear about the segment of the market it's serving, and its formula is working:
Have a good weekend!
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

69 comments
Hi,
The Connect (LON:CNCT) profit warning didn't look too bad to me. Disappointing yes, but only a fairly modest miss on predicted profits. Does that warrant a near-halving in share price? I'd say probably not, so have been adding a bit to my position. Won't be a big one.
Regards, Paul.
Hi Graham!
IQE (LON:IQE) - I don't currently have any view on this stock, other than it's too complicated, and it dawned on me after reading Tom Winnifrith's article on it last year (which was very good, generally, in particular looking at competitors), that I didn't really understand the company or sector, so I sold out.
Trinity Mirror (LON:TNI) - I started buying this one recently, and bought some more today. What's interesting is that rising interest rates might now help reduce the pension liabilities, over time. So I quite like the idea of looking again at companies with pension deficits. Picking up more newspaper assets, and stripping out duplicated costs, sounds very sensible to me. The cash generation of newspapers is astonishingly high, considering it's a declining sector. Remember that TNI paid off its debt from cashflow, as I predicted back in 2012. Something may happen, who knows?
Creightons (LON:CRL) - I've just updated yesterday's report with a review of this - the profit warning doesn't look too bad to me, and it might possibly be a buying opportunity?
Have a lovely weekend everyone!
Paul.
Blimey Paul - back in Trinity Mirror (LON:TNI) ?
That takes me back - I remember a good few years ago buying in somewhere around the 20p ish and then reading something you wrote suggesting the fundamentals could support a valuation of £2+. I thought it was fanciful nonsense until I worked the numbers and found that I agreed.
As I recall you sold out 'too soon' on the phone hacking issues, I top sliced quite heavily between about 60p & 120p but we actually made the predicted £2 and then some, sadly that coincided with a period when I pretty much switched off from active investing - so I still have all of those.
I have however been accumulating again over the last few months so this is again one of my biggest positions. I believe PH recently re-iterated a price target of £1.90, which I'd regard as credible - but I don't honestly expect to still be holding at that level.
Hi Paul, you wrote:
"IQE (LON:IQE) - I don't currently have any view on this stock, other than it's too complicated, and it dawned on me after reading Tom Winnifrith's article on it last year (which was very good, generally, in particular looking at competitors), that I didn't really understand the company or sector, so I sold out."
For someone who doesn't understand the company or sector, with hindsight the timing of your buying and selling IQE's shares last year was perfect!
I said a couple of days not to rush to buy this mkt and here we go again. Ftse futures just about hanging on to 7000. Already the 2017 gains are history. My guess is 6800 will be short term lows with 6000 by end of year. Interest rates have to go up...central banks cannot hold them any longer. That means falling profits and the curse of many companies.....growing pension scheme deficits. My view is that plenty of company profits are dubious in fact and are just doubtful accounting mechanisms. Many assets are way overpriced and especially house prices. When you see all this building going on and at mad prices that no-one can afford or wants to pay....two bedroom leasehold box flats in Brighton for up to half a million? Cash......
I think its a case of if interest rates rise, the pension scheme deficits will fall as the liabilities will be discounted by a higher interest rate.
Interest rates rise usually implies some inflation, which increases the liabilities, and everything else being equal lower asset prices, which negatively impacts the assets side.
On IQE (LON:IQE) the bigger UK-based shorters haven't come off much yet though it is correct that the net short interest quoted in the UK is decreasing. As of today the net short is 10.7%
However, Bloomberg quotes MarkIt as having 22% of IQE (LON:IQE) shares outstanding short : I assume this includes the US funds who are short and do not disclose via the FCA?
https://www.bloomberg.com/news...
Good point on most discussed shares....... Friday afternoon distractions ..
Interesting watching the bears and bulls fight it out re: IQE (LON:IQE) . Price and volume action tells me that the bears have the initiative at the moment.
Re IQE (LON:IQE)
All interested parties should read the innocuous RNS from September 2014
IQE plc : Memorandum of understanding to establish a Centre of Excellence for Compound Semiconductor technology in Singapore
They announed some form of jv with no financial info as to contributions from other parties, anticipated outputs/revenues just that they were 'giving away' £14M of assets.
The shares collapsed circa 50% overnight. I thought the RNS was so dubious that I considered it a 'reverse ramp' if there is such a phrase. I took the risk and doubled my holding . A few days later it was announced the lead directors had lumped on at the new price which then reversed back to around the previous level. I then sold vowing never to get involved with this crew ever again.
I sold out of IQE in late 2014 when it became apparent that the (still current) CEO had taken out a loan against his equity holding, in similar vein to the notorious Quindell crew and using the same Equity First vehicle. Whatever the reason and however legitimate the transaction it struck me at the time as evidence of sharp practice and entirely consistent with the opaque accounting apparent even then and causing so much controversy now. Making things complicated and hard to follow is done for a reason, and generally not a good one.
Exactly.
IQE (LON:IQE) is so heavily discussed, whatever they do, I shall pass & look elsewhere.
Graham, bestace - re. IQE (LON:IQE) Many thanks for your insightful analyses. The consensus appears to be that the bears are desperately trying to find skeletons in the cupboard when in reality there is nothing of substance.
Have a great weekend.
Re IQE (LON:IQE), my slightly different reading....maybe something of substance but if so small in the bigger picture (ie is there bright future for IQE or not!) and thanks to all for te accounting education and discussion.
However, the difference is important as conviction in the eye of the market on dodgy accounting plus the unusual director arrangements re shares might lead to someone getting pushed. If the future is really long term bright (and as a long term holder I hope so), maybe they need some new leadership players to reflect a new, bigger company increasing focused on commercial deals that can attract the big institutional support the share price wants in both the UK and overseases.
Anyway, maybe we should all now wait for the next results statement - sure that will generate a lot of interest and close reading ! Management will absolutely be on show.
I only know about IQE from the discussion boards on here - so don't have any strong views either way.
But what seems odd to me is that IQE is nothing without its IP and seems to have sold it on for buttons. Questioning the accounting treatment seems to be something of an aside.
if you read the very sensible posts above in more detail you will see that they have done absolutely nothing of the sort.
I've been following the daily disclosable short position on IQE (LON:IQE) here: https://shorttracker.co.uk/company/GB0009619924/. It seems to me like the big shorters are buying back as soon as the price goes below 100p, and the overall disclosable shorts have decreased from over 12% to close to under 11% in the last few weeks. Even with this "market correction" the price seems to be holding around the 90-110p level.
I've read a lot of research documents and I find the SF and MW documents a bit too emotive and desperate to prove their case. I am attributing more weight to the actions of the shorters rather than their words when forming my view at the moment. I hold.
Certainly been a busy week, holding both Gattaca (LON:GATC) and Hogg Robinson (LON:HRG) shows both ends of the spectrum.
Personally I get amused by the asymmetry of weeks like this, especially when the "sell-off" is on the back of concerns the US economy is doing so well interest rates might need adjusting further upwards. If that's bad news bring it on again, and export it to the UK too please!
For some time I have been focussing on stocks with pension deficits. It might take some time but effectively it's a hedge against interest rates rising. Trinity Mirror (LON:TNI) updating on it's scheme(s) today for instance with deficit falling, and that's now historic, with gilt yields having risen further to approximate 2 year highs. Hopeful that a number of smaller UK companies suffering in this sell off in a knee jerk fashion will turn out to benefit from this realignment of pension obligations.
IQE (LON:IQE)
Not sure I agree with Graham's take on this. Just because IQE and the JV are related parties does not necessarily mean their respective accounting treatments should be mirror images of each other. The facts for each entity have to be considered separately.
From IQE's perspective, I'm not sure how the 'sale' of IP can be treated as a gain on disposal of its assets: presumably IQE continues to benefit from the IP despite the 'sale' to the JV. It is not like selling a car where you no longer have the rights and benefits of ownership after you've sold it.
If that is right, IQE could sell the same IP multiple times to different entities and if they were to account for each such transaction as a disposal of intangible assets, theoretically they could end up with negative intangible IP assets which makes no sense, particularly if they continue to enjoy the benefits of the IP themselves.
So in my mind it is correct for IQE to have accounted for the transaction as a licensing sale, particularly if there are no further ongoing obligations to the JV in relation to the transaction.
From the JV's perspective, if they were to mirror IQE's accounting treatment, they would be writing off the cost of the purchase in full against their income statement in the year of purchase. However they will be benefiting from the IP over a number of years, so the accounting principle of matching costs to their related benefit suggests that the cost should be charged to the income statement over a number of years. By capitalising the purchase as an intangible asset in their books and amortising the cost over time, that is precisely what the JV has done.
So whilst it might seem odd for the two entities to have taken a different accounting approach to the same transaction, and while that certainly provides fodder for those who want to build a picture of aggressive accounting, I think there is a reasonable argument to be made that the approach taken by IQE and the JV is not just technically correct, but is also consistent with a 'substance over form' approach.
Completely agree with this. By focusing on the JVs, the bears are spectacularly missing the point.
From IQE's perspective, I'm not sure how the 'sale' of IP can be treated as a gain on disposal of its assets: presumably IQE continues to benefit from the IP despite the 'sale' to the JV. It is not like selling a car where you no longer have the rights and benefits of ownership after you've sold it.
If that is right, IQE could sell the same IP multiple times to different entities and if they were to account for each such transaction as a disposal of intangible assets, theoretically they could end up with negative intangible IP assets which makes no sense, particularly if they continue to enjoy the benefits of the IP themselves.
This is correct, bestace. You just need to replace the words "sell" or "sale" with "license". This is what ARM do all the time but I don't know how their customers do or should account for the license fees paid.
All the best, Si
Graham,
IQE recognised the payments from CSC as revenue. However, if these are purchases of IP, as described in CSC's reports, then IQE should have recognised the payments as representing a gain on sale of intangible assets, rather than as ordinary revenue. So IQE's revenues and gross margin would be overstated.
Actually, this looks OK to me if this is purely an IP licensing transaction. I haven't got time to look back at the IQE reports etc. but I think you need to understand how semiconductor IP licensing works - something I very much doubt MW bothered to consider!
With IP you only buy a license giving the right to use the IP, you are not "buying" the IP! The IP, and all rights to it, resides with the licensor (IQE) and the licensee (CSC) pays an up-front NRE license fee in return for the right to make products utilising the IP. As such, there is absolutely no need for IQE to account for a gain on sale of intangible assets, because no "sale" has actually taken place.
All the best, Si
Thanks for that useful point simoan (IQE (LON:IQE) licensing) - it clairfies my thoughts on that one.
So to paraphrase :
CSC "bought" (leased?) the right to use IQE's IP for seven years. - So from their perspective it is absolutely reasonable to spread this cost over the 7 years.
The argument that it is a disposal and should not have gone through the P&L would not therefore stand up on two accounts
1. It's effectively a "lease" not a disposal.
2. It's not a disposal, because (I presume) IQE also retain the right to use the IP - ie they still possess the "asset".
I suppose there is however still the question of whether IQE should have spread the revenue and profit over the 7 years. I presume that would only be applicable though if CSC had the right to hand back the deal and be refunded for the unused time period - I presume that is not the case.
It might however be fair to say that IQE could have excluded this licensing revenue and profit (or at least the upfront element) from their adjusted numbers, but aside from that I cannot see an issue and certainly nothing that would have any relevance to the forecast numbers.
I suppose there is however still the question of whether IQE should have spread the revenue and profit over the 7 years. I presume that would only be applicable though if CSC had the right to hand back the deal and be refunded for the unused time period - I presume that is not the case.
Why should they do this? It is genuinely a one-time payment and so there's no need for them to recognise the revenue outside the financial year in which the payment was received. The more I look at the MW report, the more crap it looks. They have completely overlooked a number of factors and clearly don't understand IP licensing. That's a major balls up IMHO. The report has little credibility IMO and I'm considering taking the long side of this battle before they can cover.
All the best, Si
Re IQE (LON:IQE) - "They have completely overlooked a number of factors and clearly don't understand IP licensing." possibly more accurate to have said "they have chosen to completely overlook". These are very astute investors and I'm sure they understand perfectly well the difference between "sale" and "lease".
They are not really interested in presenting a balanced view, they want the share price to go down so they only present a case for it doing so.
re: IQE (LON:IQE)
Hi Si, what you say may be true, however, MW prints an excerpt from CSC's 2016 annual report (p. 6 of MW paper) which states that CSC "purchased £20 million of intellectual property from the IQE plc Group". I don't see any reference to a license being purchased.
If it really is a multi-year license, then it is more reasonable but we also need to bear in mind that IQE recognises revenue from a "customer" in year 1, for a sale which can't be repeated for another seven years.
Hi Graham,
Hi Si, what you say may be true, however, MW prints an excerpt from CSC's 2016 annual report (p. 6 of MW paper) which states that CSC "purchased £20 million of intellectual property from the IQE plc Group". I don't see any reference to a license being purchased.
I've now had time to look at the IQE and CSC accounts for 2016. The transaction described in "Related Party Transactions" of the CSC accounts is definitely not a license. You and MW are correct that this is a sale of IP by IQE to CSC. The word "purchased" is used, and besides, the amount is way higher than you'd expect for a license fee (IQE's total license fee revenue in 2016 was approx. £7m). It is all quite murky and the RPT section is worth reading if you're an IQE (LON:IQE) holder. The CSC accounts are here:
https://s3-eu-west-1.amazonaws...
However, it was reading the IQE 2016 annual report that has put me off even a short term long position. The director remuneration alone is a bit rich and the whole thing reads more like a sales brochure. Last post from me on IQE (LON:IQE) !
Thanks for your most excellent contributions.
All the best, Si
IQE (LON:IQE)
Nice summary Graham! Kind of hits the nail on the head and echoes my own views. Personally I am more bullish on the future photonics market but that arguement is rather more worthwhile to have than some of the breathless nonsense ive seen in recent days. Anyway well done on a piece of good analysis.
Cheers David!
Too many schoolteacher types on this thread today scolding some naughty children. Happy weekend everyone!
Morph Graham & Paul's faces together so that it looks really weird
I wonder if the SCVR should be renamed to recognise the contributions Graham N makes. Include his photo too on the main banner?
Re IQE (LON:IQE) i have no position.
I have read both reports and, as a qualified Chartered Accountant, I would have to say that I am always turned off by aggressive accounting in a company. IQE (LON:IQE) may well not be a Globo but I wonder if it may be a £UTW? The accounting policies adopted do seem intended to flatter the results and, to that extent, raise some serious questions about the integrity of management.
Having doubts about your accounting policies won't deter all instis but will deter many. And many PIs. Looking down the list of insti holders throws up some of the ones that reassure (e.g. Miton) but other reliables like BlackRock and Old Mutual are notable by their absence. And even Gervaise Williams gets it wrong sometimes.
The tone of the reports stops a long way short of calling this an outright fraud. But 'egregious manipulator' is quite a damaging epithet. I think it very likely that the eventual outcome here will be some form of re-statement of the accounts and consequent lowering of forecasts. The auditors at Utilitywise (LON:UTW) were incredibly slow to remedy the aggressive accounting there that many familiar with the business had been pointing out for years.
How many other companies that have been accused of accounting irregularities by Muddy Waters have gone on to overcome the accusations and prove them wrong? The fact that Mr Block appears to be thriving (Muddy Waters up 20% in 2016) and that his potential losses are theoretically unlimited suggests that he is on to something. After all, there are plenty of other more obvious slam-dunk frauds out there. Of course, he will get it wrong just as (so far) Mr Ackman has. But as Paul and Graham constantly say, why invest in companies with red flags when there are so many others out there that don't have the same risk? Or something along those lines
Thanks mammyoko. In amongst the torrents of hot air surrounding this share, yours is the most concise and reasoned argument against investing (gambling) on IQE (LON:IQE) that I've heard so far.
Looking down the list of insti holders throws up some of the ones that reassure (e.g. Miton) but other reliables like BlackRock and Old Mutual are notable by their absence. And even Gervaise Williams gets it wrong sometimes.
I asked Gervaise about his holding in Quindell at Mello 2014 & issues with poorer quality NOMADS. His answer was along the lines of having a very simplistic process to assessing companies: top line growth, good margins, strong balance sheet and good value.
So while he has an eye for good companies, given the number of companies he holds I doubt he does forensic accounting analysis on each one. With great diversification he can ride out the impact of companies that turn out to be frauds, fads or failures.
The takeaway for me is that we should never follow even great investors into a stock or take their holding as a sign that a company is above board. Their strategy, diversification, risk tolerance, research level, etc. will all vary from yours. And at the end of the day they make the same mistakes we all do. It really does pay to always do your own research.
Sorry to bang on about the macro situation but some people may find it useful. The question for all UK small-cap holders is when (or whether) they should buy the dip.
I think this will fall further - by another 10% in the US in the first instance and probably quite quickly. Then we are into bear market territory. The instis aren't loading up at this level. Record weekly equity fund outflows of $32.9bn last week according to Citi. Interest rates are going up, possibly more and more quickly than was anticipated. The market is nowhere near representing value here.
I expect further movements similar to yesterday. Some early strength perhaps today but then a further 500 points down. Either today or early next week.
My advice to those holding cash: be patient until it's clearer whether this is a correction or a crash. Very little to make the market go up from here now that sentiment has changed.
My advice to those holding cash: be patient until it's clearer whether this is a correction or a crash. Very little to make the market go up from here now that sentiment has changed.
We really shouldn't be giving out advice here. Everyone should make their own decisions based on their own personal circumstances. What makes you think you can predict the future? I could quote some Buffett or Munger but you've heard it before. Buy good companies when they are on offer and hold them through this wobble. Look at the update from Victrex (LON:VCT) today - out in the real world everything is going well.
All the best, Si
You are absolutely right of course. Embarrassed to have used the word 'advice'. So many apologies to all for that.
I haven't the faintest clue, any more than anyone else, about where the markets will go. Except that they will go up and down but not necessarily in that order!
I am just presenting a view based on the information that I have. None of which is any more sophisticated (or less) than that available to anyone else.
I think we all contribute to this board so that we can listen to other people's point of view. By listening to the contrary view we get information that challenges or supports our own views.
Whatever we think about where the price of a UK small cap should be, it will be heavily influenced by the trend in the market. As we've seen over the last two years, the price of all UK small caps go up when the market is trending upwards and sentiment is positive and will do the reverse when the market is trending downwards,
My view is that the market appears to be trending downwards because of economic fundamentals that could have serious and long-lasting consequences for the value of all UK small caps, regardless of quality. Multiples blew out in the last two years and, I think will now contract. I am keen to hear other people's challenges to this view though.
Mammyoko, Was it Rockerfeller who was asked on his death bed what had been the secret of his success? The old man beckoned the questioner to him and whispered "buy low and sell high". I think there is very much a need for a discussion on the current market gyrations and the underlying economics. Please don't apologise.
Si, I'm certain that we are all in the business of predicting the future. Predicting the past just isn't profitable!
Si, I'm certain that we are all in the business of predicting the future. Predicting the past just isn't profitable!
Yes, not much point in predicting the past, I grant you. If you want to predict the future I would tear up all your investment books, I mean, who needs to listen to Buffet & Munger, Terry Smith, David Dreman etc. They are yesterday's men. And in the name of equality, this is your girl!
https://www.amazon.co.uk/Books...
All the best, Si
Hi,
Really interested why you think instis (presume you mean institutions) aren’t ‘loading up at this level’. It’s simply impossible to tell what they are doing at any given time. Most will be mandate driven. Remember, there is a significant difference between an institutional and retail mandate. I think it’s worth considering, at times like this, marginal players ie hedge funds can have a disproportionate effect on moves and we have no clue what they are doing until well after the fact. The weekly equity fund outflows you cite need to be contextualised to the inflows in previous weeks/months. Simply put, citing anything like this is extremely presumptuous & should not be used as a basis for forming a view.
Regards
Tracsis (LON:TRCS).
They have released further details about transaction costs for their recent acquisitions. Bit of a hurt note to the last sentence of the relase, inasmuch as they didn't feel they had to reveal this much about the transactions due to AIM rules, because of size. But then again the deferred elements are potentially large, subject to performance, so I think this release is a wise move.
1. An initial cash payment of 1.75m;
2. The issue of 28,571 Ordinary Shares in Tracsis at a total value of 0.15m;
3. An additional cash payment in respect of net current assets (yet to be calculated) of up to 0.25m; and
4. Contingent deferred cash consideration of up to 4.7m, payable annually based on the significant growth in performance of the acquisitions over a three year period.
As at 30 September 2017, the gross assets subject to the transaction were 0.4m.
Tracsis confirms the ordinary shares in relation to the vendor equity consideration have been issued at 525.0p, the closing price as at 31 January 2018.
Tracsis would like to make it clear that the size of the transaction falls significantly below all of the disclosure thresholds for corporate transactions under AIM Rule 12.
My quick view in the absence of time to write a more detailed response: it's a better attempt than Shadowfall's report, but still falls a long way short of proving its thesis (IMHO).
I have no interest in IQE (LON:IQE) but took time to read the Muddy Waters report yesterday. It just struck me that they were trying too hard once they started looking at profiles on LinkedIn. If I was a holder and believed the long term story for the technology, I'd see it as a great buying opportunity.
All the best, Si
Read it too, pacey and breathless in tone to boot. 50 shades of shadows. It reminded me of the accounting equivalent of The Picture of Dorian Gray : poor old CSC being the rather battered and worn effigy in the relationship. That said, there appear to be anomalies in the treatments of the same transactions by both parties
Interested in Paul's view as I know he gets a bit rabid on the creative treatment of intangibles and capitalising of IP : this should be right up his strasa
Phil Oakley has been tweeting about the disconnect between reported EPS and FCF in IQE (LON:IQE) accounts, raising an eyebrow but no forensics.
Between shadow plays and muddy waters, IQE (LON:IQE) is a bit lacking in transparency for me atm: filed under too difficult with a watching brief. It's beginning to look a bit £BLNX like
Read it too, pacey and breathless in tone to boot. 50 shades of shadows. It reminded me of the accounting equivalent of The Picture of Dorian Gray : poor old CSC being the rather battered and worn effigy in the relationship. That said, there appear to be anomalies in the treatments of the same transactions by both parties
Yes, it's not all sweetness and light and there are some questions to be answered. I believe MW were correct to question the value of the IP being transferred and this is what would worry me the most. Putting a real book value on Intellectual Property is virtually impossible, so I would have a question mark about that. I have seen companies spend years developing complex semiconductor IP and then in a fire sale it is sold off for buttons. I could mention a few transactions I know of but don't want to bore anyone.
However, the LinkedIn stuff really discredits and calls into question the basis of the whole report. If there's any credibility in the dissection of the accounting, then it is shot to pieces by the silly hunt for the smoking gun on LinkedIn. In terms of personnel working for more than one organisation in a JV, if there was anything wrong with this half the start ups and University spin-outs in Cambridge would never exist. It just shows a complete lack of understanding of a research based JV between a Uni and industry.
All the best, Si
Hi guys, Paul is planning to do Creightons (LON:CRL).
Morning Graham,
I'd be keen for you to pick over the Creightons (LON:CRL) profit warning issued into the open market yesterday afternoon. I have posted my personal thoughts here: https://www.stockopedia.com/content/creightons-profit-warning-312928/?comment=8#8
Thanks,
IG
Slow day here so I thought I'd share an interesting article about excessive director remuneration at Character (LON:CCT) Conviviality (LON:CVR) and Walker Greenbank (LON:WGB) juxtaposed with Quartix Holdings (LON:QTX) , who's directors interests are more aligned with shareholders.
https://www.investorschampion.com/channel/blog/scandalous-pay-on-aim-needs-to-stop-these-companies-are-getting-away-with-d
cheers
Francis
Thoughts on Trinity Mirror (LON:TNI) please. It looked like a company that was clawing its way back onto a sound financial footing, then they go and double down on newspapers.
re: Trinity Mirror (LON:TNI)
Hi tabhair, it perplexes me, but I've had a look at it. Feel free to share you thoughts and have a good weekend. G
I appreciate the response, Graham.
Unfortunately I have come to the same conclusion as you. Namely, that the uncertainty of the proposed acquisition throws too much uncertainty into the air for me to make this worthy of investment. Like its counterpart in Ireland Independent News & Media (LON:INM), clearly there is a business here that could be stage managed into maintaining a decent stream of cash flow for shareholders. Unfortunately, in both cases management have deemed it to be that they should embark on acquisitions in their related sectors.
Hi Graham - re. IQE (LON:IQE) If you have any further thoughts following yesterday's Muddy Waters report, would be keen to hear your views.
Oh dear, I can feel another essay coming on...
My quick view in the absence of time to write a more detailed response: it's a better attempt than Shadowfall's report, but still falls a long way short of proving its thesis (IMHO).
As before, the thing I am wary of with IQE (LON:IQE) is they keep on trying to reassure the market with positive statements about revenue growth... but there is no mention at all of profit growth
ref IQE
andrea34I
"As before, the thing I am wary of with IQE (LON:IQE) is they keep on trying to reassure the market with positive statements about revenue growth... but there is no mention at all of profit growth"
Huh - did they not say the following on 20th December ? - i have copied and pasted this sentence direct from the announcement that day!
As a result, profit before tax for the Group is expected to
be ahead of current market expectations.
Does anyone have any views on 8p stock 'virtual tumour' biosimulation company Physiomics Physiomics (LON:PYC) - has just got a third major pharma contract worth 70k a year, price spiked then reduced - still needs a few more of those to hit breakeven however I think and has been a p&d favourite in the past. Doing research on it now.
Is it not a reasonable suggestion to suggest those asking for views on AIM listed loss making Bio's start a new thread of their own?
In this case for example, once you've done your research, it's then perhaps even more worthwhile (starting a new thread). It means that if you ever want to see your notes and views from others in relation to that AIM listed loss making Bio you'll be able to easily find them in the future as they'll be linked to the stock under the discussion tab.
Just a suggestion like!
Re Physiomics (LON:PYC) I thought I would see if there's any interest before doing that Matylda! I know Graham & Paul don't cover pharma or microstocks themselves but it was an RNS on a slow news day.
I too would like to see if Graham has more to say about IQE (LON:IQE) though I doubt there's much more to be said given Muddy Waters didn't seem to say much more itself and I think it must be at the bottom now - if the general market correction is too.
Good morning Graham
Your views on the trading update from Creightons Creightons (LON:CRL) released just after 4pm yesterday would be appreciated. I have already given my thoughts in an earlier post, however as I don't have yours or Paul's skills when it comes to interpreting company finances your more forensics approach would be welcome.
PS I thought I had posted this request earlier but it doesn't seem to have been uploaded so apologies if it suddenly appears twice.
I realise £7DIG is micro cap but just in case there is little company news and you feel inclined .... Hogg Robinson (LON:HRG) seems to have had an interesting development. Thanks
re: 7DIG
Hi, I've added it to the report, cheers. G
Hi Graham - Re Trinity Mirror (LON:TNI) or in fact N&S - which N&S company did you pull the figures for (there are so many to choose from!!)?
I thought that it was Northern and Shell Media Group Limited (04086466) - but the numbers appear a little different from those you quote.
Hi Gromley
re: Trinity Mirror (LON:TNI)
Yes, 04086466. I've used some rounding.
Best,
Graham
Trinity Mirror (LON:TNI)
Thanks Graham - actually it wasn't rounding - you cite the N&S pension deficit at £64m, which actually would seem plausible give that TNI commit to pay in £70m by 2027, but the N&S accounts only seem to show £23m (£19m net of tax).
Was there something else you had taken into account?
On a more general note, as a general principle I agree with your caution as to whether EBITDA get converts into net earnings, however, whilst I haven't gone through the N&S numbers in vast detail I notice it shares so similarity with TNI. In 2016 N&S accounted depreciation of £7.5m but capex of only £1.8m (in the prior year depreciation + impairment was £15.8m vs £5.4m capex).
Trinity Mirror (LON:TNI) has been a massive cash cow (beyond it's reported profits) - using that cash recently to fund (i) Debt reduction, (ii) Pension Deficit reduction, (iii) Dividends , (iv) sharebuybacks, (v) phone hacking damages. (The latter is hopefully winding down)
It looks to me as though the N&S deal should strengthen this profile.
Morning Gromley,
re: Trinity Mirror (LON:TNI) and N&S
£23m is the accounting pension deficit in 2016, while £64m is the actuarial pension deficit in 2015 (see the RNS for the proposed acquisition). The next actuarial valuation of the deficit is due this year.
Cheers,
Graham
My morning smallcap tweet:
Trinity Mirror (LON:TNI), £7DIG, Hogg Robinson (LON:HRG), SCISYS (LON:SSY), Kennedy Ventures (LON:KENV)
Trinity Mirror (TNI) FY trading. Guides adj results marginally ahead of mkt exp., quotes consensus EPS 34.6p. Net debt now £10m. IAS 19 pension deficit expected to be £378m down £88m. But then blows up debt and pens deficit by buying Northern & Shell's publishing assets (ie Dirty Desmond's totally crap Daily Express and Daily Star) for £127m: £47.7m cash, deferred cash £59.0m payable over 2020 - 2023 and the balance of £20.0m in shares. Worse, there's a one-off £41.2m to the Northern & Shell Pension Schemes and a recovery plan through to 2027 totalling £29.2m. The acquisition will be materially earnings enhancing in the first full year of ownership. Losts of synergy and cost cuts. The Express and Star already run on half a chewed shoestring.
7Digital Group (7DIG) guides adj EBITDA loss significantly down and be better than market expectations.
Hogg Robinson Group (HRG) recommended offer 120p from Amex and also agrees sale of Fraedom to Visa for £142m. If Fraedom sale falls though the Amex offer reduces to 110p.
Scisys (SSY) renews BBC contract for 10 years.
Kennedy Ventures (KENV) will be unsupended as it produces delayed FY results to end June. Loss £1.1m.
SCISYS (LON:SSY), the supplier of bespoke software systems, IT-based solutions, web and mobile application development and support services to the Media & Broadcast, Space, Government, Defence and Commercial sectors, is pleased to announce the renewal of its service contract to supply support and maintenance services for the BBC's enterprise audio broadcast technology.
SCISYS' Media & Broadcast division, which supplies the dira! Media Asset Management platform, a bespoke version of dira! used by the BBC to deliver its radio news and entertainment, has signed an enhanced service contract to continue supporting the BBC for a term of up to 10 years.
No numbers on that but Paul is positive on this stock and think it's due a re-rate after Brexit fears. Would be interested to hear your view as a cautious investor, ta. I hold a smidgy-widgeon.
Quick read on overnight market temperature via the futures/IG. As of 6.50, FTSE 100 down 40pts at about 7120, a fall of 0.6% since London close. Had touched down to 7093 at one point. DOW is back up about 225pts (0.95%) on NY close (down about 1,030 on Thursday) at about 24075. Some big falls overnight in Asia - notably China 300 currently down 5.5%. Don’t those algorithms ever get tired?
Gus.