Small Cap Value Report (Fri 9 Oct 2020) - SGC, TET, GFIN, MARS

Good morning,
It's Jack here with Friday's SCVR. Any suggestions or talking points just drop by with a comment while we wait for the RNS statements to come through.
Some interesting tidbits from either end of the Quality spectrum this morning: on the one hand, renowned quality investor Lindsell Train has opened a position in Experian, the world’s largest credit data company.
With a forecast PE ratio of 35.8x and a forecast PEG of 3.1x, it’s one I’ve consistently pushed to the back of the research pile for being ‘too expensive’. But in the long term, quality shines through so perhaps I’ve been too dismissive of this valuation in the past.
It’s the third new position at Lindsell Train this year following FeverTree (edit: and PZ Cussons - thanks iwright7!).
And then, further down the scale, we have news that shareholders are revolting over Restaurant Group’s CEO pay plans. After years of underperformance as a result of price gouging and tired brands, this group actually emerged with some credit following its clear-eyed appraisals of lockdown and some useful models of the potential impact.
It has also used this period to fit a couple of years’ worth of turnaround into a couple of months - but it’s obviously not out of the woods yet. It’s a much riskier bet with a potentially higher payoff than either of Lindsell Train’s picks. A totally different and much riskier proposition.
If society normalises on a 1-2 year view then RTN might be left to pick up the pieces after a ‘grand reset’ in the Leisure sector. But the downside risks are much greater too.
It could be a bumpy ride over the next few months with a few big variables: not just the scale of any increase in COVID cases, but the government and economic reaction to those rises, as well as potential news flow around Brexit developments.
I do note that Bank of England governor Andrew Bailey said last week that risks to the UK economic outlook remain ‘very much to the downside’. Meanwhile in the stock market volatility clusters - what happened in March can happen again - so we’d do well to keep our wits about us when making investments in this environment. But as Dale Winton would say, 'you have to be in it to win it'.
With the weather cooling and the days growing slightly darker, it would be great to hear how others are positioning themselves for the winter ahead - even if your strategy continues to be ‘make no changes at all’.
Stagecoach (LON:SGC)
Share price: 41.94p (pre-market open)
Shares in issue: 550,778,551
Market cap: £231m
Stagecoach (LON:SGC) is not normally a small cap, but these are not normal times. Back in the beginning of 2020 this was nearly a £1bn company (£900m) with annual revenue approaching £2bn. But when was the last time you voluntarily hopped on the bus?
It shouldn’t come as a surprise that transport stocks are still reeling:

If you take the FY20 figures, SGC trades at:
- 0.16x sales
- 3.6x free cash flow
- 6.6x earnings
That’s a big leap in the current environment though. These are not companies I want to go near owing to low operating margins and capital intensiveness (having to spend a lot of cash on maintenance of its transport assets).
That said, with such a steep drop in share prices there could always be contrarian value on offer.
SGC continues to withhold FY21 guidance.
It reports a ‘substantial fall’ in regional bus demand for public transport in the wake of the pandemic, although demand has been ‘steadily recovering’ since April with commercial revenues returning to around 50-60% of prior year levels.
SGC will continue to receive COVID-19 Bus Services Support Grant Restart payments with an eight week notice period. This, it says, will be enough to remain EBITDA positive and avoid significant operating losses.
London bus demand has been much more robust and the group continues to unwind its former train operating companies.
Conclusion
SGC says it has adjusted liquidity of £605.6m. For as long as government support continues then it should be ok. But is that much of an investment case?
The group also mentions its pension deficit and an upcoming triennial valuation for the main fund. It expects the deficit valuation to reduce from its current £404.1m to somewhere between £150m-£200m.
That’s all well and good but in this market I’m not looking at transport companies with net debt, pension deficits, and poor share price momentum.
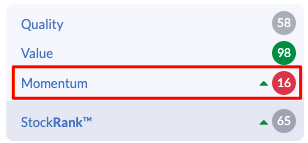
There really might be some contrarian value here but, with no real edge into this sector or company, I’ll gladly sacrifice a bit of the upside for more certain signs of a sustainable recovery in public transport. I do think some of these stocks will come good, but picking the winners will seem much easier in a couple of years with the benefit of hindsight!
Treatt (LON:TET)
Share price: 592p (+0.34%)
Shares in issue: 59,608,089
Market cap: £352.9m
Speaking of high quality, superficially expensive stocks, here’s one mid cap the Lindsell Train bunch would presumably be all over.
Treatt (LON:TET) is a global independent ingredients manufacturer and supplier to the flavour, fragrance and consumer goods industries. It’s got a diverse and internationally-recognised product portfolio ranging from natural ingredients to synthetics and ‘impactful aroma chemicals’ - so it makes things smell good.
This seems to be a useful niche facing some big, global markets and, sure enough, TET has managed to consistently grow revenue over the past five years or so.

At the same time, operating margins have held steady at a useful 11% with returns on capital ranging between 12-20%.
You also can’t fault the group’s Financial Health scores or liquidity metrics, so it looks like a Quality Rank of 85 is well deserved.

The only issue is around valuation, with a trailing twelve month PE ratio of 35x and a PEG of more than 4x.
Trading Statement for the year ended 30 September
It looks like a resilient FY20 performance for TET, with profit before tax in line with pre-COVID expectations (c£14m) - that’s probably what you’d hope for given the premium relative valuation. That would put the company at about 14x PBT.
Revenue for the full year is expected to be down 3% due to a substantial reduction in orange oil raw material input costs. Excluding this, revenue would have increased by 4%.
The citrus category (which makes up 50% of group revenue) was down 10% but gross profit was up ‘as the business continues to transition away from traded and minimally processed products to more added-value customer solutions’. That could be a useful way to enhance margins in future.
Non-citrus revenue was up in a number of categories, with underlying growth in Tea looking particularly strong, up 47% in H1 before on-trade site closures brought it back down in H2.
In other news, new product launches have been reduced due to COVID-19 although the group is making inroads into the alcoholic seltzer market and its ongoing work into natural coffee extracts ‘represents a significant growth opportunity for the business’.
TET is also now three-quarters of the way through a substantial capital investment programme in the UK and US, with a new UK facility to come online in Spring 2021 and its expanded US facility fully operational.
Conclusion
These are the type of results you might expect from a high quality operator that has consistently impressed the market. TET has finished the year with net cash of £1m despite ongoing capital investment for future growth, which is testament to its resilience.
It looks expensive across relative valuation measures, but the best companies often do - and then they just keep growing.
TET is using its expertise and product knowledge to diversity its revenues and find big new markets. That’s an encouraging sign heading into FY21.
The group gives useful contextual information in its update too - the alcoholic seltzer market was valued at $4.4bn in 2019 and is expected to grow at a compound annual growth rate (CAGR) of 16.2% from 2020 to 2027. That’s just one of the markets TET can supply its products to. The group also has its sights set on the cold brew coffee market, for example.
Meanwhile TET’s core business continues to be in demand with growth tailwinds and strong margins. Recent capital investment in the UK and US should also increase production capacity. It has proven its ability to generate strong margins and returns on that capital.

This looks like a great company with promising long term growth potential.
My question is whether the valuation prices this in but then we’re back to the ‘Lindsell Train buys Experian’ point above. You usually have to pay up for quality and long term growth.
Needless to say on a c15-year view TET has trounced the market.

And given the size of the markets TET is targeting, I don’t see why this can’t continue to grow into a bigger company on a ten year view.
Gfinity (LON:GFIN)
Share price: 4.1p (+22.6%)
Shares in issue: 763,795,860
Market cap: £31m
Gfinity (LON:GFIN) is an interesting company. It’s always talked a good game about exposure to the massive, growing eSports market - but the fact of the matter is it has consistently lost cash and diluted shareholders over the past few years.


Management and business models have both changed in that time. Meanwhile, the share price has tanked.

I’m wary of this stock given the track record of losses and shareholder dilution. Stockopedia classifies it as a Highly Speculative Micro Cap Momentum Trap (!) so there’s a warning for you.
That said, it’s up 23% today on the announcement of a strategic review. I remain open to the idea that GFIN can prove itself as a viable high-growth business, so let’s take a look at what’s changed.
The group says that considerable corporate and strategic development post-COVID has left it ‘exceptionally well positioned’. It is now focused on three key areas:
- JV's and partnerships with an initial focus on virtual motorsports;
- Expanding the Company's own community franchise; and
- Using its tech platforms and production know-how to build communities for others.
It’s a move away from delivery of physical eSports events. I did actually visit one of these events a few years ago and it was fun, but not really at the level of the huge arena-style events you might imagine. It also seemed like a potentially cash-hungry endeavour.
So a move away from single-handedly developing that business and re-focusing on other avenues could be a step in the right direction.
GFIN is now targeting profitability by the end of Q1 2021 calendar year.
There’s a frenzy of activity in the update but precious little in terms of trading figures.
Digital media
- Launched Gfinity Digital Media in July 2020 which generated over £130,000 of revenues in September 2020;
- New sites launched;
- Partnered with YaLLa Esports to expand its RealGaming101 offering into the Middle East-North Africa (MENA);
- Gfinity Plus, the ‘reward-based product’ driving increased engagement across the sites; and
- On track to deliver target revenues from digital media for this financial year of approximately £2m.
Joint Ventures and Partnerships
- Partnered with BT Sport to deliver a series of celebrity led gaming entertainment shows;
- Partnered with ViacomCBS to deliver Street Fighter experiential event at Vidcon London 2020; and
- Entered into a five-year agreement with Abu Dhabi Motorsport Management to design, develop and deliver a esports racing championship (ERC), to be jointly owned by Gfinity and ADMM.
Building communities for others
- Continued partnerships with brands including: F1 Esports Series; EA Sports; ePremier League; Activision Blizzard and the Forza Racing Championship;
- Chosen to deliver the new F1 Esports Virtual Grand Prix series extended into 2020 and 2021, and the 2022 qualifying events;
- Selected by premier cricket broadcaster Willow TV (owned by the Times Group) to design and deliver "The eCricket Challenge", in partnership with Betway;
- Appointed to operate the inaugural and follow on ePremier League ("ePL") Invitational tournaments; and
- Partnered with BT Sport to co-produce a new entertainment based competitive gaming series, "The BT Sport FIFA Challenge".
Given the track record I’m waiting for more concrete signs that these developments can translate into shareholder profits, or at least materially reduced losses.
What’s probably grabbed people’s attention is the following extract:
The Board believes that the Company can continue on its current pathway towards profitability it believes, at this point in time, that it is important to all its stakeholders to ensure that it has explored all strategic options to capitalise on the potential market opportunity and to deliver shareholder value, including options for making acquisitions, forming partnerships, separating the activities of the Group or a potential sale of the Company.
As of yet, no interested parties have come forward but it’s early days.
Conclusion
A lot has changed at GFIN since I followed it in any detail so I don’t want to attribute previous false dawns to the current management team.
That said, this is a strong price reaction to a company effectively hanging up a ‘For Sale’ sign.
GFIN has a lot going on and eSports is a great space to be in for some operators. Others will pour their heart into building the infrastructure only to see their timing is wrong, they run out of cash, and other players swoop in to reap the profits.
There is value in this market, but where does that value ultimately accrue? I would suggest that it goes to the owners of intellectual property - the games makers - but perhaps others disagree.
I certainly don’t know for sure but I’m still not tempted here. There are plenty of signs suggesting it might be better to wait for more tangible signs of profitability and cash generation. On that note GFIN is targeting profitability by the end of Q1 2021, so let’s see if it can make that happen.
Marston’s (LON:MARS)
Share price: 49.5p (+19.2%)
Shares in issue: 634,100,000
Market cap: £314m
The CMA has cleared the proposed joint venture between brewing companies Carlsberg and Marston's (LON:MARS) .
This was originally announced back in May and led to a sharp rerating as Marston’s showed it has more than just a pub estate with some debt attached.

It also has a pretty useful brewing and distribution business. Marston's is merging its operations here with Carlsberg's to create an enlarged distribution business. The pub operator will keep a 40% stake and equity upside, as well as receiving £239m in cash.
There should be some material and straightforward synergies resulting from the combined scale of the enlarged distribution business.
Here’s the presentation pack from back in May if you’d like a refresher. It’s a good operator but a lot of people worry about the debt, even backed as it is by freehold property.
The Competition and Markets Authority (CMA) has cleared the deal following its investigation, concluding that:
In relation to their role as brewers, the CMA found that Carlsberg and Marston’s have different areas of focus, meaning competition between the 2 businesses is generally limited at present, with Carlsberg largely focusing on the production of lager and Marston’s focusing on ale. They also face several competitors in all of the product categories where they are both active.
Conclusion
MARS shares have drifted back quite a lot since the original joint venture announcement. I didn’t consider the CMA a big threat to the deal so perhaps the fall was just on general anti-Leisure sentiment in the short term.
I’m also surprised the shares are up by quite so much today. This is good news, but also known news.
The deal will now complete at the end of the month at about £380m above book value and will result in MARS owning 40% of an enlarged distribution business as well as receiving a cash windfall of £239m - the majority of its market cap - resulting in a useful upgrade to net asset value per share (barring any drastic property write-downs).
Say what you want about the treacherous trading environment, but this at least looks like a canny bit of business.
Before COVID, management had just begun to acknowledge the perception that MARS had too much debt and was committed to debt reduction in the medium term.
It’s probably paid out too much in dividends in the past given the level of free cash flow generation:

It would do well to re-base the dividend in my view, so that it could re-direct cash into higher return activities. Perhaps this is that chance. Even just share buybacks could be better if its stock trades at a fraction of net asset value (once COVID is well and truly behind us of course).
A tightening of restrictions in the north is a concern, and also a reminder of just how changeable the situation is right now.
I wouldn’t get involved in this sector at all if you can’t handle short-term, news-based share price volatility. Shares fell gradually after the initial announcement back in May. It’s not hard to envisage something similar happening again.
But at some point there could also be a sharp rerating. In the longer term, I have one eye on MARS as a good pub operator, brewer, and distributor with a clear path to shareholder value via debt reduction should conditions show signs of normalising over the next year or so. Just my take - I don’t hold right now, so DYOR as always.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

98 comments
That is an excellent response Sam. I think many of us are guilty of misjudging our tone from time to time or even being overly acerbic (which your tremendously grown up response now makes me feel).
I think "Trollism" seems to have become more of "a thing" recently and I probably misconstrued where you were coming from. We are probably actually in fervent agreement that claims of genius based on single instances of past great calls are somewhat dubious.
If you are planning any workshops on how to do that - I might well sign up - it not always something I find easy!
I think in general, nerves seem a little frayed at the moment; and I apologise for contributing to that - hopefully normal levels of civility will be restore in the near future.
Marston's (LON:MARS)
Jack
I’m also surprised the shares are up by quite so much today. This is good news, but also known news.
To me the bounce today is semi logical albeit way more than i would have expected - the cash provided by the deal really has probably dug them out of a huge hole (alternative probably being raising of funds with very depressed shareprice combo). So on that basis until the deal is done and they have the cash in the bank anything could go wrong in which case shareprice could be any % lower - the closer they inch towards having this cash in the bank the better as its one less thing that could go wrong 2 hurdles to pas now rather than 3 kind of logic.
There is the big slilent elephant in the corner though as to how trading has been since the end of lockdown "1"- i am not aware that they have said anything at all about how they have done since July - we really could do with some idea of how close they are to breakeven etc or a clue about sales levels at least - perhaps they think this huge "pot o cash" means the basic funadmentals of the business don't matter at present - sigh.
Anyone know how general info on Stocko pages are updated? Just noticed ceo for Gfinity (LON:GFIN) is out of date & not current....
Old site:
https://help.stockopedia.com/t...
https://help.stockopedia.com/t...
New site:
https://app.stockopedia.com/le...
https://app.stockopedia.com/le...
I hold TET in my SIPP and see them as a quality company, providing stability and steady growth over the next 10 years. The fact that they have had such a solid year, despite the capital investment, and covid, and the fall of income from their previous main earner, citrus, is all evidence to me, that they are well placed to grow significantly over that ten year period. Others may well see it differently, but I am targeting £15 by 2030
Gfinity (LON:GFIN)
Thanks for covering this stock - now up 30%
Gfinity (LON:GFIN) - 764m shares issued? You do wonder how some companies are managed.
25% of a portfolio in one stock is probably too high a risk - unless the portfolio is a relatively small percentage of the investors overall assets.
It could also arise as result of an ESOP where it might be more acceptable.
I had to look that up (Employee Share Ownership Plan).
I would disagree that makes it more acceptable. 25% of your net worth and probably 100% of your income, would all by tied to the fortunes of a single company.
I know that people tend to think that they have the inside track on the company that they work for, especially if they are relatively senior. Whilst that is obviously true to some extent, it is definitely limited and does not protect you fully.
I used to work for a FTSE100 company which was hit heavily on two occasions by senior management fraud. The second occasion only came out after I left although it was ongoing whilst I was still there and in part of the organisation close to the one I had been working in.
Whilst, with hindsight, I could see the management culture that arguably contributed to the fraud (aggressively grow at all costs, failure is not acceptable) there was no way I could really have predicted it. Thankfully I had sold most of shareholding before this second issue came out.
"I would disagree that makes it more acceptable. 25% of your net worth and probably 100% of your income, would all by tied to the fortunes of a single company."
A single shareholding as a result of an ESOP does not necessarily equate to 25% of ones net worth. It depends on what other assets are held.
My point was that for someone with a large spread of diverse assets it might be acceptable to hold 25% in one share as part of share portfolio where the share portfolio might only be 20% of total assets.
Yes – it does help not to invest in a company which has fraudulent management.
I agree Gromley and can back it up with an anecdote.
I had a mate who did some IT consultancy at a bailed out bank. At said bank was an employee who every lunchtime spent an hour staring at his company shares from his bonuses and purchase plan, basically his dream of retiring and buying a house for cash - gone. Over 300k turned into less than 5k.
I'm sorry but anyone with 25% of their portfolio in a single stock simply does not understand risk. It really depends where you are in your investing life though - for someone in their 20's or 30's maybe it's fair enough as they have time in the market to recover any losses. As you get older, you increasingly don't have the time.
I reached financial independence two years ago and so no longer need to shoot the lights out. As such, no single share is more than 2% of my portfolio. But that's just me. The correct position for someone else depends entirely on their financial situation, but 25% seems nuts to me.
All the best, Si
The 25% relates to earlier posts and was given as an example "at one extreme". I agree, unacceptably risky for most people, although I also think (and there are statistical studies to back this up) that too diversified a portfolio inevitably leads to less good performance. I cannot remember the source, but I recall the results of one study which suggested 15 to 20 shares gave the optimum risk to reward ratio for a shares portfolio.
The 25% relates to earlier posts and was given as an example "at one extreme". I agree, unacceptably risky for most people, although I also think (and there are statistical studies to back this up) that too diversified a portfolio inevitably leads to less good performance. I cannot remember the source, but I recall the results of one study which suggested 15 to 20 shares gave the optimum risk to reward ratio for a shares portfolio.
I agree that 20 shares is probably about right to eliminate market risk, however you still have to be a pretty good stockpicker to actually beat the market. I always find it interesting that even the very best and highest conviction fund managers have more than 20 holdings, normally more like 30.
I hope I won't hurt anyone's feelings by saying that the vast majority of investors are not good stock pickers who will beat the market holding 20 shares. The question we should be asking ourselves (I ask myself all the time) is not what level of risk we want to take in our share portfolios but why bother investing yourself when you can let Terry Smith, Nick Train or Keith Ashworth-Lord do it for you while you get on with the rest of your life?
Well, my portfolio is up on Nick Train but not close to Terry Smith YTD. Very disappointing to be underwater even if I'm beating the FTSE All-Share by 17%. Tbh I'm not sure the All-Share is a worthwhile comparator these days.
All the best, Si
Hello Si
You have mentioned three fund managers (out of hundreds) with the benefit of hindsight. Fama and French would argue, how much of that performance is down to luck and how persistent will it be, going forward? If you had been making a similar post 5 years ago, it is very probable Neil Woodford would have been on your list. Worldwide low-cost tracker anyone?
Hello David,
I think the key point about Terry Smith, Nick Train and Keith Ashworth-Lord (the fund managers mentioned by Si) is that their philosophies are distinctive and fundamentally similar (though not identical) and if you believe in their clearly stated quality-based philosophies, it is actually quite possible to have selected them on this basis many years ago. I not only purchased sizeable (for me) holdings in the Fundsmith and Buffetology funds soon after they launched, I have been a Lindsell Train Trust fund investor since 2009. I copy many of the shareholdings selected by these managers for holding directly, as well as trying to use their philosophies for purchasing smaller companies (which they don't generally purchase). I also made multiple posts warning investors about Woodford as early as 2016 as biotech is my specialist area and it was apparent to anyone with expertise in this area that he did not understand what he was doing. You are absolutely right about the benefit of hindsight but for the fund managers you mention here, I would argue that it was possible to identify their qualities quite a long time ago. It is apparent from SCVR that investing approaches driven by news, events and share prices also work for many people, but I find that long term, quality driven approaches seem to suit my character.
I think the key point about Terry Smith, Nick Train and Keith Ashworth-Lord (the fund managers mentioned by Si) is that their philosophies are distinctive and fundamentally similar (though not identical) and if you believe in their clearly stated quality-based philosophies, it is actually quite possible to have selected them on this basis many years ago.
I completely agree. I wish I'd seen your post earlier as it would have saved me replying to David myself :) The performance is a result of their very focused quality-based investment approach. If you're going to hold a fund in place of your own portfolio that's ideally what you want. I have always been surprised that apart from maybe Unilever, Sage and Diageo there's very little overlap in their largest holdings, which suits me fine too.
All the best, Si
Hi David
This issue of are funds/trusts worth buying or are etfs etc better because very few fund managers out perform the index over a long period of time (and we can only know which with hindsight) comes up every so often.
The strange thing to me is that it should be raised on something like the SCVR. If someone is reading the SCVR then I would think that means that they think they can beat the index. So, if they believe they can, why believe that certain professionals cannot? It could be argued that the small private investor has certain advantages of nimbleness and an ability to hold very small cap stocks that the pros do not have but the pros have other advantages such as greater information or better access and more time as it’s their full time job.
My view is that all the tools have their place. Yes, I held Patient Capital for a while but sold early on when I realised he was making too many investments which were quite likely to only have a binary outcome (e.g. early stage biotech). And yes, I still hold Fundsmith, Lindsel Train and Scottish Mortgage. But I also use a tracker for the US and an ETF for gold.
Hello Si
You have mentioned three fund managers (out of hundreds) with the benefit of hindsight. Fama and French would argue, how much of that performance is down to luck and how persistent will it be, going forward? If you had been making a similar post 5 years ago, it is very probable Neil Woodford would have been on your list. Worldwide low-cost tracker anyone?
For the record, I selected those managers only because their investment approach is similar to my own. It had nothing to do with past performance. I suspect they will likely underperform for periods in the future, but then so probably would I. Meanwhile I can get on with enjoying life. Woodford never interested me in the slightest. I am not saying that from hindsight, I just always thought his investment approach was rubbish. Who on earth wants to hold equity income funds anyway?
Sorry I realise this is sounding very dull, but it seems to me that there are investors who don't understand when they've already won and need to stop playing. I've reached that point and Covid has made me seriously consider my position. We take so much for granted and there is more to life than investing.
All the best, Si
I agree with you when you say:
“The question we should be asking ourselves (I ask myself all the time) is not what level of risk we want to take in our share portfolios but why bother investing yourself when you can let Terry Smith, Nick Train or Keith Ashworth-Lord”
However is that not hindsight bias? Buffett has now underperformed the S&P for 10+ years but I don’t think many saw that coming 10 years ago.
I don’t thing any of these funds can demonstrate pre 2008 track record apart from Buffett.
Secondly I enjoy investing and the intellectual challenge that it brings (though the emotional side of things is still tough for me but I am beginning to master it). I don’t want to spend 20 hours on the golf course and I don’t have a garden. So in my head I discount my bench mark by an intellectual/enjoyment factor.
With regard to maximum size a 2% maximum implies 60 to 70 holdings assuming some are less than 2%. There is no way I could handle that number of investments and if I felt that I needed to manage risk this way then absolutely I would move my entire pf into funds and trackers.
Regards
Michael
However is that not hindsight bias? Buffett has now underperformed the S&P for 10+ years but I don’t think many saw that coming 10 years ago.
Shock horror: I have never been interested in investing with Buffett! He holds banks, did hold airlines etc. and all kinds of rubbish trading companies. It's a conglomerate with a large insurance company, not a fund. Please see my other post - this has nothing to do with hindsight, it's all about investment approach.
With regard to maximum size a 2% maximum implies 60 to 70 holdings assuming some are less than 2%. There is no way I could handle that number of investments and if I felt that I needed to manage risk this way then absolutely I would move my entire pf into funds and trackers.
As I inferred. That is what I am in the process of doing. Obviously, you're newer to share investing than me. I agree it's stimulating and exciting to start with and I will maintain a much smaller portfolio that I manage myself going forwards for a bit of fun and excitement.
All the best, Si
I know a number of investors who have 60 per cent of your portfolio in one stock; Novacyt Sa (LON:NCYT) It started as a balanced portfolio but when a stock goes up 140 times in a year ......? Very few bought at 6p but plenty did at 30 pence. So what do you do? If you continue to sell to rebalance you will never hit a really big winner. Sell half on a double is a fair strategy I think or you risk the possibility of ending up with plenty of big losers and few big winners.....because you sold those. This year is unique of course; there are large numbers of small cap stocks that have gone up ten or twenty times from the lows in March because of the extreme volatility we have seen.
If you bought Novacyt SA (LON:NCYT) at 30p it will be up 28x. If you are up 140 times then you have already bit a big winner unless you bought only a small amount and I would cream off some of the profits. Actually I do hold some and have just sold half at 847p, I can see this falling back soon, if it does I will probably top up. I maybe wrong but still have half my holding. It's about risk and probability for me.
Novacyt Sa (LON:NCYT) Up to 880p now herbie. I think taking a bit of profit is wise....I certainly have and am looking at £10 for the next place to sell a few more. One of the interesting points about this stock.....where are the institutions? The broker coverage? Nowhere to be seen. It is the small and often maligned PI's that have bought this stock. The pension funds and other funds....what are they buying? We know they sat on cash far too long after the March lows . So what exactly are the highly paid "professionals" buying? Oilers and banks?
Two and a half million shares being traded every day - out of 50 million. In 20 days the entire shareholder base would change. Of course that doesnt happen so you have to think the day traders are pushing the stock higher. I dont have it and never would - dont understand if the revenues are sustainable - so would be careful.
it’s an easy decision for me - bought at 550p when they announced their NHS contract. For me, the difficulties in the stock all are in the delivery - they have no track record on delivering the sort of scale they are currently on track for. So the market gets excited and starts pumping it up.
This is the sort of stock that stop losses were invented for - I don’t want to sell out because I have no idea how high it could climb. So I have a trailing stop loss 100p behind the price. Once it gets above 900p (my back of an envelope valuation), I’ll tighten that up a good bit. At some point, there will be a large correction - I’ll get stopped out and depending where it goes to, buy back in. This is not the type of stock where careful analysis and balance sheet calculation helps - its a runaway freight train, a total gamble, I love it (because I’m on the right side of it) - would hate it if I wasn’t
Hi Phuntt,
I bought Novacyt the same day last week as you - when it announced its NHS contract. I agree with you that the biggest risk of this stock is whether the company can deliver at such a high scale, and whether its management can cope with such a rapid growth of its business. If it doesn't deliver, I assume that would adversely affect its future profits. Like you, I'm enjoying the upward ride so far.
Hey PKA, yeah I have no idea if it’s the right strategy but I have no better idea of how to deal with what appears to be a straight vertical line. If I try to look forward, I can see so many things that could cause a collapse in the price. But I can also see them announcing tomorrow a new contract for as much if not more with another country.
For me anyway, this is impossible to predict (I’ve never owned a share before that hit my optimistic 1 year projection in a week) so just try to relax and enjoy the ride (and thank god every morning you got on the train but don’t be afraid to jump off and wish all the passengers well when they leave you behind at the station).
I know a number of investors who have 60 per cent of your portfolio in one stock; Novacyt Sa (LON:NCYT) It started as a balanced portfolio but when a stock goes up 140 times in a year ......? Very few bought at 6p but plenty did at 30 pence. So what do you do?
No idea, but it's not a problem i have by design. The chance of anything I hold going up so much that it is more than 4% of my portfolio is non-existent. I wouldn't be worried if something got to 4-5% though.
It's great to hear people are making serious money on stocks like Novacyt Sa (LON:NCYT) but as mentioned I don't need to get involved in highly speculative situations in industries I don't understand anymore. And best of all, I don't feel like I'm missing out.
All the best, Si
Gfinity (LON:GFIN)
Price moved on recommendation of Frontier Tech Investor
Treatt (LON:TET) is one of those real investing regrets. Why oh why did I sell this stock in my March meltdown at 322p. If I still held I would not be selling at this level but I cannot bring myself to buy back in at this level.
Is that muddle headed!?
Truly the investor’s dilemma ! But for all the one’s that get away, there are plenty more...etc
Perhaps replace thoughts of missing this one with positive vibes about the gains to come from a certain clothing e-retailer !
Forget the past - it is irrelevant to your current decision (I know, easy to say, harder to accept). Does Treatt represent your best current investment opportunity? If so, invest.
Not really. Treatt (LON:TET) to me does look expensive considering, the lack of growth over the next 2 years, also there is the cost of relocating. I'm surprised the shares have gone up so much.
Then we have Brexit to come, how will that effect trade?
I have no great knowledge of Treatt (LON:TET), but worth noting that the broker forecasts of some well managed quality growth companies look as though past growth rates have essentially come to an end and performance will be more pedestrian going forward. What we as investors need to decide is whether this is due to conservative management, as has been regularly the case at say Games Workshop (LON:GAW) in the past, or whether something fundamental has changed and it really is the end of such strong growth.
That is true but I'm looking at the current Treatt (LON:TET) figures not just the forecasts, all seems pretty flat for such high priced share. Games Workshop (LON:GAW) is pretty high but growth is stronger and the forecast have been revised up recently, the problem with Games Workshop (LON:GAW) is if there is another lockdown which seems increasingly likely.
Some shares are looking overpriced to me so I have been taking some profits recently.
This might be pie in the sky - but I'm wondering if the collapse of the High St is going to be a driver for Games Workshop (LON:GAW) growth. The thing about their games is, you need someone to play. You need a community of like minded individuals. If rents come down, they can take larger stores, create more playing area, get more people into the shop which drives a larger community and sell more product.
Also their stores are usually in the less glamorous end of town, being able to get a store nearer the centre where the posher shops are - posher shops, more affluent customers, then see above.
Yes that maybe so with Games Workshop (LON:GAW) but we have to get through this covid problem first, if there is another lockdown then that will affect them, the shares dropped about 50% in March, next time it may not be so bad but high flyers usually do fall the most when there is a correction.
You might be right herbie47 re Games Workshop (LON:GAW) and whilst their shops were certainly shut, overall they came through much better than most expected. Share price now up over 70% since January 1st.
Disclosure: now 4% of my pension and more than 5% of my ISAS. For me those are pretty big percentages, in a way I'd like to reduce but with the trajectory I just can't bring myself to press the SELL button.
Minervini: The bottom line is that you’re not going to get huge performance consistently if you’re diversified all over the place. If you have a significant edge, diversification does not protect you; it dilutes you. I want to concentrate as much of my money as I can in a position up to 25% of my portfolio. I may not start out at 25%, but that’s where I would like to be for my best positions. This number is not just off the top of my head; mathematically speaking, the optimal position size for a 2:1 trader is 25%. You can look up “Optimal f” or the “Kelly formula” to get a better understanding of how to determine this.
Minervini, Mark. Momentum Masters: A Roundtable Interview with Super Traders (p. 43). Access Publishing Group, LLC. Kindle Edition.
Morning Jack,
Regarding your comment about what will be the strategy for various Stockopedia investors, my strategy will be to sit and hold on to my shares, ride out any potential storm, and keep collecting my dividends. Since WW2 there have been 38 corrections (a correction is defined as a drop of 10% or more). The good news is that the stock market has made a full recovery 38 times out of 38 and then gone on to set new highs. This strategy of holding has worked for me because although the UK stock market is currently in negative territory and it is down by around -23% following the crash in March, my portfolio is back in positive territory and it is above were it was at the start of the year. You just need to have strong nerves to hold on to your shares and believe in yourself that you have chosen the right investments. I only buy high quality shares with a good balance sheet and which make a profit. There are no Blue Sky or Jam Tomorrow shares in my Portfolio.
If you know the shares are likely to drop more than 10% why wouldn't you sell them and buy back? Likely you'd net at least 8% after trading costs. Instead of being in "positive territory" you'd be significantly up.
Hi IGotPoesPocket, the answer to your question is that at the time of the event you never know how much the market is going to fall. At the time I didn't know if the market would drop more than 10%, or would the market fall 5% and recover (in that case it is not worth selling due to costs)? Nobody knows. Covid 19 is a once in a lifetime (I hope) event. At the time nobody knew how much the market would drop and how much it would recover. I'm sure there are people who sold out at various stages of the market crash back in March, decided to sit on cash, missed out on the big bounce backs believing the market had further to fall and are now sitting on loses. In years to come the coronavirus crash will just be a blip on some analysts chart. If only I owned a bottle of hindsight!
You only had to look at what was going on in China and realise this was a black swan. As soon as Italy started having problems, that was your cue.
I'm almost always 100% invested. In February I went 50% cash. I started buying back in April, I just wanted to get that first fall out the way. I've made 50% since then - the market is still 13% down YoY.
Normally I'd agree, it's time in the market not timing the market, but this was a slow motion train crash that was obviously coming for literally months.
Morning Jack
I have been looking at asset managers, most of which have taken a beating. Liontrust Asset Management (LON:LIO) is an exception and favoured son as far as I can see, but despite its very good performance is a little expensive for my tastes. Polar Capital Holdings (LON:POLR) recently announced a 25% increase in AUM but the market reaction has been surprisingly understated. This morning Premier Miton (LON:PMI) announced a creditable performance with AUM up 4%. All have cash rich balance sheets as one would expect. On a medium term view Polar Capital Holdings (LON:POLR) and Premier Miton (LON:PMI) look attractive in terms of share price growth and dividend income. It was comment from Richard Leonard in his recent PI World interview that spurred my interest.
All the best
This won’t come as a surprise but I think Mercia Asset Management (LON:MERC) is under-valued and worth a look. They have a profitable fund management business as well as giving investors direct interest in a portfolio of growth companies in sectors that are benefitting from the pandemic eg. health. They have a competitive advantage and a good network in the UK regions, cash for investment in their managed funds and in their portfolio, trade at a significant discount to NAV and look to be on the cusp of breaking a 5-year downtrend.
I purchased Mercia Asset Management (LON:MERC) at offer price 18.10p last month; out of hours dealing showed circa £2mn shares sold the same night. So I chickened out the day after, selling out at a loss. Turned out it was a bad move with a rise to its most recent SP (where did the sold shares go????). Agreed undervalued. However, underpinning the resistance would be the 26p (from memory), the subscription price for the fundraising to take over the VCTs late 2019. So effectively, circa 20% upside medium term, from current price. Appears as if PI's are quite negative of management as well.
H1, is likely to be good with all the bad stuff shoved into EOY 2020 (provisioning already done for C19). Goodies including their profit from sell off of native Antigen which earned them a nice earner + full 6 months of VCT AUM fees (2% p.a.) to be included. So LFL, H1 21, should be much better than H1 20. Alas, with recent SP rise, how much more petrol its got in its tank.
Sorry to hear you were put off by that large trade. There have been numerous large sells over the last month, absorbed by the market makers as they moved the price up. One of the directors recently bought 1.2 million shares @ 20p so he obviously sees upside and I’m sure there is other significant accumulation going on and expect some holdings updates. It’s possible Invesco are still reducing - this was one of the companies caught up in the Woodford whirlwind. I like PI negativity, provided I disagree with it, as it creates buying opportunities. The main issue seems to be they were shut out of the fund raise done at 25p but as they’ve had nearly a year to buy in bulk up to 10p below that price what’s the problem?
I held Premier Miton (LON:PMI) and Polar Capital Holdings (LON:POLR) is on my radar. From my observations. Polar Capital Holdings (LON:POLR) holds its value well i.e. sentiment with PIs is very good and a bargain price is snapped up quick.
Premier Miton (LON:PMI), on the other hand, I bought during the summer, continued to slip. The MMers appear to enjoy marking Premier Miton (LON:PMI) down. Premier Miton (LON:PMI) did come alive prior to the most recent big drop in the market in Sept. I believe this could have been due to the CEO of Premier Miton (LON:PMI) being interviewed (?) and the recent exposure gained the SP traction. Other than that, if the forthcoming months are going to be thundery and unpredictable, Premier Miton (LON:PMI), I predict may not hold its value and slide. Me, personally, after a 15% slow fall, I yanked my position. Long run wise, Premier Miton (LON:PMI) offers value, agreed. However, short run, if the markets continue to be bearish, expect SP to be marked down. Premier Miton (LON:PMI) painful fall can be seen https://finance.yahoo.com/quot...
Small piece of news about Premier Miton (LON:PMI) - I hold one of their funds directly and they have taken admin back from Link. I guess they will save a bit of money now they have that capability.
My preference would be for Polar...58% of its funds are in technology and 15% in healthcare. (Two years ago I went to Mello Derby and then bought Miton and Impax. I sold one of my two holdings eight months ago.)
Gfinity (LON:GFIN)
Opened this morning up 30% with no reason - now we have an RNS saying there is a strategic review with them looking at options including sale of the company.
I have done very well with this investment recently and am enjoying this mornings rise BUT I really do not know how the share price will move through this review.
There is a lot of money in eSports at the moment and the publicity of the US float of the company supported by David Beckham has raised profile even further - SO perhaps this is a good thing and I should hold for a while longer?
Thoughts anyone?
Have traded GFIN over the last few years. It failed to live up to expectations for a long time, and had a huge fall in value a couple of years ago.
However, the last 12 months has seen a complete turnaround led by an effective new management team and approach - resulting in an entirely different - and apparently, highly effective/attractive move to e-affiliation with some of the most well-known games.
IMO (only!) it looks very well-positioned in an exciting market, with crucially, established monetised relationships - it is no longer all about jam tomorrow, which was the previous issue - and on this basis, am choosing to hold and see what bids will bring - it certainly seems to have attracted market attention today !
DYOR
Position sizing is all relative though.
Miniverni will not have 25% if his total assets in one trade.
It’s when people say i have 20% in this one stock, within a trading portfolio of 100k in their ISA, but they actually have 80% in bonds in their £2m SIPP. Its not representative of the risk they are talking, or the true size of the position unless its a % the total invested assets.
Morning Jack,
I recently fed this suggestion back via a Stockopedia questionnaire and thought I would sound out everyones opinion as to its value. Since Friday is a slow news day and it is the end of the trading week could all the discussions and ideas that have been aired in that week by Paul,Jack,Ed plus investor posts be collated and published on a Friday in to a watchlist of up to 3 shares. Maybe call it The DYOR Watchlist so there is no question of it being misconstrued as advice or recommendation but rather the current top shares for investors to scrutinise in more detail.
Hi Jack if you could take a look at Marston's (LON:MARS) now the brewing merger with carlsberg has been approved.
Morning Jack
Some positive green shoots in the ventilation industry (supplier to the building industry). Volution (LON:FAN) reported yesterday that organic sales growth in August and September was up 7% on the previous year. Today, at the other end of the market cap spectrum Titon Holdings (LON:TON) (I hold) says that sales growth turned positive in September.
Mechanical ventilation providers might be a long-term winner in the post-Covid world. Although Titon does serve this market, it has a stronger position in “passive” or “trickle” ventilation.
Titon is too small (MC= £9m) and illiquid to be looked at here but its sits in the deep value (with a reason) bucket, as it is trading around the level of its current assets minus total liabilities. So you could argue that you get the £4m plant and the 49% stake in its Korean subsidiary for free (so I hold). But it will need to see a return to profitability in its Korean operations, I think, to see a move up in the share price.
I have traded far more than I would want to this year to try and reposition myself for COVID. I don't hold any leisure/ retail or entertainments stocks but continue to watch from the sidelines to jump in should some vaccine or something be found. I am keeping around 20% cash for that purpose and in case there's a general March style collapse.
I am focused now mainly in technology stocks which in Europe are very cheap compared to the US markets which typically won't be impacted (unless positively) by COVID. I have these longstanding positions in Insurance which frankly haven't been too good but the yields are still good so I'm holding tight on them at least in the mid term.
Morning Jack,
Would there be any chance of a comment from yourself on position sizing in a portfolio if there aren't many interesting RNS's please?
My question really is, if a quality share goes up in value so it is over a certain percentage of the portfolio (I know a lot of people set the max. at 10%) why sell?
I noticed recently the Buffetology fund sold some Games Workshop shares because the value had gone up too much as a percentage of portfolio. I appreciate they may have governance/legal reasons for maximum limits of a certain percentage but us private investors don't.
Does it really matter if a great share with good future prospects ends up way oversized?
I would greatly appreciate yours, and others, thoughts on this.
Many Thanks
James
I have been having these thoughts myself recently with my £BOTB growing at one point to 20% of my portfolio. I have been bringing it down over the last few weeks (its now about 12%) as I am so happy with the gains I want to pocket some of it.
I think it depends on your risk profile and how much you are willing to potentially lose to gain. Personally I happy with gains between 10-15% a year and would prefer not to have a big downside. If you want more gains then you need to concentrate your portfolio which adds risks
A trader would look at the Value At Risk. What is the maximum drawdown of this stock, it’s volatility vs the rest of your investments and the impact on your portfolio of this loss.
True, and that's fine for events within the scope of drawdowns/volatility studied, but will not cover other 'black swan' events or even larger but less-common drawdowns. Some ever-vigilant traders, depending on their trading system, might also generally be happier constantly monitoring a much larger position size than a buy-and-hold investor with a day-job would. Ultimately, any individual share, however great under normal conditions, can actually go to zero given a black swan event (Covid, credit crunch, short- or 'bear-' attack, accounting mis-statements etc) that is its own particular undoing. Holding say 25% of one's wealth in an individual share, however much admired, is quite some risk and would need very close monitoring.
I guess it depends on your risk profile but, at one extreme, the momentum investors with the most successful track records, such as Mark Miniverni and David Ryan, are happy with single holdings representing 25% of their total portfolios. The book, Momentum Masters, is an informative, fascinating read.
Hi James,
I follow similar rules to Brookeda.
My initial position size can be up to 5%, and I will let it grow to 15% before top-slicing the investment. I don't want one share representing to much risks.
BSV
As everyone else is saying, it depends on your attitude to risk. It also depends on the level of your convictions for those large holdings. The more confident we are the larger we can allow our holdings to become. As Warren Buffett said “When it’s raining gold, reach for a bucket, not a thimble.”
As an example, I did the calculations over the weekend and (if I am right) worked out that £NYCT was on a p/e of 5 for this year’s already counteracted revenues. With more to follow next year. Clearly this is an exceptional case as revenues may dry up once the need for Covid tests has passed. But until then I am more than happy to have Novacyt Sa (LON:NCYT) above my usual 10% limit and growing.
I've really used the volatility over the last 7 months to shape my portfolio to be more diverse in both asset classes and sectors. I've tactically allocated amongst growth, value and deep value shares but allowed myself a maximum of 60% in individual stocks, with the rest made up of funds with physical assets exposure (infrastructure and real estate), themes (I hold Hipgnosis Songs Fund (LON:SONG), Merian Chrysalis Investment Co (LON:MERI) and a healthcare ETF) and exchange exposure through ETF's. I then also track via sectors, so currently my highest sector exposure is Technology (13%) through Merian Chrysalis Investment Co (LON:MERI) and Frontier Ip (LON:FIPP)
I've tried to focus on portfolio weighting much more recently and balancing out where necessary as for much of last year and the start of this year Boohoo (LON:BOO) was over 30% of my portfolio, which meant its daily share price performance was essentially what was driving the performance of my portfolio.
Hi James,
The strategy I have used for many decades is to 'Run your Winners'. I buy quality shares for long term investing. If you look at Liontrust Asset Management (LON:LIO) , I bought this share back in 2017 at 397p but due to the rise in its share price, it has grown to be around 25% of my portfolio. It was never planned to be such a large holding but why kill your golden goose? If you believe in the company and you believe it has a good future, why sell it?
Hi Logical David,
I think you have summed up my question far more eloquently than my rambling wording.
I'm going to get a sign made for the wall saying
"why kill your golden goose?"
Hi Logical David,
I agree with run your winners but the reason to not have 25% of your portfolio in one stock - and is this 25% of your entire investments, to my earlier point?
BUT the reason not to is risk management, tomorrows RNS.... 'Liontrust - fraud identified/FCA launch investigation/mis-selling' etc etc
You just never know. So if this is 25% of your entire net worth, that is a crazy risk . imo
I'm glad I didn't have 25% of my wealth invested in Patisserie Holdings (LON:CAKE) . Until the fraud was revealed it looked like an almost perfect company.
"If you believe in the company and you believe it has a good future, why sell it?"
Because we're just investors. We don't run the company, we don't know precisely what's happening in the company - we're ultimately reliant on delayed information controlled by third parties and most importantly, we can't predict the future / control external issues.
"Belief" is not the same thing as logic. Logic points towards taking gains off the top and holding at a sustainable level. A sustainable level will of course be different for every investor, depending on circumstances, but as above, holding 25% of a portfolio in a single company is, IMO, a risky strategy.
(And the golden goose is a fairy tale !)
Dear nigem2000. I disagree with your sentiment that logic points towards taking gains off the top and holding at a sustainable level. It takes a lot of time and effort to find a winner, so once you find one, is it logical to sell it as it rises? If I put funds into a stock that has the potential to fly, there’s no way I’m pulling anything out if that stock is a winner. Because then you miss out on all the hard work you have done to find that winner, recouping the losses of the failed stock picks and reaping the full rewards. I have had various multi-baggers that I have let run without slicing off the top. These winners can transform a portfolio. For example, at one stage Barratt was a 24x bagger for me, but as I had not sold a share from the day I bought them, all the effect paid off. At one point Barratt accounted for 50% of my share dealing investment total, but I still didn’t want to slice off the top, I saw no reason to as the share price was still in an upward trend. As I see it, these are the ones that make a big difference to your investment pot and they don’t come along everyday, so why sell out as you hit the jackpo
I think Jack will know much more on this than I but I have learnt the hard way with Anglo Asian Mining (LON:AAZ) and Rockrose Energy (LON:RRE) about oversized positions and portfolio risk.
Unpredictable things happen that can cause a share price to drop 20% 30% 40%. I can no longer sleep at night with that risk. So I have now set myself a maximum initial investment size of 10% and will top slice when it rises to 15% as an absolute maximum. I haven’t formalised it completely but for example if I decided that my maximum initial position for a stock is 5% and it rises to being 10% of the portfolio then I will top slice it down to 7.5% or even back to 5%.
It is all very well to have a conviction investment (AAZ it was gold and prodigious cash generation, RRE it was cash on the balance sheet) but this IMO can blind you to other risks.
Anyway that is my penny worth.
Regards
Michael.
Michael,
I too had a large (20% of pf) RRE holding, I bailed/chickened out in March to crystallise a 50% loss on that position. I never did buy back lower foolishly but its other holdings that have made the money back thankfully.
With this experience I am now perfectly happy holding on when the percentage of pf of a share grows itself but never to invest too much in any one share.
We all wish we had bought Games Worksop for £5 etc etc
Hi James,
Why don't you set a mental stop loss say 10% above the current price , now when it reaches this level you revist the stock: 1) reduce or continue to hold, 2) what can I buy that's attractive and offers similar risk return profiles with the spare cash i release? If you are still unsure whether to top slice then move your stop loss up another 10% and repeat the process? Remember dealing costs and spreads are the hidden killer. Liquidity is also something to watch-make sure there is good broker coverage, reasonable sizes positions being traded and diversify your portfolio across different market caps-do't fish only in small caps -build balance into your portfolio-then no nasty surprises if one sector of the market moves against you and liquidity dry-up.
Your not a portfolio manager, not constrained to holding circa 25 positions with a 4% weighting-so enjoy the freedom you have. Restrict your portfolio to say no more than 15-20 holdings that way you can monitor what you have got and live a normal life.
Be brave when all the key data backs up what you think.
And don't dig up the roses to save the weeds-there is nothing worse than chasing a story that's not there..
Hi Mark,
There's some very solid reasoning there, many thanks for replying.
James
No worries James.
Just try and grow into your learning-keep it simple until you gain confidence in your bets,- log what you do and no why you bought it. Then you can explore what next-don't over complicate and don't ever believe your perfect - nobody is.
As Warren Buffett said" I have never yet met a man who can read the market"...
There's some great comments and words of advice in this thread, many thanks all.
Have a great weekend
James
Many thanks guys for your various comments, as James says, "great comments and words of advice". Bearing in mind the potential for future fraud, then maybe I need to mull over the idea of top slicing my Liontrust Asset Management (LON:LIO) Golden Goose. I have several Golden Geese in my 18 share Portfolio. Maybe I could top up on both Volex (LON:VLX) and Luceco (LON:LUCE) which I bought summer 2019 because each of these shares only represent just under 10% of my holdings. Food for Thought.
I found this article from Paul and Graham really good in respect of sizing and no. of stocks in portfolio - hope it helps - https://www.stockopedia.com/co...
That is a great read, highly recommended.
Thanks for the link.
Thanks for finding and sharing the link.
Not seen before and very informative
Hi Logical David,
For me the contrary views is what makes SCVR so useful and if you are now re-considering your 25% in Liontrust, good, might be the wrong thing to sell, but never wrong to reassess.
I set an absolute max of 3% for an individual share & 5% for a fund or etf, you never know.
But what i do know is the 3 shares i’ve had a 100% loss on in last 20 years have all been frauds, i didn't sell straight away and very quickly they went to suspended and bust- rabbit it headlights, i now sell on really bad news.
On Liontrust Asset Management (LON:LIO) bear in mind that the management are taking an extraordinary amount of money out of the business, far more than is being returned to shareholders.
From last year's finals: "Members drawings charged as an expense" were at £32 million plus there was another million in share compensation. On top of that the two executive directors were compensated directly to the tune of about £7 million - so about £40 million flowed out of the company to management.
After all that the company booked about £13 million in profits which was less than the dividends paid out to shareholders.
To be fair the executive directors held about £15 million in stock as well, but given that's two years earnings for them I'm not convinced it offers a great deal of shareholder alignment.
On the face of it this doesn't look like a company run on behalf of shareholders. In fact it looks like a company that used to be a partnership whose partners want to maintain the financial benefits of that arrangement while laying off its risks onto shareholders.
Broadly, of course, fund management is a fickle business, prone to swings in earnings, changes in sentiment and unexpected interest rate movements. Liontrust - along with the other high quality fund managers discussed on today's SCVR - have done extremely well over the past few years. However, it would be a bold call to expect the same level of outperformance over the next decade as seen over the last for any of them - and an even bolder call to claim that outperformance was predictable in advance.
Most of these highly successful funds don't have a long term record but Nick Train does. He was espousing his quality brand approach as far back as the 1990's without any discernable evidence of outperformance - a quick look at the long term chart for Lindsell Train Investment Trust (LON:LTI) shows that it went nowhere from 2001 to 2008 and then took off shortly afterwards.
So in order to explain that change something really extraordinary must have happened in the world of finance around 2008 that triggered the rerating of a fund that fundamentally doesn't change its holdings. Now ... what could that have been?
timarr
Hi Jack,
If you have time Petropavlovsk (LON:POG) and Treatt (LON:TET) would be interesting.
BSV
Good morning Jack. For my portfolio I'm trying to find compounders for a simple buy and hold strategy.
If that’s what you want why not go for Fundsmith? Leave it to a great fund manager. It saves time on research. Its 15% of our portfolio and looking back I wish it were more!
It will be interesting to see how Experian compete against blockchain based credit scoring applications like Bloom.co
Re Experian (LON:EXPN) (no position) competing against blockchain based credit scoring applications, that's an interesting question, but blockchain isn't very eco-friendly is it?
I've no expertise in blockchain but I get the inpression that it will be difficult to achieve large scale in blockchain given its high energy consumption, especially in the face of growing clamour to achieve 'net zero carbon' emissions.
Bitcoin uses a lot of electricity due to the "proof of work" algorithm that restricts the 'mining' of new coins. A Blockchain implementation doesn't need to use proof of work.
I haven't looked at blockchain credit scoring but suspect there is a significant barrier to entry against the big boys and their network effects never mind how their technology has been implemented.
Jack, The other company Nick Train brought into (at the end of last year) is PZ Cussons (LON:PZC)