Small Cap Value Report (Friday 5 July 2024) - SPA Brief: SIS

Good morning from Paul!
Practically nothing on the newswire today. So today's
Labour landslide
Is now fact rather than forecast. This is not the place for discussions on politics itself. So please can we stick to how the election might affect the economy, markets, and companies/sectors.
Futures on IG are currently showing (at 06:23) little to no change (FTSE 100 up 17 points, sterling flat at £1 = $1.276), because markets already price in high likelihood events in advance. It's only big surprises that send markets haywire - who can forget the Brexit vote, when equities and forex markets went absolutely haywire - I can vividly remember that - even some FTSE 100 stocks collapsing, and (briefly) there were no buy orders on the books at all for some mid and large caps (so technically a bid price of zero!) - that's the danger of stop losses when something big and unexpected happens - fortunes were made and lost that day by geared traders.
FWIW I won't be making any adjustments to my portfolio, because I don't see that much is likely to change any time soon. The general drift is likely to be similar to 1997 I reckon - lots of new stealth taxes, but probably no big changes to the main taxes (if Labour stick to their pledges). I know a lot of affluent/rich friends are worried about potential tax raids on CGT, Inheritance Tax, etc. One has even emigrated to a tax haven! Will AIM IHT relief survive? Will pensions be raided? I was very worried about the Lifetime Allowance being re-introduced, so I wrote to Rachel Reeves explaining why that would be a mistake, and that proposal was dropped. Maybe not cause & effect there with my letter, but hopefully my voice added to others saying the same thing? It's always worth writing to people in positions of power, because apparently for every 200 people who agree on an issue, only 1 actually writes a letter. Also I like sending a physical letter because they probably receive very few (with people preferring emails, which are more easily ignored). The same is true of writing to company Directors - a physical letter will stand out, and will probably be read by the Chairman/CEO, whereas an email is less likely to reach them directly.
What comes next on Govt spending? Well, more public spending, but within tight constraints. Labour won't be able to increase planned borrowings - look what the forex and gilt markets did to Truss/Kwarteng when they tried to do something seen as radical. That lesson won't be lost on Rachel Reeves I'm sure, and she seems a sensible person with a relevant background in economics & finance.
So all in all, I'm pretty relaxed about this in the short term. That calmness might not survive Ms Reeves first budget! Since we don't know, there's little point in speculating about it.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Hardly any company news today -
Other mid-morning movers (with news)
Pipehawk (LON:PIP) - down 72% to 2.35p (£1m) - Trading Update - Paul - NO COLOUR
Says its subsidiary QM Systems has seen worsening of previously reported problems. Two material orders are not proceeding. QM’s finances “now under severe financial pressure”. Looking at putting it into insolvency process. Says remainder of the group will continue trading, and is in line with exps. QM delivered 65% of group revenue in 2023, and made a £1m loss.
I won’t give it a colour, as it would need more detailed work to see if there’s any value in the other parts of this group. Market cap so tiny, surely de-listing now seems likely? Not for me.
Summaries
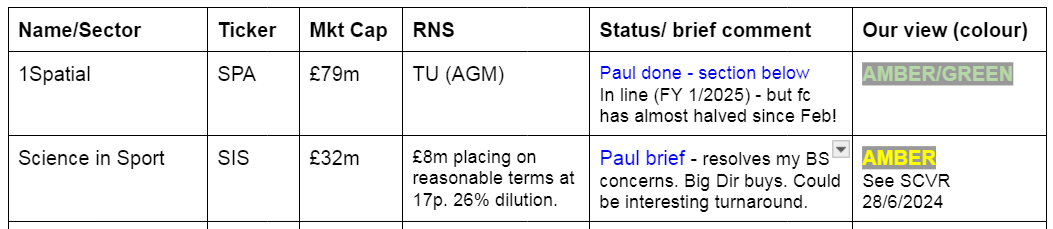
1Spatial (LON:SPA) - up 1% to 71.7p (£79m) - Trading Update (AGM) - Paul - AMBER/GREEN
Today's update is in line with expectations. The outlook sounds positive. Shares aren't cheap, but I think there might be something interesting here. So I've flagged it AMBER/GREEN more to say that I like the potential, rather than the figures as they stand (it looks expensive, and is still cashflow negative due to heavy R&D spending). Over to you, for more detailed research - let me know what you think!
Paul’s Section:
1Spatial (LON:SPA) - up 1% to 71.7p (£79m) - Trading Update (AGM) - Paul - AMBER/GREEN
1Spatial, (AIM: SPA), a global leader in Location Master Data Management (LMDM) software and solutions…primarily to the Government, Utilities and Transport sectors via the 1Spatial platform. Our solutions ensure data governance, facilitating the efficient, effective and sustainable operation of customers around the world. Our global clients include national mapping and land management agencies, utility companies, transportation organisations, government and defence departments.
I haven’t yet managed to visualise what the company actually does. It seems to be specialist software. Here’s their website. I see there are recordings of management webinars on InvestorMeetCompany, so I must find time to have a look through these, to better understand the company and its markets.
I’ve started looking again at SPA this year, because the figures have improved dramatically from when we last looked about 4 years ago. So it’s a much more credible share now than before, having broken into profits, hence why I resumed coverage in Jan 2024, to recap -
11/1/2024 - 52p - Me - AMBER/GREEN - Contract wins. Worth a closer look. Much improved in last 4 years.
11/3/2024 - 56p - Me - AMBER/GREEN - Muddled TU, shares dropped 11%. Potentially interesting co.
24/4/2024 - 60p - Me - AMBER - Final results FY 1/2025 - small profit, negative cashflow. I’m not convinced yet.
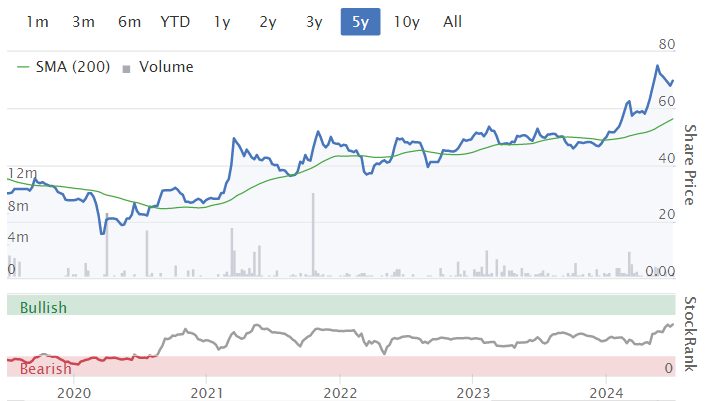
It’s since had a more recent rise, and at 71.7p is up roughly 41% YTD 2024, not bad!
Today’s news - sounds reassuring, but not price sensitive either way, being in line -
“Trading for the full year is expected to be in line with expectations. We have secured several new contracts in Europe and the US (as previously announced) in recent months, and we continue to make progress with our innovative 1Streetworks SaaS offering.”
“Planned headcount increases” are underway. Hopefully these additional costs should be baked into the forecasts already.
Outlook -
“The Group has a strong order book, a growing recurring revenue stream and substantial sales pipeline underpinning the Board's confidence in the outturn for FY25. We believe the investments we continue to make in people and technology have positioned the business well to take advantage of the huge opportunity ahead."
I like “huge opportunity” situations! Let’s hope that’s realistic, and not over-excitement.
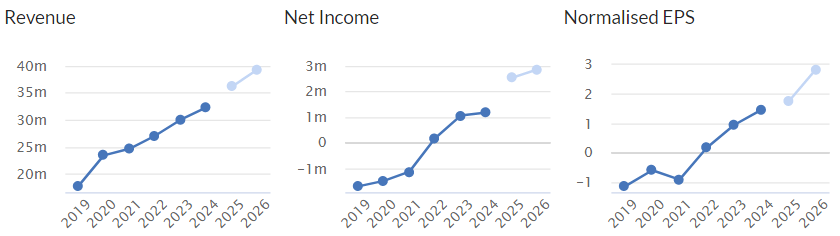
The graphs below are impressive, and tell me this looks to be quite an interesting opportunity, with a credible track record so far -
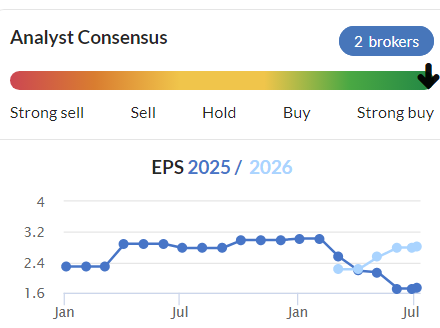
Note that the broker consensus numbers seem to have been reduced significantly in recent months - so delivering in line with expectations now, would effectively have been a profit warning if they hadn't walked down the forecasts in advance -
Paul’s opinion - This share is tricky to value at this stage, and the forward PER of 32.4x looks aggressive. However, I find PER isn’t a good measure for growth companies that are spending heavily on expansion. PER is more useful to measure more mature companies I think. Often the best growth companies look very expensive early on, and it’s a mistake to screen them out as overpriced, as all too often I’ve missed some multibaggers in the past by being blinkered on valuation.
Looking again at SPA’s FY 1/2024 results, R&D spending is heavy, and absorbs more than all the cash generation. That’s fine if the results are going to be booming sales, so generally I like big R&D spend, if it’s being used on something productive. I can’t really assess that though.
I’m going back up to AMBER/GREEN, because I suspect there could be something interesting here, that’s at least worthy of further research. I’m a bit worried that if we mark too many things as just plain amber, then readers who only follow up on our green or amber/green sections might miss something good.
What do readers think? I’d like to hear from anyone who’s done more research on SPA.
I see Marlborough funds hold 16.9% and increased in March 2024. They're no fools, and are very good stock pickers. I would like to see SPA strengthen its balance sheet with a placing of say £5-7m, which would only be c.7-10% dilution, and I think would be beneficial, since its current balance sheet looks a little stretched, with negative NTAV of c. £(2)m. Software companies don't need much capital, but NTAV should be positive in my view. Customers like to know that a key software supplier will definitely still be around in future.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Can anyone help me. There is a regular investor and sometimes contributor on here who has written an e Novel about Investors. He has very kindly said he is donating some or all profits to Pauls favourite charity Zane. Thanks to Paul I am now a trustee of Zane. I would like to make contact with this person and know who he is. If he reads this will he contact me at charles (at) woodlandswitney.co.uk (if I use the normal at symbol it doesn't work properly on here) I hope someone can help. Thanks in anticipation.
I don’t know his user name on here but the author is Andy Vaughan and the book was entitled Pigs get slaughtered. He also did a chat with David Stredder on Mello Monday on 13th May, so he may be able to provide contact details.
cafcash, that's me. I'll drop you a line.
I recently bought the 'Pigs Get Slaughtered' paperback and found it very good. It was nice having small chapters, easier to leave it at the end of a chapter. A well thought out book.
What gets me is that pundits blame politicians (some justly, some not) but the electorate (their viewers) is treated as deeply wise.
The main thing about the election is we have the prospect of a stable government for the next 5 years. So much better than numerous other western countries at the moment. (France, USA etc etc)
I don't suppose Rachel Reeves remotely wants to shock the markets in tribute to Liz Truss! So expect a few stealth taxes and in a way quite a boring initial few years. At least until the super majority of Labour backbenchers get restive with limited economic and welfare changes.
The thing to watch out for are under-the-radar changes which have longer termm effects. I'm thinking of Gordon Brown's 1997 (or was it 1998?) abolition of the Advance Corporation tax/ dividend tax credit regime. This change was accelerated the decline of a natural UK demand for home based equities, and 25 years later the London Stock exchange lacks the range and quality of shares it once offered.
Interesting to see Kier (LON:KIE) up 7% when Keir enters No.10. ..
Apparently no such thing as bad publicity. Is Mr Market really that crazy?
For the investment rationale, it is worth taking a look through postings by contributor yiannos1 (no point me reinventing the wheel).
(For those who wondered who Close Brothers (LON:CBG) might have had a 10% rally the other day..) Close Brothers (LON:CBG) Deutsche initiated coverage of Close Brothers on Friday with a 'buy' rating and 610p price target as it said the overhang on the shares has opened "considerable value."
At 0.5 x TBV Close Brothers is worth the risk."DB noted that the shares year-to-date have been driven by the FCA review. It said the shares have overly discounted this risk.
Graham do appreciate the demands but as a Stout swilling man could you to take a look Cairn Homes (LON:CRN) when you have a wee moment am I right that any dividends will be taxed by the Irish Government
Cheers Steve
Hi Steve.
Cairn Homes (LON:CRN)
this was covered earlier this week
Tommy
Thanks ever so much only saw Paul’s brief comments
Irish shares
Don’t know about dividend tax but the stamp duties is 1% instead of 0.5% for UK shares. I think Aim shares have no stamp duties.
Anybody else following Celebrus Technologies (LON:CLBS) ahead of next week's earnings? Difficult to assess what exactly this company does but with a general understanding my instinct is they might be in the right place at the right time with their behavioural data technology and cybersecurity fraud solution and AI capabilities (which are vague but a selling point of theirs). Good balance sheet - almost passes Roland's growth stock checklist. I don't hold as the stock price has gotten away from me, but I wish I had bought in when I discovered it.
Yes, bought in a few months ago, but it did nothing and drifted down. There was a steady increase from 220s in June and shot up quite quickly this month, so I guess expectations are high for good results on the 9th and maybe news on any new contracts - hopefully
I've held Celebrus Technologies (LON:CLBS) a long time now, and am very nervous heading into Tuesday's results. March's trading update stated "Results are expected to be in line with market expectations1, with full year revenues above £32.0 million (FY23: £21.5 million) and adjusted profit before tax in the region of £5.5 million (FY23: profit £3.8 million). Being pedantic over words, I am more encouraged by "in line with" than I am by "in the region of"....
This is a tricky sector and profit misses get punished, hence my nervousness. I am keen to move into Cohort (LON:CHRT) which wins in the Stocko "Compare with" tool, but is not as strong in my screen developed from the "Fix the Odds" teach-in, where CLBS meets all criteria for a Q-V-G type screen but CHRT misses on the Operating Margin and ROCE 5 yr averages.
So yep, I'm following with keen interest !
thanks. Just saw this just now: https://ukinvestormagazine.co....
It is a tricky sector and the US software stocks are very weak if that is an indication. Will wait until after earnings but very interesting.
Thanks for pointing it out as i've missed the company.Sorry not much to say about it.But seems like a service that's definitely needed if they have the best solution to the problem.I think they might analyse data, so if you purchase a Gucci bag online, always shop in Lidl and are 70 (and you never have before) as a simple example.AI algorithms would block it i would guess, even if a fruadster had taken control of your mobile phone and authorised it with 2 factor authorisation.Could be totally wrong though.
But banks and financials are now liable for many fraud/scam losses, as long as the customer has been warned i think (eg. if they still withdraw their own money and send it willingly afterwards).And scams are always getting more sophisticated even without AI.It's a war similar to cybersecurity between the good guys and the bad guys.Stocko's forward p/e of 20, if still accurate doesn't potentially seem too pricey for a software company.
Celebrus Technologies (LON:CLBS) - with regards to what they do I found the Capital Markets Day presentation 7 months ago quite useful, it's available on the Investor Meets Company channel on YouTube if you've not seen it already.
yes I did thank you. I was also very impressed with the CEO's interview with Fintech Times last November. Seems like 2019 was their best year - be interested to see if they are headed back to that...
Celebrus Technologies (LON:CLBS) Hello stockorocko - yes, I hold in my 13 company UK small cap portfolio.
Seems a lot of investors find it hard to assess what Celebrus does?
Not surprising - it's what used to be referred to as CDM (customer data management) though that's now frowned upon as outdated terminology. These days it's an SaaS platform that plugs into a corporate software stack (website plus backend) and enables sales, marketing and fraud departments to better understand their customers needs during (live-time) and across sessions. In the companies own words '
Celebrus builds better relationships between consumers and brands.
Effortlessly build a comprehensive understanding of every visitor - from anonymous to known and everything in between!
Traditionally Celebrus partners with major SaaS providers eg Adobe, Teradata etc to major global clients eg Bank of America, Quantas, HSBC, BNP Paribas. They how have a cloud based platform which allows them to offer directly to customers - eg with a Salesforce API or custom interface.
Customers are very sticky. Which is great for ARR when you have them. Not so great when you want to acquire them? As third party cookies are removed the private cloud based Celebrus platform allows first party data capture - an unique opportunity for Celebrus to acquire customers that otherwise would not be keen to change. Customer acquisitions will likely start small - the cloud based platform allows rapid scaling of customer use - the 'land and expand' strategy.
Like others I recommend the recent capital markets day, on IMC, or here on Youtube
&t=4521sThe video includes a demonstration of some of the software modules by the CTO and at around 1 hr 24 mins a presentation by a Merkle executive (global marketing and sales consultancy) on why they choose Celebrus Technologies (LON:CLBS) platform for their customers - which I think is helpful in understanding what the Celebrus platform does for its customers.
The trading update in March was issued a couple of weeks prior to the year end - hence the revenue figure gives an 'above' and the profit and cashflow are 'in the region of' - as it would not be possible to be accurate prior to the year end?
I'm keen to see the results - but not too fussed on the actual figures for revenue and profit as the 'in-line' represents an increase of 50% in revenues and 67% in profits over the prior year with confirmation in the TU that ARR is up 20%.
I'm primarily interested in the commentary on their 'land and expand' approach using the cloud based platform and any more colour that they can give on the outlook for the current year. I often find its important to watch the presentation Q&A to help read between the lines on the outlook? As its this that will dertermine whether Celebrus Technologies (LON:CLBS) proves to be a quality company with sticky customers but lacking scale - or a company that can scale its operations rapidly with the share price upside coming from growing profits though operating leverage and re-rating on increasing margins. Time will tell?
cheers
Mark
Regarding 1Spatial it rang a bell with me. Last month there was a webinar with AJ Bell and the CEO Claire Milverton gave a 20 min presentation.
It's here for anyone who is with AJB
https://www.sharesmagazine.co....
I’ve held Cavendish Financial (LON:CAV) since the merger and it could still be well worth checking out as a beneficiary of possibly improving sentiment towards UK smaller Companies post the election, along with good chance of more small cap IPOs and fund raisings. It’s one on Graham’s best 2024 idea list and still looks cheap.
Combining FinnCap and Cenkos gave immediate cost savings and they are no longer competing with each other. They had cash around £21million at the end of March and market cap only around £50 million.
Cavendish Financial (LON:CAV) looks very cheap. One for a possible “better than expected” trading update ahead?
Ken
I too have been long Cavendish Financial (LON:CAV) for a few months as I feel it is a stock with exposure to a market rally but reasonable downside protection (from the balance sheet). Cost cutting from the merger has been done and private M&A activity has proved remarkably resilient in FY24. I have been particularly impressed by the cash generation in recent updates with b/s cash rising from £12.3m (Sep 2023) to £17m (Nov 23) and £20.8m (Mar 24).
I believe FY 24 results are announced on 11 July. I would not be expecting any surprises as key FY24 data was already announced in the 4 April Trading Update. I also think it unlikely to get a “trading ahead of expectations” statement only 3 1/2 months into FY25, particularly how volatile Cavendish’s revenue stream is and susceptible to market momentum. I will be looking closely at any guidance CAV gives on how trading and cash flow generation has performed since end-March. Also I am hoping there might be an outside chance of a dividend reinstatement - following the resilient FY24 performance and this would be a positive signal of ongoing confidence from the board.
Stocko is sometimes incorrect with earnings release dates. I checked with Cavendish Financial (LON:CAV) directly and, after multiple attempts, heard back from the Head of Broking that the results date had not yet been announced to the market. So it could be July 11th, then again, it may not be. I am also hopeful for an upturn in their share price, given the slowly improving market sentiment and cash on their balance sheet compared with market cap.
Strange goings on at microcap Pipehawk (LON:PIP) which announced three sizeable contracts for its subsidiary QM Systems (one in January, two in May) and today announces that " two anticipated material orders will not be forthcoming. As a result, QM's financial position is now under severe financial pressure. Accordingly, the Board is now taking steps to potentially, inter alia, place the Group's subsidiary, QM, into administration or a similar corporate insolvency process."
The other subsidiaries are said to be trading in line with management's expectations. Pipehawk (LON:PIP) share price is down 70%.
(disclosure: no position)
On a quiet day for corporate news I would just like to add that I’m regularly taken aback at the quantity and quality of the output from Paul, Graham and occasionally Roland.
In addition there a number of regular subscribers / posters who are insightful and add real value.
I also like the way the format continues to evolve , summaries, colour coding, short and long sections.
Lastly I always enjoy listening to the podcast at the weekend.
A very grateful subscriber
Thanks West65, much appreciated! :-)
Speedy Hire
I suspect going to be election beneficiary
Big blast on housing / infrastructure from Labour no doubt .
Speedy picked up a big contract from HSS I suspect largely due to the investment in their “green” fleet which ticks a big box for the corporate hirers .
For clarity I did hold HSS which was just a trade as they were on lows, sold in 6 weeks for a quick 15% bounce and moved that into Speedy which was at lows of 24p region so timed both nicely for once .
Speedy has had a huge bounce since then so not sure where it’s going to level out at but it’s travelling with some momentum right now .
Morning planetX
Hopefully some of the companies I hold will be beneficiaries of investment in infrastructure/housing/construction, to a greater or lesser extent.
Namely VP (LON:VP.) Galliford Try Holdings (LON:GFRD) Brickability (LON:BRCK) Van Elle Holdings (LON:VANL) Flowtech Fluidpower (LON:FLO) and Sigmaroc (LON:SRC)
Construction companies and the Labour government
Housebuilders are already up today. I add Breedon to the list. Energy companies, both , the fossil fuels and renewable will benefit from the spending up.
Vistry (LON:VTY) too even after the run so far.They have a former board member from US listed NVR (NYQ:NVR) through large US investors too, a massive multibagger over the last 20 or so years.
The good news is that this government can’t increase the energy profits Levy as much as the last government did. Because there is only 25% left to tax.
They’ll still have a good try.
Labour have clearly stated that they will increase the North Sea windfall tax from 75% to 78%. The pips need to squeak more apparently.
Yes Alphafight
In preparation for the continuing abuse and waste of our North Sea assets I recently pulled the plug on my last North Sea involvement in Serica Energy (LON:SQZ) and Jersey Oil and Gas (LON:JOG). Ha e opted for Arrow Exploration (LON:AXL) and Petrotal (LON:PTAL) instead.
Also watching the rapidly developing exploration play offshore Namibia and South Africa. There are still some places that like the value extractive industries can add to their National Wealth and job creation. Galp Energia SGPS SA (ELI:GALP) and Africa Oil (TSE:AOI) of particular interest.
Why bother waiting and wishing and hoping for an outbreak of common sense in the new world wokery order ?
thanks for that axl and ptal look interesting
It will be interesting to see how Namibia finds fare deepwater and far from shore?
If anyone is interested, I'm hosting an election special LIVE this morning on YouTube at 9.30am today (5th July) with accomplished investor & ex City (re Schroders UK smallcap) fund manager Iain Staples.
Here we're planning to cover lots of fascinating stock ideas including: #CMCX #FCH #IGR #SUP #EQLS #CHG #MPE #SDG #FRP #CHRT #DSCV #FNX & many more.
Alongside of course, trying to answer any questions that you might have.
So please feel free join us. Everyone is welcome. Lots to discuss.
Really enjoy your shows Paul so thank you and keep up the good work!
Excellent Paul, I really enjoy listening to Iain.
I thoroughly enjoy all of your fund manager interviews and with Paul Scott and Richard Crow etc, please keep them coming
"This is not the place for discussions on politics itself. So please can we stick to how the election might affect the economy, markets, and companies/sectors."
Ever the optimist, Paul!!
Irrespective of one's political views, at least we have a government with a sizeable working majority. Let's hope that Kier Starmer's government plays it with a 'straight bat' and is honest with the public unlike the shenanigans of some of his predecessors. I wish him and more importantly the country well.
Going to be interesting next few years in parliament, with two vocal voices to hold Starmer on his toes :)
I for one will be watching more PMQs to see Jeremy Corbyn hold him accountable from the left left, Nigel Farage from the right right.
And the Greens from the middle!
And the Greens from the middle!