Small Cap Value Report (Mon 1 Aug 2022) - FLO, BUMP, JNEO, BLV, XPP

Good morning from Paul & Graham!
Weekend podcast - the latest edition, I recorded on Saturday. You can add this to your podcast platform, by putting in the URL. A listener suggested this, and it works on Google Podcasts, and should on others. This one was a bit too long, rather rambling, apologies, I'll try to stick to 30 mins total in future. If you're short of time, then skip the first 18.25 minutes, to get into the individual companies part.
Agenda -
Paul's Section:
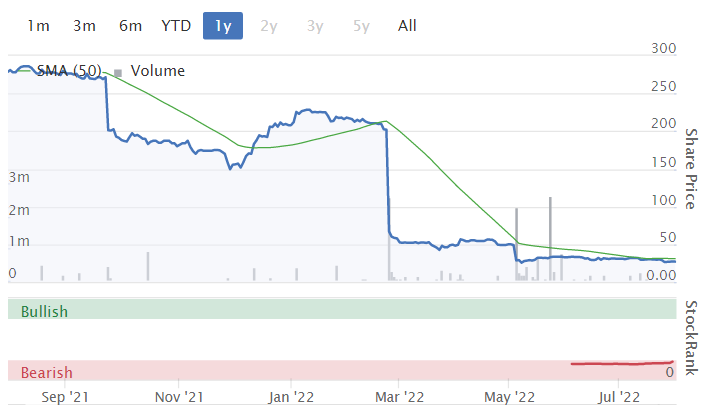
Seraphine (LON:BUMP) (I hold) - another profit warning, this is the 4th since it listed a year ago! However, I think the disappointments are already in the price, with it having joined the 90% club (down 90% since listing) in just a year, along with a lot of other opportunistic, over-priced floats in 2021. However, the business looks potentially very interesting to me - a long-established niche brand selling high margin, own-designed maternity wear. The experienced new CFO has a lot to sort out (including inventories being far too high), but a positive going concern note suggests the risk of a discounted placing may not be as high as I feared. Risky still, but if the turnaround works, then this could have multibagger potential I reckon. Although it has to be said, I do get quite a lot of these wrong, because nobody can predict the future, and riskier shares are just that - risky.
Belvoir (LON:BLV) - we're given an in line update today for H1. Everything looks fine. This is a really nice little group, well-run, and making acquisitions which are adding value. It's still reasonably priced too. Thumbs up from me.
Graham's Section:
Flowtech Fluidpower (LON:FLO) (£77m) - this H1 trading update says that performance is in line with expectations, but the broker says that strong gross margins are offsetting a weaker revenue performance, and the EPS estimates for this year and next year are cut by mid single digits. This company tends to be a solid performer: it now needs to work on reducing its debt, which has risen significantly in the post-Covid environment as the company battles with difficult supply chains by increasing its inventory pile. Looks fairly valued at current levels.
Correction - Trackwise Designs (LON:TWD) (£14m) - Just a quick note to say that last Thursday’s SCVR (now amended) had a typo: the “severe but plausible” downside scenario in which the company experienced a financial shortfall was outlined by its outgoing CFO Mark Hodgkins, and not by its CEO. Happy to clear that up.
Journeo (LON:JNEO) (£10m) (+2.6%) [no section below] - this previously traded as 21st Century Technology Plc (C21). For many years it enjoyed very little financial success, but it did report small profits in both 2020 and 2021. The company provides both products and services to the transport sector.
Today’s H1 update shows revenue growth of 23% and orders up 36%. Full-year results are still expected in line with expectations, and include a new £0.9m follow-on contract signed with a vehicle operator at Heathrow airport. Brokers are expecting profits of £0.9m this year (EPS 10.4p), on revenues of £18m.
The company has access to a £2.75m invoice discounting facility, and is forecast to finish the year with a modest net debt position. The major risks here are likely to do with customer concentration and lumpy earnings, given the small size of the company. These risks may be priced in at current levels, if you have confidence in the continuation of positive business momentum and can see expectations for 17p EPS being hit next year.
XP Power (LON:XPP) (£565m) - H1 was very difficult for this manufacturer of power products. The company suffered from component shortages, lockdown in China, port disruption, the general inflationary pressures, and even lost a jury trial in the United States (potentially very costly). Net debt has increased significantly and the company has reported a meaningful operating loss for H1, after everything that went wrong. More positively, customer demand appears to be resilient and when supply chains work properly, the company’s revenue performance should improve. Short-term outcomes are unpredictable but I still view this as a decent-quality company trading at a price that is depressed by some (hopefully) temporary factors.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul's Section:
Seraphine (LON:BUMP) (I hold)
27.25p (pre market open)
Market cap £14m
Seraphine Group plc, the international digitally-led maternity and nursing wear brand, today issues its maiden Final Results for the 12 months ended 3 April 2022 (the "Period" or "FY22"), against the backdrop of an extremely challenging year for the retail sector.
I’ll call this FY 3/2022, as it only just crosses into April by 3 days.
Key points (on an initial skim read. I need to go through it all again in more detail, when time permits) -
Very high gross margin of 63.2% (although down from even higher 65.9% last year)
High average basket value of £135 (up 6.5%) - it has pricing power.
Low cost of acquiring new customers, CAC of £16 (but since risen to £25.40, see outlook section)
Long-established niche in maternity wear, with limited competition, due to specialised fit, and limited market size - larger companies have tried this niche too, but often bow out, once they realise volumes are too low, and range of sizes is so extensive. Leaving the business for BUMP instead.
Logistics problems, especially with customer returns internationally - too slow (see poor TrustPilot reviews mention this as main problem) - mgt is aware, and working on solving this (I raised this issue in a call with the CEO a while ago).
Operates globally from single distribution centre in Belgium (Europe is largest market).
New CFO, ex FCCN & Asos, Lee Williams - who I see as a safe, experienced pair of hands, and he must see potential at BUMP, otherwise why join? But lots of things need sorting, this was a big weakness previously.
Adj EBIT £2.2m (down from £5.6m) - so still profitable, and adjustments are reasonable I think, given that FY 3/2022 figures include IPO costs and adjustments re high finance charges under previous private equity ownership. Clean numbers should look better in future.
3 profit warnings since floating, make that 4 now!
Shares floated at 295p, now in -90% club! Disappointing float, but is there value here now? It's a full listing, not AIM.
FY 3/2022 numbers -
Revenues of £44.0m, in line with guidance of £44.1m given on 5 May 2022, and is up an impressive 29% vs LY (last year) - in a sector where many online fashion businesses are struggling to report any growth.
Adj EBITDA of £2.6m (down 59% on £6.2m LY) - this is below guidance, which was “not less than £3m” - a bit disappointing, but not a disaster. “Final audit adjustments” are blamed. I can live with this, as the new CFO Lee Williams has only recently joined, and the former CFO was clearly out of his depth, so I would expect some odds & ends to get picked up under a new, more experienced CFO.
Statutory loss is massive, at £(33.9)m, mainly due to exceptional write-offs of intangible assets of £27.9m, and IPO costs of £3.5m. Bear in mind that this financial year includes the first few months when it was under private equity ownership, then floated on the main market in July 2021. So that distorts things like finance costs, which will be much lower in future.
There’s no getting away from the fact that this was a disastrous, over-priced IPO. One of many in 2021, as companies/brokers took advantage of the pandemic online boom, to stitch up fund managers with over-priced floats, passed off as structurally growing. However, the wreckage may contain some bargain nuggets of gold, and I think this could be one of them, possibly. But that’s dependent on a proper turnaround, and there are still headwinds facing the business - e.g. supply chain, logistics, higher marketing costs. These should be fixable issues, over time.
Outlook - previous guidance (from May 2022) was for revenue growth of 10-20% in FY 3/2023, and EBITDA margin of 8-9%.
Today’s guidance lowers revenue growth to 0-15% (sensible, given macro conditions), with the EBITDA guidance replaced with “expect to remain profitable”.
The final bullet point below is key, in that it reassures me no placing is imminent. I think this share could do well, if mgt avoid a dilutive fundraising. Note it is dependent on a £6m facility from HSBC.
.
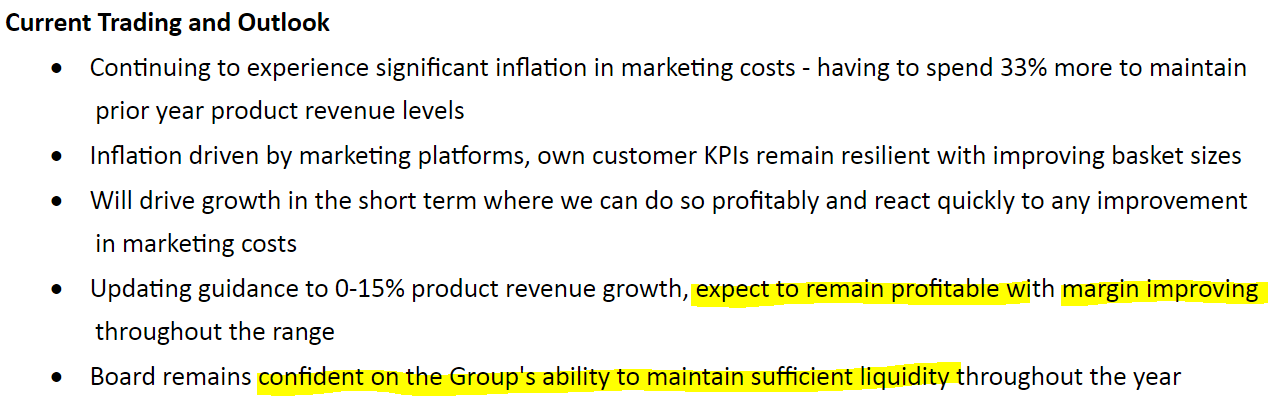
There’s more detail given in another outlook section -
Customer acquisition (CAC) has now risen to £25.40 (up 60% on LY), but this isn’t too bad considering average order size is £135 - should still be profitable from first customer order.
Q1 revenues - below LY Q1, but improving trend (June 2022 flat vs LY).
Customer returns - increased marginally in Q1 (no figure given), but offset by increased basket sizes. BUMP can afford customer returns, due to high margins, and high basket size, whereas fast fashion, low priced competitors struggle. BUMP sees free returns as all part of their service.
Management is focused on driving efficiencies and setting a strong base for profitable growth once the challenging external conditions subside. The recent reinforcement of the management team and the resilience seen in customer KPIs once exposed to the brand provides reassurance on the underlying strength of our proposition. We remain confident in the medium-term opportunities for the business.
[Paul: my bolding]
Marketing - interesting that digital marketing has become expensive, so BUMP is “redeploying budget to traditional marketing channels and partnerships” - this could have wider read-across - i.e. have Google & Facebook cooked the golden goose, by price gouging too much?
BUMP says it won’t chase short-term growth by increasing marketing spend.
Liquidity - this is key for me, as the main risk is a discounted placing being necessary. At least that doesn’t sound imminent -
The Board is confident on the Group's ability to maintain sufficient liquidity throughout the year.
Cash was £2.8m at 3 April 2022 year end, but £3.0m (half the HSBC facility) drawn down, so £0.2m net debt - looks OK. The going concern note says that £5m was drawn down in total more recently.
Going Concern note - very interesting to read, with lots of useful information in it. Although I think someone should have edited the wording, as in places it doesn’t really make sense.
The pleasing thing is, and bear in mind the auditors sign off on these things, BUMP should remain in compliance with its bank covenants, even in a severe but plausible downside scenario - thus making a placing less of a risk -
The Directors believe, after careful consideration of forecasted cash flows and expected trading performance that the Group will have sufficient cash to meets its liabilities as they fall due, no covenant breaches are also forecasted. The Directors have therefore concluded that it is appropriate to adopt the going concern basis for the preparation of these consolidated financial statements.
Balance Sheet - a big rise in inventories jumps out at me, with the commentary saying that was due to stocking-up to prevent supply chain problems. Even so, £14.7m inventories is a huge amount for the size of business.
At the reported 63% gross margin, those inventories (stated at cost, remember) equate to £39.7m revenues - compared with FY 3/2022 actual revenues of £44.0m! So it’s holding almost a year’s worth of product in stock - that’s insanely high. Retailers should be holding about 6-8 weeks inventories.
Even in current circumstances, I wouldn’t expect to see more than about 3 months inventories. So nearly a year’s inventories held at 3 April 2022 is way, way too high. Even allowing for the fact that BUMP has a lot of continuity ranges, that sell continuously. It’s less exposed to fashion trends than brands. Remember BUMP is serving a niche, of maternity & baby wear, not general fashion.
Does being over-stocked matter? Yes, because the suppliers will want paying for it! Usually about 60 days after the product has been delivered. Note 20 shows that BUMP owed supplies £6.9m for stuff that has been invoiced, and £4.4m of accruals (usually stuff that has been received, but not yet invoiced). So I think BUMP needs to urgently reduce its inventories, to generate the cash to pay suppliers.
It’s clear that managing supply chain is one of BUMP’s weaknesses. So I hope the new CFO gets a grip on this area. I’d say much tighter internal controls are needed over stock ordering by the buyers, to prevent such a large inventories position building up again in future. Meanwhile they need to sell the excess inventories. There could be write-downs, and a lower gross margin, if slow-moving items need to be discounted to shift them. Hence expect plenty of half-price sales online.
NAV is £20.4m, less intangible assets of £23.1m, and deferred tax of £(5.7)m, gets me to adjusted NTAV of £3.0m - a tad weaker than I would like.
Being over-stocked, and dependent on HSBC facilities, is not ideal. But equally, I wouldn’t want to see dilution in a placing, with the shares this bombed out.
Unfortunately, it was not floated with a robust enough balance sheet.
Hence there is some risk here.
My opinion - there’s a decent business lurking here, in my view. Disappointing performance since listing has been due to a range of factors, but poor financial controls and management seem clear - now fixed with an experienced new CFO, who I think should be able to sort things out, and refocus the business. That’s the upside case, on a completely bombed out share price, with market cap of only £13m - could this be a multibagger from here? If they get performance back on track, then it’s possible.
Very high gross margins and high average transaction value, show that it operates in a lucrative niche. Orders are profitable from day 1, and there’s limited competition. Seraphine has been around a long time, and is well-known for its stylish, special fit maternity wear. Many influencers have worn its products, including pregnant royals.
A handful of flagship shops are operated mainly for brand & influencer purposes, to have a key physical presence - that’s fine, as long as they don’t lose money heavily.
Most sales are online, and it has 3 key markets - Europe, USA, and UK. To achieve good sales in all 3 is a key point which impresses me - that this is a potentially scaleable international business, which could excite investors again in a future bull market - just like it did at IPO last year.
We’re now up to 4 profit warnings since it listed, including today’s, hence the share price being on the floor. So this is not a high quality, strongly performing company at the moment. It’s more of a value, special situation, turnaround type of investment. So, speculative essentially, hence it won't appeal to everyone. Although note that renowned shrewd investor Christopher Mills has been building up a position recently, with Harwood Capital at 5.1%. The shareholder register is still dominated by the private equity form which floated it, with 42.7%. I don't know what their intentions are.
It seems to me the key concern now is excessive inventories, which need to be greatly reduced to generate cash. As Far Eastern supply chains seem to be beginning to ease, that should be possible over time.
There is some risk here, but this share could be a good recovery candidate in 2013. I hold. Sorry for spending so long on a micro cap, but it's a key personal holding, so I would be digging deep anyway, so it makes sense to share it here.
Dear oh dear -
.
Belvoir (LON:BLV)
235p (down 1%, at 10:25)
Market cap £88m
Belvoir Group PLC (AIM:BLV), a leading UK property franchise and financial services Group, provides the following update ahead of publishing its Half Year results on 5 September 2022.
H1 performance (6m to 30 June 2022) -
Revenue up 11% vs H1 LY (despite tough LY comparative as FOXT & WINK have also said recently)
The growth has mainly come from 2 acquisitions, of financial services advisory businesses, now up to 301 advisers (from 243, 6 months ago).
Core underlying revenues (fees to franchisees) was up 1%. Within that, lettings growth offset sales reduction.
Net debt is £3.1m, down £0.9m from a year ago, despite paying out £3.9m for acquisitions - I like this a lot, self-funding more acquisitions.
Overall trading is good -
Consequently, the Board confirms that the Group is performing well and is trading in line with management's expectations for the year ending December 2022.
There’s a webinar on IMC at 16:30 on results day, 5 Sept 2022. Management came across well on previous webinars I think - they strike me as down-to-earth, competent, unpretentious, and experienced - ideal really.
My opinion - we like Belvoir here at the SCVR. Experienced management are methodically building a bigger group, as you can see from the Stockopedia graphs below -
.

.
The share count has roughly doubled since 2016, but that’s taken into account in EPS calculations, so this shows the acquisitions have added value.
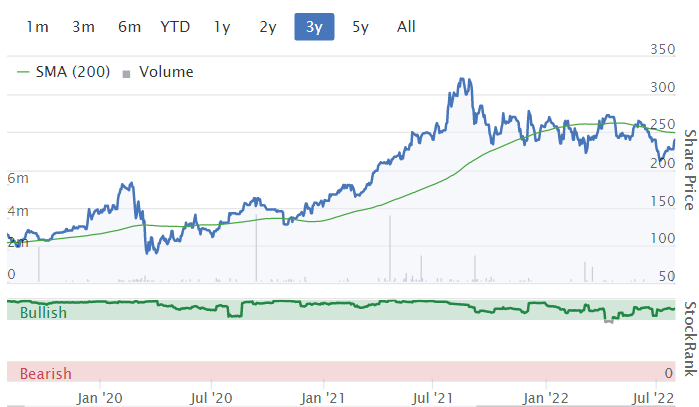
Some demand was pulled forward into 2021, hence the kink in the profits & EPS, but the long-term trend is very clear. This share has shrugged off the pandemic & cost of living squeeze. Rents are going up, so it should be inflation-protected too.
EDIT: Finncap has helpfully issued an update today, available direct or from Research Tree. No changes to forecasts, as I would expect, given it's an in line update. Looking at future years forecasts from Finncap, I think these look beatable. Hence very low risk of a profit warning, and more likely to be issuing ahead of expectations updates this year & next year, in my opinion. That's a key point right now, we have to avoid the banana skins by focusing on companies & business models that are set up to meet or beat expectations. There's also a useful graph in Finncap's note, showing the breakdown of activities. Financial Services revenues in particular stand out, as a big growth area for BLV that has flown under the radar a bit. End of edit.
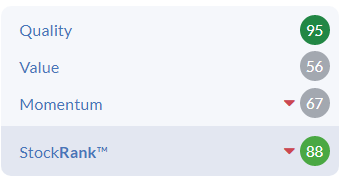
I think if you want a well-managed, defensive share, at a reasonable price, BLV is well worth considering.
Stockopedia’s algorithms agree -
.
.
.
Graham's Section:
Flowtech Fluidpower (LON:FLO)
Share price: 125.25p (unchanged)
Market cap: £77m
This is a supplier of hydraulic and pneumatic components to industry, and a provider of related services. Additionally, it “designs, manufactures and installs bespoke solutions” for its customers.
This H1 trading update is in line with expectations. Key points:
- Like-for-like revenues +4.8% (total revenues +4%).
- Net debt increases to £19.7m at the end of H1, leaving headroom of £5.3m.
The headroom is obviously looking a bit tight, and management are keen to assuage concerns:
Given the supply chain related pressures encountered in late 2021, which have continued into this period, we decided to continue our investment in inventory, which increased by £11m in the 12-month period to 30 June 2022… we expect a degree of unwind of this position in the remainder of the year as we benefit from a more predictable supply chain environment.
Paul also noted that FLO’s debt was rising when he looked at this stock last August. The rise back then was also attributed to working capital needs.
Outlook - inflation and the macroeconomic environment are mentioned, but the tone here is positive. The company has invested in e-commerce (if you want to see its main UK customer-facing website, click here) and is looking forward to “attractive returns” from its “broader e-business agenda”.
Estimates - I’ve checked the latest broker note, and it says that actually the company’s H1 sales performance did not quite meet its expectations. However, it is thought that stronger margins have offset this. Overall, due to an accounting change and economic worries, it cuts EPS estimates for FY 2022 by 3.9% (to 10p) and for FY 2023 by 5.4% (to 11.1p)..
My view - this is not a stock that’s likely to ignite strong opinions either way. In recent years it has been a solid performer, except for the Covid-impacted 2020.
The present environment is tricky for it but perhaps FLO can come through it better than the average company - as a distributor, maybe it can pass on price rises to its customers without too much complaint?
Its industrial end-markets are difficult to judge, but revenue seems to be holding up OK, despite possibly missing prior expectations for this year.
The balance sheet is also worth mentioning - if supply chains don’t normalise as expected, there must be a possibility that action will be needed to improve headroom.
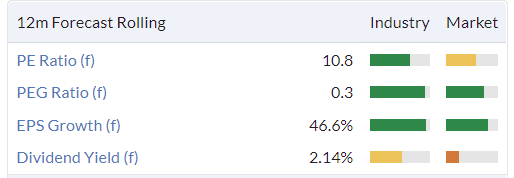
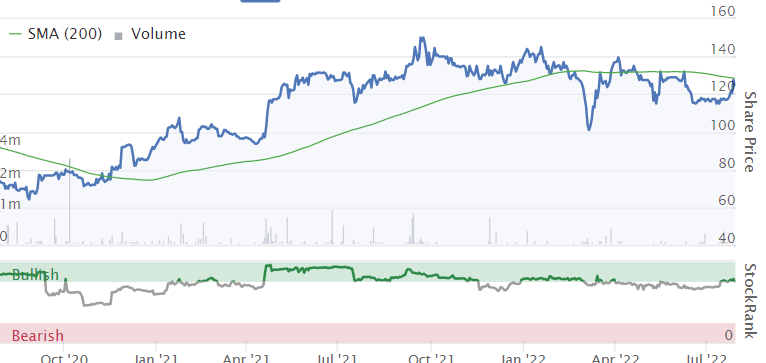
Overall, I don’t think this stock should be on a high PE rating and the market agrees, putting it on 11x next year’s EPS estimate.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

50 comments
Let me see Seraphine, IPO and Private Equity, no thanks. Less 90% possibly. Thanks for the write up Paul made the situation much clearer. But isn't it time we as private investors said NO to private equity taking the mickey? It is constant and we need to get smarter!!
Private equity aren't holding a gun to anyone's head forcing them to buy the future while PE are busy buying up dinosaurs like Morrisons.
Despite what the actions of fund managers may suggest
Paul , great analysis on Seraphine (Bump)
This looks all about stock turn and stock management .
We had a very simple internal saying “control the stock control the business)
As you correctly say a 12 month stock turn is pretty much beyond belief . For an online player should be maximum 4 times (even that is bad )
A key question right now is what is the provision policy against the stock file , I would have expected a decent provision on this level of stock but the implication is stock is still at full value so probably safe to assume there will be margin drop for the next 12 months .
I’m very surprised the new CFO hasn’t “kitchen sinked” it , meaning put a huge provision against st this stock and take the pain now, then at least margin will be maintained / increased on the next 12 months as the provision is released .
It would have certainly been easy to do and as incoming CFO / CEO actually make themselves look very clever as the current position with a full provision could be blamed on previous management and they could take the credit for the improvement.
I think further investigation of the stock file would give a better picture (aged stock / provision policy / out of range stock ) and without that it’s a bit hard to establish the current position .
I had similar once when I hired my first world class FD. He sat me down very quickly and said
Dave you have 16 million turnover, you have 8 million in stock , 2 million debt, and we can’t meet payroll . - your an imbecile and we are almost out of business .
I want a stock turn of 4 not 2 , then we will
- have 4 million stock
- have 2 million quid in the bank
- and it’s a great business .
It’s all about stock turn in a trading business , took me 25 years to learn this and a great FD to turn the lights on .
This is a great comment and I'm not disputing what you say :) But... yes they have too much stock, but from the going concern note I guess they think they can sustain it as they unwind. This is a "what would I know as a middle aged man" comment, but I don't think maternity wear has the same relentless fast fashion pace as other ladies wear so discounting is less of an issue and we saw at SOS that some niche markets the requirement to shift fashion quickly isn't as urgent. So, yes stock levels a worry, probably not as much as a worry as other fashion based businesses with the caveat the going concern note is doing a lot of heavy lifting here :) At least, that's what I hope having taken a position here :)
Good point but it’s more about having correct purchasing and stock control .
A strong FD in a trading business should not be allowing purchase orders to be placed that don’t have a stock turn within the boundaries he has set .
Paul is correct that stock turn should be 6 for Bump .
What this does is amazing, it will totally transform a business.
A very key point also is that you can bet your bottom dollar that HSBC who may or not provide the required funding will be all over that stock file, for sure they will provision it based on their own metrics - probably
- stock over 2 years - written off
- stock over 1 year old 75% mark down
- stock 6-13 months 50% mark down
And HSBC will run their numbers based on this detail - not the detail we have to hand , and if they aren’t happy they won’t fund it and then there will be the discounted fundraise.
So even if we aren’t able to get behind the stock file it WILL be pivotal to the business.
HSBC will be having lengthy talks with the new CFO who will be giving them monthly updates on the stock situation .
Control the stock control the business .
I totally agree - the new CFO should be able to sort this out. My point was about why they didn't kitchen sink, not that they weren't stupid to get into this position in the first place :)
Cathie Wood said “ Loud and clear “ this is a recession.
She never gets is right though!
I thought the US had declared two quarters of negative growth? Which is the definition of a recession.
Agree about KW though, complete turnip.
Now who do I believe – a JacketPotato or a turnip ? 8-) I know John Authers’ view today is that this is a bounce and there’s a lot more downside to come. 8-(
Many thanks for the look at Belvoir (LON:BLV) - this is a great little company in my view with good defensive qualities. Decent hedge against rising inflation given its link to rents, and the financial services side should also benefit from people needing to refinance their mortgages as rates rise. Should also do well in a recession as more people are forced to rent rather than purchase (and on a long term view I think the trend is very much towards renting). I also like the franchise model, which is not only low risk from the company's perspective, but also provides strong incentives for the franchisees to generate lots of business.
Good Afternoon (LON:DIA) Dialight PLC - Would appreciate Paul or Graham having a look at this one following todays market update / results - They are world leaders in LED Lighting for Commercial Heavy Duty applications (factories/plants etc) - with the best products and the need for customers to save energy I think this could one to watch ...
HALF YEAR RESULTS WERE OUT TODAY
HI,
Anyone know if Richard Leonard is still in Seraphine ( LON:BUMP )? Think he was a big investor at the IPO
Nice acquisition by SDI (LON:SDI) consistent with its strategy. I watched the recent presentation on www.investormeetcompany.com and admit to being impressed. I saw the company 3 or 4 years ago at Mello and failed to buy at around 40p. I have now ended up paying 160p or thereabouts!! Still never too late to buy into an excellent company especially when markets, particularly for UK small caps are depressed.
Also good updates from Belvoir (LON:BLV) (thank you Paul for the overview) and EKF Diagnostics Holdings (LON:EKF) Also I see that Chris Mills via the North Atlantic Smaller Companies Investment Trust of which he is CEO has purchased 500,000 shares in MJ GLEESON (LON:GLE) No one gets its right all of the time, but young Christopher has as good a record as anyone.
I hold shares in all of the above.
I realise Thinksmart (LON:TSL) is not often discussed but as a holder, 4.5% of my portfolio, I think the RNS on Friday last stinks my view being endorsed by MrContrarian.
I would appreciate the views of others who may have more knowledge than I have on this very strange decision by the Board of Thinksmart.
This is an excellent deal for the shareholders , especially the recent ones that got in around 25p and had as well a dividend of 2.35p paid to them!
The company is offering an exit with no discount in reference to the Block shares , whereas for the last 3 months this was trading at times even at 40% discount.
The company has no real operations anymore that might offer an upside on its share price.
For the ones that feel that the offer is a strange one they can easily buy the Block shares after the delisting of Thinksmart plc if they think they have a further upside in them. It is as simple as that.
Thanks
RE: Thinksmart (LON:TSL)
This is an excellent deal for the shareholders , especially the recent ones that got in around 25p and had as well a dividend of 2.35p paid to them!
I imagine the ones that were holders when they accepted the offer that secured the Block shares, when the price was hovering around 90p, or shortly after, are less happy. As the Executive Chairman gushed at the time:
"We believe this outcome provides our shareholders with an opportunity to continue the exciting Afterpay journey now directly with Block and we as a Board see continued long term value accretion with this outcome."
Long term, it turns out, is about seven months. Caveat emptor and all that.
If I was a shareholder I'd accept the offer and get myself as far away from this as possible.
However, the board pick up a nice bonus with a million shares vesting and the Executive Chairman ends up holding the Block shares, which he obviously continues to see value in personally. Which as this must be nearer the bottom than the top of the market is understandable.
timarr
I was talking about today’s events and prospects and not about something that happened in the past. Shareholders are given the chance to exit at a fair price and with almost no discount to the block shares. Great deal
Hi Paul can you have a look at OTB (On The Beach) as its share price has been taking a hammerings lately despite the industry is struggling to fulfill demands. I do not think under inflation cutting back on their holidays will be the first priority for the consumers given that the unemployment remains low.
Morning Eesha,
The agenda here at the SCVRs is driven by the day's RNS announcements - trading updates & results. I can't see anything for On Beach group (LON:OTB) today.
I last looked at OTB here on 1 June 2022, reviewing its interim results.
I'm amazed to see it has since almost halved in price, on no news. I suppose travel chaos at airports, etc, won't be helping sentiment, so the market is probably pricing in a profit warning? I see from the StockReport that FY 9/2022 earnings forecasts have dropped by two thirds -
.
The travel sector seems very bombed out right now, so for longer-term investors, maybe there are some bargains around?
Maybe OTB shares got too expensive pre-pandemic? Providing there's nothing horrible gone wrong with the business since, then it could be worth investigating now?
The last balance sheet at Mar 2022 was positive NTAV of about £74m, albeit with very large receivables & trade creditors. So we would need to understand how that all works. Also £99m in cash is shown on the balance sheet as "Trust account", which is strange, as I though customer funds in trust would be off balance sheet (as was the case last week with Foxtons (LON:FOXT) - although different sector, and maybe the travel sector has different rules?)
Anyway, do post your own views on OTB, I'd be interested to hear what people think.
I'll do a proper update when it next releases a trading update.
Regards, Paul.
thanks Paul for your valuable insights as always
Flight cancellations have been bad for On Beach group (LON:OTB)
They not only have extra customer service costs, but also extra costs like the cancelled hotels and transport and other activities they provide as part of the package. They have to offer to refund customers fully when one part of the Package is cancelled. Or find alternative flights etc (not sure whether airline foots this fully, or shared with OTB).
Therefore, I'm fully expecting that margins would be hit, and profits will disappoint, in their next trading update.
Then there's the knock-on effect, of customers now holding back booking more holidays, until the airport chaos situation resolves itself. So forward bookings likely have slowed down.
OTB focuses on short haul, "cheap" holidays, despite moving into more premium hotels and long haul recently. Majority of customers will be low-mid income, and those are the income groups being squeezed hardest by inflation for discretionary spending.
Yes, I think the business as a whole is strong and competitive in its sector, but its hard for one ship to sail against headwinds it cannot control.
I suspect also with On Beach group (LON:OTB) that the landscape has become more competitive with Easyjet moving into its own package holiday options, and others (such as booking.com, which now does flights/holiday cars etc) now offering a fuller package. I recall OTB's main airline partner was Ryanair who don't seem to be going down that route, and also seem to have a better handle on recent cancellations, so perhaps that is a positive for a forthcoming update.
All in, my sense is that I suspect buying On Beach group (LON:OTB) now will likely be profitable on a 1-2 year timeframe, but for some reason I just can't pull the trigger and buy it. I do also agree with Paul that it's rating pre-Covid was far too high, i.e. it never had any business trading on 25x+ forward earnings.
All the best. Will
During the pandemic it did not do badly either! It is now trading well below it's Covid low (around 1.25, now 1.07) and it bounced back well above others last year. I don't see any material changes here but who knows..
On top of my initial comment on On Beach group (LON:OTB) I forgot another reason why I haven't bought until now. If you look at the directors exercising options so far this year, all of them exercised and sold all. Not just partial to cover taxes and costs. Around the 210-230p range.
The current airport/airline crisis wasn't known back then (or maybe it was to insiders?)
So its a sign perhaps that insiders also think there's something rotten in the company. Otherwise, why would you not hold onto your shares? At that point the narrative was that travel was going to boom back over the summer, with pent up demand, etc.
However, could one argue that at 100p, it is now oversold? Maybe. At a 20%+ operating margin, paying just 1-2x revenues is not a bad price.
Thanks for the Seraphine (LON:BUMP) write up. We’ve seen some evidence at Sosandar how a decent CFO can turn things around in a short space of time. Tempted to stick a cheeky few hundred pounds here instead of the 4:55 at Carlisle
Hi MJP,
Funny you should mention Sosandar (LON:SOS) because there are some broad similarities with Seraphine (LON:BUMP) (I hold) I think - both addressing an under-served niche, with high margins proving they have pricing power & are doing something different/better than the competition.
BUMP got itself into a mess though, mainly due to lack of financial control in my view. So I agree with you that an experienced new CFO now in place could potentially work wonders.
It's so cheap at £13m mkt cap, but I am quite scared about the reliance on HSBC, and the huge over-stocking situation.
I've requested a call with mgt, to air my concerns.
Regards, Paul.
Mayfair Private Equity are the major shareholder in Seraphine (LON:BUMP) - were they the owners who floated it? If they were, do they have a lock-in period for their shares that may mean a share overhang that will hold back any price rise?
One year lockin. That's what's stopped me from buying in July. Was waiting to see if they would offload, even at this depressed price. Theyight be a forced seller if the fund their stake is held in has come to the end of its life and needs to be liquidated.
Hi Boon,
I can't imagine that the 42% shareholder in Seraphine (LON:BUMP) would try to dribble out shares in the market, that would be pointless, as there isn't the liquidity.
Hence if they do sell, I imagine it would be placing blocks of shares with institutions, hence would have no impact on the market price.
The price is so low now the whole company is only valued at £14m, that I don't suppose its remaining holding in BUMP will be of much interest either way, being worth only about £6m.
A linkedin page for Mayfair Equity PartnersLLP says they control over £1bn in assets, hence BUMP would now be under 1% of their portfolio.
Who knows, they might still be fully supportive of BUMP? Would be good to find out, but I don't suppose they'll be telling us either way.
Regards, Paul.
Very good points. And they might have just rolled over their position in Seraphine (LON:BUMP) into another fund they have.
Ref. Seraphine (LON:BUMP) I don't follow the argument that "placing blocks of shares with institutions ... would have no impact on the market price". Surely any significant volume of sales is going to affect the overall demand and supply balance and hence impact on the market price?
I can see that a managed sale to institutions will allow that effect to be better managed and result in much less volatility than dribbling out shares in an illiquid market. But I wouldn't imagine institutions will be prepared to provide this service 'for free'. They will expect to make a return and most likely obtain that through buying below the market price and then selling on. I just don't see how this could be price neutral.
Perhaps I have misunderstood.
Paul big buy in MJ GLEESON (LON:GLE) 500k shares harwood
Hi Paul et al. I would be interested to hear your views on the half year results today from XP Power (LON:XPP) . I wonder if this has now lost it's star quality. Whilst the order book is up, margins are down impacted by various issues such as supply chain. However with the legal case loss to Comet with 40m at least to pay plus the recent acquisitions there has been a notable rise in debt and debt facilities. Once the Comet case is settled this pushes up further the debt to EBIT ratio, pushing it away from my comfort zone.
Also, in terms of working capital inventory turn has decreased with inventory levels now higher as a % of revenue than in the prior half year. Logistics issues maybe? The only positive I can see as a holder is the dividend being maintained at the same rate as last year. Mind you I've never really held this for the yield so would sacrifice that if debt levels were brought down quickly.
I'm currently mulling the sell button but will see what direction the share price goes in the next few days, whilst the initial market makers reaction dies down.
Hi wildshot. Whilst the increasing debt levels at XP Power are understandable, like you, I find them discomforting at a time when other financial parameters at the company are also worsening. It also appears that XP's manufacturing capacity is being expanded as production is being limited by component shortages. The bulk of XP's volume manufacturing facilities are in China, Vietnam and Malaysia (the latter is still being built) yet almost 90% of its revenues are from Europe and the US so this must have potential for logistical problems in the current environment where onshoring seems to be increasing popular. I previously regarded these facilities as a strength of the company. I am tempted to play safe and cut my losses here as I am not convinced that the company's difficulties will be solved in the short or medium term.
A few weeks back the S&P 500 was down at 3666 .... Paul said enough is enough, its time to start buying. Since then the Fed has put rates up 75bps but the market no longer thinks they are behind the curve and markets have rallied. The yield curve has inverted suggesting the current tighter financial conditions will do the trick.
In March 2020 the market rallied strongly in a straight line after unprecedented Fed policy response to Covid. At this time the fed has the reverse policy in place. The market has rallied despite this because the perceived victims of a recession were treated brutally. Furthermore the beneficiaries of the virus ( many tech) have had a difficult time matching market expectations for earnings. This trend played out quickly and caused a 20% + fall in the US....much less in the UK. We have now reclaimed more than half this. I have no idea whether this can continue .... but since we have the reverse Fed policy in place, and the UK will likely raise by 50bps this week....I suspect a different outcome to 2020.
In the last week Banks earnings in the UK market have been positive, and caused upgrades. The stocks have reacted well. This is positive for the UK market. Its also positive for the value trade. However resources stocks are doing the reverse reflecting weaker conditions in China. Apart form the Banks, the cyclical consumer stocks and small caps have been a real mix and somewhat disappointing in this rally. I put this down to the prospects of recession has now weakened the expected recovery. Classic defensives like tobacco and telco have started to weaken. Based on trends in banks I would suggest the consumer may not be as weak as stock prices suggest.
My view is the rally is getting long in the tooth, it doesn't mean its over but markets are somewhat trapped....since if they go much higher then this loosens financial conditions and weakens the argument that the Fed is done. Much more likely is the Fed doesn't do much .... and neither does the market. A churning stop start period could easily unfold from here.... which means its a stock picking market and if earnings disappoint so will the stock. It goes without saying that if you believe you are sat on stocks likely to disappoint then its probably time to get out.
For the past decade we have got used to the US economy bouncing back quickly due to Fed policy. Inflation trends suggest to me we have reached the limits of this. Therefore we now need a period to adjust...and invest ... to create capacity. So in contrast to the last decade it suits the Fed if the economy remains a little weak not the reverse. Especially in the run up to mid terms...
In summary I hope everyone has enjoyed the rally but now is the time to redress nagging portfolio issues whatever they maybe. The Autumn earnings season is likely to be tricky....and throw up some bargains ...so for me cash isn't trash... and Im happy to have more not less from here.
I enjoyed your rambling Paul :) . Thanks for going to the trouble of making these informative podcasts
Likewise Paul, I find the podcast very useful. Here are my reasons: sometimes I struggle to keep up during the week and the weekend summary not only lightens the monotony of whatever menial work I'm doing at the time, but more importantly it's something I can pay attention to while doing said work below my desired station in life. I've quickly started to use the weekend summary to help provide extra direction/ priority to any particular follow-up research I might want to do, so it's a filter that means I don't have to trawl back through all the SCVR's for the week but can hone in on matters of interest. I do like the helicopter/ macro musings as well, we all have them and it's good to hear another view. I'm sure there are other things you could be doing instead at the weekend but if it's useful to you then it's gratefully received by me personally. I'd also add that weekends are when I do a lot of my share research/ thinking so the timing of the podcast is good. Thanks.
I'll add my tuppence to the thanks for the Podcast - and please don't worry about sticking to a particular time limt. if you have things you'd like to say - I'd prefer to hear them - especially for your macro thoughts,
I'm not a natural fan of audio/video - so I am quite suprised to be finding them such easy and useful listening. Keep going you never know - you might end up alongside the shipping forecast :-)
cheers
Mark
Thanks for all the feedback on my podcasts, much appreciated! :-)
Classic bolt-on acquisition from SDI (LON:SDI) this morning. Progressive Research have increased their EPS estimates by 3.3% for current FY (to 9.4p), and 4.4% for next (to 10p). LTE makes sterilsation equipment. Whilst LTE is well asset-backed, it looks like the funds will mainly come from undrawn bank facs.
Any comments or analysis on National World (LON:NWOR) would be appreciated. It has bounced off recent lows, but appears extraordinarily cheap given the cash position, performance trend and management capability. No pension scheme and digital appears to be growing nicely - both weak points for Reach last week. Clearly headwinds with inflation, and print decline. Typically this share bounces on results before retracing to new lows. I am not sure I understand why.
Morning BE70,
Yup we've got National World (LON:NWOR) on the list.
To give you all an idea of what we're likely to cover today, here is our agenda googledoc so far ...
this is perfect, avoids people saying "can you do ABC trading update..."
Abcam (LON:ABC)
Hi Paul, Graham,
You might remember Journeo (LON:JNEO) being brought to your attention a couple of months ago.
I hold this speculative tech small cap because they are operating in an interesting area optimising transport via information systems. They also appear to be profitable and growing organically.
I wonder if one of you would like to cast your eye over todays update and financial position.
I continue to hold and remain confident about their medium/longer term future. I do wish they would stop saying in line with management expectations without really saying what they are. Seems from their interims though they are growing about 20% and starting to become profitable/cash positive
Thanks Revs8 - sounds interesting, so I'll add it to the list :-)