Small Cap Value Report (Mon 1 Feb 2021) - FNX, 5 new listings, BIDS, PRV, ZYT

Good morning, it's Paul here with the SCVR for Monday.
Timing - I've covered quite a lot this morning, and am taking a break for lunch now. More later. Update at 18:23 - today's report is now finished.
Agenda -
Fonix Mobile (LON:FNX) - I looked at this one over the weekend, an interesting-looking recent float (Oct 2020)
Brief thoughts on vaccinations progress
5 new companies intending to, or actually listing, reviewed in brief
Bidstack (LON:BIDS) - 2020 trading update (needs a placing)
Porvair (LON:PRV) - quick review of its FY 11/2020 numbers
Zytronic (LON:ZYT) - Tender Offer, and (previous) trading update
.
Fonix Mobile (LON:FNX)
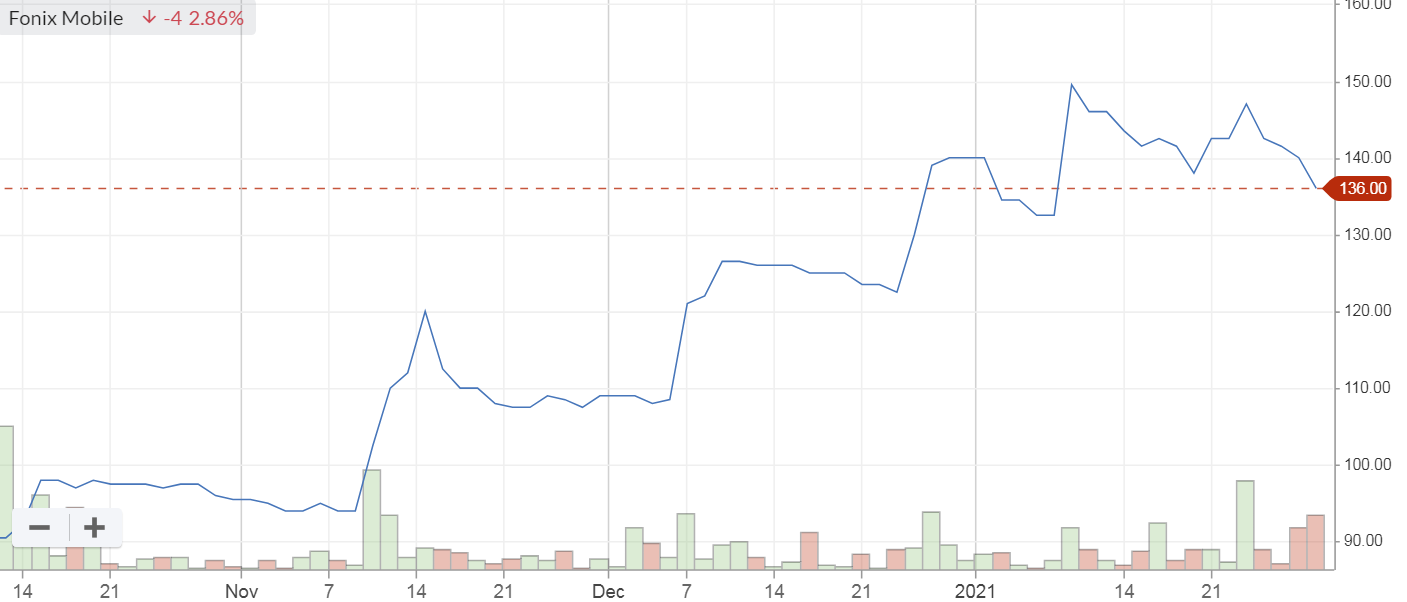
Share price: 136p
No. shares: 100.0m
Market cap: £136m
Several readers mentioned Fonix last week, which jogged my memory to look at it over the weekend.
Fonix listed on AIM recently, the first day of dealings was 12 Oct 2020.
I must have been rather bored around that time, because I recall spending a Sunday evening reading its Admission Document, but never got round to typing up my notes, so belatedly here they are;
Floated at 90p
Placing of 50m shares, half the total, to raise £45m for selling shareholders - i.e. no fresh money raised for the company itself. Therefore the IPO should be seen as a half-exit for existing shareholders, which I’m generally not terribly keen on in an IPO
Directors sold 36m of the 50m placing shares, being about half their personal shareholdings
Paid big divis prior to the float, £6m in FY20, and £5m in FY19, so it’s a proper business, generating real cashflows, which is what aroused my interest in the company
Rapidly rising profit before tax:
FY 06/2018: £2.8m
FY 06/2019: £4.7m
FY 06/2020: £7.3m
Recent trading (at time of IPO) in line with expectations
Dividend policy to be 75% payout ratio (of earnings, I presume?)
Balance sheet - weak at only £2.4m NAV
Cashflow unusually high in FY 06/2020 - not sure why
Development spending - only low level of capitalisation into intangibles, which is good
High trade payables
Deferred payment to a charity of £3.9m - this was explained later as being for some technical reason at the request of the charity concerned, so not a problem
Notable institutions buying, mentioned in prospectus: Slater Funds 10.2m shares, Kestrel 4.0m
Questions arising from my review;
- Client risk? Top 10 clients are 83% of revenues. Impact of losing biggest?
- Why sell half the company if the future is so bright?
- How are they going to create any market liquidity in the shares, by placing them in large lumps?
- Barriers to entry? Competitive landscape & threats?
Overall - I like the look of this business, and want to investigate further. It’s a decent, cash generative business, in a profitable niche. Management have an impressive track record & still hold a large stake in the business (over a third) after the shares sold in the float.
Some time later, I touched base with Fonix’s advisers, who kindly organised for me to talk to the company late last year. This was part briefing, part Q&A. Here are my notes from that conversation;
Rob Weiiz, CEO & co-founder
Background in telecoms startup 2005/6 - sold for $75m in 2011
Boku & Bango mentioned, good strategy (I can’t remember the context for this remark, sorry)
Fonix is focused on the UK
Launched in Jan 2014
Messaging/payments company for mobiles
No debt, and not much capitalisation of development spend
33 staff, of which 14 are developers
Lots of runway for growth
Goal was to achieve a return - ie. partial sale at some stage, hence the AIM listing
Richard/Rupert are AIM veterans, CEO not previously involved in a float
Fonix shares should provide income (divis) and growth
Continue to pay divis
Question - if the future’s so bright, why are you selling half your holding? Answer - that was always the strategy. Options pool for loyal staff, been with us many years. Additional credibility with clients & potential clients, becoming a plc listed company
Not regulated by FCA (?)
Children in Need - big client, £12.5m revenues last year to Fonix, who processed 73% of all donations
Very sticky clients - never lost one
Fonix is closely integrated with clients & their systems, so don’t want upheaval of changing suppliers
Profit margin is 4-5%, which looks high to me for payment processing, but reassured this has proven sustainable in the past
Focusing on reducing basket abandonment by customers, and mid-tier operators like ITV
Brilliant team, lots to go after
My overall impression of CEO - seems lucid & straightforward.
Good, that’s some background, now onto the first trading update since the float.
Fonix Mobile plc is pleased to provide a trading update for the 6 months period to 31 December 2020.
This update was issued last week, on 29 January. Fonix has a June 2021 year end, so this is an update for H1. The company’s financial structure did not change in the IPO, so apart from one-off listing costs, there shouldn’t be any other adjustments needed.
Impressive growth here, and I think this is all organic too (ie. not boosted artificially from acquisitions) -
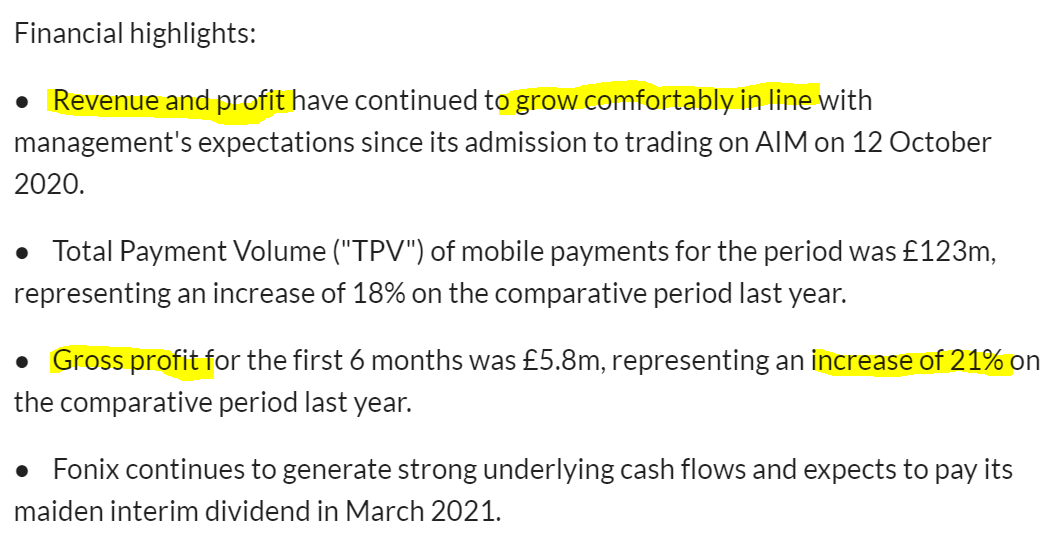
Other points -
- All 3 business segments have grown, in line
- Operating costs unchanged (so should be nice operational gearing to profits)
- New customers, and robust pipeline for H2
- Children In Need raised £13.9m through Fonix (up on £12.5m last year)
- Diary date - 22 Feb 2021 for H1 results - good prompt reporting
Outlook - confident
Broker update - see Finncap’s note from 28 Jan 2021, many thanks for providing us with this. Unlike some other antiquated brokers, Finncap “gets it” - i.e. that small cap investors need information and forecasts to help us form a view on a share. That then improves liquidity, and increases the market cap, if there’s a good investing proposition.
Forecasts are adj EPS of -
6.8p FY 06/2021
7.6p FY 06/2022
The forecast for the current year looks too low, given that H1 has out-performed, and also Finncap’s figures don’t seem to build in any operational gearing from the costs being flat against last year. So I’m thinking that a fairly decent beat against forecasts could be on the cards here.
Therefore the PER of 136p/6.8p of 20.0, is probably over-stated. I reckon 8-10p EPS might be more possible, which would be a PER of c.14-17 - quite reasonable in an expensive market.
My opinion - this looks a very decent growth company, and sensibly priced.
Finncap points out that other payment processing companies are much more highly priced.
My main hesitation here, is that there could be risk from one or more big clients making alternative arrangements. This year in particular, there could be cancellations of big TV shows, possibly? Hence I’d rather sit on the sidelines, and see how 2021 plays out.
But overall, it’s one of the better small cap floats I’ve seen in a while, so it could be worth readers spending a bit of time to research it yourselves.
.
.
Vaccinations & re-opening
Stunning news over the weekend over the progress of the UK’s vaccinations, this is really heart-warming. Nearly 600k people vaccinated on Sunday alone, taking the total to c.9m now vaccinated.
Market confidence seems to be ebbing & flowing on a daily basis, re covid. However, the rapid fall in new cases, combined with most of the vulnerable now having been vaccinated, has reinforced my optimism that we’re probably soon going to be over the worst. Then gradual re-opening & relaxation of restrictions.
For that reason, I’ve been topping up my Saga (LON:SAGA) (I hold) position this morning. The recent drop from c.300p to c.250p looks like an opportunity to me, given the positive update last week. The only fly in the ointment is the current negotiations to relax banking covenants. However, how many companies are hitting a brick wall on that? None that I’ve seen. Lenders are being co-operative. Why wouldn’t they relax covenants, when interest rates are this low, and there’s light at the end of the covid tunnel? Hence I feel that SAGA could get a double benefit, from agreement on covenants, and then resumption of travel. It’s not without risk, but to my mind, if I’ve weighed things up correctly, then risk:reward seems highly favourable.
As always, it’s essential to always do your own research, as the future may not pan out how I think it will, there are always uncertainties, with everything.
.
New floats
There are an unusually large number of new companies announcing their floats today. I think the London market feels a bit stale right now, and definitely needs some new blood, so I welcome good quality new floats. Here are today’s newbies, I’ve put in links so you can click through to any which might float your boat;
NextEnergy Renewbls - Intention to Float - an IPO to raise up to £300m for investment into renewables infrastructure. It intends to pay divis, and achieve capital growth. Renewable energy is certainly a booming investment area. How to pick a winner in the field though?
Digital 9 Infrastructure - Intention to Float - is hoping to join the Main Market, priced at 100p, to raise up to £400m in an IPO. Prospectus due in March. This is a newly established investment trust. It will invest in internet infrastructure;
The portfolio will comprise future proofed, non-legacy, scalable platforms and technologies including (but not limited to) subsea fibre, data centres, terrestrial fibre, tower infrastructure and small cell networks (including 5G). The Company will focus, primarily, on digital infrastructure investments which are operational and with an existing customer base.
It will be managed by Triple Point Investment Mgt LLP, an experienced manager.
MGC Pharmaceuticals - Intention to List - “working through now the final steps” to join the Main Market. Dual listing (London & Australia). Expected to complete in February. Operates in cannabis sector. Tiny company, revenues in 2020 of AU$2.1m. Floated by Turner Pope. Moving on…
Auction Topco - Expected Intention to Float - Auction Technology Group - claims to be the operator of world-leading online auction marketplaces, operating 6 websites. Claims that its “proprietary technology is a key strength”. Revenues of £52.3m in FY20, so quite small. £22.3m adj EBITDA. No mention of what proper profits were! Partial exit by existing shareholders.
Edit - sorry I’ve just found more detailed financial information further down in today’s update. The figures don’t look great - it seems to have made escalating pre-tax losses: 2018 £(2.9)m, 2019 £(7.5)m, 2020 £(18.5)m. The balance sheet looks horrendous, stuffed full of debt, and intangibles, so hopefully that would be sorted out in the IPO, as it would be bargepole job as it stands.
I’ll keep an open mind, and wait to see the Admission Document for more detail. At this stage though, it doesn’t look much good.
Supreme (SUP) - last new company, this has actually listed today, AIM Admission & First Day of Dealings -
Supreme, a leading manufacturer, supplier and brand owner of fast-moving consumer products… Supreme supplies products across five key categories; batteries, lighting, vaping, sports nutrition & wellness, and branded household consumer goods.
It’s raised £7.5m in new money, and £60.0m for selling shareholders, at 134p per share.
The AIM Admission Document is here. Whilst these documents look daunting at first, they’re worth a thumb through, you only have to skim the key bits, which only takes about 10-20 minutes, not read the whole thing. Then if it looks interesting, re-read it more carefully (especially disclosures at the back, which can be interesting!).
I’ll possibly have a look at this later, once more urgent things are done.
.
Bidstack
down 31% today - mkt cap £29m
A highly speculative company, with an interesting product - advertising within computer games.
Trading update today for FY 12/2020.
Big % rise in revenues, but from a low base £1.7m (LY: £140k), so a very early stage business
Loss before tax increased to £(7.18)m (LY: £(5.36)m) - awful
“Available cash” of £2.76m most recently, at end Jan 2021
Commentary throws in a few big client names & generally upbeat words.
This sounds concerning - an opportunity, or just under-performance? You decide -
Bidstack has now run native in-game campaigns in over 30 countries. While this undoubtedly proves the system works, in 2020 fill rates for native in-game advertising remained in low single digits. As the Bidstack sales team matures there remains significant scope for organic growth.
Pandemic is lengthening sales cycles
Anyone know what this means? -
To address this, Bidstack's strategy will be to concentrate on the appropriate implementation of its technology even if this is at the expense of some short term opportunities.
Claims to be the leader in its field.
My opinion - today’s update dodges the big issue, the elephant in the room - that it’s rapidly running out of cash. Rather than ignore this, the update should have said what the company is doing to raise the next wave of cash funding?
We’re in a bull market, so I imagine another placing should be do-able.
Bidstack won’t be able to get its 2020 accounts signed off without another fundraising, so there’s probably one already underway, in secret, I imagine.
If this is going to work, then the company needs proper funding, i.e. £20m+, enough for 3 years or more, in my opinion. Lurching from one placing to another, is a hopeless way to fund jam tomorrow companies, but all too often that’s what happens on AIM. Why be a lamb to the slaughter, in funding early rounds, when you know the company will need repeat funding, often at lower & lower valuations, as targets are inevitably missed by practically everything of this nature that lists?!
I don’t want to take a risk on this, whilst it has an obvious funding requirement in the short term. The market cap is far too high, for something that’s a pure punt at the moment.
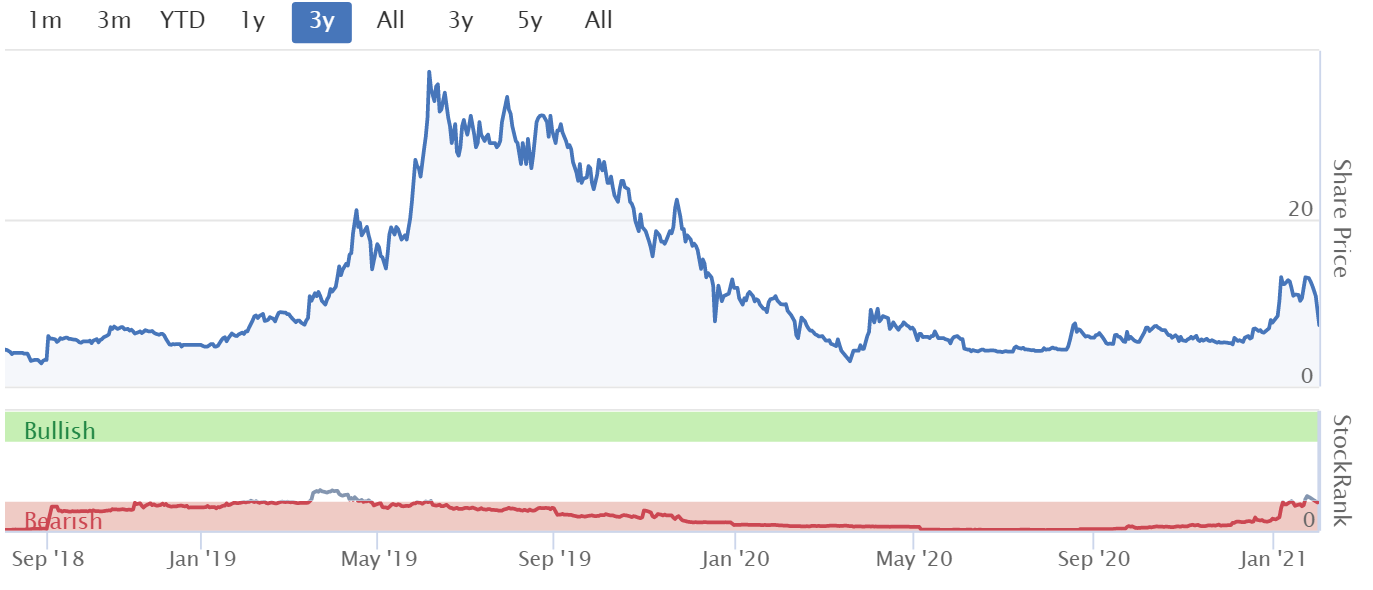
Note the speculative frenzies that this share attracts from time to time, 3 year chart below. Also note the resolutely poor StockRank, with the Stockopedia computers reminding us constantly that this is a jam tomorrow, loss-making share, hence usually poor risk:reward for that category of share, on average.
.
Porvair
down 4% to 530p - mkt cap £245m
For FY 11/2020
Resilient performance in challenging circumstances, optimism for the future.
Considering what a badly disrupted year it was, these numbers do indeed look resilient, as the company claims.
- Revenues down 7% to £135m
- Adj profit before tax down 15% to £12.6m
- Adj basic EPS down 14.6% to 21.6p - a PER of 24.5
- Dividends of 5.0p (up slightly), yielding a modest 0.9%
Outlook -
"Until the pandemic recedes, near-term trading remains unpredictable and the Group continues to withhold earnings guidance. But the results for the year turned out to be better than initially feared in our contingency planning…
We entered 2021 with a strong balance sheet and a lower cost base than a year ago, which will be helpful while we wait for vaccinations to bring the pandemic under control. The next few months may continue to be difficult, but beyond that we are increasingly optimistic.
Investments made over the last few years will help margins and our new product development pipeline is strong for the near term.
Prospects for the medium term are good and Porvair should return to its historical levels of growth once the pandemic retreats."
Results presentation slides (only 15 pages) are worth a look, here. This is much easier than ploughing through the whole RNS, so I’m skimming them now. Nicely laid out & good info.
Balance sheet - looks sound overall.
Investors will need to adjust the valuation downwards to take into account the cash outflows related to the pension deficit.
Cashflow - looks OK. Note that it's spending about a third of cashflow on capex. It made an acquisition (£9.8m) last year, so that might be flattering growth figures a bit this year.
My opinion - this is only a quick review of the figures, I haven’t ploughed through all the detailed commentary, otherwise each company would take me hours to get through.
I do quite like this business. It’s always looked expensive, but the rest of the market seems to have caught up, hence PRV no longer seems particularly over-valued. Once you factor in a recovery from covid, then EPS might rise to say 25-30p, helped by reduced costs, meaning that a share price of possibly up to 600p might be justified in due course. That’s a bit of upside on the current 530p, but not enough to get me excited.
I’m impressed with how resilient profitability was in 2020 (looks in line, or slightly above forecasts), so Porvair has proven itself as a safe haven if similar events were to recur. That justifies a premium on the price. A lot of its products are specialised consumables, hence demand continues regardless of the macro situation.
Overall then, it gets a thumbs up from me, as looking a sound, fairly safe investment for the long-term, but not something I feel the urge to rush out and buy now.
A possible bid target, I wonder?
Directors seem rather too fond of cashing in their share options. I thought the whole point of share options was to enable them to build up long-term meaningful stakes, not to be a lucrative bonus scheme?
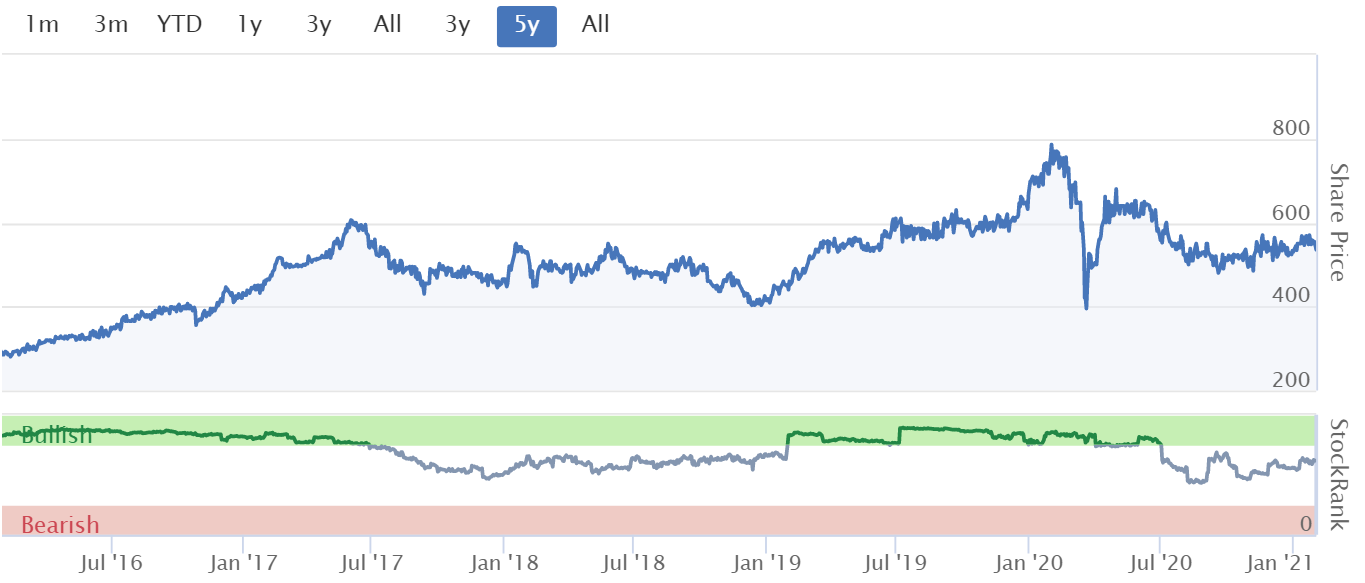
Sideways trending share price since mid-2017. So is it actually as good as people think? Particularly as very little has been paid out in divis over that time.
Excluding acquisitions, is this actually a growth company at all?
.
.
Zytronic (LON:ZYT)
140p (up 6%) - mkt cap £22m
Tender offer at 145p (sorry, earlier typo corrected)
This is a method of returning £10m surplus cash to shareholders. You can tender as many shares as you hold, but the basic entitlement that's guaranteed to be paid out at 145p, is 43%.
The idea is that the share count will drop by 43%, so you'll still own the same % of the company as you did before, if you tender your basic entitlement of 43%, but will have received cash for the shares you tender.
Companies can pay out excess cash to shareholders through special dividends, buybacks, or tender offers. Maybe a tender offer is more tax efficient, I don't know.
It's a sensible move, as the company built up far more cash in the good times than it needed, and wasn't doing anything with it, so this makes sense.
This is how it would look (at 140p per share, being the current share price);
Before tender offer: 16.0m shares in issue, market cap £22.4m
After tender offer: 9.1m shares in issue, market cap £12.7m (and the business would still have c.£4m net cash remaining).
Of course there's no guarantee the share price would remain at 140p. Once the tender offer has been done, the share price would freely float again. A tender offer tends to anchor the share price in the short term, whilst it's underway.
If you hold ZYT shares, your broker will write to you, asking for your instructions on how many (if any) shares you want to tender. It's up to you whether you find the tender offer price an acceptable price to sell at, or not. This sums it up neatly, from the announcement today -
Qualifying Shareholders may choose whether they want to tender some, all or none of their shareholdings, and are not obliged to tender any of their Ordinary Shares if they do not wish to do so.
.
Trading update - issued on 22 Jan 2021.
Zytronic, a leading specialist manufacturer of touch sensors, provides the following trading update.
I reviewed its accounts for FY 09/2020 here on 8 Dec 2020. Even though sales have crashed, it's reduced costs mean it looks to be trading at a run rate of a bit below breakeven. Therefore it should survive, and who knows maybe win new orders, and start to rebuild profits? That's the bull case anyway.
Today it says -
The downturn in sales experienced in the second half of last year has now levelled out at approximately £2.0m for the quarter to 30 September 2020 and the first quarter of this financial year to 31 December 2020.
That's ambiguous wording, but it means a run rate of c.£8m p.a. revenues - way down on historic levels, in the twenty millions.
Outlook -
... However, with the constraints imposed by the Coronavirus pandemic, that are affecting our major overseas markets such as Gaming, it is difficult to foresee a return to profits in this financial year, and a recovery to historic levels will depend on how quickly there is an effective vaccination programme enabling a return to normality.
My opinion - my worry is that the share price might slip back down again after the tender offer.
A further worry is that Zytronic will be such a small business, revenues only c.£8m, trading at a small loss, that why would it remain listed on the stock market? What's the point of all those costs & hassle of maintaining a listing, when they do nothing with it?
On the upside, it should still have c.£4m net cash remaining after the tender offer, and there could be upside if it wins new orders & returns to meaningful profitability.
The real reason this company has done badly, is not covid. It's end of life products. It needs to win new business. Since I can't possibly predict if/when new orders would be won, then I've got to say I'm neutral on this share, and personally would be inclined to tender at least the 43% basic entitlement, if I held any (which I don't). For larger holders, the tender offer is a liquidity event which may never repeat, hence I imagine institutions would be likely to tender all their holdings, thus leading to over-tendering, and scale backs on the excess.
.
I'll leave it there for today's report, and we'll hit the ground running tomorrow morning with some additional sections from today, which I'll write up this evening.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

97 comments
I honestly cannot get my head around BIDS technology; by this, I mean how the gamer immersed in the game is going to make BIDS make any money? Or should I say, the advertisers using the platform? You may argue the same can be said for advertising at a live sports event's has the same problem. Is it just trusting human habits on subliminal messages adverts embed into our minds?
Even if I was to answer my own questions, I would not invest in a company that leads its investors up the garden pass as frequently as BIDS has.
Sorry Paul
Postscript
My children like you dash off a reply in seconds
It takes me hours.
Hi Paul
Thank you Sir for your reply.
I hope having watched in silence ,for a long time, and being in truth a bad investor, until I recently discovered/tried to implement, Stockopedia .
I am getting better.
Also then trying to get my head round buying expensive/momentum stocks (behavioural bias ), I hope that you are wrong on the issue of Lookers .
Why, the facts change and then I change my mind .
You have a better knowledge than me of account matters, but I believe now that this is the cleanest set of books that you will come across. They paid enough to the accountants to make sure. New management, new conventions,
Could you rethink your facts ?
I am still trying to buy low, hence building up a position in Saga . Re Saga I believe your analysis is 100% correct, but perhaps too optimistic re Covid timetable, and cruises.
The more I read your thoughts and history, the more I like your moral worth.
Yes it is about money, but sterling character is more important.
Thank you for your reply.
Sorry old person typing with one finger-takes ages
Best wishes
Tender offer.
As a newbie I was confronted with this by Venture Life and also Shanta Gold if recall. Both after reasonable press announcement's but 'bombed' thereafter. Dipped into Reddit over weekend and Wallstreetbets - between the computers, money and social networkers do not feel in an investable place. But believe the small person can dip under the radar and 'nick a few quid' - maybe. Good fun though if don't have a job!
Paul
The only fly in the ointment is the current negotiations to relax banking covenants. However, how many companies are hitting a brick wall on that? None that I’ve seen. Lenders are being co-operative.
I think Card Factory (LON:CARD) is perhaps the exception where they have simply been given a 30 day stay of execution.
As you say though banks have generally been supportive i would agree - which is great to hear when we compare back to the nightmare that was 2008 in that regard.
Hi rmillaree,
Yes indeed, Card Factory (LON:CARD) is a good example that you gave of a company where the bank is probably leaning hard on them to do an equity fundraise, hence just a 1 month extension of the covenants. That rings alarm bells to me, and could mean an emergency fundraise at a deep discount, if institutions don't like the idea of refinancing it. So very high risk I'd say.
CARD management missed their chance to refinance last year, when lots of other companies were doing placings, was it around April-May 2020? It was obvious pre-covid even, that CARD had too much structural debt, and had been paying excessive divis, so it has no balance sheet reserves to fall back on. Management gambled that the cashflows would keep pouring in forever, which we have since found out was a mistake.
I see Saga (LON:SAGA) as very different. The bulk of its debt is the 2 ship loans. In that case, the lender is co-operative, and it stands to reason that everyone, including the lender's best interests are served by waiting until the ships can start generating revenues again. Hence it would make no sense at all for the lender to resist relaxing the covenants, in my view.
The £250m bond has no covenants (or none of any significance right now anyway).
Leaving just largely undrawn bank facilities.
The insurance division generates enough cashflow to support the c.£6m cash burn from the travel division. It's a pity that the company's comms people bungled the last update, so some people have wrongly assumed the whole group is burning £6-8m per month, which is nonsense. That figure just relates to the travel division, and insurance division pays for it, so not a problem at all.
Put it all together, and I think the position at Saga stacks up fine.
Apologies for repetition. I think it's so important to drill down into the detail. Apparently high net debt at Saga is not problematic when you dissect it down into the detail. Hence why I feel we should (fairly soon) get an update confirming that covenants have been relaxed. Maybe the lender might negotiate an increase in fees though?
Regards, Paul.
Hi Paul - you are probably right that the lenders will not pull the plug, however the bigger worry is the price they will extract for not doing so. I am seeing a lot of ratcheted rate increases, expensive restructuring or 'deferral fees' and more stringent corporate controls being put in place by lenders in similar situations in the industry at the moment. Banks will be 'supportive' as long as they are getting something out of it to sell to management - i.e. more profit in the long haul which means more expensive funding for SAGA.
The other potential issue here is the cost of getting the vessels out of warm stack (or, worse, cold stack if COVID persists) - contrary to what most would think, you cannot simply decide to start using these sorts of vessels again one morning and get onboard, press the start button and sail off. The cost of getting the vessels out of layup and back into a ready for operations state can cost a pretty penny (I haven't checked the accounts/reports to see if they have tried to quantify this and made reserves for it?). The longer a vessel is laid up, the more issues you tend to have with it afterwards too, so there are potentially higher running costs to factor in due to that (or, in the worst case of having to drydock the vessel to fix anything, also potential 'down time' in operations for that). Depreciation is also a factor to watch - if you end up losing 2 full years (the 'best' two years too when the asset was supposed to brand new and at its highest earning potential) out of an operational life of say 20 years then that's a big hit to the projected profitability of the investment.
Crewing costs are also escalating rapidly presently and will remain elevated in the short and medium term at least.
Perfectly possible that the investment case might still stack up despite these things of course - just highlighting a few issues that I haven't seen raised here yet from a maritime industry perspective and which do need to be built into any projections.
Just being pedantic, but the Zytronic RNS says offer at 145p, not 140p
Hi Devlishcunning,
Just being pedantic, but the Zytronic RNS says offer at 145p, not 140p
Not pedantic at all, you flagged an error, thanks very much!
I've already corrected it, as I spotted my typo myself a little while ago. Profuse apologies, I hate making mistakes, the information has to be 100% correct, I just typed it wrong & didn't notice at first :-(
Sorry, Paul.
I see is asking how often the stock report is updated? This is really important as if , for example , the share count has gone up and the report has not be updated , The the figures are seriously misleading.
Hi Ken,
The share count figures on the StockReports are very reliable I find. A few years ago there was a bad patch with the data provider, when there were errors in the data, but these days I find the share count/market cap data very reliable.
Edit: Sorry, just seen another post below, saying there's a data error for VLG shares in issue. If you find a data error, then please do raise a "green blob" to report it. Stockopedia HQ then follow it up with the data provider and usually corrected within a day or two. Looks like this was a false alarm, and the data was correct after all.
Regards, Paul.
Folks
Your advice please; anyone have insights into Lookers (LON:LOOK) restoration to market on Friday, interim results, and new board changes. I had initally invested pre Covid and the expectation of a booming economy .I had thought that it would eventually get assistance from Electric motors, was reorganising, and also the attraction that one of the directors Tony Bramwell had spent over 7 million pounds buying shares in the range group of approximately 44-55p
Any chance Paul of an examination
Thanks
Hi AJC,
I decided against scrutinising Lookers (LON:LOOK) as it would take too long to analyse, given all the historic problems, accounting irregularities, etc. It rose vertically on coming back from suspension, so I decided it wasn't a good use of my time to unpick everything that's going on. Generally I steer clear of all companies that have had accounting irregularities, as they can often under-perform long-term, and I just don't trust the figures. Staffline (LON:STAF) is another example, where I won't ever buy the shares again.
Sorry about that.
Regards, Paul.
Hi all,
Does anyone know how often StockReport data gets updated?
Re: Venture Life (LON:VLG)
According to Stockopedia, Venture Life has 84 million shares in issue. However, after a recent placing in December 2020, the actual number of shares in issue is just over 125 million. I used the Stockopedia data in some calculations which, as a result, are now quite off the mark... I'm not sure how to approach this in future. Is there some way to tell how recent the data is?
Thanks,
I never noticed. And they seem to have fixed it already.
Good point about being able to check the age of the data though.
Sorry but I think you're wrong. The 84 million number is shown against "Average shares" i.e. an average for the period. If you look further down the stock report (in the Profile Summary) you will see:
"Shares in Issue 125,831,530"
On top of that, Market cap is clearly using the 125M figure and appears to have done so since Dec.
The average shares of 84M is under TTM, and I'd automatically assumed that any figure in that column was at the date of the last figures, which i believe was Sept. I don't expect any other value in that column to be updated on a daily or weekly basis, but only when new interim or full figures are released, so I wouldn't expect share count to be updated either.
Different assumptions I suppose.
PS Just read Gromley's comments and I think he's already said what I was trying to say.
That strikes me as quite an important point you raise Kieran.
I presuming you are taking the number of shares in issue figure from the Financial Summary of the StockReport?
All of the figures in that section relate to the date the latest included results were published.
If you want the current number of shares in issue your best bet I think is to look at the share price and market cap at the top of the report.
As far as I can, all of the ratios in that section of the StockReport refer to the past data for number of shares. Mostly this is reasonable, however it looks as though the forward PE ratio (to give one example) is also calculated on the old share count. That is problematic - especially when it looks in this case as though the EPS forecasts have been reduced to account for the higher share count.
Venture Life (LON:VLG)
Normally if i am looking at any company first go into the news section for that company and click the announcments button and have a scan of the news for the recent past - any interetsing stuff normally shows up on the first page there unless its a big company- second and fourth and seventh lines down all contain relevant info in that regard. This route might not specifically answer the full question but it will flag up the fact there could possibly be an issue with the share count.
Shares in issue
Last weeks short squeeze on wallstreet episode perhaps highlights that there are potentially, maybe, guessing, far more shares traded than actually exist - with options, shorting et al. Attempting to be a trader with a few 'longs' or 'wrongs'.
Paul thank you for the IPO summary. It would be great if you can explain how you identify upcoming IPOs - I struggle to find a reliable source for this. Thank you
Hyrdus,
Forthcoming & recent IPO's on London Stock Exchange are here: https://www.londonstockexchang...
Thanks Bill but that website (which I do look at) does not include a number of the upcoming IPOs Paul mentioned so assume he has another source
Hi Hydrus,
Paul thank you for the IPO summary. It would be great if you can explain how you identify upcoming IPOs - I struggle to find a reliable source for this. Thank you
I just skim the morning RNS, and saw lots of "intention to list" announcements, hence thought it would be interesting to review all 5 today, since it was an unusually large number.
Regards, Paul.
Thanks Paul good to know
Trapped holding a few Bidstack (LON:BIDS) shares from an ill-judged "investment" 2 years ago. Revenues up significantly, but still paltry.
A mix of gaming and advertising which sounds like rocket fuel in principle, but despite supposedly having sector-leading tech, they're not getting any traction. Low single-digit fill rate even during a pandemic? Surely this is as good as it gets for companies wanting to target customers through gaming.
Also, communication from the company is absolutely terrible and leaves investors trying to fill in the blanks - normally on the cult-like forum 'Bidlievers'.
Despite being a holder, I too would struggle to make the case for buying in, which is a shame.
I had a look recently as it's obvious there is money to be made 'ingame' but I couldn't get past why the games developers wouldn't just do it for themselves? It also sounds like the sort of thing Keyword Studios could offer as part of their suite of services so maybe they could snap them up.
I think part of the reason is that Bids offer a dedicated suite (Ad console) where metrics can be viewed and analysed.
I can imagine it would be quite a big task for a developer as you'd be liaising with multiple customers, who may want to update their campaigns frequently and you'd have to negotiate all kinds of details regarding the placement of the ads in the game, rates etc.
Bids effectively do all the dirty work so all a developer has to do is build the inventory into their game and leave Bids to act as the middle-man.
For an advertiser the benefit is having a centralised, consistent platform to view the performance of the campaign cross different games, instead of potentially dealing with various developers who would no doubt operate in different ways.
This is my understanding anyway. Bidstack play the role of the middle-man, connecting demand with supply and taking their commission on the way.
Thanks for the short review on recently announced IPOs, Paul. The proposed IPO by Cordiant Digital was picked-up by the press this weekend. It's a REIT looking to raise between £300-500m to buy digital infrastructure assets in the UK/US; basically the tech and infrastructure that supports 5g and broadband rollouts. It looks quite interesting, and I am still musing it over, but my concern is that they will be looking to buy assets in a very expensive market so run the risk of significantly overpaying. The executive chairman seems to have decent and relevant experience. Anyone else had a look at this? My gut is saying to sit it out and watch how it pans out, but certainly is interesting. Best, Will.
Cairn Energy (LON:CNE)
I hold and this is why
https://timesofindia.indiatime...
The way I see it, India is going to have to settle somehow or it risks alienating potential future investors. What I don't understand is why this is not being reflected in the share value yet. Do others know something I don't?
Cairn Energy (LON:CNE) Took a look a month back - like case with Vodafone - Indian gov likely to lodge appeal = further time delay. Also, the settelement, at least a large portion, if I am not mistaken is already factored into current SP as per some of the investors on the LSE BB have stated.
"Vaccinations & re-opening"
About time we had some positivity regarding where we might be before too long:-
https://www.bbc.co.uk/news/wor...
About time we had some positivity regarding where we might be before too long.
Hmm, the isolated Isle of Man is probably not representative of either the globally interconnected UK or the rest of the world. We're going to have travel restrictions, elements of social distancing and testing for years until we can crush community transmission everywhere. Anywhere the virus can run free it can mutate.
For instance ... in Woking:
https://news.sky.com/story/cov...
Residents in parts of Surrey will be offered coronavirus tests after two people with no travel links were found to have caught the variant discovered in South Africa.
timarr
Just thought some might like to know you can get all RNS's on any share you are interested in or hold by going to Alerts in Stockopedia stock report and ticking the box News Alert. You then get an e Mail and can easily click on the RNS. I find it really useful. Hope it helps. Good to see Holland Smith back but let's not forget Mr Contrarian who hasn't been away. (Prodigal son)
Venture Life (LON:VLG) total smoke and mirrors. It will be interesting to see the details in the full year as I think they are being a bit tricky dicky with how they account for things. 2021 eps expectations look outrageously optimistic. Adjust for dilution in 2020 and 2021 eps forecast is saying that company will have increased profit by 7x from 2019 to 2021...wow....all things are possible but VLG need to blow the bleedin doors off in everything they do...do you feel lucky punks? <ahem...apologies>
VLG was resoundingly hyped in here and on twitter by number of punters...inc Stockopedia fund I believe. Can only be explained by one or combo of credulity, not reading the details or trying to use profile to play punters for a momentum ride in a stock...its probably the first two which is forgivable but always keep an eye on the latter.
VLG needs a good announcement. They are promotional in their RNS so expect something hyped...but read carefully. Its very likely to be jam tomorrow and new products....but do check out what's happening with existing.
Few bits of banalysis here:
https://www.stockopedia.com/co...
https://www.stockopedia.com/co...
https://www.stockopedia.com/co...
I should be getting thanks from people rather than opprobrium for being sceptic (no worries...I don't need either).
VLG has high chance of being sub 50p stock this year unless its got a real magic trick up its sleeve.
mojoword out
Talking of companies coming to the market ChargePoint looks very interesting. Its one of the world’s largest charging network operators for electric cars with
around 115,000 charging points. They expect to float next month via a
special-purpose acquisition company (although i must confess to having no knowlege of an SPAC)
Looks good, these type of companies have really taken off in the US.
$BLNK is one of them.
Cramer did a segment on the charging companies last Monday
Zytronic (LON:ZYT)
Should this method of Returning capital to Shareholders be the template for buying in shares ort returning capital to small shareholder at no extra cost?
Zytronic (LON:ZYT) (I sold last year - not holding) I am wondering why they decided to buy back shares rather than distribute cash to holders? Share buy backs are a good strategy if the business is growing and is profitable, as consolidation improves shareholders value. However, Zytronic (LON:ZYT) seems to be in the last stage of a business lifecycle (in decline), so think a dividend would have been better for holders. I might have missed something?
As I see it, a dividend would be taxed as income, and a share buyback as proposed will be taxed as capital gains, so it depends on one's circumstances which would be preferable. I don't know how much the directors hold, but this may be why they chose the capital option.
Additionally, a dividend would be a committed cash value on a fixed date, at which point the share price will no doubt drop by the divi value. With the capital option as proposed, they have the potential benefit of gauging the market's appetite and possibly purchasing more back if there is the demand to do so.
Either way, investors would retain the same proportion of the (less valuable) company, but either the same number of less valuable shares or fewer shares at the current value.
I think that capital gains tax is a consideration - for individual shareholders the tax liability they incur under a buyback scenario is different from, and lower than, dividend income. I've seen this in other scenarios such as Port Erin Biopharma that did something similar a few years back.
Good morning Paul
It would be great to have your views on Dx (group) (LON:DX.) Who have posted a materially ahead trading update.
There might be value here due to transformative management and change accelerated by Covid (increased parcel delivery)
Thank you
I see the Reddit crew are going after Silver now, spot silver up 10%
Long John Silver would have loved it! or is it Johnnies are Long on Silver :)
I find the Venture Life (LON:VLG) headline of today's RNS annoying. "Full year profit ahead of market expectations" is the headline but we are not told what that expectation is. We are told that adj. EBITDA is not less than double last year. Last year's adj. EPS was 2.18p so double that and you get 4.36p cf 4.35p forecast.
The market was not fooled by the headline. After an initial flurry at 08 00 the offer now (08 45) is 88p cf 90p on Friday.
Meanwhile no news on the acquisition programme - 'Project Vulcan, Target A, Target B' teased in the highly dilutive P,O,O. @90p in November.
Edit - I have just found the last report from joint house broker Cenkos (20/11/20) showing adj. EBITDA for 2020 forecast at £6.0m. So does saying that it will be not less than that warrant the headline?
Fully agree regarding £VLG. Always get slightly twitchy when companies start using EBITDA rather than pre-tax profit. I hold and will sit on the fence for the time being.
Also agree the update from Venture Life (LON:VLG) is poorly written. How hard is it to provide a clear trading update?
I sold out last Monday as I was clearing out my lower conviction stocks in anticipation of a general downward trend. I actually bought a number of their products over Christmas and generally wasn't too impressed with them if I am honest.
Re Fonix Mobile (LON:FNX) Paul is correct. One of the big ITV programmes - Britain’s Got Talent is cancelled for 2021.
I'd be surprised if there were not repercussions regarding Gamestop.
Given that, IGIndex's acquisition of Tastytrade looks questionable to me - aren't they catering to the beginners trading options?
The power of the crowd is truly something; if they restricted something they didn't like, they could be abandoned and get a load of 1-star reviews. How much value has been reduced off Robinhood?
Even if nothing happens I'd expect way out of the money calls to become more expensive and bad value.
Given that, IGIndex's acquisition of Tastytrade looks questionable to me - aren't they catering to the beginners trading options?
Yep. They're making money on cash balances, short stock loans, order flow and portfolio margining.
There are two businesses - tastytrade, which is a media channel full of information about how to trade options - and tastyworks which is the dealer-broker. Those seem to be separated so that the information on tastytrade isn't classified as advice on tastyworks.
Supposedly the average tasty trader is a lot older than the average subreddit crowd, but it's definitely in the same area.
Comment from reddit:
"IG Group who agreed to purchase tastytrade for $1B just a week ago restricted trading on GME and AMC. I just opened a tastyworks account. Not sure if I want to have my account with companies who think this behavior is ok."
timarr
Fonix Mobile (LON:FNX) I like the way Fonix Mobile have concentrated entirely on the UK market. This has enabled them to take significant market share in their home market, prove out the business model and become very profitable. This has put them on a very strong financial footing to take their business overseas.
As we have seen with Bago and Boku, mobile payments is a fast growing area; there is plenty of growth available in the UK market. In sports, for example, Fonix is chasing rights owners in football, rugby and F1. The idea is to enable consumers the ability to watch sporting events on their digital device after paying for it by entering a code on their mobile phone. As well as continuing to build their UK presence, they now have eyes to take their business further afield, both in Europe and the US. According to a research note I found in the Momentum Investor, "a tilit into the US at the National Basketball Association (NBA) and the National Football League (NFL) is also on the cards".
Hi golfnut59, the sports angle is interesting. Are you saying that no subscription to Sky or BT is required instead you buy an event, lets say the Rugby WC and watch on your phone?
I'd be interested to know that as well. I can see a good fit with Sky for their NowTV offering where you can already buy individual sporting events. Having a simple mobile payment solution for products like this would be very popular in my view
Just on a personal note, I love cricket and really annoyed how the matches are all over the place e.g. the upcoming India v England tour is still TBC (hopefully Ch4!)
Thanks for writing up Fonix Mobile (LON:FNX) is such detail Paul. I have a small holding here on the basis that this is a real, cash-generative business with steady costs and room to grow. I like the fact that the CEO stated that the plan was always to make some money by selling some of the company. Honesty goes a long way!
My morning smallcap tweet:
Bidstack (LON:BIDS) Tracsis (LON:TRCS) Avacta (LON:AVCT) Iconic Labs (LON:ICON) Remote Monitored Systems (LON:RMS) Zytronic (LON:ZYT) Hardide (LON:HDD) Sportech (LON:SPO) DX (Group) (LON:DX.) Netcall (LON:NET) IDE Group (LON:IDE) Venture Life (LON:VLG) Parity (LON:PTY) Staffline (LON:STAF) Totally (LON:TLY) Air China (LON:AIRC), Renewi (LON:RWI), Seeing Machines (LON:SEE)
Bidstack (BIDS) guides FY(Dec) rev c.£1.7m, above mkt exp. Pretax c. -£7.18m (-£5.6m). Warns "the pandemic may well result in a further lengthening of sales cycles. To address this, Bidstack's strategy will be to concentrate on the appropriate implementation of its technology even if this is at the expense of some short term opportunities." [SP=10.75 Cap=42m]
Tracsis (TRCS) new CFO today. Outgoing is thanked. [SP=650 Cap=190m]
Avacta (AVCT) AffyXell Therapeutics JV gets $7.3m VC funding. [SP=123 Cap=311m]
Iconic Labs (ICON) gets termination notice for mgmt of JOE Media and TheLondonEconomic businesses citing today's resignation of the senior management team of John Quinlan, Sam Asante and Liam Harrington. This is the most significant proportion of co's rev. JOE media termination immediate effect. [SP=0.01 Cap=2m]
Remote Monitored Systems (RMS) commissioning of anti-viral mask manufacturing machine delayed because the engineers have caught guess what? Covid. [SP=2.45 Cap=49m]
Zytronic (ZYT) Tender Offer at 145p, a 14% premium, to return up to £10m. [SP=135 Cap=22m]
Hardide (HDD) £775k min placing at 30.9p, a 5% discount. Needed in case oil mkt demand slow to recover. [SP=31 Cap=16m]
Sportech (SPO) sells Bump Worldwide for c. £5.7m including c.£1.1m earn out. [SP=27.6 Cap=52m]
DX (DX.) guides FY(July) adj pretax materially above market expectations after strong H1. Cites strong progress at DX Freight, [SP=35.5 Cap=204m]
Netcall (NET) guides H1 rev up 9% and adj EBITDA up 38%, comfortably in line with management expectations. [SP=57.5 Cap=85m]
IDE (IDE) guides FY(Dec) rev £23.6m down 16% and adj EBITDA £0.5m (£1.1m). In line implied. Cost savings to come though this FY. [SP=2.25 Cap=9m]
Venture Life (VLG) guides FY(Dec) rev up 49% and adj EBITDA over double. In line? "The significantly increased revenues and higher prevalence of revenues from the VLG Brands in the year have contributed to improving gross margin, as expected. Revenues from the newly acquired PharmaSource business were ahead of 2019, and a number of planned synergies have already been achieved." [SP=87 Cap=109m]
Parity (PTY) wins 3-6 year contact worth up to £5m from Scotland. [SP=9 Cap=9m]
Staffline (STAF) guides FY(Dec) U/L op profit marginally ahead of expectations. "Board continues to evaluate its options in relation to strengthening the Group's finances." [SP=55.5 Cap=38m]. I hold.
Totally (TLY) 1 year contract extensions worth c. £16.8m [SP=32 Cap=58m]
Air China (AIRC) RNS called 'Profit Warning'. How refreshing. Guides FY(Dec) loss RMB13.5bn to RMB15.5bn. [SP=0 Cap=112667m]
In line: Renewi (LON:RWI) Seeing Machines (LON:SEE)
Paul
Mania - Gamestop / Reddit / Wall St Bets
You will have noticed a lot of discussion in media about this, indeed I think John Authers has written about it at least three times last week.
I do suggest that all subscribers go have a look at the WallStBets site on Reddit, just to get a real feel for the extent of the mania, manipulation and complete sense of omnipotence (and indeed righteousness) that oozes through the 100s of posts and 1000s and 1000s of comments.
In the context of now this, Tesla, and Bitcoin I certainly feel fearful that this is not going to end well (possibly quite soon) and may see some spectacular market adjustments in the US...to which, we in the U.K. of course will not be immune.
Consequently I am thinking about how to be suitably defensive towards such mania / potential market downturn whilst not in any way turning my back on the very good opportunities that exist in the U.K. small caps market?
I am thinking of increasing cash from 5% to 10%....
Any other ideas / views welcome. But as I said, go look at WallStBets yourself to really get a sense of what’s going on in the States....
Martin
I think righteousness is a little harsh. Why is GameStop any different to Tesla over the last 12 months which is up 13 fold, which has been mainly pushed by institutional investing rather than retail investing?
Clearly the bubble on these kind of stocks is going to burst soon and it could end up being a disaster for those leveraged in the stocks. Not nearly as much as a disaster for Melvin Capital though, who get what they deserve for being so cocky!!
I used ‘righteousness’ as many of the comments I saw, expressed a hugely strong sense of a moral mission, of good against evil, hence the huge anger when their favoured broker prevented further purchases last week.
Honestly, I have never seen anytime like it in investing. The emotions, the huge number of people involved and the accessibility of ‘advice’ and encouragement by the second...wow!
Yes, re Melvin Capital, I’m not making any moral point one way or the other.
Re comparison with Tesla, well I think what has happened with GameStop and now others makes Tesla price action seem sedate or conservative.
Hi Martin - it's not confined to the States. If my sons and their friends (i.e. Millenials) are anything to go by, their ONLY source of information is Reddit and most own a GME share or two. Things are changing! To the moon!
In my opinion precious metals (ideally physically backed) would serve this purpose. Silver has had a sharp movement over the past few days but still looks like better value than gold. But physical gold is much easier to store and you don't need to pay VAT on it. But either of these would serve as good hedges against chaos. Personally I'm about 15% in gold/silver.
I hedge my risk using volatility indexes (VXX, VIXY), basically load up when they are low, bale out when high, I find it easier/safer than index shorts.
Been following WSBs (Wall Street Bets) since it started, there is a lot of good analysis in between the large amounts of larpping and YOLO stories.
I didn't go for the $GME play, but in $NOK and Silver play at the moment. Heavily in US Spacs $CCIV and $IPOD, $IPOF. WSBs has changed my investing and trading approach with good results.
As someone who started investing based on solid fundamentals and dividend yield, I now mainly follow price action and social ARB plays for swing trades.
Hi Old Man Fit-I'm interested in your Volatility Indexes. Is VXX Barclays Bank Ipath S&P500 Vix short term Futures? and is VIXY Proshares Vix Short Term Futures ETF? or have I got it totally wrong? Your help and response will be very much appreciated if you have the time.
Hi
I use ProShares VIX Short-Term Futures ETF (VIXY) and iPath Series B S&P 500 VIX Short-Term Futures ETN (VXX), in a mix between Spreadbet and Share dealing.
I got out of using index shorts as I think shorting anything can bring in unseen risk as Melvin Capital has shown.
When you buy a stock its price in theory can have a limitless rise, so transversely if you short a stock it can have an almost limitless fall.
I have found from studying the volatility indexes, that they drift between certain parameters in relaxed market conditions. A volatility index measures an implied level of volatility in simplistic terms if linked to the S&P 500 if it falls then the $VXX usually rises, though not always, but nearly always.
The reassuring aspect of a volatility index is that there will always be a certain level of volatility in the stock market it should never go to zero. Hence, I felt it was a safer hedge than an index short.
So basically I load up if it is at the lowest I have seen for a while based on basic indicators.
VXX - I loaded up in December 2020 at 16.95 and VIXY at 13.58 in early Jan
Not come across those before but I can't buy them on HL platform and IG can't buy within an ISA.
I hear what you say about shorting shares but indexes don't tend to rise that much, the FTSE100 has gone up in 20 years.
I would only do index shorts in time of trouble, as we had back in March 2020.
Thats very helpful thank you Oldmanfit.
One question - what's the difference between these two? I understand the VIX500 but not the VIXY.
Cheers
Francis
They are basically the same thing with similar costs and returns, though they VXX is an ETN and VIXY is an ETF.
Thank you
Thank you old man fit and apologies for not coming back to you yesterday. Many thanks, I think I understand and will now explore. Many thanks for your help. Charles
I too am feeling nervous around this - I don't feel like I have enough knowledge/experience in the science (art?) of hedging my portfolio. FWIW: I have sold some of the shares that have come back significantly from march lows but which I am now less confident in than when I originally bought, leaving me with circa 5% cash, added to my holdings in preference shares (AV.A, AV.B, ELLA) circa 8%, and added to my holding in Personal Assets Trust circa 5%. Geographically I am overweight in Asia/Emerging markets via investment trusts and underweight US. And that is about it.
I do feel like the traditional equity/bond 60/40 strategy (which my wife is still being advised for in her workplace pension) is at risk here as bonds and shares could fall at the same time so no hedge.
Probably the biggest risk here is that of contagion. One hedge fund is reportedly down the best part of $3 billion dollars and has decided to close its position in GameStop. Robin Hood has also reportedly had to increase its funding by $1 billion to cover client’s positions.
In 40 years of investing I never seen amateur investors being able to reach a critical mass and target large short positions. In a world changing 12 months we have yet another uncharted waters situation.
No position here other than a direct holding in Hochschild
Yes, it’s that sense of contagion and unforeseen consequences that makes me a little nervous.
Thanks also to Robert W, Old ManFit, Gdawgeedawg and any others for useful (and different) ideas on how to hedge the risks.
This is also something I'm mindful of. Its not an exact science but I'm short the Nasdaq and long gold at the moment, I use spreadbets to control my portfolio insurance, I see the tech heavy Nasdaq as an easy target given it's steller performance in 2020 and sky high valuations. I'm hesitant to reduce my mostly value and GARP portfolio as I think it's postponed for a recovery into 2021 and beyond.
I'm surprised theres not a short only ETF that targets high value/momentum stocks as these are the ones that are likely to fall the hardest if a correction or crash occurs in my humble opinion.
Asos (LON:ASC) Has bought Topshop and Miss Selfridge for 295m
I can say that the best bullet I ever dodged was having no shares in landlords nor commercial property.
Its sad and tragic what (HM Government) has happened to Retailers - particularly for the little people, the staff and workers.
I have a feeling retail - the experience will be back - however (forgive my lack of expertise here), what appears to be happening is that the retailers are being stripped of the brand and loyalty value, and the expensive landlords and staff costs are being dumped for now.
I think they'll be back in the future, minus the pensions, shorter more lean employment contracts or zero hours, and renegotiated leases.
The other thing that is missing is the "society" (not exactly pleasant that it was) that the lack of bustling high streets and shopping centres misses.
Just IMO,
I have the feeling retail is becoming 'barbelled'
What I mean by this is that
-when the local shops - the ones you walk to - were open, they were doing well.
-we all know online is doing well
All the 'middle' - shopping malls you drive to - shopping areas in cities that depend on commuters - places that are not convenient and not a fun destination will be squeezed v. hard.
On that theory am long Tritax Big Box Reit (LON:BBOX)
You might also want to look at Tritax Eurobox - Tritax Eurobox (LON:EBOX) discussed here
The stock rank is +24 in the last 30 days and edging into the green.
Barclays Wealth Management have sold all their Real Estate investments for their clients, they have also put the Commodities under review.
The real-estate returns were not brilliant over 5 years, but considerably better than the Commodities returns over 5 and 10 years.
I really wouldn't want to be in commercial property other than warehousing or logistic boxes for the foreseeable future - too much risk for me.
One more comment to add to my demise of the high streets comment.
Where as Retailers and their Administrators can forestall and renegotiate private landlords lease charges, my understanding is that there is no flexibility on The Government's Business Rates side of the cost. If you are stuck with a loss making shop or building, and the local council can't forgive Business Rates, what are they going to do?
At the end of the day a Landlord has to rent shop space to only a limited number of retailers. He'll take a short term reduction to keep base revenue.
The autopsy of dead retail, not that there will be an autopsy (even though their should be - its a Public good), is that Business Rates may have been the one factor above wages and rent that put local high street businesses under.
And the consequences of creating unemployment because non-profitable businesses need to avoid tax liabilities... is more tax liabilities. Doh.
your back!
Good to see you back posting here.
As others have said, it’s great to see you back!
Thanks - Like the v.v. short form.
I think the script might be breaking when market cap is in Billions:
// JD Sports Fashion (LON:JD.) - £0m// Conditional Agreement for the Acquisition of DTLR
// Hargreaves Lansdown (LON:HL.) - £0m// Half-year Report
// R.E.A Holdings (LON:RE.) - £0m// R.E.A. Holdings plc: Trading update
Thx HS. Good to see these back and the short form is excellent.
Regards
Michael
If you are interested in the area of epigenetics and personalised medicine come along to the Oxford Biodynamics (LON:OBD) webinar this evening at 5.30pm. New CEO Jon Burrows will talk about the progress made over the last year and the exciting prospects for 2021. A covid 19 disease severity test is due to launch this quarter which will identify the risks of a severe outcome, requiring intensive care treatment, from catching Covid. This diagnostic test will use blood samples and is suitable for use before catching the virus.
Later in the year the company plans to launch an Immuno Oncology test for cancer patients to determine the response from various treatments. Progress is also being made with the Master Service agreement with a major US Pharma company and on its project with Mitsubishi Tanabe.
Register here
Fonix Mobile (LON:FNX) Thanks Paul, I was also looking at this over the weekend. Looking at the June 2020 accounts, the increase in trade creditors is driving large increase in operating cash. Does anyone know what this is? I couldn't find an Investor Relations email address to ask, so emailed the sales team!
From what I can make out nanotrader, this is because Fonix collects revenue from the Merchant (so the cash passes through their books), once passed on to the Mobile Network Operator (MNO) they collect a fee.
Thanks Matthew. I wonder if this is expected to continue or it is a one off as they had a bumper inflow last year
Its a very good point you raise though. I guess another way to look at it is to subtract this cash from net cash flow from Operations, effectively saying it isn't their cash. To me it still leaves a reasonable free cash flow of 67% for this year, which is better than last year. I will be interested to hear what the company say if you get a response from them!
Thanks for this Paul. For anyone wanting more info on Fonix Mobile (LON:FNX) this Finncap report from 11th November 2020 is very good and detailed https://www.research-tree.com/...
Their target price, since this, has been upped to 200p.
Thanks for the overview of Fonix Mobile Paul. I was looking at this share a few months ago but didn't have the time to explore further.