Small Cap Value Report (Mon 1 July 2024) - ATG, GMS, PRV

Good morning from Paul, and welcome back Graham!
I see several companies have announced their brokers have changed, due to a merger of Liberum and Panmure Gordon. It's good to see more consolidation in the sector, and I wish both firms well as a larger group. I rely on Liberum's excellent research a lot through Research Tree, so I very much hope the combined entity will adopt Liberum's approach of getting their research out to the people who create the liquidity and set the share prices for small caps - private investors!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
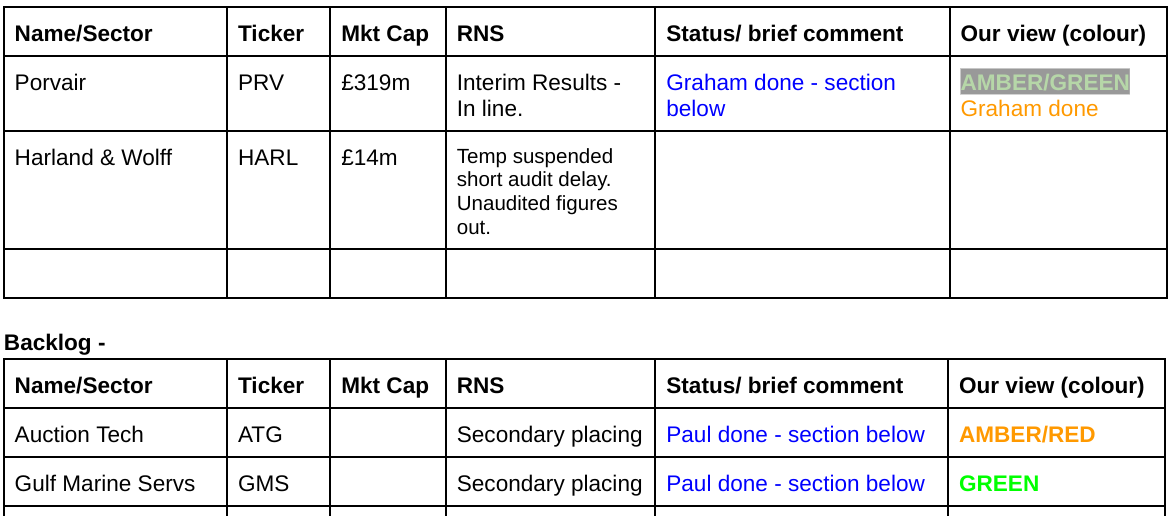
Companies Reporting
Extremely quiet today, so a nice leisurely return to duties for Graham!
Summaries
Auction Technology (LON:ATG) - 501p (£610m) - Secondary Placing - Paul - AMBER/RED
Late last week this share price was hit by about 10% after JP Morgan sold 5% of the company for the original private equity backer, at a c.5% discount. This raises questions, which I discuss below. A wider review of the company doesn't impress me, so I'm uneasy about possible warning signs here.
Gulf Marine Services (LON:GMS) - 17p (Friday's close) £182m - Secondary Placing - Paul - GREEN
A similar situation here, with a big shareholder selling a chunk at a 15% discount. After a long gap, I get up-to-speed with this previous SCVR favourite, and like what I see. Not entirely risk-free, but to me, risk:reward looks potentially very good. So this 15% discount might be a buying opportunity perhaps, but please do your own much more detailed research, as always.
Porvair (LON:PRV) - up 2% to 676p (£323m) - Interim Results - Graham - AMBER/GREEN
Performance has been in line with expectations, according to management. Underlying sales growth is negative but acquisitions in 2023 and 2024 have helped to boost the numbers. The balance sheet remains in net cash (just) and overall little has changed: this is a fine company, perhaps not far from fair value?
Paul’s Section:
Discounted Secondary Placings
This was something I noticed on Friday, which is a bit of a concern. We’ve talked a lot about how the UK small caps market has suffered over the last c.2 years from client redemptions. These force small cap fund managers (those operating open-ended funds) into selling shares in the market. This type of fund outflows seem to be diminishing now at last.
However, Friday last week demonstrated that there can be other selling overhangs, where a large shareholder wants to sell, but there’s inadequate market liquidity. Hence a secondary placing needs to be conducted by a broker, to shift the overhang of shares, at a discounted price. No money passes to the company remember, it’s just a mechanism to shift a block of shares from one shareholder to buyers.
What concerns me is that these are happening at a price discount. A couple of examples below, one of which ATG makes me nervous, and the other GMS I reckon could be providing a buying opportunity. Maybe! You need to do your own more detailed research, as always.
Auction Technology (LON:ATG)
501p (£610m) - Secondary Placing - Paul - AMBER/RED
Proposed Sale of Shares (27/6/2024)
Shares closed at 556p last Thursday 27/6/2024, then JP Morgan announced after hours that it had been appointed to organise a secondary placing -
Quantity for sale - c.5% of the whole company (6.1m shares).
Seller - TA Associates (private equity) - largest shareholder with 17.6% (21.4m shares)
Price - to be determined by a book build (ie JPM ringing round asking for orders/prices from potential big buyers).
Lockup of 60 days for seller.
Result of Placing (28/6/2024)
Announced at 07:00 the following morning, as is usual with placings, as they’re usually secretly almost buttoned up by the time the first announcement comes out, but might pick up some more stragglers. As an aside, I’ve been with a broker friend in the pub when this type of deal happens, and he frantically makes & receives calls for about half an hour, writing down client orders on any receipts he can find in his pockets! Then I sit there laughing, as he tries to remember who ordered what, and in a flustered state tries to get the consolidated order in to the main broker doing the deal. I will never reveal his identity, as he's a mate! Anyway back to ATG.
Quantity sold - as expected, 6.1m shares.
Price - 525p, which seems to be a discount of 5.6%
Value - £32m shares sold to new owners.
TA Associates now holds a lower 15.3m shares (12.6% of the company).
Paul’s comment - this seems to have been badly received by the market, with ATG shares closing at 501p (down almost 10% on the day) on Friday 28/6/2024, or c.507p (down about 9% on the day, if we ignore the large 16:35 auction uncrossing at 501p). That’s well below the 525p placing price, so buyers who thought they were getting a bargain are instead sitting on an immediate loss.
What does TA Associates intend doing with its remaining 15.3m shares once the 60-day lockup has expired? Will it come back and sell another tranche at a discount, clobbering the price again? Who knows.
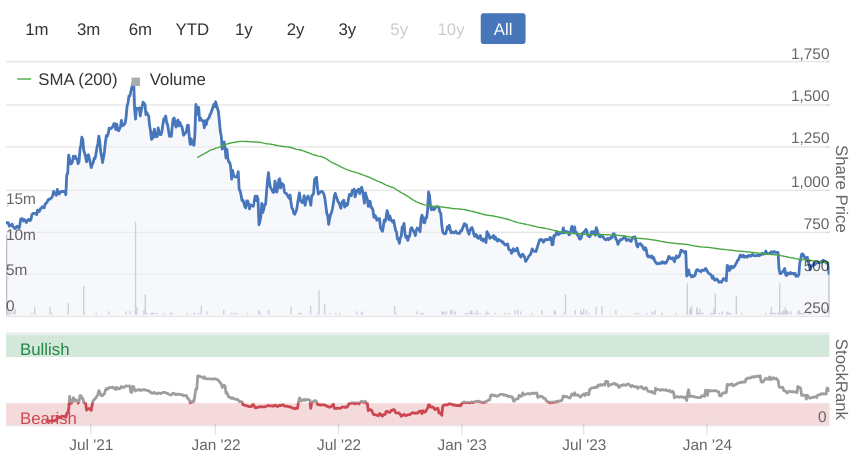
ATG shares were originally floated by TA Associates, formerly its 100% owner. The Feb 2021 IPO was at 600p, and it quickly soared to peak at almost 1600p in late 2021, but has since lost two-thirds of that peak price. So it’s surprising the original private equity backer is dumping shares at a discount now. I wonder if this means they no longer believe in ATG, or just want out, almost irrespective of price? Maybe they want the funds for something else, which is usual for private equity? Who knows, but this deal is bound to harm sentiment, at least in the short term.
Checking our previous notes,
Roland covered its profit warning on 3/12/2023.
Graham went green on 31/1/2024 on a good TU.
Paul went down to AMBER on 17/4/2024 H1 TU, pointing out a weak, heavily indebted balance sheet, and an apparent lack of growth.
I think we also had reader comments, saying that online auctioneers were facing stiff competition from a challenger under-cutting them, and some readers thought ATG had been too greedy on fees, this damaging client relationships & losing business possibly.
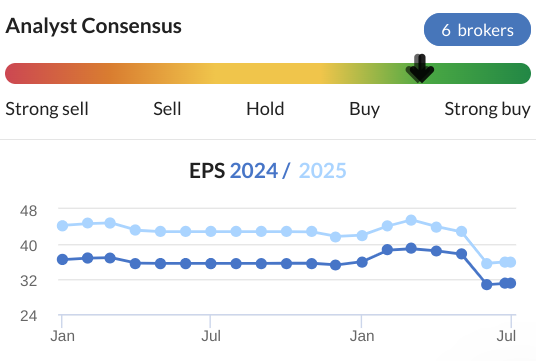
Broker forecasts have recently moved in the wrong direction -
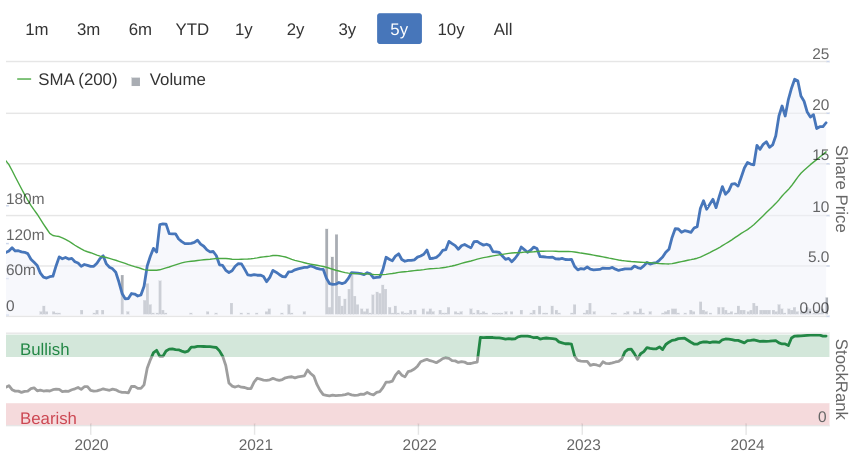
With the original private equity holder now seemingly keen to get out, and offering a discount, I’m wary about where this is going - with an already sick-looking chart -
I’ve had a quick look back at ATG’s last H1 results (6m to Mar 2024) and its balance sheet is weak. Dominated by $583m goodwill (overpaid for acquisitions maybe?) plus $256m other intangibles. Eliminate both those, and NTAV is negative $(178)m mainly due to too much debt (net debt was $142m at 31/3/2024).
Although we could be kind and also eliminate the deferred tax liability of $43m, which would help NTAV to a still poor $(135)m.
Cash generation doesn’t look particularly strong in the last accounts.
There seem to me some warning signs here, and the original private equity owner wanting to sell adds to that.
This might be controversial, but I think I’ll shift down to AMBER/RED, which will be too harsh if it achieves current forecasts, as the forward PER is only 14.5x. But why would it be higher valued, given that the business looks ex-growth, has a lousy over-geared balance sheet, is seeing broker forecasts reduced, and now its original financial backer is selling?
Gulf Marine Services (LON:GMS)
17p (Friday's close) £182m - Secondary Placing - Paul - GREEN
The same thing happened at this company last week.
Zeus capital announced that major (28.5%) shareholder Seafox has instructed it to sell $10m of shares (about 4% of the company) at a minimum price of 17p - a hefty 15% discount to the 20p share price before this announcement. The price peaked at 24.6p in April 2024.
Lockup of 75 days.
Result of secondary placing - 51.1m shares sold, slightly more than planned at 4.8% of the company, but at the bottom price of 17p.
Seafox remaining holding is 23.7%, which is not comfortable for other shareholders, knowing that the largest shareholder might think it’s fully priced, and may want to ditch some more, perhaps? Also it worries me that demand seems to have been quite weak, since buyers demanded the full 15% discount, and got it.
Looking back at our archive, I see my view in 2019 (at 8.3p) was very bearish, since its debt problems seemed insurmountable, with covenant breaches.
However by Oct 2021, I remember that an experienced & successful investor briefed me that GMS looked like it could gradually resolve its debt issues, and trade out of trouble. I’d even bought a few myself (at 4.6p) and peppered my Oct 2021 report here with risk warnings, rightly so, as it was high risk.
It wasn’t until June 2023 that the shares really began to zoom up, but unfortunately by that point I seemed to have lost interest & moved on.
It’s quite interesting sometimes to look back, and see how special situations work out. This one certainly played out very well.
After that trip down memory lane, what’s the recent news?
Debt reduction 13/5/2024 - reads positively, with net debt down to $256m in Q1, and down again to $250m after a recent payment. The leverage ratio is down to 2.96x EBITDA. Whilst this bit below sounds positive, I’d need more details on the debt refinancing plans -
“Achieving a senior net leverage ratio below three times puts GMS in a stronger position to obtain favourable terms on its debt refinancing. It also allows the Company to benefit from a ten-basis points reduction in funding costs, effective from 1 April 2024, as per the current debt agreements.”
Contract update on 10/6/2024 says the order backlog is $431m, but gives no context or comparisons. Without knowing the timescales of orders, it’s difficult to interpret order book numbers for most companies.
FY 12/2023 Results -
A very impressive 3-year progression, although laid out the opposite way around to what I’m used to -
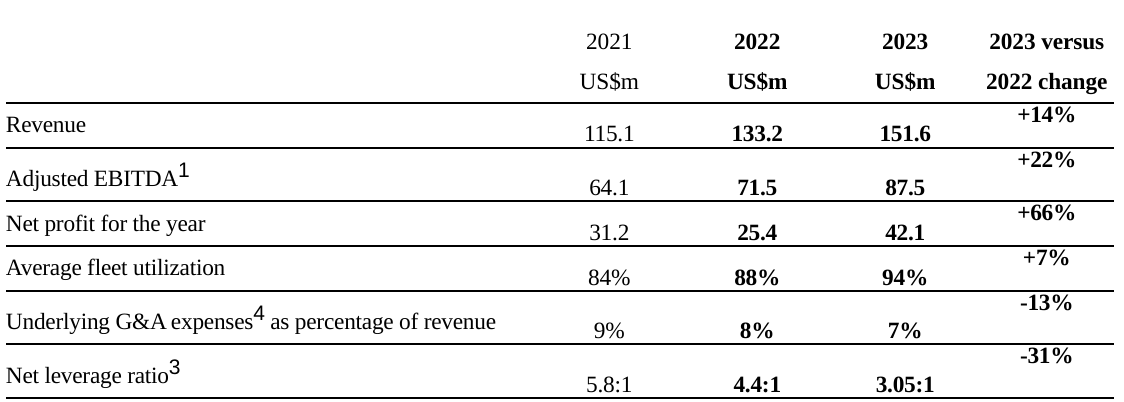
You can see how decisively the net leverage ratio is falling, very impressive I’d say.
On closer inspection the 2023 results suffer from a much higher finance cost, and seem to benefit strongly from impairment reversals, so those areas need careful scrutiny.
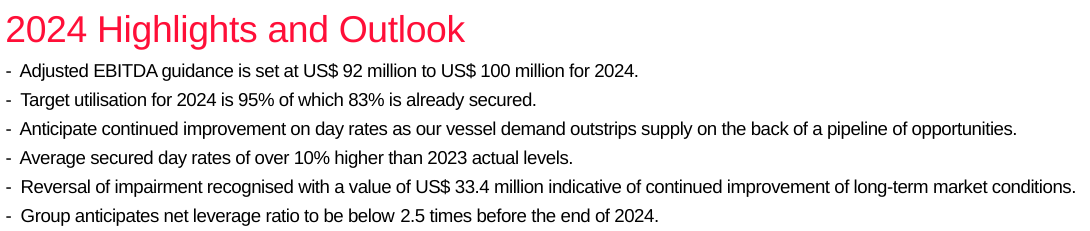
Impressive outlook too -
Balance sheet - total equity is $330m, about £260m, which is well above the market cap of £182m.
Now the risk has receded considerably, and its assets (specialist ships) are clearly in demand, with high utilisation rates and improving fees, then I could see a persuasive argument for the market cap rising to be at or above NTAV of £260m. Imagine if this share re-rates to something more like Ashtead Technology Holdings (LON:AT.) ?!
Paul’s opinion - on a quick skim, I think the big institution dumping shares at 17p could be providing us with a possible buying opportunity.
Given how cash generative GMS is, then I imagine it should be able to refinance, hopefully at cheaper rates too. But that’s obviously the main risk, if something untoward goes wrong that we’re not aware of. Another risk is that, now these special ships are in demand again, then competitors might start building new ones, thus reducing charge out rates.
Overall I think it looks intriguing, and there could be good upside on this, if demand continues to be strong, and the debt can be further reduced. Some risk, but this looks good to me. GREEN.
Graham's Section
Porvair (LON:PRV)
Up 2% to 676p (£323m) - Interim Results - Graham - GREEN
These results are in line with expectations:
Porvair plc ("Porvair" or the "Group"), the specialist filtration, laboratory and environmental technology group, announces its interim results for the six months ended 31 May 2024 ("H1 2024" or the "period").
Some key bullet points:
Revenue up 8% at constant currencies to £94.6m
Adj. operating profit up 2% to £12.5m
Adj. PBT down 3% to £11.5m
Unfortunately, the company doesn’t mention organic growth (i.e. growth excluding the benefit of acquisitions) in its headlines. The operating review reveals that underlying sales were down 3% at constant currencies, once you exclude acquisitions.
The company’s comments on shrinking underlying sales:
… underlying sales revenue was down 3% at constant currency as industrial and laboratory consumables markets adjusted to lower inventory levels and more normal lead times through 2023 and into 2024. The Board's view is that underlying market growth will be more evident in the second half.
Net cash of £4.1m is down from nearly £20m last year. The company notes that £12.7m was spent on capex and acquisitions, but I immediately wonder a) how much of the capex spend was replacement capex, not growth? b) why didn't the company generate any cash to at least partially offset this spending?
Before getting into the cash flow performance in more detail, here are the CEO’s comments:
2024 is unfolding as expected. Over the first six months, strength in aerospace and petrochemical markets, helped by the benefit of 2024 acquisitions, has offset weakness in industrial and laboratory consumables and foreign exchange headwinds. This has been in line with management expectations. The trading outlook for the second half of the year is positive…
The Group's fundamental demand drivers have not changed. Porvair remains well positioned to take advantage of tightening environmental regulation; the growth of analytical science; the need for clean water; the development of carbon-efficient transportation; the replacement of plastic and steel by aluminium; and the drive for manufacturing process quality and efficiency….
Cash flow statement for the six month period shows:
£10m spent on acquisitions
£5m of cash generated from operating activities (after tax)
£2.4m of capex and nearly £2m spent on lease payments in the “financing” section of the cash flow statement.
Therefore, the cash generated from operating activities was barely enough to cover capex and lease payments - and that’s before counting the cost of acquisitions.
But if we drill into it a little more, we find the real culprit in the footnotes: there was a nearly £8m cash drain from receivables, i.e. from rising amounts owed by customers.
Referring back to the CEO’s notes:
The Group normally sees an outflow of working capital in the first half of the year. Working capital increased by £7.0 million (2023: £5.0 million) in the period.
The working capital outflow was about £5m in both 2023 and 2022, so this explanation makes sense (although it’s unfortunate that the working capital outflow was even bigger this year than in previous years)..
Graham’s view
Paul has been positive on this one and included it in his top 20 stock list for 2024. I also have a generally favourable impression of the company, for a variety of reasons.
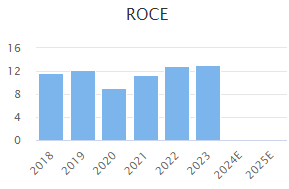
For one example, the company highlights its return on capital employed as a KPI and calculates that it earned a ROCE of 14% in H1. The ROCE is much higher if you write off goodwill and other items, but I’m not sure that it’s entirely fair to do that. In any case, the company does have a good track record of generating acceptable returns. Here is Stockopedia’s view:
From a macro point of view, I tend to agree with Porvair that it is well-placed for the future with likely increasing demand for filtration/environmental products.
The stumbling block here is nearly always price: how high is too high?
The share only gets a ValueRank of 31, due to a high PE Ratio, an expensive PEG ratio, and a low yield:
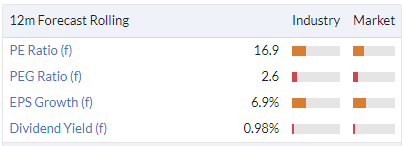
Today’s results show earnings per share of 18.1p for six months, while the share price is now 676p.
And the sequence of earnings upgrades may have flattened out a little:
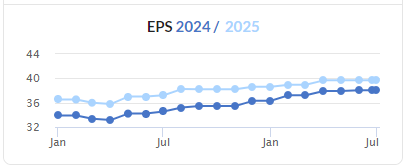
If underlying revenue growth was positive I could maybe hold my nose and stick with a GREEN stance, but with underlying sales in reverse I don’t think I can quite manage that. Therefore, this one is AMBER/GREEN for me. Hopefully the management forecast will hold true and we can start to see some underlying growth again later in the year.
In summary: I view this as a nice stock to hold, but this doesn’t strike me as an appetising entry point.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Porvair(PRV) is a good company but my concern is that its success has been driven by CEO Ben Stocks who has been running the company for 26 years. He is due to step down within the next year after a new CEO has been found. The forthcoming change at the top, along with the valuation, is the main reason I am reluctant to invest at current share price levels.
RNS out yesterday for @GMS reveals Fiera Capital acquired 3.47% holding (presumably in the placing). They are a serious bunch, and clearly thought 17p was a good entry pont.
Thanks for your analysis on Gulf Marine Services (LON:GMS) , Paul - I remember talking briefly to you about it at Mello last November (as a safer share than Plexus Holdings (LON:POS) in the oil & gas services sector). I think at that point it was just about to be my largest holding after a very good run. Since then I've top-sliced a little and it's fallen to second place, but I still think the rapidly falling debt has the potential to transform both the balance sheet and (eventually) the share price in time.
fyi some international CGT rates:
I would lay a little bet that Higher Earners, will be disallowed ISA tax fee status on their ISA investments, once a threshold is past in the not too distant future.
It's possible although I'd be surprised if they took this step - very bad form to change something like this retrospectively - a lot of people will have used ISAs as a key part of their pension planning. I think more likely they will target pensions to grab some extra tax - the 40% tax relief on contributions will probably be reduced to 30% would be my guess.
Unfortunately pensions have become a great source of issue with Drs and State beneficiaries of Public pensions etc, so quite a bit of complication there, although a juicy target of value. Imposing a threshold for ISA's on high earners plays to a particular gallery.
I would like to think our tax systems couldn't get any more complex, but Govts of all stripes are desperate and careless of consequences in their desperation.
It will be levelled down to 20% IMO - it's what Labour would see as 'fair' and TBF, whilst I'm only at an age when it will start benfiting me, it makes sense; however, I am running out of ideas on how to effectively deploy my money without getting taxed at every corner. Thankfully I do have dual nationality in a country with very favourable tax incentives, so more trips to Mauritius may be required.
Re: Auction Technologies and Private Equity
Private Equity generally want to realise their investments within defined time lines, and 3-5 years isn't unusual. Some PE houses, like us ordinary punters, get stuck for longer, because they can't sell on to another private equity owner or find a suitable buyer , but with a ready market like AIM were they don't see much further upside, they will start to bale, particularly so if the sale still locks in some of their original IPO price.
I don't know whether the prospect of a Labour Govt, with their desire get rid of the current 'carried interest' treatment of PE Partners earnings as a Capital Gain, rather than Income, is prompting them to act now, rather than later also.
I am sure we are looking forward to CGT rates themselves going up!! Probably one of the few certainties of the future.
Hi Paul- in your weekend pod/chat you asked a preference on what’s covered.
Personally, focussing on the good sized articles on the ‘Green’ and good quality companies, of ‘reasonable’ size (minows with no liquidity I ignore). I think focussing the good articles on the solid, best quality or value and changes is great and maybe take some time back on the smallest / dross / low to no liquidity shares. just my opinion but may help goo my forwards!
I agree this is a very good suggestion. If a share is listed as red or red/amber, because I trust Paul's judgement, I will often just not read the full writeup. Amber (particularly for potential turnarounds) and above is where I read fully and get much more value out of the service.
I always enjoyed your podcasts Paul. Yes - enjoyed - because I cant get them any more since Google dumped that route. I did try unsuccessfully with one suggestion to an alternative route a couple of weeks back.
Any help which will be good for a non techie such as myself would be much appreciated. YouTube for instance?
Grateful thanks in advance of a dreamy return to a PS-enhanced weekend this weekend coming.
Spotify works very well for me!
I'm using Antennapod now. I really hate YouTube for podcasts!!
You could try https://shows.acast.com/paulsc...
Thanks for that Jim. I see that on my laptop. Is it available as an app on my phone. do you know?.
I just tried it in Google, typing in 'Paul Scott Acast', and clicking on that and it works fine.
Found it quite easily on YouTube Music app.
You can get Paul's podcasts on "UK Radio" app for mobiles, includes access to every UK radio station.
I've transferred to the Podbean app. Seems to work ok.
Spotify!
Re advice on H2 find Paul's podcasts going forwards, thanks to all for their suggestions.
UK small caps appear to be a little perkier this morning, surprising as I thought the evolving French political situation would continue to dampen any enthusiasm. Hopefully the former is in anticipation of an end to electioneering in the UK and a decisive result one way or the other.
Le Pen did not achieve 37%+ and it seems difficult to get 50%+ in the second round due to the tactical voting that will take place.
I believe this is the reason that the markets are up today; especially the CAC.
Interesting to see the outcome next Sunday and the reaction on Monday morning.
All the best
Indeed. Many of my shares got clobbered on Friday afternoon, probably some risk-taking off the table. Only to bounce back strongly this morning.
Its going to be a bit of a volatile week. What with polls and the situation on the French elections getting clearer towards Sunday, as well as the UK's own election on Thursday.
Morning Paul, many thanks for all the SVCR reports. I think that the new format is excellent. I have just listened to the new podcast, which i find very helpful, would like to make a couple of comments.
It is quite unbelievable that a country with a population of over 250m people that the Americans can only find these these two presidential candidates. Especially as there is a huge amount of money in US politics.
With regard the London Tunnels there is an article in yesterdays Sunday Times saying that the FCA prevented them from listing in London, The reason given was that the FCA did not believe the valuation so the company decided to list in Amsterdam at the same valuation. This, imo, is ridiculous. Its not the job of the FCA to decide the valuation of a company.
Protect the consumers ie investors in this case, is their main priority!
Good on them and perhaps they should do it more often.
All the best
The FCA failed to protect investors from Neil Woodford and the mini bond scandal. Plus there are quite a few companies listed that would appear to be of extremely dubious quality.
I agree and add that there are quite a lot not quite a few so we do not want more rubbish ones listed.
The company in question was valued at £130m! and that was by supposedly having 2m visitors a year to go see the famous London tunnels??
Just so you understand the nonsense on that prospectus ; the Madame Tussauds Museum attracts 2.5m visitors a year from all over the world.
All the best
With regard the London Tunnels there is an article in yesterdays Sunday Times saying that the FCA prevented them from listing in London, The reason given was that the FCA did not believe the valuation so the company decided to list in Amsterdam at the same valuation. This, imo, is ridiculous. Its not the job of the FCA to decide the valuation of a company.
Interesting
hmmm i wander what then uplift in valuation is compared to the "cash" invested to date.
Presumably there is some rule that allows them to do this - its hard to know if its fair cop without knowing what the rule is and why they blocked it. If they use this rule rarely and its a ridiculously speculative valuation - i can kind of see that they may want some proof its not just a huge ponzi scheme. At the end of the day each country will have its own listing rules so if this is rarely applied rule i would probably side with the FCA here is they are protecting consumer investors.
I agree the FCA and their never ending bureaucracy is one reason that listing business in down in the UK. It took friends 12 months to overcome this bureaucracy in the meantime their business opportunity had gone elsewhere. In this country we seem to promote incompetence the former CEO Andrew Baily was made Governor of the Bank of England. In my view a disastrous decision.
It is quite unbelievable that a country with a population of over 250m people that the Americans can only find these these two presidential candidates.
This is what the problem is, to be in US politics a personal worth of multli-billion dollars is a prerequisit.
This is what the problem is, to be in US politics a personal worth of multli-billion dollars is a prerequisit.
i didnt think Joe Biden was "meant to be" particularly wealthy !!!!! - guessing we best not ask him the answer to that question though
Nonsense. Trump is the only billionaire ever to have been U~S president.
List of presidents of the United States by net worth - Wikipedia
Maintel Holdings (LON:MAI) in demand this morning. Fwd p/e 6.6 and peg 0.1, psr only 0.32, Mtk cap £32 m.
Maintel was tipped in the SCSW at the weekend
if a miracle happens and you get a quiet day this week Graham could you backtrack and give your views in #LIO and #POLR. Thanks
Good idea Alex. Thanks for the suggestion!
Holders of Advertising Testing platform System1 (LON:SYS1) may be interested to see that at the end of last week they RNS’ed that their YE results will be announced on 3rd July.
This is 28 days earlier than last year (1st Aug 23) and 9 days earlier than the year previous (12th July 22). Could this be a case of SYS1 management being keen to announce further good news? In February they noted that they were only “Scratching the surface of the opportunity” and since have announced a Q4 sales increase of 30% and the intension to pay a dividend.
We will know more on from their RNS and Investor Meets Company presentation on Wednesday - I hold; so am biased!
Maybe. Or there could be a be innocent explanation for System1 (LON:SYS1) earlier results?
They changed auditors since last year's results. This year's auditors might be more efficient? Last year's ones may have been incompetent and slow (and hence fired?)
Last year, they were also resolving the lawsuit with System1 USA at the end of June, so maybe management attention / auditor attention got delayed with those matters...
Plexus Holdings (LON:POS) breaking news - CEO and Finance Director both retiring, to be replaced by colleagues.
Porvair (LON:PRV) Decent H1 results, in line with management expectations and only marginally lower than last prior year which included restocking benefit. Reference to continued de-stocking in industrial in Feb results RNS raised risk of a warning at the half year but all seems on track. A large petro order to be shipped in the second half and anticipated better performance in H2 suggests that this could do 40p FY eps putting it on a p/e of just over 16 which is historically cheap. If risk-taking returns and barring any accidents I think this could easily return to a p/e of 20-plus.
In the meantime, a safe place to invest and always with the possibility that they get bought.
Thanks for that summary mammyoko. Having only just invested in them , they look a solid outfit and the narrative is straightforward with very little management speak. In fact I only had to read it once. hHeading upwards I think both in profitability and SP
Paul, could we have the benefit of your opinion on this very overlooked industrial
Threepeat,
Could i politely ask that you add the ticker of the company you are talking about to save readers the bother of scrolling back to find out.
Please.
With all due respect Helvellyn I was replying to Mammyoko note on and about Porvair (LON:PRV) and the reply is linked by a line on the left
Not if you read in an unthreaded format which a lot of people find the most efficient way of capturing new comments.
Morning Paul, I thought that you might cover Porvair (LON:PRV) ?
The interims look to be in line with an encouraging second half anticipated. CEO, Ben Stocks is not given to bluster so I have confidence in his views.
All the best
Sigmaroc (LON:SRC)
More outside the box thinking from this entrepreneurial management team. A significant holding for me.
SigmaRoc and Duo Group Forge Strategic Alliance
to Revolutionise Sustainable Limestone Aggregates Supply in the UK
SigmaRoc, the Northern European quoted lime and limestone group, is pleased to announce it has entered into a 10-year ground-breaking strategic alliance with Duo Group to produce and sell sustainable limestone aggregates in the UK market. This 10-year agreement has the potential to generate incremental revenue of over £150 million over the course of the alliance, whilst significantly reducing SigmaRoc's environmental impact through the repurposing of limestone quarry waste.
Under the terms of the agreement, Duo Group has agreed to establish state-of-the-art processing plants at up to seven SigmaRoc limestone quarries to reprocess historically uneconomical quarry tip waste into a premium construction material. The process therefore advances SigmaRoc's ambition of utilising 100% of the resource it quarries.
Innovative Waste Processing
Quarry tips, also known as spoil tips, are accumulations of previously uneconomical processable material removed by the quarrying operations. By repurposing this previously overlooked resource, using state-of-the-art processing equipment installed by Duo Group, the Strategic Alliance aims to extend the operational life of quarries, conserve natural resources, and align with sustainable development goals. This initiative also supports SigmaRoc's ambition of utilising 100% of the resource it quarries, ensuring a more sustainable future for the construction and infrastructure sectors.
Alliance Structure
Under the agreement, Duo Group will establish large scale state-of-the-art reprocessing plants to cover material preparation and processing, load and haul, plant operation, and material dispatch. SigmaRoc will put at the disposal of the Strategic Alliance all unprocessed "tipped" materials which previously held no commercial value.
Sigmaroc (LON:SRC) counterparty appears to have quite a job on its hands to find the money to put in processing kit on any scale
Morning Rhom, as you infer no indication of how the installations are to be funded in the RNS, although it does suggest that this will be be sourced by DUO?
I read an article on the us's big infrastructure bill and the megacycle for many associated us industries including quarrying companies (eg. Martin Marietta Materials (NYQ:MLM) , which have a natural moat if no current oversupply and unusual demand due to regulatory issues and time to 'get going (!)'.And there being speculation whether a similar megacycle replacing outdated, 'crumbling' public infrastructure might happen this side of the pond in Europe.Could the EU fund and coordinate that or would individual countries be responsible?I don't know enough about EU legals, economics, politics.
My morning smallcap tweet: Forging ahead
Aptitude Software (LON:APTD) Ascential (LON:ASCL) Libertine Holdings (LON:LIB) Verici Dx (LON:VRCI) Induction Healthcare (LON:INHC) Argo Blockchain (LON:ARB) Sigmaroc (LON:SRC) Feedback (LON:FDBK) SEEEN (LON:SEEN) Harland & Wolff group (LON:HARL) Argent BioPharma (LON:RGT) Codex Acquisitions (LON:CODX), Porvair (LON:PRV)
◄Aptitude Software (APTD)► >£4m three yr contract for Fynapse and the Aptitude Accounting Hub. [SP=370 Cap=216m]
◄Ascential (ASCL)► talks on sale of sale of Hudson MX ongoing with multiple parties. [SP=337.82 Cap=682m]
◄Libertine (LIB)► confirms £2m placing at 1.5p, a nil discount, to keep the lights on for a year. [SP=1.5 Cap=2m]
◄Verici Dx (VRCI)► hermo Fisher Scientific has confirmed the completion of the transfer and achievement of all transfer-related activities for the pre-transplant prognostic testing technology licensed by VRCI. Triggers a further milestone payment. [SP=6.05 Cap=15m]
◄Induction Healthcare (INHC)► sells subsidiary Horizon Strategic Partners for £1.2m completing the divestment of Induction's non-core assets. [SP=11.49 Cap=11m]
◄Argo Blockchain (ARB)► extends its loan with Galaxy Digital Holdings to Dec 28. Balance down to $5.7m. [SP=8.5 Cap=60m]
◄SigmaRoc (SRC)► 10 year strategic (natch') alliance with Duo Group to produce and sell sustainable limestone aggregates in the UK market. Potential £150m rev total over the period. [SP=66.65 Cap=739m]. I hold.
◄Feedback (FDBK)► wins contract for Bleepa Community Diagnostics Centre worth £500k over 1 year plus 1 yr option. [SP=70 Cap=10m]
◄SEEEN (SEEN)► FY-Dec accounts not ready, suspension. Expects publication by 5 July. [SP=3.01 Cap=4m]
◄Harland & Wolff (HARL)► FY-Dec out but accounts not ready due to the wrangle over deferred rev reconition. Suspension. Expects accounts in week commencing 8 July. FY-Dec - rev only £87m and a thumping loss. Keeps target of £200m this FY. UK Export Finance loan - "Further work continues on this facility and the Company expects UK Government to reach a decision after the General Election. Should there be any material delays to securing the facility post the General Election, the Company's ability to execute new and large contracts would be adversely affected". [SP=8.38 Cap=16m]
◄Argent Biopharma (RGT)► $500k placing at 80 cents (~A$1.20) (a 400% premium to the 15-day VWAP of A$0.30 prior to the stock being placed in a Trading Halt on 28 June), to continue the development of key drug candidates, CannEpil and CimetrA. [SP=17 Cap=15m]
◄Codex Acquisitions (CODX)► FY-Dec. Material uncertainty going concern stmt. [SP=5 Cap=m]
In line: PRV
Good morning Paul, I'm listening to the latest podcast and I wish to share my feedback regarding the brief comments. I like this new approach and I think it's very useful to have a little more info and cover more companies. Maybe adding a couple of lines in a micro section would be useful (a brief comment on the news but more detailed than the table)
Thanks Abel,
Yes good idea, I'll see what Graham thinks, and we might adjust the format a little to something in between the super-brief comments in the table, and a shorter section below. Leave it with us!
Regards, Paul.
Good morning Paul, a big thank you for both your SCVR reports and weekly podcasts! Both are invaluable resources for me, as well as being easy reads/ listens as they include humor and anecdotes.
To answer your podcast question about whether to continue with your new SCVR format, which adds short in table summaries to the existing in depth share reviews, my vote would definitely be the new format.
Agree strongly on the new format.
Hi Paul,
All of your work (SCVR reports, large sections, short sections, your podcasts, your share ideas, your traffic light system, your spread sheets, your new videos, your proposed micro comments) are invaluable resources for me, in fact they are all my first go to choices along with stockopedia.
This is because I believe in you and your work because I know that you are truly the most genuine and honest of people in this field of investing.
So please continue with your new SCVR format, adding the short summaries to the existing more detailed share reviews.
Best regards
Neville
Aviva (LON:AV.) announce completion of much-trumpeted share buyback scheme after purchase and cancellation of, er, 0.1% of existing shares. That'll make all the difference....
Aviva (LON:AV.) share buyback was 300m shares, that is around 10%?
Aviva (LON:AV.) It was £300m worth of shares ( So nearly 63m) not 300m shares I believe? This makes it approx 2.5% of shares held
Yes, sorry misread the statement.
I hold Aviva (LON:AV.) and would like some clarification as to how many shares were bought back and how many were subsequently cancelled.
Aviva (LON:AV.) Apologies. That's what you get for reading RNS on an I-phone before coffee. I saw the 3 million cancelled that day not the 63 million purchased overall. 2.5% repurchased and all cancelled. None in treasury.
Are you sure?
Aviva (LON:AV.) I don’t hold
Morning Paul. A terrific review of Gulf Marine Services (LON:GMS) and Auction Technology (LON:ATG) before the day’s RNSs even come out. I ran the rule over the latter on Friday and came to a very similar conclusion - but with the caveat that growth may only be stalled by the macro. Nevertheless you captured this possibility implicitly with your observation that a PER of 14x will look very good value if growth reaccelerates. I think it’s worth keeping this on the watchlist, although I spent the cash I might have fed into ATG by reopening my position in Kainos (LON:KNOS. One to avoid for adherents to the curse of BnB.