Small Cap Value Report (Mon 10 Jan 2022) - COG, ELTA, MEX, QTX, BOOM, MRK, NGHT

Good morning, it's Paul & Jack here, raring to go, with what should be a busier week for trading updates. Today's report is now finished.
Agenda -
Paul's section:
Cambridge Cognition Holdings (LON:COG) (I hold) - contract win, and positive outlook comments from CEO. This remains one of my favourite small growth companies.
Electra Private Equity (LON:ELTA) (I hold) - final stage of the breakup of this investment trust. ELTA now becomes "Unbound", the holding company for Hotter Shoes (comfy shoes for the over 55s, mainly women). Looks cheap, but I reserve judgement until we get clean accounts for the standalone company in due course.
Quartix Technologies (LON:QTX) - a really comprehensive TU for FY 12/2021, giving very clear profit guidance. This share looks expensive, but the international growth now being achieved looks impressive.
Audioboom (LON:BOOM) - we didn't spot the series of "significantly ahead" updates in the autumn, sorry about that, as this share has done really well. Another impressive update out today. There's a lot to like here, apart from the high valuation. Nice to see a serial disappointer turn the corner into being a viable, fast-growing company.
Marks Electrical (LON:MRK) - impressive figures in this update to end Dec (Q3). However, I question how sustainable its sector-leading profit margin is?
Nightcap (LON:NGHT) - very strong like-for-like (LFL) sales growth in July-Dec, but how much of that has been driven by refurbishments? We're not told. Also the cash figure reported is gross, not net. There's a big difference, and the company's balance sheet is not strong, as it claims. Too expensive for me, and I don't like selective reporting of positives.
Jack's section:
Tortilla Mexican Grill (LON:MEX) - strong end-of-year update from Tortilla which ensures full year results should be materially ahead of expectations. Profitability is helped by Covid-related government initiatives and profits over the next year or two are forecast to fall, so there’s still a question over the underlying profitability of the enterprise. But as an operator, Tortilla looks good and is ready to roll out.
Does anyone read this I wonder? It's still useful to include, to help new subscribers, and as an occasional reminder to existing subscribers who expect us to be clairvoyant.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Cambridge Cognition Holdings (LON:COG) (I hold)
130p (up 5% at 08:40) - mkt cap £40m
Contract win with a top 20 pharma. £700k over 2 years. Upbeat comment from CEO (who I rate highly, having turned around the company) - this is almost a trading update, hence me mentioning it -
“This is the second pharmaceutical client to award Cambridge Cognition major contracts for cognitive assessments for schizophrenia in the last year(1) . Approximately 30 clinical trials on new drugs for schizophrenia run every year(2) , demonstrating the potential for further sales in this therapeutic area….
We are pleased with this client win which continues the very positive momentum in the business and further improves our revenue visibility."
My opinion - I remain keen on COG, because it has reached profitability, shouldn’t need to raise any more cash from shareholders, and has good tailwinds from increased drug testing online (triggered by the pandemic). It has relationships with the big pharmas, and wins repeat business at high gross margins. Mkt cap only £39m, probably because it has disappointed in the past, so some investors remain sceptical perhaps?
Electra Private Equity (LON:ELTA) (I hold)
67.2p (unchanged, at 09:10) - mkt cap £26m
Unbound Group planned AIM listing; trading update
As planned, this is the last stage in the dismantling of Electra Private Equity. The last big investment (casual dining chain “Fridays” [formerly TGI Fridays]) was disposed of through a demerger, with ELTA shareholders receiving Hostmore (LON:MORE) (I hold) shares. That looks very promising to me, priced way below sector peers, so I am hoping for a 50-100% re-rating of MORE in due course.
So far, the demerger has been a flop, with Numis and the company itself noticeably failing to drum up buying interest in the company. That doesn’t matter in the long term though, if we’re patient.
The last bit of ELTA is Hotter Shoes (comfy shoes for the over 55s). This is now being renamed “Unbound Group PLC”, will carry on the ELTA listing, but transferring onto AIM, to reflect its currently tiny market cap of c.£25m.
The Unbound strategy is to capitalise on its big customer base (affluent over 55s) and expand into complementary product/services, on a low-risk partnership basis. Potentially interesting, so let’s see how it develops.
Unbound's expanded offering beyond footwear is expected to feature apparel, wellness and lifestyle products and services, with third-party complementary brands featuring alongside new Unbound brands, as well as Hotter.
Today’s update explains the strategy, which I won’t repeat here, see RNS if you’re interested.
Timescale -
First Unbound revenues from sales of products other than Hotter footwear expected in Q2 2022, with medium-term ambition to generate more than half of Unbound's profit from non-Hotter products.
Current trading - sounds OK -
Hotter has continued to deliver strong growth during November and December, with revenues being +9% compared with the previous year and gross margin continuing to perform positively at 65.5%.
This robust performance despite supply chain cost and availability issues, coupled with the negative impact of Omicron suppressing high street demand in the latter weeks of December is encouraging.
I particularly like that gross margin of 65.5% - very high.
My opinion - I’d like to see the first set of proper numbers as a standalone listed company, before forming a clearer view. At the moment though, I like Hotter Shoes niche, and the market cap of only £26m seems a very gloomy assessment by the market.
It has been suggested that the price could be artificially depressed by forced sellers - some of the original ELTA shareholders are apparently not mandated to hold individual company shares, only investment trusts. In which case, we could have an opportunity to buy now, at an artificially depressed price - that’s just the sort of special situation that I like, buying a quid for 50p.
Personally I hold a small existing position here, and am waiting for more facts & figures, before deciding whether or not to increase my position (or sell, if the numbers are no good).
.
Quartix Technologies (LON:QTX)
Quartix Technologies plc, a leading supplier of subscription-based vehicle tracking systems, software and services, is pleased to provide an update on trading for the year ended 31 December 2021 (the "Period").
Nice clear guidance here, with specific numbers, and a market expectations footnote, excellent stuff! -
The Board is pleased to report that it expects revenue and free cash flow to be in line with consensus market forecasts1 at £25.6m and £3.8m, respectively. Adjusted EBITDA is expected to be substantially ahead of those forecasts,1 at £5.7m.
[1] The Board believes that consensus market expectations for 2021, prior to this announcement, were as follows: revenue: £25.6m; adjusted EBITDA (which excludes the US 3G provision) £5.0m; free cash flow: £3.5m.
Personally, I’m not interested in EBITDA, and would prefer to see the adj EPS guidance, because that’s the number we need to be able to quickly value the shares, by comparing it with the share price.
If revenues are in line, but EBITDA is substantially ahead, then that suggests gross margin and/or overheads must be better than expected. Yes, the commentary says that some marketing spending was deferred into 2022, therefore the higher than expected EBITDA is not significant, it's just down to timing of discretionary marketing spending.
Checking back to last year’s accounts, here are the comparisons -
Revenue - 2021: £25.6m, 2020: £25.8m - so slightly down this time
Adj EBITDA - 2021: £5.7m, 2020: £7.9m - a decrease of 28%
I hate to say it, but that’s not very good, is it?
Reduced EBITDA is blamed on increased marketing spending vs 2020. So why hasn’t that fed through to faster revenue growth? There is the drag of declining (low margin) insurance telematics. Core fleet revenue did grow, by 8%.
Continuing disruption from covid is mentioned, so hopefully growth might accelerate in future - it really does need to, if this share is to retain its growth company rating.
Fleet - the figures here look more impressive.
The subscription base (i.e. customer vehicles using Quartix telematics) grew an impressive +17%, to 202,734. Particularly good growth in France (+29%), and USA (+19%). Also Rest of Europe was up 141%, but from a low base.
Maybe this is why Quartix shares are on a high rating - because it’s demonstrating strong overseas growth, which could result in it being a bigger business in a few years?
Also, the subscription growth is much better than revenue growth, which could be because new customers only contribute a small amount in the first partial year, but would then show up better the following (full) year?
It’s good that the company discloses the attrition rate (customers lost), which is 11.6% (improved from 12.2% in 2020).
Insurance division - low margin business which Quartix has been winding down, now described as “insignificant” for the company (revenues, and profits), which is good, as it should no longer be a drag on revenue in particular - declines there partially masked the growth in the core business previously.
Diary date - 1 March 2022, for FY 12/2021 results.
My opinion - this is a comprehensive update, giving lots of information, and clear guidance, so a thumbs up for that.
My main issue is that revenues, and profits at Quartix have gone nowhere in the past 5-6 years. In fact, profit has actually fallen. Yet it’s rated as a growth share, with Stockopedia showing the forward PER as 41.3
See the graphs below - reduced profits, but graph 4 shows that the shares have re-rated to a much higher PER, which is very surprising for a company with declining profitability.
The bull case is that spending is now being done on marketing, which is driving good international growth, which would take time to feed into profits. I can see that argument holds water, but it’s been several years already, waiting for this growth.
As you can see from graph no.5 below, it has been a consistent, and quite decent dividend payer, unusual for this type of company. So is it a value share, or a growth share?
.

.
Overall, I do like the international growth coming through now. However, you do have to take into account that there’s attrition each year from losing customers too, which shouldn’t be ignored. It’s the net increase that matters. There’s also constant pricing pressure, due to widespread competition.
On balance, I can see that the international growth could result in a much bigger business, and revenues are recurring in nature, monthly subscriptions typically, which tend to be valued highly by the stock market.
As things stand now, Quartix shares are certainly not a bargain, despite the share price essentially trading sideways since the peaks in 2016. However, I do like the international growth coming through, so this might be worth considering, if you can stomach the high valuation.
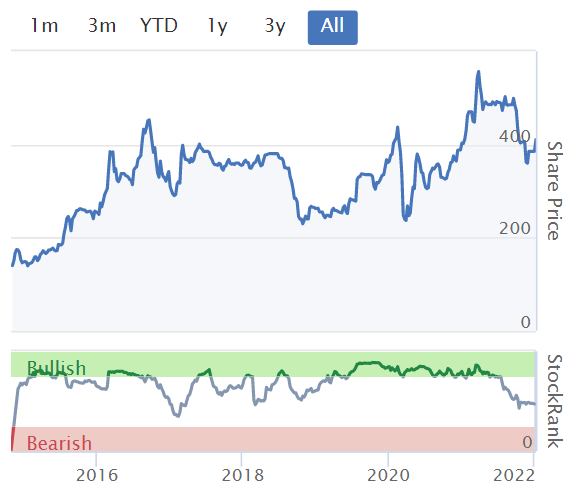
Here's the long-term chart, and note the middling StockRank of 51 , which has come down from previous higher levels, so the disappasionate StockRank system is a bit more sceptical these days -
.
.
Audioboom (LON:BOOM)
1460 (up 3% at 09:41) - mkt cap £229m
Looking back through our archive, we last covered BOOM in July 2021, when sales growth was increasing, and it received a daft all-paper bid approach, which was never credible. Unfortunately, I dropped the ball on this one, and didn’t notice that the company issued strong trading updates in succession in H1 2021 - “significantly ahead” updates on 13 Sept, 13 Oct, and 16 Dec. It’s really bad that we missed those here at the SCVR, so profuse apologies, as this turned out to be one of the biggest share price risers of 2021. It came up the other day on one of my year end screens (biggest % annual risers).
Possibly I didn’t look at its previous trading updates due to skepticism, given the company’s lamentable long-term track record? Or I might have wanted to actually see the full year numbers? Anyway, we missed a big riser, so that’s a bit disappointing.
They’re not just pleased, but delighted!
Audioboom (AIM: BOOM), the leading global podcast company, is delighted to provide a trading update for the 12 months ended 31 December 2021.
Revenue growth - very impressive indeed, at +125% to $60.2m - that’s all organic growth too, I believe (i.e. no acquisitions of other companies to boost growth).
Acceleration of growth in H2, since H1 revenue growth was +93%
On profitability, it quotes both EBITDA and proper profits -
Maiden annual adjusted EBITDA(3) profit, ahead of market expectations, of approximately US$3.0 million (2020: US$1.8 million loss), with the Company recording positive adjusted EBITDA(3) in every month in 2021
· Maiden annual net profit of approximately US$1.4 million (2020: US$3.3 million loss)
3) Earnings before interest, tax, depreciation, amortisation, share based payments, non-cash foreign exchange movements and material one-off items
H1 adj EBITDA was only $0.2m, so H2 works out at $2.8m - impressive.
Note that the $(3.3)m loss last year, was the statutory loss, after all costs. The adjusted operating loss last year was $(1.7)m.
Cash - looked tight when I last looked, but currently $3.0m, with $3.3m of undrawn loan facility. Maybe it can carry on without a placing, but with a big market cap now of £229m, and terrific growth numbers, they would be crazy not to do a placing - from a position of strength, for the first time ever! Raising say £10m would only dilute existing holders by about 5% - worth it, for the reassurance of having a cash buffer.
Often companies which fail to raise fresh cash when their share price is buoyant, regret it once the party is over.
Outlook comments - positive - there's good visibility too, with advance ad bookings -
Significant pricing growth for premium inventory in 2022. Q1 2022 Average Unit Rate (AUR) for top 25 podcasts is 26% higher than Q4 2021
· As of 31 December 2021, the Company had contracted revenue in excess of US$45 million for 2022 through advance advertising bookings. At 31 December 2020, US$20 million revenue was contracted
The Board is delighted to report this strong performance for the year to 31 December 2021 with the Company exceeding market expectations once again. The Board continues to be excited about the opportunities for the business and is confident that this positive momentum will continue into 2022.
Global growth - BOOM is not just a UK business, it’s doing well overseas too, which helps explain why the market is prepared to value it so highly -
Our revenue growth has once again significantly outperformed the wider industry. We've gained strong market share, and now rank as the 4th largest podcast publisher in the US. Alongside our ranking of 2nd in New Zealand and 3rd in Australia, we continue to develop a strong global position.
Investor presentation - on Investor Meet Company at 15:00 on 20 Jan 2022.
My opinion - when looking through the numbers recently for BOOM, my main reservation is that the gross margin is low - only 21% in H1. Therefore, there’s not much operational gearing. So it needs to achieve continued very high revenue growth, to move the dial on profitability. And companies which have scraped along for years, with a tight cash position, often have pent-up costs, which snowball once they reach cashflow breakeven. Hence forecast profits are rarely achieved.
Receivables looked high in the interim numbers, and cash looked tight. So I’d want to see another set of numbers before being convinced this is turning into a profitable company.
Much to my surprise, after many years of dreadful performance, BOOM looks to have reached an inflexion point, where it’s becoming a viable, and very high growth business. Internationally too. If that growth can continue, then it’s looking quite exciting.
How do you value BOOM shares though? It’s sky high at the moment, at £229m, so it’s really up to you to decide if you’re prepared to take a leap of faith (with the risk of it plummeting if growth slows), and pay up, or whether (like me!) you want to watch from the sidelines as the price goes up & up!
Your money, your choice!
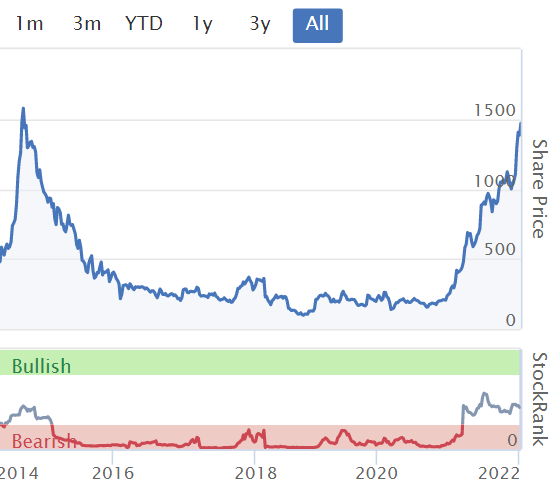
As an aside, it’s really pleasing when a serial disappointer finally turns a corner, and becomes viable. As you can see from the long-term chart below, investors who spotted the turning point, have a multibagger on their hands now. Although also note how the initial boom in BOOM in 2014, was followed by a 6-year flop. That said, the company was just a start up back then, so not comparable at all to today’s proper business.
The more I think about this, the more tempted I am to have a little speculative punt on BOOM (very late to the party though, which worries me). Also we need to consider stock market conditions - the US (which sets the direction here) is seeing a widespread & large sell-off in highly rated growth stocks. Hence I'm worried this might be a really bad time to start buying a highly rated stock like BOOM? On reflection, I'm inclined to add it to the watch list, and wait.
.
.
Marks Electrical (LON:MRK)
119.5p (unchanged, at 11:31)
No. shares on AIM admission (Nov 2021): 104.95
Mkt cap £125m
This is an online electricals retailer (mostly kitchen appliances), website is here, which listed on 5 Nov 2021, at 110p per share.
The StockReport is not yet populated, so I’ve raised a green blob to chase up HQ on this.
For background info, a subscriber gmtrader has posted an excellent briefing on the company here. He even publishes a short Q&A with the CEO. I’m impressed, thank you for posting that!
I’ve looked at MRK myself at some point in late 2021, but can’t find my notes either here, or on paper. However, I do recall thinking it looks interesting, and a nice little business. Much better than larger competitor Ao World (LON:AO.) - due to having a smaller, simpler, more focused business model. The founder of AO World always struck me as a bit of a fantasist, and not enough gritty, hard-nosed businessman, which is what you need in a low margin sector.
The year end seems to be 31 March 2022, so today’s update is for Q3 to date.
Marks Electrical Group plc ("Marks Electrical" or "The Group"), a fast-growing online electrical retailer, today announces its trading update for its third quarter ended 31 December 2021 ("the period" or "Q3-22").
Revenue in Q3 is up 27% on LY, and YTD (year to date) revenue up 55% - so slowing growth in Q3, but still good. Paragraph 8 of the Admission Document does fore-warn that growth would slow in H2, so no surprise there.
On track to deliver full year revenue target.
On track to achieve adj EBITDA margin target of 9% (much larger competitor AO World only achieved 3.8% adj EBITDA margin in FY 3/2021, which looks to have been a one-off good year! So MRK is achieving a much higher profit margin than AO).
Current trading -
Our momentum has continued into January and we look forward to maintaining our performance management discipline [Paul: eh?!] on revenue, profit and cash in the final months of the year."
Thumbing through its Admission Document, it strikes me that the company doesn’t have much track record prior to the pandemic - e.g. look at the modest profit, and low profit margin in FY 3/2019, and FY 3/2020, which is what I would expect from a company in this sector.

.
Hence I am wondering how realistic it is, to expect MRK to continue achieving the 9% EBITDA margin it is reporting for FY 3/2022? Could there be some unsustainable elements in that? Maybe favourable purchasing deals that could expire, with higher priced production feeding through from manufacturers? I don’t know, it just seems strange to me that a small company like this can suddenly produce sector-leading profit margins in the last 2 years (pandemic) which it didn’t achieve previously. And float the shares on the back of it, at a punchy rating.
My opinion - the figures look impressive, but eCommerce as a sector has been battered in 2021. That leaves MRK shares looking an outlier, on a hefty multiple of sales, when larger eCommerce businesses which theoretically should have better buying power, are cheaper.
For me, the valuation on MRK looks too high, and I’d be surprised if it can maintain such high margins long term.
.
Nightcap (LON:NGHT)
20.6p (up 6% at 11:49) - mkt cap £40m
Trading and openings update for the 26 weeks ended 26 December 2021
This is a rapidly expanding, but still small, bars group.
Very strong +22.4% like-for-like sales increase versus pre-pandemic 2019 numbers. Although I imagine the sites would have been re-fitted since acquisition, so does that really count as like-for-like? Excluding the last 2 weeks, LFL was even more impressive at +28.3%.
Only £15.5m sales in H1, which is not much for a £40m market cap business, but that’s rapidly growing through acquisitions of more sites.
Christmas bookings - this is a very interesting point, and something I picked up on when visiting other bars in December. When asking them if everyone was cancelling Xmas parties, they said most are just being deferred into the new year, once covid is in retreat (we hope). So it’s good to hear NGHT confirm this, which has very good read-across for the whole sector I think -
Although more than 7,500 bookings for the Christmas period across the Group were initially cancelled following Plan B, the Board is pleased that over 70% of these bookings were re-scheduled to take place between January and March 2022.
New sites - lots in the pipeline -
Nightcap currently has a further 25 sites in legal negotiations or under offer across several of its brands. The Group expects for several new site leases to be entered into before the end of March 2022.
Cash - this is highly misleading in my opinion, as it ignores debt -
The Group's balance sheet is solid with unaudited cash at bank of approximately £9.4 million at 26 December 2021.
See my review of the FY 06/2021 results here, to get the full, true picture.
The balance sheet is actually quite weak, and I can’t see that any fresh equity has been raised since then. Correct me if I’m wrong on that.
I also question the huge share options charge in the FY 06/2021 accounts.
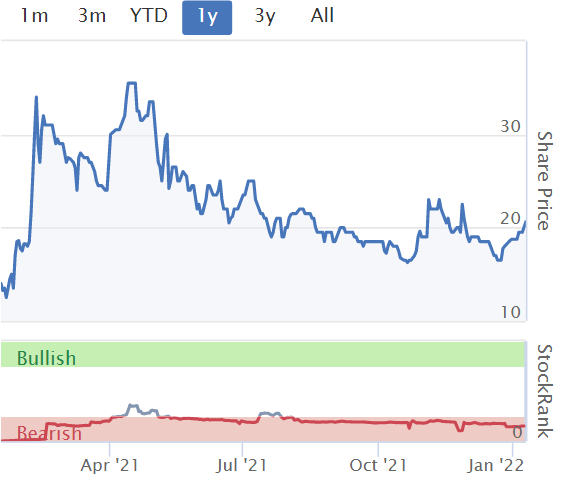
My opinion - performance looks good re LFL sales growth, but I’d want to see a breakdown of those numbers, in particular which sites have been refurbished in the comparison period?
Also, hiding the debt and only reporting gross cash, is unacceptable, and I personally wouldn’t trust anything the company says after that - everything needs to be checked, when companies gloss over negatives, and cherry-pick positives.
This share has a premium for newness, which I’m not prepared to pay.
.
.
Jack’s section
Tortilla Mexican Grill (LON:MEX)
Share price: 192.25p (+4.77%)
Shares in issue: 38,664,031
Market cap: £74.3m
Tortilla is the UK’s largest fast-casual Mexican restaurant brand. It has expanded since inception in 2007 to more than 60 sites across the UK and UAE.
The group floated last October and the shares have not really done much since then, so it looks fairly off the radar with not much activity. That said, the market cap of £74m is not obviously cheap.

Trading momentum is good though, and placing proceeds are being used to accelerate the UK rollout, develop franchise opportunities, and expand its cloud-kitchen portfolio. The group hopes to open 45 sites in the medium term but, given the nature of the sites, there’s scope to possibly double beyond that (to about 200 sites).
There’s a six month lock-in, so it’s worth keeping an eye out for any director selling from March onwards. Directors sold into the placing but continue to hold around 12.3% of the company.

Trading update to 2nd January 2022
FY21 revenue and profits are materially ahead of our expectations following stronger trading in Q4, despite the emergence of the Omicron variant of Covid-19
- Group revenue +79% to £48.1m (and up 36% compared to FY 2019),
- UK two-year like-for-likes up 23.8%, and +30.3% excluding lockdown affected Q1,
So revenue is coming in comfortably ahead of broker forecasts of £44.8m and profits should be materially ahead of expectations after a strong end to the year. Once you account for the VAT benefit, the UK 2Y LfL figure ex-Q1 falls from 30.3% to closer to 11% however, and there are a few government initiatives over the past year that for now obscure underlying profitability.
Strong cash generation sees the group end the financial year with net cash.
Seven UK company-operated restaurants and two UK franchise restaurants opened, taking Tortilla's estate to 64 stores: 51 UK company-owned, three UK franchised, and 10 franchised in the Middle East.
The group is developing business away from the High Street, including a partnership with Merlin at Chessington World of Adventures and the opening of two further sites in partnership with £SSP at Gatwick Airport and Skelton Lakes motorway services.
Delivery now comprises more than 30% of total revenue, down from about 80% at the height of lockdowns. Presumably, tacos and burritos are more transportable than other dishes, but it is lower margin with more costs involved. It’s somewhat diversified revenue at least, providing a greater degree of resilience than some other operators out there.
All in all, the openings and delivery performance suggest demand for the product.
The Board remains confident that the Group will perform in line with expectations for FY22, as the reduced financial assistance from the UK Government will be offset by reduced trading restrictions.
The Board also remains confident in the Group's ability to make good progress against its store roll-out strategy to open 45 new sites in the next five years.
Conclusion
Underlying trading is currently obscured by several factors such as business rates relief, none of which are broken down in great detail in today’s update. So it’s still hard to get a feel for what normalised results might look like lower down the income statement.
See below for the positive impact of government grants receivable over Covid. That’s just under £3.5m of help in FY21.

It appears as though reduced profitability is forecast.

The business itself could do quite well in terms of driving revenue and rolling out sites, but this is a tough sector with competition at all times. Meanwhile, there are cost pressures - labour, recruitment, food. These are big costs for such businesses. I wonder slightly about the timing of the IPO too, particularly with profitability set to fall in FY22E and FY23E.
Tortilla is comfortably ahead of the UK Mexican competition however, and the flexible format suggests quite a few sites could be set up, so I think the group can continue to grow beyond the 45-site target it has set in the medium term. The days of 400+ site brands are probably past (the last one to manage that was Nando’s) but a couple in the space should be able to get to 200 or so, particularly in the current property environment.
The group is performing well and has a product that appears to resonate with customers, so it’s one of the more interesting Leisure situations out there. And today’s update is certainly encouraging. Future success will depend a lot on the quality and experience of the management team here.
I’ve never met them, so I’m staying on the sidelines for now, but the shareholder register suggests some institutions have been impressed and the group looks like it has executed well so far.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

40 comments
Could there be an imminent bid for Fulcrum Utility to take it private , or break it up ?
Bayford Co and Mills seem to have positioned themselves into very strong positions to carve up as they see fit .
Jonathon Turner/Bayford now up to 26.7% and Mills/Harwood Capital at 28.8%
Given Bayford had previously attempted to take private something seems to be in the offing . add to this the three directors finally buying shares in the recent placing .
Fulcrum is in a good sector for sure and some conspiracy theorists might argue there has been a concerted effort to batter the share price down , then do a large fund raising to get yet more shares on the cheap and then a little nudge at the end to takes it private at a very good price ?
As Hannibal said in the A team / Bayford says to Mills ??
"I love it when a plan comes together "
Anybody have an idea why Volex took a hit today?
Hi banterex,
Volex (LON:VLX) has taken a battering past two months!!
Clearly some investors are spooked about something, not sure what though.
When others are fearful...
I sold out, reluctantly, a month or two ago, as it seemed any company selling 'goods' were heading south. I can imagine their next set of results won't be great due to inflation, supply chain issues and so on. OEMs are building lower volume than they'd like at the moment.
Christopher Mills buying into Rockwood Realisations again today , a chunky £385k worth of shares added taking him to over 5%.
Boy that lad gets about a bit doesnt he.
Just a couple of notes to your BOOM comment for which many thanks. The vast majority of their revenues arise in the US, over 90%, and the CEO is based there naturally enough. Podcasting is a global business and BOOM is best viewed through this prism.
BOOM has been outperforming the market as measured by podcast advertising revenues in the last five years and now has 4% of the US market for podcast advertising. That market has grown from $0.3bn in 2017 to an expected £2.0bn in 2023. I don't think it is surprising that the odds of BOOM remaining independent are low in the light of a very active M&A market and the likes of Amazon, Netflix and Spotify keen to dominate. How that is factored into a valuation of the shares I shall leave to you and your followers.
I am long.
Strategically, I think we will see a credible bid from a strategic buyer (in the advertising space) soon enough for Audioboom (LON:BOOM) . The reason? Many of the large advertising networks have been caught a flat-footed by the boom in podcast ad inventory space, and the demand from advertisers (hence why BOOM revenues increasing so rapidly).
Many online ad networks would have seen huge revenue growth themselves in 2020, 2021 (especially with the CPC/CPM inflation in 2021). But looking forwards, they're probably nervous what can keep driving their revenue growth, to support their high PE multiples. So I wouldn't be surprised if one of those companies made a bid for Audioboom, to keep their revenues "growing".
(Also many ad networks would have been hugely cashflow generative in the last two years, so have a cash pile, and also richly valued stock, to use for acquisition).
Cheers Paul for your write up on £MRK.
In the latest video interview the CFO says costs from suppliers had not gone up in the 3rd quarter but they were starting to see the costs from suppliers rise now. This I'd imagine would be passed onto the customers.
Regarding EBITDA being 9%, in the IPO document EBITDA for fy21 was actually 13.8%. The drop was due to greater expenses of wages and advertising taken on from going Public. They do not expect to see that level of % again but do expect to maintain 8-9% level.
The reason behind having a lot better EBITDA % than others like Ao World (LON:AO.) is mainly to do with their distribution. They rely on 1 distribution centre, in central England as apposed to 17 that Ao World (LON:AO.) have. That's a huge saving for the company. Less wages but also they do NO over night trunking of goods from one centre to another.
Whether they can keep this high as they grow, who knows but they have so far and are confident they can in the future.
I think they are a pretty good punt for a small investment but they are a little bit illiquid so I wouldn't invest too much.
Re: Nightcap (LON:NGHT) - worth noting that the founder lock-in's expire on Wednesday. There could well be an overhang. This was originally a pehicle in part to rescue the London Coctail Club, which was for sale and had not attracted any interest - I believe the advisers selling it were seeking (and suing for) their fees after the deal with Nightcap (LON:NGHT) .
Personally I think the juys is (or should be) still out on whether this is going to be a shareholder friendly and rewarding journey for non-inside investors.
Great analysis of Nightcap (LON:NGHT) this morning Paul
Blood pressure back down to normal having received an announcement this morning from Angle (LON:AGL) . It was only (more) research from Athens showing that Parsortix can be used in conjunction with ctDNA (presumably Cellsearch) in lung cancer treatment.
https://www.stockopedia.com/share-prices/angle-LON:AGL/news/rcs-angle-plc-insight-into-drug-resistance-in-nsclc-urn:newsml:reuters.com:20220110:nRSJ8278Xa
Hopefully FDA approval will be forthcoming sometime this year and progress on the Ovarian cancer assay will be announced soon!!
Marks Electrical (LON:MRK) delivered a trading update today.
Record quarterly revenues delivery in-line with forecasts, but more importantly their EBITDA has increased to 9% for the 3 trading quarters, the higher end of their target.
Marks Electrical (LON:MRK) have not suffered from delivery and stock issues which is encouraging.
Marks Electrical (LON:MRK) pride themselves on next day delivery and their excellent service to their customers. Their already excellent Trust pilot score has increased to 4.8. Part of their good service is having all their delivery people being share holders, giving them a incentive to provide good service.
The BOD come across as very pleased with the figures produce and are aiming for a 20%+ increase in revenues for the fourth quarter.
Currently Marks Electrical (LON:MRK) holds just 1.5% of its market share while aiming to capture 10%. They expect revenues to out grow their current warehouse in 2024 and are as such looking for another warehouse to lease. Leasing being a cheaper option.
Latest video update from VOX:
I would vote to keep the Explanatory Notes
Electra Private Equity (LON:ELTA) I agree that the fundamentals look very good, but I think we are a long way from the shareholder register getting into equilibrium eg MandG seem to be selling and other significant shareholders do not look like AIM type investors.
Hi Paul - I think we already have the numbers for Hotter and Electra Private Equity (LON:ELTA)
Hotter confirms it is trading at above £5m ebitda in current year (around £5.5m based on broker forecasts). At 9% growth announced today that looks consistent.
Current gross debt in Hotter itself is £12.5m but there is over £6m cash on the balance sheet of the group (inc Electra Private Equity (LON:ELTA)) so post name change net debt should be circa £6m.
So we have the business on an EV of £31m trading at just 5* EV/EBITDA
There is also an insurance claim for covid of £15m which the board think has a strong chance of success, so there could be hidden value here as well, perhaps being as much as half the EV.
Given that Hotter seems to be growing pretty well and with good margins this valuation feels wrong to me even before they start selling complimentary services.
I've held off buying more because of the potential for forced sellers giving me a slightly better price but I'd imagine they will be more or less out by now.
Thanks David, re Electra Private Equity (LON:ELTA) (I hold).
I wasn't aware of a £15m insurance claim re covid, that's over half the market cap, so highly significant as you say. Don't know how I managed to miss that - stretched too thinly over too many companies, so it's really helpful when subscribers point out pertinent facts like that, thank you.
Best wishes, Paul.
Thanks Paul - to be honest I'm not that surprised because the one gripe I do have with Electra Private Equity (LON:ELTA) on the Hotter side of things is that management seem incapable of presenting the numbers investors want to see in a clear and transparent format.
For example - the management of Hotter said they expected debt at 2* EBITDA in the short term and move to net cash in the medium term (but without saying what EBITDA should be, so a useless metric!). I had assumed around £12m of debt as I managed to find a broker forecast for EBITDA. Then right at the end of the recent investor comms presentation the Electra Private Equity (LON:ELTA) management, but only in response to questioning, confirms the £6m cash sitting there and net debt of £6m. Why not volunteer that information rather than have it dragged out of you?! Similarly the insurance claim info came right at the end in response to questions.
It's a very annoying trait as it makes the valuation trail very hard to follow. When even the EBITDA number is difficult to extract you have to ask questions about communication style.
Electra Private Equity (LON:ELTA)
Very interesting comments davidjhill- most appeciated , bit bizaarre that things seem to be so slapdash from the communication point of view - they have had plenty of time to prepare for going it alone so i would have expected exactly the opposite. Very precise and clear updates so as not to leave bods in the dark. I do understand if these bods are concentrating on running a business the minor live updates ref exact cash situation and the like might not be their "strong point" and i would rather they were good at running the business so i will perhaps give them a pass. In some resepcts as long as they are known to be straight talking ref what they say now (time will tell) perhaps this gives non holders a decent buying opportunity if the market in general doesnt easily have the full picture being slapped in tehir face. - i kind of guess with regard to institutions lining up to load up on the shares now that line may be non existent or negative? As Paul i wasn't aware of the potential insurance claim interesting food for thought.
I think the confusing messages have come about because the capital markets day is done by the CEO of Hotter who just talks about that business but actually the Electra Private Equity (LON:ELTA) group is made up of more than just Hotter, despite the fact that all of those assets will trade under the Unbound group.
Whilst PBT is obviously usually a better measure I think in this instance EBITDA is a more useful interim view until the Unbound business is trading without the one offs associated with all the demergers etc.
The Hotter PBT vs EBITDA should actually be quite close together over the next 12 months as they don't capitalise much and I would expect interest to moderate around the £400k p/a mark. So I see PBT (before any growth) normalising at around the £4m - £4.5m p/a level which, against a market cap of £25m is around 6*. On an EV/EBITDA its 5* so not much in it from my calcs.
The £15m insurance claim could make quite a difference but I prefer to discount that to zero until there is certainty.
Morning Paul,
From memory the Hotter board "expected the claim to be settled by late 22 early23 "
but i now cannot find where i read this !!
Richard
Re Electra Private Equity (LON:ELTA) and it's insurance claim, this was reported in the interim report on the 2nd Dec:
"The Hotter equity value reflected in both tables above does not reflect any value arising from an ongoing business interruption insurance claim relating to the Covid-19 pandemic lockdowns. A range of recovery outcomes from this claim is possible ranging from nil to in excess of £15 million. Resolution is expected in late 2022 or early 2023."
https://www.investegate.co.uk/...
Well done Epsilon!
I would rather work off PBT than EBITDA, which obviously overstates actual profits. I had a quick look at Hotter and was put off by its spotty history - had a couple of very bad years and was loss making, and I know that Electra themselves took a big hit with the value marked down from their original purchase price. That is not to say to can't be turned round as it moves to a purely digital proposition, but would need to do further analysis before I considered investing.
It's already turned around and the management/proposition is completely different so you need to start the analysis from scratch - you can't look at history and think you are inferring anything relevant. Unless you are prepared to do that research yourself then you shouldn't invest in anything imo.
The value I find in this community is that people will do that analysis and highlight interesting opportunities or threats. If that piques my interest I will then do the research myself and decide. Saves a lot of time sifting through dross.
IMC very helpfully put their latest presentation with the Unbound management team on YouTube.
Electra Private Equity (LON:ELTA)
Good point ref PBT Bouden - practicably speaking i like to have the full chapter and verse of both as only loking at the detail of the differences can we start to get a picture as to whether decent EBITDA may be overpimping things or whether it may be the opposite (less likely) . Certainly looks like expected PBT ye sep 2022 is negative so that puts a different picture on things - i suspect though there will be a lot of one offs this year that may mean the expected loss doesnt really reflect the true ongoing earnings potential. here Time for some further digging perhaps. seems quite positive they think non shoes can get to over 50% of profits hopefully thats some reasonably organic non organic growth coming along (like vegan steak bakes).
Rmillaree, Re Electra Private Equity (LON:ELTA) /Hotter. On what is your comment "Certainly looks like expected PBT ye sep 2022 is negative...." based.
The slide below is from the last investor presentation I know about. Today we had Nov-Dec revenue growth confirmed as +9% at 65% %GM. If we assume H2 is the same as H1 that is >£3Mn underlying EBIT which I see as consistent with their definition of EBITDA being >£5Mn. I can't therefore see why this year will be negative.
Will a conversion listing really cost more £3Mn for a £25Mn cap business that is already quoted or am I missing something?
I hold as I really like the re-structuring done in last few years and the go forward strategy. The old have all the money and the "young-old", 55-70 have discovered online shopping big time the various lock-downs.
Hi Zipmanpeter
Remember the listing is Unbound Group. That consists of Hotter shoes and other assets, not just Hotter.
I expect Unbound may well report losses because it demerged £HOST and has been busy unwinding itself. That has costs in advisor and listing fees as well as a more swollen BoD than is needed.
However, once all those one offs come out this year we should be left with a business that has £6m of cash, a £15m+ covid insurance claim and Hotter Shoes. The latter will have £10-11m of debt and should be making £5.7-6m EBITDA. I reckon at a PBT level that should start to unwind at around £4m p/a and if they continue along growth trajectory considerably more in my view.
For me the opportunity is twofold. Firstly I don't think the market has really got its head around what Unbound is and is confused on forward profitability and secondly there is selling pressure from institutions that could hold Electra Private Equity (LON:ELTA) but not Unbound. As all this unwinds over 12-18m months I think the value should become clear, at which point I am hoping the price will be considerably higher.
Electra Private Equity (LON:ELTA)
Zipmaster
Rmillaree, Re Electra Private Equity (LON:ELTA) /Hotter. On what is your comment "Certainly looks like expected PBT ye sep 2022 is negative...." based.
Hello Zipmaster thanks for highlighting the fact my comments ref losses being expected were nonsensical , i made the silly mistake of just lifting the number from Stockopepia - i see that the total revenue figure is £1 million for the same 2022 period so its clear everything contained in stockopdia ref 2022 is simply faulty data that should be ignored - i should really have expected that to be the case when i looked at the numbers - so please everyone disregard my comments about the expectations being for losses for the year ref profits.
I can't deal in Electra Private Equity (LON:ELTA) at the moment through A J Bell. Is that a general restriction because of the imminent name change or is it local to A J Bell?
Looks like it's AJ Bell, I can trade Electra Private Equity (LON:ELTA)
Did a dummy trade on ii and I can buy.
I've the same restriction on AJBell. ELTA is not due to de-list until the 31st Jan so I'm surprised they've stopped trading so early.
The insurance claim is not for £15m.
The insurance claim is UP to £15m.
It can be from £1 to £15m.
Thanks
Tortilla Mexican Grill (LON:MEX) -great first trading update from this newly floated casual dining outfit (Tortilla Mexican Grill in case ticker lookup doesn't work) - any thoughts Paul/ Jack? I hold
Strong update from Dekel Agri-vision (LON:DKL) this morning too, sales and production are up, sales prices remain strong coming into their high season (I hold). If possible to fit it in, would appreciate it if this one could be reviewed to look into the numbers further.
https://www.investegate.co.uk/...
Nice upgrade from Dekel Agri-vision (LON:DKL) brokers (Arden) who increase target price from 7.9p to 9.4p.
With €4.9 EBITDA for for 2021 rising to €9.4m for this year
Good news from Plus500 (LON:PLUS) this morning - ahead of expectations for the full year. Metrics for the final quarter appear to suggest that activity has been robust - potentially positive across for widely held Cmc Markets (LON:CMCX) and Ig Group (LON:IGG)