Small Cap Value Report (Mon 10 June 2024) - MEGP, STAF. Brief: GMS, BBSN, CHLL, PTY

Good morning from Paul & Graham!
Holidays
Over the next fortnight or so there might be somewhat reduced coverage here, as we (Paul, Graham & Roland) all have holidays booked. I'll take my laptop with me, and do what needs to be done, but the time difference could be tricky (I'll be in Washington DC). It's not the sort of thing anyone else can cover, as I jealously guard our colour-coding system! Anyway we'll manage, but just don't expect miracles for the next fortnight. We work on a flexible basis here - that most days we deliver far more than required, but there might then be some other days where these's less content, that's just the way it is.
Videos
This was fun! I found a new bit of software that makes recording videos from my screen dead easy, and I made 2 of them, which seem to have gone down well.
Does the SCVR colour-coding work? (the short version is, yes, very well!). Thank you to Phil Hanson who crunched the data which I talk through in this video.
Update on our 2024 top share ideas - Graham and I are now neck & neck at c.+27% YTD, which we're obviously delighted with, for our fixed top 30 share ideas for this year.
For ad hoc stuff, making a quick video like these is so much more efficient than spending hours writing an article, so if people like them, I'll do more of these.
** EDIT at 11:44 - I've just recorded a new video here, demonstrating how to set up a simple stock screen to identify & sort broker upgrades **
Mello Monday
The popular online investor shows run by renowned investor David Stredder. Starts at 17:30 tonight, details here. I'm looking forward to hearing what Gervais thinks - let me guess, super-bulllish?! LOL. But he's right to be, as UK small-mid caps still have plenty of bargains on offer. Companies presenting include Impax Asset Management (LON:IPX) and React (LON:REAT) both of which we've written about here recently.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Summaries
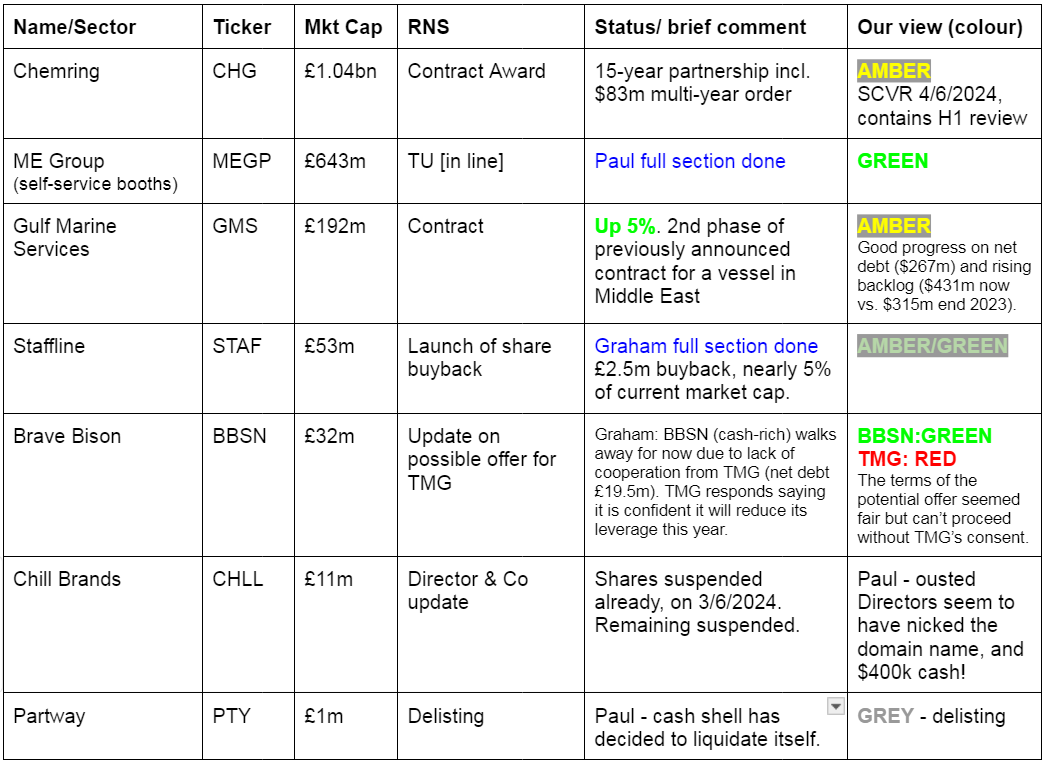
ME International (LON:MEGP) - down 2% to 168p (£629m) - Trading Update [in line] - Paul - GREEN
A confident, in line with expectations update for H1 to 4/2024. My view is this share remains under-appreciated, and seems a GARP share (growth at reasonable priced) wrongly priced as a value share. Maybe I've missed something negative, but I see further upside in due course, despite MEGP being up 32% YTD. This was one of my top 20 share ideas for 2024, and I remain keen on it.
Staffline (LON:STAF) - Launch of Share-Buyback - up 6% to 37.7p (£56m) - Graham - AMBER/GREEN
It’s a small (£2.5m) buyback but follows a £5m buyback last year. Staffline’s Chairman - a major shareholder - seems to be driving this agenda. The business itself remains average (or below-average?) quality but if it’s run sensibly for cash with a reducing share count then perhaps shareholders can do well.
Paul’s Section:
ME International (LON:MEGP)
Down 2% to 168p (£629m) - Trading Update [in line] - Paul - GREEN
ME Group International plc (LON: MEGP), the instant-service equipment group, announces an update on the Group's trading for the six months ended 30 April 2024 ("H1 2024").
Company’s headline -
Record number of Revolution laundry machines installed in H1; on track to deliver another year of record performance
Interesting that they’ve given prominence to the self-service laundry machines. Investors were slow on the uptake about how important the laundry division is becoming. As a reminder, I mystery shopped a ME Group laundry, when my washing machine had broken down, and wrote up a post about it here (Jan 2024). Broker notes now usefully split out the various divisions, and the laundries are a very good money-spinner, after the initial capex. A key point of difference from conventional launderettes being that they’re outside, typically in car parks, or a corner of petrol stations, so have little fixed costs. The core original business is photo booths, which are surprisingly perhaps, still very relevant for ID documents, as they can’t be tampered with, unlike smartphone photos. There are other smaller divisions too, but they’re not significant financially.
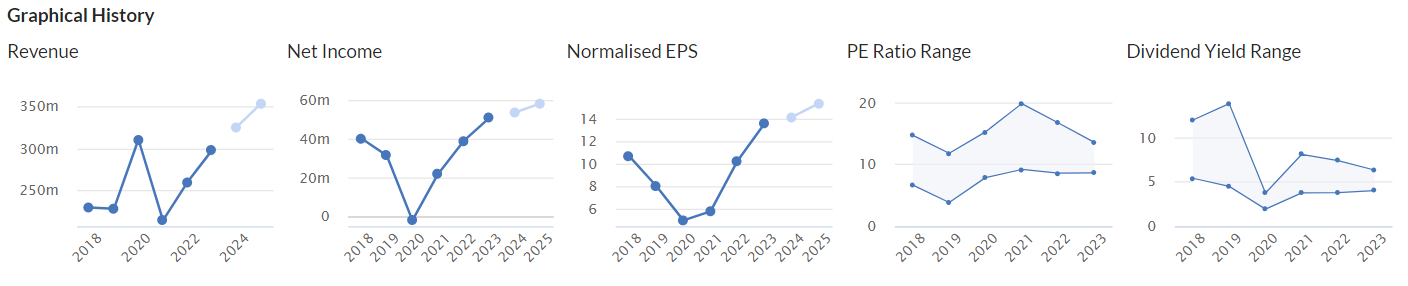
Impressive track record below, after an understandable hit from the lockdowns in 2020-2021 - yet MEGP shares remain good value, with a lowish PER and decent dividend yield. These were attributes that caught my eye last year, and why I put MEGP onto my 2024 top 20 share ideas, at 126p (it’s currently up 32% YTD) -
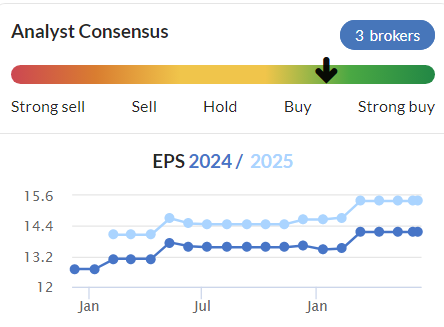
Another key thing I like is broker forecasts trending upwards -
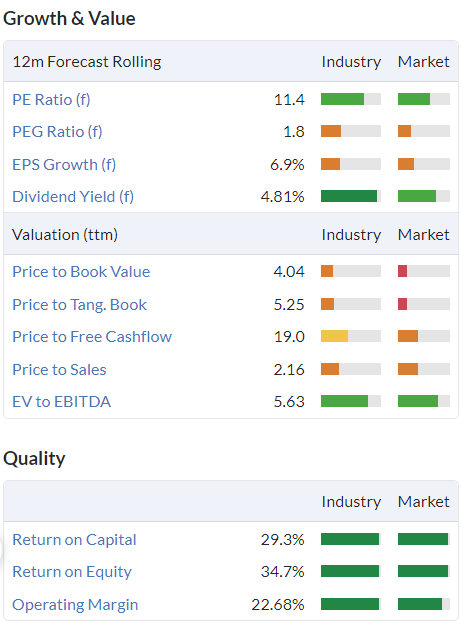
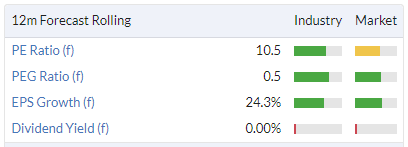
We have low valuation figures below, and very high quality scores - what more could we ask for?! -
All resulting in a very high StockRank, and “Super Stock” classification from the Stockopedia computers -
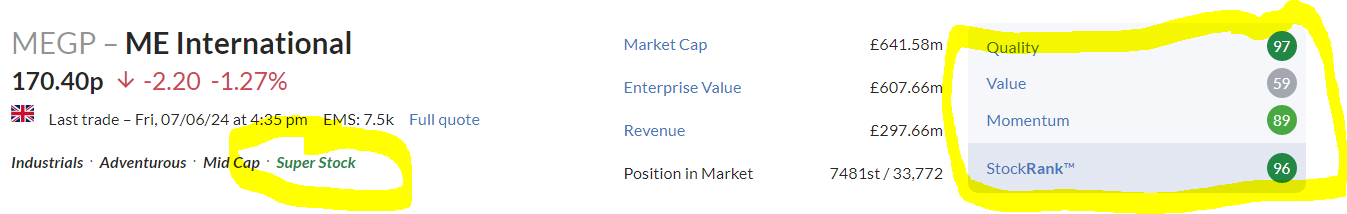
Put all that together, and MEGP shares still look attractive to me, despite being up 32% YTD.
Laundry division - is enjoying good growth, and the roll out of new sites has accelerated into a 1200 rpm spin cycle! -
Wash.ME Revolution laundry operations is the fastest growing business area with revenue up 17.4% (19.6% excluding FX impact) compared with H1 2023, as the Group delivered on its rollout of Revolution laundry machines and built on its record performance.
The number of Revolution laundry machines in operation grew by 18% compared to H1 2023, with a record 420 Revolution machines installed in H1 2024. The Group continues to expand across its established partnerships in high footfall locations, such as supermarkets and petrol forecourts, and its installation pipeline indicates that it is on track to deploy a record number of Revolution machines during FY 2024.
H1 trading overall - note the impact of Japanese Yen (down 15% vs sterling) forex moves -
“Positive trading momentum continued throughout H1 2024 compared with the six months ended 30 April 2023 ("H1 2023"), with Group revenue up 4.6% (up 8.6% excluding FX impact) and profit before tax up 10.3% (up 13.6%, excluding FX impact). The Group remained focused on the continued growth of its core photobooth and laundry operations.”
Net cash - is broadly unchanged. I remember previously querying why it had large gross cash, partly offset by debt, and somebody here kindly asked management. The answer was that it locked in cheap borrowings, so no benefit to paying it off early. Although the figures below suggest it has paid off some of the debt -
“The Group remains in a well-capitalised and strong financial position, with high cash flow generation and long-term customer contracts providing the Group with good predictability and visibility on revenue streams. At 30 April 2024, the Group had a gross cash position of £82.9 million (H1 2023: £113.1 million), and a net cash position of £21.9 million (H1 2023: £24.4 million), excluding investments in convertible bonds of £4.7 million (H1 2023: £4.7 million).”
I haven't looked into the convertible bonds, do post a comment if you've looked into that. By calling them "investments" it sounds like this is an asset rather than a liability.
Overall this looks encouraging to me. ME is self-funding a rapid roll-out, has bolted on more photo booths in a Japanese acquisition, and paying decent divis, all with its self-generated cashflows. That’s impressive. You’re getting a growth share here priced like a value share.
Outlook - is in line -
Historically, the second half of the financial year is seasonally the strongest for the Group in terms of revenue and profits generated as well as the installation of machines across key locations. As the Group capitalises on the significant market opportunity for laundry and photobooth services, the Board is confident in delivering record profitability for the year, in line with market expectations.
It’s helpful when companies add a footnote stating what market expectations are, but this seems to have been overlooked here.
Cavendish put out a note on 23 Feb 2024, indicating 14.3p adj EPS for FY 10/2024. That ties in with broker consensus of 14.2p on the StockReport. Since we’re told it’s trading in line, that suggests a PER of only 11.8x - which looks good value to me still.
Paul’s opinion - MEGP shares strike me as under-appreciated still. It’s owner/managed with Serge Crasnianski owning an effectively controlling stake of 36.6%. We usually like owner/managed businesses here at the SCVR.
Whilst I’ve been writing this, the shares have slipped a little lower, which surprises me given that I read this update as confident and reassuring. Maybe I’ve missed something?
Am I still bullish on MEGP shares? Absolutely, it looks an excellent GARP share to me. So a continuing GREEN view.

Graham’s Section:
Staffline (LON:STAF)
Launch of Share-Buyback - up 6% to 37.7p (£56m) - Graham - AMBER/GREEN
Some pleasant news this morning for shareholders of this staffing and recruitment company as it’s announced that the company is launching a £2.5m buyback.
It’s not quite 5% of the market cap but it’s still a helpful boost to earnings per share.
Staffline’s explanation of the decision:
The Group remains disciplined in its allocation of capital with the main objective being to enhance shareholder value. We continuously assess our medium-term plans which take account of growth prospects, investment in the business, cash generation, net borrowings, and leverage. Therefore, the amount allocated to buybacks is based on our predicted trading cash flows and financing headroom.
Graham’s view
As pointed out by Paul in his coverage last year, long-term shareholders have suffered tremendous dilution here:

This has resulted in long-term shareholders being hopelessly diluted:
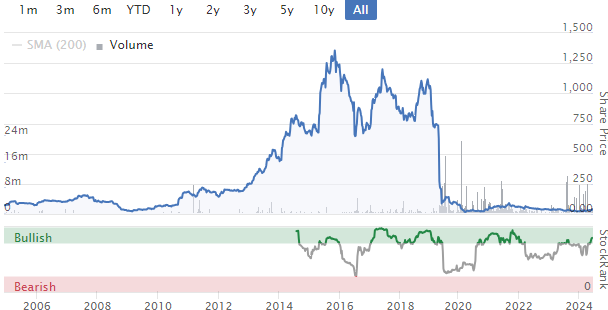
However, you may notice on the previous bar chart that the share count did drop back between 2022 and 2023. According to the full-year results for 2023, the company had a £5m buyback last year.
So today’s news is a continuation of that trend. If these buybacks are sustainable, perhaps we could start to get excited about the investment story here, if the share count keeps dropping and the business remains stable?
There are always a few things that need to be checked when studying any buyback: 1) can the company afford it? 2) Is the company buying back its shares at an attractive price? 3) Is the company neglecting other potential uses of its cash?
Tackling each of these questions in turn:
The company finished 2023 with net cash of £3.8m and balance sheet equity of £55m, although tangible equity is negative if you strip out intangibles. My initial impressions are that the balance sheet has moderate strength. There are some large working capital items and the company does need to use borrowing facilities.
The company is buying back its shares at around 10x earnings, so again the value on offer is moderately attractive for the recruitment sector where multiples tend not to get very high (best in class SThree (LON:STEM) trades at the same earnings multiple). Staffline’s ValueRank according to Stockopedia is 75, implying good value. These shares must come with the disclaimer that the profit figure is volatile: gross profits are £80m+ and small changes in costs can have a big impact on the bottom line.
3. Is the company neglecting other potential uses of its cash? No, I doubt it. Staffline has been around for a long time, is not growing particularly fast, and doesn’t have a good track record of earning a high ROCE or ROE. Blue-collar staffing is a mature industry. So I doubt that it should be reinvesting all surplus funds back into the business, or making acquisitions. Instead, I agree that it makes sense to send surplus funds back to shareholders.
Staffline doesn’t yet pay any dividends: it’s unusual for UK companies to choose buybacks over dividends.
I’m going to take an AMBER/GREEN stance on this company because while the business itself doesn’t excite me, I am intrigued by the Chairman’s views on capital allocation and how he might use the company’s cash flow.
This is what he said in the 2023 results. I’ve highlighted some sentences that stand out:
Net cash (pre-IFRS 16) was also a highlight in 2023. The year ended significantly ahead of original market expectations by £6.8m, our ongoing balance sheet strength maintained with net cash of £3.8m (2022: £5.0m). The litmus test of creating shareholder value on a long-term basis will be how well we use the profits generated by the business.
The elegant name given to such decisions is 'capital allocation'. In simple terms, the success of any business is how well management make decisions on retained cash and its reinvestment, as well as their choices about when and how to redistribute that cash to shareholders.
In 2023 the stock market gave us an excellent opportunity to repurchase 10% of the Company's outstanding shares at what we regard to be very attractive prices. Yet, this begs the question "What is a buyback?" and "Why do we think our remaining shareholders should like them so much?" Well, it's really very simple; a buyback is another form of capital distribution.
When companies choose to distribute a dividend, our investors receive an income payment from the company whether they want it or not. With buybacks, the company purchases shares from investors who want to sell them (perhaps because they need the money, or perhaps because they have forgotten the reason why they bought their shares in the first place). When cancelling these shares after purchase, their proportional ownership of the business grows for those who hold on to their shares, as well as their claim on any future cashflows.
What's notable is that during that process we were able to buy back those shares at an average purchase price of 30p. While we won't provide a running commentary on what we regard the intrinsic value of the Company to be, we will repurchase shares when they are trading at a substantial discount to what we believe they are worth.
We don't know exactly what 2024 will hold for the price of our publicly traded shares. What we can say though, is that we intend to generate more cash and if some of that cash is better used in the repurchase of the Company's shares, we will not be slow in doing so.
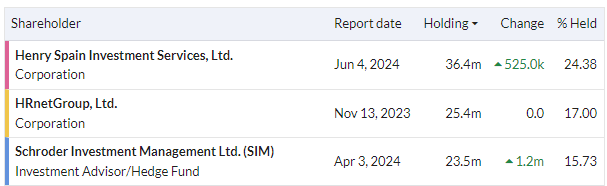
These words were spoken by the Chairman, whose company is the top shareholder and has recently been buying shares at 34.6p:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

99 comments
Watched Ed's story stock presentation yesterday.I forgot what a great presentor Ed is and very apt considering the action of the pandemic darling Eurasia Mining (LON:EUA) over the last 2 days.From up 70% today by 9:30 on huge volume to ending the day almost 50% down.A lot of fomoing going on there.Avoiding large losses in capital is half the game, but naturally emtions are tough to control at times (even when all the red flags are staring you right in the face sometimes)!Anyone else willing to admit they remember UK Oil & Gas (LON:UKOG) who had apparently found huge amounts of oil somewhere near Gatwick airport?
You're right Paul, Loom is a great little piece of software.
The Mello Monday show starts in about 45 minutes with Gervais Williams the guest speaker
MelloMonday 10th June 2024 – Mello Events
Here is the programme....
Programme
5:30pm Gervais Williams of Premier Miton presents UK Breakout – What Next?
6:00pm Company presentation by Impax Asset Management
6:30pm Company presentation by REACT Group plc
7:00pm BASH Panel featuring Mark Simpson (Ramsdens RFX) and Kevin Taylor (Polar Capital POLR)
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50
Yet another miserable day then, down six on the trot
Try not to be too obsessed with the (very) short-term - unless you need the money now who cares? Try and imagine what your shares will be worth this time next year.
Sound advice. I try to see days like today as an even better buying opp for some of my higher conviction shares, even though sometimes it's difficult!
Just seen my order for Raspberry PI IPO has been filled at £1 per share.
Looking forward for Friday when they start the unconditional trading. I don't think any of the trading platforms I use (T212, CMC, SpreadEx) will offer the option to start trading until Friday
Raspberry PI looks an interesting float. This is what we need to bring the London market alive again - some interesting new companies!
I've had a brief rummage through the IPO document, but it seems incomplete?
Has anyone got more up-to-date info?
So far, I like the revenue & profit growth. Not sure about the dependence on 2 key suppliers. Also big rise in inventories. I think it might capitalise R&D, that needs a close look.
Sounds like there's good demand, so everyone is expecting a premium open. That's what we need!
On a relatively quiet day, I am taking another look at a not so small company Indivior (LON:INDV) which has been caned recently following a legal battle which has now been settled at roughly 1/3 of the amount claimed.
The Stock Ranking is in the 30s, However, the Final Results and latest forecast by the company indicate that the forecasts for the year ended Dec 24 and forecast 25 showing on the Stock Report a significant recovery. '
The target price is more than 90% higher than current SP. The brokers support is moving in the right direction.
The company is already listed and HQ in the US, their main market and is about to move the main listing to the US which traditionally values companies higher than the UK? The company's products currently play an important part in the US counter drug addition programme.
The PER and PEG figures are modest going forward.
The company has a programme of share buy backs.
The cash situation is poor presumably because of the legal loss. The value of the shares at the end of 2023 currently shows zero on the Stock Report.
What am I missing and where should I be looking for more negatives, and /or how realistic are the company's forecast for this year and calendar 2025?
Thank you for any inputs.
Hi rdavies. I keep any eye on Indivior (LON:INDV) and the thing that prevents me buying is the heavy reliance on a single drug, Sublocade, to produce growth. Indivior does have other drugs on the market and in development but its success is likely to remain dependent on Sublocade sales for quite a few years to come and this drug is facing gradually increasing competition. Since you are asking for negatives, I would also suggest that the Science section of Indivior's web site shows that it has limited internal capabilities in this regard so is likely to need to buy in new products rather than develop them itself.
Vertu
Cinch have sold their 9%
Been mopped up by cap 2 vega .
That’s interesting
Market hasn’t reacted .
Cap 2 vega bought Marshall’s motor holdings .
Maybe they want vertu as well .
Vertu another sitting duck .
Same group are they not- Cap 2 vega was vehicle for Marshall bid- I think. Both registered in Hook.
Google at least brought up a car. Plenty of room for the battery which is nice.
Anyone guess whats going to happen with old cars. There will always be petrol available and as time goes on and gets cheaper than electricity. But Mr Tax of course doesn't want humans to have any life.
That's a Facel Vega, if I'm not mistaken? I see the link from previous posts mentioning "vega".
France's 1960s (?) answer to the Rolls Royce Corniche or Aston Martin, powered by a big American V8. They featured one of these on my favourite TV Show, "Bangers and Cash" recently, and it sold for a very low price of £75k. Smug new owner said he would have paid more than double.
Sorry for off topic. But pictures of gorgeous classic cars always catch my eye, far more than a painting for example.
Cap 2 vega bought Marshall’s motor holdings .
Maybe they want vertu as well .
Vertu another sitting duck .
They are all part of the same group!
Hi Paul
Thank you, the Video posts were a huge help and enjoyed your podcast as always
Hi Paul - I just watched the 2024 share ideas update which was very informative and entertaining, thank you. I did laugh afterwards when the video told me how much time I'd saved by watching at at 1.2 times normal speed - I hadn't realised and thought you were just over excited or on the high energy drinks :)
Paul - I also wondered why your voice had become higher!
I now see there is an indicator underneath the play button in the midle of the screen with 1.2x as default (showing you save 5 mins). If you hover the cursor over that you can chose from options between 0.8x and 2.5x -
Thats a good spot! I was thinking he had sped up his rate of speech. This explains it :-)
One day in the not too distant future it will be an Avatar bot whilst Mr Scott is languishing in his pool. Working From Home on a new level.
Is AI for the benefit of us i.e workers, or the bosses. A: latter.
Did AI write your post? LOL!
I should apologise for LOOM's AI-generated titles, summaries, transcripts, etc, it I didn't bother going through it all to correct some of the nonsense AI generated. As soon as I saw it call the SCVRs the Small Cap Valley Reports, it reminded me that as yet, we have nothing to fear from AI. Because it's not actually intelligent at all, it's incredibly stupid from what I've seen so far. But it can do some fancy things I believe, just not in shares analysis. All automated analysis I've seen has been pretty pathetic, as it doesn't pick up on any anomalies or nuances.
International Personal Finance (LON:IPF) up 6% and looks like it may break through the downtrend resistance from Feb 2020 today (the last 10 years actually if you extend the view).
Stock rank of 96 with 9% yield and NTAv almost double MV. (I hold)
IPF - I've held the 12% bond IPF3 for quite a while now. Graham has commented on this in previous SCVRs.
Stocko reduced coverage ?
At the risk of getting shot to pieces as I Know everyone loves the guys here and this will go down like a lead balloon .
But it’s fairly standard in small companies to manage holidays so that not all staff go away at the same time.
Except of course Italy where of course the entire country closes down for 2 weeks in August .
Oh and China where CNY everyone goes home .
I currently have only 3 employees and it’s one away at a time otherwise our customer promise can’t be met .
Anyway I will now duck for cover .
Your forgetting France where most avoid work at all costs and whole country shuts down for August, on second thoughts as I'm heading towards sixty and have had nigh on forty years at the coal face it sounds great.
and what about the Glasgow fortnight?
I must have missed that one ?
It is one at a time. Me 12-18 June. Graham 19-28 June.
It's a team of 2.
Roland wasn't available unfortunately.
I hope you both have a great time on your holidays - very much deserved. I very much appreciate all the work you put in throughout the year.
Thanks M! Wish I'd listened to you more carefully when you told me about NVidia ages ago!! Well done you :-)
June is generally quiet enough for City news that one of you can probably cover it anyway. Historically it was the start of the City/Social season with Ascot, Wimbledon and then Henley I believe. And the majority of companies are December year ends with half year updates in July and Interims in September. Not much happens in the City in August either so both great times for a hol. Enjoy.
Perfect - that’s much better planning .
I stand corrected .
I'm not particularly fussed either way but Ed is Paul's boss. If everyone wants 2 people at all times to cover the SCVR (and that would be nice) then it's up to Ed to arrange that imo. Not a criticism, just an observation.
I think Paul is Paul's boss. Ed and we are the beneficiaries of what he chooses to do.
Hi OsullivanB,
This made me chuckle -
"I think Paul is Paul's boss..."
I am unmanageable, as I'm sure others at Stocko would readily agree! But somehow it works ;-)
Regards, Paul.
Raspberry Pi IPO is oversubscribed multiple times
https://www.google.com/amp/s/w...
It seems like a nicely profitable ipo.However, i wonder if some are at least hoping for a little of our own uk ipo day bounce, just because Arm Holdings (NSQ:ARM) is a cornerstone shareholder.Arm Holdings (NSQ:ARM) did that with getting NVIDIA (NSQ:NVDA) etc.. as cornerstone investors pre its own ipo.That would definitely happen other side of the pond.Interesting to see what happens on ipo day.
@ Graham, I would suggest a fourth item to check when studying a buy back.
Namely, 'Does Management's bonus/LTIP depends on some form of EPS?'
I doubt I need to explain the reasoning for that.
Cynical, yes. Sadly all to commonly answered in the affirmative, absolutely.
Really good point, thanks.
I receive the very welcome and entertaining podcasts via Google. They tell me that after the 21st June, they wont be supplying them - at least for free, if I read it correctly.
Is there any other route I may use gratuitously? I take them on my cell phone which is Samsung and I use Android of course.
Thank you for any assistance,
There should be a message on google podcasts explaining how to move your podcasts onto Youtube Music. I did this, and it's very easy, just click on the links and it copies all your subscriptions over.
Or you can find my podcasts on other podcasting services, eg Apple, Spotify.
Thanks you, Paul. Wouldn't miss them for the world....even if I have to pay!
Hi, I moved to the free version of Podbean a few months ago and seems to work well. I tried the transfer from Google podcasts to YouTube Music yet can't find podcasts in it. I am at least one customer Google has lost on the podcast front from this business decision.
SRT Marine Systems (LON:SRT) I hold.
I’ve just finished watching Simon Tucker’s presentation this morning. A recording should be available on their website soon. Very informative regarding their technology and the contracts in the pipeline.
I’d recommend anyone who thinks the company is ‘something along the lines they design something, sell it (eventually), and then it's back to square one again’ takes the 45 mins required to view.
Judging from the sp reaction others have been impressed.
Hi JimMcLad,
I've not watched it yet, but the big problem with SRT Marine Systems (LON:SRT) is that he's been saying essentially the same things for many, many years, with just the occasional good year keeping the story alive and allowing another placing to be done. So it's no wonder that many investors won't touch it.
On a more positive note, I was very impressed with Ocean Infinity Group taking a stake in SRT, which added a lot of credibility.
Maybe this time it might be different?! Good luck to bulls, I hope it works out for you.
We're definitely in a bull market now, with the SRT share price actually going up on maybe its worst ever profit warning last week! That seems to be telling us that there can't be many stale bulls still on the shareholder list, just optimists! So maybe the price goes up now, who can say? For those reasons, I remain bearish on fundamentals & poor performance to date, but can also see there's the chance of a potential nice trade here too, for risk-takers.
Historically, trading it, rather than buy & hold has been far better - easy with hindsight! Buying the dips has worked nicely in the past -
Regards, Paul.
Paul
Do watch the recording if you have time – it really gives a great insight as to where the company is now and the dilemma Tucker has in passing on to markets targets that are outside SRT Marine Systems (LON:SRT) control. They are advised a date by a major bank, foreign and UK government (Export Credit ) when they expect to complete their pre-required financial work. They missed their target. Tucker's team are ready to go.
Other divisions are performing well – one having doubled turnover in the last 3 years.
Recently, you rightly gave up on a favourite share of yours based on “When the facts change, I change my mind. ” . Hopefully you’ll soon be able to apply the same logic to SRT Marine Systems (LON:SRT) .
Jim
Hi JimMcLad,
Recently, you rightly gave up on a favourite share of yours based on “When the facts change, I change my mind. ” . Hopefully you’ll soon be able to apply the same logic to SRT Marine Systems (LON:SRT) .
Absolutely, we apply this logic to everything. Hence every SCVR we approach each company with the word "COLOUR" put in our draft. Then we decide, based on the updated news, and with fresh eyes, what colour we think it suitable. We frequently change our views, up or down, depending on what the facts, figures and forecasts have done.
So absolutely, if/when SRT starts to actually deliver, then we'll be happy to change colour. Although forecasts are not something I would give any credence to at all with SRT, because for reasons outside its control, it basically has zero visibility, as it has demonstrated many times over the years!
Regards, Paul.
If you are interested in this marine surveillance space, have a look at Norwegian company Kongsberg Gruppen ASA (STO:KOGo) Kongsberg Gruppen ASA (OSL:KOG) which, as you can see, is available on the Stockholm and Oslo exchanges. They are among the World leaders in marine surveillance. They have 5-bagged for me in the time I have owned them. They are 50% owned by the Norwegian Government which you may view as a positive or a negative. They are also involved in marine defence systems, marine drones, and space. I added to them through A J Bell in an ISA, buying on the Stockholm market.
I looked at SRT Marine Systems (LON:SRT) but cannot see any competitive advantage with their product. It looks like they will have to issue some more shares shortly as well to keep things moving.
jamesalastair
Thanks for that, I’ll take a look. Sounds like the Norwegian company are far more diversified which may be good or bad.
Not sure SRT Marine Systems (LON:SRT) will need to issue more shares.
Jim
Centaur Media
Very easy to buy at an unusually low 38p.
Looks like Downing are clearing their last 3%.
Can’t see much possible downside here and very good chance of upside especially when Rockwood really force them to get it sold or broken up .
Nice dividend whilst you wait .
Don’t think I’m missing anything this is one of the sitting ducks of undervalued unloved overlooked small caps .
Plenty others out there I guess and centaur has admittedly gone sideways for a long time .
How long left before Mills and Staveley force the action ?
Centaur Media (LON:CAU)
A frustrating hold planetX. The Lawyer on its own must be worth a large percentage of the current market cap. Hopefully Messrs Staveley and Mills can conjure a positive outcome, as they have held it for quite sometime.
I agree that Centaur Media (LON:CAU) looks very cheap, but I would say that as a long term holder wouldn't I! What concerns me is that the very 'preliminary talks' with the private equity group recently came to nothing without flushing out a trade buyer at all (as, no doubt Norwood had hoped). Why was this? I have no idea, but I hope that we get some further corporate action soon or I worry that this is going to remain an unloved and lowly rated dog.
Centaur Media (LON:CAU)
Downing Strategic has reduced its holding to just above 3% from 4.39% (RNS of 5 June).
I suspect that Downing's holding in Volex (LON:VLX) is also keeping a lid on the share price.
June not great so far. Perhaps instead of the time-expired adage about "sell in May..." we need an updated version like: "Close the laptop down in June and open it up at the next full moon".
I agree, but I must say this year I've put time into setting alerts on all my PF stocks to generate emails to a specific Gmail account which buzzes my google watch while I'm trying to attack the Matto Grosso which used to be my garden. Such a lot of rain, seems non-stop since October. Automatic stop losses are hopeless for a lot of stocks in my PF, being only traded via market makers, it's very easy for them to hit stop losses by dropping the bid so I get a warning which I can act on or not.
Great idea and setup.Just got a google pixel to replace an old iphone.Might need to look into google watches; never had a smartwatch yet.Good luck with the garden!The rain has totally destroyed by echiniccea this year.I had a lot of the prairie coneflowers and thought they were pretty hardy being prairie natives.However none appeared this year and after a bit of research i think the rain has had them and/or a rain borne fungal disease.Such a shame as i had a lot and was starting to try make them more of a theme in the garden!However, i must say the rest of the garden has benefitted and is looking nice and lush and lucky to have someone to keep the lawn under control (as that's a boring job imo!), while i tinker with the flowers.
Slugs/snails, slugs, slugs and slugs!
Haha, yes indeed. I used to have a racing snail which I modified by taking off its shell. Didn't help a bit, if anything made it more sluggish.
Seriously now, I said my watch was a Google watch, it's actually one of a selection available on Amazon which aren't well known brands but with Amazon's usual guarantees. Connects to my Android phone by bluetooth and I think there is a version of the app for Apple too. While talking of Amazon, I bought a second-hand Samsung 5g phone on Amazon but found that it wasn't actually sold by Amazon with their usual protection although the ad was worded such that I thought it was. I was a bit worried when I had a little problem but the seller handled it very well so caveat emptor read the feedback.
Morning,
Trading update by ME International (LON:MEGP) will you be covering this morning please? Share price down as I type.
Staffline (LON:STAF)
The point of buybacks is to buyback your shares when the price is very low as it was a couple of months ago hovering around 25p and not when it has climbed about 50+%!
All the best
I made a similar observation a couple of weeks ago about Vistry (LON:VTY) (I hold), who seem to buy the new highs, rather than the pullbacks. Their latest was last Tuesday at 1294p. Today the price is 5% lower but expect them to miss buying the dip.
Hi Paul, videos sound a great idea and have a great break, any discussion on any day is always welcomed. Out of interest what software did you use?
Hi Steven,
Out of interest what software did you use?
It's a google chrome plugin called "Loom". It's a free trial, but they're slowly drawing me in towards having to pay $240 for an annual subscription. That said, so far it's performed superbly - incredibly easy to make videos, as I just press one button in my browser to activate it. No downloads or uploads for each video, it's all done automatically in the background, amazingly easy & intuitive to use. So far I'm very happy.
If there's any simple, free alternative video recording software, do let me know, as I don't really want to have to pay for this. There again, it works so well, might be a worthwhile cost.
Regards, Paul.
Paul Video software
Another innovation from Google. No wonder its share price keeps going up!
Maybe you could email them with the influencer angle and get a free version.... Hey I'll make videos watched by thousands using your software from the pool in Gozo... top half only... If Kim K can do it so can you.
Thanks Paul I've tried some free video recording software but they always have some sort of limitation. I think the free trial ones are good as you can see how it works without committing to buying it.
If they weren't confident in their products they wouldn't offer a free trial. Thanks for the quick reply too.
Positive U turn by Labour - Was chatting about this with my IFA last week. Quite a few clients were concerned so good to hear.
Labour abandons plans to bring back lifetime cap on tax-free pensions savings
https://archive.ph/M1S5b
Positive U turn by Labour
you mean good for the lucky few who benefit here.
thats £800 mill they will have to raise somewhere else all other things being equal.
being frank giving generous tax breaks to those with over £1 million in their pension pots seems crazy - albeit i do understand that moving goalposts with pensions is rightly so a touchy subject.
for transparency here i would say Kier was possibly backed into a corner here from moral standpoint - he IS one of the lucky elite who had his own legislation written in his name to specifically exempt his DPP pension income from being subjected to the lifetime limit ref tax charge (The Pensions Increase (Pension Scheme for Keir Starmer QC) Regulations 2013).
Probably easier to give other similarly well of people the same break rather than having to face the very obvious double standards accusations he would (and did) face otherwise.
Oh and just in time to grab a few votes - i doubt the policy change is well enough understood by the majority of the electorate that there will be much of a fuss about the money being found elsewhere - or added to the national debt.
I spent the last 10 years of my employment being unable to contribute to a pension. What makes Sir Kier different?
Unbelievable but true…
Not really unbelievable. It was standard practice for retiring DPPs.
Starmers views on the issue for the Beeb were
"Sir Keir said it was "a government pension scheme put in place for DPPs", which was why it needed an act of parliament to bring it into effect.
The Pensions Increase (Pension Scheme for Keir Starmer QC) Regulations 2013, external means the lifetime allowance does not apply to Sir Keir's contributions from his time as DPP between 2008 and 2013.
The legislation means Sir Keir would be exempt from paying additional tax on pensions savings over £1m.
Sir Keir said he had not taken advantage of the tax break, adding: "Nor do I want to."
....
"When we reverse that change the government put in place last week I will be included within that.
"Whatever changes is needed within legislation or anything else, I am very happy want to be and will be in the same position as everybody else in this country."
he is part of the elite - that was the point i was trying to make !! not sure if there is any logical reasons why he and other similar may have had special treatment - perhaps there was a good technical reason but i very much doubt its much other than "because they can" .
to be fair to Kier he may not have actually benefitted from this generous arrangement (see his comments below) - hmmmmm could it be that he might benefit in the future begrudgingly - looks like he stopped short of saying he would NOT beenfit in the future. - simply that he didnt want to benefit !
Sir Keir said he had not taken advantage of the tax break, adding: "Nor do I want to."
As ever with stuff like this where they the politicians flip flop on their views depending on whats popular or suits their current narrative kinda says everything that you need to know really.
ref unfairness of lifetime allowance - it probabaly wasnt unfair till they started using it as a tool to presumably raise extra taxes by reducing it in real terms from 2015.
This is good news indeed. Funnily enough, I wrote to Rachael Reeve about this a few weeks ago, saying that the lifetime limit was a terrible concept, capping peoples' pension pots just means they'll collect far less in future taxation. £1m is not a lot of money to fund a retirement that could include 30+ years of living costs, and possibly increasing amounts required in care costs. Not just for us, but possibly having to pay care costs for other family members.
I suggested to Reeve that mores sensible changes to the pension system might include -
1. Removing the IHT exemption for pensions. After all, the point of a pension is to provide for my own future living costs & care expenses. Why should that pass to the next generation exempt from IHT?
2. Reduce the recently increased £60k pa tax-free allowance for putting money into pensions.
3. Reduce the tax relief for money going into pensions to a flat rate of 20%. The 40% tax relief for higher earners putting money in, seems too generous to me.
Then let people build up their pension pots to the maximum they can, and the Govt will subsequently receive much larger tax receipts from affluent pensioners drawing down their pension and paying income tax on it.
So I reckon it seems obvious actually, that abolishing the lifetime allowance will enable the Govt to collect in far more income tax, longer term.
Care costs are now incredibly expensive. An unnamed pal is currently having to pay £30k per MONTH to have 24 hour care for his parent, who refuses to go into a care home. That's an extreme case, but it requires employing 6 qualified people - as there have to be 2 people there all the time, in 3 shifts. That would burn through a previous max of £1m pension pot in just 3 years.
Finally, I think a 55% punitive tax charge when a pension pot goes over an arbitrary maximum, is just morally wrong. It's theft, pure and simple.
So bravo to Rachel Reeves. I actually think she looks a reasonably safe pair of hands. Not sure about the rest of them though LOL!
Regards, Paul.
The other consideration is that there were certain well-paid professions, like judges and potentially doctors who were going to be exempt anyway. In what world does that make moral sense? At the very least it should be a level playing field for all.
What an excellent review of the options, advantages and consequences. I trust that Ms Reeve takes the good advice.
Pension tax relief is the tax you don't pay because you've put money aside into your pension to ensure you can support yourself when you stop work. It's a subsidy from all taxpayers to you as an individual. So many decisions about pensions are party politically expedient rather than financially rational. I've never understood how George Osborne justified the IHT exemption. Instead of tweaking annual contribution limits and lifetime allowances, see the problem clearly: to limit the advantage (and cost) of pensions tax relief fairly you need to cap the annual or cumulative amount of relief an individual can claim. As an example, £10000 allowance a year (or maybe £200000 over a lifetime) would allow a 20% taxpayer to contribute and get tax relief on £50000 (as if!) and a 40% taxpayer to get tax relief on £25000 a year etc. Equal tax savings to each taxpayer.
Lab did the right thing in doing nothing. There are (from memory) 6 different types of minimum tax free benefit that a person can have within the lifetime allowance regs (and people can have more than one protection). Adding a seventh would not solve any problems .
Chill Brands (LON:CHLL) has to be one of the worst RNS’s I’ve ever read
Can see this as being a textbook example of what can go wrong at listed companies- worth a read for shock value (& hopefully no one here ever invested in it)
Agreed Astongirl. Lunatics running the asylum.
There was a bloke on here a while back trying to ramp them, was subtle as a brick.
He was Wolfie well spotted
But when I tried to reason him with numbers of the fraud Chill Brands (LON:CHLL) all my posts were deleted!
Chill Brands (LON:CHLL)
I remember that well yiannos1.
It was Bri72. He came across as a very argumentative and rampy individual.
He last posted on Chill Brands (LON:CHLL) on 28/12/23. No surprise that he hasn't been seen or posted since.
https://www.stockopedia.com/co...
Snazzy
to be fair he just put his point out there and because it didn’t fit the value narrative everyone jumped on him. Hopefully he didn’t have too much on the line.
Let us hope Plod and the FCA get involved with Chill Brands (LON:CHLL) . They have a strong track record on bringing miscreants to justice. Oh, hang on....
Chillbrands
Might be a bit more to it than meets the eye ?
We’re only getting one side of the story .
It’s a pretty good domain to own chill.com
Website and products actually looks pretty good and it’s not actually a bad sector to be in so wonder what this will end up looking like .
That’s the last remnants of a bull case .
Then again , if it looks like a turd , smells like a turd, and feels like a turd it’s hardly going to be a diamond is it ?
Indeed, the domain might have some value. Having been part of several secondary purchases of domain names in prior roles, something like chill.com could be worth at least hundreds of thousands, if not low millions (maybe even more).
If they manage to get the domain name back and if after suspension the shares drop to c£5m market cap, it could be fully "NTAV" backed by the domain name.
My morning smallcap tweet: Smoking ruin
Chill Brands (LON:CHLL) Woodbois (LON:WBI) Arecor Therapeutics (LON:AREC) Partway (LON:PTY), ME International (LON:MEGP)
◄Chill Brands (CHLL)► update on this car crash. Sacked CCO Antonio Russo has transferred chill.com to himself. Also $400k transferred from US subsidiary to Russo and ex COO Trevor Taylor. "We are totally shocked by the extent of destructive behaviour and actions of Mr Taylor and Mr Russo." [SP=2.15 Cap=11m]
◄Woodbois (WBI)► now expects to get FY-Dec results out this month. [SP=0.54 Cap=22m]
◄Arecor Therapeutics (AREC)► needs new funds sooner, in Q3 2024 due to higher working cap. Guides FY24 rev in line with market expectations,. [SP=155 Cap=49m]
◄Partway (PTY)► has not found an RTO candidate and proposes de-listing. Will return capital to holders. [SP=0.75 Cap=1m]
In line: MEGP
Great videos over the weekend Paul and many thanks for all the other valuable work you do every day. That you can make it entertaining as well is a near miracle.
Thanks Peter! :-) Shares/macro can all be rather dry content, so I tend to inject a bit of silliness and the occasional rant, just to liven it up a bit!
Hi Paul, I can only echo all the sentiments, your efforts are amazing and fun too! You did mention about screening for broker u/g and d/g did I miss that link? Cheers.
Hi TheOx 2906,
You did mention about screening for broker u/g and d/g did I miss that link?
That was just an idea that I mentioned in the podcast I think (in between rants!), I haven't done a video on that yet.
As it's quiet for news, I might do a video on screening for upgrades a bit later today.
Regards, Paul.
Here we are, I just recorded a new video demonstrating how to set up a stock screen to identify broker upgrades.
Fantastic thanks Paul!
Great little pice of work Paul - How to set up a "filtering" screen away from pure financials the lets you focus on performing financial quickly! I played with permutations of it for ages last night looking for good prospects to DMOR on (D My Own R)
Videos? Did I miss a meeting?
That'll teach not to go straight to the comments
To paraphrase Private Eye;
Sir, Peter Withe and Paul Scott, are they by any chance related?
ENA B. MARWOOD