Small Cap Value Report (Mon 11 Feb 2019) - UPGS, AVAP, STR

Good morning, it's Paul here!
It's a very quiet day for trading updates, and results.
Graham and I had a natter about some stocks in my portfolio, just after the market closed on Friday evening. Here's that podcast, which is a potentially painful 1 hour long. We continued chatting about Brexit for another 1.5 hours after that, but you'll be relieved to hear that Graham had switched off the red button before that started!
Incidentally, the picture that Graham chose to illustrate the podcast, of some people playing football, perfectly sums up my school memories of football - namely the player (in red) on the right, who is recoiling in horror, in a slightly camp way, as the football comes in his direction & he feels the pressure of having to do something with it. Yep, that was just like me;
UP Global Sourcing Holdings (LON:UPGS)
Share price: 65.2p (up 12.4% today, at 11:38)
No. shares: 82.2m
Market cap: £53.6m
Ultimate Products, the owner, manager, designer and developer of an extensive range of value-focused consumer goods brands, announces the following trading update for the six months ended 31 January 2019 ("the period").
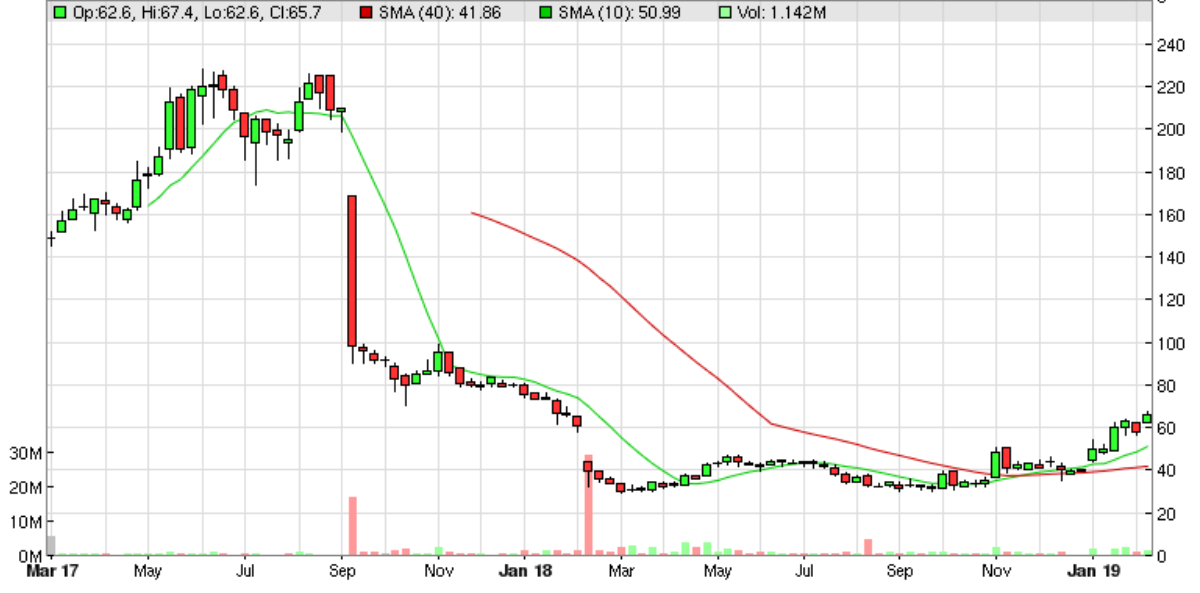
This company, which imports consumer goods from China, I think, was a very disappointing stock market float in March 2017. It floated at 128p per share. Note that the float did not raise any cash for the company, it was a sale of 50% of the company, raising £52.6m for the selling shareholders. I'm really not keen on this type of float, as they often seem to go wrong later.
Initially UPGS shares did well, and rose to a high of about 223p. Then came the (first) profit warning, in Sept 2017, just 6 months after floating. I really do think that selling shareholders should be legally required to repay some or all of the proceeds, if a share price collapses so soon after listing. Maybe listing proceeds should be put into escrow, and released gradually over say 3 years? Or have a clawback clause?
After languishing for a while, the share price has had something of a recovery recently, so this share could be worth a fresh look. People who follow sentiment via the chart & moving averages, etc, might like this. I think there's also something to be said for looking at shares which are resilient in a lousy market such as we have now.
H1 trading - this company has a 31 July 2019 year end date, so today we're looking at H1 performance, and full year outlook.
My summary of today's update;
- Revenues - good growth, up 36% reported, up 20.8% underlying (stripping out one-offs) - impressive that the company has disclosed this openly
- Comfortable headroom on funding (i.e. bank facilities) of £10.5m
- Nothing said about H1 profitability (doesn't matter though, as FY outlook is given below)
Current trading & outlook - this is good;
As a result, and notwithstanding the higher overhead costs associated with servicing the increased revenue and the investment in the growth of the international business, the Group now anticipates that its EBITDA performance in FY19 will be above the market's current expectations.
Why do companies use EBITDA as the performance measure? It just arouses suspicion. Profit before tax is the correct performance measure to use. That gripe aside, above expectations is a clearly positive outlook.
Broker forecasts - there's an update from Equity Development today.
FY 07/2019 EBITDA (yuk!) is raised 10% to £8.7m
Adjusted EPS forecast is 7.0p, half paid out in divis of 3.5p
That gives: PER of 9.3, and yield of 5.4%.
My opinion - it always takes time for investor confidence to rebuild after companies disappoint with profit warnings.
UPGS share price has more than doubled from its recent lows. That to me looks justified, given today's update.
Looking at its last balance sheet, overall it's OK. There's a fair bit of debt, but that is only partly financing inventories & receivables, which looks fine to me.
Taking everything into account, I think the current share price looks about right. The positive chart might lead to momentum buyers taking it a bit higher, perhaps?
Avation (LON:AVAP)
Share price: 273p (up 4% today)
No. shares: 64.5m
Market cap: £176.1m
Avation PLC (LSE: AVAP), the commercial passenger aircraft leasing company, provides investors with an update on current operations concerning the half-year period ending 31 December 2018.
Things seem to be going well;
The Company's business continues to perform well.
Results preparation is underway and Avation expects to report increased profit for the six months ended 31 December 2018, with both earnings per share and profit before taxation expected to be approximately double that of the comparable half-year period ended 31 December 2017.
Revenue (unaudited) is expected to increase to approximately US$58 million (2017: US$52.4 million).
Outlook - there is no mention of expectations for the full year, which is a glaring omission. That's the whole point of a half year trading update - to let investors know how the company is performing against expectations, and what the outlook is like for the full year.
I can't find any broker updates today.
Valuation - it looks good value (measures as stated before today's 4% share price rise);
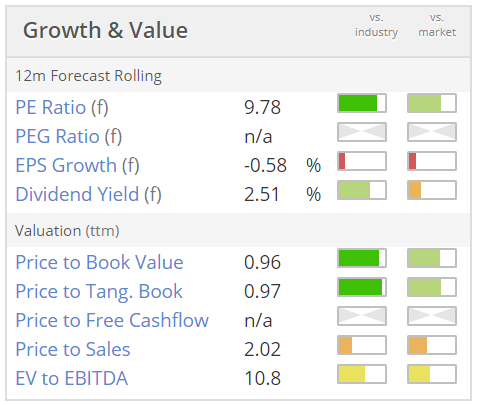
Of the above, I focus on the PER, which looks good value.
Also important is the P/TBV of 0.97, which again looks good value.
Dividends of 2.5% are unexciting, but worth having.
My opinion - We've discussed this share here a lot in the past, with it having looked good value most of the time.
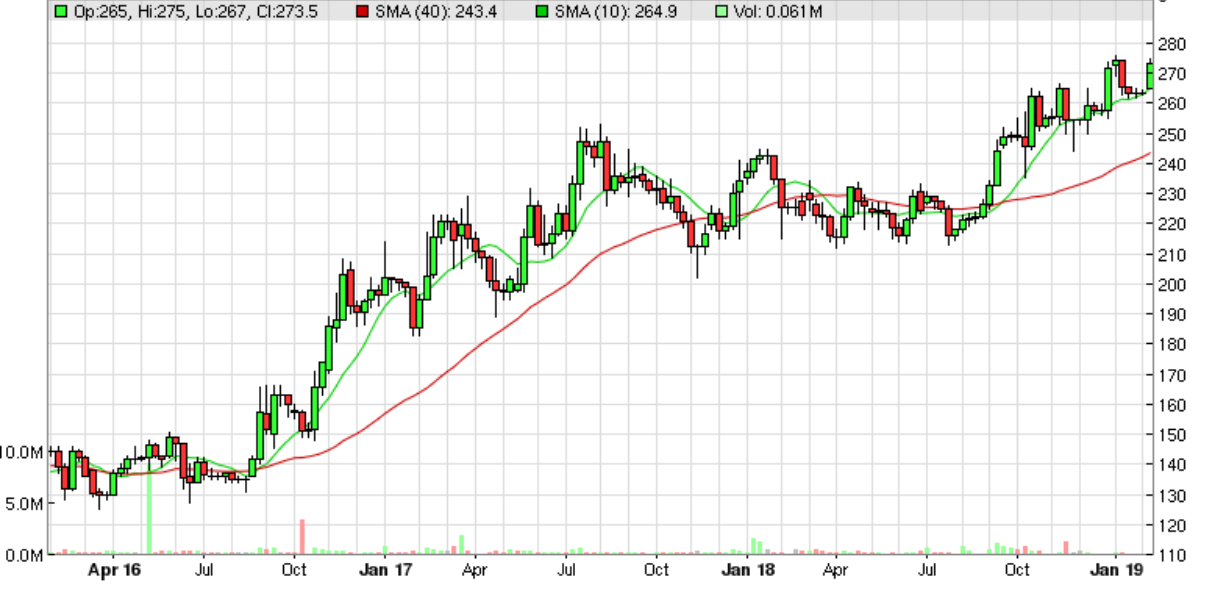
As you can see from the 3-year chart below, shareholders at Avation have done well. It's of particular note that this shares has been unusual in having shrugged off the recent market correction which has dogged many smaller caps, and growth companies;
The main issue with leasing companies, is that investors need to carefully assess the depreciation & residual value calculations. That's where the financial risk lies.
Avation's CFO, Richard Wolanski, has proven very shareholder friendly - attending many investor events. I remember attending several of his briefings, where he always sounds very alert to the risks, and it's clear the company carefully considers & manages its risk - e.g. with interest rates, bad debt risk, etc.
Overall then, I think this company has established a good track record to date, and seems reasonably priced.
Stride Gaming (LON:STR) - has put itself up for sale, in a strategic review.
It also counters press reports which said it was fined twice by the Gambling Commission. Stride says it was actually fined once.
I looked at this share last week, concluding that it looked cheap. The regulatory problems & fines, and tax increases, put me off buying any. With possible bid interest now added into the mix, this could be quite an interesting each-way bet - being cheap on fundamentals, with a big dividend yield, and possible upside from a potential sale of the business, maybe.
All done for today.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

26 comments
Regarding UP Global Sourcing Holdings (LON:UPGS) (I hold), I can't reconcile their statement that there has been "good growth across each of the Group's four strategic pillars - i.e. discounters, UK supermarkets, online platforms and international customers" with their other statement that international has increased from 20% to 40% of revenue. By my calculations based on the numbers given, that leaves non-international roughly flat from H1 '18 to H1 '19. There may be some scope for error in how I/they have handled the 2 exceptionals in the international percentage calculation, but however I work it out I can't get to "strong growth" in all catagories based on that international percentage increase.
Re UP Global Sourcing Holdings (LON:UPGS) surely major customers can be both discounters & International...I believe B&M is a major customer so they could have their business split U.K. & International ?
Also Action is a discounter/supermarket & operates in 7 non U.K. markets & is a customer so no idea where that would sit..either
UP Global Sourcing Holdings (LON:UPGS) Yes, I think you're correct, that there is overlap between catagories. In the annual reports the segmental analysis is split between discounters, UK supermarkets, online and other, and the UK / non-UK split is given separately. There is no segmental split in the interims.
I think they've probably just been a bit careless in the trading statement in lumping international customers in with their segmental split in a way that they don't in the annual reports (and omitting other), and that I was reading too much into it. However, it does seem clear from the numbers that UK is flat, and international is booming. UK flat is probably not a bad performance in the present retail climate though.
was tipped elsewhere on saturday and added growth portfolio
https://www.scsw.co.uk/searchresults.php?textfield=upgs&ftype=
IPO - blame gullible Other People's Money investors for setting the price, and gullible their own money investors for thoughtlessly chasing a price higher if the listing price was risk discounted. An IPO is very high risk where the sellers know infinitely more about the company. If the market was in any way efficient the first exit would be at a discount, and there would be minimal trading until sufficient news announcements for trends and assumptions to be verified. The market for an IPO'd company is not efficient for most of the business cycle, being too cheap at the beginning of the cycle when prices are low but prospects high, and too expensive when the cycle is mature when the reverse is true. The value of the former, and subsequent good returns, is a root cause of the latter.
Thanks fully for investors it is easy to come up with a winning and non-losing strategy; don't invest in new listings apart from in the foot hills of a recovery from a recession.
Podcast would be a fantastic idea. Or even just doing a verbal SCVR. Having seen Paul do an early morning SCVR on the stage at Mello it was really interesting seeing the way he proceeded though company reports.
Can I suggest the Friday podcast commences with a review of the prior night's Question Time...
Please no, I can't watch QT because of the half-wits spouting their opinions, and that includes both panel and audience members!
It was said in jest, Andy. You clearly don't follow Paul on Twitter!
“We continued chatting about Brexit for another 1.5 hours after that, but you'll be relieved to hear that Graham had switched off the red button before that started!”
What a shame I bet it would have been fascinating!!
“We continued chatting about Brexit for another 1.5 hours after that, but you'll be relieved to hear that Graham had switched off the red button before that started!”
What a shame I bet it would have been fascinating!!
Well I share Paul's relief. I'm not sure there's anything more boring currently than listening to people discussing Brexit. I voted Remain but now really honestly don't care what happens. I just hope one day I'll be able to listen to and enjoy the Radio 4 Today programme again.
All the best, Si
Hi Simoan.
I thought it was just me! Since the mid December Brexit flare up, I’ve stopped taking a daily paper (shame as I liked to do the crossword), switched from Radio 4 to Classic FM (should’ve done that years ago) and stopped reading the BBC news website (not really found a non-Brexit alternative yet). Who said Brexit wasn’t likely to change anything?
Gus.
+1 for the podcast- really enjoyed the last one
Graham/Paul
Excellent Podcast. I would be an avid listener if you did more like this.
Regards
Howard
UP Global Sourcing Holdings (LON:UPGS) - Equity Development have published new research paid for by UPGS:
https://www.equitydevelopment.co.uk/edreader/?d=%3D%3DgM0UjM
To expand on my earlier post, compare that with this from October:
https://www.equitydevelopment.co.uk/edreader/?d=%3D%3DgM4QjM
So we've gone from:
* In September I thought we had a timing issue and short term growth setback in FY2018 meaning FY2019 revenue would be slightly above FY2018's £110m (albeit at lower margins / EPS).
* In October they forecast FY2019 revenue of £95m (and 5%pa growth thereafter).
* Today, they forecast FY2019 revenue of £118m, above FY2017 and in line with my September expectations.
While clearly things have gone well, I strong suspect there has been some expectation management going on here in order to create and maintain momentum. On this basis I think FY2019 is on course be modestly ahead of today's forecasts and FY2020 should show growth significantly above 5% on top of that. EPS back to 10p for FY2020 looks quite possible vs. latest forecast of 7.3p.
Paul, Graham,
Excellent podcast, really insightful and a pleasure to listen to.
Keep up the great work.
DG
Today Avation (LON:AVAP) issued a Trading Update in which the key parts were:
Avation expects to report increased profit for the six months ended 31 December 2018, with both earnings per share and profit before taxation expected to be approximately double that of the comparable half-year period ended 31 December 2017. Revenue (unaudited) is expected to increase to approximately US$58 million (2017: US$52.4 million).
Mmmmm I sorta disagree! The business of Avation is aircraft leasing and therefore it is aircraft leasing revenue that I am interested in. The comparable figure of $52.4m is flattered by what I would claim is an exceptional figure of around $10m which was the recovery of maintenance reserve from an insolvent (Air Berlin) A320 so the comparable figure is actually $41.7m That means comparable lease income has increased by around 38%
So, lease revenue $58m v $41.7m (+38%)
We can work out H1 2019 lease revenues by calculating H2 2018 revenues and then adjusting for fleet changes in H1 2019 :
FY2018 Lease revenue $109m
Less H1 2018 Lease Revenue 2018 ($41.7m)
Less Air Berlin Maint. reserves ($10.3m)
Gives H2 2018 (June 2018) Revenue of $56.7m
So if no changes to revenue then H1 2019 should be $56.7m
But there were some changes:
ATR 72's (DAT) additional revenue ($0.59 + 0.24m) = $0.83m
A220's = ($1.8m + $1.6m) = $2.4m
A230 (Vietjet sale) loss of revenue = -$0.74m
Net change = $2.49m (i.e. additional lease revenue in H2 over lease revenue H1
= 56.7m + 2.49m = $59.2m ie. more than the TU today of "approximately US$58m"
The difference can be due to around $0.1m in EUR/USD exchange (the DAT ATR72 aircraft)
Timing issues in my calcs ~$0.2m
Me just getting lease rates wrong ~$0.5m
So I end up with $58.4m
So where is the revenue being recognised from the A320 Vietjet aircraft sale? So I bunged an email to Avation and got it confirmed that the revenue does not include the Viet Jet sale. i.e. there will be even better news when the results are released namely;
Lease revenues +35 to 39%
Additional 'profit' on Vietjet aircraft which are claimed to be substantial and ny that I would say anything between ($1.0 and $3.0m)
For the avoidance of doubt I have been a multi year shareholder in Avation and visited them in Singapore a while ago. It is my number 2 shareholding. I consider Avation should be a long term share holding and should be valued at NAV or above. EPS and Profitability can be massively skewed year on year by one-off transactions which, whilst perhaps is useful for short term traders holds little appeal to me. The business is about bringing in more aircraft every year. Avation are an absolute minnow in the aircraft leasing world. Tiny, and as such gives them capacity to make substantive increases in NAV. Currently one of the most exciting things about Avation is there activity in the A220 (ex Bombardier C300 series aircraft) which are being procured at exceptionally low cost and I forsee in 5-7 years will provide significant increases in aircraft valuation and hence NAV as the aircraft proves itself in service. But again this is a multi year outlook. I often post about Avation on the Lemon Fool (and here)
I consider the current share price to be reasonable value.
Graham, Paul, very useful thank you.I do like the way you bounce off each other. Clearly different investors, both with good insights. I know the story on Intercede now which is in your portfolio, Paul. I was quite pleased with last results which showed some progress under the new CEO, i recall revenues up 14% and costs coming down. However was surprised at the share price movement. Quite resoundingly down. I can see that the shares are tightly traded and so any seller will impact which is what I suspect happened. Have you heard anything else any where? But my question is this, i hadn't realised the institutions were becoming unwilling to fund small company raises. IGPs balance sheet isn't the strongest. Do you see this as being an issue?? All the best
UP Global Sourcing Holdings (LON:UPGS) - Unfortunately I halved my holding after the Equity Development note on 3/10/2018 which forecast a very modest recovery in FY2019 followed by medium term sales growth of only 5-6% which was a long way from my expectations of a significant snap back after well-advertised one-off factors and a return to 15-20% growth.
Following the unscheduled trading update in January it became obvious that business was progressing closer to my original expectations rather than ED's note. After today's update it seems this is down to a mixture of management guiding ED to be very cautious after multiple previous disappointments and also outperformance overseas.
With a PE under 10 and PEG around 1 before pending upgrade, good momentum (supported by management guidance that may remain behind the curve), and reducing debt, a recovery back over £1 in the next 12 months looks quite possible. Margins remain a concern, but hopefully they will report some improvement in their H1 results.
Edit: mojomogoz wrote this excellent update last night: https://www.stockopedia.com/co...
My morning smallcap tweet: No wonder Windar was wilting
Connect (LON:CNCT), UP Global Sourcing Holdings (LON:UPGS), Windar Photonics (LON:WPHO), DCD Media (LON:DCD), Stride Gaming (LON:STR)
Connect Group (CNCT) new contract with Reach from October 2019 to 2024 to distribute Daily Mirror etc. Worth £220m PA.
UP Global Sourcing (UPGS) H1 trading: rev up 20.8%. Guides FY EBITDA above market expectations.
Windar Photonics (WPHO) FY18 trading: rev up 59% to £3.5m (prev guided €4 - 4.5m), EBITDA loss €0.36m (€1.22m). Order book only €1.0m (€3.9m). Component shortages hit H2 prodn, some orders deferred. Why has it taken months to warn?
DCD Media (DCD) guides FY rev only £7.3m (£10.2m) and £0.1m pretax. Current Q1 strong, Q1, with sales that were expected to fall into last year falling into the current year.
Stride Gaming (STR) confirms press reports that it is reviewing all strategic options including sale of group. Denies it was fined twice by the Gambling Commission last year, only once.
Paul/Graham - It's an excellent audio, much appreciated, highly recommended to all who have not yet listened to it.
As Fridays are usually quiet, perhaps you could consider a 1 hour audio on markets/holdings instead - Would probably also be much easier on both of you time wise too.
Thanks once again to both of you for your time and sharing your valuable knowledge.
Hi Matylda,
That's a really good idea - maybe Graham & I could do a weekly roundup podcast, of all the things that caught our eye that week.
I'll run it past Graham & see what he thinks.
P.
Hi Paul,
Great, look forward to hearing how that might progress, thanks again to both, have a great week.
1 hour audio.... every week!!
I might have found time when I was employed but I'm retired now. How am I going to find that much free time?!!
(Joking apart, thanks for the audio Paul & Graham. I've not played it yet but very much look forward to doing so sometime over the weekend, sooner if we get some poor weather).Hi liontamer,
Oh God no, it wouldn't be an hour every week!!!
If we do a weekly (or fortnightly) podcast, then it would be much shorter. Think 20-30 mins max. After all, at 4:30pm on a Friday, I'm limbering up to get stuck into some tinnies!
P.
Great initiative to spruce up slow Fridays (credit to Matylda)
Don't push yourself to an each week fixed podcast commitment Paul / Graham
Why not also include some catch up on wider topical news / views you couldn't get to in the week-
- (From today) Expound on IPO Sell out into Escrow
- Where is the High street going?
- What has Mike Ashley bid for this week?
- Will Just in time supply work during the critical period of Br**it?
Or what ever floats your boat from the week