Small Cap Value Report (Mon 11 Jan 2021) - JD., CALL, IDP

Good morning, it's Paul here with the first of this week's SCVRs.
Mello - tonight!
It's Mello Monday time again - David Stredder's very popular investor evenings, now on Zoom.
This evening Ed will be presenting a review of Stockopedia’s Stock Picking Challenge 2021, and reviewing the leaderboard for 2020. It’s a great way to find out what stocks the community is looking at, so tune in to see the breakdown.
Jack will also be there later on, to take part in the Mello BASH (Buy, Avoid, Sell, Hold), with 4 new investment opportunities up for discussion alongside renowned investors Leon Boros, Alan Charlton, and Kevin Taylor. Find out more here.
Message from David Stredder;
"There are at least another 17 Mello Monday evening webinars already planned for 2021 and if you would like to make the most of these during lockdown then I really would recommend buying an annual pass for just £95 (or £85 with the early 2021 discount until 11th January using the code APXMAS10 when buying one here https://melloevents.com/mellom... Alternatively if you want a half price ticket just for this show on Monday and maybe want to 'try before you buy' the annual pass then please use this code MMStocko21 and it will be just £9.75"
Timing - Update at 12:22 - I'm taking a break now for lunch, and some exercise. I'll do some more sections from mid-afternoon onwards, so please do check back later. Update at 18:14 - sorry I've been busy with other things, so didn't get round to looking at any more companies today. I'll put them into tomorrow's report instead. Today's report is now finished.
Agenda -
Jd Sports Fashion (LON:JD.) - not a small cap but: remarkably good trading update
Cloudcall (LON:CALL) - another recruitment sector integration
Innovaderma (LON:IDP) - profit warning
.
Jd Sports Fashion (LON:JD.)
850p (pre market open) - mkt cap £8.3bn
This company has clearly emerged as the big winner in the sports retailing space, in the UK, and increasingly internationally.
Trading Update - this morning is strikingly good, and clear. Here it is in full -
JD Sports Fashion Plc (the 'Group') today announces an update on performance following the Christmas trading period.
Against a backdrop of further forced temporary store closures in many of our global territories, it is pleasing to report that demand has remained robust throughout the second half, including in the key months of November and December. Total revenues for the twenty two week period to 2 January 2021 in the Group's like for like businesses were more than 5% ahead of the prior year as consumers readily switched between physical and digital channels.
The positive nature of the demand through the second half to date means that we are now confident that the Group headline profit before tax for the full year to 30 January 2021 will be significantly ahead of the current market expectations, which average approximately £295 million. It is now anticipated that the outturn for the full year will be at least £400 million...
... Under normal circumstances, we would be confident that the results for the forthcoming year to 29 January 2022 would show a strong improvement on the current year. However, given the ongoing uncertain outlook with stores in the UK likely to be closed until at least Easter and closures in other countries possible at any time, our current best estimate is that the Group headline profit before tax for the full year to 29 January 2022 will be 5% to 10% ahead of the current year.
.
My opinion - this looks a remarkably strong update. Once again, it shows the importance of retailers being able to move sales online, as a key way to soften the impact of the pandemic.
My worry is that the big brands might move towards internet sales direct to customers (Nike has already indicated it favours this strategy in the USA). For that reason, I'm wary about whether JD's performance has longevity. So far though, that worry has cost me dear, as I've missed out on probably the best performing retailing share in recent years.
Well done to shareholders here, looks like you're in for an enjoyable day, with a big price rise likely, due to beating market expectations by a long way. Nice to see the company set out its trading update in such clear language, giving us the precise figures of;
1) What profit it expects to make, and
2) What the existing consensus market expectation is.
That's it, that's all we need! Why can't all companies do this? It's simple, and helps everyone understand the situation quickly & easily. I'm coming round to the view that some companies & brokers are being deliberately obstructive, by withholding this information in trading updates.
.
Cloudcall (LON:CALL)
(I hold)
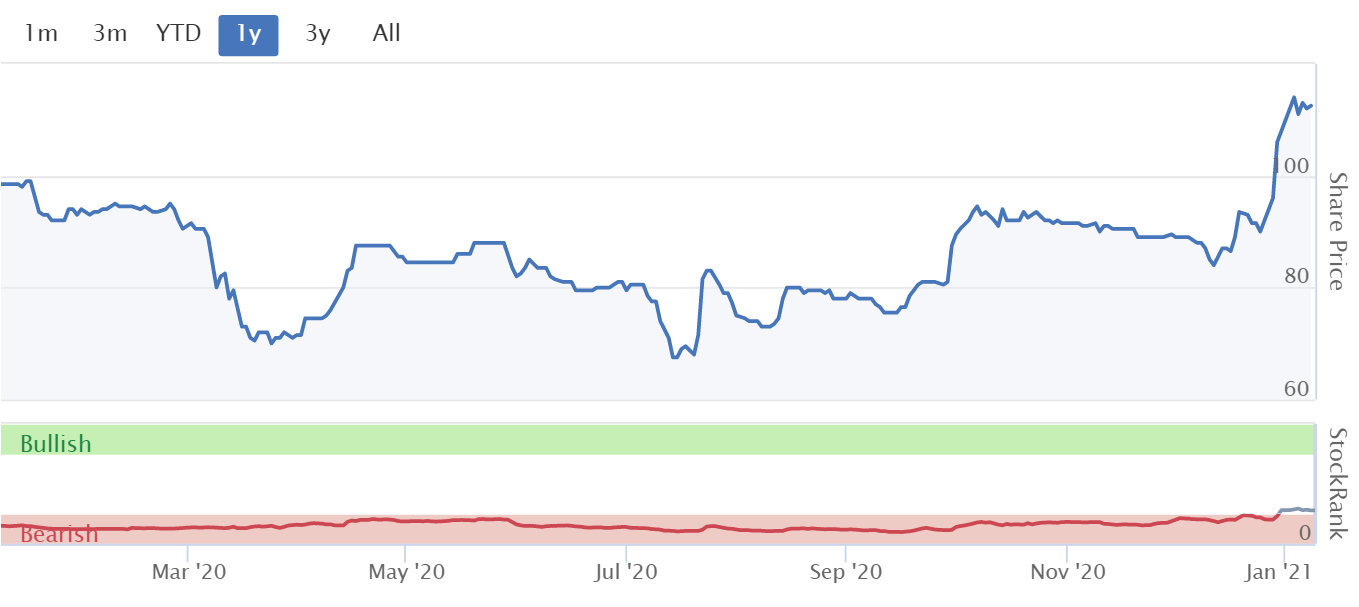
112p (pre market open) - mkt cap £44m
Second integration with The Access Group
I've had to read this statement 3 times to understand it. It looks like a nice to know, rather than a price sensitive announcement.
CloudCall (AIM: CALL), the integrated communications company that provides
unified communications and contact centre software that tightly integrates
with Customer Relationship Management ("CRM") platforms...
- The Access Group is an important CRM software provider to the recruitment sector, including well known names such as Adecco, Alexander Mann, Impellam & Staffline.
- CALL has "strengthened its partnership" by integrating its own communications software with a second of its products.
- Opens up CALL product to a "new group of users".
.
Directorspeak -
... This is a significant launch for CloudCall within the UK recruitment industry,
solidifying our position as the integrated communications provider of choice
for any of the leading Recruitment CRMs and further bolsters our vision of
providing users with the ability to discover business insight from
communications complexity."
My opinion - useful background information, but not particularly price-sensitive, in my opinion.
Note that CALL shares have been overlooked by investors for a long time, but have perked up a bit recently. There's a massive tech boom underway in the USA markets in particular. CALL does a significant proportion of its business in the USA, and also has about (from memory) 40% of its shareholders are now American, including several disclosable major shareholders. The CEO mentioned on a webinar a while ago that US investors had pushed for the company to do a big fundraise, which it did, and go for it, in terms of more rapid growth. I think that's great - UK companies & investors are generally far too cautious, scared of cash burn, and hence so often become also-rans, rather than leaders.
Maybe we're seeing some of the sparkle in US markets rub off on CALL? It's been a long haul, but I think the company is on its way to success now. Difficult to value mind you. Hopefully a US investor might decide to get out the chequebook and buy it for a whacking great premium!
The cash position should be fine for the time being, so we don't have to worry about another placing. Another lesson that can be learned from CALL, is that speculative, cash-burning companies tend to be floated in the UK market with nowhere near enough cash. Brokers need to address this, because performance usually falls short of plan with almost all speculative companies, leaving them high & dry, needing more equity fundraisings, often into a falling share price. Much better would be to build in a decent cash reserve, into the original float. So simple, but usually overlooked when companies are floated. Why is that same mistake made over & over again?
.
.
Innovaderma (LON:IDP)
50p (down 23% at 09:27) - mkt cap £7.3m
Bad luck to shareholders here, nursing a 23% loss this morning. It's very small, so just a brief comment from me, as I happened to have looked at this share last year when it seemed good value. A Director sold £2.15m-worth of shares in Nov 2019 (often a worry that something might be going wrong). Although I see from the Director dealings page, that a different Director bought £270k-worth at 69.5p more recently, in Oct 2020.
Trading Statement today -
InnovaDerma (LSE: IDP), a UK developer of beauty, personal care and life sciences products, provides a trading update for the six months ended 31 December 2020 [Paul: H1 of FY 06/2021]
My summary of main points -
- Covid restrictions have impacted performance
- H1 revenue £4.1m, down 20% on LY
- Skinny Tan doing well overseas
- Direct-to-consumer channel is priority, and now 62% of company sales - interesting. I'm guessing this must be mainly online sales? Do any readers know?
- Expecting tanning products (83% of total revenues) to improve as covid restrictions are eased. Peak season is April-June.
- 2 new product launches in Dec 2020 "very successful"
- "Strong roster" of new products launching in 2021
Cash position - uh-oh, I don't like the sound of this -
The Company has agreed in principle to enter into a loan agreement in the amount of £500,000 with M.Ward, a Non-executive Director and the largest shareholder of the Company.
A further announcement will be made shortly providing details of the agreement once it has been signed.
"Substantial" impairment review of balance sheet intangibles - doesn't matter to me, as no cashflow impact.
Board update - clearly there's been a massive falling out (or worse?) here, as the Chairman who was resigning with effect from 31 Jan 2021, has now been dismissed with immediate effect. It's very unusual to see the word dismissed used. To borrow, and amend MrContrarian's usual wording on these matters, he is not thanked.
An existing NED is taking over as Chairman.
Outlook -
- Strong H2 weighting expected, as in previous years, due to seasonality of tanning products
- Anticipating recovery in Q4 (Apr-Jun 2021) as covid restrictions hopefully ease
- Should be EBITDA positive in H2
- Exploring options to strengthen the balance sheet - oh dear, that means we should probably expect a placing, at who knows what price?
- Substantial growth opps once restrictions eased
- New (7 weeks) CEO talks up future growth potential
My opinion - this one looks too risky for the time being. Needs to do a placing, and being propped up with a Director loan, is not a good position to be in. I might look at it again once the balance sheet has been repaired with a placing. Why take the risk before then? Looks too small to be listed, so de-listing risk seems elevated.
Does anyone know what the new CEO is like, track record, etc? I like turnaround where a brilliant new CEO comes aboard, such situations can occasionally be terrific investments. Although important to remember that lots of attempted turnarounds don't work.
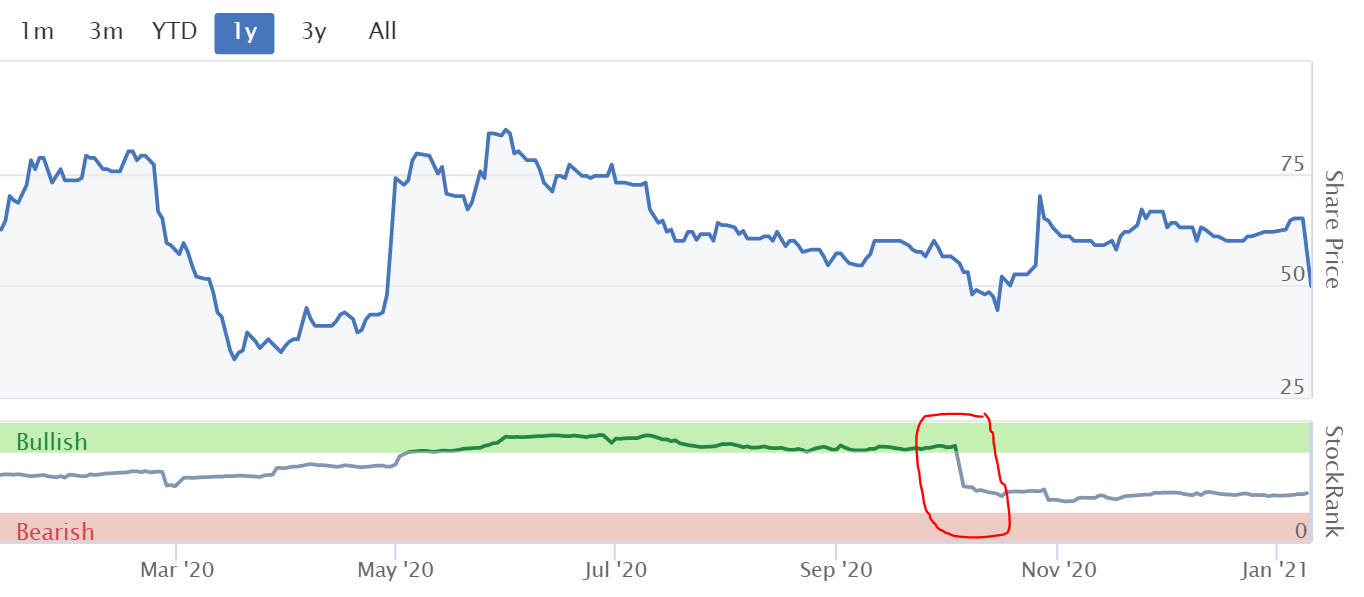
Interesting to see that the Stockopedia computers spotted something they didn't like in early Oct 2020 - see below (red circled by me).
.
.
John Authers article today
I'm a big fan of John Authers (formerly FT, for a long time, now at Bloomberg) daily email articles. I try to read it every day. Today's article is particularly interesting. In it, he compares Tesla (disclosure: I'm short, again) 800% rise in the last year, with the 1999-2000 TMT boom & bust. His conclusions, and the evidence he provides, are thought-provoking.
I agree with his conclusions, that there are good reasons why markets as a whole are where they are, but within that, there are pockets of really extreme over-valuation. Risk:reward on Tesla is therefore terrible at current levels - even if it does as well as people hope, in the upside bull case, it's still too expensive!
In the 1999-2000 TMT boom, people buying at the top, had to wait 10+ years to get to breakeven, even for great companies like Microsoft, Amazon, and Cisco, which he uses as examples.
Well worth a read! I'm not sure how you sign up for his free daily email, but it's highly recommended. Many thanks to MichaelFBS for providing the signup link, which is here: https://www.bloomberg.com/acco...
I'm also short of Bitcoin again, as I've digested all the bull & bear arguments, and understand it pretty well. It strikes me as a gigantic speculative bubble. If you're worried about fiat currencies being devalued with QE (a reasonable position), then don't hold so much cash. Put it into property, or shares, or other genuine assets. Putting it into worthwhileless computer code, seems to me to be folly, long-term. In the short-term though, Bitcoin bulls can thumb a nose at bears like me, as they're making the money (at least on paper), for now. It remains to be seen who is right in the long run.
EDIT: I forgot to mention, that the appalling energy consumption/waste of cryptocurrency mining, means that nobody with a shred of ESG credibility could possibly hold bitcoin.
Manias, Panics & Crashes (Kindelberger) - book review
I listened to an audiobook review of Kindelberger's classic, "Manias, Panics, and Crashes" over the weekend, and both Bitcoin & Tesla tick the boxes for a speculative frenzy, namely -
- Easy access to credit
- Over-optimistic mania
- Assumption that price of asset will rise forever
- Some significant event triggers an end to a boom (e.g. a bank failure) - prophetic, re Bear Sterns, and Lehman in 2008)
- Eventually a selling panic, and crash happens
- Banks liable to go bust as bad debts pile up
- Wave of insolvencies, creating international contagion
- Financial crises can't be stopped, but only contained (probably no longer true, given extreme Govt & central bank actions possible these days)
- One country should lead the international response to a major financial crisis
- Prophetic book, as written just before a series of major financial crises hit
- Debunked the efficient market hypothesis, which was academically fashionable (but clearly wrong) in the 1970s
- Entertaining text - novel in an economics book, for being an entertaining/human story, not full of numbers & formulae
- Irrational investor behaviour will always exist - an unorthodox view at the time
- Spawned the field of behavioural economics, e.g. Schiller (a student of Kindelberger)
- Investors are consistently over-optimistic in researching, assumptions, and their own ability to forecast & stock pick! So experience can actually count against you - if it makes you too certain of your forecasting ability
.
Well worth a read of the original, I'll add it to my (groaningly weighty) reading wishlist.
Sorry, I didn't have time for any more today. See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

87 comments
Just in case you haven't encountered the following view on bitcoin:
https://www.linkedin.com/pulse...
Good luck with the shorts Paul. I don't go short often and always keep positions fairly small as I've been burnt in the past but today the triumvirate of Tesla, Bitcoin and Trainline all paid off. With Tesla and Bitcoin I'm very cautious as I'm always reminded of the quote from Steve Eisman "You can't short something that's a cult". And indeed having a made a few quid I'm now stopped out already of both BTC and TSLA.
Interesting times for Tesla shares. The stock has had a massive runup from about $650 in late December to $882 yesterday. It fell 7.8% today. Legendary investor (is it OK to call him "legendary"?) Michael Burry announced he was short in early Dec 2020.
So whatever happens, it will be interesting!
Is January 2021 going to repeat the history of January 2020?
A market peak followed by (3 month) bear market?
The virus news in the short term, including purported death rates, is grim,
I am not going to get into the rights and wrongs of this today, merely to say that it is what it is, and Lockdown III is most certainly is happening, and the political and media narrative is grim. The World Wide virus picture also isn't great, and there is some US uncertainty too.
People selling their BTC and the only obvious safe place is into Tesla who will probably monetise the solar system through space cars and allow earthlings to swap their bitcoins for MarsCoins to go play beyond earth...
The stock market is clearly the place to discount such raging certainties
The linked comment (and replies to it) is a bit old and I've not been keeping up to date but IMO Innovaderma (LON:IDP) negatives have been coming down the pipe for a while:
https://www.stockopedia.com/co...
I remain sceptical that it has a good and expandable product line too. I'd make comparisons with Brand Architekts (LON:BAR) and Venture Life (LON:VLG) in terms of business and the potential for product failure to sink business.
As a tangential but connected aside, I remain amazed at the share price of Venture Life (LON:VLG) following recent hugely dilutive raise to perhaps one day spend on product acquisitions that will one day make money maybe...at 45x 2020 earnings (and those earnings might be high estimate and have a disappointment in them) its not cheap today....
Then throw in that profits are expected to double in 2021 in year after they had a real boost to sales that is at least partly and maybe largely covid linked (selling lots of cheap to produce hand sanitiser at a nice margin)
I could be very wrong and these guys do it....but the hurdle is nose bleed high. The sales and acquisition strategy from VLG has got to be absolutely perfect.
I put some more detail in responses I gave to hypy VLG specific threads
https://www.stockopedia.com/co...
mojo out
Held Venture Life (LON:VLG) in 2020 on trading update & sold on half year results.
Clearly some capable investors like it a lot but they do capitalise an awful lot of development spend for a company that buys heritage brands that are ready to go to market. Not to mention receivables - pretty easy to increase sales if customers don't have to pay you.
Mid market fund raiser after a rampy CoVid announcement (study sponsored by Venture Life (LON:VLG) ) & from my untrained eye Dentyl wasn't doing much that other mouthwashes don't do just creates more doubts.
Maybe I am being overly cynical or just an embittered ex holder - reading financial statements seems to be hazardous to your wealth in this market.
But if shareholders are happy to finance ever higher adjusted EBITDA, who am I to judge.
Vivek, facts or boundaries of reality seem optional at the moment
I thought this what quite a good general summary of conditions (US specific but I think applies to AIM to some extent)
https://theirrelevantinvestor....
My criticism of it is that bubbles are usually always narrow-ish and often pop without infecting the whole market beyond short term volatility and drawdown.
Bubbles with longer term and more sustained impact tend to be linked to bank exposures (eg 2008) or when value/cyclical drives the bubbling process (again 2008 was an example)
So I am simultaneously bullish and bearish right now. Schizoid environment IMO
Hi Paul,
I can see that and tend to concur with pockets of bubble theory.
My fear stems from fact that (without any knowledge and a great deal of speculation), the city / wall street work on the basis of FOMO (notwithstanding Citadel/Virtu front running retail) while the market makers are chasing their tail (short gamma for those who like their Greek), so the pockets maybe a little more crowded.
Pullback/rally/pullback/rally in a small group of (bubble) stocks as I understand is indicative of retail participation.
I managed to make 40% on Peleton in a month (I bought the vaccine dip and got lucky) - thought I was stupid buying on 800x earnings - clearly even stupider selling at 1,100x earnings!
Call me a cynic, but we will find out whether institutions are involved if "hype mania" pops and the FED put is written one more time.
Not wanting to be take John Hussman literally, but I do worry that it will be the passive funds/investors that will be left holding the bag. Had a great run with some thematic ETFs and really feel I should reduce (re-balance as a minimum).
I imagine like all things, passive / active also have cycles although I have no evidence to support my supposition. Nasdaq fell 70%, I can't trust buying the whole index, active didn't protect me in 2008 so why should I pay the fees. You probably have some real world experience / expertise to support/negate my assertions
But in the meantime, I take some shadenfreude in Robin Hood dumb money short squeezing the masters of the universe!
As far as the schizoid environment, this blog by Morgan Housel was a nice piece of inshite :)
https://www.collaborativefund....
Thanks Paul,
I'd quite forgotten that exchange re Innovaderma (LON:IDP)
Was it really 2019? Whatever happened to 2020?
Oh yes - THAT!
A useful reminder of some of the things to look for - as I commented at the time I wasn't too concerned about the points you raised and don't really think that any of them have played out negatively.
Except - I was comfortable with the intangibles (capitalising the cost of customer acquisition) :
1. Because even if excluded they were still modestly profitable during a growth phase and
2. Because the cost of customer acquisition (mostly via social media) was real and quite high but once a acquired repeat business could be generated at zero marketing cost (email). In fairness I think I only understood that second point fully a couple of months later when Kieran Callan spoke at MelloBASH.
This second point is interesting in that I believe they are about to write down these capitalised customer acquisition costs. Essentially, as I mentioned earlier it looks as though conclude that they will have to spend to "reacquire" these customers all over again once fake tans come back in vogue.
I'm not so sure on this point, so long as they have retained the right to contact these people (Data Protection and all that) then I think a "Hi remember us?" email might be quite impactful.
It will be interesting therefore to see the scale of the write downs and the market reaction to them. I think the market reaction will be adverse (particularly if the write downs are especially large, but I think that may be an over-reaction.
I watch with interest and thoughts about a possible second bite at the apple.
Mr Gromley, I confess that I looked in some detail at Innovaderma (LON:IDP) only in about 2017 so I'm out of date and can accept my perspective is mistaken (I'll shoot holes to partly see if someone turns my potentially wayward fire). The founder Chairman was still around and he seemed overly promotional to me and had listed a biz that didn't seem quite suitable/ready (and so he was trying desperately to work magic...spin stories etc) and the accounts were a bit questionable IMO in that they weren't as tractable as they should be. My view back then was that it would fall in price and that I would be able to get it at p/s <1...this was sitting on the fence in that I felt there would be a tougher period proving out product than was being expected.
Since then I've become a bit prejudiced against these small consumer products businesses with handful of products. They feel in a weak position to develop their products and prone to a negative surprise in sales. I struggle to see what gives them sustained traction beyond a truly hot product (whatever that is....bigger cos make it hot by really backing it). So they are always having to develop and spend to promote and never making escape trajectory.
I will probably watch what happens a little a bit...I can see it could become very cheap...but I worry about being able to see the sustainable runway for product. Do you have good comparison cases to shift my perspective? (I realise some will flag Venture Life (LON:VLG) but I think that's a highly problematic situation that could let investors down hard)
"The FCA is aware that some firms are offering investments in cryptoassets, or lending or investments linked to cryptoassets, that promise high returns,” the regulator said today.
"Investing in cryptoassets, or investments and lending linked to them, generally involves taking very high risks with investors’ money. If consumers invest in these types of product, they should be prepared to lose all their money,.”
Bitcoin fell $7000 today at the lows as it did last Monday in fact.
Paul - are the Mello talks recorded for viewing later please? Parts would be of interest to me but there is no way I can watch for 3 hours. I am too busy this week.
You are a brave man shorting Tesla and Bitcoin. I have held neither but could quite easily see Bitcoin going anywhere - down to $10,000 or up to $100,000 (hopefully for you down to $10,000 first!). My son is always kicking himself because he was aware of Bitcoin when it was a dollar but thought it was only for criminals to hide their money!
As I've learned the hard way, position sizing is everything with shorts - i.e. I keep them relatively small, so a big drawdown doesn't hurt too much.
Hi Paul,
Re:Bitcoin, as the saying goes, there is nothing new under the sun.
This has all happened before. About 15 years ago there was a cryptocurrency that was even backed by gold, called E-Gold. It too was the currency of choice for criminals. The FED watched it grow and when it reached a useful size, they closed it down. You can read the story here:
Bullion and Bandits: The Improbable Rise and Fall of E-Gold
The chap who set it up did so with good intentions, but as this quote from that article says. "No matter how innocent a person is you can always find a law that government agents can use to convict him of something," Timberlake says, "And this is a perfect example of it. Any time anybody tries to produce money, the federal government is going to be on their tail."
It's just a matter of time IMO. I've no position either way.
Think there is a video doing the rounds on twitter with the bull/fur guy from the Capitol incident. Maybe a conspiracy theorist, but like all jokes, conspiracies often have a kernel of truth.
Personally, I thought the guy was a Bitcoiner whether he knew it or not (No position). I would share but I don't want to be de-platformed :)
Doublelutz - The Mello evenings are recorded - you'll need to register ( and pay up) then in a day or two they will send you link to access the event.
doublelutz and all.....yes every show is recorded and the ticket holders get the recording about 24 hours later once any pauses/gaps in filming have been removed but they do tend to run smoothly tbh.
The big bonus is for annual pass holders as anyone buying one of those gets all the eight recorded shows so far and also the 20 plus shows that will take place during 2021. There is an offer currently running for £10 off those if you use the code APXMAS10
I see Tesla are up another 8% today. I read recently that Tesla shares and BTC / other cryptos are now the main destinations for the stimulus checks (sic) being issued by the US government!
But I suppose all this newly printed money has to end up somewhere.
I can't help feeling this is all going to end in tears.
According to the American economist, Robert Schiller, once a Stock Market's P/E exceeds 30 then strange things can start to happen. I believe the American stock market is currently on a P/E of around 36. Hence, I am expecting some sort of potential correction in the near future or some time this year. When and how much it might affect the UK stock market I don't know but when America sneezes the UK catches a cold.
Hi If you subscribe to Mello they release a video of the event a couple of days afterwards to watch at your leisure.
Paul - are the Mello talks recorded for viewing later please? Parts would be of interest to me but there is no way I can watch for 3 hours. I am too busy this week.
Yes - u get sent a link to rewatch it as many times u like - I think the next day
Sign up for John Authers newsletter is at:
https://www.bloomberg.com/acco...
For me it is a daily must read and he has, IMO, great music tips. I would never have listened to Taylor Swift until he suggested it last week!
"I would never have listened to Taylor Swift until he suggested it last week!"
Blimey Michael - what planet are you living on??
That has put me right off.
Innovaderma (LON:IDP) (not a holder) - Maybe of passing interest, Director Mark Ward could he be the same Mark Ward who has a large stake in Revolution Bars (LON:RBG)?
Here is Mark's biography from when he was appointed as an Innovaderma (LON:IDP) non-exec https://www.stockopedia.com/sh... I am fairly sure he is also the Revolution Bars (LON:RBG) shareholder. He built up and then sold a business, so he will have amassed significant capital. I don't hold Innovaderma (LON:IDP) currently and it seems something of a gamble until the board has settled its refinancing plans (the director loan and any equity raise). I wouldn't invest until those were known.
Tesla
I sold out completely last week, although when you were allowed to drive ( late summer/autumn) i did see more new (70 plate) Teslas than any other model, this may have been confirmation bias. If it wasn't just because they have sold a lot of cars cannot justify the ridiculous valuations. Unfortunately if Teslas sp does crash i think it will take a lot of others down with it.
Often covered here Quartix Holdings (LON:QTX) has released a trading statement today which I view positively:
"The Board is pleased to report that it expects revenue, profit and free cash flow to be in line with current market forecasts(1) and that the Company will have therefore recorded growth in both revenue and adjusted EBITDA during a year in which the markets for its services were severely disrupted by the coronavirus pandemic. Management's current estimates for revenue, adjusted EBITDA and free cash flow for the Period are GBP25.8m, GBP7.8m and GBP5.3m respectively. The Company's cash balance at year-end was GBP10.6m."
Very positive to see a company report growth in revenue and adj, EBITDA during this disruptive period so credit to the company. They've also reiterated their commitment to a dividend which is welcome but not essential at this time.
I've been a holder of Quartix Holdings (LON:QTX) for just over 6 years and showing a reasonable return of +126% on cost plus dividends. Not record breaking but a nice return. It's been a bumpy ride at a c. £200m market cap however management seem to keep delivering.
Prompted my Paul's mention that Boohoo (LON:BOO) might buy Topshop, this is well worth a read. The title of the article reflects the article's content; it suggests that Next (LON:NXT) are well placed to pick up Arcadia, perhaps in a joint venture.
"How Simon Wolfson is turning Next into a British mini-Amazon"
https://www.thetimes.co.uk/article/65dd7ac6-52aa-11eb-a81c-e93ccd0a2dea?shareToken=5f5f985686fe11eebddc62c3b8ec00ef
Hi shanklin,
I also read that 2 American companies are potentially interested in buying TopShop. Maybe BOO should bide its time, and just wait for it to go bust again under new owners in a couple of years' time? I think overseas investors often over-estimate their ability to turn around problem UK businesses. Look at those clowns who bought Homebase a few years ago. Or another set of clowns that bought Quindell.
Thanks for the article about Next, really interesting. I've been very keen on Next shares for several years now, but foolishly sold out too soon. Can't bring myself to buy back in now it's risen so much.
Regards, Paul.
Paul,
Thanks for your great updates. I never miss my daily dose of you and/or Jack. I know online retail is one of your favourite research topics. Two of my top 10 holdings in my SIPP are ASOS and BooHoo and I have been a long-term holder of both. This could be a big week for both. I also have some N Brown but keep getting my fingers burned on Quiz.
I know, Quiz (I hold) is very high risk compared with the others you mention. It's a special situation really. But having ditched the loss-making stores, and got the rest onto turnover rents, then it should be in a good position once restrictions are lifted (Easter seems to be the best guess at the moment). Plus its specialism in special occasionwear should see lots of pent-up demand. Plus remember that QUIZ has a highly developed online offering.
Quiz is still in the game, and the founders own c.50%, and are loaded (they got nearly £100m from part-selling in the IPO). Hence I doubt it's likely to be allowed to go bust, as a matter of pride. Cash burn has been quite modest since the pre-pack administration, and it has no debt.
Could be an interesting one, but definitely not for widows & orphans.
Best wishes, Paul.
Not company specific but interesting nevertheless for those of us who did not know.
The FCA will from February 2021 ask for all short positions of 0.1% (a change from 0.2%) to be declared. https://www.sharesoc.org/blog/...
cheers
Francis
Yes, but as someone has mentioned on this link, the FCA only publish shorts of 0.5% or above so even the 0.2%'s are not shown let alone the 0.1%'s unless they change their policy. Actual shorts are often far more than those published. There are also the shorts placed by punters on cfd's probably not taken into account
This is in the news today. It sounds extremely important to me, especially for any firms with assets in China. It's massively under-reported IMO but maybe I'm reading too much into it?
Sorry about the bold type, can't get rid of it since pasting in quote.
"China is pushing back against a flurry of US sanctions with new rules that protect its firms from "unjustified" foreign laws.
Changes announced over the weekend allow Chinese courts to punish companies that comply with such restrictions."
China brings in new law to fight Trump's sanctions - BBC News
Boohoo (LON:BOO) Results on Thursday Paul. All the best to you and Jack for 2021 and many thanks for your excellent share analysis and take on life.
Thanks andrew,
Yes I've got a lot riding on Boohoo (LON:BOO) (I hold) as by far my largest long position.
What I'm expecting/hoping for is - continued strong trading. Some additional costs from ESG supply chain stuff, also additional costs from freight & dispatches - a generic problem at the moment. Probably not much supply chain disruption due to clogged ports & sea freight, because a high-ish proportion still made in the UK.
International growth is also important, especially in the USA market.
Will be interesting to see what they say about more brand acquisitions - e.g. TopShop. I feel TopShop could be a good brand acquisition, although it's lost a lot of its sheen from the glory days of the 1990s.
I think the ESG impact has probably run its course now, as surely by now anyone wanting to sell because of that issue, would have done so? It's quite liquid after all. Once the issues are more publicly resolved, then of course we could have a wall of ESG buyers wanting to get back in again, bidding up the price hopefully! Also, by now, I imagine BOO shares would have attracted a fair bit of attention amongst US investors, who would likely regard the stock as very cheap, compared with the bonkers valuations put on growth companies across the pond.
Fingers crossed!
Regards, Paul.
Jd Sports Fashion (LON:JD.) Is remarkable with their announcement and trading momentum.
TBH, what I am struggling to understand is how many clothes/trainers do people need and how often replaced Same for home furnishings.
Bought Sofa in 2011 - still got it, when moving home, the sofa moved with us.
Last trainers I bought, 2018, although they probably need replacing now, but hopefully can stretch to last full 3 years. In
Admittedly, I am neither an athlete nor a fashionista and all our walls are painted white (why would you use any other color), but still.
Maybe I'm just getting old and choose to ignore what I spent/how I spent when younger
I struggle to make shoes or trainers last much more than a year. I used to get Doc Martins, but these don't last. Makes you wonder if the recognised brands are just using the same far east clothing/footwear sweatshops as unbranded.
So I can easily see why there's ongoing demand for cheap n cheerful clothing and shoes from Primark/Boohoo etc. Not exactly fitting the eco agenda, but maybe what the average purchaser likes.
I reckon trainers last about 6 months, but I am about 93kgs and they are designed for someone of 70kgs, I also have long term knee damage hence recommendation to always have good cushioning for pavement pounding (thank you to Michele for that lesson and the leave the work shoes under the desk every night that way you can have really nice leather sole ones and not worry about it raining outside!) and about 4 months in do a check and walk with the old trainers and new trainers straight afterwards to see if I can notice a difference, when I do, the old ones go in the Charity Bin at the local Co-op.
So good luck if you can make the last ages, I am just a high mileage non-standard model even if I class as vintage!
I bought some NBs about 3 years ago and use them quite a lot and they have lasted well, can't get the exact same ones but they are leather and were about £35.
These are the closest I could find: https://www.sportsshoes.com/product/new692684/new-balance-624v5-training-shoe-%286e-width%29-~-aw20/#sku-new692684
You know, I used to buy work shoes with leather soles that used to be all shiny. Best pair of work shoes I bought were from Tesco. No leather soles, but the soles lasted a lot longer than the fancy ones and had grip.
I was able to buy two pairs for half the price of normal.
Maybe my wardrobe was a contributor to my career didn't work out as well as I hoped!
Morning,
Excellent update from SAG this morning. Will you cover Paul?
Thanks.
Hi JohnDoe2378,
Thanks for flagging up the update from Science (LON:SAG) - I somehow missed that on my first trawl of the RNS. So yes, I'll take a look at this one next, it looks good.
Best wishes, paul.
"Why is that same mistake made over & over again?" Maybe I am over cynical, in my defence that is my increasing years Paul, but I suspect the answer is the only thought going through anyones mind at IPO is how much money can I make. All the buyer can often see is all the hype thrown at them by the masters of spin. I won't buy anything at IPO now. I even have a rule that I won't buy it until I have seen it trade for 1 year. If the owner of a business is so willing to sell they obviously feel it is near the top or noone else will lend them the money.
Hi Camtab,
Yes I agree with that, I normally avoid IPOs too, as so many of them seem to go wrong, often in the first couple of years.
I think brokers like to under-fund small cap IPOs, so that they have future fee income lined up from placings. Trouble is, that acts against the interests of the initial investors.
If investing in a new listing, I would want reassurance that it is fully funded, for the next 5 years, on a pessimistic but plausible downside scenario.
Regards, Paul.
When I was a young investor (50+years ago), my broker would phone me and suggest that he include me in a new issue. Invariably it would open with a good premium and I would usually take an early profit. Happy days!
tonydrew
Regarding IPOs - yes, it was a different world. It is probably only older investors that know the term 'stagging' (buying IPOs and selling immediately for a quick profit).
There was a rule then that for most "Offer for Sale" companies a certain proportion had to be offered to the general public. Most were priced to start at a good premium and so public demand was high resulting in scaling back and often a ballot to see who would get shares.
That rule was scrapped (I forget when) to exclude the hoi polloi under the excuse of reducing the cost of printing so many prospecti. Ironically the term 'Offer for Sale' was replaced by the American 'IPO' after the Public had been excluded!
Morning Paul, Not sure if Gamma Communications (LON:GAMA) is out of scope now for the SCVR. If not, I would love you to take a look and comment on what seems like a great trading update.
Morning tomhurst1,
Gamma Communications (LON:GAMA) is £1.5bn market cap now, and in a sector that I don't really understand or have any insights in, so i'll pass on that one. Sorry about that.
Regards, Paul.
Apologies for the inadvertent error, my earlier post, now corrected should refer to £SHI.
jonno,
You have an hour from posting a comment, to be able to edit the original, which is better than putting up an apology/correction additional comment.
Regards, Paul.
Cheers Paul
Have just twigged the edit option. Look forward to hearing from Jack on tonight's Mello session, not sure whether you are participating.
Best wishes
Early days, but trading at Sig (LON:SHI) (SIG) appears to have turned a corner. Successful turnarounds take time and patience, hopefully this is the start. Like for like revenues up 4% in the fourth quarter compared to the prior year. Organic revenue growth expected in 2021 including market share gains, subject to the caveat of no further material disruption due to the pandemic.
I hold but need but need to temper optimism with realism.
Constructive views and thoughts welcome, positive and negative.
Hi Jonno, I take it you meant Sig (LON:SHI) as opposed to Signature Aviation (LON:SIG) , fortunately the confusion is about to end as Signature Aviation (LON:SIG) will be taken over before long!
Peel Hunt have SIg trading on circa 16x PE for 2023 with a margin assumption of 2% vs the 20yr average of 4.6%.
They haven't upgraded numbers on the back of today preferring to be cautious though clearly the company expecting to grow sales. Post the raise the balance sheet is clearly much better.
On a 5% margin I'd expect it to trade at circa 0.5x sales historically. On sales of £2bn you'd be talking a share price closer to 90p.
The pe outfit who have bought in at 25p have also just acquired the Wolseley UK business in the divestment from Ferguson.
I suspect the downside is limited because of the corporate angle with potentially decent optionally around better trading.
I do hold
I’m very new to this type of investing but have recently bought some SIG shares. I worked for the company in the U.K. Sheffield Insulation’s division 14 years ago and they were very dominant in the market. They had a lot of clout with their suppliers and always bought better than the competition.
I couldn’t believe how low the share price had fallen. It seems since I left they’ve lost their way a bit. However they are still the dominant player in the insulation market despite this. If they turn things round I feel there is plenty of upside.
Given the huge upturn that I feel is not that far away in the construction market and the green agenda I think there’s every chance they’ll do very well over the next 5 to 6 years.
I’ve invested 100% in buy to let property up until now (I don’t want any more tenants) and my reading of the property cycle indicates strongly that shares in the construction market sector should do very well just like they did in the last housing boom from 2002 to 2007. I’m hoping 2022 to2027 will see a similar excellent performance if this current cycle plays out like the last one. So far all indications are that it is.
“That's it, that's all we need! Why can't all companies do this? It's simple, and helps everyone understand the situation quickly & easily. “
I would have thought it would not be beyond the abilities to make trading updates be obliged to have a standard form rather being PR puff pieces. So a TU would start with figures we want in a standardised format and the standard ahead/comfortably ahead/materially ahead/below etc and then go on to the PR puff if they want to.
Regards
Michael.
It would be nice if they could at least check what they post for errors and use of English in the normal way.
Take this in the update from Directa Plus (LON:DCTA)
“ We have been requested to raise to 2000 metres per month the production capacity in 2021.”
Confusing metres and metric tonnes is abysmal. I’m not a particular stickler for grammar etc. (What’s considered acceptable grammar is changing all the time anyway). But you really do get the impression that this was written very poorly and no one bothered to check it before releasing it.
Innovaderma (LON:IDP) profit warning.
We expect revenue to be c.£4.1m (H1 19: £5.1m). A decline in UK sales (H1 20: £2.9m, down c.32%), was partially offset by encouraging growth in our key international markets (H1 20: US £0.4m, up c.17%; and Australia £0.8m, up c.52%) led by Skinny Tan. Both Retail as well as Direct-to-Consumer ("DTC") sales have been impacted by a reduction in beauty category consumption, particularly in the tanning category, due to Covid-19. DTC remains our priority channel and represents c.62% of the Company's sales (H1 19: 60%). We expect the tanning category consumption to significantly improve as Covid-19 restrictions ease, and moreover as we enter the peak tanning season from April to June.
And it looks like they will need some money.
at the prices it was trading at earlier this morning, I'd say this was overly-discounted.
Using AJBell (for my sins), I was unable to purchase any at all (limit or quote) and missed a predictable 15-20% bounce, whilst IG was happily offering me quotes at the desired quantity.
I did hold and got out just now.
And so missed the low lows. Not due to judgement, just being at work.
And will possibly miss the recovery as well.
There is a business in there (once things are back to normal) but not sure things will be normal until '22 ... and so follow the 'sell on profit warning meme'.
yes, entirely agree. I was expecting ~15%-20% down and also agree with Paul's comment re placing risk - similarly sold out today.
Wish I'd been able to get some of the shares when they were on offer at <40p though, would have been a nice 25% uplift for not much work and might have balanced the otherwise loss ;)
A few random thoughts about Innovaderma (LON:IDP)
I hold held - asleep at the wheel somewhat!
I don't think that there is anything too surprising in today's announcement - some people might want to top up their fake tan for Zoom , but not so many as do so for real life interactions.
That though makes it doubly naïve of me to have continued to hold - bad news is never "already in the price".
Looking back the sharp recovery in the share-price in early May, with no real justification, so have been a good opportunity to exit and watch from the side-lines, but hey ho.
The early departure of Joe Bayer is a bit of surprise given that he was going in three weeks time anyway. There's probably a story there!
They should be around about the low point of their cash cycle, so if the director loan can tide them over then it doesn't look too critical (assuming the coming season sees some return to normalcy) but the CEO is clearly signalling some form of refinancing. I'm not convinced that it would have to be equity however.
They will be reviewing and writing down their intangibles, which is likely to be "substantial".
This I imagine will be their customer list - the fact they capitalised customer acquisition costs was a bit controversial, but I think justifiable given their ability to generate repeat business. However, I think they will conclude that after a break they will need to spend to re-acquire customers.
Personally, I have sold out now, I think those write downs will be seen as a second (or third?) profit warning and whilst I don’t think dilution is a given, if it comes it could be big.
Back on the watchlist.
agree,
for me the director loan (why not a covid-business loan?), booting out of the chairman and likely placing were more than I was expecting to see, so have sold.
Hopefully some better news for them in ~6 months with the H2 figures also.
I get a sense the new ceo may be flushing bad news out of the way perhaps.
I was surprised that the hair removal product hadn't done better - I don't quite get why that is more of a physical retail product - and even so, I'd thought places such as Superdrug would have remained open during the various lockdowns so I'm surprised by the poor trading really.
I sent a complaint email to AJ Bell twice last year because what you describe happened to me on two occasions. They have offered me a £250 cheque as a reimbursement for not pursuing my complaint any further. Possibly they are worried about a class action coming their way.
they offered me no transaction fees for a month in a similar 'retention effort' I suspect based on a similar complaint I raised when the first vaccine was announced, its fine up to a point (4.95 better off on each purchase/sale and when properly enthused I can do a few a day so maybe not quite £250 but not too bad).
Of course though, if their platform won't actually let me trade, I can't milk their offer properly!
hmm I wonder if they perhaps thought of that.... !
Over the weekend I placed my vegetable seed order for spring planting. D T Brown, seed suppliers, had the following warning on their website. “We regret that we can no longer supply any products, including seed and seed potatoes, to Northern Ireland and Europe. This is due to the imposition of non-tariff, phytosanitary checks and procedures now required by law as a result of Brexit.”
How many other small companies have imposed such restrictions? Partly explains why there are no queues at the ports.
Another issue is the change in regulations whereby HMRC now requires retailers based abroad to collect and remit U.K. VAT on all direct shipments to U.K. customers.
For example a number of bicycle parts suppliers have stopped direct internet sales from Europe to the U.K. Parts are still available from U.K. distributors.
I noticed that AliExpress are now charging taxes on U.K. orders.
I believe a company in the EU can get around the paperwork by selling through a third party platform registered for UK vat. They place their offer on the website at the price they want and the online platform accounts for the vat to HMRC. Of course, they will have to pay commission on the sale. That is why UK distributors will still be selling their products. If VAT were not charged it would put UK manufacturers at a disadvantage and is something they have wanted. Larger EU businesses will be able to deal with it and it is probably the smaller ones that are having to deal with something they are not used to that see it as a problem. They need to take advice as to how to proceed but there seems little reason why vat should not be charged.
The Europeans were all charging VAT before but now they have to register and account separately for UK VAT so they have to decide if it's worth their while.
Hi Stevenlondon3,
Yes, I've seen similar announcements from lots of retailers & eCommerce businesses (in trade press articles, like drapers record), saying that they won't be shipping goods to N.Ireland or Europe for the time being, until restrictions are sorted out.
Also, press articles recently saying the French ports are not happy with poor paperwork from UK exporters, and are about to clamp down.
So I imagine we're likely to hear continued news items about teething problems with the new arrangements. Hardly surprising, as it was all agreed at the last minute. My feeling was that Brexit would probably cause 3-6 months of chaos, then everything likely to settle down. Pleasantly surprised so far, but let's not jump the gun.
Also as JohnEustace says below, some EU companies are now stopping shipments to the UK for low value items, as not worth the hassle. I suppose if they want to trade in the UK, then they might open UK subsidiaries. That's how UK companies are getting round restrictions - many had already set up subsidiaries within the EU.
Regards, Paul.
So I imagine we're likely to hear continued news items about teething problems with the new arrangements. Hardly surprising, as it was all agreed at the last minute. My feeling was that Brexit would probably cause 3-6 months of chaos, then everything likely to settle down.
Almost certainly true. The underlying problem is that many SMEs who are already struggling due to CV-19 restrictions are unlikely to survive 3-6 months. They didn't have the resources to prepare for all Brexit eventualities and are now trying to figure out how to deal with the new bureaucracy and non-tariff barriers such as the VAT issue and rule of origin regulations.
That's unlikely to affect us directly as investors as most of those businesses aren't quoted. If it leads to increased unemployment it will have knock on impacts on domestic businesses though. The Federation of Small Businesses index study is out and it's pretty grim:
https://www.fsb.org.uk/resourc...
Unsurprisingly confidence is on the floor.
As with all such surveys it needs to be treated with an element of caution, the FSB is quite rightly lobbying the government for support for its members. However, given that SMEs employ nearly 17 million people it is a bit worrying for anyone counting on a UK economic recovery this year.
timarr
Re low value imports from Europe (or elsewhere) and including fast fashion, I think an under-priced risk post Brexit and medium term is the introduction govt taxation per delivery.
A 50p/delivery tax would raise a lot of money, hardly affect higher value buys but decimate purchases like the 1 bag of screws I am (hypocritically) expecting this morning
This would be easy to collect (even from Amazon) , help the High Street/local shops without stopping a move online and be pro-environmental by discouraging cheap one-use items. In some ways it simply taxes an otherwise unrecorded externality in an economist's terms.
Bad news on taxation has to come the medium term from somewhere; this allows for a little greenwash cover and was not ruled out in the Tory manifesto !!
Morgan Stanley, when are they going to let up on rns’s. £boo
Not sure why thumbs down. I agree but maybe they are obliged to?
Best not to comment on thumbs downs at all, as we then get a whole load more pointless posts about the thumbs down, which I know I'm adding to now, so will shut up!! ;-)
noted. Wish they weren’t there!
I don't think Edinburgh Investor is complaining about £BOO so doesn't really merit the two down ticks shown at present. He is reiterating what Paul said the other week where RNS's have to be issued showing small changes in holdings when often those holdings go up and down like a yo-yo. Year's ago I decided to monitor changes in institutional holdings and what a waste of time that was with increases and reductions from the same holders on a weekly basis. I think I gave up when an RNS referred to a transaction on, say, 3rd February and a few days later there was an RNS referring to an earlier transaction on 1st February in the other direction.
I probably should have added some context to be fair, I was going to ask Paul if he submits an invoice for time wasted he could do it on all our behalf.
I agree, those RNSs from Morgan Stanley re Boohoo (LON:BOO) (I hold) every day are such a nuisance. There must be some technical reason why they have to be issued. I have to check them every day, just to make sure it's not something more important. Grrrrrr!
P.
Boohoo (LON:BOO) FCA rules dictate a holder needs to file each time they cross a whole percentage from 3% onwards but also if the composition of the holding changes ie they switch some of their holding from direct shares to a financial instrument or vice versa - both of which are happening in the case of Morgan Stanley
Alb
My morning smallcap tweet: Full speed ahead with 15 summaries
Sourcebio International (LON:SBI) Directa Plus (LON:DCTA) Studio Retail (LON:STU) SIG (LON:SHI) Yourgene Health (LON:YGEN) Octagonal (LON:OCT) Brave Bison (LON:BBSN) Diaceutics (LON:DXRX) Science (LON:SAG) Deepverge (LON:DVRG) Stobart (LON:STOB) Churchill China (LON:CHH), Quartix Holdings (LON:QTX), Rotala (LON:ROL), Dekel Agri-Vision (LON:DKL)
SourceBio (SBI) one year supply agreement with a leading UK high street retail and pharmacy group to provide laboratory-based testing services to support the roll-out of COVID-19 testing across UK stores. [SP=220 Cap=163m]
Directa Plus (DCTA) guides FY(Dec) rev €6.5m, above mkt expectations (not stated). Cites better than expected sales of G+ enhanced face masks and growth at Setcar. [SP=79.55 Cap=49m]
Studio Retail (STU) Q3 product sales up 32% and gross margin up 440bps. Findel Education rev up 15% but will be hit be closures. Adj pretax in first 39 weeks up £16m cf £6m rise in H1. [SP=283.7 Cap=246m]
SIG (SHI) guides FY(Dec) op loss £57-61m, at the better end of the range of previous expectations. LFL rev down 13%. H2 2%. Outlook "Providing there is no material disruption to either our business or end markets as a result of the pandemic, the Board expects the near term benefits of the actions taken in 2020 to deliver organic revenue growth in 2021, including market share gains. The benefits of this will become increasingly evident as the year progresses and should enable us to return to underlying operating profitability during the second half." [SP=30.72 Cap=363m]
Yourgene Health (YGEN) lab testing shows that the Clarigene SARS-CoV-2 assay is not impacted by any currently known mutations. [SP=14 Cap=102m]
Octagonal (OCT) to avoid a protracted dispute with the SEC re complaint co will stop conduct cited by the SEC. GIS will no longer carry accounts for, or provide financing services to US persons. Co " remains optimistic of remaining operationally profitable whilst GIS restores lost earnings." Also if co de-lists "it remains the intent of the board to offer to shareholders a scheme to buy back shares...at a fair market rate." Remains suspended. [SP=0.84 Cap=6m]
Brave Bison (BBSN) guides FY(Dec) rev £12.7m, gross profit at least £3.9m and adj EBITDA at least £0.1m after H2 was ahead of mgmt expectations. [SP=1.27 Cap=8m]
Diaceutics (DXRX) guides FY(Dec) rev £12.6m and adj EBITDA £0.5m, ahead of revised market expectations. [SP=142 Cap=119m]
Science Group (SAG) guides FY(Dec) op profit above previously upgraded expectations of £10m. CFO resigns. She is thanked. [SP=299 Cap=123m]
Deepverge (DVRG) confirms maiden EBITDA profitable Q and guides FY(Dec) rev up 300% to £4.4m. Guides £10m in FY21. [SP=34 Cap=57m]
Stobart Group (STOB) will change name to Esken after a vote. [SP=30.65 Cap=192m]
Churchill China (CHH) vague FY trading. H2 profit. Expects better FY21 but too early to declare a dividend. [SP=1350 Cap=142m]
In line: Quartix Holdings (LON:QTX) Rotala (LON:ROL) Dekel Agri-Vision (LON:DKL)
I had thought Octagonal (LON:OCT) would be my worst investment of 2020 but the positive update today gives some hope. BBs are full of vitriol for the boss and majority shareholder. I was lucky to escape from Wirecard before the meltdown but can't win them all I guess.