Small Cap Value Report (Mon 11 Sept 2023) - RTN, SPO, VTY, INSE, EXR, WAND, MPE

Good morning from Paul & Graham!
We're still having remarkably hot weather in the UK. As Father Ted once said during a September heatwave, "If it stays this warm throughout the whole of the winter, we won't need to turn on the heating at all!" (shortly after he had blown the entire year's heating allowance betting on the wrong sheep). Sometimes my portfolio feels like I've bet on the wrong sheep too, so remarkable parallels there.
Mello Monday 5pm today - is this evening, great to see these interesting investor shows back after a summer break. I’m looking forward to hearing highly experienced fund manager Rosemary Banyard interviewed, she talks a lot of sense, and kicks off the show at 17:00. Also the BASH session is always good. Do support these events, as the danger is in a bear market, investor apathy might mean they wither away.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Scraping the barrel today, I'm afraid -
Summaries
Restaurant (LON:RTN) - 47.5p (pre market) £363m - Proposed sale of leisure business - Paul - AMBER/RED
As usual, RTN tries to put a positive spin on a not very good situation - it's having to pay another group £7.5m to take away what's left of its loss-making Chiquito's and Frankie & Benny's restaurant chains. Some lease liabilities remain with RTN though. I reiterate my concerns below about RTN's weak trading, and dangerously stretched balance sheet.
Sportech (LON:SPO) - down 68% to 30.7p (£3m) - Proposed delisting - Graham - AMBER
This small betting company proposes to exit stage left. I’m neutral as the current derisory market cap seems too low, but how many of us want to own shares in a private company? I take the opportunity to remind everyone (including myself) to be careful with delisting risk.
Not a small cap but ….
Vistry (LON:VTY) (mid cap housebuilder) caught my eye, being up 14% to 910p today (£3.2bn). It’s now up 31% since the recent low just 3 weeks ago. H1 results are “robust” (profit up vs LY H1), and in line with expectations. It reiterates FY 12/2023 profit guidance. Note that broker consensus forecasts fell about 40% in late 2022, but have been flat, or slightly up, throughout 2023 to date - surprisingly resilient in a very tough sector. It seems to have a more resilient business model, with public/private developments, with “good demand” for rental affordable housing from local authorities and others. Cost synergies from the acquisition on Countryside. Strong forward order book. Superb balance sheet with £2.0bn NTAV, including huge inventories number of £3.2bn.
Paul’s opinion - I don’t know this company very well, but want to flag it to you as something to possibly research more, if you want upside/recovery from the housebuilding sector, but with seemingly more downside protection than conventional companies in this space, due to its mixed business model (public & private). [no section below]
Inspired (LON:INSE) - down 6% to 85.25p (£86m) - Results for H1 - Graham - RED
These shares are lower despite the company confirming full-year guidance, and the broker increasing estimates for 2024 and 2025. I’m a sceptic on this one due to its balance sheet, debt, acquisition strategy and the presentation of its barely profitable results.
ENGAGE XR Holdings (LON:EXR) - up 14% to 3.24p (£17m) - Interim Results - Graham - RED
This “Metaverse/Spatial computing technology company” announces a pre-tax loss in line with expectations of €2.2m over the six months to June 2023. Revenues were about the same size as the loss (€2.1m, up 18% year-on-year). The company says revenue momentum is picking up, with €1m generated over July and August.
Thanks to a fundraise, the company finished H1 with over €9m of cash. Cash burn in H1 was around €3m so it should have some cash runway - over a year, hopefully? Maybe 18-24 months? Best of luck to investors in this one but I have to give it the thumbs down based on the statistical improbability of it working out. The StockRank is 11 (including a ValueRank of 2).
WANdisco (LON:WAND) - down 6% to 62p (£73m) - Interim Results - Paul - RED
I won’t go over all the detail again, as we’ve wasted far too much time on this dreadful company in the last year. The short version is that the exponential rise in sales bookings, which took the market cap up to nearly £1bn, was all a fraud. Despite this, the rich & successful financial backers refinanced it at 50p, and shares have come back from suspension.
Today we have more dreadful figures from WANdisco (LON:WAND) as expected. My main concern is that the forecast cash is said to be down to $16m by Dec 2023. It raised $30m recently, so is tearing through that fresh cash raise pretty fast (although c.$7m one-off costs re survival/restructuring/fraud).
Looks utterly grim, for sure, as the published accounts always have done. I foolishly believed their too-good-to-be-true bookings/pipeline RNSs, which of course then turned out to be completely fictitious, not something that anyone predicted I don't think.
Paul’s opinion - I can’t see any merit in this share for now. Given the rate of cash burn, it has to be RED.
M P Evans (LON:MPE) - down c.3% to 740p (£399m) - Interim Results - Paul - AMBER/GREEN
Fancy owning part of an Indonesian palm oil producer? Then this is your share! A long track record of generous divis, strong asset backing, and reasonable PER have caught my interest here. H1 profits are well down, but it sounds like H2 is improving, and Cavendish leaves forecasts unchanged. Could be worth a closer look, but obvious overseas risk, and volatility of price for its palm oil production.
Paul’s Section:
Restaurant (LON:RTN)
47.5p (pre market) £363m - Proposed sale of leisure business - Paul - AMBER/RED
I reviewed the interim results here last week, and was distinctly unimpressed with the wafer thin profit margin, and the awful, overly-indebted balance sheet, also with onerous lease liabilities.
Press reports over the weekend suggested a deal was imminent for the disposal of its slowest-growing leisure division (Chiquito’s, and Frankie & Benny’s restaurants). A “dowry” was mentioned in press articles, suggesting that RTN would actually be paying the buyer to take away its problem leisure division.
Today it says -
- Agreement signed to sell 75 trading sites to Big Table Group (private equity backed, operator of Bella Italia, Las Iguanas, and Banana Tree) for £1.
- RTN will pay £7.5m to Big Table Group, to get rid of this loss-making division.
- Expected to complete soon, in early Q4 2023.
- Improves leverage - not really, because it’s only getting rid of lease liabilities, not actual debt.
I don’t like the sound of this bit (equity placing on the cards, possibly?) -
…continuing to actively explore its strategic options to further accelerate margin accretion and deleveraging.
I don’t like this bit either, which suggests that there might be some potential liabilities remaining for RTN (TRG) -
Sites that have been previously closed as part of the Leisure businesses estate rationalisation plan will remain the responsibility of TRG… and we expect to exit the majority of the lease obligations of the recently closed sites by the end of FY24. We would therefore expect the remaining liability and expected cash outflow from closed sites (most of which are currently sub-let) to be no more than £1m to £2m a year from FY25 onwards.
Paul’s opinion - it’s striking how RTN has got rid of most of its original businesses. Some investors thought the acquisition of Wagamama a few years ago was a life raft for management, tacitly admitting that their older brands were withering away. They were right!
It’s another demonstration of how restaurant chains come in and out of fashion, and that they have to continuously adapt to stay relevant. Also, there's clearly still over-capacity in the restaurant sector. Good reasons why I’m avoiding this sector altogether these days - it’s so difficult to make any profit at all, after the big hikes in wages, energy, and raw materials. It could take years to rebuild margins, if that's even possible.
Why get involved here, when it’s also laden with excessive debt, which could further destroy what’s left of shareholder value?
Shareholders must be hoping that the consumer squeeze ends, and households increase their spending on eating out. And that costs reduce. If those things don’t happen, then it’s difficult to see RTN making any progress, and with little to no prospects of any meaningful divis, why would anyone want to invest here?
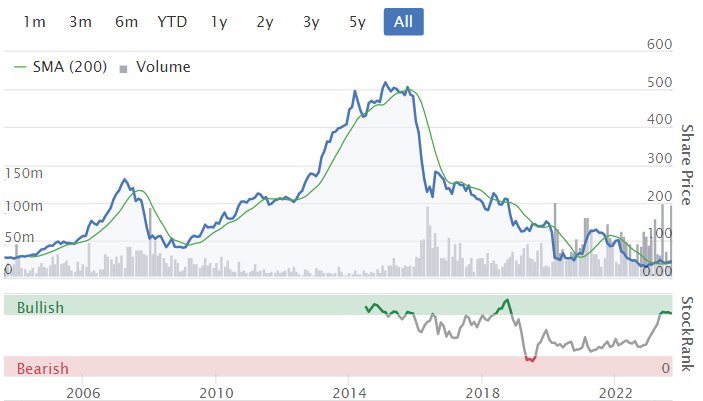
A reminder below of the huge shareholder value destruction long-term at RTN. It's now hoping that Wagamama will succeed, where the other brands failed -
M P Evans (LON:MPE)
Down c.3% to 740p (£399m) - Interim Results - Paul - AMBER/GREEN
A producer of sustainable palm oil in Indonesia. Not a company I follow or understand. Graham reviewed it here in Dec 2022, sounding quite positive.
H1 figures today look poor - operating profit is 62% down to $23.4m.
Interim divi maintained at 12.5p is a good sign. Note that the FY 12/2023 forecast yield is a healthy 5.6%, and the history of paying reliable and growing divis is excellent, over many years.
Post period end it agreed a substantial $60m purchase of 8,350 hectares of planted land.
Outlook comments are vague, with no mention of performance vs expectations. But it does say that new land purchases
…along with increasing cropping levels, put the Group in a strong position to deliver a productive and profitable 2023 and bodes well for its longer-term prosperity."
Also, production in H2 to date (July & Aug) is up 35% on H1’s rate, which sounds good.
Balance sheet - looks good. Large NTAV of $467m, means it effectively owns outright the land & palm trees on them and all its equipment. Cash offsets borrowings.
Paul’s opinion - not a share I’m familiar with, but the lowish PER, strong asset backing, and generous/reliable divis (plus small buybacks) impress me. Cavendish has left forecasts unchanged, so see their note for more info. Could be worth a closer look. I’ll go with AMBER/GREEN - modestly favourable.
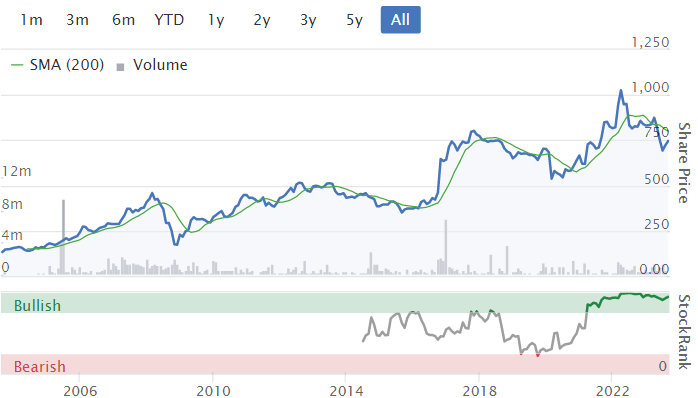
Very good long-term share price performance, especially if you add on all the generous divis on top of the share price -
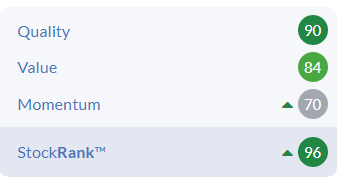
Stockopedia's computers put a cherry on top, with a high StockRank -
Graham’s Section:
Sportech (LON:SPO)
Share price: 30.7p (-68%)
Market cap: £3m
We covered this one very rarely - when I looked at it in April, it was the first mention of the stock in five years.
This morning, we are reminded why we normally use a £10m market cap cut-off. This one had a £9m market cap last night. It is now just £3m.
It has signalled an intention to delist, pending shareholder approval (a vote in favour with 75% support is required).
Sportech has at least distributed vast amounts of cash to shareholders over recent years - £121m since 2017.
The remaining businesses are of a small size: revenues of £13.5m in H1 (according to the interim results published today), with adjusted EBITDA of less than £1m.
I note the presence of Harwood Capital: they are the third largest shareholder with 18%, recently (30th August) announcing an increase from 17%. This may just be a coincidence, but we are used to the pattern of seeing Harwood-related entities delisting.
Are Sportech’s existing business worth more than £3m? The end-of-August cash balance is slightly more than that, and it owns betting licences and venues in Connecticut. So I would say that the answer is perhaps yes - for anyone who is happy to own an unlisted company.
At a sub-£10m market cap, with limited liquidity, and with no plans to raise funds, I tend to agree that a stock market listing is uneconomical for companies with this profile.
It’s another good reminder to check whether any companies you own are at risk of delisting in a manner that might be unfavourable to you.
Remaining Sportech shareholders will be feeling sore this morning with the share price down nearly 70% on this announcement. Perhaps we don’t talk about delisting risk enough - it’s one of the most serious and most common dangers of micro-cap investing.
Inspired (LON:INSE)
Share price: 85.25p (-6%)
Market cap: £86m
Inspired (AIM: INSE), a leading technology enabled service provider supporting businesses in their drive to reduce energy consumption, deliver net-zero, control energy costs and manage their response to climate change, announces its consolidated, unaudited half-year results for the six-months ended 30 June 2023.
I fully agree with Paul that energy consultants aren’t the most attractive of investment sectors, and I’d be inclined to avoid them entirely.
Let’s see if there is anything in these H1 results that might spark some interest:
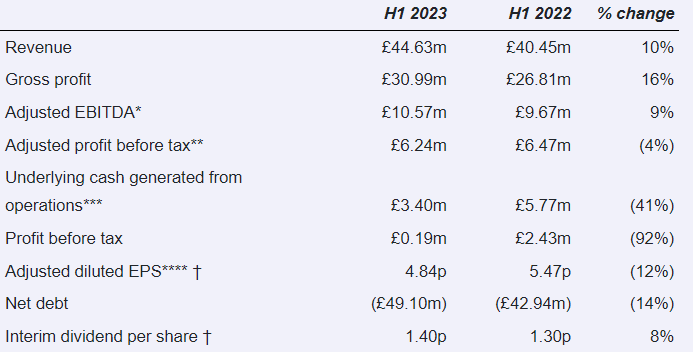
Note that actual PBT is close to zero, despite revenues of £45m and “adjusted EBITDA” of £10.6m.
Net debt of £49m is significant relative to e.g. the company’s market cap and its profitability.
As flagged by Paul in January, there are significant liabilities relating to acquisitions. In H1, £8.6m was paid in earnouts for prior acquisitions.
Balance sheet - this has negative tangible value and looks quite ugly to me.
Tangible value minus £32 million.
Cash £8.4m
Contingent consideration £11.3m in current liabilities (i.e. due within a year).
Bank borrowings £57.5m
£46m of value is tied up in receivables - much of it not invoiced/due yet. The company says that some of this has unwound since H2 began but regardless, working capital management will be crucial when dealing with a number of this size.
Liquidity - only £2.4m of the company’s RCF was undrawn at the end of H1. Normally that would imply almost no headroom, but there was also a £25m “accordion” facility (i.e. it may have been possible to borrow more, if the lenders agreed).
Outlook - “The over-arching business necessity for energy efficiency initiatives should support continued strong demand for the value added by Optimisation Services in H2. ESG Services is expected to maintain its strong momentum in H2..”
The Board is “confident in delivering market consensus for the full year 2023.”
Graham’s view
I was thinking of sticking with a neutral stance on this, due to the valuation:
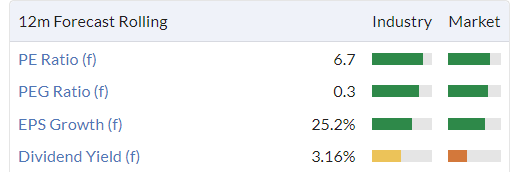
However, a neutral stance wouldn’t convey what I really feel - which is that this one is to be avoided.
It promotes a nonsense adjusted EBITDA metric that excludes many important costs, including large spending on internally-generated intangible assets.
Balance sheet is hollowed out by acquisitions, leaving negative tangible value for shareholders.
Net debt is significant and the company is carrying large acquisition-related liabilities, too.
Operates in a highly competitive sector and currently earning very little or zero real profits.
A history of shareholder dilution with a rising share count.

So for me personally, this is a bargepole situation.
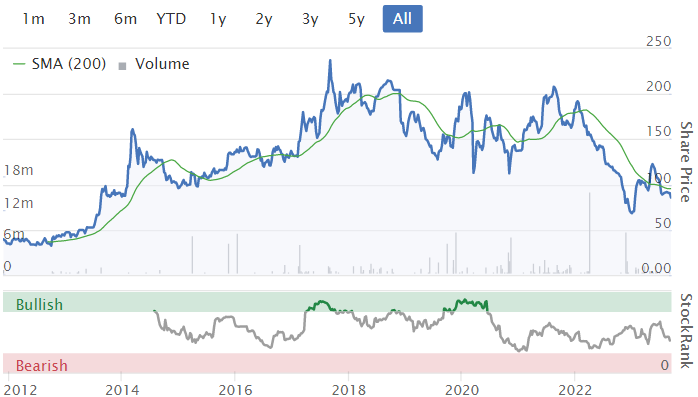
The shares are lower today despite confirming its 2023 estimates, and the broker increasing estimates for 2024 and 2025 - perhaps the market is starting to get worried about this one?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

95 comments
Not had a day like this in a long time, long may they continue. Things can certainly change quickly. Certainly starting to feel better to me, fingers crossed and all that.
Eneraqua Technologies (LON:ETP) +21%
LungLife AI (LON:LLAI) +23%
Tesla (NSQ:TSLA) +8%
Just need hVIVO (LON:HVO) to come out with some stonking results tomorrow and all will be peachy
M P Evans (LON:MPE).
I have held for a couple of years and am slowly understanding a bit more about both the company and the industry. A long way from becoming any sort of expert however.
MPE is now helping by regularly doing a webinar following results announcements. All recent progress seems very sensible but unlikely to shoot the lights out. I think political risk (Indonesia and/or Malaysia) likely to be a thing of the past barring something unexpected in world markets. The company itself has been going for 150 years and the directors seem to operate in a slightly old fashioned paternalistic fashion providing medical, schooling and I believe some accommodation for their plantation workers. Should assist with ongoing labour and govt relations.
A few months ago, the company held a 150 year anniversary reception and lunch in Mansion House no less for shareholders amongst others. I managed to get a ticket. Met some long term shareholders who spoke well of the business and confirmed many of my impressions. Speeches after lunch (lengthy yawn) emphasised management links to past generations.
Both chart and Stocko numbers suggest that I should hang on, so I will.
Mark
I bought MPE back in May 2022 at a price if 925p, mainly due to the high StockRank. That turned out to be a bad idea, as the price is 726p. I still hold (although that's probably far from great advice). If I had thought about it more, I would have realised that the good momentum was due to palm oil going stratospheric, like many commodities.
The palm oil prices have come down, along with the share price. My lesson is: if it's a company based on commodities, don't buy when the price of the commodities has shot up.
From their report, their average price of (palm) oil was US$986/tonne. This is 8% higher than the 5-year average (which includes the big spike up in prices, of course) and 20% higher than the 10-year average.
In their last meeting, they said that they didn't expect the price of oil to go down, but I think that might have been a little bit of wishful thinking on their part.
We're in an inflationary environment at the moment, so commodities should be a good hedge. Finger in the air time, that means that I wouldn't expect prices to drop by as much as 20%, although they may drop by more that the 5-year average (8%). It's just a guess, of course.
Free cashflow over the last 6 years has been about 22p, making the FCF yield about 3%. Not a bargain. So if I was looking at it dispassionately today, I'd stay on the sidelines and wait for a better opportunity to invest. The company has been expanding, of course, so it's possible that the situation could improve. Or not.
I read somewhere that the demand for palm oil grows at about 7% annually, so that's worth bearing in mind.
Management seem competent enough. They are building mills and seem to be investing wisely. They are presenting online at https://www.investormeetcompan... tomorrow at noon, in case anyone is interested.
It is a very uncomplicated and straightforward business, M P Evans (LON:MPE) .
Key risks are of course government, commodity pricing, and more recently - climate change.
What might be intriguing here is that with Olive Oil output way down in Med countries (and likely to keep declining due to heat wave and Xylella) - other oils will benefit in terms of demand. Already seeing a trading down from olive oils to other vegetable oils - which in turn, will drive those prices up, and then cause trade down to palm oil?
On top of that, governments around the world are now more proactively restricting new razing of forests for palm oil plantations. So existing land becomes more valuable, and thus prices will increase given lack of new capacity coming online.
However, the migration away from palm oils to other oils is always a macro threat too.
I don't know enough about this area, but the shares do look tempting at the current value!
The board addressed some interesting questions today.
They seemed quite comfortable with the government and don't expect Indonesia to do a crazy.
They also state that they've seen no significant changes in rainfall, so are not concerned about climate change fears.
The also seemed fairly happy about current oil prices. MPE is earning good ROCE at the moment, and they are not expecting serious declines.
West Africa is entering the palm oil market, but the board wasn't concerned.
You can never predict the future of course, but things seem to be doing OK.
DX (Group) (LON:DX.) potential offer just announced- 48.5p
Looks a bit stingy given past issues appear to be behind them and the recent news re Tuffnells? (more so given that it doesnt exactly trade on a premium rating)
Hi Wolfy
Just seen, so that makes the longer post to Planetx earlier a kind of why am I not running concentrated portfolio as this would have made a very nice suprise.
So my second take over, a lot better terms for DX (Group) (LON:DX.) than Ediston Property Investment (LON:EPIC) but again could it get more.
Just looked, and you can sell at 42.875 and buy at 43.15 so there is still a 10% being left by the market. Debated just take the money or see what tomorrow brings when a high riser is picked up by the market, or double down and see if I can make a bit more tomorrow?
No right or wrong answer, did nothing as it was easier!
I think the fact that whilst DX (Group) (LON:DX.) were delisted earlier in the year whilst the legal review was going on the price is more than tripled. So maybe there is take the gain now rather than wait for a few more years for a what if maybe, there was always a question of where they fit in the whole UK delivery pecking order and at what point growth becomes harder...
Tommy
I hold DX (Group) (LON:DX.) prospective bid looks ok but nothing special. The fact that they’ve tried multiple times at lower prices indicates to me that a firm bid is quite likely now. As the cat is out of the bag in terms of price acceptability there is also a potential for others to get involved. It’s all cash too so that helps.
I’m happy to hold here. If a bid isn’t forthcoming I can see them at this level in the next few months anyway given momentum but I guess I can recycle the money if they are taken out around 50p level given some of the Uk bargains on offer right now.
Re. M P Evans (LON:MPE) - for a step back into colonial history, join the update on Investor Meets Company tomorrow at 12. Being more serious for a moment, H1 is always weaker than H2 due to crop seasonality. Profits down because the price spike from Ukraine war has passed - could there be another though in future? This is a product used in almost all ready meals so there is a good moat given you can't grow these palms everywhere. Main threats are political - local government caps local prices and adds new taxes on a whim - plus the envinronmental lobby worried about the rainforest - M P Evans (LON:MPE) do their best to mitigate by promoting their ethical grown credentials. I hold and plan to continue to hold.
Monthly Income Challenges...
I have caught up on my reading, Ediston Property Investment (LON:EPIC) have agreed a value ~72p share subject to vote on 26 September.
So a winner, though not retirement...
The price has dropped today is the market thinking this will fall through? Or those hoping for a bidding war just moving on?
There is a 0.005p dividend going ex on 14 September which I am assuming will be honored as no mention in the announcement?
I need to find another plan for the income diversity, or more to the Skipton Building Society transfers?
No inspiration today
Tommy
Tommy. Re Ediston Property Investment (LON:EPIC)
It would be a good idea to read the series of announcements from Ediston Property Investment (LON:EPIC) over the last few months so that you are not guessing about what is happening. A “bidding war” is very unlikely and anyway it’s not a bid. It’s disposal of their entire Property Portfolio as explained here:-
https://www.stockopedia.com/sh...
Does anyone have an opinion on Serica Energy (LON:SQZ) in relation to the fact that Labour may be heading the next government. I currently hold and am considering a time limit on my holding (will try and get out over the next 6 months or so).
From what I have heard it seems there will likely be a general election in about 18 months. Currently Labour are well ahead in the polls. And it is almost certain that a Labour government will be bad news for Serica and their ability to reward shareholders (a threat of further windfall taxes is almost a guarantee from a new Labour govt imo based on the rhetoric over the last couple of years).
So assuming Labour win (and wins comfortably as many predict) - and assuming the stock market prices these outcomes ahead of time - then perhaps one doesn't want to be holding Serica in the months approaching the election. I assume the price will weaken well ahead of time.
Opinions would be welcome, as always especially those to the contrary.
cheers
Matt
Hi Matt I own Serica Energy (LON:SQZ) I bought it ahead of winter 2022 but instead of high gas prices driving the shares forward... M&A and their unpopular deal did the reverse. Operating metrics are favourable and the company is awash with cash. There could be a nice combination of further deals and / or cash returns..... So for the time being they look like they are in a solid recovery phase. A lot can happen over 6 months so Im not too worried about a labour government yet....
Personally I view this sector as rich pickings at the moment and the management team have an enviable track record. Mega caps are keen to offload fossil assets to satisfy ESG investors.... so deal flow should be good. The relationship with Mercuria should develop and it's possible a decent size deal outside the UK reduces risk on any tax change that may come with a change in government. Wait and see job for me.
Many thanks Richard. I also bought due to the cash pile and their very good track record of M&A (obviously the market didn't like the Tailwind deal - but overall they have grown well through acquisitions over recent years). I agree that a lot can happen over the next few months and so the best plan for me is to just monitor the situation and remain flexible with my thought process. Further expansion outside the north sea would certainly add some wanted diversification in my eyes - so I hope that more developments might happen in this regard in the coming months. I just worry that the stock could drift as we approach an election, and so I am still very reluctant to hold beyond another 6 months or so.
cheers
Matt
From what I have heard it seems there will likely be a general election in about 18 months.
By law the next general election must be held no later than 28th January 2025, five years after the last one. At the moment it's hard to see how the Conservatives can end up with a functioning majority, they barely have one now, even though they have an actual majority in the Commons.
Labour has pledged to ban issuing any new exploration licenses, onshore or offshore, while bringing forward investment in renewables. It also pledged to increase the windfall tax while removing the investment incentive.
Quite how much of that would survive contact with reality is hard to say, but it clearly isn't great for North Sea focused producers and developers.
timarr
Thanks Timarr. So if Jan 2025 is the latest possible date, I need to re-think my time horizons. I won't personally feel comfortable holding Serica going into the election and don't want to hold too long in the coming months assuming at some point I could get caught in a sentiment drift . Something to ponder for me over the coming weeks.
But in reality Labour don’t really have a plan for energy security. It’s basically hot air designed to get climate change voters and play to the mood music of bashing a piñata until it cracks even if that means importing all our oil and gas at 3 times the price and then wondering what went wrong and why there’s no investment in energy!!
My guess is that the rhetoric gets watered down a lot once a new chancellor actually realises what they have to contend with and the senior civil servants show them the numbers! Usually happens on party change in government.
As for Serica Energy (LON:SQZ) it looks as though they can generate sufficient cash to maximise use of tax losses prior to any major changes so much of market cap should be net cash at that stage plus they will focus capex spend in assets outside of North Sea. I know the mgmt are cognisant of the risks so are planning around it. Feels like risks are pretty well priced in to me.
One things to note is that the tax losses only apply to the ex-Tailwind part of the business. That info came from the CEO in answer to a question on one of the presentations - IMC I think.
I hold, fortunately from early 2021. Serica Energy (LON:SQZ) was the closest clone I could find after the Rockrose takeover.
I think the unions have been kicking up a fuss about the North Sea. They don't want to lose jobs, naturally. So, fingers crossed, Starmer won't go too crazy pursing green policies.
I've heard someone say (although they have a vested interest, so make of it what you will), that the infrastructure (mining and grid capabilities) are nowhere near capable of meeting anyone's targets. How much of that reality is sinking in, though, before real damage is done, remains to be seen.
Yes it’s utterly crackpot that Labour (who claim that Conservatives should have done more to reduce the nations energy costs) think that by banning new licenses in the North Sea peoples heating costs can go down or become more manageable! Let alone impact on corporate Britain. I mean it’s actually moronic if they genuinely think they can push that through without implications. But I suspect they don’t really mean it - they just want a hammer to attack a conservative govt whilst it’s down.There are too many jobs at risk for a start.
What we really need is a proper transition plan - one that incentivises the use of lowest carbon and thereby incentivises capex to be diverted to oil and gas projects that contribute the cleanest whilst at the same time increasing the use of clean energy and dynamically pricing it below the marginal unit cost of fossil based energy to attract increasing investment.
That way you avoid energy price shocks that tip consumers towards the lowest cost fuel irrespective of climate implications and keep your reserves and energy independence.
I was reading recently about the 10-15 year wait for any new renewables projects to get connected to the National Grid. That's obviously a major problem if you want to ramp up renewables deployment!
Once that sinks in for any new incumbent government I'm sure any plans to halt new Oil/Gas investment will go by the wayside, or they'll fudge the windfall tax somehow.
Add in the amount of extra electricity capacity required when (if?) lots of heat pumps get installed, and you soon start to realise there is no way they can shut off gas production any time soon.
It's one thing to install enough renewable capacity to replace the existing gas/coal/oil generation, but it's a completely different ballgame to double or treble the grid's output that will be required to power millions of heat pumps/electric boilers/EVs.
So in short, I can't see any way of Gas production not needing to increase for the next few decades.
It's interesting to see what National Grid say about this. They do NOT see any major issues with raw energy generation, including a nearly all renewables generation plan, because change is going happen over 10-15 year period so we don't need the capacity for heat pumps, EVs etc now. (In fact, the complete absence of a coherent plan for getting a heat pump supply chain going and to a lesser extent EVs means we are likely to be behind plan in transition, and behind most other developed countries which will be a competitive disadvantage).
In my previous comment I pointed to the opportunities for efficiency and demand shifting (with AND without batteries through simple pricing/market rule changes). These are relatively easy to fix with a govt of any colour.
The real problem is in the distribution of electrical power - sub- is stations, powerlines and real micro-connection issues. Fortunately this too is largely administrative (similar to allowing more low cost onshore wind) and therefore fixable within the 10-15 horizon that this needs planning on - far longer than most stock investment sites like this worry upon.
However, the balance sheet 'assets' of gas field licences and power plants should be considered carefully as they are always at risk of aggressive govt action and the political support that oil&gas lobbying can buy will likely weaken as the impact of climate change becomes more visible. In reverse, the industrial lobbying power of the renewables companies is building as they grow in scale and clout and they have more popular support - wait until the next pricing reform.
I hold Shell for instance but now as a trade vs a long term 'forever' hold as it was 20 years ago.
However, as ever, no one 'knows' and only time will tell.
Hi Matt,
I also hold Serica Energy (LON:SQZ). Personally I'm keeping hold for now for a number of reasons -
its a great company, very well run with lots of cash.
seem to increase their oil assets despite extraction, owing to extremely efficient extraction, they seem to find more.
oil price is currently on the up owing to Saudi and Russia extending their cuts, and according to the FT should reach $100 per barrel before the end of the year.
maybe maybe this government will review the Windfall tax before the next election. There were comments they were review it.
Serica may well announce international opportunities. Their CEO answered positively when I asked the question on the last results webinar.
and while we wait, a very nice divi yield of over 7%
Cheers Andy
Hello,
WANdisco (LON:WAND) got to be a viable short option!
definitely was in March LOL !
Cavendish = finnCap + Cenkos
Trying to read something on finnCap this morning I found 'Cavendish' at the head and that I was logged out. Gave Cavendish my email and got an automatic link in inbox to click on then straight in. Looks as if they are using the finnCap page style but all the historic reports from both sides are there with the Cenkos ones with a prefix of that name.
With a disastrous revamp of tvguide.co.uk forcing me to find a new listings site a week ago (note to self take Digitalbox (LON:DBOX) off watchlist) and six weeks of hell following the 19th June so-called upgrade here at Stocko I was very relieved that here was an organisation that could get its IT right.
Although Digitalbox (LON:DBOX) exchanged contracts for the acquisition of tvguide, there has been no completion announcement and as it was expected in H1, it looks like it has fallen through and they have bought assets from social chain AG instead.
House Prices
It is only logical that a correction has to happen and is happening, seems a hard fact to ignore so house builders are going to feel some pain and in the sort to medium term their as to be a correction to their NAV and profits.
Lots of things adding up now and the various government long term printing of money and spiralling debt with increased interest rates, replicated all around the world just does not seem to be a happy ending in sight.
Looks like the key sectors are resources and healthcare.
Have to say I am really scratching my head at the moment as these are sectors I am pretty rubbish in .
I cant see any way at all the economy is going to bounce and the political parties do not have any solutions other that waste more money .
Im down to 8 key holdings right now, do have funds to deploy but cant for the life of me find something Im comfortable with.
House Prices
It is only logical that a correction has to happen and is happening
Is it though if you are expecting material house price decline? - if we factor in 4 years of high inflation with house prices remaining broadly static does that not do the same job as 25% crash in house prices now with slow later bounceback to same end position?
House prices are overvalued by some 30% and an adjustment has to happen. It has lost connection with earning and that connection has to be restored. Bear in mind that the house price inflation is mainly in the south of the country.
The Housebuilders share prices have already adjusted for that in my calculations.
A wishful thinking more likely than the actual reality , but tend to agree that it is the south part of the country that will probably see a correction.
House prices are overvalued by some 30% and an adjustment has to happen. It has lost connection with earning and that connection has to be restored.
My thinking here is that this does not have to happen by a specific crash (following by rebound 3 years later) Its entirely possible house prices simply go nowhere until they have reduced in value by 30% in real terms compared to where we are today.
Hi Planetx
I put you in the far cleverer than me box, but what do I know as a "son of a Yorkshire Farmer" who has done well enough to get weekends off and 5 weeks paid holiday a year! That is 5 weeks more than my dad got in 42 years at work...so maybe I did do something right?
Anyway, usual responsibility for my own money and various family holdings, and I finally took charge of my SIPP last year. I have been in varying levels of cash for a while now, and know that there is an opportunity cost there, but at the same time going "I cannot understand why this is down another 5% this month alone".
I have been slowly trying to get into a positive mindset, but for every Bank of Georgia (LON:BGEO) there is a Legal & General (LON:LGEN) which nets the portfolio red in terms of capital position.
I keep making time to try and do my research, which is not as great a depth as many here including yourself. Finding this fits and ticks your checklist boxes, but then thinking it looks like a "Stage 4" chart... So whilst I know that I am really good at buying at the top, selling at the bottom, buying back at all new highs to sell at all new lows, and I know that I can never get anywhere near the bottom (look at 2020 played a nightmare picking several bottoms to sell at) a 48 year old is trying to learn a new trick. So hence why buy now, and watch it go down another 20% over the next 3 months?
Last week I pulled 20% of my mum's ISA (aka pension) into a cash ISA with monthly interest with the Skipton Building Society, yes less than I can get as a monthly yield on say Twentyfour Select Monthly Income Fund (LON:SMIF) but at the same point pays the monthly income and I am not thinking that this time next year I am down another 10-20% of capital having only drawn the dividends out. Sleep a night is a good thing, and it is not a wrong decision, just better than no decision and sitting there with cash in the S&S ISA earning 0%, so actually a right decision in its own way!
So not a simple answer, but a concurrence.
My SIPP is now in an account that pays interest, so is up this year on the basis of the interest payments, another good decision in the last 18 months. No it is not making or beating inflation, but I can sleep soundly. Then add in that I am still paying into another pension with the current employer too, and drawing a salary. I also acknowledge that I am happy with its overall value (DC so my pot), so I do not need it to return ridiculous amounts per year to contemplate any form of retirement. What is the worst thing that happens, I drive for Tesco 3 days a week when I am 55 or my daughters have to take a loan out if they chose to go to University and the funds I have been building for them don't quite cover all the costs?
There are some great companies out there that are a worthy home for our hard earned cash. But with many of them continuing to drift downwards, and then trying to guess where the next big lurch (aka profit warning, change in market sentiment, latest political announcement to get a headline) there is a nervousness.
I have moved my own ISA away from a concentrated portfolio on the sleep at night policy, so no longer 8-10 holdings, the biggest holdings are typically ~4-5% with many more what I would have called starter positions at 1-2%, with accepting that I need to develop my long term mental position. It is ok that a 1% position can go down 20% and if I still believe that it is a good investment (rerun the check list) then I can take it to a 2% position. Ok that 2% might loose another 20% or it might be next years winner!
As for house prices, even up here in North Yorkshire they are slowly starting to drop. Ultimately it depends what someone wants to pay for it, so someone moving up from London area thinking 2:15 direct train to Kings Cross the days I am in the office, and you can buy in town with a 10 minute walk to the station a 4 bed detached for less than a 2 bed flat, will pay more than a local who is on a 80% mortgage with both folks working fulltime with a chance to pay for it. Value is in the eye of the beholder.
Will chat with my nephew at the weekend and see what is happening with his company, last chat was they had just slowed all the starts down on the sites he was covering, so were still building, just at a slower place, so controlling supply (not sure if were starting once they had a deposit, or still building a couple speculatively) and cash flow, whereas previously it was a get them built we cannot supply fast enough. So for house builders the key one is debt levels and what is the breakeven cashflow to cover the overheads. House builders are contractors, I started as a Wimpey Group trainee after all when I was 18, cashflow is king! Also look at how much direct labour and plant, and how much is just subcontract it all out so can be switched off quickly.
We live on an island that is slowly being added to in some places and washed away in others, we are not taking the Singapore approach of dredging to make more land. So eventually either lots of people have to emigrate, or those that hold building land, or potential land Henry Boot (LON:BOOT) will come good if they survive through this period.
Good luck!
Tommy
I hold Twentyfour Select Monthly Income Fund (LON:SMIF) Bank of Georgia (LON:BGEO) Legal & General (LON:LGEN)
Tommy
Many thanks for the detailed response .
I’m not averse to risk as I have a good chunk of investment in other areas (forestry) that is so bloody boring but it is true money does grow on trees albeit very slowly, and less so if the deer and weevils destroy them .
I don’t think having a broad spread with low % holdings in this market is a good idea as you are designed to track the market, probably better in a low cost tracker ?
I was very fortunate (though actually it wasn’t luck as I knew the company very well) to have 25% of my portfolio in Crestchic and later 5% in Sureserve so 2 bids have put me on good footing .
Bank of Georgia I did have a big holding in but I bailed out too soon .
The big loser I had was national world and I underestimated what a self serving ego driven leader can do to destroy shareholder value whilst vastly filling his boots so that’s David Montgomery off my Christmas card list .
I think all those I’m holding are ok especially Georgia capital and Filtronic .
Most are all near their highs .
The problem stock is Holders which is totally illiquid and I want them to take private and stop the charade of being listed .
I have enough firepower to buy one more full position but think I’ll sit back a bit and have a think .
Don't forget the cost of new build will of jumped considerably. Many builders will opt for off plan or a large deposit paid before they start, why sink millions in unless sold. High new prices support existing prices so indeed some correction but without forced sellers I suspect price will dribble down only. There is a shortage after all, rental is dire from renters perspective (I'm a land lord of many years South East). Population is going through the roof. 31% of births last year were from mothers who were not born in this country BBC fact so it must be true. Gov meddling in tax and other matters has and will continue to drive up rents. Perhaps supply and demand needs to be explained to our dim whit politicians on all sides. The next boom is being baked in.
Planetx
Are you willing to say what your key holdings are?
No problem currently
In descending
Full positions
Equals (top sliced 10% recently )
Avingtans
Vertu (top sliced 5% recently )
Hargreaves
2/3 positions
Colefax (top sliced 10% last well
Holders technology
Georgia capital
Bloomsbury
1/2 positions
Filtronic
Trifast
Wynnstay
1/3 positions
Bank of Georgia
Croma
Sanderson
Small but building on drops
palace capital
AA4
Tiny can’t be bothered to sell
BP
AstraZeneca
sold out all the minor holdings last few weeks for head Soace and a big position in Titon because I needed cash for other stuff (speculative high risk but fun )
Vistry (VTY)
An incredible reaction to Vistry results this morning , up 15% to 920p.
It was not an Ahead statement, infact on most metric it was down. I think it was the return of surplus cash to shareholders over the next three years which caused this reaction.
Clearly there is a disconnect between what market thinks of Housebuilders and the reality.
Housebuilders share prices have collapsed in anticipation of a collapse in house prices. The latter has not happened though there is a downturn which is manageable. This is , in my mind, a golden opportunity for the long term investor .
Yep £1b to be returned over the next 3 years which by my calculations equates to approx £4 per share. Eventually the share price has to catch up with its value, hopefully.
Morning Paul.
Not a SCVR share but you may want to take a look at Vistry (LON:VTY) as I know you are interested in housing. I do have a personal holding here.
Seing a number of recommended podcasts today. Thought I would add.
My go to is Ramin Nakisa, search Pensioncraft YouTube. He does not invest in individual shares but rather ETFs long term foryour retirement. Extremely knowledgeable and a great source for macro stuff. I especially enjoy the live streams following interest rate announcements from the FED and BofE, he gives a great summary. Always very factual and data driven.
Ramin also does a Podcast with Michael called Man Happy Returns which is also great for topical macro stuff.
Looking at the good Vistry (LON:VTY) results today (I hold) led me to the PYAD screen (which VTY qualifies for, along with other housebuilders) and the PYAD screen led me to look at Triple Point Energy Transition (LON:TENT.
Are there holders of TENT here? I'd welcome views. I notice it has a capital markets day on Sept 28th.
It might betoo late for you to see this, but yes, I am a TENT holder on a "too deep a discount to NAV" basis, with a high yield. (Also trying to helpful stuff in the world.) Half my rather diversified portfolio is this. If only I had more time, I might set up an IT forum. I like to sleep nights, and there are a good few out there like Triple Point Energy Transition (LON:TENT) .
Sportech and Delistings.
Im less harsh on nano caps delisting especially ones sat on cash / assets above market cap provided that management will work for shareholder value.
At this level AIM rules and costs are seriously restricting a managements ability and agility which is a key ingredient of a small company.
It is hardly the fault of the company that the stock market is no longer functioning so for sure go private.
We all like to trot out the Warren Buffet quote something like "you are buying part of a business think like a company owner" and even private provided there is some pre agreed mechanism for liquidity you should be happy to hold provided your investment case still stands.
HDT Holders which I have a chunk of would be far better private, they are immediately 200k a year better off.
Imagine owning a business and having to give away 10% of your value to mr AIM who does nothing other than restrict you and fails to deliver what he promised in terms of market making and liquidity ,
Harwood are 100`% right to take companies private and provided small shareholders are not frozen out it is a better place to be .
As long as smaller investors are not effectively forced out at a meagre price then I agree.
Problem has been companies delisting and then consolidating shares into a very small number and paying out fractional shares in cash but at a marked discount. Thus removing small shareholders from the register forcibly at below market values (or effectively legalised theft in my view).
In this particular case I doubt that would occur with Harwood as a major shareholder. In fact I suspect it may do rather well as a private company and subsequently sold/ relisted at a later date 2 or 3 years down the line but you need to be comfortable with mgmt and their integrity in these scenarios.
It really does highlight the poor state of UK markets though.
Hi can someone clarify how Sportech (LON:SPO) are able to delist. I thought this required 75% shareholder approval. The shareholder register doesn't show much possibility of this - it would require agreement from a lot of holders - so imo would seem unlikely . However, obviously it must be likely as the share price has cratered.
I don't hold the stock, in fact I have not heard of it before today. But when I have gone through my own holdings to analyse the likelihood of any delisting's - I have always used the share holder register as an indication of whether this would be likely or possible.
If I had seen Sportech's ownership structure - I wouldn't have thought it was a concern. So how are they able to get the delisting passed? Have all the top 5 holders aggreged to this?
My naivety, I believed that if a company's ownership structure was like this, then they would be having to take the company private via a fair market offer (often a premium). And going private = good result for shareholder (as you receive market price or better). Delisting = disaster for shareholder (as everyone runs for the exits while liquidity still exists).
And to avoid delisting risks I always thought you should look at the shareholder register and Sportech's wouldn't have looked like a big risk to me. So maybe I am mis-understanding something, or is it just a case of all the major holders coming together to screw the private shareholders!
This is going to make me re-consider some of my holdings - which I assumed were very safe from a delisting - but as the UK market has become the wild west - I think my feeling of safety is naïve and needs a serious re-think.
ps. Just to clarify - I find this delisting to be very distasteful (and most delisting's for that matter) and imo is a way of legally robbing shareholders (who have supported the company and get rewarded with a punch in the face). The UK market is becoming more of a joke by the day. Global sentiment is low and totally justified in my opinion when we see ridiculous shenanigans like this happening on a daily basis. The situation is almost untenable for a small cap investor at the moment.
cheers
Matt
Sportech (LON:SPO)
The top 5 shareholders have 79.77% between them and would in all probability have been sounded out on this. The necessary circular will not be published until "the second half of September" and there may be an indication then as to who has agreed to vote for. Certainly, as noted by Graham, it is Harwood's style to go for delisting (SourceBio, Fulcrum Utility Services).
I'm sure you're correct, it just seems such deceitful behaviour against those that are supporting your company. Basically they are happy to screw people over to satisfy their own greed - I do not understand how these people can look at themselves in the mirror - shame on them. The fact that Harwood has a rep for this sort of thing says it all - imo the man is selfish, arrogant, and greedy (given his already substantial wealth). He should have the ability to make good returns for his investors without trying to manufacture special situation where he can screw over a large pool of smaller investors (imo it is no different to many financial scams that go on). He has no regard or consideration for anything but the size of his wallet. It has been said before many times - do not touch anything Harwood has involvement in - if you do you should have a pot of vaseline near by to make the experience less painful.
Yes, it is always a worry if they are on the register. Here someone with that worry last March got a reassuring answer - go to Q&A tab Q1 (login needed):
https://www.investormeetcompan...
It is interesting that they don't even deny that they screw over the shareholder pool. The response sounds like they would happily do it if they could (in regard to EKF), but the situation isn't appropriate as there are other holders who they describe as 'strong holders'. It is hard to know what they mean, as they refuse to answer the majority of the question and do not define what is meant by a strong holder. So perhaps strong holder means = those that do not seek to hurt others for their own personal gain.
Agreed, if investors in delisted firms like Sportech (LON:SPO) can sit it out and wait 2-3 years, then they may well do well from this low level (after today's fall at least, commiserations to existing holders).
I wondered if Christopher Mills of Harwood Capital had spoken about this before as he is not averse to an interview around his portfolio holdings and I located this Paul Hill interview with him from the end of 2021, in which he said (from 28:20): "...if you look at the shareholders in this, it is basically Richard Griffiths, us and Lombard Odier, and I'm quite sure all of us would like to maximise value, you know, over a reasonable period of time... so I very much doubt Sportech will be public in 18 months time."
Sportech | Xmas stock picking special & 2022 outlook with Christopher Mills of Harwood Capital (getseeen.ai)
And lo and behold, another delisting! Which suggests he, and maybe others, have the ear of the Board and were persuasive with the 'cost saving' angle.
So I'm wondering what other microcaps Harwood has a 20-25% holding in, and could agitate for a delisting? This list is from the Annual Report of Harwood vehicle North Atlantic Smaller Companies Investment Trust (LON:NAS) albeit dated as at 31 January 2023:
So watch out if you hold any of these.
Paul really enjoyed your podcast this weekend. Many thanks for the time and effort you put into it. My one issue is your suggestion Gas is a good option for the environment. For total clarity it is a hydro carbon. Putting more carbon in the atmosphere is a very bad idea. (How Much Carbon Dioxide Is in the Atmosphere (bloomberg.com - please click on historical data)) What i will accept is it is a better idea than many other ideas. But therein lies the problem............The reason I take exception is I believe it will increasingly become the major investment decision as time moves on, and I like you guys! Just my opinion, not looking for an argument.
Hi Camtab,
Yes fair point about gas, but what I was trying to say is that using North Sea gas is much cleaner than the alternative - importing LNG from half way around the world. So really it's the least bad option whilst we're gradually transitioning to renewables. So the Just Stop Oil idea to not develop any new N.Sea gas is completely wrong, as it just leads to more LNG imports, I'm told, hence a worse outcome for the environment. That was the specific point I was trying to make.
Regards, Paul.
This is an extract from an 8/6/23 Carbon Brief article which gives a bit of perspective..
"Oil and gas licences typically take an average of 28 years to produce new fossil fuels, meaning a licence issued today may not be contributing to supply until the 2040s or 2050s. (Licences awarded to sites with known reserves, close to drilling stations, tend to come online a little faster.)
By this time, the UK should be well on its way to meeting its legal target of net-zero emissions by 2050.
The journey to net-zero will see petrol cars replaced by electric cars, fossil-fuel boilers replaced by heat pumps and gas power stations replaced with low-carbon alternatives, such as renewables, nuclear and storage. All of this will see oil and gas demand plummet over the coming decades.
As oil and gas demand decreases, so too will the need to import fossil fuels. This means that, even if the UK has to source a larger proportion of its oil and gas from imports because of ending new North Sea licences, it would still be importing far less oil and gas than at present.
It is also worth bearing in mind that oil and gas produced in the North Sea does not necessarily “belong” to the UK.
Once a licence is awarded, North Sea oil and gas belongs to the licence holder. These are mostly multinational or state-owned fossil fuel companies, including firms fully or partly owned by the Russian, Iranian, Chinese, Norwegian and other governments.
Around 80% of oil produced in UK waters is currently exported. Similarly, during the global energy crisis last year, UK gas exports soared."
Factcheck: Why banning new North Sea oil and gas is not a ‘Just Stop Oil plan’ - Carbon Brief
I find 28 years hard to believe. I find most published data on climate change distorted to produce the desirable result. On a quick search (admittedly ChatGPT) I find a more believable result:
> as it just leads to more LNG imports, I'm told, hence a worse outcome for the environment
This is not true as has been pointed out by many. North Sea Gas is actually worse for the environment than the majority of our LNG imports which come from Norway.
“To make this claim, the Government is comparing UK gas to the dirtiest LNG imports yet these make up a fraction of our overall imports.
“What they conveniently leave out is UK gas is in the bottom half of the global league table for overall cleanliness and it is twice as polluting as gas from Norway which is where we get the vast majority of our imports.
“Moreover, 70% of what’s left in the North Sea is oil, which definitely isn’t cleaner than the global average and the vast majority of which we export anyway. So the Government’s focus on LNG comparisons is a complete distraction.”
https://www.heraldscotland.com...
Hi syrio,
I got my information from Plexus Holdings (LON:POS) (I hold) which has covered this topic in its results & presentations. Plexus made it clear that N.Sea gas is indeed much cleaner than imported LNG, because the N.Sea operates at high environmental levels compared with say M.East or N.America. In particular, he's said that it's the wellhead methane leaks which are so damaging to the environment, whereas the N.Sea generally has high standards (and Plexus knows the N.Sea inside out).
Also there's the obvious question of hauling LNG half way around the world on huge ships, which use dirty fuels to power them.
We can probably find plenty of sources which give a range of views on this, depending on what their agenda is. But to me it seems blindingly obvious - let's use the local infrastructure that's already there, rather than imports, as we press ahead with more renewables. But there's likely to be a gradually declining need for gas in the UK for some time to come, maybe 2-3 decades? Not my area of expertise obviously.
Regards, Paul.
Why would you believe Plexus Holdings who obviously have an interest in the North Sea gas industry?
I step into the N. Sea debate with considerable trepidation.
But before I do - let me thank all contributors for a very civil and insightful discussion. Quite rare - and not easy to achieve when GHG emissions are mentioned! Well done all.
It seems that there is some quite contradictory data on N.Sea emissions?
“What they conveniently leave out is UK gas is in the bottom half of the global league table for overall cleanliness and it is twice as polluting as gas from Norway which is where we get the vast majority of our imports.
and also
the N.Sea generally has high standards
So is it possible for both statement to be more correct than false?
Yes I think it is. But let me get S&P Global - commodity insights - to explain far better than I can, as they've just been studying it:
The average GHG intensity of production in the UK and Norwegian areas of the North Sea was 12 kilograms of carbon dioxide equivalent per barrel of oil equivalent (kgCO2e/boe) in 2021. A deeper analysis revealed that nearly 2/3 of total production was found to have an intensity below that basin-wide average. Meanwhile, assets responsible for just 20 percent of total production generated half of the basin's total GHG emissions.
Overall, individual assets across the basin displayed a wide variability, ranging in GHG intensity from less than 1 kgCO2e/boe to nearly 150 kgCO2e/boe. Such a wide range is consistent across all the regions that have been explored to date and highlights the challenges of averages, the report finds.
So a lot is going to depend upon whether we are considering the 20% of assets that account for half the N.Sea basin emissions or the 80% that are below average? Here's more from S&P
The S&P Global Commodity Insights analysis compared production in the United Kingdom and Norwegian areas of the North Sea to illustrate the influence of these factors.
The analysis found that, on average, UK production in the North Sea was nearly 3 times more GHG intensive (23 kgCO2e/boe) than Norwegian production (8 kgCO2e/boe).
Norwegian operations were advantaged on a GHG intensity basis as, on average, fields tended to be less mature and with a greater share of output from larger, more productive, and technologically advanced operations. Additionally, Norway benefited from electrification projects that tie back to Norway's relatively low-emission, hydro-dominated power grid.
By comparison, UK North Sea output tended to come from smaller, more mature or more geologically challenging fields, as well as from fields with older infrastructure and technology. These factors resulted in lower productivity and thus higher GHG intensity, the analysis finds. UK operations also had wider use of flaring—flaring and venting accounted for 28% of total UK North Sea emissions compared to 9% for Norway—and, unlike Norway, did not benefit from electrification projects to offset emissions from fuel combustion.
Here's the link to the S&P release: https://www.spglobal.com/commo...
To my mind that does seem to resolve some of the apparent contradictions between differing statements on GHG emissions from the N. Sea basin?
While I am carefully sitting on the fence it does occur to me - that this only addresses the past. I have no idea what the GHG emissions of the proposed new fields are likely to be? Perhaps the UK could licence new fields that significantly exceed the basin average if something can be done to reduce/remove the 20% worst offenders at the same time? and overall meet the UK's GHG emission commitments? Just sayin'?
All very interesting, but I suspect that the answer will be political rather than optimised with our two party contenders in opposing corners of the ring as usual?
In any case there are many years of N.Sea production ahead from the current fields - so I find the Plexus Holdings (LON:POS) technology to be very interesting. Well done Paul on spotting this and seizing the moment. I was too slow. I'd seen the company, put it down for some research and as usual, forgot about it! Now keeping a beady eye on it.
cheers
Mark
Thanks illiswilgig for the contribution, is interesting to see the difference in emissions between different field.
However production emissions are dwarfed by the GHG emissions produced by actually burning the natural gas of 320 kg CO2 per boe.
That is what we really need to focus on and how we get fossil fuel use down as fast as practically possible, even if it is expensive the short run. David
Paul has pointed out that transporting LNG from wherever it is produced in the world is a source of greenhouse gases. It also needs to be said that liquidising (the L in LNG) the gas requires a substantial amount of electricity, as does converting it back from liquid form to a gas in the UK.
Paul has pointed out that transporting LNG from wherever it is produced in the world is a source of greenhouse gases. It also needs to be said that liquidising (the L in LNG) the gas requires a substantial amount of electricity, as does converting it back from liquid form to a gas in the UK.
The problem is that the vast majority of GHGs are released by burning the gas not by producing or transporting it - the difference in production / transportation costs means the actual difference is about 10%.
If we want to reduce GHG emissions we need to use less gas, period, it doesn't matter where it comes from.timarr
This is not true as has been pointed out by many. North Sea Gas is actually worse for the environment than the majority of our LNG imports which come from Norway.
Small correction (well perhaps not so small in impact!). As you say the vast majority of our imported gas comes from Norway, but it's not Liqified, as it comes by pipeline, one of the cheapest, and least energy demanding ways possible.
The arguments that licences for new fields now that will not come into production till after we are supposed to have reached net zero, or that they will provide energy security, are very weak. Getting ahead with building planned nuclear stations, allowing onshore wind development, overing sensible prices for offshore wind, so we don't end up, as we just have, with no applications for licences, will provide cheaper energy far more quickly (apart form the first) and more securely than new production a decade or more down the line from the NS.
Paul, it is simply not true that "using North Sea gas is much cleaner than the alternative - importing LNG from half way around the world" and the least bad option.
This is Government truth distortion at its worst - listen to "More or less: behind the stats" on Radio 4, 6th from about 20mins in ( https://www.bbc.co.uk/sounds/play/p0gbvhqt) . The only difference between burning a methane molecule sourced in Indonesia and one from the North sea is the saving in transport, a very small part of the total supply chain carbon impact of its production. Many of their statements would not stand up to your 'balance sheet' scrutiny
We will need gas as part of the transition but IMHO a much better and more sensible order of 'least bad' action as we transition to renewables (which will take 20 years!) and is sensible for the economy as a whole would be to focus on :
Energy Efficiency - around 25-30% of lofts are still largely/completely uninsulated, for instance, the fuel escalator has been stuck for 10+ when it could have stimulated innovation and consumer adjustment (fewer SUVs), build well insulated houses to begin with, etc etc.
Demand shifting - Economy 7 as an idea is that goes back 50years, EVs will be around 10% of all vehicles on the road by 2026 according to Govy data, most with batteries x2-4 daily household consumption. Not rocket science to make vehicle-to-grid work, for instance. Differential pricing during the day is easy to implement
Low cost govt loans tied to property as a priority creditor - so the can't be run away from like Covid loans - to encourage all the stuff existing technology like heat pumps, solar water heating, solar and wind farms etc that has an upfront cost but typically a 7-12 year almost certain payback. Such a return is great for the country, less so for the household/ landlord/small business. That's why bigger businesses are doing it now if they have the cash and we have such poorly insulated homes vs near European neighbours.
Only after this, recalculate how much gas we will need; it will be much less! The above all help the country but come at a cost to existing incumbents. Unfortunately, the existing industry lobbyists have the ear and fill the pockets of ministers (check out historic party donations from housebuilders)and the typical conservative voter is 60+, retired and with a pension and a world view from 30 years ago.
But economic led truths are stronger than short term political economic nationalism as a tactic (which will no doubt adapt to follow the economics as the gap between dogma and latest widensreality) ......... and just because Just Stop Oil are idiots who should be arrested more often does not mean some of the issues they attempt to raise are wrong.
I hold Shell when it went ridiculously cheap a few years ago AND it was positioning for the future. Now it looks more like the coal companies of 15 years ago. Where are they?
Re: Use of Fossil Fuels
A few weeks ago I saw a tweet that noted that the UK had just two remaining coal-fired power stations for occasional baseload top-up during peak demand e.g. in midwinter. At the time, China had 1132 coal-fired power stations and they build the equivalent of 2 per week (106 in 2022). I'll refrain from the long political rant I could launch into about the insanity of UK energy policy (to the extent there is one) and just point out that continuing to buy all our manufactured goods from China is not commensurate with the UK's Net-Zero policy, if not its actual committed targets. Surely, sense will catch up with policy to some extent and when it does there must be an investment impact on China, no? Have we not already seen 'Peak China' or very nearly?
On Restaurant (LON:RTN)
I recall wagamamas was quite successful when they bought the chain, but there were concerns over the valuation (overpaid)
Is this a case of 'this happens to restauraunt chains as they are just not great businesses' or is it a rtn specific problem.
The only successful listed chain in my memory is macdonalds
Fair point. When it comes to McDonalds (without studying the accounts) it has always been promoted to me as a successful business model of land owner and franchisor, not a restaurant.
Entertaining film about McDonald's origins on Netflix. Called The Founder
Just a quick word on US CPI data.
The monthly number comes out on Wednesday ....if it stays pretty steady give or take around the 0.2% monthly number then year on year numbers will continue to rise up to the year end. However due to monthly numbers of 0.8% an d 0.5% falling out of the data in Jan and Feb... the year on year numbers will fall quickly in 2024. In 2024... if you simply input 0.2% give or take then inflation pretty much falls to target of 2%....not quite but close enough at 2.4%. This suggests to me that inflation will recede in 2024 as the data point of importance. The market will likely shift its focus to employment data as its benchmark for the strength of the economy and direction of interest rate policy. Bumbling along would seem to be goldilocks.... but my guess is we are a weak data point away from a less favourable interpretation. ( and therefore more confidence rates will fall).
The bit of the equation we don't know is how quickly the Fed can or will react. Of course the mistakes of 70s were easing too early.....but as the CPI data goes below 3% in 2024....this does leave real rates quite high and positive. In theory some scope to reduce...and possibly more than most think. Hard to say whether this will be received well or not, since rates coming back down signifies a weakening economy. The best defence is a little firepower to deploy should things get difficult.
Best of luck out there.
I've just had a look at WANdisco (LON:WAND) interims. What a joke this company is. Talk of cleansing the pipeline reminds me of lifting the manhole cover at my son's house when the drains were blocked. After a lifetime working in IT I maintain that there is no need for their software to move data to the cloud apart from a very small number that have already signed up to replicate data from a live system. Plenty of users of cloud computing are managing to upload large quantities of data without Wand.
Yes, dreadful figures from WANdisco (LON:WAND) as expected. My main concern is that the forecast cash is said to be down to $16m by Dec 2023. It raised $30m recently, so is tearing through that fresh cash raise pretty fast (although c.$6m one-off costs re survival/restructuring/fraud).
Looks utterly grim, for sure, as the published accounts always have done. I foolishly believed their too-good-to-be-true bookings/pipeline RNSs, which of course then turned out to be completely fictitious, not something that anyone predicted I don't think.
You make a very good point, that everyone else seems to manage without WAND's software. I made this very point, in person, to the disgraced former CEO. He claimed that the majors (like Amazon, Microsoft, etc) do already use WAND software! (in which case why would revenues be negligible?). The strange thing is, I sort of knew that none of the stuff he was saying made any sense, and he was continuously giving out deceitful body language, yet I still didn't sell my shares (this was at a meeting about 2 weeks before the fraud was announced).
Anyway, after today's numbers, doubt I'll be touching WAND again. It was a nifty trade from 50p to 100p, but it's difficult to see any value in it after today's figures. Maybe the major shareholders refinanced it because they didn't want egg on their faces?
Regards, Paul.
Well - you won't be able to invest in WAND any more - as with all such cases there is a rebrand and HL have already renamed them CIRATA - And will anybody be hauled over the coals over this saga - 'The Authorities' won't rush to bring anyone to account - they only face making themselves look bad
Paul, think you're spot on about the major shareholders and egg on their faces. There were some big egos involved in WAND. Well done you for your nifty (IMO very brave) trade but I still don't see the current share price being any where near justified. P.S. I was one of the early sceptics and have worked in the data migration sector.
Iofina (LON:IOF) (I hold), the 'specialists in the exploration and production of iodine and manufacturers of specialty chemical products' announced their interim results today. This might be worth a look for those that like smaller companies with attractive niches.
Bull Points:
For the half year results H1 2023 compared to H1 2022, Revenue up 27% and Profit Before Tax up 80%. Net cash also up despite investment in new plant.
New plant now producing - total production expected to rise from 242 metric tonnes ("MT") of crystalline iodine during H1 2023 to 325-350MT in H2. Should be good for margins, revenue and profit.
Both high returns on capital and equity and continuing opportunities to deploy that capital.
Bear Points:
Dependant on iodine prices staying at current levels.
Relies on oil industry for feedstock material - possible long term risk.
Might be hard to trade in larger volumes - Spread of 333bp, Free float of 34.5%, EMS of 15k (£4.5k)
Still looks pretty positive, and continuation of a turnaround story. RS 1yr of 28% so good momentum.
Would be glad to get an expert opinion though, still very new at this.
Inspired (LON:INSE) H1 results today, here's an overview video & podcast They are transitioning from a B2B service for customers to get the best energy costs, to a full service sustainability full service provider. The Assurance Services get the best energy costs, together with the ESG disclosures divisions drive the Optimisation (removing carbon emissions and making energy consumption more efficient) and the Software Services business divisions. They aim to double EBITDA over 5 years.
Today's results show H1 in line Revenue +10% and aEBITDA +10% although EPS fell 11% due to higher interest costs. Cash generation was -41% due to the timing of orders which should positively reverse in July. The outlook is in line for FY23 but I see Liberum have increased FD EPS FY24 & 25 by 5%.
Brilliant podcast at the weekend Paul.
I listened to it in the car - a first - while driving to Swanage to take my (elderly) parents for lunch.
My father is a keen long-term investor. He first bought shares in 1965 while living in Australia - Amatil being an ambitious regional supermarket which had the bonus of being the "bottler" of a relatively unknown, at the time, soft-drink called Coca Cola. He owned that all his adult life until its takeover, something of a multi-bagger for him.
Thanks The Jayman!
Yes I went into a couple of minor rants in this weekend's podcast, which helps me offload the week's stress, something I find helpful.
Incidentally, I found a really good investment podcast yesterday called "Fund Your Retirement Podcast" from Lee Cleasby. He interviews interesting investors, fund managers, and commentators on shares. I listened to 4 or 5 of them, including interviews with Rosemary Banyard, John Rosier, Bruce Packard, Lord Lee, Chris Boxall, and our own Graham Neary! Highly recommended, I found they all contained some interesting pearls of wisdom. I find that it's so easy to forget the investing basics, that I need constant reminders from listening to accomplished investors/insightful commentators. Hence why I find podcasts so useful, and interesting.
Here's Graham's podcast, which is terrific I think!
https://www.fundyourretirement...
Yes thanks Paul great listening, you and Iggy Confidential are my mandatory podcast weekend downloads!
I think the Fund Your Retirement Podcast is linked (part of the same series) as the Podcast for Private Investors - a collaboration between Maynard Paton, Bruce Packard, Mark Simpson & Roland Head, some of whom are "part of this Parish". It does now cost each month, but I have enjoyed the series to date and up until Aug (I think) was free.
Anyway, all four of them I find are good investors and their thoughts are well worth listening to.
With so many people now looking to charge for their content I am not sure how much is sustainable, with so many free content providers also providing superb commentary.
I will often try some of these things for a while and then make my mind up down the line.
With so many subscription services and some essentials it is easy to get sucked into over £500-1000 pa. The basics of Stockopedia, Investors Chronicle and 1 or 2 others and things quickly escalate.
It is amusing to see how many are looking to charge for their opinion via substack or courses or seminars. I've always thought if they're such good investors why would they need to bother with this, shouldn't they be on a beach somewhere? Most bizarre are the ones who only started investing in the last 5-10 years, think they're a fountain of knowledge, yet hadn't even been through a bear market, experienced inflation or even normal interest rate levels.
If people are willing to pay and they offer something different then I suppose there may be a market for it. You even have guys like Minervini and Weinstein offering expensive 'courses'
Much like trying to lose weight there's no quick fixes tho, time, hard work and experience count for a lot, unfortunately you can't buy that.
Hi Kevin,
Podcast for Private Investors - a collaboration between Maynard Paton, Bruce Packard, Mark Simpson & Roland Head
Yes, I agree they're very good commentators/investors, and I enjoyed listening to their podcasts when they were free. Now they're charging a fee, I wish them well, but won't be subscribing myself - mainly because I put my podcasts out free, and so don't see why I should have to pay other people to listen to their views!
A solution I think would be for the best investment podcasters to form a group, charge a single fee of say £10 per month, for people to access a whole basket of decent quality investing podcasts. Then split the money amongst the podcasters pro rata to how many unique downloads they get.
The numbers would only be small, so it wouldn't raise much money, but they do take a fair bit of time to prepare for and produce, so I can understand why people baulk at doing them free forever.
Mine are intended mainly as a service for Stockopedia subscribers, although other people can listen too.
Regards, Paul.
Paul
Yes I went into a couple of minor rants in this weekend's podcast,
All the more reason to tune in imho !!!
I'll second that Jayman. Excellent podcast.
Please keep saying it as you see it Paul, especially enjoyed the mini rants. Anyone offended or distressed by an opinion needs to take a good look at themselves. You're offended? So what, nothing happens!
I was always taught "sticks and stones may break my bones, but words will never hurt me" tho that's probably a non crime hate crime now.
. . . . the mini rants are always highlights and greatly amuse my otherwise disinterested wife (who BTW thinks Paul has an "engaging" speaking voice)!
Been stuck in bed the past week with covid then somehow caught the flu straight after. In between videos of cats falling off bookshelves I've watched some good financial videos.
There's a good one here with Graham which I think is new (tho maybe done June/July?) Ive seen him talk a few times and he always strikes me as a very smart, thoughtful guy. I especially like that he isn't a crowd follower and is happy to admit his mistakes.
I also rewatched Richard Leonards interview from 2021, it's a classic macho "the markets wrong, and I'm right" type situation at the top of the market. Saying he won't sell anymore Synthomer (LON:SYNT) at 380p as it's too cheap is very funny now we know the share price. The whole thing is a risk management disaster at the start of a bear market. Hopefully next time he's interviewed he'll admit he made some big mistakes and is humble enough to say he learnt from the experience.
Get well soon, we got a text yesterday from our decorator who we were expecting today. He is in hospital with COVID. Looks like time to be careful again.
Ah sorry, I've just seen your post Wolfie, I inadvertently duplicated your link to Graham's excellent podcast.
Get well soon :-)
Minder on the orient express christmas special on youtube Wolfie will help while a few hours away.
Thanks Phoenix, you know me too well. :-)
I've been working through the avengers episodes from the 60's with Diana Rigg and also Alfred Hitchcock Presents . Way before my time but absolutely loved them.
All eyes on the Burford Capital (LON:BUR) share price then, just what will Mr Mkt decide, this sure is a complex one. I hold.
Burford Capital (LON:BUR) I hold this one as well. I have no idea what to do now! Will the Argentinians actually ever pay up? When you see the numbers involved the rise in share price is irrelevant. I'll wait for the results on Wednesday and then decide as the rest of business appears to be doing very well anyway.
Suing the Argentine Govt! Unless you can seize some capital items in lieu of damages, you could wait an awful long time to see anything for your labours.
This has been going on since 2012 so agreed!
I was thinking something similar, a country that has defaulted on sovereign debt 9 or so times is hardly likely to cough up to some British company with a gripe, unless the Malvinas are part of the deal!
Worth keeping in mind that Burford Capital (LON:BUR) is probably worth £10 to £15 excluding the Argentina case. We now know the case is worth around £5bn to Burford if they collect in full. Clearly not likely to get the full figure and will take a long time, but anything they do get is essentially thrown in for free, IMO. There are lots of recovery options and wouldn't surprise me if they sell some or all of the claim.