Small Cap Value Report (Tue 18 April 2023) - FRAN, VLX, TPFG, CPC, BILN, SPO

Good morning! Graham and Roland here with today's report.
This report is now finished - 10.20am. Have a great day!
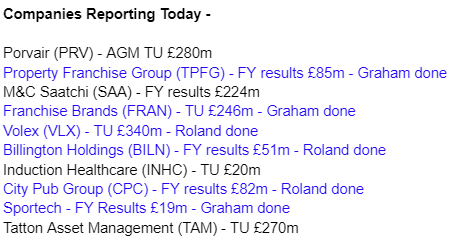
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
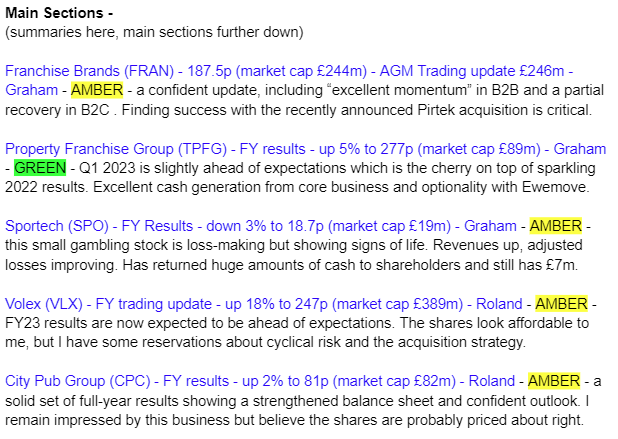
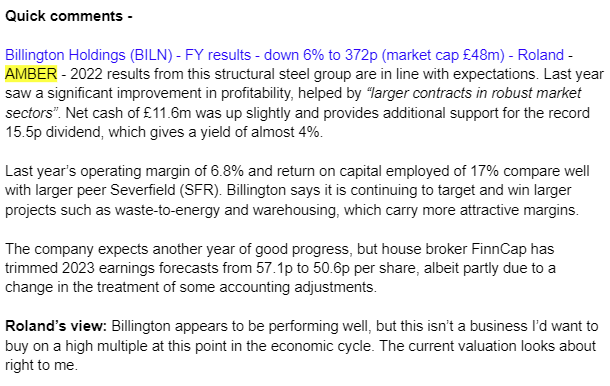
Graham's Section
Franchise Brands (LON:FRAN)
- Share price: 187.5p (pre-market)
- Market cap: £244m
We already looked at this one two weeks ago - with the remarkable news that it was making a £200m acquisition, funded by £110m of new equity.
Today we have an AGM trading update. I don’t see many new numbers here; but there is lots of reassurance for shareholders that the overall group continues to trade well:
…the excellent momentum in the B2B Division that was a feature of 2022 has continued. Metro Rod experienced strong growth in system sales, achieving record levels in Q1. The integration of Filta UK within this division continues with the combined objectives of improving customer service and reducing costs in the medium term. The defensive, mainly essential services provided by this division have proved resilient despite the current macro-economic uncertainties.
Other points:
Filta in North America performed “robustly” in Q1
Car paintwork repair company Chipsaway has seen a recovery in franchisee recruitment, but “the loss of franchisees in 2022 and increased overheads generally have impacted income in Q1 2023”.
Acquisition of Pirtek Europe (hydraulic hose repair and replacement company) will complete on 21st April, subject to shareholder approval.
Overall, it has been a “good start” to 2023.
Graham’s view
There’s little reason for me to change my opinion on this one, following this update.
I continue like many aspects of this stock and I agree that that Pirtek deal has the potential to be a huge success for the company and its shareholders, if the planned synergies and opportunities from the deal materialise.
I’m going to stay neutral for the same reasons that I did last time. Firstly, it looks like they may have paid a heavy multiple for Pirtek. And secondly, the level of debt and equity dilution that’s involved is significant and in my mind will be difficult to justify. But let’s see if they can in fact justify it with continued financial success.
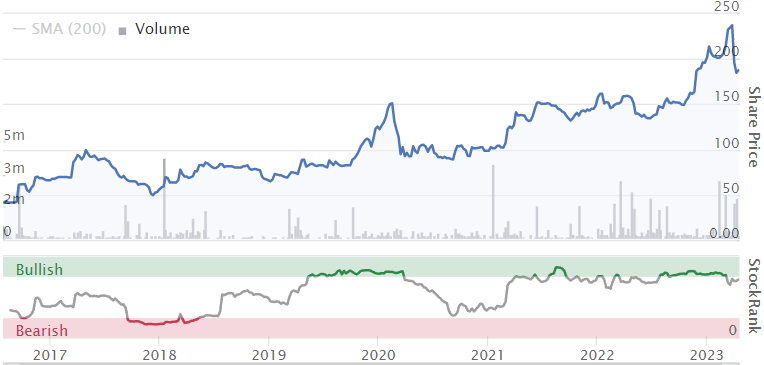
Long-term shareholders have done very well here and I certainly wouldn’t want to short this one:
Property Franchise (LON:TPFG)
- Share price: 277p (+5%)
- Market cap: £89m
Today we have full-year results from “the UK’s largest property franchisor”. We covered the corresponding trading update here, in February.
Let’s review some of the key bullet points:
13% total revenue growth to £27m
8% like-for-like total revenue growth (even stronger than the 7% reported in the trading update)
Management service fees (“royalties”) up 5% like-for-like, up 8% overall to £16m.
The adjusted operating margin is 41%, up from 40% last year - this is a high-quality business!
PBT increases 38% to £8.8m, and is matched by £8.2m of free cash flow.
The company borrowed £12.5m from Barclays to help fund the £24m acquisition of Hunters in early 2021.
Of this borrowing, £7.5m was a term loan, repayable over four years. Thanks to the free cash flow generated, this loan has now been repaid. Very nice!
They have moved from a net debt position (£2.7m) to a net cash position (£1.7m), while also paying a nice divi (yield currently c. 5%).
Q1 Trading and Outlook
Q1 is “slightly ahead of management’s expectations with regards to both revenue and profitability”.
The residential market “is expected to align with that of 2019 as we move through the year”.
And rental inflation continues to be a strong theme in 2023, being driven by “a lack of stock, unprecedented demand, and rising mortgage costs”.
It’s important to understand the sales vs. lettings mix for these businesses. In 2022, lettings were responsible for 47% of TPFG’s total revenues, and 55% of its high-quality royalty income.
The number of tenanted properties managed by TPFG only increased by 2,000 (to 76,000), but revenues were also boosted by the rental inflation mentioned above.
CEO comment:
It must be lovely to write up commentary for annual results when you have achievements like these to report:
We have delivered another strong set of record results in 2022. Particularly pleasing given the economic backdrop and contraction in residential sales transactions. In two years, we have grown group revenue almost 2.5 times, maintained recurring revenues at half of group revenue, doubled adjusted profit before tax and grown adjusted fully diluted earnings per share by two-thirds. We have also put ourselves back in a net cash position within eighteen months of our largest acquisition to date, Hunters, giving us a strong platform for future growth.
Graham's view
I’m particularly impressed with the growth at EweMove, which has doubled its territories covered in the last two years to 189.
This is a hybrid agent that puts a modern twist on traditional estate agency but without moving to the very cheap model employed by Purplebricks or Strike.
Ewemove is still quite small, so it remains to be seen what it can achieve at a larger scale. However, it does currently enjoy much higher ratings from customers than Purplebricks. Its rating against Strike is more even. Remember that Purplebricks was at one point valued at nearly one and a half billion pounds!
My overall view on TPFG remains very positive. It strikes me as a high-quality, cash-generative, shareholder-oriented company. The only thing they are missing is a share buyback, which I think could make sense at a sub-£100m market cap.
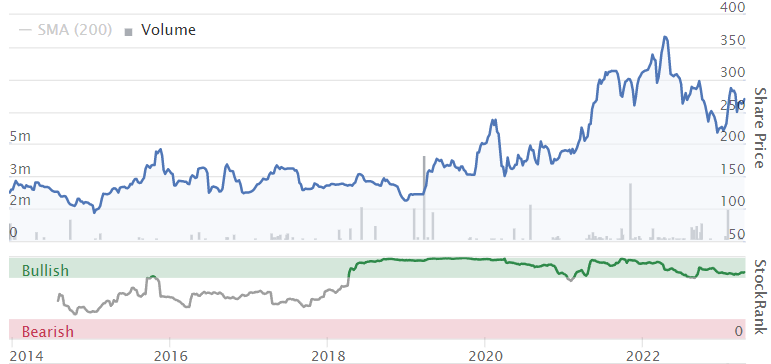
The shares may be held up currently by macro concerns. I think that TPFG is well-diversified between sales and lettings so that it can do reasonably well even in a poor sales market. But it may be fair to have some concerns about overpaying for this stock in a fragile housing market:
Sportech (LON:SPO)
- Share price: 18.7p (-3%)
- Market cap: £19m
It’s been a long time since we looked at this gambling share. The share price hasn’t done very well:

It returned money to shareholders in 2021, at 40p per share, after the sale of various assets.
Let’s quickly review the latest situation:
Revenues up 2% to £26m (previous year: £25.6m at constant currencies)
Gross profits up 11% to £14.2m (previous year: £12.8m at constant currencies)
Adjusted loss £0.1m (previous year: adjusted loss of £3.4m)
The company finished the year with cash of £7.4m, after paying a £7m dividend. It has returned lots of cash to shareholders, that’s for sure!
The group currently consists of a range of gaming venues in Connecticut, and also two digital businesses including one which offers lottery technology.
In sports betting at their US venues, they were very pleased with a handle of $98.7m in 2022 - this is the amount wagered by customers. The company then achieved a “hold” of 9.4%, i.e. that was the margin it achieved on bets. My understanding is that most bookies would be delighted with that number!
Comment by the Exec Chairman:
2022 Operational leverage was impressive, as modest revenue gains translated to impressive gross profit gains and a return to positive EBITDA during the year. We are reviewing various strategic options for the current business lines while evaluating online betting opportunities that leverage our brand, people and expertise. Cash position is strong and we will update the market regarding potential further shareholder capital returns ahead of the May AGM.
Outlook
Goals in 2023 include “materially” reducing the corporate cost base, evaluating a range of corporate/growth opportunities, and delivering “further capital returns to shareholders”.
Graham's view
I’m enthused by this company’s strong willingness to return cash to shareholders, which it has done repeatedly. Management claim that they are focused on the efficient use of cash and on accurately measuring their returns on capital deployed - I always like to hear this, especially when it’s true! Their words and actions do strike me as highly shareholder-oriented.
More study is required but this one strikes me as potentially interesting
Roland's Section
Volex (LON:VLX)
- Share price: 249p (+18% at 08.15)
- Market cap: £389m
Full year trading ahead of market expectations
This manufacturing group led by Nat Rothschild looks more reasonably priced than it has been over the last couple of years. Today’s trading update is ahead of expectations, so I wonder if we can expect the stock to regain some of its lost momentum.

Volex produces electrical cabling for commercial customers, including electric vehicles, medical equipment and other industrial markets. The group has been growing by acquisition as well as organically in recent years.
Today’s full-year trading update covers the 52 weeks ended 2 April 2023.
Main highlights: the company says that full-year results are now expected to be ahead of market expectations. These are helpfully included in the footnotes.
Here are the main highlights:
FY23 revenue: “at least $710m” (previous consensus $692.9m)
FY23 underlying operating profit: “at least $66 million” (previous consensus $62.9m)
Revenue is expected to be at least 15.5% higher than the prior year, with underlying operating profit at least 17.4% higher than last year.
Paul looked at the adjustments Volex uses in its underlying profits in November – they were fairly conventional, although I would subtract share-based payments charges, which were $2.6m in H1.
Costs: Volex says that it has been able to increase gross margins and manage rising costs. As a result, underlying operating margin is expected to be 9.3%, compared to 9.1% last year.
Cash flow: operating cash flow is said to have improved in H2. After capex, dividends and acquisition payments totalling $46m, the company expects to report net debt ex-leases of c.$76m.
This is said to represent a multiple of 1.0x EBITDA, “comfortably below the Group’s target leverage corridor”.
FY24 Outlook: Volex says it has “strong momentum” into FY2024 and says that market share gains are helping to offset weaker demand in some markets, such as consumer electricals.
No specific guidance on the outlook for the year ahead is provided, but Volex remains committed to its five-year strategy to increase revenue to $1.2bn by the end of FY2027, aided by acquisitions.
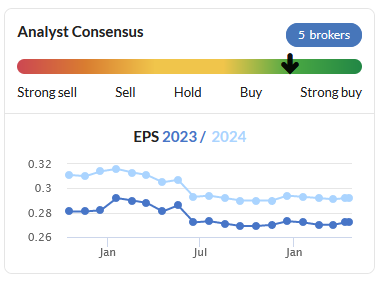
Broker forecasts have consistently suggested another year of growth in 2023/24. Today’s update seems likely to reinforce this outlook:
Roland’s view
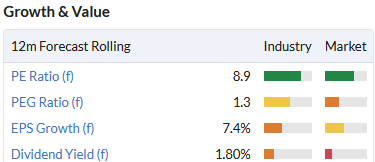
Volex appears to be performing well and in reasonably good financial health. The shares look reasonably valued to me and quality metrics look acceptable, if not outstanding.

My main concern with this business is that its desire for growth may mean that it makes acquisitions which add bulk to the group, but don’t necessarily move it up the value chain or deliver clear synergies with other parts of the business.
Despite this risk, my view on Volex is broadly positive. The current rating looks undemanding and I think the shares could perform well, if Volex can continue to improve its profitability and cash generation.
City Pub (LON:CPC)
- Share price 81p (+2% at 08.15)
- Market cap: £84m
“For the first time in 3 years, I am confident about crystallising enhancement of shareholder value. The Company is now in the best shape it's ever been in.” - Exec Chairman
This upmarket pub group is focused on London, the south of England, and Wales. Today’s results show a return to profitability and suggest the group is now positioned to resume its pre-pandemic growth trajectory.
Profit margins remain low, but unlike some of its larger listed rivals, City Pub is now carrying very little debt. This – plus the group’s premium positioning and freehold estate – suggests to me it could be a more attractive prospect for investors in this sector than some of its larger and more indebted rivals.
Let’s take a look.
Financial highlights:
Today’s results cover the 52 weeks ended 25 December 2022. As expected, they show a significant benefit from the removal of pandemic restrictions in place at times during 2021.
Revenue: +63% to £57.8m
Adjusted pre-tax profit up 280% to £3.8m
Operating margin: 2.5%
Reported net profit: +£1.1m (2021: loss of £2.9m)
2022 balance sheet net asset value: 91p per share
Company estate valuation NAV: 150p per share
Net debt: £4m
Net debt was reduced significantly last year with the help of £17m proceeds from disposals.
The company says that a March 2022 valuation of its estate gives a portfolio value of £160m, or 150p per share, but it’s not completely clear to me how this aligns with the balance sheet PP&E value of £99m and lease assets of £17.6m.
However, I’m confident that at current levels, the stock is trading below book value with minimal debt – an attractive position providing some margin of safety.
Dividend/buybacks: There was no dividend, as City Pub has opted to buyback shares instead. With the stock trading below its book value this makes sense and should be accretive to NAV.
Buybacks totalled c.1m shares totalling c.£0.83m last year. Further buybacks will be considered, but the board is keen to maintain “prudent gearing levels”. Sounds sensible enough to me.
Operational update: over the last year, City Pub says it has completed a refurbishment of its estate and concluded a number of disposals. This has left the group with a strengthened balance sheet and strengthened “premium estate”.
Executive Chairman Clive Watson, who is a 3% shareholder, is now confident the group is positioned to resume progress:
Our premium estate is now fully refurbished creating, together with the strengthened management team, a platform for expansion when the time is right.
Mr Watson says that trading was challenging last year due to rising costs and staff shortages. However, he says that the company has now weathered the storm and is positioned to “adopt a more ambitious approach”.
Outlook: trading during the first three months of 2023 is said to be “ahead of expectations”, with like-for-like sales versus 2022 up by over 13%.
The group’s investment in Mosaic Pub & Dining Group was increased to 48% in April, and management expects to take operational control in the next two months. This will give City Pubs an estate of over 50 pubs, its largest ever.
The outlook for the year appears confident, although no specific guidance is provided.
Prior to today, Stockopedia consensus forecasts suggested earnings could rise by 55% in 2023. My impression is that this remains a reasonable estimate.

Roland’s view
When I last looked at City Pubs in April 2022, I was cautious about the outlook and valuation for the business.
Today, the share price is unchanged but the outlook and balance sheet appear to be improved.
Forecasts for this year imply a further improvement in profitability, in addition to continued sales growth.
I’m cautiously optimistic that this business should be able to perform well from here. However, I’m not entirely convinced that the shares offer compelling value. While City Pubs is trading at a discount to book value, the pub trade is a low-margin business that’s very exposed to consumer spending and input costs.
On a P/E basis, the shares don’t look especially cheap to me, on 18x FY23 forecast earnings.
On balance, my feeling is that this looks a good business, but it’s probably priced about right at current levels.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

90 comments
Hello Graham/Roland, I notice that most of the tags are missing on this report.
Fixed it, thanks Rusty.
National World (NWOR)
Great to see the fabulous team at national world have seen their fantastic success recognised with the 12 million shares received at zero cost as a result of the 2019 “value creation plan”
What an honour it is to be a shareholder in David Montgomery”s. Listed vehicle .
That’s 10% of the company earned at zero cost .
Always great when such poorly paid senior managers achieve their goals and receive their due reward .
A happy holder , I have written to the company asking for David’s bank details so I can send him a few more quid out of my own pocket as a further reward .
I will get my cost, utter and total disgrace of a management team a benchmark in blue collar crime .
National World (LON:NWOR): "Within the total above, 4,432,177 awards to Vijay Vaghela, a director until September 2022...The VCP was put in place on Admission in September 2019 to support the delivery of the Company's strategy, to retain the lead executives and reward them for driving its successful delivery."
Well, it didn't retain Vijay Vaghela did it?
BTW the total is 5% of the co.
Totally agree and I will be selling this week.
Crest Nicholson Holdings (LON:CRST) currently up 7% this morning while most UK housebuilders are flat to down, anyone any ideas ?
Crest Nicholson Holdings (LON:CRST) is already up 10% today, +30% in 2 weeks. No idea about the jump, but it looks like other housebuilders are up ~20% YTD, while Crest was far behind them, so just followed the trend a bit later.
Anyone got any thoughts on Silver Bullet Data Services (LON:SBDS) ?
Horrible float, well down from IPO price - came to market around its 4D marketing product for the world that is "cookie free", but almost inevitably that adoption didn't arrive anywhere nearly as quickly as management expected.
However, fast forward to todays trading statement and my interest is piqued..... It is now an £8m market cap (so tiny and presumably horribly illiquid). But it has done £5.2m of new contracts in the last 6 months so looks like it is on track to move above £10m of revenues. (Q1 was over £2m so £10m+ run rate makes sense given growth).
Client base is genuinely blue chip (Heineken, Mars, Sony, US Government).
So trading on less than 1* sales but with revenue growth exceeding 100%.
Was heavily loss making since float but most of the cost sits in the admin expense line. We are told that to deliver the 100% revenue growth costs are same as Q1 of last year so does this mean that getting to £10m+ revenue equates to broadly break even? It suggests it does, in which case the shares look cheap to me, but it's too woolly a statement for me to ascertain that with any certainty. (is that a deliberate obfuscation or just poor wording?)
I intend to do a bit of digging as this looks like it may have potential but has anyone on here looked at it?
Just been poking around their website. I would want to know how much revenue they are getting from the services side of things and how much from the '4D' product.
My impression is that it's probably mostly getting income from the services.
The 4D product looks interesting - in theory, you can check to see if your adverts are being placed in places that you wouldn't want them to be. Does it offer anything over what you already get from the platforms (YouTube, Facebook etc...)?
Kromek (LON:KMK)
Following this one for a while (with a very small holding) but now wondering if it is worth a significantly closer look. It has been a perennially underperformer. Super tech but never got profitable, raised money a few times....we all know the story....blah blah blah.
However, trading update today confirms now basically cashflow breakeven moving into cash profitability. Tick. That alleviates the risk of a forced dilutive equity raise, which I think was the reason for the heavy falls.
Signed a 7 year agreement with a Tier 1 OEM in advanced medical imaging scanners. This is important because Kromek (LON:KMK) is the only independent company globally as I understand it capable of providing this tech. The other 2 have been bought by OEMs so the rest of the market won't use them. This means theoretically Kromek (LON:KMK) should be able to take a large %age of the remaining market, which is big. According to last results they are working on a few of these agreements and appears the first one has landed.
Now the market cap of the company is small - circa £20m and the valuation on the public market is very dislocated to the private market. The tech is undoubtedly worth way more than £20m. I think a couple of years back a company with less developed tech went for something like 5 or 6 times Kromek (LON:KMK) valuation, possibly more. So there is a lot of strategic value in the company. Whether that can ever get realised on a public market is debatable, given it hasn't happened yet. But if the company is now going to be cashflow profitable and growing well then maybe.....just maybe....
One for me to mull over.
I share similar thoughts. I hold and am long suffering but just maybe..... They announced a £1m order back in March so it is not all agreements.
Agreed Berksbee - the radiation detection tech and business / revenues are world class as well but on their own don't make a business, as has been amply demonstrated by the company over the last few years. Combined with the CZT tech though it could. They have to demonstrate a positive operating cashflow (after research spend) though and they need to do this without trying to dilute equity. It's on the cusp.......can they move it to the next step is the big question
I looked a couple of months ago and took some around 10p thinking some contracts could make it spike up. Hit my stop loss and sold. They really need more biz. I am watching from the sidelines.
Hi David,
As always, you make some excellent points. However, the debt and remaining cash position is still precarious so it wouldn't surprise me if there was an equity raise; the company could use this latest announcement to drum up support for just such a move. Just a thought.
I had rather taken my eyes off Pressure Technologies (LON:PRES). I see they are suspended as audited accounts delayed. This occurred days after the announcement of a £3m contract. Apologies if this has already been discussed but anybody got more on this. I have been a holder on and off for a few years now, but not currently holding.
Hi Cantab,
I bought an opening position in Pressure Technologies (LON:PRES) at 40p. I don't think that I can add anything to your knowledge but have below regurgitated the reasoning behind my purchase and holding of the shares, which hopefully is not too flawed.
The Vox market interviews with Richard Staveley regarding the results of Rockwood Strategic (LON:RKW) are worth a listen. The interview from last December is especially informative on Pressure Technologies (LON:PRES) the commentary on which starts at about 50 minutes.
The results from Pressure Technologies (LON:PRES) and re-listing are due by the end of the month. Everyone makes mistakes, even Messrs Staveley and Mills, but I think that the risk/reward balance is tilted in favour of the latter over the medium term.
Thankyou Jonno.Gave me a bit of a start mentioning Pressure Technologies (LON:PRES) in the same breath as WANdisco (LON:WAND)!!! All points welcomed and I think the accounting error sounds rather minor. Over the years seen many discussions about when revenues/profits should be recognised. Anyway fingers crossed because I think this companies time is coming.
Hi
Google's Bard, a bit off topic but it might interest some (apologies for rather long posting).
Yesterday Ben Hazzard provided a very insightful post of how he had used Google trends and Google's Bard to assess customer volumes using Revolution Bars (LON:RBG) facilities. See yesterday's SCVR at 8:36am. Then DeWit199 added posts at 9:47pm with another 11:08pm.
The posts are interesting examples of how these AI platforms might help us PI's, with limited time and resources, to carry out extensive research. However, they are clearly embryonic and do produce completely fictitious results (see DeWit199's posts).
Today one of my holdings Wise (LON:WISE) reported Q4 FY23 TU.
RNS here ....
https://www.investegate.co.uk/...
On the face of it I thought the Wise (LON:WISE) TU was pretty good. By way of an example, these are but two points stated
The appeal of Wise for customers around the world continues to drive strong active customer growth of 33% YoY and 6% QoQ, with 6.1 million active customers in Q4 FY23, comprising 5.8 million personal (+34% YoY, +6% QoQ) and 340K business customers (+27% YoY, +7% QoQ). This growth primarily reflects customers joining Wise to use the Wise Account.
Continued growth in active customers drove cross border volumes higher in Q4 FY23 to £26.7 billion, representing 25% growth YoY and 1% QoQ[2]. Personal customers moved £19.5 billion, 23% growth YoY, while Business customers moved £7.3 billion, 30% growth YoY.
I was surprised that the share price dropped over -11% at the open.
Being short of time I thought how might I get some clue as to why the market reacted this way (an issue we all seem to face from time to time)?
I tried Bard, this is the outcome.
My experiments with Bard confirm it is very bad with figures and calculations (see again DeWitt199 posts) and makes data up without highlighting that to be the case.
However, recognising that Bard (and ChatGPT) have been designed to be AI language tools (rather than financial AI platforms). I therefore try to bias my use of them towards text based interrogations (rather than figures and calculations).
The above Bard response may not be the best, nor be completely accurate. Furthermore, it is only as good as my prompt to it.
But, it did provide two important benefits (for me).
First, I obtained these insights in seconds.
Second, and Importantly, it furnished me with some useful pointers with which to reassess my investment case with Wise (LON:WISE), thus pointers with which to do further investigations.
Clearly it could be taken further by being subjected to additional refinements of interrogation (a task for later).
Part of my reasons for making this post are: I only started with Bard yesterday, this is my fourth query, so it is extremely easy to use. Second, to demonstrate through but one example, of how a pretty complex question (which we all face at times) can be submitted to get some quite useful insights very, very quickly. Finally, to illustrate that these AI platforms are here and are useful, today.
Regards
Howard
But even then Bard is giving false information. According to a specific statement in the trading update Wise's revenue for Q4 FY23 was £223.5 million up 45% YoY but the Bard answer to your question states Wise's revenue grew by 29% year-over-year. Where did it get that number?
I am reasonably certain that Bard or ChatGPT lack access to current information so they just invent stuff that at a first glance seems plausible. They are both extremely proficient liars and should be viewed with utmost caution. I am able to spot most of the "rampers" on bulletin boards but these two AI tools are much more subtle deceivers.
I am reasonably certain that Bard or ChatGPT lack access to current information so they just invent stuff that at a first glance seems plausible. They are both extremely proficient liars and should be viewed with utmost caution. I am able to spot most of the "rampers" on bulletin boards but these two AI tools are much more subtle deceivers.
I don't agree with Elon Musk on many things but I do with regard to the dangers of AI. It appeals to those that don't understand the power of it, especially those who see it as a short-cut to putting in the hard yards and doing their own research and critical thinking. It appeals to people's inherent laziness, and that is a huge danger for the future.
Agree with you about Elon Musk - except that he's now investing heavily in AI himself and has left Twitter wide open to fake news by stripping it of the humans vetting content. You can't rely on anything he says.
He has specifically confirmed he has cut back on the bots (according to him !!)- is that not the main source of fake news? - were the human do gooders really concetrating on fake news or was there an agenda behind the scenes with regard to what they were spending time on? - car crash interview with person from the bbc where imho (feel free to disagree) bbc guy made himself look like a complete fool. From my viewpoint jury it owt with regard to anything he says - but equally pre musk twitter looked like a complete basket case business.
Hi DWit199
Thank you for your build onto my earlier post regarding Bard.
Yes you are completely accurate that Bard presents false results.
Both Bard and ChtGPT do this often (I am finding), and Bard's response to me about Wise (LON:WISE) today is indeed incorrect.
I am concluding with my short experiments with Bard and ChatGPT that anytime they use numbers the results must be checked in detail.
I surmise they have clearly not been trained in quants (quantitative) in any shape or form.
That noted, the two platforms have been trained on vast volumes of data (but very different data sets, so each gives different responses to the same question), which is text, which is language. Thus they seem to be able to offer some quite useful pointers along the qual (qualitative) front.
For example my question was complex, required quite a high degree of interrogation in order to even understand what I was in fact asking. But the Bard AI was able to determine the context of the question, assemble a set of ideas and present them quite coherently (but obviously they need to be validated for accuracy and truth).
In short, I think the current iterations of Bard and ChatGPT can offer some support for investors who might be digging into the context of equities, markets and the financial domain.
But the two AI platforms ought to be viewed as a rather flawed but fast working researching or data gathering assistant. Who must be supervised and checked closely.
Regards
Howard
Wise (LON:WISE)
Thanks for sharing that Howard. Quite interesting (and to Dewit199 for the response, which I found highly informative).
I'm still stuck in the old days of trying to make sense of updates by myself. Below are my very brief notes. Any critique of my generally positive views from today's update would be appreciated:
By my estimate card usage revenues = c2% of average customer deposit balances across the year.
Current Market Cap = £5.4b
Undervalued
Hi abtan
Many thanks for your informative post of Wise (LON:WISE) TU.
After my earlier posting I in fact added to my Wise (LON:WISE) holding as I too thought results were overall positive (got 510.05). Thankfully the price has continued to rise (529.60 as I type)
After I had added to my holding, I have only just seen this newsfeed, which might explain some of the big early price fall.
BUZZ-UK payments firm Wise Plc declines on weak volumes per customer
 Wise
News9:31 am** Shares of Wise Plc WISEa.L slide as much as 11.2% to 520p, stock set to post worst day since March 13, if trend holds** Money-transfer firm reports a fall in quarterly volume per customer (VPC) on lower discretionary spending amid challenging macroeconomic conditions
** Says average VPC down 7% y-o-y and 4% qtr-on-qtr on a slower place of growth of customers who move volumes of more than 10,000 pounds ($12,433.00)
** Co reports 25% rise in total volume to 26.7 billion pounds, but below expectations of analysts at Credit Suisse and Peel Hunt
** Peel Hunt analysts say the second consecutive quarter of declines in PVC is a notable negative, adding that co is likely to remain subdued amid current macro environment
** Including session's losses, stock down about 7% YTD
($1 = 0.8043 pounds)
I think this factor caused an over reaction in contrast to the wider investment thesis (hopefully).
Regards
Howard
Wise (LON:WISE)
Yes. The fall on VPC was the key metric that bears seized upon in the previous TU. Today’s further fall only adds to that argument. The rest of the report wasn’t so bad IMO.
Wise (LON:WISE)
Hi Howard and BnB
Yes, I saw the declining volume/personal customer figure today.
Volume/business customer actually went up YOY%.
Given the diversification into non-FX revenues, and all the positive metrics that drive this, I'm less concerned with volume/customer; it will come back as economies improve.
Far more important for me was:
1) the accelerating growth in active customer numbers, indicating continued adoption of Wise's services (and hopefully future cash deposits into the Wise ecosystem).
2) Increasing customer deposits, where the growth here is remarkable and which will hopefully continue to drive non-FX revenues:
(NB: customer deposits shown as negative in my screenshot)
3) and the increasing revenues coming from usage of Wise Accounts and Debit Cards (and interest, though this will come down in % terms as the company attempts to return this to customers).
This table shows % revenue splits, especially the decline in FX-derived revenues since 2020.
To put some numbers to the Non-FX Revenue % in the table above (eg Wise Debit Card usage), these have increased from £85m in FY22 (the 15.2% figure in the table above) to £178m in FY23 (the 18.5% figure in the table above).
----
So yes, volume/customer is down...but there's far more here to drive revenues going forward as they showed with today's update and kept repeating in the call this morning.
Now to wait until June to see profitability levels. Given the lack of debt, positive cash generation and what I see as pretty average competition, I haven't seen anything yet to concern me about the long term future of the company.
A
Hi abtan
Many thanks for this detailed analysis of some of the Wise (LON:WISE) stats. Very useful.
As I'm sure you have noted, Wise (LON:WISE) had nearly 6m in volume today versus an average of just over 1m. Further, its share price had a low of 490.0 (10:29am) a high of 543.8 (1:18pm), nearly an 11% low to high journey. Closed at a clean 540.00.
It seems the market digested the data and decided that the bull case was the better option (today).
Let's see what tomorrow brings.
Regards
Howard
Morning everyone. Another one of my slightly off-topic observational emails coming up that doesn’t really have anything to do with small caps (skip this post now if that irritates you in any way) but on which I'd be interested in the learned views of this forum.
Some slightly odd things going on in the investment trust world at present. Big sell offs and discounts opening up for seemingly no reason connected with the actual quality of the underlying assets. I am assuming this must just be because of investment flows out of equities in general. If that is the case then one would think there should be some good opportunities here to take a position and then hold until sentiment improves then ride the ‘double whammy’ of the narrowing discount supplemented by the rising tide of the underlying equities.
Two cases in point:
First, Invesco Select Trust UK Equity. Now sitting at an 18% discount (way wider than its historical average). This is a basic UK equity fund holding primarily large and midcaps – its top 10 (making up >40% of the fund) are the following:
Shell PLC
5.8
BP PLC
4.8
SSE PLC
4.6
RELX PLC
4.4
National Grid PLC
4.3
Next PLC
4.2
Barclays PLC
4.1
Barrick Gold Corp
3.7
PRS REIT Ord
3.1
AstraZeneca PLC
3.1
OK it’s not wildly exciting stuff, but that’s exactly the point - this hardly looks high risk and being able to buy the above portfolio at 18% off their list price looks quite appealing. Discounts of that size are usually reserved for the likes of emerging markets and small caps funds etc. – not for stable quality FTSE 100 dividend stalwarts. You might not like Barclays being in there at 4% if you’re worried about the banking issues but big picture in context that’s not a huge exposure, and yes the fund is quite oil-heavy – but if you don’t mind supermajors/fossil fuels then there’s perhaps value to be had here.
Next up : RIT Capital Partners. The Rothschild family wealth fund. This venerable old fund rarely trades at a discount of any size (often at a premium in fact) and is targeted at wealth preservation and slow/steady wealth accumulation. It’s currently sitting at a 20% discount to NAV. It hasn’t been at that level (a very brief COVID panic blip aside) for at least 20 years. There is some degree of faith needed in the family and management team (but at least the family stake gives comfort on aligned interests), since a portion of the underlying investments are private/unlisted, but again this appears worth a look on a long term view.
Many of the PE trusts are on much bigger discounts, but I would not touch these unless you have detailed knowledge of the holdings – some of those discounts in the PE space could be illusory as it’s hard to know the true value of the private holdings and I suspect many of these are not correctly marked to market – hence the wide NAV discount as the market isn’t daft and knows this. But the above two (and a few others at present) are harder to fathom as to why the wide discounts.
So, the question is … are investment trusts just falling out of favour and is this a long term structural issue that is unlikely to reverse (discounts have certainly been widening for a couple of years now) or is there an opportunity here to buy some fundamentally sound long term retirement investments ‘on sale’? I tend to think there must be a natural limit to some of these discounts – after all, if a fund's assets are permanently worth 20% more than its shares, the fund can simply do some buy backs to realise value for the shareholders (or even in the extreme wind up/liquidate the fund to give everyone an immediate uplift of say 15%+ after wind up costs). As long as the underlying assets are sound, some of these discounts look too large to me and are reaching levels where the managers won’t let them get wider.
Could be a good time to have a root around in this space if looking for some lower risk collective funds to add to your spicy smallcap portfolio?
How interesting, thanks BIACS!
I've always thought that playing the premium/discount cycle on investment trusts seems a really smart way to invest, but it's not something I've ever really looked into, as I've been too busy looking for multibaggers!
So a very welcome post, thank you. Anything that helps people find credible/sensible ways to make money, is more than welcome here, as far as I'm concerned.
Best wishes, Paul.
I agree BIACS that there are some exceptional Investment Trust Investment opportunities available, with discounts overall exceptionally wide. The average discount has widened from 3% to 17% recently.
I hope this is NOT because Investment Trusts are falling out of failure as they are SO much better than Open Ended Funds, not least because the latter always trade at NAV whereas at present there are Investment Trusts trading at huge and undeserved discounts up to nearly 50%.
I.e it’s possible to buy for 50p assets worth £1….
e.g the UK Commercial Property and European Commercial Property sectors are at big discounts at present with e.g .Tritax EuroBox (LON:EBOX) at 45% discount and paying a 6%+ dividend too.
Open Ended Funds are hopeless imo for Property investing because if a lot of holders want out at the same time, and because Property can’t be sold at a drop of a hat so the Funds have no option but to ban selling and lock their investors in.
in contrast Property Investment Trusts just see heavy selling that sends the Trusts out to huge discounts until sentiment improves again (which is very likely if/when interest rates fall again). Hence the big discounts now and buy opportunities now, in many Investment Trust sectors. I.e not just Commercial Property.
I’ve no time to post more now, but I have a substantial amount of my investments in Investment Trusts across a range of Countries, Regions and sectors and hope to have time to post more later today.
For now here’s AIC link for UK Commercial Property Trusts. AIC is the official site for full information on Investment Trusts, and it’s easy to check out the Regions and sectors.
https://www.theaic.co.uk/aic/f...
and the link for Europe Property where Tritax EuroBox (LON:EBOX) and Schroder European Real Estate Investment Trust (LON:SERE) look well worth checking out. I hold both.
https://www.theaic.co.uk/aic/f...
e.g the UK Commercial Property and European Commercial Property sectors are at big discounts at present with e.g .Tritax EuroBox (LON:EBOX) at 45% discount and paying a 6%+ dividend too.
Absolutely. UK Commercial Property REIT (LON:UKCM) also worth a look. There seems to be a disconnection between yield and NAV across the property trusts. Many of these seem to have been treated as quasi-bonds, with share prices falling to compensate for interest rates rising without taking any regard to the NAV. Equally, the values of the underlying portfolios will also have fallen but the current discounts more than compensate for that.
This kind of disconnect doesn't last forever, either NAV's have to fall or share prices have to rise. The whole sector looks ripe for consolidation - Industrials REIT (LON:MLI) was bid for last week, for instance.
Plenty to look at - Helical (LON:HLCL) at a 40%+ discount or Cordiant Digital Infrastructure (LON:CORD) is an interesting play on digital infrastructure now at a discount (so is Digital 9 Infrastructure (LON:DGI9) but that's more risky). Plenty to pick from, but when some of the biggest companies in the country are on yields more common to failing small caps there's clearly something very peculiar going on.
timarr
Following up my previous post and others too, here are just a few Investment Trusts and sectors to check out for starters, in addition to those already posted by other posters today.
Again the aic site is imo the best for Investment Trusts.
ASIA PACIFIC.
Note the excellent performance from Pacific Assets Trust (LON:PAC) . It’s a growth style Trust. Check out the performance compared with sector average (those figures are at the top).
https://www.theaic.co.uk/aic/f...
BIOTECH AND HEALTH SECTOR.
Sector has been out of favour….often a good time to look to buy.
e.g Worldwide Healthcare Trust (LON:WWH) and/or International Biotechnology Trust (LON:IBT) and Blackrock Floating Rate Income Trust (NYQ:BGT)
Obviously clicking on those brings up the Stocko figures etc. Good though those are for individual shares, they are far less useful for Investment Trusts with figures I never consider but lacking must know info like discounts. So check out the aic Biotech/Health section too.
COUNTRY SPECIALIST.
e.g VinaCapital Vietnam Opportunity Fund (LON:VOF)
Vietnam is being described as the new China. VOF is a solid performer and in a 17% discount, Do check out those monthly factsheets all 3 Vietnam Trusts provide.
GLOBAL.
e.g Scottish Mortgage Investment Trust (LON:SMT)
SMT has a fabulous long term record but short term anything but for reasons well covered recently. SMT usually trades at a premium whereas recent events have seem SMT go to a rare 20% discount. Could be a very good time to look to buy.
e.g the 4 UK sectors. Loads to choose from!
UK ALL COMPANIES
UK EQUITY AND BOND INCOME
UK EQUITY INCOME and
UK SMALLER COMPANIES
It could be that many here invest mainly in UK and then mainly in UK smaller Companies coveted so brilliantly here every day. BUT there’s then the negative of being very exposed when they are out of favour. So looking to invest worldwide via Investment Trusts csn be a great way to diversify and cash in when those markets are doing well while UK might not be.
I follow the investment trust space quite closely and also like to play the discounts. Thanks for highlighting the Invesco trust - 17% discount does seem quite wide for this sort of fund (5-10% more typical for vanilla UK equity income funds), although the spread seems quite wide - would need to check that first, but generally if it's more than a couple of per cent then not much point in trying to trade it.
I'm a big fan on some of the more traditional buyout PE funds right now on close to 50% discounts so have to disagree with you on that point (Harbourvest Global Private Equity (LON:HVPE) Pantheon International (LON:PIN) ICG Enterprise Trust (LON:ICGT)) - their NAVs have always tended to be conservative, with typical uplifts of around 30% when holdings are realised. Even now, holdings are still being realised above book value. Given the fall in equity markets, many assume PE NAVs will have to fall too - however multiples on these more traditional PE funds never increased that much like they did in equity markets in 20/21 (NAV growth was largely driven by earnings) so this should give a good cushion in falling markets. Different story in the venture space, where it's very difficult to judge the accuracy of NAVs.
Thanks BIACS for this - I have always been sceptical about ITs for this very reason - the discount - though I fully agree that property simply cannot be reasonably traded via a conventional Fund. I just looked up the monthly factsheet on HL (tried to paste here but its too much) - have a look and scroll down to the percentage growth figs in comparison with Net Asset Value and FTSE All Share. Not appealing!
Aren’t you missing the point about discounts bohenie? As in the example in BIAC’s post, they mean we can buy quality assets for far less than they are worth. What’s wrong about doing that?
It’s always necessary to check performance and announcements etc too in case, as happens too, a Trust is just a lousy performer with the discount fully deserved and NOT an Investment opportunity.
At present though a lot of Trusts on big discounts are quality Trusts with excellent longer term records, that are simply on much higher discounts than normal. OR as is the case with Tritax EuroBox (LON:EBOX) and some other Commercial Property Trusts too, where the Trust has gone from a premium to a very wide discount. So much of the share price fall is for that reason and with sometimes only a modest fall in NAV or sometimes even despite an increase in NAV!
Hi Ken - Its not that simple - or maybe it is... Compare Invesco IT with Invesco UK Opps Fund. Similar portfolio but widely different results
see pic I have attached or go to HL to view.
umulative performance
With ITs you have to consider both the quality of the fund (performance, fees, fund manager, underlying portfolio, etc) and the discount (not only in absolute terms, but versus similar funds and its own typical range). Only then can you make an assessment of whether there's an opportunity. I've been following ITs for years and have had very good results just by exploiting discount opportunities. I have a fairly good knowledge of the sector and can usually quickly identify when something look cheap based on its discount.
Worth noting that alongside the more traditional equity/property funds, there are a lot of niche ITs investing in some very obscure asset classes - some of these trade on very wide discounts, although in many cases the assets are very opaque/illiquid and I generally avoid these.
bohenie.
We only have to look at the lack of recommendations for your post and my reply to you to see that readers are MUCH more interested in knowing more about Investment Trust opportunities ( lots of ticks for those posts today) than comparisons with open ended funds.
So suffice to say that which are the better can’t be decided on the basis of just one Open ended Fund against a similar Investment Trust! Also there has been plenty of research showing that Investment Trusts often outperform Open Ended Funds, including parallel Funds and Trusts.
An exception is times like now, when Investment Trusts are out of favour and going to sometimes huge discounts. Then Open Ended Funds that always trade at NAV will have won based on PAST performance. BUT for anyone looking to buy a similar Unit Trust or Investment Trust right now it’s not rocket science to realise that the Investment Trust on a 40% discount at 60p is a better buy than the Unit Trust similar alternative with a £1 buy price!
I don’t buy Investment Trusts trading at premiums to NAV. So then a similar Unit Trust alternative might be the better choice.
Note that if buying a Trust at a premium and choosing to pay more than it is worth, a big problem is if the sector goes out of favour as then there’s the double negative of the falling share price being made MUCH worse because at the same time that premium goes to a big discount. And this is exactly what has happened in the Commercial Property sector where Trusts have gone from overvalued to extreme bargain prices.
Conversely now that so many Trusts are on big and often undeserved discounts to NAV, the reverse happens. As they come back in to favour, the rising share price is given a big extra boost as the big discounts fall towards NAV.
Note this too. Tritax EuroBox (LON:EBOX) was £1.20 in August 2021 and then at a premium to NAV. Today the share price is down almost 50% to just 65p and that fall is largely because of the Premium going to a very big 45% discount. There are so many similar examples. AND it’s also why short and long term performance figures have taken a hit too.
So big discounts are often great buy opportunities. And there are buy opportunities across the Investment Trust sectors right now.
Excellent stuff BIACS. I think one of the reasons for the wide discount of the Invesco fund is that it was/is viewed as super safe and sensible - but has punished investors over the last the last 18 months. This has resulted in people giving up and going for a safe 3% on deposit. I have no doubt they will recover.
If I have one criticism of your post it is that its far too good and useful to be tucked away in a single SCVR. It should be a post in its own right.
For anyone who is interested in Investment Trusts ( I hold quite a few as I like to get exposure to PMs or strategies I couldn't otherwise access ) interesting article in IC at the weekend about the implications of the Rathbone & Investec merger regarding the trusts they overlap on and the amount they would end up owning etc .
The trusts affected by a Rathbones-Investec tie-up
Futura Medical (LON:FUM) ... looks pretty perky* already ahead of its application in all senses
*price -> there seems to be a lot of high expectation invested in this situation...and it's managed to stay admirably firm for a long time as it waits for its moment
FUM has for a long time been a 'jam tomorrow' share and Stocko has it as a momentum trap. I However,this was my choice at the start of this year for best investment. Their erectile dysfunction treatment gel is on sale in Boots as from today, FDA approval is almost certainly coming before the end of this quarter, and it is starting to be on sale in a number of markets around the world. If they can get a fraction of the Viagra market , then they will hit the analyst forecasts ( which are for a share price three times that of this mornings open). Up 10% today. Down to sales and marketing now. Good support from Dr Hilary and featured in most of the morning papers today.
Haha. I don't know it well. Justing funning with the news
Did anyone ask about the Trustpilot reviews of. Sosandar (LON:SOS) at Mello last evening?
Morning FREng,
Thanks for flagging this. I see Sosandar (LON:SOS) has received 9 bad reviews in April. Unwelcome, but for a business doing £40m revenues, so say 400k customers p.a., 9 bad reviews in a month isn't a trend. It's similar to what you see for any retailer - people are only motivated to go on TrustPilot to complain, and not many happy customers leave a review. So Sosandar's overall ratings look similar to what I would expect - nearly all 5-star or 1-star, as it's only the extremes who do reviews.
The ultimate reviews are the revenue & profit numbers!
Regards, Paul. (I hold SOS)
I hate the likes of Trust Pilot and the culture of star based reviews as I think it encourages the wrong behaviour. In my experience a customer that doesn't get their way over something (irrespective of whether they are right) will leave a 1* scathing review as revenge / anger management. Anyone that is generally satisfied won't bother and the 5* reviews are often left by brand disciples so are equally unrealistic.
And as for companies that insist on employees getting 5* reviews or risk being fired....well don't get me started on that.....appalling corporate culture behaviour based on, and designed to mislead!!!!
I agree on Paul largely .
However if he puts on his videos “I was paid to do this “
Then very reasonable to expect him to do so when posting on Stockopedia ,
Even more so in fact as he has taken a pro active decision to post on a paid members forum
You and I are both pretty active and can scratch under the surface as you say
However very clearly sone Stockopedia members didn’t know .
I'm sorry but I find this whole argument totally ridiculous. Anyone that takes anything they see or read on the internet at face value is a cretin. All I read every day on this forum are the various biases of Paul, Graham, Roland and the myriad contributors in this comments section. That's a given because I suspect most contributors are human beings, not AI chatbots, although the jury is out on some :)
What's the difference between someone getting paid a few quid to discuss a company and someone with a significant amount of their net worth in a particular company's shares? I'd say none and if anything the latter is worse but no subscriber is compelled to disclose such a position. I would suggest you read the Cialdini book on Influence if you haven't already because you might find that even your own contributions here are influencing your future actions.
Trustpilot .
It is worse than what you describe
What is little known is the mafia style tactics they employ to “persuade you to join”, extortion and blackmail is a great business model and this company is the worst I ever dealt with in 30 years
Goes like this
Non trust pilot company
- any customer can leave a review , but in reality only pissed off customer leave a review in this case , so you have 99% happy customers 1% pissed off .
- so your company ends up with an average of 1 or 2 stars
trustpilot then can you up and say “we csn help you improve your rating “ - just pay us sone money
sign up to trust pilot . Then every customer receives a nice message post sale “review us on trust pilot” and they click through and the 99% of happy customers do the job of leaving review .
you calls ask for negative reviews to be removed
Same company by 5/5 rating
sane company 99% happy 1% pissed off , as founder of Planet X I told them to get stuffed for years and our trustpilot was only ever poor , when I sold new management succumbed to the extortion and paid the fee and px are now trust pilot 5/5. Superstars . It’s extortion
Yep - and they are all like it. The holiday ones are just as bad.
From an investor perspective complete waste of time looking at them.
From a consumer perspective I will ignore 1 & 5* and only look at 2-4* as the rest is a waste of time.
From a business owners perspective looks and feels a lot like legalised extortion.
From an employees perspective - horrible
Value to society? frankly in my opinion it has negative value and should be taxed out of business.
Trip Advisor - same business model. Amazon product reviews - paid shills.
planetx
Trustpilot
" It’s extortion"
What tosh !!! no one is forced to signup to Trustpilot so i fail to see how it can be classed as extortion end of . Wouldnt disagree with the viewpoint that the fees are extortionate and their practices heavy handed but thats life with business and every business clearly has free choice whether to pay them or not - so i would take exception to that term (their legal department may too) and i am not even a holder of the stock.
How about the "we will give you a discount for a good review". I always fall for that one
Maybe before responding with “what tosh” take the time to talk to sone business owners who have been subjected to these tactics .
Pretty easy to make “what tosh” with an exclamation for effect but you are so wrong .
- if you sign up you have a clear pathway to get 99% positive reviews
- if you do not sign up this is not open to you
Furthermore the sales team of trustpilot explain this .
So in this case you speak out of ignorance and are incorrect .
Sorry
https://medium.com/@ryanbadger/how-trustpilot-extorts-businesses-91ca4b6a6f62
Read that - explanation much better than mine
Pretty easy to make “what tosh” with an exclamation for effect but you are so wrong .
No worries i fully understood what you said and have stated my point of view and i fully stick by it (no one is forced to sign up end of - infact you chose not to sign up yourself) i am happy to disagree here - plenty of room for alternative viewpoints in my world. No need to apologise if you feel you are right and i am wrong.
Worth you reading this , it’s very detailed and then you can make an informed choice of whether to stand by your view .
https://medium.com/@ryanbadger/how-trustpilot-extorts-businesses-91ca4b6a6f62
His words “extort” this time not mine , and it’s pretty damning .
My morning smallcap tweet: Success foretaste or toxic waste
Kromek (LON:KMK) Cineworld (LON:CINE) Zenova (LON:ZED) CAP XX (LON:CPX) Spectral MD Holdings (LON:SMD) Light Science Technologies Holdings (LON:LST) ASA International (LON:ASAI) Crossword Cybersecurity (LON:CCS) Triple Point Social Housing REIT (LON:SOHO) Advanced Oncotherapy (LON:AVO) Franchise Brands (LON:FRAN) Fireangel Safety Technology (LON:FA.) Induction Healthcare (LON:INHC) LifeSafe Holdings (LON:LIFS) Journeo (LON:JNEO) Porvair (LON:PRV) Volex (LON:VLX) Silver Bullet Data Services (LON:SBDS) Futura Medical (LON:FUM) N4 Pharma (LON:N4P)
◄Kromek (KMK)► seven-year agreement with a Tier 1 OEM to develop CZT-based detectors. No £££. Trading in line. [SP=5.5 Cap=24m]
◄Cineworld (CINE)► fails to sell 'Rest of World' business for a value level required by its lenders. [SP=0.91 Cap=13m]
◄Zenova (ZED)► gets £300k order from distributor Zensafe for sale via Amazon. [SP=7.1 Cap=7m]
◄CAP-XX (CPX)► Continental Automotive GmbH, a global Tier 1 automotive supplier, has granted the Part Submission Warrant to CAP-XX. [SP=2 Cap=10m]
◄Spectral MD (SMD)► $4m award from the Medical Technology Enterprise Consortium as funding to support military battlefield burn evaluation via a handheld DeepView. [SP=48 Cap=66m]
◄Light Science Technologies (LST)► £1.6m placing at 1p, a 17% discount. [SP=1.15 Cap=2m]
◄ASA International (ASAI)► Jan-Mar update. All subsidiaries had collection efficiency of more than 90% with 10 countries more than 95% with the exception of India and Nigeria. [SP=85 Cap=86m]
◄Crossword Cybersecurity (CCS)► wo UK universities have gone live with co's third party supply chain assurance platform Rizikon Assurance. [SP=9.97 Cap=9m]
◄Triple Point Social Housing REIT (SOHO)► share buyback. [SP=48.15 Cap=195m]
◄Advanced Oncotherapy (AVO)► strategic review, update on financing discussions & formal sale process. Looking at a possible sale to NASDAQ quoted corporate vehicles. Will review potential partners with the technical expertise, strategic mindset and financial backing. Loan note talks. [SP=2.5 Cap=13m]
◄Franchise Brands (FRAN)► AGM stmt: good start to 2023. [SP=188.95 Cap=246m]
◄FireAngel Safety Technology (FA.)► re delivery and production agreements with Techem Energy Services. "The total income opportunity for FireAngel has grown significantly to an aggregate of up to c.$7.50 per alarm (comprising fees, royalties, and purchase price of the Company's own CO sensor)." Total opportunity has now increased to up to $53m from $38m. Shipments to start in 2024. [SP=10.15 Cap=18m]
◄Induction Healthcare (INHC)► guides FY-Mar rev up 12%. On track to hit objectives of self-sustaining growth and cash breakeven in 2024.. [SP=20.75 Cap=19m]
◄LifeSafe (LIFS)► launches new StaySafe All-in-1 fire extinguisher with 'next generation fluid'. [SP=31.2 Cap=7m]
◄Journeo (JNEO)► 1-year extension to April 2024 for framework agreement with Arriva UK Bus. Expected to generate c.£1.1m. Supports the Company's medium term growth expectations. [SP=177 Cap=29m]
◄Porvair (PRV)► AGM stmt: last 4 months LFL constant currency revenue growth was 8%. Order book up on all previous years. [SP=602 Cap=279m]
◄Volex (VLX)► guides FY-Apr ahead of market expectations. Rev up at least 15.5%. U/L op profit at least 17.4% higher. [SP=212.55 Cap=338m]
◄Silver Bullet Data Services (SBDS)► Q1 rev up over 100%. In line? Significant visibility for expected revenues for the full year. [SP=48 Cap=8m]
◄Futura Medical (FUM)► MED3000, under the brand name Eroxon, is now available for purchase in the UK. Stocked by Boots. [SP=43.31 Cap=125m]
◄N4 Pharma (N4P)► siRNA update. We are very pleased with the EGFR results which show excellent knockdown of the siRNA..." [SP=2.02 Cap=5m]
Morning all! Sorry to jump the gun, but I'm impressed with FY 3/2023 TU from £vlx
H2 revenue actually dropped slightly from H1 (H1: $357.5m, H2 $352.5m) = $710m+ FY
However, margins rose (H1: 9.0%, H2: 9.6%) underlying operating profit margins.
Annoyingly, the update quotes a profit measure that is *not* quoted in the last Singers note (from Nov 2022). So we have to manually work it out, which I've done, as follows:
Underlying operating profit of $66m turns into u/l profit before tax of $60m (assuming the differences in H1 are unchanged in H2)
Assuming same tax charge %, then I estimate EPS as H1 actual: 14.4c, H2 est: 15.3c, FY 3/2023: 29.7c
Translate into sterling, gives 24.0p EPS (my estimate, based on today's TU)
With net debt strikingly lower than forecast at $76m (Singers last forecast was $102m) and only 1.0x EBITDA, nobody needs to worry about debt, and not much of an adjustment is needed for valuation purposes.
Outlook sounds perky.
How to value it? I can't see why we wouldn't apply a PER of say 12-14. That would give a valuation of 288p to 336p. So at just over 200p last night, this share looks significantly under-priced, and should logically be a 20-30% riser today, I reckon.
Complaints - why has Volex left it over 5 months from the last trading update? That's a yawning gap, and causes shareholders to worry. So it needs to introduce another trading update in between this too-long gap in future.
Why does the trading update quote underlying operating profit, which is a measure that Singers does not include in its forecasts? It needs to quote u/l PBT, and EPS in trading updates too.
Overall, this looks terrific, and VLX shareholders are going to be rewarded nicely for their loyalty, I reckon. Well done to holders!
Regards, Paul.
P.S. Singers note has just come through. They've estimated 27.4c for FY 3/2023, so a little lower than my guesswork above. Not sure what the reconciling items are - they're probably building in a little caution, so actuals beat slightly?
Are you buying back in to Volex?
Are you buying back in to Volex?
No, not yet - no available funds. I'm very frustrated at the moment, as my new policy of zero gearing, means I have to sell something else before I can buy things I like.
VLX is on my previously published 2023 top 20 watchlist ideas, so I'm glad it's come back to breakeven, as with Wincanton (LON:WIN) it was the only significant loser YTD on my list.
Regards, Paul.
Wincanton (LON:WIN) was a bit of a milestone for me. I bought a full holding (4% of portfolio) at 299 in February, not just because of Paul's views because I definitely do my own research, of which Stocko analysis is only a part. I managed to sell at 229 on the morning of the profit warning for a loss of 23% and it's not recovered to that price since. Having seen how sensitive it is to individual large contracts I regard the company as being pretty close to bargepole status along with civil engineering contractors and, frankly, the majority of the UK smallcap market. The trouble is, I had pointed to one of their trucks the day before and remarked to my wife that we owned shares in the business. Her confidence in my ability to manage our investments had already declined significantly and is now at rock bottom. I have spent years trying to convince her that the stock exchange isn't a casino and I have failed.
Hi Michael C,
Very amusing! I have a similar reaction with some of my friends - I explained in detail to some friends outside the financial world, about all the analysis I do, and writing reports. They summed up by saying: so what you and your friends do is "posh gambling" then?
Of course I vehemently rebutted their view, but on the way home thought to myself that they do have a point!
As regards Wincanton (LON:WIN) it's the only 1 item out of 20 on my 2023 top small cap watchlist best value/GARP ideas that is significantly down. Here is the original list.
EDIT: and here is the live spreadsheet, that keeps track of live prices.
I put a lot of thought into the list, and was resigned to there being some profit warnings in 2023 on that list. WIN did surprise me as the first one to trip. But as you say, it seems to have been heavily reliant on individual contracts.
Although I deliberately picked things that would possibly be more appealing value, to buy more, if they had a setback. I'm tempted to buy some WIN, but don't have enough cash to spread around all the ideas I like, and want to keep quite concentrated, so that the winners move the dial enough to make it worthwhile.
The whole portfolio is up 12% year-to-date - very good I think, since small caps are flattish year-to-date.
The top 5 in my 2023 top 20 have done very nicely -
.
As for the bottom 5, out of 20 - surprisingly few disasters, especially since VLX recovered sharply today, eliminating a c.20% loss instantly -
I really should properly update the comments columns.
All the entries are static, so nothing is amended after original publication, as that would be cheating!
4 months is nothing in the overall scheme of things, but it's still a good start, in a static market overall for small caps.
The risers have been due to good announcements & performance, not due to their presence on a commentators list!
Regards, Paul.
Tatton Asset Management (LON:TAM) "Organic growth train rumbles on with inflows +40%" -
new research note with audio summary: https://www.equitydevelopment....
FY23 AUM closed on £12.7bn (on 31 Mar 23), +12% y-o-y on a like-for-like basis (31 Mar 22: £11.3bn), and well ahead of our previous forecast of £12.2bn. Adding 8AM Global’s assets brings Assets Under Influence up to £13.8bn (Tatton acquired 50% of 8AM in Aug 22).
But most impressively, the bulk of growth came from exceptionally strong net flows of +£1.8bn (16% of opening AUM and +40% y-o-y), with momentum through the year (H1: +£907m; H2: +£887m). Tatton’s ability to attract and retain assets has been far above peers in recent years. It clearly has a strong strategic positioning and is gaining market share.
Our FY23 rev. forecast rises to £31.1m from £30.6m (FY24: £35.0m from £34.0m) and our FY23 adj. operating profit to £15.8m from £15.1m (FY24: £17.9m from £17.8m). We also highlight that Tatton is ahead of its medium-term growth plan. Our core value rises from 500p to 560p per share.
Equity
Thanks for the post
Can you clarify if these are clients paying you a fee to “present them to the investing public “
Volex (LON:VLX) How much are the adjustments?
Notes:
1. Underlying operating profit is before adjusting items which are one-off in nature and significant (such as restructuring costs, impairment charges or acquisition-related costs), the amortisation and impairment of acquired intangible assets and share-based payment charges. This trading update is based upon unaudited management accounts information. Forward-looking statements have been made by the Directors in good faith using information available up until the date that they approved this statement. Forward-looking statements should be regarded with caution because of the inherent uncertainties in economic trends and business risks.
re: volex Volex (LON:VLX)
given the amount of acquisitions they have done (funded by debt and equity raising i.e share issuance) and the amount of share-based comp that they have dished out, both leading to significant share dilution- the shares have nearly doubled in the past 5 years! - those adjustments will be interesting to see and i expect they will be chunky
acquisitions, amortization and share-based comp are all very real costs to a business after all, and no amount of handwringing or account presentation or glossing over will change that e.g presenting them as 'one offs' when they clearly aren't in this case
additionally, all that goodwill has bloated the assets; they have more than tripled in 5 years vs revenue/sales which has only just doubled. this will lead to worse returns on capital as the decade goes on if this trend continues as, simply put, you are earning less revenue (and by extension profits) against a larger asset base
add in all of that + the 25% main shareholder (nat r.) who clearly is not particularly bothered about the stock-based comp, massive increase in debt, dilution of minor shareholders etc...you can probably tell i'm not a fan lol
REF -concerns over postings policy .
Was mulling over sone postings yesterday and something is not sitting right .
As a relatively frequent contributor you get a good feeling from other posters and there are some experienced investors with good knowledge especially useful in areas where you have no knowledge .
What is alarming and personally I think needs addressing is any comments made , or even more concerning threads started by posters who are analysts paid to “present “ (kind ). / promote (less kind) ramp (harsh) a company .
This is not right and should not be allowed IMHO unless accompanied with a clear precursor .
What winds me up is then the old “we maintain a fair value of “blah blah “ which is inevitably far higher than share price .
The final kicker is the old DYOR which I find a cliche and not appropriate when the the thread has been started .
I’m only directly aware of Equity developments / Paul Hill (who I rate) but on reflection I don’t this it is good form to post comments on a company you are paid to represent without the clarification .
Certainly most posters here do usually say “I hold” when discussing their holdings as it gives a biased opinion maybe , certainly “I’m paid “ is ten times more of an incentive .
No if that is happening it is deceitful and misleading. I do like the fact that many people do declare their interest, especially Paul. Not sure what Stocko can do about this if people abuse the forum?
I don’t think it is particularly deceitful and misleading at the moment as the guidelines / rules have not been clearly set in place .
It is such an easy fix , just make it a simple rule .
I’m sure Paul Hill / Equity developments who are very professional people / companies will be 100% happy to comply .
If you watch the videos put out by Justin and Paul, you will notice certain companies like Venture Life (LON:VLG) appear in their talks every time. Paul is very bullish on this one (and others like Saietta (LON:SED) Totally (LON:TLY) among others) and you would easily be mistaken to believe he is a holder. Yet he is not, which begs to believe he is just paid to ramp these or otherwise he would certainly be a holder. And if he is not a holder, why not say what he really thinks of the companies and why he really does not think they are good enough to hold. Makes me believe I can not trust a word that comes out of his mouth on any company reported. Having spoken to Jerry Randell from Venture Life (LON:VLG) on several occasions, I trust the CEO as far as I could throw him and have found him to say the things you would want to hear and not to say the truth.
Sorry but to be fair to Paul Hill he (a) says when he is long and (b) publishes his portfolio quite openly if anyone bothers to scratch even remotely under the surface. He is very concentrated to around 10 stocks so the fact that he doesn't hold all companies he rates is more a function of his portfolio construction than a damning indictment of being paid to ramp, which is what you are suggesting. If you only own 10 stocks that doesn't mean you can't like another 20 for heavens sake.
He, like the rest of us won't get everything right but has never struck me as disingenuous. You don't have to agree with his analysis but at least it's out there and you can use it alongside other research to evaluate a stock.
Note. He also already puts "I was paid to do this by......" on the videos he publishes.
David
I agree on Paul largely .
However if he puts on his videos “I was paid to do this “
Then very reasonable to expect him to do so when posting on Stockopedia ,
Even more so in fact as he has taken a pro active decision to post on a paid members forum
You and I are both pretty active and can scratch under the surface as you say
However very clearly sone Stockopedia members didn’t know .
It’s so easy to fix
If I was to take a retainer ftom titon say to increase their public profile and post on here and various bulletin boards
A/ “I maintain a fair value of 2 pounds a share and the share price is significantly undevalued “
B/“I maintain a fair value of 2 pounds a share and the share price is significantly undevalued “
and they are paying me 5k a month retainer for investor relations
very different
Re Paul Hill and many others...its really simple...
There's no shame in owning dross
There's no honour in pumping dross
Unless you fancy yourself as the nimble sort that is going to play the emotional flows of micro cap markets (and be able to avoid the potential liquidity blows that come with that) and think you can successfully fade the Hill Shill etc then I do not understand why you would look at and take some content/comfort from this sort of unashamed shilling.
NOTE: Equity Development, PI World/Tamzin, Investor Meet Company and others like them provide a valuable service whereby they provide detailed analysis (not glib shilling) or a full communication platform for cos to communicate with private investors AND its clear they are paid to do it. Obvs you are a fool if you take their views or recommendations unquestioningly but information can be parsed by the intelligent/diligent (yes they might not platform the thornier areas if their clients don't want to go there!)...whereas a pump is always just a pump
I, probably naively, didn't know this was even happening. I just assumed all comments on here were people's honest opinions.
Has made me think very differently about how much I can trust the site.
You shouldn't be "trusting" anything. But I have some comments
1)The fact that the likes of Paul Hill, Tamzin, Equity Development all provide valuable services to the investment community should be applauded rather than vilified.
2) They post under a name you already recognise so you know what they do for a living and can take/leave it at your own discretion
3) The fact that they post under their own name is open and transparent. Anyone with a subscription could be on here paid to promote and you wouldn't have a clue. Those are the ones you should be concerned about rather than the likes of the 3 you are throwing stones at and frankly no "policy" would stop that anyway.
The point of this board is to get analysis on an under researched sector of the market and it is done very well. Nobody here should be buying because anyone else does. It should add an edge to your own investment dynamic because people will challenge your assumptions/assertions and make you think as well as offering up some nuggets of value when looking for ideas.
could not agree more David . I think people like Paul and Equity Development do us all a great service which is , after all, free . One must always do one’s own research on any stock held, which would include taking into account the views of people like Paul , our Paul, Roland Graham etc etc . Part of the fun for me in owning stock ( and selling it) is the research involved.
I posted recently about this subject, as I found that the postings from 'advisors' were not transparent enough. I think that EQ has taken this onboard a bit, as the posts are clearer. Could this go further ? - maybe. It is interesting as I don't get any bad vibes from PIWorld - I find that Tamzin is doing her thing, and that as an investment community we need the sort of information that she is providing. Their posts are always clear and objective and dont go any further with regards to personal opinions about the companies presented. There are other advisors where their opinions are mixed in with presented information in a way that is slightly more questionable. Great to have the discussion about it ! - this is a subscription only bulletin board after all.
edit : for clarity I have no affiliation to PiWorld !!! :o) - and my investment advice is certainly not worth reading !
Davidjhill I've not mentioned anyone by name, I'm not sure why you are saying I'm throwing stones at 3 people in particular?
Of course everyone should do their own research and not blindly follow people online. I don't think that's the point of the original post.
It is seen as good practice to say 'I hold' to show there could be unintentional bias when giving an opinion. Shouldn't there then also be something along the lines of A fee was received for this post to show there could be unintentional bias.
FWIW I don't say 'I hold' when I make a comment on a stock I own. I find this phrase a bit irritating TBH and it usually only comes with stocks that do well and is part of the self backslapping people like to indulge in to plump up ego! But I'm happy to do that if it becomes the established etiquette even if I don't think its helpful in a setting like this.
Mostly I don't comment on stocks I own as 1) I don't want to anchor myself and 2) do I need to write a mea culpa if it goes wrong or flag I've exited for any reason? (tricky!). When I do its usually obvious I own tho. And perversely, I'm more likely to comment on the stocks I own that are controversial or where I might have doubts. Partly seeking contradiction and partly by outing myself I might shame myself into sense.
But 'ramping' or 'shilling' - I can't easily define it but I feel pretty confident I know it when I see it.
However as moany points out, much of this conversation is kind of a reflection of our own biases and angsts and is thoroughly post modern ;) (Nevertheless I will retain the right to call ramping when I believe I see it)
David
I’m going to have to respectfully disagree with you .
It’s such a simple thing to sort and request .
The fact is Paul hill puts these on his videos but not on posts on “our “ forum shows my thought process has merits
I’m fine either way and I have the right every time they post to raise the point they are getting paid which will become quite annoying
Anyway enough from me on this
Hi Planetx. I agree with you and would like to have more transparency on Stockopedia in this area. I would suggest the following changes be made for people who are paid to promote / represent other companies; 1) The name shown above the post should be in a format such as "John Furlonger on behalf of Equity Promotion Ltd" 2) The name shown above the post should be shown in a different colour to the names of persons who are not being paid to comment.
I think commentaries provided by people who are paid to comment are worth having and can be informative so I would not like to see them banned.
We probably also need a third colour for the names of people who are paid by Stockopedia to provide commentary on here. Eg Paul Scott and his colleagues.
So there would be three classes of names: 1) Subscribers who pay to use Stockopedia. 2) Employees or contractors paid by Stockopedia. 3) Persons who are paid directly or indirectly to represent the interests of the company that they are posting about or commenting on.
Property Franchise (LON:TPFG)
Superb FY22 results today, ahead of expectations on every metric. PE 10 yield >5%. Haven't seen any updated forecasts for FY23 but they say Q1 23 which is a seasonally quiet period is trading ahead of expectations on profit and sales.
Webinar today at 1pm. Register here.
Yesterday, we published the Windward (LON:WNWD) full year 2022 results presentation to analysts. Valued on 1x 2024 EV/Sales multiple. Canaccord have a target price of 115p. They are now focussed on moving to EBITDA positive, investment in FY22 should mark the high point and reduce from here. Video & podcast.
Tamzin
Ref my post above
For the sake of clarity are the companies mentioned here clients paying you / your employer / your company a fee .
I’m guessing so .
No problem if they are but for me I think this needs to be clearly stated that you are paid to represent these companies and help them present themselves to investors .
Sorry, I have only just seen this! PIWORLD is a production company, so we handle the video production / live stream / webinar / filmed interview / on site filming / AV of any sort, for companies who want to engage with investors. Not all that we produce goes out on PIWORLD. PIWORLD.co.uk is the distribution platform for our content. Over our history we have done a lot of free interviews for investors, these are listed on the 'Education' part of the website. On the 'Companies' part of the website are investor relations videos which we have been paid to produce by companies as part of their investor relations, and on the events page, these are events which we are paid to run by the companies and we produce a video of these. Although I am an investor, when posting our material here or on social media, I try to remain factual, generally using the company's words used in their announcement. I'm not trying to pump companies. We started PIWORLD because at the time, back in 2015, there was very little opportunity for retail investors to meet companies. From my experience as an investor, seeing management present was very valuable, and we wanted to make that opportunity available to a wider audience of investors. At the time, there were almost no small cap company videos, thankfully there is now both the appetite of companies to want to communicate with retail investors and a lot of great content, which investors can access to aid their research. Going forward, I hope all companies, irrespective of market cap size, put a recording (video or audio) of their analyst presentations on their website. This is standard in the US.
Property Franchise (LON:TPFG) Not sure they beat on every metric per Sharepad forecasts:
Act EBIT= £9.3m versus Forecast £10.4m
Act PBT = £8.8m versus Forecast £10.1m
Act PAT = £7.2m versus Forecast £8.2m
Morning All,
Fantastic update from £VLX! At odds with recent price action, completely mis priced. Should be a strong move up today.
You never know with markets in a punishing mood JohnDoe2368 but I agree with you, what's not to like with that TU! I hope Graham or Roland have time to cover Volex today.
Morning JASVFS - Volex is indeed on the menu! Graham