Small Cap Value Report (Mon 12 Aug 2024) - SUS, MSLH, SRAD, TIG

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Summaries
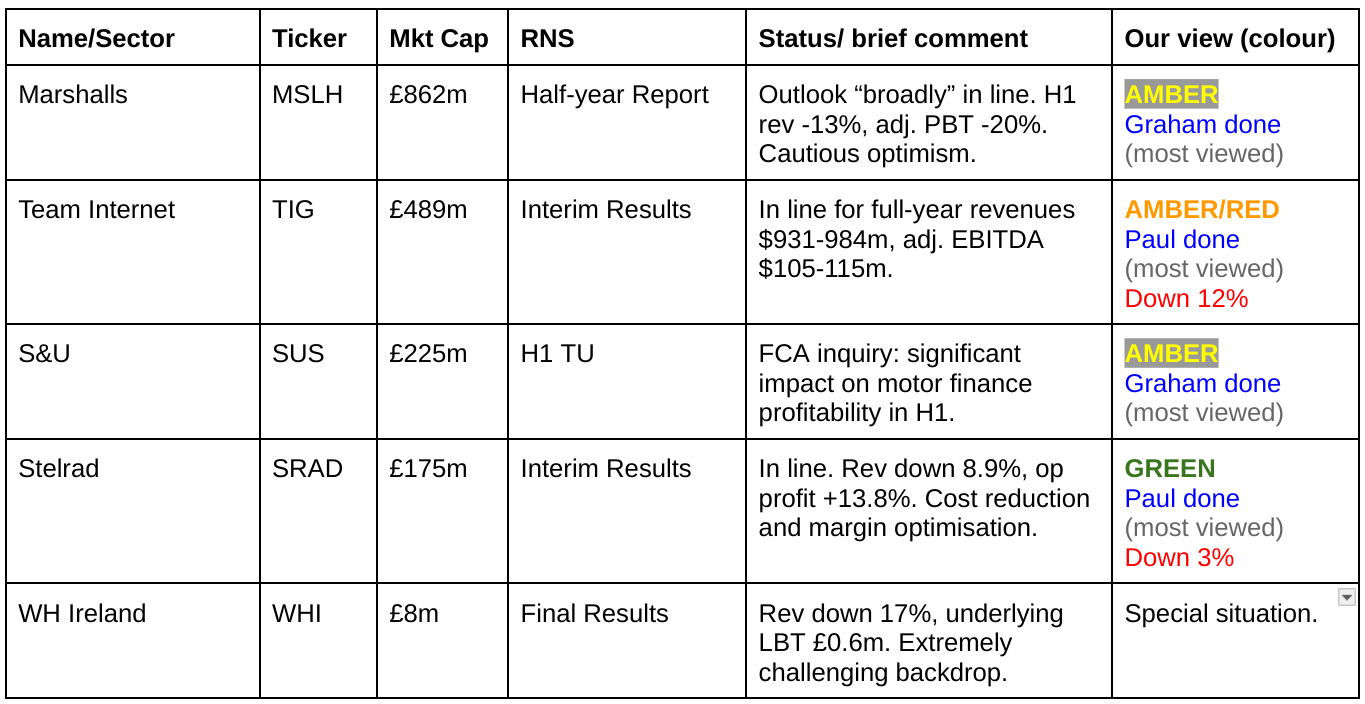
S&U (LON:SUS) - up 0.5% to £18.95 (£230m) - Trading Update - Graham - AMBER
Plenty of optimism from management here that performance will rebound in H2. I’m a long-term fan of this business and I believe and expect that they will emerge in good shape, but I wish to remain disciplined while the Skilled Person Review/FCA inquiry is ongoing. I’m also a little concerned by the company’s high utilisation of its existing debt facilities (£240m out of £280m), and the large drop-off in up-to-date collections.
Marshalls (LON:MSLH) - down 1% to 336.8p (£852m) - Half-year Report - Graham - AMBER
Unpleasant numbers with more negative operational leverage dragging on profits. Full-year results are expected “broadly in line” (i.e. a slight miss). More positively, net debt and the leverage multiple have reduced slightly. I do like this company but it seems to me that the wider investor community shares this positive view and has priced the shares at an accordingly high level.
Stelrad (LON:SRAD) - down 2% to 137p (£174m) - Interim Results - Paul - GREEN
I maintain my positive view of this maker/distributor of radiators. Improved operating margins have offset reduced revenue in H1, which is impressive. The balance sheet isn't perfect, with more debt than I'd like, but half is supported by freehold property. A reasonable PER, and a good dividend yield, plus there should be decent further upside on SRAD shares once its markets recover.
Team Internet (LON:TIG) - down 15% to 162p (£420m) - Interim Results - Paul - AMBER/RED
A rather questionable business model, in my view - will profits be sustainable long-term? Very weak balance sheet, with far too much debt, hence why divis are only small. It's been doing share buybacks using increased debt, which I disapprove of. I am biased against this sector, as I've seen many internet-based advertising companies go badly wrong.
Paul’s Section:
Team Internet (LON:TIG)
Down 15% to 162p (£420m) - Interim Results - Paul - AMBER/RED
We’re overdue a review of this collection of businesses that has often struggled to explain clearly what it actually does, as you can see below -
“Team Internet Group Plc (AIM: TIG, OTCQX: TIGXF), the global internet company that generates recurring revenue from creating meaningful and successful connections: businesses to domains, brands to consumers, publishers to advertisers, is pleased to announce its unaudited financial results for the six months ended 30 June 2024 ("H1 2024").”
About a third of net revenue comes from selling domain names. The remaining two thirds comes from online marketing, which seems to be advertorial and review websites - which doesn’t appeal to me, as I’ve seen so many online marketing companies go badly wrong in the past. These businesses tend to be vulnerable to changes in algorithms by eg google, so it’s a space I’ve tended to very much avoid. Shares in this area often look superficially cheap, with low PERs, often with rather opaque accounts.
Its previous name was Central NIC (CNIC), since changed to Team Internet.
I last reviewed it a year ago, here on 14/8/2024 H1 2023 results, coming out moderately negative at AMBER/RED, due to balance sheet & debt concerns, also whether its business model is sustainable?
The company’s headline sounds perky, so why are its shares down 15% today? -
“Year-on-year growth in all key financial metrics including a 7% increase in net revenue, 13% increase in operating profit and an 8% increase in profit before tax”
Profit -
“Profit before tax increased by 8% to USD 14.4m (H1 2023: USD 13.3m)
Adjusted EPS (diluted) increased by 12% to USD 10.74 cents (H1 2023 restated(iii): USD 9.63 cents)”
That doesn’t sound a lot for a company valued at £420m.
Although there is a large amortisation charge, which Zeus adjust out in their useful note today, with est. adj PBT of $92.8m for FY 12/2024. Zeus says that TIG is the cheapest tech share in its index.
Outlook - is in line -
"Team Internet has once again delivered a strong quarter, with growth in both adjusted and statutory earnings. Although the Group prioritises earnings growth over top-line growth, a robust 9% organic revenue growth has been maintained on a pro forma basis for TTM 2024. Adjusted EBITDA conversion remained healthy at 48% (H1 2023: 49%) of net revenue, demonstrating continued strong profit margins.
The Directors remain confident in the Group's strategic investments in product innovation, vertical integration, and international expansion. These initiatives have positioned the Group for success. Given these strong foundations, the Directors are confident that the Group will meet market expectations for the full year.(vi)”
Balance sheet - remains weak. NAV is $142m, but that includes $338m intangible assets. So NTAV is horrible, at negative $(196)m. That rules this share out for me.
Cashflow statement - all of the cash generated in H1 was spent on an acquisition. So this means that shareholder returns of divis & buybacks, were funded through increased debt. I’ve flagged before that I think with its highly indebted balance sheet, TIG should not be doing share buybacks funded through debt.
Interest on the heavy debt burden in expensive too, at around $12m pa.
Director trades - seem to mainly be M Royde buying, who is connected to major shareholder Kestrel who own 25.8%. Note that Slater are also involved here, with 11.6%, so some heavyweight investors clearly like this share.
Other Directors have been sellers though, with several £7-figure Director sells in recent years.
Paul’s opinion - my concerns are unchanged - a weak, heavily indebted balance sheet mainly. Also I just don’t rate this sector at all - these internet advertising businesses can be very vulnerable to changes that are outside of their control. It tends to be a fast-moving space, where business models can wither away, or suddenly collapse. Hence they are often doing M&A, trying to find the next big thing. Note that dividends are negligible, and they have to ask the permission of the bank to pay them.
This might infuriate some readers, but I’m sticking with AMBER/RED, due to my various concerns.
On the upside, the fwd PER of 8.7x does look superficially cheap, if you’re happy to ignore the weak, indebted balance sheet.
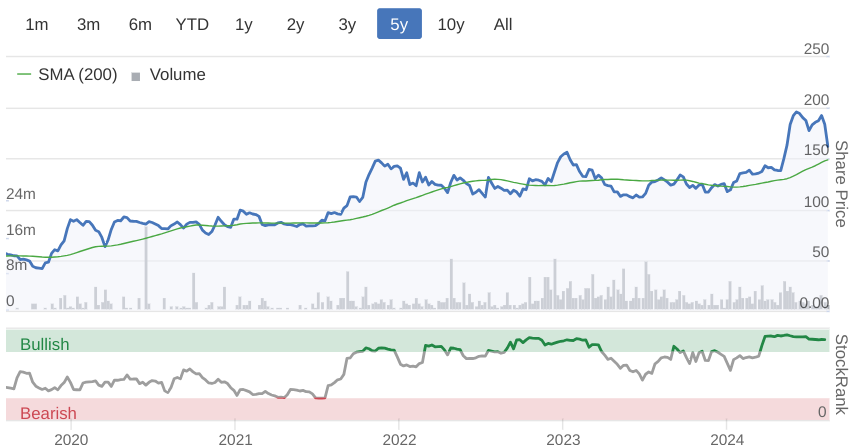
Also shares have done OK long-term, roughly tripling since the 2019 lows.
Stelrad (LON:SRAD)
Down 2% to 137p (£174m) - Interim Results - Paul - GREEN
Stelrad Group plc ("Stelrad" or "the Group" or "the Company", LSE: SRAD), a leading specialist manufacturer and distributor of radiators in the UK, Europe and Turkey, today announces its unaudited interim results for the six months ended 30 June 2024.
Strong performance; on target for full year outlook
Checking my previous notes this year -
29/01/2024 - AMBER/GREEN at 128p - in line TU & fairly upbeat outlook. Looks well set up for a sector recovery. Main downside is high debt.
11/03/2024 - GREEN at 112p - FY 12/2023 Results - looks a nice cyclical recovery value share.
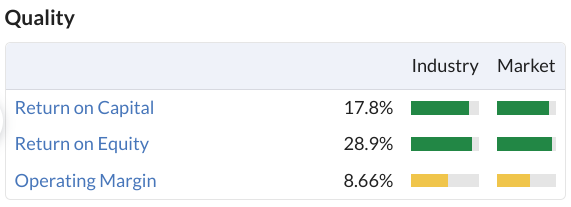
SRAD was a 2021 float - the infamous year when brokers killed the UK IPO market by floating overpriced and often poor quality companies. SRAD was certainly an over-priced IPO, but it seems a decent quality company to me, priced attractively (PER 9.8x and 5.5% divi yield, and although debt looked high so I’ll check that carefully now) -
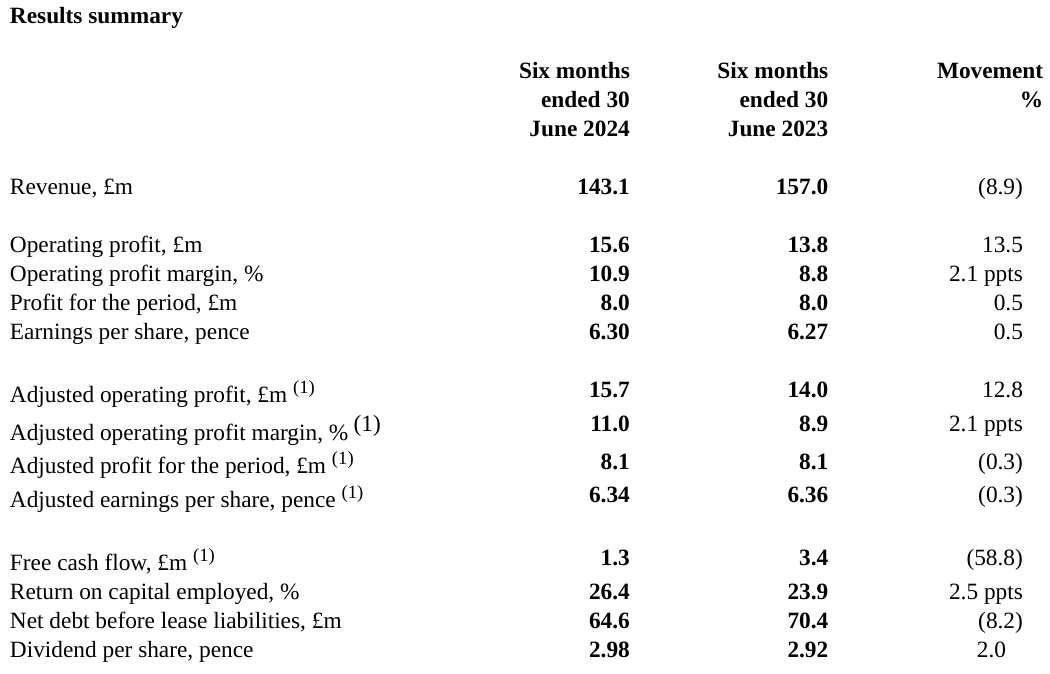
The latest H1 results show a story of reduced revenues, but offset by a higher operating margin, leading to adj PBT and adj EPS (my preferred measures) flat at £8.1m and 6.3p. This is just H1 remember, so full year numbers are about double -
I see net debt has come down 8%, but still looks high at £64.6m. The commentary says June half year end is a seasonal high for working capital, so debt should be reduced by Dec year end. Debt is more expensive now of course, note that in 2023 finance charges consumed 28% of operating profit.
Maybe it should cut the divis to de-gear faster? Although a gearing multiple of 1.49x is not in danger territory.
Summary/outlook -
"Stelrad's performance during the period, particularly in terms of market share growth and growth in contribution per radiator, combined with cost base reduction and ongoing margin optimisation actions, demonstrates the strength of our business model, and further underpins the Board's confidence in the outlook for the full year.
"Stelrad remains well positioned for a sustained period of profitable growth as markets recover across our core geographies, with the Group well placed to benefit from strong underlying replacement demand across Europe and the long-term regulatory tailwinds for decarbonised, energy-efficient heating systems."
The Group's outlook for the full year remains unchanged with the Board remaining confident in its long-term growth plans.
While challenging economic conditions across the Group's key territories have begun to show indicators of easing, interest rates remain elevated, which continues to subdue both RMI and new build markets for now.
There have been some early indicators of a recovery in the volumes in some of the Group's European territories, with recent volume increases in Belgium, the Netherlands, Poland and Sweden.
Valuation - no broker notes are available I’m afraid, but we do have the broker consensus figures on the StockReport, showing 12.7p for FY 12/2024 and 15.2p for FY 12/2025. We shouldn’t go crazy on the PER multiple to apply, due to significant net debt. So I’d be happy with 12x, hence a price target for me of 152p, rising to 182p on 2025 estimate.
Hence the current share price of 137p looks reasonable, and should have further upside as its markets recover hopefully in 2025, which is what the UK housebuilders are telling us to expect.
Balance sheet - NTAV is £50m.
It’s a capital-intensive business, with £82m in fixed assets. Checking note 17 in the 2023 annual report, I’m delighted to see freehold property of £31.5m. I often offset this against net debt, so looking at it this way, almost half the net bank debt is supported by freehold property assets.
Inventories seem high at £70.5m, which works out at just over a third of full year cost of sales. So a question to ask management would be whether they are holding too many stock lines, and if the business could be run more efficiently and at lower borrowing costs by slimming down the large inventories?
Gross long term bank debt of £89.6m stands out as too high for comfort.
Overall then I find the balance sheet a little troubling, but it’s not a deal-breaker.
Cashflow statement - impresses me. SRAD is managing to not only service its high debts, but also gradually reduce them, whilst funding capex and generous divis. This looks a decently cash generative business. Although as its markets recover, more cash could be sucked into working capital in future, hence why I’d like to see a greater focus on keeping inventories under tighter control.
Paul’s opinion - I’m happy to stick at GREEN.
This strikes me as a good candidate to add to the research list for building supplies companies that should benefit from a cyclical upturn in their markets.
SRAD seems sensibly priced, with pretty good potential upside, and seems to have traded well, improving margins, despite tough macro conditions. That’s very much what I look for in cyclical recovery investments.
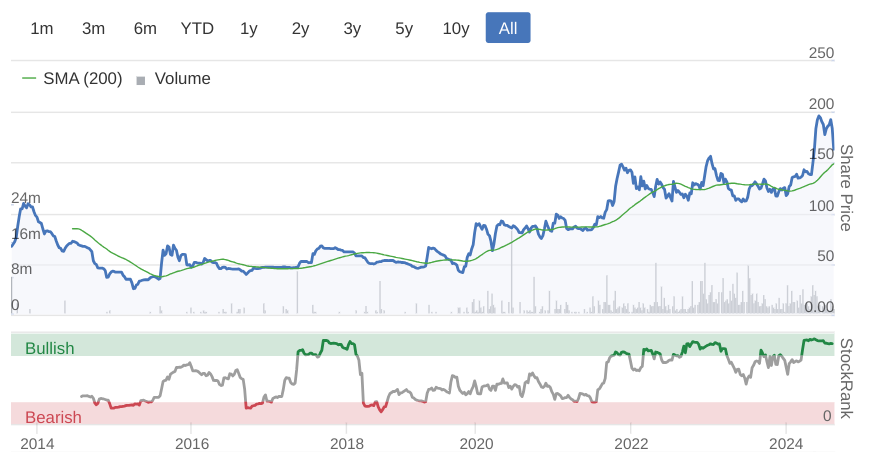
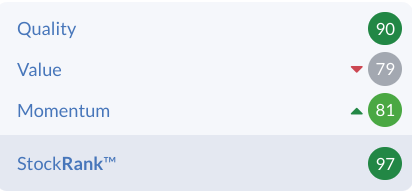
We also have the comfort of a very high StockRank -
Graham's Section
S&U (LON:SUS)
Up 0.5% to £18.95 (£230m) - Trading Update - Graham - AMBER
S&U PLC, the specialist motor and property finance lender, today issues its trading update for the period from its AGM statement on 6 June 2024 to 31 July 2024. S&U will announce its half year results on 8 October 2024.
We had a good discussion here on the topic of Jarvis Securities (LON:JIM) and its FCA-ordered “Skilled Person Review” last week.
The experience with JIM has taught me to treat Skilled Person Reviews with the utmost caution from a shareholder perspective.
S&U is also in the throes of this type of review, although it can’t bring itself to use the phrase Skilled Person in today’s H1 trading update.
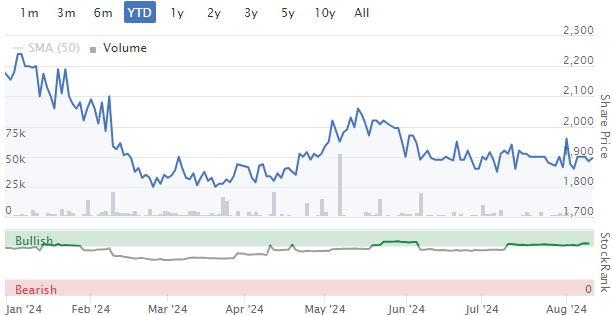
This review was announced back in December, causing me to reluctantly switch to a neutral stance on this stock.
I’m glad that in this case at least, I seem to have found the necessary caution:
Let’s get into today’s update.
Firstly, on the subject of the review itself.
S&U has restrictions on its ability to trade during the review, however: “constructive but vigorous negotiations [are] taking place to remove the restrictions, which are now nearing their conclusion”.
S&U expect a “sensible and proportionate conclusion” to the process.
They berate the regulatory regime and urge Labour ministers to deliver change.
Motor Finance (Advantage Finance):
“ restrictions on managing customer arrears and on repossessions have seen a year to date level of 87% repayments to due, from 94% last year”
“Up-to-date live receivables have fallen to 69% of the total, from 79% last year, although a release from current restrictions should see a bounce back in the second half of this year.”
At the AGM statement in June, we were told that collections in Q1 were 87.7% of due. With a year-to-date level of 87%, that suggests a slight deterioration.
The “up-to-date live receivables” figure of 69% is scary to me, since that is a drop of 10% (from 79% last year) and the total receivables book here is £327m. So there’s £30m+ of additional receivables that have a question mark hanging over them.
Property Lending (Aspen Bridging)
This division is unaffected by the FCA review and it continues to grow:
..A firming residential property sector, a recent fall in interest rates and a youthful and dynamic team have seen record profits achieved in June (more than double last year) followed by good results in July too…
The Aspen loan book now stands at around £149m (31st July 2023: £104m).. The deal pipeline is good and we anticipate further steady growth in the second half of the year. Credit quality remains excellent…
I’ve always valued S&U on the basis of prospects at Advantage, but perhaps it’s time to start treating Aspen as a major division with long-term prospects that could rival Advantage?
Borrowings have increased to £240m (vs £224m at year-end Jan 2024, £184m a year ago).
This is said to be “well within current committed facilities available of £280m”, but the way I see it, S&U is using 85% of its facilities and this should start to ring alarm bells. I’d prefer if the company had facilities of £300m+ right now.
Chairman comment:
"Although current trends at our Advantage, our motor finance business are undoubtedly challenging, we thrive on challenges and work for a significant rebound in the second half. By contrast, Aspen continues to trade sensibly and at record levels. We remain confident and determined for the year ahead."
Graham’s view
The share price hasn’t moved today, and management appear confident around prospects in H2.
Personally, I can’t be budged from a neutral stance. Scarred by the events at JIM, I don’t have faith that the Skilled Person Review will end shortly and that business will be back to normal very quickly - although of course I hope that happens.
In terms of the substance of the review, it’s worth reminding ourselves that S&U is not at risk of regulatory action with respect to discretionary commissions (whereby brokers could historically receive higher bonuses for selling loans at higher rates).
Instead, it’s about Consumer Duty and how Advantage Finance treats customers in financial difficulty. As I understand it, the entire sector is under review on this front.
Fortunately, from what I can gather, Advantage Finance are best-in-class when it comes to how they treat customers in financial difficulty.
They have 4.7 out of 5 on Trustpilot from nearly 4,000 reviews, and here is the most recent one:
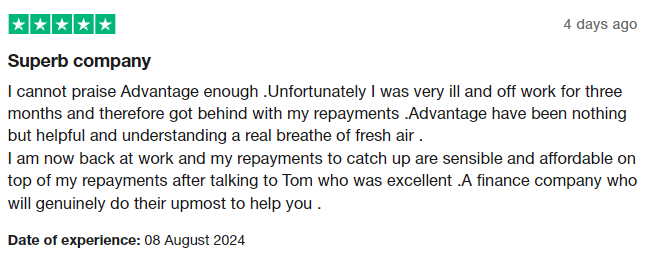
I still believe that Advantage Finance treats customers very well, and I would be shocked if their longstanding collection practices were inconsistent with Consumer Duty.
However, until the FCA agrees, I will hold back from changing my stance.
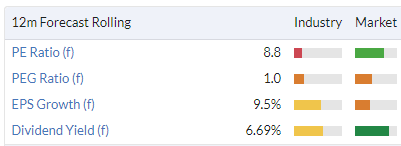
The shares do offer some value for those who wish to the plunge right now, but they aren’t at distressed levels.
Marshalls (LON:MSLH)
Down 1% to 336.8p (£852m) - Half-year Report - Graham - AMBER
Marshalls plc, a leading manufacturer of sustainable solutions for the built environment, announces its results for the half year ended 30 June 2024.
I covered full-year results for this stock in detail back in March.
Today’s interim results show continued deterioration, although the company describes it like this:
Resilient Group performance in weak end markets, with the impact partially mitigated by decisive management actions and the benefit of our diversification strategy.
There has been a 19% like-for-like revenue decline in the company’s main division, Landscape Products, where weak demand resulted in both lower volumes and pressure on pricing.
Building Products saw a 6% fall in revenues, while Roofing Products was down 5%.
Demand from new building housing and private housing RMI (repair, maintenance and improvements) is described as particularly weak. Commercial/infrastructure demand, by contrast, seems relatively robust.
The full-year result will be “broadly in-line” with previous expectations, which as we know is management-speak for a slight miss.
The results table:
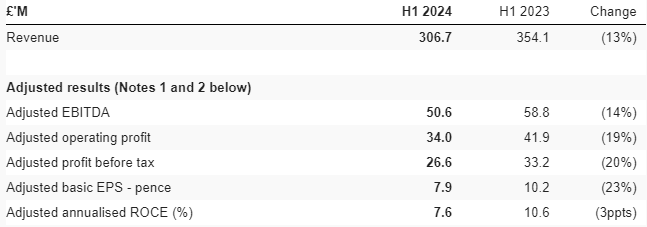
The company had already suffered negative operating leverage last year (i.e. profits falling at a faster percentage rate than the fall in revenues) and that remains visible today.
On the bright side, net debt (excluding leases) reduces from £185m a year ago, to £173m at the most recent financial year-end six months ago, to £156m today - a nice progression.
The company calculates its leverage multiple at 1.8x. I’m impressed that this has fallen slightly from 1.9x at year-end, despite the fall in profits (when profits fall, this tends to increase the leverage multiple).
Dividend: showing no signs of panic, the company declares an unchanged interim dividend of 2.6p that is well-covered by earnings (H1 EPS was 6.4p).
Outlook:
The Board remains cautiously optimistic of a modest recovery in its end markets during the second half of the year predicated on a progressive improvement in the macro-economic environment.
Against this backdrop and with the benefit of decisive management actions taken in 2023, the Board believes that profit and pre-IFRS16 net debt for the full year will be broadly in-line with its previous expectations.
CEO: the new CEO has been in place for six months, and is working on a new 5-year plan to be outlined in November.
Adjustments: I complained that the full-year results were unclean and involved too many adjustments.
So it’s only fair that I acknowledge a huge reduction in the adjusting items in this H1 report.
In H1 last year, adjusting items added up to £15m. For the full-year, they were nearly £30m.
In H1 this year, they have only added up to £5m. There were no restructuring charges this time, and no impairments - great news and well done to management for giving us cleaner numbers to work with.
Graham’s view
I’m inclined to leave my neutral view unchanged on this one. I do have a favourable impression of this company and it strikes me as a good way to bet on positivity: if you have a sunny outlook when it comes to the consumer, the housing market, and interest rates, then owning MSLH is probably a fine way to express that view.
But for me, the shares already price in quite a lot of positivity:
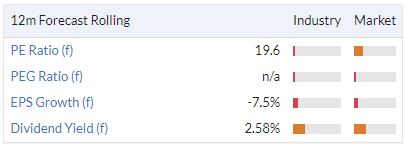
When conditions improve, operating leverage should start to work positively again and we should see profits soar back to prior levels, but again I think this is already to a large extent priced in.
The shares are already up 25% since I expressed a similar view in March, so maybe I’m just not getting it?
One important feature I should point out: this is larger than the typical company we look at here - it’s a FTSE-250 stock with blue-chip investors on the shareholder register ("abrdn", BlackRock, AXA, Vanguard).
With names like this on the register, who in recent times have been buyers of the stock rather than sellers, perhaps it’s unrealistic to expect to get bargain pricing. But that only strengthens my sense that there are probably easier ways to find value than to get involved here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Freight costs turning down again
I know freight costs ares a matter of concern for several very active investors on here. I spent 90 minutes with my bank’s industrials analyst today and one of the topics that we dived into was the fortunes of the world’s largest freight forwarders, such as DSV and Kuhne & Nagel. They mentioned that, although these firms have benefited from the spike in costs of late, the costs have started to turn down again now, albeit not yet dramatically. Whether this is a sustainable new trend I guess I’d need to consult the Houthi rebels, which poses larger challenges. But I thought it worth mentioning and hope it is of some interest.
I remain a holder of Team Internet (LON:TIG) which reported today and has been handed a 9% down raspberry by the market. Which is surprising given its very modest rating, continued growth in an advertising market with price and volume pressure, and what I believe is good cash flow supported share buybacks, a substantial acquisition and a dividend.
The cash flow and net debt may be the market's concern and as a result it was extensively covered in the Investor Meet Company results review this morning. The management have given a clear statement of estimated revenue and profit for the year (Paul would approve!) and it continues to growth in both measures. Despite todays dip the share price has shown a good recovery this year from the sub 120p level to todays cut back to 166p. I do believe that the company can continue to do what it says it will do, but I have to admit that I don't know when (or if) the market will believe it.
Charts and graphs and brain types .
Great post by Richard somewhere below on charts .
Have to say my brain has never done graphs and charts . My old FD used to try to get me to look at charts and graphs much to my annoyance and Id just say “can i please just have the expletive numbers”
Must be a brain type issue. I can look at a thousand line spreadsheet with loads of columns and spot the issues .
Show me a graph or chart and i just nothing .
I'm the same planetx, it is a brain wiring issue and for me too much testosterone as a teenager. I'm not proud of being the maths dunce in the family but I've always known when I was on profit. Stockopedia is giving me a belated education.
I agree planetx, it's the way our brains are wired. When I look at a chart it's like looking at an ordnance survey map, it paints a picture which I find easily understandable.
Slap a spreadsheet down and a cold sweat comes over me.
I'm in the chart camp. " A picture paints a thousand words".
Card Factory (LON:CARD)
I wasn't sure if this was real or a joke article when I first read it, but I think it could deliver a small amount of progressive growth with their 1000+ store network over the next few years.
"Just Eat Takeaway.com NV (LON:JET) is continuing its expansion into non-food with an exclusive partnership with greetings card and gift retailer Card Factory.
Consumers will be able to choose from more than 200 Card Factory products on the aggregator app, including greetings cards, candles, balloons, gift bags, key rings, confectionary and stationery.
The partnership has gone live in 19 of the retailer’s 1,000 UK and Ireland stores, including in Belfast, Cardiff, Glasgow, Manchester and Wakefield. The partnership will extend to a further 21 stores nationwide later this year."
It might actually be quite huge.
Genedrive (LON:GDR) have blown a huge fanfare for a tiny order in Manchester (they seem able only to sell on their own doorstep). In principle, they've got plenty of potential worldwide, but seem incredibly weak on commercialisation. They've sacked their CEO and promoted the longtime Operations chief who doesn't seem to have much commercial experience - is this a step even further backwards? I have quite a large (for me) holding
Genedrive (LON:GDR) another case of great tech, poor commercialisation.
They appointed the CEO because he was supposed to be good at commercialising and have now sacked him after he didn’t. Of course that came with more dilutive fundraisings and more fanfare……. NICE approval might live up to its acronym and be nice but seems to make little difference to their ability to sell their products. Revenues of any significance have just never materialised. What will make the difference going forward? - it isn’t obvious, I don’t see any traction that might make me want to invest right now. It feels like history repeating itself with this share.
Appointing their Ops chief also feels like another backward step to me I’m afraid. Given the track record surely they have been part of the problem. If they had the magic bullet they’d have already used it!!
Genedrive (LON:GDR) has been a fan favourite with huge volume, in between placings, since the pandemic.Unfortunately management have never managed to deliver in terms of sales and profit since then despite various medical approvals.However to be honest it isn't easy to get traction as a tiny company with tiny resources up against huge companies in their area of biotech.Great trading share for the brave (never should have been for more as that's too much stress for my personality and i see it as a zero sum game which i don't really like as it can feel like taking someone's money who has less luck, less scepticism (which was admittedly me plenty in the past) - i prefer if all shareholders can gain in the upside due to an easier business sector and model to bring to profiitability).But good luck to those who can.
Following the link on the SCVR Summary spreadsheet I see
Is there a new one?
Is there a new one?
It's work-in-progress, I'll share the new link when I've finished creating an updated summary spreadsheet.
As its quiet ... Ive just reviewed the charts to see what's changed since the shock which I think was largely triggered by the Yen. Overall not much really ... ie not a major reversal in relative momentum. Selective defensives at the margin are doing quite well and some growthy stuff has seen profit taking. One stock stood out, Man (LON:EMG) which has rattled back 20% since mid July. So I had a quick check on AHL which is down 10%. I have no particular view on Man (LON:EMG) other than high quality long term winner. It does suggest to me that obviously AHL was on the wrong side of recent moves and that most likely means other systematic funds were. Of course we either suspect this or know it already. For me, it solidifies the view that recent turmoil is a positioning shock rather than a major turn in economic prospects. The 2 can go hand in hand.... but in a way it's actually quite positive that the market can absorb such events ( a 10% one day fall in the Nikkei is pretty extreme).
It will therefore be interesting to see the CPI reaction this week. My suspicion is there isn't much room for positives because a weak no ...will now confirm recessionary fears and a strong number boxes the Fed in...in truth one cut ahead of the election doesn't really matter. But it will be a test of whether the market still has short term appetite to sell of even though a lot of damage is done. I suspect not, but we will see.
Have been looking at Ramsdens Holdings (LON:RFX) . The company operates in what might be described as an unloved sector, but as Peter Lynch said buy companies, subject to the usual caveats that operate in areas that generally have something unpleasant about them and as a result are often shunned, examples being Supreme (LON:SUP) and H & T (LON:HAT) . I hold neither of these.
Anyway back to Ramsdens Holdings (LON:RFX), it has just issued an ahead of expectations trading statement, the shares remain cheap on a range of metrics, it is cash positive and the CEO, Peter Kenyon holds over 3% of the company. On the downside FX it appears is trading 'broadly' in line, but if interest rates continue to decline, foreign holidays, which it appears most of us tend to value should continue to be supported. FX weakness if it materialises will touchwood continue to be offset by the gold price that has been strong for sometime and the growth in the pledge book plus a steadiness in the demand for jewellery and high end watches.
Cutting to the chase I hold sold a few Bloomsbury Publishing (LON:BMY), which appear up with events to fund an opening position in Ramsdens Holdings (LON:RFX) . On the subject of holidays I also hold Jet2 (LON:JET2).
All the best
I held Ramsdens Holdings (LON:RFX) and sold when the technicals broke down. It is on my watch list and I am waiting for the right time enter, which could be soon. It is in a Stage 1 base with some nearby overhead supply to the left at 215-220p to get through, break this resistance zone I will be placing an initial position and will follow up if a Stage 2 uptrend gets established. Fundamentals would support a long-term hold - just need the market to recognise the potential.
Hi Richard,
I base my investment decisions on fundamental analysis, as best I can and am not a chartist. However each to their own and I certainly would not knock that which I don't understand. My use of charts extends simply to the direction in which the share price is moving allied to the volume.
Good luck with whatever you decide.
I hold both Ramsdens Holdings (LON:RFX) and H & T (LON:HAT) for my perils and agree on the unloved part. Both are paying a reasonable dividend enough to keep me interested until they get closer to PE of about 10 which at that time I might consider moving on. Have held H & T (LON:HAT) for many years and have gained about 70% over the time but given I have has it like 10 years it can't be called stellar by any means.
We've held Ramsdens for a few years jonno, it's our second biggest holding by book costs but is at the top by value. We're happy to hold a steadily growing company on a modest p/e paying a decent dividend which is Green on Stockopodia.
The problem with Ramsdens is the market never wants to rate it highly. It may be cheap on a load of metrics, but it’s always cheap.
Ramsdens Holdings (LON:RFX) True it's never been highly rated, although it was trading at 260p just over a year ago - even if it just gets back there then that's a 20% gain from today's price.
Error. Ignore
Paul’ podcast
I know others have commented on this before but after listening to Paul’s latest podcast I couldn’t resist not saying this: it is really a joy to listen to your podcast. It’s informative, witty, informal and personal.
Long it may last.
Totally agree Yadi. I listen to various financial podcasts such as Bloomberg's "Merryn Talks Money", Interactive Investor's "On the Money", and something called "In the Company of Mavericks" which interviews fund managers.
Paul's Podcast is far and away the best. Just listening to his off-topic intro to the latest podcast, which covered a few thoughts on the recent riots, re-confirmed to me that Paul's heart is in the right place.
That's so kind, thank you! I enjoy making the podcasts, and I treat them like having a natter with a friend! So it's great to hear that other people enjoy them too :-)
"John Lewis-based flooring firm enters administration
A flooring business which traded out of John Lewis stores has gone into administration and is being wound down, with almost 200 staff losing their jobs.
The Floor Room, which sold carpets, laminate and other types of flooring, closed its concessions in 34 John Lewis shops with "immediate effect" after administrator's PricewaterhouseCoopers (PwC) were appointed on Friday.
The company, which had one of its own stores in London, said it was unable to fulfil any outstanding orders that had been placed."
Source: BBC https://www.bbc.co.uk/news/art...
Tough trading conditions in this sector currently but the surviving companies will have less competition when conditions improve.
Yes Carpetright have gone also. Tapi are cleaning up, l just bought a carpet from them, it was ok but lots of add ons, such as delivery. Tapi have taken over some Carpetright stores but not in my area. Tapi were close the Carpetright shop.
Here's a bit of a blast from the past ...
Ben Hobson wrote an article on 18 Oct 2013 for This is Money https://www.thisismoney.co.uk/...
He looked at James O’Shaughnessy's work and came up with a "trending value" screen that had JET2, MGNS, RCH, AV., and Resolution. If you would have held these companies for the last 10 years, you would have found JET2 went from 206p to 1339p, or 6.5X, MGNS 3.6X, RCH 0.6X, AV. 1.0X, RSL 0X. I'm assuming that Resolution went bankrupt, as I can't find any info on it. Perhaps someone will remember.
That's an average of 2.3X, or a gain of 130% over 10 years. That works out at 9% pa, excluding dividends., which would presumably work out higher than the indices. The ASX, meanwhile, went from 3641 to 4465, for 1.2X, which equates to an underwhelming 2%pa.
Sure, you're supposed to rebalance the portfolio every year, but I was curious as to what would happen if they were held longer-term.
Just a little curiosity that I'm throwing out there.
Mark wasn't Resolution taken over by Phoenix? Or am I thinking of something else?
Same Resolution ? https://en.wikipedia.org/wiki/...
Ah, thanks. https://en.wikipedia.org/wiki/... Resolution changed it name to Friends Life Group in May 2014 (ticker FLG). It was acquired by Aviva in 2015. Aviva acquired the company by way of offering its own shares. According to this document, this would value FLG shares at 394p.
But you know what, I'm going to keep things simple and assume that holders in RSL had the same return as AV. So instead of an average 2.3X return, it will be 2.5X, so around 9,6%pa. Not bad! That's the kind of return that the US market makes.
Not to mention that you were likely receiving massive dividends along the way. AV currently yields 7.7%, and has paid consistently high dividends. MGNS have been lobbing out the dividends. RCH too. JET2 only has a small dividend.
I'm spitballing numbers here, but I reckon that the portfolio would have been yielding 5%. Maybe a little less, but probably more. So the total return on the portfolio would probably be around 14.5%. Very nice indeed.
Great podcast again Paul. Thanks for the beginning bit, as an ethnic minority the riots have got me down and made me wary to go out with my family. Hopefully all over now and we can focus on shares!
Is anyone else struggling to get the "charts' button working - I have reported it through the green button?
My morning smallcap tweet: Brats leaving the stinking ship
Bivictrix Therapeutics (LON:BVX) Celadon Pharmaceuticals (LON:CEL) Argo Blockchain (LON:ARB) Genedrive (LON:GDR) S&U (LON:SUS), Team Internet (LON:TIG), Stelrad (LON:SRAD)
◄BiVictriX Therapeutics (BVX)► yet another AIM delisting. Blames difficult fundraising environment, shares underpriced, liquidity, costs etc. [SP=12 Cap=11m]
◄Celadon Pharmaceuticals (CEL)► ops in line. CO has only £48k cash at hand. £400k overdue from one subscriber to May's placing. Also £900k due from a £1m drawdown on a credit line, will now be paid on completion of a property transaction which has been delayed by a number of months. Talks on substantial longer term debt facilities. [SP=52.6 Cap=35m]
◄Argo Blockchain (ARB)► has repaid $35m Galaxy high-interest rate loan four months ahead of the current schedule, and nearly 18 months ahead of the original repayment schedule. [SP=9.15 Cap=73m]
◄genedrive (GDR)► first UK commercial sales of the Genedrive CYP2C19-ID Kit for use in stroke treatment. [SP=3.15 Cap=17m]
◄S&U (SUS)► June-July trading. Aspen Bridging still doing well, Advantage Finance car financing worsening. Talks with FCA to end section 166 restriction are now nearing their conclusion. [SP=1885 Cap=229m]
In line: TIG, SRAD
Proposed voluntary delisting from AIM by BiVictriX (BVX). A pre revenue company that has, unsurprisingly, never made a profit.
I can almost hear Paul saying "Companies like this shouldn't be listed"
I don't hold. Sympathies to anyone who does, I suspect the shares will be hammered today.