Small Cap Value Report (Mon 13 Feb 2023) - JNEO, BRCK, FRP, POLX, TGP, LOK, KAPE

Good morning from Paul & Graham!
Today I noticed for the first time this year, that it's just starting to become daylight outside, when my alarm gives its second and final time to get up message. That's a nice positive milestone!
Podcast - here's the link for the audio of this weekend's podcast. I'm not typing up transcripts any more, as they take too long. Also there seems to now be very good software available for transcription, so hard of hearing people who need transcripts, can hopefully get their own generated using such software.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda/Summaries
Paul’s Section:
Journeo (LON:JNEO)
140p - market cap £23m
Journeo plc (AIM: JNEO), a leading supplier of information systems, software and services to transport operators and local authorities is pleased to provide an update on trading for the year ended 31 December 2022.
Guidance for FY 12/2022 -
Revenues £21.1m (up 35%)
Order intake of £27m is up 50%, but I can’t see a closing order book figure.
Profit in line with expectations (a note from Cenkos puts this at £0.9m, both pre-tax and post-tax)
Recurring revenues (no figure provided) being received from 10k connected vehicles.
“No material issues” with supply chain.
Acquisition - this seems a game-changer, which makes me wonder why the vendors sold it for such an apparently cheap price?
The acquisition is Infotec, a leader in the rail passenger displays markets, which seems a good fit with JNEO’s existing business for CCTV on public transport.
The acquisition is said to be adding £12m annual revenues, and £2m profit to the enlarged group, thus more than tripling overall profitability. Cenkos is forecasting £3.3m PBT for FY 12/2023. In EPS terms, this is 17.4p, so the PER is still in single digits at 8.0x, assuming the enlarged group hits profit guidance for 2023.
My opinion - this looks superficially attractive. My main worry is that JNEO has been around for a long time as a listed company, previously called 21st Century Systems and the track record was distinctly patchy, with occasional good years fizzling out subsequently. So I’d need a lot of convincing that it’s suddenly morphed into a high quality business.
The acquisition looks strikingly cheap - why was that, I wonder? People selling a business know it better than the buyers. So again, I'd need convincing on this.
The share count was increased from c.9m to c.16m as a fundraise at 105p was used to fund the acquisition. So I’d be careful about chasing the price too much higher than such a recent fundraise.
This share looks to have momentum behind it for now, but I’d need convincing that long-term value exists here, which would need more than one good year’s results.
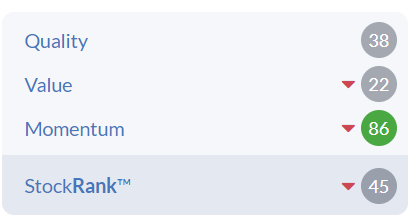
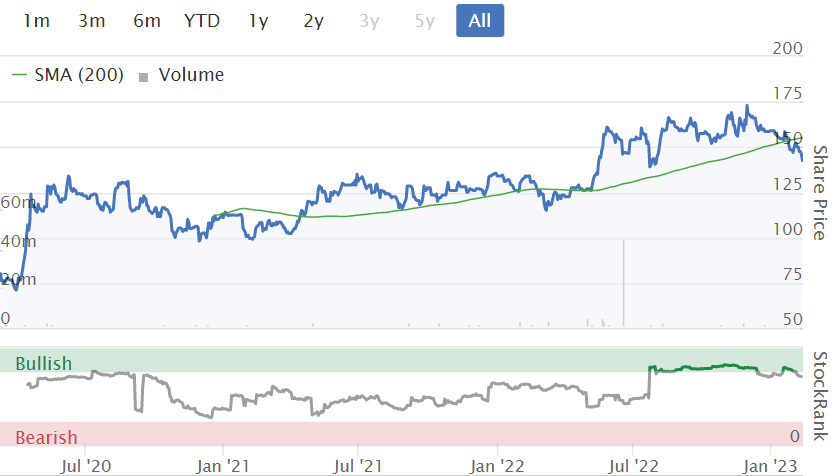
The StockRank system also looks a bit sceptical - flagging that this share is running mainly on momentum, and not so much on quality or value -
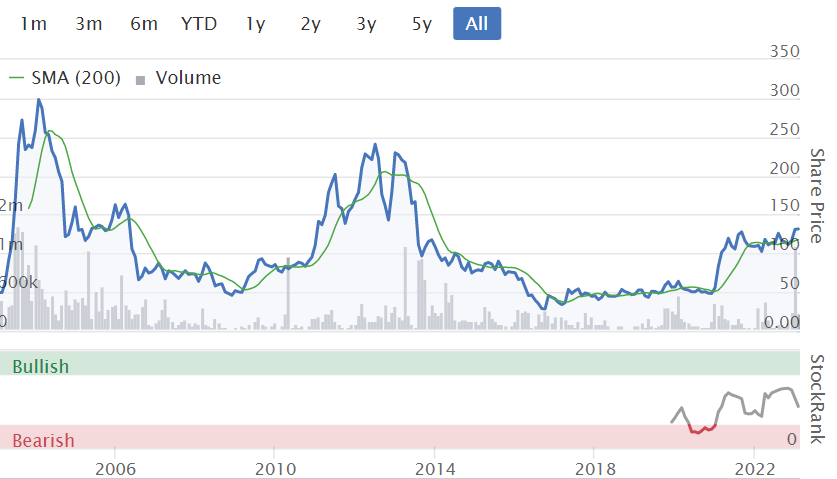
Nearly 18 years as a listed company -
Brickability (LON:BRCK)
69p (pre market open)
Market cap £206m
Brickability Group plc (AIM: BRCK), the leading construction materials distributor, today announces the following update on trading for the financial year ended 31 March 2023.
This strikes me as a positive surprise, in a sector I would have imagined to be struggling right now -
Following the release of the Group's interim results for the six months ended 30 September 2022, Brickability has continued to deliver a strong performance across all of its business divisions. As a result, the Brickability Board is pleased to announce that it now expects to report an adjusted EBITDA1 of a least £47 million for the full year to 31 March 2023, ahead of current market expectations2.
2. Current consensus analyst forecasts are FY23 EBITDA of £44.7 million (with a range of £44.5 million to £44.9 million)
It’s so helpful when companies provide a footnote, so we can quickly see that the latest guidance is £2.3m ahead of consensus forecasts, or a 5.1% beat against consensus.
Thanks also to Cenkos, who translate EBITDA into real profits (adj PBT) of £40.1m, and 10.8p adj EPS.
That gives us a PER of 6.4x (69p share price, divided by 10.8p EPS) - clearly that’s cheap, if you think earnings can be maintained at this level. The current share price seems to be implying that the market is sceptical about future earnings strength. Or it could be a mis-pricing, with the recent downward share price trend having overshot on the downside?
I see the market price has just opened 9% up at c.75p (at 08:04), a good start to the day.
Note that higher corporation tax is kicking in for next year, which has quite a sharp impact on EPS (this point is relevant for many/most companies). So Cenkos is leaving FY 3/2024 forecasts unchanged, with profitability flat vs this year, but EPS down from 10.8p to 10.2p, mainly due to higher corp tax.
Outlook - vague, but this sounds fairly upbeat in tone, and it doesn’t sound as if the group is seeing an immediate downturn -
Whilst mindful of the short term impacts on our sectors that a challenging macro-economic environment could bring, the Board remains confident that the Group is well placed to continue delivering on its strategic objectives and the underlying growth of the business.
My opinion - this looks encouraging to me.
BRCK floated in the year before covid struck, and the share price is now very similar to then. Although note there are c.300m shares in issue, more than the c.230m when it floated - not an excessive increase in share count, given the rapid expansion of the business through acquisitions. I’d say shareholders now are getting a lot more for their money, than people who backed the IPO.
Note that there’s no asset-backing, with a balance sheet that carries £150m of goodwill, bringing NAV of £154m down to only £4m NTAV. Although we could probably also write-off the (usually related to goodwill) deferred tax creditor of £17m, so that would increase NTAV to £21m.
Another point to note on the balance sheet, is that BRCK owns few inventories, as I believe the business model is more based on drop-shipping (acting as an intermediary, but not actually holding the physical stock). That means it doesn’t actually need a lot of asset backing, providing manufacturers are happy to continue tolerating an intermediary that skims off some of the profit.
Are the shares attractive? That depends entirely on your macro view. If you expect a deep & prolonged slowdown in construction, then this sector would be best avoided altogether. If you’re more sanguine, then this could be a good value entry point. I’m personally leaning more towards the latter, so I’ll mark this one down as something I see broadly positively on balance, because the shares have already de-rated a lot, and yet the company seems to be trading well & doesn’t sound too worried about the outlook. Hence buyers are able to buy at a price which already factors in some downside protection from lower future earnings.
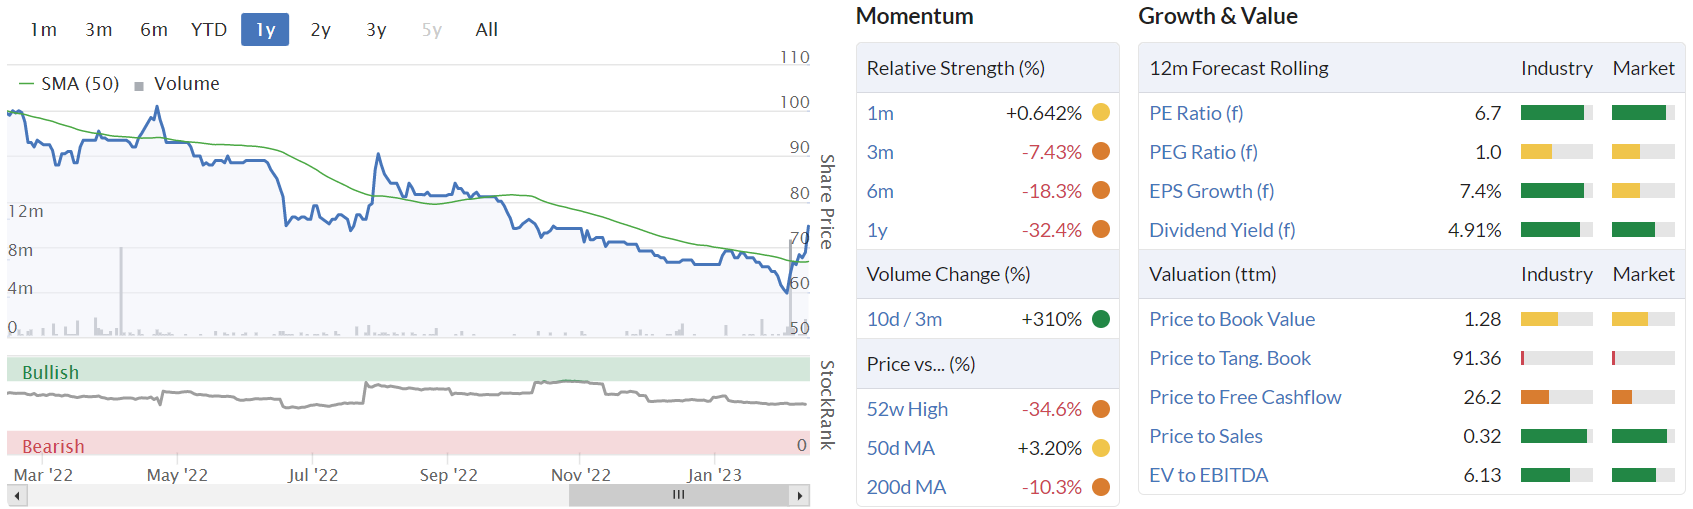
Attractive valuation scores below right -
Graham’s Section:
Frp Advisory (LON:FRP)
Share price: 146.6p (pre-market)
Market cap: £365m
FRP Advisory Group plc, a leading national specialist business advisory firm, today announces a trading update for the nine months to 31 January 2023 and declares its Q3 quarterly dividend.
Paul neatly summarised FRP’s H1 results here. Here are the key points from this morning’s Q3 update.
“Financial Advisory” - the company has launched this new “pillar”, to go along with its other four existing services (Restructuring, Corporate Finance, etc.). This is just a reorganisation of the services already offered, as the Financial Advisory pillar replaces and includes the pillar that was called Pensions Advisory.
Trading - FY 2023 results are expected to be broadly in line with consensus expectations (revenue £101m, adj. EBTIDA £26.7m), “with the outcome subject to the timing of completion of several FRP Corporate Finance transactions around the year end.”.
I would interpret this as a mini-profit warning, as I take it to mean that the company is more likely to miss expectations than it is to exceed them.
Trading does sound reasonably busy:
As mentioned in the Company's interim results, the volume of work in the higher value restructuring and administration market is still to recover to pre-Covid levels and the Group expects to see increased activity in these areas during 2023. The Group has seen an increase in the number of liquidation mandates in line with the widely reported increase in the overall number of insolvencies for companies during 2022.
Q3 dividend is 0.85p (vs. 0.8p last year).
My view
In general, I think that companies in this sector should trade on cheap multiples (it’s better to work for them than to own them, in my view) and that is why I’ve been worried that Begbies Traynor (LON:BEG) is at risk of becoming overvalued.
However, according to the StockReport, Begbies trades at a PER of 13x and a Price to Sales multiple of 1.8x.
FRP’s StockReport, on the other hand, suggests a PER of 18.5x and a Price to Sales multiple of 3.6x.
Those metrics strike me as very worrying and so I’m tempted to take a negative view on this stock. But I’ll stay neutral for now, as the company’s financial performance has been fine so far, since its 2020 IPO (this explains its very high QualityRank of 85).
Lok'n Store (LON:LOK)
Share price: 916p (-5%)
Market cap: £278m
This self-storage company provides an H1 update. The full-year ends in July, so H1 ended in January.
I reviewed last year’s results here, if you’re interested.
H1 highlights:
Same store revenues +10.3%, price per square foot +9.2%.
Same store occupied unit space +2.6%
NAV to be “broadly unchanged at year end”
So there’s good pricing power and improved utilisation, but NAV isn’t going to move much this year - and could even move lower?
Here’s the reason for that: lower property valuations generally, and higher interest rates:
Our trading assets will be independently revalued at our 31 July 2023 year end. The maiden valuations of three new stores combined with continuing strong trading should materially offset any changes in exit yields and discount rates that we are seeing in the market.
Or in other words, the company’s underlying growth and profitability (which increase NAV) should nearly match the reduction in NAV caused by higher interest rates.
I noted previously that the company had deleveraged its balance sheet, and it confirms today that its LTV is still very very low at just 8.8%. Rising rates therefore have little effect on its own day-to-day cash flow, even if they do affect the valuation (on paper) of its properties.
The company also doesn’t seem too worried about inflation:
…we are seeing some cost pressure, specifically in the areas of business rates and energy. We believe these cost movements are shorter term and expect the rate of cost growth to return to more normalised levels in due course. Beyond that we would expect any increases in absolute cost levels to be driven mainly by the increasing number of stores.
The company has four new “landmark” stores in the pipeline, and sees further opportunities “beyond the secured pipeline”.
My view
I still think there’s a lot to like about this one. Self-storage is a niche whose future I believe in, as population density only seems to be going in one direction.
I’ve spent a few minutes this morning checking how the company calculates its “adjusted net asset value”, and there’s a huge number left out of the calculation: potential tax liabilities on gains from rising property values.
In the 2021 results, adjusted NAV was £7.42 after making provisions for these taxes, a very different figure to the £9.72 headline number.
After making this realisation, I’m going to have to take a neutral view on this stock. I’d be much more positive if it was trading around or below NAV (conservatively estimated). However, at its current share price, it is trading at a meaningful premium.
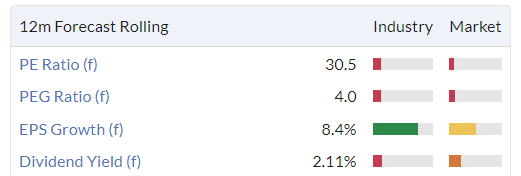
It’s also very expensive against earnings:
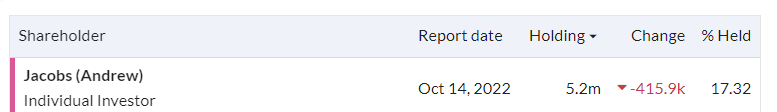
And the founder-CEO appears to have reduced his holding since the last time I checked:
Therefore, even though I like many aspects of it, I’m neutral on this stock for now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

56 comments
Hi
Not a UK SCVR in any shape or form, my apologies, but might interest some US/Tech investors
For any Palantir Technologies (NYQ:PLTR) followers, stock price up over +18% in after hours after making GAARP profitability for the first time in their history (a big deal for US markets).
A stock not for the fainthearted but for the deep DYO people worth digging into deeply IMO.
I hold. Also Palantir Technologies (NYQ:PLTR) is integrating AL/ML capabilities developed over past 20 years, so not Mickey Mouse stuff at all.
Of particular note, they have placed to the fore data protection and integrity.
A webcast is on their website.
Regards
Howard
I assume you mean AI/ML, Artificial Intelligence/Machine Learning? Not everyone is ofay with tech acronyms.
Hi
Augmentum Fintech (LON:AUGM) released this RNS this afternoon.
The headlines are ......
Augmentum Fintech plc
Proposed acquisition of Cushon by NatWest Group
Augmentum Fintech plc (LSE: AUGM) (the “Company” or “Augmentum”), Europe’s leading publicly listed fintech fund, announces that NatWest Group, the FTSE 100 banking and financial services group, has agreed to acquire a majority shareholding in Cushon, a portfolio investment of the Company. The acquisition will be subject, inter alia, to the receipt of the necessary regulatory approvals. This transaction will represent Augmentum’s fifth successful portfolio investment exit, all of which have been at or above the last reported holding value.
Augmentum first invested in workplace savings and Net Zero pension provider Cushon (www.cushon.co.uk) in June 2021 with a £5 million investment as part of Cushon’s Series A fundraising round and since that date the Company has invested a further £5.8 million.
Augmentum is expected to receive proceeds of £22.8 million from the completion of the acquisition, representing a 46.2% uplift on the unaudited 30 September 2022 holding value of £15.6 million, a multiple of 2.1x on cost and an IRR of 66.3%1.
Rest of RNS is here ...
https://www.investegate.co.uk/...
I hold
Regards
Howard
Bidstack (LON:BIDS)
If Mojo is reading would appreciate views on trading update.
I was expecting it to be poor but £1m pm revenue in weakest quarter so far is much better. Plus £8m (half its market cap) in cash now. Doesn't seem to be burning cash as quickly as I had feared either and if they are going to do £15m revenue approx this year then suspect the balance sheet may be better than I'd anticipated.
Market hasn't really appreciated them much this morning clawing back a little of the recent losses mind and i'm wondering why.
Obviously a high risk stock and certainly not for widows or orphans but I wonder if they might actually make it now even despite the Azerion fiasco.
Obviously I owe you that pint :) not forgotten.....
The William Currie group look to have picked up 3.5% of Sosandar (LON:SOS) shares. Interesting person on the team:
https://williamcurriegroup.com...
Watkin Jones on a bit of a pull back after going ex dividend .
Am I missing anything or just a bit of heat coming out the market and an ex dividend fall ?
Looks good to me on a 3-5 year timeline .
Have started building a position by scaling in just wondering where the bottom of this drop might be .
Re Watkin Jones, I started rebuilding our holding too early at 1.20 planetx but bought more below 90p. The shares have been good to us twice, around this price I think they're good value and expect them to reward our patience again.
Hi, I cannot get my head around the fact that Watkin Jones (LON:WJG) is trading at a premium to its assets rather than a discount like most of the housebuilders. What is the reason for this do you think?
I think this has been covered before, but Watkin Jones (LON:WJG) had always tended to trade at a premium because it is an asset light business model - it forward sells its properties to institutional investors. It therefore doesn't hold as much stock on its balance sheet as a traditional housebuilder and makes less sense to be priced with reference to its tangible book value. In many ways it's more like an asset manager - the investors pay over the money, while they oversee management of the project and get a fee in return.
I think the long term fundamentals look very strong for the build to rent and student accommodation markets - a big demand supply imbalance and rents expected to grow strongly. For these reasons, expect institutional demand to remain strong. I see the recent issues as just a short term hiccup and hardly unexpected given what was going on in gilt markets and funding costs, but this has already calmed down considerably.
I think this has been covered before, but Watkin Jones (LON:WJG) had always tended to trade at a premium because it is an asset light business model - it forward sells its properties to institutional investors.
To try and find some negatives - there is a potential exposure to counterparty risk - i.e. a buyer goes bust before a development is completed, leaving the company with a partially built site and no funds to complete it. And the move into affordable housing has been self-funded, although they're now moving to the same capital light model there.
There's also a cladding charge - £9.4 million carried forward, but the government could change the rules there. Must be a lot of high rises in their back catalogue.
Overall, though, it's pretty low risk - student accomodation, buy-to-rent, affordable housing nearly all pre-sold to end clients and institutions, who they state are blue chip and a small but growing rental management business. It's a very different model to traditional housebuilders self-funding developments and selling direct to consumers.
timarr
Yes your point about counterparty failure is a potential risk, although I would say mitigated by the fact that they have plenty of cash, so in a worst case scenario they could pay for the rest of the construction themselves. Also, given the strong investor demand I'd be fairly confident they'd be able to line up another buyer.
Hi Bouden54
RE: Watkin Jones (LON:WJG)
Yes, I agree with that. Still, as a holder, my job is to look for reasons why I shouldn't be a shareholder. Disconfirm, always disconfirm.
Overall, though, I'm optimistic that WJG will turn out to be a rare long term compounder in the "housebuilding" space. As a minimum it's very hard to envisage a situation where the company is at risk of failure so, at worst, it's a question of waiting for the next economic upturn.
I hold quite a lot (for me) and have been buying more, but remain considerably underwater overall.
timarr
Just renewed my Stockopedia subscription. Thanks for all the great work you all do.
Graham, Lok'n Store (LON:LOK) I see that your primary valuation metric is NAV. I know that this is often the case for companies in the financial sector. But please could you explain why this is the case, instead of focusing on the EPS?
Why is Lok'n Store (LON:LOK) under financials?
Hi Rusty2 Unfortunately I don't know why Lok'n Store (LON:LOK) is under financials. My guess is that it has more in common with financial companies than with the other sectors. Perhaps someone else can shed some more light on this?
Hi Paul
On Journeo (LON:JNEO) I think you have to distinguish between the business 5 years ago of C21 and the one today as fundamentally you are confusing two quite different animals.
The previous company was a hardware only camera installation business where the CEO decided it was too hard and walked. A new management team came in with some investment and out of those ashes created Journeo (LON:JNEO. They've spent a few years turning the business around - they still do the hardware but have really moved the business into a SaaS model around software, connectivity and monitoring. This becomes more recurring and in todays age is a necessary on any public transport system around the world. Revenues and profitability have been consistently moving up over the past 3 years so execution has actually been good.
The problem for the business until now was that revenue could be lumpy and it was sub scale with little presence in the rail networks. The acquisition of Infotec achieves just that combination - no overlap in customers, earnings accretive and gives the business scale from which to grow. Post acquisition there are synergies in merging operating sites which should add additionally to the bottom line.
Infotech is private and has a single shareholder. He is clearly cashing in but taking half a million Journeo (LON:JNEO) shares as part of that for upside and staying with the business. £8m in cash plus upside from shares isn't a bad deal at current CGT and entrepreneurs relief. Given there was net cash in the business it is also a good way to extract that cash paying only CGT (rather than as a dividend which would be almost double the tax). So it makes sense really for both parties.
You need to look at the business for what it is and not what it was under previous management who exited some 5 years back.
best
David
Polarean Imaging (LON:POLX) Well I certainly seem to time dealing in shares with big market moves just not always positive!
Think Paul will cover shortly , unhelpfully they company gives no indication of what this is worth they intend to sell in next 24 months
" 75 to 100 Xenoview Gas Blend cylinders and 15 to 20 Polarizer systems over the next 24 months."
Share price is in reaction to future raises as cash runway is 15 months from here
Always regret buying medical related stocks! So hard to value them on an "x% of the market is worth £Y million" basis as they never seem to achieve it or not with the existing shareholder structure and massive dilution or delisting somewhere along the way. Hoping this would be a strong takeover candidate but that's also not a good trading philosophy
Always regret buying medical related stocks!
Picks and shovels is the way to go. Plenty of options there, all priced pretty much identically and all performing pretty much in line. Thermo Fisher Scientific (NYQ:TMO) is the daddy, with a slice in every pie from diagnostics to instrumentation to contract manufacturing. Less sleepy than you’d expect - up c.100% in 3 years
Polx might be worth another look. They released an investor presentation yesterday, webinar to come on Monday with Q and A , answering some of your questions on value. Sentiment seems to have gone full circle since a few days ago.
ChatGPT has attracted a lot of interest recently so I I thought it would be an interesting project to get the app to give a numerical rating of the sentiment of some trading updates. This is what it came up with on today's updates.
Journeo (LON:JNEO)
I would rate the sentiment expressed in the trading update as a 9 out of 10. The update is predominantly positive, with strong financial results, growth in the number of vehicles connected to the platform, and successful integration of the recent acquisition. The CEO is described as being "very pleased" with the company's achievements and the Board expresses confidence in delivering increasing value to shareholders.
Brickability (LON:BRCK)
I would rate the sentiment expressed in the trading update as a 9 out of 10. The company has delivered a strong performance across all of its business divisions and is expected to report an adjusted EBITDA of at least £47 million, ahead of current market expectations. The Board is confident in the success of its diverse multi-business strategy and the ability to continue delivering on its strategic objectives despite the challenges and uncertainty in the macro-economic environment.
Lok'n Store (LON:LOK)
I would rate the sentiment in this trading update as a 9 out of 10. The company is reporting strong financial performance, with same-store revenue up 10.3% and move-ins up 13.5%. The company also has a significant development of new stores in the pipeline, which will drive growth and increase value. Additionally, the chairman of the company expresses confidence in the company's future, saying "the cash flow from these stores can then fund future growth and an increasing dividend to our shareholders."
Bidstack (LON:BIDS)
I would rate the sentiment expressed in the trading update as a 7 out of 10. The unaudited revenue, gross margin, and cash balance for FY22 have increased significantly, with a successful placement and growing global network of premium developers and publishers. The outlook for Q1 2023 and the strong pipeline of premium publishers are also positive indicators. However, the outcome of the case against Azerion and its potential impact on the revenue, gross margin, and consequent profit or loss are subject to a provision and can be considered a negative aspect.
Frp Advisory (LON:FRP)
I would rate the sentiment expressed in the trading update as a 7 out of 10. The trading update can be considered positive, with the company announcing continued progress over the first nine months of the financial year and a strong pipeline for its Corporate Finance team. However, it also mentions that the volume of work in the higher value restructuring and administration market is still yet to recover to pre-Covid levels.
Hi Dwit199 & others
Thank you for your ChatGPT examples, I have thought that ChatGPT will start to make an impact into the world of finance, this is an interesting example.
For those interested, Microsoft (NSQ:MSFT) launched their integration of OpenAI's software into their 'bing browser and their Azure cloud'. Their presentation was in quite some depth and illustrates how Microsoft (NSQ:MSFT) have taken 'search' and 'browsing' the web to a completely different level.
Their vid is 55 mins long but well worth a viewing.
They layout how the conversational AI (like ChatGPT) integrates with search and compute to provide an incredibly rich result to questions. But additionally it takes it into inferences.
Of particular interest to this community they summarise a 15 page Lululemon Athletica (NSQ:LULU) results report to a few key points. They then build on that to ask bing/Azure/the AI to compare Lululemon Athletica (NSQ:LULU) results against Nike (NYQ:NKE) in tabular format. All this is with two questions, and responses are instant.
Paul/Graham, you might want to take a peek.
Vid here .....
Disclosure: I hold Microsoft (NSQ:MSFT)
Regards
Howard
The score on MJ Hudson's RNS would be interesting.
The score on MJ Hudson's RNS would be interesting.
MJ Hudson (LON:MJH)
I would rate the sentiment in the statement as a 3 out of 10. While the company mentions that there have been "encouraging" initial bids for the acquisition of their business units, the resignation of their auditor (Ernst & Young LLP) due to loss of trust in the company's management and their ability to provide accurate information has a negative impact on the overall sentiment of the statement.
I understand ChatGPT to be based around a Large Language Model trained on huge amounts of internet text. It apparently predicts what words are most likely to be used and to follow rather than doing any up to date search. Tim Hartford quoted an example where a reference to an academic paper was apparently invented as the paper did not exist. Its plausibility should not be mistaken for accuracy.
Richard Beddard wrote an article on Chat GPT, in which he asked it about a topic he knew inside out (himself), as well as some questions around investing:
https://knowledge.sharescope.c...
From this, I conclude that ChatGPT is an outrageous success. When it knows the gist of something, it fills in the blanks by making stuff up. It is a lot more human than I anticipated.
He's not entirely negative on it, mind. As he concludes:
It is a tool. We still need to formulate the right questions and interpret the answers
timarr
I think the Microsoft implementation in the new Bing search should address some of those issues. ChatGPT does seem to make stuff up. I asked it for a list of books on a particular, slightly obscure subject. The first result was genuine but I couldn't find any evidence via Google that the next two in the list actually existed.
The exercise that I undertook today was slightly different. I provided the text of the trading updates to ChatGPT and asked it to summarise the update and provide a sentiment score. I think it did a reasonable job.
What was your opinion of the summaries and scores?
The scores look too high to me, on Frp Advisory (LON:FRP), Graham says "I would interpret this as a mini-profit warning".
9/10 for a broadly inline update, far too high, IMO.
If there is some really news then can only get 10/10.
"9/10 for a broadly inline update, far too high, IMO."
The Frp Advisory (LON:FRP) score was 7/10.
Just for timarr I asked ChatGTP to summarise the FRP update again, but this time with humour.
FRP Advisory Group is making progress, despite the ongoing struggles of the world and the fact that the higher value restructuring market hasn't fully recovered from the pandemic, but they're still optimistic about being in line with expectations for 2023, until their full year trading update in May - which might or might not burst their bubble.
I don't think Mr C has much to worry about at the moment :-)
timarr
I don't think Mr C has much to worry about at the moment :-)
Agreed.
This is the first time I have tried using AI to provide some interpretation of text. Overall , I am actually quite impressed with the analysis ChatGPT has performed on these trading updates and the way it has summarised them. Bear in mind that it is only trying to analyse the text of the update as provided to it by copy and paste for the broad sentiment that it expresses rather than an in-depth analysis of the numbers. If you look at the FRP update for example, that Rusty2 considers to have too high a score, there are many positive points in the text and few negative, so based on the text alone, the score of 7 seems to me to be about right.
OK, but still too high.
What was your opinion of the summaries and scores?
I don't follow any of those companies so couldn't offer an informed opinion. To the extent that they might be accurate then I'd say that they would offer an interesting starting point for research if used to generate summaries of each days results and trading statements.
Perhaps Mr Contrarian needs to look to his laurels?
(Although ChatGPT will need to learn to replicate sardonic humour to ever become a like for like replacement).
timarr
I recommend Tim Harford's piece from the FT the other day.
Why chatbots are bound to spout bullshit.
He makes the point that ChatGPT does not have a model of the world but a model of the kinds of things that people tend to write. Of course this makes it sound believable but we know that some of what people write is true and some not. Hence ChatGPT will be very plausible but not reliable.
Hi jimrog64
Yes, I saw Tim Harford's article. Of course, the things that people write do influence the world so I think there's a plausible (sic) line of argument that ChatGPT (or replacements) will have more impact than we expect.
For example, people believe (and act) on advice from plausible "experts" more than than they do from hesitant ones. Given the uncertainty in the world the latter are more likely to provide good advice than the former but sadly we prefer to follow confident (and wrong) leaders more than cautious (and right) ones.
What would be interesting is, if in the hands of Alphabet and Microsoft, ChatGPT offers the same information to everyone. At the moment search engines proactively serve content that we prefer to read - so if we're red-blooded, right-wing conservatives we get Fox News and if we're livy-livered, left-wing liberals we get the Guardian.So will ChapGPT be impartial or will it, like human beings, attempt to tailor its messages for its audience?
timarr
"Why chatbots are bound to spout b......"
Worryingly humanlike characteristics if that is the case
How did you express the query to ChatGPT for this may I ask please?
Start a new chat and type an instruction in the input box:
Sentiment of this trading update on a scale of 0 - 10? "......paste trading update here...."
Usually, this will then return a single paragraph summary which includes the sentiment score. It won't always generate exactly the same summary from the text but the scores seem consistent. There may be better ways to phrase the question.
If you are interested here is what a prototype Google AI had to say about the BRCK trading update:
"I would rate the sentiment of the update as 7/10. The announcement is positive because it reports that Brickability is doing well and has performed better than expected. However, the announcement is not overly positive because it does not provide any details about the company's future plans or expectations."
Do you have a link to the Google AI?
I think the ChatGPT summary is rather more informative than Google's. However, I am unsure of how to systematically integrate this information into an investment process, although I feel there is potential.
Could anyone more knowledgeable than myself comment on the announcement today by DX (Group) (LON:DX.) ? Tufnells have made a claim against them which DX will defend. Would defending such a claim likely to run into the millions of £ or are we talking tens of thousands ?
Pleasing trading statement from Brickability (LON:BRCK)
“…the Board remains confident that the Group is well placed to continue delivering on its strategic objectives and the underlying growth of the business.”
(I hold.)
Doesn't seem much growth left in that one for me...
Brickability This bit appears to have created some excitement
"it now expects to report an adjusted EBITDA of a least £47 million for the full year to 31 March 2023, ahead of current market expectations"
KAPE (LON:KAPE)
Best of the Best (LON:BOTB)
Low offer for Kape Technologies from 54% shareholder Teddy Sagi accepted - a danger of having an over-sized holder.
Sagi also has a large stake (just under 30%) in BOTB via Globe Investments which appears to be a PI favourite at the moment. What's to stop a low ball takeover from him at BOTB?
Sagi went to prison in 1996 for bribery and fraud which is a red flag for me. I owned Kape shares a long time ago but sold when I understood the Sagi connection
Ripoff Report | Teddy Sagi Review - Internet - Teddy sagi spent nine
My thinking is that if he will cough up >than the market price for something I own I might be irritated I haven't got full value, but on the other hand knowing he is in the picture gives me some confidence that Best Of The Best (LON:BOTB) has a price floor under it. On a separate note, thanks Michael Tee for flagging up Diaceutics (LON:DXRX) a few weeks ago.
Hi Funnymoney
Thanks for the name check. I hope Diaceutics (LON:DXRX) works out well.
Michael
Morning Michael T,
I think there's a very different dynamic between Sagi holding 54% of Kape Technologies (LON:KAPE) (which is a controlling stake), and his 30% at Best Of The Best (LON:BOTB) (a big, but not controlling stake).
A battle for control of BOTB could work out quite well for smaller shareholders, if existing management (who also have deep pockets remember, since they sold heavily at £24/share) refused to be steam-rollered by Sagi, and began buying shares in the market.
I get the impression that BOTB and GIL are working together collaboratively at the moment, but still don't have a formal agreement over growth plans for BOTB.
The thing I like about BOTB shares (I hold, my largest position currently) is that it's cheap on the existing level of profitability. So there's no bid premium in there. And no premium for future growth from the intended international expansion either. Hence risk:reward should be fine either way. But as always, future events could take us by surprise.
Regards, Paul.
Morning Paul (Scott)
Really enjoying your weekend podcasts, a great way to communicate the week's events in small companies- thank you.
I agree BOTB and KAPE situations are not the same but 30% gives Sagi more than a pretty good toehold in the company. I hope the existing management with large holdings know exactly what they are doing as Sagi is clever and very experienced.
I was not comfortable with Sagi in Kape and sold and I think his ownership held the share price back. He is clearly out for himself (probably doesn't help that I am watching Game of Thrones atm
Sold Kape Technologies (LON:KAPE) at 290p today, slight premium to Sagi offer. Might be a higher offer to come, might not. Could be hassle if investors say no and he takes it private anyway. Suspect there are enough management shares issued at generous discounts that will vote with him to keep their jobs.
Disappointing but then I was aware of the Sagi connection and didn't entirely trust the team. Still learning that if you play with fire you can get burnt.
Simon Thompson valued this at £5 in his most recent comments on the company I believe. Was hoping to see some of that and at least 350p if taken out early. Seems several offers are coming in on the tight side. Eg K3C at 350p when worth 450p+. Homeserve at £12.
He needs 75% to de-list. Slater and co will have a say here. May extract more for other shareholders. Expect another higher offer imo
Random info I will put out there. Speaking to a consultant the other day who said PE have 2trilion (can't recall of that's £ or $) of dry powder they need to deploy, most likely in h2. Private valuations haven't budged much so they are looking at public markets. What they want is profit warnings so they can get in cheap.
Morning,
Not a small cap, but can't believe the scandalous low ball offer for Kape Technologies (LON:KAPE) this morning!!
What you get with a dominant shareholder I guess, that's the risk!
Kape Technologies (LON:KAPE) Certainly not generous - and looks like he is prepared to play hardball by going for a delisting regardless of the outcome of the offer.
Kape Technologies (LON:KAPE) Certainly not generous - and looks like he is prepared to play hardball by going for a delisting regardless of the outcome of the offer.
Tedi Sagi has an interesting CV, and most deals he does favour himself. Nothing wrong in that, but shareholders need to consider this when investing in stocks he's involved with.
Tim
Yes indeed. Much has been made of the prospects for a revived Best Of The Best (LON:BOTB) now that Sagi is invested but this might give pause to that idea. It seems a little like Russian roulette getting involved wherever he's dominant.