Small Cap Value Report (Mon 14 Aug 2023) - GLAN, GMR, LOK, CNIC, OTB, HSW

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections below
Lok'n Store (LON:LOK) - up 1% to 738p (£242m) - Trading Update (in line) - Graham - AMBER
Forecasts unchanged as this self-storage company delivers a good increase in pricing and continues to expand. The share price has weakened but personally I’d hold out for a better entry. Insiders have been selling and valuation remains high vs. after-tax NAV and earnings.
CentralNic (LON:CNIC) - Unch at 131p (£366m) - Interim Results - Paul - AMBER/RED
Trading and outlook seem fine, and the valuation appears cheap. However, on closer inspection my previous concerns remain - a horribly weak balance sheet, with the bank debt now costing $6m for H1. Buybacks can't really be afforded in my view. Also are profits/cashflows sustainable? I discuss the bull & bear points below, and come out moderately negative overall.
Hostelworld (LON:HSW) - 134.5p (£166m/€192m) - Interim Results (in line) - Graham - AMBER
This online travel agent for hostels has seen a terrific upswing in trading over the past 12 months, as long-distance international leisure travel has boomed. The company is close to a statutory profit but isn’t quite there yet. Cash flow is good, enabling debt reduction.
Paul's Section:
Some quick comments first -
Glantus Holdings (LON:GLAN)
20p (£10m) - Recommended Cash Offer - Paul
A very lucky escape for shareholders in this Irish accounts payable niche software company. It was floated in May 2021 at 102p, by Arden, and very quickly turned into a disaster, losing 90%+ of its value by Oct 2022, after a nasty profit warning, and running out of cash. It had to use heavy borrowings to survive, but managed to cling on.
We only commented on it once, here in Sept 2022, writing it off as a hopeless float, with woefully inadequate funding. 2022 accounts were absolutely dire, and it looked insolvent (but lenders gave it more time to sort itself out).
It did report improved trading in July 2023, which I didn’t notice at the time, although finances were still perilously weak, which made it uninvestable for me regardless.
Today we get news that an accounting software specialist, Basware, is offering 33.42p to buy Glantus, which is a terrific, and very lucky outcome for shareholders. Way below the IPO price of 102p, but this could easily have been a zero without fresh funding, so a good outcome in the circumstances. I won't say well done to shareholders, as owning it was a terrible decision!
Gaming Realms (LON:GMR) (Paul holds)
34p (£100m) - NED buying shares again - Paul - GREEN
I recently flagged up large Director buying by one of GMR's NEDs, Mark Blandford. He's been at it again - news today of another purchase by him of 350k shares, at an average 35.17p = £123k. He bought £180k-worth a few days ago on 4 August. Who is he? Google reveals that Mark Blandford is the founder of Sportingbet, a pioneer in online gambling. That's similar to the space Gaming Realms operates in, so it's encouraging to see him enthusiastically buying up shares in it. I wouldn't comment normally on Director buying, but when it's a in £6-figures, I sit up and take notice - that's not messing about for PR purposes!
I explained why I've turned positive on this share, after previous scepticism, here on 27 July 2023. It's worth a fresh look I think, as the numbers are now looking very good, with a forward PER of only 15.0x, based on realistic-looking forecasts.
On Beach group (LON:OTB)
Up 4% to 95p (£159m) - Director buy - Paul - GREEN
I last looked at this holidays company on 19 May 2023, concluding AMBER, that there was too much guesswork involved at that stage, but that at 105p it might be a possible trade for a bounce? I'm going GREEN on it today, because news has just come through of a pretty spectacular Director buy - the founder (now a NED) Simon Cooper, has through an intermediary just spent £2.5m buying 2.82m shares at 88.1p. That takes him up to 7.5% of the company. When a founder Director buys on that scale, I'm inclined to follow suit, especially as I was already eyeing it as a possible trade.
This share was also flagged in the reader comments below by our star contributor, Wolf of Small Street coincidentally, so many thanks for that.
CentralNic (LON:CNIC)
Unch at 131p (£366m) - Interim Results - Paul - AMBER/RED
I inwardly groan when this company comes up on the list to analyse.
Checking back to my previous notes, I’ve looked at this internet advertising/domain names company 4 times this year -
31/1/23 - 146p - AMBER - top end of exps. Looks quite interesting.
24/4/23 - 115p - AMBER (almost red) - positive Q1 update. But I dislike the 2022 accounts, and question why it has large cash pile and large debt? Awful balance sheet.
16/5/23 - 114p - AMBER - My most thorough review of the figures, better than I expected, but some concerns remain - how sustainable is profit/cashflow?
3/7/23 - 116p - AMBER - Big expansion of share buyback programme.
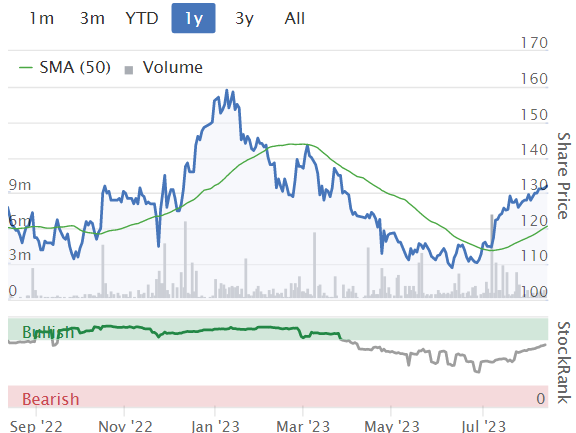
Note that the share price has put on a decent spurt since the buybacks announcement.
On to today’s news, which is interim results for the six-months to 30 June 2023.
CentralNic Group Plc (AIM: CNIC), the global internet company which helps online consumers make informed choices, is pleased to announce its unaudited financial results for the six months ended 30 June 2023 ("H1 2023").
Not a very good start, with a (deliberately) vague self-description.
CNIC reports in US dollars, some key numbers -
Substantial revenue of $396m, up 18%
Net revenue/gross profit of $91.2m (up 11%), so presumably the main element of revenue above must be pass-through revenue of some kind?
IMC webinar is at 13:00 today here. I’ll try to attend, although that sometimes coincides with my lunchtime nap.
I see the commentary is pushing the idea that CNIC is an Artificial Intelligence type of share. There’s a lot of that kind of talk about at the moment.
H1 profit - take your pick from £44.6m adj EBITDA, £17.5m operating profit, or £9.4m profit after tax. These are the highlighted figures in the “performance overview” table. I don’t really find any of those measures satisfactory.
Adj EPS (diluted) is 11.26 US cents, up 37%, but note that last year H1 suffered from a much larger tax charge, which flatters this year’s H1 adj EPS.
Balance sheet - this is usually where CNIC falls over for me as a possible investment.
It’s the same this time too, I’m afraid. NAV is $162.5m, little changed from 6 and 12 months earlier. This includes a huge $335m intangible assets. Getting rid of that means NTAV is heavily negative, at $(173)m.
Working capital is balanced, with $178m current assets (including $83m cash), and $183m current liabilities. On a day-to-day basis, I would expect those to move around a fair bit, since annualised revenues are c.$800m - there could be large intra-month swings in working capital, depending on when customers pay, and when liabilities are settled.
This is the problem area - non-current liabilities contains $147.6m in “Borrowings”. Whilst net debt might look reasonable at $68.2m, it’s the gross debt of $147.6m that worries me more. What we need is the average daily net debt number, which would give us the true picture, ironing out working capital swings. Without that number, I don’t really know how to assess the overall financial position. Other than to say that a negative $(173)m NTAV looks unpalatable to me.
Companies with such a weak overall NTAV really should not be doing big share buybacks, or paying divis in my opinion.
Outlook - sounds reassuring -
Whilst the Directors continue to monitor the global macro-economic environment closely, they are confident in the Group's targeted investment in product innovation, vertical integration and international expansion. These strategic moves have positioned the Group to succeed. Therefore, the Directors expect that the Group will trade at least in line with current market expectations for the full year.*****
Latest analyst forecasts are within a range of USD 783m and USD 834m for FY23 revenue and USD 91m and USD 98m for FY23 Adjusted EBITDA
Cashflow statement - there’s good cash generation at the top, in all 3 periods covered.
Note almost half of this $35.3m operating cashflow went out paying $15.2m deferred consideration. So if you’re considering buying/holding this share, it would be worth digging into the hefty $177m trade and other payables, to check if any of this is additional deferred consideration, since that’s a one-off outflow (bad), as opposed to normal trade creditors that just rotate (good).
Ignoring small items, the rest of the cash generation was spent on $13.9m share buybacks, $3.6m divis, and a hefty increase in interest costs to $6.0m in H1.
Put it all together (with smaller items I’ve not listed), and cash outflows exceeded cash inflows by $13.9m. Coincidentally, that’s exactly the same figure as the share buybacks, so I would argue it can’t really afford to be doing share buybacks, and is decreasing the cash pile, thus increasing net debt as a result of buybacks.
Although you could argue it the other way, that the $15.2m deferred consideration is what caused the cash pile to drop. Depends on how you look at it.
The bank debt is expensive now remember, and note 6 shows H1 interest charges on bank borrowings of $6.1m, so $12.2m annualised, which is a lot. This also suggests that the $148m bank borrowings are fully drawn down all the time, with an interest rate around 8.2% implied. Note 6 doesn't seem to show any credit interest at all on the cash balances.
My opinion - as you’ve probably gathered, this one’s not for me.
The weak balance sheet, and heavy interest costs don’t appeal.
Although, as mentioned before, my main reservation is that however it’s dressed up, this is an online advertising group. I’ve seen lots of similar companies go badly wrong (eg XLMedia (LON:XLM) and maybe Tremor International (LON:TRMR) ), when factors outside their control go against them. All the while the shares look really cheap, and have interesting spikes up sometimes, before resuming the downward path.
Director deals can sometimes shed light on the outlook. M Royde has been a repeat buyer at CNIC, but 3 other Directors have banked about £8m from sales in 2023 to date. That doesn’t give me confidence.
Overall, the investment case here is pretty simple -
Bulls: Low PER, good growth (AI), trading well despite some other online marketing groups reporting subdued demand.
Bears: Profit/cashflow may not be sustainable (cigar butt advertorial websites?), weak balance sheet with too much (expensive) debt.
Take your pick! My instinct is to go AMBER/RED, it’s just not something I want to invest in. But of course we all look at companies in our own way, so good luck to investors who see it in a more bullish way. As always, I’ve no idea what the share price is likely to do, I’m only reviewing the company fundamentals.
Graham’s Section:
Lok'n Store (LON:LOK)
Share price: 738p (+1%)
Market cap: £242m
Lok'nStore, the fast-growing AIM listed self-storage company, is pleased to provide the following update on trading for the year to 31 July 2023.
I like this company but I’ve suggested that its stock may be too expensive. The stock has been coming off the boil in recent months, so maybe it’s starting to get into value territory?

Here are the highlights from the full-year trading update:
Same-store revenue +12.1%
Pricing up 6.8% (good but not quite keeping up with inflation). There is “continued strong demand”.
Total self-storage revenue up 5.3%
The slow self-storage revenue growth of only 5.3% is explained by the company’s strategy to dispose of certain sites after it has built and developed them, on a “sale and manage back” basis. It continues to generate management revenues from these sites, but not self-storage revenues.
This strategy results in the company having very little leverage as defined by its loan-to-value ratio (LTV). LTV was only 8.9% at the time of the interim results.
No. of stores in the portfolio: 42. Bedford and Peterborough opened during the year. Staines, Basildon and Kettering to open in the next 12 months.
Andrew Jacobs is the founder and Chair of Lok-n Store. He says:
"We continue to deliver on our strategy of opening more new stores in the under supplied self-storage market, adding 9.7% to our owned available space in the last 12 months. We are onsite at 3 further new stores, all of which will open in FY24 and have a secured pipeline of a further 8. These new stores will accelerate our growth in cash flows to fund more dividends to shareholders and more growth of the business."
Estimates - today’s RNS doesn’t provide much information on estimates but a note from finnCap confirms that there is no change to forecasts. For FY July 2024, these suggest revenue of £29.8m and adjusted EPS of 25.4p.
Graham’s view
In June, I said that I would be more interested in these shares “around 700p”. With the shares currently around 730-740p, I’m going to stubbornly stick with a neutral view on them.
I previously calculated that NAV (including deferred taxes) was 645p, a much lower number than the company and its broker uses but one which I think is fair. I’ll revise this figure when I get the next balance sheet. Remember that the earnings multiple here isn’t cheap, either (pushing 30x, depending on how you measure it).
Also in my mind is the Director Dealings page:

There were token-sized purchases of stock back in 2022 but they have been fully reversed by sales and the sales have been substantial.
Therefore, while it’s tempting to turn bullish on this given the recent weakness in the shares, I think it’s important to stay disciplined. So I’m still neutral, waiting for a lower entry point.
Hostelworld (LON:HSW)
Share price: 134.5p (+5.5%)
Market cap: £166m/€192m
10th August 2023: Hostelworld, a leading global Online Travel Agent (OTA) focused on the hostel market, is pleased to announce its interim results for the six-month period ended 30 June 2023.
These results were published late last week, but we didn’t get around to them at the time.
As a reminder, Hostelworld is a post-Covid deleveraging/recovery story. Its balance sheet has improved, its revenues have recovered to pre-Covid levels, and it is encouraging travellers to use its “social network” to make friends during their holidays.
Here are the H1 results:
Record gross transaction value of €339.5m
Record revenue €51.5m
H1 loss €7.5m (improved from a loss of €14.3m in H1 last year).
Last year, the company was still suffering from Covid-related disruption.
But it’s in a totally different place now.
Let’s consider it from the perspective of adj. EBITDA:
In H1 last year, adj. EBITDA was negative €5m.
Full-year adj. EBITDA was positive, so the H2 result was positive by over €5m.
In H1 this year, adj. EBITDA is +€5.1m.
And the expectation is that H2 adj. EBITDA will be up to €12m, for a full-year result of up to €17m.
Granted that these aren’t “real” profits, but they are hopefully a good start on the road to real profits.
Net debt finished H1 at €16m, down from nearly €22m at the start of H1. The company is now only paying a margin of 3.25% over EURIBOR - a great value facility, compared to what the company was paying before.
CEO comment: among other things, he discusses the resurgence in cross-border and especially long-haul flights, and “follow-on” flights after an initial journey. All of these things are good for the hostel sector.
Outlook is similar to before. Hostelworld now routinely includes a disclaimer that their performance depends on flights/travel not being disrupted as they were before:
The Board remains confident in the long-term resilience of our business model and the potential of our differentiated growth strategy and reiterating earnings guidance of adjusted EBITDA in the range of €16.5 million to €17 million for the full year, absent any deterioration in the macro-economic climate, the re-introduction of travel restrictions or other air travel related disruptions.
Which earnings measure is best? Hostelworld provides multiple earnings measures, so it’s not easy to decide which one to focus on.
Going down to the income statement to investigate, I think the one I’d use is operating profit/loss.
This wouldn’t work for a company with lots of lease liabilities, as leases have an interest expense that is excluded from operating P/L. But Hostelworld has minimal lease liabilities.
Also, Hostelworld’s exceptional items this year almost all relate to the cancellation of its old borrowing facility. These exceptional items are considered a finance cost, so again they aren’t relevant to the operating P/L.
Hostelworld’s operating loss in H1 was c. €1.6m (an enormous improvement from the c. €13m operating loss in H1 last year).
A large part of the loss relates to amortisation of intangible assets. Hostelworld’s cash flow statement is much more impressive than its income statement, so it could be argued that the income statement is overly harsh on the company.
Graham’s view
In July I said: I’m close to turning green on this one, but I’ll hold out and wait for proof of convincing profitability down at the bottom of the income statement.
It’s tempting to go green today, but I think that would be a little bit rash. I did say that I wanted proof of profitability on the income statement. The company has not yet done that.
Hopefully it will do it soon.
Stockopedia doesn’t rate the value on offer here very highly: the ValueRank is only 19. That’s a helpful sense check for someone writing a “Value Report”! With the ValueRank so low, I feel a little better about sticking with a neutral view. But I do rate this company highly, and I’ll be very happy for them if/when they start to generate real profits. They did that pre-2020 and they should be capable of doing it again.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Paul, Thanks for your Green flag for OTB. I also believe OTB should do well under high interest rate era as they are renowned for their competitive cheap holiday packages. Good luck to all the holders.
An interesting article in the FT based on some analysis of how individual stocks have performed against 'local money' measured on the US Stock market. Measured from 1926 to 2016 the majority of individual US stocks have lost money, measured against a local money benchmark (e.g T bills). Specifically only 42.6% outperformed, and that basically it was down to 4% of stocks accounting for the entire net shareholder wealth between 1926 & 2016. This was updated this March when the figure of underperforming stocks amounted to 58.6% over the last three decades. This was even worse in markets like the UK - but it seems to apply to a greater or lesser extent in other markets. This was analysed on the basis of reinvesting dividends.
This seems to indicate that unless you invest in aggregate (presumably on an index tracker?) as opposed to stock picking, you lose relatively speaking - or at least that's my take on it.
I am sure that speaks to something of the experience of those of us who are huggers and holders of individual equity stocks.
I am not the best interpreter of this information, but it certainly seems to goes against the grain of general investing advice that-equities are the best investment over the long-term- save perhaps when that investment is either in a restricted number of top performing stocks, or in a broad tracker to allow the market as a whole to be the measure of aggregate outperformance.
The article is not behind the FT paywall but you do have to register for FT Alphaville, to get access.
https://www.ft.com/content/caa...
I strongly suspect it’s the Bessembinder study that is being referred to. 2 opposite conclusions in my opinion: 1) all the returns to the stock market are driven by an incredibly small sample of stocks, so you are best off indexing as at least you are assured to get exposure to them or 2) if you have the skill you can pick some incredibly high returning stocks, run your winners but be prepared for high individual volatility eg Apple has declined over 70% 3 times. So it’s iron constitution time. (I’m in camp 2, FWIW)
Here’s the study
https://papers.ssrn.com/sol3/p...
I couldn't read the article but these figures are often misleading. To compare an index over a 90 year period with the individual components might sound like a fair comparison - but I don't think it is.
Obviously the index will always exist and so will compound over time while the component companies come and go. Most discounted cash flow models assume all future earnings of a listed company to be only about 15 - 20 years. So if you invest in that company, it may do very well for a very long period but at some point it will likely fail.
The general view is, over an infinite period of time, all businesses will eventually fail / go to zero. But you don't have to hold for an infinite period!
If I asked the question - will Volex outperform the market over the next 90 years - it would sound like a bit of an odd question. Because no one intends to hold it for 90 years. I am pretty sure the index will still be about - but who knows what may happen to Volex. Maybe you hold Volex for 30 years and then as their market position changes or if management becomes questionable, maybe you decide to sell - and perhaps the company fails in 61 years time. So the FT comparison really has no bearing on whether it would be a good investment today - it could outperform the index for decades and then when it eventually fails - as one assumes all businesses will - then the index (the tortoise) will keep marching on forever - thus defeating it easily on the long 90 year comparison model through its immortality.
The idea that you would hold anything forever for infinite success makes little sense. So the point is that you can trade in and out of stocks depending on the companies prospects. You can make a lot of good long term investments (betting on the hare) - but they are never likely to fair well over a comparison period of 90 years and compared against an immortal index which will never be going anywhere. No one buys with a 90 year view. I am sure Warren Buffets portfolio has changed a lot over the decades. I am sure he did very well on companies that are no longer around.
(Also there are so many delistings, merges and acquisitions that the terms of the comparison should be made a bit clearer).
cheers
Matt
Holding(s) in Company - 15:30:44 14 Aug 2023 - DLAR News article | London Stock Exchange
De La Rue (LON:DLAR)
Another interesting 'purchase' , although it is a CFD, Richard Griffiths seems to have upped his exposure in De La Rue
Good weekend podcast Paul.
I think the "macro" every week is overkill - by definition that would be prone to being repetitive of previous weeks and also observations made in the company podcast (but which make sense retained there when the is sectoral look-across or other themes arising, e.g. from profit warnings). Perhaps a monthly round-up and take-stock might work best?
Hi The Jayman,
Yes I agree that a macro podcast every weekend is overkill, that's why I've stopped doing them - it was mainly repetition of the same points. So I've gone back to just adding any macro comments into the main companies podcast. I might do a special from time to time, if sufficient new material appears.
Thanks for the feedback.
Regards, Paul.
Housebuilders looking like they may roll over this week
Is there a UK housebuilder tracker or ETF you can short?
Hello Wolf,
Thanks for that. Been looking at housebuilders as a potential short this past few days, any you think are more shortable than the other? I would favour Persimmon (LON:PSN) & £RDW.
Regards,
IG have a FTSE 350 Household Goods and Home Construction index type of thing you can short.
Grateful for your updates on CentralNic (LON:CNIC) Paul. Ended up selling at 128p at the end of July. The debt combined with buybacks didn't sit well with me. Happy with the decision; even if sp momentum continues I'm more concerned with sleeping comfortably at night.
Nice looking chart on Volex (LON:VLX) just now. Ideally would like to see a volume spike on the breakout, but beggars cant be choosers in such thin markets.
Price surfing above the moving averages rather than drowning underneath them on the way down.
Volex (LON:VLX)
Much discussion of the dangers of averaging down in this parish. But this is one where I did commit the cardinal sin at levels well below the 200 dma. And very happy to have done so am I. My investment is back to where it started in performance terms, while still 20% down on the level of my original purchase, providing hope for future upside. And it still looks cheap!
I guess this is the benefit of not sizing too ambitiously in the first bite. You give yourself the option of doubling up without pushing the position size to uncomfortable levels.
"Looks Cheap". What is your valuation? I'm at £725m - so 10% margin of safety from todays ent value. Interested in your valuation.....
I'm in the region of £850m for enterprise value. Still more than 5% below HSBC, who've raised their PT to 510p today. In a more accommodating market, stock should be on a mid to high teens fwd PER in my view, taking into consideration past performance, growth trajectory and secular drivers.
Volex (LON:VLX) do we know what HSBC said? Did they raise their PT and forecasts based off the Tesla announcement last week?
Oops - error
I want to pay the least amount possible for any given stock, clearly one doesn't want to stand in front of cavalry charge or play King Canute, but if a share is cheap and the company is to my eyes undervalued and not drowning in debt, my inclination is to buy. The share may of course get cheaper but my inclination remains to add, provided the investment thesis continues to hold water.
I look to buy where I believe the share price fall has been overdone. However this doesn't also work as one hopes. Watkin Jones (LON:WJG) being a prime example, where the near term recovery prospects were not as management envisaged or initially expressed to the market. Having bought/added around 75p, I exited around 50p!
Volex (LON:VLX) is a more positive example. I have held shares in Volex (LON:VLX) since 2019 having added some and sold some along the way. Today it is my largest holding having added this year 5 times between 230p and 293p. Hopefully this will prove to be a better experience that Watkin Jones (LON:WJG).
Whilst we are on the subject of dubious big business practices you can add the recently highlighted issue of Etsy and Amazon withholding funds from businesses who use these platforms to sell their products. Less publicised was Booking.com withholding 3 -4 weeks of letting income in June & July citing maintenance of its payment system at the busiest revenue generating period of the year. These 3 businesses will have generated significant incomes from monies held on deposit. Surely there can be no coincidence that this is happening in the current high interest rate environment.
I think you have touched on the reason cash is being held back. Strikes me it is hardly a coincidence high interest rates have coincided with a decision to hold onto payment money for longer. Didn't we also an interest rate contribution made to the p&l on Plus 500 deposit accounts?
CentralNic (LON:CNIC)
Paul writes "Director deals can sometimes shed light on the outlook. M Royde has been a repeat buyer at CNIC, but 3 other Directors have banked about £8m from sales in 2023 to date. That doesn’t give me confidence".
Note that Max Royde is a Managing Partnerof Kestrel who hold 23.8% of CNIC. This breaks down roughly into 6.35% held in Kestrel Opportunites fund and 17.45% held on behalf of discretionary clients. In both cases Mr. Royde is deemed to have a beneficial interest and hence is shown as a director deal..
Re CentralNic (LON:CNIC) - ah yes, thanks for pointing out that the M.Royde purchases are really Kestrel. I'd forgotten about that!
Stelrad (LON:SRAD) interims today. I don't hold, but starting to research. Looks a good company with a #1 position in radiators and a solid management team + record. New radiators are probably getting a bit more growthy with the energy transition.
Downside is it was a private equity float (but dropped c50%) with selling shareholders still having a controlling stake, challenging end markets and debt a tad on the high side following an Italian acquisition.
Will keep watching for now as probably at risk of an H2 warning given the very challenging end markets.
Anyone else holding / following?
Stelrad (LON:SRAD)
Can see why you are interested here Topvest. Superficially looks cheap with PE of 5.9 and a leader in a likely growth market.
I agree with your bear comments. In particular I'd be very wary of Private Equity floats (or any 2021 IPO's) and also level of debt (1.75 x f/c EBITDA). Private Equity trousered £60m at IPO so have already done very well but still hold 49.5% so investors are just along for the ride.
Floated at 215p, now 118p after today's rise.
Would also add;
Short term forecasts don't look good. EPS f/c down 30% to 13.3p with a forecast dividend cut of 20%. There is also a pension deficit of £4.5m (up from £1.7m) which would need researching.
Too much potential downside for me but good luck if you decide to invest.
Snazzy
Thanks Snazzytime yes, agree with you. I will keep on my cyclical watch list though. Maybe a tad too early at this stage as its still in a downtrend and I can't see their end markets getting any better in the next 6 months.
Stelrad (LON:SRAD) It may have changed since but many years ago I went round their factory. Basically they took sheet steel punched the profile into it then welded it to another piece. Very automated but also completely reliant on the price of their main input (steel). I haven't looked at it since it floated, but keep an eye on steel prices.
CentralNic (LON:CNIC) [I Hold] CNIC have enjoyed impressive growth over the last few years and have reached a size where operational gearing should improve the margins. However, like Paul, I find the focus on EBITDA disingenuous given that much of the acceleration in business has been by buying what is in effect goodwill. I notice a small decrease in pre-tax profit at the half year, after amortisation, which (other than in strict accounting terms) is absolutely a cash expense - indeed it is a deferred recognition of cash expenses previously incurred! Looking to the future I see two critical factors that will affect its success or otherwise:
1) Much of the intangible asset will be fully amortised in 5 years time. If the goodwill in those underlying businesses have been successfully maintained that will result in a large increase in profitability - the EBITDA will increase close to pre-tax profit.
2) The rapid organic growth element of recent years is a hard act to maintain. I suspect that the retail comparison service to on-line shoppers (which, to be fair, is pretty awesome) had a massive boost during the pandemic, when shoppers couldn't go to John Lewis to touch and discuss the products they wanted to buy. The fact there is any organic growth is an achievement; potentially future years will show a much improved growth rate, even if not quite the 60%+ we saw in lockdown.
Against these positives I agree with Paul (again!) it is too soon to be paying dividends and doing share buybacks. Until recently the CEO was CFO providing a stabilising influence on the management team, so hopefully he will be sufficiently astute not to put the whole operation at risk in an attempt to please shareholders. My (unfounded) suspicion is that his promotion may have been tied up with agreement with some large shareholders to start returning capital to the members.
I believe the business model is more secure than that of XLM (though I have lost money on that one) but have reduced my holding to take some risk off the table - a tactic the last two years has taught me!
I too am a holder of CentralNic (LON:CNIC) and rely on Paul to give me a twice yearly dowsing of my enthusiasm. On a couple of his points I would note that the Directors sales shown in Stocko, which drive his concern, are almost all by two holders, Sifferin and Dayani. It seems fair to note that a) Sifferin is not a Director and that b) Sifferin has reduced his holding from 12.4% to 11.3%, while Dayani has gone down from 5.4% to 4.8%. I don't see this as actually heading for the hills, both retain substantial amounts.
Also I would note that the deferred cash payment for the purchase of a company was fully earned in cash by the new subsidiary. So they successfully bought a company that is funding its own purchase - I would count this as a good thing, justifying some non-cash goodwill.
I will try to listen to the update at 1pm or check later.
Hi Aislabie,
Interesting points re CentralNic (LON:CNIC) thanks.
Although one one point, you said -
Also I would note that the deferred cash payment for the purchase of a company was fully earned in cash by the new subsidiary. So they successfully bought a company that is funding its own purchase - I would count this as a good thing...
Companies often say this sort of thing, but on checking its cashflow statement, H1 2023 operating cashflow actually fell by about 10% to $35.3m, vs H1 in 2022. So depending on when the acquisition (which triggered the deferred payment) was made, it doesn't seem obvious that the acquisition actually has boosted overall cashflow. Or I suppose it's possible that it might be masking a heavier fall in cash generation in the rest of the business. Or it could have been included in the last year H1 figures? Not sure, but the key point is that operating cashflow is down, not up.
Regards, Paul.
On Beach group (LON:OTB) Director buy - Simon Cooper bought £2,500,000 at 88p last week.
Fantastic endorsement. I've been accumulating lately as On Beach group (LON:OTB) and Saga (LON:SAGA) have been left behind the curve. SCSW (scsw.co.uk) thinks it's a sitting duck to a predator.
He pocketed £14m! a couple of years ago after selling around £4m shares at 360p.
What that really means of course is that he can afford the £2.5m. It's still a decent chunk of cash to justify to your other half if you invest it badly.
Hill & Smith (LON:HILS) H123 presentation given to analysts last week video & podcast. Exceptional results from this enigineering company that has 3 divisions: Galvanising, Engineering Solutions and Roads & Security. The US is driving the success. With a Market Cap of £1.37bn it is slightly larger than companies usually covered here. Has a stock rank of 90 and qualifies for the 52 week high momentum screen and is described a 'high flyer'. A summary of the highlights:
Management have been buying which reinforces the positive commentary. Sadly Alan Giddins, Exec Chair is looking to retire by this time next year.
Great overview Woss thanks. Would you be willing to share the screens you use as part of your routine to populate these viewpoints. I would be super grateful as I'm always looking for ways to refine screen searches.
VMT
Caduceus, just as in the 'IT Crowd' when Jen thought typing Google into Google would break the internet............talking about sharepad filters in the Stockopedia comments section may blow up SCVR. :)
I completely agree Paul on Glantus Holdings (LON:GLAN)
Was a joke float right from the start. They said the first thing they'd do was to renegotiate expensive debt they had with Beachpoint Capital. They didnt, presumably because no normal bank would touch them. The end.
I wasted an hour of my life listening to Maurice Healy talk hot air on a presentation after the float. At least hes a name everyone can add to the uninvestable management list.
Boohoo (LON:BOO) hires a third broker. Does a sub 500M company need three brokers, or should it be "cuttings its cloth to suit".
Umar Kamani now a 3% shareholder, Frasers recent holding 5%, is a private sale or fund raise on its way?
Morning GloucesterBob,
Curious indeed that BOO has appointed a third broker - Graham spotted it and messaged me about it earlier. We can only speculate as to why they've done this, but it does seem curious. I suspect the family might want to take it private possibly, but that's a complete guess. They're very hard negotiators, so I wouldn't expect a generous premium! They can't be happy seeing Mike Ashley buying up shares either.
Did we ever solve the conundrum of who provided the large borrowing facility, that was fully drawn down? People assumed it was HSBC, but I don't recall ever seeing that specifically confirmed by BOO.
Personally, I wouldn't write off BOO shares. It should be able to rebuild margins, at least somewhat, now that sea & air freight costs are so much lower.
Hardly anyone spotted the competitive threat to BOO and Asos from aggressive Chinese fashion company, Shein. That, together with supply chain problems during the pandemic, was what wiped out BOO's profitability. All the stuff about corporate governance, factories, etc, was a complete sideshow that had no commercial bearing on things at all (EDIT: probably).
Regards, Paul.
I still don't get how sending parcels from China, is cost-competitive in terms of shipping costs, compared to locally sent parcels within the UK.
Would love to hear thoughts - but I remember reading ages ago that the price charged by national postal companies to other countries' postal companies was complex, fixed, and likely subsidised.
If there are any experts out there I'd love to hear some views on this!
Presumably the goods are made in the Far East and therefore come to the UK anyway whether it is direct or via a wholesaler/retailer, so transport costs are still incurred whether sold by Schein or Boo.
I thought that Boohoo (LON:BOO) employed their own slave labour in Leicester, as there was a scandal concerning their suppliers working conditions a couple of years ago. It may be as you say though, and that they decided discretion was the better part of valour, and moved the whole shebang to a more 'slavery neutral' country :o). In general though, I agree with your point - even for 'premium' products, many are still made in the Far East, the Chinese model of local sourcing (as the US used to, maybe still does), means that IP can be stolen with ease. It may be that trend is to onshore now, and that China has its own problems, but I can't see them giving up their position without a fight.
Boohoo (LON:BOO)
No cheekyminnows, that was a band-wagon created by union organisers and labour MP's to shut down what for many years has been part of the garment industry and that is work farmed out to small companies and individual homeworkers. Many worked happily in this fringe economy doing hand finishing or simple machining to earn money at home in their spare time until do gooders got involved, the likes of Keith Vaz MP, remember him and drugs and rent-boys? They would rather no jobs than unorganised jobs when union subscriptions help support the Labour Party and vice versa.
Boohoo (LON:BOO)
the issue here is that i suspect Bohoo were probably well short of expected standard ref supplier integrity checks. This being the case boohoo only have themselves to blame imho for not doing the basic due diligence they should have done - and therefore leaving themselves open to valid criticism.
https://assets.publishing.serv...
Hi Samsgrandad, just to clarify - my views are based on a healthy skeptisism of company behaviour, rather than any partisan position. I am sure that there were some instances of dodgy working practices, just as much as I am sure that these were exagerated by some who believed they had something to gain. Despite how odious Keith Vaz is, I thought he came under critisism for the affair, rather than highlighting it. Anyway, I only wanted to point out that I thought Boohoos production was UK based, rather than Far East.
Fair enough, I'm a sceptic too but I thought "employed their own slave labour in Leicester" was pretty damning and probably based on hearsay evidence whereas I lived in Leicestershire for many years and saw the rise of unemployment in the whole industry. It used to be a significant employer of mainly women in most towns and workers could and did vote with their feet if employers treated them badly. The same applies to Nottinghamshire.
Yes, emotive language from me - a mistake. I meant it more as amusing rather than a harsh criticism. I take it back !
Haha, my emotive language has got me a red flag from someone who doesn't believe in me voicing my opinion.
From memory, they tend to design and produce a small run in the UK before offshoring larger production runs of successful items. 2022 opening of their own factory took some of the local politics away and allows them to template the production and use the facility to train the offshore manufacturers.
There was an article at the weekend, I can't remember where (probably Saturday Times), focusing on Temu. Said that majority of stuff test-purchased was complete tat. Delivery costs (to the consumer) are zero or near zero, with Temu accepting the burden as a cost of buying market share. That the company avoids import duty by almost all packages being below the £130 cut-off. Supply chains not audited and probably relying on slave labour. We buy from such Chinese companies at our long-term peril.
Why are Boohoo (LON:BOO) employing HSBC as a 3rd broker? I can only think they hope they will gain some intelligence on trends (regulatory and commercial) in China. It all sucks.
Couldn’t agree more grumpy5 about Temu. They buy from cheapest supplier so quality is what you get when price is the only factor. Chinese are ruthless long term actors and we will all lose if we allow cheapest wins policy to succeed.
Saturday Times Temu article is here (I subscribe so apologies if this is blocked for non-subscribers). I won't be buying any goods from them after reading this although I expect plenty will be doing so.
Use this link to read it https://archive.li/9sejK
In a country where you can barely take a dump without the political class regulating and taxing everything, they seem very relaxed about loss making Chinese junk putting British businesses out of business. I guess they'll see it as good for inflation, just as mass immigration is good for GDP.
After all the hoo-ha about UK following EU regulations when we left, its incredible these same people couldn't care less about the working conditions, regulations, workers rights and net zero when it comes to China.
Just to add a few penneth .
I’m on the train on way back from Java .
On the subject of low cost labour not really limited to Chinese companies penetrating the UK market .
We drove past a huge factory with thousands of workers leaving their shift .
My friend driving started spitting feathers .
I asked what he was on about .
The min wage in that factory a woeful 5 usd per hour but the government have allowed a 2 year exemption “trial period” for employers to pay 3 usd per day .
Unscrupulous employers then have the workers for 23 months and 30 days then get rid so they only have to pay the 3 usd rate .
The employers are Nike and Reebok .
Easy for us to pin our negative views on a Chinese company clearly taking advantage but the bigger abuses are happening right on your feet and in your wardrobe .
I have no answers the world is bonkers .
The bigger the corporation the bigger they chase slave labour around the world .
Typo ! 5 usd per day !
That reminds me of being on the dole in the early 1990's when I was forced to take a job as a night security guard. For £2.00 an Hour!!
Needless to say if anyone had wanted to steal the contents of the warehouse Id not only have let them get on with it, Id have helped them load it into their vehicle.
Looking back I should have just said I was scared of water or warehouses or the dark
My worst job was at Safeway, the (now thankfully defunct) UK supermarket. They paid me just over £1 and hour, in about 1984, for a 4 hour shift that was back-breaking, and ended up being nearer 5 hours (but they only paid for 4 hours, then locked the doors so nobody could leave until the supervisor, a horrid little toad called Amoire had deemed that the work had been completed).
They sacked me over the phone when I took some time off for a family holiday, so I told them to stick it.
The supervisor stamped on my foot once, when I was impertinent. Oh, and a warehouse operative pinned me up against the wall and told me he was going to sexually assault me, which wasn't a high point either (I yelled at him & pushed him away from me, and he left me alone after that).
Honestly, young people today, they don't know they're born!!! ;-)
I enjoyed working at McDonalds. Learned loads about running a business, stock rotation, metrics, planning etc I think it was £2.26 an hour in 1988
Ha, you young ones! £1 an hour? In the late 60's I earned £13 a WEEK (£10 without London weighting) as a Junior Research Technician, with A levels.
As a 15- and 16-year old, I got up at 5:30am to do an hour's paper round for £1.27 per week for a 7 day round, so less than 20p per hour. Never missed a day. I've since made a few bob as an adult and I suspect there's a connection.
No, not that I'm a hard worker, although I am. I learnt that it's worth working in an industry with big profit margins.
I seem to recall that Paul bought some items through Temu and recommended them on a fairly recent Podcast !!! :)
I wouldn't say I was recommending Temu items overall. Many where shockingly bad quality. But the earbud headphones were Lenovo, and only cost £8, and work perfectly. That was a stunning bargain. Also I gave some kitchen items to Mum for her recent 86th birthday, and she was delighted with them. So it's a bit hit & miss.
On the ethics side of things, I know it's wrong to buy cheap Chinese-made junk, that's air-freighted into the UK. But it's a bit like buying pawnbroker shares - you know it's wrong, but when they're on a PER of 4x and yielding 8%+, you can't help yourself, and ethics go out of the window!
"... the company avoids import duty by almost all packages being below the £130 cut-off. "
Temu do charge VAT though.
US Markets
S&P down slightly on the week. Big reversal day on Thursday after an initial rally (inflation data) Tested ~50 day ma Friday and bounced slightly. I closed my short on Friday.
VIX is subdued, Greed + Fear is still elevated. MACD on sell but plenty of support below with uptrend well intact.
Semiconductor index biggest weekly fall since October
Happened to see the story last week that egomaniac George Noble's stupidly named 'NOPE' ETF is being wound up.
He's one of those people who cant help himself making big macro calls, had a 50/50 chance and he was wrong, losing 60% of other peoples money in about 10 months. Waste of time listening to 'experts', no one really knows where the market is going.
He said right at the bottom in October last year “Hedge funds who are basically just long-only funds and drag with leverage, and they've been buying Facebook and Apple, all that kind of stuff, they're going to get destroyed," Noble said. "They've been getting destroyed............. what the wise man does in the beginning, the fool does in the end”
Looks like hes the fool!
UK Markets
FTSE 250 was down just under 1% last week on extremely low volume, continuing the sideways pattern since March
No change from last week.
Only 5 shares above 2x normal weekly volume
70 Above 50 + 200d moving averages
AIM All Share was down almost 1%
No change really from last week. Just about triggered a sell signal on MACD and trend very much down, tho theres still some good opportunities for quick bounces in individual shares on good news/sellers clearing.
153 above 50 + 200d moving averages
56 above 2x normal weekly volume
Always good to lookout for risers in a down week. Card Factory obviously after a very good update but 2 that caught my eye were SAGA and On The Beach up 6.6% and 10%
on the beach saying Sunday “UK holidaymakers are flocking to Turkey and Egypt to take advantage of favourable currency exchange rates, according to a travel company. On The Beach said the number of bookings it has received for summer trips to those destinations is more than double the level from 2019, before the coronavirus pandemic.”
How this translates into profit Ive no idea but they're 2 travel companies left behind on the summer travel bounce.
Where did you see the On Beach group (LON:OTB) story about Turkey and Egypt? Do you have a link?
https://www.independent.co.uk/...
On Beach group (LON:OTB)
per this article
Holidaymakers visiting Egypt are receiving approximately twice as much local currency for sterling than they were before the virus crisis
- if the turkish lira - egypt whatever are depreciating quickly surely prices charged to uk "vistors" are likely to also be appreciating at a similar rate in local currency to compensate ? - i cant imagine traders in these 2 countries will be doing anything other than trying to extract "top dollar" from all uk visitors.
It’s also on the Sharepad news from Sunday
Saga (LON:SAGA)
I noticed that Sabre Insurance made some very positive noises on pricing in motor insurance (20% up) from memory. Insurance names usually respond well to pricing inflection.
Its possible that both sides of Saga may be performing well at the same time-finally!
There have been big rises in Motor Insurance premiums, as I suffered recently. Mostly the industry is following suit, so comparison sites are not really eroding margins too much.
Saga (LON:SAGA)
on the basis saga have been telling us that its tough out there as recently as 60 days ago i am not inclineed to presume its exactly the opposite of what they have been telling us investors !!!!!
note if we take a look at broker forecasts these have clearly taken further tweeks downards since june for this year and next - so the reality of what the company is saying is the opposite of any sort of glimmer of hope - things have continued to worsen ref their nod and a wink approach to updating shareholders !
per company june
In Insurance, market conditions, particularly in motor, continue to weigh on our Group result.
Note there perhaps is a glimmer of hope - perhaps if premiums are going up en masse NOW s they might be more positive on the next update. However if things have taken material turn for then better i would expect them to officially tell the market that is the case rather than not issuing timety update.
The reality is that there are several reasons why prices are going up that are explained by specific extra costs rather than free lunch for providers - so higher premiums may simply be reflecting higher costs !
https://news.sky.com/story/why...
Any company in this area need to box very clever at present so as to maximise profits/keep customer base/steal customer base of competitors without doing so in mannner that would upset the regulators. Unfortuantely i wouldnt trust management here to be able to get out of carboard box never mind boxing clever ! - hey ho any hope is probably slightly better than no hope - so perhaps it will all come good next update "onwards"?!
Speaking of On Beach group (LON:OTB) - big share purchase by founder - nearly £2.5m.
Previous purchases recently where:
- Dec22: £340k at 118p
- Aug22: £2m at 130p
Current holdings of c£11.5m so these are quite sizeable buys in the last year.
Annoyingly, this probably means that current trading is not outperforming market expectations (otherwise he wouldn't be able to trade, as insider information?) so at best will be an in-line trading performance so far this summer?
(I hold in the Boon Fund)
Hi Boon,
On Beach group (LON:OTB) - is that correct that he cannot trade due to knowing how trading is going?
I thought that they couldn't trade only during "closed periods" which is just before a TU/results or some other market sensitive announcement.
If they aren't due a TU for a few more weeks they possibly haven't entered a closed period yet.
I am obviously biased as I hold, but I took this as very positive news.
Every public company I've worked for, has internal rules on trading if you have no public information that is market moving, even if the trading window is open.
But maybe not him? Non exec role now, so supposedly removed from day to day business information...
On Beach group (LON:OTB)
presumably if they know trading is materially ahead of public expectations - that would require an immediate release to the market?
Obviously what is material here may be subjective particularly if you have been sketchy ref propsects in the first place. Can't argue with those that choose to follow the money here when all the other ducks are lined up too. But i would like to think director cannot bu knowing they are materially ahead but without that info having been released.