Small Cap Value Report (Mon 14 Oct 2024) - Gambling sector. THRU, MUL, OBD, TIFS

Good morning from Paul & Graham!
All done for today!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
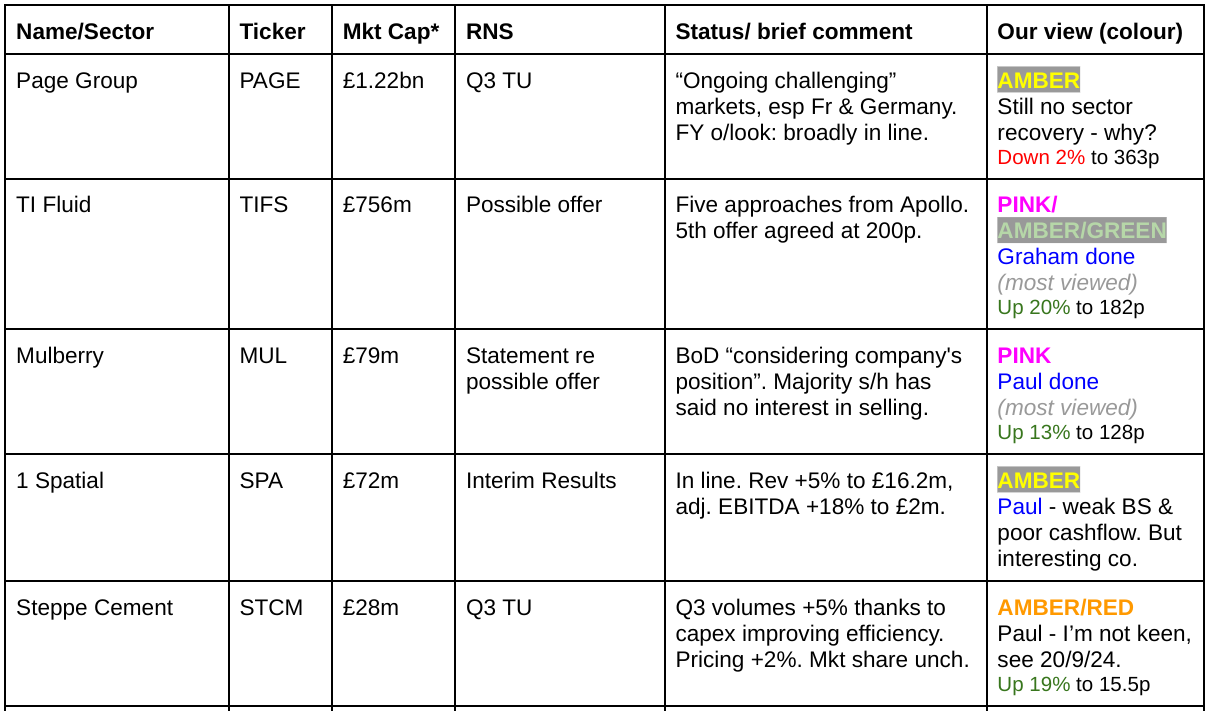
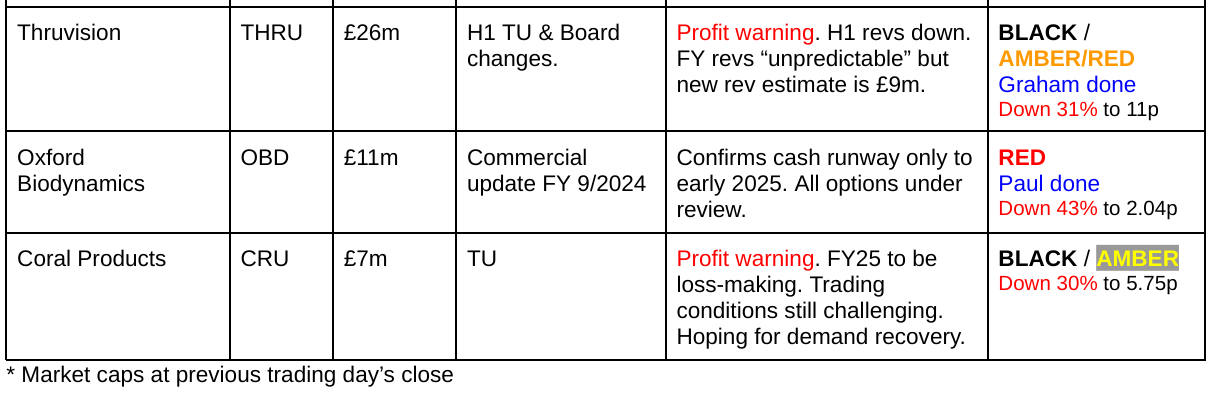
Summaries
Thruvision (LON:THRU) - down 6% to 15p (£24m) - Trading Update and Board Changes - Graham - AMBER/RED
It’s a profit warning as this provider of people screening equipment fails to catch any large orders in H1, and it can’t predict what large orders it might secure for H2. With the cash balance below £2m and losses at the adj. EBITDA level, this one seems very risky to me.
Mulberry (LON:MUL) - 113p (pre-market) £79m - Statement re revised offer from Frasers - Paul - PINK / AMBER/RED on fundamentals
I run through recent events in FRAS trying to bully a majority shareholder into selling, and so far drawing a blank. Meanwhile MUL reported dire recent results, and a £10m emergency equity raise.
Oxford Biodynamics (LON:OBD) - down 43% to 2.04p (£6.5m) - Strategic Review - Paul - RED
I'm quite surprised to see OBD shares take another nosedive today, given that it's only reiterating what we already knew - that the cash runway is rapidly running out, and set to overshoot and crash into the undergrowth on the airport outskirts in early 2025 - very soon, in fundraising terms. They're looking at all available options, so let's hope mgt can pull something out of the hat, and fast. Otherwise existing shareholders could be lambs to the slaughter.
TI Fluid Systems (LON:TIFS) - up 19% to 181.8p (£903m) - Statement re: revised offer - Graham - AMBER/GREEN
Exciting news for TIFS as we learn of three additional bids for it, from a private equity-backed automotive parts supplier. Two bids were previously disclosed, so there are now five in total. I expect this deal is likely to go ahead at 200p as I think the biggest TIFS shareholder wants out.
Paul's Section:
Gambling Sector
I noticed that several mid-large cap gambling shares have dropped sharply this morning, eg -
Entain (LON:ENT) [Ladbrokes] down 14% to 659p (reducing its market cap c.700m to £4.2bn
Evoke (LON:EVOK) [888, highly geared] - down 14% to 56p (£251m mkt cap)
Flutter Entertainment (LON:FLTR) [Paddy Power & others, also highly geared] - down 8% to 17,125p (£27.6bn)
The newswire says the reason is -
“media report the Labour government is mulling a 3 billion pound ($3.92 billion) tax raid on the gambling sector to shore up public finances.”
I’ve found a Guardian article, key excerpts -
“Treasury officials are understood to be weighing up proposals, put forward by two influential thinktanks and backed by one of the party’s top five individual donors, to double some of the taxes levied on online casinos and bookmakers…
Sources familiar with the discussions said the Treasury had yet to make a decision but appeared receptive to tweaking the UK’s complex regime of betting and gaming duties to raise extra funds of between £900m and £3bn, despite opposition from industry lobbyists.
“It’s definitely on the map,” said a source familiar with Treasury thinking. “There’s no obvious pushback to it.”
Paul's view - here’s another good reason to avoid shares in this horrible sector.
Mulberry (LON:MUL)
113p (pre-market) £79m - Statement re revised offer from Frasers - Paul - PINK / AMBER/RED on fundamentals
This is a strange situation mainly because of its absurd shareholding structure, where there is hardly any free float thanks to the 2 major shareholders owning 93.5% of the company. If AIM has a long-term future, surely this is one of several obvious areas for reform, to increase free floats to a sensible minimum, and improve liquidity?
Frasers (LON:FRAS) has been increasing its stake, and mooted a takeover bid, but there’s no point in doing that unless it persuades the majority shareholder to sell.
Previously, on 30/9/2024, FRAS issued a statement critical of MUL, saying it (a supportive major shareholder since 2020) had not been consulted until the last minute about the company’s 100p fundraise, and that FRAS would have been prepared to invest more, potentially on better terms. FRAS indicated it would be prepared to buy the whole company for 130p.
Shortly before that, on 27/9/2024, Mulberry issued terrible (FRAS has publicly called the figures “catastrophic”!) results for FY 3/2024, reporting a £(34)m loss before tax. The going concern statement included a “material uncertainty” over banking covenants in a downside trading scenario. So this is clearly a financially distressed situation, but it has the support of banks and major shareholders, so should be survivable.
NTAV at 3/2024 was only just positive, and was in freefall, so I suspect unless the new CEO takes drastic cost-cutting action, the current equity fundraise probably won’t be the last.
The value in the shares is the brand name, which did have extraordinary success selling expensive handbags from 2010-17, but fashion risk being what it is, those glories have not been repeated yet.
On 1/10/2024 both MUL’s Board, and its controlling shareholder rejected the previous 130p approach from FRAS, saying -
“The Board believes that the combination of the recent appointment of Andrea Baldo as CEO alongside the recently announced Subscription and Retail Offer (together, the "Capital Raising") provides the Company with a solid platform to execute a turnaround and, ultimately, to deliver best value for all Mulberry shareholders. In light of this, the Board has concluded that the Possible Offer does not recognise the Company's substantial future potential value. In addition, the Board has been informed that Challice is supportive of the Company's strategy and has no interest in supporting the Possible Offer. As a result of the above, the Board has rejected the Possible Offer.”
On 4/10/2024 FRAS took up its entitlement to subscription shares, under the clawback arrangement from the original 10m shares issue to Challice, this maintaining its position at c.37% of the whole company.
The latest news - on Friday, FRAS issued another pugnacious announcement, increasing its possible offer to 150p. It also contrasts this offer with the 100p fundraise, which of course is conflating two completely different types of transaction (a fundraise, and a takeover bid).
FRAS dismisses MUL’s turnaround plan -
“Frasers is clear that there is no current commercial plan, turnaround or otherwise.”
Today, MUL itself issued another response, which seems to have softened in tone (maybe over worries of legal action, if Directors are not seen to be acting in the best interests of the company or minority shareholders, I wonder?), saying -
“In light of the above, the Board is working with advisers to consider the Company's position and will provide a further announcement in due course.”
Paul’s opinion - FRAS is using its characteristic strong-arm tactics to try to steamroller through a bid for Mulberry. However, it’s up against an immovable object - a majority shareholder that would have to agree terms before any takeover approach stands any chance at all of succeeding.
So it all depends on how rich Challice is, and its ability and preparedness to continue funding losses at Mulberry, plus me resisting the temptation to think up a pun involving poison!
For now then, it doesn’t really matter what the Board of MUL says re the offer - they could recommend it if they want, but the majority shareholder is the sole decision-maker here. For that reason, this bid approach currently looks highly unlikely to succeed. Even if FRAS buys out all the other minority shareholders, it will still be unable to force through anything in the face of a 56% majority shareholder. It is interesting though that FRAS sees considerable value in the brand, despite its lamentable current trading.
On fundamentals, I would be forced to see MUL as AMBER/RED, since its current trading and financial position are both very weak.
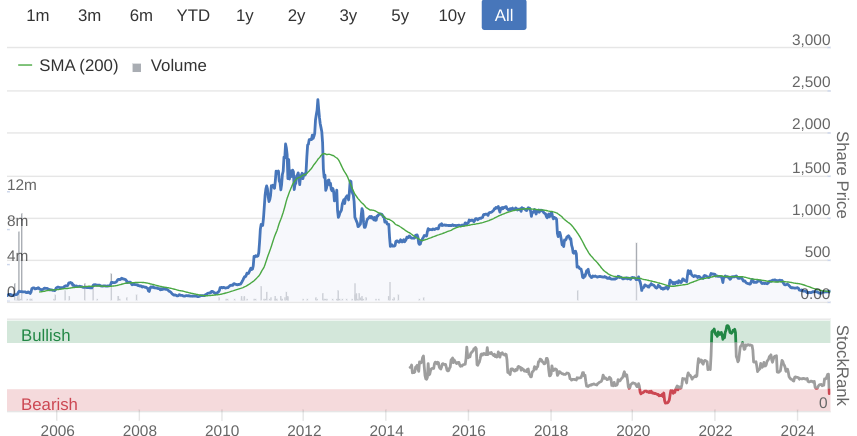
Long-term chart shows the stunning effect of its handbags becoming fashionable for a while -
Oxford Biodynamics (LON:OBD)
Down 43% to 2.04p (£6.5m) - Strategic Review - Paul - RED
“Growth in test sales over the year, new sales model initiated and resources focused on PSE. Business restructured to maximise runway, with a material reduction in costs.”
We flagged here on 14/3/2024 that the last 9p fundraise would only last until early 2025, due to the high cash-burn.
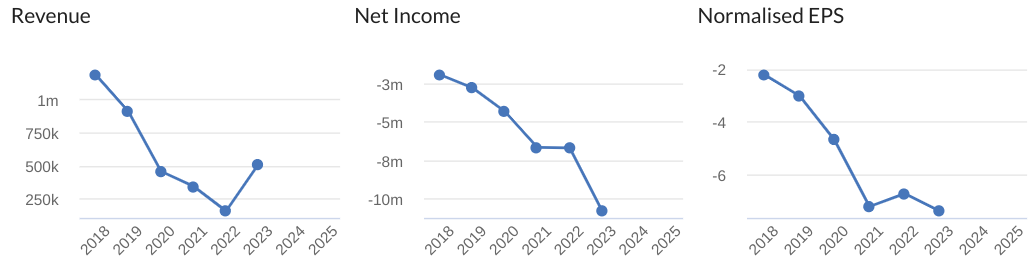
Looking at the historical numbers below, and combine this with the current wider malaise in AIM, then OBD is clearly now in a very tight spot -
Today it announces a strategic review and confirms what we already knew, that it’s rapidly running out of cash -
“The Board acknowledges that access to capital in the UK market is limited and the burn rate of the Company has been high in order to get to its current position.”
“Notwithstanding the measures being taken to reduce the cost base, the Company will require additional cash resources by early Q1 of 2025. The Board has therefore launched a comprehensive review of the strategic options open to the Company. In addition to exploring available funding options, the review will consider a range of potential actions, including but not limited to a licensing or sale of Company assets - such as the EpiSwitch NST and EpiSwitch SCB tests - and a possible hive-off of the Company's US business into a separately funded entity. Currently, the strategic review does not envisage an offer for the Company under the City Code of Takeovers and Mergers."
I find in situations like this, it’s best to sit on the sidelines and wait for either a refinancing (often at a deep discount), or some other event (such as de-listing or insolvency). Existing shareholders who do nothing are usually lambs to the slaughter.
OBD also benefited in the past from Odey backing a fundraise at a premium, which probably won’t happen again as his funds were being shut down I think?
Occasionally though, we do get a surprise, and an apparently almost-bust company manages to sell off something unexpectedly that raises a lot of cash. OBD’s technology does sound quite interesting, but how on earth can we value it? Particularly as the company is only c.3 months away from running out of cash. By the time legals get done, it will probably have its back against the wall, so all the bargaining power is surely now with anyone who is prepared to put in fresh funds.
Paul’s opinion - I’m quite surprised that this share is down almost half today, as there’s not really anything new in today’s update. We had previously already been told that it was likely to run out of cash in early 2025.
Obviously I haven’t got any choice other than to flag the high risk here with RED.
We can look at OBD with fresh eyes if/when it’s refinanced.
Let's just hope that no more IPOs happen for early stage companies. The IPO market (and AIM generally) has almost been killed by greedy advisers floating trash at inflated valuations. No wonder there's so little interest in the London market now, when most of it is populated by companies making the depressing journey from hype and over-expectations, to the grim reality of achieving little to nothing, and needing more cash from investors who don't want to keep pouring more funds into failed ideas.
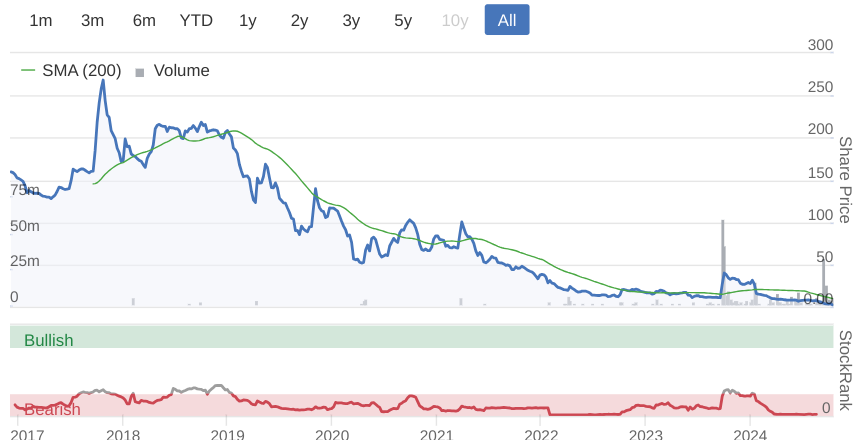
OBD now down >99% from its early days high -
Graham’s Section:
Thruvision (LON:THRU)
Down 6% to 15p (£24m) - Trading Update and Board Changes - Graham - AMBER/RED
Thruvision is “the leading international provider of walk-through security technology”, and its H1 period runs to the end of September.
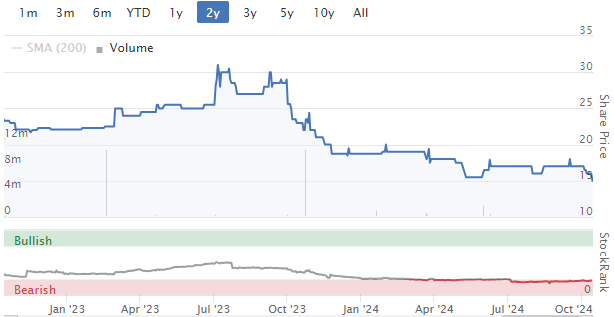
Here’s the two-year chart: it’s down by 50% from the high.
Key points from today’s trading update:
Revenues of £1.9m (H1 last year: £3.5m). There were no material Customs orders in the period, whereas last year there was a £1.9m order to boost revenues.
The current order backlog is only £0.3m, compared to £1m at the same stage last year.
The Outlook statement gives with one hand and then takes away.
There is “a healthy pipeline across all our markets, with particularly significant near-term opportunities in Entrance Security and Retail Distribution”. There is also growth in the sales pipeline arising from THRU’s partnership with Sensormatic.
Against that, full year revenue depends on “the timing of significant contract awards, which is unpredictable”. And even if these significant opportunities are won, they will probably slip into the next financial year.
The result is that the new revenue forecast is £9m (last year: £7.8m).
Estimates
We have a note out from Progressive, confirming that their previous revenue forecast for FY March 2025 was £10.9m.
Even at the previous revenue forecast, Progressive were expecting THRU to post a loss at the adj. EBITDA level. The new revenue forecast sees the loss estimate expand to £1.7m.
CEO is leaving at the end of this month, “to further his non-executive directorship portfolio”. The founder of Thruvision is still on the Board and will be Exec Chairman until a new CEO is found.
Graham’s view
Paul upgraded this to AMBER a year ago (link) as the company had raised some funds (£3.2m) in a placing to stabilise things, after a profit warning in October 2023.
Here we are with another profit warning and I note that the cash balance has reduced to £1.8m (down by £0.6m year-on-year).
This is despite the company seeing its outstanding receivables shrink by nearly £2m year-on-year, which boosts cash, and is also despite the aforementioned placing. The company notes that it has an undrawn overdraft facility of nearly £1m.
I don’t think a neutral stance makes sense here in light of all of the above. I am therefore going to be AMBER/RED on this today.
Small, order-driven businesses can make for very difficult investments even when they are profitable and firing on all cylinders. When they are unprofitable and have light balance sheets, my personal view is that it’s best to just avoid them.
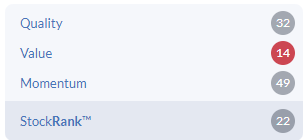
The StockReport doesn’t like what it sees here, either:
TI Fluid Systems (LON:TIFS)
Up 19% to 181.8p (£903m) - Statement re: revised offer - Graham - AMBER/GREEN
We haven’t given this too much coverage since August when I’m relieved to see that I kept my positive stance on this share.
At the time, I noted that the shareholder register included some potentially weak hands. There was also a large debt load (nearly €700m/£600m) and negative organic growth. The result? A very weak valuation with a single-digit PER. Which brings us to…
16th September: The board of TIFS confirms that it received two offers for the company, the first at 165p and the second at 176p.
The proposals came from ABC Technologies, “a leading manufacturer and supplier of custom, highly engineered, technical plastics and lightweighting innovations to the global automotive industry”. ABC’s headquarters are in Toronto and it is majority owned by the private equity giant Apollo.
The response from TIFS? The proposals “significantly undervalued” TIFS and its prospects.
Today: we learn that ABC has made three more bids for TIFS! First at 188p, then at 195p, and then at 200p. So there are five bids in total, with the most recent one being 21% higher than the first one.
The directors at TIFS are now persuaded:
The Company remains confident in its strategy. However, having considered the Proposal … [the Board] would be minded to recommend it to shareholders.
This means there is an extension to the “put up or shut up” deadline, to give time for due diligence, documentation, etc.
ABC has until 8th November to make a firm offer.
Graham’s view
If the deal goes ahead at 200p, that will generate another c. 10% return over the current share price. So if I was holding TIFS shares because I truly believed in the company, I would probably continue to hold and wait for 200p and that extra 10%. But my bias as a shareholder is to take no action, so others may prefer to bank some immediate gains!
There is always the risk that the deal falls down at some hurdle between now and the finishing line.
As for whether or not the deal should go through, some may be uncomfortable seeing another stock taken off the UK market and into the arms of private equity. In terms of valuation, I’m inclined to think that ABC/Apollo are probably getting a good deal at 200p.
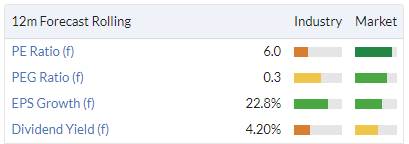
A quick view of valuation:
And the StockRanks are nearly perfect:
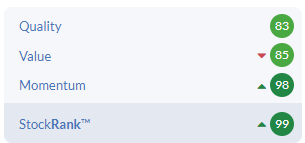
But there’s not much that can be done to stop the deal going ahead, I think. The major shareholder at TIFS is a private equity fund which I assumed was looking for an exit from their investment. It now looks like they are going to get that, and in fairness to them, they didn’t let the directors at TIFS jump at the very first opportunistic bid from Apollo.
The buyer will have to contend with the large debt load mentioned above and a business that has stalled (excuse the pun) when it comes to growth. It might also be argued that the real profitability at TIFS is quite a bit lower than the headline numbers suggest (at the interims, real net income was €40m vs. a headline number of over €70m).
I was GREEN on this before. Now in a takeover situation with the company potentially leaving the market at 200p, I’ll nudge my stance down to AMBER/GREEN. I would ordinarily be neutral with a takeover on the cards, but there is still a meaningful gap of nearly 20p between the current share price and the fifth bid that might be worth holding out for. Of course there is always the risk that the proposed acquisition gets delayed or even falls through completely.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

99 comments
This should have been a reply to Andrew Guppy not a new thread, sorry.
I was a holder of RTC (LON:RTC) years ago and the subject of their low margin came up regularly. They are an employment agency rather than recruitment and their income is mostly paid out to the workers on their books less their margin. If times are hard then it's the DCM award (don't come Monday).
As an “inline” 1Spatial (LON:SPA) has not attracted the attention that it might have. I continue to be impressed by the confident and steady spread of the geographic business and the opportunity to expand in current markets. Small companies are bedevilled by the “lumpy”impact of major contracts but SPA is increasing its recurring revenue stream and adding significant contracts. With every year its past experience and increase in key data acquired makes a deeper moat. There are plenty of reasons to always be careful of “story” stocks or “jam tomorrow stocks”, but there is a continuing, good, story here and there is a solid base of bread and butter to receive increasing jam over the next couple years (if that metaphor isn’t stretched too far).
1Spatial (LON:SPA
Hi Aislabie I agree. The in-line results give further confidence that they are progressing to plan.
It's a company I've been watching for quite a while, I refrained from buying whilst unprofitable and still developing the new products.. Thought I'd missed the bus until the recent fall in share price. So just started buying recently.
I think there is a huge opportunity here. But the market is only just starting to develop - so 1Spatial (LON:SPA?are having to raise awareness as well as persuade customers to buy. Tricky job to get right. Develop the market at the right pace to grab it. They seem to be making all the right moves and now its down to how much land they can grab before competition develops? It looks as if they are well placed with 1Streetworks and NG9-1-1. Quite possibly right product in the right place at the right time?
I'm looking forward to seeing how this goes - I think that they may be about to turn the corner in the next 12-24 months and operational gearing will kick in as they get sales traction. Seems a lot less risky than it was a year or two ago? But as ever nothing is guaranteed and i am normally a little bit too optimistic?
cheers
Mark
1Spatial (LON:SPA) H125 presentation to analysts video and podcast.
Thanks Tamzin,
I found the presentation very useful. Covered quite a lot quite quickly with no messing about - I need to listen again, when I can focus better.
The body languarge is unmistakeable, the management are enthused and excited by the prospects beyond what the PR and rules allow them to say. No guarantee of success but you do know the management team is 104% motivated and working hard to deliver on the prospects.
Also shown by the RNS with the CEO's purchase of more shares this morning (tuesday).
I have followed her example and purchased a few more myself.
1Spatial (LON:SPA) is now covered by 3 brokers/analysts 2 of which released updates visible freely on Research Tree. Edison initiated coverage with FY25 and FY26 figures very similar to Cavendish. Unfortunately I can't see the Panmure note as its not freely available.
The market guidance for FY25 has remained the same - but according to Stocko this morning (tuesday) the FY26 market guidance dived yesterday from 2.7p to 2.3p eps.
There was nothing in the interims or presentation which pointed towards a downgrade of the FY26 figures? It this a refinitiv (relayed by Stockopedia) mistake? Or has Panmure (house broker) significantly moved down its estimates for FY26? Seems unlikely? But weird? I tend towards it more likely being a mistake in the pipe somewhere? But it's not helpful that we can't see the house broker figures without paying more for them. If 1Spatial (LON:SPA) have used their broker to 'soften' the FY26 figures I would be very disappointed.
cheers
MarkGreat podcast for walking the dog as always Paul
You said you may write Rachel Reeves a letter, random idea but I would happily put my name to it too, they have not looked at the bigger picture at all so far, I'm sure many other stockopedia subscribers would too, a letter with the support of hundreds of individual investors may carry more weight.
Hmmn...
London AIM market should be axed for failing to win tech floats, say think tanks
https://archive.ph/F4NFT
Do we scrap the main market too?
Think Tanks are free to dream up any idea they want
All,
Just announced on BBC news that Revolut was the most complained about bank last year 2023-24. 9,973 complaints, more than all the big banks. Customers were scammed and money taken from their accounts without standard scamwear, that other banks use, stopping them. I think they mentioned Panarama, so I think they are doing an investigation and probably a programme to air soon!
Graham.
I wonder if this impacts CMC Markets (LON:CMCX) ?
Ref revolut specifically
I have watched the program and its much ado about nothing - what is surprising is that people would be so trusting of Revolut with very large sums of money when up till recently they didnt have a full uk banking licence. Certainly their fraiu measures were inferior to other banks - but its the same old line of sammers ringing up and people happily conversing with them to aid the fraud to be commited.
Revolut story on Panorama tonight at 8pm on BBC1
Hi eParo - I have to say my view of Panorama of late, now watered down to 30 mins on BBC1 at 8pm is similar to my recent experience of Wagon Wheels, as compared to that of my youth. Better still I can read it all on line now with an advert at the bottom to watch it with pictures streaming now on Iplayer, or on REAL BBC TV "live" at 8pm! (Fings ain't wot they used t' be) https://www.bbc.co.uk/news/art...
Re the piece on gambling sector. Interested in others thoughts on the move in Gaming Realms (LON:GMR). (I hold)
I’d have thought any increase in tax would most likely be borne by the operator rather than licensor of IP - GMR? I’ve added a few more on the dip as seems like this could be a baby getting thrown out with the bath water.
Yes. Gaming Realms (LON:GMR) mention increased gaming duty as a risk factor in the AR but in the mitigation column it says the tax is borne by the operator.
Also, even if you add their geographic revenues from UK/Isle of Mam/Gibraltar together and assume that's all for UK consumption, it's only 25% of their revenues and that % is declining fast as the US and Europe grow.
I've also been adding on the dip at 33p.
Vistry (LON:VTY) This may have been covered last week but, just in case, I have only just noticed that last Thursday it was announced that "Browning West LP a person closely associated ("PCA") with Usman Nabi, Non-Executive Director of the Company have purchased 800,000 ordinary shares of 50p each in the Company ("Shares") for a total gross sum of £7,449,694.72.
Browning West LP is an independent investment partnership based in Los Angeles, California and currently the Company's largest shareholder of which Usman is Managing Partner and Chief Investment Officer."
That seems to suggest very strong confidence that the investigation won't discover wider financial problems in Vistry (LON:VTY. I hold
Vistry (LON:VTY) I picked up on this last week in a post that may have been missed by many. I’ve bought a starter position for exactly the reasons you quote.
A massive vote of confidence in buying on this scale but Paul was justifiably cautious given such a "blunder".
Sure - it is a strong vote of confidence but I'm rather puzzled by the list of shareholders - a number of USA based so called hedge funds one of which - Inclusive Capital - seems to be in a spot of trouble. How much do these firms manage - millions or billions - we just have no idea of their rationale, - added to that, what is puzzling is the lack of support from UK institutions
Your post seems to have impacted the market!
The politics post is at https://www.stockopedia.com/co...
(in reply to bohenie https://www.stockopedia.com/co... but that button did not work)
Great write up Paul on Mulberry (LON:MUL),
I think it was Charlie Munger who recommended 'invert- always invert!" to differentiate good v bad..
I think if I was looking for exactly the opposite of something investable it would be Mulberry; PE 66, SP down 96% from ATH, no profit, doubling debt, no free cash, no liquidity, no turnaround plan (!!) . And to spice it up- handbags at dawn for the two effective shareholders (count'em).
One for bag holders only I fear (geddit?)
If you invert the inversion and multibaggers are your thing, by comparison the galloping elephant Hermes International SCA (EPA:RMS) looks surprisingly healthy.
Enough bag jokes. Truly sorry.
Today’s comments display all the current up and down concerns of the future that are exacerbated by the UK Budget guessing, the US elections, wars , strikes and so on. With optimism around rates, inflation (misplaced I believe), and apparently over pessimistic UK prices. Unfortunately I was already an investor when Wilson came to power in 1964, so I have seen this movie before and it did not have a happy ending. But even then there were stocks that individually prospered and there will be now, so the search continues…
Can I ask one slightly off topic? Has anyone found a good way to scan for catalyst with stock - thinking CMDs, management change, insider trades. Clearly you can look through all the RNS but it isn't always possible. Was hoping to broaden it out to US and EU markets as well. Just starting out my private investing journey having spent many years on the buyside and keen to implement a more catalyst driven process.
Maybe it is a really good, consolidated financial calendar is what I need - just not sure where to get it
Hi Misfit muser,
Welcome to the private investor (PI) community!
With your experience "many years on the buyside", I hope you'll be a regular contributor to the comments here, sharing your highly relevant experience with us.
Best wishes, Paul.
PS. Sorry I forgot to say that I've never found any "catalyst" tracker information in a consolidated form. Hence I have to just plough through thousands of RNSs each year, and keep notes here and manual notes of anything noteworthy.
Also it's really helpful when readers flag up interesting potential catalysts, such as big Director buys/sells, or anything else (eg change of NOMAD for no apparent reason, CMDs, which can lead to a fundraise later, abrupt departure of CFOs, etc)
Thanks Paul - having trawled through about 12 different websites, it seems you can get every type of news barring CMD, new strategy. Surely a pretty easy addition and enough enterprising people out there.
A few interesting events coming up as far as I see it (apols not all under £1bn).
1) PINE CMD 24th Oct, stock down 15% post a recent in-line - the stock needed upgrades on that rating, so fine, but the wording is overly bullish, they are a glass half full mgt team and are going to announce 2030 targets. I'm mildly skeptical on the execution risk re implementing these systems, feels like ERP++ minefield, but if UK Lithia completes fairly easily, should open pathway to other UK wins + the US Lithia and US JV upside. Anyway, hard to see where the negative news is into the CMD.
2) BURB - NEW CEO strategic update 14th Nov. Not sure i care too much for the brand and China still very important, but again, a new vision from the CEO can't be negative. Shares consolidating at the lows?
3) MKS - trading update 6th Nov and CMD 12th. Next report on 30th Oct, so prob get a clear view on the consumer then, but both upgrading and trading well.
Mm,
Looks a good idea but would probably be better to start a new thread for this so that it doesn't get lost here and doesn't also clog this thread up.
Regards, Graham.
Do we think the spread betters would be affected by any potential gambling tax raid? Share prices for IG group (LON:IGG) and CMC Markets (LON:CMCX) little moved this morning, which suggests not.
Spread betters could be seen as a form of gambling, but they could equally argue that they are a legitimate way for investors to offset risk, and so more of an investment.
Okay. I made it out of the bathroom in time for the cleaners to arrive and now I’m cloistered in my office trying to make sense of the recruitment malaise.
Firstly to Planetx. You’re half right. A lot of recruiters are absolutely awful. These will tend to be the low wage high street contingent that compete at the lower end of Hays and Page’s commercial (office, book-keeping) markets and also represented by firms like Hercules and Staffline in drivers and warehousing. You get what you pay for life and the consultants in these sectors are relatively poorly rewarded and of limited ability. Good ones soon move up the value chain into specialist firms. The second category is the big brands, where you will find a mixture of talents but it is important to recognise the value of those brands. Recruiters enjoy a network effect moat whereby the more employers they represent, the more candidates they attract, and the more candidates on their books, the more useful they become to employers. They have spent a lot of time, money and effort on building those platforms and no employer can hope to appeal to as many candidates, nor handle their administration as efficiently as a slick, tech-native recruiter does. Meanwhile, at the top of the tree you have the specialist recruiters, represented by SThree or my 1990’s listed firm at the larger end, or the sort of boutique that I ran for many years in the new century. Companies that you could genuinely call headhunters, search consultants or whatever and whose consultants develop a specialist niche in which they become not expert in the technical niche, but expert sifters and deal-makers. I cannot stress this last characteristic enough. Recruitment isn’t just about attracting candidates. It’s far more about the art of the deal (with acknowledgement to Donald). In my firm there were several consultants earning over GBP 250k, not because the job is easy, but because it is difficult!
Anyway, clarification over, let’s look at the state of the market today, characterised by depressed fees. In the thread below, I’ve twice answered and dismissed suggestions that this is anything to do with the acceleration of in-house recruitment programs and the availability of LinkedIn, AI tools etc. As another poster astutely observed, these only make recruitment firms more productive. Please avail yourself of those counter-arguments below.
Further evidence that it is the market is found in that, for the second year running, the major accounting firms, EY, PWC etc have announced delays to start dates for their graduate intakes. I think it was EY yesterday who announced a 6-9 month delay. And yet, they also announced that a generous stipend would be paid to keep those new employees on-side while they spend the time touring Vietnam or trekking to Everest basecamp. On a personal level I find this situation quite alarming as my son is a trainee management consultant with only a year’s employment and his level of implementation on client projects has been limited at best. I dread the call from him that he has been let go. Meanwhile, over at SThree and comparable tech recruiters, new contract hires are thin on the ground, but existing contractors, with in-built expertise in the employers systems, are being jealously retained.
And perhaps the whole answer lies in this dichotomy. There is no new work for new hires, but no desire to lose access to the talent they expect to need, or are already exploiting. In the same way as the velocity of money in an economy dictates its health, so the flow of employees in the jobs ecosystem defines its vigour. And what we are seeing is a clogging up of the system that is reducing the number of job moves, and correspondingly, hiring fees. The question is why?
I think we have to go back to the pandemic, the ripples of which are still roiling economies. Employers have had to make extraordinary adaptations in recent years, from furloughing their entire workforce, to switching to remote working, to coping with rampant wage inflation, to facing the prospect of an AI-powered Industrial Revolution that upends their workforce, all while interest rates soar from zero to 5%. Is it any wonder they want to take stock? And the news flow keeps giving shorter term reasons to maintain the cautious stance: there’s a budget coming, a US election, a war in the Middle East, China is manoeuvring off the shore of Taiwan, the Northern Lights are out again. There’s always a reason for employers to cite while they reel from the revolution in work already well underway and the utter uncertainty over what shape AI imposes on the workforce.
I am struck that this is the longest hiatus in global hiring since my first job in 1985. Longer than the 1993 recession and longer even than the GFC in 2008 onwards. And yet, there is no recession globally and only small downturns sequentially in a few G7 states like the UK, now hopefully past, and Germany. Given the length of the hiatus and the absence of a clear economic explanation, I think you have to look at that force which markets themselves detest: it’s the uncertainty launched by pandemic-related physical and monetary convulsions and the pace of technological change. And even that latter force is not prompting hiring because such is the exhaustion of organisations’ IT spending over the last few years, that appetite does not exist to push forward with more investment while there is an excuse to do nothing.
Excellent - thank you.
Knowledgeable and wise, thank you BnB. I would have welcomed your view on the effects of Brexit on recruitment companies too.
I would have welcomed your view on the effects of Brexit on recruitment companies too.
I think I would disappoint you because I could not discern any measurable impact in the sort of large cap or multinational that my firm represented. Typical clients were AstraZeneca (LON:AZN) , the NHS, RS (LON:RS1) , HSBC Holdings (LON:HSBA), Barclays (LON:BARC) , Aviva (LON:AV.) , BT (LON:BT.A) Marsh & McLennan Companies (NYQ:MMC) , Experian (LON:EXPN) , Next (LON:NXT) , Auto Trader (LON:AUTO), Sky etc. These businesses just carried on their programs.
Much more impactful were the IR35 changes brought in a year or so later, which created real operational challenges and much uncertainty.
IR35 is my bete noire. You do not know where you stand with it, even when you try to comply. However there is some evidence that the consultancy market is cooling quite quickly. I think this is a form of discretionary spending and companies are starting to sit out the budgetary uncertainties et al.
Thank you for taking the time to write that.
There is one other element here I think: it is getting much harder to fire people for non-performance (and sounds like it is only going to get worse). So the cos hold to what they have and know rather than face into the risk of hiring of someone they don't know and potentially having to go through all the grief of gettign rid of them.
Thanks for the outstanding reply BnB. I held a couple of recruiters a year or so ago on the basis that the market would surely turn. Except it didn't and I eventually bailed out. If global uncertainty is the problem then it could be a while before the sector improves.
“media report the Labour government is mulling a 3 billion pound ($3.92 billion) tax raid on the gambling sector to shore up public finances.”
Put another way. "Let's look at upping taxes where we can get away with it. We are incompetent and have no idea about running a business, let alone a country's finances, so we will try and get away with anything we can"
Err - No politics please - go to x for that
Grout's comment is valid as it directly affects several easy "targets" for a desperate tax grab. CMCX's share price was unmoved on great figures because of the perceived overhanging threat for months on end.
A more socially acceptable target given most betting companies target labour voters
No politics remember
Supreme (LON:SUP) - £2.5m disposal. Follow his lead?
Supreme (AIM: SUP), a leading manufacturer, supplier, and brand owner of fast-moving consumer goods, was notified on 11 October 2024 that, on the same day, Sandy Chadha, Chief Executive Officer, sold 1,600,000 ordinary shares of 10p each ("Ordinary Shares") at 160p per Ordinary Share to an institutional shareholder to meet investor demand.
Following this disposal, Mr Chadha retains an interest in 65,666,845 Ordinary Shares, representing approximately 56.31% of the issued share capital of the Company.
Supreme (LON:SUP)
i dont know any of the detail but i am guessing that it was only a matter of time before Mr Chadha would start selling down his stake once the company listed , with him having such a high % ownership it seems natural that over time he would probably start to reduce his holding for sensible diversification reasons. It doesnt seem he is selling right at the top ref company news/shareprice here either and if capital gaisn tax rate is likely to rise its perhaps sensible to sell just before the budget - its not as if he is selling a huge percentage of his stake either. I dont hold here but if i did i dont think i would be particularly worried about this sale.
He's not the only one selling:
Executives have stepped up sales of their shares in UK-listed companies ahead of this month’s Budget, as chancellor Rachel Reeves considers increasing capital gains tax in a bid to bolster public finances.
Since the country’s July 4 election, directors of listed companies have sold shares at an average rate of £31mn a week, more than double the £14mn pace of the previous six months, regulatory filings show.
The total value of disposals since election day has reached about £440mn, according to the figures compiled by investment platform AJ Bell.
https://archive.ph/dvldk
My disposals are about 90% of my UK portfolio. All being switched to the US
Just a thanks in advance Paul. I am away trekking for the next two and a half weeks, so may have limited internet connection. Looking forward to catching up on the markets via your weekly podcast. I particularly enjoy your macro views.
Safe travels Ted
If anyone can shed any light on what has happened to the recruitment industry Id be fascinated. Even Manpowergroup (NYQ:MAN) and Adecco AG (SWX:ADEN) shares and earnings are under a lot of pressure. Certainly judging just off this sector you would have expected that we were already deep in a recession. And wondering when we might emerge from this. Another sector hit v hard from Covid that does not seem to have recovered. Pagegroup (LON:PAGE) read terrible and reminds of watching this share in 2002 waiting for the recovery, it came eventually but no sign yet. If they aren't increasing headcount you can just step away. I know they tried last year but got that wrong and had to retreat... as nothing came through. Interesting sector on its knees.
Morning RDHOWARTH,
Exactly my concern too. Staffing companies seem to be on their knees, and reporting not even tentative signs of recovery. I would have expected firm evidence of green shoots by now, but there's nothing. As you say, this is what you'd expect in a proper recession, not when economies are flat-lining. Not confined to UK either, with Hays saying last week that UK & Australia were bad, but Europe not much better. Today Page saying France & Germany are the worst.
I'm wondering if there's an industry-wide problem - eg are employers using apps or other means to recruit, rather than going through staffing agencies? It just seems odd that this sector is seeing no signs of recovery, when logically it should be - or at least they should be saying that sentiment is beginning to improve, but I've not seen anything like that yet.
I wonder if there's any research on the timing of economic recoveries, showing which sectors historically have started reporting recovery, and the timescales, in various sectors? That would be an interesting project to create from our reports here actually - to measure when previous cycles began recovery, and which companies were the best indicators.
Regards, Paul.
Morning Paul,
Thanks for all your hard work and insights - love the podcast!
I think you hit the nail on the head about recruiters using different channels. There are very powerful tools available now to help businesses find people very cost effectively, eg. well established channels such as LinkedIn -It’s not difficult to build a funnel of prospective staff through these channels for a few hundred quid. Compare that to recruitment firms charging 20-30% of starting salary and/or large retainers. They are very expensive compared to the alternative - I’m not surprised they are struggling.
I think you hit the nail on the head about recruiters using different channels
They’ve been doing this for years and barely making a dent in recruiters’ revenues. You can immediately discern this is not the issue because temp fees are badly down for the likes of Hays and Page and even dropping for SThree. These have never been sourced directly by employers because the associated hassle of running enlarged and far more complex payroll functions and the effort that goes into finding someone to turn up for just a week don’t make any sense to an employer with its own business to focus on. So LinkedIn, AI, in-house recruiters, blah blah definitely not the reason for reduced fees. It’s the market. More later.
I agree. Spent 36 years in recruitment as CFO, CEO then recruiter of CFO’s. When job boards first came along, there were fears they could kill the recruitment sector. All they really did was to make recruiters more efficient and take cost out of the process. The same is true of LinkedIn.
Historically the Accounting industry used to run on a 6 year cycle and the best indicator would be to monitor graduate recruitment of the big accounting firms - it bottoms at next to nothing and picks up significantly in a recovery. However I wonder whether 4 day week, working from home and maybe even AI are already eating into the professional services sector. You don’t need PAs etc when no one is in the office. All just guesses on my part though. Are the middle office jobs getting hit hard in the new world.
I'm wondering if there's an industry-wide problem - eg are employers using apps or other means to recruit, rather than going through staffing agencies?
Hi Paul. definitely not. If that were the case there would be more mobility. But candidates are reluctant to accept offers at the moment and keeping their heads down, indicating a frozen market. Also employers are reducing their in-house recruitment capability, which would be the opposite of what you’d expect to see if they were boosting in-house recruiting productivity.
I don’t have a clear explanation, because that would require us to be in recession, but I’ll see if I have time to share some thoughts later this morning. But the cleaners are coming round and I need to be in and out of the bathroom before they get here!
I'm wondering if there's an industry-wide problem - eg are employers using apps or other means to recruit, rather than going through staffing agencies?
Paul,
I asked my wife who works in HR for a major global company and she thinks there is an increasing reluctance to use the traditional staffing agencies. Mainly for cost reasons. Where they can use Linkedin, etc, they often will. Also, another factor may be a shift towards outsourcing. People who want more flexible working conditions may be opting for this.
I am currently listening to the Pagegroup (LON:PAGE) call. According to the company the issue is the current market is made of people transitioning from one job to another. The upside bump in salary is often not enough, candidates are looking at the market and not following through on offers...which are often only 5% or so better. Ie not enough....so they stay where they are. The honest answer here is it is not so simple to boil down to one issue or another. The fee rates are not under pressure which suggests structurally the industry is ok actually, no new negative emerging other than reluctance to move. This industry obviously depends on business being rather desperate for candidates and that just isn't the case at the moment. I think they expected a recovery that hasn't happened...and for example, sluggish financial services industry conditions hasn't helped. Things like Aim, IPOs, Private Equity Buyouts, M&A etc all result in less desperate professional services sector and big bumps in salary just aren't there. They do highlight it is incredibly difficult to find candidates however and so "if" things pick up all the ingredients for a strong recovery would be in place.
The depressed activity levels in private equity may well be having quite an impact and be something of a ticking time bomb. Industry valuations have held up and the expected refinancing wave hasn't happened yet. If interest rates remain higher globally then this could cause something more serious to emerge. We don't have much visibility because the quoted vehicles haven't really taken the hits. The longer rates remain high then who knows. Watch everything re private credit levels for a problem building. Ironically a recession if it ever arrived would probably help this industry through much lower rates... and remerging inflation the opposite. At the moment its possible the muddle through conditions are not helping the recruitment sector. These stocks are an avoid for now unless you have a nice long time horizon.
These (recruitment) stocks are an avoid for now unless you have a nice long time horizon.
Yes, I agree. I held Robert Walters (LON:RWA) and Hays (LON:HAS) for the recovery and have let them both go. I’m still in SThree (LON:STEM) because operationally it is holding up well on the back of its almost total dedication to contract hires. And I’m sentimental about IT recruitment which looked after me rather well and I expect to recover at the front end of the rebound. Companies die if they don’t invest in new technologies and the skills to implement them.
Hays (LON:HAS) looks particularly attractively priced for the rebound if/when it eventuates however.
Hi BnB, Any thoughts on RTC (LON:RTC) please?
RTC Group (LON:RTC)
I'm interested in RTC (LON:RTC) especially given my understanding that engineers are in demand and are amongst the hardest to recruit.
Hi BnB, Any thoughts on RTC (LON:RTC) please?
Sorry I don’t follow the firm but looks to have very narrow margins that will create horrible negative operating leverage in a downturn. Obviously the opposite applies in better times, as the chart suggests. And they must be doing something right at the moment, relatively speaking.
I was a holder of RTC (LON:RTC)
years ago and the subject of their low margin came up regularly. They
are an employment agency rather than recruitment and their income is
mostly paid out to the workers on their books less their margin. If
times are hard then it's the DCM award (don't come Monday).
PS. Thanks for the Podcast Paul. It makes for a fascinating weekend listen on market closure.
Hi Paul,
I’m going back some 10 years or so and remember reading an article in MoneyWeek about sectors that do well in the early stages of recovery, Chemicals was one of those as they are linked to the consumption of goods (so this sector can also act as an early barometer for a slowdown too) I’ll have to go away and have a closer look at this sector.
Staffing / recruitment companies
Most small employers detest using recruitment agencies .
Just generally super slick sharp dressed weasels pedalling employees around industries .
By definition these employees typically are transient and lack loyalty and dont settle
Fees are really high and most recruitment companies just really are not very good .
The long term way to success from great companies i which is going to become much more common is to set up apprencce / graduate / undergraduate training plans which massively benefits the young as they emerge from university / college / school both educated , debt free , and loyal .
not many young, emerging from uni, debt free Planet. quite the opposite!
Just to take the flip side. There is nothing here that would make me want to sell my s&p tracker yet. Lots of people say it's overvalued and due a big correction but they've been saying the same thing for months and years. Eventually they'll be right and a 20-30% correction can't be ruled out, but all that would likely happen here is we'd selloff at least as much. UK markets can barely get through a 1 day US holiday without panicking.
Nice one Wolfie!
Off to the US for four weeks-too much at stake to ignore :
Very important elections.
Labour market that doesn’t make sense and would like to actually witness the true picture.
Witness the data centres that will charge the way we live.
And yes a US correction will happen at some point (S&P over 6425 perhaps) but every time this represents a new opportunity for further outstanding gains. What most people are missing is that this time it will mark more UK outflows into the US market!
All the best
Many readers may want to take a look at BnB's excellent summary of his UK holdings - which will be widely held by subscribers.
The background comments and hindsight observations about the rationale and timing of the positions are food for thought for many of us considering top-ups, particularly with current small-cap/AIM volatility.
Hi can you please advise where I might find that ?
Under the “ALL DISCUSSIONs” tab , it’s about 4or5 discussions down the list.
Discussions
Apologies, meant to include the link - Stockopedia | The BnB Fund - UK Edition | By BnB
Apologies, meant to include the link - Stockopedia | The BnB Fund - UK Edition | By BnB
Thanks
Apologies, meant to include the link - Stockopedia | The BnB Fund - UK Edition | By BnB
Thanks for the shout-out, TJ. And for extra spice, I’ve today added my estimation of intrinsic value for each of the shares mentioned. So maybe worth a second look for those who have skimmed already. Although, like any analyst forecast, it’s just a guess, and maybe not a very good one!
Thanks for highlighting these, I often forget the All Discussions tab, so don't look. I've had a quick scan through and they look fascinating. BnB's comments are always interesting - I need to set aside some time to read properly.
Where is the All Discussions tab please
On your laptop, hit the DISCUSS button on the left hand side then All posts, on the app, its at the bottom
if you click discuss at left hand side then all posts below discusions (further up the screen) - then you will see the individual discussion threads with the most recent (including BnB's) near the top-The BnB Fund - UK Edition
My morning smallcap tweet: Beating around the Mulberry bluff?
Mulberry (LON:MUL) Thruvision (LON:THRU) Oxford Biodynamics (LON:OBD) B.P. Marsh & Partners (LON:BPM) S&U (LON:SUS) Coral Products (LON:CRU) Elixirr International (LON:ELIX) Helical (LON:HLCL), 1Spatial (LON:SPA)
◄Mulberry (MUL)► re: increased 150p approach from Frasers - 56% holder says "has no interest in either selling its Mulberry Shares to Frasers or providing Frasers with any irrevocable or other undertaking". Is that a bluff? Board is working with advisers to consider the Company's position. [SP=113.5 Cap=79m]
◄Thruvision (THRU)► guides H1-Sept rev £1.9m (£3.5m). Warns FY rev only c. £9m because there's likely to be a modest slippage of revenue into FY26. CEO scarpers end Oct. He is thanked. [SP=15.8 Cap=26m]
◄Oxford BioDynamics (OBD)► commercial update. Cost cuts. Fires the Fire-Sale gun with a review of strategic options. "In addition to exploring available funding options, the review will consider a range of potential actions, including but not limited to a licensing or sale of Company assets...and a a possible hive-off of the Company's US business." [SP=3.66 Cap=11m]
◄B.P. Marsh (BPM)► buys 25.5% Cumulative Preferred Ordinary shareholding in Volt, a London-based start-up Managing General Agency specialising in energy insurance. BPM to provide funding of up to £2.5m via both equity and a loan. [SP=551 Cap=204m]
◄S&U (SUS)► big relief as FCA lifts collection process restrictions for Advantage Finance. [SP=1730 Cap=210m]
◄Coral Products (CRU)► warns FY25 rev flat and co expected to record a loss. Blames "reduced order levels from our core customers in both the Telecoms sector affected by the sustained reduction in housebuilding and infrastructure projects in the UK and the FMCG and automotive markets". Expects 500bp fall in margin. [SP=8.5 Cap=7m]
◄Elixirr International (ELIX)► gets a £45m revolving credit facility. [SP=650 Cap=329m]
◄Helical (HLCL)► H1 trading - good progress delivering on targets. "The market appears to be moving in our direction, with our best-in-class office developments due to deliver into a supply constrained 2026." In line? Throw me a frickkin' bone here. [SP=213.5 Cap=263m]
In line: SPA
TI Fluid Systems (LON:TIFS) ABC Tech raises offer to 200p. Board minded to recommend this to shareholders should a firm offer be made (subject to due diligence etc.)
Join us for MelloMonday tonight at 5:00pm. The programme for the evening is as follows:
5:00pm An introduction to Lucius Cary of Oxford Technology
5:30pm Company presentation from Transense Technologies plc
6.10pm Educational Presentation
6:30pm Company presentation from Newmark Security plc
7:00pm Budget special
7:15pm BASH (Buy, Avoid, Sell, Hold) Panel
For more information, click here: https://melloevents.com/mm141024/
There are lots of interesting sessions and all annual pass holders and individual ticket holders will be sent a recording of the show within 48 hours of registering. For half price tickets, use code MMSTOCKO50. https://www.tickettailor.com/events/melloeventslimited/1367830
More Upcoming Events:
Mello @ The London Investor Show on Friday 1st November 2024, 9.30am – 5.00pm Novotel London West https://melloevents.com/mellolistickets/
Mello 10 Year Anniversary Event in DerbyTuesday 19th November & Wednesday 20th November 2024, 9.00am – 7.00pmDerby Conference Centre, Derbyshirehttps://melloevents.com/mello10tickets/
Hello carmensfella. I t6hough originally that Warpaint London (LON:W7L) were down to present this evening. Is there any particular reason for the change?
They presented at the previous one - still available to Mello subscribers
Has the moment of truth has arrived?
You see with the Dow (Fwd 19x PE), SP500 (21x PE) & Nasdaq (28x PE) trading near all time highs, the next 4 weeks is where this perhaps 'mis-placed euphoria' (or at least stretched optimism) needs to come true.
There's little margin for error.
My concern is that a lot could go wrong. Not least the US presidential election, 30th Oct Budget (UK only), wars in Ukraine/Middle East and possible belligerent Trump tariffs (ie if he wins on 5th Nov)
Worse still, these are not the biggest hurdles either.
The US Q3'24 earnings season kicked off last Friday with encouraging statements from a couple of US banks like JPM.
Here Q3 SP500 EPS estimates have been massaged down to a pedestrian +4.1% growth. That's the easy bit though.
The real 'rubber its the road' moment, comes with Q4 & FY25 guidance.
Indeed looking ahead, Wall Street analysts are forecasting YoY EPS growth of 14.2%, 13.9% and 13.1% for Q4'24, Q1'25 & Q2'25, respectively. For CY'25, they're 'praying' for +14.9%. In a low inflation world too!!
To me, this is simply too rich. Meaning there's a decent chance valuations will reset lower sometime this quarter.
Watch out for a bumpy road ahead.
October 19th 1987 re-run? I hope not Paul but the stars are aligning.
Yes, great article Paul - I would agree with you. 2025 estimates look like downgrades are more likely than not in the US. Possibly a "blow-off" market top first though!
The only thing that I would add is that there is some evidence that the US economy is rolling-over despite probable efforts to distort the labour data in the run-up to the elections. I am expecting massive downgrades to the numbers post-election. Cynical, but there are lots of people saying the same things and the latest jobs report was ridiculous - roughly 1m new government jobs and -0.5m private sector jobs if you remove the seasonal adjustments. If that's true then the government recruited more staff in one month than ever in history, just to get the unemployment rate from 4.2% to 4.1% whilst the private sector is losing jobs fast!
As Steve Hanke would say its all about the M2 money supply and the impact of this turning negative 2 years ago and even now its only growing at half the the required level to hit 2% inflation. This has "long and variable lags" with a recession "baked in the cake".
Most investors have been selling the UK to buy the US for quite some time. That makes no sense at this point in time, in my view. It was a great trade a few years back. The risk reward ratio is not good at all now.
Yes there is usually a blow off top before a fall, but arn't we in the middle of that blow off. October is usually the month that bears maul the market. I suggest this year will be no different. Buffett is 45% in cash, a wise man worth following. Gold and silver are also good hedges.
Equally though September is normally the worst month of all and its been positive this year, and Oct is normally positive even allowing for some big crashes so we equally could see a strong year end run in.
I share your concern but...re earnings, are they not always a little high at this time of year?... and we seem to get through the adjustment. Knock a few percent from earnings from the struggling sectors which get crushed but normally the market copes. It's much more serious if you need to adjust +15% to -5% but we aren't suggesting this I think. Unless something not on the above list derails things. For sure, the port strike etc is going to temper things. As for the UK budget ... my guess is most of damage has been done, and the affected parties have had weeks to submit statements to government highlighting the negative consequences of various policies. Net net we do a full circle and end up back at the staring point, the big picture being the US is deficit spending and easing monetary policy. China have woken up to their own slow down. So we can probably muddle on. Not too hot not too cold? Who knows but in a nominal world, equities will remain the preferred asset, even if its peak valuations on peak earnings.
Hmmmm. The US economy has been flying and the 50bps rate cut isn't going to slow things down. I agree that certain sectors are getting very expensive, however I can't see any kind of crash on the horizon UNLESS we start to see a reacceleration of inflation. If that happens than yes, there will be a major correction.
For anybody interested in Spectra Systems (LON:SPSY), particularly those who didn't attend the recent presentation, I strongly suggest you take a look at the presentation slides, as per today's RNS...
https://spectrasystems.wpengin...
They contain a lot more information than the H1 results RNS and I am quite surprised they have been put in the public domain, as they haven't been for past presentations.
My second largest holding and I think its obvious from the presentation why this is the case.
Thanks shanklin100,
Spectra Systems (LON:SPSY) is becoming one of my favourite GARP shares (alongside Intercede (LON:IGP) and Beeks Financial Cloud (LON:BKS) ) - I think all 3 companies have remarkable growth potential, hence why I've focused my portfolio on them (plus Plexus, but that's been silent for >6 months now, which is infuriating).
I managed to get on a results call, based on the slides you posted a link to, and my impression afterwards was -
Amazement at the range of activities SPSY already has underway, it seems to have a remarkable ability to innovate, and successfully commercialise a range of activities. Whereas the usual approach of small caps is to try for 10-20 years to commercialise one thing, dismally fail, and repeatedly raise money as the share price heads relentlessly for zero with the occasional blip! SPSY is the opposite.
Acquisition of Cartor looks inspired, and didn't cost much (worth it just for the production equipment it owns).
Cash position should rebuild rapidly in 2025 from major contract order, plus big increased in profits, giving a good catalyst for shares to re-rate in 2025 possibly?
Set against these positives, SPSY shares do seem to be suffering from a persistent seller. I bought some more a couple of weeks ago, and my broker said the seller had been cleared, but then the price promptly fell back again. So it could be one of the AIM shares that are currently seeing erratic market activity due to Budget fear sellers maybe? I don't mind that, as it's potentially laying the ground for a strong autumn rally, as those sellers could become buyers again, depending on what decisions are made in the budget. It's most important to focus on the company fundamentals I think, as other factors tend to resolve themselves over time, and create buying opportunities for people prepared to look through any short term price disruption.
Regards, Paul.
I can't help but agree. The presentation that went with the slides was highly impressive as Nabil discussed all aspects of the business without hesitation or deviation. I'm planning to talk about Spectra Systems (LON:SPSY) tonight on Mello Monday and will try and cover the key attractions of the business.
Damian, I note that Cockney Rebel was playing silly buggers when SPSY was on the bash last time, saying it had no liquidity or trades. There are two tickers for Spectra;
SPSY - decent liquidity (can usually trade >10k shares each way) and average daily volume traded of 70k shares
SPSC - No volume or liquidity
As per the 20th August RNS they said;
"The Company's issued share capital now comprises:
559,380 shares in the Regulation S stock line ISIN number USU8457D1091 (AIM:SPSC); and
47,669,592 shares in the unrestricted line ISIN number US84756T1060 (AIM:SPSY)."
From my understanding the Regulation S stock can't be traded by US investors, Maxcyte used to have something similar. Maybe worth clarifying tonight though.
Seems ticker in US is SCTQ worth $2.
Spectra Systems Corporation invents, develops, and sells integrated optical systems in the United States and internationally. It operates through four segments: Authentication Systems, Secure Transactions, Security Printing, and Banknote Cleaning.
Taggant materials and sensor equipment to authenticate banknotes and security documents.
Banknote cleaning and disinfection systems.
Optical materials for security and quality control, such as fluorescent and phosphorescent pigments and dyes, invisible pigments and dyes, and gasochromic response materials;
Internal control systems for real-time fraud control and risk management used by lottery and gaming operators.
High-speed currency authentication sensors
Postage, tax, voucher, coupon, certification.
The company was formerly known as Spectra Science Corporation and changed its name to Spectra Systems Corporation in June 2001. Spectra Systems Corporation was incorporated in 1996 and is headquartered in Providence, Rhode Island.
MC $155, EV 162m.
spsy.com
Providence in the US (leave your gun at the door cowboy).
Yes indeed thanks. The Reg S shares are gradually being reduced I think and it'll be useful to have that distraction out of the way.