Small Cap Value Report (Mon 14 Sept 2020) - TUNE, COST, BOO, TPX, PIER, PCIP, XPD, SCE, SYM

Good morning, it's Paul here with the SCVR for Monday.
This article will gradually take shape during the day, but is initially here for you to add your comments on the 7 am RNSs.
Estimated timings - I'm mostly done now (at 12:42), but might add a bit more later this afternoon.
Update at 20:18 - today's report is now finished, with a few new brief sections added in the evening.
.
Second wave?
I'm sure we're all very conscious of the news, showing considerably increased numbers of covid cases in the UK (and elsewhere). Whether it should be called a second wave, or just a continuation of the first, who knows? It doesn't augur well for the colder autumn weather, once we're all inside again, does it?
Should this affect our investing, that's the trickier question? People who panic sold in March, have since missed out on one of the best bull markets ever, and certainly the quickest. Apparently there's still money on the sidelines, of people waiting for another big pullback, which so far just hasn't happened.
Personally, I've decided to focus new positions on companies which have demonstrated that they can ride out, or even trade well, through the last covid/lockdown crisis. Or companies that took a hit, but recovered very quickly, with very strong sales once lockdown was lifted. Also, companies which are strongly financed, and previously paid out big divis, are high up my agenda.
There are some super opportunities to lock in probable future divis of 5-10% p.a. (I like Somero Enterprises Inc (LON:SOM) (I hold) and Headlam (LON:HEAD) (I hold) as good examples of this). In a super-low-permanently interest rates environment, which is increasingly my view of the future. then big and safe yielding shares are likely to become more sought after - buying now locks in a lovely yield, and probably a future capital gain as other investors chase the price higher to get the yield once it becomes more obvious.
I've got enough of my post-covid recovery shares which are looking riskier right now , so am not adding to those positions (e.g. Revolution Bars (LON:RBG) and Ten Entertainment (LON:TEG) and Hollywood Bowl (LON:BOWL) ). Although we're probably only months away from at least the early stages of vaccines, and better treatments. Vulnerable people are (rightly) isolating themselves, and it looks as if we might need to get some degree of herd immunity amongst younger people, maybe? That might happen whatever the rules are, as we're seeing increasing reluctance to follow rules, which seem a contradictory muddle anyway. Helped along by media which seem to be actively trying to make them seem more complicated - e.g. by running through all the different rules in England, Wales, Scotland & N. Ireland, whereas actually they only need to tell people which rules pertain in their local area.
On balance, as long as the death rate remains very low, then I'm not planning on making any changes to my current portfolio.
I'm reading a book on the far worse 1918-19 Spanish Flu, which is certainly helping to put the current situation into perspective.
.
Focusrite (LON:TUNE)
Share price: 805p (up 9.5%, at 09:40)
No. shares: 58.1m
Market cap: £467.7m
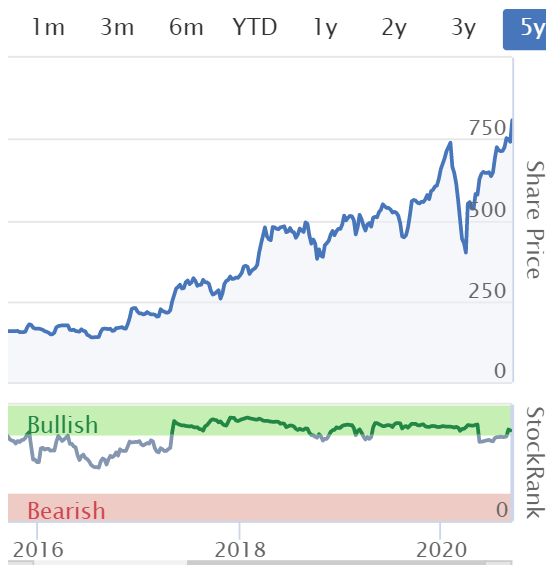
The market cap has gone above my usual (flexible) £400m limit, but this is such an interesting company, I'll carry on doing updates on it. Sadly, I didn't buy any, because it always looked too expensively-rated. The trouble with over-paying for shares is that you might be buying the best companies, but some of them can't maintain the growth and then drop heavily in price. Without a crystal ball, it's very difficult to determine which are longer term winners, and which ones are just in a speculative bubble. I think that's where sector knowledge comes into play.
Focusrite plc (AIM: TUNE), the global music and audio products group of companies, supplying hardware and software used by professional and amateur musicians and the entertainment industry, is pleased to update the market on a strong trading year in which revenue, profits and cash flow have all grown substantially.
It's been making some acquisitions, so some of the growth comes from that. Organic growth also looks very strong at +23%;
The Group expects revenue for the financial year ending 31 August 2020 to be ahead of market expectations at approximately £129 million, up from £84.7 million last year. This growth comprises a full year of ADAM Audio revenue, acquired in July 2019; eight months of revenue from Martin Audio, acquired in December 2019 and growth of approximately 23% in the core Focusrite Audio
Engineering business.
It's so much clearer & easier to when the figures are put in a table, rather than text like this. The £129m revenue figure above is £5m ahead of the broker consensus forecast shown on the StockReport - a decent revenue beat, especially as it's all come at the end of the year, when most revenue is already in the bag. This probably suggests that a strong start to the new financial year is likely.
Gross margins are up, and EBITDA is ahead of expectations;
Gross margins have improved from the prior year and as a result EBITDA is also expected to be ahead of market expectations.
That's a great combination - when products are in strong demand, then selling prices can be raised, giving a lovely geared boost to the bottom line.
Cash generation - this is particularly impressive. I was previously a bit concerned about the level of debt taken on to make this acquisition, but it's been rapidly repaid;
Cash generation remains a high priority for management and, as at 31 August 2020, the Company had a net cash balance of approximately £3 million. This has improved substantially from a net debt position of £19.9 million as at 29 February 2020. For comparison the net cash balance as at 31 August 2019 was £14.9 million, prior to the acquisition of Martin Audio for £35.3 million, net of acquired cash but prior to acquisition costs.
Note that this has been partly achieved by reduced inventories, due to strong demand. It would have been helpful for the company to give us some figures on that. So net debt is likely to rise again somewhat, as inventories rebuild. But it's so low, it doesn't matter now.
The company is paying back £164k Govt support under the furlough scheme.
My opinion - this is a really good group of companies, in the right area - business must have been boosted considerably by lockdown, increasing blogging & vlogging, etc. There are a lot of musicians out there, kicking around with nothing to do (as live gigs are a thing of the past for now). Plus millions of amateurs also. Focusrite serves that niche with suitable equipment.
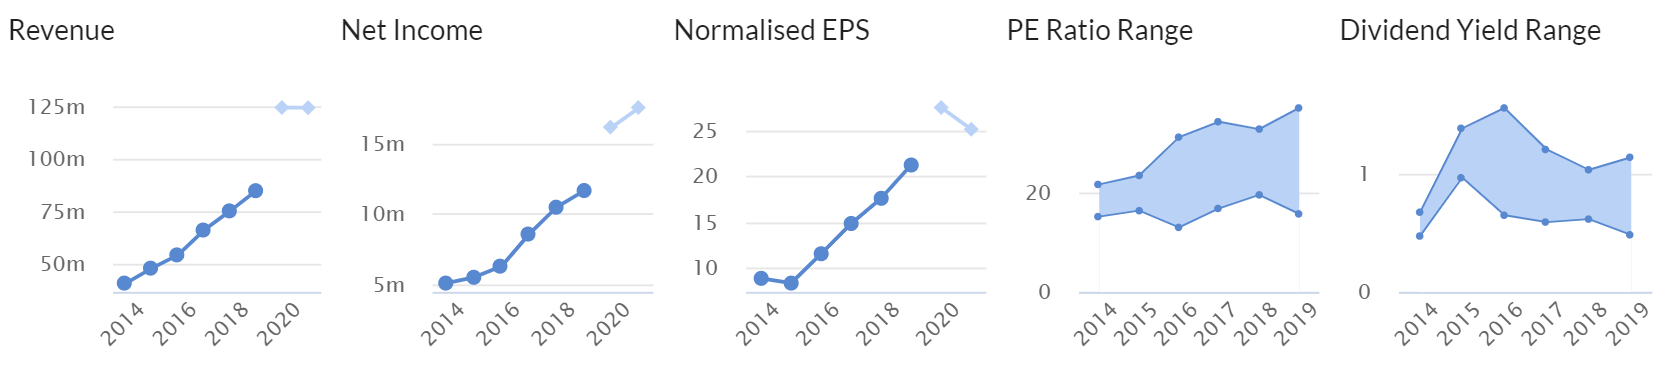
The consensus forecast shown on the StockReport is 27.5p EPS, so let's assume something like 30p is more likely. That puts the PER at nearly 27 - quite high, but as you can see below, the track record justifies a high rating;
.
.
Overall, I see this as a terrific company, probably priced about right, in my view. Expensive, but the facts & figures justify that premium.
.
.
Costain (LON:COST)
I've covered this infrastructure company a lot in the past, always concluding that its complicated, large contracts, on low margins, make it an unattractive sector.
Looking through today's results, the size of the exceptional charges relating to 2 contracts that went wrong, is such that I've decided to drop coverage of Costain. It's just not a good use of my time, to spend hours unpicking the results, to draw the same conclusion every time. I'd rather write about companies which are quicker & easier to analyse, and where I see a good opportunity for us to make some money. Talking of which...
.
Boohoo (LON:BOO)
306p- mkt cap £3.73bn
This has become my largest personal long position in recent weeks. I know the business very well, and believe that a combination of misjudged short selling, and indiscriminate selling by so-called ethical investing firms (triggered by re-hashed allegations of supply chain problems in Leicester), may have created an artificially advantageous buying opportunity.
As it's become my biggest holding, I spent some time over the weekend revisiting the facts & figures, to reassure myself that risk:reward is still favourable.
Downside risk - this comes mainly from an adverse market reaction to the findings of the supply chain investigation which is due to report directly to BOO tomorrow (15 Sept). The timetable is that BOO will then update the market on its findings, together with its Q2 trading update (June, July, August trading) on 30 Sept.
It's not clear whether the report is going to be published in full, or whether BOO will filter it and summarise the findings? If the latter, then there is clearly scope for BOO to edit out any unhelpful details.
The bottom line with this supply chain issue, is that it won't affect profitability, and the liability for any malpractice rests with the suppliers concerned. All manufacturing is subcontracted out, so there should not be any liability with BOO itself, I believe.
Commentators who say that BOO's profits are built on low wages in Leicester, don't know what they're talking about. Leicester is used for convenience, not because it's cheap. As mentioned here before, the product can be made far more cheaply in Bangladesh, and then air freighted into the UK. Which is what some of BOO's competitors do. Therefore moving production abroad will raise gross margins, not lower them.
Overall then, I see the risk being purely of another short term, sentiment-driven spike down in price, which would present us with another buying opportunity.
Last trading update - I looked again at the RNS on 17 June 2020, updating on Q1 progress. It's remarkably good. After initially weak lockdown sales, trading rebounded, and the group hit +45% sales growth vs LY Q1. Core UK growth was +30%, but overseas much better, e.g. USA +79%, Europe +66%. Total international sales are now half the group total, and growing faster than the UK, so by now are probably exceeding UK sales.
New brands were all trading well in Q1. Gross margin was up to 55.6%. Guidance for the full year was raised. Longer term guidance is for continued revenue growth of +25% p.a. 2 new brands (Oasis & Warehouse) bolted on for just £5.3m.
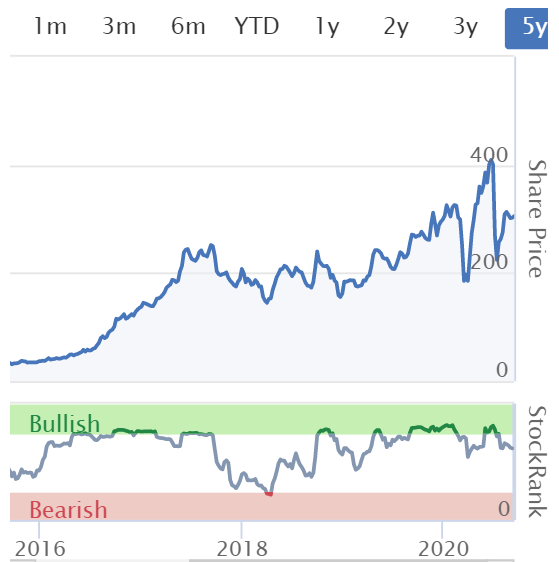
On the back of this, the share price rose to over 400p. It's now just over 300p, so the supply chain issue is knocking 100p+ off the share price, for no reason.
I reckon EPS could rise to c.20p in 2-3 years. Put that on a PER of 40-50 (justified by the continuing growth), and we've got a share price target of 800-1000p, with patience. Hence why this is now my largest position.
New Look - in today's news, rumours are that BOO is interested in buying major competitor New Look. It's not clear whether that is an alternative to the CVA underway, or if it would involve BOO buying NEW post-CVA? So far, BOO has determinedly resisted the temptation to operate any physical shops, but that might change in future, if it can acquire shops on turnover rents? (which is what CVAs are increasingly seeking to do).
Overall, I reckon that once the supply chain issue has been forgotten about again, then maybe we could see the share price of BOO surge again to maybe 400-500p? Longer term, the sky's the limit, as long as it keeps growing.
Obviously please DYOR, and we have to be prepared for a potentially bumpy ride, but I think the fundamentals look very strong here.
.
.
Panoply Holdings (LON:TPX)
Share price: 138p (up c.6%, at 12:21)
No. shares: 67.3m
Market cap: £92.9m
I remember listening to the podcast version of the last results presentation published by PIWorld, and thinking this company sounds interesting. Here is the video of it.
(this guy is either a visionary, or full of buzzwords & horsehair! I'm not sure which)
.
Although when I got home and crunched the numbers, I didn't like the way it was funding acquisitions, which from memory was something like having large deferred consideration dilution in the pipeline. This means the PER isn't actually as low as it seems, once you take into account future dilution.
Today's update- sounds reassuring;
"The Board are confident that results for the full year will be in line with their recently upgraded expectations and in their ability to achieve their three-year commercial vision to deliver £100m run rate revenue by 31 March 2023 with EBITDA of £12-14m.
Acquisitions - the last bit above is an aspiration only, remember. It's fuelled by acquisitions mainly too, so the big question is whether management can execute well. A key question is therefore, what previous experience of acquisitions do management have, and did those work out well in the long term, or not?
The financial year end is 31 March, so Q2 trading referred to below means July, Aug, and Sept to date;
"Following the Group's record performance in the first quarter, in which we delivered organic revenue growth of 10% on a like-for-like basis, I am pleased to report that trading remains strong.
The Group has signed approximately £10m of new contract wins in the first two months of the current quarter, including a £1.8m contract win with Cheshire West and Chester Council, and Cheshire East Council, as well as the previously announced Land Registry contract. In addition, we have enhanced our offering by welcoming Arthurly and Difrent to the Group, with the integration of both companies progressing well".
That's a bit vague, with no figure given for Q2. Good to see that it delivered organic growth in Q1, as well as acquisitions.
My opinion - the valuation looks stretched to me, given a very strong recent rise.
Anyone looking at this share needs to examine the detail of the acquisitions, in particular what dilution & deferred payments are to be made. That's quite material to the valuation, I seem to recall. As I'm not interested in buying this share myself, I'll leave you to do the work on that point!
.
I'm taking a break for lunch now, but might add a bit more later this afternoon. We're mostly done though.
A few brief comments, now that the temperature has reduced to a level where I can think again!
Brighton Pier (LON:PIER)
33.5p (up 10%) - mkt cap £12.5m
This micro cap owns the Palace Pier in Brighton, and has a small group of 12 sub-par late night bars, and 8 golf sites.
It says trading since re-opening has been better than expected, but of the bars, only 2 seem to have re-opened.
Group trading for the period from 4 July to the 6 September has been better than the Board expected, with total revenue from all the Group's open operations at 77% of the same period last year.
On a divisional basis, during this same period, revenue for the Pier was 78% compared to last year, for the open Golf sites was 86% compared to last year, and for the open Bar sites was 59% compared to last year.
I'd have preferred an indication of profitability, more than revenues, or both actually.
It talks about trialling all-seated nights in 2 venues, and being encouraged by the results, but I don't see how that can possibly work longer term - why go to a dark, smelly nightclub, if there's no DJ, and you have to sit down, instead of dance? It doesn't make sense to me. Whereas the larger venues operated by Revolution Bars (LON:RBG) are more versatile, and seem to have better converted into basically being large pubs.
My opinion - I'm struggling to find much appeal to this. Maybe if it jettisoned the bars division, with a pre-pack administration, that would clean up the balance sheet, and get rid of the heavy lease liabilities. I don't mind lease liabilities, if a company is trading profitably from those sites, but doubt that is the case here.
As for Brighton Pier, it's anybody's guess what it's worth? It certainly attracts huge footfall, and is a major landmark.
Group net debt was £11.0m when last reported, and NTAV about £13.2m - similar to the market cap. It's impossible to value, without knowing what someone might pay for the pier. There must be quite a high de-listing risk here too, as I cannot see any point in it remaining a listed share. Maybe Luke Johnson might come up with a plan to inject some new assets into it?
Overall, I can't form a strong view either way, so am neutral.
.
Pci- Pal (LON:PCIP)
40.5p (up c.1%) - mkt cap £24.0m
This is an interesting little software company, that provides niche product to help call centres take card payments securely. Something like that anyway. My friend, who's an expert in call centres, reckons this share is one to back. So I picked up some stock a while ago, but recently got a margin call, and this position had to go, as I had less conviction in it than everything else.
I've not yet had a chance to talk to my pal, for his better-informed-than-mine view.
Skimming over the results for FY 06/2020, there are some interesting signs of progress. Here are my very brief notes;
- Strong growth, revenues up 56%, but only to £4.4m, so still very small
- Recurring revenues now at a run rate of £6.75m (up strongly, +66%)
- Heavy loss of £4.35m, but this is in line with expectations
- Cash for about another year of burn, at £4.3m, plus a £1.25 debt facility. Hopefully the cash burn would reduce as it grows further, with high gross margins
- Recent trading looks solid at +41% in July & August, although maybe it needs more growth than that?
My opinion - looks interesting. Maybe a £24m market cap is appropriate at this stage given that it still has a mountain to climb to reach profitability? I'll probably buy back into this, on a small scale, if/when I have any spare cash burning a hole in my pocket.
.
Xpediator (LON:XPD)
26.25p (unchanged) - mkt cap £37m
Xpediator Plc (AIM: XPD), a leading provider of freight management services across the UK and Central and Eastern Europe, is pleased to announce its unaudited condensed interim results for the six months ended 30 June 2020.
I can't see myself ever investing in freight companies again, but on a quick skim of these interim numbers, XPD seems to have done fairly well in H1 2020. Adj PBT is up a little on H1 LY, at £2.1m - low margin work though, as you would expect, with revenues around £100m for H1.
Outlook comments sound solid, if unexciting, with business returning to normal, and profits expected to be similar to last year.
Note the large adjustments in both years - so how real are the adjusted profits?
Balance Sheet - write off intangibles, and NTAV is only £3.6m. Note also the very large receivables, and payables. So managing risk & financial control generally, is of the utmost importance, in a low margin business like this. You need credit controllers with nicknames like "The Rottweiler", within this type of business.
My opinion - I wish them well, but XPD has not impressed since it listed. To be acquisitive, and create shareholder value, the trick is to get a high stock market rating, then make lots of cheap acquisitions funded by expensive equity and cheap debt. That doesn't seem to have worked here, and I can't really see any reason why it would begin to work in future. Probably best to spend our time researching things with more upside potential & better business models?
In the back of my mind, I had a hunch that this IPO was about shareholders wanting to make a killing from the stock market and then retire comfortably? It's not really worked, if that was the agenda. Can't blame anybody for wanting to make a few bob though. Caveat emptor & all that. Nobody forces anyone to buy any share.
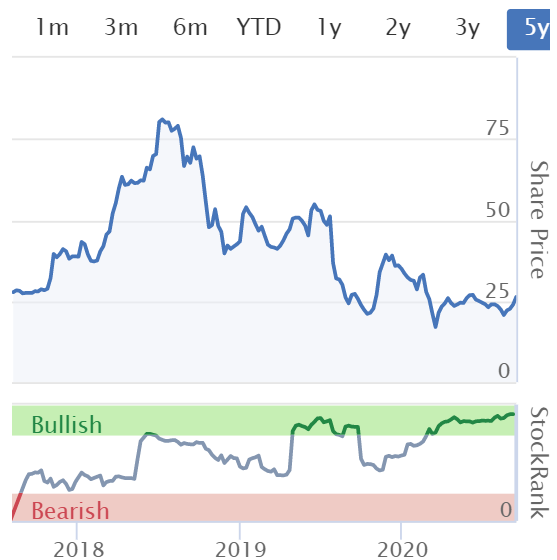
Interesting to see that the StockRanks seem to like it - maybe I've missed something positive? Do let me know if so, as always opinions here are subject to change whenever the facts change.
.
.
Surface Transforms (LON:SCE)
41p (up 67%) - mkt cap £63m
This share reminds me a bit of Torotrak - remember that one? Both companies seemed to have invented solutions to automotive problems that didn't exist. Torotrak decided that tractors, or ride-on lawnmowers, or something like that, suffered from inefficient gearboxes. SCE thought that conventional brakes weren't good enough. Investors randomly seemed to become emotionally attached to the shares, and support repeated fundraisings, defying all logic, and occasional clear-outs of management.
The reason I'm highlighting SCE today, is that it's put out an announcement which actually looks quite interesting, hence is worth a closer look. Sports car makers seem to be convinced of the merits of its brakes, hence it seems possible that a viable business could eventually emerge here?
What sustainable advantage does it have? With vastly larger R&D budgets, how can it stop competitors copying/beating it? Won't costs just rise as fast as revenues? Will there be any sustainable divis?
Answers on a postcard please! Good luck with it. I'll stick with my juicy divis from cheap sofas, and concrete screeding!
.
Symphony Environmental Technologies (LON:SYM)
29p (up 24%) - mkt cap £47m
Interim results show £4.8m revenues, and breakeven.
So why is it valued at £47m? Jumping on the covid bandwagon, in my view. Previously, the story was all about biodegradable plastic. Now its switched to covid-proof plastic.
I got smooched into this a while back, on some rampy story, and I lost £8k on it by the time I realised it was largely hot air! Not by the company, I hasten to add, but an over-excitable friend.
So please forgive me for being a bit more sceptical, second, or maybe third time around.
.
I'll leave it there for today. See you in the morning!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

67 comments
If you are unwilling or incapable of researching the carbon ceramic brake for cars probably best not to comment at all. There are two companies in this line of work Brembo indirectly owned by the family behind BMW turnover 100m plus supplying chopped fibre ceramic brakes and Surface Transforms which make a more robust long fibre product which is used by some of the extreme sports car manufacturers SCE is being pulled into offering a rival product by the other car manufacturing groups who are uncomfortable with the Brembo monopoly.
Great! You're going to be rich, rich, rich!!!
Tomb,
Your comment has been unfairly voted down. Surface Transforms (LON:SCE) are in an interesting position because ceramic brakes are widely used and there is only one other competitor in the space. You know this, other readers may not.
The problem SCE always was going to have is initial orders. Brakes are mission critical components: if they fail, people die. And so no manufacturer wants to take a chance using a new brake supplier unless they are certain they work. Now SCE has 2 major clients, given that their product is better than the alternative, it is quite possible that they will quickly become the main player in this industry.
So having been a basket case company for 10 years plus, they are now in a sweet spot imo. I see no reason why there won't be many years of growth for SCE from here. They've done the hard work, its a market which has been a monopoly dominated by a BMW owned company that most manufacturers would want to be free from, and SCE have a superior product. I think for investors looking to park some money for a few years SCE will be a very good place.
Best Of The Best (LON:BOTB) bought in before the takeover bid and getting 'bored' which may be a 'tactic' but wondered how long these things go on for - put up or shut up I feel and get it over with.
Changing name to Mr Impatient.
Panoply Holdings (LON:TPX) - super relevant as digitalisation takes place with councils (and private clients) but the spread - you can fit a bus through there!
You can fit a bus between what its valued at, and what I reckon it's worth too!
re: Boohoo (LON:BOO) Paul says "It's not clear whether that is an alternative to the CVA underway, or if it would involve BOO buying NEW post-CVA?" These suggest the former:
https://www.retailgazette.co.uk/blog/2020/09/boohoo-circles-new-look-as-it-lurches-towards-administration/
https://www.drapersonline.com/news/boohoo-circles-new-look
That is what EWM did with Austin Reed in 2016 - bought the brand and online customer list from the Administrator and let the shops go.
Paul
Which book about the Spanish Flu are you reading,, and would you recommend it in a review ? Thanks
Hi threeputt,
I tend to buy audiobooks, on audible, because my eyes are too tired for reading, after staring at a computer screen all day.
Hence I only had a very limited set of options for audiobooks about Spanish Flu. The one I've just started is called "Pandemic 1918". I've found it slightly irritating in parts, so far, so no I wouldn't recommend it.
If anyone knows of something better, then please let me know!
Regards, Paul.
Thank you for your insights into £BOO. My largest holding (at 10% of pf) apart from Anglo Asian Mining (LON:AAZ) and the way the two shares are performing at the moment I could see that position switching!
Regards
Michael
Michael I'm not a shareholder or ever would be and I'm not quite the right demographic to be a customer (by around 50 years). I am though interested in Boohoo (LON:BOO) as a business story. Boo buys more than £500m of products each year and they will have very close links with their supply chain - they have a Director of Sustainability whose job description includes this. See pages 24-31 of the annual accounts. They will likely have term supply arrangements with their suppliers and daily interactions with them. This would include routine inspections.
Lets see what comes out of the review but a PER of 57 is not allowing for any surprises.
Hi kgb1953,
Re BOO, you say;
They will likely have term supply arrangements with their suppliers and daily interactions with them. This would include routine inspections.
That's not at all how the fast fashion sector works.
BOO's predecessor companies, Jogo and Pinstripe, used to be the biggest suppliers of the retailer where I was CFO between 1993-2002. We placed orders with them on the basis of what our buyers thought would sell the best, and based on how quickly they could make it. As the buyer, we often had no idea where it was being made, i.e. which country, let alone which factory. They would source from all over the world.
We only inspected product for quality, before it was shipped and this was not necessarily in the place it was made. That was only done if there was some question mark over product quality. If the supplier consistently produced good quality, we wouldn't inspect anything. We'd just send it back, if it wasn't any good. I don't think we ever inspected working conditions in factories. That would have cost a fortune, and be totally impractical. Why on earth would we do that?
Yes there are close relationships with suppliers, but we didn't think it was our job to police how the product was made. That's the job of the supplier itself, and Govt agencies.
I suspect (but have no proof whatsoever for this) that retailers, whether online, or physical stores, recognise that they need to give the appearance of caring about ethics, but in reality, I don't think they give a damn. Nor does the end customer - they also pretend, but ultimately buy product if they like it, and it's cheap.
Regards, Paul.
Well we have different experience. I recall how Marks and Spencer dealt with its suppliers. If you read the bit in the annual accounts of Boo they outline a very big programme working with their suppliers. Also we now have the Modern Slavery Act where companies are obliged to ensure their supply chains are compliant.
Finally you at least have to consider how integrated Boo is with these local suppliers. It might be closer than you think.
Michael I saw your other post about this, saying the share price could triple within 5 years. This made me think. If we say the PER goes to 25 then EPS will have to increase by a CAGR of 45% over that five years - EPS would grow six times. Doubling the share price would require 35% CAGR. Isnt a lot of the forward value already in the price?
Not having a go - just interested as a value investor in how 'growth' shares like this are valued and what assumptions have to be made.
Hi Paul,
I recently bought small amount of BOO as I like the fundamentals however, my usual criteria in picking an investment is double digit operating margins. I see BOO's margins are high single digit is that the norm for a fashion retailer?
The stock report for Boohoo (LON:BOO) shows its operating margin is 7th out of 38 for its industry.
Thanks - found it. I have never hovered over those bars - luddite, lol
Fashion retail stocks like BOO live and die on publicity, BOO and its competitors' sales are literally built on influence(rs). The supply chain scandal earlier this year is really likely to dent the sales with the target market combined with the fact the lockdown meant everyone was buying less clothes. Personally, I can't see the forecast above being realised due to the above.
You did not see the ASOS (LON:ASC) update "Asos shares surged on Wednesday after the online fashion retailer said full-year sales and profit were set to be "significantly ahead" of market expectations thanks to a shift to online shopping during the coronavirus lockdown and as customers return fewer items."
As Paul says the problem with Costain (LON:COST) (and other contractors) is low margins and the risk of things going wrong.
For any still interested in Costain management go into some detail on how they are addressing these specific issues here: https://www.investis-live.com/costain/5f2c19bb6fbfa21200a11820/efds with slides https://www.costain.com/media/599145/hy20-analyst-presentation_140920-final.pdf My own view is that if this does improve things it will still take a time to work through - slide 23 shows FY 2024 target date.
Paul, I have have been persuaded by most of what you say on Boohoo Boohoo (LON:BOO) (and have bought back into Boohoo itself ) but I think there will be some financial impact from the supply chain allegations. In July they said they were "making an initial commitment to invest an incremental £10 million to eradicate supply chain malpractice", That sounds like a revenue expense although may be over a couple of years? Plus there will be some lost sales, even if not too much - I think it unlikely the bad publicity will affect any brands other than Boohoo, even though I think the original allegations actually concerned items sold under the Nasty Gal brand.
I would have thought that long term the effect on Boohoo (LON:BOO) will be negligible and in short term at least half of their sales (the non U.K. element/non Boohoo branded element?) will also be completely unaffected.
I am not at all concerned and suspect that Paul is right that within three to five years the price will have doubled/tripled from here and happy to hold through any turbulence.
Regards
Michael
Theres a free report from Equity Development here on Xpediator (LON:XPD)
https://research.equitydevelopment.co.uk/research/positive-agm-update-0-0-0
Not sure how good this site is but they do not appear to be rampers. I used to own Xpediator (LON:XPD) as its was a Jim Slater screen pick at one stage, but I bailed out at a loss at 58p and they are now currently 27p. Brexit did it for me, but they do appear to be a well run company.
I have shares in Mj Gleeson (LON:GLE) which reported today. Its a funny one as it has two quite separate activities - building low cost starter homes in the North of England and buying land for development by others in the South of England. The shares don't seem to go anywhere and I wondered if others have a view. At a market cap of £350m I think its in scope here.
The thing I don't like is the high level of executive remuneration that seems to be an issue with the housebuilding sector.
The former CEO was ejected in June last year largely because he was too expensive, I presumed that the new incumbent would be cheaper. (Especially as he effectively oversees to largely independent businesses.)
I haven't had chance to look at the latest figures yet, but was your comment related to the past or is the situation still the same?
Dont think he is and there was a large share award in July to the CFO and others - nearly 3% of total shares. The new CEO has a base salary o over £500k and a max package of over£1.5m (or if the share price goes up £2m). When the company is making c. £30m this is too high. Also the LTIPs dilute the shares.
I like the model - the low cost housing piece anyway - and cant see why the shares aren't doing better.
Dont know if this is on Paul's radar of other holders might like to comment.
Thanks kgb,
I must check up further on the remuneration, reading today's announcement now I see that it is nor covered* so that must be hidden away in the R&A.
* Other than the warm and fuzzy : "The Board and senior management accepted temporary salary reductions ranging from 5% to 30% so that more junior colleagues could continue to receive full or near-full pay." Ahh, bless!
I slightly mis-read you comment and thought to myself that if the share-price went up 2m, i would not begrudge any bonuses - DOH!
I should probably kick the tyres more on that aspect. FWIW though two theories on why MJ Gleeson (LON:GLE) remains unloved (re the homes business) :
1. Because of the lower end price point focus; Gleeson is more exposed to the potential withdrawal of "help to buy".
2. Perhaps there is a perception that Gleeson's target market are more likely to be hit by the Covid recession.
On the first I think that something will replace HTB (especially with this "interventionist government") but it will be more targeted - by and large I would say GLE's buyers are the intended target audience.
On the second; I am not sure how far that holds true - I doubt many Barristas can afford to buy even a lower end price point home.
You have given me a useful reminder though to review my small position here - I am not too badly underwater here having bought on the dip from Jolyon Harrison dump his shares after leaving,
Actually I wrote about this at cube (for those that subscribe) and from my note's Harrison was paid £3m, so whilst I would agree that the new chap is perhaps not "cheap" he is substantially cheaper!
Mj Gleeson (LON:GLE)
Hi Gromley
I don't hold £GLE , but it's high on my watch list.
With regards to your comment on the target audience, I added 1 excerpt to my notes from today's update:
"At the heart of what we do is build homes that are genuinely affordable and provide our customers with the opportunity for wealth creation through home ownership. It is substantially cheaper to buy a Gleeson home than rent with a typical three-bed Gleeson home costing as little as £76 per week with a Help to Buy mortgage compared to renting a three-bed home which costs around £138 per week in the private rental market.
A working couple on the Minimum Wage can buy a home on any Gleeson Homes development site."
Knowing that a large portion of their buyers are key workers, I can't imagine they will ever have a problem selling their properties.
Cheers
A
Thanks abtan,
I do agree that the fear of their demand drying up, seems overblown.
I'm pretty amazed though by the numbers they quote there - maybe there is a bit of smoke and mirrors with introductory rates, but a £76 / week mortgage for a 3 bed house is insane. At an interest rate of say 2% that puts the mortgage amount at less than £80k.
My mind boggles.
A quickie on the saga of Saga . Do we think the placing is effectively a done deal and the vote on October 2nd a formality.? They seem to be halfway there already. There maybe 1 intstitution with a 5% holding against the deal. Also the percentage issues are giving me serious brain ache. If Sir DeHaan is investing at least 100 million in a company worth 160 million plus placing of 150 million he's pretty well got 33% of the company. Would that be a breach of takeover panel regulations? Many thanks
I'd say it's a very high likelihood of the Saga (LON:SAGA) (I hold) fundraising being voted through. The shareholder base is quite fragmented, and the deal includes an Open Offer, so I can't see why anyone would object to it, and thereby knowingly put the company at greater insolvency risk. It's incredibly rare for a deal like this to be voted down.
I think the Open Offer might claw back some of the shares from Sir Roger, but the detail is quite complicated, and doesn't really matter that much.
The results presentation video on SAGA's website is a good use of an hour of your time, as it goes through a lot of detail.
https://corporate.saga.co.uk/d...
Once the (brand new) 2 cruise ships are operating again, and generating forecast £40m p.a. EBITDA each, then the group could be making £200m+ profit/cashflow per year. The plan is to use that to reduce debt, so no divis likely for a couple of years, but what would the valuation become at that stage? Over £1bn I would imagine, maybe up to £2bn. Hence if things go well, I could see this being a very good investment.
Even in the downside scenario, of covid preventing the ships from sailing, the travel division's cash burn of £6-8m per month is manageable, and should be more than covered by profits from the insurance division.
Nothing is guaranteed of course, it all depends on how management executes. I like their plan though, it all makes sense. Going back to basics on the brand value, but modernised for a digital world. In my view, the brand is potentially worth a fortune, if the group is better managed.
Regards, Paul.
Hi Simon,
My understanding is that the most equity Sir Dehaan can own after the capital raise is 26.4% and this is likely to be lower assuming existing shareholders take up their rights - the reason for the discrepancy with your maths is likely to be that Sir dehaan is subscribing for the majority of his new shares (224m) at a price of 27p rather than the 12p price paid by other subscribers . Hope this helps.
Thank you both.
Mirriad Advertising (LON:MIRI) IGotPoesJacket Suggested on friday that if i liked Mirriad Advertising (LON:MIRI) id love Blackbird (LON:BIRD) which having had a look over w/e i do love, cloud video editing software. They have an amazing client list & and are signing customers very fast, loss making but not for ling I suspect. Thankyou for the suggestion IGPJ, and the most crazy name, yours not blackbird!
Your view on XPD would be appreciated who reported today.
Decent looking interims from Medica (LON:MGP) today. Nighthawk reporting activity now higher than pre-covid levels, and elective procedures reporting now over 45% of pre-covid levels. Imo i'd expect vast majority of the missed elective activity will be recovered in time as the NHS attempts to clear the massive backlogs over the next couple of years. Company had grown impressively over several years pre-covid.
Re Medica (LON:MGP) I saw a documentary on the use of non-human parallel to human (ie Medica) type analyses, and frankly the former performed as well as the latter. The combination required only 50% of the normal double-up human process-and-check standard system, and turned me away form the Medica-type service because the demand for human specialists would be reduced. I may be barking up the wrong tree, but that was the conclusion I was left with. Also the historical perfomance of Medica has been disappointing against a series of promising forecasts. No longer on my watch list
Yes you are barking up the wrong tree for the short to medium term in my opinion. AI will ‘assist’ the radiologist in the future well before the human eye is replaced by technology (eg could be used to highlight lung nodules on chest CT). That is science fiction for now. That is were the technology is being developed but has been slow to be adopted. There is no risk to Medica from this in the short to medium term.
Medica is essentially a human resources/staffing company, and one of four or five similar teletadiology companies in the UK (the rest being private). Medica has been around for a long time - 15yrs-ish.
There was a good debate with Paul last week about £MIRI. If you'd like to find out more on the company come to the webinar with management today at 12 and ask them the important questions. register
https://us02web.zoom.us/webinar/register/2815984378116/WN_41qwB0SQRn-VLJPzmylGaw
Paul please can you provide a view on LON:FRP Thanks
He covered the results here
Onthemarket (LON:OTMP) signs up Taylor Wimpey (LON:TW.) to the platform. Very good news, the portal is going from strength to strength.
Any chance, please, if you could look at why Concurrent Tech (CNC) has negative momentum recently. It's a quality company in my view but with specialised and diversified product portfolios there may be delays in both demand and supply. I remain a HOLD but I'm down c11% and graph trend is down.
Thanks for flagging this up Phil. Possibly the interims are a bit flat. One off cost associated with reorganisation of engineering team. cessation of Indian operation presumably all to do with Covid. On the plus side the new chairman's first purchase for 20,000 shares and record order book. Inline market expectations reaffirmed. It has just tested new highs after almost halving back in March/April. Although growth looks a bit muted for now and something about way results are presented. This seems to be a reoccurring theme recently in company results. Maybe Paul could enlighten us on that. Also like many would have liked to hear more specific news how Ai enablement on their boards is adding to the company. They certainly don't oversell themselves, which is no bad thing. Let the numbers do the talking. Have been in and out of this since the 20p days. has been slow progress at times, but divi growth helps. I'm confident enough to have a little top up on this slight pullback. GL
I just sold my Concurrent Technologies (LON:CNC) so you can have them ;)
No big reason beyond the drop in price. I decided it wasn't working the way I hoped and moved on. I guess that's dumb momentum at work. Also I wasn't that impressed by the ~£20k initial buy by the new chairman - he might have done better not to bother than make that lukewarm commitment.
I've put the proceeds into £CLIG. Fingers crossed for us both.
Without any fresh news I suspect Paul is unlikely to prioritise Concurrent Technologies (LON:CNC) today - but perhaps sometime on a very slow news day, or when they actually issue an RNS, since it has had no SCVR coverage in 2020? Paul, this is another favourite Lord Lee holding (like Anpario (LON:ANP) you recently wrote about), with similarly super-strong balance sheet, great margins and some growth.
I am a holder, but with a modest stake I would be happy for the share price to continue to fall (fading tipster effect, reality of earnings w/o life insurance), so that I can buy more at a more attractive valuation. (For patient investors I think this is a good one to tuck away; less sure about AI hype and momentum-chasing).
Hi where do you get the latest Lord Lee portfolio and updates ?
Thanks Andy
I rarely read the FT so have never seen Lord Lee's articles in there, although I have read his book.
I keep track of his investments by using the Parliament website list of registered interests: https://members.parliament.uk/member/1132/registeredinterests
Many thanks
You will need FT sub.
https://www.ft.com/stream/7bff...
I often read the Saturday FT (in paper version) where every month or two he writes about his portfolio in the Money section. In addition I have a free online registration with FT and on my "MyFT" I have selected "John Lee" as a topic, and titles of all his articles come up. The free registration (sometimes?) enables you to access a full online article. E.g. on Saturday 1 August he wrote about his favourite 5 picks for a bet with a friend: Anpario, Cerillion, Concurrent, Lok'nStore and Treatt (his largest holding).
Another nice contract win for £MWE in the 5G antenna space. This companies been re-rated over the last year but I continue to see upside over the next couple of years with both there 5G and water intelligence businesses in the right place at the right time. I have been long for a few years and continue to be.
Not one for the traders but very pleased with the progress of this over the last couple of years.
Dear Paul - I would be very interested to know what you think of City Of London Investment (LON:CLIG) as a long term investment: conservatively managed investment company with good track record, a long history of growth in dividends (currently yielding 7.8%), very reasonable results IMHO considering Covid-19 flows out of funds, and recent acquisition opening more access to the US market and significantly expanding funds under management. Thanks!
I've always been a fan of City Of London Investment (LON:CLIG) and an on/off holder (I currently hold). The company is usually very transparent and conservatively run with a fantastic dividend and balance sheet. The downside is it's never commanded a very high rating even though it has a secure dividend. A 20p final divi is being proposed to holders on 9 October making the total dividend for the year 30p - around 7.5% at c.400p.
The EPS today looks like a slight beat against house broker's expectations. According to the broker the merger is expected to then push EPS to around 45p for FY21 then 50p the year after (with 30p DPS) - obviously these figures are best guesttimates in today's market environment.
While the company it is merging with only earned $461,898 post-tax profit last financial year, its CEO Mr Karsus earned US$15.5 million last year but will resign from the Board and only earn $100,000 in consultancy fees thus providing an immediate uplift to profits.
Obviously there is huge execution risk here - particularly as this firm seems to have been focused around a powerful figurehead - but the merger looks like a very good earnings enhancing move at face value.
Just to add a technical aspect - looks like a nice cup and handle on the chart, could be priming for a move up.
On City of London Investment (LON:CLIG)
I bought and have held since 2013.
Not a real 'technical' person but if you look at the monthly chart from ~2013 you can see a fairly clear and narrow channel and the sp fell below that channel in March and is just moving back in.
It does amuse me that imagining a squiggly line in some resembles a cup and handle is in some way considered "technical".
I’m also a holder of CLIG for the long term. Could Paul also look at Bango which is up > 200% this year!
Tony D
Simon Thompson tipped £CRL. any thoughts on it being misjudged after the trading update and undervalued.I have had it on my watch list and considering buying
There is a great presentation on PIWorld, and various pieces of assessment and commentary, if you go to Creightons (LON:CRL) and then click on the discussion tab you will find them.
https://www.piworld.co.uk/2020...
Solid company doing what it says on the tin, makes a profit, traded reasonably well through the shutdown.
Note that it has a fairly low free float ~33% and a fairly wide spread with no broker coverage so smaller trades can trigger larger movements (up and down) but a good track record of year on year growth.
I do not hold (currently).
Tommy
The most interesting bit of the Creightons (LON:CRL) results announcement last week was during the presentation they say they are aiming for £55m revenue and 7% post tax profit for FY 21. Given that ends in March those seem like good indicators, albeit no-one knows what will happen over the next few months. 7% post tax profit reads through to about 5.2p EPS by my rough calculations. However, I am not sure I want to pay a very high multiple at the moment as surely during a recession people will cut back on non-essential beauty products...?
Creightons (LON:CRL) Creightons - 10 years of growth at an average of 14% is it time to rerate as a growth stock.The link below provided a valuation model below. Creightons (LON:CRL) happy to hold for the long term.
https://www.stockopedia.com/co...
BSV
My morning smallcap tweet:
Symphony Environmental Technologies (LON:SYM) Brighton Pier (LON:PIER) £N4P Aeorema Communications (LON:AEO) Focusrite (LON:TUNE) Surface Transforms (LON:SCE) Seeing Machines (LON:SEE) Fletcher King (LON:FLK) EKF Diagnostics Holdings (LON:EKF) Colefax (LON:CFX) Xpediator (LON:XPD), Panoply Holdings (LON:TPX)
Symphony (SYM) H1 & trading: "more recent activity within our strong pipeline indicates a pick-up for the rest of the year and into 2021." Also further testing shows efficacy against viruses of d2p anti-microbial technology in plastic products. [SP=22.99 Cap=39m]
Brighton Pier Group (PIER) last 2 months rev down 23%, better than the Board expected. "The potential need to repurpose dancefloors and to seat customers in a socially distanced fashion, with an absence of live music and dancing, will fundamentally change the business model with significant reduction in capacity. Given the uncertainty surrounding reopening dates, the Group has been working on plans to trial this new model in some of its larger venues...encouraged." [SP=30 Cap=11m]
N4 Pharma (N4P) Covid-19 Proof of Concept Update: a single injection used in the stage 3 pre (pilot) in vivo study didn't result in desired effect but neither did the positive control. "Additional exploratory studies will continue to understand the translation potency of the Coronavirus plasmid including optimisation of Nuvec plasmid loading. With this in mind and taken together with previous positive data, the Company has decided to proceed to a full in vivo study." [SP=9.6 Cap=15m]
Aeorema Communications (AEO) opens first US office to better service US clients. Has also completed the development of its own virtual events platform. [SP=20.45 Cap=2m]
Focusrite (TUNE) guides FY(Aug) rev £129m, up 52%, ahead of market expectations. Core Focusrite Audio Engineering business rev up 23%. Will repay furlough cash. [SP=741 Cap=431m]
Surface Transforms (SCE) chosen as tier one supplier of a carbon ceramic brake disc on a vehicle by a global vehicle manufacturer. Est rev to 2024 c. £27.5m but no min. Guides FY rev £2m, £400k higher than market expectations. [SP=25.04 Cap=39m]
Seeing Machines (SEE) to launch driver monitoring system Kit on Qualcomm Snapdragon Automotive Platform. [SP=4.14 Cap=139m]
Fletcher King (FLK) FY rev doen 15%, adj EPS 12%. Outlook "It is very difficult to accurately assess our future trading performance in the current market conditions. It will be extremely challenging to remain profitable and it is very likely that the Company will make a loss in the first half of its financial year." [SP=31 Cap=3m]
EKF Diagnostics (EKF) H1(June) rev up 23%, pretax up 180%, div 1p( 0). FY likely to exceed management expectations. [SP=57.22 Cap=260m]
Colefax (CFX) FY(Apr). No div. Current sales trends are ahead of initial expectations at the start of the pandemic. [SP=392.8 Cap=36m]
Xpediator (XPD) H1(June) rev down 3%, adj pretax £2.1m, up 5%, div 0.45p (0.28p). Now trading close to normal levels. Guides FY adjusted profit at least flat. [SP=26.25 Cap=37m]
In line: Panoply Holdings (LON:TPX)
Paul - Would be good if you could cast an eye over EKF Diagnostics Holdings (LON:EKF). Seem to have done well from COVID testing, notably from its swab sample stabilisation vials. If the Boris "Moonshot" has his way this could be transformational for them.
I hold Ekf Diagnostics Holdings (LON:EKF) and think it is well positioned for Covid and longer term for the greater focus that I expect will be given by healthcare systems to diagnostics. Strong net cash position. Good track record of creating value, particularly with £RENX
This morning the stock is down, which I think is fair enough as there is no new news. The market is expecting roll-over orders into Q4 and 2021 for PrimestoreMTM (which is the key near term driver for the share price.). The company is still expanding its production capability - so either we can take that as a sign of confidence or as a reason to get nervous as Q4 approaches.
There is an InvestorMeetCompany presentation at 4:30 today.
I'm puzzled by the Ekf Diagnostics Holdings (LON:EKF) investment in start-ups that come out of its relationship with Mount Sinai and then distributing the shares in specie to its shareholders. rather than keeping them as an investment (and where appropriate supporting the start-up's growth). Has there been an explanation of the reason for this?
The interim results today look detailed and transparent and the business looks like an interesting GARP opportunity. I'd welcome Paul's view of the finances.
Julian Barnes gave his justification for Ekf Diagnostics Holdings (LON:EKF) investing in the Mount Sinai partnerships on page 8 of the InvestorMeetCompany presentation. I suggest listening to the presentation (rather than just reading the slide) as he talked around the slide quite a bit (although he did not explicitly answer your question - why then distribute them in specie). From the presentation I would expect more such investments in future.