Small Cap Value Report (Mon 15 Aug 2022) - JOUL, PMP, GUS, TET, SEE

Good morning from Paul & Graham!
Weekend Podcast - for anyone interested. I've no idea how many listeners these are getting! It went up on Sunday morning this weekend, as I was out on the razzle on Friday night in Bournemouth, so nothing much got done the next day.
Agenda -
Paul's Section:
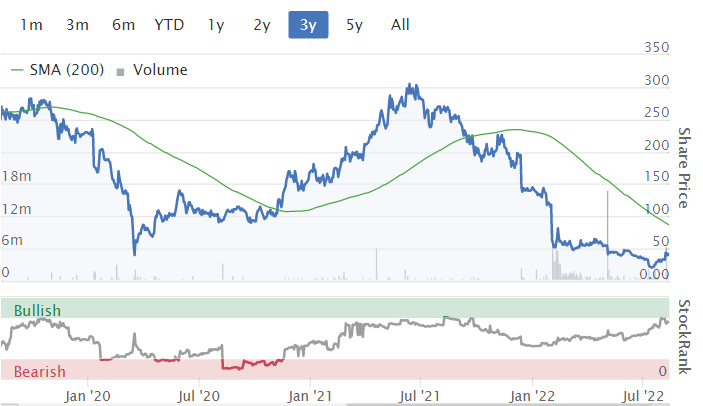
Joules (LON:JOUL) (I hold) - good news that a new CEO has been found. I recap on the various issues that have made this share such a disaster in the last year. So it all hinges now on shoring up the balance sheet, and swift action needed from the new CEO to sort out its problematic supply chain & excessive inventories. Could be a good turnaround, but risks remain.
Gusbourne (LON:GUS) 67p up 5% at 08:45 (mkt cap £41m) [no section below] - I’ll keep this brief, as GUS shares are illiquid, given that Lord Ashcroft owns 66% of it. H1 (to 6/2022) revenues are small at £3.0m, but that’s up 108% Y-on-Y. Asset-backed borrowing facility increases from £10.5m to £16.5m, for 5 years, “at a competitive rate”, 2.5% over BoE base rate. GUS is spending £1.6m buying 137 acres of adjoining land from one of its own Directors. Vines will be planted in May 2024, so it’s long-term in nature. I reviewed GUS’s last accounts here in June, and was unimpressed. On the same day I also looked at fellow English wine maker, Chapel Down (OFEX:CDGP) and think that looks a far better financial bet, if you have to own one of these shares CDGP is clearly the better investment proposition - bigger, already profitable, and with a decent balance sheet.
Graham's Section:
Portmeirion (LON:PMP) (£56m) (pre-market) - a very small acquisition for Portmeirion but the new brand “Aromaworks” could have significant long-term growth potential in the hands of Portmeirion (time will tell). I use the opportunity to discuss why companies in administration often make for spectacular investment opportunities for the people who buy up the assets or who buy the debt and wipe out existing equity holders. We can’t take part in these deals ourselves, but we can look for listed companies who are able to do it, and share in the rewards.
Treatt (LON:TET) (£340m) - there’s a major profit warning from this provider of extracts and ingredients. The macro headwinds are more difficult to overcome than either the company or its investors expected, and have appeared rather suddenly over the past three months. This does raise some questions about the underlying quality of the business. However, if the problems are temporary and can gradually be resolved, as I suspect, then this remains an attractive business to own and the outlook for investors willing to own it for many years has not fundamentally changed.
Seeing Machines (LON:SEE) (£263m) (+3.6%) [no section below] - this FY June 2022 trading update is in line with expectations. The company is keen to stress that its cash position is ahead of expectations. SEE is a loss-making cash-guzzler that is not expected to be profitable for the foreseeable future, but it commands a large market cap due to its driver monitoring system (DMS). This technology can save lives and is in a niche likely to experience rapid growth in the years ahead. Today’s RNS includes huge percentage growth figures at the top; lower down, it acknowledges that revenues are only up by 15%. This is an interesting company but as an investment it sits firmly within the category of extremely risky stocks, along with lottery tickets and racetrack betting slips.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Joules (LON:JOUL) (I hold)
42p (before market opens)
Market cap £47m
The Board of Joules, the premium British lifestyle Group, is pleased to announce that following a thorough selection process, Jonathon Brown will become the Group's new Chief Executive Officer (CEO). This follows the Group's announcement in May 2022 that Nick Jones would be stepping down from the role during 2022. Jonathon will initially join the Group as CEO designate on 7th September 2022 and will become CEO on 30th September following a short handover period from Nick.
The section about the new CEO Designate’s background shows he was most recently CEO of Compare the Market. I wonder if he’ll be bringing in adorable furry animals to represent Joules in its adverts too? Have you noticed how they’ve watered down the meerkats’ Russian accents in the latest ads?!
Brown seems to have a fair bit of other big company experience (Aviva, British Airways, Coca-Cola, etc.), but not exactly a fashion focused CV. Although arguably Joules has got too many creatives already, and above all it needs someone to keep them in line, and stop over-ordering stock that doesn’t sell. It’s the logistics (and excessive costs) that have gone wrong at Joules, so let’s hope he can straighten that out. Although it could be tricky with the lurking presence of the founder Tom Joule as Chief Brand Officer, and 22% shareholder.
Pricing power is key at the moment, and when I get a daily email from Joules offering 50% off large numbers of lines, it concerns me. Permanent sales means that customers wait for the discounts, so margins are permanently under pressure. Superdry (LON:SDRY) (I hold) has been rigorous on this, only selling full price product in its stores.
Also the new CEO will need to shore up the finances, as banks don’t like exposure to companies that are performing badly, and are over-stocked. The last broker note on JOUL said that the business was being run for cash, not profits, which is obviously concerning.
Although being a decent-sized listed company, banks don’t normally pull the plug, they nearly always give companies time to raise fresh funding from shareholders. Although that can sometimes be at a deep discount, if raised from a position of weakness.
Joules also has a large freehold head office, which plenty of people think was a vanity project costing far too much. Although it could in theory be used to reduce bank debt, via a sale & leaseback. The existing bank debt is secured on it.
The final issue, is negotiations underway with Next (LON:NXT) reported in the press, and confirmed by the company recently on the RNS. That would involve dilution of course, but having Next on board as a key strategic investor would make total sense, given Next’s expertise in supply chain & logistics, which is Joules’ persistent weak spot. Also JOUL product would clearly be prioritised on Next’s multi-brand eCommerce platform, if NXT owned the mooted 25% of JOUL which has been suggested it might pay £15m for (enough to pacify the bank, I imagine).
My opinion - it’s been grim, but there are signs of hope now. It all depends on how the new CEO performs, and whether he’s able to make sweeping changes to unlock what I still think is an excellent mid-market brand.
Shares are very difficult to value at the moment, because we don't know if, or how quickly, the business can be turned around. Sorry it's been such a disaster, I didn't realise how badly things were going wrong at the company. Although I note that in the last couple of months, broker forecasts have edged up, from breakeven to a small profit, so maybe some progress is already being made?
We saw recently with Revolution Beauty (LON:REVB) that excessive inventories have delayed the audit, and a (currently unknown) write-off is going to be necessary - which hits profits of course. JOUL might need the same thing, due to it also being over-stocked.
.
.
Graham’s Section:
Portmeirion (LON:PMP)
- Share price: 402.5p (pre-market)
- Market cap: £56m
This well-known crockery group acquires a small home fragrances company. Portmeirion already owns Wax Lyrical, a brand that provides candles and diffusers.
To be more precise, however, Portmeirion has not actually announced that it’s buying a company today: it’s only buying the intellectual property, inventory and certain assets of the target company (which is in administration).
While this deal is very small (<£1m), it does give Portmeirion ownership of a new brand that is already listed in major retailers in the UK and the US. That brings with it both an opportunity to use its own resources to grow this brand, and potential cross-selling opportunities for all of Portmeirion’s brands. So despite the low price, there is optionality for a much bigger financial outcome.
This comes back to a theme I’ve been thinking about recently and which is only going to get more relevant as more companies experience financial distress: the best financial deals often involve companies in administration. The amounts paid in these deals tend to be tiny, as brands and assets with significant long-term potential are auctioned off for a song.
There are sound structural reasons for this: it’s a private market in which few buyers can take part. And on top of that, the sale happens in a timeframe which may not suit every potential buyer. For these reasons, companies in administration often turn out to be spectacular investments.
Unfortunately, it’s difficult for private investors to gain access to these deals. The most convenient substitute we have is to invest in listed companies who are able to pull off these deals intelligently and build business empires on the cheap. I think Portmeirion investors should be very pleased with this bit of business announced today.
Treatt (LON:TET)
- Share price: 560p (-30%)
- Market cap: £340m
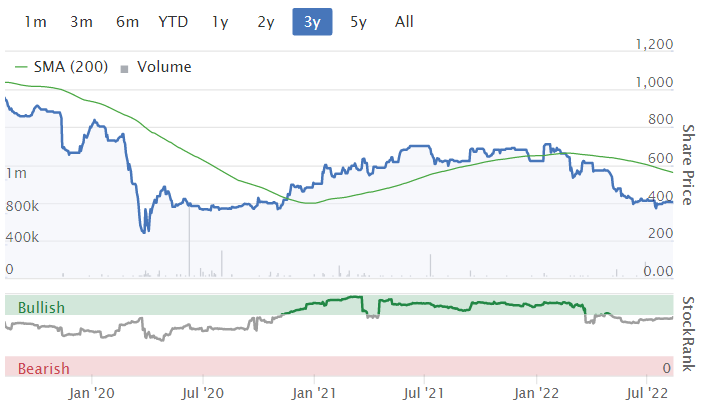
Well done to Jack, who sounded the alarm re: Treatt’s valuation in May (at a share price of 934p).
This is (was?) a very highly-rated extracts and ingredients company.
However, it turns out that Treatt’s ability to withstand macro headwinds is not as robust as expected, and when you have a highly-rated stock, that can cause big swings in the share price.
Stockopedia’s metrics (using last night’s share price) demonstrate how little value was on offer here. The poor value score goes a long way towards explaining why the company’s StockRank was below average:

Let’s get into today’s trading update for FY September 2022. Key points:
- Adjusted PBT will be £15m - £15.3m.
According to a note published by Edison last month, the “normalised PBT” estimate was £24m. So this looks like a very significant shortfall.
As highlighted in an excellent comment below by MichaelFBS, the company said only three months ago that it was on track to deliver expectations for the year.
So what is going on?
- Weak consumer demand in the US has reduced margins in the Tea category.
The US government argues that the country is not in recession, despite two quarters of negative GDP growth. My view is that we have recessionary conditions in many countries, even where a recession has not officially been declared.
- The “rapid devaluation” of the pound against the dollar has had a “significant impact” on margins.
The note from Edison highlighted Treatt’s FX risks. Many of the company’s commodity inputs are denominated in US dollars. As for sales, they are partially in the US but are also spread out internationally to more than 90 countries.
These risks are managed with the help of forward contracts, but hedges are never perfect and always have an expiration date.
Ever since the mess at Accrol group (LON:ACRL) in 2018, I’ve been more keenly aware of how companies can appear strongly profitable when in reality they are benefiting from temporary commodity or FX rates, and are successful for only as long as those rates stay where they are.
Treatt is a far superior business to Accrol: Treatt has been profitable year in and year out for many, many years. Treatt’s gross margin has been within a range of 22%-34%, so that even when rates go against it, it can still generate a positive result. That should be true again this year. But even a good business like this can suffer from FX volatility.
- Inflation - this is hardly news. Treatt is suffering from significant input cost inflation. What may be news is that there are long-term contracts preventing price increases from being passed on to some customers.
- China - lockdowns have resulted in the loss of some higher margin revenues.
Any positives? The order book is still up by 25% year-on-year.
In addition: revenue growth is still “strong”, all categories are growing except Tea, the new manufacturing site is still promising to deliver the expected efficiencies, and the company is exploring ways to limit FX volatility.
My view
There has been a lot to digest in this update. My first instinct is to say that if so many things can go wrong in just three months, it raises questions about the quality of the business. The best businesses don’t suddenly suffer from lots of issues beyond their control.
On the other hand, we shouldn’t forget that Treatt has an excellent long-term record and a profit warning like this is historically rare.

Furthermore, these really are unusual times and many other companies have struggled in an environment where China is imposing lockdowns, inflation is at a multi-decade high, currencies are moving in strange and unusual ways, and there is negative economic growth in the US for six months (even if this is not officially a “recession”).
Overall, therefore, I’m going to retain my positive view on Treatt and would argue that this is just a blip in the long-term story of the company.
Whether it’s worth buying at this moment in time is another question.
As noted by readers in the comments, the de-rating today has not necessarily resulted in any compression of the current-year earnings multiple: the earnings forecast for the year is down by 35% and the share price is down by less than that.
My personal view is that the problems disclosed today are temporary in nature and will be resolved over time: long-term contracts will expire allowing price increases to be passed on to more customers, lockdowns in China won’t last forever, and the US will get out of its economic slump. I don’t see any evidence of Treatt’s competitive position having deteriorated.
So if you liked Treatt before (like me), I don’t think today’s profit warning makes a huge difference. Profits are temporarily lower, and so is the share price. Over time, both should make a recovery - but the timing is anyone’s guess.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Please keep doing the podcasts Paul. I really enjoy them.
Interim results for MTI Wireless Edge (LON:MWE) seem good to me but I missed the Investor Meet Company presentation. Announcement from Tekcapital (LON:TEK) re Lucyd holding looks even better and surprised price hasn't increased further. I hold both and would welcome comments from anyone cleverer than what I am.
Just in case you don't know, you can listen to IMC presentations after the event. Find the company on your My Companies tab and click it to see what's available. Normally takes about 24hrs, and they have a very helpful questions tab, which condenses the Q&A, and has the Directors' answers captured there for eternity....
And they're usually up on YouTube a day or two after that.
Thank you Paul for your comprehensive reply to my post earlier today and in particular to your points on £BOO. One of the main reasons behind my decision to invest in £BOO last year related to the major brands they were acquiring to which I attributed considerable value. It is reassuring to read that you also see great potential from the brands some of which are very well known. I also appreciate your info that "serial returners" are having their accounts closed. This makes complete sense to me. I am going to give serious thought to adding to my position. Next up though is to listen to your latest Podcast.
One of my concerns about Boohoo (LON:BOO) strategy with regard their brands is best illustrated by the Debenhams website.
Click on dresses and you find ones from Karen Millen, Wallis, Coast, Principles, Dorothy Perkins next to Boohoo and Nastygirl. I'd bow to someone more qualified about brand marketing (Zipmanpeter?) but it seems to me incongruous to have Boo and Nasty girl next to more higher perceived quality brands like Karen Millen. In addition, I don't understand why their Debenhams retail offer has Nasty girl/Boo/PLT there at all. - surely a very different market?
And that to me suggests they have no idea how to market more up-market product brands and are in danger of undermining the Debenhams retail brand.
Cheers
Francis
Francis, Thanks for call out on Boohoo (LON:BOO) and its website putting Karen Millen next to BooHoo ! For what its worth, I would say:
For me (I hold), the jury is still out on whether the boatload of brands they bought a couple of years ago will pay out long term. Debenhams was the big bet but is there a market for an online Dept store? (I hoped they would do really well from getting into beauty products as Denhams was strong there but it’s a risk as the beauty area is notoriously not a pile it high, sell it cheap business.
Furthermore, their overall business has been hit, there is clearly a big transition cost in Mgt time in bedding acquired brands that are then moved in terms of price position in the market and crucially we don’t see profit breakouts by brand.
My guess is similar to Paul’s in that I think the bad news on Boo has either been overstated (ESG governance) or is in the past/being fixed (no/high airfreight to the US, 1 warehouse) or has had capital applied that has not yet had time to pay back (prepping warehouses for bigger volumes, pre-commitments on a US warehouse and I hope buying distressed brands from administration etc).
Net, net, on a 2 year basis, I am quite optimistic. In the short run, fast fashion might be an obvious area to retrench if cash is tight – although the wider range of price points gives them options. Maybe people will trade down? Maybe they stop buying altogether. Maybe Shein will drive on or come unstuck. There seems low risk of going bust so I wait.
So in summary, what do I know, DYOR and place your own bets - my overall portfolio is down this year and maybe I am fighting yesterday's war on Boo (I bought at 23 and sold at 125p several years ago before a period out, buying back in and now being well underwater on my re-purchase.
Humility and patience need to be our watch words currently! At least I am worried by share prices not heating.
If you use Hargreaves Lansdown be aware that their share alerts are not working. They know about it. Appalling that they have not told clients - well not me at least.
Wow, $4m extra revenues in FY Dec24, to add to what presumably is c$20m forecasted before the announcement, over at Spectra Systems (LON:SPSY)
A pity that they've chosen to reinvest it all into sales and marketing for their new polymer substrate! However, it shows the strength of Spectra that new product development can be completely funded from existing profits and cash flows.
My view is that the valuation is so low, as though it is an ex-growth company with declining revenues and profits. Yet they are still paying out decent yearly dividends, AND developing new products and entering new markets (polymer substrate, TruBrand, K-Cups business, lottery growth, etc) that if one of them takes off in a big way, this share could really re-rate to a 20-30x PE from its existing 13.3x FY22 forecast earnings.
The big risk, of course, is the big central bank customer that dominates revenues. However, today's announcement, and previous ones this year, seems to suggest they are very happy with Spectra; having increased their investments over the next few years.
I continue to hold, for a tasty 7%+ dividend yield, and the free option of one of its growth areas delivering.
(I hold in the Boon Fund)
Morning Boon.
I also hold £SPSY The share price performance has been grim for the last 6 months or more, but the same can be said of many good UK listed small caps. I suspect the fact that it is a US domiciled company listed on AIM doesn't help, similar to Somero Enterprises (LON:SOM) which I also hold. Also there are a lot of moving parts, which I suspect is likely to put off some investors.
But there is much to like Spectra Systems (LON:SPSY) has net cash, is buying back its own shares and the CEO continues to hold a 5% stake or thereabouts plus off course the generous dividend. There is also the added potential of Solaris, in which from memory Spectra Systems (LON:SPSY) holds 49% or thereabouts.
Fingers crossed, Spectra Systems (LON:SPSY) share price enjoys a renaissance.
All the best
Spectra Systems (LON:SPSY) (I hold)
Hi Boon,
My understanding is that today's contract amendment takes the testing revenue up to $14.8m (from $10.8m after the 15/06/22 update, and from $8.8m announced in the FY results.)
This is on top of the $50m of hardware sales and 10 year $8m servicing contract, which both commence in FY24.
I'm not quite sure when the testing revenue will be recognised in the accounts. Today's announcement implies that it will all be in FY24, even though a large chunk of this cash (or possibly all of it?) has already been received.
In any case there's still a lot to like and I remain a happy holder.
A
I also hold Spectra Systems (LON:SPSY) and have done for long enough to still be well in profit (which tends to dull the proper sense of alarm that you should feel as prices fall). The problem is that this is a curious oddball of a company in many ways:-
As you note, it is dominated by a very few large customers, each in a different field of its business. 2021 showed 73% in 3 customers, 2020 was 60% in 2 customers
It has a rule that an AGM quorum for a resolution requires that 50% of all shares are voted - but they never are, so no AGM ever has a quorum. No votes appear to be registered from the 10.18% held by Close asset Management, nor the 6.47% holding of Herald or the 4.97% of Canaccord Genuity. The AGMs are in Rhode Island !
The CEO is the only Executive member of the small Board. The Auditor is Miller Wachman LLP who have between 25 and 50 employees and do not even maintain a website (a "404" comes up at the moment).
In the SPSY website there is an Investor Relations section which, excitingly, is headed "Reports and Presentations" but....there are no presentations!
It seems therefore that the chances of a smaller private shareholder getting real insight into what is going on in this company is very small, as a $16million annual revenue covers such a range of businesses that the opportunities and risks seem to be beyond calculation without some inside guidance. Can I defend to my wife (key audience!) why I am OK being invested here? Probably not.
'there are no presentations!'
A year or two ago, the CEO gave a compelling presentation at a Mello evening. He came across as an academic at least as interested in the technology behind the products that he sells as in the financial performance of the company. I was encouraged to invest, and even though I am currently mildly underwater I am happy to receive the dividends and have no thoughts of selling.
Was surprised that Gusbourne (LON:GUS) didn't put out a proper outlook for the upcoming harvest (Aug-Oct). Would have been good to know their view. FWIW there has been numerous interviews in the press, as well as from direct competitor Chapel Down (OFEX:CDGP) , that this year's weather has been good for the grapes. Not perfect, so no bonanza yields, but a solid quantity and quality is in the bag, which is much better than last year's disappointing harvest. Bodes well for good sales and revenue growth next year of still wines, which is quite dependent on the harvest volumes from the previous summer/autumn.
(I hold Chapel Down in the Boon Fund).
Hello Graham, thank you for picking up on the Portmeirion (LON:PMP) (I hold) acquisition so promptly. I agree.
Digging a little deeper. The acquisition is for the brand, IP, stock, trade and assets of Aromaworks. Portmeirion paid £0.44m for £4.1m of revenue and £0.3m of pre-tax profits (FY2021 unaudited). Which looks like a very cheap deal?
It begs the question why was the company in administration? Looking at the available accounts filed at companies house it seems that aromaworks was indebted going into the pandemic - and was using invoice financing. Never a good sign? Perhaps no bank would touch them? A strong possibility is that they overstretched in setting up the US listing, the invoice financing company pulled the plug on them - and Portmeirion pick up the hard work Aromaworks have already done. Portmeirion have a US brand in Nambe and a much more extensive US base than aromaworks to carry the brand forwards. In which case it looksl be a valuable brand and assets with a considerable future - untangled from its poor finance and perhaps previous management?
There is also a second angle to this. Portmeirion's prestige brands, Spode, Royal Worcester and Portmeirion itself as well as the Nambe acquisition in the US have been growing well. The CEO has previously said that they were not hunting for futher acquisitions because of the scope within the existing brands - though if one came along that they could not refuse then they'd look at it.
Wax Lyrical has been my only concern. Very much a UK centric business - a lot of investment has been pumped into the manufacturing and testing capabilities and they reacted swiftly to the pandemic by manufacturing hand-sanitiser for the NHS and established a new production line. But so did a lot of other companies. Profitable growth coming out of lockdown looks to be hard work for Wax Lyrical. Aromaworks with US listings and premium UK listings is highly synergistic with the reorganised UK and US sales teams of Portmeirion and could well be a catalyst for Wax Lyrical as well as boost to manufacturing margins.
I rate the current management team at Portmeirion very highly. I think that they have the ability to take Portmerion places. My one criticism was that the placing during 2020 lockdown might have been an unnecessary dilution - but with the benefit of 20/20 hindsight - under the current circumstances its now looking to have been a very good judgement call and puts Portmeirion in a prime position to add valuable assets if and when they arise whilst other potential buyers are short of cash.
I'll look to add at current levels, if and when I have cash available,
cheers
Mark
Hi illiswillgig,
Re Portmeirion (LON:PMP)
I did the same thing as you, looking up the accounts for AromaWorks at Companies House. As you say, its insolvent balance sheet must have pulled it down into administration, so I imagine a major creditor decided to pull the rug out from under them. I couldn't see anything on the Cos Hse page that indicated it was in administration, which is odd.
Pity, as it looks a nice brand, and a bit of googling shows the products are stocked in lots of big retailers.
Clearly a very nice deal for PMP, picking up the assets with presumably none of the debt or other liabilities.
I also think the mgt at PMP are strong. I'd like to buy back in, at some point.
Regards, Paul.
Looks like debtors included over £800k from a related entity. No sign at Companies House that it's in administration either.
Portmeirion (LON:PMP)
Mark, thanks so much for the detailed comment and insights into the situation here. Some exciting synergies and cross-selling opportunities bought for almost nothing - lovely news.
Best regards
Graham
£JOUL
When I see a CV like the new CEO’s that shows job-hopping I wonder whether they ever hang around long enough to ever be accountable.
Paul I listened to your Weekend Podcast of the 6th August and was astonished by your honesty about your losses since last October. Quite mind blowing but it helped me so much to put things into context as I, like so many Private Investors, am down 25% since last November.My biggest losers are Boohoo (LON:BOO),Hostmore (LON:MORE),Ferrexpo (LON:FXPO), Polymetal International (LON:POLY) and £SAGA. One thing you said was about not chasing losses. In the next comment however you said you had twice added to your holding in £BOO. This sounded like averaging down and left me perplexed. Would you mind clarifying please. I am looking forward to listening to your latest Weekend Podcast today which I highly recommend to other subscribers.
Thanks portugull.
I don't like the phrase "averaging down" because it implies a sort of mindless approach, buying more purely in the hope of recouping losses. What I tend to do is reappraise every share as if I didn't already own it. Would I buy now, for positive fundamentals, if I didn't already own some?
With BOO, my decision recently to increase my position size was purely forward-looking, and had no basis on what happened in the past. I reckon that BOO (and other eCommerce companies) are now lapping the last of the strong prior year comparatives from the pandemic boost. So comparables from this point onwards are likely to be against soft comps. So my idea is that they could start demonstrating structural growth returning, and that could trigger a re-rating of the whole eCommerce sector.
Next (LON:NXT) confirmed this in its recent update, saying that it sees online returning to more normal structural growth. Whereas the stock market seems to have priced ecommerce companies as if they were ex-growth, which I think could turn out to be wrong. Hence the scope for a re-rating.
With BOO, I suspect the family might want to take it private again, given the bombed out share price, and the scrutiny & hassle of being a listed company. Possible upside there.
Another positive point, is that BOO relies heavily on air freight. Googling this, the rates are coming down significantly, as aviation becomes more normal. All those planes flying again with passengers, have holds to fill with freight. Hence supply is rising, and rates are coming down. So last year's headwind on freight could become an increasing tailwind for BOO, which services everything out of the UK.
The longstanding issue of high returns rate is also now being tackled by eCommerce fashion companies, with an admin fee for returns of say £2-3 now becoming the norm. With a returns rate typical for the sector of 40-50%, this could be material to profitability. Some eCommerce companies are also closing the accounts of serial returners, who over-order, then return most of it. That business is not worth having, so I hope BOO does the same, which should result in smaller revenues, but more profit.
Then we have the new brands. BOO took on lots of new brands, and has been busily working on extending the ranges, and growing them. I think the new brands have a lot of potential, and are not subject to competitive worries from Chinese competitor Shein, which must have damaged to core brands Boohoo and PrettyLittleThing, as they're chasing the same customers. Although a 2-week delay for delivery is Shein's achilles heel for young customers who want next day delivery, so BOO still has a big competitive advantage there, and it's never been the cheapest anyway.
I could be wrong, but putting all that together is why I think the time could be right for BOO to bounce strongly at some point this autumn.
Regards, Paul.
Agreed, "averaging down" is more akin to doubling up at the race track each time the favourite you backed doesn't win. Very different to buying more shares in a company when it's become more of a bargain price. (Of course both can end up becoming costly if things don't turn out as expected.)
Hideous TU from Treatt (LON:TET) (I do not hold but use to. It will be a horrid day for John Lee.) this morning:
“Although the Group is still expecting to report strong revenue growth for the full year and retains an excellent order book, it has been affected by a number of separate factors which will impact profitability for the full year. We now expect profit before tax and exceptional items to be between £15.0m and £15.3m.”
And it also covered inflation pressures, margins being squeezed, foreign currency headwinds and Covid issues in China.
Only three months ago the H1 TU management wrote:
“On track to deliver full year expectations - reversion to H2 seasonality”
“As anticipated, returning to traditional H2 profit weighting“
“Revenue growth for full year now expected to exceed 15%; on track to deliver full year PBT market consensus of £21.7.”
I feel I have seen quite a lot of this from companies or was the second quote in May a clue (to use Paul’s words) “the dreaded H2 weighting”. Are management being wholly honest in TU’s/RNS or is there quite a lot of hope over reality creeping into them? Obviously they cannot say “with the macro economic picture we haven’t got a … clue” but perhaps more candour and less precision would give a better picture to the market.
I tweeted on Thursday or Friday that I thought Treatt (LON:TET) was looking quite tempting, and in theory it is now looking even more tempting but I would say buyers have no real visibility where the company will be at YE especially if the US weakens further and inflation continues to run riot. I wouldn’t be surprised if the full year was below (even materially below) the £15.0m and £15.3m given in this TU.
Marked down 30% at the open and down 57% from ATH. Still on a PE of 27. Surely 15 to 20 would be more appropriate.
I am not a believer in going to cash in down times but I would rather be in BRK or Coke (or even some large tech) than in AIM at the current time. Unfortunately in the main I am not!
Regards
Michael
HI Michael, ref Treatt (LON:TET) I agree with all of your points - similar to mine posted around the same time. Very tempting, but could be a falling knife.
I think the PE hasn't been updated - I think Stocko do these on the overnight updates the evening after the TU/results. When I did a quick manual calc this morning on £15m profits it came out around a PE of 22. Still not cheap, and with a very small Divi its not paying you to hold-on/wait.
I'll put it on a watch list, which is getting bit full at the moment.
Hi Kevin
I was wondering about PE’s and whether they update in real time but assume that that would put too heavy a load on the servers? Probably need a Bloomberg at £25,000 a year for that. Shame though.
I certainly think that a PE of 22 for £TET is too high when taking in to account the lack of visibility caused, mainly/in part(?) from macro issues to some extent outside of their control.
That said I do think that at some point Treatt (LON:TET) will become a Buffett type stock of a “great company at a reasonable price”. But for now like you I will just continue to watch.
Regards
Michael
Re Treatt (LON:TET) - I've only looked at it briefly, but my main concern is that the sudden switch from in line trading, to a substantial profit miss, due to factors that surely should have been in the budget, or hedged, suggests to me there looks to be a lack of financial controls in place. The CFO needs to be on top of all these issues, and prudently create a budget that reflects risks, and the macro situation, guiding the market towards forecasts that can be consistently beaten. So by dropping a bombshell today, this could cause lasting damage as to the credibility of future forecasts. And as others have said before, TET has never been cheap - a lot of jam tomorrow factored into the price.
On the bullish side, I remember Lord Lee briefing me over the phone about TET, saying that there are only a handful of world-class companies doing what it does, and they all tend to be on high ratings. So with a new factory as well, TET could be attractive to a larger competitor maybe, for a takeover bid maybe?
One disappointment doesn't make something a bad business overnight does it?
Regards, Paul.
Very much agree with you, Paul, on the failure of Treatt’s CFO in this instance. The issues contributing to the profit warning are macro/financial, not operational, and the CFO should have been far more active in a) addressing the challenges and b) communicating with shareholders.
In his defence, it looks like he has only been in place for two months and CFO for one, so perhaps we should direct the majority of our ire towards his predecessor Mr Hope. Hope is not a strategy - if you’ll forgive the pun. And perhaps therefore, Mr Govender will not be so personally tarnished by this warning.
As for M&A potential, I agree again. Treatt must today look like a tasty and easily digested morsel to board members of the big ingredients companies. Particularly if they need to boost their natural flavourings capability.
Pure speculation on my part but I do wonder if the timing of this announcement is not a coincidence given the fairly recent appointment of a new FD. Any good FD would be all over the areas of risk to the business as soon as he/she got in there to make sure something horrible doesn't come out of the woodwork "on their watch". It sounds like he's done his due diligence pretty quickly. The factors referred to in most of the TU seem to be fairly basic risk management and commercial issues, rather than volume related.
The bombshell that the business has long term contracts with customers that appear to have no or only limited inflationary input cost clauses sounds astonishing to me.
£TET
“One disappointment doesn't make something a bad business overnight does it?”
Agreed but it may cause the market to re-rate it permanently downwards, if it thinks that whenever these sort of issues come along, profits will reduce? If the market was assuming profits over five years of say £100m but now thinks that profits are more likely to average £75m then it deserves a much lower PE.
I for one, who has only been investing since 2012 ish, had got carried away with the idea that environment was benign and would be forever so (in the same way that central bankers fooled themselves in to believing they had conquered inflation forever and took their eye off the ball). So I could predict X profits growing at Y percent forever into the future. That was naive of me to say the least.
An example would be Somero Enterprises (LON:SOM), which is, IMO, a great business but persistently trades on a PE the high single digits, when, again IMO, it should trade in the mid-teens.
Further on Treatt (LON:TET), though I no longer hold, I first purchased in October 2014 at 142p so it has still managed to four bag from there. So perhaps in 2030 it will be trading at £22!
Regards
Michael
Could Treatt (LON:TET) be reverting to the mean? To fall-back would be complacent. I don't hold.
I listen and enjoy your podcasts Paul, great for a lazy Sunday afternoon. Thanks for your efforts !
Nasty profit warning from perennially highly rated Treatt (LON:TET) . Even after the recent market sell offs it has somehow retained its nose-bleed valuation. Like many, I've not been able to fathom the reasons for this aside perhaps from the enthusiasm of Lord Lee (I believe I'm correct that he's an investor or it may have been another high profile figure). I can't see this valuation discrepancy surviving long after today's update.
I remember being impressed by the new UK facilities they've built and a presentation by someone on a Mello BASH who highlighted their supposed margin power due to the relatively disproportionate significance of their products to the flavour profile and identity of their customer's brands whilst comprising a relatively small percentage of the cost of those end products. This argument appears to have been blown out of the water judging by today's update with mention of materially reduced margins.
Some of the explanations given include unfortunate Fx exchange contracts which have worked against them as sterling has depreciated (as a holder I'm hoping they'll get underperforming Argentex (LON:AGFX) on the case to solve the problem) but equally seems to be long term customer contracts which they've been unable to renegotiate in the face of soaring input cost inflation - this to me does not speak of pricing power.
The storm of bad news continues with Covid lockdowns negatively impacting their China subsidiary as well as falling consumer confidence in the US causing lower demand for their higher margin Tea category. Considering that we're probably only just at the front end of the full impacts of energy price rises, interest rate rises and potentially looming unemployment and recession, I can only see worse headwinds ahead for £TET.
This really does read like a horror show of a trading update and it will almost certainly take the bloat out of the valuation but if the market over corrects to the downside, there might be a long term opportunity here in my opinion as the new capacity and infrastructure spending should be behind them now and the benefits may be seen in the years to come although I would be interested to know if anybody with better knowledge of this sector understands if Tate & Lyle (LON:TATE) are a direct competitor?
Yes in December Lord Lee wrote about his holding in Treatt (LON:TET) in his FT column:
“Although I trimmed it by 20 per cent some time ago, it still represents approaching 40 per cent of the total value of my Isa. Many would say that is far too many eggs in one basket, but I believe it to be an exceptional business — highly valued, yes, but with outstanding growth opportunities ahead.”
Important to note that this was of his ISA not his entire portfolio but still.
Even the best of us get it wrong and this level of concentration doesn’t seem like a good idea?
Regards
Michael
RE: Treatt (LON:TET)
Even the best of us get it wrong and this level of concentration doesn’t seem like a good idea?
John Lee may well take a different view on "getting it wrong". Having followed him over the years I've seen him add to stocks following a profit warning as long as he was convinced by the business. I remember him increasing his holding of Gooch & Housego (LON:GHH) after such an event and doing incredibly well after a few years. No doubt he'll be talking to the management soon.
A lot depends on your investment timescale. Many longer term investors focus on their process rather than short term outcomes. Personally I agree that this level of concentration isn't advisable, but John Lee is extremely wealthy anyway. I've often found that people who espouse concentration in their share portfolios have other sources of income and wealth.
I have a small (now very small) stake in Treatt, and can't see any rush to add to it. But the demand for flavourings isn't likely to go away and most of the issues do look short-term(ish).
timarr
I have a small (now very small) stake in Treatt, and can't see any rush to add to it. But the demand for flavourings isn't likely to go away and most of the issues do look short-term(ish).
I’m in the same boat. There’s a lot of comment here about the multiple being excessive, observations which do not take into consideration the difference between a business like Treatt and Ultimate Products, which also updated this morning, and which is on a PER discount well in excess of 50%. The latter sells commodified (relatively) non-essential products to a low discretionary income customer base while the former’s ingredients are embedded in the manufacturing process of its FMCG customers’ higher margin offerings. You do not change the recipe of a successful food product without considerable debate. And Treatt’s products are in high demand for their focus on natural flavourings.
As I mentioned below, Treatt is already on a lower multiple than any of its competitors, which reflects its scale and the potential for accidents like today’s TU. While some moderation may be justified, I would not expect the multiple to contract significantly. Those viewing the company through a purely value lens will get their opportunity to buy at a good price - perhaps this is it today, perhaps not. However, barring market meltdown, they won’t execute their entry if they target a low teens PER!
As I mentioned below, Treatt is already on a lower multiple than any of its competitors, which reflects its scale and the potential for accidents like today’s TU. While some moderation may be justified, I would not expect the multiple to contract significantly. Those viewing the company through a purely value lens will get their opportunity to buy at a good price - perhaps this is it today, perhaps not. However, barring market meltdown, they won’t execute their entry if they target a low teens PER!
I'm in the same boat as others that have never understood the valuation of Treatt (LON:TET) and I rarely take much notice of PER. For a supposed quality business it has very low Gross Margin (sub 40%) and nothing to write home about operating margins. If some are surprised by the size of the fall in PBT since the last trading update you need look no further than these metrics. The same thing happened to Fevertree Drinks (LON:FEVR) which has similarly average Gross Margin compared to its valuation. It seems to me in that regard you'd be far better investing in Treatt's customers who clearly got the better end of some of the contracts in managing their own input costs.
I must admit I've never looked in detail at the company's cashflow but the capex has always seemed high to me and operating cashflow does not seem to convert efficiently enough into free cashflow for a quality company on a high rating . In fact the Stockreport shows FCF being negative most years, so maybe there is something wrong with Stockopedia's interpretation of the cashflow statement.
All the best, Si
re Treatt
Your comments are very reasonable but the analysts like to lump companies in the same industry together and value them comparatively in order to make their own job easier. And the market then dumbly follows. Treatt’s gross and operating margins are a little bit worse than obvious comparators Symrise and Givaudan - although in the same ballpark. And its valuation is appropriately diminished - while again in the same ballpark.
As long as you are confident that the valuation regime holds, it’s not really relevant to be deterred by the high multiple. And shares have not re-rated today on an absolute doozy of a profit warning. The problem is the poor performance - not the valuation!
Secondly, the role that names in the ingredients sector play in a portfolio is rather different to that played by special situations, recovery or value plays, where you target an entry looking for a margin of safety and exit at a predetermined re-valuation. Their job is to chug along delivering relatively predictable total returns of ~7% over decades. They might be volatile short term, but they are keyed into healthy eating megatrends and deeply ingrained in their customers’ products and processes. It is quite possible that this dip is a long term profitable entry even if another warning follows.
Your comments are very reasonable but the analysts like to lump bcompanies in the same industry together and value them comparatively in order to make their own job easier. And the market then dumbly follows. Treatt’s gross and operating margins are a little bit worse than obvious comparators Symrise and Givaudan - although in the same ballpark. And its valuation is appropriately diminished - while again in the same ballpark.
But no-one has to invest in the food flavouring industry. Comparisons with companies in the same sector does not work for me because it could simply be a case they are all overpriced. I only ever use absolute valuation unless I really have insight into a sector, which I don't outside of semiconductors. Look at the profitability metrics of Treatt (LON:TET) compared to Coca Cola or PepsiCo - even boring old Unilever (LON:ULVR) can eek out a GM > 40% with all its overheads.
Don't get me wrong, it's always looked a decent, well managed company, but valuation matters and I have just never understood why it got rated so highly, or more importantly, why it still is even after the fall today.
All the best, Si
But no-one has to invest in the food flavouring industry. Comparisons with companies in the same sector does not work for me because it could simply be a case they are all overpriced
Then the valuation is not there for your benefit other than to persuade you not to invest! For those interested in potential annuities and undeterred by the price tag, they make more sense!
Then the valuation is not there for your benefit other than to persuade you not to invest! For those interested in potential annuities and undeterred by the price tag, they make more sense!
I’m not sure I understand what you’re saying? I’m absolutely interested in high quality, annuity like investments, just that Treatt (LON:TET) strikes me as a bad example given the substandard margins they enjoy for such a company, and the very high rating (on just about any valuation metric you care to choose). Not exactly Games Workshop (LON:GAW) is it? It’s never struck me as a company with much of a moat for that reason.
Of course, we are probably talking at cross purposes as you seem to be a thematic type investor, and I’m most definitely not.
I’m absolutely interested in high quality, annuity like investments, just that Treatt (LON:TET) strikes me as a bad example given the substandard margins they enjoy for such a company
Are they substandard? Certainly compared to SaaS providers. But not if you compare to its blue chip competitors. At 34% and 17%, the gross and operating margins combined for FY21 are within touching distance of Kerry Group and Givaudan, on a par with Symrise and ahead of International Flavours & Fragrances. But they are all within a certain ballpark. So it’s the sector that’s the issue, not the stock.
And yes, I’m more of a thematic investor than you. Decades in business taught me that, no matter how smart you might be, or how hard you work, the thing that mattered far, far more than anything else was being in the right market. So I bring that learning into my investing.
Are they substandard? Certainly compared to SaaS providers. But not if you compare to its blue chip competitors. At 34% and 17%, the gross and operating margins combined for FY21 are within touching distance of Kerry Group and Givaudan, on a par with Symrise and ahead of International Flavours & Fragrances. But they are all within a certain ballpark. So it’s the sector that’s the issue, not the stock.
IMO, yes the Gross Margin is really substandard for a highly rated, highly quality annuity like compounder. Both PepsiCo and Coke have GM's in the mid 50% range, A G Barr (LON:BAG) mid 40% range, Diageo (LON:DGE) over 60%. A 35% GM is little more than glorified distributors like Gear4music Holdings (LON:G4M) and in the Food & Beverage sector is more inline with boring old Tate & Lyle (LON:TATE) (a possible acquirer?).
I agree it is likely the nature of the sector, but as I mentioned before, no-one has to be invested in a sector with average margins and competition that acts to put a cap on them.
All the best, Si
Perhaps badly phrased and as you say concentration has to be taken context, and we have no idea what percentage of his wealth is tied up in is ISA. But for me Treatt (LON:TET) is not the sort of no brainier company (it is too vulnerable, as the TU demonstrates, to outside factors beyond its control) on which you would make a huge concentrated bet. But what do I know!
Regards
Michael
"long term customer contracts which they've been unable to renegotiate in the face of soaring input cost inflation - this to me does not speak of pricing power"
Not sure I would agree with this part - a more usual gauge of pricing power would be whether on renewal / extension of the contract £TET are able to pass on their input cost rises via increased prices. Trying to add in cost increases mid-contract when they have no right to do so contractually (unless they have negotiated ongoing cost escalation clauses from day one, which would be highly unusual / unlikely in this sector) would be exceptional rather than expected and isn't a very fair test of pricing power. Such action would require something closer to a monopoly in the market - i.e. to be achieved by threats in advance of non-renewal/extension and done in the context of their being few or no other suppliers the customer could turn to at the end of the current long term deal - i.e. . pure leverage of the relationship to change the already agreed and locked in contract terms mid-term. This sort of behaviour, even if successful, can sour commercial relationships very quickly.
I think the bigger issue raised here by todays' update is their strategy of utilising such long term contracts for such a significant proportion of sales and not having seen the inflationary risks coming in doing so. It's a difficult one, as locking in long term deals can provide fantastic stability downside protection for a business if done right so one would not want to see such deals abandoned altogether. Would be interesting to know how long ago some of these deals were signed and how long the problematic contracts still have to run (if they have a long tenor still to run down this could be disastrous for future years).
The real proof of the pudding for Treatt will come when the contracts are renewed and how much of a price uplift they can achieve at that time.
I do not hold but am watching developments with interest as at some point there will be a good entry point for what is ultimately a sound business.
BIACS
Hi BIACS - good points well made and I don't completely disagree. Really I was speculating that their big corporate customers maybe insisted on long term contracts (foreseeing future inflation) and Treatt either did not have the negotiating heft (and by extension the pricing power) or management insight to push back with inflationary break clauses etc.
Put another way, they either have pricing power and haven't wielded it very effectively or they simply don't have it against the might of their giant customers.
Paul
Did your mystery shopping (aka ‘razzle’ reveal what sort of customers are resisting the inflations crisis?
I find your podcasts interesting and useful. Thanks for your remarkable hard work analysing small cap companies.
FREng
I listen to the podcasts too Paul - really find them useful
Treatt (LON:TET) reporting full year profits likely to be 30% below expectations.
My experience of having followed European competitors Symrise & Givaudan for a number of years is that this industry is serving a number of large buyers (Nestle, Unilever, Danone etc) which can beat down margins at will, leading to unpredictable profit growth for the likes of £TET.
Not a stock for widows & orphans.
Treatt (LON:TET) never been able to understand the high PE on this one. Can see big SP falls to come.
£TET never been able to understand the high PE on this one.
High PE reflects high PEs right across the flavourings sector - these being highly defensive essential ingredients in consumer staple products. Defensive until you bet on a strong pound, anyway!
For comparison, look at Givaudan, Symrise, Chr. Hansen. Treatt is competitively valued. And a lot cheaper this morning but still on the same PE. Valuation reset is all about the profit warning and not a re- rating as far as I can tell.
I had always admired Treatt (LON:TET) from afar over the last couple of years and watched as its SP had risen and the good news continued too flow with a new factory, solid growth, growing profits etc.
But, I had always struggled with the PE and never got brave enough to pull the trigger.
So on this mornings news I immediately started to look at it again, and even got to the point of getting a quote from my broker - BUT........ the issues it has warned on this morning are potentially not a one-off and this could be a good indicator in the direction of things to come, not just for Treatt (LON:TET) but also for many other companies - the slow-down in the US is a worrying sign.
To this end I haven't pulled the trigger as the PE remains high and I fear things may get worse before they get better. I'll continue to watch from the sidelines and hope I can get in later on in a few months time.
Whatever the outcome it seems that anyone currently issuing a profit-warning seems to be getting hit with an immediate 33-50% decline in their share-price. The markets are not holding back.
Isn't part of the problem that companies like Treatt (LON:TET) (and MPAC (LON:MPAC) is another one) have contracts with much bigger businesses where the margin is comparatively thin and the prices agreed for the long term. If they get short term price rises, they have to swallow them until the contract runs out, and then hope they can negotiate a higher rate for the next period. I suppose the silver lining is if the price rises are genuinely short lived, and abate, they could get bigger margins when that happens. But its all a type of risk we've got used to ignoring during periods of minimal inflation.
Keep the podcasts coming, I read listen to them Mon/Tues as I cycle into work.
And I listen to them whilst on the rowing machine in the gym !! Time passes quickly and helps reduce the pain of 30 minutes at level 10 on a Concept2 machine:)
Mine goes up to level 11 ;-)
UP Global Sourcing Holdings (LON:UPGS) report a "record financial performance".
This share price has been totally hammered despite as far as I am aware not issuing any profit warning, expanding into Germany and an ex Jim Slater screen, so you assume management are very competent.
Is this a multi bagger in waiting or a consumer based company to avoid, what do the experts say?
I'm not an expert, but I say they've got too much debt and not enough cash flow to pay it off. Hence the fall in sp...
Morning truegent,
Graham's taking a look at UP Global Sourcing Holdings (LON:UPGS) now, but I've had a quick look too, and can't see any issue with excessive debt.
It says today the ratio of net debt: EBITDA is 1.3x, which is generally considered reasonable. Trading is in line, so that's OK. The last balance sheet only had NTAV of about £1m, so not the best balance sheet. Cash generation was poor in H1, due to a big increase in working capital, but that might reflect the acquisition of Salter maybe? In the past its cash generation has been fine, and it's a fairly capital-light business model - e.g. fixed assets only £5.7m.
Generous divis (current yield 5.7%) doesn't suggest any problems with cash generation either.
I'm surprised UPGS is trading in line, as I would have imagined small electrical appliances would be seeing a dip now, as other electricals are down c.20% market-wide. But it seems that well-managed companies like this and MRK are bucking that trend. Maybe small electrical items are not discretionary? After all, if your kettle breaks, you just buy another one, and they're so cheap, it's not going to be something that needs to be deferred, or saved up for.
If trading was plummeting, then I'd be worried about the £24m net debt, but trading is holding up well, so I can't see any problem with debt.
Regards, Paul.
morning Paul - you're right, its not *excessive* debt that I thought was the the problem, but the fact that in the last report they did not make any cashflow in fact they burned nearly £10m including dividends, and had to take on more debt to cover this, over £12m. But I agree its not excessive. Maybe in the next report they will catch up and pay some of it back. But for me it was a red flag. And I think for others too hence the sell off shortly after the last report (which was the interims in April).
Hi truegent,
Interesting, thanks.
This cashflow issue is cropping up at lots of companies at present, which we've touched on here before. Higher inflation means that when inventories have to be re-stocked, they cost more per unit. Then selling prices have to be raised, so the receivables balances also go up. That's 2 debit entries on the balance sheet rising, but only one credit entry rises correspondingly - trade creditors.
Put that together, and it means cash is being sucked into working capital, resulting in lower cash, and/or increased bank debt.
However, this cash is not being "burned" as you say. It's just being diverted into increased working capital due to higher inflation. That's very different to a loss-making business which is burning cash through day-to-day trading losses.
Also UPGS made an acquisition, which would have included the target company's balance sheet in with the rest of the group for the first time. That can skew the cashflow statement sometimes because all the balance sheet items are included in full, but only part year's trading goes into the P&L.
For these reasons, I don't see UPGS as being of concern, just because one half year saw cash sucked into greater working capital.
Remember also that a lot of companies have increased inventories, in order to solve supply chain problems - e.g. getting product in early, so that they don't run out, if the next shipment from the Far East is delayed.
Although as I flagged with Revolution Beauty (LON:REVB) before the stock provisions issue was revealed, it only took a few simple checks to identify that it was seriously over-stocked, hence profit-destroying provisions were likely. So we need to redouble our focus on balance sheets, and work out the stock turn, and the debtor days in particular. If these are excessive, then trouble could lie ahead.
Regards, Paul.
Interesting and duly noted Paul thanks ;) UPGS are still on my watchlist and I've owned the shares before and also spread bets and will be keeping a keen eye on the next set of prelims...
Worth noting that UP Global Sourcing Holdings (LON:UPGS) has been in the market buying shares on behalf of the Employee Benefit Trust. This is something they have done before.
Essentially it hedges against issuing new shares when options are exercised.
Perhaps not quite in the league of Director purchases, but indicative of some Company view of the market pricing of the shares, as presumably the wouldn't be buying f they thought they were overpriced?
The Share don't get cancelled, as they are treated as still being in issue.
I hold
Re UP Global Sourcing Holdings (LON:UPGS)
"Is this a multi bagger in waiting or a consumer based company to avoid".
The company appears to have £18m of headroom for further acquisitions, but surely to be a multibagger it needs to improve its organic growth rate of 1% - it's hard to see a re-rating otherwise.
Looks like a resilient performance to me.
Revenues pretty much in line, EBITDA in line, improved margins, net debt falling despite paying a dividend...they've done what they said they'd do. Not bad for a retailer of household goods in the current climate.
I'm naturally keen to see the full details and profit GAAP numbers in September. I'd especially like to hear an update on supply chains and how they view the economic and cost of living crisis challenging their key markets in Germany and the UK