Small Cap Value Report (Tue 10 May 2022) - SUP, NWF, TET

Good morning, it's Paul & Jack here with Tuesday's SCVR.
Chaotic market conditions continue. I'd love to have a pearl of wisdom to make everyone happy, but can't really think of anything. We're not traders here, but are focused on the company fundamentals being reported. It strikes me (Paul) that the current panic sell-off seems overdone, and I'm just ignoring it because my shares are long-term investments. My SIPP is now down 28% year-to-date, and down 37% from the all-time high, but I'm very happy with all the positions, so it should come back up again in time, as has always happened in the past.
We've got a nice community here, so please do continue sharing your thoughts. I read them all, but wasn't really in the right frame of mind last night to reply, when I got back from my local.
Agenda -
Paul's Section:
Supreme (LON:SUP) - a reassuring update, saying that it supplied only a negligible amount of products to McColl's, and it was supplied via Morrisons. Therefore SUP has no bad debt exposure to McColl's. There's also a brief trading update saying SUP is "trading well".
Nwf (LON:NWF) - yet another upgrade to forecasts for FY 5/2022. That's at least 3 upgrades, just in the last 3 months! Although before we get too excited, NWF does say that conditions for its oil supply busiess are "exceptional", hence unsustainable. This looks a solid company, and its shares mainly appeal for a reliable divi yield & inflation protection.
Jack's section:
Treatt (LON:TET) - revenue up 9% despite a one-off first half last year, and forecast to be up by more than 15% for the full year, although profits are down after accounting for a net gain on property disposal. The group’s new UK facility is an important factor in the valuation as it could drive significant growth, but high valuation multiples are at risk of a derating in the current environment so I’m wary in the short term.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Supreme (LON:SUP)
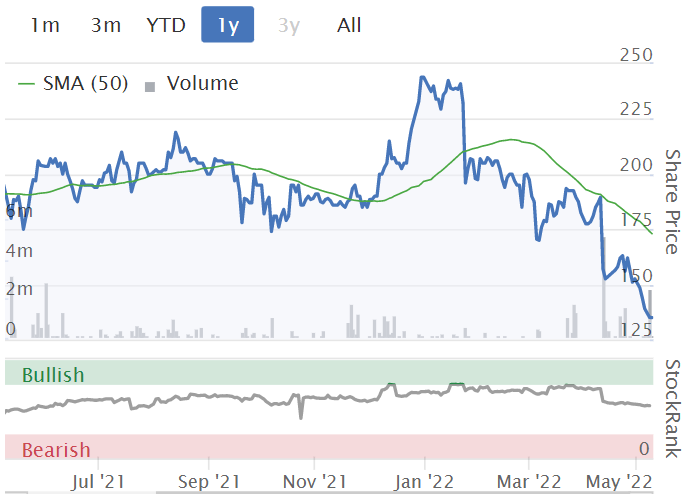
135p (pre market open)
Market cap £157m
Good news for SUP shareholders, as the company seems to have dodged a bullet re McColl’s being placed into administration yesterday (thus wiping out MCLS shareholders, as expected).
Breaking down SUP’s announcement into parts -
Supreme (AIM:SUP), a leading manufacturer, supplier, and brand owner of fast-moving consumer products, notes confirmation of the sale of McColl's Retail Group plc ("McColl's") to Alliance Property Holdings, part of the Morrisons Group ("Morrisons").
No bad debt exposure to SUP, it seems (not clear if this was by design, or an accident! -
The Company wishes to clarify that it has always served the McColl's store estate via a distribution agreement with Morrisons (meaning Supreme delivers and invoices to Morrisons directly).
Sales via MCLS were negligible for SUP anyway -
The Company estimates that the McColl's estate contributed approximately £350k in revenue to the Group (less than 0.5%) for the year ended 31 March 2022.
Trading update for SUP of sorts. I think we have to assume that it’s trading in line with expectations, why didn't they just say so?! -
The Company continues to trade well and looks forward to updating the market further at the announcement of its year end results in July.
My opinion - a reassuring update from SUP. It sells small ticket, repeat purchase type products, so I imagine should be fairly resilient in a higher inflation environment.
I remain of the view that this share looks good value, and seems to have a decent business model & entrepreneurial management.
The forward PER is now only 10.0, with a forecast dividend yield over 5.0%. Therefore the current share price plunge looks irrational to me, and down to market conditions rather than company fundamentals.
More generally, it’s still not entirely clear how the sale of McColl’s to Morrisons is going to impact trade creditors. Press reports so far have concentrated on the position re bank debt & pension scheme, but remember companies often have as much, or even more, trade credit outstanding - because suppliers typically give 30-60 days credit on the goods they send in to retailers. When McColl's last published its balance sheet, trade creditors was a frightening £187m, so this looks very nasty for the suppliers concerned, if they didn't have credit insurance.
I see from an announcement last night, that MCLS has confirmed administrators from Price Waterhouse Coopers (my old firm, 30 years ago!) have been appointed. I did hear suggestions that it might only be the plc holding company that goes into administration, but it seems to have been some subsidiaries too.
The directors of the Company and of each of Martin McColl Limited, Clark Retail Limited, Dillons Stores Limited, Smile Stores Limited, Charnwait Management Limited and Martin Retail Group Limited have appointed Mark James Tobias Banfield, Robert Nicholas Lewis and Rachael Maria Wilkinson of PwC as Administrators of the Company and of the named subsidiaries.
This makes me speculate that MCLS trade creditors are probably likely to suffer bad debts. Normally trade creditors rank as unsecured creditors in insolvencies, which usually (but not necessarily) results in them getting nothing - because they rank behind secured creditors (banks usually), and preferential creditors. Shareholders are at the bottom of the pile, so they get nothing.
If that’s correct, then there are likely to be lots of other companies reporting bad debts to McColl’s, if they supplied it directly (i.e. not via Morrisons, which will obviously be honouring its trade creditors). Supreme is in the clear though, with no exposure.
.
.
Nwf (LON:NWF)
213p (up 7% at 08:39)
Market cap £105m
NWF Group plc ('NWF' or 'the Group'), the specialist distributor of fuel, food and feed across the UK, today announces a further trading update for the current year ending 31 May 2022.
We last looked at NWF here at the end of March 2022, with a positive trading update. This agricultural group is benefiting from the higher oil price & shortages.
Today we get another hike to forecasts -
Further to the trading update of 31 March 2022, the Group continued to experience exceptional trading conditions in the Fuels business, with very significant short-term volatility in oil prices and a supply constrained UK fuel market.
As a result, performance during the final quarter of the year, to date, has been materially stronger than anticipated with the full year result now likely to be significantly ahead of the Board's previously upgraded expectations.
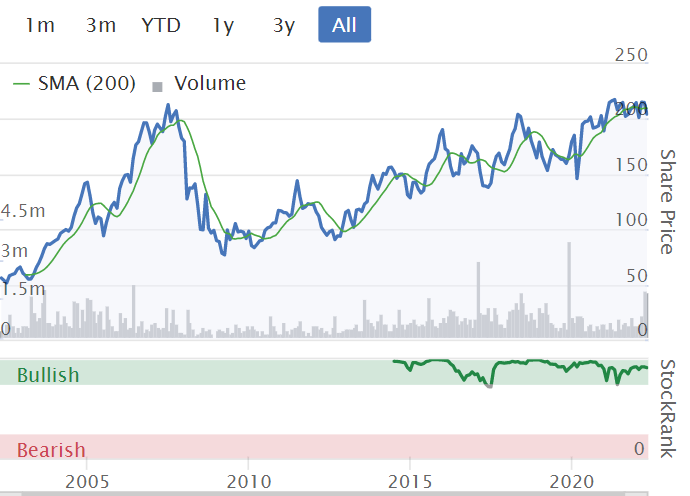
As I whinged about last time, there is no broker research available. However, the StockReport here is picking up some consensus data. As you can see below, forecast EPS for FY 5/2022 has risen a lot, and this is before today’s further “significantly ahead” announcement. At a guess, we might be looking at say 35-40p EPS for this year, a PER in the range of 5-6, so very cheap.

However, as the company has said before, and repeats today, these are exceptionally (i.e. unsustainably) good conditions for NWF’s profit margins, hence it would be foolish to value any company on a normal multiple of earnings that are seeing a one-off boost for any reason.
Once earnings return to normal, then (as you can see above) a more normal level of EPS is expected to be c.18p - giving a PER of almost 12. That’s still OK value.
My opinion - this share has some appeal, mainly for its reliable & gently rising divis, not so much for capital gains (unless you got lucky and bought at the right price).
I can’t get excited about the repeated out-perform announcements this year, as these are one-offs in exceptional conditions. That said, it’s a nice problem to have - excess profits pouring in! This share is probably best thought of as an income generating investment, that should also have inflation protection built-in, and suitable as a very long-term, hold forever type of share.
.
.
Jack's section
Treatt (LON:TET)
Share price: 933.92p (-6.98%)
Shares in issue: 59,898,032
Market cap: £559.4m
Interim results to 31 March 2022
Treatt is a manufacturer and supplier of natural extracts and ingredients for the beverage, flavour, and fragrance industries. It’s a nice, high margin niche which requires specialist knowledge and technology.

But the issue for me is one of valuation - the shares rerated to all-time highs in 2021 and have been rangebound ever since, currently trading at around 33x forecast rolling earnings.

- Revenue +9% to £66.3m,
- Gross profit margin down from 35% to 27.5%
- Operating profit before exceptionals -37.8% to £6.6m,
- Profit before tax and exceptionals -39.4% to £6.3m,
- Adjusted basic EPS -36.5% to 8.21p,
- Dividend +20% to 2.5p.
Profit figures strip out the £3.3m net gain on disposal of Treatt’s old UK premises.
The group says that H1 2021 benefitted from COVID-19 related retail channel growth and significant product launches, and that these results return to a more normal H2 weighting. This has been flagged previously, and the weighting does come across in the interim EPS chart below but, given the valuation, it’s worth noting that H1 EPS was 8.3p in 2018, 8.2p in 2019, and 8.1p in 2020.

Edison’s last note has 32.2p of full year EPS penciled in. That would require Treatt’s strongest ever H2, but the group assures investors that it is on track to meet full year PBT expectations.
The group adds that the first half finished strongly, with momentum so far continuing and an order book up by more than 25%. Revenue growth for the full year is expected to exceed 15%.
Regarding the fall in gross margins, Treatt notes:
Gross profit margins were lower in the Period (27.5% vs 35.0% in H1 2021), reflecting the COVID-19 impact on our H1/H2 weighting last year, as noted above. Alongside the growth in serving our customers' retail channels, H1 2021 also saw some very significant new product launches which further skewed the comparable prior year period's performance. As a comparison H1 2020 margins, which were more reflective of our usual weightings, were 26.2%.
Operating costs increased by 8.9% to £11.7m, almost all relating to higher payroll costs after increasing headcount by 15% as Treatt prepares to capitalise on its new state-of-the-art UK facility.
Workers are currently being moved over, and the group comments:
The final transition to the new site, involving our most complex manufacturing processes, is on course to be completed by the middle of 2023. We now expect that the final costs incurred in relation to the UK site investment and relocation will be approximately £46m-£47m, being 5-6% higher than previously advised as a result of inflationary cost pressures and some higher than originally expected commissioning expenses. Three years post completion, we expect to be generating a 10-15% return on investment ('ROI') from this site. We believe the UK facility, along with our recently expanded US facility, will provide Treatt with the platform needed to support its ambitious growth plans.
Balance sheet
A net cash outflow from operations of £6.8m results from a working capital outflow of £15.1m and a strategic increase in inventory. A further £6.7m of capital investment means that Treatt’s net debt balance has grown from £9.1m to £19.8m. The direction of travel there is negative, but it’s not a concerning level of net debt for an enterprise of Treatt’s scale.
The group’s pension liability has declined, from £6.8m to £3.9m due to a higher discount rate.
Conclusion
This is a good, defensive business which should comfortably survive the macro headwinds buffeting the market right now. Branded beverages are seen as affordable luxuries, and so Treatt is well insulated against rising inflationary pressures.
Meanwhile, a strong order book means the group is confident of meeting expectations for the full year.
The question mark for me is valuation, and what kind of expectations are built into the share price. The stock has held up well recently and retains a lofty rating. That may well reflect the longer term growth prospects, new plant potential, and general sense of security around its operations, but I still struggle to see value here when looking at the rest of the market.
There is the new UK facility, which has the potential to drive expansion and enhance profitability. I get the impression that Treatt has a relatively stable and long-termist shareholder base, which is valuable if true and something of a rarity. On a five-year view it could really do quite well, but sentiment drives prices in the shorter term and so I’m personally wary of initiating a position at present.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
Just looking to learn-Where does the forward dividend of 5% on supreme come from?
Here is the Treatt (LON:TET) analyst presentation from yesterday, video & podcast. This is a Lord Lee favourite. As Jack alludes to, long term-holders have been rewarded and by the sounds of things and over time, will continue to be so. Yes, a H2 weighting, when the higher-margin healthier living categories are expected to perform better, hence the higher profitability. Edison have raised their revenue forecasts to reflect the strong momentum but their profit estimates remain broadly unchanged, due to mix considerations and cost inflation.
Severe market reaction to the Treatt TET update today (I hold).
Possibly there may have been some confusion with the negative comparatives, caused by a switch in seasonality back to the norm after Covid. But its not exactly rocket science and I'm sure most shareholders are way more bright than me and will have picked up on the reasons.
Or that the very high rating has led to some disappointment that strong sales growth was not resulting in any profit growth ?
Slightly concerned that headcount has gone up 15% - one might have hoped that the new consolidated site was supposed to increase productivity and automation ?
And on that subject I have a slight gripe that the business keeps repeating how well the site move is going, and yet the only people to have moved are the office based staff, which is very straightforward to manage. The issue is that they say that the manufacturing processes will not have moved for another year yet, and this is where there is significant risk imo. No reason to suspect that the current team ( who have proven themselves to be very capable) wont manage it but its a big project and there are many examples of businesses being badly screwed up getting this sort of thing wrong
And whilst this change takes place, the business will shortly be losing its FD, who has been a long term very steady set of hands . Strange that he is going part way through such a transformational change in the company.
Plus personally I feel there is still an overhang from the outgoing FDs decision to sell over 85% of his shares during the second half of 2021, mostly in December. Totally understand not wanting too many eggs in the his basket - to be expected, but 85%, pretty well in one go ?
It would be interesting to hear others’ thoughts
Hi RutlandRam, Great to read your post. Rightly or wrongly I was much more spoked by the results than you. below are my thoughts.
Treatt (LON:TET) has been a super performer over the past couple of years but I found today's results underwhelming and frustrating. Its high PE is in line with peers but as Jack mentioned it put the TET SP at risk given market conditions. Unfortunately, I think this may have encouraged management to be less forthcoming with what I perceived as bad news.
In short, I sold first thing as I didn’t think the results or outlook merit the high PE. Below are my concerns.
I also agree with some of your concerns around both the timing and cost of the facility build and migration
Excellent points Cuddlesticks , much to think about. Thanks
Paul, just wanted to say that your frankness is both refreshing and reassuring. There may be no quick fixes with the markets as they are, but at least we know we're not alone here!
Surely IDEA is a rare buy, isn't it? There is an offer on the table from Hg at £3.50 and French PE firm Astorg have said that they are going to make an offer which will obviously have to be higher than £3.50.
£MACF the packaging group (I hold) issued an in line trading update at noon today at its AGM which illustrates the decline in on-line shopping:
" We expect weaker sales in the e-commerce retail sector to continue
for the remainder of the year, offset by recovery in the industrial and
hospitality sectors and the benefit of new business wins. Macfarlane will
continue to manage inflationary pressures in input prices and operating costs,
mainly labour, energy and transport."
Richard
Someone asked for a history of bear markets recently. Here is the S&P
I don't like the look of 1974. Even worse, that was the last energy crises.
While I'm positioned for a bear market, I have been surprised by the extent of market declines in recent days. I conceptualise a bear market lasting another 5-12 months from here, with an ultimate low of c.3,000 on the S&P500. Equities seem primed for a short-term rally any day now, however. Sentiment appears so extreme and I don't see many immediate catalysts for further declines. If economic growth is about to flatline as many suggest, it will take many months for profit warnings to be cleared and for an ultimate bottom to be reached.
I have two decent holdings that have not done particularly well so far this year. Volvere (LON:VLE) and £SIGC. I don't intend selling either. They are down 15-20%.
For Volvere (LON:VLE) its possible the food business struggles to pass on the cost inflation. So its quite possible numbers don't match expectations. Longer term though the operating platform of the business isnt much affected by this. Im happy to wait because I trust the Lander brothers. They have loads of cash in Volvere (LON:VLE) and there should be good investment opportunities for this in the current environment. If anything this suits them. Of course others selling has caused a rather decent discount to NAV to open up. They have bought back stock and may do more...which will support NAV... last stated at 1350. So if I were to start fresh this would still be on my list.
Sherborne Investors (guernsey) C (LON:SIGC) is also down ... falling from 60 too 47. However if anything things look better... current NAV is about 70. A decent discount. The have invested in a target co for turnaround - NAVIENT a US listed co. Importantly a vote to appoint E Bramson to the board happens on June 2. This has been recommended by the board and should go through. If it does Navient should be in a position to accelerate restructuring to the benefit of shareholder returns ie profits and growth. Also, Sherborne Investors (guernsey) C (LON:SIGC) still should have £50-70m cash that could be used to buy back stock and improve their own shareholders return. I think they have agreed with Navient not to go over 20%. I would encourage listening to the Navient call if interested....I have a target of 150 over a couple of years ....which should help recover some of those losses elsewhere.
So two stocks neither doing very well at the moment but both I remain very happy with. Neither are caught up in the current cycle but they don't escape the selling pressure. Both would get on my bank piece of paper today. I bought them for this type of market and although on the face of its disappointing they aren't doing better - the important thing is I do not want to sell.
I have to agree I have sat on Volvere and made very little to date but I do have faith in the Lander Bros too. I recently increased my Begbie Traynor holding on the basis more opportunities are going to arise in a higher interest environment so I will probably add to Volvere at some point.
Paul, with regard to the McColls bad debt ,a read over to the RNWS comment a couple of days ago ,might give some insight,as to how bad this could be ,unless the new management agree to settle a part of this ? Tony
I think the only piece of advice that really works when things are against you is to build a portfolio from scratch today. Compare this to your actual portfolio and start to make decisions accordingly. The great advantage private investors generally have is they can make sweeping changes without too much pain.
Institutions move more slowly, existing managers doing poorly will be hoping things pick up. It would cost them another 3-4%, maybe more, to reorganise their portfolio. They probably should but often wait to be sacked. Then the client pays for reorganisation as everything gets sold. Either the pension fund changes manager or the fund group sacks the manager and brings in someone new. ( The new manager often gets 3-6 mths grace to reorganise the portfolio without impacting his compensation - they call it being on risk - the length of time an incoming manager is not on risk indicates how much surgery is needed.) It goes without saying that the more managers no longer on risk - trying to sell similar stocks - produces some pretty crazy stuff. I don't think too much of this has happened yet. It may not but ....its definitely what happened following the 2000 bust which feels similar.
Clearly we have pretty much reached the limits of monetary policy leveraging growth of the existing infrastructure. We need more investment to increase the operating assets of the economy. To make investment more attractive we need higher rates... the real economy should be the beneficiary. Wall Street pays....as asset returns of the last cycle suffer. Bonds suffer and long duration equities suffer. Its not all bad though, actually should address many of the problems of the last cycle, nominal growth will be higher. Overall equities should do ok. I guess what im somewhat clumsily saying is don't be too negative on real companies, and equities generally. Its just not a time for so called blue sky situations. I think the consumer will be ok. The recession most probably mild for most ....
.
Are you suggesting crystallising losses and starting again? Hard pill to swallow when you're nearly 25% down.
Apologies, no not at all. I suppose I tried to say this is how institutions will and do behave. And if you aren't sure what to do, this is one way of deciding. There is actually nothing wrong at all with losses , but you do have to know what your investments are worth. Riding it out is the right strategy but only if you would still buy the same stock today.
M&c Saatchi (LON:SAA)
As Mr Contrarian notes below M&C talks are pushed back again. It strikes me that a walkaway is hard for both parties, given the stake that Advancedadvt (LON:ADVT) have in them plus Vin Murria's personal holding. Also M&C has proffered quite exciting future growth figures, thus making it hard for ADVT to formulate a bargain value that Vin Murrua has been used to in the past. So quite a long period of arm wrestling has resulted.
Be interested to hear how this resolves itself, but they have had quite a long time to establish whether there is a mutual value that can be recommended.
M&c Saatchi (LON:SAA) seems an interesting situation....
based on M&c Saatchi (LON:SAA) profit fcsts to double to 40m by dec 23 the £220MV (180p) even allowing for deferred shares to be issued the current share price seems a below average rating despite the growth in profits.
then there is a bid at 200p which the directors turn down as under valuing,
and yet they still talking to a bidder whose bid is at 190p because their shares are at 80p when the NAV of their business (CASH + shares in the 'undervalued' M&c Saatchi (LON:SAA)) is 97p (even adjusted for their loss on M&c Saatchi (LON:SAA) shares purchased at 200p).
none of these individuals are 'stupid' so I've been pondering why keep going around in circles?? my conclusion is that they are 'waiting' on something... so lets say that Advt is trying to get another deal over the line and, they think, that will get the share price back up to 100p +, in this scenario the bid now becomes worth 220p and the non exec of M&c Saatchi (LON:SAA) could feel comfortable to recommend the bid. thus at the moment Advt/Vin have persuaded the M&c Saatchi (LON:SAA) non exec to wait and see the market reaction and they believe it will make the bid realistic? just my own thoughts.. interesting to watch and have taken a 1% portfolio position in both.
my strategy is low risk.
I fortunately sold most of my holdings that had anything to do with the consumer a few months ago (for reasons I've stated before) but one that I held on to was Supreme (LON:SUP) . My belief going in to this was that the very high end and very low end would be the least scathed parts of the market, so given the other good things about it, Supreme fitted the bill.
I will continue to hold unless the story changes but I don't hold with the views that this stock and many others are outstanding value because I still don't believe that either companies or analysts have a good fix on 2023, so rendering outlook statements and earnings forecasts as highly dubious. I have more confidence in the forecasts of stagflation conditions through 2023 (in the UK and Europe at least). So I expect earnings forecasts for many stocks to come down as cost inflation at one end and embattled consumers at the other, crimp margins.
So I'm not rushing in to buy the dip (even though I'd expect a temporary bounce from these levels) but I'll hang on to the likes of Supreme. If the opportunity arises to buy more later then so much the better. I've said before that 100% equities is never a good idea for anyone except the very young, and this type of market underlines why.
For what it's worth, this is easy - it's a buyers market, so I'm buying.
No idea about timing, I just look at my companies and if the market prices them below my valuation, I buy and keep buying until that changes. Reading history shows that timing is incredibly difficult and there are very few cases of repeat success. I wonder when I will stop buying, but this is the upside to this market - the downside, the market value of what I own keeps falling.
When things change, there is a time when I can do nothing as the market agrees with my valuation, and then there is a time when it is a sellers market as the market prices above my valuation.
I will at times get my valuation wrong, but on the whole I will be more right than wrong and time helps to correct the mistakes I make, and I will always be conservative in my valuations.
Patience is very hard to learn, but I am a net buyer of equities and will be for quite some time, so this is the time to accumulate not capitulate.
I plan to accumulate government bonds in the next 15 years to the value of 3x annual income before I retire so these periods will not force me into becoming a seller of equities at the worst times - which is why I will never use leverage. I currently have 1x annual income.
I really should be thanking all the sellers for giving me the opportunity to buy very good companies at deflated prices.
It looks like the casino is emptying and my long term plan remains intact.
Interesting thoughts Mark B, fwiw i tend to agree with you!
Mark, how many companies are hitting you valuations?
I do the same and am surprised, that despite the sell off, 80 percent are still above what I would pay for them, making me feel we have a way to go yet...or am a tight b%%$$d. ;-)
40% are now under my valuation. For some this would be too little, for others, not enough. How much I am willing to pay is entirely up to me. As long as I am comfortable with my process, then I can sleep well. There are a multitude of people who would disagree with me, and they're entitled to that - just as I'm entitled to agree with myself.
How long will this market trend downwards - I don't know and I am very sceptical of anyone who tells me they do. I do know that it will change. It always has and always will.
Absolutely agree - Buffett summed it up with his saying be fearful when others are greedy and be greedy when they are fearful obviously with the latter now applying
As in all things patience is key. The current crisis is nowhere near as bad as immediately after 9/11. Personally, I shall just hold and wait.
A few shares looking tremendous value now, Facilities By Adf (LON:ADF), K3 Capital (LON:K3C), Supreme (LON:SUP) to name a few. Interested to know what might be on fellow investors watchlists?
Regards
Topped up all three. When there's blood on the streets...
High on my watchlist for top ups are B&m European Value Retail Sa (LON:BME), Somero Enterprises Inc (LON:SOM) and Domino's Pizza (LON:DOM) (only Somero Enterprises Inc (LON:SOM) a small cap I know)
Put my toe today into Vertu Motors (LON:VTU)
Be interesting to see what the final account RNS says tomorrow about the outlook and the buy-backs should restart. Bit of a risk maybe.
On watchlist:-
Somero Enterprises Inc (LON:SOM)
Supreme (LON:SUP)
Portmeirion (LON:PMP)
Atalaya Mining (LON:ATYM)
I hold all three, so a little endorsement is also welcome. In general I agree with Mark B's sentiment. All my holdings are in ISAs which imposes a little discipline as one needs to sell to buy, once the annual allowance is committed. At some stage the market will bottom, as to when I have no idea. Until then I will use dividend income to add to the likes of Headlam (LON:HEAD) Volex (LON:VLX) and Vitec (LON:VTC)
I have already added to Supreme (LON:SUP) and Facilities By Adf (LON:ADF) a little early, but if they are good companies and I believe they are, that will ultimately be of little be relevance.
Except for tinkering at the edges, I did little through the pandemic and will adopt the same approach in the current market. I hold no mining or oil companies.
My portfolio currently looks somewhat bedraggled, but nonetheless I am overall a buyer in this market. Not a time to sell in my opinion.
Supreme (LON:SUP) - I hold. Thought it was a steal at 150p - weighing-up adding.
It seems to me that this year for the first time in ages macro decisions have been key for performance. Given rates have started rising in reaction to inflation ALL stocks should be rerated which makes it difficult to value them. This might suggest a longer term reduction in prices given the period of time over which interest rates have been falling. I note is the FTSE 100 was around 6930 at the end of the millenium. It is around 7200 today so in capital terms it has not gone far in 20 years. Dividends have been the answer to long term returns. But lower pe ratings can do a lot of damage to equities. People always claim it is different this time and it rarely is but there are factors that are developing continually, demographics, wars (which destroy wealth), technology, global warming which will lead to changes in prospects for equities. The translation of these things in monetary terms is defined by interest rates and inflation. I am therefore nervous of holding equities but is there another choice? So I am not going to say I sold all my equities I didn't and frankly doing so would have locked in a loss with inflation rising. So my question is where are you putting money when you raise cash? I have made some by shorting 10 year treasurys and Gilts. The L&G Commodity fund has done me well and physical gold with its exposure to the dollar has also helped me this year. Sorry I know its a bit off the theme of this board but for me there isn't too much to talk about in stocks at present and there is an intelligent discussion to be had in my humble opinion. Ignore if you feel it is out of line.
Camtab
You write "I note is the FTSE 100 was around 6930 at the end of the millenium. It
is around 7200 today so in capital terms it has not gone far in 20
years."
Is this a fair comparison, when the constituents of the index have changed over those 20 years? I can't even decide what it means in terms of economic performance, can you?
FREng,
It is a fair point you make. However I am just using the index as a proxy for shares. Effectively looking at it from the point of view of a passive investor. I don't invest this way but my comment above is really about asset allocation so I need a proxy to explain the performance of that asset class. You may feel I should have used the MSCI World or even FTSE World? But my point really was had I bought a FTSE100 index fund it would have risen by under 5% illustrating how important the dividends remain to returns.
In terms of economic performance wouldn't we just look at the UKs GDP growth over that period. But I am no economist!!
All the best
I think it's fair, albeit imperfect. The hundred largest constituents of the LSE today are valued by the market at barely more than the hundred largest constituents of the LSE over 20 years ago.
Yes ... this is no longer the same set of companies but individual companies will always wax and wane. I think a comparison of the 100 largest then and the 100 largest now is still valid.
Yes, but if you always add companies that are growing, and discard companies that are declining, you have a constant upside bias
So why has the FTSE 100 performed so poorly then?
Yet the FTSE250 is almost 4 times higher than it was in 2003. Is that a better or worse proxy for shares than the FTSE100?
dotcom boom meant that FSE 100 had lots of little companies in it perhaps. When the chicken cam home to roost?
Compare the S&P 500 to the FTSE and you see little incentive to invest in UK equities, based on performance.
Perhaps the rerating of the tech firms may help, but are they not the next value investments with 'the next big thing' being listed in the USA?
I favour USA tracker over FTSE which is a great shame.
Naturally, past outperformance of the S&P500 vs FTSE is a surefire guarantee of future success...
Paul, if it’s any consolation, my portfolio is performing almost exactly in line with yours. But I went to a music festival at the weekend and had just as much fun as when I was much wealthier, and in the company of my wonderful wife and lovely friends. We had a blast. So the important things in life are all still in place.
Ditto - re my performance too. I've just finished a great motorbiking holiday in Spain with a mate and am with my wife on the Med coast now. Trying to remind myself of your final point!
In the US nominal growth is very high and real interest rates remain very low. Employment is high although this is somewhat flattered by some worker (mainly boomer) exit from employment market. US housing market is quite strong driven by combination of younger buyers finally getting on ladder and sustained undersupply since 2008. The USD is also strong and this mitigates many input price pressures. The US had crazy market prices in many areas though due to nexus of 'innovation' and liquidity. Rising long bond yields suggest the bond market is 'bullish growth'. US consumers are in financially strong position and have significant room to borrow too. Make of this what you will...its not obvious to me at all that this presages recession. That said the period on period comparisons are generally out of whack as we did the whole mad covid dance with decreed flash depression so we can print volatility and have snapshots that look like recessions.
Commodity markets and inflation expectations are the hot button. If you are of a paranoid persuasion you believe that Putin and Xi have the weak West locked up in a trap and that is being transmitted through commodities and general inflation pressures (Chinese messing supply etc). I'll take the other side of that. They have set their own trap by believing that the global economy is a stock and not flow governed system...all the evidence points to the latter but of course 'stock' can cause shocks (as we currently see). BUT...this is truly transitory...yes that word...flow will win as the world that can always goes forward and we now massively responsive govt and CBs that stop us falling into a stock dynamic depression (it was the belief that hard value like gold rather than valuable activity was true worth led to historic depressions)...
Beware the 70s trap. We are obsessed with that decade and we have created a massive angsty misperception from it (...as an aside, Volcker was an idiot who damaged US economy). It was a one-off in history yet we repeatedly believe we must work to avoid it. Madness. Without a strong global investment and credit cycle inflation and high commod can't persist. Without this credit propellant high prices kill demand. That's an uneven process and is likely seen by some curtailment in say Europe but many EM countries being taken out and shot in the head. This dynamic could and may already be extending to China which has a terribly unproductive excess investment driven infrastructure and real estate growth model.
What have we all learned recently? Hopefully that energy is not a meme to be tossed around with abandon but the basis for civilisation. Reliable excess energy is essential to our way of life. I find the bs around net zero and efficiency to be quite unbearable. And that we think the solution to energy shortage and intermittency is more of the same is true stupidity. I too want greening...but civilised life is an energy system fighting inherent universal entropy.
I will vote for any party that addresses energy problem in UK and sets path to independence. I'm not a Farage fan but this is set up for him to set up UKEIP (UK energy independence party).
However, the greatest lesson we need to learn is that the world needs a credit cycle. We over-learned from 2008 and decided that banks are evil and that credit is the devil's work. What idiots. Credit makes the world go round...and we can't solve a credit overhang with austerity (unless we think a corrective depression is the remedy -> only gold wing nuts think that as they misread history)...got to let good credit (activity and flow) chase away the bad.
So I will vote for the Make Credit Great Again party...whoever that is. The govt learned the ropes during covid crisis -> underwrite lending...but this time do it with some planning and aims. Kick start a cycle and get the banks firing again.
Bit of a ramble! Take from it what you will....or feel free to tell me I'm as mad as a clown's c$ck
Interesting stuff Mojo.
The difficulty I see in what you say is who has the wisdom to determine what is good credit (activity and flow)? Is credit for infrastructure projects good credit for example? Just to take one example, it seems very unclear (or at least there’s not a great deal of consensus) as to whether HS2 is worth it (whatever that means).
Several decades ago, government started referring to spending as investment, hence all public services suddenly became investments (hospitals, schools, etc.) implying a financial return. The education, education, education mantra justified sending many more people to university at least partly on the grounds that a better educated workforce would be more productive and yet productivity growth has been very weak. So, plenty of activity and flow but at least one if the most important intended outcomes, higher productivity, just hasn’t happened, and instead we have large amounts of personal debt and a bill for the government for those that cannot pay it all back.
So, if we cannot determine or agree on what is activity and flow that will generate prosperity then how are we going to decide what is “good credit”?
There's no reason to decide. The market will do that...and it will get it wrong often too so we will have default and crisis too. This is part of the natural capitalist economy flow. Over exuberance creates great folly. Sadly, in our wisdom, we decided we can regulate away folly. But folly is one of the great motors of our civilisation. Tesla is a wonderful example...and the US boom in shitcos another (they replaced Wall St derived bank financing with VC...the only country to innovate a credit alternative!).
C19th UK was a great example of many exuberant follies. That was a time we believe money to be real and limited so the exuberance got punctuated with many harsh depressions.
Infrastructure like a modest bridge or tunnel or toll road can be funded privately but things like HS2 are necessarily a political and policy decision...and yes we should have done it and it was insane not to. The austerity mindset infection gets in the way. Austerity is the road to nowhere as a society (different from households) and Dave and George were the worst leaders we had in a long time (I'd nominate Osbourne for worst and most incompetent Chancellor...Spreadsheet Phil would get a look if he lasted longer...and Rishi is now looking like he wants to challenge for the title). We can never afford something like that in an accounting redux...but we need to do enough things like that to push forward. US Highways were once a madness and folly...
'The North' is a giant lowly tapped area of potential and it makes sense to do things that encourage a flourishing. As an aside I think the Greater Manchester area is one of the most interesting in UK. Innovation can no longer afford to be in London (that includes artists of all sorts)
Being of a somewhat simple soul I fear governments put employment for their people at any price a priority, hence S2. Going back a century or two, for employment of surplus labour there was dry stone wall building and tree planting on the estates of the Landed Gentry, they were the government of the day and like HS2 and Concorde it was palliative care. Definitely bad credit. Don't ask me about the Welfare State just now.
You may be as mad as a clown's thingy but I agree with most of what you say. Austerity isn't the answer (please someone tell Rishi), growth is the only answer but unfortunately growth will be hard to come by in our new world of constrained resources. Whatever you or anyone else believes about carbon, we are now travelling down the road of decarbonisation. We will also be reversing our journey of globalisation and investing in localisation. These things will all require a lot of investment which is why you're right to underline the need for credit.
But this country has a very poor record of allocating credit. We need the right incentives in place so that credit goes in to investment in supply, not just more demand which is what we typically do (house prices going up again, yahay!). We should also recognise that all this investment is merely replacing perfectly good energy infrastructure and global supply chains, not adding to what we've got. So in many senses, it's a lot of money to help us stand still, not move forward. That's not great for growth. Meanwhile, we don't have an excess supply of all the resources needed to do this, so all of this is inflationary. It's not like investing in a post-depression economy where there are lots of available resources and growth is cheap.
The world has been on a great run since China decided to join in and America discovered fracking, and a lot of that is now going in to reverse. How we cope will depend on the wisdom of our governments (which I have no faith in) and the market's ability to drive innovation (which I do).
As I understand it, during the peak of the pandemic, the BoE created money, bought Gilts and effectively cancelled a lot of them by letting them expire and returning any interest payments made by HMG to the Treasury. That pumped cash into the economy, held down interest rates and stimulated an asset bubble. Monetarists say it added to inflation. But it didn't cause a run on Sterling.
The Ukraine war will end and the inflationary consequences of it will abate. So what would be the downside of the BoE creating money and giving it to HMG to use to alleviate the worst consequences of inflation for the poorest? A bit more inflation perhaps? Possibly balanced by a bit less recession?
During the pandemic, the strongest objection that I read to the suggestion of creating money to be used for current spending was that it might become a habit and lead to a major currency collapse.
Hi FREng
IMO the inflation is all about supply disruption -> stop start of global economy and the bottlenecks it creates. In UK and Europe we didn't print money and create extra demand...we just used debt monetisation to support services and incomes during a period when activity and tax receipts down. Demand in UK and Europe hasn't recovered past pre pandemic
The US did 'print' use fiscal space to stimulate demand which particularly went into goods which then hit supply restraints.
The UK should employ further debt monetisation (ie truly you can call it printing money at this point as then it translates into govt fiscal spend with no countervailing tax or debt support) to support strategic investments - energy (nuke IMO), defence, food supply, infrastructure that then supported private enterprise (road, rail, ports, etc).
This is not a gold-but / Austrian economics disaster movie where the currency collapses due to monetary inflation. The monetary inflation impulse is low and soon turning negative. We will have severe disinflation v soon...
Great ramble Mojo you seem clued up on markets and cycles any thoughts on whether 10 year US treasury bond yields are peaking (or not) and if they are could there be some chinks of light on the horizon ? I'm assuming bonds should show signs of recovery ahead of stocks when the corner starts to turn ?
Regards Andy
Supreme (LON:SUP) there were big trades yesterday at 134.5p so maybe an overhang. I've added at the open. SCSW commented in this month's issue:
"With the NHS preparing to prescribe vaping to help people stop smoking tobacco products in due course and a dividend yield of 4.3%, I am inclined to keep buying."
I sold everything outside my Sipp and Isas last month the stuff I kept is all in Infrastructure, renewable energy and IG index that usually does well when market volatility increases. My view is high energy prices higher taxes and high Interest rates will suck spending power out of the Economy. On top of this China having Covid shutdowns ongoing problems in global supply chains the war in Ukrain sending fertiliser costs through the roof a drastic reduction in wheat from Ukrain together will lead to a global recession.
I dont see much upside in global markets but a hugh potential downside.
My portfolios are in drawdown so my expenses will be covered by what I hope are safe High income shares in my SIPP and ISAS the purchase of the Portugese villa has gone on hold everything else is in cash on the hope I can buy back in at a much lower value.
I know not everyone agrees but thats what makes life and Investing interesting
infrastructure and renewable energy eh? Good luck with that particularly the renewable energy 'scam'.
Yes I am hoping for some luck. Thank you
I get the impression the Nasdaq still has a way to go to get to more sensible levels, the risk is it takes everything else down with it. Uk markets seems to be sensibly rated however the risk is with inflation of collapsing profitability which would bring the P/E ratios much higher.
I was thinking of whether to reduce my exposure to UK only companies (those that operate in UK only) as it clearly appears that the UK is in line for several years of higher inflation and slower growth than elsewhere. The ability to export freely and the lack of available European workers seem to be adding to the inflation worries. Can anyone remember a time when there's a recession looming but there's a huge labour shortage?
On Monday last week John Authers wrote:
" the American Association of Individual Investors’ regular weekly survey showed that the number calling themselves “bullish” had collapsed. By April’s last survey, many were prepared to call themselves bears. In the last 30 years, bears have outnumbered bulls more than they do now just once. And that was in the second week of March 2009, in what turned to be the last survey before stocks hit rock bottom and started their great post-Global Financial Crisis rally
So sentiment is looking very negative, indeed startlingly so, given the strength in the jobs market and the resilience of corporate earnings. That implies that a turn shouldn’t be far off. The risk is that one final cathartic collapse (as has often in the past happened on a Monday after a bad close on Friday) might be needed to get there. The next week, with the last big download of corporate profit numbers, plus Institute for Supply Management data on Monday and non-farm payrolls on Friday sandwiching what is likely to be a 50-basis-points rate hike and the start of quantitative-tightening bond sales by the Fed on Wednesday, will provide plenty of opportunities to change direction (or not)."
Also (https://edition.cnn.com/market...)
So, short term it looks like (at least) a bounce is due.
Morning all,
Futures are blue, let's see what happens today...
Regards
I am reading Sandy Nairn's book again. It was published about a month before the market peak at the end of last year. Well worth reading, but it won't make you feel any better I'm afraid! "The End of Everything Bubble".
Nwf (LON:NWF) trading update:
”Further to the trading update of 31 March 2022, the Group continued to experience exceptional trading conditions in the Fuels business, with very significant short-term volatility in oil prices and a supply constrained UK fuel market. As a result, performance during the final quarter of the year, to date, has been materially stronger than anticipated with the full year result now likely to be significantly ahead of the Board's previously upgraded expectations.”
(I hold)
Perhaps we should all retire to Paul's local and Mello ;-)
I am game for that,