Small Cap Value Report (Mon 15 May 2023) - RST, WG., CURY, FRP, CER

Good morning, it's Paul & Roland here today! Many thanks to Roland for joining me today, as Graham needed some time for another project.
Update at 13:18 - I'm still working on CNIC, so will carry on until that's finished.
Update at 16:39 - I've just finished reviewing CNIC, but it's too late for today's report. So I'll type it up now, and put it into tomorrow report first thing. Took me a lot longer than anticipated, sorry about that!
Today's report is now finished.
Podcasts - from Paul, went up on Saturday morning as usual. Gave me a good chance to have a moan about a couple of little things that have been irritating me (!), and to run through the usual recap of small companies news. It's great taking stock each weekend, as the blizzard of company news stops for two days. I'm told my podcasts are popular with dog walkers, and gym members!
Tonight - Mello Monday investor show online, is free! More details here. I'm looking forward to the Q&A with Sosandar (LON:SOS) management (I hold).
Mello Chiswick - I'm looking forward to attending next week, I'll be there both days, in the afternoon/evenings, and look forward to seeing old friends, and new - do come and say hello if you're there, I love meeting Stockopedia subscribers in person!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
The list looks manageable today -
Summaries of main sections
(more detail below)
Restore (LON:RST) - down 15% to 249p (£349m) - TU (profit warning) - Roland - AMBER
A 25%-30% slowdown in PC/laptop sales has resulted in a slump in demand for Restore’s IT recycling services. The remainder of the business is said to be performing well. Another warning is a risk, but I can see some signs of value here.
Currys (LON:CURY) - up 6% to 59.7p (£672m) - TU (ahead) - Roland - AMBER
Currys expects results for the year to 29 April to be ahead of expectations. But the relaxation of a key lending covenant suggests the outlook for the year ahead is uncertain. A cash-sucking pension deficit is another worry. I think the shares are deservedly cheap.
Cerillion (LON:CER) - up 2% to 1220p (£360m) - Interim Results - Paul - GREEN
Superb interim results, and confident outlook. I suspect a beat of FY 9/2023 forecasts is more likely than just meeting expectations (as indicated today). Lovely balance sheet, with the cash piling up, giving options. In summary, I like everything about this share, apart from the price! (which is challengingly high, but I suspect it's justified in this case).
Quick Comments
John Wood (LON:WG.) - down 34% to 144p (£1.0bn) - Apollo not bidding - Paul - AMBER
Apollo ($598bn funds under management) announces that it does not intend making a takeover bid for this consulting & engineering group. No reasons are given. Looking back, Wood announced on 22 Feb 2023 that Apollo had approached it 3 times, with indicative takeover bids of up to 230p, which Wood said “significantly undervalued” its shares. We can now buy them at 144p, so are the shares a bargain?
Paul’s opinion - it’s difficult to see much appeal to this share from the rather erratic historical performance, or the valuation. Revenues are massive, but it seems to have struggled to generate reliable profits in the past. Maybe there’s hidden value, because I can’t find anything obviously good, on a quick review. Have any readers looked at this share? If so, do post a comment.
Frp Advisory (LON:FRP) - up 3% to 114p (£284m) - FY trading update (ahead) - Roland - AMBER
This business advisory services group says revenue for the year ended 30 April is expected to be up by 9% to £104m. Adjusted underlying EBITDA (!) is expected to be 5% higher, at £27m. Both “slightly ahead of current market consensus” of £100.5m/£25.8m. Restructuring, insolvency, and corporate transactions are the main growth areas highlighted.
Roland’s view: FRP’s revenue growth has been strong since its AIM listing in 2020, but reported profits have been broadly flat, due mainly to hefty share-based incentive employee payments. However, profit margins are still high at this business and FRP has generated a c.30% return on equity over the last 18 months. With the shares now trading on 14x earnings with a 4% yield, I can see some potential attractions.
Paul's Section:
Cerillion (LON:CER)
Up 2% to 1220p
Market cap £360m
Cerillion plc, the billing, charging and customer relationship management software solutions provider, today issues its interim results for the six months ended 31 March 2023.
Cerillion specialises in the telecoms sector, with sticky client contracts.
It’s one of my favourite GARP shares. Although the RP (reasonable price) bit of that is challenging, with a forward PER of 28.8x. I was talking about this in my latest podcast over the weekend, that in a higher interest rate environment, it’s very difficult to justify any PER over about 20 (an earnings yield of 5% or less), when the risk-free return on cash is now c.4-5%, and future cashflows are discounted using a much more challenging interest rate compared with the 15 year era of zero interest rates. My worry is that maybe some investors haven’t yet reduced their valuation criteria, as old habits take a while to unlearn?
So my starting point with CER, before looking at the figures, is that it’s a smashing growth company (organic too), one of the best growth companies on the UK small caps market, but shares are expensive.
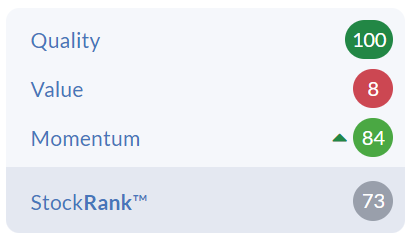
Stockopedia’s algorithms say the same thing, in far fewer words!
On the the numbers & commentary for H1 (6m to 31 March 2023) - note the prompt reporting, which is good.
Record Six-month Period and Strong Prospects
Outstanding highlights table -
Note the very high profit margin (£9.2m adj PBT, divided by £20.5m revenues) of 45% - not many companies achieve this high level of profit margin -
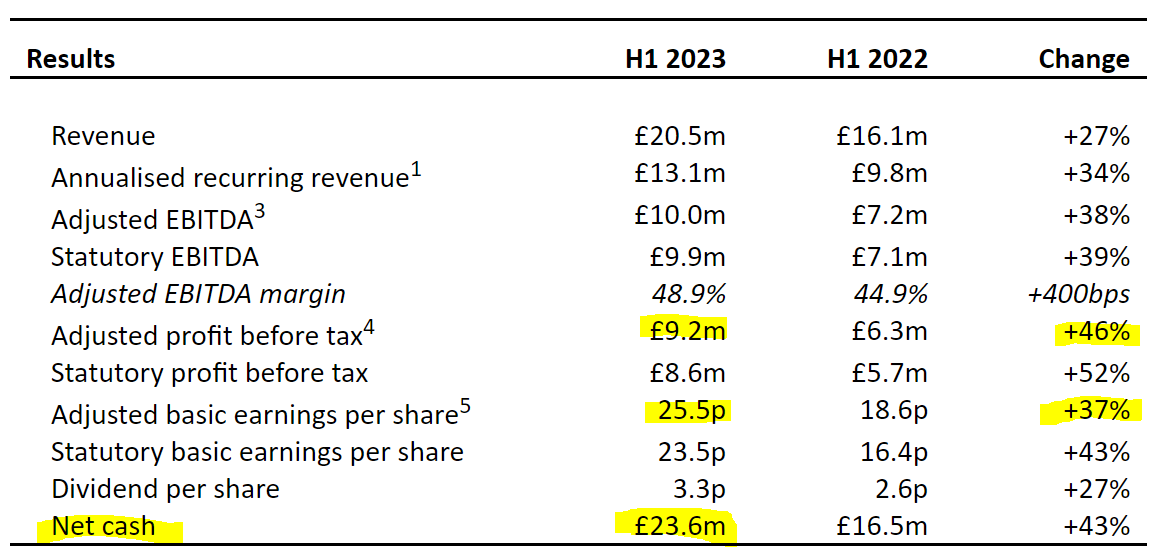
Remember these are just H1 figures, so P&L items should roughly double for a full year.
Really excellent profit & earnings growth too and a nicely building cash pile too.
Lots to like in the table above!
Order book - is up a more modest 8% to £43m - is growth slowing now perhaps?
2 Back-order book of £43.0m consists of £34.7m of sales contracted but not yet recognised at the end of the reporting period plus £8.3m of annualised support and maintenance revenue. It is anticipated that 75% of the £34.7m of sales contracted but not yet recognised as at the end of the reporting period will be recognised within the next 12 to 18 months.
Customer pipeline - obviously only part of this is likely to turn into actual orders, and this measure is wide open to manipulation, but from a company I trust, with a good historic track record, I’m willing to attach at least some importance to this measure -
New customer pipeline up 23% to a record £212.0m (H1 2022: £172.0m)
Adjustments in the P&L are small, and perfectly reasonable in my view, so the adjusted numbers are reliable for valuation purposes.
Outlook -
The Board believes that the Group is well-positioned to deliver its full year targets
From a market perspective, we are continuing to see strong investment in 5G and broadband infrastructure. This will create substantial opportunities for Cerillion as communications service providers seek to monetise those new assets and gain more value from their network real estate.
Looking ahead over the balance of the current financial year, we remain very confident of continuing progress, supported by our strong back-order book and new customer sales pipeline.
We believe that Cerillion remains well-positioned to achieve its full year targets, supported by existing major implementation projects, the healthy back-order book, and our strong new customer pipeline, which includes a number of advanced-stage new contract discussions.
The Company's robust balance sheet, which carries no debt, and the increasing level of recurring income, provide a strong underpinning for the business as it continues to grow and develop. The Board views near and mid-term growth prospects very positively.
Dividends - are stingy, with only about 1% forecast yield, well below the 4-5% you can get in cash, so investors here are betting on capital growth, not income -
As previously stated, the Board aims to distribute between a third to a half of the Group's free cash flow as dividends each year, subject to the Group's performance and the Board's assessment of the trading environment.
Share based option charges are very modest, which is nice to see.
Note the founder CEO holds 30.5% - so very much the owner’s eye, but not so large that small shareholders are lambs to the slaughter.
Balance sheet - looks lovely. NAV is £31.8m. From that, I deduct intangible assets of £4.2m, giving us NTAV of £27.6m.
The cash pile has grown to £23.6m, and looks genuinely surplus cash, so CER has plenty of scope to raise divis, do share buybacks, and/or acquisitions, should management wish to.
A big cash pile also reassures customers & potential customers, who look for financial strength in a supplier, if they’re going to commit to buying a business critical software package. Plus of course, with higher interest rates, CER can now earn a nice return on interest receivable, which could be heading for say £1m pa?
Cashflow statement is simple and clean. Note that it only capitalises £0.5m of R&D in each half year, indicating prudent accounting.
Paul’s opinion - very positive indeed. This is clearly a cracking growth company, with the right products at the right time. Very sticky client contracts too, which lowers risk. So it's a thumbs up from me.
My interview with the CEO in Nov 2022 is still relevant, and dug into the business model, to understand what is driving the superb growth achieved in the last 3 years.
How to value this share, that’s the tricky question!? That’s ultimately down to each investor. I do find the current valuation a bit challenging, at almost 30x this year’s forecast FY 9/2023. However, the forecasts look quite modestly set, so I imagine an earnings beat could occur.
Also, as we always say here, you’re not just buying this year’s earnings in isolation. We’re buying all future earnings forever, if we become a part-owner in the business. With that in mind, I think it could be worth taking the plunge here, and paying top whack for a very high quality business, which also seems to have continuing growth potential.
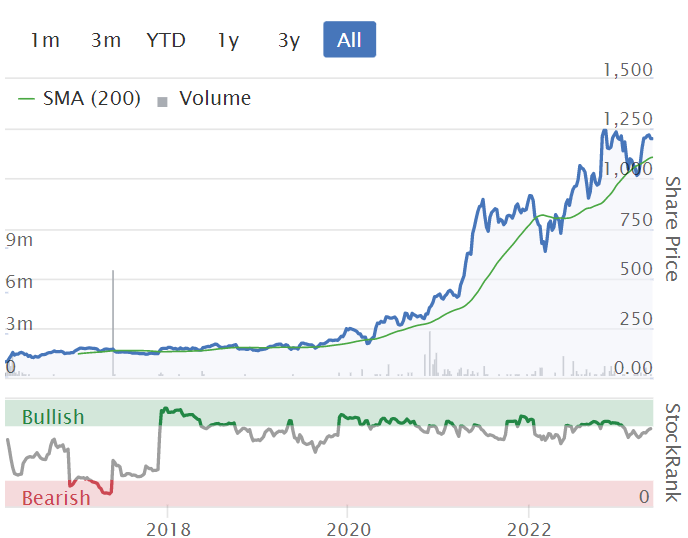
A fantastic share, for investors who have had the patience to buy & hold. I recall Graham flagging this share a few years ago, and I had a call with management which impressed me, and I think they were about one-tenth of the current price at that time! But the facts have changed since then, very much for the better. So we couldn't possibly have foreseen that it would 10-bag! With multibaggers it's often just a leap of faith in the early stages -
Roland’s Section:
Restore (LON:RST)
Share price: 249p (-15% at 08.05)
Market cap: £342m
Today’s update from this document management and information services group is a mild profit warning.
management now expects the Group's adjusted PBT to be below their previous expectation and in the range of £41-43 million for the year.
The shares have already lost a third of their value over the last year, so it looks like investors were already taking a cautious view on the outlook for this business.
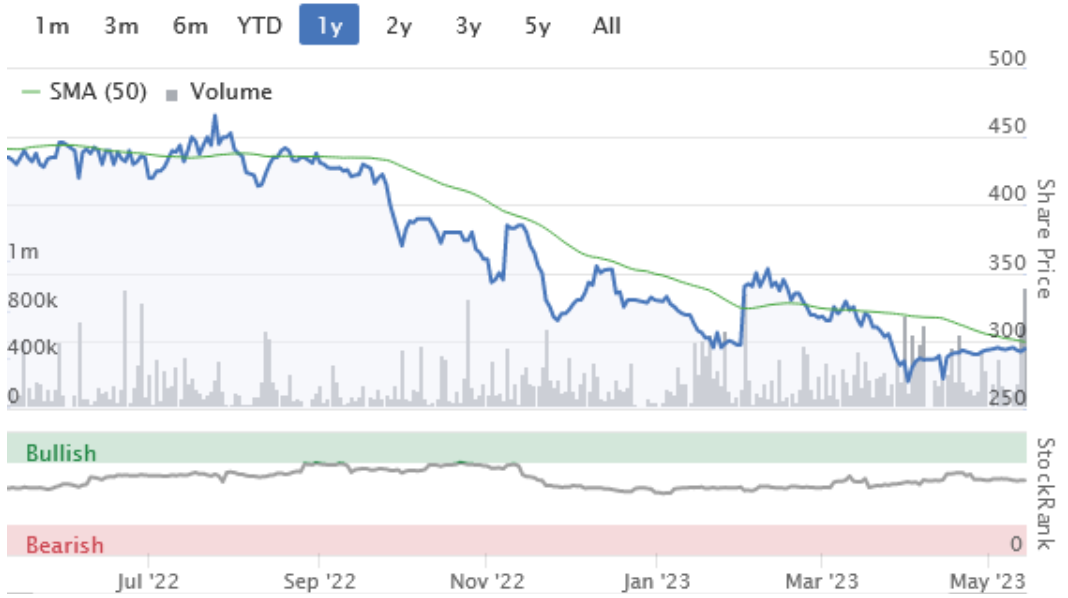
Let’s see what the damage is in today’s trading update, which covers the four months ended 30 April 2023.
Revenue rose by 4% to £92.8m during the first four months of the year, compared to the same period last year.
Digital and Information Management: these divisions deal with paper records archival and digital workflows such as document scanning.
The company says it put through price increases at the start of the year and is also seeing increased activity from new customers. This progress is offsetting the loss of a large, one-off public sector contract in H1 last year.
A contract with the BBC (the largest in the company’s history) is said to have started well.
Net box growth is said to be positive and within the guided range of 1-2%.
Secure Lifecycle Services: this division deals with shredding confidential documents, IT disposal and recycling and commercial relocation. These operations are all said to be ranked either first or second in their respective markets.
Activity in the group’s Datashred and Harrow Green (relocation) businesses are said to be in line with expectations.
In Technology, demand is said to be strong for “ultra secure IT Destruction and IT Relocation projects”, which represent 20% of technology revenue.
However, the group has seen a “slower than anticipated recovery in hardware recycling volumes”. Management say this is consistent with market reports of a 25-30% fall in new PC/laptop sales, after elevated pandemic demand.
Cost savings: plans to reduce the group’s cost base by £3m are continuing to be rolled out.
Outlook: Restore’s management have helpfully provided updated financial guidance in today’s update, so we’re not left guessing.
Revenue and adjusted EBITDA are now expected to rise by around 5% this year, suggesting figures of £293m and £85.6m.
Previous consensus estimates were for an increase of 10% in revenue and EBITDA.
Adjusted pre-tax profit is now expected to be in a range £41m-£43m, compared to previous consensus figures I can see of £45m. So a reduction of 5%-10%.
My view: this looks like a fairly mild profit warning, with perhaps a 5% reduction to expected earnings to c.23.5p per share.
The reduction is blamed solely on the slump in PC recycling – all other elements of the business appear to be performing in line with expectations.
On the face of it, I don’t see too much to be concerned about. Corporate PC buying cycles were distorted during the pandemic by the need to supply staff for home working. It’s not entirely surprising to see that sales levels are now slowing.
All else being equal, this should just be a temporary headwind. However I can see a couple of risks that might be worth considering for anyone researching this stock in more detail:
Restore has been quite acquisitive in recent years. The group made eight acquisitions in 2021 and five in 2022. A number of these were aimed at expanding capacity in the Technology business, which is now suffering a slowdown. If I was considering investing in Restore, I’d probably want to go back and take a closer look at these deals.
The reduction in PC sales might also be a sign of a broader slowdown in service-related sectors of the economy. So weakness could persist for a little while yet.
I estimate that today’s share price fall has left Restore shares trading at around 11 times 2023 forecast earnings.
That doesn’t seem expensive to me given that this business generated more than £30m of free cash flow in each of the last two years. That gives the stock a tempting trailing free cash flow yield of around 9%. Debt levels don’t look excessive, although they have been rising.
I’d need to do further research to understand the moving parts of this business. I’m also aware that the first profit warning often isn’t the last.
For these reasons, I’m going to stay neutral for now. But I can see some potential signs of value here, so Restore could be worth a closer look.
Currys (LON:CURY)
Share price: 58p (+4%)
Market cap: £659m
Stronger UK&I business drives better than expected results
Electrical and tech retailer Currys has upgraded its guidance for full-year profit guidance for year ended 29 April 2023:
Adjusted pre-tax profit is now expected to be £110m-£120m, compared to previous guidance of £104m.
Year-end net debt is now expected to be around £100m, compared to £100m-£150m previously.
However, this increase in profit appears to have been driven mainly by improved margins, rather than higher volumes. The company says full-year like-for-like sales were down by 7%, which appears to be broadly in line with consensus forecasts.
In an inflationary market, falling revenue implies a reduction in sales volumes. The pandemic boom is still unwinding here, I think.
Higher profits are still good news, though.
UK & Ireland: management say trading was better than expected, especially in the final two months of the year. Gross margins are said to have improved, suggesting Currys may be benefiting from reduced shipping costs and perhaps better pricing from suppliers.
One-off benefits from the wind-down of the group’s legacy mobile operations are also said to have been “higher than prior year and forecast”. In FY22, mobile debtors resulted in a £22m working capital inflow. A smaller figure was previously guided for FY23.
UK&I operating profit is expected to have risen by >40% in FY23, which I calculate should be at least £100m (FY22: £71m).
International: operating profit from the international business is expected to be materially lower than last year, driven by a slowdown in the Nordics. The group’s “market-leading business” in Greece is said to have delivered another “robust performance”.
Balance sheet: lower-than-expected net debt is obviously good news. Currys also ended the year with a 10% reduction in stockholdings.
Reducing inventories should aid short-term cash generation, but this process may need to be reversed before the Christmas peak trading season.
I wonder if this is one reason why Currys tells us today that it’s negotiated a relaxation of a key covenant on its £500m revolving credit facility “for the measurement periods from 28 October 2023 to 26 October 2024”.
This suggests to me that CEO Alex Baldock is taking a fairly cautious view on the outlook for the next 18 months.
Today’s update did not mention current-year trading, so we don’t know if the outlook has changed. Broker forecasts suggest a recovery in earnings this year, but I’m not sure how this squares with the relaxation of lending covenants.
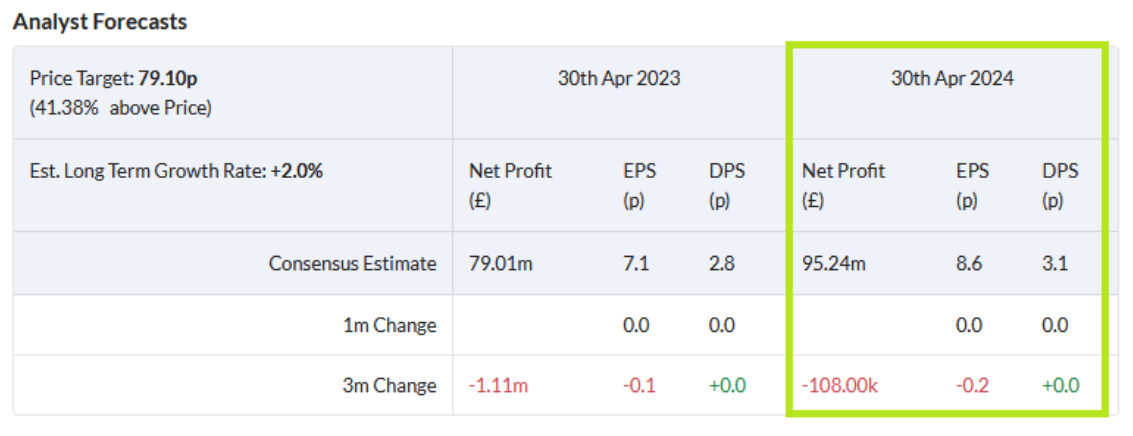
My view: Currys is one of the biggest players in its sector in the UK. I don’t think it’s a bad business, but I don’t see much attraction to the firm as an investment.
This is always going to be a low margin box-shifter in a highly competitive sector. A growing customer credit offering may help to improve margins slightly, but it isn’t without risk either.
The relaxation of lending covenants leads me to think that Currys’ balance sheet is not as strong as its lenders would like it to be.
Another worry is the group’s large pension scheme. Cash contributions to reduce the deficit are running at £78m per year – last year this accounted for 15% of operating cash flow.
Annual pension benefits of c.£50m are being paid due from scheme assets that were valued at £987m in October 2022. My guess is that deficit reduction payments will need to continue for a little while yet.
The shares look temptingly good value, but Stockopedia’s algorithms also classify Currys as a Value Trap. I think this could be accurate and I can see some risk to the dividend.
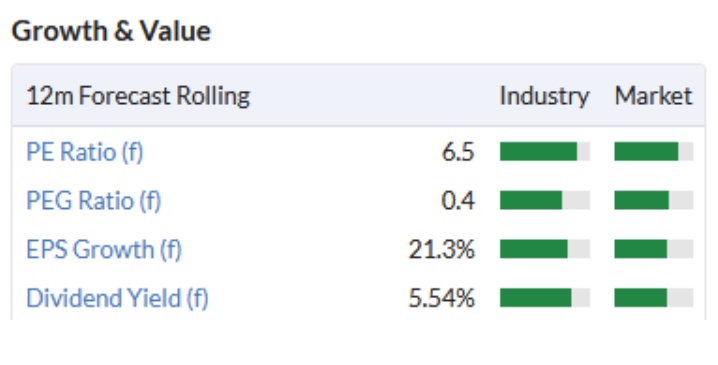
I think there are better opportunities for investors elsewhere.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

66 comments
Share purchase by CFO of £SUP. 21K not a massive amount, but positive nonetheless!
Quite significant relatively speaking in that:
1) In a previous Supreme (LON:SUP) results presentation she (Suzanne Smith, CFO) answered a question about her nil holding by saying she didn't have funds
2) Very soon after she was awarded options but it's good to see her now committing in this way and from zero not long ago this can probably be seen as a decent commitment.
Thanks for highlighting JohnDoe.
[I hold]
Apologies that this isn't a small cap? but I know a few of the readers are likely to have a interest.
Investment Trust Valuations. Taking (LON: IVPU) (Invesco Select Trust) as an example.
On Stockopedia the IVPU NAV is 150p
On Hargreaves Lansdowne the IVPU NAV is 188p
Both say its based on Debt at Par and Fair Value. Both seem to be based on press releases dated 12/5. Am I missing something? Presumably they both cant be correct.
Dont hold but they update NAV every day by RNS by the looks of things. Above chart shows discount to NAV.
Today-
"Invesco Select Trust plc
UK Equity class Ordinary shares (IVPU)
As at close of business on 12-May-2023
NAV per share (unaudited) with Debt at Par &
Fair Value
EXCLUDING undistributed current year revenue 188.80p
INCLUDING current year revenue 188.80p
The fair value of debt is not materially different from
the carrying value."
Investment trust NAVs are updated daily. As far as I recall, Stockopedia shows the NAV from the last set of accounts, so in other words could be very out of date! The AIC website is the best place to research investment trusts and has all the latest data where you can see the discounts, returns, etc.
Thanks Wolf and Bouden. Looking more closely the daily news NAV values are wrongly attributed and updated on Stockopedia - have reported it.
Revolution Bars (LON:RBG) has pushed up another 8% today, that's over 25% gain in the past 5 trading days. Interestingly the volumes, which are vastly higher than previous weeks where they were basically non-existent, are still quite low (£60k of shares traded on Friday and £40k of shares traded so far today). With the shares so bombed out this could be the beginning of a much larger spike higher if trading volumes continue to increase as investors return to the sector. As Paul mention in his podcast, J D Wetherspoon (LON:JDW) has already seen a big spike upwards from the lows, as a holder here, I am hoping to see RBG follow up with a similar move in the next month or two.
Yes it’s certainly encouraging and I also take some comfort in that not one Director has sold any shares in the last 5 years . And, of course, it’s one of our Paul’s largest holdings :)
Litigation Capital Management (LON:LIT) looks like a decent win relating to an Australian class action. Been a good year for the litigation financiers so far after some positive developments with Burford Capital (LON:BUR) Just need Manolete Partners (LON:MANO) to also start showing some signs of recovery.
I do hold CentralNic (LON:CNIC) and have been happy with the company making fairly audacious, acquisition based, growth plans. The aim when buying other companies is to acquire companies that can grow and bring in cash.
Acquiring assets is nice, but they are completely unavailable for software companies, and sales are fine as long as everyone keeps an eye on the fact that it is cash which brings home the bacon. The intangible assets acquired are the skills, contacts and operational capabilities of its people. So the key question is - has CNIC shown that it can bring in cash return for its expenditure? And it seems clear to me that it has, as well as floating stock and increasing debt. The fact that the AIM market (and perhaps, more generally, the London market) cannot value the cash flow without forcing companies "prove it" by doing dividends and buybacks (as CNICis now doing) is not helpful. I hope, that having provided the proof, CNIC will be allowed to resume growth without their ambition frightening the punters.
Morning All,
Just seen a 1.7M trade go through for £TEG. Would assume this is a sale, perhaps why the sp has been depressed?
We are doing a deep look into TEG tonight on the Mello show. It is on the BASH so worth clicking in and watching
Hi JohnDoe2378,
Just seen a 1.7M trade go through for £TEG. Would assume this is a sale, perhaps why the sp has been depressed?
By definition, a trade of that size will have both a buyer, and a seller (unless it's an existing holder moving stock around from one account to another, which usually happen at the mid-price). Large trades like that are usually negotiated, and don't go through a market maker, so they won't usually affect the share price at all.
All trades have to have a buyer and a seller. For small trades, the buyer/seller is a market maker, which I think is why people sometimes comment that it's a buy, when what they mean is it's a retail buy, and the other side of the trade (the seller) is a market maker.
Regards, Paul.
Following a discussion on here about declaring payment for interviewing, some personal and vitriolic comments were made about Paul Hill as a result of which he decided not to post on here for the time being.
I have discovered that he has done a discussion with Judith McKenzie of Downing covering a number of companies which are often discussed here (listed below).
Declaration: I have not been paid by anyone to post this, Paul H was probably paid by Vox to record it, whether Downing or any of the companies involved paid anyone I haven't a ****** clue.
Equals (LON:EQLS)
Centaur Media (LON:CAU)
National World (LON:NWOR)
Journeo (LON:JNEO)
Eagle Eye Solutions (LON:EYE)
Inspecs (LON:SPEC)
EKF Diagnostics Holdings (LON:EKF)
OnTheMarket (LON:OTMP)
Supreme (LON:SUP)
Ramsdens Holdings (LON:RFX)
Ashtead Technology Holdings (LON:AT.)
Flowtech Fluidpower (LON:FLO)
Volex (LON:VLX)
Tatton Asset Management (LON:TAM)
Frenkel Topping (LON:FEN)
<yawn>
The Paul Shill Show was not persecuted away. He took a massive childish huff with people disagreeing with what he said in terms of investment content (I'll own up to being that bad guy) and then others suggesting he should be much clearer about what he's (paid) promoting and what's his personal view. Stocko is an investment view and discussion platform after all that we pay to participate in, not a free to use platform we've got to accept advertising (...and he was advertising not analysing!).
He's all over social media so it's not hard to find his 'wisdom' if you really can't live without it.
I've not asked for him to be deselected or whatever from Stocko...but I will post disagreements with him if he promotes companies that I think have dodgy history (eg Venture Life (LON:VLG) ) that he's not dealt with in his promo, or talks macro nonsense about stuff he clearly doesn't understand (eg VIX) implying others should follow his inshite. Is that unreasonable?
He's not here as he probably prefer mediums that don't permit counterpoints so easily...
Umm. I see being a bit sarcastic/humourous gets one red-flagged here. Interesting juxtaposition to what is being supported. But hey, up to the individual.
I tell people when I disagree with them...so if the flagger wants to tell me my sin then that would be great
Nice one.
It all depends if you offend their holdings!
About 2 years ago I wrote that most of the shares suggested in the Small Cap Report , were heading south and I have urged holders to exit and go 50% cash. I was attacked ( from all sides) , and some of the comments were embarrassing to read.
We all know what happened though. Some of these shares are not even listed now and most of them have lost over 80% of their value.
But I have to say that I can see a lot of improvement by the writers of this report , and this is one of the reasons I have renewed my subscription.
Thanks
Well...I'm a bit ornery sometimes. I accept that.
I do actually like people disagreeing with me though. I will probably tussle back...but I think the disagreement, with a bit of info in it obvs, is useful. We are all egotistical (me for sure) and sometimes its hard to accept the negative pushback. But often it gestates and surfaces down the road.
Share investing is a funny game where people do take disagreement with their stocks at a very personal level sometimes.
It's your style that's unreasonable. You couldn't help but have a dig at him in this post either, Stick to your point, drop the pejoratives, they're unnecessary.
Duplicate deleted
There is a real problem on Stockopedia with people promoting youtube channels and ramping stocks. What is needed is active moderation to maintain (well, gain) quality standards. If they won't do that then they should at least permit us to filter out the shills.
Instead we had the childish "lets all be nice to each other" gesture of removing downvotes.
I pay a subscription I should be able to choose what I see and filter out what I don't want to. To recap, we need moderation, filtering and the restoration of downvotes.
Well I for one really enjoyed listening to the Vox videos and although I appreciate they are freely available on YouTube , I appreciated the convenience of Paul posting them here, and his feedback .
Who cares whether he is paid or not ? It’s the company individual I am listening too , such as the very impressive, Judith McKenzie and surely it’s all part of DYOR to understand that Paul and Vox are running a business not a free investment chat show for everyone !!
TL:DR - Some of the points raised are valid, but squandered through rudeness.
To be fair, one should be transparent about what one is being paid for, and one should be transparent about any positions one holds in a company one is commenting on. A lot of the arguments about "is this advertising" or "talking your own book" go away at that point. I would suspect, though I am an idiot and likely to be wrong, that the laws that protect consumers, such as the advertising laws and market abuse regulations, would mean if the accusations are true there would be legal ramifications. I take pages like this for guidance, happy to be told where I am wrong or naive:
#Ad(vice) – Making clear that an ad is an ad - ASA | CAP
Also, he (and others) post under their own names. It's notable (yes, I'm a hypocrite) that those using language they wouldn't use to someone in the pub, because doing so would have consequences, are hiding behind anonymity
I tend not to listen to Paul’s own views so much as I do his guests. And that is obviously because mainly we know his guests or employer own the shares they are discussing . If that is not clear, then I am still interested to listen what they have to say, but not with the same conviction. To me, it’s all part of DYOR. And it’s free !!!
I like VOX videos, they quite often get me looking at a new company. Thats the point of them I suppose so they do a good job, as long as you understand you'll only hear the bull argument. Surely thats obvious tho.
One thing theyre very good for is showing private investor sentiment. Justin Waite was on a one man mission to show in video form what an investor sentiment cycle looks like.
The usual emotions over 18 months-
Just a dip > Denial > "im a long term investor anyway" > Anxiety (but I'll style it out) > "I only hold 5 stocks which I have the most conviction in" > Panic > "Cant believe it, these are great businesses" > I dont agree with stop losses> Too late to sell now > Capitulation > Blame.
Capitulation and blaming the government/Fed/banks/CEO happened right at the bottom in September/October.
Useful to go back on youtube and look at what guests were saying around September/Oct. One or two were very good, stayed calm and called things well. The rest are safe to ignore going forward.
That's fair and up to you Caper4. I'm not aware that Paul Hill has been stopped from posting. I believe he chose to do that...hence why I said he'd taken the huff.
TBH if you are going to be an active stock promoter (v different from analyser IMO) then you should be able to take some disagreement/objection.
So what's the deal? Paul Hill should post rampantly here and we should all have awed hush? This all seems rather silly...and like has been said, if he can't 'take the very moderate heat' here then you can easily find all the same stuff in other places!!
Thanks for posting, footnote made old Ernie laugh
Thanks for the weekend podcasts Paul. They are really interesting, so thanks again for all the effort and time in making them. Essential listening for me and many others.
Looking forward to hearing the Q+A with the excellent management from Sosandar (LON:SOS) on Mello this evening. I hold a decent chunk and will be adding. I see this as a well-run growth story that has a plan and is sticking to it. Nice margins, more partners coming on board and growing brand awareness and uptake. International expansion? Hopefully, hear more about that later today. ASOS on the other hand are down heavily today after a broker downgrade this morning. ASOS and BOO have vanishingly thin margins and therein lies their problem. Obvs.
Hi Raleigh4343,
I'm also looking forward to hearing from Sosandar (LON:SOS) management at this evening's Mello webinar. Although I know the story very well already. It's reached profitability already, and the growth now looks to be pivoting towards international, with a low-risk approach to this (no physical stores, and selling through online partners). The UK business has done very well through partners, with the big 5 being: Next, M&S, J Lewis, Very, and SEWNEM (someone else whose name escapes me).
I think SOS shares have suffered recently possibly due to some investors imagining that there could be read-across from poor results by ASOS, THG, and Boohoo also looking wobbly. Personally I don't think that's right, because Sosandar is serving a different part of the market, with a more affluent client, and increasingly strong brand loyalty. Although SOS does have very tough comparatives to compete against itself this year.
For me, Sosandar is now a coffee can stock, with an intended holding period of 5-years for me, after a recent purchase (which I may well add to). I think it's important not to lose sight of the bigger picture by over-analysing short term metrics. If international expansion works (and I can't see any reason why it wouldn't, as British brands can do well overseas), then the addressable market is dozens of times the UK market, where Sosandar has created a credible brand that is performing well, from scratch, in only about 5 years. Imagine what could be done overseas in a similar timeframe? It's a genuinely exciting business I think, although totally dependent on the 2 ladies running it.
Regards, Paul.
Thank you. I agree and think that in 2 years that SOS will be a more significant company that will attract more institutions and possible offers. I am mindful of growing pains and problems, but I have confidence in the management to ably deal with them along the way.
SEWNEM - new deal with Sainsburys
Guys, any chance of a quick review on UJO who announced their results today. $1m income every 5 weeks, maiden profit, debt free, paying dividend + doing share buybacks. SP 1/3 down on 2 years ago when had no income. Doesnt make sense Cheers
Oil companies are not covered here.
Union Jack Oil (LON:UJO) average shares have increased sevenfold in 7 years. So what’s the point of buying back a few now?
They did a share consolidation a year or two back. Results are great, can only think the selective buybacks are holding the SP back
Union Jack Oil (LON:UJO) are a small UK onshore oil exploration company. You're right, there is a poor hostory of dilution and the share count has increased considerably. There have certainly been accusations over the years that they were a lifestyle company.
However they did actually strike oil and one of the fields they have a share in is now in production, so they are now profitable and paying a small dividend. It's not a big field - the oil is taken away by road tanker - but there is more potential in the other fields that they don't have planning permission for or haven't completed the exploration.
So there's good reason to believe the dilution has stopped - they even say so in the RNS today - and there is a potential re-rate if they get one or more of the other small fields into production.
They have another small project in hand to generate electricity from gas on-site to supply to, it seems, one commercial scale user, but I'm not expecting that to be that significant.
I hold - by far the smallest holding in my portfolio - so just a dabble. Very much speculative.
It makes sense if you know the history and who runs the company. It is my opinion to stay away (as far as possible) from UJO plc.
Thanks
Many thanks Paul for your weekly podcasts and all the effort you put in. Much appreciated. I mainly invest in small caps as I enjoy the challenge. Times are tough at the moment when even good companies are treading water and any slight warning severely hits the price. However I agree with you that in the longer term say 2 years hence things will look much brighter. Positivity is key, some stocks will suffer but many will succeed and we all hope we have picked the right choices.
Good morning Paul,
I would welcome your thoughts on the 2 RNS’s this morning from Instem (LON:INS) . This is a software company specialising in the life sciences sector and is already utilising AI, which is helping in the reduction of animal experimentation in drug development. Today along with their results they announce the following:
“Instem plc (AIM: INS), a leading provider of IT solutions to the global life sciences market, announces that the Company has been granted exclusive rights to transition the ToxHub Platform (the "Platform") from eTRANSAFE.
The Platform, which has benefited from c.€41m investment to date and has been designed to speed up the development of medicines, will be commercialised by Instem following integration into the Company's unique in silico suite, which it has rebranded as Centrus®.”
The whole RNS is well worth a read rather than me reiterating here, but this does sound very interesting going forward. There is an Investor Meet Company presentation scheduled for 4pm which I shall be watching as a long term share holder.
Hi shopping 365 and mammyoko,
I have held Instem (LON:INS) since 2019 when I saw Phil Reason (CEO) present at Progressive and also talked 1-1 with him afterwards. It developed into a core holding as I gained confidence and understanding. I continue to communicate with him on a regular basis.
Management have always done what they said, are passionate and loyal. They are excellent acquirers who know their industry inside out, buy the best of breed and look after their employees well, as evidenced in the salary increases made in H122 post acquisition and inflation so all employees are treated equally. Clients are the largest pharma in the World
I was very pleased with today's update as it shows the strategy set out when raising money in 2020 to scale the company was successful. The raise was at a very slight discount to the prevailing price and unlike most placings, the SP did not drop below the placing price. As well as excellent 2022 results being confirmed, the outlook statement said FY23 had started well, the pipeline is strong and there is no sign of evidence of slowdown of investment from Pharma.
I like the sector of picks and shovels for drug development as it is not reliant on drug approval and there are massive sector tailwinds and it is high gross margin so companies can profits easily. I do not like to invest directly in drug development as it is highly risky as most drugs are NOT roaring successes. I also have had a core holding in Cambridge Cognition (LON:COG) since 2020 and Diaceutics (LON:DXRX) since December. All 3 have strong balance sheets with cash, are growing quickly and have excellent management teams who I have regular access to. I have less experience with DXRX so far but the large management shareholding gives me confidence and also that I have talked with them directly. DXRX will be presenting on Mello tonight.
I am naturally biased as a holder so DYOR.
Michael
Instem (LON:INS)
I’m a fan of everything about the name except the liquidity. And for that reason I’m not hanging around, with so many alternative, liquid and equally profitable life science picks and shovels plays to switch into. Despite the solid update and good prospects I have WITH REGRET sold down two thirds this morning and have 2000 more for sale in an open market order. No takers so far and the paltry volume on a day of decent news underlines my concerns. It’s all very well being a long term holder but I like the option to alter position size on days other than TU dates and when it’s not even possible then, the name is not for me. Good luck to holders. I think it’s a good company in a terrific sector.
I agree with the positive views on Instem. I see the company as a serial aquirer of small B to B niche software and technical companies in a highy fragmented area of a global industry so the runway for growth is almost unlimited. However, the sale of Samarind is a reminder that not all Instem's aquisitions have a been successful. The ROCE has been unexciting up to now so I hope this figure improves.
Half year results from Instem (LON:INS) . You have previously given this a 'green' rating, I think, Paul.
Adjusted EPS was 31.3p against a consensus of 25.2p. I would expect 2023 forecasts to rise to, say, 38p giving a forward p/e of 18 which seems too cheap for a company with good management and growth prospects. They separately announced the acquisition of the ToxHub platform which has had £41m invested in it for no consideration. They already signed up Bayer to the platform. The company has summed up this acquisition as follows:
Following an initial period of investment, the Company believes there is potential for significant revenue growth and EBITDA contribution from 2025 onwards - building from a modest base in calendar year 2024.
The initial investment is in the region of £2.5m.
This is an area which could easily see consolidation and the company are hinting at this. The shares have been up at over £9 in the last three years on much lower profitability.
There is a small pension deficit requiring contributions of £0.6m per annum through to September 2026.
I think the risk/reward looks quite good. The shares are a little illiquid but there is firm support on level 2 this morning.
I hold and have added this morning.
what do you guys make of CURYS trading statement today?
https://www.londonstockexchang...
Hi bensummers - just going to take a look at Currys (LON:CURY) next.
Roland
I'm also hoping to be on a Currys conference call later if there are any particular questions. It looks a creditable performance in light of Restore's comments too.
As an aside John Wood (LON:WG.) Apollo walked away from this deal too following THG (LON:THG) last week. Trading 100p below the last cash bid they made. I presume risk arb funds are cutting positions.
Hi MH1,
It's good to get Roland's perspective on Currys (LON:CURY)
An additional worry I have, is that CURY has a terrible balance sheet, once intangible assets are written off. This means the whole business is totally dependent on trade creditors being prepared to extend it very large amounts of credit on purchases of stock - so the company sells many items for cash, before it has paid the supplier. That's fine for as long as suppliers are prepared to let CURY have goods on tick. Often there is a trade credit insurer assuming the risk, which is really a hidden form of debt. The trade creditor insurer will do similar testing of the accounts as any other lender, and credit can be withdrawn without warning, at any time. That then often means suppliers won't send in any fresh deliveries of goods, unless they are paid up-front.
So, given that the main banker is relaxing covenants, then I wonder if trade credit insurers might also tighten their lending criteria? This is the big hidden risk with CURY. Trade credit insurers are more important than the main bank lender. So what they do in future could make or break the company. Too risky for me!
Regards, Paul.
Cerillion (LON:CER) keeps delivering. Do listen to Paul's excellent interview with Louis Hall, CEO, which gives insight into management. Here are the top line of the H123 results from this morning:
We have a webinar with Louis Hall, CEO & Andrew Dickson, CFO on Friday 1.15pm. Register here.
Good morning Paul and Roland. There's an interesting TU from Centralnic this morning which perhaps reveals your Amber almost Red comment on the 24th April Paul. We hold and your comment has put me on alert. Confident outlook declared today with Rev +24% adjusted Ebitda +16% operating profit - 23%. Adjusted EPS +23% and share buyback of £4 million planned. I'd appreciate a comment if either of you get time today, it's too complicated for me which should tell me something anyway!
Morning JASVFS - see comments on CNIC later in this comments section. I'll try to have a fresh look at CNIC today, and am hoping to meet mgt at Mello next week.
My morning smallcap tweet: Profit shredders and cheer spreaders
BSF Enterprise (LON:BSFA) Restore (LON:RST) Sondrel (Holdings) (LON:SND) WANdisco (LON:WAND) Journeo (LON:JNEO) Frp Advisory (LON:FRP) Global Ports Holding (LON:GPH) Eden Research (LON:EDEN) Malvern International (LON:MLVN)
◄BSF Enterprise (BSFA)► makes samples of lab-grown leather. [SP=NA Cap=NA]
◄Restore (RST)► warns FY23 adj pretax £41-43m, below mgmt exp. Blames lower IT market prices. Guides rev up over 5%. [SP=293.5 Cap=402m]
◄Sondrel (SND)► guides FY22 rev up 116% and adj EBITDA in line with market expectations of £1m. [SP=54 Cap=48m]
◄WANdisco (WAND)► plans $30m placing towards the end of June. Has cash until middle of July. Will remain suspended until after fundraise. [SP=NA Cap=NA]
◄Journeo (JNEO)► wins £0.9m order with rev booked late in Q4 2023 and early Q1 2024. Included in mgmt exp for FY23. [SP=172.97 Cap=28m]
◄FRP Advisory (FRP)► guides FY-Apr rev £104m (up 9%) and adj U/L EBITDA £27m both slightly ahead of market consensus of of £100.5 million and £25.8m. Outlook positive. [SP=110.5 Cap=276m]
◄Global Ports Holding (GPH)► guides FY-Mar rev up 66% and adj EBITDA $72.7m ($7m). 9.2m passengers. Guides FY24 11.8m passengers. [SP=165.5 Cap=106m]
◄Eden Research (EDEN)► Mevalone authorised in New Zealand. [SP=NA Cap=NA]
◄Malvern (MLVN)► five year student recruitment partnership agreement with the University of Chichester. "Malvern appointed as a global Representative Agent to support the University's international strategy and provide support services..." [SP=16.1 Cap=4m]
CentralNic (LON:CNIC) update 'at least in line' with expectations today although Q1 statutory profit is down due to non-cash charges like amortisation.
Which brings me to a question I want to get views from the Stockopedia community on. The market is simply not rating CNIC on a decent multiple of its *adjusted* profits which is making me think I am being too comfortable with their adjustments. Edison expects the company to make a statutory loss again this year, mostly due to $19m exceptionals (presumably hangovers from previous acquisitions?) and amortisation of acquired intangibles is still at $36.3m.
What's the view re whether ok to exclude amortisation? Would love Paul and Graham's thoughts.
Some people say acquisitions are part of its business model so you need to include those costs but the Board announced a change of strategy at the end of the last year and they are focusing on reducing debt and shareholder returns now.
Thoughts? (I hold)
ive commented a number of times here that cnic's balance sheet is far too loaded with intangibles and that they will have to write down the intangibles in every report, which will depress earnings for a long long time. even though they've written down 9m of intangibles in this quarter, intangibles are still £342. in my view they should just do one big write down and get it over with.
Hi PatrickL,
I've also got balance sheet concerns about CentralNic (LON:CNIC) - I recently reviewed the 2022 results and last trading update here on 24 April 2023. All the profit comes from adjustments, and as you say, the earnings multiple suggests the market doesn't believe the adjusted numbers at this stage. The horrible balance sheet also puts me off.
But above all, I still don't understand what CNIC actually does! If mgt can't explain their activities in plain English, then that really puts me off.
Incidentally, an adviser to the company reached out to me, and asked me if I'd like a meeting with CNIC mgt to go through all my questions, which I've accepted, so we're hoping to set something up for when they're at Mello Chiswick next week. That's also a good opportunity for everyone else here to speak to management, see a presentation, ask them questions, so it would be good if several of us grill mgt, and compare notes here afterwards perhaps?
After all, the current bear market in small caps could be presenting us with a buying opportunity? I'm not convinced that's the case at the moment, but we'll see.
Regards, Paul.
Hi Paul, this two minute video gives an insight to the CentralNic (LON:CNIC) advertising model. There are longer explanatory videos available covering all aspects of their business. Perhaps it's a concern if they have to explain at all, but CentralNic perhaps deserves some recognition for engagement, including Mello, Investor Meet etc.
It's impossible for me to attend Mello personally next week but I'd be interested in you exploring with management their shift in direction, (change of CEO, less aggressively acquisitive, more focused on shareholder return with debt reduction plus intro of share buybacks and a maiden dividend) and how this might relate to your investment concerns - perhaps the new CEO and CFO share the same concerns as subscribers and your good self.
I hold and watch like a hawk, the stock rankings have certainly turned more bearish since the strategic redirection.
TEIN
Morning both, If CentralNic (LON:CNIC) are actually loss making and all the profit comes from adjustments then where is the quarterly free cash flow coming from that is paying down debt, paying for a dividend and paying for the share buyback?
The FCF /FCF yield looks fairly decent to me (if I'm correct in saying it's doing >$10m per quarter?) Is it wrong to focus on a statutory profit figure?
Re the balance sheet, I'm wondering why the cash balance hasn't been used to reduce the debt load given it was only supposedly held in order to pursue the acquisition strategy ?
What I do find strange is the investor community is now less keen on CNIC as it seems to be moving towards a company focused on shareholder return. It's too complicated for me but certainly interesting so v much looking forward to the Mello interview !
I am nowhere near clever enough to interpret the CentralNic (LON:CNIC) balance sheet, but do listen to Paul's thoughts.
Also, with so many others voicing concerns around about Jan/Feb I got jittery and decided to sell out and invest somewhere else - shame I didn't do this on so many other companies!!!
I've come to the conclusion that whilst I will continue to develop my investing skills I will avoid anything overly complex and/or which I cannot explain to myself what it is that they do. With so many other opportunities out there why take the risk at this point in time.
I am not a technical investor, but looking at its daily chart there is definitely a case for waiting for it to up-trend for anyone looking to buy into it. If only I had followed this advice on many others.
Good luck in whatever you decide.
HI Patrick,
Acquisition-driven amortisation costs should definitely be adjusted out of earnings when valuing a company. Nobody sensible would include balance sheet intangible assets in valuing a company, so why would you include the amortisation cost of those intangible assets?
The cost of the acquisition is already included in full on the balance sheet, whether it be through a reduction in cash, an increase in shares, or some combination of the two. With regard to the benefit, what matters for valuation is the future cash flows from the combined businesses, not projected profits that include a somewhat arbitrary non-cash adjustment for amortisation.
Apollo have walked away from John Wood (LON:WG., I guess shares fall back to 160-170 area....150 pre bid....worth keeping an eye on. Sector lost its shine but still long term attractive IMO. No details on what happened as you would expect.
can not get a price on from HL
Share price is 144.9 to buy on IG group (LON:IGG)
WG has fallen back to where it came from, as you said around 150. It has been around for decades, advising on oil and gas developments, based in Aberdeen but I am sure extremely international though Tory policy on 'windfall' tax is crippling N Sea investment. This is really a pretty specialised area but I would also love to hear the vews of somene who knows the copany and business. My ancient memory is that this was a highly respected outfit.
Apollo, however, seems to be a disgrace. Do they really have that much money under management? I hadn't heard of them until recently but they will have cost a lot of people and businesses a lot of money.