Small Cap Value Report (Mon 16 Aug 2021) - MWE, AVON, TEK

Morning all, it's Paul & Roland here, with the SCVR for Monday. Welcome back Roland!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to cover trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Agenda -
Paul's Section:
Avon Protection (LON:AVON) - profit warning from Friday seems temporary/fixable supply problems, rather than a lack of demand. So might be worth a closer look? Probably priced about right.
Roland's Section:
Mti Wireless Edge (LON:MWE) - this radio technology group has reported a strong set of figures today. It’s an overseas AIM stock, but it’s ticking quite a few boxes for me.
Tekcapital (LON:TEK) - This Oxford-based intellectual property specialist has released record results today. There’s a history of dilution, but profitability appears to be impressive.
Paul’s section
Avon Protection (LON:AVON)
2132p (down 28% on Friday) - mkt cap £661m
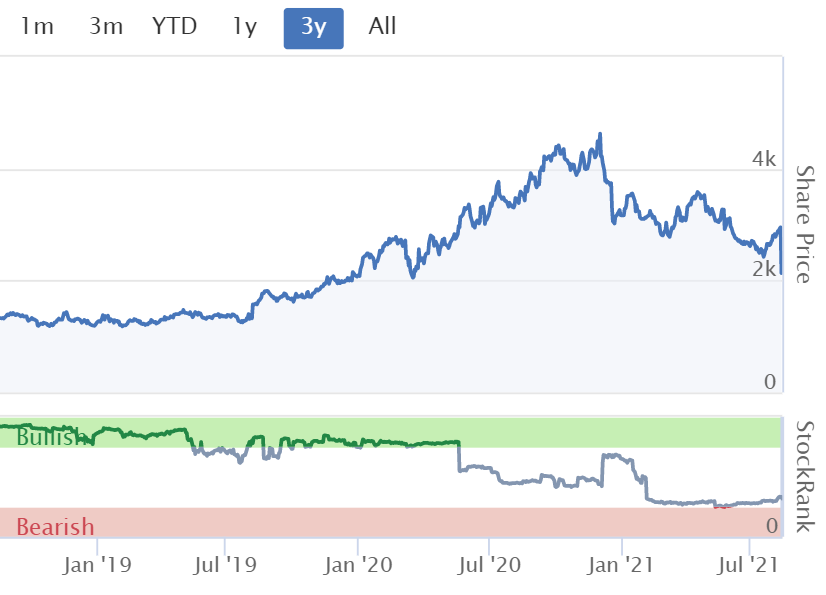
Shareholders here have had a rough time since AVON shares peaked at about 4635p in Dec 2020, having more than halved since then - opposite to the general market, which has done well over that period. It’s dropped back into our under £700m market cap territory here at the SCVR. As there’s not much news today, this profit warning from last Friday looks more interesting to cover.
Avon Protection plc ("Avon") today provides the following trading update for its current financial year ending 30 September 2021 ("FY21").
Positives -
- “Good commercial progress” in H2
- Order intake over 10 months to 31 July 2021 up 13%, at $221m
- Order book currently up 21% on LY, at $146m - this includes the the benefit of an acquisition called Team Wendy, bought in Nov 2020 for $130m
Negatives -
- “Delays in receipt of orders” - e.g. $16m order delayed due to “procurement bottlenecks”
- “Supply chain disruption” - e.g. extended lead times in obtaining components has delayed shipment of a $6m order
- “Tight labour market” in US
- Build up of inventories and receivables, with poor cash conversion of 50% (i.e. only half of profits turning into cashflow) - expected to unwind in FY 09/2022
- These problems are said to be temporary, and covid-related
- Revised revenue guidance - $245m-260m
EBITDA guidance -
The result of the lower revenue expectations, combined with an adverse mix effect and an overhead base that is fixed in the short term, means that adjusted EBITDA margin guidance is expected to reduce to between 17% - 18% for FY21, before recovering thereafter.
Outlook -
The Board is confident that the delayed orders will be received over the coming months, but expects supply chain disruption and a tight U.S. labour market to persist into next year. As a result, the Board believes it is prudent to take this into account and reduce FY22 revenue expectations to $320m - $340m, whilst maintaining current guidance for FY23…
These issues will be resolved over the coming months, but as they are affecting both our customers and suppliers simultaneously the situation has significantly limited our operating agility in the short term.
We remain as confident as ever about the medium-term prospects of Avon Protection, underpinned by a record order book, a growing and visible contract pipeline and world leading businesses and technologies. We will carry significant momentum into next year, which will also benefit from a strong ramp-up in the Ballistics business, and remain well set for growth in FY22 and beyond."
Broker updates - I can’t find any updated forecasts, expect them to feed through into consensus numbers shortly.
Since FY 09/2021 has been impacted by these various delays, then I’m inclined to value the shares on FY 09/2022 forecasts. That runs the risk of over-valuing the share, as it does say that supply problems are expected to continue into 2022.
We’ve got 121p EPS as consensus forecast for FY 09/2022, so at 2132p per share the PER is 17.6 - seems reasonable.
My opinion - if we have to endure profit warnings, then the best type are like this - temporary supply disruptions, whilst demand remains strong.
It’s brought the valuation of the company down to what seems about right to me - goodness knows why it reached over double the current level last year?
Last Interim results - I’ve had a very quick skim of the numbers, and spotted two noteworthy points - a hefty $96m pension deficit, and that capitalised development spend looks very high. Apart from the pension deficit, the rest of the balance sheet looks OK.
Overall, I don’t know much about this company, so don’t have an opinion either way on it. Although I’m leaning towards thinking the 28% drop on Friday, on problems that should be temporary, could be more of a buying, than selling opportunity? It’s not cheap enough to tempt me in though.
.
.
Roland’s section
Mti Wireless Edge (LON:MWE)
76.5p (pre-open)
Market cap: £68m
Mti Wireless Edge (LON:MWE) is an Israel-based company that specialises in radio technology - primarily antennas for mobile and other types of network. Here’s an example of a recent military contract win.
MTI also has a division which sells wireless control systems for irrigation.
Today’s interim results appear to confirm the attractive qualities of the business and show further progress.
Investor seminar: MTI Wireless Edge is hosting an investor seminar on the Investor Meet Company platform at 10am today. I’ve found the IMC platform easy to use and an excellent way to get some additional insight into a company’s operations and its management team. I plan to dial in later and will try to add in a comment here if anything interesting arises.
I’ve become interested in this business recently because it’s appeared on a number of my screens, thanks to its solid balance sheet, attractive profitability and good cash generation. MTI shares have also performed well this year - the stock is not so obviously cheap as it might have been a few months ago:

I should probably point out that this is an AIM-listed overseas stock, so might be considered slightly higher risk than some UK firms. However, MTI has been listed in the UK since 2006 and benefits from owner management. The group also has a track record of dividend payments. So I wouldn’t rule it out automatically on the basis of its overseas status.

Let’s take a look at today’s numbers.
“Another positive trading period”
Today’s interim results strike a positive tone, which appears to be supported by a strong set of numbers. Here are the financial highlights:
- Revenue +9% to $21.3m
- Operating profit +14% to $2.2m
- Earnings per share +14% to 1.89 US cents
- Cash flow from operation +52% to $3.1m
- Net cash +28% to $9.7m (versus June 2020)
- Annual dividend +25% to 2.5 cents per share (paid 31 March - MTI only pays a single dividend each year)
The company’s financial results are refreshingly free from adjustments - nice to see.
MTI’s business is divided into three operating divisions, all of which made progress during the first half of the year. The accounts include a full segmental breakdown of revenue, profit and assets, which again is nice to see. Some larger businesses do not provide this level of visibility.
Antenna: This business makes radio antennas for 5G mobile applications, including network backhaul, vehicle, marine and military use. A recent contract win will see the company develop a new range of space antennas. Management says this is a new market “and one perhaps which the Company can expand into”.
The Antenna business generated 27% of revenue but just 12% of operating profit during the half year. Segmental margins were low, at just 4.3%.
This manufacturing operation does not appear to be as profitable as some of the group’s other divisions, but presumably it does benefit from intellectual property assets.
Sales growth during the first half is said to have been in line with the company’s internal targets.
MTI Summit Electronics: This is MTI’s consulting and distribution business. It sells products from approximately 40 international radio/microwave component suppliers to Israeli customers.
MTI Summit generated 40% of revenue and 42% of operating profit during the half year, with a solid 10% margin.
The business serves defence and commercial customers, but my feeling is that the main market is defence. MTI Summit also has a satellite office in Russia.
Commentary on trading is fairly general, but management reports “new orders from a number of significant military customers”.
Mottech: This business sells wireless systems to manage irrigation and water distribution for agriculture and other markets. Mottech’s products combine Motorola hardware with the company’s proprietary management software.
Mottech is expanding in Canada and Australia and also appears to have a significant client base in France - its Tethys system is installed in vineyards covering more than 6,000 hectares.
2021 is said to have been “another good trading period”. Somewhat surprisingly (to me), this is the most profitable part of the group.
Mottech generated 33% of revenue but 45% of operating profit during the first half of the year. The operating margin for this business was a healthy 13%.
My view
I like what I’ve seen of this business. Today’s numbers suggest to me that the steady growth seen in recent years is continuing:

I’m also encouraged by the attractive profitability of this business - note the steady progression of return on capital employed:

The balance sheet has consistently shown net cash in recent years, too.
Valuation: Consensus forecasts in Stockopedia show the shares trading on 33 times 2021 forecast earnings, falling to 30 times 2022 forecast earnings. Annualising today’s figures would give earnings of 3.6 cents per share for 2021, versus 3.2 currently shown on the StockReport.
Interestingly, I’ve seen forecasts elsewhere suggesting a figure of c. 4.5 cents per share for 2021, so I’m not sure whether the Stockopedia numbers are fully up to date.
Today’s management commentary doesn’t mention any upgrade to expectations, so I’m guessing that the outlook for earnings is broadly unchanged. That seems to be supported by the share price reaction -- the stock is flat in early trading.
In this case, I’m inclined to value the business based on its trailing 12-month earnings yield and dividend yield, rather than P/E.
- Earnings yield: 4.8%
- Dividend yield: 2.4%
These ratios suggest to me that the stock is fully priced, but not especially expensive, if growth can be maintained.
I remain interested and may consider operating a starter position - subject to further research - at this level.
Tekcapital (LON:TEK)
24.5p (+1% at 08:50)
Market cap £31.7m
This Oxford-based firm specialises in working with universities to commercialise intellectual property. It’s a new stock for me, but looks potentially interesting - so thanks to the subscribers who suggested it in the comments.
TekCapital highlights a number of its portfolio companies in the results. I’m not familiar with any of them but they appear to cover a wide range of sectors:
- Medical devices (Belluscura)
- Bluetooth sunglasses (Lucyd)
- Air traffic control software for drones (Guident)
- Reduced salt crisps (Salarius/SaltMe!)
I note that Lucyd sunglasses have had mixed reviews online - e.g. here. The lack of audio privacy seems a big downside to me, but otherwise I can see this could be an attractive product.
I’d imagine that anyone considering an investment in Tekcapital would want to spend some time gaining a much more in-depth understanding of the company’s asset portfolio. That’s outside the scope of this report, so I’ll concentrate on reviewing the numbers for now.
“Record results for the period”
Today’s interim results are modestly headlined “record results for the period”. This is certainly true, as far as I can see. But I think we should probably mentally caveat this with a reminder that half-yearly profits from Tekcapital’s operations can be quite lumpy. Here’s a snapshot of the pre-tax profit since 2016 to show what I mean:

However, on an annual basis there is a much cleaner progression, so I’m encouraged by today’s numbers:

Let’s take a look at today’s interim results, which cover the six months to 31 May 2021.
Financial highlights
- Net assets +56% to $51.1m
- NAV per share +11% to $0.39 (note the impact of dilution)
- Revenue $14.5m (H1 2020 $2.9m)
- Pre-tax profit $13.9m (H1 2020 $1.9m)
- Completed a placing of 38m new shares at 10p to raise $5.3m gross in March 2021.
- Cash position of $2.5m at 31 May 2021.
There are a couple of points I think are worth highlighting from these numbers.
Revenue: Reported revenue for the half year of $14.5m is a substantial increase from the $2.9m reported during the same period last year. However, most of this increase came from a $13.8m unrealised revaluation gain on Tekcapital’s assets.
Around $9m of this reported increase came from the IPO of medical device firm Belluscura (LON:BELL), which floated on AIM in May. This holding was booked at $2m in November but valued at $10.8m when Belluscura floated at 45p.
Belluscura shares have since doubled from the IPO price of 45p, suggesting that Tekcapital’s holding (if it hasn’t sold any shares), could be worth more than $20m today.

However, although Belluscura’s market cap has soared to £100m, this business does not appear to have any material revenue or profits. I’d want to do further research to understand the valuation here.
Returning to Tekcapital, the group says that revenue from services (i.e. actual billings) rose from $557,684 in H1 2020 to $715,753 in H1 2021. That’s a healthy 28% increase, but still a fairly small amount.
Pre-tax profit: In a similar way, Tekcapital’s pre-tax profit of $13.9m is almost entirely driven by the unrealised revaluation gain on assets. Excluding this non-cash item, my sums suggest an operating loss of $823k for the half year.
Net asset value vs NAV per share: Despite rising headline revenue, it’s clear that this business is still in cash-burn mode. This is reflected in the share count, which has risen from 30m in 2015 to 130m today.
The dilution suffered by shareholders is reflected in NAV per share, which only rose by 11% despite the 56% rise in reported net asset value.
Incidentally, the latest fundraise saw 38m new shares issued at 10p in March. Congratulations to buyers then, who have already enjoyed a 150% return.
However, longer-term shareholders have not done so well. At 24.5p as I write, the shares are worth less than they were five years ago:

Until Tekcapital can realise some material income or capital gains from its assets, I would suggest that there’s a continued risk of further dilution.
Cash burn in 2020 was $2.3m. Today’s figures show this outflow increased to $3.1m during the six months to 31 May 2021.
Insider shareholdings
Chairman and serial entrepreneur Clifford Gross retains a fairly modest 6.6% shareholding, according to Stockopedia. Tekcapital’s second-largest shareholder is well-known UK investor Nigel Wray:

My view
Tekcapital appears to be making steady progress with its strategy of commercialising university discoveries. However, group’s reported profits appear to be entirely derived from unrealised valuation gains, often on unlisted early-stage businesses.
For me, this is too speculative to be of interest. I’m wary of attributing too much value to unrealised valuation gains when they aren’t backed by cash flow or even revenue.
I can see that Tekcapital could have significant potential, but I’m also concerned about the risk of further dilution for shareholders. I don’t feel able to value this stock, so I’ll watch with interest but won’t get involved.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Well I am really looking forward to the next few months as I have now read Simon Thompsons analysis of the Tekcapital (LON:TEK) numbers. Simon originally suggested buying Tek's shares at 15.5p in June this year, with and end of year target of 25p. He has now raised his target to 35p and still therefore a BUY.
Best Of The Best (LON:BOTB): regarding director selling, one think I have noticed on the Yahoo Finance Insider Traders page: https://uk.finance.yahoo.com/q..., is that a Daniel Burns actually bought 20,833 shares (£691k) at price £33.19 per share on the 1st of April 2021 (same time as when the other directors sold). There is a Daniel Burns listed as NED for Best Of The Best (LON:BOTB), so I assume that's the same person. Not sure why Stocko doesn't pick this up as a director trade?
If this is true, he must be livid!
good spot
Best Of The Best (LON:BOTB) (I hold): Down another 10% today, however, have spotted that MI Chelverton UK Equity Growth Fund have taken up a 5% interested in Best Of The Best (LON:BOTB) this afternoon (477,772 shares). Possibly a small glimmer of hope?
Hi Andy,
Having pondered things over the weekend, I'm coming round to the view that the market has probably overshot on the downside re £BOTB. The business model isn't broken, they've just run into a bump in the road - revenues down 15%, which with hindsight shouldn't really have been a surprise given the ending of lockdown. It's still a very good business, and management have lots of levers they can pull.
The problem with BOTB's business model is that cost of sales are semi-fixed (being cost of cars given away). Hence every £1 of extra or reduced revenues, feeds through almost directly to higher or lower gross profit.
That said, most other costs are variable, and marketing spend can be tweaked up or down as required.
There is more competition now too, and Omaze in particular seems very well funded, and presumably running at a loss in the short term, whereas BOTB has a 20 year track record of being self-funding.
I'm tempted to top up at this depressed price, and given how negative investor sentiment is currently. I think it's likely to recover partially once the dust has settled, although previous highs now look very unlikely.
Regards, Paul.
Best Of The Best (LON:BOTB)
There is more competition now too, and Omaze in particular seems very well funded, and presumably running at a loss in the short term, whereas BOTB has a 20 year track record of being self-funding.
Perhaps one extra thing to worry about (as if we don't have enough) is that the more companies enter this space the more likely it is that the government will decide to treat this activity as most other gambling activities and tax it as such - kinda guesing such a change would probably hit the profit by at least 50% of what they currently have left. Unfortuantely IMHO a change in the law here is easy pickings for the government if they want to raise extra revenues. Practicably speaking there is very little difference betwen spot the ball and roulette and buying a lottery ticket. BOTB really don't need a kicking when they are on one knee but profit warnings do come in 3's as they say.
Hi rmillaree,
I think this is a really good point and only adds to the risk. I think some competition is acceptable, after all, the big betting house remain profitable even though there is quite a bit of competition, so hopefully, that would be similar for £BOTB. But, like you say, regulation could kill profit levels. There is quite a bit of chat now, on last Fridays SCVR around competition. Omaze seems to be more property based driven by a raffel. https://yiannimizecomps.com/ is far closer to £BOTB. They offer a monthly subscription, which reduces ticket prices. Definitely an idea for Best Of The Best (LON:BOTB) to replicate.
Thanks,
Andy
Hi Paul,
re Best Of The Best (LON:BOTB), I agree, I think the price has overshot the downside, as you say. I'm afraid, i'm not brave enough to top up currently, as I think the risks are now too high for me.
However, I am against selling around these prices and the purchase from MI Chelverton, backs that up to an extent. Also, summer is a naturally depressed sales period for Best Of The Best (LON:BOTB), so hoping for far better news with the next trading update.
I'm planning on holding on until the next trading period and selling around £15 (my average purchase price) or up to £20 (if momentum takes hold again) or will bale quickly if the next update is more negative news.
Thanks Andy
The problem with BOTB's business model is that cost of sales are semi-fixed (being cost of cars given away). Hence every £1 of extra or reduced revenues, feeds through almost directly to higher or lower gross profit.
In view of the warnings about availability of new cars by listed dealers, what happens if they can't source any supercars to give away? I would assume the cost of those they do will have increased at the very least. Anyone considered that?
I should point out I have zero interest in Best Of The Best (LON:BOTB) as an investment.
All the best, Si
I am in same boat but I see no light at the end of the tunnel. Why?
1. Competitors like Omaze (+++++) have almost bottomless cash to push out rivals like BOTB. Endless advertising by these competitors (and I include general gambling brands like Gala Bingo etc in this, not just Omaze) must be, and carry on, eating some of BOTB's lunch.
2. Directors are not incentivised to fight back - they sold high and yeppo they knew what they were doing!
3. When households' spending is divided, this biz experiences a boost in lock-down but a paring back during re-opening time - as is the case now.
I don't agree it is oversold.
Hi Roland, I held Mti Wireless Edge (LON:MWE) from almost exactly to today in 2017 adding more twice until getting stopped out 3 years later in 2020. Had I held on I would easily have a double-bagger under my belt today. I didn't go back in because I was concerned about the company helping China with its irrigation control systems. Normally I wouldn't blink where ethics are concerned but viewing Google Earth and zooming down to village level in many places in north-east China such as at Bamianchengzhen district and seeing thousands of collective farms I wonder what kind of life the workers have. I'm more than happy with the 80% profit I made.
Silver
The number of companies that don't help China in some way is probably near zero. Whether it's selling to them or buying from them, it will be hard to find any that don't participate. In your daily life, you will also be helping China. Just in posting your comment, you probably used several bits of technology that had some involvement in China. Taking a stand on irrigation systems seems rather curious and I can't see it benefiting the people you feel sorry for.
Yes, I do feel sorry for them, my dad was a farm labourer and we lived in a tied cottage. He hand-milked the cowherd twice daily 7 days a week until the electric came along and he did everything agricultural in between milkings but I'm not forgetting that the Chinese labourers collectively feed a huge military.
@Silver Moon
I know what you meant but I did smile a bit at He hand-milked the cowherd twice daily 7 days a week
The cowherd is the person who looks after the cows......
Hi Johns, I guess I should have left it at 'herd', still , it made some folk smile and that can't be bad.
Silver
Hi Roland, Thanks for the review. I hold Tekcapital (LON:TEK) after a recommendation from Investors Chronicle a couple of months ago. Now showing a healthy profit, but Chairman Dr Clifford Gross did announce on an investor call on the 3rd August 2021, that we would see more good news before the end of September 2021. I continue to hold :-) .
Hi Roland, thanks for helping with the SCVR again!
Important news today from AFC Energy (LSE code AFC) which is one of my favourite hydrogen fuel cell system developers. (Yes, I did put in AFC with the £ sign and it came up with an Arsenal Ofex designation. Not all systems are perfect, even Stockopedia!!)
The first AFC's fuel cell system following the agreement with ABB, one of its huge global partners, will today arrive for operational integration at ABB's packaging facility in Estonia.
The integrated system will be configured as a high power EV charging product for grid constrained environments with a sizable opportunity to support rapid charging capability across multiple key target markets, including Private vehicle hubs; Charge point operators; Logistics hubs and distribution centres; Public and private urban transportation (including bus depots); Marine (including port and marina charging); and Vertical Take off and Landing Craft (VTOLs).
AFC is also actively working with two very big players in the users and providers of generators on construction sites – Mace worldwide and Altaaqa in the Middle East. One of the attractive features of this market is that the individual unit is small and relatively inexpensive, there are literally millions of them worldwide, and Construction is responsible for 30% of the world’s emissions.
It will be interesting to see how the SPs of UK equipment developers powered by hydrogen pan out in the run up and especially in the wake of the COP 26 UN Climate Change Conference in November. This event will be strongly influenced by the hugely impactful recently published IPCC (Intergovernmental Panel On Climate Change) report which the UN Secretary-General António Guterres describes as "a code red for humanity".
Re. Mti Wireless Edge (LON:MWE) - as a follow-up to my comments above, I thought I'd share a few quick notes I made while on the Investor Meet Company webinar with CEO Moni Borovitz.
Please remember these notes may contain errors on my part and don't represent official comment from the company.
Antennas: I mentioned the low margins in this division in my comments. Borovitz says that this business is currently transitioning from older technologies to newer areas of 5G and RFID. Sales in these areas are now exceeding those of legacy tech. If this can be maintained should pave the way for a return to growth.
MTI works with 4/7 of the main radio manufacturers in 5G mobile. "If they do well, we do well."
Mottech (water controls): Borovitz pointed out that climate change and growing water scarcity support a structural growth story for the irrigation business. He's encouraged by prospects.
Distribution/consulting: CEO Borovitz described this operation as the jewel in the crown for the group. It's said to be the largest RF/microwave component supplier in Israel. Component sales are generally paired with design/consulting services.
In terms of ESG, I'd guess that not all UK investors will be comfortable investing in a business that serves the Israeli and Russian defence sectors. But this does seem a decent business to me.
Customer concentration: in reply to one question, Mr Borovitz said that the group's largest customer was probably 10%-12% of revenue, split across the distribution and antenna divisions. The customer was described as a large defence company that buys a lot of equipment from MTI.
Takeover: seen as unlikely, due to the group's diversity - the sale of individual divisions might be more likely.
Overall impressions: My impressions was of a well-run business with a conservative balance sheet and methodical management. I remain interested but have no position at present.
Re Mti Wireless Edge (LON:MWE) there is possibly a bit of confusion over the EPS as ALLENBY'S note on Research tree shows EPS of 3.2p versus Stocko showing 3,2c for 2021. Not sure which is correct but I think it is probably Allenby. I hold.
Hi Ned,
I suspect you're right the Mti Wireless Edge (LON:MWE) forecasts + that would explain the discrepancy.
Roland
Excellent write up on LON:AVON Paul. thanks. I am a long term holder ( a 10 bagger) so it is most useful to have a fresh pair of eyes cast over it. The one bit I would add to your comments about AVON is that it has a huge moat - e.g. it sells Gas Masks and Helmets to the US Army and Navy. Top sliced a while back so I am going to buy back.
Morning Berksbee re Avon Protection (LON:AVON) and following the debacle in Afghanistan, the orders and sales of gas masks and especially helmets to the US military should only increase, and possibly quite quickly!
Why? Are you expecting the USA to start or enter new wars?
What does pulling out of Afghanistan have to do with needing more military gas masks?
We bought Avon Protection (LON:AVON) on current weakness. Strong moat in a problem-solving niche (see Spirax, Halma etc), robust R&D supported by the US DoD, USD-earner, long-term ROCE > 20% is much higher than the accounts suggest (see Phil Oakley’s analysis in IC), all potentially justifying a much higher than average multiple and the problems appear temporary. This is the third of a series of profit warnings which might signify the point where trading and momentum bottoms. Or not.
I concur. I last looked at it around 2018-2019 where I really liked it but my buy price was lower than market price, so never picked up a stake. Kicked myself as it went from 1300p to 4000p. Kept going through the sums and thought anything more than 2000p was crazy. But it's taken over a year for Avon Protection (LON:AVON) now to correct itself, and at 2100p I've added it to my to do list to re-evaluate.
No rush to buy IMO. Don't see the price going anywhere for a few months, as positive news take time to come and stale bulls will be exiting for a while, given the near 50% loss from the high.
A company in same field TSE:BOS (Airboss of America) still has much better numbers even after AVON (Avon Protection)'s correction. BOS has done well for me this year and I still hold some. Suggest those with access to North American data bases make the comparaison.
TSE:BOS is a terrific recommendation for the rear view mirror but it looks as though growth has topped out. Maybe a cautionary sign for new AVON shareholders like me of course. Thanks for the pointer.
Tribal (LON:TRB) H1 21 analyst presentation from last Thursday. Mark Pickett, CEO & Diane McIntyre, CFO present H1 results, giving an overview of the strategy, financial performance and the outlook. In summary, they have grown annual recurring revenue (ARR) 5%; expanded the market opportunity, with new products and geographic expansion; have a strong pipeline of opportunities with existing and new customers; strong cashflows with continued investment in future growth. With a positive start to 2021, they anticipate the full year will be slightly ahead of expectations. Video & podcast.
Vertu Motors (LON:VTU) join Robert Forrester, CEO & Karen Anderson, CFO for an investor presentation & Q&A, tomorrow Tuesday 17th August, 4.30pm. Register here.
Fairly aggressive note from Science (LON:SAG) regarding their intent towards Tp (LON:TPG) - worth a read just for the entertainment value.
I don’t hold either. TPG is a share that went nowhere for years and I managed to wipe my face on the trade just before the big plunge. Better lucky than good.
Science (LON:SAG) Entertainment value indeed. I do hold - bought at 88p about8 years ago whilst my daughter did a Uni "year in industry year" with them. Everything I heard sounded impressive.
Thanks for the review of MWE Paul, I appreciate your perspective.
I've been looking at it myself and trying to figure out if I want to enter or not. It's on Simon Thompson's list of small caps and he has put up a few write ups of it with the most recent one in June 21.
Hi Will S,
Roland wrong the section on Mti Wireless Edge (LON:MWE) just FYI.
Regards, Paul.
Lack of coffee.... Thanks Roland
Update from £MWE this morning (I am long) shows continued steady growth with revenue up 9% and net profit up 13%. I believe this is still a very exciting company with very exciting prospects in 5G and water conservation which are both very fast expanding businesses.
The share price got ahead of itself last year and is still showing a 90% increase from this time last year which I do not is justified at the moment with 9% revenue growth and it does need to grow into that re-rating. In the meantime I plan to continue to hold. This has already returned 300% to me in the last 4 years so am a very happy holder.
Obviously its foreign owned so doesn't appeal to everyone but has been on the market over 15 years now so not a fly by night company
Edit
I saw you just beat me to it , thanks Paul agree with your sentiments on it.
Morning Paul, any chance you could look at TekCapital, results out today.
I am long on Tekcapital (LON:TEK)
Seemed a very strong update but to me a lot of it is built into the share price today and the increase over the last few months. This is in my top 5 holdings and I believe that at least two of their investments have a lot of room to grow..
Coffee Can for these in my portfolio.
Tekcapital (LON:TEK) I hold following Stock Slam presentation in April:
Alex Schlich: Tekcapital (LON:TEK)
Small-cap investment group specialising in commercialising university IP around the world. Has made four key investments with the aim of tapping large potential markets with good management. Price fall in March caused by a discounted equity raise - but they do have sufficient cash and are likely to be selling portfolio businesses soon.
Hi CheshireUK,
I'll take a look at Tekcapital (LON:TEK) now.
Roland
Not a small cap, but Cobham and their PE backers have now made a recommended all cash bid for defence sector company Ultra Electronics Holdings (LON:ULE) at £35 per share plus an in train 16p dividend. 60% plus premium to various benchmarks. I hold. Plenty of commentary about jobs, national security undertakings etc..
https://www.investegate.co.uk/....
As a holder of Best Of The Best (LON:BOTB) and Avon Protection (LON:AVON) that got walloped by profit warnings on Friday a case of what the Lord giveth, the Lord taketh away ….
Gus.
My morning smallcap tweet:
Cellular Goods (LON:CBX) Audioboom (LON:BOOM) Immotion (LON:IMMO)
Cellular Goods (CBX) multi-year manufacture and supply agreement with Chanelle McCoy Health which will initially supply three CBD ingestibles which will go on sale under the Cellular Goods brand in the UK, followed by continental Europe in 2022. [SP=6.9 Cap=35m]
Audioboom (BOOM) PUSU deadline extended [SP=881 Cap=138m]
Immotion (IMMO) guides H1(June) rev £2.7m and near EBITDA breakeven. H2 has started very strongly. Cites improved trading in our LBE division, which benefitted from school holidays. [SP=5.85 Cap=24m]
Paul, today is Monday. Damned copy and Paste ;-)
'Morning all, it's Paul & Roland here, with the SCVR for Friday'
Probably thinking about Friday because of planned "research" in his local pub!
Ah yes, thanks for pointing out the correct day. I've amended it now.
Best wishes, Paul.