Small Cap Value Report - Mon 16 May 2022 - MADE, OCN, GRG, SRAD, VTU, RWS

Good morning, we have Paul & Jack here for you today.
Agenda -
Paul's Section:
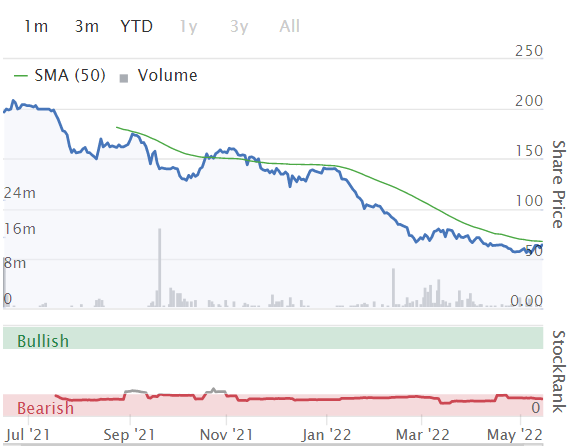
Made.Com (LON:MADE) - a severe profit warning. Instead of recovering this year, losses are now set to increase considerably. Consumer discretionary, bigger ticket items, are clearly being slammed at present, due to the squeeze on consumers, but that's already been reflected in big share price falls. MADE has a strong balance sheet, so I'm not worried about insolvency risk. Big hitter new CFO joins.
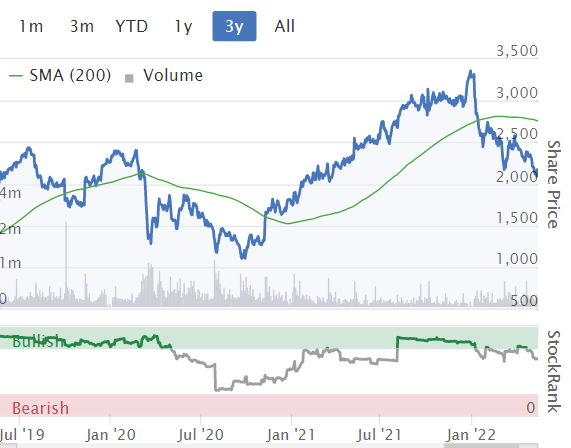
Greggs (LON:GRG) - Greggs is doing OK (for now), and leaves full year forecasts unchanged. I'm looking at this mid cap for read-across to smaller caps, and the retail/hospitality sectors as a whole. A rather rambling section, covering macro factors too.
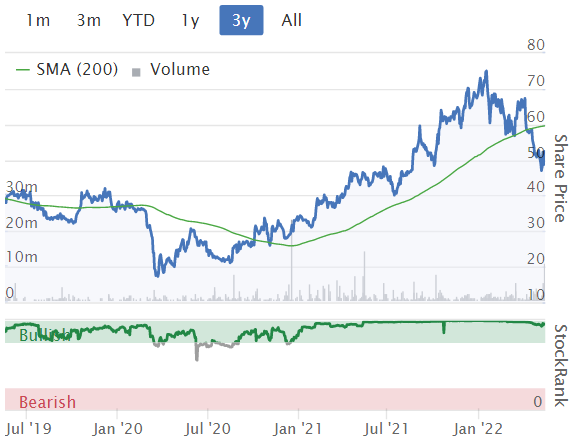
Vertu Motors (LON:VTU) (I hold) - I've typed up my notes from this morning's webinar. Some really interesting additional points.
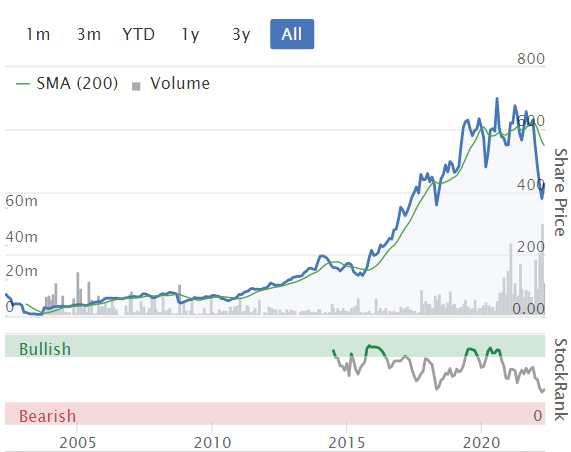
RWS Holdings (LON:RWS) - bidder pulls out. I have a quick look to see if there's any read-across, but no clear reasons are given. So I assume it must just be general market bearishness? Looks a very good business, long-term track record.
Jack's Section:
Ocean Wilsons Holdings (LON:OCN) - a fall in volumes is offset by better revenue mix and foreign exchange rates at the operating division. Headwinds remain, with inflation and supply chain bottlenecks. This business is run for the long term so it could appeal to certain investors with its 5.7% yield and perennially high StockRank, but the shares are thinly traded and the share price has not made progress over the past decade.
Stelrad (LON:SRAD) - lower volumes but better mix and improved margins mean the group is trading slightly ahead of expectations. It’s been a very poor period for IPOs but Stelrad is so far doing better than most. It’s a tough backdrop out there and there are headwinds, but this is worth flagging as a potentially better-than-average and neglected new listing to keep tabs on. More research required though, and there's a nasty spread.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Made.Com (LON:MADE)
64p (pre market open)
Market cap £249m
New CFO appointed - sounds amicable, and with a handover period, so probably not something for investors to panic about.
Patrick Lewis takes over, and sounds a big hitter, previously CFO of John Lewis, and a NED at Ocado. This looksSounds a good appointment, as he apparently has experience of sorting out supply chains, which is clearly needed at Made.
This is one of a number of board changes, including when the CEO stepped down, replaced by the COO Nicola Thomson, in Feb 2022.
Made.com, the leading digital lifestyle brand for the home, today announces a trading update and revised guidance...
That sounds ominous. Is it another profit warning? (EDIT: Yes, and it's a bad one).
The current financial year is FY 12/2022.
- The first paragraph sounds terrific, saying the company is out-performing the market by >20%.
- Lead times are good, and on target at 3-4 weeks.
- Customer feedback & repeat orders are also improving.
Sounds great, but then they hit us with a series of negatives -
- Volatile trading in recent months
- More challenging than anticipated
- Gross sales were down “only” 10% in Q1 (but up 64% on pre-pandemic year)
- Market (for online furniture & home) said to be down 30-40% this year - an alarming statistic
Outlook - revised guidance. I do like the format that MADE provides, giving upper & lower guidance, which makes a lot more sense to me than just a single number -

.
The table above seems a bit muddled, because the first 2 lines are % change on last year, but the adj EBITDA line is an actual number, not an annual change. I’ve confirmed this by checking revised forecasts published this morning by Liberum, many thanks to its analyst Wayne Brown for crunching the numbers - it’s a big help to us.
Liberum’s update now suggests £(35)m EBITDA loss (so it is working from the “Lower” guidance given above, sensible at this stage I’d say). That translates into a thumping FY 12/2022 forecast loss before tax of £(47.6)m, and negative EPS of (9.8)p.
Its previous estimate was a loss before tax of £(5.7)m, so this is a massive profit warning I’m afraid.
This is going to be a tough year, which shouldn’t really surprise anyone, and has already been reflected in the share price losing two thirds of its (inflated, I would say) IPO price. Even so, I’m shocked at how much the forecast loss has ballooned.
We now assume the market will remain highly challenging for the rest of 2022 despite the significantly easier comps for H2…
Freight costs - good news here, with read-across to many other companies - but this benefit seems to be overwhelmed by reduced demand, for now anyway -
Spot freight rates continue to normalise in line with previous expectations, but lower sales mean the benefit will be reflected in gross margin later in 2022 than previously anticipated.
2023 outlook - expecting a big bounce back in profitability, which sounds ambitious to me -
These actions will position the business to deliver positive adjusted EBITDA and free cash flow in 2023.
Is it likely to go bust? - in a word, no. That’s because the balance sheet is strong (as last reported at 31 Dec 2021, NTAV of £74.4m, including plenty of cash, at £107m and no bank debt. That’s fine, and gives the financial strength to ride out a period of dismal trading.
Remember that furniture retailers have highly favourable working capital characteristics, getting cash in from customers, before they have to pay suppliers. So there’s a lot of headroom here.
In terms of listed competitors, DFS Furniture (LON:DFS) is high risk, with a very weak balance sheet. SCS (LON:SCS) (I hold) has a bulletproof balance sheet. I would say MADE is nearer to SCS than DFS, in terms of balance sheet strength.
Also remember that online businesses have the flexibility to cut their substantial marketing budgets, as far fewer costs are fixed, an advantage over conventional retailers.
My opinion - this announcement is a wake up call, that discretionary, bigger ticket consumer spending is really taking a pounding right now, and probably for the rest of this year, due to the increasing squeeze on consumer incomes, and confidence.
That said, share prices have already anticipated this, with huge falls across the board.
At some point, the market is likely to anticipate recovery, but it feels too soon to do that here.
At least guidance from MADE is now more realistic, and there’s little risk of insolvency, so shareholders just have to decide whether to bail out, or to ride out the downturn if you have a longer term perspective.
I don’t know which of those is the best thing to do, because the economic outlook is so uncertain. At some point, Govts might turn on the QE taps again, and get the economy moving again. Fed Chairman Powell has previously indicated this would be his reaction to a recession. At the moment we seem to be sleep-walking into a recession, so it all really hinges on Govt policy here & in other countries.
Here at the SCVR we do like the potential at MADE, but it’s never made a profit, even in the good times. That said, the business model has been to grow aggressively, and it’s definitely carved out a niche, particularly amongst younger customers (several friends/family in their 20-30s tell me it’s excellent, with great designs, and generally reasonable prices, in a rather staid sector).
Would I buy it now? Unfortunately not. Although I see the price has opened down 18% this morning, at 52p (as at 08:11), which is quite a modest drop, considering the huge fall in forecast earnings for 2022. So maybe we’re getting closer to the point where the downside is priced-in, and investors begin looking at recovery potential? I noticed the same thing with Boohoo (LON:BOO) (I hold) - terrible figures, but the price still seems to be forming a base at 70-80p.
Who knows, it’s really all just guesswork in the short term. Longer term, I think MADE looks an interesting business, but it’s very tricky to value right now. It doesn't scream value to me, even after the huge fall.
Let’s hope the new CFO does a proper sort out, including cutting costs to better reflect a very tough trading environment probably for this year, and maybe into next year too?
.
.
Greggs (LON:GRG)
2172p (flat today)
Market cap £2.2bn
Why on earth is a mid-cap in a small caps report, I hear you cry? Partly because my sector specialism is retail, but also because I’m looking for guidance on how consumer demand is changing, and how this might affect small caps. So it’s the read-across that interests me, as we’re apparently entering a much worse macro phase, due to inflation, higher interest rates, etc.
We can either ride it out - tempting, as share prices have already plunged so much, that it might make more sense to concentrate on the recovery, and ignore any further short term pain). And/or to make a list of the most attractive bombed out shares to buy, which have been beaten down unreasonably.
I liked the look of JD Sports Fashion (LON:JD.) the other day, which is performing well still, and looks strikingly cheap on a forward PER basis, for a very impressive business. It’s bounced a bit, but the fwd PER is still just under 11.
The thing that strikes me, is the higher quality companies with better management somehow seem to manage their supply chains, and cope with disruption, whereas others (often the smaller caps) seem to be overwhelmed by supply chain, and other problems.
Now we’re also looking at some consumers (especially those reliant on state benefits - uplifted by a ludicrously low 3.1% apparently) facing a really big squeeze on disposable incomes. The thing is, that doesn't mean an across-the-board reduction in sales & profits for consumer-facing businesses. Tightening their belts, different groups of consumers adjust our spending in different ways. Some businesses still do well, even in recessions. It would be worth looking back, and seeing what happened to companies' profits in 2008, the last severe recession. 2020-21 doesn't help a great deal, as the figures were so distorted by unprecedented Govt support measures.
Even more affluent consumers seem to be, as you would expect, demanding value for money before parting with money right now.
Which brings me on to Greggs. Its products are certainly good value for money, for stodgy, calorie-laden food. That matters because plenty of customers paying more (at, say Pret) might trade down in price/quality. Also if your product is already cheap, then raising prices by maybe 5-10% would barely be noticed by customers, e.g. a £2 bacon roll going up to £2.10-£2.20 is probably not going to make much (if any) difference to demand. Hence why I reckon Greggs should be doing OK, so it’s interesting to see if that theory is correct.
Trading Update - I won’t repeat all the detail here, but the short version is that things are fine -
Trading in line with plan, expectations for the full year outcome unchanged
LFL store sales are strong, but the prior year comparatives distort things, due to the last lockdown in early 2021.
Cost pressures -
are “increasing”.
“Considerable uncertainties”.
“Continue to work to mitigate the impact of cost pressures whilst protecting Greggs’ reputation for exceptional value”.
My opinion - the share price has come down a lot, but with a forward PER of 18.1, Greggs still looks far too high, in my opinion, compared with other high quality retail businesses, some of which are now on PERs much lower - e.g. JD Sports Fashion (LON:JD.) (PER 11), B&M European Value Retail SA (LON:BME) (PER 12.1), Halfords (LON:HFD) (PER 6.9) , Marks and Spencer (LON:MKS) (PER 7.8), Dunelm (LON:DNLM) (PER 11.2). I’m not sure why you would pay such a premium for Greggs, although it probably does have good earnings resilience, due to its products being popular, and cheap. It could be that the apparently cheaper companies mentioned there might be more vulnerable to forecasts being reduced, who knows? Hence forward PERs are currently very unreliable, with such poor earnings visibility for many or most companies.
Remember that this squeeze on consumers is only temporary, so people who can see further out than 1 year (which is meant to be the whole point of owning equities, but instead the market has turned into a giant casino) we could be in a position to buy attractive businesses at attractive prices, maybe?
Retailers actually have built-in inflation protection, as they can raise prices at will. The key question is whether consumers still find the product attractive, at say a 10% higher price. I reckon with Greggs, they probably will. So maybe it's premium rating is justified?
The other point is that we’ve really only scratched the surface of inflation for food. I’m hearing some horror stories about very much higher ingredients costs coming down the pipeline, combined with numerous other cost pressures & withdrawal of Govt support, which is likely to combine to make it absolute carnage in the hospitality sector. Only the best are likely to survive, with many independents likely to disappear.
.
.
Vertu Motors (LON:VTU) (I hold)
52.4p (up 1% at 11:03)
Market cap £187m
Webinar today
I spent an hour watching the webinar laid on today by PIWorld, superb quality as usual. Anyone interested in this share, and the car dealers sector, really should watch the recording when it is published. Robert Forrester always gives a masterclass in his webinars, and this was no exception.
I felt a bit sorry for the CFO, who was barely able to chip in, apart from a few specific accounting queries in the Q&A. Maybe it would be better to let her switch off her camera, rather than sitting awkwardly, being watched, whilst doing nothing for an hour?
I reviewed the bonanza results for FY 2/2022 from Vertu here.
Here are my notes from today’s webinar - which contained some interesting additional points.
So NB below is not a comprehensive report (you need to watch the webinar yourself for that), it’s just some key additional points which I noted down, in particular if they were new facts to me.
Long-serving CEO Robert Forrester, since group founded in 2006. He comes across as very (maybe too?) charismatic, rational, and forward-looking, on top of the detail too. So a thumbs up from me for management quality.
Strong tailwinds, 7 upgrades in FY 2/2022 (but obviously profits not sustainable at that level)
Only 900 cars sold purely online. But many more sold via deposits placed online, then subsequently purchased. 75% of customers want to test drive before buying.
Net tangible asset value (mainly freehold property) is 66.8p. This includes the pension surplus. In Q&A, asked whether this is a realisable asset? CFO replied yes, otherwise she wouldn’t be able to put it on the balance sheet, and the pension scheme was “no cash call on the business”. I didn’t know that, so maybe we should include pension surpluses within NTAV in future? More digging needed on this point.
I can’t think of any other car dealer chain that is trading below NTAV, as VTU is.
I queried if freehold property is worth more or less than book value? CEO replied that freeholds are in the books at cost. He doesn’t know what their market value is, because he’s focused on generating returns from them. Although I felt he was hinting they’re definitely worth more than book value, but not clear how much. Freehold property disposals have nearly always been at above book.
Strategy is growth - more expansion in the pipeline.
Multi-franchise (e.g. 4 brands from one site) is more efficient than large, single franchises.
Relationships with manufacturers - have to plan 5-10 years ahead. Mentioned Toyota as a good prospect. Close liaison with manufacturers. Can build better shareholder value by creating new sites, than buying existing ones.
Vertu has never lost money, not even in 2008 financial crisis, nor covid.
Govt support reduced to £6.6m, nearly all business rates relief.
Click-to-drive is an online sub-brand, doing well. Showed us advertising on a racing car. Creating other supporting businesses, eg a van online retailing business, and a parts business.
How to make huge profits? Sell less (sic) cars! Previously the sector was over-supplied, causing margin destruction. Tight supply set to continue - could be up to 4-5 years for used cars. This is a good thing, as tight supply = more profit.
Ukraine - is a big parts manufacturer, especially wiring looms. Very surprising that manufacturers became so reliant on key components from Ukraine.
Manufacturers have responded by reducing production of mainstream models, prioritising higher margin top end vehicles. Hence why secondhand car prices rose so much, as limited supply of both new & used cars. Bizarre situation, which drove up used car prices 25-30%.
Last 3 months more normal - used car prices falling c.2% per month.
Used car volumes have dropped 10-15%
Order books (for new cars) still at record levels.
Stock turn - at Vertu is fast, at 35 days. This is a competitive advantage, because VTU is now selling cars it has bought recently at lower prices, whereas competitors with more stock are having to discount cars they paid more for.
Gross profit on used cars rose from £1204 to £1,740, main driver of bumper profits in FY 2/2022.
Cinch/Cazoo are spending hugely on advertising. But customers still like the franchised dealers - and 75% want a test drive.
IT - Vertu has 50 in-house IT developers, so a lot going on.
Online “concierge service” is doing well, sold 400 cars so far (where browsing customers that drop out are nurtured back in).
Aftersales (e.g. servicing) will decline, due to lack of new car sales.
Cost discipline - as lots of suppliers are raising prices (i.e. for non-cars), then danger is we just accept price rises, and don’t challenge them or shop around.
Energy costs - a lot of work being done here (not explained what!)
Good start to current year, as in the RNS results, with Mar & Apr 2022 about level with last year, around £19m profit.
Consumer confidence - way too early to say. Noticed that some prospective buyers are mentioning reduced monthly payments as important.
I asked whether staff costs could be reduced again, in a downturn? “We’re no longer in control of staff costs”, due to minimum wage rising. We do have flexibility on staff numbers. Have 400 vacancies currently (implying could freeze recruitment if necessary). Also I noted from the slides that sales staff are getting performance-related pay, so there must be some flexibility in there. Typically each salesperson sells 120-150 cars p.a. (so about £200-250k gross profit per person, pretty impressive).
Good case for share buybacks, but main focus is on deploying capital to achieve high returns.
Acquisition of new sites - tight supply, only 2% nationally are empty.
Closing remarks were the most interesting, e.g. -
Industry is seeing emergence of “mega groups”. We need to grow, or end up in a mega group, “otherwise we won’t have a future”. CEO has a tendency to hyperbole sometimes, but I think it’s becoming clear that VTU is likely to be taken over by a bigger group.
Q&A - what is his attitude towards any bid approach? Would weigh it up, and if at a decent premium, would have to consult shareholders.
Financial buyers tend not to be interested in the sector, since manufacturer consents are very important if transferring business ownership - good point, that I think a reader here once mentioned in a comment.
My opinion - the interesting thing is that demand is still above supply at the moment (long waiting lists). This suggests to me that even if consumers do rein in big ticket spending, it might not have as much impact as we imagine? Supply is expected to continue to be constrained, in both new, and (knock on effect) used cars. Hence I think car dealers could surprise on the upside, with profits obviously falling from insanely high levels in 2021, but maybe to still above normal in 2022, possibly, who knows?
A very interesting share, and I remain of the view that priced well below NTAV, the price looks wrong to me, even if you factor in earnings falling by half or more.
Takeover bid very likely, in my opinion.
.
.
RWS
Possible bid falls through
It’s above our usual (flexible) £700m market cap upper limit, but I thought it would be interesting to have a quick look, to see why the possible bid has fallen through.
The potential bidder, Baring PE Asia Fd.8 has only issued 2 RNSs -
21 April 2022 - “Response to press speculation” that it was in the “preliminary stages of considering a possible offer” for RWS. This caused a c.30% spike up in the share price.
Today, it announces that it won’t be proceeding with a takeover bid. It kindly states that - “BPEA's decision not to proceed at this stage is not a reflection of its views on the RWS business. “
RWS responds today with this -
The interest from BPEA was unsolicited and did not result in any proposal being made to RWS. The Board of RWS believes the Company has a strong future based on its clearly defined strategy, as outlined at its Capital Markets Event on 23 March 2022, which includes accelerating organic growth, capitalising on a simplified technology portfolio, driving operational leverage and enhancing growth and returns. The Company is focused on the actions and investments which support this strategy and its five year accelerated growth plan. The Board believes the delivery of this strategy will create significant value for the Company's shareholders.
My opinion - it’s not clear why the potential bidder pulled out, but I can only assume it’s down to current economic & stock market bearishness. Also. we're not told how involved the bidder got - did they do due diligence, etc? I wish disclosures would be more open about bid approaches.
RWS has a long track record of delivering excellent shareholder value.
It’s now dropped by almost half from the average share price in the last 3 years.
It could be worth a look for investors with a strong constitution. Often the best long-term buys are when everyone is scared witless, like they are now.
.
.
Jack's section
Ocean Wilsons Holdings (LON:OCN)
Share price: 1,010p (unchanged)
Shares in issue: 35,363,040
Market cap: £357.2m
Q1 trading update to 31 March 2022
This is a Bermuda-based investment company with a maritime services division operating out of Brazil. A slightly unusual mix for the SCVR, which comes across in Ocean’s small average daily traded volumes and 302bps spread. It’s off the radar for most despite a StockRank of 98, a single-digit forecast PE ratio, and a 5.65% forecast dividend yield.
Q1 revenue of $101.4m is up 9.6% and EBITDA of $45.9m, up 9.5% on the same quarter last year. Net profit for the period was $27.8m, up some $23.0m on the previous period thanks to improved operating profits and foreign exchange gains.
Total containers moved declined 14.7% at 161,500 TEUs (2021: 189,300 TEUs) ‘as the impact of global container availability and delays in off-loading cargo continue to prove challenging’. TEU means 20-foot equivalent unit. Import volumes in the period declined with the closure of some Chinese ports as Covid restrictions were reintroduced.
Regarding the investment portfolio:
At 31 March 2022, the investment portfolio including cash under management amounted to US$328.2 million (31 December 2021: $351.8million) a decrease of a 6.7% decrease. At 31 March 2022, the investment portfolio represents US$9.28 or £7.08 per Ocean Wilsons share value. At 30 April 2022, the investment portfolio including cash under management amounted to US$312.9 million, a decrease of US$38.9 million (11.0%).
Conclusion
The OWIL portfolio takes a long term, conservative approach to investment and appears to be well diversified, although changes in valuation do affect group profits. The dividend yield is attractive.
There are near term uncertainties around the 57% stake in WSON, with supply chain bottlenecks and high inflation.
This is a thinly traded share, probably one to either hold as part of a diversified portfolio or to have a lot of long term conviction in. It generally doesn’t track the market, so there are periods of inactivity and the stock earns a rare Conservative RiskRating.
Directors and established shareholders own a good chunk of the business, so I think it’s going to just carry on doing its thing and not get too interested in external perceptions of progress. That could be an attractive feature for patient shareholders focused on income, but it might frustrate others.
Ocean remains something of an oddity. The StockRanks appreciate the business and have been consistently in the green since 2014, although the share price performance has been pedestrian. What would the catalyst be to spark a rerating?

Stelrad (LON:SRAD)
Share price: 214p (unchanged)
Shares in issue: 127,352,555
Market cap: £272.5m
A new company here, Stelrad supplies radiators to over 500 customers across approximately 40 countries. Today we have a brief ‘slightly ahead of expectations’ AGM update.
Overall volumes are lower year-on-year against very strong comparators but this softening has been more than offset by improved margins, cost management actions, and an improved mix of premium steel panel radiators.
Stelrad's market leading products and brands ensure that the Group remains very well positioned across all key geographies. The Group continues to manage inflationary cost increases and avoid any adverse impact from supply chain dynamics through its well established supplier relationships.
Trevor Harvey, Chief Executive of Stelrad, commented:
As energy prices continue to place pressure on household incomes, our products remain central to how consumers across Europe affordably heat homes and reduce energy consumption while governments continue to debate how best to decarbonise homes and meet long-term net zero carbon commitments. We are confident in our strategy and ability to continue growing our market share both organically and through M&A as we address this important trend.
Conclusion
The share price hasn’t done much since listing, and the valuation remains fairly modest on 10.3x forecast earnings with a 3.9% dividend yield.

Again, we have poor liquidity with a 566bps spread. Trading has really dried up in general. And it doesn’t look like any analysts are covering the company so Stelrad is flying under the radar.
The group notes a leading market position, favourable regulatory tailwinds, and wider macro trends in relation to reducing home heating costs and carbon emissions. Sounds good, but this needs to be investigated in more detail. How will the company fare with inflation? Steel is a large input cost and that’s rising. There’s presumably a lot of competition out there as well.
I’m just flicking through the IPO doc now, here are some of the stated risks:
- Customer concentration - in the year ended 31 December 2020, the top 10 customers of accounted for 49% of revenue, the top 5 customers 35% of its revenue, and the largest customer 14%.
- Turkey - Stelrad has three manufacturing facilities (in the UK, The Netherlands and Turkey). The Turkish facility at Çorlu produces c71% of the group’s products in the year ended 31 December 2020) could have a material adverse effect on its manufacturing capacity.
- The Group may be adversely affected by the fluctuation in availability and cost of steel required for its products.
- Disruptions to international freight can adversely affect the Group.
Most of these strike me as particularly pertinent right now.
There’s a small free float, just 35%, and the major shareholder owns nearly 50% of the company. Meanwhile, the group’s long time CEO Trevor Harvey keeps a 9% stake.
I’m waiting to see how management handles the current difficult environment. So far, it seems to be going well, but the UK market has been plagued by poor IPOs over the past couple of years. So I think, statistically speaking, it makes sense to watch and wait for a bit. Made.com has lost nearly three-quarters of its value in less than a year for example, although Stelrad’s operating performance is certainly more encouraging.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

47 comments
Vertu Motors (LON:VTU) (no position)
I've been trying to get my head around why this company looks so cheap.
As Paul mentioned there are significant property assets on the balance sheet, which, net of debt, look to be equal to the current market cap. On top of that there's a profitable and cash generative business, which looks to be thrown in for free.
Aside from the cyclical/inflationary/etc...worries that we are all talking about at the moment, the main risk I think I can see is that the company mainly deals with Honda, VW and Toyota.
I recall that Volvo have a strategy to only sell direct to consumers from 2030 and I imagine that it would be very financially damaging to Vertu if something similar was announced by one of their aforementioned partners.
----
In contrast, Marshall Motor Holdings (LON:MMH) , who were recently acquired at what looks to be a much higher valuation relative to Vertu Motors (LON:VTU) , appear to have relationships with many manufacturers. Presumably therefore if one of those relationships breaks down, there will be less of an impact on the group, which perhaps explains why it was a more sort after target.
I know very little about cars, so I'd be interested to hear from others with more knowledge here. Could the limited number of partnerships be a risk for Vertu Motors (LON:VTU) ? Has this been asked at any of the presentations?
Cheers
A
Paul, an excellent write up on Vertu Motors (LON:VTU) FY22 webinar yesterday. Here is the video & podcast.
(moved comment to threaded under another)
On Greggs (LON:GRG) the economics looks quite good to survive high inflation.
Gross margin is 63%, so it means there's lots of operational leverage if they can force through price increases to maintain that gross margin.
H2 operating margin was only 13%. So if we take say a 10% price hike this year = 10% more revenues (assuming no loss in selling volumes) and if they can hold fixed costs, that would be almost a double of their operating profits.
However, of course, the fixed costs include staff wages I presume, as well as utilities, transport, etc. But if one was to go digging in that fixed cost line and see how much is really fixed (ie rents, etc) it might be possible to work out whether the operational gearing is positive for Greggs in an inflationary environment where they have pricing power and can maintain volumes.
On Made.Com (LON:MADE) it seems like Patrick Lewis is part of the founding family that set up John Lewis? I think I saw that correctly in one of the media snippets this morning. If so... did he get the CFO job based on merit? I don't know enough about the JL structure or partnership so something for any serious Made.com to probably investigate.
Made.Com (LON:MADE) Interesting point. I'd not 'made' the connection from Patrick 'Lewis' to the founding family.
From what I can see. The John Lewis business started transferring ownership to employees in the 1920's. By the 1950's had transferred ownership to trustees, established an employees council which holds the partnership board to account, elects a number of board members and directly elects the trustees - but with the son of the founder as chairman not owner. By 1993 the chairman of the business was no longer a family member. Patrick Lewis became Finance Director in 2015 - having worked at the company for years. I can see how his famiy ties might have helped him into the company in the first place - but there appears to be no mechanism by which his family ties would allow him to be selected to the board and it seems very unlikely. There is a strong argument for the reverse - I'd expect that the independent board would go the extra mile to establish the merit of the candidate - anticipating that employees would question it and the council if not the trustees would hold them to account.
Even so. In the unlikely event that his family ties played some part in his selection at the JLP it's very hard to imagine that MADE would select Patrick Lewis except upon merit? I have to say that he is not who I would have expected them to appoint and looking axross the whole board I can't see that they would have made his selection easy in any way.
There is also the question of why Patrick Lewis would choose to join MADE? I find that quite intriguing.
thanks for raising it,
cheers
Mark (I hold - a small holding - but with potential I think. Not without risk perhaps but much lower at this price?)
Thanks Paul S. for your comments on Greggs (LON:GRG) though I have one or two things to add.
One of the things that seems to help the SP and PER being above what is expected is that to date they have plans to open more stores/outlets and the potential to do so. I don't think this should be forgotten. I say 'outlets' because they are quite creative at finding appropriately sized and located 'stores' as I originally chose to call them.
Additionally, their Marketing and R&D people have been very creative, especially in the vegetarian and vegan offerings (which many restaurant chains are still really very poor at covering to their potentially increasing percentage of customers).
Excellent coverage Paul on Vertu's webinar which sadly I could not watch -- thank you. During the last one Robert Forrester gave some information about their various brand recognition among groups they control, last year Bristol Street Motors was by far the most recognised and well above Vertu's. It's heresy to suggest it but I've thought since then a name change to BSM for the whole group could be rewarding.
Agree with your comments JASVFS on Paul S's coverage of the Webinar. Also referring back to Paul's comments on the CEO's view of the big advtg spenders like Cinch and Cazoo.
Vertu Motors (LON:VTU) are not out of the TV advertising market themselves. I dont know whether they have national coverage (and their HQ is in Newcastle, Border TV country) Recently, I was on holiday in Cumbria - Border TV country - and saw quite a lot of Vertu Motors (LON:VTU) advertising of the heritage of the Bristol Street Motors brand. As a retired FMCG marketing man, I can appreciate the appeal of the 'been around for a long time, personal service after test drive' model though got tired of the ad after a while., On the other hand, thoroughly tired of the Cinch and Cazoo advertising too!!!
Hi JASVFS,
Thanks. The Q&A did touch on brands, with someone asking why didn't they consolidate the group under the Vertu name (the opposite of what you suggested). The CEO blew that out of the water, saying that the group's Bristol Street brand is one of the top 3 customer recognised brands. Also pointed out that the separate Scottish brand within VTU is well recognised there, and seen as Scottish not English, and they have different timing for holidays, which means bespoke advertising is better.
Overall, he accepted that there are "marketing inefficiencies" from having several brands, but that it would be "moronic" to change them!
Regards, Paul.
Re £VTU
Energy costs - a lot of work being done here (not explained what!)
One thing I picked up from a separate results video is that Vertu are changing out all workshop and showroom lighting for LED. A big upfront capital cost but the long term savings are substantial - particularly in current energy market.
On Vertu Motors (LON:VTU) and car dealerships in general, I didn't realise that it takes about 5-10 years from pitching to actually securing the dealership rights for a country etc.
Doesn't that mean there is a bit of a big long-tail risk for Vertu? Lose one of their main franchise brands, and it'll be hard to win back for like 10 years? I haven't had a look but what is their revenue concentration by car brand?
I notice that if you want to operate a 15% stop loss strategy, then sitting on the side lines still appears to be the right thing to do for now at least....even five year lows in decent companies seem to be able to trigger a stop loss.....still away to go yet I think. Over 70 percent back in cash now, and nothing on my watch list is tempting me in yet...must be a load of investors in the same boat.
Hi Paul
I had a longer write up on thoughts last week, basically I am doing different things for different family members, and for myself I am actually doing different things in different parts of the holdings (e.g. main SIPP 90% cash, current employer SIPP 100% invested and continuing to buy each month but that is ~7% of total SIPP).
The hardest part is control of emotions, so looking say Legal & General (LON:LGEN) Somero Enterprises (LON:SOM) or £PHNX bargain, but is the rise going to continue, or will it do as before drop back even lower? I know there is no right answer, some things I have sold are up, some things I have sold are down, the biggest thing is I have slept at night :) and right now I am trying to learn to sit out for a few weeks and then make a decision.
I am probably going to end up allowing myself to start to buy small starter positions in some companies as they are just too tempting, but these would be <1% so can build in a rise, or double down on a fall.
I have no stop losses on my remaining holdings but running a manual 10% go to minimum position size and 20% exit and put on watch list.
Good luck!
Tommy
hi Paul / Jack
You may want to take a look at Kitwave (LON:KITW) (I hold) which seems to have gone under the radar on here. Some bullet points:
Seems there is lots to like and operates in a largely non discretionary spend arena.
Would be interested in your views.
regards
Snazzy
Also if your product is already cheap, then raising prices by maybe 5-10% would barely be noticed by customers, e.g. a £2 bacon roll going up to £2.10-£2.20 is probably not going to make much (if any) difference to demand
Paul,
I disagree with this statement. I used to sell consumer goods and across the world. In all countries, I found poor consumers on clear price points for single item purchases - still often paid for in cash - are much harder to move up. Prices hold and hold and hold (causing pain to suppliers and finance directors) until they make a big jump, led by a price leader.
So £2 bacon will stay this until the pain is too great and then jump to £2.50 ( although the picture is often deliberately blurred eg here with meal deals, managing portion size and substituting ingredients. Much easier to move up a £6.75 meal to £7.25 then £7.75 etc. Better yet a meal starting at £11.25 or £21.25.
The poor also just run out of money and stop consuming or drop a category eg stop buying bacon rolls and bring a home-made sandwich – less convenient and nice but cheaper. The rich grumble but just save less quickly or make 1 or 2 major big ticket revisions (no 2nd holiday, delay the new car) which enables day-to-day consumption almost as before. I therefore see value in consumer product companies targetted at the wealthy, dragged down with mass & poor-focused companies (eg I think UBG is a steal and hold).
However, within a (low) price point market, I agree the big chains like Greggs, able to exert power on their own suppliers, will do OK; independents will typically really struggle.
**PERSONAL ANECDOTE WARNING**
I have to agree with Zipmanpeter, something similar happened when I worked at Wetherspoons. A pint of Boddingtons was 99p (and a bottle of Stella the same - and this was only approx. 2003-2005ish so very good value), and the day we moved it up to GBP1.09 - a price still a lot cheaper than anywhere else at the time - there was absolute uproar from the regular drinkers.
It's hard to know how it dented demand, if it did at all, but then we were in pretty good times on the whole, with 2007-2009 still a long way off. If it was done at the start of or during a recession, I reckon it would cause a material drop in demand.
Thanks
Chris
I'm sure you're both right, in normal circumstances.
But my point is that everyone is having to raise selling prices, due to much higher costs in multiple areas (raw materials, energy, ingredients, etc).
Therefore in that scenario, a 10-20p increase for a bacon roll is probably less of an increase than all the competition are pushing through. Especially if you're trading down from a more expensive competitor, which might have just put through a 40p price increase on their sandwich.
I use JustEat a lot at the moment, through sheer laziness, and am staggered at how expensive it has become just to get a McDonalds breakfast (around £10-12 now) or a Pret lunch (£15-20) sent over, just for one person!
Regards, Paul.
Fair points all, thanks Paul. Thinking about it, given all other prices of everything is/will be going up, people will probably look at the price of a bacon roll going up as either:
It seems we're going into a difficult (in so many ways) next few years. There are going to be so many people affected in so many different ways and pulled from so many different financial directions, we don't know what's going to happen to individual businesses' demand.
Cheers
Chris
Greggs (LON:GRG) I'm off to buy myself a sausage roll
Hi Paul&Jack,
Any chance you could do a report on Iog (LON:IOG) . First oil and gas began in March 2022, 500k income a day to double when more fields come on line in 4th quarter. Seems a no brainer to me at the current price during a pullback, but would be great to hear some expert thoughts? Gas prices expected to stay high for years.
Hello Guybrush,
Sorry but we don't cover the oil & gas sector in these reports - too many companies to cover, and we don't have the sector expertise needed - as mentioned in the "explanatory notes" above, included in every report.
Regards, Paul.
.
I hope MrContrarian is OK. Am really missing his invaluable updates.
…perhaps Stocko should put him on the payroll?
Totally agree. I think they are so important it would be good if regulars like myself could do it for him when he is away. I don't know how he turns it around in the time but I would be happy to share duties on a particular day(s) to cover for example announcements from companies between A-G. Two or three others could do other parts of the alphabet.
Good idea ... but who will take charge in the acerbic dry wit department?
On holiday and liking the lie-ins. Back soon.
MrC
Enjoy your holiday Mr C. you have been missed.
John Authers today suggests the Canadian and Australian dollars as a hedge against stagflation. Is there an ETF that tracks either or both?
John Authers today suggests the Canadian and Australian dollars as a hedge against stagflation. Is there an ETF that tracks either or both?
IMHO playing around with currencies is a mugs game for private investors. I assume it is because they are seen as commodity currencies? This assumes we get stagflation, of course, which is by no means a certainty, just this one person's opinion. Surely there are better ways of achieving what you want via equities, or using a FOREX broker cash account?
Just saying, Si
How much of your portfolio are you prepared to move into CAD or AUD? Surely it would have to be a high proportion to have the required impact - if stagflation happens at all. And if we get recession instead, then commodities will fall along with everything else.
There are a number of ETFs/Funds in different markets, that allow you to trade a currency pair, or go long/ short USD v a basket of currencies for example. Given the strength of the USD in recent months, one that might be interesting is Invesco DB US Dollar Index Bearish Fund , as you would expect the USD to retrace once some of the geo-political issues and inflation have subsided. You can find information on other currency pairs eg. https://www.betashares.com.au/...
FXC for the Canadian Dollar
FXA for the Australian Dollar
Both are relative to the U.S. dollar, increasing in value when the Canadian / Aussie dollar strengthens and declining when the American dollar appreciates
I have held Ocean Wilsons Holdings (LON:OCN) for a while. Its main attraction is the large discount to NAV (45% on my calculations) and the fact that the dividend paid by Wilson Sons is fully passed through to OCN shareholders.
The current wide discount to NAV has been maintained since the early days of Covid when Wilson Sons (and hence OCN too) reduced an already announced dividend due to Covid uncertainty. With OCN being held by many for the dividend this seemed to lead to selling pressure on OCN. Later in 2020, as it was clear Wilson Sons had weathered the pandemic the dividend was made whole but the OCN discount remained wide.
I personally prefer owning OCN to Hansa Investment (LON:HAN) (which is the family holding company one level higher up) because I get a high dividend out of OCN (so over the years, a fair chunk of the underlying value of OCN is paid out at 100% but I can buy in at almost half-price)
To buy in to OCN,you have to be reasonably positive about the outlook for Wilson Sons and Brazil. While Jack is correct that the 10-year graph of OCN is uninspiring, the long-term graph of Wilson Sons (ticker now PORT3, previously WSON33) is impressive. Wilson Sons seems well-placed in the Brazilian containerisation drive and a well-managed company. In 2019, Wilson Sons undertook a strategic review but no transaction occurred. A future transaction on Wilson Sons would be a potential catalyst.
While I think that OCN’s current 45% discount to NAV is high - some discount is clearly warranted. The just less than half of assets held in a well-diversified range of funds does not have a good track record and the fees charged to OCN for managing them are far too high in my opinion. Non-controlling shareholders are merely passengers.
I also hold OCN and for me it is a long term play on Brazil with a good dividend thrown in.People have been saying for 70 years at least that Brazil has amazing potential in theory and i hope to be still alive to see the potential realized.
Bunge is another share that one can play Brazil with
OCN : “the share price has not made progress over the past decade.”
True, but it’s not done bad since November 2020 - up 42% thank you very much.
Obviously way outside Small Cap territory but Diploma (LON:DPLM) has been on my watch list for a while and i have read todays Half Year report and cannot understand the market reaction, 7.5% down as i type, would any holders be kind enough to explain what i have missed.
TIA
Richard
Diploma (LON:DPLM) - the only “negative” that I can see on a quick read of the RNS is “Expect growth to moderate in Q3 as the comparators get tougher”. However today’s price action simply brings the SP movements into line with 10-20% falls of other industrials since the price spiked on the early April profit upgrade. Shares are still outperforming the sector.
Angle (LON:AGL)
From an article in Medical Device and Diagnostic Industry Journal
CEO Robert Ford hinted at the types of acquisitions Abbott is most likely to go after in 2022.
https://www.mddionline.com/digital-health/abbott-looking-ma-opportunities
Hello JimMcLad. Thanks for the comment on matters which may relate to Angle (LON:AGL) though the reference was to an article back in January. Given the delay, what made you bring it up now?
I was interested to see the $billions tags related to the activity in these markets. However, without FDA clearance, that is keeping the price tag for Angle (LON:AGL) pretty low in comparison, though it would seem from the Angle (LON:AGL) R & D results in so many top class (IMHO) health institutes in the UK, Europe and the USA that the products of these multi $billion competitors is rather inferior!
It is now the anniversary of the fulfillment of the extra data request from the FDA to Angle (LON:AGL) which they supplied in full and on time. I am struggling to understand why the FDA is taking so long - admittedly Covid has continued to i intervene and we have Ukraine,though I am struggling to think what effect that has on the timely response rate of the FDA to reasonable applications.
It is probably a totally different section dealing with the Polarean Imaging (LON:POLX) application but theirs seems to be having more progress from the more specific RNS's that are coming out. After the first refusal, it was forecast that the next final response would be about a year, and it seems that is playing out ok.
If I were a different kind of person, I might start to think about conspiracy theories because Angle (LON:AGL) is not a US company (though has received more shareholder support in the US in recent times). In my worst moments, I could be thinking that there are some heavy players with inferior processes out therein the US who would have quite a lot to lose from a fully certificated and powerful Angle (LON:AGL) and may have some kind of influence with decision makers .....but of course that would be absurd, wouldn't it?
In the meantime, do you have any further thoughts on why the decision is taking so long? Have you had any contact with management / PR people at Angle (LON:AGL) recently?
Hi ridavies
Given the delay, what made you bring it up now?
It was mentioned on another board and although dated Jan it was an interesting bit of info I had missed and assumed others here may have as well. Angle are working with Abbott (and I believe Astra Zen) and whilst Andrew Newman has said they want to stay independent – which I’d like to see – I suspect a lot of shareholders would happily snap up an offer way above the current share price. As you say, the size of the market for many cancer types runs into $billions in the US alone.
I am struggling to understand why the FDA is taking so long
As it’s a de novo submission and a new stream for the FDA a lot of work apparently has to be done from their angle (sorry !). There seems no doubt the functionality of Parsortix has been proved and accepted and as Newman said the FDA are now in the ‘administration’ stage. This submission covers breast cancer and the work undertaken should make clearance of the other 27+ cancer types much quicker.
If I were a different kind of person, I might start to think about conspiracy theories because Angle (LON:AGL) is not a US company....but of course that would be absurd, wouldn't it?
Oh yes ! ………. but a train of thought I’ve read before 8-) Imagine the damage to the FDA (and USA) if they were found to be deliberately holding back a system that would benefit millions of people worldwide.
Have you had any contact with management / PR people at Angle (LON:AGL) recently?
No point contacting Angle (LON:AGL) on this, they would say no more the AN said at the results presentation. We just have to wait. FWIW, I increased my holding last week.
Added myself today.
Morning all,
If you haven't already found it, Ben's Market wrap he puts out on Friday afternoon is a great read.
He succinctly and briefly summarises the current market moods and trends.
Have a great (and hopefully profitable) week everyone,
James
Hi James, please let me have a link or where to find Ben's Market wrap
It is on the main "Today" page - along with the 4 or 5 most recent "official" reviews/updates.
Alternatively just go into the "discuss" tab and you'll see the link to it in there.
https://www.stockopedia.com/co...