Small Cap Value Report (Mon 16 Oct 2017) - Footasylum, SYS1, BVXP, SPSY, RBG

Good morning!
I'm writing from my underground bunker in advance of the post-tropical rain which is about to strike Ireland.
There's an eerie silence outside, unusual cloud formations have appeared, and the animals are acting strangely.
All in all, these are fine conditions in which to write about a few stocks:
Footasylum (LON:FOOT)
It's a new fashion retail float, so I'm sure many readers will be looking at it either as a potential purchase or as a comparison with their existing holdings.
The basics:
The Company retails "on-trend" product ranges which are predominantly aimed at 16 to 24 year old fashion-conscious customers and are sourced from an extensive stable of third party and own brands.
Similarity with Boohoo.Com (LON:BOO) in terms of age bracket but with the emphasis on footwear, obviously!
The Company operates a multi-channel model which combines a 60-strong store estate - in a variety of high street, mall and retail park locations in cities and towns throughout Great Britain - with a fast-growing eCommerce platform and a recently launched wholesale arm for distributing its own brand ranges via a network of partners. In FY17, the store estate accounted for 71 per cent. of revenue and eCommerce accounted for 29 per cent.
Next (LON:NXT) (in which I hold a long position) enjoys 47% of branded sales from its online Directory arm, so Footasylum hasn't quite achieved that sort of mix yet. But 29% online is still a significant level to have reached already.
The retail growth plans in a nutshell are to open 8-10 new stores per year, with the potential to get to at least 150 (presumably over the next decade, given that it currently has 60).
Management plans are a bit unusual: the former Chief Executive off JD Sports Fashion (LON:JD.) is scheduled to join Footasylum as Executive Chairman in June 2018. But they already have a CEO, so it looks as if there is going to be some kind of power split between her and the Exec Chair? Clarity would be helpful.
Financial results are presented as follows:
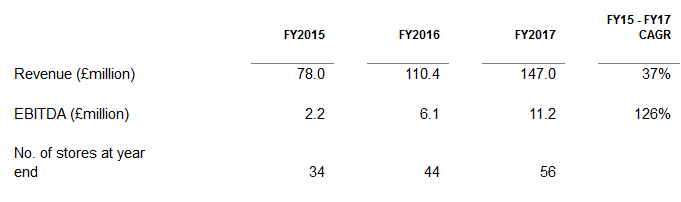
Growth numbers are clearly quite good but we have to make the standard disclaimers in relation to EBITDA.
And in general, investors need to be careful about pre-IPO numbers being puffed up a little.
For example, if some maintenance capex is neglected in the year or two ahead of IPO, this can result in lower depreciation charges and therefore earnings can look artificially high.
Footasylum says it plans to make "significant investments over the next three years in increasing the Company's digital presence as part of a broader upgrade of its IT systems to support growth."
So that's a large part of what the IPO investors will be paying for: upgrading the company's IT systems. And if, say, spending hasn't been enough to keep the systems up-to-date over the past couple of years, that's the sort of thing that could temporarily increase earnings. These are the difficult questions that are worth asking, in my opinion!
As the recent debacle with Accrol Group (LON:ACRL) helped to demonstrate, IPOs can look fine for a year or two until the hidden problems/risks emerge. I still find them really interesting, I just think an extra dose of scepticism is needed!
Getting back to Footasylum, the sales split is 71% menswear, 8% womenswear and 18.5% childrenswear (plus 2.5% accessories). A very different audience mix compared to Boohoo.Com (LON:BOO), then.
It sells its own-brand gear but "Global third party brands constitute the core of the Footasylum offering" - it's primarily of distributor of other brands. Half of revenues are from Nike and adidas.
Its Oxford Street store is loss-making at the EBITDA level, "but has helped to build brand awareness". Surely there are more efficient ways to advertise!
My opinion
Overall, with a few questions which will hopefully be answered in due course, it looks highly suitable for AIM. I'm looking forward to seeing news on valuation (rumoured at £150 million) and the mix of new money/old money in the IPO. Maybe we will get our next big bargain about six months after the flotation, which is set for next month.
Additional comment from Paul Scott: Many thanks to Graham for his review of FootAsylum. I had been meaning to look at this one, as my broker flagged it to me as something that fits my sector specialism.
I've only done limited research so far, but like what I've seen. It seems to be almost JD Sports mark II. So, given what a rip-roaring success JD Sports Fashion (LON:JD.) has been, it seems sensible to take seriously what FootAsylum is doing.
My main worry is that the big brands might decide to cut-out the physical retailers, and go direct to customers, and/or via Amazon. I read something over the weekend (can't remember where unfortunately) saying that footwear (especially designer trainers) is an area being specifically targeted by Amazon. So the big worry is that places like JD Sports, and FootAsylum might become expensive showrooms, with customers then making their purchases online, via Amazon (at lower selling prices). That would then kill the profits of the physical retailers.
I do like that FootAsylum is developing its own brands as well though. The big danger with just selling third party brands, is that you're very vulnerable to competition from Amazon - who as we know, are perfectly happy to just trade at or near breakeven, in order to deliberately kill off their competition. Therefore, the only online retailers which really interest me, are ones which develop their own, unique products. I think Amazon will find it a lot harder to compete with online fashion companies that are great at sourcing product (e.g. Boohoo.Com (LON:BOO) ).
I can't see from the RNS today any details about selling shareholders, although they are mentioned;
The Directors believe that the Placing will provide the Group with an appropriate capital structure to pursue its growth plans and that Admission will further raise the Company's profile and assist in attracting and retaining key employees through appropriate incentive arrangements. Admission will also enable the selling shareholders to realise, in part, their investment in the Company.
So I think it would be essential to find out how much of their shareholdings are being sold by the selling shareholders. Too many IPOs go wrong, and as Graham mentions above, problems can often emerge some time after the selling shareholders have pocketed their profits.
Overall though, from reading the RNS, and a broker note on FootAsylum, in my opinion it looks worthy of further research.
SysGroup (LON:SYS)1
- Share price: 530p (-1.4%)
- No. of shares: 12.4 million
- Market cap: £66 million
Regular readers will know that this market research / brand consultancy was previously known as Brainjuicer, and traded under the BJU ticker.
It suffered a horrible profit warning in August, when the share price fell by about a third in a single day.
I've been watching this share for several years, and never quite felt comfortable enough to buy it. The directors have always been really honest about their lack of visibility over future sales, and sales finally took a hit this year when some big one-off projects failed to repeat.
A more competitive market was cited as one of the reasons for this, along with client spending deferral.
Something else which I noticed, and which I still think is a problem, is that this company doesn't own system1.com (it's instead owned by a US firm).
Today's announcement is fairly stark:
As announced on 18 August, trading in H1 has been slower than expected, and Gross Profit (the Company's main top line performance indicator) is 9% lower than prior year (12% in constant currency), due in the main to non-recurrence of large one-off Innovation projects as a result of some significant client spending reductions and a more competitive market. Profit Before Tax in H1 is some £0.8m (prior year: £2.8m).
We remain cautious about our prospects over the remainder of the financial year due to our usual lack of revenue visibility.
It's a huge reduction in PBT despite a relatively modest reduction in gross profit, which I believe is attributable to much higher staff costs after some new hires were needed to bolster the offering.
It's the old problem with investing in consultancies - the revenue split between staff and shareholders can end up primarily favouring the latter.
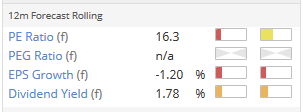
I reckon this is vulnerable to further de-rating.
Bioventix (LON:BVXP)
- Share price: 2700p (-2.4%)
- No. of shares: 5.1 million
- Market cap: £138 million
This is a new one for me, so I've been trying to get up to speed with it in response to reader requests for coverage.
It's a small company (13 full-time equivalent employees) which provides sheep-derived antibodies for use in medical diagnostics.
The royalty revenue model means that it gets a small share every time the large medical companies uses its products.
Vegpatch covered it in some depth on this website, last November. Here is the link.
Sales are abroad, mostly to the US, creating an additional layer of risk for domestic investors.
Results have been consistently sparkling, however, and these latest results (for the year ending June 2017) are no exception.
- Revenue up 31% to £7.2 million
- Profit before tax up 37% to £5.7 million
Stockopedia graphics do a neat job of summarising the company's excellent progress. They also show how the earnings multiple has become more volatile, and higher:
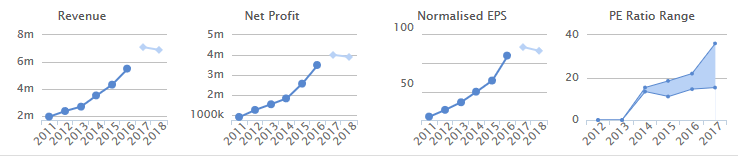
As you can see from the light blue dots above, (unrevised) expectations were for revenue and profits to stall in 2018.
This appears to make sense according to the latest company guidance. Though they have been overly cautious before, so perhaps we might get another pleasant surprise a year from now.
In relation to the most important vitamin D product:
Our prudent belief is that the vitamin D market will plateau in the near future. Nevertheless, we anticipate a modest further increase in vitamin D antibody sales over the next year as a limited number of smaller customers bring new vitamin D products to the market.
Furthermore, there is a specific license (in relation to a heart failure test using Brain Natriuretic Peptide, or "NT proBNP") which has been terminated, with the prospective loss of £1 million in revenue. Rather than continued growth in the short-term, it looks like merely replacing this lost revenue is the objective for now. And there is no clear-cut guarantee that this will be achieved in FY 2018.
The company explains recent developments in its industry and its overall competitive position as follows:
Within the field of antibodies, technology changes relatively slowly as new antibody technologies are validated and used... For example, we are aware that rabbit monoclonal antibody technology is established at some customers and this could have resulted in lost opportunities for our sheep monoclonal approach. However, we believe that having established our antibodies in customer products over the last ten years or so leaves our core business relatively secure due to the significant barriers to changing an antibody that works well in a diagnostic test.
"Relatively secure" - moderately safe, then!
Outlook statement includes the following:
For the financial year 2017/18, our challenge will be to make up for the approximately £1 million of lost sales mentioned above with revenues from the newly launched Siemens troponin project and modest growth from additional vitamin D antibody sales and royalties.
So they will try to replace lost revenue, but they may not.
My opinion
When a company has strong IP, high margins and high returns on capital, I think it's often worth paying a high multiple even when growth has slowed.
In that case, what you're paying for is the cash flow and for the strong competitive positioning.
For that reason, if I was holding this, I'd want to keep holding it. New buyers at current levels will need patience, however, because it's unlikely to see much earnings growth in the short-term, and the earnings multiple looks about as high as it can bear. It looks interesting on a 2-3 year horizon.
Spectra Systems (LON:SPSY)
- Share price: 88p (+8%)
- No. of shares: 46 million
- Market cap: £40 million
This is a somewhat mysterious (to me) security technology company, whose shares multi-bagged this year.
It has historically done a lot of work cleaning banknotes, but this year started branching out into new categories.
For example, last year it started producing specialty phosphours for a security thread manufacturer which it "believed" was working for a large Asian central bank. (Rare phosphours light up in special ways and are an important part of currency anti-counterfeiting measures.)
More recently, it announced an agreement with a US coffee system maker, so that its systems will only work for coffee cups which carry the correct signature.
So there is a lot happening to help explain why the share price has been so strong and Spectra has turned into a Super Stock.
Today we have news that ones of its key divisions has done extremely well this year:
Spectra Systems Corporation, a leader in machine-readable high speed banknote authentication and brand protection technologies, today announces that it has been informed by its covert authentication technology licensee, that royalties based on finished printed notes will reach a record level in 2017. As a result, Spectra expects that its profits for the year ending 31 December 2017 will significantly exceed market expectations.
Fantastic news, though it is tempered by an expected tapering in 2018. Next year, these royalties are projected to be "higher than average", but "not necessarily at these record levels". So there probably won't be year-on-year sequential growth.
Still, it's good news and this remains an intriguing story.
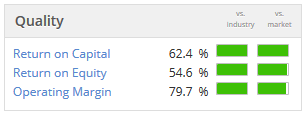
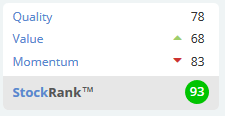
Overall, it's a bit too mysterious for me. Stockopedia really likes it though! Taking a purely quantitative approach, it looks excellent:
Thanks for reading! I think Paul will chime in with a few words on Revolution Bars (LON:RBG) if he gets a chance.
Best wishes
Graham
Revolution Bars (LON:RBG)
Share price: 187p (down 5.2% today)
No. shares: 50.0m
Market cap: £93.5m
(this section written by Paul Scott - at the time of writing, I have a long position in this share)
Proxy voting - this is a very important announcement. It appears that RBG shareholders are poised to reject the Stonegate 203p cash takeover offer;
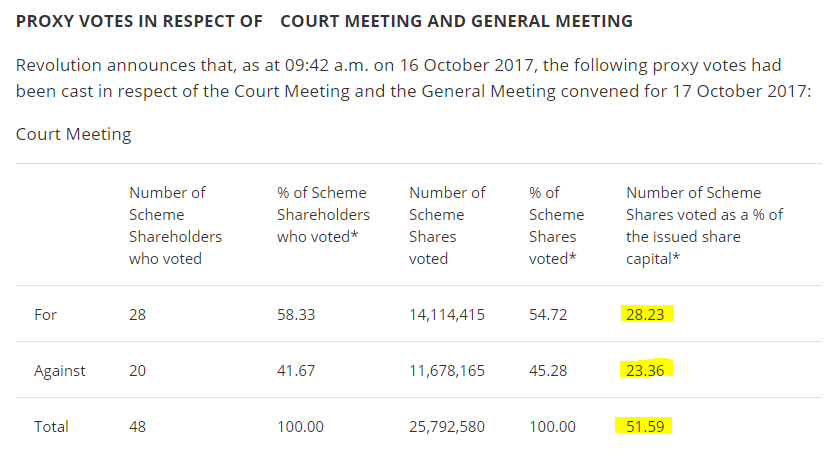
As you can see from the table above, although more shareholders have voted in favour, it now seems almost impossible that the necessary 75% vote in favour could be achieved. This triggered an immediate sell-off in the share, although it bounced somewhat within a short space of time, to end the day down 5.2%, on quite heavy volume for this share - of 2.6m.
Just 7 minutes afterwards, we got a short statement from Stonegate;
Offer update (from Stonegate);
Stonegate notes the announcement by Revolution on 16 October 2017 regarding the proxy levels for the Scheme.
Stonegate is considering its options and a further announcement regarding Stonegate's intentions will be released in due course.
My opinion (Paul Scott) - who knows what happens next? There now seems to be a very real risk that the Stonegate 203p offer could fail. In a way, I think that's good, as the price is too low. Although in retrospect, it clearly would have been better for us to sell up in the market at 210p a few days ago (and then buy back in, more cheaply).
What has changed, since the lows around 105-110p earlier this year, is that we now know that two potential trade buyers (Stonegate & Deltic) both think that RBG is worth a lot more. Stonegate are prepared to pay 203p in cash - so they clearly think that RBG is worth a fair bit more than that, otherwise they wouldn't be happy to buy it at that price! Deltic confirmed that for us, repeatedly saying that the Stonegate offer undervalued RBG. Unfortunately, RBG clearly didn't have the financial firepower to mount a credible counter-offer.
I'm not familiar with all the ins & outs of the Takeover Panel rules. However, a reader here who sounded as if he knew his onions, commented recently that by stating that their 203p offer price was "final", then that apparently prohibits them from offering a higher price for RBG. I don't know whether that's true or not.
It seems to me that RBG is clearly in play, is a terrific business earning excellent returns from its existing & new sites. Although it is up against well-publicised industry & macroeconomic headwinds - weakening demand, and cost pressures.
We'll just have to wait & see what happens next. My view is that, as RBG probably now won't be sold for 203p, because RBG shareholders think that price is too low, then it's either going back to being a private company, or someone else might come along and bid for it, at a higher price.
The share price is perhaps most likely to drift down in the short term, but I see good long-term upside. Also, if many RBG shareholders are prepared to reject an immediate 203p cash offer, then you imagine they would be happy to buy in the market, if the share price remains below that level. Mind you, you can't be sure about that - because there are effectively two markets - institutions, and private investors. Its the small trades from the latter that tend to set the share price. So the price could go anywhere, on small volumes, nobody knows.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

36 comments
Regarding SPSY & their more recent area of application; the coffee machine identifier is I believe for Coffee Capsules, not Cups; No doubt to prevent copycat cheaper capsules muscling in ; as they have done with 'Nespresso' That of course could limit the sales of the coffee making machines if buyers realise they are limited to high cost coffee capsules.
I used to hold SYS1 back in the Brainjuicer days. I gave up when it produced two successive trading statements. The first announced outperformance but then noted that most of the benefit of that would go to staff due to the incentivisation scheme. The second was a profit warning a few months later that turned out to have minimal impact because it meant the staff didn't get their bonuses.
At that point I put it in the "too hard" pile, and moved on ...
timarr
Peter Harrison (£bvxp) has sounded a note of caution on Vit D antibody royalties on more than one occasion.
16/17 Interims
"The roll out of our customer’s vitamin D assay products has advanced further towards completion."
15/16 Prelims
"This roll out process has advanced but is not yet quite complete and we remain optimistic that revenues from vitD3.5H10 will continue to grow modestly over the next year."
14/15 Prelims
"This roll-out process has advanced but is not yet quite complete and we remain optimistic that revenues from vitD3.5H10 will continue to grow over the next year or so."
Obviously, this could be the year though it would strike me as a bit unusual for organic growth of 24% to drop to "modest" in a single year. That would be a pretty drastic deceleration.
I was encouraged by the new found disclosure bug that saw them reveal some of the growth rates of the "core" portfolio. Testosterone (market entry 2009) £600k, +12%. Virtually every high throughput diagnostic company uses the BVXP antibody. T3 (market entry 1995) £500k, +33%. Estradiol (market entry 2010) £300k, +30%. Progesterone (market entry 2013) £200k, +51%. (Market entry referenced from the portfolio slide in the VegPatch post Graham linked). Those are very strong growth rates for products that have been in the market for quite a while. Those growth rates may not be all "organic" since they could include new licensees or a full year effect from a prior year licensee.
They have a big hole to fill with the loss of NT pro-BNP (which, incidentally, went from about £300k to £1m in about 4 years). I take at least some comfort that the growth rates for the "core" portfolio are very healthy and that Siemens HS troponin launched in May. Medium-term (2-3 years), they have some interesting things in the pipeline. Androstenedione was last described as already providing "meaningful" revenues. A non-exclusive test for HIV was last reported as in evaluation and four exclusive tests (cancer, viral, vitamin deficiency, thyroid) are also in evaluation. Longer-term (5+ years), secretoneurin (cardiac) and beta amyloid (Alzheimers) could be very interesting and the antibodies developed for these tests were described as "exciting" by a man not prone to hyperbole. I believe both secretoneurin and beta amyloid have diagnostic method patent protection which may mean 2% of a higher than normal test price.
Bioventix (LON:BVXP) - I was at the hospital today with my son (he has Duchenne Muscular Dystrophy) where he once again had a blood test to check his vitamin D levels. This is an important check now which wasn't routinely carried out when he was originally diagnosed. There have been studies showing that low levels of vitamin D can be detrimental in Duchenne (and I believe other neuromuscular conditions). So my son takes a vitamin D supplement and his levels are regularly checked.
This will be where some of the growth in vitamin D testing will be coming from. As the evidence base grows and clinical guidance is updated I think there is still growth left for vitamin D testing.
(long £BVXP)
Great detail, many thanks gsbmba99
gsbmba99
You seem to know the Bioventix (LON:BVXP) story pretty well having just read your post back in October.
The sp seems to have pulled back a fair way, below £20 at one time today from nearly £30 in October, although it had moved up pretty quick at that time.
Do you think the concerns are filling the loss of NT pro-BNP or do you think there is more to it, other than current market shenanigans? The stockrank rating is down to 66 and it has reached key support on the chart but on all other measures it looks like a quality company that I would like to add to my portfolio.
I would be pleased to learn your thoughts or those of other holders.
Thanks
Methinks price got ahead of earnings in what is a very impressive business
I will wait for more information before investing look's a bit ify to me, would like a few figures from previous years
Graham,
Re System1 - you comment:
It's a huge reduction in PBT despite a relatively modest reduction in gross profit, which I believe is attributable to much higher staff costs after some new hires were needed to bolster the offering.
It's the old problem with investing in consultancies - the revenue split between staff and shareholders can end up primarily favouring the latter
I can understand this comment but actually I think consultancies can be good long term bets. I hold Omnicom shares, and would consider holding shares of other ad agencies such as WPP (LON:WPP) and M&C Saatchi (LON:SAA). Both WPP and Omnicom are huge multinationals, but M&C Saatchi is quite small and so more comparable to System 1. But all three have delivered good results over time.
Part of the reason for this in my view is that, although advertising as an industry is undoubtedly cyclical, these companies all have very good client retention and a good degree of recurring business as a result. You can see this in Omnicom's financials in that it has very, very consistent operating margins, even in bad years (because it still retains clients and can scale down variable compensation to protect its margin).
So for me, System1 is potentially investible. But the difficulty for me is:
-it seems to have a less stable recurring client base than the ad agencies I mentioned. This seems to be a structural feature of the type of project it works on
-it is suffering increased competition.
So I worry that other agencies will simply copy its offering and it won't be able to retain clients.
Could get interesting if it drops further but at the moment I'd feel safer in M&C Saatchi (LON:SAA).
Rgds
Phil
Hi Phil. Not sure that advertising agencies and market research agencies are really alike enough in their businesses to read across directly like this.
Yes, there is a lot of low-margin, pass-through revenues with the advertising agencies. Quite different businesses versus market research companies. But I agree with Phil's other ideas.
Re Revolution Bars (LON:RBG) - share dropping. From RNS re proxy votes it looks as though Stonegate deal could well be voted down.
http://www.lse.co.uk/share-regulatory-news.asp?shareprice=RBG&ArticleCode=v1d0vh0b&ArticleHeadline=Proxy_Voting
Laughton...thanks for that,
So more than 75% of shareholders think Revolution Bars (LON:RBG) is worth more than £2.03. That should create a share underhang!
Ah - if only life were so simple.
When shoe retailers begin listing (especially if the current owners are taking significant cash off the table), it's a sure sign we're nearing the top of the market !
Barratts, Stead and Simpson, Jones, Brantano, Shoe Zone ....are just a few dogs that spring to mind!
If you want exposure to the ath-leisure shoe space, I'd just by some JD sports instead ! At least they have the scale and presence to be an important route to market for the big manufacturers which can offer preferential terms.
As an aside, it would be interesting to compare the returns rate of internet shoe retail vs general clothing. I find ordering shoes a bit more of a lottery online (in terms of getting the comfort and fit right).
Athletic shoes sell well on line across the world. Sizes on existing pairs are easy to check, so sizing is less of an issue than normal shoes or even clothes. This space continues to grow as it appeals to Gen Z's preference for easy, practical attire. Look at growth of brands like Netshoes in Latin America, which is Nike's biggest client in the region. The market opportunity seems robust to me. Also, I don't think Nike will want to become too dependent on Amazon. I believe that they will continue to drive "cool" new stock through high quality retail partners like JD.
Hi Graham. Please can I second Bioventix (LON:BVXP) for you to run the rule over? Thanks.
Yes, I'll look at BVXP now.
EBITDA already excludes depreciation but your broader point about costs being artificially lowered leading up to IPO remains...............
Good catch, many thanks.
There a jump in Mobile Streams (LON:MOS) today on high volume but no news. Was it tipped somewhere?
Hi Graham/All
Not sure if I am missing something...but the news that there will be no higher RBG bid seems to have pushed the shares down by around 7%...and unless the AGM votes against accepting the bid 203p will be paid on 23rd October.
It would seem logical for any major shareholder who is voting against the Revolution Bars (LON:RBG) offer to sell their shares ahead of the AGM, if they conclude that the AGM will vote it down.
Hi FREng.
I don't agree. I can think of at least two good reasons for institutions to hold onto their Revolution Bars (LON:RBG) shares.
1. They might agree with the brokers' analysts and many commentators that the Stonegate offer is at an undervalue. Hold onto their shares, vote down the offer, maybe buy some more from the short term speculators who are off loading and hold for the long term.
2. Tactically, demonstrate to the likes of Stonegate and their advisers Barclays, that insti shareholders won't simply roll over at the first sniff of a hardball approach on a takeover. Next time, for this or another bid situation, they might think twice about trying to strong arm the likes of Artemis and may be more willing to negotiate a sensible price. Bidding for a public company is an expensive process, especially when it fails. Lots of unpaid fees and third party costs to be picked up. Also a fair bit of reputational egg on face as well.
Gus.
Gus (re £RBG)
I thought of (1), but wouldn't it make more sense to sell and then buy back when the price was lower? There seems to be plenty of liquidity.
Your (2) seems to be adequately demonstrated by voting the deal down. Whether they then hold is a different decision.
But I'm not an institution, so I don't have a good insight into the considerations that motivate those who deal in such high quantities of shares.
Anyway, the market will do what the market does. The decision I have to make is when to buy some more, since I think the current SP seriously undervalues the business medium term, even though trade seems poor at the moment.
Hi, I think Paul is preparing a section on RBG!
Yes - you are missing the fact that the Court meeting needs 75%
The proxy deadline has passed so somebody would have to physically turn up at 10 a.m. tomorrow at the meeting with authority to exercise the vote for 20,920,080 shares to get to 75%.
Re Footasylum.
After several decades in the software industry, I have a rule to sell any company that announces a major IT upgrade programme, so I'm not interested in the IPO.
ah, the shoe shop event horizon cometh.
Hi Graham,
Could you have a look at Spectra Systems (LON:SPSY) if you get time. You've looked at it at least once before, It's an interesting company which I've just bought some of for the first time this morning.
It makes "machine-readable high speed banknote authentication and brand protection technologies". It sells through third parties to 18 central banks, and seemingly has very little visibility itself on what these banks are doing or likely to want in the future. They have put out (another - prev. on 21 August) significantly outperform trading statement today, on the bank note technology. Good SR93 as of before this update (Q78 V68 M83). The update today was that it already knows today that royalties based on finished printed notes will reach a record level in 2017, and therefore profits will significantly exceed expectations. EPS was stated as 4.7p, so it could now be approx. 5.2p - 5.7p. The PER isn't super cheap, but it would be approx. 15-16 for this year. I think it has net cash. The year end isn't until 31 Dec., so there is a while to wait, but it bodes well.
This doesn't seem to take into account any of Spectra Systems (LON:SPSY) brand protection business either.
Thanks
Chris
HI Chris
I have been a holder for a while now and I think it has good growth prospects and there is certainly some momentum behind the business at present. I also think the broker estimates are very conservative.
The share price has been depressed over the last 6 weeks or so in the face of very positive updates. My gut feel is that there is a seller trying to shift a fair amount of stock.
Thanks
Ric
Hi Chris, thanks for flagging that up for me. I've taken a look at it now, although to be honest I do find it a very difficult one!
Best wishes
Graham
My morning smallcap tweet:
Augean (LON:AUG), Acal (LON:ACL), Bioventix (LON:BVXP), Low & Bonar (LON:LWB), SysGroup (LON:SYS)1, Spectra Systems (LON:SPSY)
Augean (AUG) Trading dismal. CEO gone. "Augean remains in active discussions with HMRC with regard to a landfill tax assessment. The impact of the HMRC assessment, which the board believes will not be resolved imminently, as well as a continued weaker trading performance, is expected to lead to full year profit being below the level of 2016 with 2018 also expected to be lower than previous expectations"
Acal (ACL) Exp FY earnings slightly ahead of board's expectations.
Bioventix (BVXP) FY rev beat at £7.2m. Pretax £5.7m up 36%. Warns on troponin test take-up? "The rate at which this new test will be adopted by Siemens customers in hospitals in the EU, Asia and elsewhere outside the US is unfortunately not something of which we have detailed knowledge. Whilst it is clear that a quicker test will be of benefit to patients, clinicians and hospital budget holders, it is also clear that there is likely to be an education period during which clinicians become comfortable with a significant change in diagnostic practices that can result in non MI (i.e. patients not having a heart attack) being released from A&E much earlier. We will develop a better understanding of this matter during 2018." Div 31p. FY div 51p + special div 40p. I hold.
Low & Bonar (LWB) FY warning? Civil Engineering subs poor due to weak demand for higher value specification projects. Raw material prices have not fallen as anticipated. However board expects the Group to show good progress overall for the year.
System1 Group (SYS1) H1 trading: Gross Profit (the Company's main top line performance indicator) is 9% lower than prior year. I guess they mean 900bp. Prev guidance 6-11% lower. Pretax £0.8m (£2.8m).
Spectra Systems (SPSY) FY profit will significantly exceed market expectations due to record royalties. "Expect the royalties to be somewhat higher than average next year although not necessarily at these record levels."
Anyone a holder and aware of reasons for the drop in £NTBR? I cant see any news.
Hi Graham, any thoughts on Bioventix (LON:BVXP) results this morning?