Small Cap Value Report (Mon 17 July 2023) - CTO, MEX, CRW, DNM, UBG, DFS, GHE, BRCK, VINO, CNC

Good morning, it's Paul & Graham here today.
Today's report is now finished. 10 companies today, whoop whoop we're on fire!!
Podcasts - there was only 1 from me this weekend, as I was busy on Sunday watching the exciting tennis final and cooking a roast for Mum, on her 86th birthday! So no macro podcast, but I didn't have much material this week anyway. My main point was going to be the very positive news on rapidly falling inflation in the USA, which I think augurs well for the direction of travel here in the UK too.
So my overall macro/market view remains: nervous short-term, but bullish medium-term, and excited by all the great value shares that the UK small caps market is currently offering us. This seems to me the time to be holding our nerve, and embracing the value in UK small caps, not getting despondent and selling (probably at or near the low).
Also, the main theme we're hearing from individual companies at the moment seem to be -
- Supply chains improving, and
- Inflation easing.
So despite question marks over demand, and the possibility of a recession triggered by large, and (too) rapid increases in interest rates, there are also nice tailwinds which could offset the negatives for some companies.
Mello Monday - starts at 5pm online this evening. Renowned fund manager Christopher Mills will be doing a presentation, and I'll be on the BASH twilight session (when most people have probably nodded off!) at the end, giving an update on strong performance from Renold (LON:RNO) (I hold), which we covered in the SCVR last week here.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
Summaries of main sections below
Tclarke (LON:CTO) - up 4% on Friday to 136p (£60m) - Half-year Report - Graham - AMBER
A solid set of interim numbers from this diversified construction and engineering firm with particular expertise in data centres. Expectations are for a big H2 and a record £500m of total revenues. I am happier being neutral on the sidelines after recent fundraising plans.
Tortilla Mexican Grill (LON:MEX) - 81.5p (pre market) £32m - H1 2023 Trading Update - Paul - AMBER/GREEN
An in line trading update for H1. I take issue with the company quoting adj EBITDA as a measure of profitability, when actually the lease and depreciation charges wipe out almost all of it! I run through the bull & bear points, and wonder if this might be getting into buying range for a contrarian/recovery situation once macro improves?
Craneware (LON:CRW) - up 2% to £14.85 (£503m) - FY23 Trading Update - Graham - AMBER
This US-focused software business, serving the healthcare industry, provides a nice update to its shareholders; revenue is at the upper end of expectations at c. $174m. If you value this through UK eyes, it’s expensive, but it’s probably cheap through an American lens.
Dianomi (LON:DNM) - down 40% to 47p (£14m) - Trading Statement - Graham - AMBER
H1 revenues are down 18% at this digital advertising company, which seems partly due to macro issues but probably also some company-specific failings. The stock IPO’d at 273p and perhaps shareholders have suffered enough. There’s still c. £8m in the bank balance.
Unbound (LON:UBG) - shares suspended at 0.75p - Paul - RED
As expected, this unsuccessful project has reached the end. It's bust basically, and the operating company is being placed into administration. There's nothing in the group holding company either, where liabilities exceed likely asset realisations. So that's a zero for UBG shareholders I'm afraid.
I ponder the lessons to be learned below, and what I can learn from my misplaced initial (moderate) enthusiasm for this project. Apologies again for initially getting this one wrong. Although to be fair, we did turn negative on it quite a long time ago, once it became clear that things were going wrong.
DFS Furniture (LON:DFS) - Up 1% to 115p (£269m) - Trading Statement - Paul - RED
Year end trading update says this market leading furniture retailer is trading in line with (greatly lowered) forecasts, making around £30m aPBT for FY 6/2023, and expecting only slightly more for FY 6/2024. No mention of the sizeable net debt it recently ran up, to recklessly pay divis & fund buybacks. Precarious balance sheet means I have to maintain my high risk, RED opinion. But, as a recovery trade, it might have some merits for risk-takers, once macro worries have eased?
Gresham House (LON:GHE) - Up 55% to 1056p (£404m) - Recommended Final Cash Offer - Paul - N/A
Well done to holders of this fast-growing alternative asset manager, which announces an agreed cash bid at a lovely 63% premium. Could the whole sector now be too cheap maybe? A few general thoughts from me below, although I'm not at all familiar with Gresham House.
Brickability (LON:BRCK) - Up 2% to 56.5p (£169m) - FY 3/2023 Results (audited) - Paul - GREEN
Good, in line results for FY 3/2023, plus an in line current trading/outlook section too. Balance sheet & cashflow statement both look fine. Looks astonishingly cheap on a PER of c.5x, but the market must be pricing in a sharp slowdown. Tempting to start nibbling at this, taking a longer-term view, but I'm nervous shorter-term. EDIT: I've upped my view from AMBER/GREEN to GREEN, because a subsequent webinar with mgt was excellent, and addressed my macro concerns. They're already forecasting for a 20% drop in demand re private housebuilding, saying that's in the forecasts.
Virgin Wines UK (LON:VINO) - Unch 29p (£16m) - Trading Update - Paul - AMBER
In line with previously lowered expectations for FY 6/2023 is today's message from this wine subscription service. It was an opportunistic IPO in the pandemic, which has since unravelled, as most of them have. Only £0.5m profit now expected, but with plenty of cash in the bank, the downside risk seems quite low. Could be a recovery/turnaround, but not one I can muster a lot of enthusiasm for.
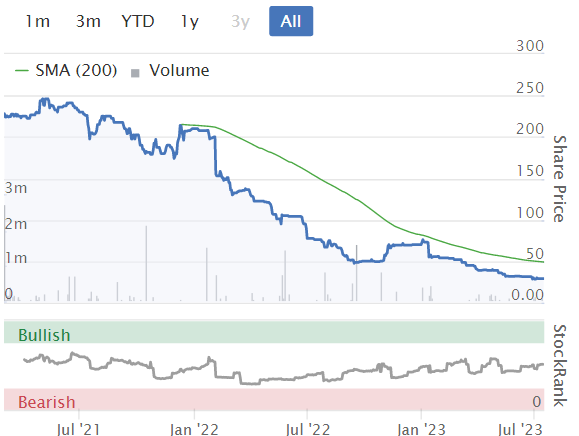
Concurrent Technologies (LON:CNC) - Up 22% to 70p (£51m) - Trading Update - Paul - GREEN
A cracking trading update today, with Cenkos raising forecast profit by 29%. Supply chain easing, and the customer orders are piling up. So this is now looking very interesting! Recent problems over accounting adjustments can probably now be disregarded. I'm happy to go GREEN on Concurrent, thumbs up!
Paul’s Section:
Tortilla Mexican Grill (LON:MEX)
81.5p (pre market) £32m - H1 2023 Trading Update - Paul - AMBER/GREEN
Tortilla Mexican Grill plc ("Tortilla"), the largest and most successful fast-casual Mexican restaurant group in the UK, provides a Trading Update for the half year ended 2 July 2023 ("H1 2023", the "Period").
Overall trading is in line -
The Board remains confident in the Group's ability to deliver FY 2023 results in line with market expectations1.
1 Company-compiled consensus: FY23: revenue £69.8m, Adjusted EBITDA £5.0m (Adjusted EBITDA defined as statutory operating profit before interest, tax, depreciation and amortisation (before application of IFRS 16 and excluding exceptional costs) and reflects the underlying trading performance of the Group)
I disagree that adj EBITDA reflects the underlying performance of the group. Looking at the FY 12/2022 Results, adj EBITDA was £4.0m, but that became a loss before tax of £(0.9)m. So EBITDA looks to me an unrealistic measure of financial performance. There are large entries for depreciation of the fixed assets (shop fits), and big IFRS 16 lease entries, which render the cashflow statement completely useless, even gibberish really - not the company’s fault, but rather the geniuses at the accounting standards organisations, who came up with this deeply flawed way of accounting for leases.
However, what we can probably all agree, is that were MEX to operate in a steady state, not opening any new sites, then it would be nicely cash generative.
Other points today -
H1 revenue up 22% to £32.7m (helped by new store openings in H2 LY, and H1 TY).
LFL (same stores) revenue up 8.4% - that’s pretty good in the current conditions I think, and means it should be absorbing inflationary increases in wages, in a labour-intensive business.
Franchised stores “performed very well”, further expansion planned.
3 new sites opened in H1 (2 company operated, 1 franchised), total now 85 sites - so there should be plenty more suitable sites to expand into, in the UK.
Net bank debt is minimal, at £1.6m - as expected, it says.
Efficiency & cost-saving measures have helped.
“Some easing of cost inflation in relation to certain key food ingredients” - I think this relates primarily to meat prices, which shot up last year.
Paul’s opinion - I’ve been sniffing around this share since it listed, as something I’d like to possibly take a small stake in personally, when the time is right.
The bull case being -
It’s an appealing format with attractive shops, serving tasty, fairly healthy, affordable, filling meals (it’s one of my personal favourites).
Repeat business from customers once they discover it.
Roll-out of new sites on attractive lease terms, with a lot of the capex being funded by landlord contributions, so it’s a good time to be expanding, and more sites dilutes central costs.
Has coped with multiple macro shocks, particularly food price inflation (very high for meat), and energy costs (now being hedged).
Management seem sensible & competent (subjectively) - I've met the CFO, but not the CEO.
Potential to increase margins, as inflationary pressures ease/reverse?
Holding its own, with decent LFL sales growth of 8.4% in H1.
Bear points -
Not really making any money! Although that’s in a tough macro environment.
Incredibly tough, competitive sector - so why invest in anything here?
Weakish balance sheet, with negligible NTAV, which limits expansion plans.
Lots of competition - esp in London, where Mexican-style food is growing in popularity (although competitors are mostly not very good, in my opinion).
Illiquid shares, with only 25% free float, with 4 big holders owning over half - delisting risk?
Overall - looking forward say 3-5 years, I think this share has the potential to be a much bigger, and more profitable group. Although at this stage, it’s a bit of a leap of faith, but not that much really - because we’re probably over the worst in terms of cost pressures.
LFL sales growth of 8.4% in H1 is a solid performance in a tough market, which makes me feel this brand/concept is now proven in all market conditions.
I’m not ready to go GREEN on Tortilla just yet, but think I’ll ease in that direction with AMBER/GREEN.
Too expensive when it floated (like nearly all IPOs!) but given a solid update today, this looks overdue a bounce. Trouble is, there could be unwilling institutions selling the background, so price could remain depressed for some time, who knows?
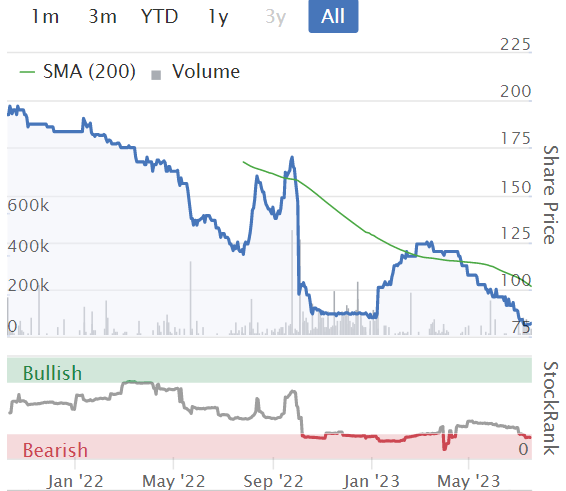
Unbound (LON:UBG)
Shares suspended at 0.75p
A sad postscript for this share, which was the remnants of Electra Private Equity, after all the other assets had been sold off, or in the case of Hostmore (LON:MORE) split off into a separate listing (which has also been a disaster).
Anyway, Unbound (Hotter Shoes), is where naive (and dishonest, as I’ve mentioned before - they denied to me that a fundraising was being done, when they were in the process of doing one!), prolific buzzword-wielding management have completely failed to execute their plan. It was also floated with too much debt.
The main part of Electra was Hostmore, so the shares we got in Unbound were always a bit of a bonus if it worked, but not particularly material overall. Sadly it just hasn’t worked.
Here at the SCVR, my initially quite positive thoughts about the potential (based on forecasts at the time), turned to negative comments quite a while ago, once it became clear the project wasn’t working as planned, and management failed to achieve the forecast profitability. Mind you, most of the shareholder value had already disappeared by the time it became obvious that the shares were not worth holding.
This is par for the course with micro cap investing I’m afraid - lots of them do go wrong.
Sceptics were right to dismiss UBG shares.
Rather than try to blame other people for our investing mistakes, I find it’s better to look for the signs of what went wrong, and avoid similar situations in future. Hence, with hindsight, these strike me as things I should have put more emphasis on at UnBound -
- Relying too much on broker forecasts, when there wasn’t a proven track record.
- The physical stores business of Hotter Shoes had failed, so why would it work online?
- Naive, inexperienced management, spouting trendy buzzwords all the time (this infuriated a lot of us at one of their online presentations, I remember the discussions afterwards here)
- UBG retained too much bank debt, and this wasn’t obvious until its first standalone accounts were published - so I must check more rigorously what debt new floats have, if any.
- Several zooms with apparently credible Electra management, allowing them to pull the wool over my eyes.
For speculative shares, I think using an informal stop loss might be a good idea.
Averaging down on shares which are failing, is a disastrous strategy (thankfully I didn’t, as I ditched them) - as emphasised by both Paul Hill recently, and the Naked Trader interview with our Megan (I started listening over the weekend, the recording is here) -
I’m sure ACounsell will post his usual post on UBG, blaming me for an investment that went wrong. So I thought I’d get that in first! As we always say though, all we can do is review the facts, figures, and forecasts at any specific point in time. When the facts change, we change our mind, which is what happened on UBG. But on reflection, I should have been a lot more sceptical initially, so please accept my apologies again for that. Lots of speculative micro caps go wrong, which is why we’re sceptical on nearly all of them here. But I probably need to raise the bar even higher, so that another UBG doesn’t slip through the net.
DFS Furniture (LON:DFS)
Up 1% to 115p (£269m) - Trading Statement - Paul - RED
DFS, ("DFS" and "the Group"), the market leading retailer of living room and upholstered furniture in the United Kingdom, announces the following update for the 52 week period to 25 June 2023 ("FY23").
FY23 profit within previously guided range
Group achieves record market share
However, profit has halved from last year -
Underlying profit before tax and brand amortisation for FY23 in line with previous guidance at slightly above £30m despite the market being significantly worse than expected
To put that £30m aPBT figure in context, it was £60m last year FY 6/2022, and £109m in FY 6/2021.
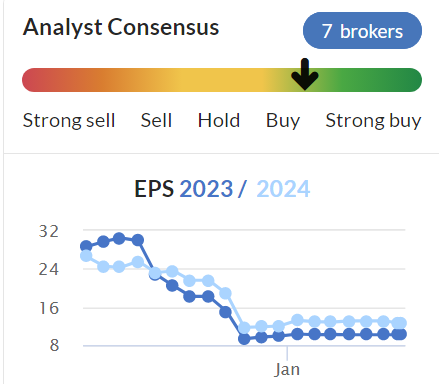
Look at how much market forecasts had already been lowered, so meeting these low targets is not good news, it’s just not any worse than expected -
Other points -
Impressive market share claimed of 38%
Gross margins improved as freight costs reduced.
Consumer demand is soft, “market volumes down by c.15-20% across FY 23” - it’s unclear whether this is company-specific, or the market generally?
Current trading - “consistent with the Board’s expectations”.
Outlook - only a slight recovery expected -
Expect to continue to outperform a declining market in FY24 and grow market share delivering low single digit £m profit growth…
We currently expect market volumes to decline by mid-single digits for the full year, however, the economic outlook remains uncertain. To that end the business has been prudent in its planning, is taking actions to maximise operating cashflow through continuous margin improvement, delivering cost savings and reducing capital expenditure. Despite the ongoing pressure on market volumes, we expect underlying profit in FY24 to be slightly above FY23 levels, supported by the Group's leading brands, scale and well invested integrated retail proposition.
When the market recovers, given our increased market share, the operating leverage within the business and our negative working capital cycle, we are well positioned and remain confident in delivering our long-term targets of £1.4bn of revenue, an 8% profit before tax margin and 75% post tax free cash conversion driving strong returns for our shareholders.
Nothing is said about cash or debt. That’s a key (deliberate) omission, because the main risk with DFS is that management launched a reckless debt-fuelled dividend and buyback programme, at a time when profit was heavily falling. What on earth were they thinking?
Net bank debt was £135.6m at Dec 2022. That sounds a lot for a company that’s only made a profit of about £30m in FY 6/2023, and only expects a little more for FY 6/2024.
Balance sheet - is a big problem. NAV was £230m at Dec 2022, but included £535m of worthless intangible assets. So NTAV is negative £(305)m!
Where has all the customers cash gone? They’ve spent it, and run up bank debt on top, to pay for divis & buybacks.
Hence the whole business is financed by bank debt and supplier credit - very high risk I’d say. Smaller SCS (LON:SCS) is the opposite, prudently sitting on piles of customers & its own cash.
Paul’s opinion - this is a good business I think, but run by reckless financial engineers, who’ve plundered the balance sheet in order to pay unjustified & unaffordable shareholder returns.
That just makes it too high risk for me, as any further downturn in trading could put the whole rickety structure in danger of collapse (if bank, and/or trade credit insurers, get cold feet and pull cover - the sort of thing they do in economic downturns).
The strange thing is, DFS sailed close to the wind in the pandemic, but managed to get a rescue equity raise away on quite good terms, I remember. You would have thought such a close shave would have made management more prudent, but the opposite seems to have happened - instead of hunkering down, they instead decided to max out the overdraft to pay divis & do buybacks more recently.
Looking for positives, for balance, DFS shares could do well in a cyclical recovery, and there’s no doubt DFS is fundamentally a decent business. But investors also need to be aware that its extremely weak financial structure means you’re taking a big risk here.
There was chatter about the intentions of a Polish furniture manufacturer which has a c.10% position in DFS. A possible takeover maybe? Or any deep-pocketed overseas buyer might see merit in buying DFS to get an instant 38% market share of the UK market. So I can see strategic value in the company, and debt might not worry such a buyer.
DFS cannot afford to pay any more divis, so I would treat the yield as being irrelevant.
On the upside, the stock market has ignored balance sheet risk at DFS before, so looking at the chart below, a soft landing might see a repeat of the 2021 rally perhaps? So it might be an interesting share to trade, for risk-takers.
The balance sheet position is so awful, that I am compelled to maintain a RED opinion on this one. Why take the risk, when the macro situation is so uncertain right now?
Gresham House (LON:GHE)
Up 55% to 1056p (£404m) - Recommended Final Cash Offer - Paul - N/A
This is not the usual bid talks in progress type of announcement (which often fall through). This is a proper, agreed takeover bid at 1105p, by Searchlight Capital Partners LP. - whose website says it has $11.6bn assets under management, and has made 40 private equity investments. I’m assuming it’s US-based, with the contacts page showing 3 North American offices, and one in London.
Gresham House calls itself
“A leading specialist alternative asset manager focused on sustainable investments across a range of strategies, with expertise covering forestry, real estate, sustainable infrastructure, renewable energy, battery storage….”,
with c.£8bn assets under management.
The offer is a very good premium of 63%, which I’m sure shareholders will be secretly delighted with (after having made the customary public complaints about how disappointed they are!)
I’ve skimmed a bit of the announcement, and it’s basically saying that the public market hasn’t rewarded Gresham House with a valuation it believes it merits, having grown very strongly from almost nothing about 9 years ago. Clearly the bidder agrees.
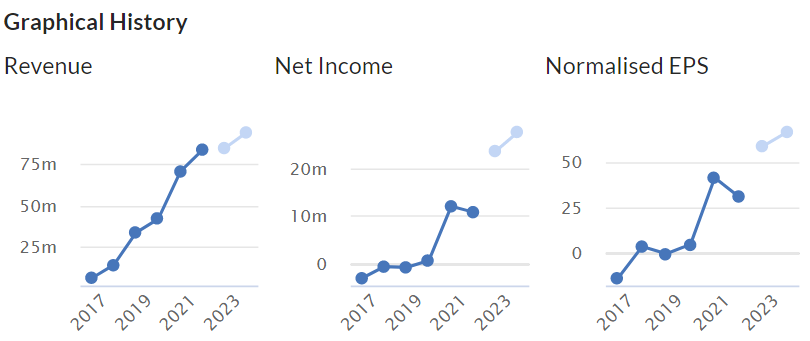
Gresham House’s growth track record does indeed look really impressive, as you can see below. Although it can be tricky to ascertain whether profit growth like this is sustainable, when they come from nothing, and grow very fast -
Paul’s opinion - this looks a generous premium, but that’s about as far as my view on it goes, as it’s not a company we’ve covered here before I’m afraid.
Although as others have said, it does add credence to the idea that the whole sector might now be cheap.
We’re given one clue on valuation, which could be useful to searching for other possible takeover targets in the sector -
The Acquisition implies an enterprise value multiple of approximately 15.9 times Gresham House's EBITDA for the 12-month period ending on 31 December 2022.
Graham’s finished for today, but as our resident sector expert, maybe he could flag up any other promising potential bid candidates? He was right about Numis, for example. Although it’s often very difficult to predict bids, because bidders often see something quite intangible, usually structural growth opportunities, rather than just focusing on price.
Anyway, congratulations to GHE holders, it’s a lovely feeling when a takeover bid comes through at a decent price. The more bids we see coming through at big premiums, the more it should help rebuild market confidence I think, and of course gives the existing institutional holders a liquidity event, which provides the firepower to buy other shares.
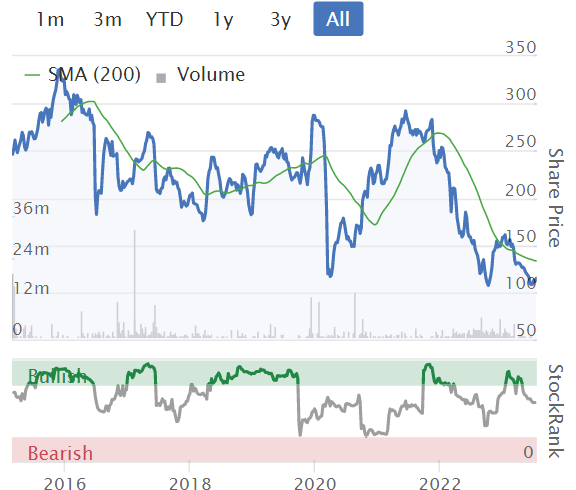
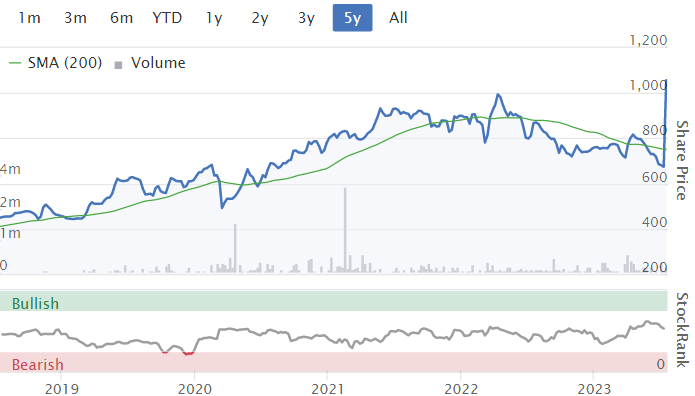
The agreed bid looks to be an all-time high too -
Brickability (LON:BRCK)
Up 2% to 56.5p (£169m) - FY 3/2023 Results (audited) - Paul - GREEN
Brickability Group PLC (AIM: BRCK), the leading construction materials distributor, is pleased to announce its audited final results for the twelve-month period ended 31 March 2023.
Good performance across all divisions
Impressive revenue growth +31% to £681m, nearly all from acquisitions.
Very low gross margin of only 16.6% (very slightly down on LY)
Adj Profit Before Tax (aPBT) up 29% to an impressive £44.6m.
Adj EPS up 19% to 11.9p (LY: 10.1p)
PER only 4.7x
Net debt modest at £8.0m.
Total divis up 5% to 3.16p - yield of 5.6%
What’s the catch then, why are these shares so cheap?
Outlook - there doesn’t seem to be any sign of a slowdown as yet -
As previously announced, and whilst remaining conscious of the challenges in some of our segments in the short-term, the Group believes that the underlying long-term demand for UK housing remains robust as does the demand for quality materials for the construction sector generally. The Board remains confident that the Group is well placed to continue delivering on its strategic objectives and the underlying organic growth of the business and, notwithstanding a number of industry participants publicly communicating their own expectations of volume reductions in the near term, trading in the current financial year to date has remained in line with Board expectations.
Note that BRCK achieved broker consensus earnings for FY 3/2023, despite those forecasts actually being raised - completely the opposite of what I would have expected. The raises were probably due to acquisitions though -
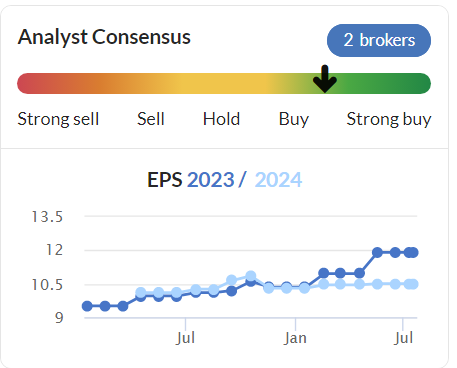
As you can see for the lighter line, the new financial year is currently forecast to show a fall in EPS from 11.9p actual for FY 3/2023, to 10.5p for FY 3/2024 - that’s not a bad starting point, with an assumption that earnings might dip. Although in my experience, when earnings do drop in cyclical sectors like this, they tend to drop a lot, not just a little! That’s what the low share price is telling us too.
I also wonder whether the tight supply, and hence rising prices, of building materials might turn into a glut, and falling prices, which often happens after supply disruption in many areas? The danger is, we could be valuing this share on peak, unsustainable earnings.
Balance sheet - is it shot to bits? Actually no. NAV of £175m is mainly intangibles (relating to acquisitions) of £152m, so I’ll deduct that, but also the (usually acquisition-related) £18.2m deferred tax liability. That gives me NTAV of £41m, which is OK I think.
Note that inventories are unusually low at £33m, which is because a lot of the products are drop-shipped direct from the manufacturers. Hence why BRCK doesn’t actually need a lot of capital, so overall it looks fine to me.
Cashflow statement - it looks a genuinely cash generative business this year and last year. That cash was spent on divis of £9.1m, capex of £7.2m, acquisitions £16.7m, with a £53m equity raise last year also helped boost cash.
There are a lot of moving parts here, but I don’t see anything of concern.
Paul’s opinion - in normal macro conditions, I would say this share looks very cheap indeed - a current year PER of just over 5x, and an in line current trading statement. Solid enough balance sheet, with only a little net debt. Generous divis too. It looks really good actually.
However, clearly the market is anticipating a profit warning, otherwise it wouldn’t be this cheap.
I’ve toyed with the idea of buying a few BRCK shares myself, but just imagined what a numpty I’d feel as the (seemingly almost inevitable) downturn in demand might come through, and forecasts get slashed, taking the share price down further. So cheap shares can often get cheaper, as I know only too well from previous mistakes!
I don’t understand why a (primarily) brick distributor can remain impervious to slowing conditions that we’re hearing from housebuilders. Is there a time lag effect maybe? I don’t know enough (well, anything!) about how demand for bricks works.
So this might be cheap for a good reason, or it could be oversold. I’m not sure which it is I’m afraid, so will have to stay neutral-ish, but leaning towards a positive view as the valuation is now so cheap. Let’s go with AMBER/GREEN.
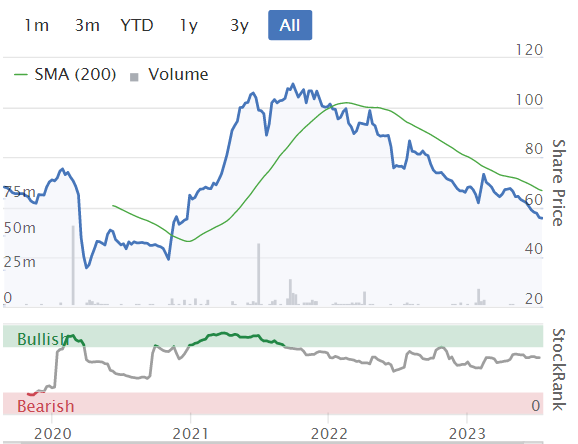
This chart is since it floated -
Virgin Wines UK (LON:VINO)
Unch 29p (£16m) - Trading Update - Paul - AMBER
Virgin Wines UK plc (AIM: VINO), one of the UK's largest direct-to-consumer online wine retailers, today provides an update on trading for the year ended 30 June 2023 (the "Period").
FY23 financial performance in line with market expectations; making progress with strategic initiatives
Performance during the Period was in line with expectations, with total revenue for the year of £59 million and adjusted PBT of no less than £0.5 million.
Virgin Wines maintains a strong balance sheet with net cash of £5.5m and no debt.
Given the plummeting share price, I think no more bad news is actually good news!
Quite a few things have gone wrong this year, including a warehouse IT system installation, causing disruption.
I last looked at VINO here in early May 2023, when it warned on profits. Surprisingly, I seemed to think it was looking tempting as a possible value/recovery punt “if it drops further”. It’s since dropped from 39p to 29p, but I’m finding it more difficult to see much upside potential, other than if someone bids for it. Gresham House (41%) and the CEO (8%) effectively control it, so there’s a risk they might take it private without paying a proper bid premium perhaps?
There might be recovery potential here, and the balance sheet is very good. The big question is whether the business is actually any good, or just an opportunistic float during the pandemic? I’m not keen on wine subscription services as investments. But as a value, special situation, VINO shares could have some potential upside from £16m mkt cap?
Its strategic growth plans are set to be revealed with results in Oct 2024, which could be a catalyst if the market views that positively.
I can’t decide, so will just go AMBER on this.
Concurrent Technologies (LON:CNC)
Up 22% to 70p (£51m) - Trading Update - Paul - GREEN
Concurrent Technologies Plc (AIM: CNC), a world-leading specialist in the design and manufacture of high-end embedded computer systems and boards for critical applications, is pleased to announce a trading update for the six months to 30 June 2023 ("H1 FY23").
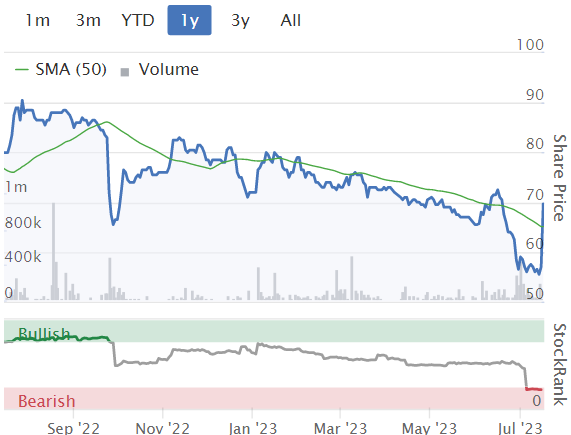
The 22% rise in share price today caught my eye. Although the 1-year chart shows this move to be a reversal of a recent sharp fall over accounting delays & gremlins -
This sounds really good actually - especially that order backlog of £29m -
Based on its unaudited management accounts for H1 FY23, the Company expects to report revenue of approximately £12M (H1 FY22: £7.4M) and profit before tax of approximately £1M (H1 FY22: £0.1M). This represents record first half revenues for the business and an increase of 60 per cent compared to the equivalent prior year period. The business is now operationally geared for a higher revenue outturn and is well positioned for future growth.
Order intake remains strong with H1 FY23 intake of £14.5M and an order backlog, as at 30 June 2023, of approximately £29M.
Supply chains “much more favourable and continue to improve”, but not yet back to normal.
Full year outlook - very nice -
The Board believes that the Company is in line to deliver revenues slightly ahead of current market expectations and profit before tax materially ahead of market expectations…
We are at an inflection point. Now that components are becoming more readily available, we will enter a period of growth. H1 FY23 revenue was a record first half for us, and I believe H2 FY23 will be better still.
**Consensus profit before tax expectations for 2023 are £2.7m
Broker updates - many thanks to Cenkos for an update note. It’s substantially increased FY 12/2023 forecasts, with new forecast PBT up 29% to £3.5m.
That’s 4.7p adj EPS, for a PER of 14.9x, which doesn’t seem excessive.
Paul’s opinion - I recall looking at this last month, when the news was negative, with accounts being delayed due to auditors questioning the capitalisation treatment, and prior year adjustments, which damaged the share price. Although as I said at the time, the positive outlook comments meant I was going to give CNC the benefit of the doubt.
I think today’s update will consign any concerns to history, with a smashing ahead of exps update, and that order book really impresses me. Clearly whatever CNC makes, is in high demand, and it’s making very good margins on it too.
Given this excellent update, I’m happy to shift from AMBER to GREEN. There’s something interesting going on here!
Graham’s Section:
Tclarke (LON:CTO)
Share price: 136p (+4% on Friday)
Market cap: £60m
Earlier this month, I switched back to neutral positioning on this stock due to a proposed £10m placing that I felt should have been unnecessary.
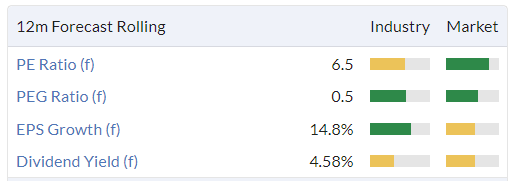
The headline reason for the fundraising made sense - a mammoth order book of around £800m that needed more cash to support it. But take a step back and you see that the company has been paying £2m in dividends every year. Due to the apparently low market cap (PER of 6.5x!), a £10m fundraise means 20% dilution. If management are shareholder-oriented, I think they should be highly reluctant to issue shares at this level. It just didn’t add up for me, so I abandoned my bullish view on the stock.
On Thursday, we had a double-whammy of news from the company.
Firstly, we had an RNS outlining how the CEO, MD, and FD were collecting nearly 1.3 million nil-cost shares (pre-tax) or 0.7m shares (after-tax) related to a 2020 share scheme. Based on the current share count, 1.3 million shares amount to nearly 3% of the company’s entire equity. This level of dilution to pay management isn’t unusual but in the context of the proposed dilution from the placing, it’s another reason for me to feel safer with a “neutral” stance on the stock.
We also had the company’s half-year results. Here’s the table at the top of the report:

As you can see, the order book (bottom row) is surging, although there is a delay in terms of improvement to the other metrics.
Trading is in line with expectations and the company reassures that “significant revenue growth is forecast for H2 2023”. They expect to hit their £500m revenue target (revenue in 2022: £426m).
They also argue for the planned fundraising:
The net proceeds of the Placing will further strengthen the Group's balance sheet and will provide additional resources with which to capture and deliver additional identified short to medium term attractive contract opportunities in the London business - in doing so driving further growth and margin expansion.
Operational review
There is no denying that business at TClarke is strong with the company very busy and likely to get busier in the months ahead. They are increasingly active outside London and the most interesting sector they work on is Data Centres, described as “our largest operational sector, with the expectation for further rapid growth in the second half of the year”.
Graham’s view
I’m much more comfortable with a neutral stance on this one now. Construction and engineering services is a sector I treat cautiously and I feel like it was important to change tack when I saw the dilution coming down the tracks here. The dilution disclosed from share options makes me feel more confident in this view.
The stock does remain “cheap” and will still be cheap after all of the new shares are issued. For this low price, investors can get one of the better businesses in this low-margin industry. The algorithms love it and it does enjoy a StockRank of 98. As always, you pays your money and you takes your choice.
Craneware (LON:CRW)
Share price: £14.85 (+2%)
Market cap: £503m / $658m
This is not one that we review very regularly but let’s take a quick look at this morning’s trading update. The company provides software to US healthcare providers. It seems to me that much of their work revolves around compliance with the US government’s rules for Medicaid drug pricing.
Their financial year has just ended (FY June 2023) and they saw “a positive close to the year”:
…revenue for the year is expected to be towards the upper end of current market expectations at approximately $174m, a 5% increase over the prior year. This has delivered an adjusted EBITDA increase of approximately 5% to over $54m which represents an EBITDA margin of 31% (FY22: 31%).
Annual recurring revenue improves to $169m, from $166m as of December 2022.
Bank debt is reduced to $83m and is offset by a healthy cash balance.
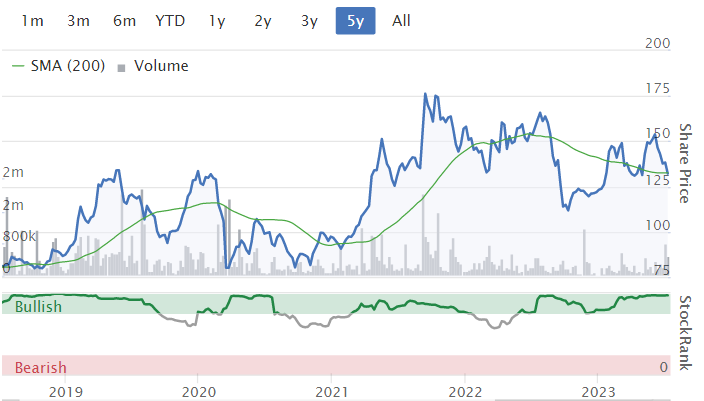
By my calculations, the company is trading at an EV/ARR multiple of 4.1x (enterprise value divided by annual recurring revenue). This would be considered very cheap in the US, but in a UK context I don’t think it stands out. The discount on UK companies versus US companies is something we are used to now; it’s about as interesting as rain in April. In other words, it’s a fact of life.
Buybacks: the company plans to continue buying its own shares, under previously announced plans to spend £5m on buybacks.
Outlook: there is “further sales momentum” helping to deliver a positive start to the new financial year (FY June 2024):
The Group's balance sheet strength, high levels of ARR and early signs of increasing customer confidence, leave the Group well positioned for FY24 and beyond.
Graham’s view
I’m tempted to go green on this one. The buyback (announced in May) is a nice sign of confidence, and hopefully we will see further debt reduction go hand in hand with this.
Maybe it comes down to your view on whether it is US or UK valuations that make sense.
If we look purely at earnings, this is on the expensive end of the spectrum
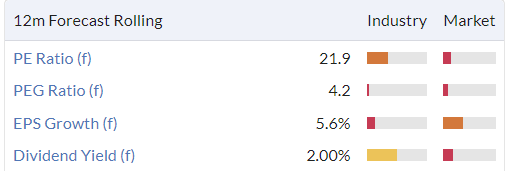
If, on the other hand, we treat it as a sexy “SaaS” business, then the ARR multiple is probably too low compared with its US peers.
I don’t have a strong view on this; I think that US valuations often look silly, but we can’t argue against the strong long-term performance of US equities. So I’ll continue to sit on the fence here.
Dianomi (LON:DNM)
Share price: 47p (-40%)
Market cap: £14m
Dianomi, a leading provider of native digital advertising services to premium clients in the Business, Finance and Lifestyle sectors, announces the following trading update for the year to 31 December 2023.
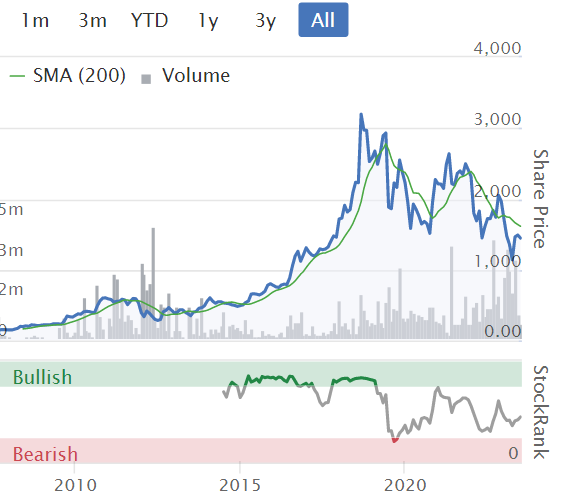
Commiserations to anyone holding this overnight. Dianomi is approaching levels where even lovers of micro-caps such as ourselves start to wonder if it is worth looking at!
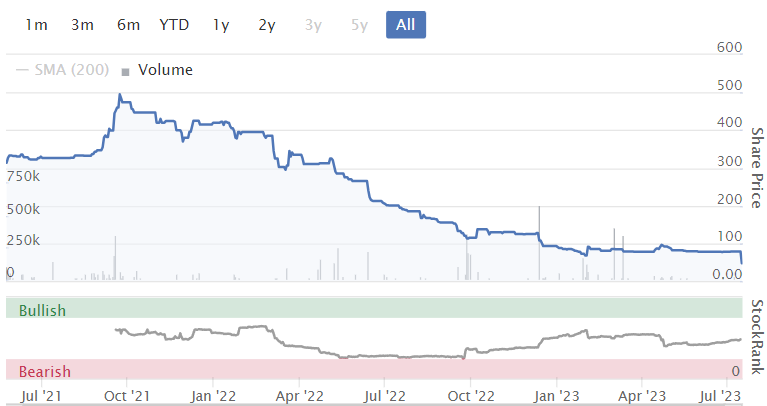
It’s another 2021 IPO that has gone sour:
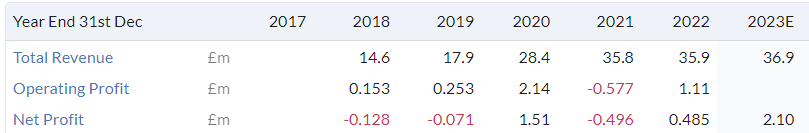
It has never made much money:
Roland took a look in April (share price then: 90p) and noted that the company reported net cash of nearly £12m. That’s pretty much the entire market cap now!
Here is today’s profit warning:
As has been widely reported, the decline in traffic volumes has been a key challenge for publishers in 2023. This trend is clear across Dianomi's direct publisher inventory with traffic levels across key publishers down by between 10-30% in the six months to 30 June 2023 vs the same period in 2022. As a consequence, while demand from Dianomi's 400+ premium financial and lifestyle advertisers has remained consistent with the backdrop announced at full year 2022 results, the reduced traffic across its publishers naturally impacts Dianomi's ability to generate revenue from the adverts it places on their digital properties. Furthermore, certain new publisher partnerships did not materialise in the expected timeframe to offset the decline in traffic across existing publishers, though they remain future opportunities.
So this is not just about declining traffic; it’s also about Dianomi failing to get deals that it was hoping for. That sounds like it may be a company-specific failing, not a macro issue.
The company also says: “Readership levels are also perhaps finding a new 'normal' level post pandemic.” How fortuitous that the company floated in 2021, before this new normal materialised!
Revenues in H1 are down c. 18% and new revenue guidance for the year is £30.5m - £32.5m (Stockopedia shows that the prior consensus estimate was £36.9m).
Cash has reduced all the way to £7m. The company does say that it expects improved cash generation in H2, and the cost base has been reduced by £1m.
Graham’s view
H1 revenues last year were £18m so I guess we are looking at c. £14.8m in H1 this year. If the situation has now stabilised (a big if!), the company’s new revenue guidance does look reasonable.
I would often give a stock like this the thumbs down but the fact that it does still have some cash to support it, and the derisory market capitalisation, make me think that shareholders might have suffered enough. If it falls much further it will be trading at its new cash balance (£1m was received from debtors at the beginning of H2, so it should have £8m now).
Therefore I am going to stay neutral for the third time today. These splinters are beginning to hurt!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

90 comments
Re Brickability (LON:BRCK) - both Ibstock (LON:IBST) and Forterra (LON:FORT) have large CAPEX projects coming to market with new capacity equivalent to 5-8% of GB brick demand in next 2 years. Being new, they will also be very cost efficient. Depending especially on your assumptions regarding UK vs European energy prices £:Euro, they will probably be able to displace a lot of brick imports - still Brickability's core business. Imports have been at record highs. On top of that there is a short term demand gap from fewer house starts from the 'Truss shock'/planning reform debacle. Brickability seem to have traded nimbly but I think they are a peaking and the UK-based vertically integrated oligopolistic brick players will win out in the end and which now represent the better/less risky opportunity over the 2-3 years period I want to invest over. The need for more building, housing & other, is only growing. Despite all this and the the CAPEX spending seeming to have gone OK, Ibstock (LON:IBST) is now trading close to pandemic lows (Disc. I hold Ibstock (LON:IBST)).
Having just watched the Investormeet presentation, it was made clear that companies like ibstock prefer to use BRCK as a distributor because they get a better price than dealing direct with house builders and are guaranteed the agreed take up of production. BRCK for its part has agreements with house builders to supply what they require despite completion or lack of availability elsewhere.
So far as importing is concerned, my understanding is that the type of brick imported differs from what is domestically produced in appearance and texture.
It was also stated that bricks is now just 45% of BRCK's revenues and that General construction is assuming a greater level of importance. The pipeline of acquisitions is also designed to increase diversification.
Hi Paul if you get a change in the future would you be able have a quick look at tissue regenix as it a really exciting company with great products. Would love to know you thought on the financial picture.
thanks in advance
Hi Olly,
I've just had a very quick look at Tissue Regenix (LON:TRX)
Its trading update sounds upbeat, and says its in line with expectations. Cash is "sufficient to support the current business growth plans", but doesn't give a figure, which is crucial for assessing a heavily loss-making, cash burning, equity issuing company like this. That's because dire market conditions mean any further funding needs could be punished with a deep discount, which seems to me that main risk. It had $5.9m cash at Dec 2022, plus an extended $10m borrowing facility to 2028. The cash was more than offset by borrowings of $6.3m, so checking out the terms of those loans is very important.
H1 revenues up 19% to $14.1m, a record high - so something interesting seems to be happening here. Although huge losses in the past, but it seems to be moving towards EBITDA breakeven, and reckons it will make an EBITDA profit in H1 2023.
$2.6m loss after tax for FY 12/2022 doesn't look disastrous.
Balance sheet is OK-ish, with about $15m NTAV at Dec 2022. Inventories looks very high - possible write-offs maybe?
Overall, I'd say this looks potentially interesting. The next step would be properly understanding its products, and markets, and growth potential, which is beyond my pay grade. But as requested, I've just done a quick review of the numbers for you!
Regards, Paul.
Hi Paul
Thank you very much for taking a look over this, it’s a massive help. Is there any particular way you would go about putting a value on this business.
thanks a lot
Olly
Hi Paul, I don’t hold Brickability (LON:BRCK) but I am watching it. Still clearly in a downward trend but it does seem to be getting cheap now. Regarding the company doing well despite the sector down turn, maybe it is to do with the fact that this country imports so many bricks to keep up with demand. With the current costs increases, import bricks are now down 40%. So is it possible demand for uk made bricks are not being affected as badly as imported brick manufacturers?
Sounds plausible, re imported bricks. We would need to consult someone in the industry. That would be a very good question to ask Brickability (LON:BRCK) management, if anyone talks to them.
Interestingly divergent views in meeting management/watching presentations. I tend not to bother nowadays, but I’m bloody glad I had a good look at Wandisco’s CEO. Totally failed my sniff test. See also Tremor, the jury’s still out on the share but the CEO put me right off!
Both scary then but it was all there in the accounts!
The first one the valuation never made any sense , and the second one after claiming to have so many millions in cash he then listed in the US as well to raise more cash to just buyback shares!
Unbound (LON:UBG) noticed this still getting a fair amount of attention and thought Paul's list of things to watch out for was very useful. In case of interest to anyone else, I did briefly hold this as part of Electra (which meant I also held TGI or whatever it's called now). However, a quick bit of research and I immediately sold (incredibly for a small profit I seem to recall).
Hotter clearly had long standing issues - the company had been loss making and forced to close all its stores. The broker notes looked incredibly ambitious on future earnings growth - why on earth would it suddenly turn itself around and spring to multi year profit growth?
As for TGI, I never liked the brand - very dated and overpriced and just struggle to see how it could make money in this environment. Worse, I found out they didn't even own the brand but had to licence it from the US parent company. Looking into the financials, the broker notes banged on about how good value it was, but all with reference to EBITDA. As a rule of thumb I halve EBITDA to get to actual profits and on that basis the company certainly did not look cheap at that time.
More generally, I was concerned that these were the last 2 Electra investments and they were clearly struggling to get rid of them. Putting all this together it was a pretty easy decision to sell - a good example of why you really need to do your own research, even if something looks good at first glance.
Virgin Wines UK (LON:VINO) Like plenty of companies I avoided this one simply because I didn’t, and still don’t, see what it’s USP is.
They sell wine
Nothing unique about that.
?
Paul, Just a quick note on Unbound (LON:UBG) mainly to say Thank you.
I wanted to write this as I was reading your comment that you want to get in first before "some" people may want to point blame.
I only started investing in 2020 - and was completely "green" then - chancing upon this site. And whilst I also personally bought myself after reading Stocko, and am still holding it to the death! (ah well) but I bought others that were mentioned on here and done very well.
On Unbound = the greatest lessons in life come from difficulty, as long as we all own our decisions and dont look to blame. That loss has been great for me as its been a tap on my shoulder to smarten up, and take responsibilty to learn more.
Noone ever said this site is like Motley fool - or the telegraph etc - where they tell you what to do (and hound you with marketing for Motley in particular).
So I would be highly disappointed if you or anyone who is contributing to this site (employeed or in the community) downgraded their comments - as I feel extremely lucky that I have a unique opportunity on here to be surrounded by many intellegent investors, both writers and those in the community, that I can learn from.
Without the site and all commentors knowlegde I wouldnt otherwise know where to begin to DMOR.
So, whilst none of us want to lose money, for those who want to blame - perhaps they should consider ETFs?
Thanks again Paul (+ others and community) this really is a great site!
Thanks for the review of Concurrent Technologies (LON:CNC) Paul. Pretty much mirrors my view when I read it this morning, seems the unscheduled? Trading Update caught the market by surprise.
Have held previously but it was always a solid company, net cash, but pedestrian EPS growth..tho didnt stop it being valued on a high multiple.
Miles Adcock came in 2 years ago(previously worked at QinetiQ and BAE I think) and looks to have put building blocks in place for much better future growth. If future earnings are to be believed (possibly could be beat by the sound of things) then this "should" be rerated onto a decent multiple again.
Good to hold a decent chunk of cash for just these situations, seems to be 1 or 2 every week right now.
To be fair, Concurrent Technologies (LON:CNC) bouncing as they start to recover from the component shortage has been flagged for a year or two now. They've regularly reported backlogs of almost finished cards awaiting the last chip or two for completion and delivery, or having to cannibalise newly completed cards for chips, and similar stories over the last couple of years. In fact this latest TU pretty much mirrors the predictions the CEO made last spring. I wrote up my notes last May so he probably said it April/May 2022. Of course it has been necessary to trust the reports that the orders weren't been cancelled and the order book was building up. And it is hard to remain patient when it takes longer than expected. I was certainly starting to have real doubts. I hold.
I'm still a little bit doubtful about the accountancy corrections in the last figures, but they did get a new CFO last year so hopefully everything is out of the way now. I'm also hoping there will be an improvement in the cash position as they are able to unwind inventories a bit more now.
Show me a person who has never made a mistake and I will show you a loser.
And I will bring round some panes of glass to help repair their house, and a bucket to put all the stones in too so we can make a nice rockery!
Tortilla Mexican Grill (LON:MEX) . Just a thought. I've been a shareholder for a while ( Pre IPO) & the original proposition was that there was a good likelihood that the company would be a takeover target for one of the large US TexMex companies such as Chipotle Mexican Grill (NYQ:CMG) . Chipotle Mexican Grill (NYQ:CMG) do have a UK presence but they don't seem to be that successful yet.
Actually, the sun's just come out here in Bournemouth, and I'm a bit peckish, so I might go and mystery shop Tortilla Mexican Grill (LON:MEX) again - the last 5 mystery shops there have been very satisfactory!
Reporting back, my chicken burrito at Tortilla Mexican Grill (LON:MEX) Bournemouth was delicious, although slightly soggy (liquid dripping out of the bottom). I highly recommend paying £1 extra for the chorizo pieces, gives it loads of extra flavour. Pleasant staff, although shop was empty (although it was in between meal times at c.16:00) - this is the big problem with fast service food outlets - their business is all crammed into quite narrow time periods, where they have to serve super-fast, but then have to pay staff to stand around doing nothing for the other times. Although strangely, MacDonalds seems to be busy (and with very slow service) all day.
I also mystery shopped Revolution Bar on the way home, so was slightly tipsy by the time my BASH session on Mello got going, hopefully it wasn't too obvious LOL!
Prompted by Paul's interest in Temu I decided to give it a go and ordered a couple of things. I'm normally ordering electronic components and would use AliExpress.
For the things I ordered, there really wasn't much to choose between Temu and AliExpress.
Quality was as you'd expect from very cheap stuff from China - I ordered a USB charger that functioned, but the features didn't match the description at all (it was billed as a Quick Charge compatible charger but didn't support any of the higher voltages or charge currents).
I also ordered a set of rechargeable magnifying glasses with a light (I do a lot of work with small bits and pieces). This was better and was of reasonable quality.
Both the items were available on AliExpress with similar prices when you take into account shipping.
Temu had free shipping, but the prices were more expensive. So it evened out.
I also found the same products (including the dodgy USB charger on Amazon with quite large markups).
I did a "tear down" of the products on my YouTube channel - definitely only of interest to very technical people - but if you're very interested you can see it here.
I'll probably be sticking with AliExpress as it's got a wider selection of PCBs and electronic components.
What's very clear is how low the quality of goods is on Amazon - there's absolutely no quality control on their side.
Yep - I think Amazon is just becoming a shell for Alibaba or Ali Express importers. I guess people will pay for time to get it "now" and good return policy. I just have to wonder how much ends up in Landfill within a year.
Amazon generally is not cheap but some items are. I was looking for some new wiper blades for my car, have Bosch at the moment, which have been good and lasted years. Checked reviews and Bosch Aerotwins seemed to be the best. Looked online and cheapest was over £28, checked on Amazon and they were under £19, plus if get delivered to Amazon hub, then £5 off.
So a good result.
I generally find ebay cheaper but more risky. Not that I buy very much.
It amazes me on eBay how many sellers are shipping direct from China - if you're going to that I might as well just go to AliExpress, it will take just as long.
I usually avoid Chinese sellers if I can.
Just on DFS Furniture (LON:DFS). Thought it worth mentioning I bought a sofa from them last September on 0% credit (since you ask, 4 years thank you very much). Turned up on time from Italy, but more to the point, I wasn't required to even add my deposit until it was confirmed in the UK (which I thought strange at the time). So from that point of view are they actually getting customers money up front?
Points from me though;
Will 0% over 3 years (as per their website) still be possible in this environment? If so, who pays? Consumer or DFS eating into margins? Will SCS be able to take share if they have a balance sheet that can handle this? Interesting to watch how this plays out.
Thanks Little Prophet,
I think with furniture retailers, even when the customer doesn't pay up-front, the retailer still gets paid before they have to pay the manufacturer.
DFS mentions negative working capital in its commentary today. The working capital section of its balance sheet is astonishing - with current liabilities about 3x current assets. Plus a load of long-term bank debt on top of that.
Another angle is that supply chains speeding up again would probably worsen its net debt position.
It's such a pity we cannot create a hybrid share that has DFS's market dominance, but SCS's safe balance sheet!
Regards, Paul.
Next (LON:NXT) make sofas in Doncaster. They certainly have market penetration if not dominance and a safe balance sheet…
I remember years back, Land of Leather showed a healthy cash balance before the
James Fisher And Sons (LON:FSJ) (I hold) HY Trading update.
The turnaround continues in line with management expectations at this highly-indebted marine service provider to the Energy, Defence and Maritime transport sectors. In view of the number of banana skins the company has slipped up on in the last few years – often self-inflicted, albeit by previous management - then in-line is good news and that’s about as good as it gets?
Revenue up 16% looks to be ahead at this stage, and H1 results are expected to be positive unlike last years loss. But FY results are normally skewed towards H2 as the North Sea operating season swallows working capital in H1, with Q4 cashflow and profits expected to pay down debt for the year end. So not expecting the interims to be exciting, though it bodes well for the year.
Media coverages indicates its a busy North Sea season with large renewable projects and life extension spend on O&G ramping up again. James Fisher And Sons (LON:FSJ) seems to be catching the wave with its Energy division and looks to be positive for the year – but its too early to count any chickens, as just about anything can happen…..and normally has in recent years.
The shares are not cheap around 19x current year expected profits of £10.7m. Which remains a far cry from the £40 to £45m in profits that the company achieved prior to the turmoil of the last few years.
Despite the high load of debt the company has avoided issuing equity. All credit to the management for this, although it has probably prolonged the agony for shareholders in the short term. There has been a lot of work going on under the covers in the last couple of years to improve operational performance. With revenue rising, gross margins rising in a strong market and debt reducing (albeit slowly), there is good reason to think that the company can return to its previous high level of operation margin, ROCE and EPS in the medium/long term and prospects in its markets look very attractive. But long term shareholders – including myself – will be wary of another banana skin before the good times might return?
Cheers
Mark
Hi Paul, regarding Unbound (LON:UBG) I was wondering whether like WANdisco (LON:WAND) talking to the company can make one less objective in whether to buy the stock. I think your analyses are brilliant and greatly appreciate them, so it is a spirit of enquiry not criticism that I ponder this!
A very sad end to Electra Private Equity Trust plc with Unbound (LON:UBG) . Its easy to forget what a phenomenally successful private equity investment trust this was a decade or so back and shareholders did very well indeed. I was only in just before it started winding down and did OK, but before that for a couple of decades it was a serious multi-bagger private equity investment trust. Did anyone here take that ride? I've just had a look and net asset value went from about £3 to £50 per share over 30 years until realisation started in 2016 or so! Private shareholders would have done much better if the capital returns hadn't all been paid out as taxable dividends was my only complaint - down to Sherborne Investors, the activist shareholder, I suspect. Fortunately, I sold my residual Unbound and Hostmore shares last year, but should have sold earlier like many of us.
Maybe someone will bring the shell back to life, although Paul has mentioned the balance sheet doesn't look good. I haven't checked but maybe Unbound now has some useful tax losses that might be of interest to someone? Sometimes old shells like this attract a bit more interest.
Hi Biogs,
talking to the company can make one less objective in whether to buy the stock.
I think that's a good question for us all to ponder. One of my most experienced & successful investor friends got caught out on several wipe-outs, having been reassured by management. So he now doesn't speak to any management teams.
With UBG, I have to say that I was very much put off by the company management itself, who never seemed that credible. But the Electra guy I chatted to on a couple of zooms did seem credible, and to be fair, Electra had delivered a lot of shareholder value from its previous disposals. Maybe the two bits that they hadn't managed to sell (TGI Fridays and Hotter Shoes) were best avoided because nobody else wanted them! Although apparently they turned down an offer for Hostmore around 120p, I've been told. They thought it was worth more. And to be fair, pre energy & cost of living crisis, restaurants would have been worth more. Look at the share price of Restaurant (LON:RTN) - that's down hugely (well over 90%) from its previous heyday in 2015. And down by over two-thirds since its recent peak in 2021.
In terms of WANdisco (LON:WAND) I recall being deeply uneasy at the meeting I had with the now ousted CEO, as I picked up on really negative body language throughout, and that was the main point I made to the 3 investors I went for lunch with afterwards, so can confirm this. If only I'd listened to my instincts on that, but nobody wanted to know, because the upside sounded so exciting. For that reason, that my body language instincts are actually better than I realised, I'm definitely going to sell instantly next time I get the "something isn't right here" instinct.
Another important point is I think to have a cooling off period after meetings, or watching webinars. I often have an urge to buy shares after meetings, but stop myself because it needs a few days to cool down and remember all the negative points!
What do other people here think on this point of meetings with mgt - good, or bad?
Regards, Paul.
Interesting on body language - a couple of years ago I made a point of watching fraudsters making presentations etc on YouTube - to see if I could identify any tells. I couldn't.
I also make a point of not attending AGMs, to avoid being unduly swayed by insider enthusiasm.
I think the question is whether you can extract information from meetings with management without being too influenced by either management enthusiasm or misdirection. Experience says I'm in the "influenced" crowd, so I am now more wary.
I've certainly attended numerous meetings with management where, with hindsight, I would have been better off staying away.
The problem is that it is very difficult to put together a detailed financial model for a company without talking to them. Stuff like capex plans, new capacity coming on stream, explanations for inventory fluctuations, forward tax rates etc. are all very difficult to access otherwise. If you are a pro then you can replace some of this by talking to a sell side analyst.
If you know enough about the sector to cross-reference the story from multiple companies & challenge the spin then meetings are worthwhile, but if you are a generalist investor relying mostly on the company to explain why their product is market-leading then you are probably going to get eaten alive.
It also depends on who sets the agenda - if you have a long list of detailed questions prepared after examining the accounts then meetings can be great. If you are time-poor and let the management perform their slide-deck then you are at risk.
If you look at companies like Autonomy and Wirecard then it is obvious there are far too many generalist fund managers letting company guidance replace proper research.
I have found that if you correspond with management/IR via email then that tends to level the playing field a little as they know false statements put in writing can come back to haunt them. It isn't always practical though.
Gut instinct that something was not right kept me away from Autonomy, but I do recall a sense of outrage looking through my notes of meetings with Marconi. If you play the game long enough you will eventually get tripped up somewhere.
Personally I never want to talk to management, it just makes it harder to sell. I may be cynical but if I treat them all as potential con artists then I can never be disappointed, only surprised to the upside. I'll watch the occasional web presentation but thats as far as it goes (tho mostly just for the Q+A) , Id much rather stick to RNS and broker numbers.
I used to do lots and lots of research but Ive trimmed this back to the minimum required as I found I'm less likely to sell having spent days looking into a company. Always want to be mentally prepared to ditch any holding, almost robotically, if red flags show up.
Everyone goes about things differently tho, which makes investing so fascinating
I think listening to the webinars and attending meetings does give some more information. There is a lot you can read between the lines in the way information is conveyed, verbally or non-verbally. However, one has to be weary that all of these are highly organised, highly planned information sharing sessions. Orchestrated by Investor Relations or PR teams, internally or externally. Naturally, the story that comes across is a very compelling buy case. And people who make it to the c-suite often have very good communication skills... politician-like skills.
If the company is in trouble or has nothing interesting to spin, they would elect to not hold any webinars or meetings. Unless they have to, like AGMs - that's why you get so many boring AGMs where the bare minimum is done - because there is no good prospects at the company (or the directors just don't care about shareholders).
In fact, I would argue that if an AGM is just perfunctory, with minimal effort made by the directors, this is a red flag. Either there is no compelling reason to invest in the company, or the directors just don't care about shareholders.
I realised many years ago after some bad experiences never go to meetings or watch any management present.
I spent a year (a long time ago) going to hotel meetings etc and in each case lost money being influenced by sweet talking guys (nearly always guys).
Indeed one company - Vanco - proudly showed me round their offices showing me what they did they were SO bullish. I thought "wow these guys are great"! I bought shares and they went bust only six months later. (Lucky my shares hit a stop loss before that happened).
I feel you just can't help being influenced and you will only be fed with positives. Also you wonder why they go out and present. If the company is going well, the shares will go up via statements and my feeling is it tends to be the more desperate ones that you see presenting or indeed paying to be interviewed. There is an argument for shorting shares in any company that is always presenting or always paying up to be interviewed. Remember they also have to pay to present at most events.
I was besieged on email recently by a company CEO telling me how great his company was and could I cover them, come and meet them and I thought "desperate I must short them"!
They are down 50pc since! (They were too illiquid to get a short never mind).
Overall I'd suggest ignore them all, use the amazing stocko screens go on cold hard figures and the likely future outlook. You then have no confirmation bias from sweet talkers.
I had a friend (the only friend I have had that bought shares!) who sadly died a while back but she would go to meetings, ignore what they said and looked at the CEO's shoes. If they were great shoes, and polished and looked after she would buy the shares! Well, this worked for her. In my case if the CEO is bald (check on their website) that's always positive as guys with hair spend an hour a day faffing about with it, which is 365 less hours a year spent on the company's welfare. If in doubt - buy bald, short hair.
Thanks Robbie for writing with such clarity about this. Sadly my experience with Mello (virtual and physical), has been more or less the same. Good presentation and you come back with the idea that you have heard or seen something that others have not and you have the edge!
To be fair, Mello has a debating session too which I like because you see both sides of the argument there. I don't know anyone has done a retrospective research on the companies who have presented at these meetings versus a sample of similar companies who have not.
Nowadays, if a company is not on my shortlist, I do not attend their presentation, discussion or anything related to the company. I do not want to be persuaded or convinced however good the story is.
I think Mello stocks had a good performance until a few years ago. Recently they don't seemed to have faired so well, but that is the market we are in, the last 2 years has been difficult in the UK, especially small caps.
If you search you may find some figures, think Damian Cannon produced some.
This has some truth to it, but it is also deeply unfair to smaller companies with decent, honest management.
Smaller companies can easily get caught in a Catch 22 liquidity trap.
The big institutions tell them they can't invest because their share liquidity is too low, and suggest that boosting their retail profile will help with spread and liquidity.
Retail investors note the absence of insitutional investors and shy away.
If things go well your RNS will still be ignored if nobody reads it, or you may be overlooked because investors can't get a decent quote when they try to trade.
Decent management do need to promote their company to investors, and it doesn't always mean they are ramping the shares or trying to con investors.
I've also been to plenty of 1 on 1 meetings (admittedly as an institutional investor) with credible management who have played down their near-term prospects.
90% of the cases they are ramping their shares and trying to con investors.
There are so many decent and well experienced investors (not fund managers) out there that they can easily spot a decent growth company with honest management from miles away.
You may be correct.
However, I suspect very few of the decent and well experienced investors you mention quote stats like "90% of the cases" on a forum without also being willing to provide the detailed evidence?
1 in 10 small listed companies survive and grow-the rest disappear-It’s a fact.
The last 3 years this percentage is even worse with the new listings. The new interest rate cycle (that’s here to stay) will make this percentage even worse.
Thanks
No Yiannos1, that is not the answer we are looking for.
a) You've moved the goalposts - we are after evidence that "90% are ramping their shares and trying to con investors" as you claim so confidently, not the survival rate which is a different matter entirely.
b) If it is a "fact" that only 1 in 10 small listed companies survive then I think everyone reading here (myself included) would be interested in reading the source of that statistic and any report it is in, or at least which index is used for reference (Hoare Govett/Numis? AIM?) and over what time periods that 90% failure rate applies to.
Please share. No sarcasm intended whatsoever on point b), genuinely interested. AIM during the period of Chinese frauds perhaps, or IPOs below a certain Mkt Cap, but I struggle to see how the FTSE SmallCap generates a positive return with a 10% survival rate.
That’s the answer you are getting though.
This is my personal opinion that 90% of the small listed companies do not survive or they just listed for no reason and about the same percentage they are just ramping their shares.
But in your post of 7.01pm you told us it was a fact. Now in your post of 9.14pm you say it's your opinion.
I'd be surprised if it's correct, but I'm quite happy for you to hold that opinion. I'm less keen on being berated by things as "fact" when they are opinions........
It’s a factual opinion.
Some people are trying to turn this useful forum into another ADVFN.
Hopefully not, I got shot of ADFN years ago.
I enjoy listening to webinars with Management but do manage nowadays not to rush in and buy when impressed , or indeed sell when less so !! After the webinar, I spend some time researching the company, using Stockopedia and other sources , and only make a decision when the research process is completed. It’s so easy to be sucked into taking action that I have often regretted.
One company that I have always been impressed with is Belvoir( LON:BLV) and although the share price continues to fall, I am 100% confident that it will be a great long term hold and am happy to buy more of on weakness.
My view is that meeting management gives you context and understanding not investment surety. You should never rely on a single meeting but build over time checking back on what they say and the validity of it. Imagine Trump! Most private investors never had the opportunity to do this but technology has changed this. The Fidelitys/Wellingtons etc of this world always quote management meetings in their sales docs. Doesn't make it right but does suggest it adds something.
Hi Caper4, I know what you mean about Belvoir (LON:BLV. Solid, dependable, reliable type of thing. Reminds me very much of Bloomsbury Publishing (LON:BMY). Both management teams appear very grounded and modest. In both cases though, the directors hardly have any skin in the game. Around 1 to 2% from memory which limits my enthusiasm (and position size) for them. Although having a significant holding then opens up management to talking it's own book maybe? But isn't that part of their role, after all??
Enjoyed the podcast as always Paul. I totally agree with your point about keeping the market updated, especially in a Bear market.
XP Factory (LON:XPF) is a great example. We don't even know how the O2 BBB is performing and it's been open 18 Months now. The devil is in the detail and knowing how that venue is performing, and the profile over the last 6 quarters would tell us a lot.
See above post "XP Factory (LON:XPF) Bit of topic, but was doing some research on website / app visits to see if there has been any downtun given summer / indoor activity, Xmas boom (no pun here :-)) and inflation, etc. The below gives me continued confidence in the growth of the business. Thought I'd share"
XP Factory (LON:XPF) Bit of topic, but was doing some research on website / app visits to see if there has been any downtun given summer / indoor activity, Xmas boom (no pun here :-)) and inflation, etc. The below gives me continued confidence in the growth of the business. Thought I'd share.
Separately, and this is what is even more exciting is the slower, but continued growth over in the US.
Thanks for sharing SGTA but BBB doesn't have a presence in the US yet, I think you are looking at the wrong website, should be https://boombattlebar.com/
Yes that's right, it does help if we're looking at the correct website! Boomplay has nothing to do with XP Factory (LON:XPF) (I hold)!
Another positive update from Northern Bear (LON:NTBR)
I'd be grateful to hear your views on it. Thanks
Posting error - ignore
Brickability (LON:BRCK)
Creditable final results today from this distributer of a range of building products. Lots of acquisitions distort comparison with prior year results but works out at 4% revenue growth on lfl basis. Importantly, despite downbeat commentary from house builders and brick makers, BRCK is more upbeat about future prospects albeit qualified by acknowledging macro conditions. Net debt is modest and the strategy of widening its offering and customer base is going to plan. Small increase in the dividend which yields about 5.8%. I hold.
Any chance you could take a look Paul?
Good morning rwh3ue,
Thanks for your synopsis on Brickability (LON:BRCK) - we really appreciate members who post something of interest like this, rather than just asking us to do all the work with no indication of why it is of interest!
I have a favourable impression of BRCK as a value share, although agree with your point that with major housebuilders reducing build rates due to tough macro & high interest rates, it might come under pressure.
BRCK didn't come up on our initial list, so I'll add it, and will try to cover it later this morning.
Thanks, Paul.
Hi Paul, I assume the ‘all the work’ bit was aimed at me? Sorry, fair enough. I’ll try again. If I’d put what was in my head I’d have said something like this:
“Hi Paul and Graham, Brickability (LON:BRCK) have posted what sounds like good full year results. Revenue is up which is good, but gross profit margin down and in debt rather than holding cash sounds bad - but there have been acquisitions so perhaps that explains it. It’s one you’ve covered before, but it isn’t on your list so thought you’d like to know. I’d be grateful if you could help untangle the numbers.”
It’s a bit daunting when there’s so much expert commentary on the SCVR. I don’t feel I can add anything of interest, just a request for help. But I can see it’s only fair to give you something to go on.
Hi Indie,
No, my post was not aimed at you! It was general.
FWIW, your original post saying this, was fine I thought - as it gives us a reason why we should look at something.
Final results for Brickability (LON:BRCK) - ‘Good performance across all divisions’ - grateful if you could have a look.
Regards, Paul.
Thanks Paul, that’s a relief!
Big cheer to you all .
Indie
Helpfully someone has posted elsewhere a note from Cenkos which adds their opinion that BRCK is "fundamentally undervalued". I've pasted it below.
I would add that BRCK , where the majority of revenue (73%) is from sales of bricks and other building materials. It is worth noting that this percentage has fallen from 78% last year as diversification starts to take effect.
I suspect many folk think only in terms of new build houses where there is clearly a drop in demand. To me that implies we can expect more renovation of existing stock as people decide to improve what they have rather than move. That may require new windows, radiators and underfloor heating, ceramic tiles, fascias and facades, roofing materials (timber, tiles and slate), solar panels, flooring, balconies and doors.
The same logic applies to refurbishment of commercial buildings where expertise as to best products for specific situations counts. BRCK has a strong reputation and good relationships with its customers. Short term macro factors will suppress demand in some areas but I suggest BRCK are better placed to survive and prosper than many less diversified companies in this field.
"Cenkos-
Brickability reported FY23 results slightly ahead of recently upgraded forecasts and encouragingly, we are leaving FY24E forecasts largely unchanged. At the headline level, LFL revenue increased by 4% to £681.1m, with EBITDA up 30.4% to £51.5m. Given the market backdrop, this is an impressive result and underlines the benefits of its strategy to diversify its revenues. We believe near-term sentiment will remain a challenge, but the current valuation looks increasingly anomalous. The share price is sitting on a two-year low, 20% below its IPO listing price and now trades on a FY24E PE of just 6x and EV/EBITDA of 4x. This is despite continued delivery/outperformance against expectations. BUY. Headlines: These are a strong set of results with revenue up 30.9% to £681.1m (inc LFL growth ex timber of 15.4%) and EBITDA up 30.4% to £51.5m (EBITDA margin: 7.6%). Net debt came in at £8.0m, in-line with recently revised expectations and reflecting the step-up in EBITDA, reduced working capital outflow and lower than expected capex. A final dividend proposed of 2.15p, gives a total dividend for the year of 3.16p, an increase of 5.3%. It is also encouraging to note the benefits of recent acquisitions, which have added scale and enhanced its client base. Forecasts and outlook: We make minor changes to our FY24 estimates, with revenue and EBITDA unchanged. EPS falls back slightly (-3.1%) to 9.9p, reflecting a slightly higher tax charge. We take the opportunity to introduce FY25E forecasts, where we have assumed a nominal improvement in underlying trading. At the headline level, we assume YoY revenue, EBITDA and EPS growth of 3%, 6% and 6% respectively. These forecasts are based on no further deterioration in its core markets and also do not factor in any additional upside from acquisitions. We would note that trading in FY24E remains in-line with the Board’s expectations. View: In our view, the stock remains fundamentally undervalued. When FY23 EBITDA forecasts were introduced in 2021, we were looking for EBITDA of £22m and EPS of 7p. Today, the group has delivered EBITDA of £51.5m (+134%) and EPS of 11.9p (+70%), the de-rating therefore looks overdone. The long-term fundamentals of the UK housing market look to be well underpinned and the need for Brickability’s service offering remains unchanged. As the market returns to examining underlying valuations, Brickability should firmly be on the radar in terms of a re-rating. BUY."
Final results for Brickability (LON:BRCK) - ‘Good performance across all divisions’ - grateful if you could have a look.
I hold.
Warpaint London (LON:W7L)
The Retail Gazette carried this story over the weekend regarding Superdrug's great and continued performance. the article mentions cosmetics as being particularly strong. Warpaint will roll out their offering into 73 Superdrug stores as from September 2023. Good timing ?
Superdrug full-year profits soar as footfall and own-brand boost sales - Retail Gazette
From the survey of one, they are also right in front of the door as you go into Boyes in Northallerton, well the right hand door, the left hand is bird seed.
I will have to go into Superdrug and see where they are at the weekend.
Nice looking update from Concurrent Technologies (LON:CNC) Broker upgrades PBT/EPS 29% for this year
Could be at the start of an upgrade cycle?
"Chief Executive Officer, Miles Adcock, said "We are at an inflection point. Now that components are becoming more readily available, we will enter a period of growth. H1 FY23 revenue was a record first half for us, and I believe H2 FY23 will be better still. Following a period of ongoing transformation, this business now has the capability, capacity, and ambition to deliver sustained growth. Whilst the management team remains prudent in its assessment of the short-term rate of improvement in the supply chain, I can confidently say that we have much greater control of our destiny. Fuelled by record levels of order intake and customer engagement, we are driving to continuously improve our performance for all our stakeholders."
........"The Board believes that the Company is in line to deliver revenues slightly ahead of current market expectations and profit before tax materially ahead of market expectations."
Indeed, this is a share I have been tracking and it looks like Concurrent Technologies (LON:CNC) might have some good tailwinds coming with the supply chain issues being fixed. I quite like this theme of picking up shares that have struggled in the past 1-2 years due to supply chain issues, but have robust order books that will quickly unwind, a bit of a bullwhip effect.
Another share that fits this mold, which I currently own, is LPA (LON:LPA) . Big order book backlog due to component shortages (theirs and their customers) which should rapidly unwind in the next 6-12 months.
The only niggling fear I have with Concurrent is their "moat". Sure, they are specialists in making rugged devices for niche, extreme use cases. But is this something that the likes of larger hardware manufacturers can't do as well, if this grows to a big enough opportunity? I don't know too much details about their products, so would welcome some more enlightened views!
Actually, I've had amnesia! I said I currently hold LPA (LON:LPA) , but actually I don't - sold out mid-June when it surged to 100p+. Can't edit my original comment, so here is my correction.
At 100p+ I had realised that a lot of the value was baked in, not much more to extract in the next 3-6 months. I was right - have fallen back to 82.5p. Tempted to buy back in, but purposely running more cash in the portfolio at the moment rather than taking on new positions.
Futura Medical (LON:FUM) being marketed by HALEON (LON:HLN). Thought this would be a long journey with fund raises. Well done to holders.
Yes, this could be the game changer for Futura Medical (LON:FUM) FUM. Haleon are a big player ( former consumer division of GSK and Pfizer joint venture). Reports from uk commercial partner that sales in Boots since launch of the Eroxon product in uk have been surprisingly good . Now that there is the green light for US and a top level commercialisation partner things look very promising. Futura Medical (LON:FUM) get 4 million up front for the US arrangement ,royalties on all sales and much bigger milestone payments for certain targets going forward.
Rose around 51p to 60p area but then pulled back to the start. One of those where need Level 2 to see whats going on.
The non-prescription erectile externally applied cream works in 10 mins as opposed to Viagra and Cialis pills which take half hour and some side effects - so more spontaneous.
Huge market of course but their patent runs out in Europe 2030 and 2028 in the US - but can be extended. Maybe just get bought out.
My morning smallcap tweet: Unbound finally trips into sinkhole. 25 companies covered.
Unbound (LON:UBG) Gresham House (LON:GHE) Getech (LON:GTC) East Imperial (LON:EISB) Kanabo (LON:KNB) Guild Esports (LON:GILD) Advanced Oncotherapy (LON:AVO) Cellular Goods (LON:CBX) £DMN Costain (LON:COST) Smartspace Software (LON:SMRT) DFS Furniture (LON:DFS) IQGeo (LON:IQG) Concurrent Technologies (LON:CNC) Oxford Cannabinoid Technologies Holdings (LON:OCTP) Redcentric (LON:RCN) UP Global Sourcing Holdings (LON:UPGS), James Fisher And Sons (LON:FSJ), Tortilla Mexican Grill (LON:MEX), Windward (LON:WNWD), Tissue Regenix (LON:TRX), Virgin Wines UK (LON:VINO), Ocean Harvest Technology (LON:OHT) Churchill China (LON:CHH) Brickability (LON:BRCK)
◄Unbound (UBG)► shoe co run by heels suspended as it plans to put main operating subsidiary, Beaconsfield Footwear into administration. [SP=0.74 Cap=m]. I hold.
◄Gresham House (GHE)► 1105p rec offer, a 63% premium. [SP=671 Cap=257m]
◄Getech (GTC)► wins 3 contracts worth £0.8m over 3 yrs. [SP=9.37 Cap=6m]
◄East Imperial (EISB)► proposed issue of £2.2m 10% converts. Convertible at a 20% discount, but at 1p minimum. [SP=0.81 Cap=3m]
◄Kanabo (KNB)► 40% owned subsidiary, Kanabo Agritec wins contract for for the development of an indoor medical cannabis cultivation and processing facility. No £££ yet. [SP=1.9 Cap=12m]
◄Guild Esports (GILD)► partnership with Pixels AI to generate ad revenues for GILD from its owned video content "by leveraging Pixels'AI-powered video platform". [SP=0.67 Cap=4m]
◄Advanced Oncotherapy (AVO)► still in Formal Sale process talks but alternatively plans a d4e (of £25.7-£37.4m), a £10m loan and a fundraise of up to c.£73m. Loads of warrants natch'. [SP=1.95 Cap=10m]
◄Cellular Goods (CBX)► MoU for a JV to develop carbon sequestration and removal services through sustainable kelp farming. [SP=0.7 Cap=4m]
◄Dianomi (DMN)► warns FY-Dec rev £30.5-32.5m, below mkt exp. H1-June rev was down 18%. Blames even weaker mkt than expected. [SP=NA Cap=NA]
◄Costain (COST)► United Utilities awards 2 yr extension to its Managed Service Provider contract. [SP=47.9 Cap=131m]
◄Smartspace Software (SMRT)► completes sale of freehold asset and the business of Anders + Kern. Gets £1.38m. Got only £0.52m for the biz itself. [SP=37.36 Cap=11m]
◄DFS (DFS)► guides FY-June in line with rev down 4% and adj pretax slightly above £30m. Current trading in line. Guides FY rev down mid-single digits and U/L profit slightly up. Economic outlook remains uncertain. [SP=112 Cap=266m]. I'm short.
◄IQGeo (IQG)► guides H1-June rev up 117%, ahead of prior expectations. Adj EBITDA in line. Order intake up 50%. [SP=301 Cap=185m]
◄Concurrent Technologies (CNC)► guides FY-Dec rev slightly ahead of market expectations and pretax materially ahead. [SP=56.95 Cap=42m]
◄Oxford Cannabinoid Technologies (OCTP)► expanding into oncology after identifying a potential "first in class" immunotherapy agent for the treatment of solid tumours. [SP=0.83 Cap=8m]
◄Redcentric (RCN)► FY delayed due to audit not finished. Reiterates guidance. [SP=129.25 Cap=202m]
◄UP Global Sourcing (UPGS)► guides YE net debt £15m cf £21m expected. [SP=122 Cap=109m]
In line: FSJ, MEX, WNWD, TRX, VINO, OHT, CHH, BRCK
US Markets
S&P had a good week - up over 2%, boosted by better than forecast inflation numbers. Some big names are reporting earnings this week.
Has room for a sizeable pullback yet still remain in an uptrend. Its amazing how Panic turns to FOMO over a short timeframe. September/October last year there were record shorts, Fear+ Greed Index was at extreme fear, almost everyone was predicting a recession. ...now there's talk of new highs by year end. In reality 99% havent a clue what will happen.
Percentage of stocks over 200 day moving average from last 20 years
Russell 2000 has been in a sideways range for over a year now. Its just starting to show some positive signs, if it breaks out of this range in next few weeks it'll likely trigger an infrequent monthly MACD buy signal.
Inflation numbers/stock rally helped give the Dollar a violent push through support.
Talking of the media heres a couple of magazine covers days either side of the Dollar peaking in 2022.
Falling Dollar helped boost Gold
UK Markets
FTSE 250 - better week 212 - 31 down on the week (36Up – 212 down last week)
54 above 50 + 200d moving average. (28 last week)
Volume was light, only 6 above 2x normal weekly volume (8 last week)
Chart still in a downtrend with plenty of work to do to get above moving averages/higher high. It did trigger a weak looking MACD buy signal tho.
AIM all share - 248 up - 294 down on the week. (117 Up – 452 Down)
126 above 50+200d moving average (78)
volume improved with 59 above 2x normal weekly volume. (23)
Also triggered a MACD buy signal. Noticed lots of shares showing signs of positive momentum reversals last Wednesday/Thursday so could rally up to around the 50 day moving average, tho lots of work to do to get above all moving averages.
There was a government jobs report last week which caught my eye, things still seem tight but this is interesting
An interesting story on Chinese exports. Weak economy or reshoring or both?
Hope everyone has a great week
Gresham House (LON:GHE) A decent premium takeover bid from Spotlight today (as rumoured once more by Sky last night)
1105p bid versus a closing price of 680p on Friday
Confirmation that others think the sector is cheap?
Yes, I have owned Gresham House (LON:GHE) since it was an investment trust, so its been a good journey and I have achieved a 4x return since 2014. I'm a bit surprised by the offer. Disappointed it is leaving the listed market, as its a great company led by Tony Dalwood, but its a good price. This will definitely have an impact on Foresight group (LON:FSG) which I also own as they are virtually identical asset management groups. It maybe also reveals some value in Petershill Partners (LON:PHLL) as well, although I am a bit more suspicious about the opaqueness of this Goldman Sachs vehicle.
For those of you interested in history, Gresham House plc is pretty much the oldest company on the London market and has been going since 1857 with a company number of just 871! Sad to see it go private, so I have mixed feelings about the bid.
Gresham House (LON:GHE) I've highlighted this a few times here as my preferred pick in the fund management sector. Sad to see it go as I feel in a few years it could be worth several times its current market cap, but decent price so can't complain. Need to find a replacement now - will take a closer look at Foresight group (LON:FSG) to start with.
Timing not to my advantage here as I’ve been sniffing around Foresight group (LON:FSG) & today’s premium bid for Greshams has sent it up. I had hoped to add a few more first but may have to either wait for a dip or pay up. Such is the nature of investing
Yes, sector is looking cheap. I've put the following comment in a few of my recent research notes "asset managers’ PERs have fallen sharply since the end of the bull market in early-2022 (by nearly two-thirds!). In January 2022, we recorded an asset manager peer group median PER of 31.3, which is now just 11.5. We suspect that asset management sector PERs may recover quite sharply should markets stage a recovery." (from 10 July note https://www.equitydevelopment....). Prices were probably a bit toppy in late21/early 22 but huge fall since then. Is the premium offered for Gresham House (LON:GHE) enough? Debatable.
Fully agree with Topvest though, great shame to see another quality co move from public markets.
Good morning Paul and Graham. Three hopefuls from our portfolio this morning which was a pleasant surprise! Concurrent Technologies in an unaudited HY saying the board expects revenue to be inline with an improving supply chain situation, while profit will be materially ahead of market expectations. Getech in a forget the gas and oil TU states Globe, their minerals exploration technology, is winning small contracts. To me (optimistically) their unmentioned expanding hydrogen efforts could be the exciting part. Finally UPGS, announces a reduction well below market expectations on their debt position with hedges also in place keeping finance costs under control. Anything there worth a quick comments? Hope all tennis lovers here enjoyed yesterdays final!!
UP Global Sourcing Holdings (LON:UPGS) - Debt reduction confirms financial strength ( new note here: https://www.equitydevelopment....)
UPGS announced a significantly better-than-expected improvement in its debt position today. Net FY23 year-end bank borrowings are expected be in the region of £15m compared with current market expectations of closer to £21m. The financial benefits of lower net debt in the current climate of rising interest rates are clear. UPGS’s cash generation capabilities not only underpin its generous dividend policy (50% of net profits) but also enhance strategic flexibility. The company is not only able to weigh up the relative benefits of increased pay-outs to shareholders (e.g. a higher dividend pay-out ratio or share buybacks) but also to take advantage of potential acquisition targets on offer.
Today’s announcement reinforces confidence in both our own and consensus FY2023 forecasts being achieved. Our 29 March 2023 report commented that a £163m full year revenue figure would require double-digit growth in the second half. Given that UPGS expects its end-year FY2023 net debt:EBITDA to be 0.7x (vs. 1.3x a year earlier), we infer that the company itself shares our confidence. Second half sales growth clearly accelerated sharply.
A combination of strong sales growth and associated financial strength is central to the investment case for UPGS’s shares as the company strives to deliver affordable “feel good” branded products for every home. We reiterate our fair value of 250p; this valuation implies 1.4x EV/sales and 11.7x EV/EBITDA using an improved £15m end-FY2023 net debt estimate.
Students of the macro picture might like to read the Ruffer year end summary, issued as an RNS today. I'm 100% equities, they believe that you should be at the opposite end of the risk spectrum, given todays monetary stance.....gulp.
Do you have a link?
Just Google 'ruffer review 2023' - it's a very good read ...
Just remember that certain individuals at Ruffer consider themselves clever enough to time an investment in & out of bitcoin.
They may have made money rolling the dice on that occasion, but they also lost all of my respect.
Ruffer have been very hit and miss in their outlooks - they occasionally get their positioning right and have the odd good year but overall I wouldn't pay too much attention to what they're saying.