Small Cap Value Report (Mon 17 Oct 2022) - ASC, EVE, MADE, BOOM, VCP, RM.

Good morning, from Paul & Graham. I'm interviewing the CEO of Sanderson Design (LON:SDG) at 16:00 today, so I got up early to prepare my questions. Should be interesting, I really like this share (no current holding). Audio interview is now up, here.
Podcast - as usual this went up on Saturday, with just a brief market overview, then most of it covering numerous shares that were in last week's written reports here. The mystery share (my best idea of the week) is already marked in Thursday's report.
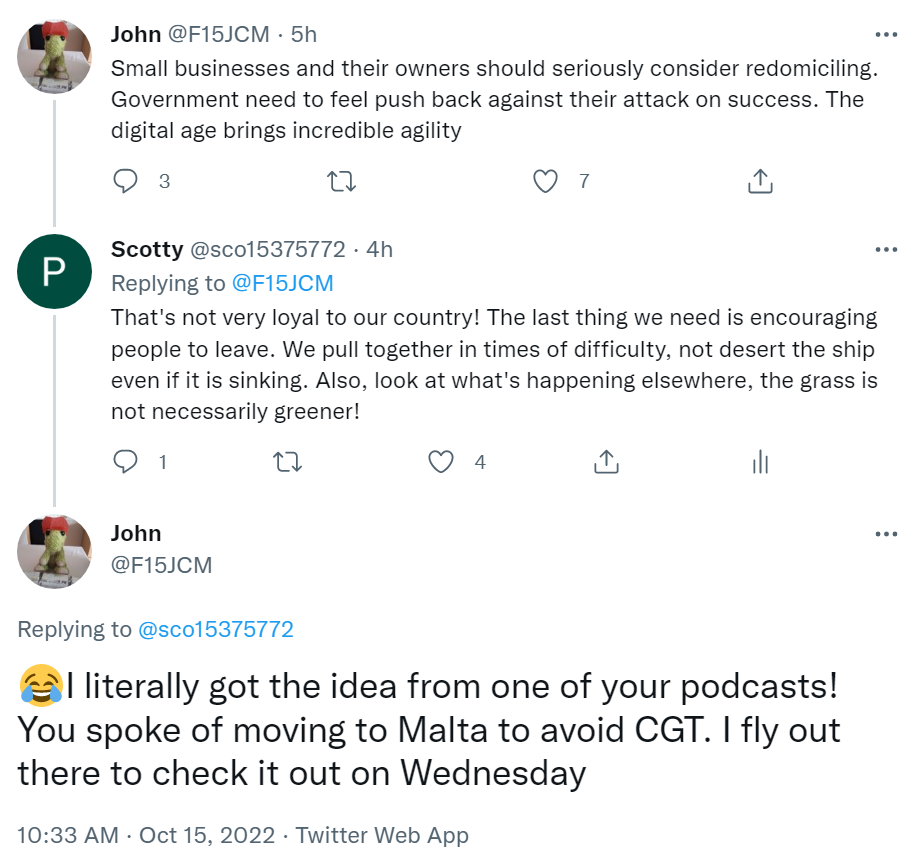
I've got to share this with you. I was telling off someone on Twitter for being disloyal to the UK, but his response floored me (rolling around laughing!). You might enjoy this -
Agenda
Paul's Section:
ASOS (LON:ASC) - this eCommerce fashion business responds to weekend press coverage that it's negotiating an amendment to its banking facilities. The press also report that trade credit insurance is tightening. Looks ominous to me, so I'd steer clear for now, due to elevated risk of a discounted fundraising.
Made.Com (LON:MADE) - another update from this almost-bust eCommerce furniture retailer. It says several potential deals have been indicated by buyers, but also that any deal would require immediate interim financing. So why wouldn't buyers just wait for it to go into administration imminently, then buy it for less, and without liabilities, from the administrator? I think this is extremely high risk, hence remains uninvestable. People could get lucky though, you never know for sure how things are going to pan out.
Audioboom (LON:BOOM) - Q3 update sounds positive, but Q3 revenues have actually slipped sharply from earlier this year. It's still trading profitably though, and has an increased cash balance. To be fair, new management have done a good turnaround here, but podcast publishing is a crowded space, hence is low margin. I'm not sure there's much of an investment opportunity here. Could be a takeover target though?
Graham's Section:
eve Sleep (LON:EVE) (£1m) (no section below) - this story reaches its almost inevitable conclusion, as the administrators are called in “to preserve value for creditors”. Additional funding was needed this month, but was not forthcoming. Commiserations to anyone still holding this. But in truth, this one never really got off the ground, even in the good times. A summary of its financial performance is pictured below: it’s hardly surprising that a company with numbers like this would eventually run out of road.
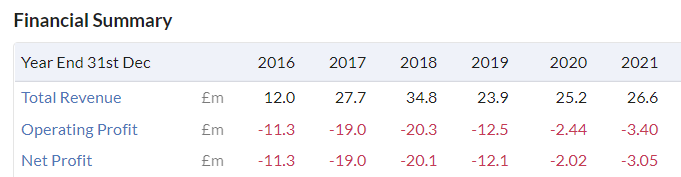
.
Victoria (LON:VCP) (£504m) - this carpet group announces that H1 trading is in line with expectations and that it expects “meaningful positive cash flow in H2”, along with “operational synergy gains”. I review some of the history here: a short-seller attack that was met with the company announcing a share buyback, during a year which has seen a crew of large short-sellers ramp up their negative interest in the company. Overall, 2022 has been a very bad year for the Victoria share price but I would have zero confidence in a long trade here, even at this lower valuation. The debt load is high, the financial structure is complicated, the acquisitions are complicated, and the flooring sector is not exactly a safe haven in a bad economy. I take a negative view on this company and therefore on the stock.
RM (LON:RM.) (£16m) - more bad news from this educational company that helps schools to modernise. Its disastrous IT project has resulted in lower revenues than expected at one of its divisions, as it continues to struggle with high operating costs and warehouse inefficiencies. While the turnaround remains possible with bank support in place, I continue to see little reason for fresh buyers to take an interest in this share. When a company has both serious operational problems and serious financial problems, I think the risk levels become far higher than most investors (including myself) are willing to tolerate.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
ASOS (LON:ASC)
492p (down 7% at 08:34)
Market cap £498m
Sky reported over the weekend that Asos's biggest lenders have hired advisers, and that Asos has asked for amendment of the terms of its £350m bank facility (RCF). Sky also says that “at least one major trade credit insurer” has “decided to reduce its support”.
This is very worrying, as when banks bring in advisers to conduct an independent review, in my experience it often means they want to get out of a lending situation, but need some independent advice to use as cover.
Listed companies of this size rarely become insolvent though, so my guess is that the most likely outcome is probably that Asos might have to tap shareholders for fresh equity, in conjunction with renewed but reduced bank facilities.
This is the response from Asos this morning -
ASOS Plc ("the Company") notes recent media reporting and confirms that it is in the final stages of agreeing an amendment to the future financial covenants in its Revolving Credit Facility, which matures in July 2024.
This action will give ASOS significantly increased financial flexibility, against the uncertain economic backdrop. ASOS retains a strong liquidity position and this is a prudent step in the current environment.
My opinion - it’s astonishing to see that the bull market in Asos’s shares over the last 12 years has evaporated. However, the company has never really made much profit, and cashflow has been poor, with no divis being paid, and all cashflow being sucked into capex to make bigger & bigger warehouses as revenues soared to c.£4bn.
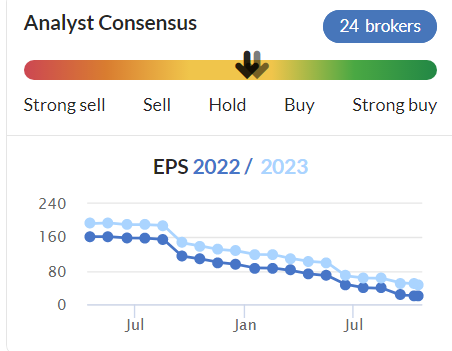
There again, even just a year ago, the forecasts looked good, and profits were on a strongly upward trajectory. However, it’s now clear that this was all down to the pandemic eCommerce boom, and look how profitability has since melted away (similar story for Boohoo (LON:BOO) [I hold] unfortunately, and the whole sector actually, here and overseas) -
.
I think it’s best to avoid any eCommerce company with a stretched balance sheet, which Asos clearly now has.
The ones to focus on in this sector, in my opinion, are the still-profitable companies, with plenty of cash in the bank. Hence the two that recently caught my eye are Victorian Plumbing (LON:VIC) and Angling Direct (LON:ANG) (I have no position in either, but they’re on my watchlist).
Asos is probably likely to survive, but the dilution risk from a fundraising (from a position of weakness) is too great a risk right now. A fundraise would probably be at quite a discount, so why would we want to be holding this share, in advance of such a value-destroying risk?
Best to steer clear, I reckon.
Made.Com (LON:MADE)
9.3p (up 30% at 08:35)
Market cap £35m
Further to the announcement on 4 October 2022, the Board of MADE has received a number of non-binding indicative proposals (the "Proposals"). Having reviewed these Proposals the Board has invited a select number of parties to progress towards firm offers by the end of October, following a due diligence process. The Proposals provide a range of different transaction structures, including possible offers for the issued and to be issued share capital of the Company.
Based on the working capital requirements of the Group, any firm offer would require interim financing to be put in place at the time that firm offers are expected, which the parties involved in the process are aware of…
My opinion - the way I read this, the range of possible deal structures probably includes buying it out of administration (i.e. a 0p outcome for existing shareholders). However, it sounds like there could also be solvent deal structures, with something being paid for the existing shares - although no indication of at what price.
The big problem with this situation, is that MADE has already told the market that it’s close to having to call in administrators. The last going concern note stressed not just that more equity was needed, but that it had to happen fast, or MADE would run out of money. Today’s announcement confirms this.
Ask yourself this, if you’re negotiating to buy a company, and you know that it’s on the brink of having to call in administrators, then what do you do? The obvious answer is get all the due diligence done, indicate a possible bid (but nothing binding), then stall them and wait for it to collapse. Then you buy it for a song from the administrator.
The only scenario I can imagine working positively here for existing shareholders, is if a number of parties are desperate to buy it, and compete with each other over price, which might result in a solvent outcome.
Situations like this are difficult to assess, because only insiders know what’s going on, and it would obviously not be allowed for them to trade with inside information. Everyone else buying or selling the shares, is just guessing (or breaking the law, if they do know inside information).
Risk:reward looks shockingly bad to me, so I remain of the view that this share is totally uninvestable. Insolvency seems to be looming, and I think a 0p outcome is by far the most likely scenario. A white knight could emerge, with a solvent solution, you never know. But why take the risk of a 100% loss, when things are this precarious?
.
Audioboom (LON:BOOM)
475p (up 2% at 09:18)
Market cap £80m
Audioboom (AIM: BOOM), the leading global podcast company, is pleased to provide a trading update for the quarter ended 30 September 2022.
44% YTD revenue growth, 125% YTD adjusted EBITDA growth, 2022 contracted revenue of US$73m
I remember researching Audioboom over the summer, and published my thoughts on the Interim results here in July.
Today’s update shows a deceleration in revenues, of $16.2m in Q3 (down 4% vs Q3 LY). The easy prior year comparatives have now finished, so it will be a lot harder for BOOM to demonstrate further growth from now, I think.
Sequential revenues this year work out like this -
Q1 $19.7m
Q2 $21.2m
Q3 $16.2m
Clearly this is a negative trend now, blamed on “global economic headwinds impacted advertising demand”. It says the trend improved within Q3, and that “improvements forecast throughout Q4”.
BOOM is a low gross margin business, so we don’t have to worry about operational gearing magnifying the reduced revenues impact on profitability.
Adj EBITDA - is $0.6m for Q3, and $2.7m for the nine months so far of FY 12/2022. Note that BOOM only has a tiny depreciation & amortisation charge, so EBITDA is very similar to operating profit, which is good. However, the interims showed that $2.0m operating profit was more than consumed by an outrageous $2.3m share based payments charge, leading me to question for whose benefit this company exists? Shareholders or management/staff? Note that a forex gain boosted the statutory $566k statutory PBT at the interims by $1.0m. Generating a lot of revenues in dollars must be helping performance at the moment too, I imagine.
Liquidity - looks OK, with cash of $8.0m, up from $5.8m at end June 2022. There’s an undrawn overdraft facility of $1.7m too.
The balance sheet looked OK to me back in June 2022, with NTAV of $17.4m. So I think the risk of equity dilution from another fundraising actually looks fairly low. I did raise a flag over receivables looking very high, at $19.0m at June half year end. Management did explain this, but I can't remember their explanation, but I still think the figure looks too high.
Outlook - this sounds positive, but I think the contracted revenues must refer to the whole year FY 12/2022, and as I identified above, the sequential performance of revenues is not good. Prior year comparisons are soft, but now turning harder.
Advertising demand began to rebound in the second half of Q3, and that trend is continuing into Q4, with advertising bookings of more than US$73 million in place for 2022 - 21% more than the entirety of last year's revenue. We are confident of a positive end to the year".
Maybe the softer Q3 was just a blip then?
So I think the talk of growth in today’s update is not really giving an accurate picture, although technically correct as couched.
My opinion - Audioboom has been an excellent turnaround under new management who I think have done a good job, taking a previous basket-case and turning it into a viable business, that makes a little profit, but all swallowed up by share options charges this year so far.
I looked at various podcasting platforms/publishers when launching my own podcast earlier this year, and quickly concluded that Audioboom’s offering was not competitive for me, because they wanted to charge fees. Whereas Acast is the publisher that I went with, because it’s free (and performs superbly, I have to say).
BOOM’s niche is actually creating its own content, which drives business, and it’s got a good place in the US podcast market. So someone might bid for it, at some point in the US, maybe?
Would I value BOOM at £80m based purely on fundamentals? No way, it’s far too expensive if just viewed as an ordinary business (not a sexy tech share), because it’s only very modestly profitable, and in reality sequential quarterly growth has now apparently stalled. Plus advertising demand is likely to soften due to macro pressures, although the US seems a lot more buoyant than Europe & the UK right now.
Overall, I think we should recognise that BOOM is now a proper business, that makes a little profit, and that’s vastly better than its speculative, and at times precarious past.
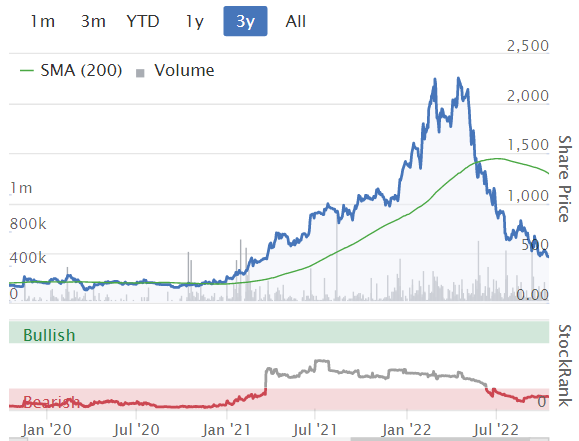
But I don’t really see any value here, on fundamentals. Maybe the best bet is for holders to hope that someone larger acquires it, at a premium price.
.
.
Graham’s Section:
Victoria (LON:VCP)
Share price: 435p (+8%)
Market cap: £504m
This carpet maker and distributor issues an in-line trading update for H1: revenues are in excess of £700m and EBITDA in excess of £100m, numbers that are in line with expectations.
Victoria expects “meaningful positive cash flow in H2” and acquisition synergies to help in “mitigating some of the macroeconomic headwinds seen across the globe”.
Let’s remind ourselves of recent news here. On 3rd August, an anonymous short-seller made claims of foul play at Victoria. The share price was around 320p on that day, versus around 400p today, so over this timeframe at least, the shorts are doing poorly.
There was no direct response from Victoria to this event, but there was a quick response: on 5th August, it announced that it had started buying back its own shares, saying:
The Board believes that the current share price is materially below the intrinsic value of the business and indeed at the current levels few alternatives exist for capital deployment that will provide equivalently high, risk-weighted returns.
Additionally, Victoria said that it “continues to generate significant positive cash flow” and had more than £200m of liquidity.
As of last Friday, Victoria had by my count bought back around 1.5 million shares, or over 1% of its outstanding shares. They’ve been buying their shares back slowly, but consistently.
Viewed as a response to short-seller scepticism, this is a clever response. Nothing screams confidence in the cheapness of your own stock quite like a willingness to buy it.
However, the number of bears involved in this stock, and their level of conviction, has recently been rising. Here are the latest figures from shorttracker.co.uk.
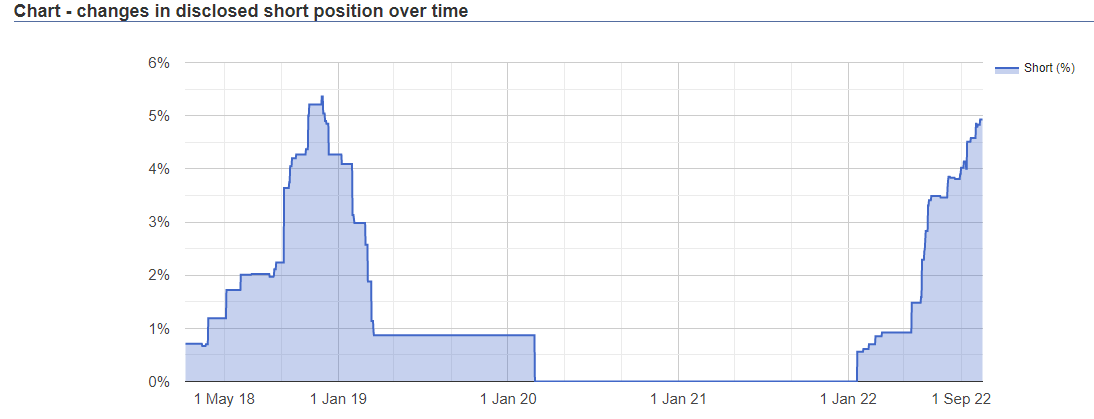
Nearly 5% of Victoria’s shares are now sold short, and that is only in the disclosed positions (i.e. positions over 0.5%). There could also be significant numbers of shares borrowed in smaller positions.
In other words, this stock has clearly become a target. It’s now in the top-15 most shorted stocks on the LSE.
What makes this all the more fascinating is that buybacks are usually kryptonite for short-sellers, because:
- They prove that the company has cash which it believes is surplus to operational requirements.
- They prove that the company thinks its shares are undervalued.
- They progressively reduce the supply of shares which are available to short-sellers to close their position, i.e. they increase the probability of a short squeeze.
So we have a very extreme level of polarisation at this stock, between the company and its short-sellers, with short-sellers willing to continue even in the face of this buyback.
My view
I did not view the short-seller report in August as a “smoking gun”. I thought it raised interesting questions about some of Victoria’s acquisitions, and I hoped that the company would answer them.
Instead, we have the company simply buying back its own shares and saying that it is highly cash-generative.
My personal view is that I am highly suspicious of Victoria Plc as an investment, although again I have no smoking gun to prove that anything untoward has happened at the company.
Executive Chairman Geoff Wilding has been a controversial and polarising figure for many years. In 2014, a few short years after a boardroom battle which saw him installed at the top of the company, the FT’s Kate Burgess described his remuneration as setting a “new standard… in executive largesse”. He ended up owning 49% of the company thanks to a package which included a CFD on the Victoria share price.
Here we are all these years later: many short-sellers have come and gone, the Victoria share price has been as high as £12 before plunging 75% this year to only £3, the long trail of acquisitions has continued, and Geoff Wilding is still in charge.
As of April 2022, the company’s net debt was over £400m and that was before lease liabilities. The company claimed that adjusted net debt/EBITDA was 2.7x, but it’s hard to believe that despite making adjusted EBITDA of £143.5m, the actual income statement result was a loss of £12m. As noted by Paul, the financial structure includes expensive preferred equity.
The previous year’s result was barely above breakeven, despite adjusted EBITDA of £112m.
Victoria would argue, among other things, that integrating its acquisitions takes time and that looking forward it will have much better statutory results.
Maybe that’s true, but this is still pretty much the opposite of the type of company that I like to invest in:
- Manufactured flooring products (a highly commoditised sector).
- A large debt load relative to historic profits.
- A complex web of acquisitions, even if the short-seller acquisitions are false.
- Financial results that require enormous adjustments to make them look ok.
On top of all that, we now have a cost-of-living crisis and housing sector conditions that likely spell bad news for consumer demand for flooring products.
So overall, I can’t help but have a negative view on this stock. Anything could happen, but there are too many issues and concerns for me to have any comfort in how shareholders will ultimately fare.
Victoria passes a Stockopedia short screen: the Altman Z-Score, which is a measure of bankruptcy risk.
RM (LON:RM.)
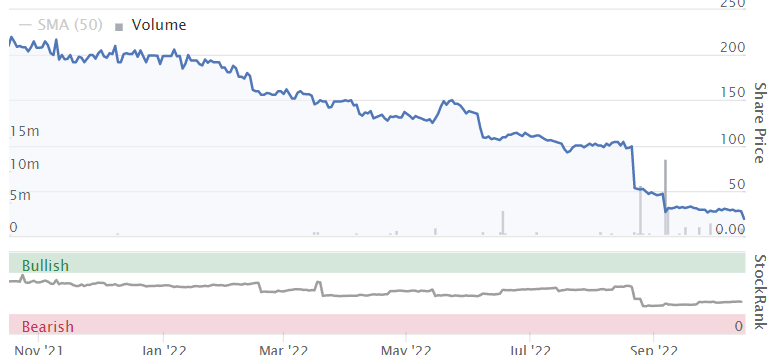
Share price: 18.95p (-30%)
Market cap: £16m
Oh dear. I last looked at this one when it released interim results in August. That day, the share price was 68p.
My conclusion was that while the company might be able to solve its problems, there was little reason to get involved with the stock. The company’s debt pile had ballooned and its banking covenants needed to be relaxed, due to escalating costs.
Today we learn that one of RM’s divisions, RM Resources, has experienced a “slower than expected recovery in the Consortium brand resulting from ongoing challenges following the IT implementation”.
RM’s IT project, based on what the company has told us about cost overruns and extended deadlines, sounds like it has been a total disaster.
The company then says:
Despite improvement through August and into September, continuation of that progress has slowed which has impacted warehouse throughout and system and process optimisation. Shipment volumes are increasing, but these are not yet at the expected level. This has also resulted in a continuation of elevated operating costs and warehouse inefficiencies with some related reduction in customer volumes.
Not sure what to make of this. Firstly “warehouse throughout” looks like a typo for “warehouse throughput”.
Secondly, I’m not sure about the cause-and-effect that is being described here. Have lower volumes caused warehouse inefficiencies, or have warehouse inefficiencies caused lower volumes? Or maybe both?
And then:
Remediation plans are in place that include reducing the order backlog to normalised levels in the short term; however, as a result, operating profit in the current year will be significantly lower than forecast. The IT plans are focused on improving delivery in Consortium, and the wider programme has been substantially slimmed down as we review the most efficient plan to completion in 2024.
Does “substantially slimmed down” mean that the rest of the IT project has been largely abandoned? That sounds important.
Net debt was £41.5m at H1 and will be “slightly higher” at the end of the year.
My view
The share price is down by over 70% since I last looked at it less than two months ago, but my view on this one is unchanged: why get involved?
It looks like a mess, both operationally and financially. Operationally, we have an IT project that has cost many millions more than it should have, and appears to have disrupted the business in serious and fundamental ways.
Financially, we have a debt load that caused the company to renegotiate its banking covenants. For what it’s worth, this debt load is now more than double the market cap.
The turnaround remains possible but I wouldn’t gamble on it.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

61 comments
£AWE (stupid ticker tagging isn't working for me) Alphawave IP
not an update, but for those who are swayed or interested by large director purchases, £580,000 purchase by the Sutardja family (Exec Director) taking their holding to 12.95%
Shocked as I am by what is happening in English club rugby, the upside for me is that Begbies Traynor (LON:BEG) are acting as administrator for Worcester Warriors and Frp Advisory (LON:FRP) have just been announced as administrator for Wasps. Every cloud and all that...
Yes Begbies Traynor (LON:BEG) surely is going to have a busy couple of years and am not sure since the slight sell off of late it's not a bit overdone. Good broker upgrades so I consider it a decent medium term upside at the current S.P....Time will Tell.
Boohoo (LON:BOO) - Paul no criticism intended here, just curiosity. You say:
However, it’s now clear that this was all down to the pandemic eCommerce boom, and look how profitability has since melted away (similar story for Boohoo (LON:BOO) [I hold] unfortunately, and the whole sector actually, here and overseas)
In that case how do you justify retaining a position in BooHoo?
In that case how do you justify retaining a position in BooHoo?
I don't have to justify it to anyone! But I think the 90% fall in share price is considerably overdone.
Thanks Paul. Sorry if i used the wrong term "justify", I meant to say what is your reasoning behind your position. All cleared up now.
Thanks for the update on LON:RM Graham. Was looking at their balance sheet and that doesn't seem to tell the Debt story. Whilst I think simplifying the IT project is a great idea (I have seen too many fail aiming for "world class excellence") I am also worried about their pensions exposure which has been discussed on Stocko before. Think this will come back in the medium term IMO as it has a half decent moat and is in a resilient sector (education). Disclosure I hold - and am pretty fed up - this was supposed to be a safe steady eddy holding - and they are supposed to be an IT company !! Double disclosure - have done a few IT Project rescues in my time and the root causes were always an overly dominant personality (business or IT) or an inappropriately close personal relationship - or both.
BTW Paul, enjoyed the Podcast - excellent synopsis on why the pensions industry has its knickers in a twist over bond prices - realised I didn't really understand it until you explained it. Recommended to others in my position.
Hi Berksbee - best of luck with RM. There is always hope. It is noteworthy that they are supposed to be able to help schools with IT projects, but they are unable to do their own IT project properly! There must be a story to tell in terms of how they got it so badly wrong. Best wishes. G
Graham - to complement your analysis of RM (LON:RM.) here is Keith Ashworth-Lord in the Buffettology Fund comments on August:
"Of the 23 fallers, six were double -digit with only one reporting during the month. That was RM (-52.6%) whose delayed interim results were quite simply a horror show. We had commented only last month that the business had struggled to regain its mojo post Covid. August’s update revealed a plethora of challenges relating to an ERP roll-out at the same time as school budgets are coming under pressure from energy costand salary inflation. Sadly, this shows little sign of abating in the short term. Damage to the portfolio was somewhat limited by its low weighting of 1.2% of net asset value at the start of the month. Our original investment was made in July 2019 at a time when the business appeared to be emerging from a big restructuring. Growth had returned, operatin g margins were moving up, returns to equity were over 30%, cashconversion looked to be moving in the right direction and gearing was about 10%. The big opportunity was the digitisation of education. Then Covid struck with its devastating impact on schools. Observant followers will have noted that we have been selling down our holding since April; being concerned about the revolving door of management changes and deteriorating investment metrics. However, having a large position in a relatively small company meant that we have been unable to exit as fast as we would have liked. Therein lies a lesson".
https://basethree.s3.eu-west-1...
Highlights why so much better to be a private investor rather than an investor in funds - you can normally exit positions very swiftly, whereas can take months for a large fund to sell out. Likewise, PIs able to quickly take advantage of something that has sold off for no apparent reason - funds generally struggle to build a meaningful stake before price recovers.
Sunday times and Paul Hill of Vox both making good points .
Highlighting liquidity pressure on small cap funds as investors draw out of funds . This makes the funds forced sellers as they will have a requirement for levels of liquidity .
So given in current market small caps are highly illiquid the only conclusion is that they are going to be forced to sell the shares that are sellable - or their most liquid and best holdings .
So probably best to watch for large volume sell trades in top quality small caps which may create lovely buying and don’t get suckered into bear trap
This is possibly happening at Avingtrans which is a good company in a good sector with plenty of cash and a proven record of turning around distressed companies with opportune acquisitions so they remain very much a firm holding and at these levels I’m starting to add .
Seems to be happening today with Avingtrans , quite chunky sell trades three biggish trades 25k 15k 16k at 9 o clock .
I’m going to check the funds that hold and then cross reference their other major holdings to see if there is a pattern .
Could be Gresham ? Downing ? Harwood ? Would find it surprising if any of the above but fiduciary regulatory requirement might force their hands ?
Jigsaw investigation to figure out .
Saietta, another Harwood significant holding, has taken a very similar drubbing in the last week. Wouldn't be surprised if the PIs who picked up one after following on VOX are reinforcing the correlations with the other.
Fair point planetx, I hold Avingtrans (LON:AVG), bought at around £2. Could be an opportunity to add. The tenure of recent prelims and management interview with Paul Hill on VOX was very much steady as she goes.
Like you I shall do a little digging, just in case there have been any adverse developments, although I think this unlikely.
I follow Avingtrans pretty closely and haven’t seen anything other about the actual company other than positives .
Think I’ll contact them to see how they engage with PI that’s a little test of mine,
I have added a few Avingtrans (LON:AVG) this morning after the share price fall. Hopefully I am being sensible and avoiding stupid decisions to paraphrase Charlie Munger.
Not sure who is selling just cannot see it being Harwood as Christopher Mills doesn’t seem the type .
What is also interesting is this feels a bit of a bear trap tempting selling by the market .
Currently no shares to buy , not been many all morning but I can sell 90k in one hit at 344p.which is very high for Avingtrabs , meaning the market wants to buy as much as it can get at these prices not sell it .
My guess is a strong bounce off these levels especially if there is no market capitulations in the next week .
Hi Paul, Given your interest in £BKS I am surprised that your haven't looked further into Aquis Exchange (LON:AQX) (I hold) which is more than just a market. I feel the technology division, in particular, has enormous potential.
They have a Capital Markets Day coming up:
Aquis Exchange PLC (AQX.L), the exchange services group, will be holding a Capital Markets Day in London on Wednesday 2 November from 14:00 - 17:00.
The Capital Markets Day will be an opportunity for analysts and institutional investors to learn more about the evolution of the Group's strategy and ambition with a focus on its state of the art exchange trading technology.
This will be a live, in-person CMD, with the option to attend virtually. A recording, along with the presentation slides, will be made available on the Company's website after the event.
Registration is required to attend. Please contact aquis@almapr.co.uk to register your interest.
Hi Jim,
I have looked at Aquis Exchange (LON:AQX) actually, several times here, but don't see any obvious upside that can be proven, or is evident in the numbers. It seems much more hope-based, and speculative.
Whereas Beeks Financial Cloud (LON:BKS) is very straightforward to analyse due to the large recurring revenues, big contract wins, exponential revenue growth, and big pipeline. So I can analyse that quite easily.
I'm happy to listen to the bull case on AQX though, we always try to keep an open mind here, but I need something a lot more tangible than just the "this could be huge" claims that we hear from bulls on so many jam tomorrow shares.
Regards, Paul.
Thanks, Paul. I have read and listened to your mentions of Aquis Exchange (LON:AQX) . You said that you didn't know what its 'Members' were and that your broker said that the Aquis Stock Exchange only saw low volume. But there are three divisions with the Stock Exchange only being one. Consequently, I thought you might be interested to learn more about the business at the Aquis Exchange (LON:AQX) Capital Markets Day.
Aquis Exchange (LON:AQX) It is not a jam tomorrow stock. It is profitable in all three divisions, it is investing for the future and seeing year-on-year growth with recurring revenues.
In many ways it is similar to £BKS.
CentralNic (LON:CNIC) Q3 update: Directors confident "will materially exceed the current market expectations for the full year". Jack (prior his departure) was very positive here re the prospects for this equity.
Global Ports Holding
2023 cruise call reservations and passenger volumes
https://www.londonstockexchang...
Superdry (LON:SDRY)
Schroders have taken a 4.82% holding
Superdry (LON:SDRY) They haven't just taken a position. They had 5.5% before and are just stating their current position.
RNS misleadingly states no previous position but you're correct
Hoping not to start a big argument but I find it interesting that you feel people should stay in UK in some form of loyalty to the country. I would see at least personally my first loyalty is to my family and ensuring I can be somewhere where I'm able to provide the best possible future for them.
For full disclosure: I moved out of the UK about 18 years ago first because of love but then just out the fact that I felt better opportunities for my family and I. It saddens me to say that and I would love the situation to be different
Sounds like a discussion for Twitter!
Wasn't the point introduced in the SCVR. Shouldn't the twitter exchange be left on twitter #BlurredLines
You bought it up.
It was a joke, to make people laugh. A nice way to start the day. Not an opener for a heated, pointless debate.
Thanks for your post
Where did you move to out of interest
I did 2 years traveling as part of my job and was basically on the road, spent then 14 years in Slovakia and have now been 2 years in Spain
Thanks
Slovakia is meant to be beautiful
Yes particularly out of the cities (which aren't anything that special.) If you go up into the mountains its lovely and it's sort of out of the tourist train apart from stag weekends in Bratislava. The cost of living there is great (although we'll see what it looks like after inflation) and you can still have a good night out for less than twenty pound.
Smiths News (LON:SNWS) news looks absolutely fantastic to me? The shares are valued on a P/E of around 3 which essentially took it to 2025 on the basis nobody knows about print media longevity. The contract signings today take it to 2030 (obviously the 3rd parties themselves have to be around and we don't knot the detail) but it seems terrific news to me and underpins the longer-term value, leaving this now looking even cheaper than it did before.
Just repositioned a lot of my portfolio onto this (hope others agree!!) as hopefully also more market volatility resistant than most shares as well. Ideally won't sell until well into 60s. (one recent broker target something like 92p on this). Appreciate Paul's view.
Hi Paul
Great Twitter interaction :)
Coincidentally, over the weekend I came across this YouTube channel and supporting web site --- 'Nomad Capitalist'.
It's an American scouring the world to see how he can visit, live, invest in countries which offer a favourable context for his interests.
His vids and supporting website are resources which cover many topics from taxation, banking, golden visas, digital nomad visas etc .....
Its going against your sentiments that we ought to stay loyal to the country in these times, but some might be interested to explore some of his ideas (for semi retirement perhaps, a sabbatical, a multi country lifestyle, and so on).
YouTube channel here .... the 15 min intro vid explains the purpose of Nomad Capitalist
https://www.youtube.com/c/noma...
The supporting website is here
https://nomadcapitalist.com/
As I visit Portugal a lot I have noted they now offer a Nomad Visa (as do several other countries), to enable people to go and live there but who are remote workers and earn their living from clients or employment in other countries. The Nomad Visa helps to make such an arrangement quite straight forward.
Regards
Howard
Morning all,
Ahead of update from £CNIC.
I hold.
I really like this post each day so thank you for doing it.
Agree a helpful heads-up summary
Long may Mr Contrarian continue to provide his succinct and humerous daily smallcap tweet.
Keep going Mr Contrarian. I read this every day. It's a great news digest.
Trading statement out of CLIG. I hold. FUM pretty well unchanged. My reading of this is that profits are holding up when forecasts have come well down. I will continue to hold.
eve Sleep (LON:EVE) has appointed administrators.
£eve i remember the new CEO highlighting in a presentation the great working culture they had - and exampled the friday afternoon drinks trolley!!@
then the CEO diversified from awarding winning matresses into CBD products which they said they dont expect to make any money from but will be good publicity for the brand!!
Good morning Paul and Graham, I'd appreciate observations on CNIC's TS this morning if you have time. 66% organic growth and going to come above expectations, reduced interest on a new long term loan. I'm sorely tempted to add to our holding unless you tell me what I might be missing.
Might even end up positive on the day LOL.
Seems a very good update and poised to move up from here. A lot to like in this update
Thanks JASVFS, I'll take note of this to potentially cover as a backlog item. G